
Hospital injectables anchor value as self-dosing spreads
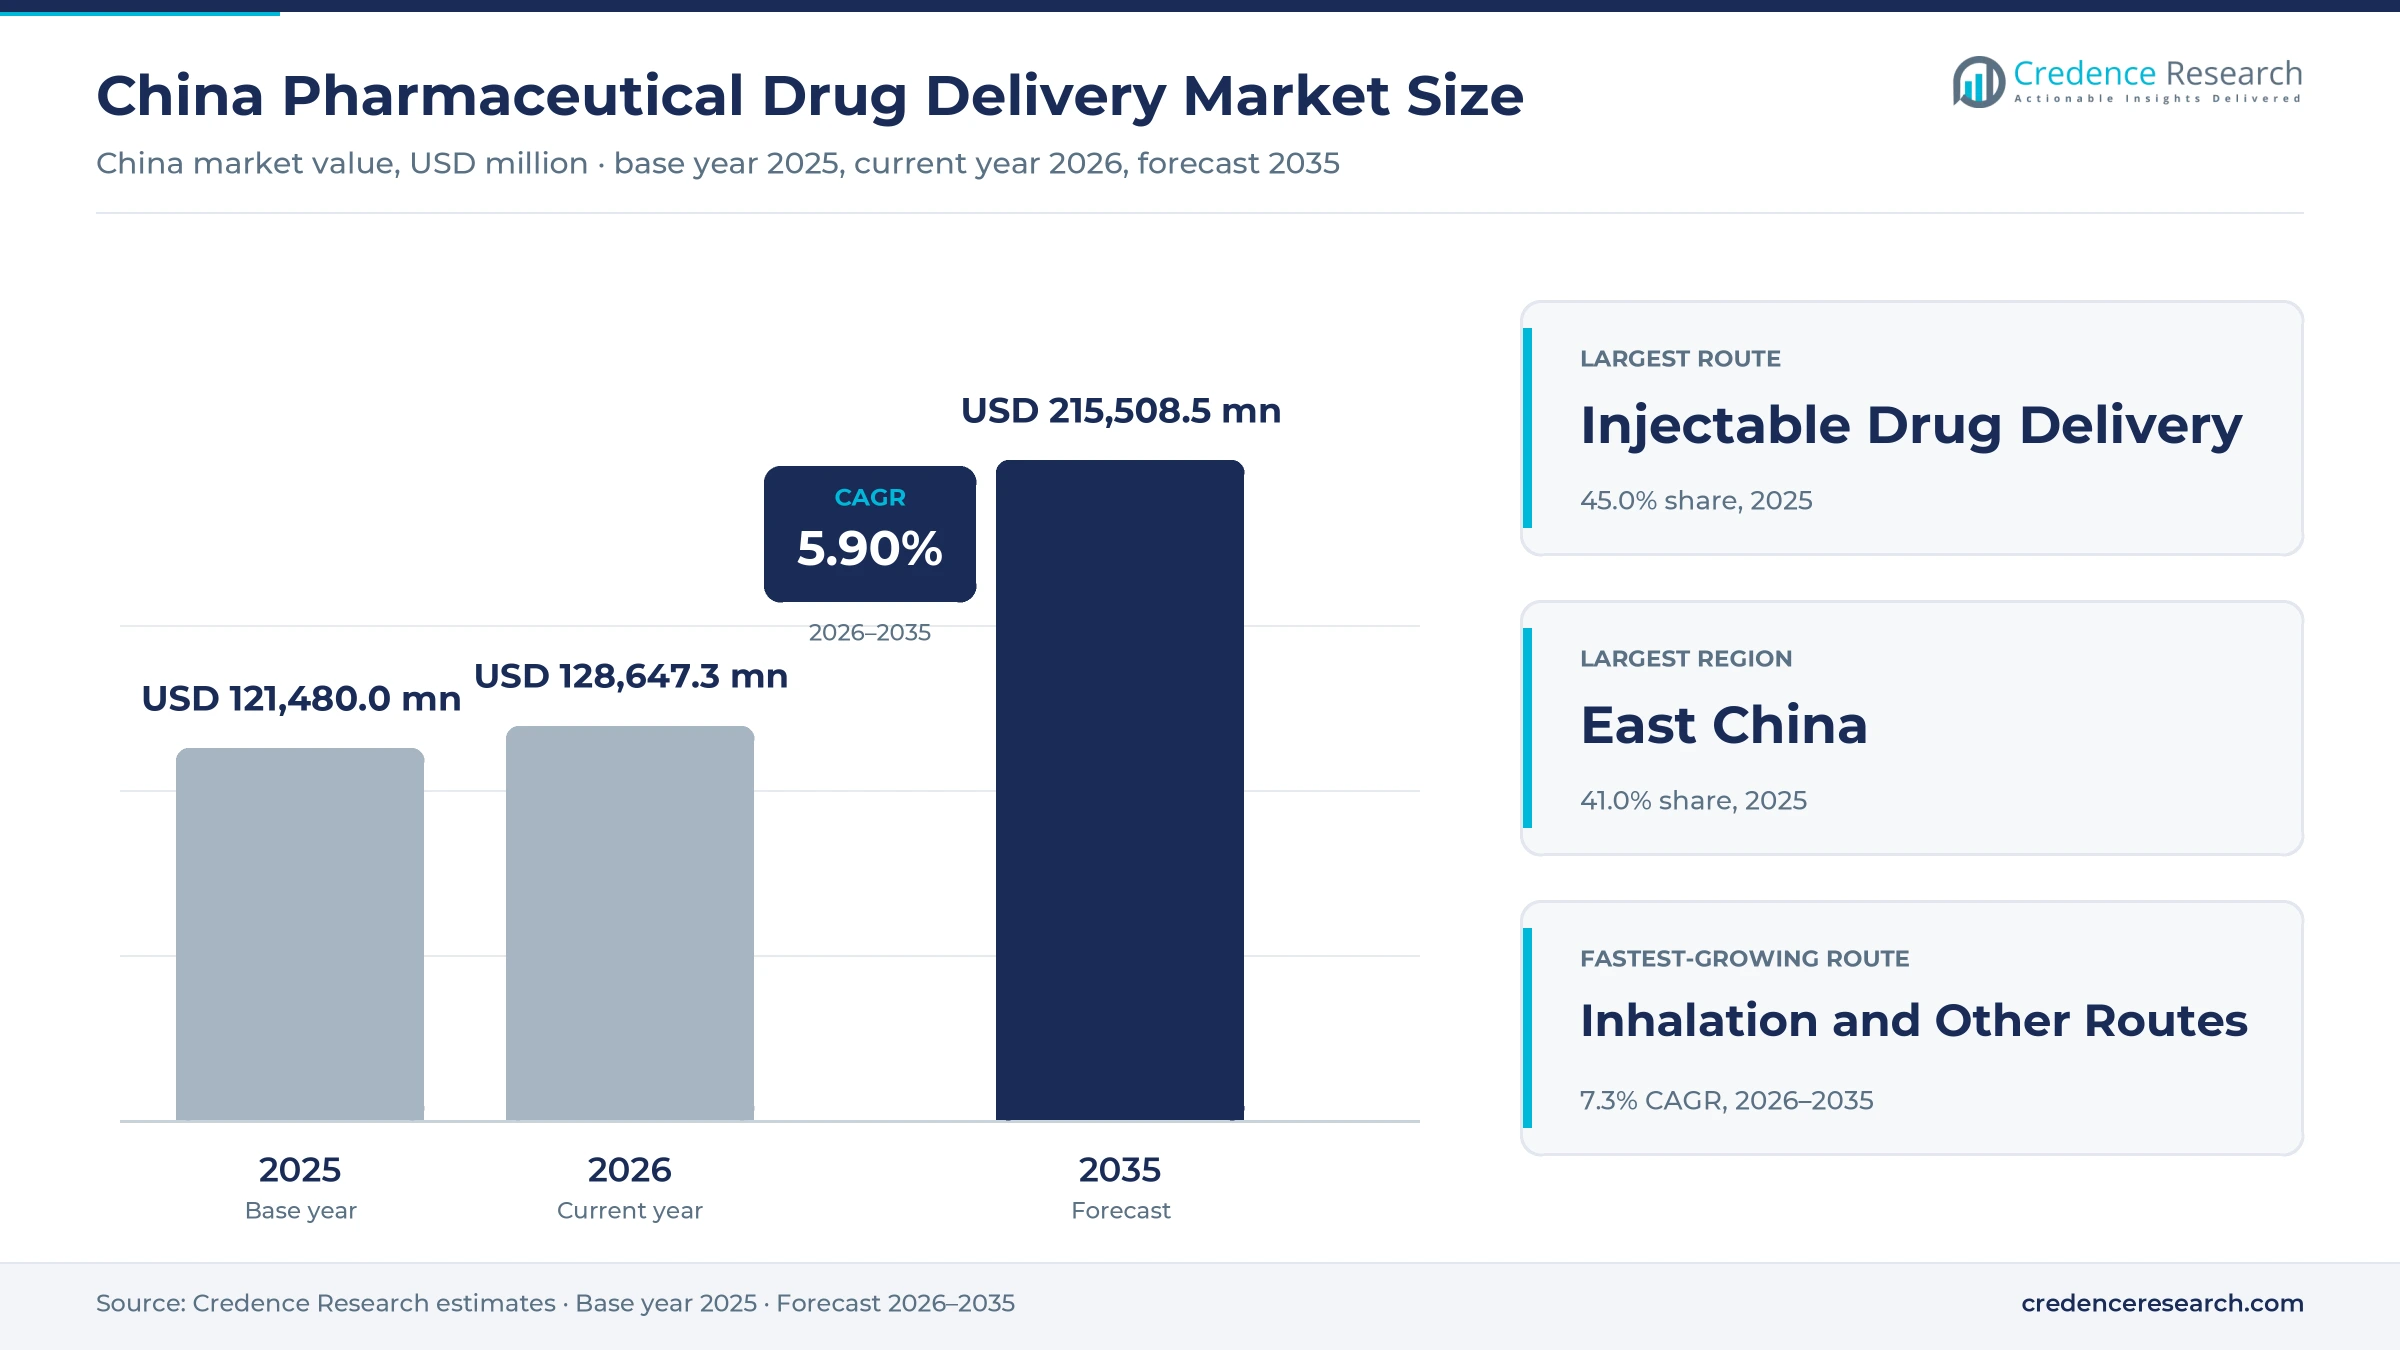
The China pharmaceutical drug delivery market was valued at USD 121.48 billion in 2025 and is projected to increase from USD 128.65 billion in 2026 to USD 215.51 billion by 2035, registering a CAGR of 5.90% during 2026–2035. Demand comes from hospitals that administer injectable cancer, anti-infective and biologic therapies, from an aging population managing diabetes, heart disease and respiratory illness at home, and from a new class of weekly incretin pens for weight management. East China held the largest regional share, 41.0% in 2025, because Jiangsu, Shanghai and Zhejiang concentrate tertiary hospitals, drug plants and device makers. Southwest and Northwest China is the fastest-growing region at 6.7% a year as inland hospital capacity and insurance coverage widen. The main commercial change is pricing, since national volume-based procurement keeps cutting generic tablet and injection prices while semaglutide lost patent protection in March 2026, which moves value toward formats that are harder to copy, such as long-acting injectables, patches and inhalers.
Medicines are counted by the route that delivers them
This report sizes the value of finished chemical and biological medicines sold in mainland China, measured at manufacturer selling prices and grouped by the route that delivers them. It counts tablets and capsules, oral liquids, injectables including prefilled syringes, pens and autoinjectors, topical and transdermal products, and inhaled and nasal medicines, together with the devices sold as part of each product. Value is therefore the sales of medicines in their delivery formats, not the separate sales of pens, patches or inhaler devices to drugmakers, which form an upstream supply market.
Proprietary Chinese medicines, decoction pieces, vaccines, contrast agents, active ingredients and stand-alone medical devices are excluded. Most volume reaches patients through public hospitals that buy through provincial procurement platforms, while retail pharmacies and online sellers handle a rising share of refills for chronic conditions.
China Pharmaceutical Drug Delivery Market Insights
- The China pharmaceutical drug delivery market was worth USD 121.48 billion in 2025 and is forecast to reach USD 215.51 billion by 2035, growing at 5.90% a year during 2026–2035.
- East China held 41.0% of 2025 value, while Southwest and Northwest China grows fastest at 6.7% a year as inland hospital capacity and insurance coverage expand.
- Injectable Drug Delivery took 45.0% of 2025 value, because public hospitals still give most cancer, anti-infective and biologic therapies by infusion or injection.
- China cleared 120 new drugs in 2025, including 40 biologics, according to the DIA Global Forum, and most of those biologics need injectable formats.
- Ypsomed opened a plant in Changzhou in June 2025 that can make up to 100 million injection systems a year for drugmakers selling in China.
Injectables lead while inhaled formats grow fastest
Why do injectables hold the largest share?
Based on route of administration, the market is categorized into solid oral, liquid, injectable, topical and transdermal, and inhalation and other routes. Injectable Drug Delivery led with 45.0% of 2025 value, because hospitals give most cancer, anti-infective and biologic therapies by infusion, and medical institutions took 72.95% of terminal drug sales in Jiangsu in 2024, according to the provincial pharmaceutical commerce association. Inhalation and Other Routes grow fastest at 7.3% a year as respiratory care moves toward branded inhalers, and AstraZeneca lifted its total Qingdao inhalation investment to $886 million in November 2025 for a site due online in 2028.
Why does cancer care lead and diabetes grow fastest?
Based on application, the market is categorized into infectious disease, cancer, cardiovascular diseases, diabetes, respiratory diseases and others. Cancer led with 27.0% of 2025 value, because antibody, conjugate and liposomal therapies carry the highest prices per course, and CSPC won approval in December 2025 for its Duoenyi irinotecan liposome injection as a first-line treatment for metastatic pancreatic cancer. Diabetes grows fastest at 7.8% a year as weekly incretin pens add to analog and human insulin therapy, and medical institutions requested more than 240 million insulin injections in the April 2024 renewal of national insulin procurement, Yicai reported.
Why do hospitals lead and home care grow fastest?
Based on end user, the market is categorized into hospitals, ambulatory clinics and primary care, home care settings and others. Hospitals led with 64.0% of 2025 value, because they hold the infusion capacity and the specialist prescribers, and the National Bureau of Statistics counted 38 thousand hospitals and 10.09 million beds across medical institutions at the end of 2025. Home Care Settings grow fastest at 7.2% a year as chronic patients refill pens and patches outside hospitals, and nine ministries agreed in January 2026 to give designated retail pharmacies the same outpatient reimbursement terms as primary clinics.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Route of Administration | Injectable Drug Delivery | 45.0% | Inhalation and Other Routes | 7.3% |
| By Application | Cancer | 27.0% | Diabetes | 7.8% |
| By End User | Hospitals | 64.0% | Home Care Settings | 7.2% |
Pen prices fall fast while tenders set generic floors
Prices in China depend on whether a product sits inside national procurement, on the reimbursement list or in the self-pay market. Procured insulin and generic tablets are priced through tenders that reward the lowest qualified bid, so suppliers compete on plant cost and volume rather than on device features. Self-pay pens for weight management follow a different path, and both multinational incretin pens were cut sharply in late 2025 before domestic semaglutide copies arrived. Formats that resist copying, such as long-acting injectables, patches and inhalers, hold their prices longer, which explains why domestic originators build platforms around them rather than around plain tablets.
| Product or tender | Typical price or fee | Basis |
|---|---|---|
| Wegovy semaglutide prefilled pen | CNY 1,893.67 cut to CNY 987.48 per pen | Yunnan and Sichuan procurement platforms via Yicai, December 2025 |
| Mounjaro tirzepatide prefilled pen | CNY 2,180 guide price, presale from CNY 450 | Yicai, December 2025 |
| Gan & Lee insulin glargine, national procurement | CNY 65.30 per injection | National insulin procurement renewal via Yicai, April 2024 |
| Lilly lispro 25R mix, national procurement | CNY 38.42 per injection | National insulin procurement renewal via Yicai, April 2024 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Aging, new approvals and obesity pens lift volumes
An older population raises chronic dosing volumes
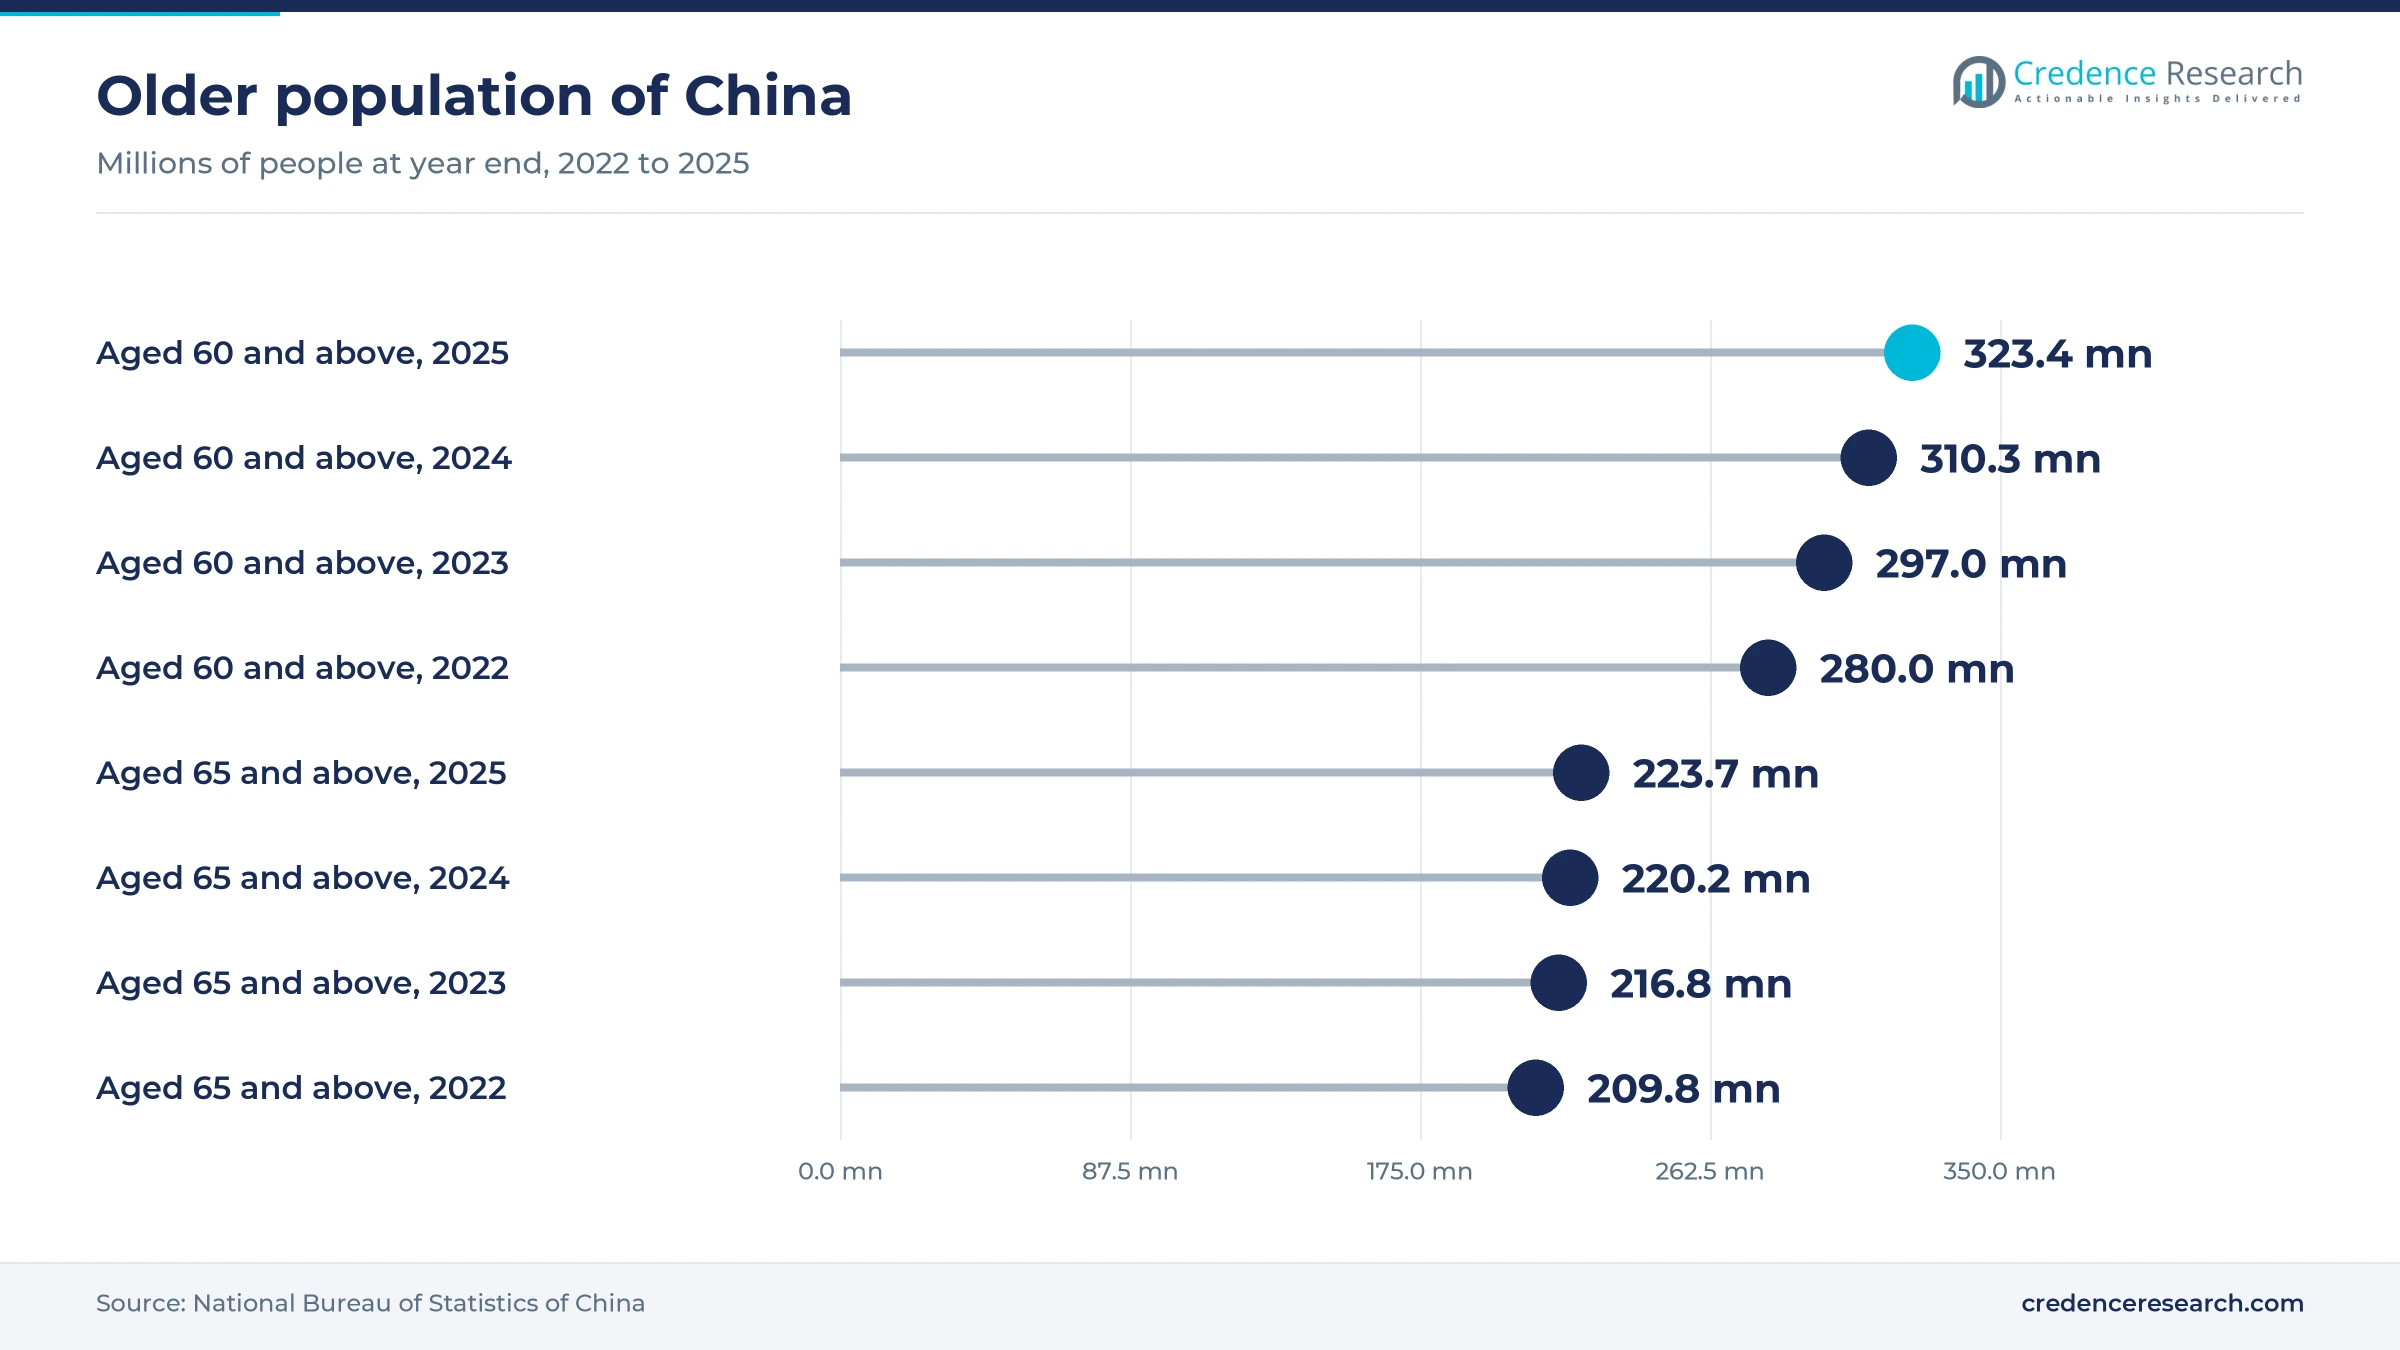
Chronic disease drives repeat dosing, so the size of the older population sets the base volume for tablets, injections and patches. The National Bureau of Statistics counted 323.38 million people aged 60 and above at the end of 2025, or 23.0% of the population, and the group aged 65 and above reached 223.65 million. The International Diabetes Federation estimates that 148.0 million Chinese adults had diabetes in 2024, a prevalence of 11.9%. These patients need daily or weekly dosing for decades, which favors once-daily modified-release tablets, prefilled pens and transdermal patches that make adherence easier. Suppliers with reimbursed chronic-care portfolios gain most, because their volumes rise even when unit prices fall.
Record new drug approvals widen injectable demand
New molecule approvals add high-value products that mostly need injection or advanced oral formats. China cleared 120 new drugs in 2025, excluding traditional Chinese medicines, the DIA Global Forum reported, including 40 biologics. Domestic companies accounted for 63 of the approvals and outnumbered imported products for the first time. The 2025 national reimbursement list then added 114 medicines, 50 of them Category 1 innovative drugs, with coverage from Jan. 1, 2026, according to the Shanghai municipal government. Faster listing shortens the gap between approval and hospital use, which favors originators of injectable biologics and the fill-finish and device suppliers that serve them.
Obesity care moves weekly injections into pens
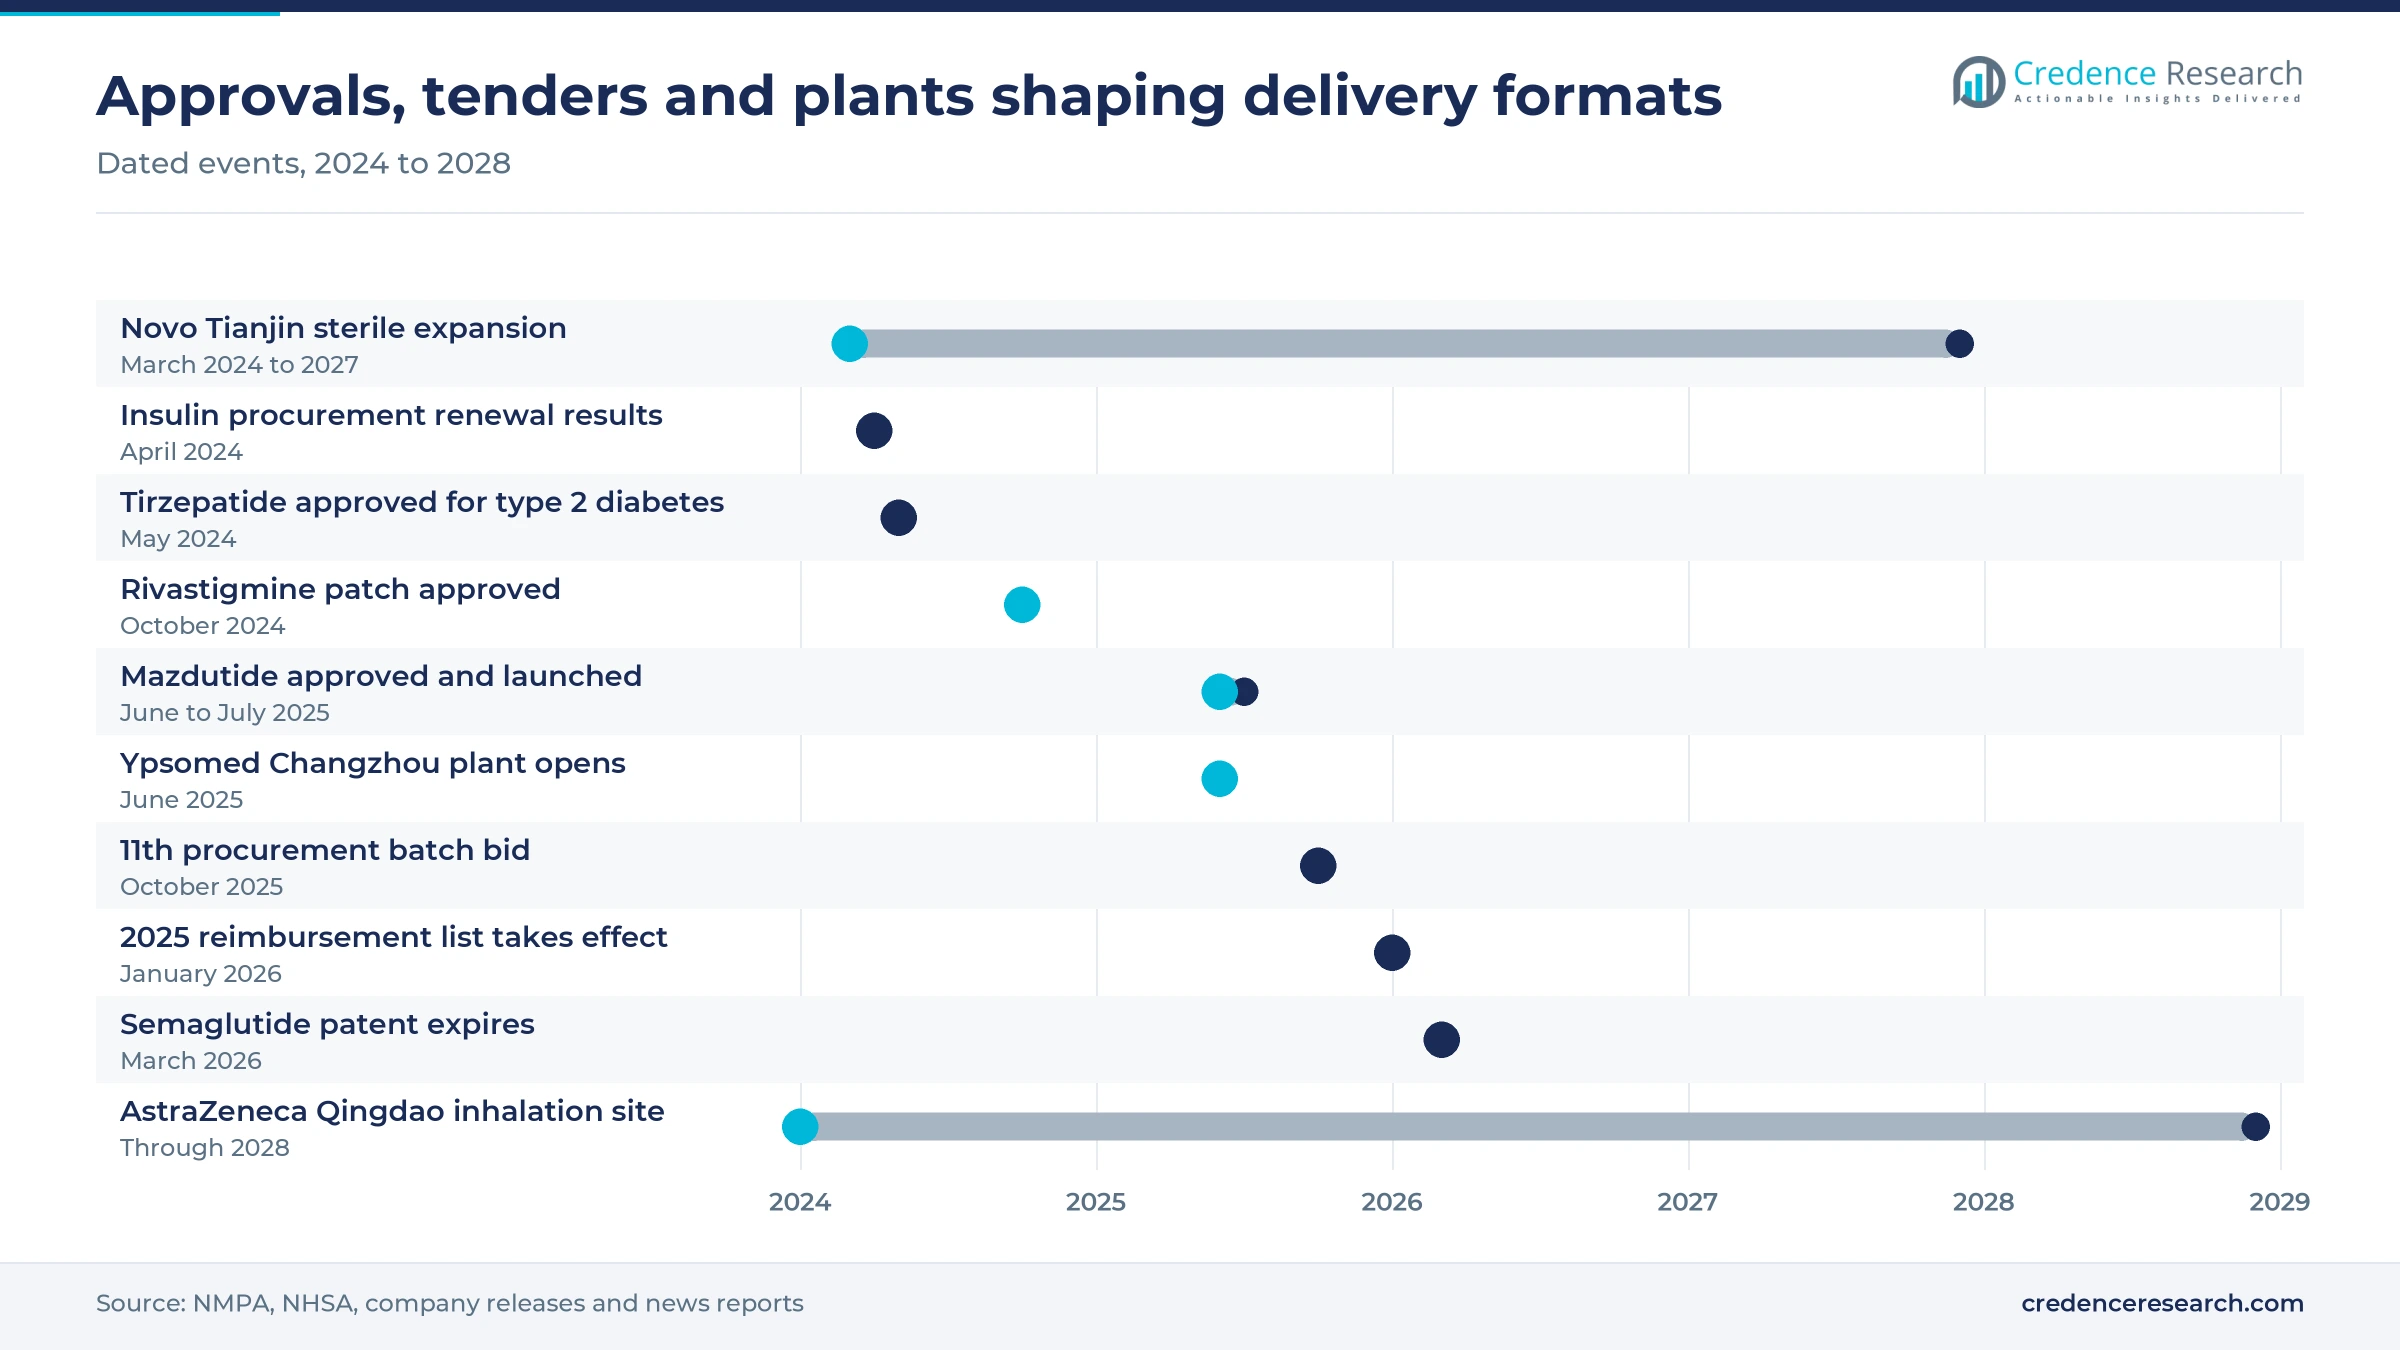
Weight-management therapy is adding a large self-injection population that barely existed before 2024. Innovent says more than 500 million Chinese adults are overweight or obese, and the NMPA approved its mazdutide for chronic weight management on June 27, 2025. The drug launched in a YpsoMate autoinjector, and Ypsomed opened a Changzhou plant in June 2025 that can make up to 100 million injection systems a year for the Chinese market. The NMPA had already approved Lilly's tirzepatide for type 2 diabetes in May 2024, according to KrASIA. Weekly dosing turns each patient into a recurring buyer of pens or autoinjectors, which benefits device makers and fillers with local capacity.
Local plant investment shortens supply chains
Multinational and domestic producers are adding sterile and device capacity inside China, which lowers landed costs and helps them compete in tenders that reward reliable local supply. Novo Nordisk began a $556 million sterile preparations expansion in Tianjin in March 2024, due for completion in 2027, BioSpace reported, and TEDA expects Novo's total Tianjin investment to exceed CNY 10 billion. AstraZeneca broke ground on a $475 million small-molecule plant in Wuxi in May 2025 and said in January 2026 that it would invest $15 billion in China through 2030. Gerresheimer said in July 2026 that its new Zhenjiang plant doubles its Chinese capacity for injectable glass packaging. Fillers and packaging suppliers near these sites gain steady orders as local supply lifts demand for injectable components through 2027.
Retail refills and patch platforms reshape the channel
Retail pharmacies are shifting into chronic refills
Policy is shifting chronic refills away from hospital outpatient desks toward retail pharmacies and online sellers, which changes how pens, patches and oral medicines reach patients. The Ministry of Commerce and eight other departments issued a policy on Jan. 22, 2026 that lets chain pharmacists review prescriptions remotely and encourages retailers to join centralized procurement, People's Daily reported. Ministry of Commerce data show pharmaceutical distribution sales rising from CNY 2.41 trillion in 2020 to CNY 2.95 trillion in 2024. Retail sales of Chinese and Western medicines grew only 1.8% in 2025, according to the National Bureau of Statistics, so retailers need higher-value chronic products to lift baskets. Suppliers of self-administered pens, patches and modified-release tablets therefore gain shelf space and pharmacist attention.
Domestic firms shift toward patch and depot platforms
Domestic originators are shifting from plain generics toward transdermal and long-acting injectable platforms that tenders cannot easily commoditize. Sino Biopharmaceutical won NMPA approval for the first domestically produced rivastigmine patch on Oct. 1, 2024, BioWorld reported, then added a rotigotine patch in December 2025 and expects more than 10 patch products approved by 2030. Sichuan Kelun received approval for its own rotigotine patch in October 2025, according to its exchange filing. Luye Pharma's monthly paliperidone palmitate injection, Meibirui, gained approval in June 2024, and Livzon won approval in September 2026 for a three-month leuprorelin microsphere injection, according to its exchange filing. These platforms create openings for transdermal skin patches and microsphere injections across neurology and psychiatry, where adherence is the main clinical problem.
Semaglutide expiry opens a domestic pen opportunity
The end of semaglutide patent protection creates an opening for domestic peptide makers and the device suppliers that serve them. Semaglutide lost patent protection in China on March 20, 2026, and ten domestic semaglutide products had applied for approval by late 2025, according to Yicai. The NMPA accepted Jiuyuan Gene's application for a weight-management version on Feb. 25, 2026, and Livzon, Qilu, Huadong Medicine and CSPC run their own programs, The Star reported. Domestic copies are likely to price below the originator, which widens access for self-pay patients. Pen makers with local plants, filling lines and GLP-1 receptor agonist supply agreements stand to win most of the new device volume.
Local device and packaging supply opens new contracts
Local device and primary packaging capacity is becoming an opening for suppliers that can serve Chinese biologics makers on short lead times. Prefilled syringes and autoinjectors register in China as drugs rather than as separate combination products, according to ISPE, so the device is reviewed within the drug application. The Changzhou device plant noted above has secured a further 30,000 square meters, and Gerresheimer has reserved 33,000 square meters at its new Zhenjiang site. The 40 biologics cleared in 2025, noted above, show how many new injectable customers each approval year adds. Suppliers of prefilled syringes, cartridges and autoinjectors with local quality systems can win fill-finish contracts that imported components lose on cost and delivery time.
Procurement cuts and payer limits hold back value
Volume-based procurement keeps cutting unit prices
National volume-based procurement compresses prices for off-patent tablets and injections, which caps value growth even when volumes rise. The 11th batch, bid in Shanghai on Oct. 27, 2025, covered 55 medicines and selected 453 products, bringing the program to 490 drug varieties since 2018, People's Daily reported. A 12th round covering 65 varieties worth an estimated CNY 60 billion opened in July 2026, according to GaBI Online. Generic makers without differentiated formats are most exposed, and their best response is to move into patches, depots and inhalers.
Incretin price cuts squeeze pen margins
Price competition in weight-management pens arrived before most domestic products launched. Wegovy fell from CNY 1,893.67 to CNY 987.48 per pen on Yunnan and Sichuan procurement platforms, Yicai reported in December 2025, while Mounjaro presale prices dropped as low as CNY 450. Domestic entrants planning premium prices are most exposed, along with device suppliers paid per unit, because lower pen prices push drugmakers to seek cheaper components. Scale and local manufacturing are the main defenses for both groups.
Payer budgets limit uptake of costly therapies
Public insurance cannot fund every high-priced therapy, which limits uptake of premium formats outside the reimbursement list. The first commercial insurance innovative drug list, released in December 2025, covered only 19 high-value treatments such as CAR-T therapies. A China Re Life and MediTrust Health white paper put commercial insurance payments for innovative drugs and devices at CNY 15.2 billion in 2025, against about CNY 90.5 billion from basic medical insurance. Self-pay biologics and cell therapies are most exposed until private cover deepens.
Imported components still gate some launches
Some new injectables still depend on devices made outside China, which exposes launches to freight, customs and capacity risks. Ypsomed said in July 2025 that mazdutide autoinjectors would come from its Swiss and German plants until its new Chinese plant could supply them. Qualifying a new device for an approved drug requires stability and compatibility data, so switching suppliers takes many months. Small biologics developers without dual sourcing are most exposed, and they reduce the risk by qualifying a local second source early in development.
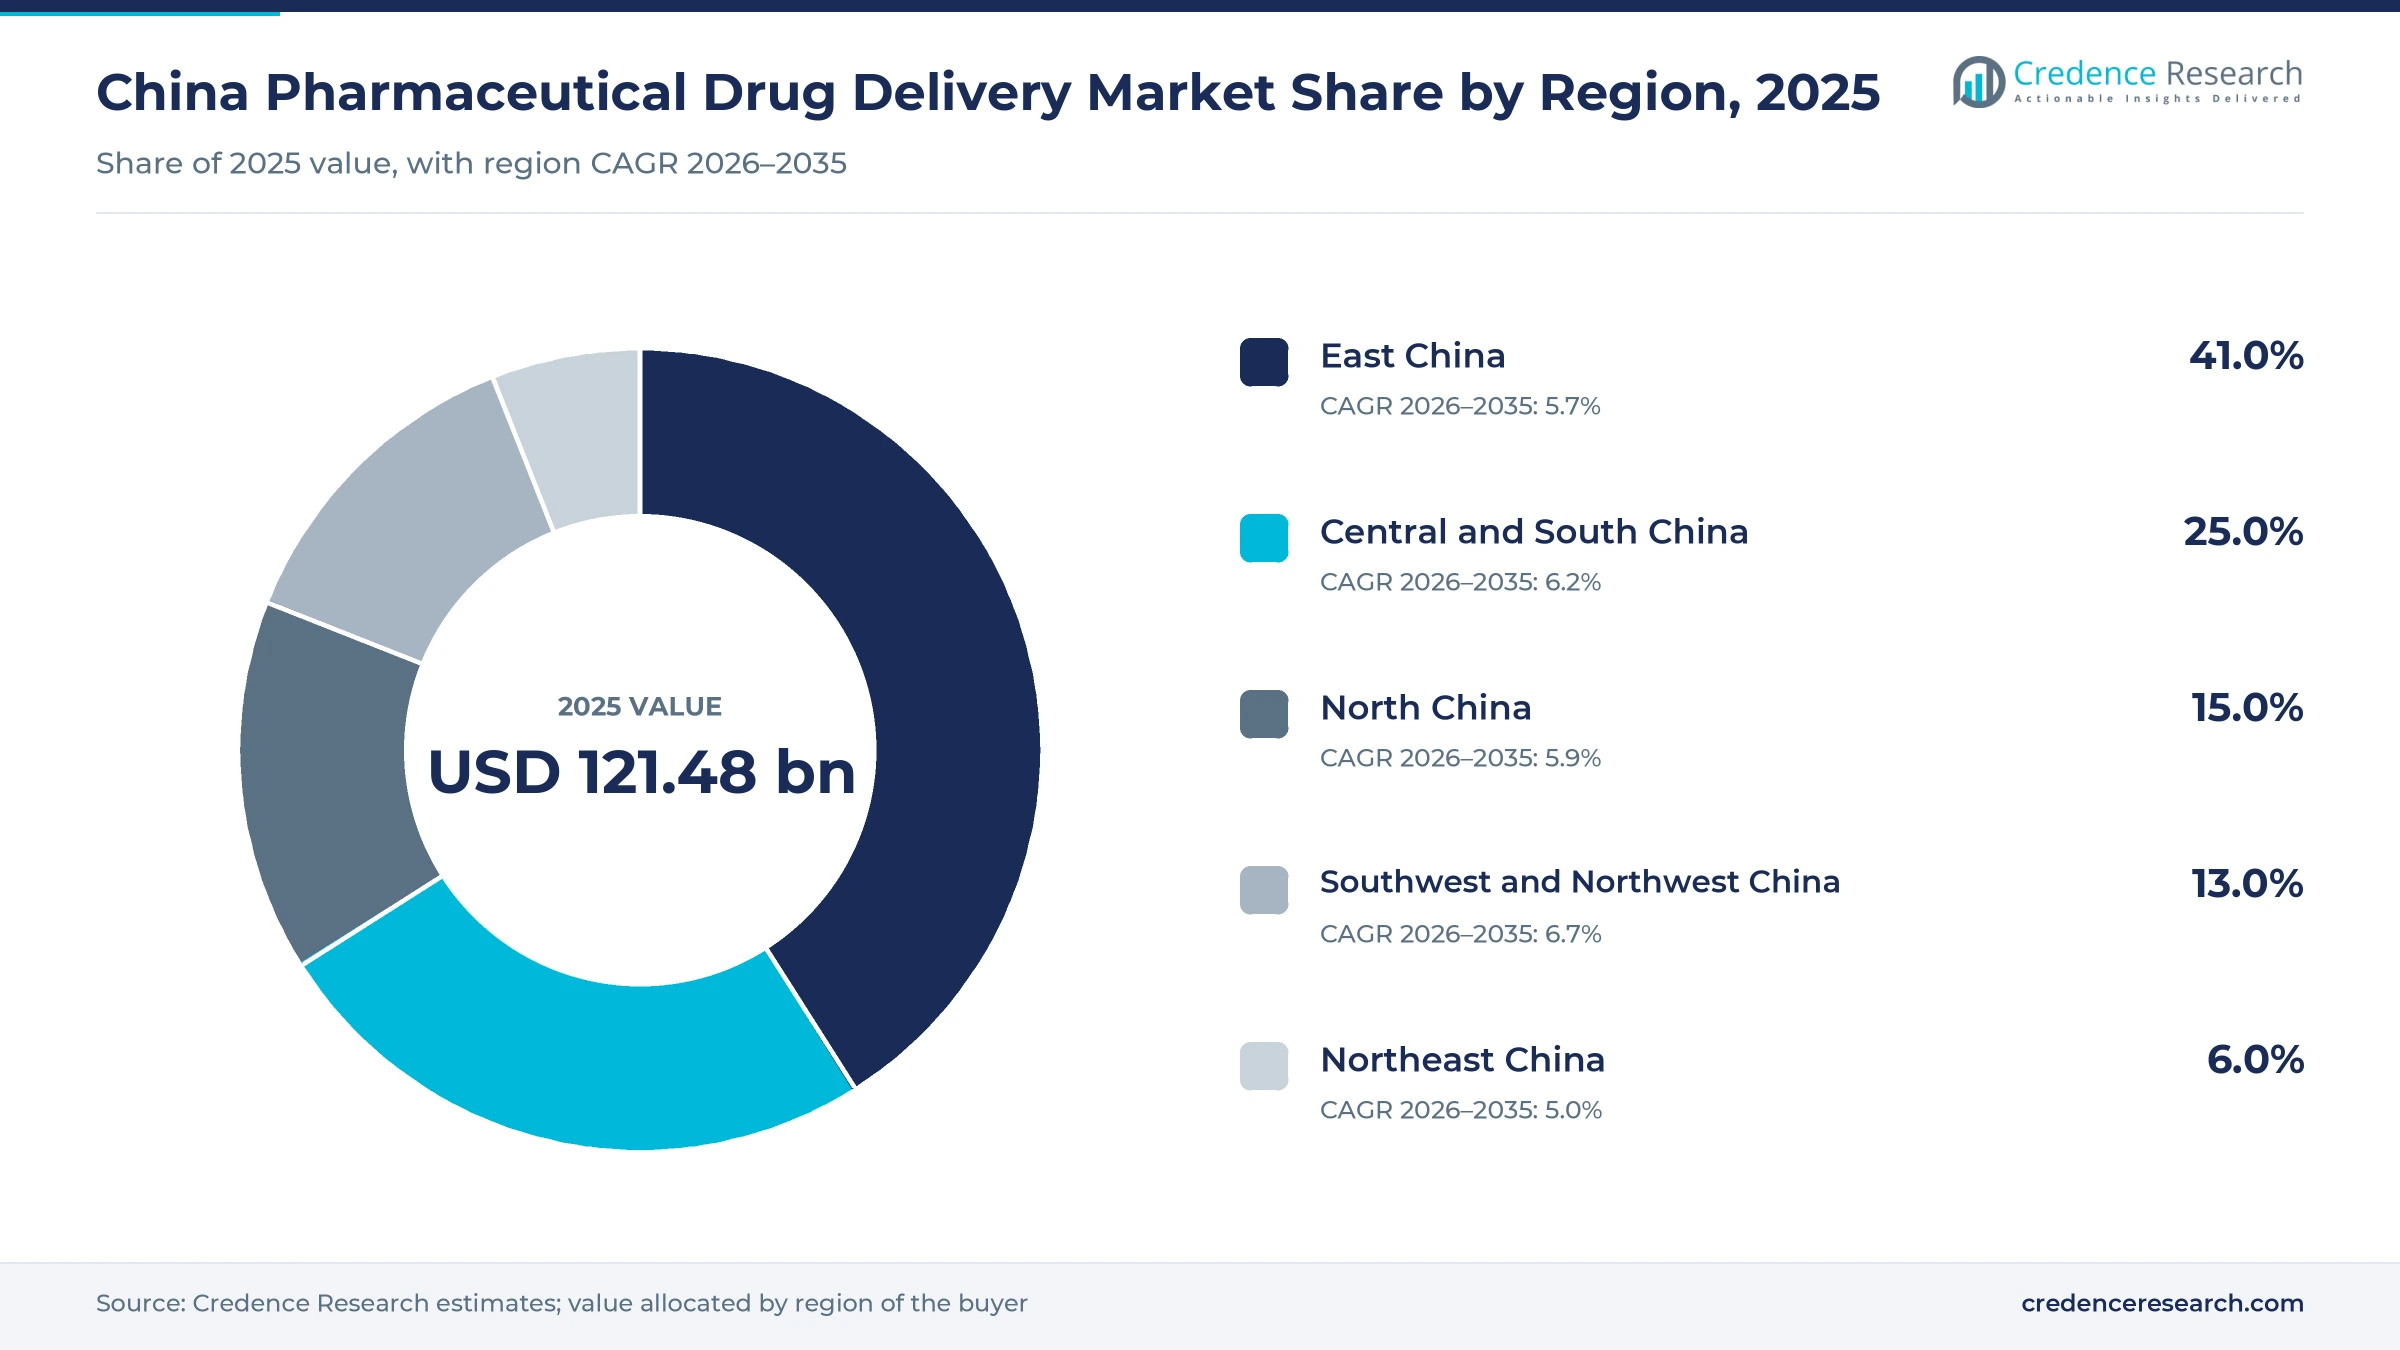
East China leads while the inland west grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| East China | 49,806.8 | 41.0% | 5.7% |
| Central and South China | 30,370.0 | 25.0% | 6.2% |
| North China | 18,222.0 | 15.0% | 5.8% |
| Southwest and Northwest China | 15,792.4 | 13.0% | 6.7% |
| Northeast China | 7,288.8 | 6.0% | 5.0% |
East China combines the largest hospitals and plants
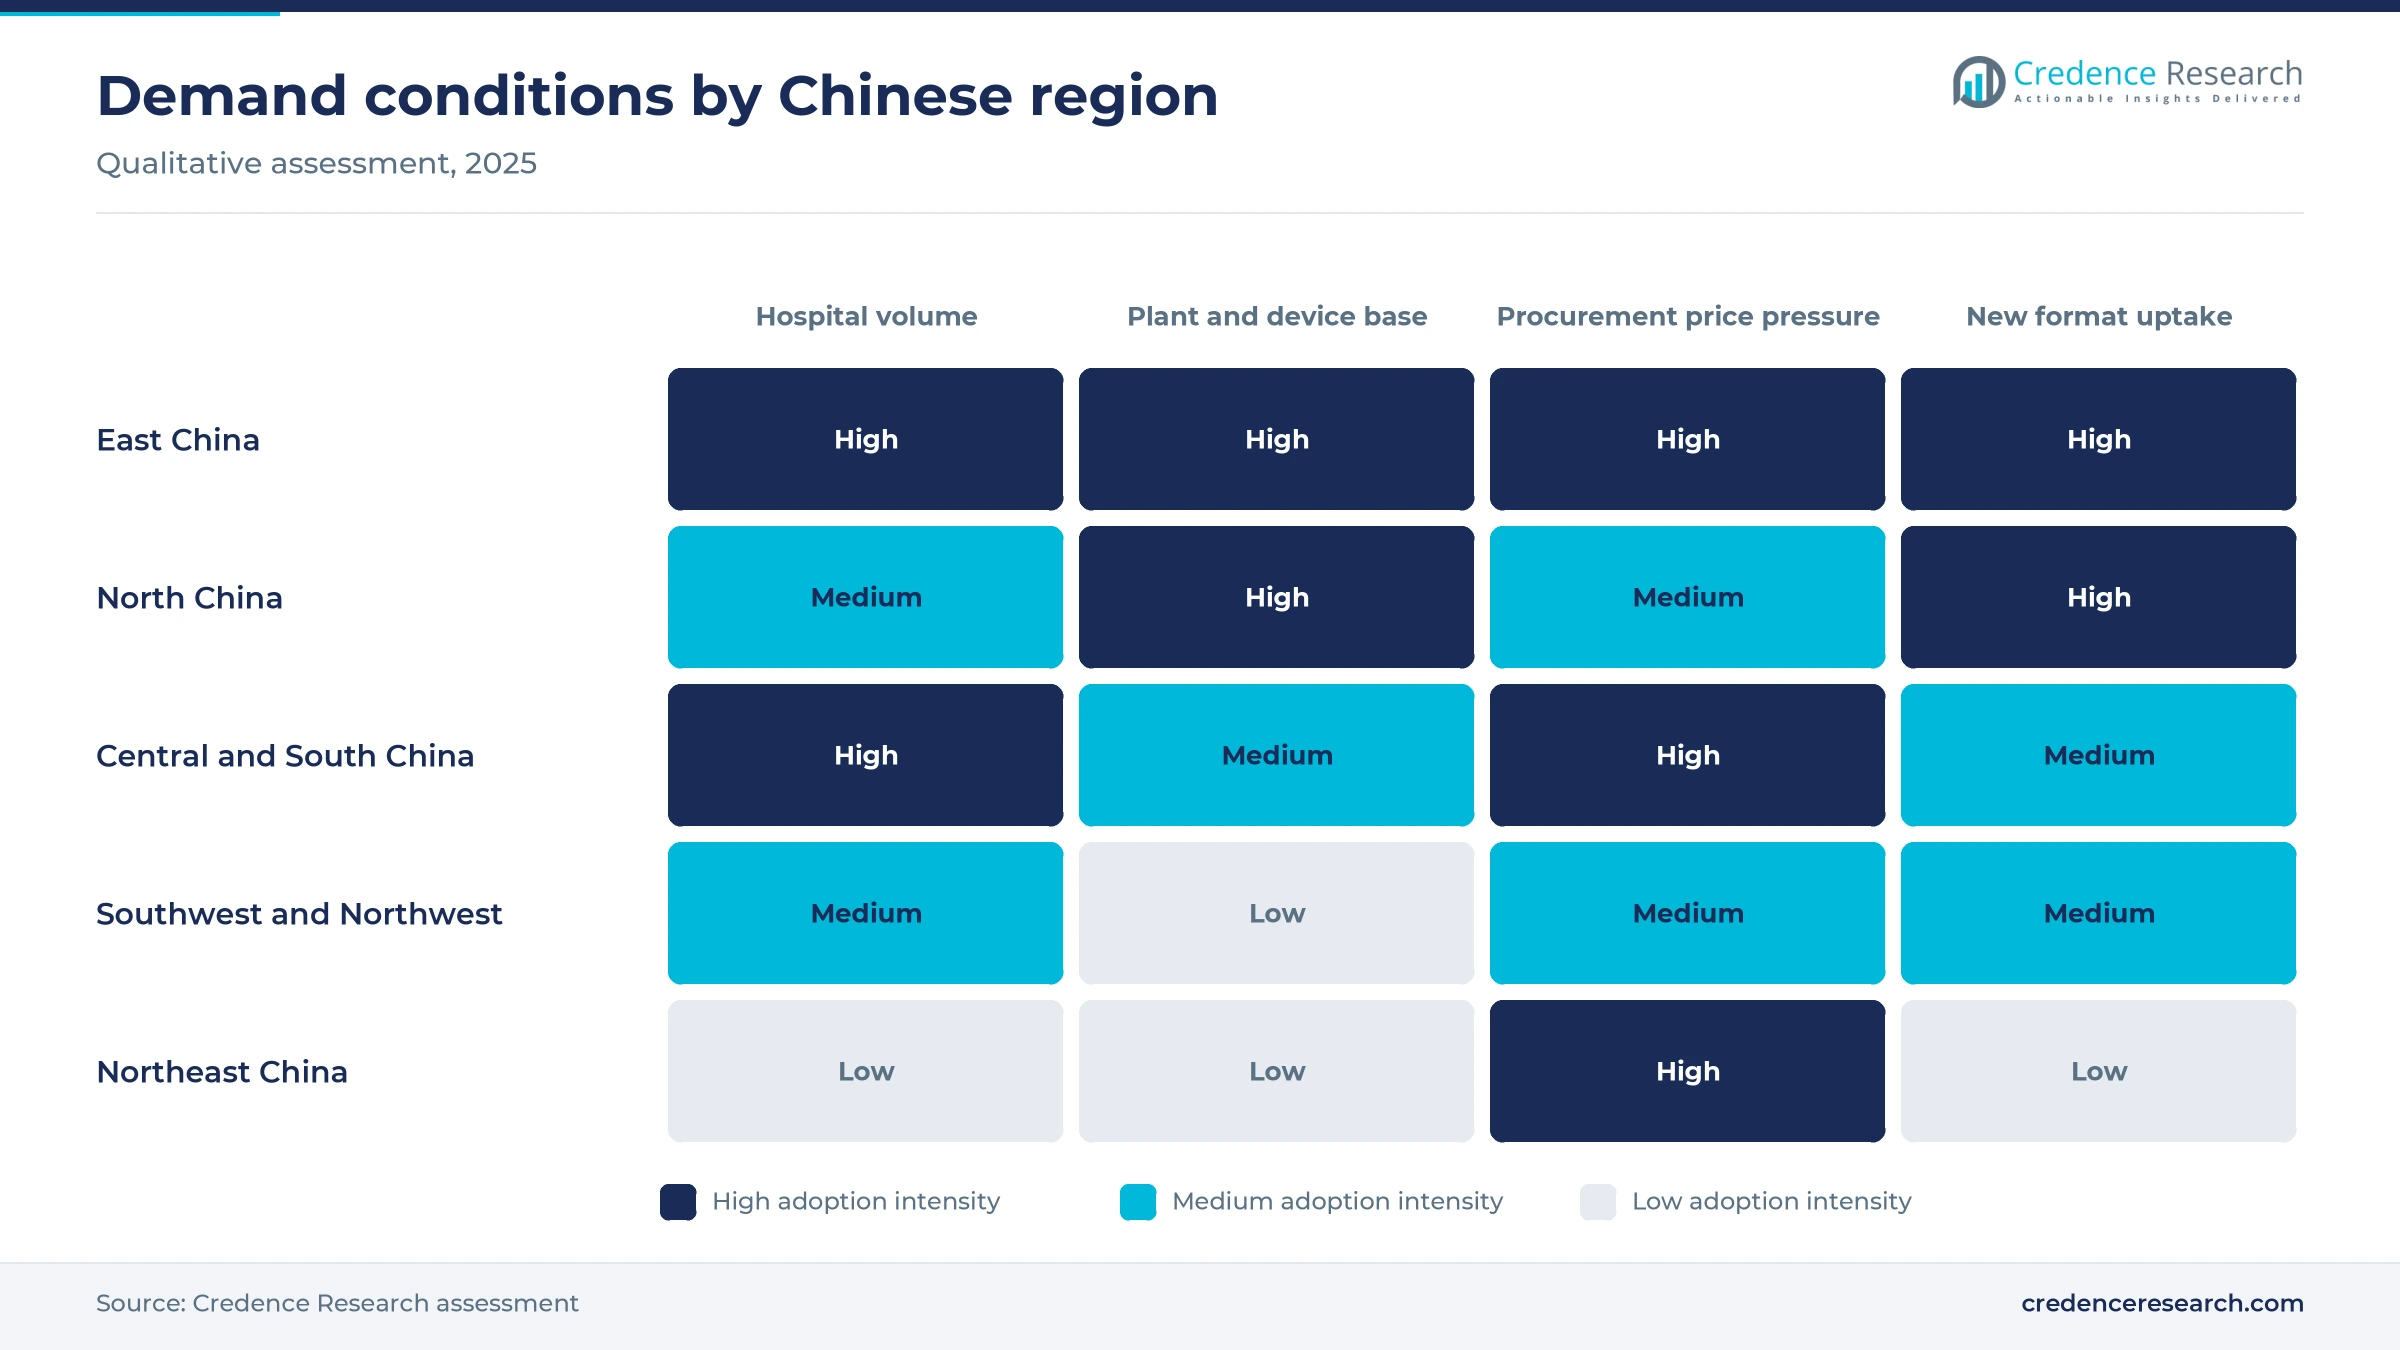
East China held 41.0% of 2025 value and grows at 5.7% a year. Jiangsu, Shanghai and Zhejiang combine dense tertiary hospital networks with the largest cluster of drug, device and packaging plants in the country. Most of the new sterile, device and packaging capacity described above sits in Jiangsu, with the inhalation base in Shandong. This concentration gives buyers short supply lines, but it also means the region feels procurement price cuts first, because its hospitals buy the largest volumes.
North China draws first launches of new biologics
North China held 15.0% of 2025 value and grows at 5.8% a year. Beijing reported CNY 1.13 trillion in pharmaceutical and healthcare industry revenue in 2025, according to the city government, and its research hospitals run many first uses of new injectables. Tianjin hosts Novo Nordisk's sterile production base, where TEDA expects total investment to exceed CNY 10 billion. Demand in North China leans toward high-value biologics and specialist hospital care, which supports injectable formats more than retail tablets.
Central and South China add volume and filling capacity
Central and South China held 25.0% of 2025 value and grows at 6.2% a year. Guangdong aims to lift its biopharmaceutical and health industry cluster above CNY 1 trillion by 2027, and Guangzhou hosts more than 6,500 biopharmaceutical companies, China Daily reported in July 2026. Akeso runs a filling line of more than 20,000 bottles an hour at its Zhongshan site. Large populations in Henan, Hubei and Hunan add hospital demand, although tenders such as the 55-medicine 2025 procurement batch keep much of that volume low in price.
The inland west grows fastest as access widens
Southwest and Northwest China held 13.0% of 2025 value and is the fastest-growing region at 6.7% a year. Chengdu's health industry passed CNY 400 billion in 2025, and its Tianfu International Bio-Town hosted more than 500 biomedical companies by the end of that year, according to a report carried by Eastmoney. Sichuan-based Kelun makes infusions and won the rotigotine patch approval noted above. Provincial platforms in Yunnan and Sichuan carried the cut-price Wegovy pens in December 2025, which shows that inland hospitals can buy new formats on the same terms as coastal ones.
Northeast China leans on procured chronic medicines
Northeast China held 6.0% of 2025 value and grows at 5.0% a year, the slowest of the five regions. Demand here leans toward procured chronic medicines rather than new biologics, because the region's population is older and its tertiary hospital capacity is thinner than on the coast, a Credence Research estimate with a wide error range. Tonghua Dongbao in Jilin, named by Fierce Pharma as a domestic winner in the first national insulin tender, has had its insulin aspart application accepted for review by the U.S. FDA, China Daily reported in May 2026. Local producers therefore look to exports while procurement holds domestic insulin prices down.
Approvals and plant moves in 2025 reset the field
| Development | Status and market relevance |
|---|---|
| In June 2025, the NMPA approved Innovent's mazdutide for chronic weight management, and Ypsomed said in July 2025 that it launched in a YpsoMate autoinjector. | Approved and launched; the first dual GCG and GLP-1 receptor agonist on the Chinese market. |
| In November 2025, AstraZeneca announced a further $136 million for its Qingdao inhaled medicines base at the China International Import Expo. | Investment announced; the site is expected to come online in 2028. |
| In December 2025, Sino Biopharmaceutical won NMPA approval for its rotigotine transdermal patch for Parkinson's disease. | Approved; it is the second patch from the company after rivastigmine in 2024. |
| In December 2025, CSPC won NMPA approval for Duoenyi irinotecan liposome injection as a first-line treatment for metastatic pancreatic cancer. | Approved; the second indication after a September 2023 approval for second-line use. |
| In February 2026, the NMPA accepted Jiuyuan Gene's marketing application for a weight-management semaglutide. | Under review; one of the first domestic copies filed before the March 2026 patent expiry. |
Pens, liposomes, depots and patches compete on adherence
- Prefilled pens and autoinjectors let patients inject weekly or daily at home, which moves chronic therapy out of hospitals and supports adherence.
- Liposomes and lipid nanoparticles carry cancer drugs such as irinotecan to tumors with less exposure of healthy tissue, which supports premium hospital pricing.
- Long-acting microsphere and depot injections release antipsychotics and hormones over weeks, which cuts missed doses in psychiatry and oncology.
- Transdermal matrix patches deliver steady doses through the skin for 24 hours, which avoids first-pass liver metabolism in Parkinson's and dementia care.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Originators and device makers compete on hard-to-copy forms
Competition in the China pharmaceutical drug delivery market turns on owning formats that procurement tenders cannot easily copy, more than on tablet prices. Hengrui, CSPC, Sino Biopharmaceutical and Fosun compete through broad hospital portfolios and platforms in liposomes, patches and biologics, while Innovent focuses on incretin injections and Luye and Livzon on long-acting microsphere injections. AstraZeneca, Novo Nordisk and Eli Lilly defend inhaler, insulin and incretin positions with local plants and price cuts. Kelun competes on large-volume infusion scale and its newly approved patches. Ypsomed and Gerresheimer supply autoinjectors, pens and glass packaging to both groups, so their wins follow the drugmakers that gain share. Domestic firms also license molecules abroad, and NMPA counted 157 out-licensing deals worth $135.7 billion in 2025, which funds further platform work.
How is the supply side organized and where do margins sit?
Supply is organized in three layers that meet in hospital tenders. Multinational originators such as AstraZeneca, Novo Nordisk and Eli Lilly hold strong positions in inhalers, insulin and incretin pens, and are expanding local plants. Domestic originators such as Hengrui, CSPC, Sino Biopharmaceutical, Fosun, Innovent, Luye and Livzon build platforms in liposomes, patches, long-acting injectables and biologics, while generic and infusion makers such as Kelun compete in tenders. Device and packaging suppliers such as Ypsomed and Gerresheimer sit upstream as a separate supply market counted here only inside drug prices. Entry barriers are low for plain tablets and high for sterile biologics, depots and inhalers, so margins sit with differentiated formats and with device platforms qualified into approved drug files.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Jiangsu Hengrui Pharmaceuticals Co., Ltd. | Domestic originator | Injectable cancer, metabolic and cardiovascular medicines sold mainly through hospitals |
| CSPC Pharmaceutical Group Limited | Domestic originator | Liposomal and nanoparticle injectables, including Duoenyi irinotecan liposome |
| Sino Biopharmaceutical Limited | Domestic originator | Rivastigmine and rotigotine patches plus cancer and liver injectables |
| Shanghai Fosun Pharmaceutical (Group) Co., Ltd. | Diversified drugmaker | Injectables, oral generics and licensed biologics across hospital channels |
| AstraZeneca PLC | Multinational originator | Inhaled respiratory medicines made in China and oral cancer drugs |
| Novo Nordisk A/S | Multinational originator | Insulin and semaglutide prefilled pens with a sterile base in Tianjin |
| Eli Lilly and Company | Multinational originator | Tirzepatide pens and insulin supplied under national procurement |
| Innovent Biologics, Inc. | Biologics originator | Mazdutide autoinjector and antibody injectables for hospital oncology |
| Luye Pharma Group Ltd. | Specialist | Long-acting injectables, including monthly paliperidone palmitate |
| Sichuan Kelun Pharmaceutical Co., Ltd. | Infusion and generic maker | Large-volume infusions, generics and a rotigotine patch approved in 2025 |
| Livzon Pharmaceutical Group Inc. | Domestic specialist | Long-acting microsphere injectables, including three-month leuprorelin 11.25 mg approved September 2026 |
Value is moving to formats that procurement cannot copy
Credence Research's view is that value in China is moving from the molecule alone to the format that delivers it. Procurement will keep pushing plain tablets and injections toward cost, so growth comes from pens, patches, depots, liposomes and inhalers that tenders treat as distinct products. Domestic originators have moved fastest, while multinationals defend share with local plants and lower prices. Buyers should expect more choice and lower prices in incretin pens after 2026, and suppliers should secure local device and packaging capacity before the next wave of biologics approvals.
Estimates rebuilt from distribution and price data
The report uses 2025 as the base year and forecasts value for 2026 to 2035. Market values come from the Credence Research model, which starts from national pharmaceutical distribution sales, removes non-terminal and non-medicine value, converts terminal value to manufacturer prices and checks the result against approvals, procurement and price data. This edition replaces an earlier estimate with a 2023 base year. Segment and regional splits are Credence Research estimates built from the same inputs. Sources include the National Bureau of Statistics, ministry and regulator releases, company releases and news reports, and no interviews or surveys were conducted.
Value rises steadily as chronic care moves home
Value should rise from USD 128.65 billion in 2026 to USD 215.51 billion by 2035, as an aging population adds chronic dosing and new biologics enter the reimbursement list. Injectables, which held 45.0% of 2025 value, will stay the largest route, while inhalers, patches and long-acting injections gain share in demand. Home care and retail channels will take more refills, helped by pharmacy reimbursement reforms. Domestic incretin pens after the 2026 patent expiry will raise volumes but cut prices, so suppliers with local device and fill-finish capacity will gain most. Deeper procurement cuts remain the main risk to the forecast.
How wide is the range of outcomes to 2035?
The outcome depends on how deep procurement cuts go and how fast new formats replace procured generics. Faster reimbursement of new biologics and broad uptake of domestic incretin pens would push growth toward the upside. Deeper cuts in later procurement rounds, slower insurance funding and a price war in weight-management pens would hold value near the downside. The aging population sets a floor under volumes, which limits how far growth can fall.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 3.9% | USD 181.53 billion | Procurement cuts deepen and pen prices collapse faster than volumes grow |
| Base | 5.90% | USD 215.51 billion | Procurement continues at its recent pace while new formats gain reimbursement |
| Upside | 7.4% | USD 244.59 billion | Faster listing of biologics and broad uptake of domestic incretin pens |
Frequently Asked Questions
How big is the China pharmaceutical drug delivery market?
Which route of administration leads in China?
How big is the transdermal drug delivery segment in China?
How does volume-based procurement affect drug delivery prices?
Which companies lead drug delivery in China?
How much do GLP-1 pens cost in China?
Which region of China leads demand?
What happens after the semaglutide patent expiry in China?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Route of Administration
- 1.2.1 Injectable Drug Delivery
- 1.2.2 Solid Oral Drug Formulation
- 1.2.3 Liquid Drug Formulation
- 1.2.4 Topical and Transdermal Drug Delivery
- 1.2.5 Inhalation and Other Routes
- 1.3 By Application
- 1.3.1 Cancer
- 1.3.2 Cardiovascular Diseases
- 1.3.3 Infectious Disease
- 1.3.4 Diabetes
- 1.3.5 Respiratory Diseases
- 1.3.6 Others
- 1.4 By End User
- 1.4.1 Hospitals
- 1.4.2 Ambulatory Clinics and Primary Care
- 1.4.3 Home Care Settings
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 121.48 billion → 2035: USD 215.51 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 China Pharmaceutical Drug Delivery Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 China Pharmaceutical Drug Delivery Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 China Pharmaceutical Drug Delivery Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 China Pharmaceutical Drug Delivery Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 China Pharmaceutical Drug Delivery Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 China Pharmaceutical Drug Delivery Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 China Pharmaceutical Drug Delivery Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 China Pharmaceutical Drug Delivery Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 121.48 billion → 2035: USD 215.51 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 China Pharmaceutical Drug Delivery Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Route of Administration - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Injectable Drug Delivery
- 12.3.7.2 Solid Oral Drug Formulation
- 12.3.7.3 Liquid Drug Formulation
- 12.3.7.4 Topical and Transdermal Drug Delivery
- 12.3.7.5 Inhalation and Other Routes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cancer
- 12.4.7.2 Cardiovascular Diseases
- 12.4.7.3 Infectious Disease
- 12.4.7.4 Diabetes
- 12.4.7.5 Respiratory Diseases
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 Ambulatory Clinics and Primary Care
- 12.5.7.3 Home Care Settings
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 China Pharmaceutical Drug Delivery End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 China Pharmaceutical Drug Delivery Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 China Pharmaceutical Drug Delivery Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 China Pharmaceutical Drug Delivery Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Jiangsu Hengrui Pharmaceuticals Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 CSPC Pharmaceutical Group Limited
- 18.4 Sino Biopharmaceutical Limited
- 18.5 Shanghai Fosun Pharmaceutical (Group) Co., Ltd.
- 18.6 AstraZeneca PLC
- 18.7 Novo Nordisk A/S
- 18.8 Eli Lilly and Company
- 18.9 Innovent Biologics, Inc.
- 18.10 Luye Pharma Group Ltd.
- 18.11 Sichuan Kelun Pharmaceutical Co., Ltd.
- 18.12 Livzon Pharmaceutical Group Inc.
- 18.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

