
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Drug Delivery Technologies Market Size 2023 | USD 44,154.8 Million |
| Drug Delivery Technologies Market, CAGR | 13.50% |
| Drug Delivery Technologies Market Size 2032 | USD 138,019.58 Million |
Market Insights
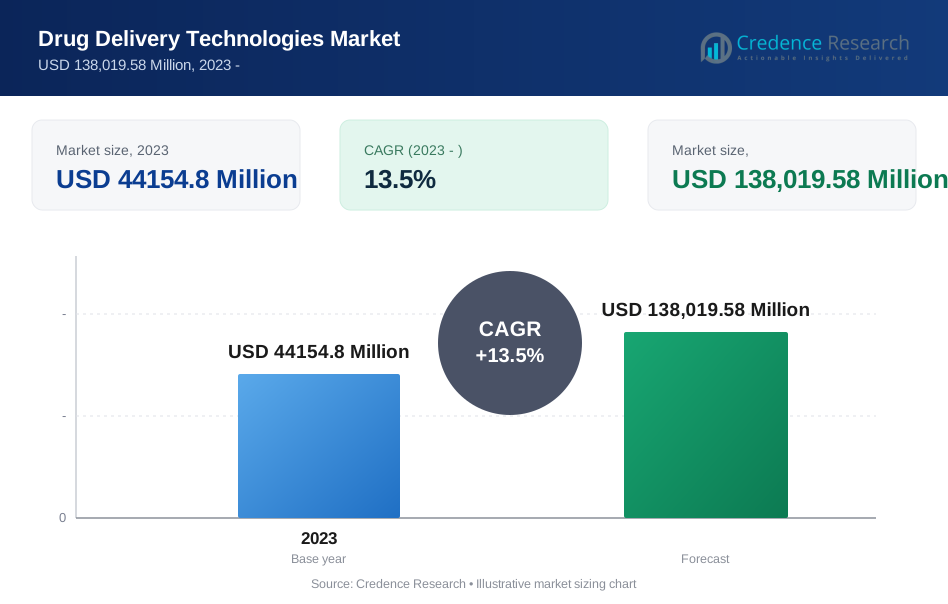
- The global Drug Delivery Technologies Market reached a valuation of USD 44,154.8 Million in 2023 and is anticipated to surge to USD 138,019.58 Million by 2032, exhibiting a robust CAGR of 13.50% from 2024 to 2032.
- Among the key segments, Injectable Drug Delivery emerged as the market leader by route of administration, constituting more than 35% of the total market value in 2023. However, Pulmonary Drug Delivery is expected to experience rapid growth throughout the forecast period.
- Hospitals and Clinics segment holds around 60% of the market share owing to the large number of patients treated in hospitals leads to a higher demand for various drug delivery technologies.
- Cancer Therapies represent the fastest-growing application segment, while Diabetes Management holds a significant market share of around 25% in 2023.
- Advanced Oral Drug Delivery Technologies are expected to witness the highest growth rate, while Injectable Drug Delivery Technologies maintain dominance, constituting a 55% share of the market in 2023.
- North America accounting for more than 35% of the market share in 2023, followed by Asia-Pacific and Europe with a collective share of just under 55%, Europe held over 20% share in 2023.
- The rise in chronic diseases and limitations in existing drug delivery methods, such as their efficacy and patient compliance, fuel the demand for advanced Drug Delivery Technologies, augmenting growth prospects.
- Key opportunities in the market include the significant growth potential in North America, increased adoption in healthcare facilities, and innovative distribution approaches, fostering market expansion.

Executive Summary
Market Definition
The drug delivery technologies market involves the creation and sale of various tools and methods that help deliver medication to the body in a precise and efficient way. These technologies can improve the effectiveness of treatments and reduce negative side effects. Examples of drug delivery technologies include tiny particles called nanoparticles, liposomes, transdermal patches, and inhalers. These technologies help get medicine to the right place in the body at the right time, making treatments more effective and easier to manage.
Market Overview
The Drug Delivery Technologies Market has demonstrated consistent growth in recent years and is projected to maintain a robust CAGR of 13.50% between 2024 and 2032. In 2023, the market valuation stood at USD 44,154.8 million, with expectations to soar to USD 138,019.58 million by 2032.
A primary driver propelling the growth of the Drug Delivery Technologies Market is the escalating demand for enhanced drug delivery systems. This surge is fueled by limitations in existing drug administration methods, such as efficacy concerns and patient compliance, augmenting the need for more precise and efficient drug delivery platforms.
The increased prevalence of chronic diseases necessitates advanced drug delivery mechanisms, intensifying the market's expansion. Moreover, the versatility and reliability of drug delivery technologies, catering to specific medical requirements, further drive market growth, especially in targeted drug delivery for various therapeutic applications.
The growing biologics market and increasing demand for advanced drug delivery systems are driving the growth of the drug delivery technologies market. Key factors contributing to this growth include the development of new drugs and biologics, which require advanced delivery systems to maximize efficacy and minimize side effects. Additionally, advancements in understanding human biology and diseases enable the development of more targeted and effective drug delivery systems.
Segmentation by Route of Administration
- Oral Drug Delivery segment dominates the market in 2023, holding around 60% of the total market share. This dominance is due to convenience and ease of administration, Cost-effectiveness, and Versatility.
- Pulmonary Drug Delivery segment is expected to be the fastest-growing, with a prominent CAGR between 2023 and 2032. Chronic obstructive pulmonary disease (COPD) and asthma are on the rise globally, creating a strong demand for effective pulmonary drug delivery systems.
- cular Drug Delivery is relatively smaller segment presents significant potential for delivering drugs to the eye for treating chronic conditions like glaucoma and macular degeneration. Technological advancements in nanoparticles and microfluidic devices are expected to drive future growth.
Segmentation by Drug Delivery Systems
- Polymer-Based Drug Delivery Systems dominates the market with around 45% share. Polymers offer versatility, controlled release, and targeted delivery, making them a popular choice for various drugs.
- Nanoparticle Drug Delivery segment is expected to grow at a significant CAGR due to its ability to deliver drugs directly to target cells, improving efficacy and reducing side effects.
- Microencapsulation technique protects sensitive drugs and targets specific areas but has a relatively smaller market share and a moderate CAGR.
Segmentation by Technology Platform
- Injectable Drug Delivery Technologies dominates with around 55% market share. IThis dominance is due to Precision delivery like injectables offer targeted delivery to specific organs or tissues for optimal drug efficacy.
- Advanced Oral Drug Delivery Technologies segment is expected to see the fastest growth, with a significant CAGR. Factors driving this include Overcoming oral drug limitations, Improved patient compliance, and others.
Segmentation by Application
- Cancer Therapies dominates the market with around 25% share in 2023. The increasing prevalence of various cancers creates a continuous demand for innovative drug delivery solutions.
- Diabetes Management segment is expected to witness the fastest growth with a prominent CAGR owing to the increasing prevalence of diabetes worldwide creates a significant market for effective glucose control solutions.
Segmentation by End-User
- Hospitals and Clinics segment holds around 60% of the market share owing to the large number of patients treated in hospitals leads to a higher demand for various drug delivery technologies.
- Homecare Settings segment is expected to grow at fastest CAGR due to several factors such as increasing number of elderly individuals and patients with chronic illnesses creates a need for convenient and self-administered drug delivery options.
Segmentation by Biologics Delivery
- Monoclonal Antibodies (mAbs) Delivery segment holds largest market share over 25% in 2023. This is primarily driven by the booming market for therapeutic antibodies in treating various diseases, including cancer, autoimmune disorders, and infectious diseases.
- Protein and Peptide Delivery segment is expected to grow at significant CAGR.
Segmentation by Patient Age Group
- Geriatric population is projected to boast the fastest CAGR in the forecast period. This rapid expansion is fueled by the number of people aged 65 and above is expected to double by 2050 said World Bank, creating a significant market for age-specific medication delivery solutions.
- Adults holds approx 60-65% market share of the drug delivery market, owing to their larger population, chronic disease burden, and wider range of medication options like injectables, tablets, and patches.
Segmentation by Region
- North America Leading the growth trajectory of the Drug Delivery Technologies Market with a market share of over 35% in 2023. This growth is propelled by robust developments in pharmaceutical and biotech sectors, increased healthcare expenditure, and technological advancements. The region's focus on innovation and research further drives market expansion.
- Asia Pacific and Europe Collectively accounting for just under 55% share in 2023, with Europe securing over 20% share in the same year. Asia Pacific exhibits notable growth driven by rising healthcare infrastructure development, expanding pharmaceutical industries, and increasing adoption of advanced drug delivery systems. Europe, with its strong emphasis on healthcare innovation and research, remains a significant contributor to the market.
- Rest of the World (Latin America, Middle East, and Africa): Contributes to the remaining demand for Drug Delivery Technologies. These regions show increasing interest in adopting advanced healthcare solutions, driving the demand for innovative drug delivery systems. The growth is supported by the rising prevalence of chronic diseases and efforts to improve healthcare accessibility.
The advanced drug delivery market has seen an increase in collaborations and partnerships among key players, which is expected to further drive the growth of the market. This drives the increased adoption of advanced drug delivery systems globally, amplifying the market's growth across different regions.

North America is expected to dominate the global Drug Delivery Technologies market in 2023. The dominant share of the region is attributed to well-developed healthcare infrastructure, significant growth in biologics in the pharmaceutical market and presence of key players across the regions such as 3M Co., Baxter International, Inc., and Boston Scientific Corp., among others. Moreover, increasing prevalence of chronic disorders such as cancer, CVDs, diabetes, and COPD is further augmenting the growth of the market in North America.
The Asia Pacific is anticipated to witness the fastest growth in the market owing to the increasing number of patients with skin disease and technological advancements, innovations along with the rising contribution of players in expansion and new launches. For instance, in July 2020, Teva Pharmaceuticals Industries Ltd., with Takeda, a joint business venture expanded its presence in Japan, which focuses on commercializing complex generics, specialty assets, and other offers pipeline opportunities under its new strategy for its local commercial operations. Furthermore, the growing awareness about the advantages offered by transdermal medicine demand is increasing in emerging countries such as India, Japan, and China among others are other factors contributing to the growth of the market.
Key Highlights of the Report
The global Drug Delivery Technologies market is segmented by Route of Administration, Patient Age Group, Biologics Delivery, End-User, Application, Technology Platform,Drug Delivery Systems, Route of Administration, and region. The demand for advanced drug delivery technologies is surging due to the escalating need for precise and efficient drug administration in pharmaceutical and biotechnology sectors. This demand is driven by the limitations in existing drug delivery methods, enhancing the growth of this market.
The market is segmented by route of administration, drug delivery systems, technology platform, end-users, biologics delivery, patient age group, and region, reflecting the diverse applications and targeted approaches within the drug delivery technologies sector.
Injectable drug delivery technologies dominate the market, offering precise and targeted delivery to specific organs or tissues, followed by a significant rise in advanced oral drug delivery technologies, aiming to overcome limitations in oral drug administration.
Hospitals and clinics constitute a substantial user segment, while homecare settings are projected to witness rapid growth, indicating a shift towards convenient self-administered drug delivery options.
North America leads the market growth, housing key players like 3M Co., Baxter International, Inc., and Boston Scientific Corp., attributed to a well-developed healthcare infrastructure and increasing prevalence of chronic disorders.
What Are The Main Drivers Of The Global Drug Delivery Technologies Market?
The main drivers of the global drug delivery technologies market include the increasing prevalence of chronic diseases, growing patient compliance with innovative drug delivery technologies, and rising research and development (R&D) investments in the field. Additionally, the market is being driven by the presence of prominent players in the pharmaceutical industry, the adoption of advanced technology for effective drug delivery, and the growing importance of developing patient-compliant drug delivery systems. Furthermore, the market is expected to grow at a significant CAGR due to the rising demand for drug delivery devices and the increasing investment in R&D by pharmaceutical companies.
What Are The Major Challenges Faced By The Global Drug Delivery Technologies Market?
The global drug delivery technologies market faces several challenges, including the high cost of drug delivery devices, the stringent regulatory requirements for drug delivery devices, and the lack of awareness about the benefits of drug delivery technologies among patients and healthcare professionals.
What Are The Growth Opportunities In The Global Drug Delivery Technologies Market?
The global drug delivery technologies market presents several growth opportunities, including the increasing adoption of advanced technology for effective drug delivery, the rising demand for drug delivery devices, and the growing importance of developing patient-compliant drug delivery systems.
Market Drivers
The global Drug Delivery Technologies market is driven by several factors. The following are the key drivers of the global Drug Delivery Technologies market:
Surging Prevalence of Chronic Diseases
Surging prevalence of chronic diseases such as cancer, CVDs, and diabetes, among others are expected to drive the demand for pharmaceutical drugs, which in turns, augments the growth of pharmaceutical drug delivery system market. Increasing prevalence of CVDs is estimated to be one of the major factors that are driving the growth of the market across the globe. As per the World Health Organization (WHO), CVDs are estimated as one of the major causes of mortality across the globe, accounting for more than 17.3 million mortality per year. Further, the number of mortalities by CVDs is estimated to reach 23.6 million by 2030. CVDs account for 31% mortalities globally, of which 80% occur in low and middle-income countries. Further, the aforementioned organization estimates that 1 in 5 men and 1 in 6 women, across the globe, develop cancer during their lifetime. Moreover, the disease has a mortality rate of nearly one in 8 men and one in 11 women.
Market Restraints
The global Drug Delivery Technologies market faces some challenges that may hinder its growth. These include the following:
Regulatory Challenges
The drug delivery technologies market may face challenges related to regulatory approvals for new products and devices, which can impact its growth. For instance, the medical device market is seen as an area with high growth potential, but it also presents significant regulatory challenges, potentially affecting market expansion. Harmonizing advanced technology development and regulatory acceptance is also a key challenge, as regulators have programs, but the process can still be complex. Additionally, the novelty and variety of implantable drug delivery systems pose regulatory challenges for registration and market approval, impacting market growth.
Additionally, the market is facing challenges due to the increasing complexity of drug molecules, which requires the development of more advanced drug delivery systems. Furthermore, the market is also facing challenges due to the shortage of skilled professionals in the field of drug delivery and the need for continuous innovation to meet the changing demands of the pharmaceutical industry.
Opportunities
The global Drug Delivery Technologies market offers significant growth opportunities. These include the following:
Technological Advancements
The development of new and advanced drug delivery systems, such as auto-injectors, jet-injectors, and syringes, is driving the growth of the drug delivery technologies market. Key market players, including Ypsomed, Medtronic, Nemera, and E3D Elcam Drug Delivery Devices, are anticipated to increase their market shares by enhancing their production capacities to meet the rising demand for drug delivery devices. Additionally, the market is witnessing advancements in nanotechnology-based carriers, targeted drug delivery, and smart drug delivery systems, further contributing to its expansion. These technological advancements are crucial in improving the efficacy and safety of drug delivery, ultimately benefiting patients and healthcare outcomes.
The introduction of new drug delivery products and devices is expected to contribute to the growth of the drug delivery technologies market. For instance, in May 2023, AstraZeneca developed cutting-edge drug delivery technologies to maximize the potential of its novel therapeutic modalities. Scientists were creating nanoparticles for targeted delivery to previously inaccessible tissue and cell targets, and exploring ways to enhance oral bioavailability of biologics. These advancements aimed to transform the efficacy of treatments and improve patient outcomes.
Competitive Landscape

Key Players
The global Drug Delivery Technologies market is highly competitive, with several key players. Some of the major players in the market and their market share are as follows:
- Johnson & Johnson Private Limited
- F.Hoffmann-La Roche AG
- Merck Sharp & Dohme Corp.
- Bayer AG
- Pfizer Inc
- Novartis AG
- 3M
- BD
- GlaxoSmithKline plc.
- Sanofi
- Antares Pharma
- generex
- EyePoint Pharmaceuticals Inc.
- Alkermes.
- Vectura Group plc
- NanoPass
- Baxter
- AstraZeneca
- Takeda Pharmaceutical Company Limited
- Others
These organizations prioritize product innovation, distribution channel expansion, and mergers and acquisitions to stay competitive.
The global Drug Delivery Technologies market's key players continually seek to stay ahead by offering new products and developments.
In November 2023, Takeda's ADZYNMA drug approved by the US FDA for treating congenital thrombotic thrombocytopenic purpura (cTTP), an ultra-rare blood clotting disorder. This approval marks a significant milestone in Takeda's 70-year legacy of driving innovation for the rare hematology community.
In June 2022, Kindeva Drug Delivery accquired iPharma Labs, to expand clinical and commercial support for dry powder and nebulized respiratory therapies. This new acquisition supports customers from early research and development through clinical and commercial manufacturing inhalation technologies for delivery to the patient to and through the lungs.
In April 2022, Catalent expanded its nasal capabilities at its Morrisville, Research Triangle Park (RTP) in North Carolina. This expansion is mainly to expand and modernize its nasal drug delivery capabilities, substantially increasing technology and capacity. Moreover, it is for the nose-to-brain drug administration, and as an alternative route for the delivery of systemic drugs, and provides several services for the development and manufacturing of unit and bi-dose nasal spray products.
Summary of Key Findings
- The increasing need for precise drug administration in pharmaceutical and biotechnology sectors is propelling the demand for advanced drug delivery technologies. This surge is driven by limitations in existing drug delivery methods, fostering growth in the market.
- Segmentation of the market is based on route of administration, drug delivery systems, technology platform, end-users, biologics delivery, patient age group, and region, showcasing the diverse applications and specialized approaches within the drug delivery technologies sector.
- Injectable drug delivery technologies dominate the market, ensuring precise and targeted delivery to specific organs or tissues, while there's a notable rise in advanced oral drug delivery technologies aiming to overcome limitations in oral drug administration.
- Hospitals and clinics constitute a significant user segment, while homecare settings are projected to experience rapid growth, signaling a shift toward convenient self-administered drug delivery options.
- North America spearheads market growth, hosting major players like 3M Co., Baxter International, Inc., and Boston Scientific Corp., owing to a well-established healthcare infrastructure and an increasing prevalence of chronic disorders.
Future Outlook
- The drug delivery technologies market showcases a positive outlook with significant growth potential in North America, driven by the pharmaceutical and biotech sectors' reliance on advanced delivery systems.
- A significant factor projected to challenge market growth during the forecast period is the increasing preference for wireless drug delivery solutions among consumers.
- Key players in the industry need to emphasize product innovation, expanding market presence, and competitive pricing strategies to stay competitive amidst market dynamics and evolving consumer preferences.
How CXOs Can Benefit from the Credence Research Drug Delivery Technologies Market Report
The Credence Research Drug Delivery Technologies Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast:The report provides detailed estimates of the global Drug Delivery Technologies market size, segmented by fiber type, network type, application, and region. It also includes forecasts for the market through 2032, based on key trends and drivers.
- Market segmentation:The report segments the Drug Delivery Technologies market by fiber type, network type, application, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape:The report profiles the key players in the Drug Delivery Technologies market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers:The report identifies and analyzes the key trends and drivers that are shaping the Drug Delivery Technologies market. This information can help CXOs to make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Drug Delivery Technologies Market Report to:
- Identify growth opportunities:The report can help CXOs to identify new growth opportunities in the Drug Delivery Technologies market. For example, the report identifies the growing demand for Drug Delivery Technologies from cloud computing providers and telecom companies as a key opportunity.
- Make informed investment decisions:The report can help CXOs to make informed investment decisions about Drug Delivery Technologies. For example, the report provides insights into the key factors to consider when evaluating dark fiber providers and selecting dark fiber solutions.
- Develop competitive strategies:The report can help CXOs to develop competitive strategies for their Drug Delivery Technologies businesses. For example, the report identifies the key strategies that dark fiber providers are using to differentiate themselves from their competitors.
- Track market developments:The report can help CXOs to track market developments and stay ahead of the curve. For example, the report provides insights into the latest trends and innovations in the Drug Delivery Technologies market.
Overall, the Credence Research Drug Delivery Technologies Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
- By Route of Administration
- Oral Drug Delivery
- Injectable Drug Delivery
- Topical Drug Delivery
- Pulmonary Drug Delivery
- Ocular Drug Delivery
- By Drug Delivery Systems
- Polymer-Based Drug Delivery Systems
- Liposomal Drug Delivery
- Nanoparticle Drug Delivery
- Microneedle Drug Delivery
- Implantable Drug Delivery Devices
- Microencapsulation
- By Technology Platform
- Advanced Oral Drug Delivery Technologies
- Inhalation Drug Delivery Technologies
- Injectable Drug Delivery Technologies
- Transdermal Drug Delivery Technologies
- By Application
- Cancer Therapies
- Diabetes Management
- Pain Management
- Autoimmune Diseases
- Neurological Disorders
- Cardiovascular Diseases
- Ophthalmic Diseases
- Infectious Diseases
- By End-User
- Hospitals and Clinics
- Ambulatory Surgical Centers
- Homecare Settings
- Research Institutes
- Biotechnology and Pharmaceutical Companies
- By Biologics Delivery
- Monoclonal Antibodies (mAbs) Delivery
- Protein and Peptide Delivery
- Vaccine Delivery
- By Patient Age Group
- Pediatric Population
- Adults
- Geriatric Population
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America
Adjacent Markets
In the Drug Delivery Technologies market, there are several adjacent markets which has high revenue growth opportunities. The key adjacent markets for Drug Delivery Technologies market

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Diseases
The increasing incidence of chronic conditions such as cancer, diabetes, and cardiovascular diseases is driving demand for advanced drug delivery technologies that can improve treatment efficacy and patient compliance.
Technological Advancements in Drug Delivery
Innovations such as nanoparticles, polymer-based systems, and smart drug delivery devices are enabling more precise, targeted, and efficient medication administration, expanding the market's potential.
Growth in Biologics and Specialty Pharmaceuticals
The expanding pipeline of biologics and complex drugs requires sophisticated delivery systems to ensure stability, bioavailability, and patient-friendly administration, boosting market growth.
Shift Toward Homecare and Self-Administration
The growing preference for home-based care and self-administered therapies, especially among elderly and chronic disease patients, is increasing demand for user-friendly and minimally invasive drug delivery solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Drug Delivery Technologies market?
What is the expected growth rate of the Drug Delivery Technologies market between 2024 and 2032?
Which segment is leading the market share in terms of Route of Administration?
Which end users segment governs the demand for Drug Delivery Technologiess in the world?
Which Patient Age Group segment is expected to post the highest CAGR during the forecast period?
Which region is fueling the growth of the Drug Delivery Technologies industry?
Who are the major players in the global Drug Delivery Technologies market?
What are the major market drivers of the Drug Delivery Technologies industry?
What are the major market restraints of the Drug Delivery Technologies industry?
What are the major market opportunities of the Drug Delivery Technologies industry?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Hospitals and Clinics
- 1.2.2 Ambulatory Surgical Centers
- 1.2.3 Homecare Settings
- 1.2.4 Research Institutes
- 1.3 By Application
- 1.3.1 Cancer Therapies
- 1.3.2 Diabetes Management
- 1.3.3 Pain Management
- 1.3.4 Autoimmune Diseases
- 1.3.5 Neurological Disorders
- 1.4 By Technology Platform
- 1.4.1 Advanced Oral Drug Delivery Technologies
- 1.4.2 Injectable Drug Delivery Technologies
- 1.4.3 Inhalation Drug Delivery Technologies
- 1.4.4 Transdermal Drug Delivery Technologies
- 1.5 By Route of Administration
- 1.5.1 Oral Drug Delivery
- 1.5.2 Injectable Drug Delivery
- 1.5.3 Topical Drug Delivery
- 1.5.4 Pulmonary Drug Delivery
- 1.5.5 Ocular Drug Delivery
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 44154.8 Million → 2032: USD 138,019.58 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Drug Delivery Technologies Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Drug Delivery Technologies Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Drug Delivery Technologies Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Drug Delivery Technologies Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Drug Delivery Technologies Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Drug Delivery Technologies Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Drug Delivery Technologies Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Drug Delivery Technologies Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 44154.8 Million → 2032: USD 138,019.58 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Drug Delivery Technologies Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals and Clinics
- 12.3.7.2 Ambulatory Surgical Centers
- 12.3.7.3 Homecare Settings
- 12.3.7.4 Research Institutes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cancer Therapies
- 12.4.7.2 Diabetes Management
- 12.4.7.3 Pain Management
- 12.4.7.4 Autoimmune Diseases
- 12.4.7.5 Neurological Disorders
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology Platform - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Advanced Oral Drug Delivery Technologies
- 12.5.7.2 Injectable Drug Delivery Technologies
- 12.5.7.3 Inhalation Drug Delivery Technologies
- 12.5.7.4 Transdermal Drug Delivery Technologies
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Route of Administration - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Oral Drug Delivery
- 12.6.7.2 Injectable Drug Delivery
- 12.6.7.3 Topical Drug Delivery
- 12.6.7.4 Pulmonary Drug Delivery
- 12.6.7.5 Ocular Drug Delivery
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Drug Delivery Technologies End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Drug Delivery Technologies Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Drug Delivery Technologies Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Drug Delivery Technologies Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Johnson & Johnson
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 F. Hoffmann-La Roche AG
- 18.4 Pfizer Inc.
- 18.5 Bayer AG
- 18.6 Novartis AG
- 18.7 3M
- 18.8 Baxter International Inc.
- 18.9 GlaxoSmithKline plc
- 18.10 Sanofi
- 18.11 AstraZeneca
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

