
Market Overview:
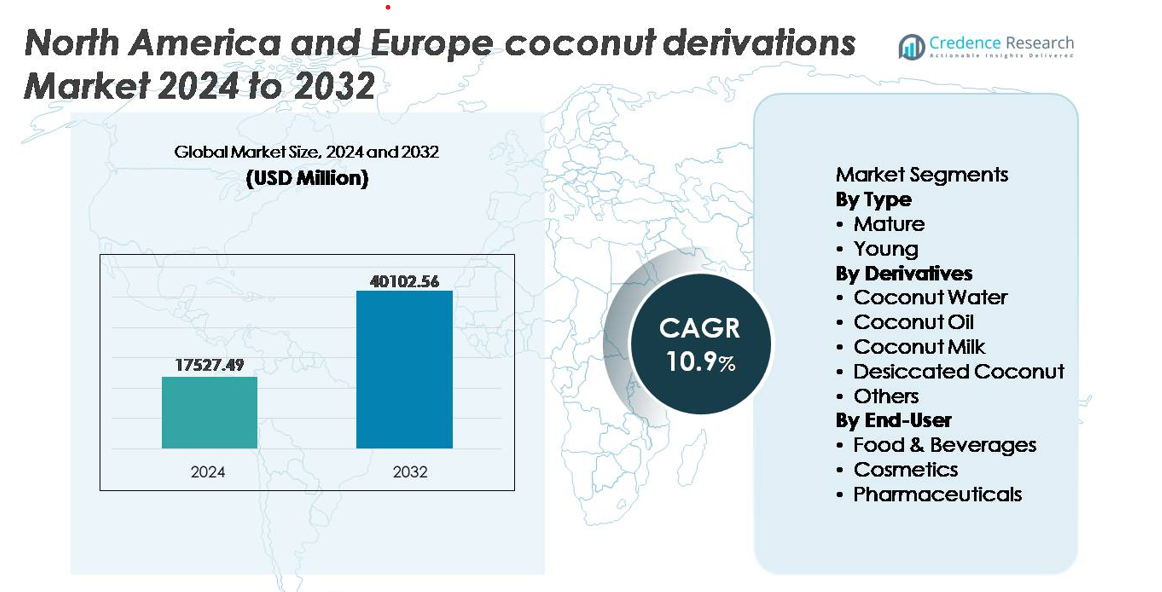
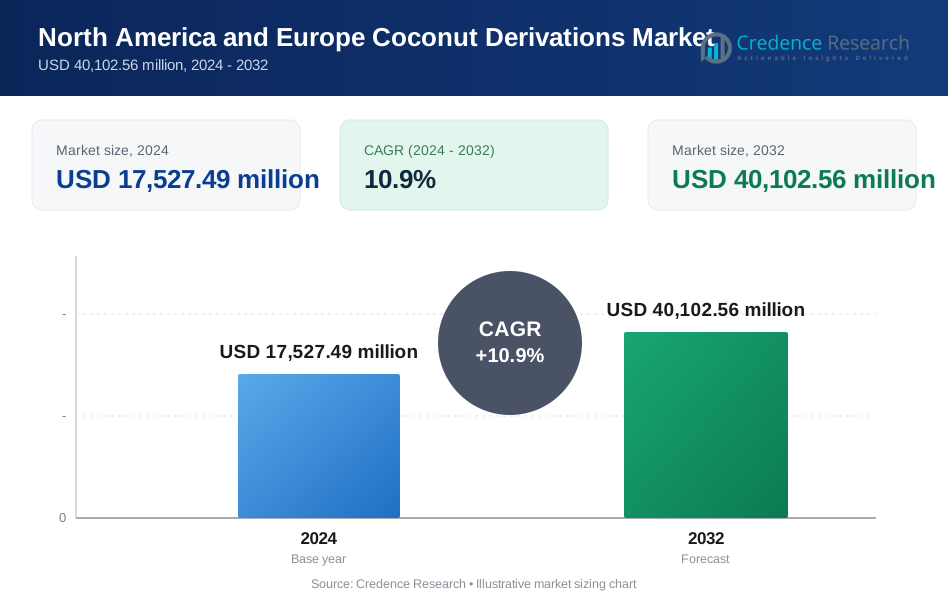
The North America and Europe coconut derivatives market was valued at USD 17,527.49 million in 2024 and is projected to reach USD 40,102.56 million by 2032, registering a compound annual growth rate (CAGR) of 10.9% over the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America and Europe Coconut Derivations Market Size 2024 | USD 17,527.49 million |
| North America and Europe Coconut Derivations Market, CAGR | 10.9% |
| North America and Europe Coconut Derivations Market Size 2032 | USD 40,102.56 million |
The competitive landscape of the North America and Europe coconut derivatives market features a mix of global beverage companies, large food-and-wellness firms, and specialized ingredient suppliers. Prominent players such as Vita Coco, McCormick & Company, Inc., Hain Celestial Group, Inc., and Danone S.A. lead in finished products, while companies like Axelum Resources Corp. and Celebes Coconut Corporation supply raw materials and bulk derivatives for food, cosmetics, and nutraceutical applications.
Regionally, North America accounts for roughly 35% of the coconut-derivatives demand in the combined North America-Europe market, driven by high consumer adoption of plant-based foods and natural ingredient personal-care products. Western Europe follows closely with an estimated 30% share, supported by strong clean-label demand, regulatory focus on natural sourcing, and rising interest in vegan-friendly beverages and dairy alternatives.These players leverage robust sourcing networks, diversified product portfolios, and broad distribution channels to cater to growing demand across food & beverages, cosmetics, and health-oriented segments-consolidating their leadership while exerting pressure on smaller niche suppliers.
Market Insights
- The North America and Europe coconut derivatives market was valued at USD 17,527.49 million in 2024 and is projected to reach USD 40,102.56 million by 2032, reflecting a CAGR of 10.9% during the forecast period.
- Growing consumer shift toward plant-based diets, clean-label products, and functional wellness beverages drives demand for coconut milk, oil, and water across food and personal care industries.
- Emerging trends include sustainable sourcing, organic-certified variants, dairy-alternative innovation, and rising use of coconut-based ingredients in nutraceutical formulations.
- The market remains moderately fragmented with key players expanding through product diversification, branding, and long-term sourcing partnerships to maintain competitive advantage.
- North America accounts for approximately 35% of demand, while Western Europe holds around 30%, with the food and beverages segment capturing the largest share due to its dominant use in plant-based foods, functional drinks, and bakery applications.
Market Segmentation Analysis:
By Type
The mature coconut segment dominates the North America and Europe coconut derivatives market, accounting for the largest share as manufacturers prefer its higher oil yield, richer nutrient density, and suitability for large-scale processing. Mature coconuts are extensively utilized for coconut oil, desiccated coconut, and coconut milk applications, ensuring steady supply for food processing and cosmetics end users. Young coconuts are gaining traction due to rising consumption of natural beverages and minimally processed ingredients; however, their lower extractable content and shorter shelf life limit industrial adoption compared to mature varieties, preserving the latter’s leadership position.
- For instance, Axelum Resources Corp. operates processing capabilities that handle over 600 metric tons of coconuts dailyat its fully integrated Medina, Misamis Oriental facility, enabling stable export volumes for coconut milk, cream, and desiccated coconut.
By Derivatives
Coconut oil represents the dominant derivative, driven by its versatile application in food preparation, plant-based ingredient formulations, organic personal care, and aromatherapy products. Demand for cold-pressed and virgin coconut oil continues to accelerate owing to clean-label preferences and expansion of plant-based consumer categories. Coconut water and coconut milk remain fast-growing segments supported by hydration beverages and dairy-alternative demand. Desiccated coconut holds steady demand from bakery, confectionery, and packaged food producers, while “others,” including coconut flour and sugar, gain momentum as gluten-free and natural sweetener substitutes become mainstream.
- For instance, Hain Celestial Group produces branded coconut-derived grocery and personal care products through operations serving more than 70 countries, supported by manufacturing capabilities across North America and Europe that enable large-scale coconut oil distribution for retail and wholesale channels.
By End-User
The food and beverages segment holds the largest market share, driven by the rising integration of coconut ingredients into bakery goods, dairy alternatives, snacks, sports drinks, and functional beverages. Health-conscious consumers continue to drive demand for coconut-based hydration and plant-derived ingredients. The cosmetics sector demonstrates strong growth as manufacturers incorporate coconut derivatives into haircare, skincare, and natural emollient products. Pharmaceutical end users expand steadily, leveraging coconut oil and medium-chain triglyceride ingredients in drug delivery, dermatological formulations, and nutraceutical products, supported by the sector’s shift toward botanical and biocompatible raw materials.
Key Growth Drivers:
Growing Consumer Shift Toward Plant-Based, Functional, and Clean-Label Ingredients
The increasing adoption of plant-derived and nutritionally enriched ingredients stands out as a key driver for coconut derivatives demand across North America and Europe. Consumers prioritize products perceived as natural, allergen-free, and minimally processed, benefiting segments such as coconut water, milk, flour, and virgin oil. The rise of veganism and flexitarian diets further accelerates the use of coconut derivatives as dairy alternatives in yogurt, ice cream, and creamers. Functional nourishment trends drive coconut water’s use in hydration beverages due to its naturally occurring electrolytes, while coconut-based oils gain traction as alternatives to trans-fat heavy ingredients in food applications. Clean-label mandates and the removal of synthetic additives push manufacturers to utilize coconut derivatives as natural flavor carriers, emulsifiers, and moisturizers in F&B and personal care formulations. This plant-forward preference aligns with sustainability-linked procurement, strengthening the market outlook.
- For instance, Danone North America operates large-scale plant-based and dairy manufacturing facilities. For instance, its Minster, Ohio plant alone has the capacity to produce over 5 million total yogurt cups or bottle servings a dayacross over 200 different products, including major plant-based brands like Silk and So Delicious, reinforcing strong market demand for both dairy and plant-based alternatives.
Expanding Utilization Across Cosmetic and Personal Care Product Formulations
Cosmetic and personal care manufacturers increasingly integrate coconut-based derivatives due to their emollient, moisturizing, antimicrobial, and conditioning properties. Coconut oil remains a staple ingredient in haircare, skincare, and natural cosmetics, driven by consumer perception of botanical solutions being gentler and safer than synthetic alternatives. The premiumization of personal grooming products reinforces demand for virgin, cold-pressed, and organic coconut oils and extracts. Growth in bar soaps, solid shampoos, and sustainable packaging formats enhances the use of coconut-derived surfactants and fats in anhydrous formulations. Additionally, coconut-based MCTs and bioactive compounds contribute to high-value cosmeceuticals targeting anti-aging and scalp health. Rising clean beauty standards, reduced paraben usage, and traceability requirements further improve adoption rates in Europe’s regulated cosmetic industry.
- For instance, Axelum Resources Corp. supplies coconut-derived ingredients to several global personal-care brands, backed by manufacturing capabilities that process over 600 metric tons of raw coconuts dailyto support large-scale skincare and haircare production requirements.
Growing Adoption in Pharmaceutical, Nutraceutical, and Therapeutic Applications
Pharmaceutical and nutraceutical segments leverage coconut derivatives for excipient, carrier oil, and functional health applications. Medium-chain triglycerides derived from coconut oil are used in controlled drug delivery systems owing to their rapid absorption and metabolization characteristics. Nutraceuticals incorporate coconut derivatives into immunity-supporting supplements, digestive aids, and brain-health formulations, aligning with preventive wellness trends. In topical therapeutics, coconut oil’s antimicrobial and anti-inflammatory attributes support dermatological and wound-care products. As the pharmaceutical sector shifts toward biocompatible and plant-origin excipients, coconut-based materials offer compatibility with regulatory and sustainability expectations. Product development initiatives in medical nutrition and ketogenic therapies further reinforce long-term demand.
Key Trends & Opportunities:
Rising Demand for Sustainable, Ethical, and Traceable Ingredient Supply Chains
Sustainability-led branding strategies unlock opportunities for coconut derivative manufacturers that emphasize ethical sourcing, reduced carbon impact, and smallholder farmer partnerships. Europe’s evolving ESG criteria and North America's growing awareness of environmental footprints encourage companies to certify origin, reduce waste, and adopt circular packaging formats. Opportunities arise in regenerative farming, water-efficient processing, and co-product valorization such as coconut husk fiber for industrial applications. Traceability platforms leveraging blockchain or digital supply chain mapping provide transparency, enabling brand differentiation. This trend positions coconut derivatives favorably compared to synthetic and petroleum-based alternatives, especially in premium F&B and cosmetic categories.
- For instance, Vita Coco’s long-term farmer-support initiative has distributed more than 1,000,000 coconut seedlings globally and funded the construction of over 30 clean water facilities in farming communities, improving sustainability credentials and securing long-term coconut supply.
Innovation in Value-Added Derivatives, Specialty Ingredients, and Product Differentiation
A shift toward specialty and premiumized coconut derivatives creates opportunities for product innovation, including coconut-based sweeteners, concentrates, protein powders, and fermented products. Demand for lactose-free, gluten-free, and allergen-friendly applications supports coconut flour and milk powder proliferation in bakery mixes and ready-to-eat foods. The evolving plant-based foods sector drives the requirement for enhanced texture and flavor profiles that coconut derivatives can deliver in dairy analogs and frozen desserts. Specialty-grade oils and tailored MCT compositions present high-margin opportunities in sports nutrition, nootropic supplements, and medical diets. Manufacturers innovating in formulation-friendly, shelf-stable, and organic-certified variants are positioned for accelerated uptake.
- For instance, Axelum Resources Corp. expanded its product portfolio to include coconut-derived MCT oil ingredients, enabling the production of more than 3,000 metric tons annually for use in sports nutrition and ketogenic product formulations.
Key Challenges:
Volatility in Raw Material Availability and Procurement Costs
Supply chain instability poses a major challenge, as production is heavily concentrated in tropical regions prone to changing climate patterns, cyclones, and seasonal fluctuations. Price volatility impacts procurement budgets for North American and European manufacturers, especially for premium categories such as extra-virgin and organic-certified variants. Dependence on smallholder farming introduces variability in production quality, yield consistency, and traceability. Currency fluctuations and export-dependent logistics create cost unpredictability, while freight disruptions magnify lead times. Mitigating these risks requires diversification of sourcing, contract farming models, and investment in farmer capacity building to ensure stable supply.
Regulatory Complexity and Quality Standard Compliance Across Markets
Manufacturers operating in North America and Europe face stringent regulations related to food safety, cosmetics labeling, organic certification, and environmental compliance. Differing market standards complicate cross-border distribution of coconut derivatives, especially powdered and fortified products. Claims regulations, allergen labeling, and clean beauty standards impose documentation and testing requirements that raise entry barriers for new suppliers. Cosmetics and nutraceutical manufacturers must validate purity, pesticide residues, and heavy metal thresholds, increasing operational overhead. Regulatory misalignment around sustainability certifications and fair-trade labeling further pressures producers to maintain multipronged compliance frameworks while managing cost competitiveness.
Regional Analysis:
North America
The North American region remains a leading contributor within the North America-Europe coconut derivatives market, estimated to account for roughly 35% of the combined regional value. This dominance reflects robust demand across the United States and Canada for coconut-based oils, waters, milks and healthier alternatives, driven by rising health consciousness, plant-based dietary trends, and strong retail and e-commerce distribution networks. Nutritional awareness, lactose intolerance, and growing interest in functional and clean-label products propel expanded consumption of coconut derivatives. As a result, North America continues to serve as a growth engine for the broader market.
Western Europe
Western Europe - led by countries such as Germany, the United Kingdom, France, Italy and Spain -captures the largest share of the European portion of the market, with Germany alone accounting for approximately 18% and the UK around 16.7% as of 2024. The region benefits from high consumer awareness around health, sustainability, and natural ingredients, leading to strong uptake of coconut-derived products in food & beverages, cosmetics, and nutraceuticals. Demand for organic, ethically-sourced, and clean-label products boosts coconut water, oil, and milk consumption. Mature retail infrastructures, regulatory familiarity with plant-based ingredients, and high disposable incomes cement Western Europe’s leadership in the market.
Eastern & Other European Markets
Eastern Europe and other emerging European markets presently hold a smaller portion of the regional market -likely under 10-15% - yet offer strong growth potential. Rising disposable incomes, urbanisation, and shifting dietary and lifestyle preferences toward Western-style diets and wellness products drive gradual adoption of coconut derivatives. Growth in niche sectors like natural cosmetics, plant-based foods, and functional beverages fosters new demand. As distribution networks expand and import infrastructure improves, these markets may progressively narrow the gap with more mature Western European markets, representing an important growth corridor for suppliers looking to diversify their European footprint.
Market Segmentations:
By Type
- Mature
- Young
By Derivatives
- Coconut Water
- Coconut Oil
- Coconut Milk
- Desiccated Coconut
- Others
By End-User
- Food & Beverages
- Cosmetics
- Pharmaceuticals
By Geography
- North America
- Western Europe
- Eastern & Other European Markets
Competitive Landscape:
The competitive landscape in the North America and Europe coconut derivatives market remains moderately fragmented but increasingly shaped by a handful of large, well-established players competing on scale, product breadth, and supply-chain strength. Leading firms such as Vita Coco, McCormick & Company, Inc., Hain Celestial Group, Inc., Celebes Coconut Corporation, and Axelum Resources Corp. dominate distribution channels across food & beverages, cosmetics, and nutraceutical segments. These players leverage strong sourcing relationships in coconut-producing countries, established logistics networks, and brand equity to deliver coconut oil, water, milk, desiccated products, and specialty ingredients across multiple markets. Their broad product portfolios and ability to scale operations give them a competitive advantage over smaller niche suppliers. Meanwhile, smaller regional and specialty suppliers stay relevant by focusing on niche segments-such as organic-certified, fair-trade, virgin coconut oil, or ice-cream and vegan dairy substitutes -where they differentiate on quality, sustainability credentials, or formulation flexibility. However, high entry barriers related to compliance, certification, and supply-chain consistency in Europe and North America reinforce the dominance of major players.
Key Player Analysis:
- Danone S.A. (Paris, France)
- PT Global Coconut (North Sulawesi, Indonesia)
- Superstar Coconut Products Co., Inc. (Quezon, Philippines)
- Vita Coco (New York, United States)
- JAKA Investment Corp. (Makati, Philippines)
- Hain Celestial Group, Inc. (New York, United States)
- Agrim Pte Ltd. (Singapore)
- Axelum Resources Corp. (Northern Mindanao, Philippines)
- McCormick & Company, Inc. (Maryland, United States)
- Celebes Coconut Corporation (Butuan, Philippines)
Recent Developments:
- In November 2025, Axelum Resources Corp.The company reported a sharp rebound, with net income rising to ₱636 million in the first nine months of 2025- marking an 88 % increase year-on-year -driven by robust volume growth and higher average selling prices across coconut product categories.
- In March 2025, Vita Coco the company rolled out an Orange & Creme coconut milk drink supported by a Y2K-themed launch event in New York City, boosting brand visibility and extending its coconut-based “Treats” line in the U.S.
- In March 2023, Danone-owned So Delicious Dairy Free (Danone North America) launched a 0g Added Sugar Coconutmilk Yogurt Alternative in the U.S., expanding its coconut-based dairy-free portfolio and strengthening its positioning in the plant-based yogurt aisle.
Report Coverage:
The research report offers an in-depth analysis based on Type, Derivatives, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for coconut derivatives will continue rising as plant-based, vegan, and clean-label diets become mainstream across both regions.
- Coconut milk and yogurt alternatives will experience strong traction in dairy-free formulations and functional beverages.
- Sustainable and ethical sourcing practices will become a core requirement rather than a differentiator.
- Companies will invest in transparent ingredient traceability to meet regulatory and consumer expectations.
- Premium organic and fair-trade coconut derivatives will expand faster than conventional variants.
- Coconut-based ingredients will grow in cosmeceuticals and dermatological applications.
- Value-added derivatives like coconut flour, protein powders, and sweeteners will diversify product portfolios.
- Regional partnerships and contract manufacturing will strengthen supply resilience.
- Branding strategies will shift toward environmental, health, and origin storytelling.
- Technological processing advancements will improve quality consistency and reduce waste, supporting scalable growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the North America and Europe coconut derivatives market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the North America and Europe coconut derivatives market projected to grow between 2024 and 2032?
Which North America and Europe coconut derivatives segment held the largest share in 2024?
What are the primary factors fueling the growth of the North America and Europe coconut derivatives market?
Who are the leading companies in the North America and Europe coconut derivatives market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17,527.49 million → 2032: USD 40,102.56 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America and Europe Coconut Derivations Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America and Europe Coconut Derivations Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America and Europe Coconut Derivations Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America and Europe Coconut Derivations Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America and Europe Coconut Derivations Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America and Europe Coconut Derivations Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America and Europe Coconut Derivations Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America and Europe Coconut Derivations Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17,527.49 million → 2032: USD 40,102.56 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America and Europe Coconut Derivations Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 North America and Europe Coconut Derivations Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 North America and Europe Coconut Derivations Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 North America and Europe Coconut Derivations Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

