
Market Overview
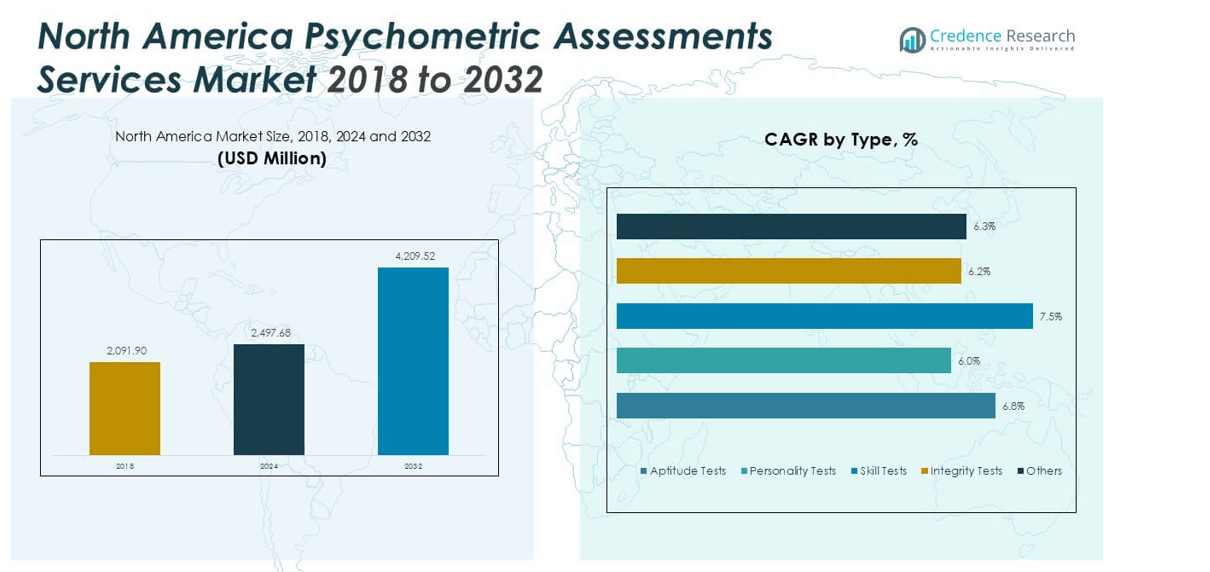
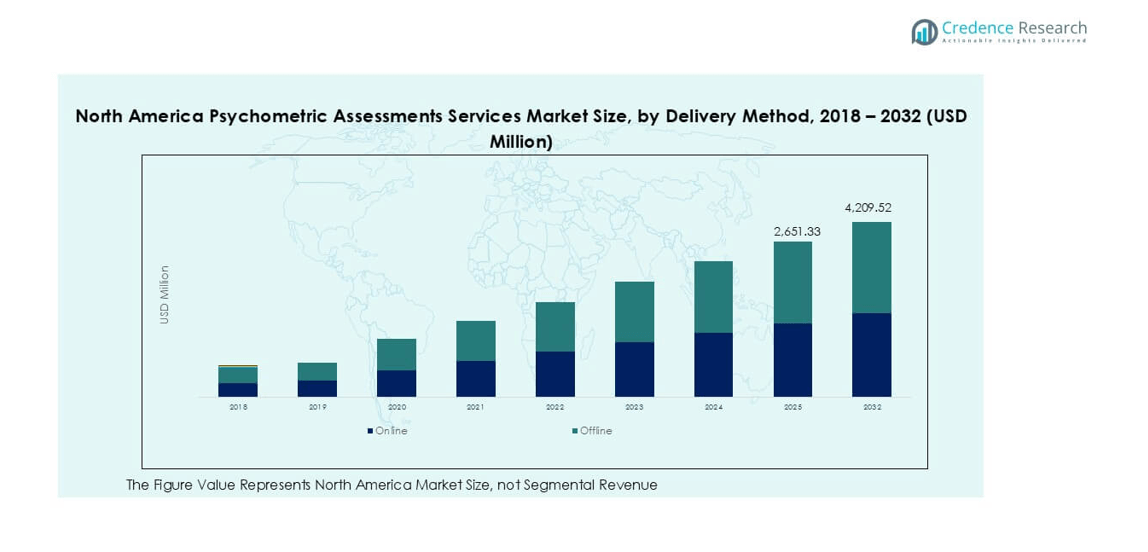
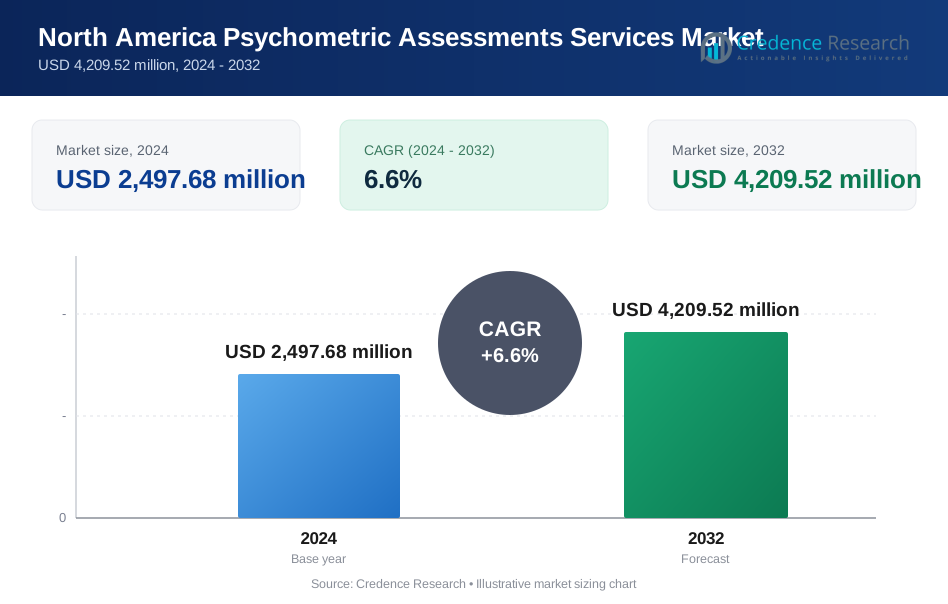
The North America Psychometric Assessments Services Market size was valued at USD 2,091.90 million in 2018, increased to USD 2,497.68 million in 2024, and is projected to reach USD 4,209.52 million by 2032, registering a CAGR of 6.6% during the forecast period (2025–2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Psychometric Assessments Services Market Size 2024 | UUSD 2,497.68 million |
| North America Psychometric Assessments Services Market, CAGR | 6.6% |
| North America Psychometric Assessments Services Market Size 2032 | USD 4,209.52 million |
The North America psychometric assessments services market is led by key players including SHL, Hogan Assessments, Aon Assessment Solutions, Korn Ferry, and PSI Services LLC. These companies dominate through extensive test portfolios, AI-driven analytics, and cloud-based delivery models that enhance assessment precision and accessibility. The United States remains the leading regional market, accounting for 72% of the total share in 2024, driven by strong corporate adoption and advanced HR digitalization. Canada and Mexico follow, supported by growing demand in education and government sectors. Continuous innovation in personality, aptitude, and cognitive testing sustains market leadership across the region.
Market Insights
- The North America Psychometric Assessments Services market was valued at USD 2,497.68 million in 2024 and is projected to reach USD 4,209.52 million by 2032, growing at a CAGR of 6.6%.
- Growth is driven by rising demand for data-driven recruitment and employee evaluation, with aptitude tests leading the type segment with a 36% share.
- Increasing integration of AI, predictive analytics, and cloud-based platforms enhances assessment efficiency and personalization across corporate and educational sectors.
- The market is moderately consolidated, with SHL, Hogan Assessments, Aon Assessment Solutions, and Korn Ferry dominating through digital innovations and product diversification.
- The United States holds 72% of the regional share, followed by Canada with 19% and Mexico with 9%, supported by expanding corporate adoption and growing use in training, development, and academic applications.
Market Segmentation Analysis:
By Type
The aptitude tests segment dominated the North America psychometric assessments services market in 2024, holding a 36% share. This segment leads due to its widespread use in measuring logical reasoning, problem-solving ability, and quantitative skills during recruitment. Organizations across technology, finance, and manufacturing sectors rely on standardized aptitude tests to improve hiring accuracy and reduce turnover rates. The growing demand for data-driven talent evaluation and AI-based test analytics further enhances adoption. Increased corporate emphasis on competency benchmarking continues to strengthen the segment’s position.
- For instance, SHL’s Verify numerical reasoning test gives 18 questions to be solved in 25 minutes.
By Application
Recruitment and selection represented the largest application segment, accounting for 49% of the market share in 2024. Companies increasingly integrate psychometric tools to identify high-potential candidates and streamline hiring decisions. Automated test platforms and remote assessment capabilities support large-scale hiring and remote workforce evaluation. The strong link between psychometric evaluations and improved employee performance drives adoption across enterprise HR functions. Continuous digital transformation in hiring processes and the shift toward predictive talent analytics remain key growth drivers for this segment.
- For instance, SHL administers around 35 million assessments globally per year, many used in recruitment workflows.
By End-User
The corporate sector dominated the market with a 58% share in 2024, driven by growing use of psychometric tools in employee screening, development, and leadership training. Businesses use these assessments to enhance workforce efficiency, align skills with organizational goals, and foster inclusive hiring. Increasing adoption of AI-based evaluation systems and gamified testing platforms also boosts corporate usage. Companies across IT, BFSI, and healthcare sectors prioritize such tools to improve team dynamics and reduce recruitment biases. The expanding focus on workforce analytics sustains strong demand within this segment.
Key Growth Drivers
Rising Demand for Data-Driven Recruitment Decisions
The growing emphasis on evidence-based hiring is a key growth driver in the North America psychometric assessments services market. Organizations across sectors increasingly use psychometric tools to evaluate cognitive ability, personality traits, and cultural fit before onboarding. Data analytics helps companies minimize hiring errors and improve employee retention. The use of psychometric insights in recruitment enables predictive modeling of performance and behavioral outcomes. As corporate HR teams move toward data-driven strategies, demand for scientifically validated assessments continues to rise. This trend strengthens the market’s role in supporting merit-based, bias-free hiring across industries.
- For instance, Aon’s Global Assessment Solutions platform has delivered over 48 million candidate assessments worldwide through its data-driven analytics system.
Expansion of E-Learning and Digital Assessment Platforms
Digital transformation in learning and development has accelerated the adoption of online psychometric testing. Educational institutions and corporate training programs increasingly rely on digital platforms to evaluate competencies and learning outcomes. Cloud-based delivery models allow flexible access, instant feedback, and large-scale deployment of assessments. AI-driven test analytics enhance personalization and adaptive learning paths for participants. These capabilities improve efficiency while reducing administrative costs. The integration of psychometric tools into e-learning systems supports continuous skill evaluation and aligns training objectives with measurable outcomes, reinforcing digital transformation in the education and corporate sectors.
- For instance, SHL’s cloud platform integrates with over 90 applicant tracking systems globally.
Growing Focus on Employee Retention and Leadership Development
Companies are prioritizing psychometric tools to identify leadership potential and improve retention strategies. These assessments help organizations understand employee motivations, stress tolerance, and interpersonal skills, forming the basis for effective succession planning. In sectors like IT, healthcare, and finance, firms use behavioral profiling to design leadership pipelines and targeted learning modules. The insights enable customized development programs that enhance engagement and productivity. As workforce mobility increases, psychometric evaluations play a critical role in retaining top talent by aligning career growth opportunities with individual strengths and organizational goals.
Key Trends & Opportunities
Increasing Use in Mental Health and Counseling Services
Psychometric assessments are expanding beyond corporate and academic applications into clinical and counseling domains. Healthcare providers and mental health professionals use validated tests to evaluate emotional well-being, cognitive functioning, and behavioral patterns. Growing awareness of mental health in workplaces and schools drives adoption of standardized tools for diagnosis and therapy planning. Digital delivery enables remote psychological evaluations, improving accessibility for patients. This expanding use case enhances the scope of service providers and supports cross-sector collaboration between psychology, healthcare, and corporate wellness programs across North America.
- For instance, the Beck Depression Inventory (BDI-II) uses 21 self-report items to gauge depression severity.
Integration of AI and Predictive Analytics
Artificial intelligence is transforming psychometric assessments by improving test accuracy, scalability, and interpretation speed. AI algorithms analyze response patterns to predict behavioral traits and job suitability with greater precision. Predictive analytics allows HR teams to forecast performance outcomes and identify future leaders. Automation reduces manual evaluation bias and shortens recruitment cycles. Companies integrating AI-driven psychometrics gain deeper workforce insights and better alignment between individual competencies and business objectives. The rise of hybrid workforce models creates new opportunities for predictive assessment tools that optimize distributed team performance.
Key Challenges
Data Privacy and Compliance Concerns
The widespread use of online psychometric assessments raises data privacy and compliance challenges. Sensitive personal information collected during evaluations must be handled under strict data protection frameworks such as GDPR and CCPA. Breaches or misuse can lead to legal penalties and loss of stakeholder trust. Companies face increasing pressure to ensure transparent data management, secure storage, and ethical use of assessment results. Maintaining compliance while offering user-friendly digital solutions remains a complex task, especially for multinational organizations managing cross-border employee data.
Limited Awareness and Misinterpretation of Results
A major barrier to market growth is the lack of understanding regarding psychometric assessments’ purpose and interpretation. Many organizations misuse or misread test outcomes, leading to flawed hiring or development decisions. In smaller enterprises and educational settings, limited expertise in administering and analyzing assessments reduces their effectiveness. Misconceptions about test validity and fairness further hinder adoption. To overcome this, service providers must invest in user education, standardized reporting, and professional training to ensure accurate implementation and meaningful use of psychometric insights.
Regional Analysis
United States
The United States dominated the North America psychometric assessments services market with a 72% share in 2024. The country’s strong adoption of data-driven HR analytics and digital recruitment platforms drives demand for psychometric tools. Corporate sectors such as IT, finance, and healthcare actively use these assessments for hiring, training, and leadership development. The growing emphasis on diversity, inclusion, and evidence-based hiring strengthens adoption among large enterprises. Moreover, U.S.-based service providers continue to innovate through AI-driven assessment technologies, supporting deeper behavioral analysis and customized workforce evaluations across industries.
Canada
Canada accounted for 19% of the regional market share in 2024, supported by its growing focus on organizational efficiency and skill-based recruitment. Educational institutions and government agencies increasingly integrate psychometric tools into academic testing, public service exams, and workforce evaluations. The rising popularity of remote assessment platforms and the need for employee well-being analytics have further boosted adoption. Companies are investing in scientifically validated tests to improve retention and performance. Collaborative initiatives between HR tech firms and universities continue to expand Canada’s role in advancing evidence-based workforce assessment practices.
Mexico
Mexico held a 9% share of the North America psychometric assessments services market in 2024, with adoption accelerating in manufacturing, logistics, and service industries. The growing presence of multinational companies and rising awareness of structured recruitment are key contributors to market expansion. Psychometric testing is gaining traction among HR departments for evaluating personality traits, leadership potential, and integrity in applicants. Local firms increasingly partner with global assessment providers to improve hiring accuracy and training effectiveness. The development of Spanish-language assessment tools and cloud-based delivery platforms is enhancing accessibility across Mexico’s corporate and education sectors.
Market Segmentations:
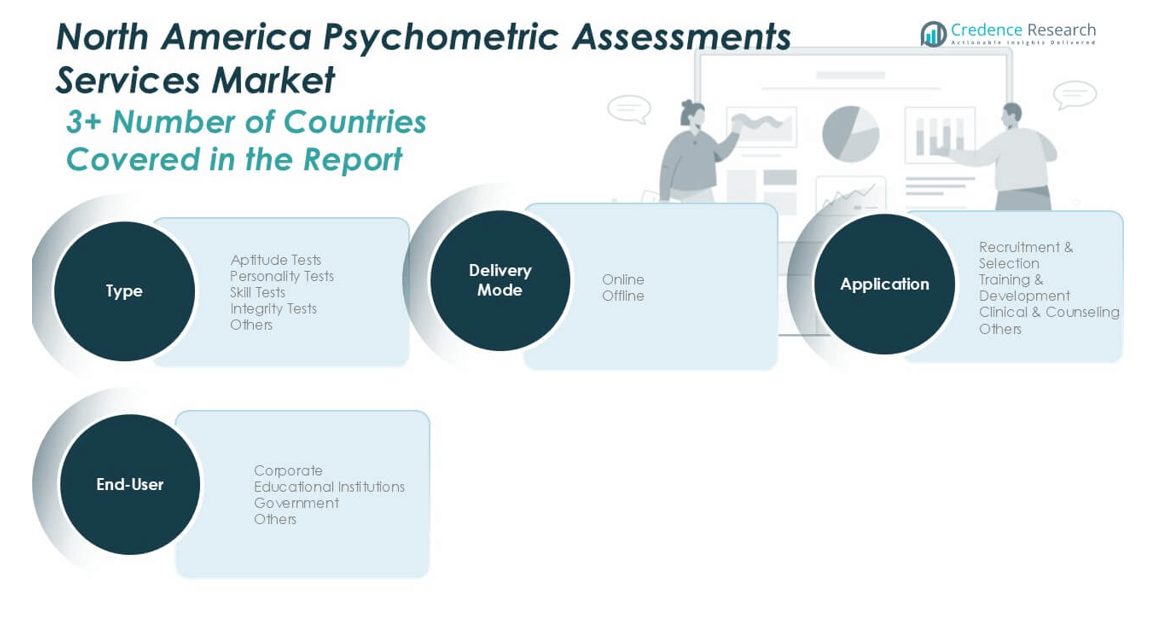
By Type
- Aptitude Tests
- Personality Tests
- Skill Tests
- Integrity Tests
- Others
By Application
- Recruitment & Selection
- Training & Development
- Clinical & Counselling
- Others
By End-User
- Corporate
- Educational Institutions
- Government
- Others
By Delivery Mode
- Online
- Offline
By Geography
- United States
- Canada
- Mexico
Competitive Landscape
The North America psychometric assessments services market is moderately consolidated, with leading players such as SHL, Hogan Assessments, Korn Ferry, Aon Assessment Solutions, and PSI Services LLC driving competition through advanced analytics and AI-enabled platforms. These companies focus on enhancing assessment accuracy, scalability, and customization to meet diverse organizational needs across recruitment, leadership development, and employee engagement. Strategic partnerships with HR software providers and cloud integration remain central to expanding client reach. Firms like The Myers-Briggs Company and Pearson TalentLens continue to strengthen their psychometric tool portfolios through digital upgrades and neuroscience-based frameworks. Meanwhile, emerging players such as Mettl, Berke, and AssessFirst emphasize data visualization and machine learning to deliver predictive hiring insights. Ongoing investments in multilingual assessment tools, remote testing technologies, and compliance-ready data management further intensify market competitiveness across North America.
Key Player Analysis
- SHL
- Hogan Assessments
- TalentSmart
- Criteria Corp
- Thomas International
- Cubiks
- PSI Services LLC
- Aon Assessment Solutions
- Pearson TalentLens
- Korn Ferry
- The Myers-Briggs Company
- Mettl
- Berke
- AssessFirst
- Psytech International
- Mindmill
- Saville Assessment
Recent Developments
- In October 2025, SHL introduced a new Personality and Ability Assessment Training Program in Czechia, focusing on professional development for HR teams to increase self-sufficiency in test interpretation and talent evaluation. This initiative forms part of SHL’s updated global training calendar for advanced psychometric assessment methodologies.
- In April 2025, TalentSmartEQ launched its 2025 State of EQ Report, analyzing data from over 37,000 Emotional Intelligence Appraisal participants. The report highlighted a shift toward people-first leadership and the growing use of emotional intelligence training to support employee well-being and adaptability in dynamic workplaces.
- In 2025, Hogan Assessments focused on leveraging AI for deeper behavioral insights in its predictive personality assessments, as presented at the IPAC 2025 conference. This aligns with Hogan's emphasis on ethical AI and enhanced cross-cultural validity, a priority highlighted in their April 2025 Top Trends in Personality Assessment report. Hogan was also a platinum sponsor of the IPAC conference, which was held from July 27–30 in Atlanta.
- In March 2023, Talent Select AI, a Milwaukee-based company, announced the official launch of its ground-breaking, self-titled psychometric assessment tool.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User, Delivery Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for AI-integrated psychometric tools will grow to support predictive hiring and talent analytics.
- Cloud-based assessment platforms will expand, enabling remote and large-scale testing.
- Corporates will increasingly use psychometrics for leadership identification and employee retention.
- Educational institutions will adopt adaptive learning assessments for student evaluation.
- Integration of gamification and virtual simulations will enhance engagement and test accuracy.
- Mental health and behavioral analytics applications will rise across clinical and workplace environments.
- Data privacy compliance will become a major priority for assessment providers.
- Customizable and multilingual assessments will see higher demand across multinational organizations.
- Partnerships between HR tech companies and academic institutions will strengthen innovation.
- AI-driven reporting and real-time analytics will redefine psychometric data interpretation and usability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the North America Psychometric Assessments Services market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the North America Psychometric Assessments Services market projected to grow between 2025 and 2032?
Which North America Psychometric Assessments Services market segment held the largest share in 2024?
What are the primary factors fueling the growth of the North America Psychometric Assessments Services market?
Who are the leading companies in the North America Psychometric Assessments Services market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,497.68 million → 2032: USD 4,209.52 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Psychometric Assessments Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Psychometric Assessments Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 North America Psychometric Assessments Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 North America Psychometric Assessments Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Psychometric Assessments Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Psychometric Assessments Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Psychometric Assessments Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Psychometric Assessments Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,497.68 million → 2032: USD 4,209.52 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Psychometric Assessments Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 North America Psychometric Assessments Services Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 North America Psychometric Assessments Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 North America Psychometric Assessments Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

