
Market Overview
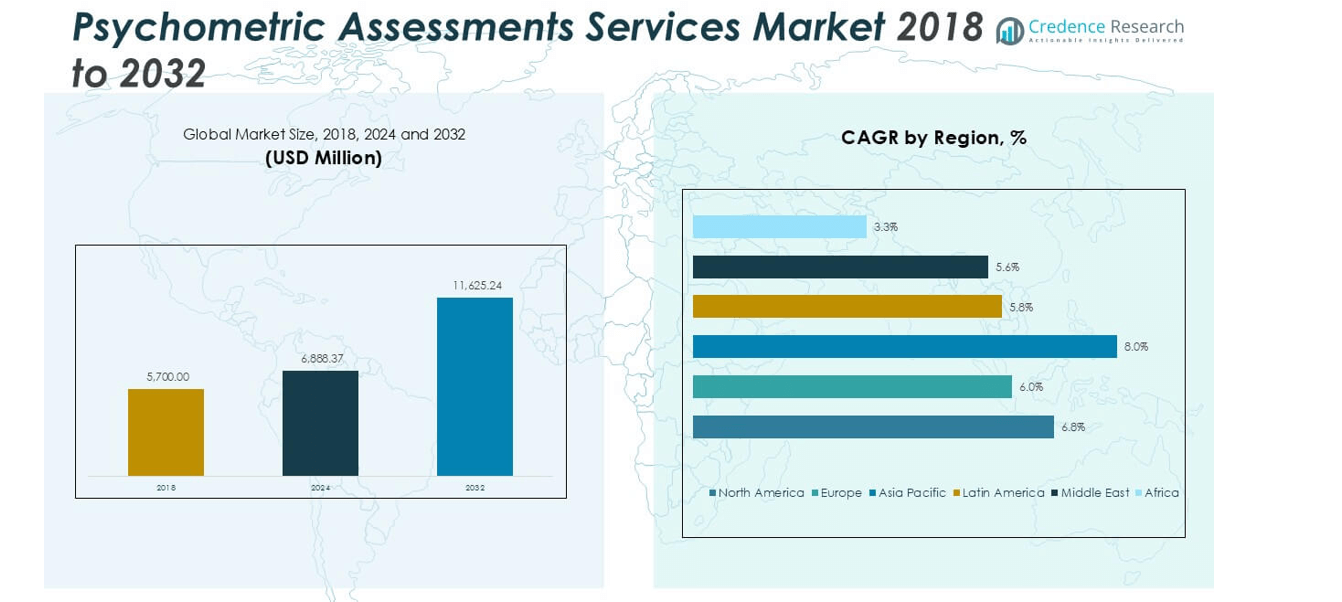
The Psychometric Assessments Services market size was valued at 5,700.00 million in 2018, increasing to 6,888.37 million in 2024, and is projected to reach 11,625.24 million by 2032, growing at a CAGR of 6.82% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Psychometric Assessments Services Market Size 2024 | USD 6,888.37 million |
| Psychometric Assessments Services Market, CAGR | 6.82% |
| Psychometric Assessments Services Market Size 2032 | USD 11,625.24 million |
The psychometric assessments services market is led by key players such as SHL, Hogan Assessments, Aon Assessment Solutions, Korn Ferry, and Pearson TalentLens. These companies dominate through advanced AI-enabled testing platforms, predictive analytics, and validated assessment tools that enhance recruitment and employee development processes. SHL and Aon lead in large-scale corporate testing, while Hogan Assessments and Korn Ferry specialize in leadership and behavioral evaluation. North America remains the leading region, holding a 38% market share in 2024, driven by strong adoption in corporate and educational sectors. Europe follows with 27%, supported by structured HR frameworks and regulatory compliance.
Market Insights
- The psychometric assessments services market was valued at USD 6,888.37 million in 2024 and is projected to reach USD 11,625.24 million by 2032, growing at a CAGR of 6.82%.
- Growing demand for data-driven recruitment and employee evaluation is driving adoption across corporate and educational sectors.
- AI integration, gamified assessments, and cloud-based platforms are emerging trends improving test engagement, accessibility, and predictive accuracy.
- The market is competitive, with key players including SHL, Aon Assessment Solutions, Hogan Assessments, Korn Ferry, and Pearson TalentLens focusing on scalable digital tools and compliance with data privacy laws.
- North America holds the largest share at 38%, followed by Europe with 27% and Asia-Pacific with 25%; aptitude tests lead the market with 36% share, supported by high corporate demand for efficient talent screening and workforce development.
Market Segmentation Analysis:
By Type
The aptitude tests segment dominated the psychometric assessments services market with a 36% share in 2024. Its leadership stems from wide adoption in corporate recruitment for evaluating analytical reasoning, problem-solving, and logical skills. Employers increasingly rely on aptitude testing to streamline candidate screening and ensure job-role alignment. Digital platforms such as SHL and Aon Assessment Solutions have enhanced test accessibility through AI-driven adaptive models. Rising demand for standardized, scalable, and data-based assessment tools in large organizations continues to reinforce the dominance of aptitude tests globally.
- For instance, SHL’s Verify G+ assessment consists of 30 multiple-choice items delivered over 36 minutes.
By Application
Recruitment and selection accounted for the largest market share of 48% in 2024. The segment’s growth is driven by organizations emphasizing evidence-based hiring and reducing subjective bias in candidate evaluation. Companies are integrating psychometric testing into automated applicant tracking systems to improve efficiency and predict job performance. Major assessment providers such as Korn Ferry and Mercer deploy customized recruitment modules for leadership and technical roles. The rising adoption of virtual hiring and remote assessments is accelerating segment expansion across global corporate and enterprise sectors.
- For instance, Korn Ferry’s Assess platform has processed over 69 million leadership assessments in the past five years, based on more than 6 billion proprietary data points.
By End-User
The corporate segment held the highest market share of 52% in 2024. Businesses use psychometric testing to enhance workforce productivity, identify leadership potential, and guide employee development programs. Continuous talent optimization strategies in sectors like IT, BFSI, and manufacturing are fueling test adoption. Educational institutions are following closely, leveraging these tools for student counseling and career guidance. Global firms such as Hogan Assessments and Pearson TalentLens are expanding enterprise-specific psychometric solutions that combine behavioral insights with AI analytics, supporting corporate workforce management and succession planning initiatives.
Key Growth Drivers
Growing Emphasis on Data-Driven Recruitment
Organizations are increasingly adopting psychometric assessments to improve hiring accuracy and reduce bias in recruitment. These assessments offer measurable insights into candidates’ cognitive ability, personality traits, and emotional intelligence, ensuring better job-role alignment. Companies in sectors such as IT, BFSI, and manufacturing are integrating these tools into automated talent acquisition systems to predict performance and retention. The shift toward objective evaluation helps HR teams minimize turnover and improve productivity. Vendors like SHL and Aon provide AI-enabled analytics to assess behavioral fit and cultural compatibility. The growing use of psychometrics in large-scale recruitment, especially for entry-level and managerial roles, continues to strengthen this growth driver globally.
- For instance, SHL’s Verify G+ test comprises 30 multiple-choice items delivered in 36 minutes.
Integration of Artificial Intelligence and Predictive Analytics
Artificial intelligence is reshaping psychometric testing by enhancing accuracy, adaptability, and personalization. AI algorithms analyze candidate responses in real time, offering insights beyond static scores. Predictive analytics enable employers to correlate psychometric outcomes with long-term job performance, reducing hiring risks. Leading providers like Mercer and Hogan Assessments are using machine learning to refine test parameters and eliminate human bias. Additionally, digital proctoring and gamified testing experiences enhance engagement and prevent malpractice. This technological integration not only boosts test credibility but also aligns with remote hiring trends, making assessments scalable and accessible across geographies. The fusion of AI with psychometrics is thus a major driver accelerating global adoption.
- For instance, Mercer launched its “Workforce Insights” platform supporting benchmarks across over 100 countries and 20,000 organizations.
Expansion of Workforce Development and Training Programs
Beyond recruitment, psychometric tools are increasingly used for employee development, leadership training, and succession planning. Organizations utilize these assessments to identify skill gaps, assess learning agility, and design targeted development programs. Companies such as Korn Ferry and The Myers-Briggs Company are offering role-specific competency frameworks supported by behavioral insights. The growing demand for continuous learning and internal mobility in corporate structures further supports adoption. Governments and educational institutions are also implementing psychometric testing to enhance academic counseling and public-sector workforce efficiency. This broadening application base positions psychometric services as essential for holistic talent management and organizational growth.
Key Trends & Opportunities
Rising Adoption of Cloud-Based and Remote Assessment Platforms
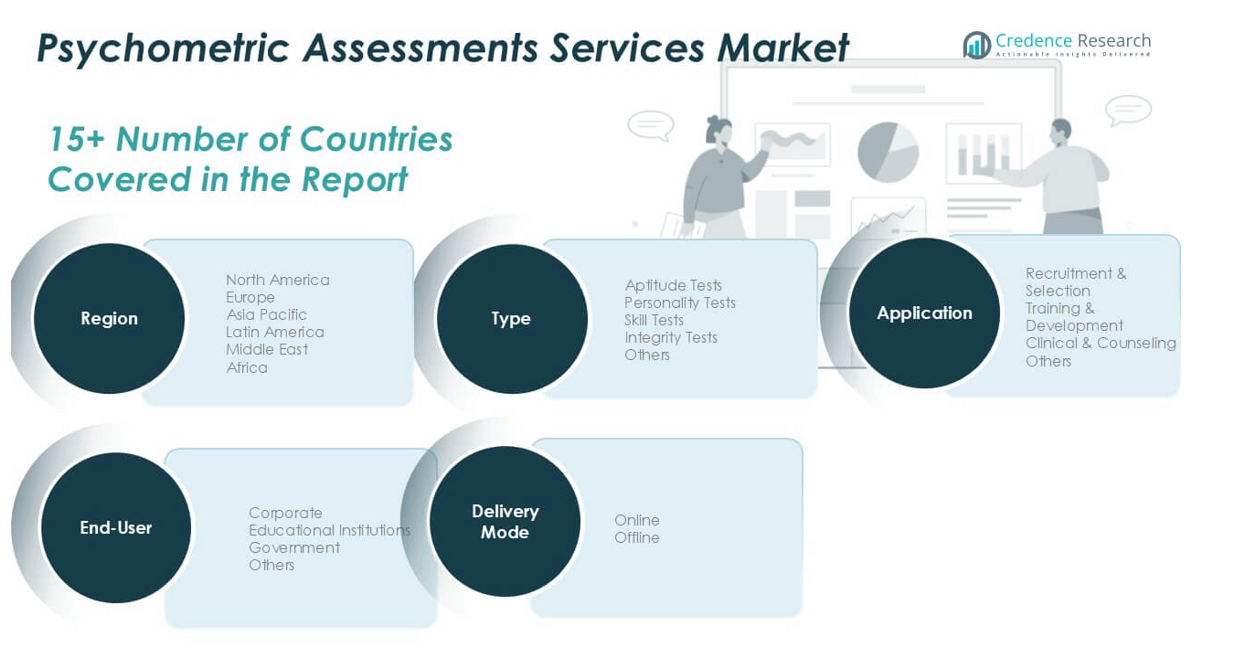
The rapid digitalization of human resource operations is driving demand for online psychometric testing solutions. Cloud-based platforms allow organizations to administer large-scale assessments seamlessly and store real-time analytics securely. With the global shift to hybrid and remote work, remote proctoring tools have gained traction, ensuring test integrity and accessibility. Providers like PSI Services and Pearson TalentLens have launched integrated dashboards offering automated scoring and benchmarking capabilities. The convenience, scalability, and cost-effectiveness of cloud solutions continue to reshape assessment delivery models. This trend is expected to dominate the industry, especially among multinational corporations and academic institutions seeking flexibility and rapid deployment.
- For instance, PSI’s test center network spans over 140 countries and delivers 17 million tests annually.
Personalization and Gamification of Assessment Modules
Personalized testing experiences and gamified assessment interfaces are emerging as key differentiators in the market. Modern psychometric tools use adaptive algorithms to tailor question difficulty based on candidate responses, improving engagement and reducing anxiety. Gamification adds interactive elements like challenges and simulations that mimic real-world problem-solving, enhancing test validity. Leading providers are leveraging these techniques to appeal to younger, tech-savvy candidates and ensure higher completion rates. Personalized analytics reports also provide employers with deeper behavioral insights. This trend enhances user experience and strengthens the perception of psychometrics as a positive and development-focused process.
- For instance, TalentLens' Standard Progressive Matrices (SPM) consists of 60 items, presented in five sets of 12. It is a primarily untimed test, though administration can take approximately 40–45 minutes.
Key Challenges
Data Privacy and Compliance Concerns
The increasing use of digital psychometric tools raises significant concerns over data security and regulatory compliance. Assessments often collect sensitive behavioral and psychological data that require stringent protection under frameworks like GDPR and CCPA. Breaches or misuse of assessment data can damage organizational reputation and lead to legal consequences. Companies must invest heavily in encryption, secure cloud storage, and consent-driven data handling. Vendors such as SHL and Aon are enhancing cybersecurity measures and offering transparent data governance frameworks. However, varying regional privacy standards create operational challenges for global providers, slowing widespread adoption of online assessments.
Cultural Bias and Test Standardization Issues
Psychometric assessments face persistent challenges in ensuring cultural neutrality and fair evaluation across diverse populations. Many tests are developed within specific linguistic and cultural contexts, which can lead to biased interpretations when applied internationally. Variations in language, social norms, and response styles affect result accuracy. Providers must localize content while maintaining psychometric validity, a process that demands extensive research and validation. Despite advancements in AI moderation, eliminating unconscious cultural bias remains difficult. This challenge limits the universal applicability of certain assessments and compels organizations to invest in region-specific test adaptations to ensure equitable evaluation outcomes.
Regional Analysis
North America
North America led the psychometric assessments services market with a 38% share in 2024. The region’s dominance is driven by widespread adoption of data-based hiring and employee evaluation systems across corporate, government, and education sectors. The U.S. and Canada show strong demand from industries such as IT, healthcare, and finance. Companies like SHL, Hogan Assessments, and Pearson TalentLens are expanding AI-enabled platforms for large enterprises and universities. Continuous emphasis on fair recruitment, compliance with EEOC guidelines, and investment in workforce analytics further strengthen the region’s leadership in psychometric testing solutions.
Europe
Europe accounted for around 27% of the global market in 2024, supported by strict labor regulations and structured talent assessment frameworks. The U.K., Germany, and France lead in adopting psychometric evaluations for recruitment and leadership development. Companies such as Aon Assessment Solutions and Korn Ferry dominate with advanced personality and aptitude tests aligned to GDPR standards. Public-sector and academic institutions increasingly use these tools for competency mapping and student guidance. The region’s growing focus on inclusivity, skill-based hiring, and digital learning ecosystems continues to drive steady market expansion across Europe.
Asia-Pacific
Asia-Pacific held a 25% share of the psychometric assessments services market in 2024, emerging as the fastest-growing regional segment. Expanding corporate sectors in India, China, Japan, and Australia are driving large-scale adoption in recruitment and workforce development. Increasing emphasis on skill certification, academic testing, and leadership training fuels market penetration. Regional players, along with global firms like Mercer and PSI Services, are introducing multilingual, mobile-compatible testing solutions. Government-backed education reforms and digital hiring platforms further support rapid adoption, positioning Asia-Pacific as a critical growth hub for global psychometric service providers.
Latin America
Latin America captured about 6% of the market share in 2024. The region’s growth is supported by rising investments in corporate talent management and educational assessment programs. Countries such as Brazil, Mexico, and Chile are witnessing greater use of psychometric tools in both private and public recruitment processes. Local firms collaborate with international vendors to integrate cloud-based testing platforms. The expansion of professional training programs and the shift toward data-driven HR decisions enhance market opportunities. However, economic instability and limited technological infrastructure still pose barriers to full-scale adoption in smaller economies.
Middle East & Africa
The Middle East & Africa accounted for nearly 4% of the global market in 2024. Demand is primarily concentrated in the UAE, Saudi Arabia, and South Africa, where governments and corporations emphasize modern talent assessment systems. Rapid growth in education, healthcare, and public administration sectors supports adoption. Companies are investing in localized, culturally adapted assessment tools to improve hiring precision. Partnerships between global providers and regional HR consultancies are expanding access to digital testing solutions. Despite limited awareness in smaller nations, the region shows promising long-term potential for psychometric assessment service adoption.
Market Segmentations:
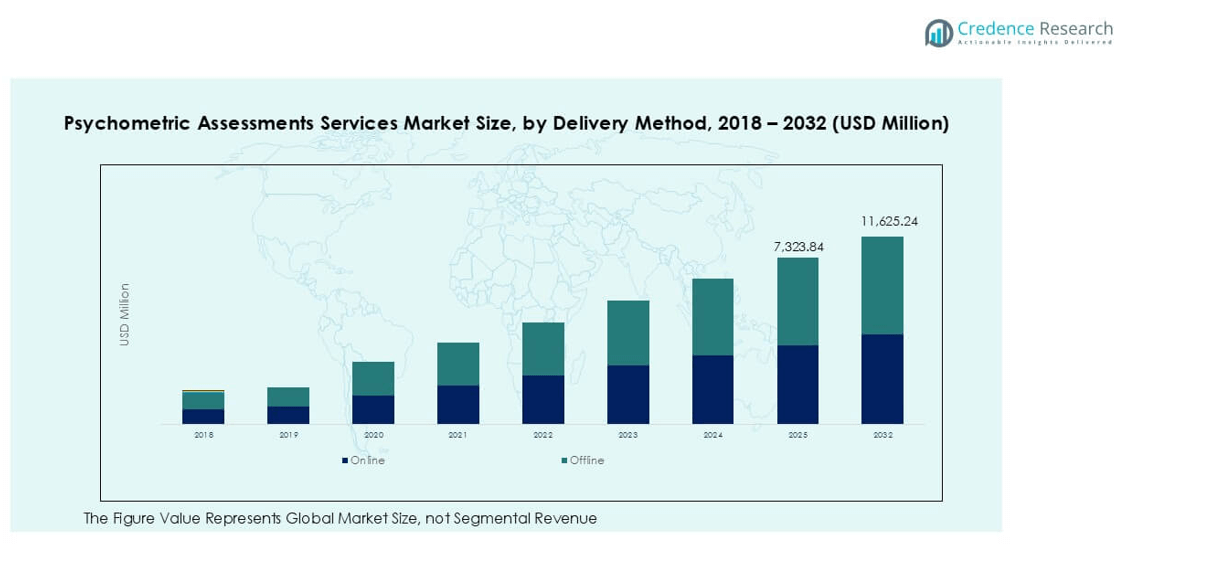
By Type
- Aptitude Tests
- Personality Tests
- Skill Tests
- Integrity Tests
- Others
By Application
- Recruitment & Selection
- Training & Development
- Clinical & Counselling
- Others
By End-User
- Corporate
- Educational Institutions
- Government
- Others
By Delivery Mode
- Online
- Offline
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The psychometric assessments services market is highly competitive, with leading players focusing on innovation, digital transformation, and global expansion. Major companies such as SHL, Hogan Assessments, Aon Assessment Solutions, Korn Ferry, and Pearson TalentLens dominate through advanced testing platforms, validated tools, and AI-driven analytics. These firms emphasize predictive performance analysis, cultural fit evaluation, and scalable cloud-based delivery to meet growing enterprise needs. Mid-tier players like Mettl, Criteria Corp, and AssessFirst are expanding in emerging markets by offering affordable, customizable solutions and multilingual support. Strategic partnerships, mergers, and technology integration are common growth strategies to enhance market reach. Continuous R&D investment in adaptive testing, gamification, and mobile-compatible solutions strengthens competitive positioning. Additionally, compliance with global data privacy laws and focus on ethical AI use are becoming key differentiators among vendors. The market’s competitive intensity remains strong, driven by the rising demand for data-based hiring and workforce development solutions worldwide.
Key Player Analysis
- SHL
- Hogan Assessments
- TalentSmart
- Criteria Corp
- Thomas International
- Cubiks
- PSI Services LLC
- Aon Assessment Solutions
- Pearson TalentLens
- Korn Ferry
- The Myers-Briggs Company
- Mettl
- Berke
- AssessFirst
- Psytech International
- Mindmill
- Saville Assessment
- Prevue HR Systems
- StrengthsAsia
- HireVue
Recent Developments
- In October 2025, SHL introduced a new Personality and Ability Assessment Training Program in Czechia, focusing on professional development for HR teams to increase self-sufficiency in test interpretation and talent evaluation. This initiative forms part of SHL’s updated global training calendar for advanced psychometric assessment methodologies.
- In April 2025, TalentSmartEQ launched its 2025 State of EQ Report, analyzing data from over 37,000 Emotional Intelligence Appraisal participants. The report highlighted a shift toward people-first leadership and the growing use of emotional intelligence training to support employee well-being and adaptability in dynamic workplaces.
- In 2025, Hogan Assessments focused on leveraging AI for deeper behavioral insights in its predictive personality assessments, as presented at the IPAC 2025 conference. This aligns with Hogan's emphasis on ethical AI and enhanced cross-cultural validity, a priority highlighted in their April 2025 Top Trends in Personality Assessment report. Hogan was also a platinum sponsor of the IPAC conference, which was held from July 27–30 in Atlanta.
- In March 2023, Talent Select AI, a Milwaukee-based company, announced the official launch of its ground-breaking, self-titled psychometric assessment tool
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User, Delivery Mode and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Growing integration of AI and machine learning will enhance test accuracy and personalization.
- Cloud-based and mobile-compatible assessment platforms will expand global accessibility.
- Increased demand for data-driven hiring will strengthen adoption across corporate sectors.
- Gamification will make assessments more engaging and improve candidate experience.
- Educational institutions will increasingly use psychometric tools for career guidance and learning evaluation.
- Predictive analytics will become central to leadership and talent development programs.
- Regional providers will collaborate with global firms to localize and customize assessment content.
- Compliance with data privacy and ethical AI standards will shape vendor credibility.
- Continuous innovations in adaptive and remote testing will redefine recruitment efficiency.
- Emerging markets in Asia-Pacific and the Middle East will offer strong growth opportunities for service providers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Psychometric Assessments Services market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Psychometric Assessments Services market projected to grow between 2025 and 2032?
Which Psychometric Assessments Services market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Psychometric Assessments Services market?
Who are the leading companies in the Psychometric Assessments Services market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,888.37 million → 2032: USD 11,625.24 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Psychometric Assessments Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Psychometric Assessments Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Psychometric Assessments Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Psychometric Assessments Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Psychometric Assessments Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Psychometric Assessments Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Psychometric Assessments Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Psychometric Assessments Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,888.37 million → 2032: USD 11,625.24 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Psychometric Assessments Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Psychometric Assessments Services Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Psychometric Assessments Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Psychometric Assessments Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

