
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Predictive Analytics Market Size 2024 | USD 14,432 million |
| Predictive Analytics Market, CAGR | 21.2% |
| Predictive Analytics Market Size 2032 | USD 67,196.6 million |
Market Overview
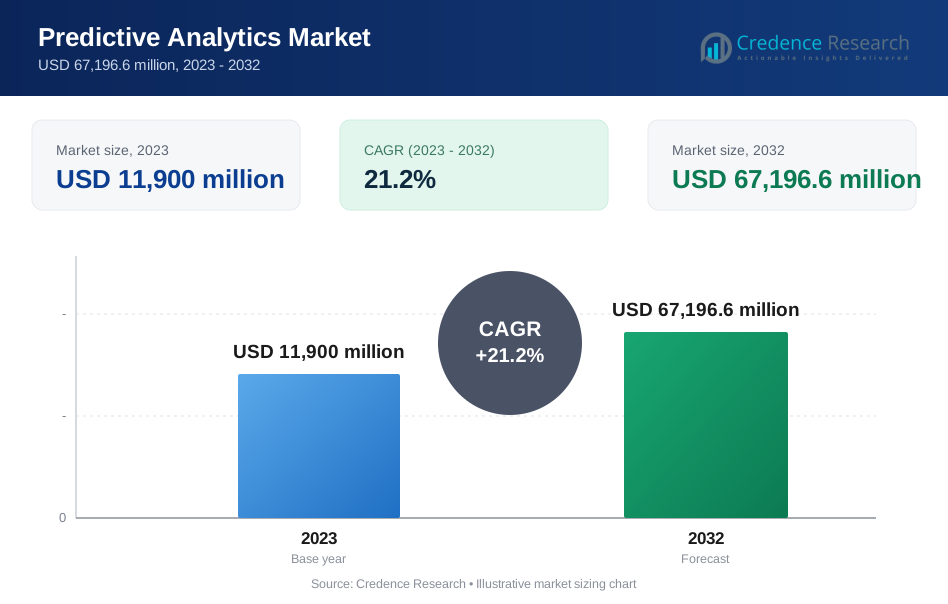
The Global predictive analytics market is projected to grow from USD 14,432 million in 2024 to an estimated USD 67,196.6 million by 2032, with a compound annual growth rate (CAGR) of 21.2% from 2025 to 2032.
Market growth is primarily driven by the surge in demand for personalized customer experiences, fraud detection, risk management, and operational efficiency. Predictive analytics is being increasingly integrated into business intelligence platforms and enterprise systems, enabling users to unlock actionable insights in real time. Trends such as the integration of machine learning, artificial intelligence, and advanced statistical techniques into analytics platforms are further enhancing their predictive accuracy and accessibility. Enterprises are also investing in self-service analytics tools to empower non-technical users, fostering broader adoption across departments.
Geographically, North America leads the predictive analytics market due to its mature technology infrastructure and high adoption across sectors such as finance, healthcare, and retail. Europe follows closely, driven by regulatory compliance and innovation in analytics applications. The Asia Pacific region is witnessing rapid growth, fueled by digital transformation in emerging economies like India and China. Key players in the global market include IBM Corporation, Microsoft Corporation, SAS Institute Inc., SAP SE, Oracle Corporation, and Tableau Software, among others.
Market Insights
- The Global predictive analytics market is projected to grow from USD 14,432 million in 2024 to USD 67,196.6 million by 2032, at a CAGR of 21.2% from 2025 to 2032.
- The increasing need for real-time, data-driven decision-making across industries is a key factor accelerating market growth.
- Rising adoption of cloud computing, artificial intelligence, and machine learning is enhancing predictive model capabilities and deployment.
- Growing demand for customer personalization, fraud detection, and risk management continues to drive adoption across business sectors.
- High implementation costs, integration complexity, and limited in-house expertise restrict adoption, especially among SMEs.
- North America leads the market due to early adoption, robust infrastructure, and strong presence of major analytics vendors.
- Asia Pacific is the fastest-growing region, driven by digital transformation, expanding data infrastructure, and supportive government initiatives
Market Drivers
Rising Demand for Data-Driven Decision-Making Across Enterprises
The Global predictive analytics market is benefiting from the widespread shift toward data-driven decision-making in both public and private sectors. Organizations are increasingly using predictive models to forecast customer behavior, market trends, and operational performance. Executives rely on analytics to enhance strategic planning and reduce uncertainties in business processes. Predictive tools help streamline operations, optimize supply chains, and improve resource allocation. Enterprises recognize the competitive advantage gained through early insights derived from historical and real-time data. This strategic application of predictive analytics is expanding across industries including retail, healthcare, finance, and manufacturing.
- For instance, in 2023, the US Department of Veterans Affairs reported the deployment of over 25 enterprise-wide predictive analytics models to improve patient care coordination and resource allocation, supporting decisions for more than 9 million veterans nationwide (VA Data Analytics Annual Report, 2023).
Technological Advancements Enhancing Model Accuracy and Accessibility
Advancements in artificial intelligence, machine learning, and cloud computing are accelerating the capabilities of predictive analytics platforms. These technologies enable faster data processing, better model training, and more accurate forecasting. The Global predictive analytics market is gaining momentum due to the scalability and efficiency provided by cloud-based solutions. It has become easier for businesses of all sizes to deploy advanced analytics tools without major infrastructure investments. The integration of AI-driven algorithms into analytics platforms improves usability and insight generation for non-technical users. Continuous innovation in predictive modeling techniques is further expanding its application scope.
- For instance, in 2024, Google Cloud reported servicing over 5,120 enterprises globally with its Vertex AI predictive analytics platform, facilitating the launch of more than 450,000 custom AI models for business users (Google Cloud Annual Report, 2024).
Increased Emphasis on Personalized Customer Engagement and Retention
Companies across various industries are prioritizing customer-centric strategies to enhance satisfaction and loyalty. Predictive analytics plays a key role in identifying customer preferences, behaviors, and churn risk. It helps brands tailor marketing campaigns, optimize pricing models, and deliver personalized experiences at scale. The Global predictive analytics market supports this shift by offering tools that extract insights from large volumes of structured and unstructured data. Businesses apply these insights to make informed decisions that align with evolving customer expectations. Targeted engagement backed by predictive insights improves retention and long-term profitability.
Rising Concerns Over Fraud, Risk, and Compliance Management
The growing complexity of global business environments has increased the need for risk mitigation and regulatory compliance. Predictive analytics enables real-time identification of anomalies, fraudulent activities, and compliance risks. In sectors like banking, insurance, and healthcare, it plays a critical role in fraud detection, claims validation, and operational auditing. The Global predictive analytics market is responding to this need by offering robust, adaptive solutions for proactive risk management. It empowers organizations to act quickly on potential threats, minimizing financial and reputational damage. By anticipating risks, businesses can maintain integrity and gain trust in highly regulated markets.
Market Trends
Integration of Artificial Intelligence and Machine Learning Into Predictive Models
The adoption of artificial intelligence (AI) and machine learning (ML) continues to transform predictive analytics by improving accuracy, scalability, and automation. These technologies help organizations detect patterns, learn from historical data, and make real-time predictions without manual intervention. The Global predictive analytics market is witnessing significant innovation in AI-powered algorithms that can handle complex data structures and large datasets. It supports faster decision-making and enhances adaptability in dynamic business environments. AI integration also enables models to self-improve over time, refining predictions with each new data input. This trend is pushing analytics from reactive reporting toward proactive and autonomous forecasting.
- For instance, 660 companies across North America deployed new AI- and ML-driven predictive analytics solutions in the past year to automate decision-making processes and improve real-time business insights.
Wider Use of Predictive Analytics in Industry-Specific Applications
Businesses are increasingly adopting predictive analytics in sector-specific use cases, creating tailored solutions for industries such as healthcare, retail, finance, and manufacturing. In healthcare, predictive models help forecast disease outbreaks and patient readmission risks. Retailers use it to optimize inventory and personalize customer engagement. The Global predictive analytics market is becoming more specialized as solution providers develop tools designed for unique regulatory, operational, and consumer needs. It enables companies to achieve precision and efficiency across diverse functions. This vertical expansion broadens market reach and strengthens demand for customizable predictive platforms.
- For instance, as reported by the U.S. Department of Health and Human Services (HHS), more than 230 hospitals nationwide implemented predictive analytics platforms in 2023 specifically to reduce patient readmissions and improve treatment planning
Growing Importnce of Real-Time and Stream Processing Capabilities
Organizations now require real-time insights to respond quickly to market shifts, customer actions, and operational changes. The emergence of streaming data analytics allows predictive models to process data continuously rather than in batches. The Global predictive analytics market is embracing this shift by integrating real-time processing capabilities into analytics solutions. It improves responsiveness and allows companies to act on emerging trends or anomalies without delays. Real-time forecasting supports mission-critical use cases such as fraud detection, demand forecasting, and emergency response. Speed and agility have become central to the value proposition of predictive technologies.
Increasing Adoption of Cloud-Based Predictive Analytics Solutions
Cloud platforms are driving broader access to predictive analytics by offering scalable, flexible, and cost-efficient deployment options. Enterprises are moving from traditional on-premise infrastructure to cloud-based models that support remote access and rapid deployment. The Global predictive analytics market is experiencing strong growth in cloud adoption due to lower entry barriers and reduced total cost of ownership. It enables businesses of all sizes to integrate advanced analytics into their operations without heavy capital investments. Cloud solutions also offer better collaboration, automatic updates, and integration with other enterprise systems. This transition supports the democratization of predictive analytics across industries.
Market Challenges
High Implementation Costs and Complexity in Integration Across Systems
The Global predictive analytics market faces a major challenge in terms of high implementation costs and integration complexities. Many organizations struggle to align predictive tools with legacy systems and existing IT infrastructure. It requires skilled personnel, significant investment in training, and continuous support for seamless integration. Smaller enterprises often lack the resources to adopt advanced predictive platforms, limiting market penetration. Complex deployment processes also extend implementation timelines and hinder operational efficiency. These barriers slow down adoption, particularly in industries with constrained budgets or outdated digital capabilities.
- For instance, according to the IDC Worldwide Semiannual Big Data and Analytics Spending Guide (2024), more than 45,000 SMEs globally adopted cloud-based predictive analytics platforms between 2022 and 2023, showing increasing uptake among smaller organizations.
Data Privacy Concerns and Shortage of Skilled Professionals
Strict regulations around data privacy and security continue to pose challenges for predictive analytics adoption. Organizations must ensure compliance with regional laws such as GDPR, which restricts how personal and sensitive data is collected, stored, and analyzed. The Global predictive analytics market must address these concerns to build trust and ensure lawful data handling. It also faces a shortage of data science professionals who possess the technical expertise to develop, maintain, and interpret predictive models. This talent gap limits scalability and delays project execution. Companies often struggle to build in-house analytics teams, increasing dependence on third-party providers.
Market Opportunities
Expanding Use of Predictive Analytics in Emerging Economies and SMEs
The Global predictive analytics market holds strong growth potential in emerging economies and among small and medium-sized enterprises (SMEs). Businesses in regions such as Asia Pacific, Latin America, and the Middle East are accelerating digital transformation and adopting data-driven practices. It creates opportunities for analytics vendors to offer cost-effective, scalable solutions tailored to local business needs. Cloud-based platforms and subscription models lower the entry barrier for SMEs to access advanced predictive capabilities. Increased smartphone penetration and e-commerce expansion further generate large volumes of data ready for analysis. Vendors that focus on localized services and flexible pricing can tap into these underserved segments.
Innovation in Industry-Specific Solutions and Self-Service Tools
Developing predictive analytics tools for industry-specific applications offers significant opportunities for market expansion. Sectors like agriculture, logistics, education, and energy are beginning to adopt analytics to improve operational outcomes. The Global predictive analytics market can grow further by delivering purpose-built models that address unique workflows and regulatory environments. It also benefits from rising demand for self-service analytics tools that empower non-technical users to derive insights independently. This democratization of analytics expands user bases and supports faster decision-making across functions. Vendors that prioritize ease of use and customization will gain a competitive advantage in this evolving landscape.
Market Segmentation Analysis
By Component
The Global predictive analytics market is segmented into solutions and services. Solutions dominate the segment due to high demand for advanced analytics software that offers forecasting, data mining, and statistical modeling capabilities. Enterprises rely on these tools to identify patterns and support strategic decisions. Services, including consulting, implementation, and support, are gaining traction as organizations seek expert guidance to integrate predictive models into their operations. The need for customized deployment and ongoing optimization is fueling growth in service offerings. Both components play a critical role in ensuring the effective adoption of predictive analytics across industries.
- For instance, in 2023, IBM reported delivering over 110,000 predictive analytics solution deployments worldwide, along with more than 12,500 professional services engagements focused on analytics integration and support (IBM Annual Report, 2023).
By Enterprise Size
Large enterprises currently hold a significant share due to their higher budgets, established IT infrastructure, and data-driven strategies. These organizations invest heavily in predictive tools to optimize operations and gain competitive advantage. The small and medium-sized enterprises (SMEs) segment is expected to grow rapidly, supported by cloud-based solutions and flexible pricing models. It enables SMEs to access powerful analytics without large upfront investments. The Global predictive analytics market continues to evolve, offering scalable tools tailored for organizations of all sizes.
- For instance, according to the IDC Worldwide Semiannual Big Data and Analytics Spending Guide (2024), more than 45,000 SMEs globally adopted cloud-based predictive analytics platforms between 2022 and 2023, showing increasing uptake among smaller organizations.
By Deployment Type
Cloud deployment leads this segment due to its flexibility, lower maintenance costs, and ease of integration with existing systems. It supports remote access and quick updates, making it ideal for businesses adapting to hybrid work environments. On-premise deployment remains relevant for sectors requiring full control over data security and infrastructure. Enterprises with strict compliance requirements continue to prefer on-site solutions.
By Industry Vertical
The market serves diverse sectors including BFSI, retail, IT & telecom, healthcare, government, and manufacturing. BFSI leads adoption due to its need for fraud detection, credit risk assessment, and customer segmentation. Retail uses predictive tools for demand forecasting and personalized marketing. Healthcare applies analytics for patient care optimization and disease prediction. Other sectors, including government and manufacturing, are also embracing predictive analytics to improve service delivery and efficiency.
Segments
Based on Component
- Solutions
- Services
Based on Enterprise Size
- Large Enterprises
- Small and Medium-sized Enterprises
Based on Deployment Type
- On-premise
- Cloud
Based on Industry Vertical
- BFSI
- Retail
- IT & Telecom
- Healthcare
- Government
- Manufacturing
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Predictive Analytics Market
North America holds the largest share in the predictive analytics market, accounting for over 38% of global revenue in 2024. Strong presence of major technology providers, early adoption of AI and machine learning, and high demand across sectors support regional dominance. Industries such as BFSI, retail, and healthcare use predictive tools extensively to enhance decision-making and operational efficiency. The United States leads the region due to a robust digital infrastructure and data-centric business models. Canada is also expanding its use of analytics in finance and public services. North America continues to invest in advanced analytics solutions to maintain competitive advantage.
Europe Predictive Analytics Market
Europe represents a significant share of the predictive analytics market with a contribution of around 26% in 2024. Regulatory frameworks such as GDPR are driving demand for compliant, secure analytics solutions. Countries like Germany, the UK, and France are leading in adoption, particularly in healthcare, automotive, and finance sectors. Organizations in the region are integrating predictive tools to manage risk, improve customer experience, and optimize supply chains. The market benefits from strong R\&D activities and partnerships between tech firms and academic institutions. It continues to mature with a growing focus on ethical data use.
Asia Pacific Predictive Analytics Market
Asia Pacific is the fastest-growing region, contributing approximately 20% of the global predictive analytics market share in 2024. Rapid digital transformation across India, China, Japan, and Southeast Asia is accelerating adoption. Organizations use predictive analytics to gain insights from expanding consumer data and improve business agility. The retail, telecom, and manufacturing sectors are leading demand in this region. Government initiatives supporting smart cities and digital infrastructure also create favorable conditions. The market is expected to grow steadily as more enterprises adopt AI-driven tools.
Latin America Predictive Analytics Market
Latin America holds a modest yet expanding share in the predictive analytics market, with nearly 8% in 2024. Brazil and Mexico are key contributors due to increasing adoption in banking, retail, and government sectors. Businesses seek predictive tools to improve efficiency, forecast demand, and manage customer engagement. It is gradually building digital capabilities, supported by public-private partnerships and cloud penetration. Vendors are entering the market with localized offerings to meet language and compliance requirements. Market growth depends on continued investment in digital literacy and infrastructure.
Middle East & Africa Predictive Analytics Market
The Middle East & Africa region accounts for about 5% of the global predictive analytics market in 2024. Countries like the UAE, Saudi Arabia, and South Africa are adopting predictive tools in energy, logistics, and public administration. Governments are prioritizing digital transformation under national vision programs, encouraging predictive technology use. It helps organizations manage resources more efficiently and make data-backed policy decisions. Market expansion is driven by increased awareness and investment in smart technologies. The region is gradually building the ecosystem required for analytics-driven growth.
Key players
- NTT DATA CORPORATION
- Oracle Corporation
- Siemens AG
- Schneider Electric SE
- Tableau Software, Inc.
- SAP ERP
- General Electric Company
- SAS Institute, Inc.
- Microsoft Corporation
- IBM Corporation
Competitive Analysis
The Global predictive analytics market is highly competitive, with key players focusing on innovation, strategic partnerships, and product enhancement to gain market share. Companies such as IBM Corporation, Microsoft Corporation, and SAS Institute, Inc. lead through advanced AI-driven platforms and strong enterprise customer bases. Oracle Corporation and SAP ERP strengthen their market position by integrating predictive analytics into broader business intelligence ecosystems. Tableau Software, Inc. and Schneider Electric SE offer user-friendly, scalable tools that appeal to a wide range of industries. Siemens AG and General Electric Company focus on industrial analytics for manufacturing and energy sectors. NTT DATA CORPORATION continues to expand its analytics consulting services across global markets. It remains a dynamic landscape where success depends on data security, platform integration, and vertical-specific innovation.
Recent Development
- In June 2025, Siemens AG expanded its collaboration with NVIDIA at to integrate AI and digital twins and predictive analytics for industrial applications.
- In May 2025, Microsoft Corporation introduced new Copilot-driven analytics capabilities across Windows, Azure, and Microsoft 365 at Build 2025.
Market Concentration and Characteristics
The Global predictive analytics market shows moderate to high market concentration, with several dominant players such as IBM, Microsoft, Oracle, and SAP holding significant market share. It is characterized by rapid innovation, strong focus on artificial intelligence integration, and a shift toward cloud-based delivery models. The market favors vendors that offer scalable, customizable solutions capable of handling diverse data environments. Demand spans multiple industries, including BFSI, healthcare, retail, and manufacturing, reflecting its versatility. It also exhibits high entry barriers due to the need for advanced technology, skilled talent, and regulatory compliance. Competitive dynamics are shaped by product differentiation, strategic alliances, and investment in R&D.
Report Coverage
The research report offers an in-depth analysis based on Component, Enterprise Size, Deployment Type, Industry Vertical and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Emerging economies such as India, Brazil, and Southeast Asia will witness growing adoption due to rapid digitalization and increasing awareness of data-driven strategies.
- The market will experience deeper integration with AI and machine learning technologies to enhance the speed, accuracy, and automation of predictive models.
- Healthcare providers and pharmaceutical firms will expand the use of predictive analytics for patient outcome forecasting, diagnostics, and drug development.
- Cloud deployment will dominate due to cost efficiency, scalability, and improved accessibility, supporting faster adoption by SMEs and remote teams.
- Organizations will increasingly adopt real-time and edge analytics to drive faster operational decisions and improve responsiveness in dynamic environments.
- User-friendly, no-code platforms will gain traction, enabling business users without technical expertise to independently analyze data and generate forecasts.
- Vendors will prioritize compliance with evolving global data privacy laws such as GDPR, HIPAA, and CCPA to maintain trust and market access.
- Industry-focused solutions tailored to the needs of sectors like logistics, energy, agriculture, and education will see accelerated development and adoption.
- Manufacturers and infrastructure operators will rely more on predictive analytics for equipment monitoring and failure prevention, improving cost efficiency and uptime.
- Technology providers will pursue mergers, acquisitions, and strategic partnerships to expand capabilities, enter new markets, and strengthen product portfolios.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Shift Toward Data-Driven Decision-Making
Organizations across industries are increasingly leveraging predictive analytics to forecast trends, optimize operations, and enhance strategic planning, leading to improved competitiveness and efficiency.
Advancements in AI, Machine Learning, and Cloud Computing
Technological innovations are making predictive analytics platforms more accurate, scalable, and accessible, enabling faster data processing and easier deployment for businesses of all sizes.
Demand for Personalized Customer Engagement
Companies are using predictive analytics to analyze customer behavior and preferences, enabling them to deliver tailored experiences, improve retention, and increase customer lifetime value.
Fraud Detection and Risk Management Needs
Sectors such as BFSI and healthcare rely on predictive analytics to identify anomalies, detect fraud, and manage compliance risks in real time, reducing financial losses and enhancing trust.
Expansion of Real-Time and Self-Service Analytics
The integration of real-time data processing and user-friendly, self-service tools empowers non-technical users to generate actionable insights quickly, broadening adoption across departments and enterprise sizes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Global Predictive Analytics Market in 2023, and what are its projected size and CAGR by 2032?
Which industries are using predictive analytics the most?
Which region holds the largest share in the global predictive analytics market?
Who are the major players in the predictive analytics market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Solutions
- 1.2.2 Services
- 1.3 By Deployment Type
- 1.3.1 On-premise
- 1.3.2 Cloud
- 1.4 By Enterprise Size
- 1.4.1 Large Enterprises
- 1.4.2 Small and Medium-sized Enterprises
- 1.5 By Industry Vertical
- 1.5.1 BFSI
- 1.5.2 Retail
- 1.5.3 IT & Telecom
- 1.5.4 Healthcare
- 1.5.5 Government
- 1.5.6 Manufacturing
- 1.5.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 11,900 million → 2032: USD 67,196.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Predictive Analytics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Predictive Analytics Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Predictive Analytics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Predictive Analytics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Predictive Analytics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Predictive Analytics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Predictive Analytics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Predictive Analytics Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 11,900 million → 2032: USD 67,196.6 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Predictive Analytics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Base-Year Market Share, 2023
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Solutions
- 12.3.6.2 Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Deployment Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Base-Year Market Share, 2023
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 On-premise
- 12.4.6.2 Cloud
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Enterprise Size - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Base-Year Market Share, 2023
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Large Enterprises
- 12.5.6.2 Small and Medium-sized Enterprises
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Industry Vertical - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Base-Year Market Share, 2023
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 BFSI
- 12.6.6.2 Retail
- 12.6.6.3 IT & Telecom
- 12.6.6.4 Healthcare
- 12.6.6.5 Government
- 12.6.6.6 Manufacturing
- 12.6.6.7 Others
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Predictive Analytics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Predictive Analytics Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Predictive Analytics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Predictive Analytics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Microsoft Corporation
- 18.4 SAS Institute Inc.
- 18.5 Oracle Corporation
- 18.6 SAP SE
- 18.7 Tableau Software, Inc.
- 18.8 Siemens AG
- 18.9 Schneider Electric SE
- 18.10 NTT DATA CORPORATION
- 18.11 General Electric Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

