
Treatment gaps, not incidence, now set device demand
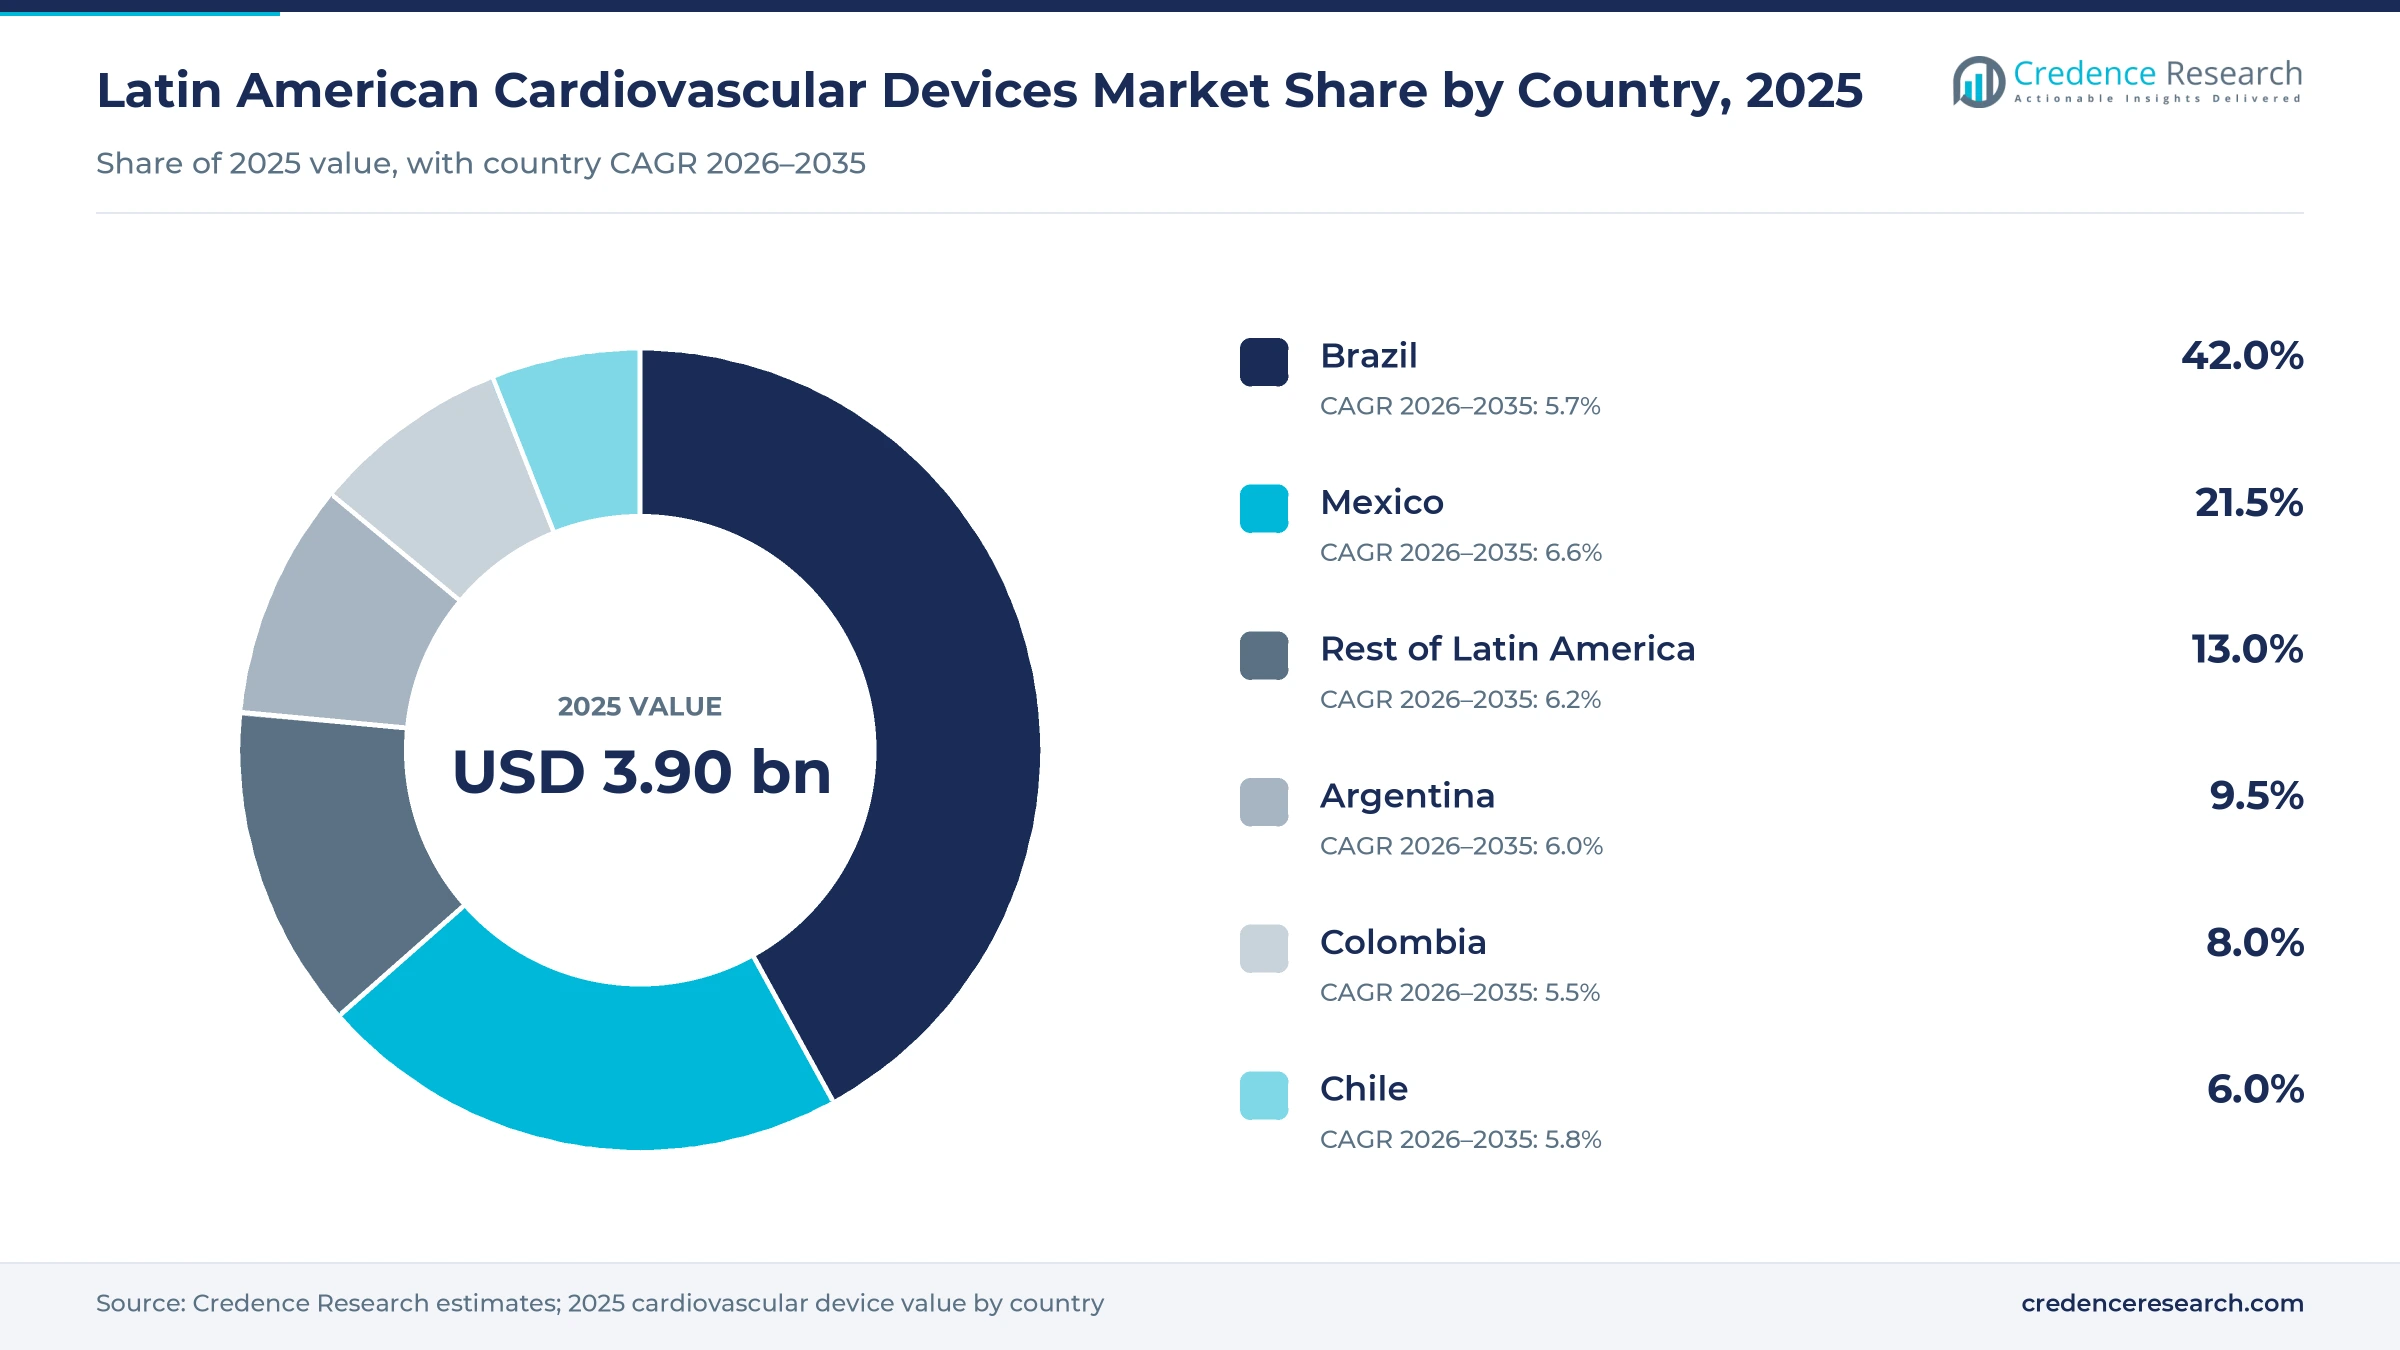
The Latin American cardiovascular devices market was valued at USD 3.90 billion in 2025 and is projected to increase from USD 4.13 billion in 2026 to USD 6.98 billion by 2035, registering a CAGR of 6.00% during 2026–2035. Demand comes from public and private hospitals that perform coronary stenting, catheter ablation, pacemaker implantation and valve replacement in a region where heart disease is the leading cause of death, and from cardiology services that buy ECG, Holter and imaging equipment. Brazil held the largest country share, 42.0% in 2025, because its public SUS network and large private hospital groups perform the most procedures in the region. Mexico is the fastest-growing country at 6.6% a year, as the IMSS adds hemodynamics rooms and widens its infarction protocol. The main commercial change is regulatory reliance, because Brazil, Mexico and Argentina now shorten or remove local reviews for devices already cleared by reference regulators, which brings new catheters and implants to hospitals sooner.
Implants, catheters and cardiac diagnostics bought by hospitals
The estimate covers coronary stents, interventional and electrophysiology catheters, pacemakers, implantable cardioverter defibrillators, cardiac resynchronization devices, heart valves and structural heart implants, and diagnostic and monitoring equipment such as ECG systems, Holter monitors, telemetry, implantable cardiac monitors and the cardiac share of MRI. Each device is counted once at the price paid by the hospital, clinic, laboratory or patient.
The estimate excludes cardiovascular drugs, physician fees, devices made in the region for export and consumer wearables sold without a medical purpose. The value chain runs from multinational and Brazilian manufacturers through local subsidiaries, importers and distributors to public networks such as the SUS and the IMSS, private hospital groups and insurers, which pay through national reimbursement tables, tenders and negotiated price lists.

Latin American Cardiovascular Devices Market Insights
- The Latin American cardiovascular devices market was valued at USD 3.90 billion in 2025 and is projected to reach USD 6.98 billion by 2035, registering a CAGR of 6.00% during 2026–2035.
- Brazil held 42.0% of 2025 value, because it performs the largest number of coronary interventions in the region through SUS and private hospitals.
- Surgical devices led product types with 66.0% of 2025 value, as stents, catheters and implants carry far higher unit prices than diagnostic equipment.
- Brazil's ANVISA opened a reliance route for Class III and IV devices on June 3, 2024, and Mexico's COFEPRIS added a 30-business-day pathway on Sept. 1, 2025.
- Pulsed field ablation reached Brazil with an ANVISA approval in April 2024, and Johnson & Johnson MedTech launched a second platform there in November 2025.
Stents lead while ablation catheters grow fastest
Why do surgical devices take most of the spending?
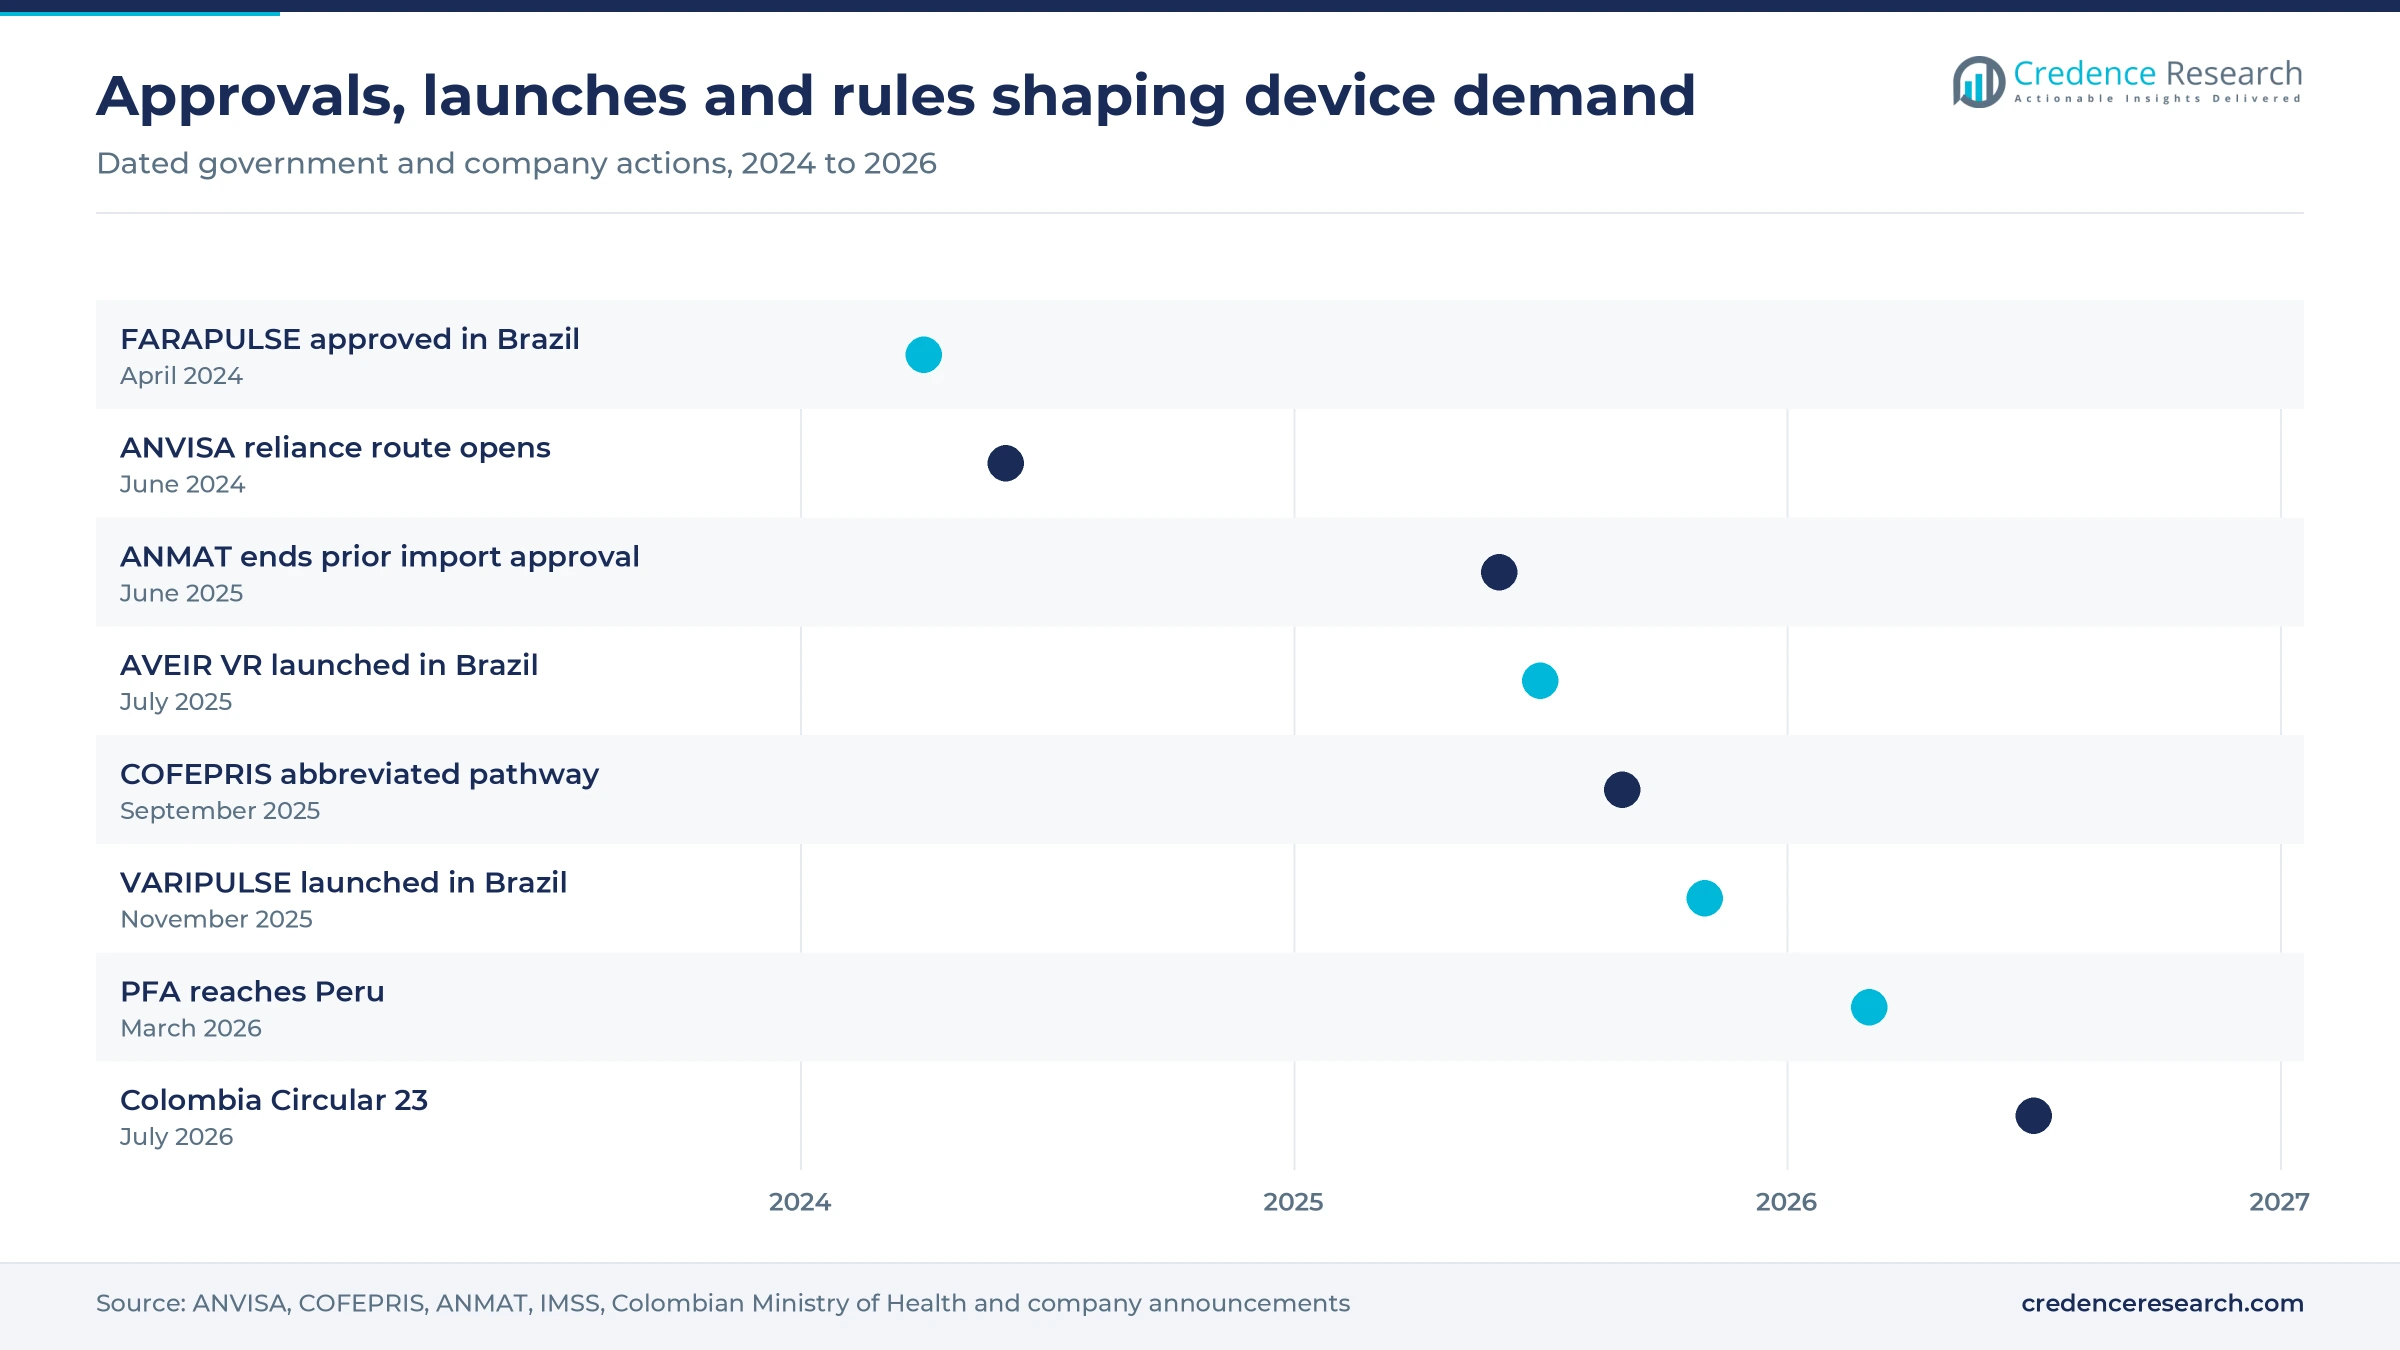
Based on product, the market is categorized into diagnostic and monitoring devices and surgical devices. Surgical Devices led with 66.0% of 2025 value, because each stent, catheter or implant is billed per procedure at a far higher price than reusable equipment, and Brazil alone performed about 175,000 coronary interventions in 2023, according to the Latin American Society of Interventional Cardiology. Diagnostic and Monitoring Devices grow fastest at 6.3% a year, as lower-risk equipment reaches buyers faster, with Argentina's ANMAT removing prior import approval for Class I and II products under Disposition 4446/2025 in June 2025 and Mexico's abbreviated COFEPRIS route shortening registration for equipment already cleared abroad.
Which monitoring devices are gaining ground?
Based on diagnostic and monitoring device type, the market is categorized into ECG, implantable cardiac monitors, Holter monitors, mobile cardiac telemetry, MRI and others. ECG led with 31.0% of 2025 value, because the resting ECG is the entry test in every chest pain pathway, and tele-ECG networks in Minas Gerais and São Paulo cut 30-day infarction mortality by more than 20%, the interventional society reports. Mobile Cardiac Telemetry grows fastest at 7.8% a year, as the pulsed field ablation launches in Brazil since April 2024 add atrial fibrillation patients who need rhythm monitoring before and after the procedure, although no public procurement data exist for telemetry, so the rate is a Credence Research estimate.
Why do coronary stents still lead surgical devices?
Based on surgical device type, the market is categorized into cardiac resynchronization therapy, implantable cardioverter defibrillators, pacemakers, coronary stents, catheters and heart valves and structural heart devices. Coronary Stents led with 30.0% of 2025 value, because stenting is the default treatment for coronary disease, and BNDES approved R$ 20 million in April 2025 for Scitech, which calls itself the main supplier of drug-eluting stents to the SUS. Catheters grow fastest at 7.1% a year, as Johnson & Johnson MedTech launched its VARIPULSE pulsed field ablation platform in Brazil in November 2025.
How much do hospitals account for?
Based on end user, the market is categorized into hospitals and clinics, diagnostic laboratories, ambulatory surgical centers and home care and others. Hospitals and Clinics led with 80.0% of 2025 value, because implants and catheters are used only in hemodynamics rooms, and the IMSS opened its sixth new hemodynamics room of 2025 at Centro Médico Nacional Siglo XXI with capacity for 1,440 procedures a year. Home Care and Others grows fastest at 7.5% a year, as Argentina's ANMAT let individuals import blood pressure monitors for personal use without a prescription from 2025, which widens home purchasing.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Surgical Devices | 66.0% | Diagnostic and Monitoring Devices | 6.3% |
| By Diagnostic and Monitoring Device Type | ECG | 31.0% | Mobile Cardiac Telemetry | 7.8% |
| By Surgical Device Type | Coronary Stents | 30.0% | Catheters | 7.1% |
| By End User | Hospitals and Clinics | 80.0% | Home Care and Others | 7.5% |
Public payment tables set what hospitals can spend
Device prices in Latin America are set mostly by public payers, which fix a procedure value or a device ceiling and leave hospitals to negotiate with suppliers inside it. Brazil's federal SUS table pays a single amount per procedure that must cover the stent or catheter, so hospitals push suppliers toward local products or delay cases. São Paulo's top-up roughly triples several cardiology payments, which lets its hospitals buy premium devices. Colombia goes further and caps the drug-eluting stent price itself. Private hospitals pay more but face insurer audits, so suppliers protect margins through new-generation products, consignment stock and training rather than list price.
| Procedure or device | Typical price or fee | Basis |
|---|---|---|
| Coronary angioplasty with stent, SUS payment | R$ 1,986.20 federal; R$ 6,256.53 with São Paulo top-up | ABC do ABC, July 2026 |
| Atrial fibrillation ablation, SUS payment | R$ 8,236.93 federal; R$ 25,946.33 with São Paulo top-up | ABC do ABC, July 2026 |
| Cardiac catheterization, SUS payment | R$ 730.04 federal; R$ 1,095.06 with São Paulo top-up | ABC do ABC, July 2026 |
| Drug-eluting coronary stent, Colombia price ceiling | COP 2,858,499.75 per unit | Circular 23 of 2026, ConsultorSalud, July 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Infarction networks and reliance rules lift procedures
Heart disease remains the leading cause of death
Cardiovascular disease sets the base volume for this market, because every infarction, arrhythmia or valve case needs diagnostic testing and often a stent, catheter or implant. Cardiovascular disease caused 2.16 million deaths in the Americas, the largest group of noncommunicable deaths, PAHO reported in July 2025. Only 36.4% of people with hypertension in the region have it under control, which keeps the pipeline of coronary and heart failure patients full. In Mexico, INEGI counted 192,563 deaths from heart disease in 2024, the leading cause of death. In Brazil, the cardiology society's Cardiômetro recorded 318,945 cardiovascular deaths in 2026 through Oct. 16. These figures point to treatment gaps rather than saturated demand, so growth depends on access more than on incidence.
Infarction networks bring more patients to cath labs
Organized infarction networks raise device use, because a patient who reaches a hemodynamics room in time receives angiography, a guidewire, a balloon and usually a stent. The IMSS Código Infarto protocol covers more than 300 hospitals and family medicine units, and reperfusion at participating centers rose from 30% to over 70%, according to the interventional society. In October 2026, Mexico's universal health service said infarction patients would be treated at participating institutions regardless of their social security coverage, La Crónica de Hoy reported. Chile's GES plan has guaranteed early ECG and reperfusion since 2005, and hospital discharges for infarction reached 19,500 in 2025, up 21% from 2022, the CIPS-UDD center reported. Each network expansion turns untreated cases into procedure volume for stent and catheter suppliers.
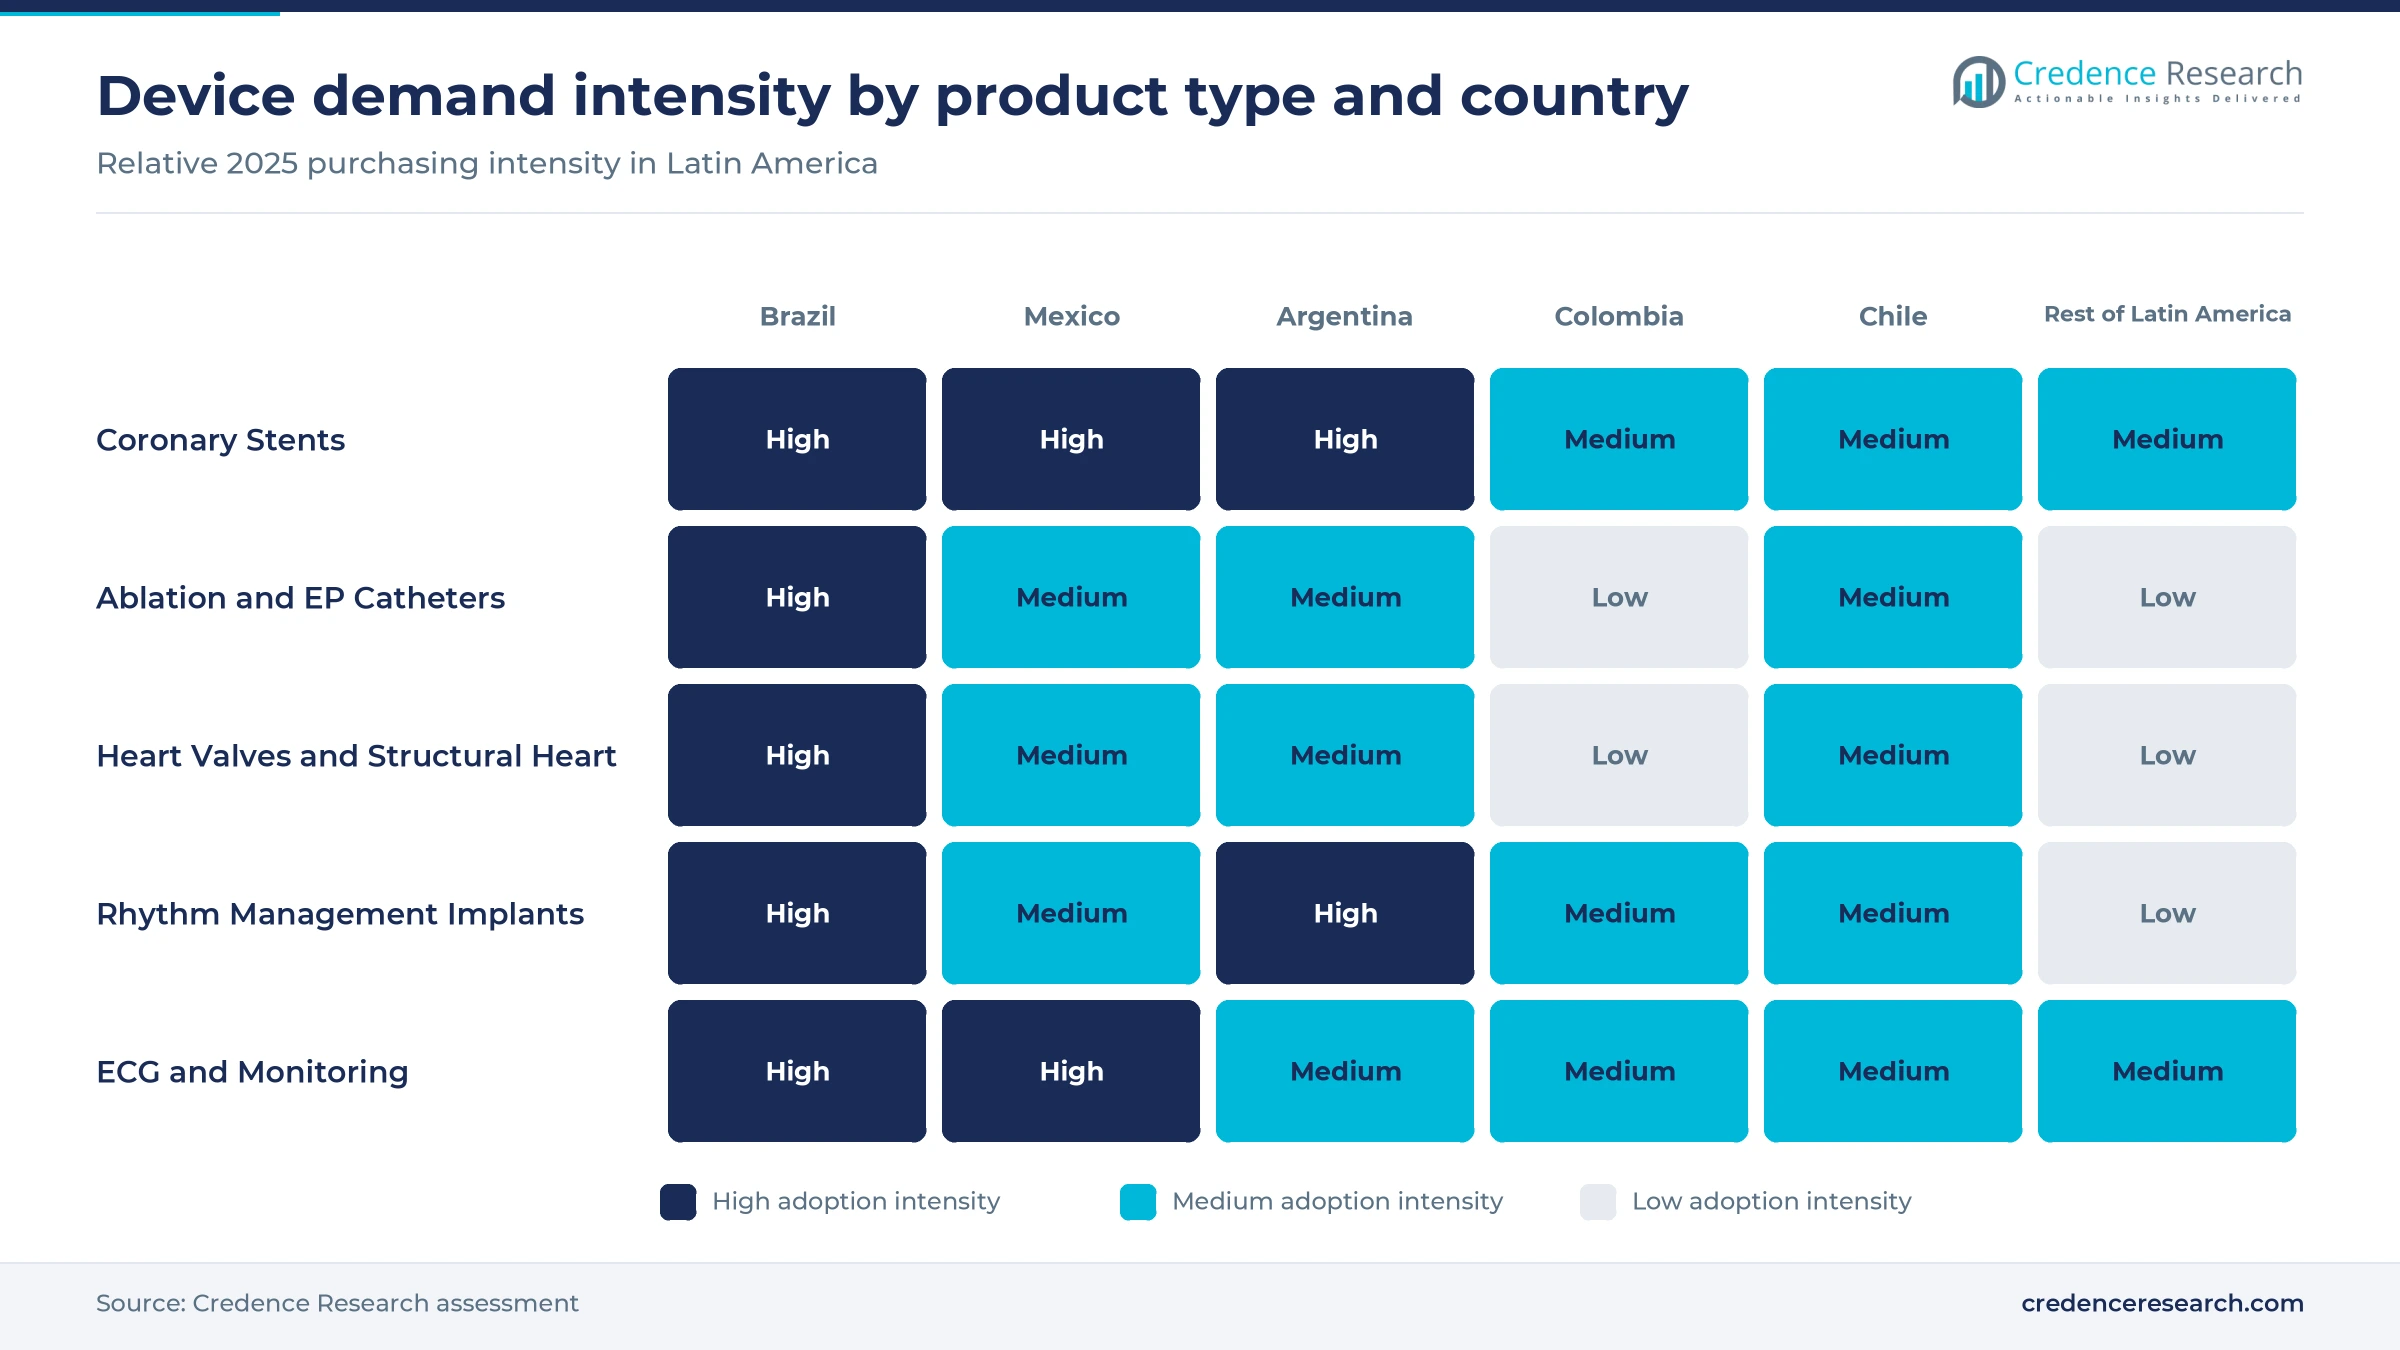
Regulatory reliance brings new devices to hospitals sooner
Regulators in the largest markets now accept foreign clearances, which shortens the gap between a global launch and the first Latin American procedure. Brazil's ANVISA lets Class III and IV devices rely on decisions by the FDA, Health Canada and the Japanese and Australian regulators under IN 290/2024, the agency states, and the route opened on June 3, 2024. COFEPRIS began a 30-business-day abbreviated pathway for devices cleared by IMDRF or MDSAP regulators on Sept. 1, 2025. Argentina also removed prior import approval for Class I and II products in 2025. Faster entry lets suppliers launch ablation catheters and new implants closer to their U.S. and European schedules, which raises the share of premium products in hospital orders.
Local production and public credit widen supply in Brazil
Brazil's push for domestic supply widens the range of lower-priced stents, catheters and valves available to public hospitals. Domestic production covers about 40% of Brazil's apparent consumption of medical devices, and the sector moved R$ 85.4 billion in 2025, Medicina S/A reported in September 2026, citing ABIMO. The Ministry of Health said about half of its PAC Saúde purchases went to Brazilian companies. BNDES approved another R$ 25 million in August 2026 for Scitech to supply interventional cardiology products to the SUS. Braile Biomédica, based in São José do Rio Preto, holds an ANVISA registration for its Inovare Alpha balloon-expandable valve. Local makers compete on price in public tenders, while multinationals keep the lead in premium implants sold to private hospitals.
Pulsed field ablation and state top-ups reshape cardiology
Shift from thermal ablation to pulsed field ablation
Electrophysiologists are shifting toward pulsed field ablation to treat atrial fibrillation faster and with less heat damage to nearby tissue, creating openings for new catheters, generators and mapping systems. ANVISA approved Boston Scientific's FARAPULSE system in April 2024, and the first Brazilian procedures followed in June 2024 at hospitals including InCor, Sírio-Libanês and Beneficência Portuguesa in São Paulo, Medicina S/A reported. São Paulo's state top-up table raised the public payment for atrial fibrillation ablation from R$ 8,236.93 to R$ 25,946.33, which makes the procedure viable for philanthropic hospitals. Hospitals that expand electrophysiology procedures now need compatible mapping systems and trained teams, which favors suppliers that sell the whole laboratory rather than a single catheter.
Rise of state top-up tables for complex cardiology
State governments are shifting toward their own reimbursement tables to keep philanthropic hospitals doing complex cardiac work for SUS patients, creating openings for implant and catheter suppliers in those states. São Paulo's Tabela SUS Paulista pays up to 215% more than the federal table for tetralogy of Fallot correction and 80% more for coronary bypass, ABC do ABC reported in July 2026. Payment for cardiac catheterization rose by 50% under the same table. Higher procedure payments let philanthropic hospitals buy more stents, catheters and ablation tools for public patients. The same change widens the gap between richer states that can fund top-ups and poorer states that rely on the federal table, so supplier volume concentrates in the Southeast.
Opportunity in TAVI for lower-risk patients
The largest open segment in structural heart is transcatheter valve replacement for patients who are neither inoperable nor very old. Public and private coverage in Brazil is limited to patients aged 75 or older who are inoperable or at high surgical risk, ABRAIDI technical director Sérgio Madeira wrote in May 2026. He cited a 2025 meta-analysis of 5,341 low-risk patients that supports wider use. The Brazilian TAVI registry already includes 2,588 analyzed patients treated at 266 centers between 2008 and 2022, with in-hospital mortality of 8.2%, Arquivos Brasileiros de Cardiologia reported. Valve makers with transcatheter heart valve replacement training programs can grow volume quickly if payers widen the criteria to intermediate-risk patients.
Opportunity in closing the coronary intervention gap
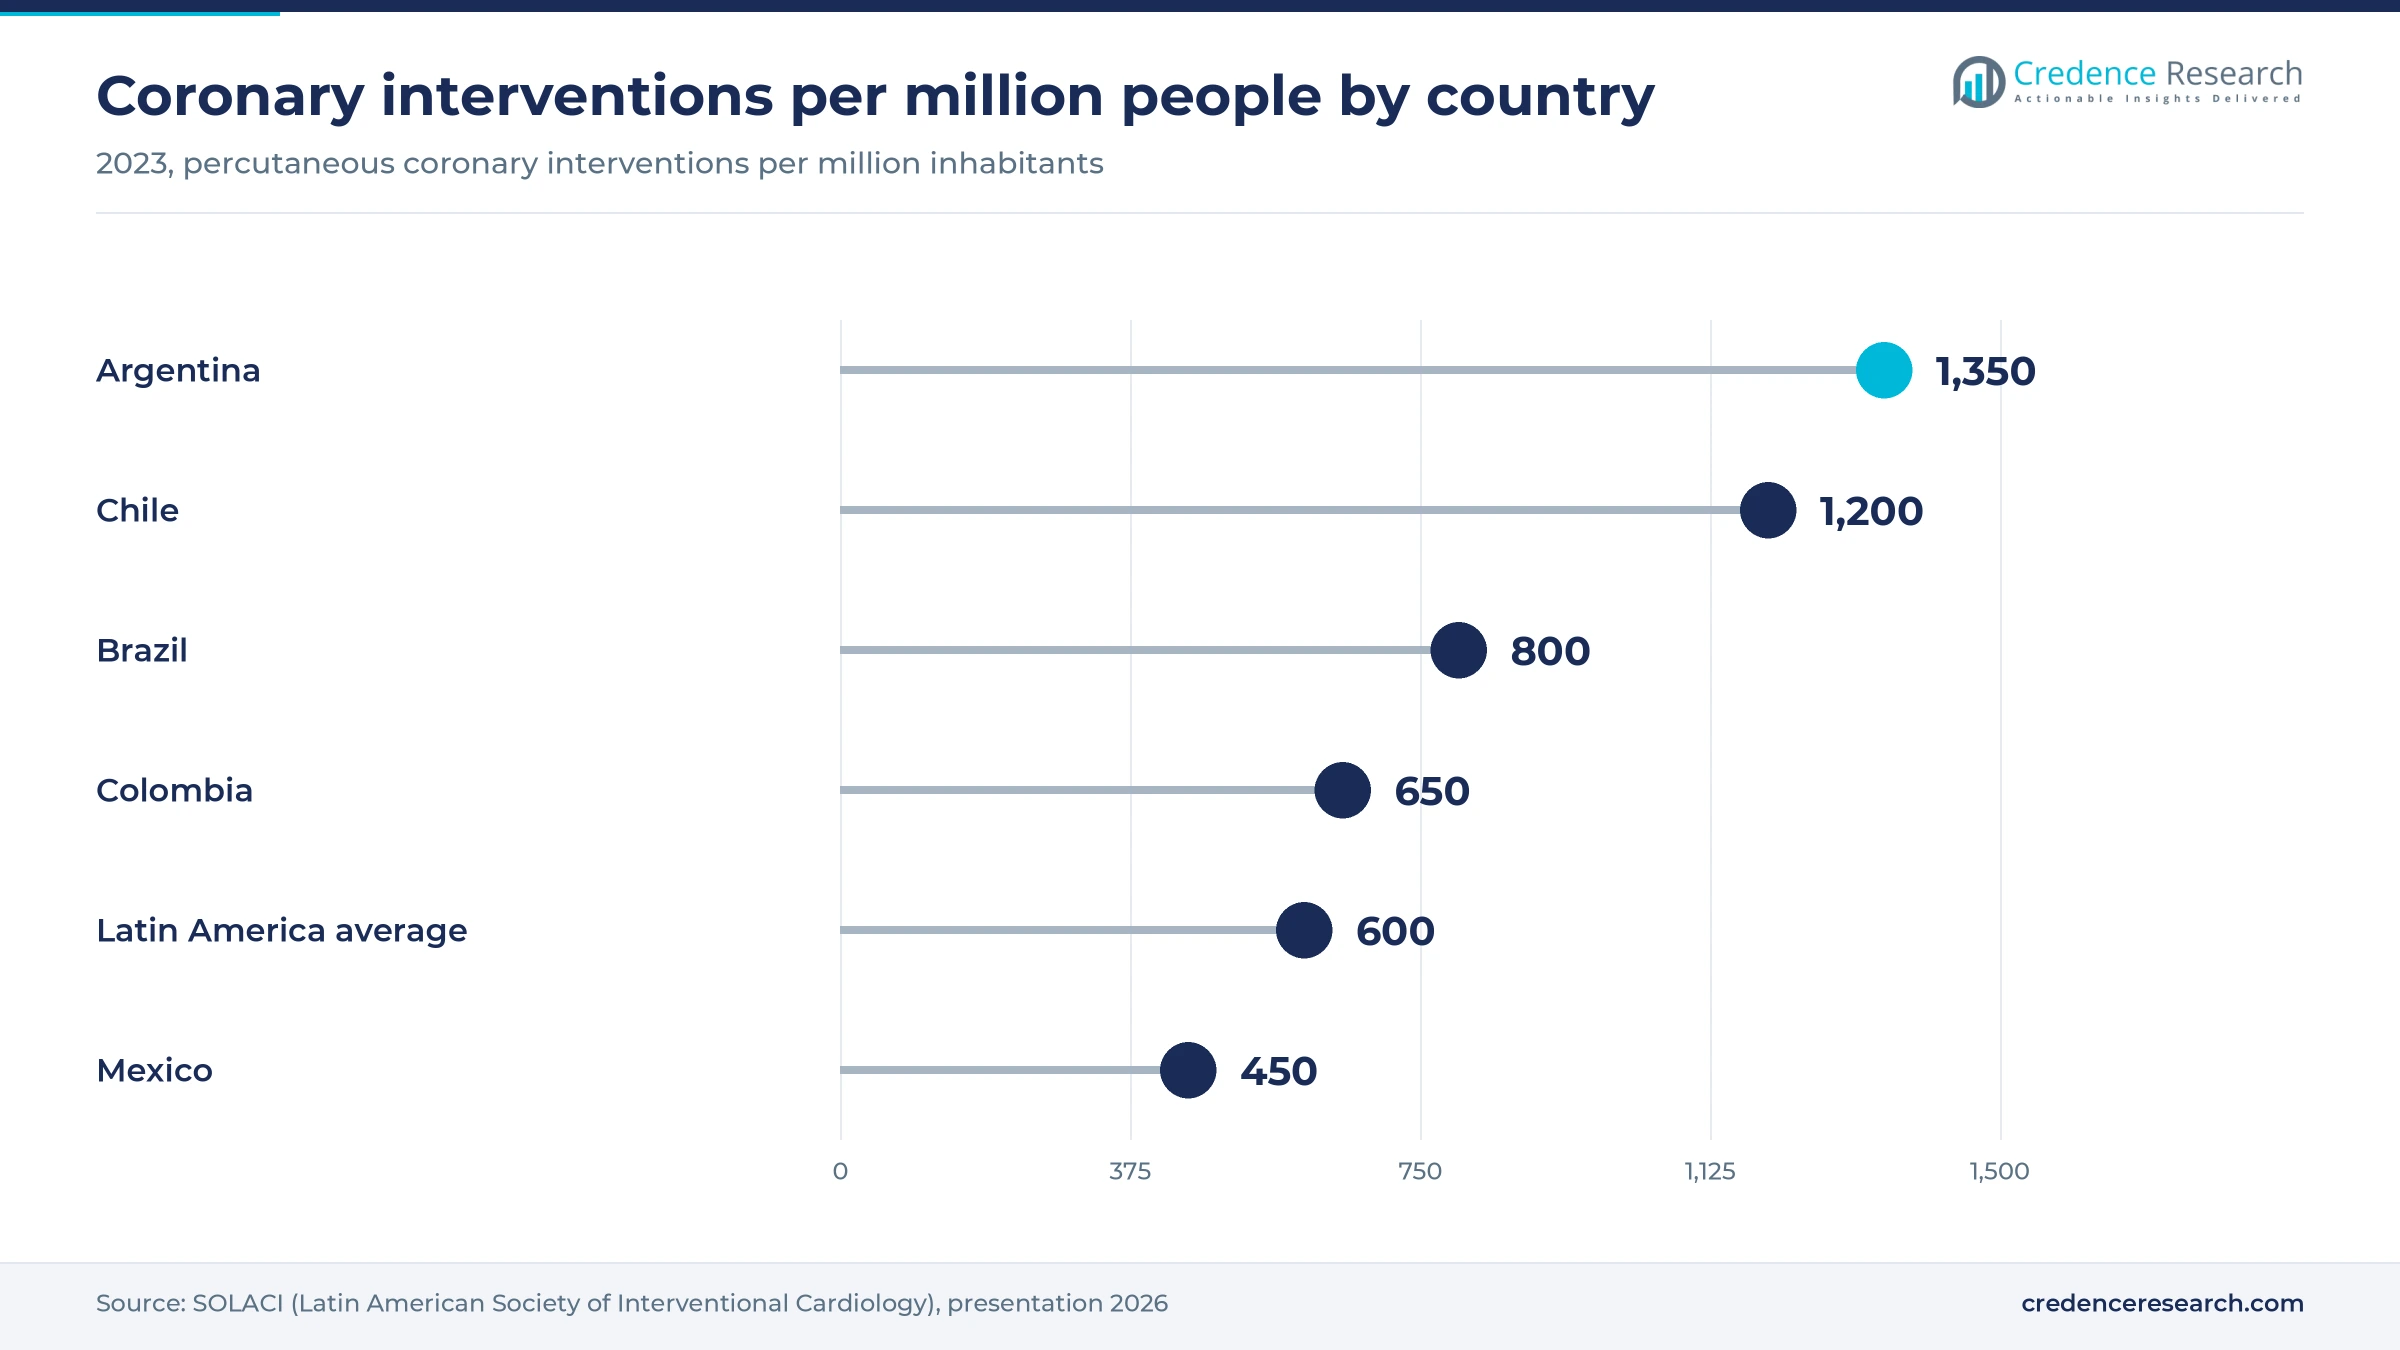
Coronary intervention rates in much of the region remain a fraction of North American levels, which leaves room for suppliers that help hospitals build primary angioplasty programs. Latin America performed about 600 coronary interventions per million people in 2023, against 2,400 in the U.S., a SOLACI presentation shows. About 40% of STEMI patients in the region still receive no reperfusion therapy. Colombia's care routes improved access in Bogotá and Medellín, but insurer authorization delays persist in the provinces. Suppliers that bundle coronary stents with training, consignment stock and network software can win share in Mexico and Colombia, where intervention rates are lowest among the large markets.
Low SUS payments, price ceilings and costly valves weigh
Federal SUS payments trail device costs
Federal SUS values leave little margin for Brazil's public hospitals and their suppliers. Portaria GM/MS 1.174 of Aug. 25, 2023 restored the device values cut in December 2021, setting R$ 2,034.50 for a drug-eluting coronary stent and R$ 4,324.34 for a single-chamber pacemaker, Conass published. Federal values remain low in 2026, since the federal table pays roughly one-third of the São Paulo top-up for an angioplasty with stent, as the price table shows. Philanthropic hospitals in states without top-ups are most exposed and ration elective cases.
Price ceilings in Colombia compress importer margins
Colombia regulates the prices of its highest-volume coronary implants directly. Circular 23 of 2026 keeps a maximum price for drug-eluting coronary stents and places defibrillators and resynchronization devices under monitored pricing, ConsultorSalud reported in July 2026. From Oct. 1, 2026, sellers must report these devices with UDI codes linked to electronic invoices. Importers and distributors absorb currency swings under a fixed peso ceiling, which can delay launches of newer stent platforms in Colombia.
U.S. tariffs weigh on regional device makers
Latin American manufacturers need export volume to reach the scale that lowers domestic prices, and U.S. trade policy now threatens that volume. Brazilian device exports fell 2.83% to US$ 1.15 billion in 2025, with the U.S. the largest destination at US$ 289.68 million, Medicina S/A reported in January 2026 amid new U.S. tariffs. Brazilian makers of catheters and stents are most exposed, because lost export orders raise unit costs for the products they also sell to the SUS.
High TAVI costs and court orders limit valve volume
Prosthesis prices keep transcatheter valve replacement expensive for public payers. A Brazilian study in the SUS setting found the total cost of TAVI significantly higher than surgery, mainly because of the valve price, ABRAIDI noted in May 2026. A Rio de Janeiro court health committee opinion of Sept. 9, 2025 confirmed that SUS covers transfemoral TAVI under the 2021 Conitec decision for inoperable patients. Patients outside those rules often need court orders, so valve suppliers face slow, case-by-case volume.
Brazil leads on volume while Mexico grows fastest
| Country | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Brazil | 1.64 | 42.0% | 5.7% |
| Mexico | 0.84 | 21.5% | 6.6% |
| Rest of Latin America | 0.51 | 13.0% | 6.2% |
| Argentina | 0.37 | 9.5% | 6.0% |
| Colombia | 0.31 | 8.0% | 5.5% |
| Chile | 0.23 | 6.0% | 5.8% |
Brazil leads on procedure volume and local makers
Brazil held a 42.0% share of 2025 value and grows at 5.7% a year. It performed about 800 coronary interventions per million people in 2023, and Abbott says more than 12 million Brazilians live with cardiovascular disease. Private networks such as Copa D'Or and Amil's hospitals were among the first to adopt pulsed field ablation, while the SUS buys most stents through tenders that favor local makers. Growth is held back by low federal payments and by marked under-treatment in the North and Northeast, the interventional society notes.
Mexico grows fastest from the lowest intervention rate
Mexico held a 21.5% share of 2025 value and grows fastest at 6.6% a year. The country performed about 60,000 coronary interventions in 2023, or roughly 450 per million people, the lowest rate among the large markets. That gap gives the most room for volume growth as the IMSS adds hemodynamics capacity and the universal infarction care noted above takes effect. The abbreviated COFEPRIS pathway also lets suppliers register products cleared abroad in weeks rather than months, which supports earlier launches.
Argentina has the highest intervention rate in the region
Argentina held a 9.5% share of 2025 value and grows at 6.0% a year. It performed about 65,000 coronary interventions in 2023, or about 1,350 per million people, the highest rate in Latin America. The Stent Save a Life program promoted quality metrics from 2016 to 2020, and the Rosario infarction network in Santa Fe reported optimal door-to-balloon times. Access to primary angioplasty outside large cities remains limited, and the 2025 import deregulation lowers costs mainly for lower-risk equipment.
Colombia grows under direct stent price control
Colombia held a 2025 value share of 8.0% and grows at 5.5% a year. The country performed about 35,000 coronary interventions in 2023, or 650 per million people, below the levels of Argentina and Chile, the other large South American markets. Care routes in Bogotá and Medellín have improved access, but the price ceiling on drug-eluting stents limits value growth even as volumes rise. Suppliers compete on service and stock agreements with insurers rather than on list price, which favors distributors with national coverage.
Chile combines guaranteed care and an older population
Chile held a 6.0% share of 2025 value and grows at 5.8% a year. It performed about 21,000 coronary interventions in 2023, or about 1,200 per million people, close to the Argentine level. Infarction deaths reached 7,353 in 2025, and the death rate in Ñuble was well above the national average, the CIPS-UDD center reported. Discharge rates were also highest in remote southern regions such as Aysén, which points to unmet need for cath lab capacity there.
Peru and central America add new programs
Rest of Latin America held a 13.0% share of 2025 value and grows at 6.2% a year. Johnson & Johnson MedTech brought pulsed field ablation to Peru in March 2026, with Clínica Delgado of the AUNA group leading the rollout. Costa Rica is the region's main device manufacturing hub, as medical devices made up 48% of its goods exports through October 2025, PROCOMER data cited by The Tico Times show. That output is shipped abroad, so it adds supply capability rather than local demand.
Approvals, launches and new capacity from 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In April 2024, Boston Scientific received ANVISA approval for its FARAPULSE pulsed field ablation system in Brazil. | Approved; first Brazilian procedures followed in June 2024 |
| In July 2025, Abbott launched the AVEIR VR leadless pacemaker in Brazil. | Launched; registered with ANVISA through St. Jude Medical Brasil |
| In November 2025, Johnson & Johnson MedTech launched its VARIPULSE pulsed field ablation platform in Brazil. | Launched; adds a second PFA platform for Brazilian electrophysiology labs |
| In December 2025, the IMSS opened a new hemodynamics room at the Hospital de Cardiología of Centro Médico Nacional Siglo XXI. | Operational; the sixth room opened in 2025, sized for six procedures a day |
| In August 2026, BNDES approved R$ 25 million in financing for Scitech to supply interventional cardiology products to the SUS. | Financing approved under the BNDES Fornecedores SUS program; follows R$ 20 million in 2025 |
PFA, leadless pacing and tele-ECG change cardiac care
- Pulsed field ablation uses short electric pulses instead of heat or cold to isolate the pulmonary veins, which shortens atrial fibrillation procedures and lowers the risk of damage to the esophagus and nearby nerves.
- Leadless pacing places a capsule about one-tenth the size of a traditional pacemaker inside the right ventricle through a catheter, avoiding chest pockets, leads and the infections they can cause.
- Tele-ECG reading sends ECGs from primary care units to central cardiologists, which speeds infarction diagnosis in towns without specialists and decides which patients are transferred to a cath lab.
- Balloon-expandable bovine valves let Brazilian makers offer lower-priced valve options for patients between conventional surgery and TAVI, using pericardial tissue and cobalt-chromium frames made in the country.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Multinationals lead implants as Brazilian makers win tenders
Competition in the Latin American cardiovascular devices market splits by therapy. In electrophysiology, Boston Scientific and Johnson & Johnson MedTech compete with pulsed field ablation platforms launched in Brazil in 2024 and 2025, and Medtronic and Abbott compete with ablation and mapping products. Medtronic, Abbott and BIOTRONIK supply pacemakers, defibrillators and resynchronization devices, and Abbott added a leadless pacemaker in Brazil in 2025. In structural heart, Edwards Lifesciences and Medtronic lead transcatheter valves, while Braile Biomédica competes as a Brazilian valve maker. Scitech Medical competes in drug-eluting stents and catheters sold to the SUS. Siemens Healthineers, GE HealthCare and Royal Philips supply cath lab imaging, MRI, ECG and patient monitoring. Registration speed, public tender pricing, clinical training and distributor coverage outside major cities decide most contracts.
How concentrated is the supply side?
Supply is concentrated in implants and more open in diagnostics. Medtronic, Abbott, Boston Scientific, Edwards Lifesciences, Johnson & Johnson MedTech and BIOTRONIK sell most rhythm devices, ablation catheters and valves through local subsidiaries and distributors. Entry barriers are ANVISA, COFEPRIS and INVIMA registration, listing in public tables and training for cath lab teams. Brazilian makers such as Scitech and Braile win public tenders on price in stents, catheters and valves. Siemens Healthineers, GE HealthCare and Philips dominate imaging, while margins sit mainly in new-generation implants sold to private hospitals.
Key cardiovascular device suppliers in Latin America
| Company | Type | Role in the market |
|---|---|---|
| Medtronic | Full-line supplier | TAVI valves, pacemakers, defibrillators, stents and ablation catheters |
| Abbott | Full-line supplier | AVEIR leadless pacemakers, rhythm devices, structural heart and vascular products |
| Boston Scientific Corporation | Full-line supplier | FARAPULSE pulsed field ablation, mapping, stents and rhythm devices |
| Edwards Lifesciences Corporation | Structural heart specialist | Transcatheter and surgical heart valves |
| Johnson & Johnson MedTech | Electrophysiology specialist | VARIPULSE pulsed field ablation and cardiac mapping systems |
| BIOTRONIK SE & Co. KG | Specialist | Pacemakers, defibrillators, CRT devices and vascular intervention products |
| Siemens Healthineers | Imaging supplier | Angiography systems, cardiac MRI and CT for cath labs and radiology |
| GE HealthCare | Imaging and monitoring supplier | Cath lab imaging, cardiac MRI, ECG and patient monitoring |
| Royal Philips | Imaging and monitoring supplier | Interventional X-ray, cardiac ultrasound and patient monitoring |
| Scitech Medical | Local manufacturer | Brazilian drug-eluting stents, balloon catheters and guidewires for the SUS |
| Braile Biomédica | Local manufacturer | Brazilian biological heart valves including the Inovare Alpha valve |
Access to cath labs decides growth more than disease burden
Credence Research's view is that spending on Latin American cardiovascular devices is limited by access to cath labs and by public payment levels, not by disease burden. Infarction networks in Mexico and Chile, reliance pathways in Brazil and Mexico and state top-ups in São Paulo are loosening those limits at different speeds. Multinational suppliers keep the advantage in ablation, rhythm devices and valves, where clinical data and training decide contracts. Brazilian makers gain in public tenders for stents and catheters. The main risk is currency and payment pressure, which can stall premium launches even when clinical demand is clear.
Country procedure volumes anchor the regional estimate
The report uses 2025 as the base year and forecasts to 2035. Market values come from the Credence Research model, which updates the earlier edition and checks it against country-level device spending, coronary intervention volumes by country, public procedure payments and the 2025 exchange rates. Country and segment splits are Credence Research estimates based on intervention volumes, population and procedure patterns. Sources include ministries, regulators, public insurers, PAHO, medical societies, peer-reviewed studies, company announcements and regional health media. No interviews or surveys were conducted by Credence Research for this edition.
Ablation and structural heart gain share to 2035
The Latin American cardiovascular devices market is expected to grow from USD 4.13 billion in 2026 to USD 6.98 billion by 2035 as infarction networks and new therapies reach more patients. Catheters grow fastest among surgical devices at 7.1% a year as pulsed field ablation spreads beyond the leading private hospitals. Mobile cardiac telemetry grows fastest in monitoring at 7.8% a year. Mexico gains share as its intervention rate catches up, while Brazil keeps the largest absolute purchases. Coronary stents stay the largest surgical item but lose share as ablation and valve procedures take a larger part of budgets.
Payment reform and cath lab access decide the range
The spread between the cases depends on how far public payers update procedure values and how quickly infarction networks bring patients to cath labs. A wider Brazilian TAVI rule and faster IMSS capacity growth would lift volumes, while weaker currencies, tighter Colombian ceilings and U.S. tariffs would hold value down. The base case keeps the 6.00% CAGR through 2035, led by ablation catheters and structural heart devices.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 4.5% | USD 6.14 billion | Currencies weaken, SUS values stay frozen and Colombia extends price ceilings to more implants |
| Base | 6.00% | USD 6.98 billion | Reliance pathways, state top-ups and infarction networks expand at their 2025 and 2026 pace |
| Upside | 7.3% | USD 7.79 billion | Brazil widens TAVI criteria and Mexico funds cath labs for universal infarction care |
Frequently Asked Questions
How big is the Latin American cardiovascular devices market?
Which country leads the market?
Which South American countries lead demand after Brazil?
Which device type has the largest share?
How is interventional cardiology access changing in Mexico?
Which cardiac implants and structural heart devices are gaining ground?
What are the main challenges for suppliers?
Who are the leading suppliers in the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Surgical Devices
- 1.2.2 Diagnostic and Monitoring Devices
- 1.3 By Diagnostic and Monitoring Device Type
- 1.3.1 ECG
- 1.3.2 MRI
- 1.3.3 Holter Monitors
- 1.3.4 Mobile Cardiac Telemetry
- 1.3.5 Implantable Cardiac Monitors
- 1.3.6 Others
- 1.4 By Surgical Device Type
- 1.4.1 Coronary Stents
- 1.4.2 Catheters
- 1.4.3 Pacemakers
- 1.4.4 Heart Valves and Structural Heart Devices
- 1.4.5 Implantable Cardioverter Defibrillators (ICDs)
- 1.4.6 Cardiac Resynchronization Therapy (CRT)
- 1.5 By End User
- 1.5.1 Hospitals and Clinics
- 1.5.2 Diagnostic Laboratories
- 1.5.3 Ambulatory Surgical Centers
- 1.5.4 Home Care and Others
- 1.6 By Country
- 1.6.1 Brazil
- 1.6.2 Mexico
- 1.6.3 Argentina
- 1.6.4 Colombia
- 1.6.5 Chile
- 1.6.6 Rest of Latin America
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 3.90 billion → 2035: USD 6.98 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Latin American Cardiovascular Devices Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Latin American Cardiovascular Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Latin American Cardiovascular Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Latin American Cardiovascular Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Latin American Cardiovascular Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Latin American Cardiovascular Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Latin American Cardiovascular Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Latin American Cardiovascular Devices Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 3.90 billion → 2035: USD 6.98 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Latin American Cardiovascular Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Surgical Devices
- 12.3.7.2 Diagnostic and Monitoring Devices
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Diagnostic and Monitoring Device Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 ECG
- 12.4.7.2 MRI
- 12.4.7.3 Holter Monitors
- 12.4.7.4 Mobile Cardiac Telemetry
- 12.4.7.5 Implantable Cardiac Monitors
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Surgical Device Type - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Coronary Stents
- 12.5.7.2 Catheters
- 12.5.7.3 Pacemakers
- 12.5.7.4 Heart Valves and Structural Heart Devices
- 12.5.7.5 Implantable Cardioverter Defibrillators (ICDs)
- 12.5.7.6 Cardiac Resynchronization Therapy (CRT)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By End User - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Hospitals and Clinics
- 12.6.7.2 Diagnostic Laboratories
- 12.6.7.3 Ambulatory Surgical Centers
- 12.6.7.4 Home Care and Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 By Country - Market Size and Forecast, 2025-2035
- 12.7.1 Segment Definition and Scope
- 12.7.2 Historical Market Size, 2018-2025
- 12.7.3 Revenue Forecast, 2025-2035
- 12.7.4 Volume Forecast, 2025-2035
- 12.7.5 Base-Year Market Share, 2025
- 12.7.6 Segment CAGR and Growth Drivers
- 12.7.7 Subsegment Market Size and Forecast
- 12.7.7.1 Brazil
- 12.7.7.2 Mexico
- 12.7.7.3 Argentina
- 12.7.7.4 Colombia
- 12.7.7.5 Chile
- 12.7.7.6 Rest of Latin America
- 12.7.8 Subsegment Pricing and Adoption Trends
- 12.7.9 Leading Suppliers and Competition
- 12.7.10 Regional Demand and Opportunities
- 12.8 Segment Growth Comparison
- 12.9 Segment Attractiveness and Priority Matrix
Chapter 13 Latin American Cardiovascular Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Latin American Cardiovascular Devices Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Country-Level Shares, 2025
- 14.2 Country Market Size Comparison, 2025
- 14.3 Country Market Forecasts, 2025-2035
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Latin American Cardiovascular Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Latin American Cardiovascular Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Medtronic
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Abbott
- 18.4 Boston Scientific Corporation
- 18.5 Edwards Lifesciences Corporation
- 18.6 Johnson & Johnson MedTech
- 18.7 BIOTRONIK SE & Co. KG
- 18.8 Siemens Healthineers
- 18.9 GE HealthCare
- 18.10 Royal Philips
- 18.11 Scitech Medical
- 18.12 Braile Biomédica
- 18.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

