
Chronic disease and new approvals drive medicine spending
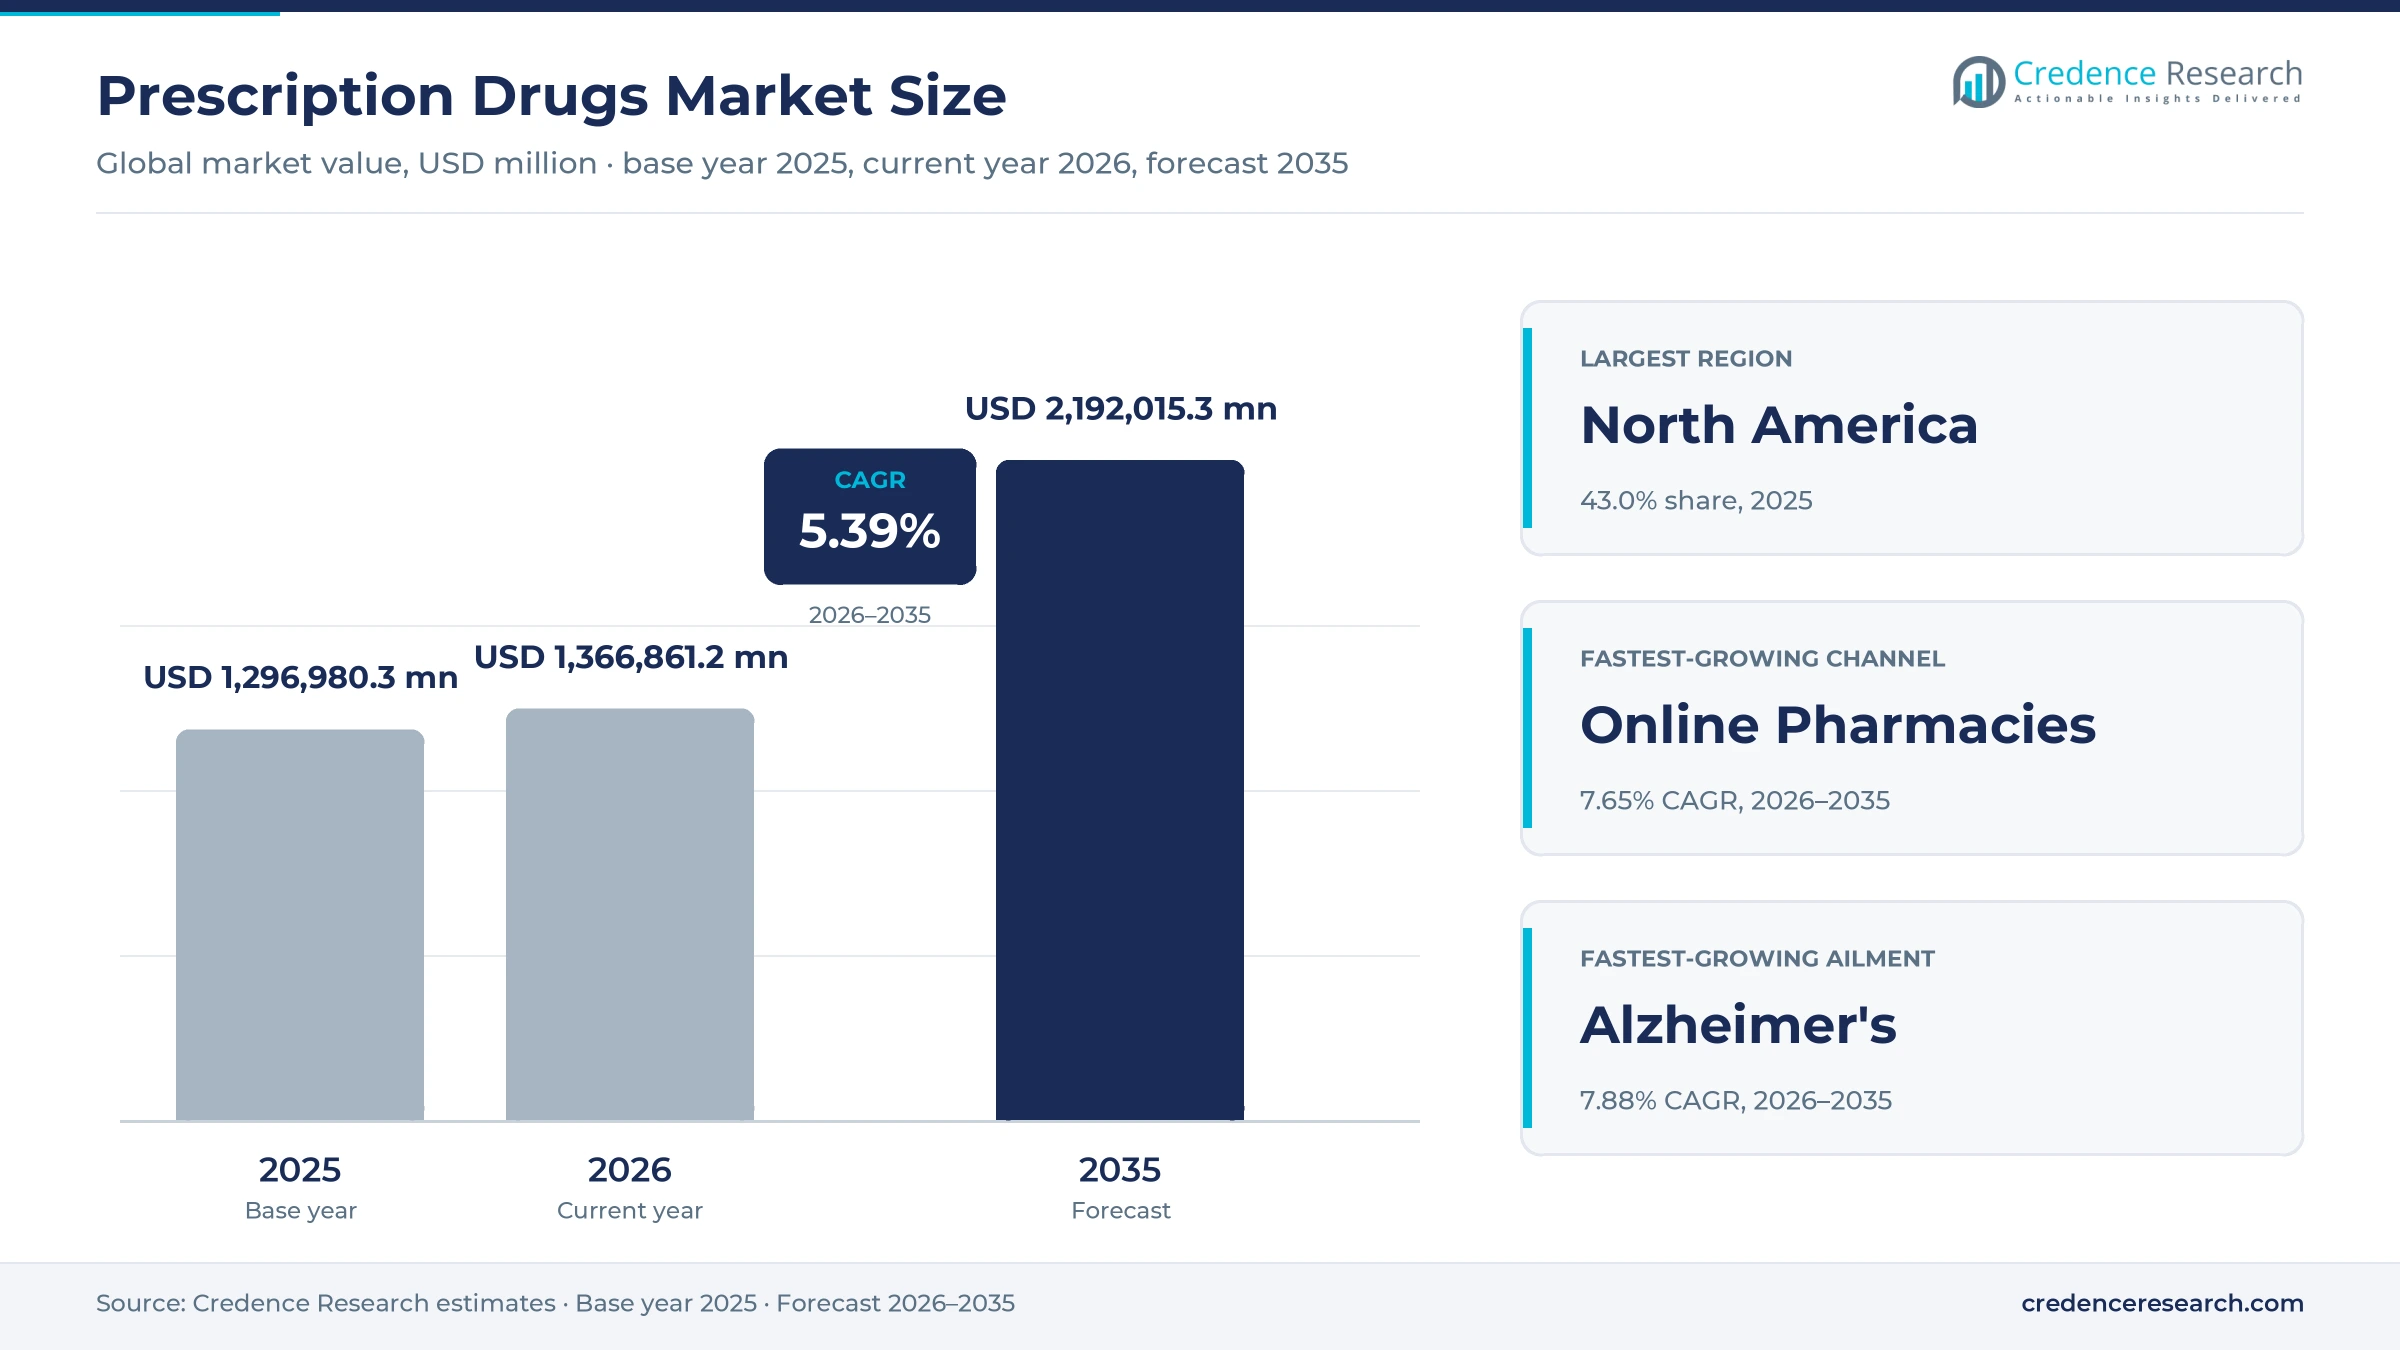
The global prescription drugs market was valued at USD 1,296.98 billion in 2025 and is projected to increase from USD 1,366.86 billion in 2026 to USD 2,192.02 billion by 2035, registering a CAGR of 5.39% during 2026–2035. Spending rises because aging populations live longer with cancer, dementia, pain and heart disease, while regulators keep clearing first-in-class medicines and generics widen access to older therapies. North America held the largest regional share, 43.0% in 2025, because the United States pays the highest list prices for branded medicines and launches most new molecules first. Asia Pacific is the fastest-growing region at 6.56% a year, as China, India and Southeast Asia widen insurance coverage and hospital capacity. Pricing policy also changed in January 2026, when Medicare negotiated prices for its first group of high-spend Part D medicines took effect. As a result, growth now leans more on patient volume and new launches than on list price increases.
Which medicines and channels does this analysis count?
The analysis counts branded, orphan and generic medicines that require a prescriber's order, across tablets, injectables, inhalers and infusions. Hospitals, retail pharmacies and online pharmacies dispense these products, while insurers, public health systems and patients pay for them under negotiated or listed prices.
Over-the-counter medicines, vaccines bought by public immunization programs and medical devices sit outside the value counted here. The value chain runs from research and clinical trials through manufacturing, wholesale distribution and pharmacy dispensing to reimbursement by public and private payers.
Prescription Drugs Market Insights
- The prescription drugs market grows from USD 1,296.98 billion in 2025 to USD 2,192.02 billion by 2035, a 5.39% CAGR as patient numbers and new launches rise.
- North America held 43.0% of global value in 2025, because the United States pays the highest prices for branded medicines.
- Alzheimer's medicines grow fastest among ailments at 7.88% a year, while online pharmacies grow fastest among channels at 7.65% through 2035.
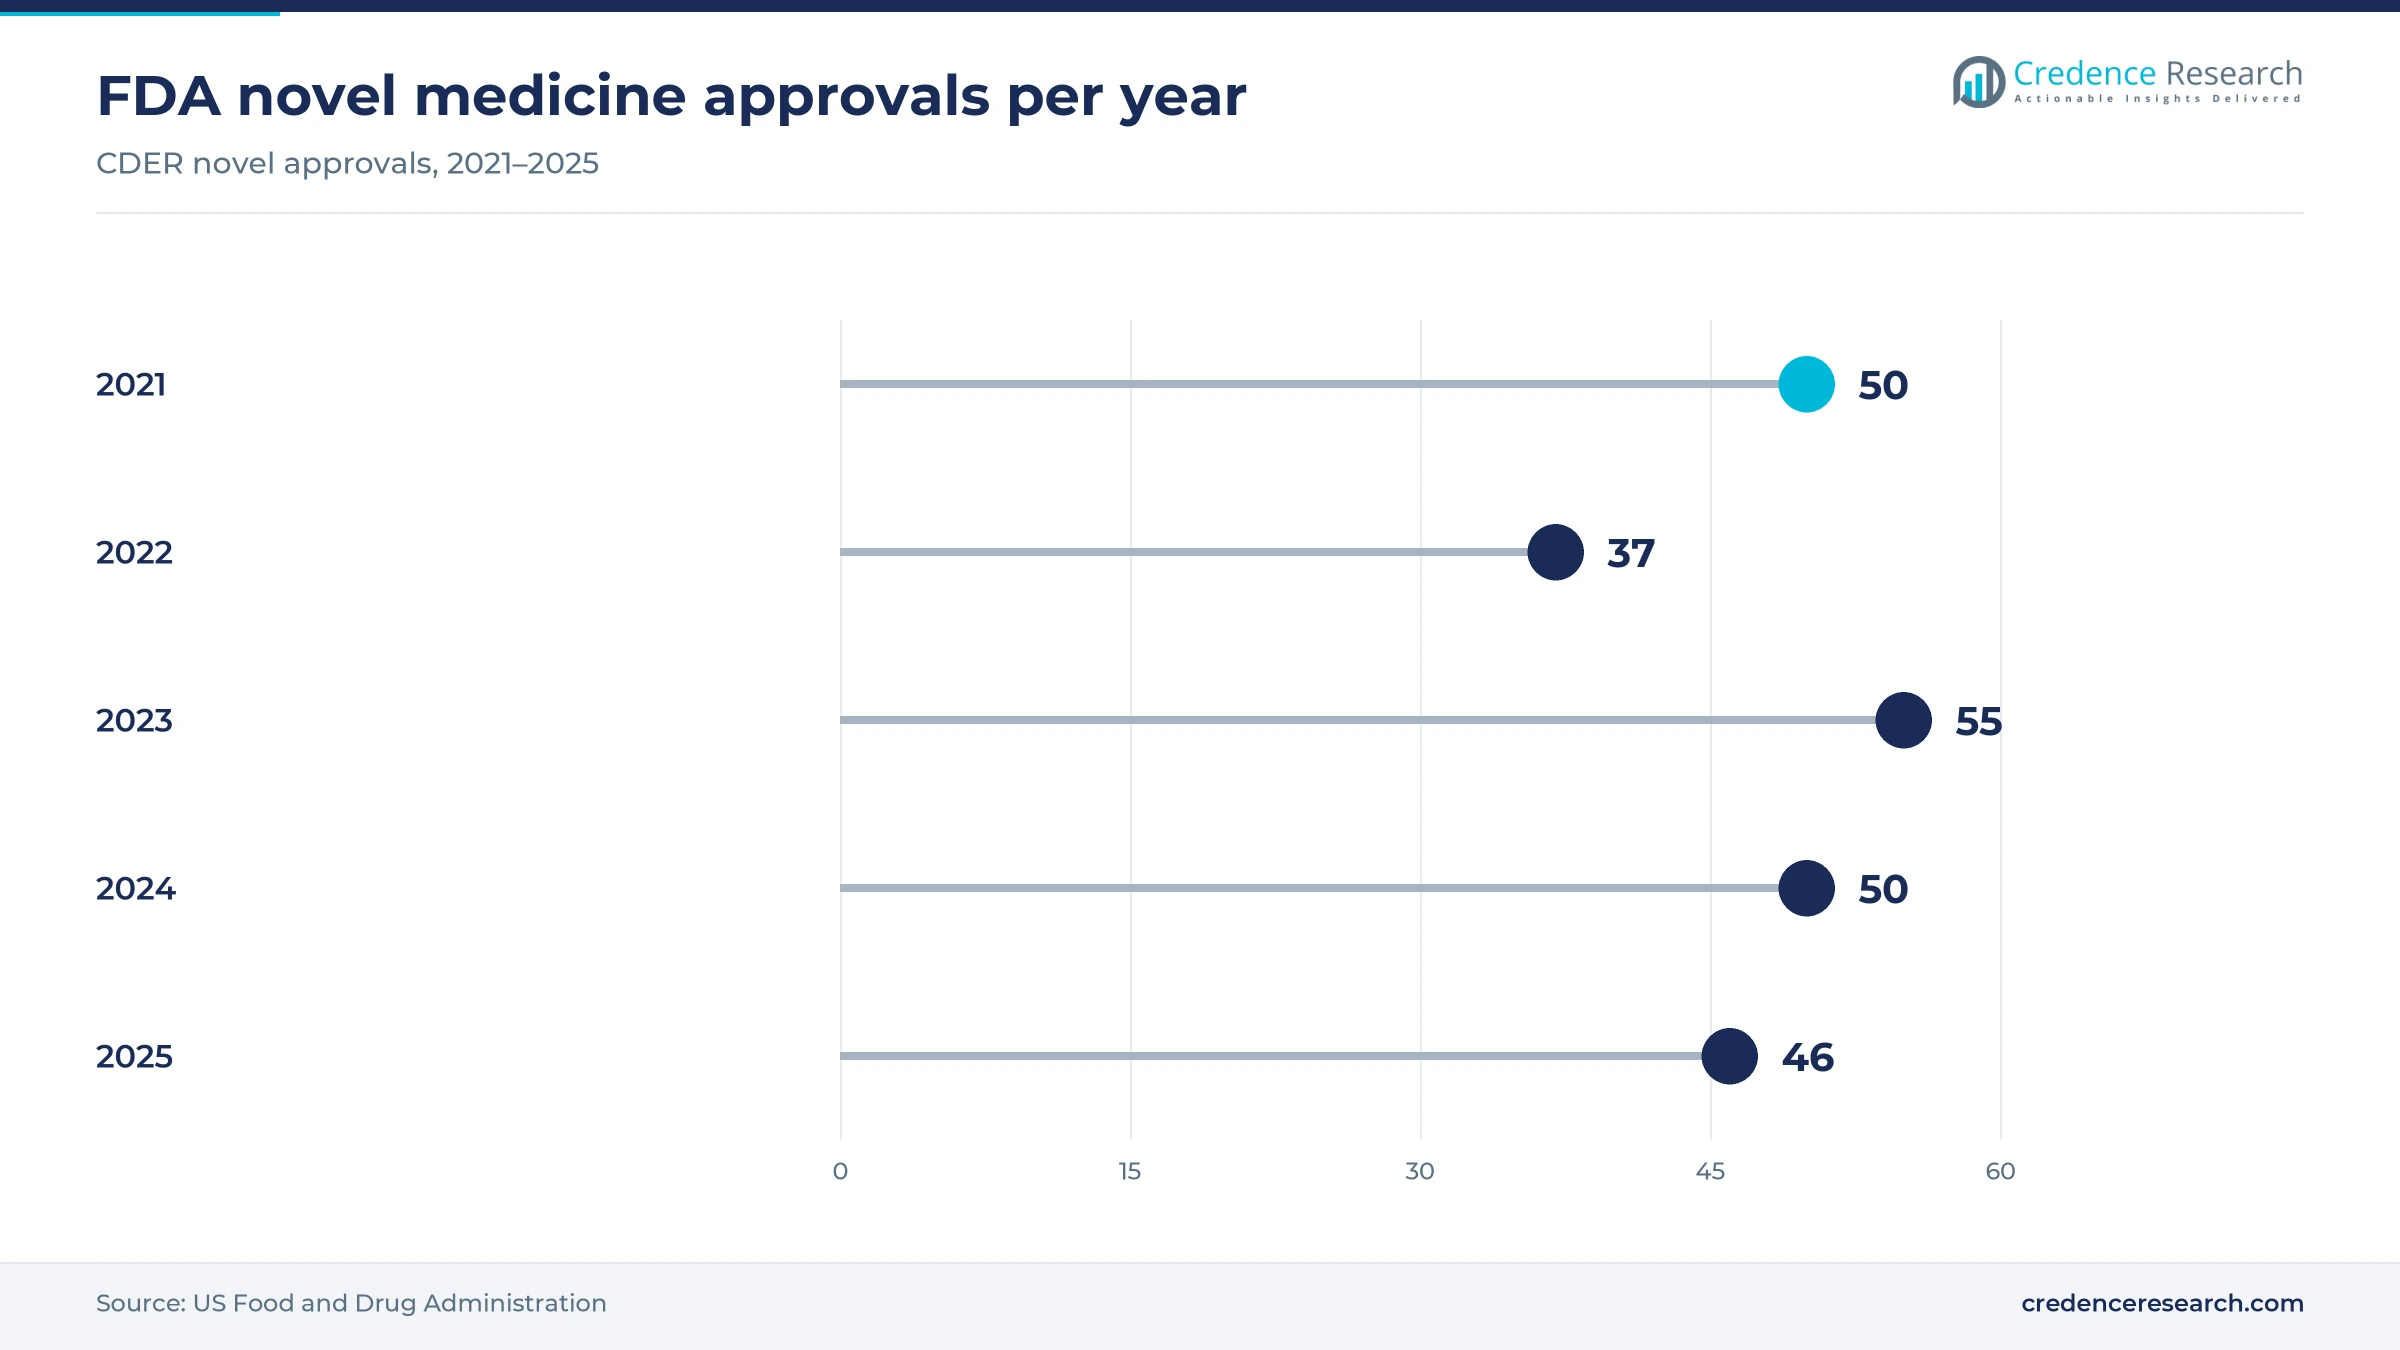
- The FDA approved 46 novel medicines in 2025, including Journavx in January 2025 as a first-in-class non-opioid option for acute pain.
- In 2024, generics and biosimilars filled 90% of U.S. prescriptions yet accounted for only 12% of spending, which keeps volume growth affordable.
Chronic conditions lead while Alzheimer's care grows fastest
Which conditions account for most medicine spending?
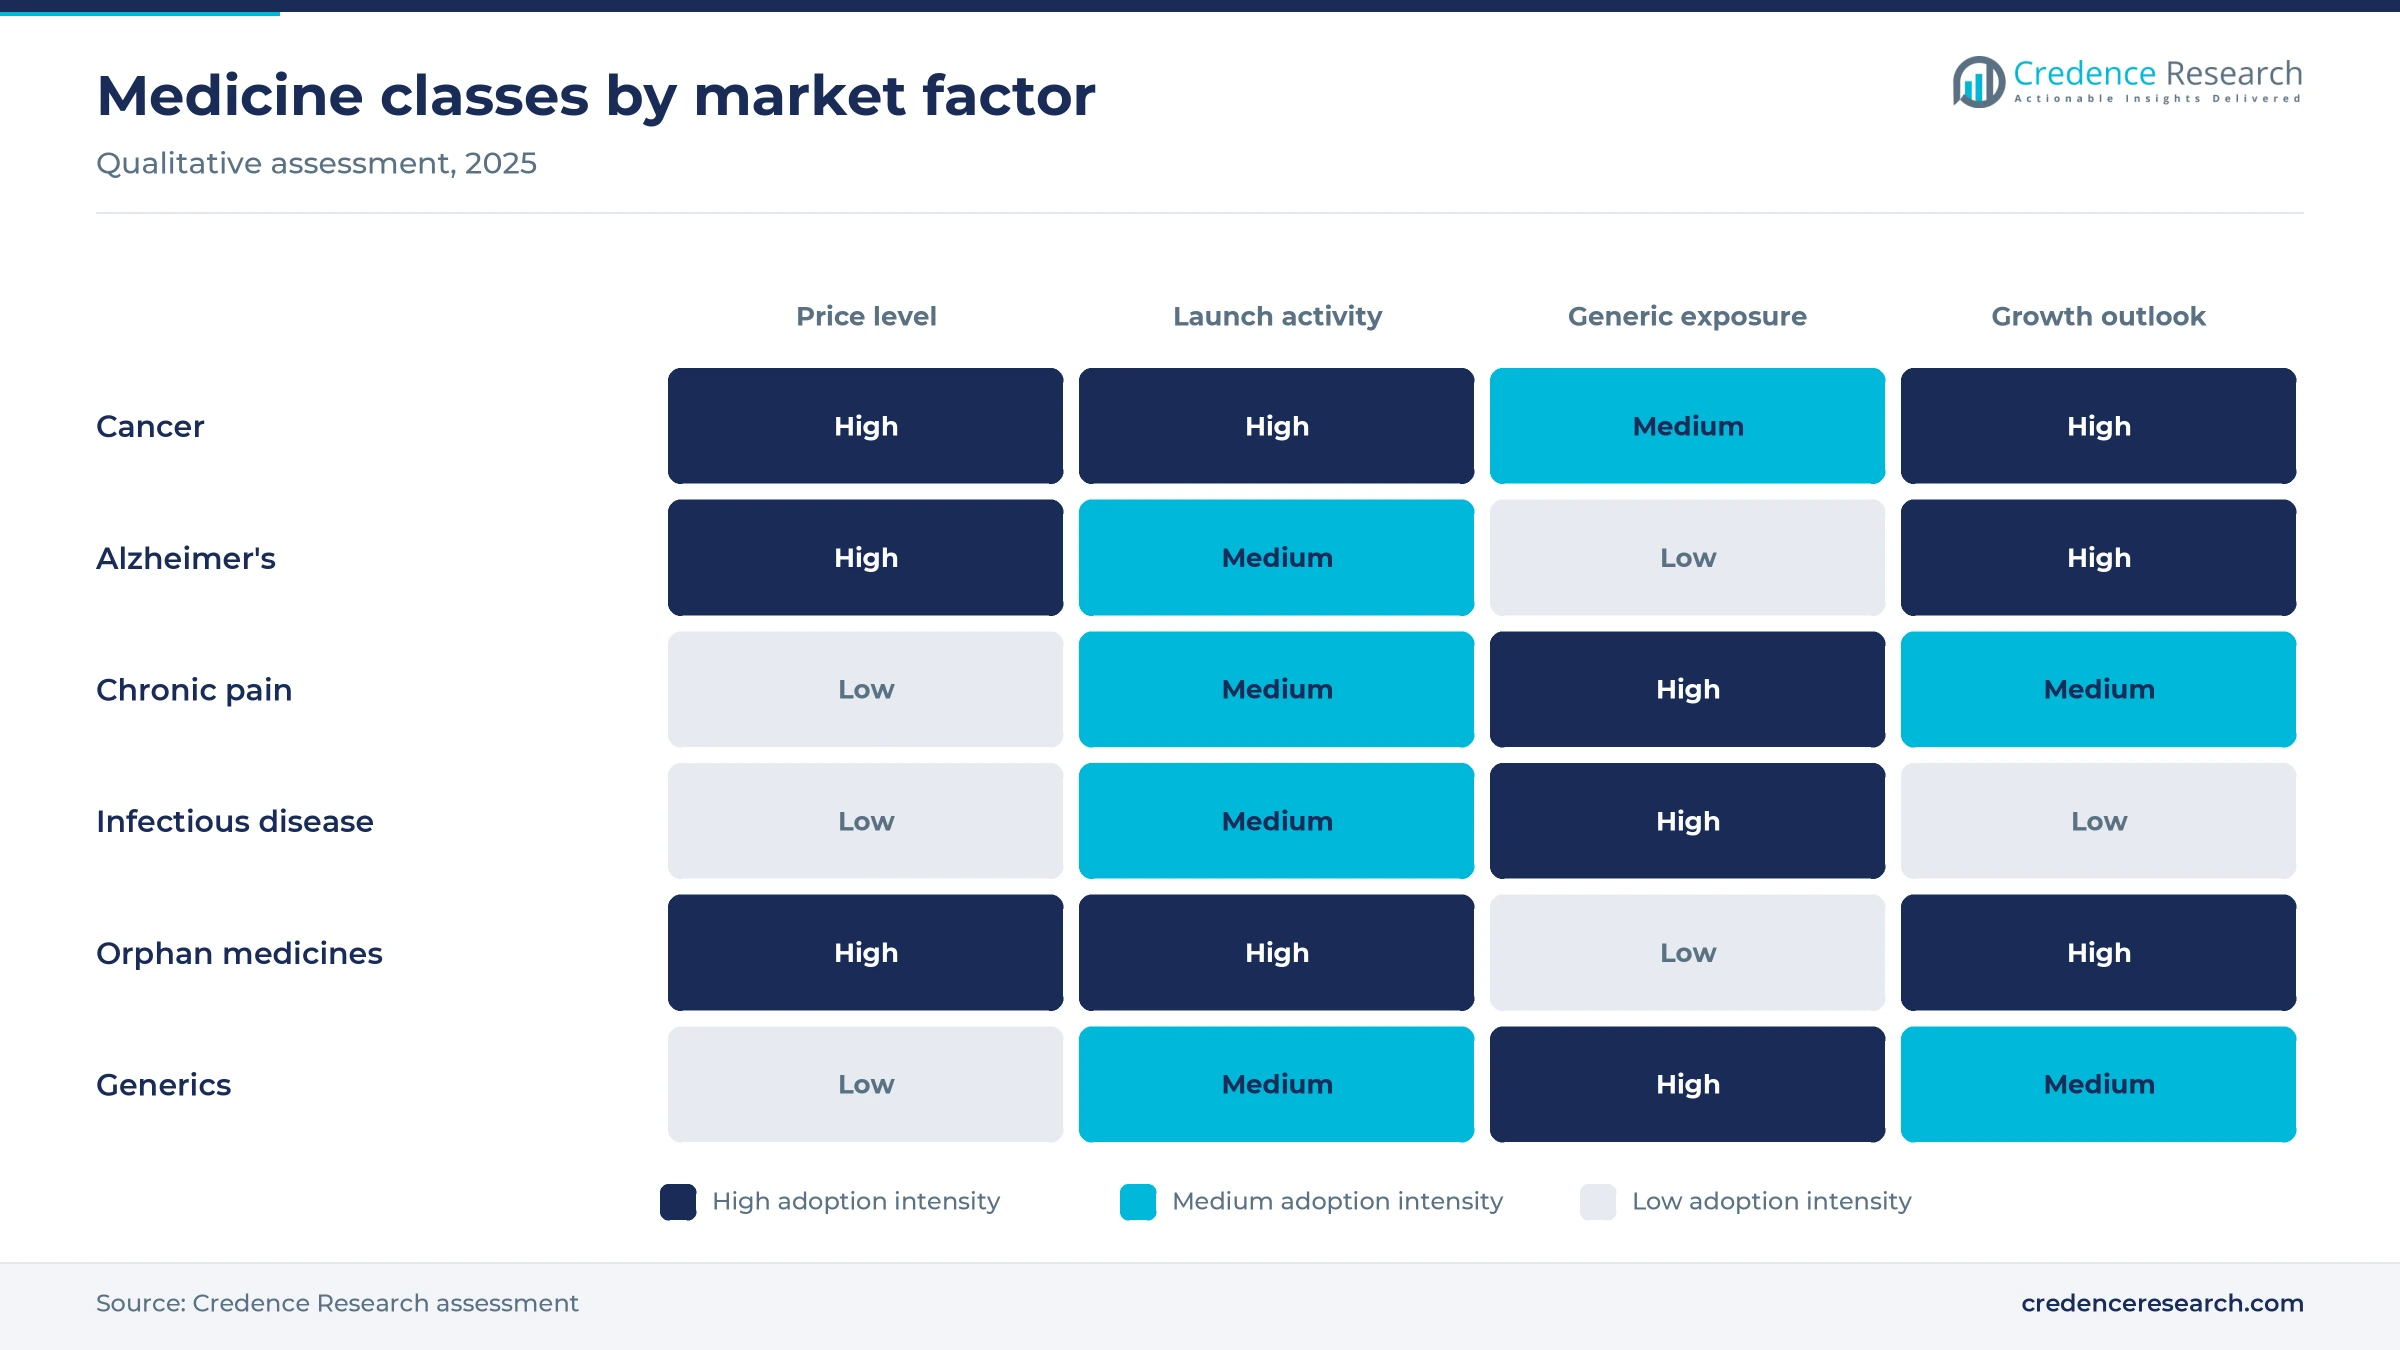
Based on ailment, the market is categorized into Alzheimer's, Parkinson's, migraine, chronic pain, cancer, infectious disease and others. The others group, which covers diabetes, cardiovascular, immune and respiratory conditions, led with 45.0% of 2025 value. Cancer is the largest single named ailment, because targeted and immune therapies carry high prices. Alzheimer's medicines grow fastest at 7.88% a year, as amyloid-targeting antibodies widen treatment of early disease.
How do branded, orphan and generic medicines split value?
Based on product type, the market is categorized into generic, orphan and others. The others group, made up of branded medicines without orphan status, led with 58.0% of 2025 value, because patent-protected therapies for common conditions command high prices. Orphan medicines grow fastest at 6.97% a year, as regulators clear more rare disease therapies. Generics hold most dispensed volume but a smaller value share.
Where do patients collect their medicines?
Based on distribution channel, the market is categorized into hospital pharmacies, retail pharmacies and drug stores and online pharmacies. Retail Pharmacies & Drug Stores led with 47.0% of 2025 value, because most chronic therapy refills happen at community counters. Online Pharmacies grow fastest at 7.65% a year, as insurers and health systems promote home delivery for repeat medicines. Hospital pharmacies handle infused cancer and specialty therapies that need clinical supervision.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Ailment | Others | 45.0% | Alzheimer's | 7.88% |
| By Product Type | Others | 58.0% | Orphan | 6.97% |
| By Distribution Channel | Retail Pharmacies & Drug Stores | 47.0% | Online Pharmacies | 7.65% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Aging, innovation and generic access expand treated patients
How is population aging raising medicine use?
Population aging is the broadest demand driver, because older adults take more medicines, for more conditions and for longer periods than younger patients. The World Health Organization reports that 57 million people were living with dementia worldwide in 2021, with nearly 10 million new cases each year. More than 60% of those patients live in low- and middle-income countries, where diagnosis and treatment rates remain low today. The WHO also reports that cancer caused nearly 10 million deaths in 2024, close to one in six deaths worldwide. Both conditions require long courses of specialist therapy once diagnosed. As a result, Alzheimer's disease treatment and cancer care add treated patients faster than most other ailments in the forecast period.
Why do first-in-class approvals keep lifting spending?
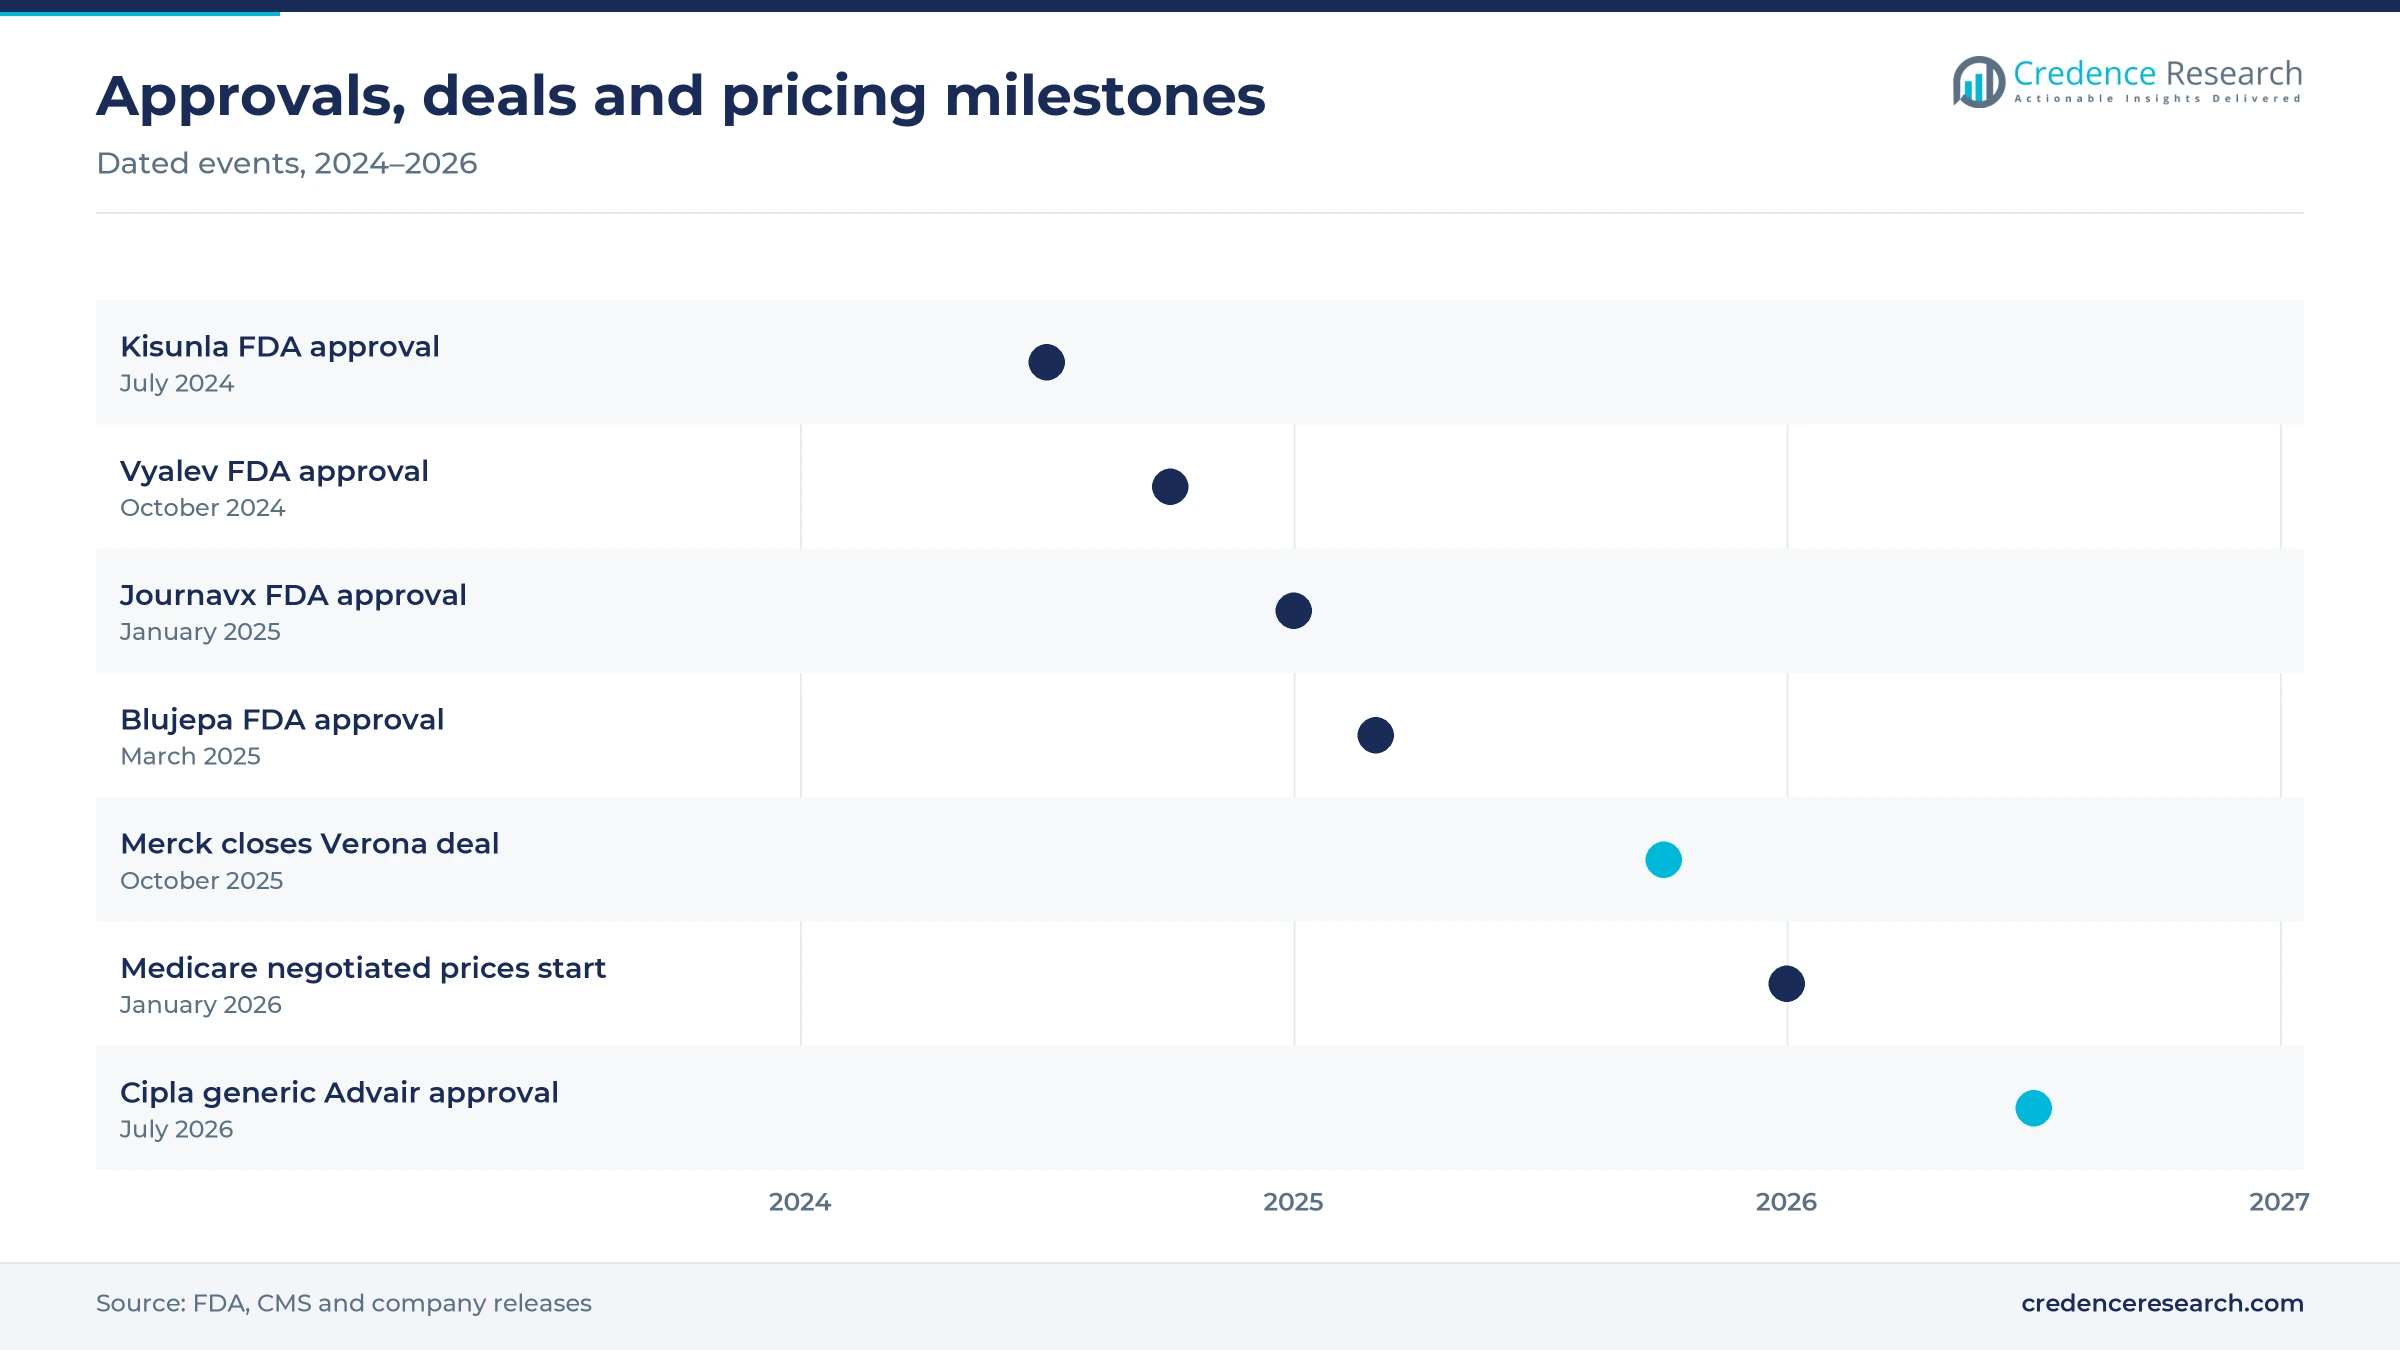
First-in-class approvals lift spending, because new mechanisms command premium prices and often treat patients who had no suitable option before. The FDA drug center approved 50 novel medicines in 2024 and 46 in 2025, according to its list of 2025 novel approvals. In January 2025, the FDA approved Vertex's Journavx for moderate to severe acute pain in adults, a non-opioid option that blocks a pain-signaling sodium channel. In March 2025, regulators cleared GSK's Blujepa for uncomplicated urinary tract infections, adding a new oral antibiotic option for a very common infection. Each of these launches enters a large patient pool that older generics already serve. In turn, new options widen treated populations and raise spending per patient in pain and infection care.
How do generics widen access to treatment?
Generics widen access, because low prices let health systems and insurers treat more patients within fixed annual budgets. The Association for Accessible Medicines reports that generics and biosimilars made up 90% of U.S. prescriptions filled in 2024 but only 12% of overall spending on medicines. The same group estimates that these lower-cost products saved $467 billion in 2024 alone. In July 2026, Cipla received FDA approval for a generic version of Advair Diskus across all three strengths, adding competition in asthma and chronic obstructive pulmonary disease inhalers. Generic launches like this cut out-of-pocket costs and raise adherence among chronic patients. As a result, generic pharmaceuticals keep dispensed volume growing even as unit prices fall.
Why are neurology launches adding new demand?
Neurology launches add demand, because Alzheimer's and Parkinson's disease have long lacked therapies that change the course of illness or ease late-stage symptoms. In July 2024, the FDA approved Kisunla for early Alzheimer's disease, adding a second amyloid-targeting antibody for patients with confirmed amyloid pathology. In October 2024, AbbVie said the FDA approved Vyalev for adults with advanced Parkinson's disease, a continuous subcutaneous infusion of foscarbidopa and foslevodopa. The WHO notes that levodopa and carbidopa remain unavailable or unaffordable in many countries, so access gaps leave room for growth. In turn, Parkinson's disease therapeutics and dementia care expand, with Alzheimer's medicines rising at 7.88% a year.
Price negotiation, orphan launches and online refills
How is government price negotiation shifting branded revenue?
Government negotiation is shifting branded revenue, because large public payers now set prices for older high-spend medicines instead of accepting list prices. The Centers for Medicare and Medicaid Services published negotiated prices for 10 Part D medicines that take effect on Jan. 1, 2026. CMS estimated that these prices would have saved $6 billion, or about 22% of net spending, if they had applied in 2023. Further rounds will add more medicines, including Part B products administered in clinics and hospital outpatient settings. Companies now plan launch prices and lifecycle strategies around the date a brand becomes eligible. As a result, originators lean on new launches and patient volume rather than price increases on mature brands.
Is the rise of orphan approvals changing the product mix?
A rise in orphan approvals is changing the product mix, because rare disease medicines carry high prices, smaller trials and faster regulatory reviews. More than half of the 46 novel medicines approved by the FDA in 2025 targeted rare diseases, with 25 holding orphan designation. In August 2025, the FDA approved Sanofi's Wayrilz for persistent or chronic immune thrombocytopenia in patients who did not respond well to earlier treatment. Orphan medicines grow fastest among product types at 6.97% a year through 2035, well ahead of generics and other branded medicines. In turn, large companies keep buying rare disease biotechs to refill pipelines ahead of patent expiries on their largest brands.
Where can online pharmacies capture refill volume?
Online pharmacies offer a clear opening, because chronic patients need the same medicines every month and value reliable home delivery. Retail pharmacies and drug stores held 47.0% of 2025 value, so even small shifts in refill habits move large sums between channels. Online pharmacies grow fastest at 7.65% a year, as insurers add mail-order benefits and health systems add digital refill tools to patient portals. Low-cost generics for blood pressure, cholesterol and diabetes suit automated dispensing and subscription pricing. As a result, e-pharmacy operators can win repeat customers in diabetes, heart disease and mental health, where adherence matters most.
Can acquisitions and Asian demand open new growth?
Acquisitions and Asian demand create growth openings, because originators need new revenue before patents on their largest brands lapse. In October 2025, Merck completed its acquisition of Verona Pharma, adding Ohtuvayre, which the FDA approved in June 2024 for chronic obstructive pulmonary disease. Asia Pacific held 24.0% of 2025 value, and wider insurance coverage and hospital capacity in China and India add patients every year. Companies such as Cipla and Teva also supply generic and complex products across these markets at low cost. In turn, biosimilars and branded launches share rising patient volume across the region.
Price controls, patent expiry and antibiotic economics
How do price controls restrain branded revenue?
Price controls restrain branded revenue, because governments and insurers increasingly cap what they pay for mature medicines. In the United States, negotiated Medicare prices for the first 10 Part D medicines took effect in January 2026. Europe and Japan already use reference pricing and health technology assessment to limit launch prices and later increases. As a result, companies must show clear clinical benefit over existing options to secure premium pricing in major markets.
Why do patent expiries erode brand sales?
Patent expiries erode brand sales, because generic and biosimilar entry cuts prices sharply within months of launch. Generic and biosimilar products already dominate dispensed volume in the United States while taking a small share of spending. Several large brands in diabetes, immunology and cancer lose protection before 2030. Originators therefore need steady launches simply to hold revenue flat, which raises research and acquisition costs across the industry.
Why are new antibiotics hard to commercialize?
New antibiotics are hard to commercialize, because doctors hold them in reserve to slow resistance, which keeps sales low. The WHO estimates that bacterial antimicrobial resistance was associated with more than 4.7 million deaths in 2021. Approvals such as Blujepa in 2025 and Nuzolvence for gonorrhea in December 2025 add options, yet unit volumes stay modest. As a result, infectious disease spending grows slower than the overall market despite a clear public health need.
How do manufacturing and supply risks affect availability?
Manufacturing and supply risks affect availability, because many generics rely on a small number of ingredient plants in India and China. Low prices leave thin margins, so some makers exit older sterile injectables and antibiotics entirely. Hospitals and regulators then face recurring shortages of basic medicines used in surgery and cancer care. Health systems are responding with stockpiles, multi-source contracts and incentives for local production of essential medicines.
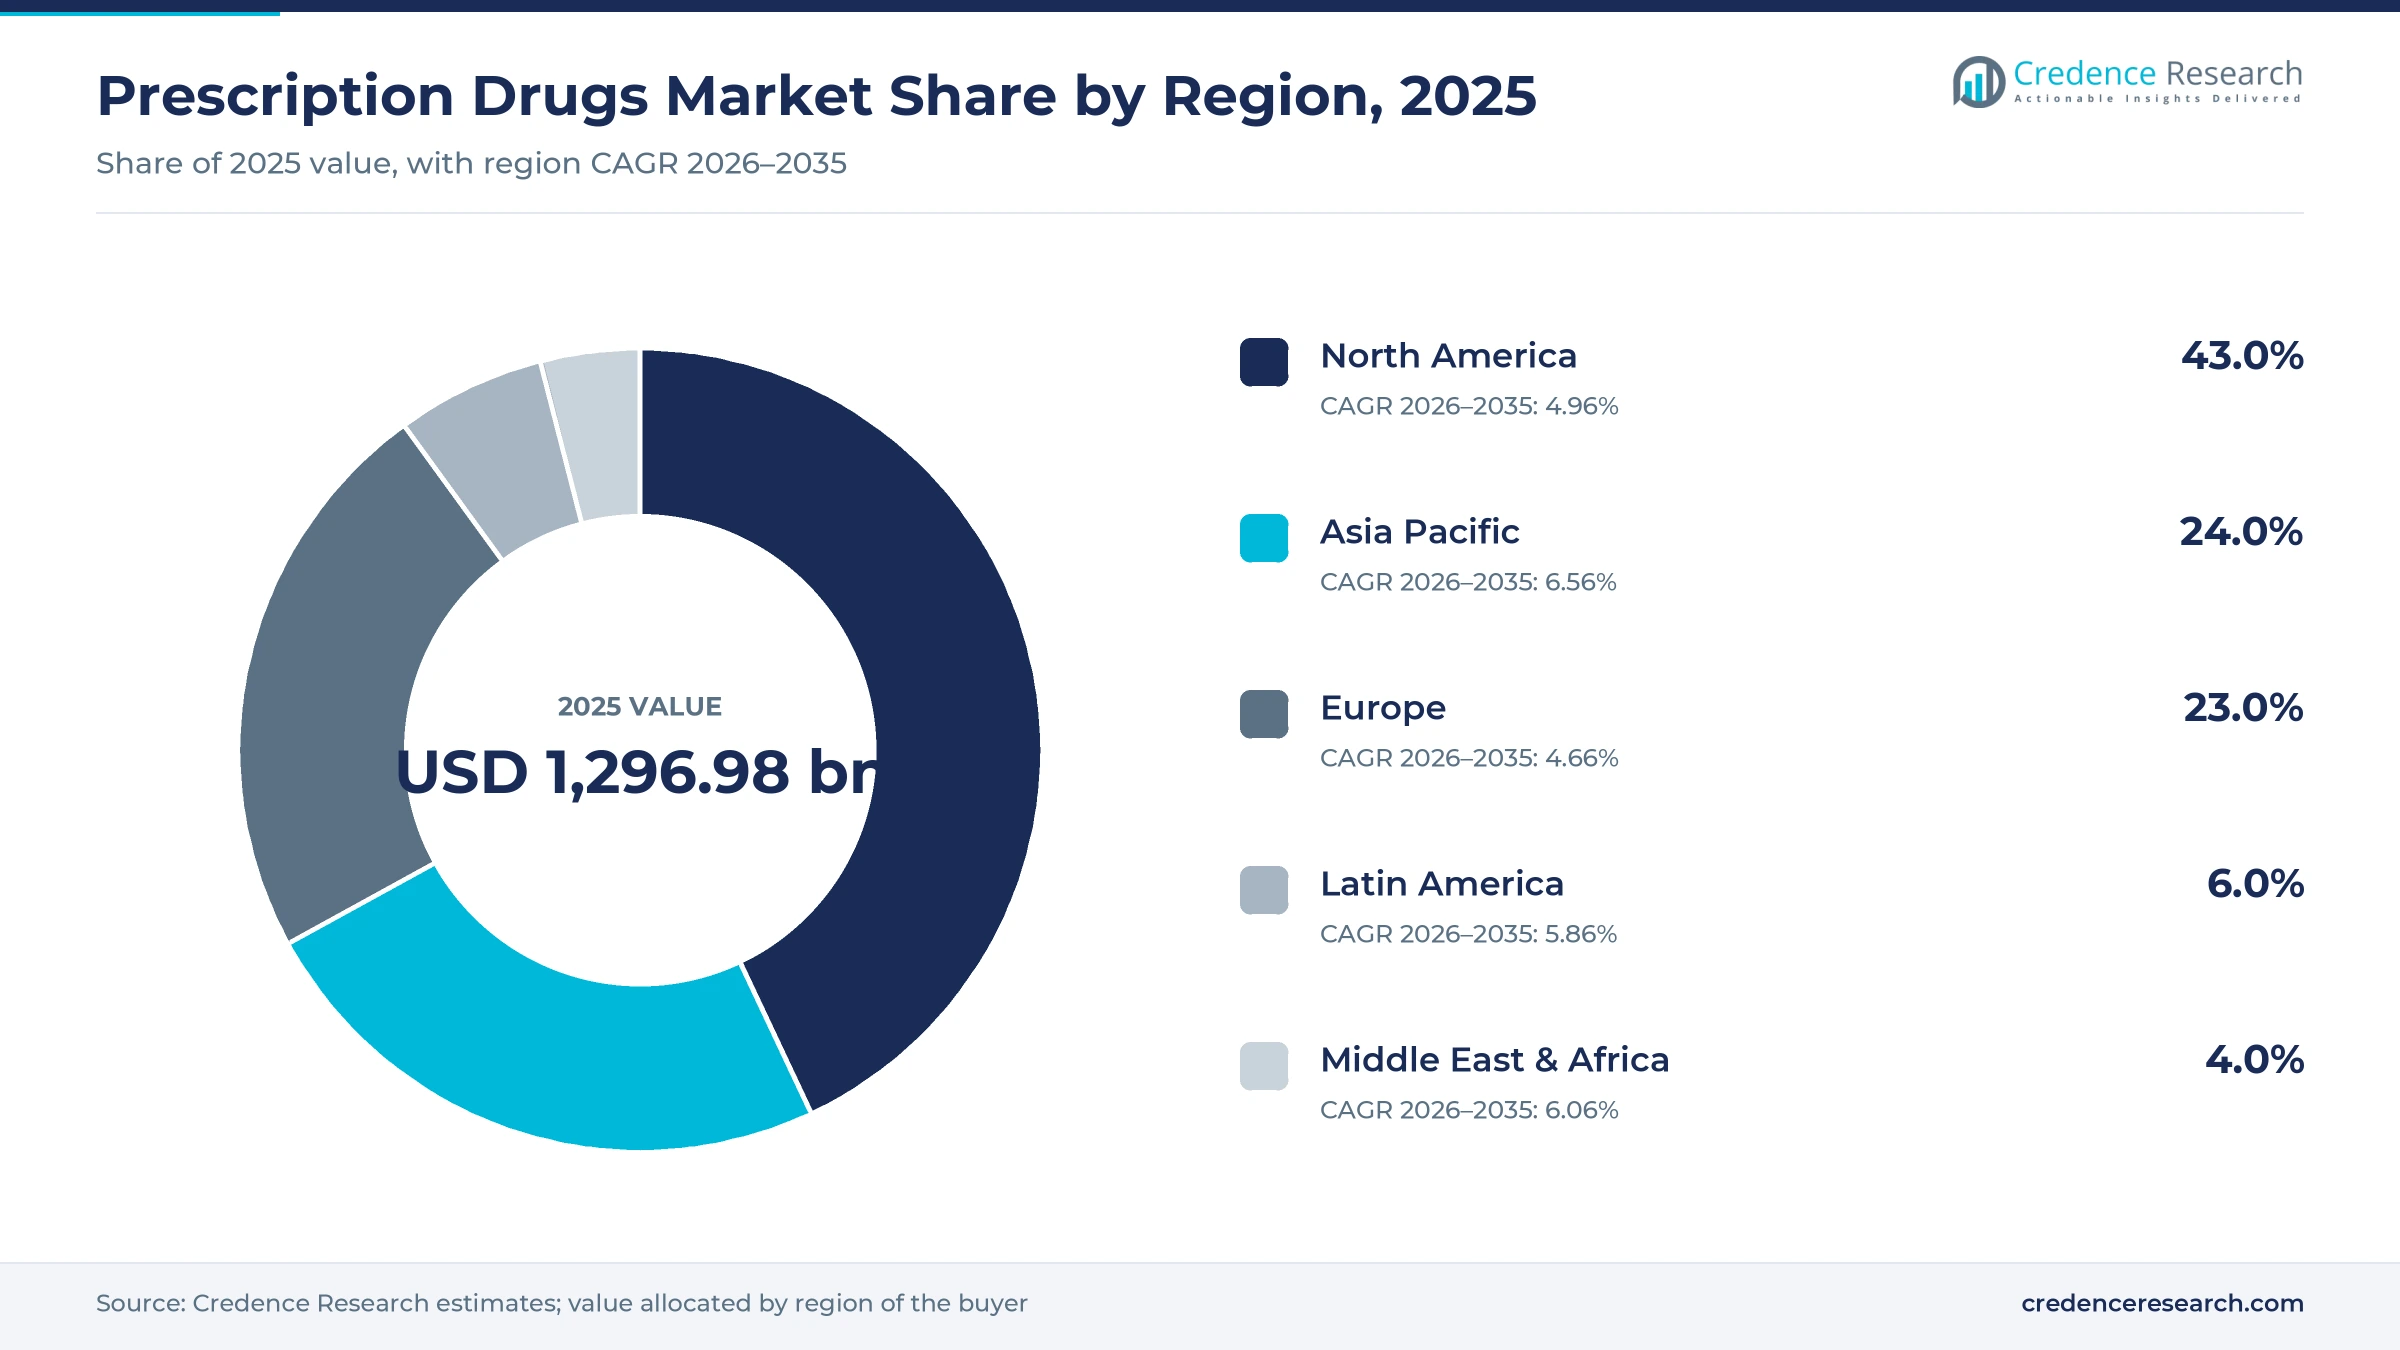
North America leads value as Asia Pacific adds volume
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 557.70 | 43.0% | 4.96% |
| Asia Pacific | 311.28 | 24.0% | 6.56% |
| Europe | 298.31 | 23.0% | 4.66% |
| Latin America | 77.82 | 6.0% | 5.86% |
| Middle East & Africa | 51.88 | 4.0% | 6.06% |
Why does North America hold the largest regional share?
North America held a 43.0% share of 2025 value and grows at 4.96% a year through 2035. The United States launches most new molecules first and pays higher list prices than other high-income countries. Medicare price negotiation from 2026 trims spending on some mature brands, while specialty pharmacies and pharmacy benefit managers shape which medicines reach patients. Canada controls launch prices for patented medicines through a federal review board.
How fast is Asia Pacific adding patients?
Asia Pacific held a 24.0% share of 2025 value and is the fastest-growing region at 6.56% a year. China uses national reimbursement listings and volume-based procurement to widen access while cutting generic prices. India supplies low-cost generics to its own patients and to export markets. Japan and South Korea add value through rapid uptake of oncology and rare disease launches.
What shapes medicine spending across Europe?
Europe held a 23.0% share of 2025 value and grows at 4.66% a year, the slowest pace of the five regions. Health technology assessment bodies review cost effectiveness before national payers list new medicines. Germany, France, Italy, Spain and the United Kingdom account for most regional value. However, Roche, Novartis, Sanofi, GSK, AstraZeneca and Boehringer Ingelheim keep major research and manufacturing bases in the region.
Where is Latin America adding demand?
Latin America held a 6.0% share of 2025 value and grows at 5.86% a year through 2035. Brazil and Mexico lead regional spending, with public systems buying generics through tenders and private patients paying for branded medicines in retail pharmacies.
What limits growth in the Middle East and Africa?
The Middle East and Africa held a 4.0% share of 2025 value and grows at 6.06% a year through 2035. Gulf states fund modern hospitals that adopt branded oncology and specialty medicines quickly. Sub-Saharan Africa depends on donor programs and imported generics for HIV, malaria and tuberculosis treatment.
Approvals, acquisitions and generic entries since 2024
| Development | Status and market relevance |
|---|---|
| In October 2024, AbbVie announced FDA approval of Vyalev for adults living with advanced Parkinson's disease. | Approved; continuous subcutaneous levodopa option |
| In January 2025, Vertex announced FDA approval of Journavx for moderate to severe acute pain in adults. | Approved; first-in-class non-opioid analgesic |
| In March 2025, GSK announced FDA approval of Blujepa for uncomplicated urinary tract infections. | Approved; new oral antibiotic option for a common infection |
| In October 2025, Merck completed its acquisition of Verona Pharma and its COPD medicine Ohtuvayre. | Completed; adds a respiratory brand to the portfolio |
| In July 2026, Cipla announced FDA approval of its generic Advair Diskus across all three strengths. | Approved; widens generic inhaler supply in the United States |
Modalities and delivery formats reshaping therapy
- Antibody and antibody-drug conjugate platforms deliver targeted treatment in cancer and immune disease, which supports premium pricing in hospital channels and specialty pharmacies.
- Amyloid-targeting antibodies such as Kisunla slow decline in early Alzheimer's disease, which requires diagnostic scans and regular infusion visits.
- Subcutaneous continuous infusion lets patients with advanced Parkinson's disease receive levodopa around the clock without brain surgery or a feeding tube.
- Non-opioid sodium channel blockers treat acute pain through a new mechanism, which may reduce exposure to opioid medicines after surgery.
- Digital refill and dispensing systems automate repeat orders and home delivery, which helps online pharmacies serve chronic patients at scale.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Originators and generic makers compete on pipelines and cost
Competition in the market splits between research-driven originators and cost-focused generic makers. Pfizer, Merck, AbbVie, Roche, Novartis, AstraZeneca, Sanofi, GSK and Boehringer Ingelheim compete on oncology, immunology, cardiometabolic and respiratory pipelines, and each relies on acquisitions to refill portfolios. Merck completed its Verona Pharma deal in 2025, adding a respiratory brand. Vertex competes in cystic fibrosis and, since 2025, in acute pain. Teva and Cipla compete on generic breadth, complex inhaled and injectable products and low manufacturing costs, often supplying public tenders across many countries. Cipla also gained U.S. approval for generic Advair Diskus in 2026. Payers and pharmacy benefit managers use formulary placement to push prices down across all of these companies. However, originators with first-in-class launches still gain fast uptake when no alternative exists.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Pfizer Inc. | Originator | Oncology, vaccines, cardiometabolic and hemophilia medicines |
| Merck & Co., Inc. | Originator | Oncology, vaccines and respiratory medicines including Ohtuvayre |
| AbbVie Inc. | Originator | Immunology, neuroscience and oncology, including Vyalev |
| F. Hoffmann-La Roche Ltd. | Originator | Oncology, neurology and immunology medicines |
| Novartis AG | Originator | Cardiovascular, oncology and neuroscience medicines |
| AstraZeneca Plc | Originator | Oncology, respiratory and cardiometabolic medicines |
| Sanofi | Originator | Immunology, rare disease and hematology medicines, including Wayrilz |
| GlaxoSmithKline Plc | Originator | Respiratory, infectious disease and HIV medicines, including Blujepa |
| Boehringer Ingelheim International GmbH | Originator | Respiratory, cardiometabolic and oncology medicines |
| Vertex Pharmaceuticals Incorporated | Originator | Cystic fibrosis medicines and Journavx for acute pain |
| Teva Pharmaceutical Industries Ltd. | Generic and specialty | Generics, biosimilars and neuroscience brands |
| Cipla Ltd | Generic | Generic respiratory and complex products, including generic Advair Diskus |
Volume grows faster than price through 2035
Credence Research's view is that patient volume, rather than price, will carry most growth through 2035. The market grows at 5.39% a year as aging populations, neurology launches and wider insurance coverage in Asia add treated patients. Price negotiation in the United States and reference pricing in Europe limit gains on mature brands. The strongest openings sit in orphan medicines, Alzheimer's care and online refill services, while generic makers gain volume but face thin margins.
How Credence Research built the medicine spending model
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, which builds spending by ailment, product type and distribution channel. Regional and segment splits are Credence Research estimates informed by FDA approval lists, World Health Organization statistics, Medicare program data, industry association reports and company releases. No primary interviews or surveys were used in preparing this edition of the report.
Branded, orphan and generic medicine outlook to 2035
By 2035, the prescription drugs market is projected to reach USD 2,192.02 billion, with growth led by Asia Pacific, orphan medicines and online dispensing. Cancer and dementia care will remain central to spending as populations age. Generic and biosimilar entry will keep pulling prices down on older brands, while first-in-class launches lift value in oncology, neurology and rare disease. North America keeps the highest spending per patient, and Asia Pacific adds the most new patients over the decade.
Frequently Asked Questions
How big is the global prescription drugs market?
Which region leads prescription drugs spending?
Which ailment grows fastest in the prescription drugs market?
Which distribution channel leads the market?
How many novel medicines did the FDA approve recently?
How do generics affect the prescription drugs market?
Who are the leading prescription drugs companies?
How does Medicare price negotiation affect the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Ailment
- 1.2.1 Cancer
- 1.2.2 Infectious Disease
- 1.2.3 Chronic Pain
- 1.2.4 Alzheimer's
- 1.2.5 Parkinson's
- 1.2.6 Migraine
- 1.2.7 Others
- 1.3 By Product Type
- 1.3.1 Generic
- 1.3.2 Orphan
- 1.3.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1,296.98 billion → 2035: USD 2,192.02 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Prescription Drugs Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Prescription Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Prescription Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Prescription Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Prescription Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Prescription Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Prescription Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Prescription Drugs Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1,296.98 billion → 2035: USD 2,192.02 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Prescription Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Ailment - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cancer
- 12.3.7.2 Infectious Disease
- 12.3.7.3 Chronic Pain
- 12.3.7.4 Alzheimer's
- 12.3.7.5 Parkinson's
- 12.3.7.6 Migraine
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Generic
- 12.4.7.2 Orphan
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Prescription Drugs Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Prescription Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Prescription Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 GlaxoSmithKline Plc
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 AstraZeneca Plc
- 17.4 Boehringer Ingelheim International GmbH
- 17.5 Merck & Co., Inc.
- 17.6 Novartis AG
- 17.7 F. Hoffmann-La Roche Ltd.
- 17.8 Teva Pharmaceutical Industries Ltd.
- 17.9 Sanofi
- 17.10 Pfizer Inc.
- 17.11 AbbVie Inc.
- 17.12 Vertex Pharmaceuticals Incorporated
- 17.13 Cipla Ltd
- 17.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

