
Atherosclerosis Drugs Market Overview:
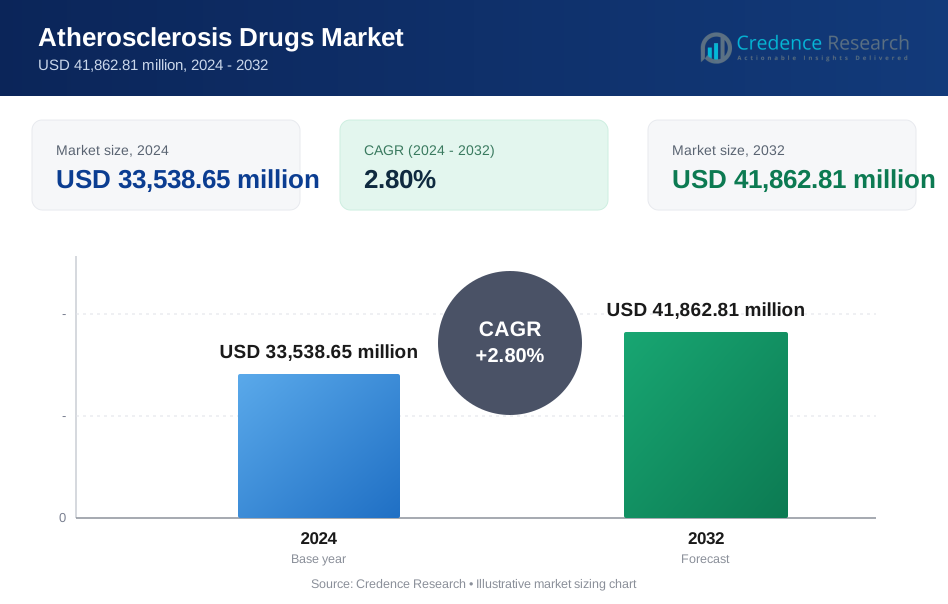
The Atherosclerosis Drugs Market is projected to grow from USD 33,538.65 million in 2024 to an estimated USD 41,862.81 million by 2032, with a CAGR of 2.80% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Atherosclerosis Drugs Market Size 2024 | USD 33,538.65 Million |
| Atherosclerosis Drugs Market, CAGR | 2.80% |
| Atherosclerosis Drugs Market Size 2032 | USD 41,862.81 Million |
Atherosclerosis Drugs Market Insights:
- North America (38%), Europe (30%), and Asia Pacific (22%) dominate the market due to advanced healthcare systems, strong diagnosis rates, and expanding preventive care programs.
- Asia Pacific, with a 22% share, is the fastest-growing region driven by rising healthcare investment, increasing screening programs, and broader access to modern cardiovascular therapies.
- Statins account for the largest drug class share, supported by strong clinical evidence and widespread adoption in risk prevention.
- Oral formulations hold the leading route-of-administration share, driven by ease of use, strong patient adherence, and broad availability across global markets.
Atherosclerosis Drugs Market Drivers:
Growing Clinical Need for Advanced Lipid-Lowering and Anti-Inflammatory Therapies
Rising cardiovascular disease prevalence strengthens demand for therapies that target lipid imbalance and arterial inflammation. The Atherosclerosis Drugs Market gains traction as more patients require long-term treatment to manage plaque progression. Healthcare systems promote early screening to lower long-term cardiac risk. Physicians prefer drugs that support strong reductions in LDL cholesterol and markers linked to plaque instability. Wider use of combination therapy improves outcomes in high-risk groups. Research programs push innovation in pathways linked to residual cardiovascular risk. Strong clinical evidence encourages broader prescribing across age groups. It supports better patient adherence across long treatment cycles.
Increasing Focus on Preventive Cardiology and Risk Reduction Strategies
Growing awareness of preventive care drives adoption of therapies that delay severe cardiac events. National guidelines recommend aggressive management of cholesterol and inflammation to slow disease progression. The Atherosclerosis Drugs Market benefits from higher prescription volumes among patients with moderate and high cardiovascular risk. Physicians seek therapies that support stable plaque formation and lower hospitalization rates. Governments promote public health campaigns to encourage early diagnosis and consistent medication use. Pharmaceutical companies introduce drugs with improved dosing profiles to support treatment continuity. Hospitals integrate structured cardiovascular prevention programs to raise therapy uptake. It strengthens adherence and improves long-term outcomes.
- For instance, AstraZeneca’s CRESTOR (rosuvastatin) was utilized in the JUPITER study to show that aggressive preventive treatment in patients with low LDL but high C-reactive protein led to a 44% reduction in the incidence of major cardiovascular events.
Rapid Advancement of Biologics and Next-Generation Cardiometabolic Agents
New biologics support higher efficacy in patients who respond poorly to traditional therapies. The Atherosclerosis Drugs Market gains momentum through wider access to PCSK9 inhibitors and agents that target novel lipid pathways. Research programs explore RNA-based drugs that suppress harmful lipid production. These developments create better options for patients with genetic lipid disorders. Physicians adopt next-generation drugs due to strong safety profiles and lower treatment complexity. Industry players invest in large trials to expand regulatory approvals for broader patient categories. Hospitals integrate these therapies in structured lipid clinics to raise success rates. It strengthens innovation across cardiometabolic treatment portfolios.
Expanding Role of Personalized Medicine and Risk-Stratified Treatment Models
A rising shift toward precision treatment helps clinicians tailor therapy to genetic and clinical risk. The Atherosclerosis Drugs Market benefits from improved diagnostic tools that reveal hidden drivers of plaque growth. Biomarker-based assessment helps physicians choose treatments that match individual lipid and inflammation patterns. Risk-stratified models support better allocation of high-cost therapies across specific patient groups. Pharmaceutical companies develop tools that predict drug response in real time. Hospitals use integrated data systems to track therapy results and adjust plans quickly. This approach lowers variability in treatment outcomes. It sets the stage for targeted innovation in cardiovascular care.
- For instance, Regeneron and Sanofi utilized genetic risk stratification in the ODYSSEY OUTCOMES trial for Praluent, identifying that patients with baseline LDL levels above 100 mg/dL experienced a 24% greater relative risk reduction in major adverse cardiovascular events compared to the broader study population.
Atherosclerosis Drugs Market Trends:
Growing Adoption of Combination Therapy for Multi-Pathway Cardiovascular Management
Clinicians use dual and triple therapy models to target lipid imbalance and inflammation together. This trend supports broader use of drugs that manage multiple disease pathways. The Atherosclerosis Drugs Market responds to rising clinical acceptance of combined regimens. Physicians see stronger plaque stabilization through integrated approaches. Hospitals update treatment pathways to support unified cardiovascular risk control. Combination therapy improves outcomes in patients with diabetes and metabolic disorders. Pharmaceutical firms design fixed-dose combinations to simplify regimens. It supports better adherence among long-term users.
Increased R&D Investment in RNA-Based and Gene-Modulating Cardiovascular Drugs
Drug developers explore gene-modulating therapies to treat lipid disorders rooted in hereditary factors. These technologies offer longer dosing intervals and stronger LDL reduction. The Atherosclerosis Drugs Market tracks rising interest in therapies that silence harmful lipid-producing genes. Clinical trials evaluate long-acting injections that reduce patient burden. Research programs expand across major academic centers. Investors support early-stage platforms with strong therapeutic potential. Hospitals prepare for integration of advanced therapies into specialty clinics. It enhances long-term viability of next-generation cardiometabolic pipelines.
- For instance, Verve Therapeutics achieved a significant milestone with its VERVE-101 base-editing therapy, which demonstrated a 55% reduction in blood PCSK9 protein levels following a single infusion in patients with heterozygous familial hypercholesterolemia.
Shift Toward Long-Acting Injectable Therapies for High-Risk Patient Segments
Long-acting formulations reduce dosing frequency and limit adherence challenges. Many patients prefer injections that maintain stable lipid levels for extended periods. The Atherosclerosis Drugs Market benefits from a shift toward therapies that require fewer follow-up visits. Physicians value the strong durability seen in long-acting agents. Hospitals adopt structured programs to monitor outcomes of these formulations. Drug makers advance depot-based delivery systems for future launches. Patient acceptance increases due to lower daily medication pressure. It aligns with broader efforts to simplify chronic disease care.
- For instance, Novartis’s inclisiran (Leqvio) utilizes a specialized siRNA delivery mechanism that allows for a 52% sustained reduction in LDL cholesterol with a dosing schedule of only twice per year, significantly lowering the treatment burden for high-risk patients.
Rising Integration of Digital Health Tools to Improve Cardiovascular Treatment Continuity
Remote monitoring tools help physicians track lipid and inflammatory markers in real time. Digital applications prompt patients to maintain medication schedules. The Atherosclerosis Drugs Market aligns with a growing shift toward coordinated digital care. Healthcare providers use AI-driven tools to predict fluctuations in cardiovascular risk. Hospitals deploy digital platforms that support personalized treatment adjustments. Mobile applications improve patient–physician communication and encourage lifestyle compliance. Pharmaceutical players integrate digital adherence tools with treatment programs. It improves consistency across long care cycles.
Atherosclerosis Drugs Market Challenges Analysis:
High Cost of Advanced Therapies and Access Limitations Across Key Regions
The high cost of biologics restricts adoption across markets with limited insurance coverage. The Atherosclerosis Drugs Market faces disparities in access between urban and rural regions. Patients in low-income settings struggle to maintain continuous therapy. Healthcare systems face pressure to justify reimbursement for expensive drugs. Physicians struggle to prescribe advanced options in cost-sensitive populations. Traditional therapies remain preferred in many regions due to budget constraints. Pharmaceutical firms encounter challenges in scaling premium therapies across emerging markets. It slows market penetration for cutting-edge drugs.
Clinical Variability, Slow Diagnosis Rates, and Patient Adherence Barriers
Many patients receive delayed diagnosis due to limited screening infrastructure. The Atherosclerosis Drugs Market encounters uneven detection across high-risk groups. Clinical variability in disease progression complicates treatment selection. Physicians face difficulty predicting individual response to specific drugs. Long-term adherence remains inconsistent due to complex dosing schedules. Patients often discontinue therapy due to side effects or inadequate follow-up care. Hospitals struggle to maintain cohesive treatment plans across large patient populations. It reduces long-term effectiveness of cardiovascular management programs.
Atherosclerosis Drugs Market Opportunities:
Expansion of Precision Cardiovascular Care Supported by Diagnostics and Genomic Tools
Growing availability of genomic testing supports deeper insight into individual lipid disorders. The Atherosclerosis Drugs Market gains opportunity to align targeted therapies with patient-specific risk patterns. Hospitals integrate molecular diagnostics to support therapy personalization. Drug makers develop tools that match treatment to genetic markers. Cardiologists adopt precision models to reduce treatment variability. Payers explore structured reimbursement for targeted solutions. It enhances value across long-term disease management.
Growth Potential in Emerging Markets with Rising Healthcare Investment and Screening Programs
Emerging economies expand prevention programs that focus on early cardiovascular detection. The Atherosclerosis Drugs Market benefits from increasing access to specialty care. Governments invest in screening to identify high-risk groups sooner. Hospitals scale capacity to treat chronic diseases more effectively. Pharmaceutical firms find growth through partnerships with regional providers. Awareness programs raise patient willingness to begin therapy earlier. It supports broader uptake of modern cardiovascular drugs across underserved regions.
Atherosclerosis Drugs Market Segmentation Analysis:
By Drug Type
The Atherosclerosis Drugs Market features diverse drug classes that address lipid imbalance, inflammation, and clot formation. Anti-platelet and anticoagulant drugs support prevention of arterial blockage in high-risk patients. Cholesterol-lowering medication and statins hold a strong share due to their wide use in primary and secondary prevention. PCSK9 inhibitors gain traction in patients with severe lipid disorders who need stronger LDL reduction. ACE inhibitors support vascular protection and treatment of comorbid conditions. Other drug types provide supportive benefits for complex cases. It benefits from expanded therapeutic options that target multiple disease pathways.
By Route of Administration
Oral drugs dominate due to ease of daily use and strong acceptance in long-term care. Tablets and capsules support broad management of high-risk groups. Injectable therapies grow due to rising preference for long-acting lipid-lowering agents. Hospitals adopt injectable options for patients who require strong and stable lipid control. Self-administration devices support wider use outside clinical settings. It strengthens adherence for patients who struggle with daily dosing.
- For instance, Amgen’s Repatha (evolocumab) is available via the Pushtronex system, an on-body infusor that provides a hands-free subcutaneous delivery of a 420 mg monthly dose, which clinical data shows maintains a consistent 71% reduction in LDL cholesterol from baseline.
By Distribution Channel
Hospital pharmacies lead due to high prescribing volumes for high-risk cardiac patients. Retail pharmacies support steady demand from those on chronic therapy. Online pharmacies expand reach by offering convenient access to maintenance drugs. Digital platforms encourage higher refill rates among long-term users. It supports wider uptake across diverse patient groups.
- For instance, CVS Health reported that the integration of its Pharmacy Advisor program for cardiovascular patients led to a 12% increase in medication optimal possession ratio (OPR) and a significant improvement in adherence for those transitioning from hospital discharge to home-based retail pharmacy refills.
Segmentation:
By Drug Type
- Anti-platelet and Anticoagulants
- Cholesterol Lowering Medication
- ACE Inhibitors
- Statins
- PCSK9 Inhibitors
- Others
By Route of Administration
- Oral
- Injectable
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies/Drug Stores
- Online Pharmacies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the Atherosclerosis Drugs Market, accounting for around 38% of the global revenue. The region benefits from advanced healthcare systems and strong adherence to cardiovascular treatment guidelines. Physicians adopt innovative lipid-lowering and anti-inflammatory therapies at a faster rate. Drug makers gain steady demand due to high diagnosis rates and broad preventive care programs. Hospitals maintain strong capacity for specialized cardiac services. It strengthens long-term therapy adoption across diverse patient groups.
Europe
Europe contributes about 30% of the global market share, driven by structured cardiovascular management programs. The region enforces evidence-based prescribing and supports reimbursement for lipid-lowering therapies. Statins and combination therapies maintain high penetration across major countries. Hospitals operate integrated cardiac networks that support early risk detection. Pharmaceutical firms see stable demand due to strong chronic disease management practices. It maintains consistent growth driven by advanced therapy adoption.
Asia Pacific, Latin America, and Middle East & Africa
Asia Pacific accounts for roughly 22% of the market, supported by rising healthcare investment and higher diagnosis rates. Urban populations show strong uptake of cholesterol-lowering drugs, while rural regions expand screening capacity. Latin America holds about 6% of global share, driven by gradual expansion of cardiac care services. Middle East & Africa represent nearly 4%, influenced by limited access to advanced therapies and slower diagnosis rates. Hospitals in emerging regions scale capacity to support chronic care programs. It grows steadily as awareness of cardiovascular risk strengthens across underserved populations.
Key Player Analysis:
- Pfizer
- AstraZeneca
- Novartis AG
- Sanofi
- Merck & Co.
- Amgen Inc.
- Johnson & Johnson
- Bayer AG
- Hoffmann-La Roche
- Regeneron Pharmaceuticals
Competitive Analysis:
The Atherosclerosis Drugs Market features strong competition among global pharmaceutical leaders that invest heavily in cardiovascular innovation. Companies advance portfolios with statins, antiplatelet agents, PCSK9 inhibitors, and next-generation lipid-lowering drugs. Firms strengthen their pipelines through partnerships, clinical expansions, and targeted acquisitions. Hospitals prefer suppliers that deliver proven efficacy, strong safety profiles, and broad therapeutic coverage. Competitors seek differentiation through advanced biologics and long-acting formulations. Brand loyalty remains strong in chronic therapy segments. It benefits from sustained R&D spending that drives product upgrades and broader adoption.
Recent Developments:
- In February 2026, Pfizer reported solid full-year 2025 results and reaffirmed its 2026 revenue guidance of $59.5 to $62.5 billion, underscoring a strategic focus on its R&D pipeline to offset a projected $1.5 billion loss from products losing exclusivity.
- In February 2026, Sanofi successfully completed the acquisition of Dynavax Technologies, adding the adult hepatitis B vaccine HEPLISAV-B to its portfolio, while continuing its collaboration with Regeneron to expand indications for the PCSK9 inhibitor Praluent.
- In February 2026, Amgen continued to dominate the PCSK9 inhibitor segment with Repatha (evolocumab), having previously secured FDA priority reviews and pediatric indications to maintain its leadership among patients who are statin-intolerant or at high cardiovascular risk.
Report Coverage:
The research report offers an in-depth analysis based on By Drug Type, By Route of Administration, and By Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand grows steadily as healthcare systems prioritize long-term cardiovascular prevention and expand access to modern lipid-lowering therapies.
- Precision diagnostics advance risk classification, enabling physicians to tailor therapy more effectively for patients with complex lipid disorders.
- Long-acting injectable options gain stronger acceptance among clinicians seeking reliable lipid control with simplified dosing schedules.
- Digital tools integrate into routine care, helping physicians track adherence patterns and adjust treatment before risk levels rise.
- Emerging economies increase investment in cardiovascular programs, creating new opportunities for drug makers to expand market presence.
- Hospitals strengthen multidisciplinary care pathways that connect cardiology, primary care, and metabolic specialists for better patient outcomes.
- Research pipelines expand with RNA-based agents, gene-modulating therapies, and novel anti-inflammatory drugs targeting residual cardiovascular risk.
- Access to premium therapies improves as payers adopt structured reimbursement models focused on long-term risk reduction.
- Regulators support innovation by streamlining approval timelines for therapies that demonstrate strong reductions in clinical events.
- Industry partnerships encourage development of integrated care models that combine advanced drugs, diagnostics, and digital health solutions for sustained improvement in patient management.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Atherosclerosis Drugs Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Atherosclerosis Drugs Market projected to grow between 2025 and 2032?
Which Atherosclerosis Drugs Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Atherosclerosis Drugs Market?
Who are the leading companies in the Atherosclerosis Drugs Market?
Which region commanded the largest share of the Atherosclerosis Drugs Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 33,538.65 million → 2032: USD 41,862.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Atherosclerosis Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Atherosclerosis Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Atherosclerosis Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Atherosclerosis Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Atherosclerosis Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Atherosclerosis Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Atherosclerosis Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Atherosclerosis Drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 33,538.65 million → 2032: USD 41,862.81 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Atherosclerosis Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Atherosclerosis Drugs Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Atherosclerosis Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Atherosclerosis Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

