
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Nutraceutical Contract Manufacturing Services Market Size 2024 | USD 149,412.25 Million |
| Nutraceutical Contract Manufacturing Services Market, CAGR | 12.25% |
| Nutraceutical Contract Manufacturing Services Market Size 2032 | USD 376,597.12 Million |
Market Overview
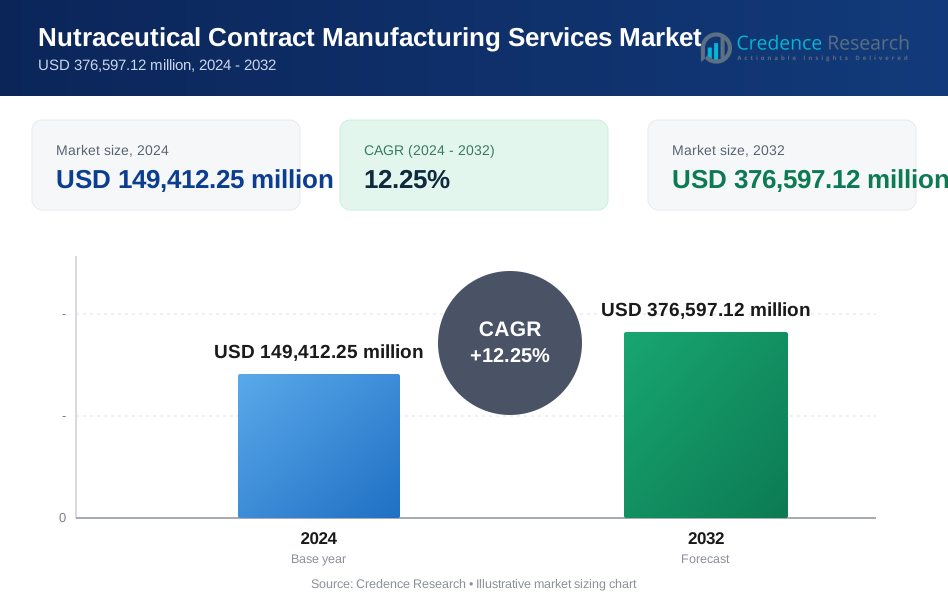
The nutraceutical contract manufacturing services market is projected to grow from USD 149,412.25 million in 2024 to USD 376,597.12 million by 2032, at a compound annual growth rate (CAGR) of 12.25%.
The nutraceutical contract manufacturing services market is driven by increasing consumer demand for dietary supplements, functional foods, and personalized nutrition. Rising health awareness, aging populations, and the growing trend of preventive healthcare further fuel market growth. Additionally, advancements in manufacturing technologies, such as automated processes and improved formulations, are enhancing production efficiency and product quality. Outsourcing manufacturing allows companies to reduce costs and focus on core competencies, contributing to the market’s expansion. The shift toward clean-label, organic, and natural ingredients also aligns with changing consumer preferences, supporting the growth of nutraceutical contract manufacturing services.
The nutraceutical contract manufacturing services market is witnessing growth across key regions, with North America, Europe, and Asia-Pacific playing significant roles. North America is a major hub due to advanced healthcare infrastructure and high consumer demand for dietary supplements. Europe also exhibits robust growth driven by increasing health-consciousness. In Asia-Pacific, particularly in China and India, the demand for nutraceuticals is rising due to a growing middle class and awareness about preventive healthcare. Key players in this market include Catalent, Inc., Lonza Group AG, Patheon (Thermo Fisher), Glanbia plc, and Abbott Laboratories, known for their expertise in manufacturing services.
Market Drivers
Regulatory Landscape and Stringent Quality Standards
Strict regulatory standards are shaping the nutraceutical market, requiring manufacturers to comply with stringent guidelines for safety, quality, and labeling. This regulatory environment drives the need for reliable and compliant manufacturing partners who can ensure adherence to these standards. For instance, the Food Safety and Standards Authority of India (FSSAI) has implemented comprehensive regulations for health supplements and nutraceuticals to ensure product safety and quality. Meeting these requirements builds consumer trust and strengthens brand reputation, making it essential for manufacturers to maintain high-quality production processes and certifications. As consumer demand for safe, high-quality products rises, meeting regulatory standards becomes a key factor in the success of nutraceutical companies.
Advancements in Technology and Innovation
Technological advancements are playing a crucial role in the development of new nutraceutical formulations and delivery systems. These innovations allow for the creation of more effective and targeted products, meeting the diverse needs of consumers. For instance, advancements in nano-encapsulation and bioavailability technologies are enhancing the efficacy of nutraceutical products. Additionally, advancements in quality control technologies ensure the safety, efficacy, and consistency of nutraceutical products, which is essential in maintaining consumer trust and compliance with regulatory standards. As technology continues to evolve, it enhances manufacturing processes, enabling more efficient and scalable production.
Increasing Health and Wellness Consciousness
Consumers are increasingly prioritizing preventive healthcare and wellness, which has led to a significant surge in demand for nutraceuticals. With a growing focus on maintaining overall well-being, nutraceuticals are seen as essential in supporting a healthy lifestyle. Additionally, the global aging population is driving the need for products that enhance cognitive function, joint health, and general vitality. Chronic disease management is another driver, as nutraceuticals are often used alongside traditional treatments to manage conditions like diabetes, heart disease, and arthritis, further boosting demand for these products.
Growing Demand for Functional Foods and Beverages
The demand for functional foods and beverages is growing as consumers seek products fortified with vitamins, minerals, and other essential nutrients to enhance their daily diets. This trend is fueled by an increasing awareness of nutrition's role in maintaining health and preventing illness. Personalized nutrition is also gaining popularity, with consumers opting for tailored solutions based on their specific health needs. This shift requires flexible and innovative manufacturing capabilities to accommodate customized formulations, contributing to the expansion of the nutraceutical contract manufacturing services market.
Market Trends
Increasing Demand for Personalized, Functional, and Clean Label Products
The demand for functional foods and beverages continues to rise, driven by consumer interest in products that offer health benefits beyond basic nutrition. Fortified foods, enriched with vitamins, minerals, and other essential nutrients, are gaining popularity as consumers seek to enhance their diets. Simultaneously, personalized nutrition is gaining momentum, with consumers increasingly opting for tailored supplements that cater to their individual health needs. For instance, the AI Nutrition Advisor launched by Revieve allows users to discover their body's optimal requirements for vitamins and supplements. Advancements in technology enable the development of precision nutrition, leading to customized nutraceutical formulations designed to meet specific health goals. Additionally, consumers are placing a strong emphasis on transparency, demanding clear labeling and product sourcing. This growing interest in natural ingredients and minimal processing aligns with the clean label trend, where products with recognizable, natural ingredients are preferred over synthetic ones.
Technological Advancements, Sustainability, and Global Expansion
Advancements in technology play a critical role in the development of innovative nutraceutical products. Cutting-edge product formats and delivery systems are continuously being introduced to meet the diverse needs of consumers. Moreover, advanced manufacturing processes and stringent quality control measures are essential to ensure the safety, efficacy, and consistency of nutraceuticals. As the market grows, companies are expanding their operations into emerging markets, capitalizing on new growth opportunities. Localizing products to meet regional preferences and regulatory requirements is crucial for success in these markets. At the same time, sustainability is becoming a central focus, with consumers increasingly concerned about the environmental impact of the products they purchase. Ethical sourcing practices, including the use of sustainably sourced ingredients, are gaining importance as brands aim to meet consumer expectations for eco-friendly and socially responsible products. Compliance with regulatory standards remains a cornerstone of success, ensuring that nutraceuticals meet safety requirements and have access to global markets while maintaining high-quality standards.
Market Challenges Analysis
Regulatory Challenges and Compliance
Navigating the global regulatory landscape presents a significant challenge for companies in the nutraceutical contract manufacturing sector. With regulations constantly evolving across different regions, staying compliant with local and international standards can be complex and time-consuming. For instance, the Food Safety and Standards Authority of India (FSSAI) has implemented comprehensive regulations for health supplements and nutraceuticals to ensure product safety and quality. Strict adherence to quality, safety, and labeling regulations is critical to ensure market access and avoid potential legal issues. Failing to meet these requirements can result in costly delays, product recalls, or loss of consumer trust. Additionally, companies must stay informed about changing regulatory frameworks in various countries, making it difficult to maintain consistent compliance across multiple markets. This challenge requires constant attention to detail, strategic planning, and collaboration with regulatory bodies to safeguard business operations and ensure product safety.
Supply Chain and Operational Constraints
The volatility of the supply chain is another significant challenge faced by nutraceutical manufacturers. Sourcing high-quality ingredients consistently can be difficult, particularly for niche or specialty components that may not always be readily available. Price fluctuations in raw materials further complicate this issue, as they directly impact production costs and overall profitability. Manufacturers must carefully manage their supply chains to mitigate these risks while ensuring product quality and cost-efficiency. Additionally, as demand for nutraceutical products grows, meeting increasing production requirements can place significant strain on manufacturing capacity. Scaling operations to accommodate this demand requires substantial investment in infrastructure and operational planning. Companies must also navigate product innovation challenges, constantly developing new and differentiated products to stay competitive in a crowded market. Quality control becomes increasingly difficult with complex formulations, making it essential to implement rigorous testing and monitoring systems. The risk of contamination is a further concern, as even minor lapses in quality assurance can severely damage a company’s reputation and consumer trust. Protecting intellectual property in such a competitive market is another challenge, requiring robust confidentiality agreements and innovative measures to safeguard proprietary formulations and sensitive information. Balancing these challenges is key to maintaining operational efficiency and building a strong, trustworthy brand.
Market Segmentation Analysis:
By Dosage Forms:
The nutraceutical contract manufacturing services market is segmented by various dosage forms, each catering to different consumer preferences. Tablets and capsules remain the most popular formats due to their convenience, stability, and widespread consumer acceptance. Liquid oral forms are gaining traction for their ease of consumption, particularly among the elderly and those with swallowing difficulties. Powder-based forms, such as those in sachets or jars, are increasingly favored for their versatility in offering customized dosages and easy mixing. Gummies and energy bars, which are perceived as more consumer-friendly and enjoyable, are expanding rapidly, particularly in the wellness and fitness sectors. Other dosage forms, such as diskettes, are emerging for specialized applications, offering unique delivery systems. The growing demand for diverse and tailored forms allows manufacturers to cater to a broad range of consumer needs, driving market growth in the nutraceutical sector.
By Product:
The market is also segmented by product type, with dietary supplements and functional food & beverages being key drivers. Dietary supplements, including vitamins, minerals, and herbal products, continue to dominate the market as consumers increasingly turn to nutraceuticals for health maintenance. Functional food and beverages, particularly energy drinks and re-constitutional one-shot powders, are witnessing significant growth. These products offer added health benefits, such as improved energy, mental clarity, and immune support, meeting the rising demand for products that contribute to overall well-being. Manufacturers are focusing on innovation and developing new functional foods and beverages to cater to health-conscious consumers, as the demand for functional nutrition continues to rise across global markets.
Segments:
Based on Dosage Forms:
- Tablets
- Capsules
- Liquid Oral
- Powder in Sachet / Jar
- Gummies
- Energy Bars
- Other Suitable Forms (Diskettes)
Based on Product:
- Dietary Supplements
- Functional Food & Beverages (Inclusive of Energy Drinks, Re-Constitutional One Shot Powder)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a dominant position in the nutraceutical contract manufacturing services market, accounting for approximately 35% of the global market share. This is primarily driven by the high consumer demand for dietary supplements, functional foods, and beverages. The region benefits from a well-established healthcare system, a strong inclination toward preventive healthcare, and an aging population that demands more functional health solutions. Additionally, North America's robust regulatory environment ensures high standards of product quality and safety, which boosts consumer trust. The presence of leading nutraceutical companies and contract manufacturers in the U.S. and Canada further enhances the region's market share. The rising trend of personalized nutrition, along with the growing interest in clean-label products and natural ingredients, is also fueling the demand for innovative nutraceutical products. As a result, North America is expected to maintain its leadership in the market, with manufacturers continuously innovating to meet the evolving needs of health-conscious consumers.
Asia-Pacific The Asia-Pacific region is experiencing significant growth in the nutraceutical contract manufacturing services market and is projected to capture around 30% of the global market share. This rapid expansion is driven by the growing middle class in countries like China, India, and Japan, leading to increased disposable incomes and a rising awareness of health and wellness. The region's demand for nutraceuticals, particularly dietary supplements, functional foods, and beverages, is soaring as consumers increasingly seek products that support immunity, cognitive function, and overall well-being. Additionally, the Asia-Pacific market benefits from the shift toward plant-based, natural, and organic products, which align with consumer preferences for clean-label offerings. The region’s competitive advantage lies in its ability to provide cost-effective manufacturing solutions while adhering to international quality standards, making it an attractive hub for global companies seeking to outsource production. As the demand for nutraceutical products continues to rise, Asia-Pacific is poised for substantial growth in the coming years.
Key Player Analysis
- Abbott Laboratories
- Biovation Labs
- Capsugel (A Lonza Company)
- Catalent, Inc.
- Glanbia plc
- Lonza Group AG
- Nature's Bounty Co.
- NutraPak USA
- NutraScience Labs
- Nutrascience Labs
- Paragon Laboratories
- Patheon, now part of Thermo Fisher Scientific
- Robinson Pharma, Inc.
- Royal DSM N.V.
- Vitakem Nutraceutical Inc.
Competitive Analysis
The nutraceutical contract manufacturing services market is highly competitive, with key players like Catalent, Inc., Lonza Group AG, Patheon (Thermo Fisher Scientific), Glanbia plc, and Abbott Laboratories leading the industry. These companies leverage advanced technologies and regulatory expertise to meet the growing demand for high-quality nutraceutical products. They differentiate themselves by providing customized services tailored to specific consumer needs, such as personalized supplement formulations, innovative delivery systems, and compliance with global standards. Additionally, many players invest heavily in research and development to create cutting-edge products, enhance production efficiency, and expand their product portfolios. This competitive landscape is further shaped by the increasing consumer demand for natural and plant-based supplements, driving companies to adapt quickly to market trends and preferences. Partnerships, mergers, and acquisitions are common strategies to expand capabilities and enhance service offerings.
Recent Developments
- In 2023, NutraLab has expanded with a new enclosed automatic manufacturing and packaging line for powder supplements, enhancing production efficiency and quality control in its powder supplement manufacturing processes.
- In 2022, Catalent is set to acquire Metrics Contract Services, a move aimed at expanding its capabilities in high-potent drug development and increasing oral development and manufacturing capacity. This strategic acquisition will strengthen Catalent's position in the pharmaceutical contract development and manufacturing sector.
- In September 2022, The purchase of Nutraskills was announced by Biofarma Group. The acquisition will allow Biofarma Group to increase its market share and presence in the upcoming years.
Market Concentration & Characteristics
The nutraceutical contract manufacturing services market exhibits moderate concentration, with a few large players holding a significant share while several small to medium-sized companies operate in niche segments. The market is characterized by a high level of specialization, with manufacturers offering tailored solutions for dietary supplements, functional foods, and nutraceutical ingredients. Companies differentiate themselves through expertise in formulation, production scalability, and compliance with stringent regulatory standards. The demand for personalized and innovative product offerings has led to an increased focus on research and development, fostering continuous innovation in product formulations and delivery methods. Moreover, market players are investing in state-of-the-art manufacturing facilities to improve efficiency and ensure quality. The market's characteristics also reflect the growing preference for natural, organic, and plant-based ingredients, prompting manufacturers to align their offerings with consumer trends. Collaboration and partnerships between manufacturers, ingredient suppliers, and brands are common, driving growth and expanding market presence.
Report Coverage
The research report offers an in-depth analysis based on Dosage Forms, Product and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for personalized nutraceutical products will continue to rise, encouraging manufacturers to offer tailored solutions.
- Technological advancements in manufacturing processes will drive efficiencies and reduce production costs.
- Increased focus on natural, organic, and plant-based ingredients will shape product offerings to meet consumer preferences.
- The global trend toward preventive healthcare will boost the need for dietary supplements and functional foods.
- Stricter regulatory standards will push manufacturers to invest in compliance and quality control measures.
- Partnerships and collaborations with ingredient suppliers will become more common to expand service offerings.
- Research and development in innovative delivery systems will enhance product appeal and effectiveness.
- Growing awareness about health and wellness will drive consumer demand for clean-label, sustainable products.
- The rise in e-commerce will lead to greater demand for small-batch manufacturing and quicker turnaround times.
- Expansion in emerging markets, particularly in Asia-Pacific, will offer significant growth opportunities for contract manufacturers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Regulatory Standards
Increasingly strict regulations around safety, quality, and labeling are compelling nutraceutical brands to partner with contract manufacturers who can ensure compliance, thus driving demand for specialized manufacturing services.
Technological Advancements in Manufacturing
Innovations such as automated production lines, nano-encapsulation, and improved bioavailability are enabling more efficient, scalable, and higher-quality nutraceutical manufacturing, attracting more brands to outsource production.
Rising Health and Wellness Consciousness
Growing consumer focus on preventive healthcare, aging populations, and chronic disease management is boosting demand for dietary supplements and functional foods, expanding the need for contract manufacturing capacity.
Shift Toward Clean-Label and Personalized Products
Consumer preference for natural, organic, and clean-label ingredients, as well as personalized nutrition solutions, is increasing the complexity of product formulations and driving brands to seek contract manufacturers with advanced capabilities.
Cost Efficiency and Focus on Core Competencies
Outsourcing manufacturing allows nutraceutical companies to reduce operational costs and focus on product development and marketing, fueling the growth of contract manufacturing services in the sector.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Nutraceutical Contract Manufacturing Services market?
What factors are driving the growth of the Nutraceutical Contract Manufacturing Services market?
What are the key segments within the Nutraceutical Contract Manufacturing Services market?
What are some challenges faced by the Nutraceutical Contract Manufacturing Services market?
Who are the major players in the Nutraceutical Contract Manufacturing Services market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Dietary Supplements
- 1.2.2 Functional Food & Beverages (Inclusive of Energy Drinks, Re-Constitutional One Shot Powder)
- 1.3 By Dosage Form
- 1.3.1 Tablets
- 1.3.2 Capsules
- 1.3.3 Liquid Oral
- 1.3.4 Powder in Sachet / Jar
- 1.3.5 Gummies
- 1.3.6 Energy Bars
- 1.3.7 Other Suitable Forms (Diskettes)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 149,412.25 million → 2032: USD 376,597.12 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Nutraceutical Contract Manufacturing Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Nutraceutical Contract Manufacturing Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Nutraceutical Contract Manufacturing Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Nutraceutical Contract Manufacturing Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Nutraceutical Contract Manufacturing Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Nutraceutical Contract Manufacturing Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Nutraceutical Contract Manufacturing Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Nutraceutical Contract Manufacturing Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 149,412.25 million → 2032: USD 376,597.12 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Nutraceutical Contract Manufacturing Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Dietary Supplements
- 12.3.6.2 Functional Food & Beverages (Inclusive of Energy Drinks, Re-Constitutional One Shot Powder)
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Dosage Form - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Tablets
- 12.4.6.2 Capsules
- 12.4.6.3 Liquid Oral
- 12.4.6.4 Powder in Sachet / Jar
- 12.4.6.5 Gummies
- 12.4.6.6 Energy Bars
- 12.4.6.7 Other Suitable Forms (Diskettes)
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Nutraceutical Contract Manufacturing Services Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Nutraceutical Contract Manufacturing Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Nutraceutical Contract Manufacturing Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Catalent, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Lonza Group AG
- 17.4 Patheon (Thermo Fisher Scientific)
- 17.5 Glanbia plc
- 17.6 Abbott Laboratories
- 17.7 Royal DSM N.V.
- 17.8 Robinson Pharma, Inc.
- 17.9 Biovation Labs
- 17.10 NutraScience Labs
- 17.11 Paragon Laboratories
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

