
Digital prescriptions move medicine buying online
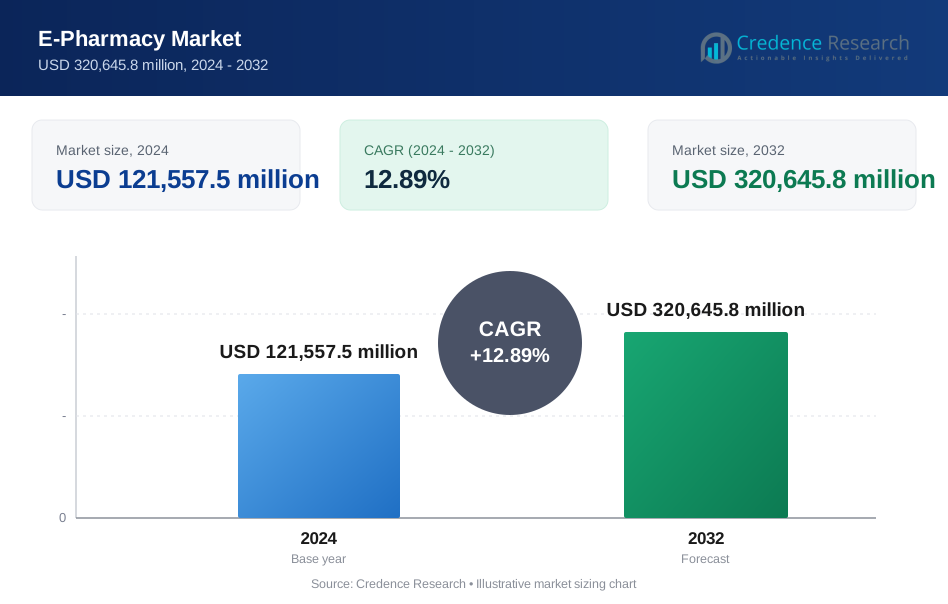
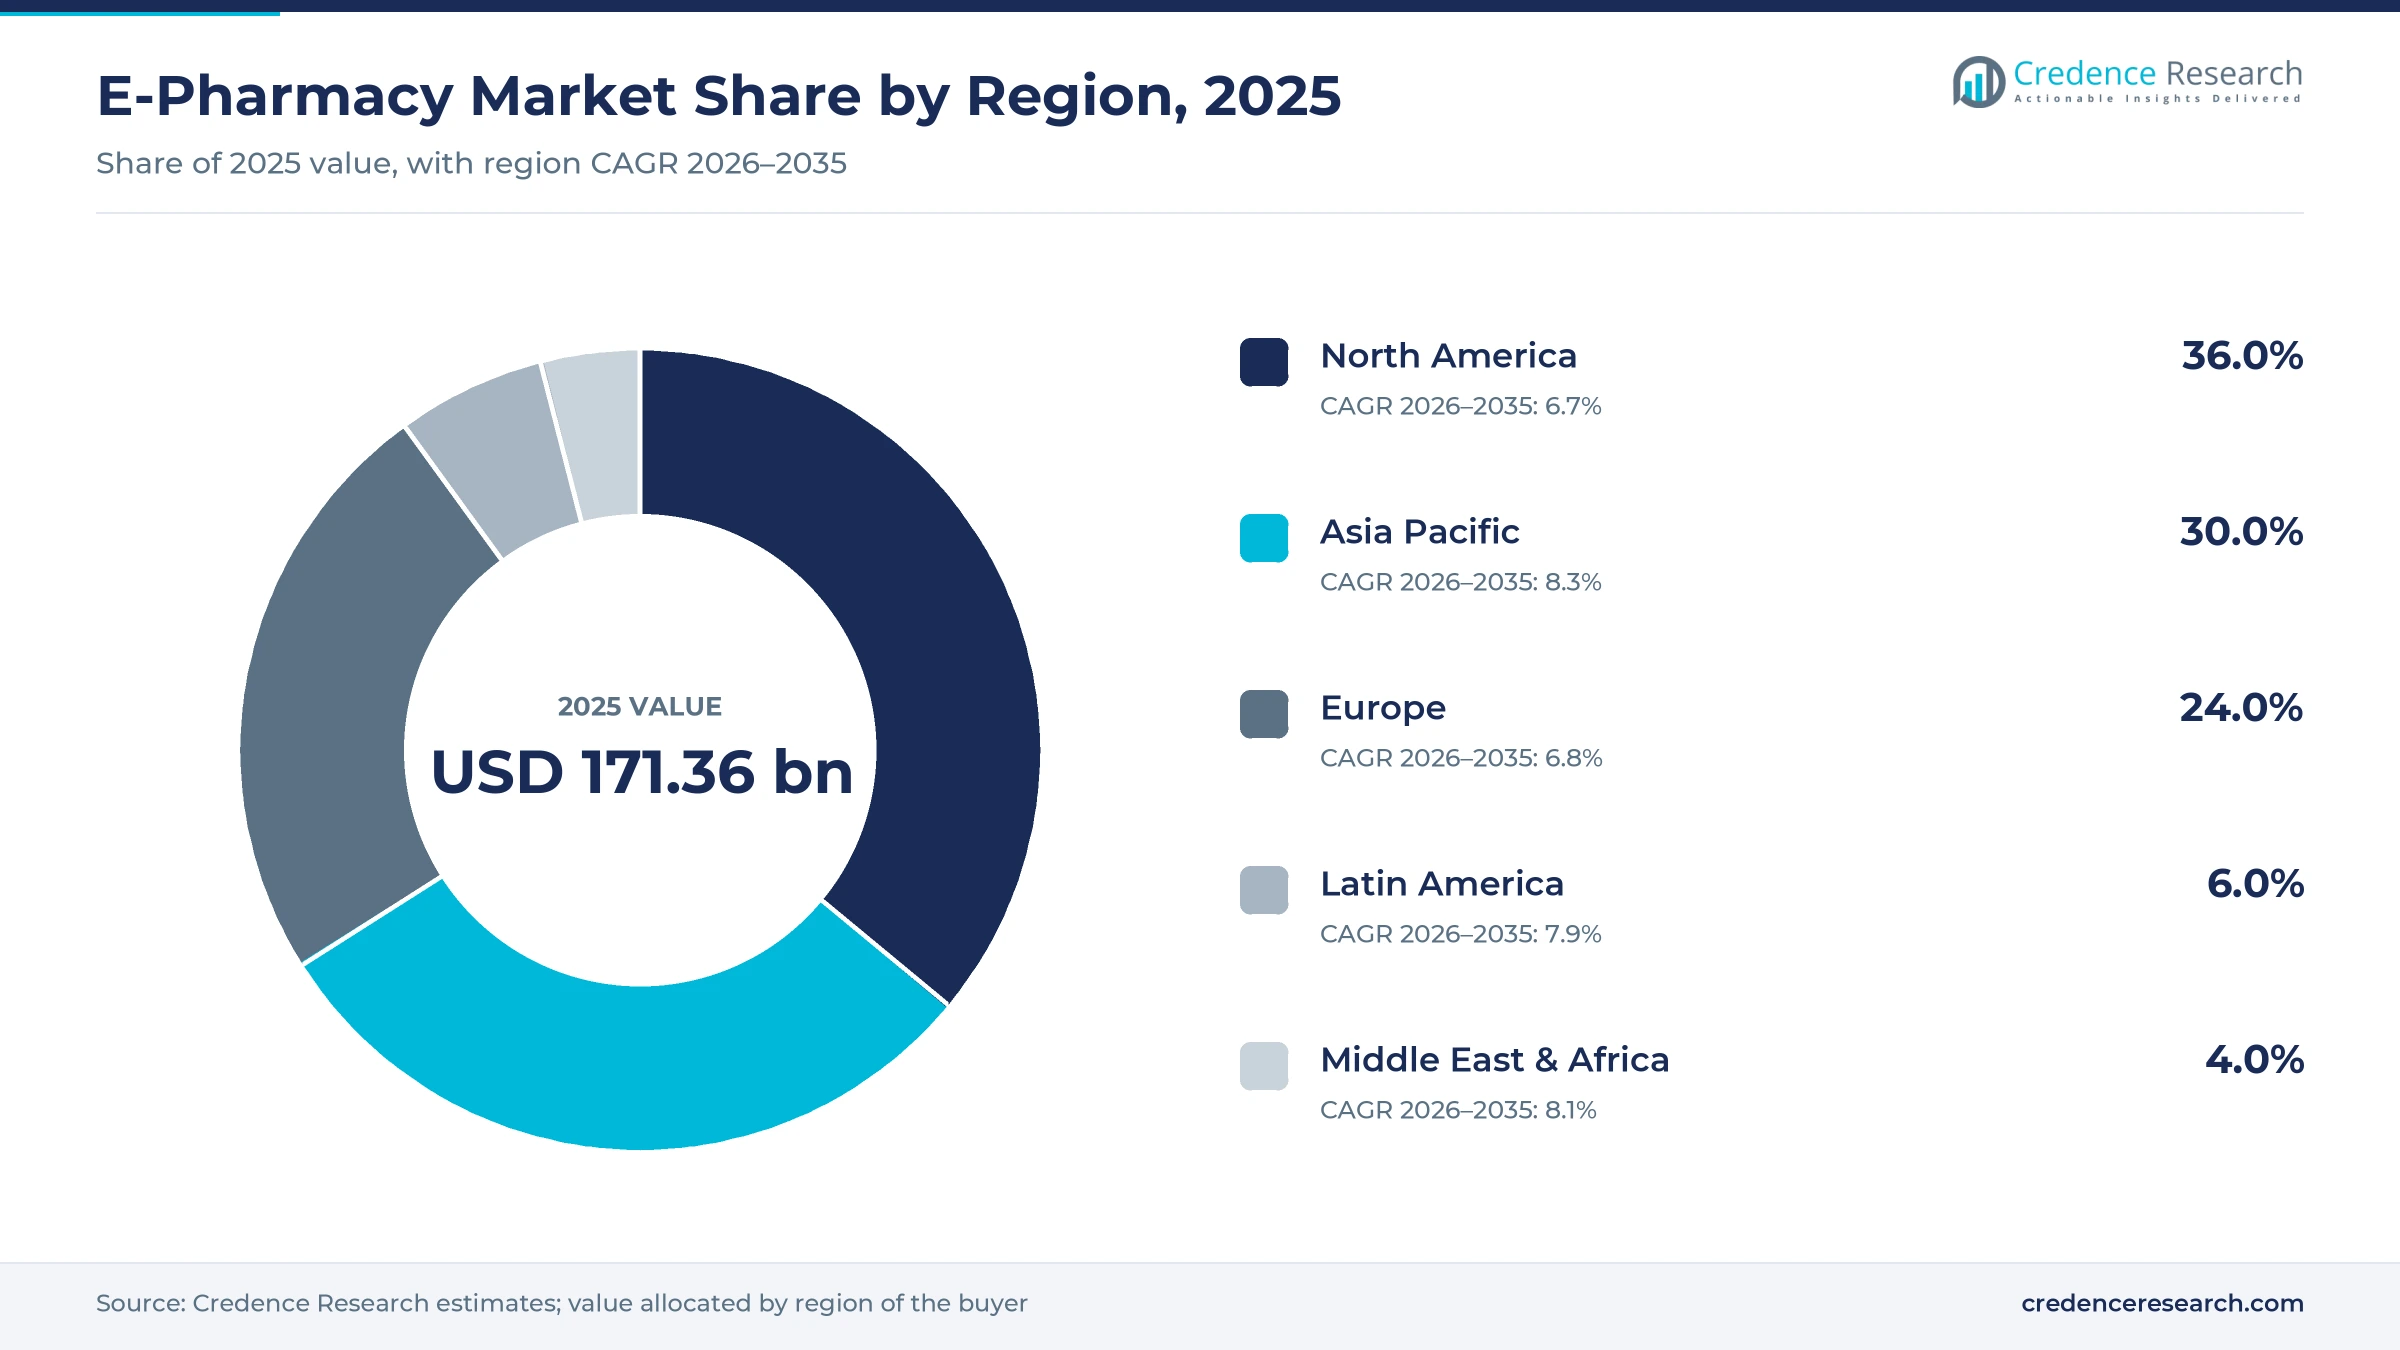
The global e-pharmacy market was valued at USD 171.36 billion in 2025 and is projected to increase from USD 184.00 billion in 2026 to USD 349.25 billion by 2035, registering a CAGR of 7.38% during 2026–2035. Demand comes from patients with chronic conditions who refill the same prescriptions every month, from households that buy over-the-counter medicines and supplements online, and from employers that arrange medicine supply for staff. North America held the largest regional share, 36.0% in 2025, on broad insurance coverage, mail-order programs and retail chains with strong apps. Asia Pacific is the fastest-growing region at 8.3% a year, as platforms in India and China widen delivery to smaller cities. The main change is the spread of electronic prescriptions, which became mandatory in Germany at the start of 2024 and let patients send prescriptions straight to an online pharmacy.
Which orders count as online pharmacy sales?
The market counts the value of medicines and health products sold to customers through websites and mobile apps run by licensed pharmacies. It covers prescription drugs filled against a doctor's order, over-the-counter medicines, vitamins and wellness products, home medical devices and personal care items. Orders are delivered to the home, collected from a store or picked up from a kiosk in a clinic.
The scope excludes medicines bought in person at a pharmacy counter, hospital inpatient dispensing and sales by unlicensed websites. Telehealth consultation fees and pharmacy benefit administration fees sit outside the market value, even when the same company provides the consultation and ships the medicine.
E-Pharmacy Market Insights
- The e-pharmacy market grows from USD 171.36 billion in 2025 to USD 349.25 billion by 2035, a 7.38% CAGR over 2026–2035, as refills, wellness buying and delivery networks expand online.
- North America held 36.0% of global e-pharmacy value in 2025, backed by insurer-linked mail order, retail chain apps and same-day delivery.
- Prescription drugs led product types with 52.0% of 2025 value, because chronic patients refill high-value medicines every month.
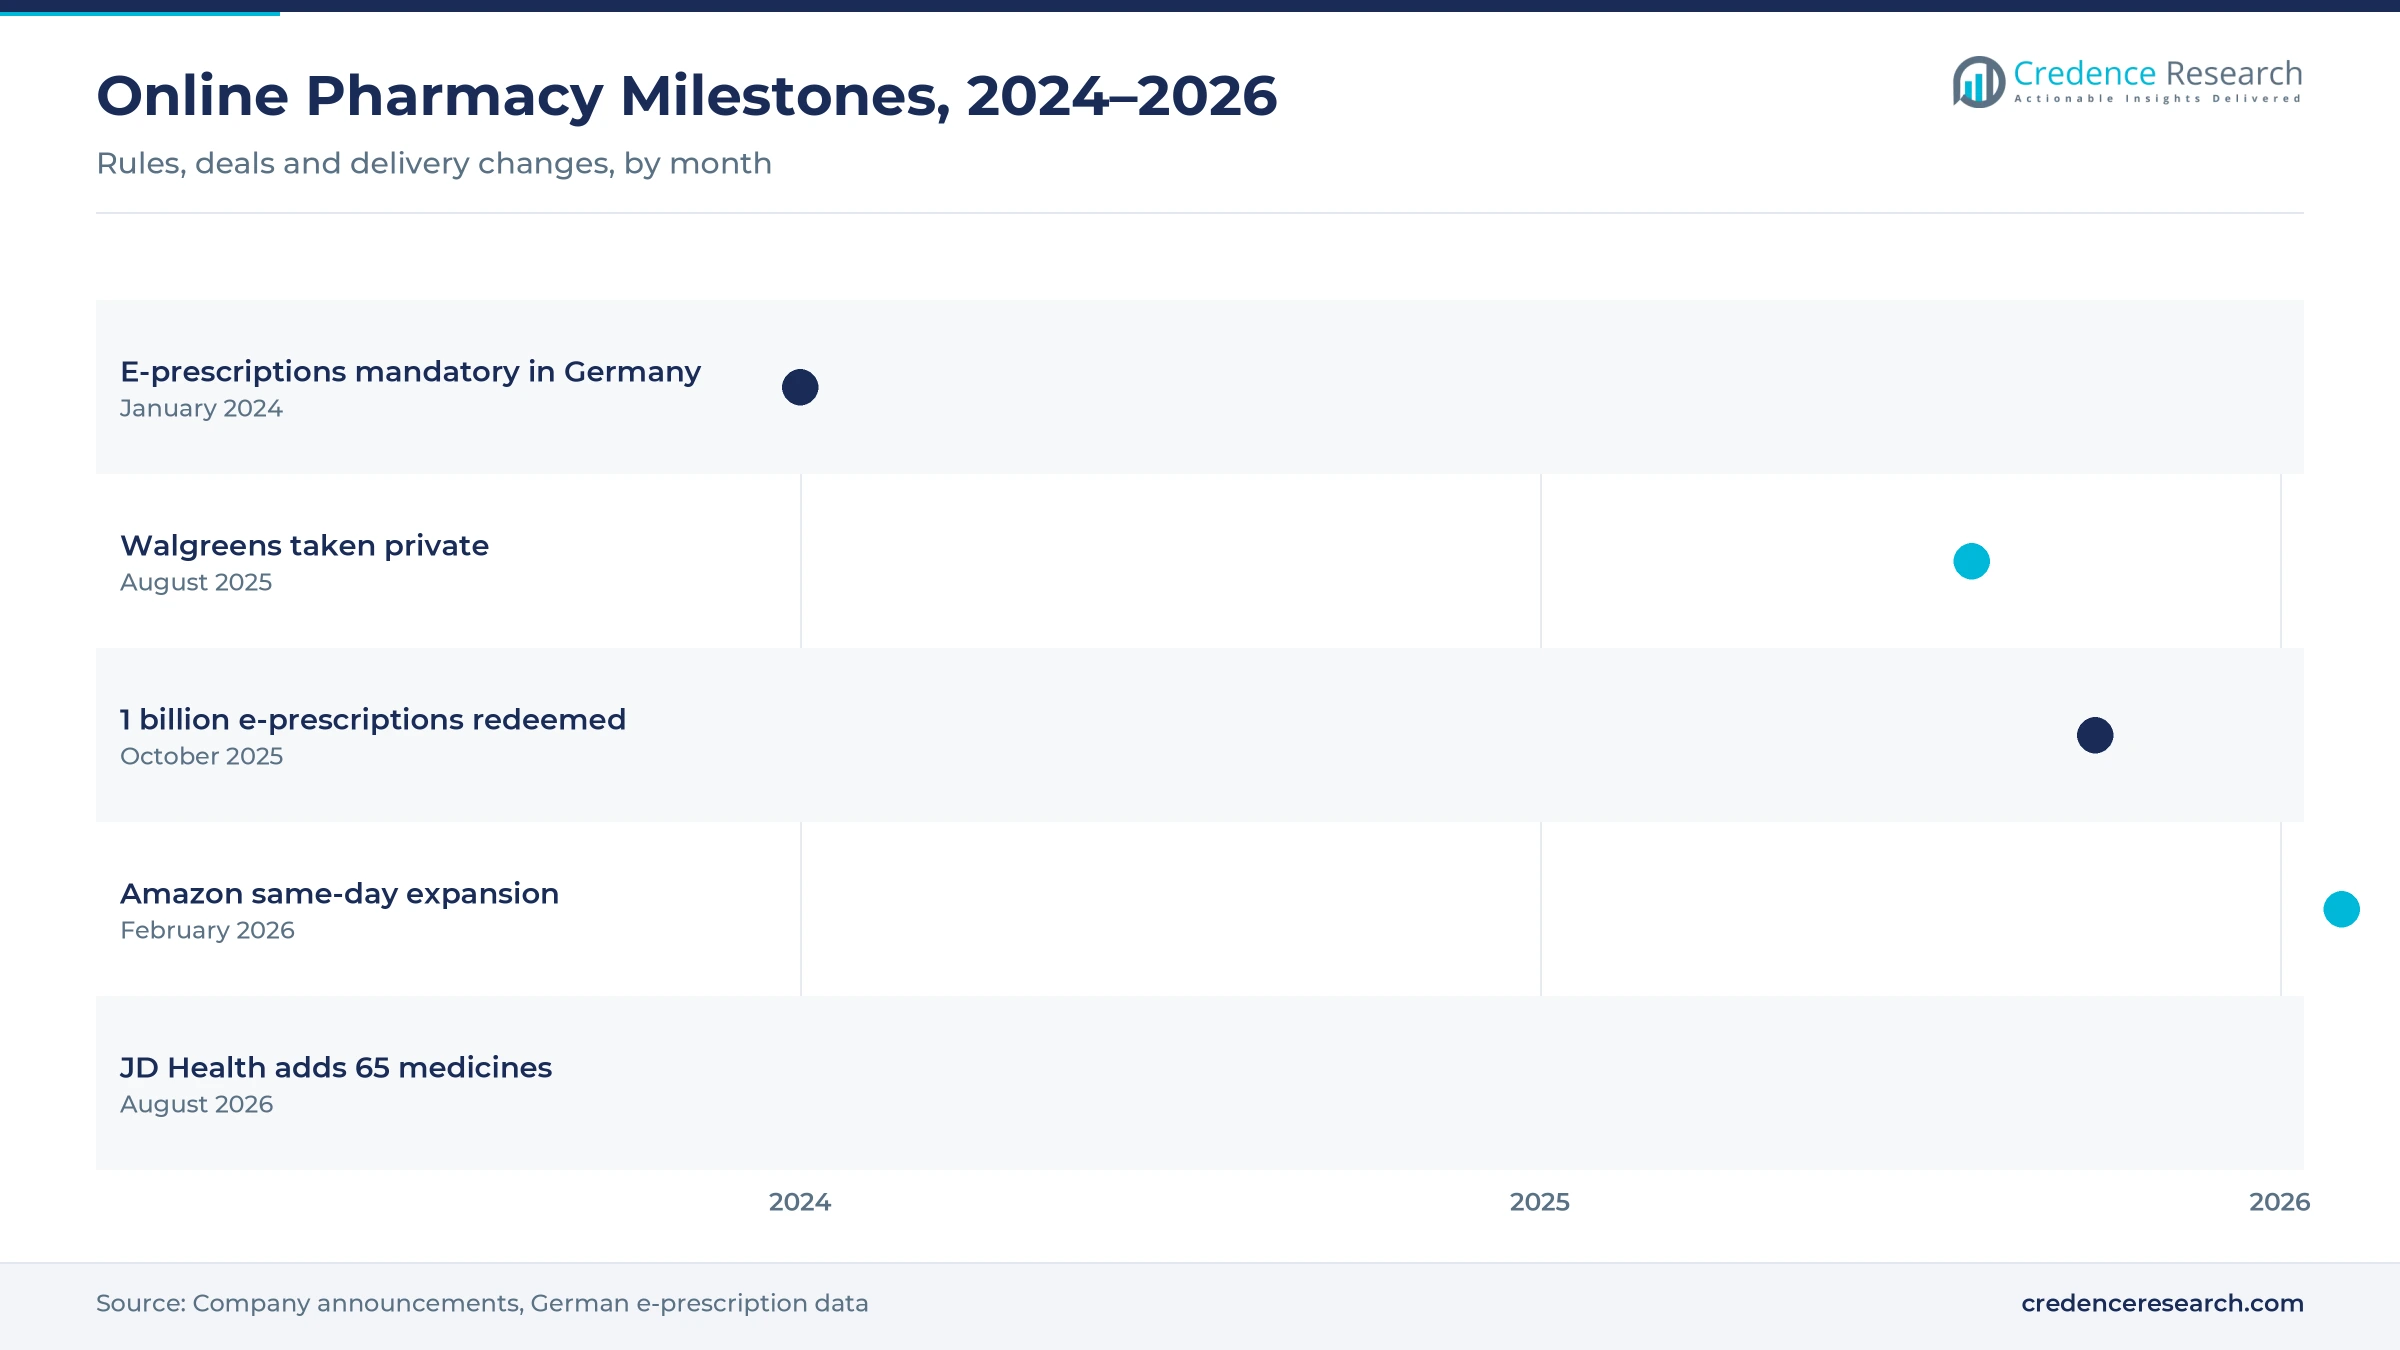
- Germany passed 1 billion redeemed e-prescriptions in October 2025, after electronic prescriptions became mandatory nationwide at the start of 2024.
- Amazon Pharmacy plans same-day delivery in nearly 4,500 U.S. cities and towns by the end of 2026, raising the bar on speed.
Prescription refills lead while wellness grows fastest
Why do prescription refills hold the largest share?
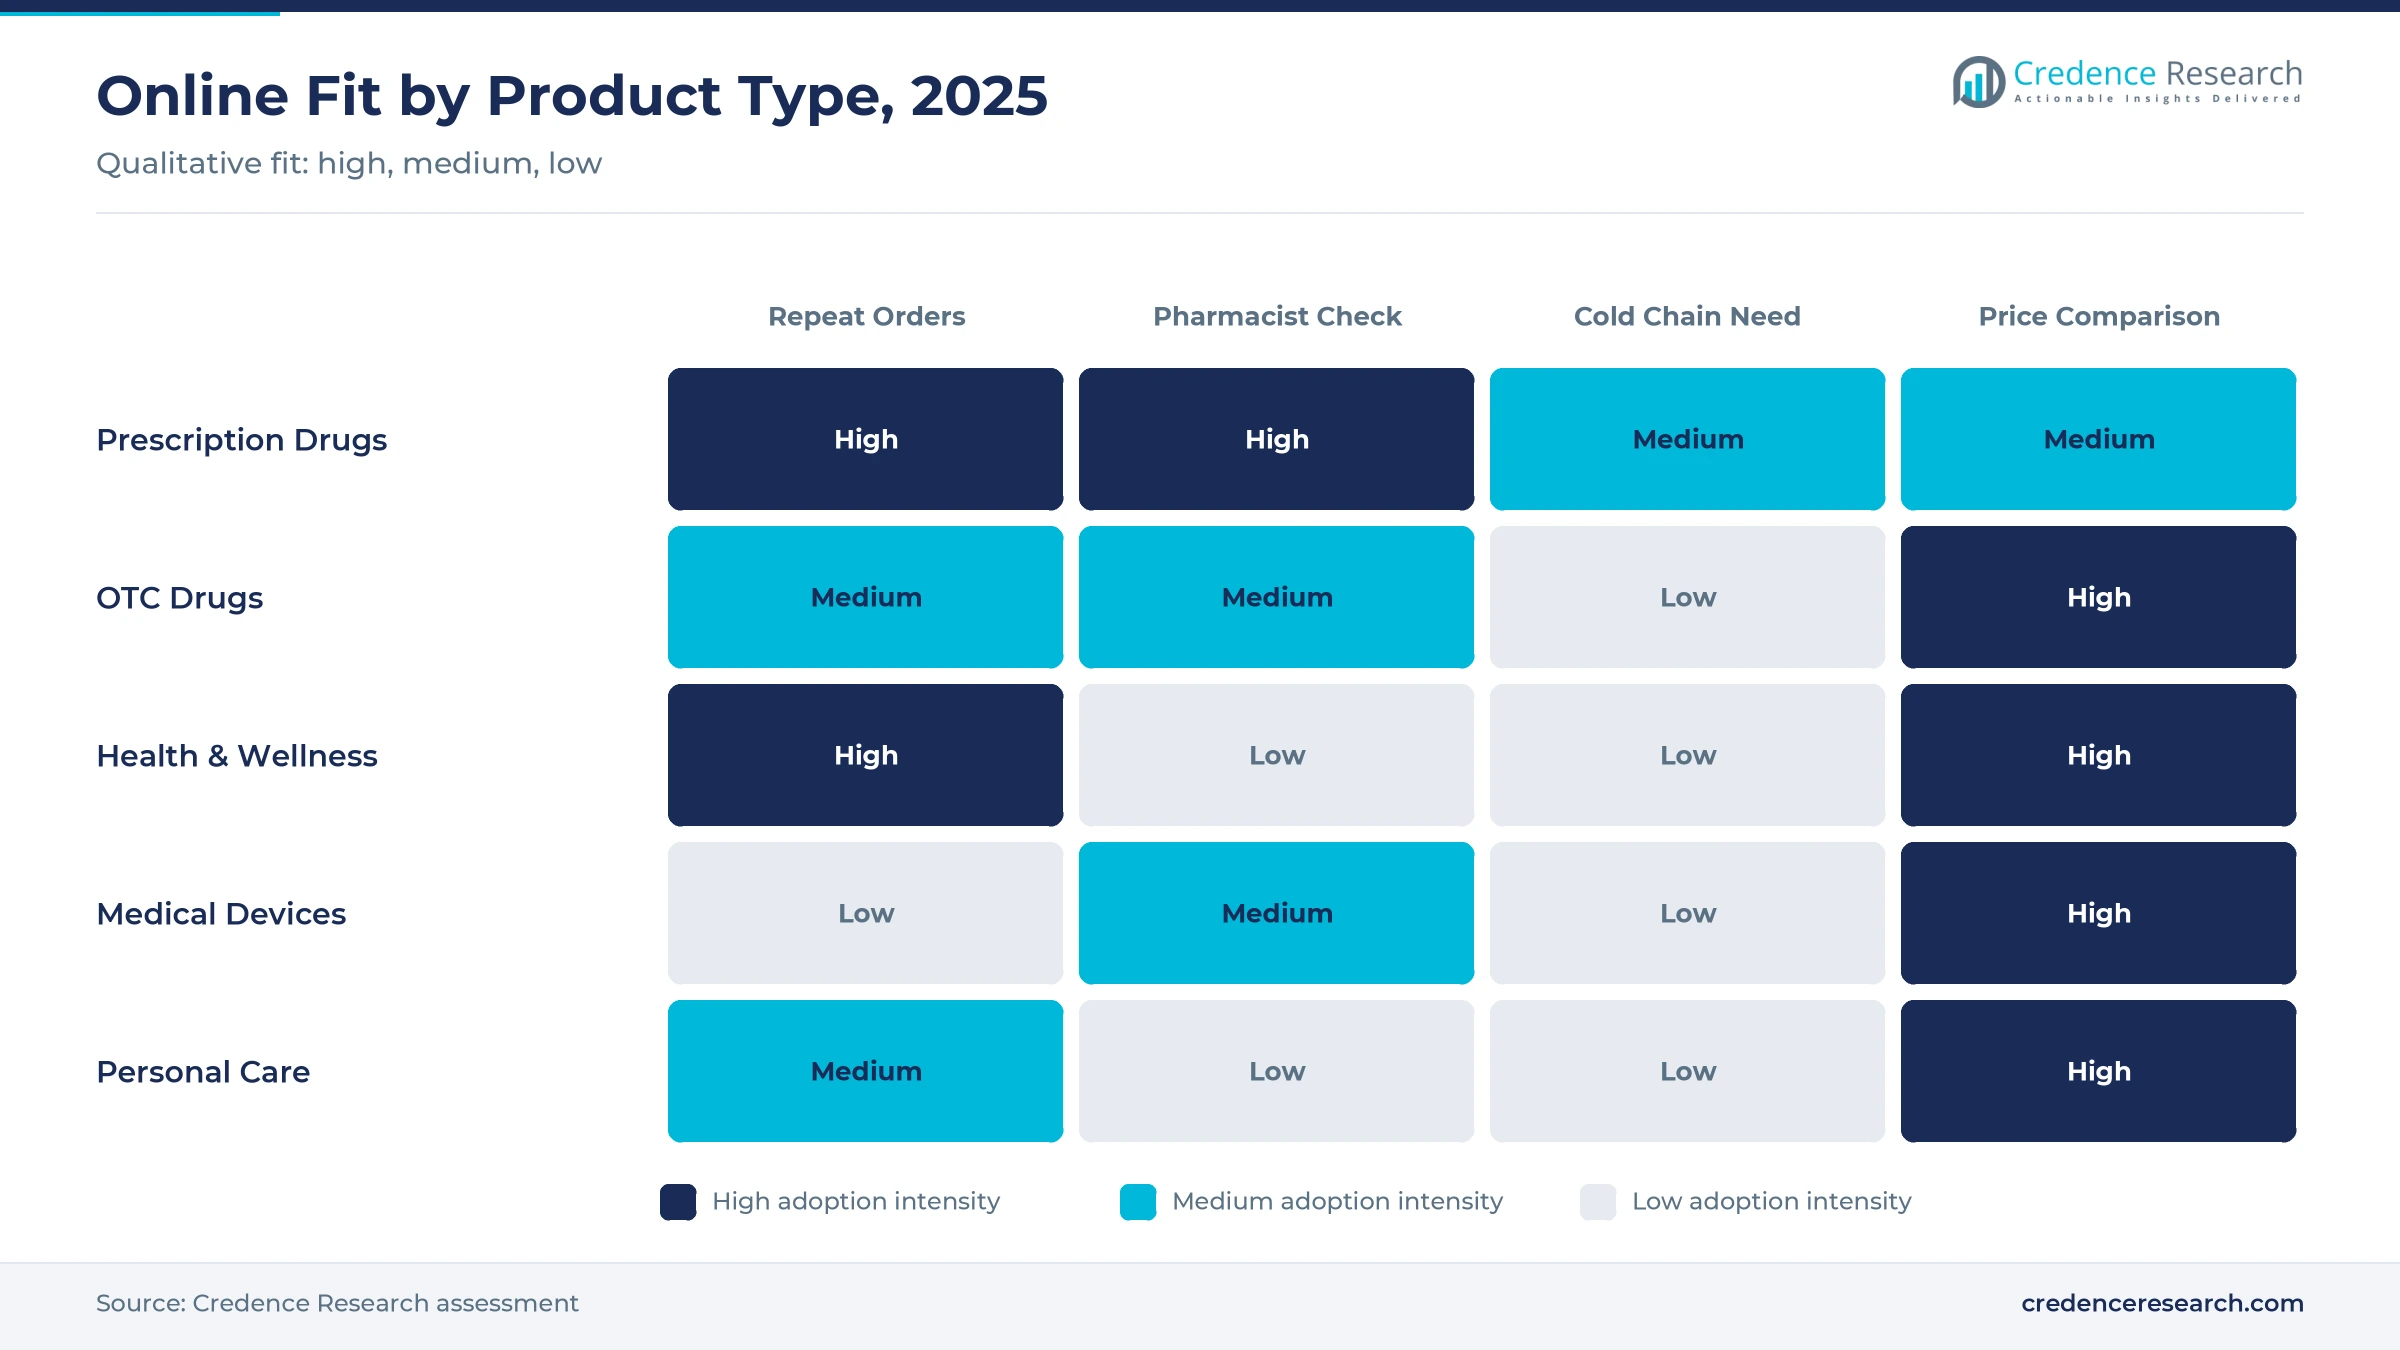
Based on product, the market is categorized into prescription drugs (Rx), over-the-counter (OTC) drugs, health and wellness products, medical devices and personal care. Prescription Drugs (Rx) led with 52.0% of 2025 value, because patients with diabetes, heart disease and other chronic conditions refill costly medicines every month. Health & Wellness Products grow fastest at 8.0% a year, as vitamins, supplements and nutrition products move into regular online baskets.
How do households and companies buy online?
Based on consumer, the market is categorized into retail consumers and corporate customers. Retail Consumers led with 88.0% of 2025 value, because individual patients and families place most orders for refills, cold remedies and wellness products. Corporate Customers grow fastest at 8.0% a year, as employers, clinics and care homes use online accounts to manage medicine supply for staff and residents.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Prescription Drugs (Rx) | 52.0% | Health & Wellness Products | 8.0% |
| By Consumer | Retail Consumers | 88.0% | Corporate Customers | 8.0% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
E-prescriptions, chronic refills and same-day delivery
How do electronic prescriptions open the online channel?
Electronic prescriptions remove the paper step that once tied patients to a nearby pharmacy, which makes online ordering much easier. Germany made e-prescriptions mandatory nationwide at the start of 2024, and more than 1 billion e-prescriptions had been redeemed by October 2025. Patients can now send a prescription code to a mail-order pharmacy instead of visiting a store. As a result, online pharmacies in Europe gain access to the prescription business that carries most of the value.
Why do chronic refills favor home delivery?
Chronic disease creates steady repeat demand, because patients with diabetes, high blood pressure or high cholesterol take the same medicines for years. Home delivery suits these patients, since automatic refills reduce missed doses and save trips to the store. Older adults and people in rural areas gain the most from this convenience. Insurers in the U.S. often offer 90-day supplies through mail order, which lowers the cost per fill for both payers and patients. This repeat pattern keeps prescription drugs the largest product group and gives online sellers predictable order volumes.
How does faster delivery change buying habits?
Delivery speed now competes with the convenience of a local store, which pulls urgent and routine orders online. In February 2026, Amazon Pharmacy said it would expand same-day prescription delivery to nearly 4,500 U.S. cities and towns by the end of 2026, adding about 2,000 communities during the year. The company also extended its $5-per-month RxPass program to Prime members in 48 states. Because faster delivery lowers the cost of waiting, more patients move refills and acute orders online.
Why does virtual care feed online orders?
Virtual doctor visits often end with an electronic prescription that patients can fill online, which links care and supply. The growth of video consultations and remote follow-up visits keeps more prescriptions inside digital channels from the start. Platforms in India and China combine online consultations with medicine delivery in a single app. In turn, each consultation becomes a likely order, which lifts conversion and repeat use across markets through 2035. Insurers that cover virtual visits strengthen this link further for chronic patients.
Kiosks, subscriptions and AI-led online care
Why are kiosks and click-and-collect rising?
Retail chains and online sellers are shifting toward hybrid models that mix home delivery with pickup points. Amazon Pharmacy placed pickup kiosks in One Medical clinic lobbies in Los Angeles, where patients collected medicines within minutes. Store-based chains such as CVS Health and Walgreens let customers order in an app and collect at the counter or drive-through. This shift blurs the line between store and online sales and keeps pharmacists close to patients.
How are subscriptions and wellness baskets emerging?
Subscription plans and wellness baskets are emerging as a way to keep customers ordering every month. Vitamins, dietary supplements, protein products and skin care sell well online, because customers compare prices and reorder without advice at the counter. Flat-fee plans for generic medicines add a second recurring stream. As a result, health and wellness products grow faster than the market average and raise the value of each customer.
Where is the opening in smaller cities?
Smaller cities and rural areas offer a clear opening, because many lack a well-stocked pharmacy within easy reach. In India, Tata 1mg and PharmEasy deliver to towns far from large hospital pharmacies, while JD Health and 111, Inc. serve similar needs in China. JD Health reported launching 65 new medicines on its platform in the first half of 2026. Companies that build regional warehouses can reach these customers at a reasonable cost and win their repeat orders.
Can corporate accounts add a second channel?
Corporate accounts offer an opening beyond household buying, because employers, clinics and care homes need reliable medicine supply. Business customers order first aid supplies, cold and pain remedies and prescriptions for residents in larger, planned batches. Online platforms can offer invoicing, approval controls and scheduled deliveries that suit these buyers. This channel grows faster than retail orders and helps sellers fill delivery routes during quiet hours.
Rogue websites, licensing rules and delivery costs
Why do rogue websites hurt trust?
Illegal websites that sell prescription medicines without a valid prescription remain a serious risk for patients and honest sellers. The FDA runs its BeSafeRx program to help consumers locate a state-licensed online pharmacy and report unlawful sales. Fake or substandard products from these sites can harm patients and damage trust in all online channels. Licensed sellers therefore invest in verification seals, pharmacist checks and clear licensing details to stand apart.
How do licensing rules slow cross-border growth?
Pharmacy licensing rules differ by country and often by state, which limits how quickly online sellers can expand. Some countries restrict mail-order sales of prescription medicines, while others allow them only from domestic pharmacies. Advertising rules, data privacy laws and controlled substance limits add further compliance work. As a result, most online pharmacies grow country by country, and cross-border prescription sales remain a small part of the market.
Why do delivery costs squeeze margins?
Fast delivery of small, low-value orders is expensive, which puts pressure on margins for online sellers. Temperature-sensitive medicines such as insulin and some biologics need cold chain logistics that raise the cost of each order. Free delivery thresholds and subscription fees help offset these costs. However, companies without dense order volumes find it hard to match the speed of the largest platforms.
What limits access for some patients?
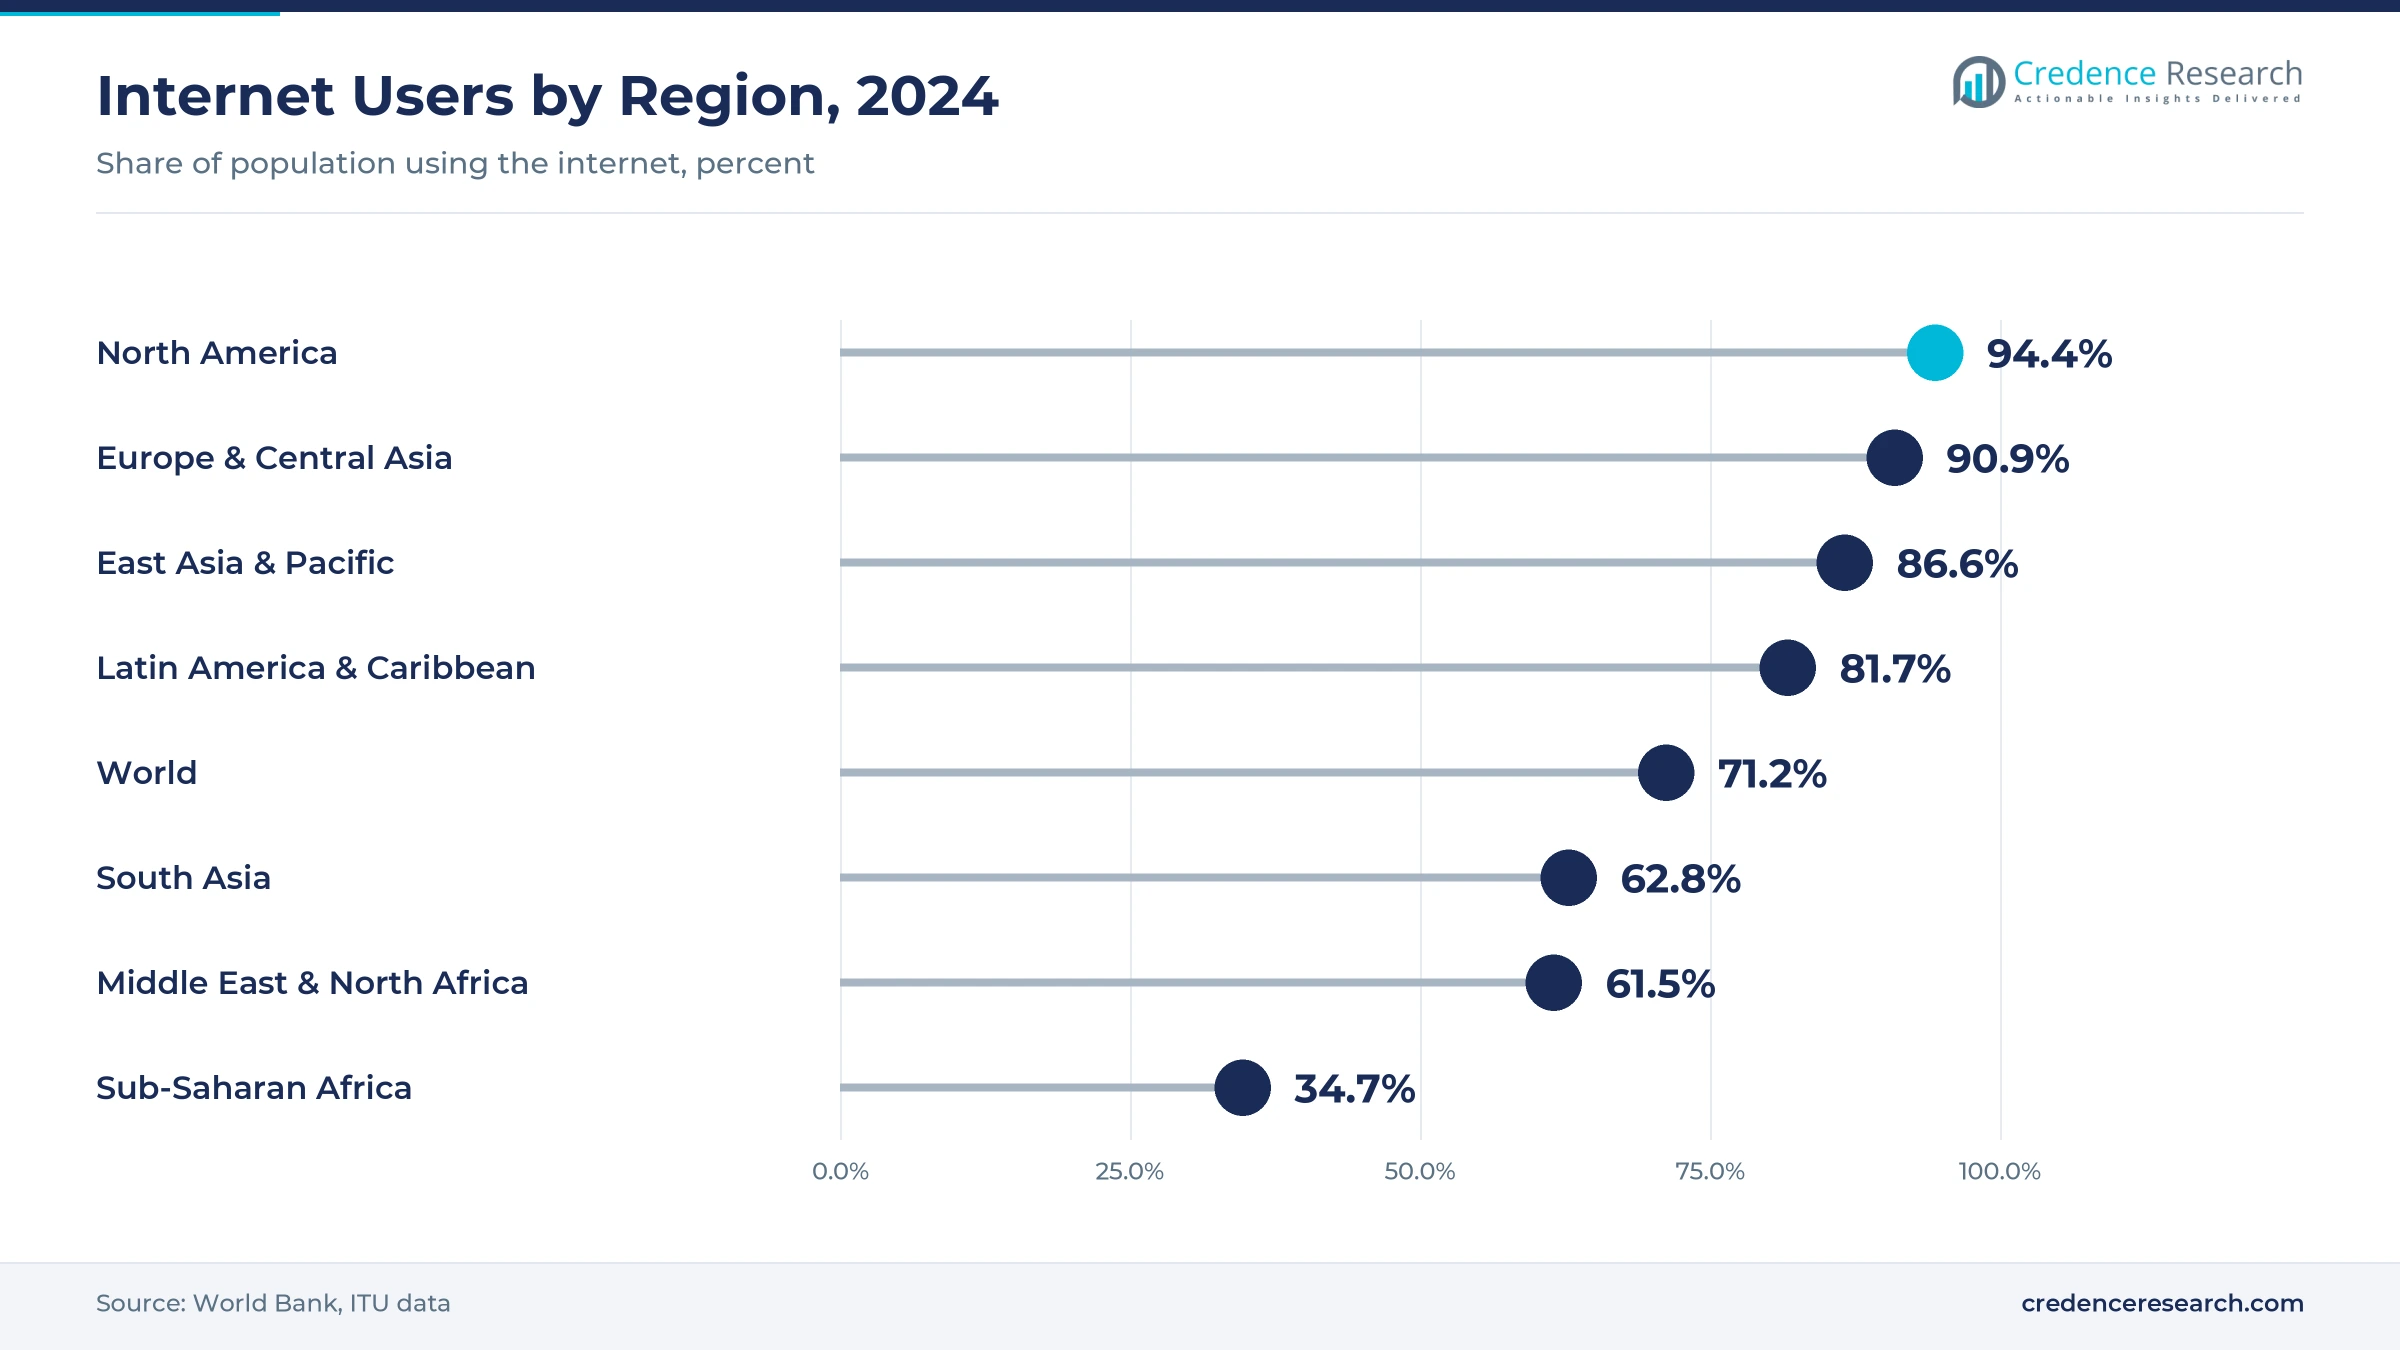
Older adults and people without reliable internet access may struggle to use apps, upload prescriptions or track deliveries. World Bank data show that internet use in 2024 ranged from 94.4% of people in North America to 34.7% in Sub-Saharan Africa. This gap limits online ordering in poorer regions and among older patients. Simple phone ordering, pharmacist calls and assisted ordering in stores help close part of this gap.
North America leads while Asia Pacific grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 61.69 | 36.0% | 6.7% |
| Asia Pacific | 51.41 | 30.0% | 8.3% |
| Europe | 41.13 | 24.0% | 6.8% |
| Latin America | 10.28 | 6.0% | 7.9% |
| Middle East & Africa | 6.85 | 4.0% | 8.1% |
North America leads on mail order and chains
North America held a 36.0% share of 2025 value and grows at 6.7% a year through 2035. The U.S. leads spending, because insurers and benefit managers steer many chronic refills to mail order and retail chains run strong apps. Amazon Pharmacy, CVS Health and Walgreens compete on delivery speed and pickup options. Walgreens became a private standalone company after Sycamore Partners completed its acquisition in August 2025.
Asia Pacific grows on app-based platforms
Asia Pacific held a 30.0% share of 2025 value and is the fastest-growing region at 8.3% a year. China and India account for most regional demand, with JD Health, 111, Inc., Tata 1mg and PharmEasy combining consultations and delivery in one app. Japan, South Korea and Australia add demand from older populations. As smartphone use spreads in smaller cities, more patients order both prescriptions and wellness products online.
Europe grows as e-prescriptions spread
Europe held a 24.0% share of 2025 value and grows at 6.8% a year through 2035. Germany is the largest market, where DocMorris reported 11.0 million active customers at the end of 2025. The country passed 1 billion redeemed e-prescriptions in October 2025, which opened prescription orders to mail-order pharmacies. However, national rules on pharmacy ownership and pricing keep growth uneven across the region.
Latin America builds on large drugstore chains
Latin America held a 6.0% share of 2025 value and grows at 7.9% a year through 2035. Brazil leads regional demand, with RD Saude using its large store network to support app orders, pickup and home delivery. Mexico and Colombia add demand as smartphone use rises in large cities.
Middle East and Africa start from a low base
The Middle East & Africa held a 4.0% share of 2025 value and grows at 8.1% a year. Saudi Arabia leads in the Gulf, where Nahdi Pharmacy links its store network with online ordering and delivery. In South Africa, Clicks supports online orders through its pharmacy chain, while lower internet use limits growth elsewhere.
Delivery expansion and ownership changes since 2024
| Development | Status and market relevance |
|---|---|
| In January 2024, electronic prescriptions became mandatory nationwide in Germany, letting patients send prescription codes to mail-order pharmacies. | In force. Opens the prescription business to online sellers. |
| In August 2025, Sycamore Partners completed its acquisition of Walgreens Boots Alliance, and Walgreens now operates as a standalone company. | Completed. Changes ownership of a major U.S. pharmacy chain. |
| In October 2025, Germany passed 1 billion redeemed e-prescriptions, as reported by the national digital health agency gematik. | Milestone. Confirms routine use of digital prescriptions. |
| In February 2026, Amazon Pharmacy announced plans to expand same-day prescription delivery to nearly 4,500 U.S. cities and towns by year end. | Rolling out. Raises delivery speed expectations in the U.S. |
| In August 2026, JD Health reported launching 65 new medicines on its platform in the first half of 2026, spanning oncology and dermatology. | Reported. Shows online platforms adding new medicines quickly. |
E-prescription links, kiosks and automated fulfillment
- E-prescription links connect doctors, insurers and pharmacies so that a prescription code reaches the chosen pharmacy within seconds.
- Pickup kiosks in clinics and stores let patients collect medicines without waiting for a home delivery slot.
- Automated fulfillment centers use robots and barcode checks to pick and pack large volumes of refills with fewer errors.
- Pharmacist video chat gives patients advice on new medicines and side effects without a visit to the counter.
- Refill reminder tools send alerts before a supply runs out, which helps chronic patients take medicines on time.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Retail chains, tech platforms and local leaders compete
Competition in online medicine sales splits into three groups with different strengths. Retail chains such as CVS Health, Walgreens, Nahdi Pharmacy and RD Saude combine apps with large store networks, so customers can choose delivery or pickup. Technology platforms such as Amazon Pharmacy, Alibaba Health and JD Health compete on delivery speed, price transparency and app design, and they use wider retail logistics to cut costs. Specialist online pharmacies, including Redcare Pharmacy, DocMorris, Tata 1mg, PharmEasy and 111, Inc., focus on one country or region and often add teleconsultations, diagnostics and supplier services. Because licensing rules are national, most companies lead in one market rather than across regions. Scale in refills, warehouse coverage and pharmacist access decide which sellers keep customers over time.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Amazon Pharmacy (Amazon) | Technology platform | Same-day delivery, RxPass and clinic kiosks in the U.S. |
| CVS Health | Retail chain | App ordering, pickup and mail order in the U.S. |
| Walgreens | Retail chain | App ordering and pickup; private standalone company since August 2025 |
| Alibaba Health | Technology platform | Online pharmacy on Tmall and Taobao plus consultations in China |
| JD Health | Technology platform | Online pharmacy and consultations in China |
| Redcare Pharmacy | Online pharmacy | Online prescriptions and OTC products in Germany and other European countries |
| DocMorris | Online pharmacy | Mail-order prescriptions and OTC products in Germany |
| Tata 1mg | Online pharmacy | Medicines, diagnostics and consultations in India |
| PharmEasy | Online pharmacy | Medicine delivery and diagnostics in India |
| 111, Inc. | Online pharmacy | Online pharmacy and supply services in China |
| Nahdi Pharmacy | Retail chain | Store network with online ordering in Saudi Arabia |
| RD Saude | Retail chain | Drugstore network with app orders in Brazil |
Refill volume and delivery speed decide the winners
Credence Research's view is that prescription refills and delivery speed will decide which online pharmacies grow fastest through 2035. E-prescriptions have removed the main barrier in Germany, and similar systems in other countries will widen the prescription pool. Wellness products add margin and frequency, but they do not replace the value of chronic refills. Companies that pair dense delivery networks with pharmacist support and insurer links are best placed, while smaller sellers will need partnerships to keep up.
How the 2025 baseline and forecast were built
The report uses 2025 as the base year and forecasts market value to 2035, with growth rates stated for 2026–2035. Market values come from the Credence Research market model, which combines online order volumes, average basket values and prescription shares by region. Splits by product, consumer type and region are Credence Research estimates. Sources used include FDA and World Bank data, German e-prescription statistics and company press releases and filings. No primary interviews or surveys were used to build the estimates in this report.
Online refills become routine in most regions by 2035
By 2035, the market reaches USD 349.25 billion, with online refills becoming a routine option in most regions. Prescription drugs remain the largest product group as e-prescriptions spread beyond Germany and the U.S. Health and wellness products gain share as customers reorder supplements and nutrition items each month. Asia Pacific narrows the gap with North America as platforms in China and India reach smaller cities. Delivery speed, pharmacist access and licensing compliance remain the main tests for every seller in the market.
Frequently Asked Questions
How big is the e-pharmacy market?
Which product type leads the market?
Which product type grows fastest?
Which region holds the largest share?
How have e-prescriptions changed online pharmacy in Germany?
How fast is same-day delivery spreading?
Who are the leading companies?
What are the main challenges?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Prescription Drugs (Rx)
- 1.2.2 Over-the-Counter (OTC) Drugs
- 1.2.3 Health & Wellness Products
- 1.2.4 Medical Devices
- 1.2.5 Personal Care
- 1.3 By Consumer
- 1.3.1 Retail Consumers
- 1.3.2 Corporate Customers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 171.36 billion → 2035: USD 349.25 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global E-Pharmacy Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global E-Pharmacy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global E-Pharmacy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global E-Pharmacy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global E-Pharmacy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global E-Pharmacy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global E-Pharmacy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global E-Pharmacy Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 171.36 billion → 2035: USD 349.25 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global E-Pharmacy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Prescription Drugs (Rx)
- 12.3.7.2 Over-the-Counter (OTC) Drugs
- 12.3.7.3 Health & Wellness Products
- 12.3.7.4 Medical Devices
- 12.3.7.5 Personal Care
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Consumer - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Retail Consumers
- 12.4.7.2 Corporate Customers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global E-Pharmacy Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global E-Pharmacy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global E-Pharmacy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Amazon Pharmacy (Amazon)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 CVS Health
- 17.4 Walgreens
- 17.5 Alibaba Health
- 17.6 JD Health
- 17.7 Redcare Pharmacy
- 17.8 DocMorris
- 17.9 Tata 1mg
- 17.10 PharmEasy
- 17.11 111, Inc.
- 17.12 Nahdi Pharmacy
- 17.13 RD Saude
- 17.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

