
Market Overview:
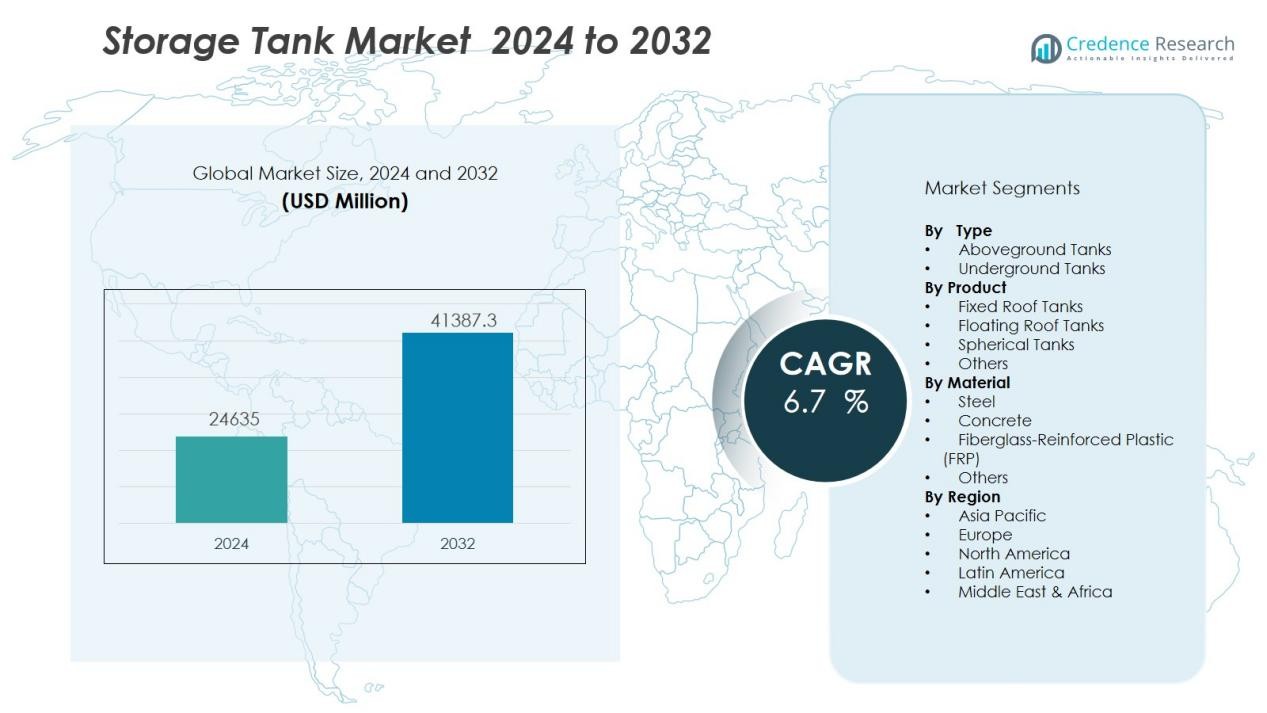
The Storage tank market size was valued at USD 24635 million in 2024 and is anticipated to reach USD 41387.3 million by 2032, at a CAGR of 6.7 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Storage tank market Size 2024 | USD 24635 Million |
| Storage tank market , CAGR | 6.7 % |
| Storage tank market Size 2032 | USD 41387.3 Million |
Key drivers fueling the storage tank market include stringent environmental regulations, a heightened focus on operational safety, and rapid technological advancements in tank materials and monitoring systems. Companies are upgrading storage infrastructure to comply with evolving standards, prevent leakages, and minimize operational risks. The adoption of automation and remote monitoring solutions further enhances market growth, as organizations aim to optimize asset management and improve overall efficiency.
Regionally, North America dominates the storage tank market due to robust infrastructure development, large-scale oil and gas projects, and the early adoption of advanced equipment. Europe holds a significant share, supported by modernization initiatives and strict environmental policies. The Asia-Pacific region is expected to record the fastest growth, propelled by rapid industrialization, expanding manufacturing sectors, and rising investments in water and wastewater management, especially in emerging economies such as China and India.
Market Insights:
- The storage tank market reached USD 24,635 million in 2024 and is projected to hit USD 41,387.3 million by 2032, growing at a 6.7% CAGR.
- Stringent environmental regulations and a strong focus on operational safety are primary growth drivers, encouraging upgrades to modern, compliant storage systems.
- Investments in oil, gas, chemical, and water infrastructure increase demand for advanced and reliable storage solutions across key industries.
- Rapid adoption of automation and remote monitoring technologies supports improved asset management, regulatory compliance, and operational efficiency.
- Rising raw material costs and supply chain volatility challenge market profitability, compelling companies to optimize procurement and production strategies.
- North America leads the market with a 38.5% share, followed by Europe at 27.4%, both supported by modernization and strict regulatory frameworks.
- Asia-Pacific exhibits the fastest growth, accounting for 24.6% of the market, driven by rapid industrialization, urban expansion, and ongoing investments in water and energy infrastructure.
Market Drivers:
Rising Investments in Oil, Gas, and Chemical Infrastructure Propel Demand for Storage Solutions:
The storage tank market experiences strong demand growth due to increased investments in oil, gas, and chemical infrastructure worldwide. Companies require advanced storage systems to safely manage and transport raw materials, intermediates, and finished products. Large-scale energy projects and the expansion of petrochemical facilities drive the need for robust and compliant storage tanks. The market continues to evolve in response to the operational requirements of these capital-intensive industries.
- For example, Fluor Corporation has recently completed significant module fabrication, including one of the second largest LNG storage tanks in the world at the LNG Canada Project, standing 56 meters high and 75 meters in diameter with a volume of more than 225,000 cubic meters.
Stringent Environmental Regulations and Safety Standards Drive Technological Upgrades:
Governments and regulatory bodies enforce strict environmental and safety regulations, compelling companies to upgrade or replace existing storage infrastructure. The storage tank market responds with innovations in materials, leak detection, and emission control systems to meet evolving standards. Industry players must implement advanced features such as double-walled tanks and vapor recovery to prevent contamination and comply with regulatory expectations. These drivers accelerate the pace of modernization across all sectors utilizing storage tanks.
- For instance, Beltecno installed huge earthquake-resistant water storage tanks across Japan with capacities ranging from 1,200 kL up to 10,000 kL, ensuring stable water supply under seismic conditions through advanced engineering.
Growing Focus on Water and Wastewater Management Supports Long-Term Market Expansion:
Rapid urbanization and industrialization place pressure on water resources and drive the construction of new water storage and wastewater treatment facilities. The storage tank market benefits from public and private investments targeting improved water supply reliability and environmental sustainability. Municipalities and industries rely on advanced tanks to ensure safe storage and efficient management of water and effluents. The market’s role expands alongside growing demand for water infrastructure solutions.
Advancements in Digitalization and Automation Enhance Asset Management and Efficiency:
Digital transformation initiatives create new opportunities in the storage tank market. Companies implement IoT-enabled sensors, remote monitoring, and predictive analytics to optimize tank performance and minimize operational risks. Automation improves inventory management, maintenance planning, and regulatory compliance. The integration of digital solutions elevates asset visibility and supports proactive decision-making, further strengthening market growth.
Market Trends:
Rising Integration of Advanced Materials and Smart Technologies Enhances Operational Efficiency in the Storage Tank Market:
The storage tank market is witnessing a marked shift toward the adoption of advanced materials and smart technologies to improve performance and safety. Companies are investing in composite and corrosion-resistant alloys, extending the lifespan of storage tanks and reducing maintenance costs. Smart sensors and remote monitoring systems are becoming standard features, enabling real-time data collection, leak detection, and predictive maintenance. Digitalization supports compliance with strict environmental regulations by improving asset traceability and operational transparency. The push for automation has also led to the integration of IoT and AI-based monitoring, which streamlines operational processes and mitigates risk. These technological advancements help organizations minimize downtime and optimize the total cost of ownership.
- For instance, Energy Robotics’ BVLOS-approved drone inspections at Shell Rheinland complete an average 8-hour manual tank-roof survey in just 20 minutes, cutting inspection time by 95% per floating roof tank.
Growing Focus on Sustainability and Regulatory Compliance Shapes Market Dynamics Across Regions:
Sustainability concerns and evolving regulatory frameworks are shaping the direction of the storage tank market. Companies in developed regions are prioritizing green solutions, investing in double-walled tanks, vapor recovery systems, and environmentally friendly coatings to minimize emissions and soil contamination. Regulatory authorities are enforcing more stringent standards, driving the demand for advanced safety features and periodic tank upgrades. The growing need for secure storage of water and renewable energy sources, such as biofuels and hydrogen, is expanding the application scope of storage tanks. Emerging economies in Asia-Pacific are rapidly modernizing infrastructure to support industrialization while aligning with global environmental benchmarks. It is evident that sustainability and compliance are central to the strategic investments and innovation occurring throughout the market.
- For instance, Sharp Tanks and Structurals P. Ltd. recently completed two Full Integrity Double Walled Storage Tanks each with a capacity of 15,000 metric tons at Krishnapattanam Port, incorporating advanced insulation and safety standards to substantially reduce environmental risks.
Market Challenges Analysis:
Escalating Raw Material Costs and Supply Chain Volatility Impact Profitability in the Storage Tank Market:
The storage tank market faces significant challenges due to rising raw material costs and ongoing supply chain disruptions. Prices for steel, composites, and specialized alloys have surged, directly impacting manufacturing expenses and eroding profit margins for suppliers. Volatility in global logistics further complicates project timelines, delaying deliveries and increasing overall costs. Companies are compelled to reassess procurement strategies and explore alternative sourcing, yet persistent unpredictability hinders long-term planning. Smaller market players struggle to absorb these fluctuations, risking reduced competitiveness. The market must adapt to maintain steady supply and cost efficiency.
Stringent Regulatory Compliance and Complex Installation Requirements Increase Barriers to Entry:
Compliance with evolving environmental and safety regulations imposes another layer of complexity on the storage tank market. The need to adhere to local, national, and international standards drives up engineering, testing, and certification costs. Installation of modern storage tanks often demands advanced technical expertise, sophisticated safety protocols, and extensive documentation. Project delays may occur when permitting processes become protracted or requirements shift unexpectedly. These challenges raise barriers to entry, making it difficult for new and smaller players to gain traction. The market remains under pressure to balance compliance, safety, and operational efficiency.
Market Opportunities:
Expansion of Renewable Energy Infrastructure and Water Management Initiatives Opens New Growth Avenues:
The storage tank market stands to benefit from global investments in renewable energy infrastructure and water management projects. Growth in biofuel, hydrogen, and LNG sectors requires specialized storage solutions, creating substantial demand for advanced tanks with enhanced safety and durability features. Governments and private organizations are increasing investments in water storage and wastewater treatment facilities, further expanding the application scope for storage tanks. Urbanization and population growth accelerate the need for reliable storage in both industrial and municipal settings. Companies that offer technologically advanced and customizable solutions are well positioned to capture emerging opportunities. The market is poised to evolve alongside new energy and sustainability trends.
Adoption of Smart Monitoring Systems and Digital Solutions Accelerates Competitive Differentiation:
The integration of IoT-enabled sensors, real-time monitoring platforms, and predictive analytics is unlocking new opportunities for the storage tank market. These technologies enable companies to optimize asset management, reduce operational risks, and comply with evolving regulations. Remote diagnostics and automated maintenance alert systems help minimize downtime and improve overall efficiency. Providers who develop comprehensive digital service offerings can build long-term customer relationships and differentiate themselves in a competitive landscape. As industries transition toward smart infrastructure, the market can capitalize on rising demand for digitalized and automated storage solutions.
Market Segmentation Analysis:
By Type:
The storage tank market segments by type into aboveground and underground tanks. Aboveground tanks dominate due to easier inspection, maintenance, and lower installation costs. Industries prefer aboveground systems for temporary storage and rapid deployment needs. Underground tanks serve applications with space constraints or strict environmental requirements, particularly in fuel and chemical storage. Regulatory standards drive the adoption of advanced safety and leak detection features in both segments.
- For instance, Veolia Nuclear Solutions deployed four modular 30 m³ double-walled effluent treatment tanks-each capable of 4–6 m³/hr throughput-at UK Magnox decommissioning sites, achieving 95% containment and reducing onsite emissions by over 90% during continuous 24-hour operations.
By Product:
It divides by product into fixed roof, floating roof, spherical, and others. Fixed roof tanks account for a significant share due to their widespread use in storing water, chemicals, and oil products. Floating roof tanks find application in volatile liquid storage, minimizing vapor loss and emissions. Spherical tanks address high-pressure storage needs, especially in the petrochemical and gas sectors. The market adapts product development to match safety and operational requirements across diverse end uses.
- For instance, CIMC Enric developed a double-walled vacuum spherical tank with a volume of 400 cubic meters, capable of holding over 25 tons of liquid hydrogen, demonstrating superior structural stability and safety in ultra-low temperature storage applications.
By Material:
Material segmentation includes steel, concrete, fiberglass-reinforced plastic (FRP), and others. Steel tanks lead the market because of their strength, versatility, and established industry standards. FRP tanks are gaining traction for their resistance to corrosion and chemicals, making them suitable for aggressive industrial environments. Concrete tanks remain relevant in municipal water and wastewater applications where durability and capacity matter most. The choice of material reflects a balance between performance, cost, and compliance.
Segmentations:
By Type:
- Aboveground Tanks
- Underground Tanks
By Product:
- Fixed Roof Tanks
- Floating Roof Tanks
- Spherical Tanks
- Others
By Material:
- Steel
- Concrete
- Fiberglass-Reinforced Plastic (FRP)
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America :
North America commands a market share of 38.5% in the storage tank market, driven by significant investments in oil, gas, and chemical infrastructure. The region benefits from robust regulatory frameworks that mandate advanced safety and environmental controls, fostering steady demand for high-quality storage solutions. Large-scale industrial projects and the expansion of refineries support ongoing installations and retrofits of storage tanks. Companies in the United States and Canada actively adopt smart monitoring and automation technologies to enhance operational efficiency. The prevalence of established manufacturers and early adopters of digital solutions further strengthens the region’s leadership. Ongoing investments in water and wastewater management also contribute to market growth.
Europe:
Europe holds a market share of 27.4% in the storage tank market, underpinned by modernization of aging infrastructure and adoption of advanced environmental standards. Stringent EU regulations drive upgrades to storage facilities across oil, gas, chemical, and water sectors. The push for energy transition and sustainability accelerates demand for storage tanks supporting biofuels, hydrogen, and renewable energy sources. Countries such as Germany, the United Kingdom, and France lead investments in automated and corrosion-resistant solutions. The market in Europe continues to diversify as companies integrate IoT, leak detection, and emission control features. Increasing water scarcity also spurs investments in water storage and management.
Asia-Pacific :
Asia-Pacific accounts for 24.6% of the storage tank market and exhibits the fastest growth rate globally. Rapid industrialization and urbanization in China, India, and Southeast Asian countries drive unprecedented demand for reliable storage solutions across multiple industries. Governments and private investors focus on expanding energy infrastructure, manufacturing bases, and water management systems. The region’s ongoing investments in large-scale industrial and municipal projects fuel high-volume tank installations. Companies target this market with cost-effective, high-capacity, and technologically advanced products. Asia-Pacific’s accelerating shift toward compliance with international environmental and safety standards supports sustained long-term expansion for the storage tank market.
Key Player Analysis:
- TOYO KANETSU K.K
- CST Industries, Inc.
- McDermott
- Ishii Iron Works Co., Ltd
- Superior Tank Co. Inc.
- Pfaudler MEKRO Sp. Z O.O
- PERMIANLIDE
- F Warren Group Inc.
- Highland Tank & Manufacturing Co. Inc.
- Fox Tank Company
Competitive Analysis:
The storage tank market features a dynamic competitive landscape with the presence of global and regional players. Key companies such as TOYO KANETSU K.K, CST Industries, Inc., McDermott, Ishii Iron Works Co., Ltd, Superior Tank Co. Inc., Pfaudler MEKRO Sp. Z O.O, and PERMIANLIDE drive innovation and shape industry standards. It focuses on advanced material development, automation, and environmentally compliant solutions to address evolving customer and regulatory demands. Market leaders invest in expanding production capabilities, strategic partnerships, and technological upgrades to maintain their competitive advantage. Companies differentiate themselves through expertise in customized tank design, after-sales services, and integrated digital solutions. The storage tank market remains competitive, rewarding firms that deliver reliable quality, regulatory compliance, and responsive customer support.
Recent Developments:
- In February 2024, CST Industries acquired Ostsee Tank Solutions GmbH to expand global business and product offerings.
- In July 2024, Announced agreement to sell CB&I storage business to a consortium led by Mason Capital Management, expected closure in Q4 2024.
- In September 2024, Kanariya Co., Ltd completed the acquisition of a 76.60023% stake in Ishii Iron Works Co., Ltd. for ¥22.3 million on September 24, 2024, and Ishii Iron Works became a subsidiary of Kanariya.
Market Concentration & Characteristics:
The storage tank market demonstrates a moderately fragmented landscape, with a mix of established global players and numerous regional suppliers. It features high entry barriers due to strict regulatory standards, advanced technology requirements, and capital-intensive manufacturing processes. Leading companies focus on innovation in materials, automation, and monitoring systems to maintain a competitive edge. The market experiences steady demand across oil and gas, chemical, water, and wastewater sectors, ensuring resilient growth. Strategic partnerships, mergers, and capacity expansions are common as firms seek to strengthen their geographic reach and product portfolios. The storage tank market rewards companies that prioritize compliance, reliability, and customized solutions tailored to evolving industry needs.
Report Coverage:
The research report offers an in-depth analysis based on Segment 1, Segment 2, Segment 3, and Segment 3. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The storage tank market will experience sustained growth driven by ongoing industrial expansion and modernization projects.
- Demand for advanced, corrosion-resistant materials will continue to increase, supporting longer tank lifespans and reduced maintenance.
- Automation and digital monitoring technologies will become standard, enabling real-time asset management and predictive maintenance.
- Environmental compliance requirements will shape product innovation, prompting companies to develop safer, low-emission solutions.
- Rising investments in renewable energy and alternative fuels will expand the market for specialized storage tanks.
- Water and wastewater management initiatives will create new opportunities for tank suppliers, especially in urbanizing regions.
- Market competition will intensify as both global and regional players focus on product differentiation and service quality.
- Companies will pursue strategic alliances and acquisitions to strengthen their technological capabilities and global footprint.
- Shifts in global supply chains and fluctuating raw material prices will influence procurement and manufacturing strategies.
- The storage tank market will reward firms that align offerings with sustainability trends, regulatory standards, and the evolving needs of industrial and municipal clients.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Environmental Regulations and Safety Standards
Governments and regulatory bodies are enforcing stricter environmental and safety regulations, compelling companies to upgrade or replace existing storage infrastructure with advanced, compliant solutions. This drives demand for tanks with improved leak detection, emission control, and safety features.
Rising Investments in Oil, Gas, and Chemical Infrastructure
Global expansion of oil, gas, and chemical projects requires robust and reliable storage solutions for raw materials and finished products. Large-scale energy and petrochemical developments are fueling the need for modern storage tanks across multiple regions.
Rapid Adoption of Automation and Remote Monitoring
The integration of IoT-enabled sensors, remote monitoring, and predictive analytics is enhancing asset management and operational efficiency. Companies are investing in digital solutions to optimize inventory, maintenance, and regulatory compliance, accelerating market growth.
Growth in Water and Wastewater Management Initiatives
Urbanization and industrialization are increasing the need for advanced water storage and wastewater treatment facilities. Public and private investments in water infrastructure are expanding the application scope for storage tanks, especially in emerging economies.
Advancements in Tank Materials and Design
Technological progress in corrosion-resistant alloys, composites, and smart tank designs is extending tank lifespans and reducing maintenance costs. These innovations support compliance with evolving standards and help companies minimize operational risks.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the storage tank market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the storage tank market projected to grow between 2024 and 2032?
Which storage tank market segment held the largest share in 2024?
What are the primary factors fueling the growth of the storage tank market?
Who are the leading companies in the storage tank market?
Which region commanded the largest share of the storage tank market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Aboveground Tanks
- 1.2.2 Underground Tanks
- 1.3 By Product
- 1.3.1 Fixed Roof Tanks
- 1.3.2 Floating Roof Tanks
- 1.3.3 Spherical Tanks
- 1.3.4 Others
- 1.4 By Material
- 1.4.1 Steel
- 1.4.2 Concrete
- 1.4.3 Fiberglass-Reinforced Plastic (FRP)
- 1.4.4 Others
- 1.5 By Application
- 1.5.1 Oil & Gas
- 1.5.2 Chemical
- 1.5.3 Water & Wastewater
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 24,635 million → 2032: USD 41,387.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Storage Tank Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Storage Tank Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Storage Tank Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Storage Tank Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Storage Tank Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Storage Tank Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Storage Tank Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Storage Tank Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 24,635 million → 2032: USD 41,387.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Storage Tank Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Aboveground Tanks
- 12.3.7.2 Underground Tanks
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fixed Roof Tanks
- 12.4.7.2 Floating Roof Tanks
- 12.4.7.3 Spherical Tanks
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Steel
- 12.5.7.2 Concrete
- 12.5.7.3 Fiberglass-Reinforced Plastic (FRP)
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Oil & Gas
- 12.6.7.2 Chemical
- 12.6.7.3 Water & Wastewater
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Storage Tank End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Storage Tank Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Storage Tank Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Storage Tank Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 TOYO KANETSU K.K
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 CST Industries, Inc.
- 18.4 McDermott
- 18.5 Ishii Iron Works Co., Ltd
- 18.6 Superior Tank Co. Inc.
- 18.7 Pfaudler MEKRO Sp. Z O.O
- 18.8 PERMIANLIDE
- 18.9 F Warren Group Inc.
- 18.10 Highland Tank & Manufacturing Co. Inc.
- 18.11 Fox Tank Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

