
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Spherical Tank Market Size 2024 | USD 3855 Million |
| Spherical Tank Market, CAGR | 3.9% |
| Spherical Tank Market Size 2032 | USD 5235.38 Million |
Market Overview:
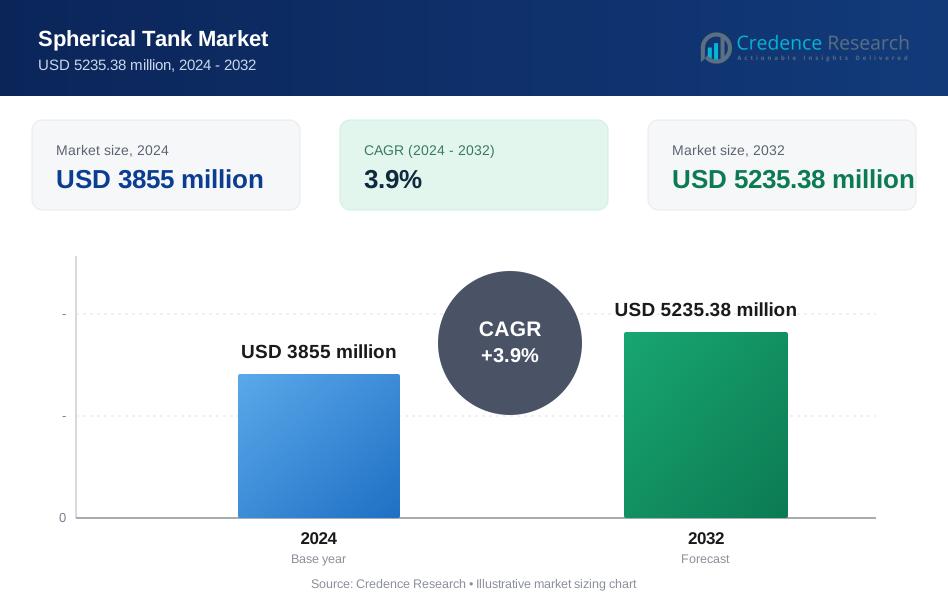
The Spherical Tank Market is projected to grow from USD 3855 million in 2024 to an estimated USD 5235.38 million by 2032, with a compound annual growth rate (CAGR) of 3.9% from 2024 to 2032.
Several factors are propelling the growth of the spherical tank market. One of the primary drivers is the escalating demand for energy storage solutions in the oil and gas industry, driven by increasing global energy consumption. Spherical tanks are preferred in the oil & gas sector due to their ability to store large volumes of gases and liquids under high pressure while occupying minimal space. Additionally, the growth of the petrochemical and chemical industries is another significant driver, where spherical tanks are used to store raw materials and finished products. Moreover, advancements in material technologies and the development of more corrosion-resistant materials have enhanced the durability and safety of spherical tanks, encouraging their adoption. Government regulations mandating safe storage solutions for hazardous chemicals further support market growth.
The spherical tank market is geographically diverse, with North America, Europe, and Asia-Pacific being key regions driving growth. North America holds a substantial market share, primarily due to the established oil & gas industry and stringent safety regulations. The U.S. leads in terms of demand for spherical tanks, supported by increased oil exploration and chemical production activities. In Europe, the market is driven by the presence of major chemical and petrochemical manufacturers, as well as initiatives aimed at improving industrial safety standards. The Asia-Pacific region is expected to witness the fastest growth during the forecast period, fueled by rapid industrialization, particularly in China and India, where the demand for energy storage and petrochemical products is on the rise. This region’s expanding manufacturing base and the need for improved storage solutions are key factors contributing to market expansion.
Market Drivers:
Rising Demand in the Oil and Gas Industry:
One of the most significant drivers of the spherical tank market is the growing demand in the oil and gas industry. As global energy consumption continues to increase, the need for large-scale, efficient storage systems for liquefied natural gas (LNG), crude oil, and other gases under high pressure has become essential. Spherical tanks, known for their strength and ability to withstand high internal pressure, are favored in this industry. These tanks provide optimal storage capacity while minimizing the space required, making them an ideal choice for both onshore and offshore storage applications. For instance, Spherical tanks can be built with capacities ranging from 1,000 barrels to 75,000 barrels, demonstrating their versatility in meeting various storage needs. The ongoing expansion of oil and gas exploration activities, particularly in emerging markets, is expected to further stimulate demand for spherical tanks.
Advancements in Storage Technology:
Technological advancements in storage systems have been instrumental in driving the spherical tank market. The development of materials with enhanced durability, corrosion resistance, and high-temperature tolerance has significantly improved the lifespan and safety of spherical tanks. For instance, Steel spherical tanks demonstrate remarkable durability suitable for demanding industrial applications, with some tanks engineered to operate for 30-50 years with minimum maintenance required. Innovations in welding techniques and construction methodologies have also enabled the construction of larger tanks with greater storage capacities. These advancements have made spherical tanks more cost-effective over their lifecycle, reducing the frequency of maintenance and replacement. As industries continue to seek more efficient and long-lasting storage solutions, the adoption of spherical tanks is expected to rise, particularly in sectors such as chemicals, petrochemicals, and industrial gases.
Stringent Regulatory Standards:
Stringent safety and environmental regulations are another key factor driving the growth of the spherical tank market. Governments across the world are imposing regulations that require industries to adopt safer storage solutions for hazardous chemicals, fuels, and gases. Spherical tanks, with their superior ability to safely store pressurized and hazardous materials, align well with these regulatory requirements. For instance, industries in North America and Europe are required to comply with strict safety standards set by agencies like the Environmental Protection Agency (EPA) and the Occupational Safety and Health Administration (OSHA). As these regulations become more stringent, industries are increasingly investing in spherical tanks to ensure compliance and to minimize risks related to leaks, explosions, and environmental contamination.
Growth of the Petrochemical and Chemical Sectors:
The growth of the petrochemical and chemical industries is another important driver for the spherical tank market. These sectors rely heavily on efficient storage solutions for raw materials, intermediate products, and finished goods, many of which are hazardous or need to be stored under specific pressure conditions. Spherical tanks are widely used in these industries due to their ability to safely store volatile substances like ethylene, ammonia, and hydrogen. For instance, Royal Vopak expanded its operations by setting up a new industrial terminal in the U.S. Gulf Coast with a capacity of 144,000 cubic meters to store chemicals and petroleum products. As the demand for chemicals and petrochemical products increases globally, especially in rapidly industrializing regions such as Asia-Pacific, the need for advanced storage systems like spherical tanks is expected to rise. This demand is further amplified by the expansion of production capacities in these industries, which necessitates large-scale storage facilities.
Market Trends:
Increasing Adoption of Cryogenic Storage Solutions:
One of the prominent trends in the spherical tank market is the growing adoption of cryogenic storage solutions. With the increasing demand for liquefied natural gas (LNG) and other cryogenic gases such as oxygen, nitrogen, and hydrogen, industries are focusing on specialized storage systems that can maintain extremely low temperatures. Spherical tanks are ideal for cryogenic applications because their shape minimizes the surface area exposed to external heat, improving insulation efficiency. As global energy markets shift toward cleaner fuel alternatives, particularly in regions like Asia-Pacific and Europe, the demand for cryogenic spherical tanks is expected to increase, supporting the global transition to natural gas and hydrogen-based energy.
Shift Towards Sustainable and Green Technologies:
Sustainability and environmental concerns are influencing the design and development of spherical tanks. Manufacturers are increasingly focusing on using eco-friendly materials and energy-efficient production processes to align with global efforts to reduce the carbon footprint of industrial activities. This trend is particularly relevant in regions with strict environmental regulations, such as Europe and North America. Additionally, spherical tanks are being integrated with smart technologies and sensors to improve efficiency, reduce waste, and optimize performance. For instance, Infinite Composites Technologies (ICT) announced its development of a spherical, linerless, all-composite cryotank in April 2020, which offers potential for a lighter, more fuel-efficient option to store fuel. This shift towards greener technologies not only enhances the operational efficiency of spherical tanks but also helps industries meet environmental compliance, contributing to long-term market growth.
Expanding Use of Spherical Tanks in Emerging Markets:
Another notable trend in the spherical tank market is the expanding use of these tanks in emerging markets. Countries in Asia-Pacific, Latin America, and the Middle East are witnessing rapid industrialization, leading to an increased demand for storage solutions in industries such as oil & gas, chemicals, and industrial gases. In particular, China and India have become major hubs for petrochemical and chemical manufacturing, which has significantly driven the demand for spherical tanks. The growing focus on infrastructure development in these regions, including investments in energy storage and transportation facilities, is further accelerating the adoption of spherical tanks. As a result, these emerging markets are becoming key drivers of growth for the global spherical tank industry.
Technological Innovations in Tank Design and Construction:
Technological innovations in the design and construction of spherical tanks are transforming the market. New materials such as advanced alloys and composite materials are being developed to enhance the strength, corrosion resistance, and durability of spherical tanks. These innovations allow for larger tanks with higher storage capacities, which are critical for industries handling significant volumes of gases and liquids. Additionally, advancements in automation and robotics are improving the efficiency and precision of tank construction, reducing production time and costs. This trend of incorporating new technologies is expected to further enhance the performance of spherical tanks, making them more competitive in a variety of industrial applications.
Market Restraints and Challenges:
High Initial Capital Investment:
One of the primary restraints in the spherical tank market is the high initial capital investment required for their construction and installation. Spherical tanks are complex structures that demand precise engineering, specialized materials, and advanced construction techniques. The cost of materials such as high-grade steel and alloys, coupled with labor-intensive fabrication and installation processes, significantly increases the upfront expenses. This financial barrier can be challenging for small and mid-sized companies, particularly in industries with tight budgets, limiting their ability to invest in spherical tank solutions. Consequently, some businesses opt for alternative storage systems, such as cylindrical tanks, which are less expensive but offer lower storage efficiency.
Maintenance and Safety Concerns:
Although spherical tanks are designed to handle high pressures and hazardous materials, they require regular maintenance to ensure safety and operational efficiency. The complexity of maintaining spherical tanks, particularly in cryogenic or high-pressure environments, can be a challenge for operators. Any lapse in maintenance could lead to safety risks such as leaks, contamination, or even explosions, especially when handling volatile substances. Moreover, the costs associated with routine inspections, repairs, and downtime can be significant, further discouraging some companies from adopting spherical tanks, particularly in cost-sensitive industries.
Limited Skilled Labor and Expertise:
The construction and maintenance of spherical tanks require specialized skills and expertise, which can be scarce in certain regions. Building spherical tanks demands highly trained engineers and technicians with experience in precision welding, material science, and structural integrity assessments. In emerging markets or regions with limited industrial development, finding such expertise can be challenging. This shortage of skilled labor not only increases project timelines and costs but also creates operational risks, as improper handling of spherical tanks could lead to safety hazards and inefficiencies.
Market Segmentation Analysis:
By Material, the market includes steel spherical tanks, which dominate due to their strength and ability to handle high-pressure applications in industries like oil & gas. Stainless steel spherical tanks are also widely used, especially in the chemical and petrochemical sectors, because of their corrosion resistance. Fiberglass reinforced plastic (FRP) spherical tanks offer advantages in terms of lightweight and corrosion resistance, making them suitable for applications where weight is a concern. Other materials, such as concrete and aluminum, are used in specific niche applications, particularly where durability and cost considerations come into play.
By Capacity, spherical tanks are segmented into various sizes. The 100 m³ to 500 m³ tanks are common for mid-scale industrial applications. Smaller tanks, less than 100 m³, are preferred in industries with limited space or lower storage needs. Larger tanks, 501 m³ to 1,000 m³ and above 1,000 m³, are predominantly used in large-scale oil & gas and petrochemical facilities where substantial storage capacity is required.
By End-use Industry, the oil & gas sector is the leading segment due to its demand for efficient storage solutions for liquefied gases and petroleum products. The chemical & petrochemical industry also heavily relies on spherical tanks for storing volatile substances. Other significant industries include water & wastewater treatment, power generation, and others, such as food & beverage and pharmaceutical, which use spherical tanks for specialized storage applications.
Segmentation:
By Material
- Steel Spherical Tanks
- Stainless Steel Spherical Tanks
- Fiberglass Reinforced Plastic (FRP) Spherical Tanks
- Other Materials (Concrete, Aluminum, etc.)
By Capacity
- 100 m³ to 500 m³
- Less than 100 m³
- 501 m³ to 1,000 m³
- Above 1,000 m³
By End-use Industry
- Oil & Gas
- Chemical & Petrochemical
- Water & Wastewater Treatment
- Power Generation
- Others (Food & Beverage, Pharmaceutical, etc.)
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America
North America holds a significant share of the global spherical tank market, accounting for around 30% of the total market. The region's strong presence in the oil & gas industry, coupled with stringent safety and environmental regulations, drives the demand for spherical tanks. The United States, in particular, leads the region due to its extensive network of oil refineries, petrochemical plants, and natural gas storage facilities. Additionally, the country’s investments in upgrading its aging infrastructure and the continued exploration of shale gas reserves have further fueled the demand for spherical storage solutions. Canada also contributes to market growth, especially in LNG storage, as the country focuses on expanding its export capacity for natural gas.
Europe
Europe accounts for approximately 25% of the spherical tank market, driven by the region’s well-established chemical and petrochemical industries. Countries such as Germany, France, and the Netherlands have a high demand for spherical tanks, particularly in the storage of chemicals and hazardous gases. The region’s stringent regulatory framework, which emphasizes safety and environmental protection, is a major factor contributing to the adoption of spherical tanks. Moreover, Europe’s focus on transitioning to cleaner energy sources, including the use of LNG as a fuel alternative, has led to an increased demand for spherical cryogenic tanks. The growth of renewable energy and hydrogen-based technologies in the region is expected to further bolster market growth in the coming years.
Asia-Pacific
The Asia-Pacific region holds the largest share of the spherical tank market, with nearly 35% of the global market. The region's rapid industrialization, particularly in countries such as China, India, and South Korea, has driven the demand for storage solutions in industries such as oil & gas, chemicals, and power generation. China and India, in particular, are major consumers of spherical tanks due to their expanding energy and petrochemical sectors. The region’s growing LNG infrastructure and increasing investments in industrial gases have also contributed to the demand for spherical tanks. Additionally, the region's focus on infrastructure development and energy security is expected to further drive market growth, making Asia-Pacific a key region for future expansion.
Middle East & Africa
The Middle East & Africa region accounts for around 10% of the spherical tank market. The region’s dominance in oil production and refining, particularly in countries like Saudi Arabia, the UAE, and Kuwait, drives the demand for spherical tanks. These tanks are widely used for storing crude oil, LNG, and other petrochemical products. As the region continues to invest in expanding its energy production and refining capacities, the demand for spherical storage solutions is expected to rise. Moreover, the development of new LNG export terminals and the growing chemical industry in Africa are contributing to the regional market growth.
Latin America
Latin America represents approximately 5% of the global spherical tank market, with Brazil and Mexico being the leading contributors. The region’s oil & gas sector, coupled with the growing chemical industry, drives the demand for spherical tanks. Additionally, investments in LNG infrastructure and power generation projects in the region are expected to support future market growth.
Key Player Analysis:
- Air Products and Chemicals
- BASF
- Chart Industries
- Cryogenics
- EagleBurgmann
- Groupe Charles André
- JFE Engineering Corporation
- Linde Engineering
- McDermott International
- Messer Group
- SABIC
- Saipem
- Technip Energies
- Toyo Engineering Corporation
- Worley
Competitive Analysis:
The spherical tank market is highly competitive, with several prominent players vying for market share. Key companies in the market include Linde Engineering, CB&I Storage Solutions (now part of McDermott International), and Toyo Engineering, which lead the industry with their strong expertise in large-scale storage solutions and engineering capabilities. These companies focus on technological innovations, expanding their portfolio to meet the increasing demand for high-pressure and cryogenic storage solutions across industries like oil & gas, petrochemicals, and industrial gases. Smaller regional players and specialized manufacturers also compete by offering customized solutions, particularly in emerging markets where local expertise and cost-efficiency are valued. The competition is further intensified by the need for advanced materials and safety features, as well as the growing emphasis on sustainability and regulatory compliance. Companies that invest in R&D and strategic partnerships are well-positioned to maintain a competitive edge in this dynamic market.
Recent Developments:
- In March 2024, CIMC Enric Holdings Limited and its subsidiaries began construction on China's first domestic commercial liquid hydrogen spherical tank in Fuyang, Anhui. The tank, designed and developed by Zhangjiagang CIMC Sanctum Cryogenic Equipment Co., Ltd., a subsidiary of CIMC Enric, marks a significant step forward in liquid hydrogen storage and transportation technology. This project is expected to play a crucial role in the rapid development of China's hydrogen energy sector.
- In June 2022, Mitsubishi Shipbuilding, a division of Mitsubishi Heavy Industries (MHI), unveiled a new spherical cargo tank system for liquefied CO2 (LCO2) carriers. This design, based on technologies used in liquefied natural gas (LNG) carriers, received Approval in Principle (AIP) from Bureau Veritas (BV), a French classification society, during the Posidonia event that year.
Market Concentration & Characteristics:
The spherical tank market is moderately concentrated, with a few dominant players holding significant market shares, while several smaller regional manufacturers cater to niche applications. Major companies such as Linde Engineering, McDermott International (CB&I Storage Solutions), and Toyo Engineering lead the market, benefiting from their extensive expertise, technological innovations, and global reach. These companies focus on large-scale industrial applications, particularly in the oil & gas, chemical, and energy sectors. Market characteristics include a high demand for customized solutions based on capacity, material type, and industry-specific needs. The market also exhibits strong growth potential due to the rising demand for energy storage solutions, cryogenic applications, and stringent safety regulations. Additionally, the shift towards cleaner energy and sustainable technologies is driving innovation, particularly in hydrogen and liquefied natural gas (LNG) storage, further shaping the competitive landscape of the spherical tank market.
Report Coverage:
The research report offers an in-depth analysis based on By Material, By Capacity and By End-use Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing demand for LNG and hydrogen storage is expected to drive significant growth in spherical tank applications.
- Advancements in cryogenic technology will expand the market for spherical tanks in energy and industrial gas sectors.
- Stringent environmental regulations will push industries to adopt safer and more efficient storage solutions, boosting spherical tank adoption.
- Growing investments in clean energy infrastructure will create new opportunities for spherical tanks in renewable energy sectors.
- Asia-Pacific, especially China and India, will see rapid market expansion due to industrialization and energy demand.
- Technological innovations in material sciences will enhance the durability and cost-efficiency of spherical tanks.
- Rising oil & gas exploration activities, particularly in emerging markets, will fuel demand for high-capacity spherical tanks.
- Increasing focus on sustainable and green technologies will drive the development of eco-friendly storage solutions.
- Strategic partnerships and mergers among key players will consolidate market leadership and drive innovation.
- Emerging markets in Latin America and Africa will present new growth opportunities as industries expand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the spherical tank market?
What drives the growth of the spherical tank market?
Which region is expected to grow the fastest in the spherical tank market?
What are the key challenges faced by the spherical tank market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Spherical Tank Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Spherical Tank Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3855 million → 2032: USD 5235.38 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Spherical Tank Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Spherical Tank Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Spherical Tank Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Spherical Tank Market Drivers
- 3.3 Spherical Tank Market Restraints & Challenges
- 3.4 Spherical Tank Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Spherical Tank Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Spherical Tank Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Spherical Tank category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Spherical Tank Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Spherical Tank Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Spherical Tank market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Spherical Tank Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Spherical Tank Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Spherical Tank Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Spherical Tank (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Spherical Tank Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Spherical Tank Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Spherical Tank Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Spherical Tank Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Spherical Tank Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Spherical Tank Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Spherical Tank Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Spherical Tank Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Spherical Tank Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
