
Market Overview:
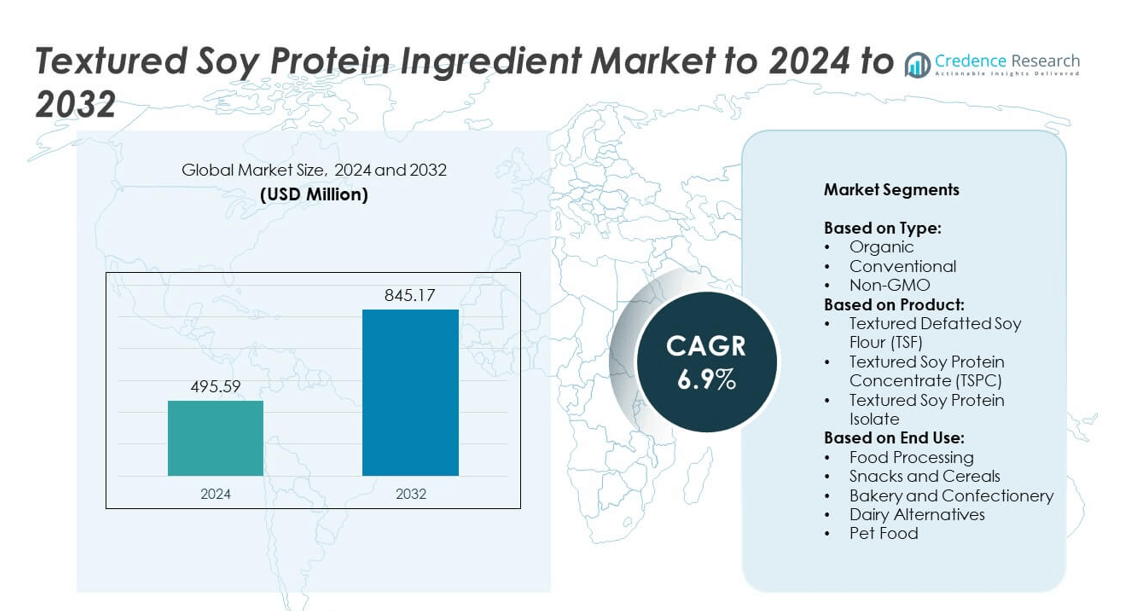
Textured Soy Protein Ingredient Market size was valued USD 495.59 Million in 2024 and is anticipated to reach USD 845.17 Million by 2032, at a CAGR of 6.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Textured Soy Protein Ingredient Market Size 2024 | USD 495.59 Million |
| Textured Soy Protein Ingredient Market, CAGR | 6.9% |
| Textured Soy Protein Ingredient Market Size 2032 | USD 845.17 Million |
The textured soy protein ingredient market is driven by major players including Cargill, ADM, Fuji Oil Holdings Inc., BRF Global, Devansoy, Wilmar International Ltd, AG Processing Inc., International Flavors & Fragrances Inc (IFF), Crown Protein Soya Group Company, and CHS Inc. These companies focus on expanding production capacities, developing non-GMO and organic offerings, and strengthening partnerships with food manufacturers to meet growing demand for plant-based proteins. Regional dynamics highlight North America as the leading market, accounting for over 35% share in 2024, supported by strong adoption of meat alternatives and health-oriented food products. Europe followed with around 28% share, driven by high preference for clean-label and non-GMO products, while Asia Pacific captured nearly 25%, fueled by rising protein consumption and expanding food processing industries.
Market Insights
- The textured soy protein ingredient market was valued at USD 495.59 million in 2024 and is projected to reach USD 845.17 million by 2032, growing at a CAGR of 6.9%.
- Rising demand for plant-based proteins and cost-effective alternatives to meat products are key drivers supporting market expansion across food processing, dairy alternatives, and snack industries.
- Non-GMO and organic product trends are gaining traction, while textured soy protein concentrates lead the product segment with over 45% share in 2024.
- Competition remains strong among global players, with companies focusing on product innovation, sustainability practices, and partnerships to expand distribution and maintain market share.
- North America led the market with over 35% share in 2024, followed by Europe at 28% and Asia Pacific at 25%, while Latin America and the Middle East & Africa contributed smaller shares but show steady growth potential.
Market Segmentation Analysis:
By Type
The type segment of the textured soy protein ingredient market is classified into organic, conventional, and non-GMO. Conventional soy protein dominated the market in 2024, holding over 55% share due to its cost-effectiveness, wide availability, and suitability for large-scale food processing. Rising demand from manufacturers for affordable protein alternatives in processed foods and beverages drives this dominance. Non-GMO products are gaining traction with clean-label preferences, while organic soy protein continues to grow steadily as consumers increasingly prioritize natural and sustainable diets. However, conventional soy remains the leading segment in global adoption.
- For instance, in 2022, Cargill announced plans for a new soybean processing facility in Pemiscot County, Missouri, with an annual production capacity of 62 million bushels. The project was later put on hold in 2023 due to shifting market dynamics.
By Product
In the product segment, textured defatted soy flour (TSF), textured soy protein concentrate (TSPC), and textured soy protein isolate are included. Textured soy protein concentrate (TSPC) led the market with over 45% share in 2024, supported by its high protein content, functionality, and suitability for meat analogs and processed foods. The product is widely used by plant-based food manufacturers to deliver desirable texture and taste. While isolates are gaining traction for premium products, concentrates remain preferred for their cost-performance balance, fueling growth across mainstream food applications.
- For instance, ADM’s soy protein concentrates list ≥65% protein (moisture-free) in specs.
By End Use
The end-use segment covers food processing, snacks and cereals, bakery and confectionery, dairy alternatives, and pet food. Food processing held the dominant position with more than 40% share in 2024, driven by extensive use of soy protein in meat substitutes, ready-to-eat meals, and plant-based protein blends. The demand is fueled by rising health awareness, protein-rich diets, and the growing flexitarian consumer base. Dairy alternatives and snacks are also growing quickly, supported by innovation in plant-based beverages and healthy snacking trends. However, food processing remains the key growth engine for the market.
Market Overview
Rising Demand for Plant-Based Protein
The growing adoption of plant-based diets is a key growth driver for the textured soy protein ingredient market. Consumers are shifting toward meat alternatives and vegan options due to health, sustainability, and ethical concerns. Textured soy protein provides high protein content, favorable texture, and cost advantages, making it a preferred choice for meat substitutes and processed food manufacturers. Rising flexitarian and vegan populations worldwide continue to fuel this demand, supporting steady market expansion across food processing, snacks, and dairy alternative applications.
- For instance, MorningStar Farms Chik’n Nuggets provide 12 g protein per 86 g serving.
Cost-Effectiveness and Functional Versatility
Affordability and functional benefits act as a major growth driver in this market. Textured soy protein offers an economical alternative to animal proteins while maintaining desirable texture, binding, and water-holding properties in various food applications. Its versatility makes it suitable for processed meats, bakery, and dairy alternatives, boosting its adoption by manufacturers. With rising food production costs and consumer demand for affordable nutrition, textured soy protein remains an attractive solution, strengthening its role across mainstream and premium food categories.
- For instance, Impossible Foods supplies >45,000 restaurants and locations worldwide.
Expansion in Health and Wellness Products
The rising popularity of high-protein and health-oriented foods is another key growth driver. Increasing awareness of balanced diets and protein intake encourages consumers to choose functional products enriched with soy protein. The inclusion of textured soy protein in ready meals, sports nutrition, and fortified snacks supports its rapid uptake. Demand is further accelerated by the perception of soy protein as a cholesterol-lowering and heart-healthy option. Health-focused innovations by global brands continue to reinforce the role of textured soy protein in nutrition-driven markets.
Key Trends & Opportunities
Growth of Clean Label and Non-GMO Products
Clean-label movement and demand for natural, transparent ingredients create a key trend and opportunity in the textured soy protein market. Non-GMO variants are gaining traction, particularly in North America and Europe, where consumers actively seek verified and sustainable products. Manufacturers are focusing on certifications and sourcing transparency to attract health-conscious buyers. This shift encourages innovation in organic and non-GMO textured soy proteins, presenting strong opportunities for players aiming to differentiate in the competitive plant-based protein landscape.
- For instance, Bunge is building a new soy protein concentrate (SPC) and textured soy protein concentrate (TSPC) facility in Morristown, Indiana, which is expected to process an additional 4.5 million bushels of soybeans per year once operational in mid-2025.
Rising Popularity of Meat Alternatives
The boom in plant-based meat alternatives presents a major opportunity for textured soy protein manufacturers. Textured soy protein delivers the desired texture, chewiness, and protein enrichment essential for replicating meat products. Leading food companies and startups are expanding product lines with soy-based burgers, sausages, and nuggets to capture flexitarian and vegan demand. With ongoing advancements in food technology and rising investments in plant-based foods, textured soy protein remains central to innovations in this segment, offering strong growth potential for global suppliers.
- For instance, Danone’s Silk Nextmilk is Non-GMO Project Verified and sold in 59-oz cartons, but Danone discontinued its Silk Nextmilk product in North America in 2023.
Key Challenges
Competition from Alternative Proteins
The rise of pea protein, wheat protein, and newer sources such as fava beans and chickpeas poses a key challenge for textured soy protein. Consumers increasingly experiment with diverse protein sources due to allergy concerns, sustainability claims, and variety preferences. Alternative proteins also benefit from marketing around hypoallergenic and non-GMO advantages. This competition challenges soy protein’s dominance, forcing producers to innovate and highlight nutritional and functional strengths to maintain market share against the expanding range of plant-based proteins.
Concerns Over Allergies and GMO Use
Soy allergies and GMO concerns present a significant challenge to market expansion. A notable percentage of consumers avoid soy-based foods due to allergy risks, limiting its consumption in certain regions. Additionally, the widespread use of genetically modified soybeans raises consumer hesitance, especially in Europe, where regulatory restrictions on GMO products are strict. These factors create barriers to acceptance, requiring manufacturers to emphasize allergen labeling, promote organic or non-GMO certifications, and invest in consumer education to maintain trust and expand adoption.
Regional Analysis
North America
North America accounted for over 35% of the textured soy protein ingredient market in 2024, making it the largest regional contributor. The region’s dominance is supported by strong demand for plant-based foods, particularly in the United States and Canada, where consumers are adopting vegan and flexitarian diets at a rapid pace. Growing investments by food manufacturers in soy-based meat alternatives and dairy substitutes continue to drive growth. The presence of established players and innovative startups also strengthens the regional outlook, ensuring North America maintains a leading share throughout the forecast period.
Europe
Europe held around 28% share of the textured soy protein ingredient market in 2024, driven by high consumer preference for clean-label and non-GMO food products. The demand is particularly strong in Germany, the UK, and France, where veganism and sustainability-focused diets are expanding rapidly. Stringent food labeling regulations and sustainability commitments encourage the use of organic and non-GMO soy protein in various applications. Expansion of plant-based meat categories across retail channels further boosts growth, with European consumers showing strong acceptance of soy protein ingredients as a key part of healthy and ethical food choices.
Asia Pacific
Asia Pacific captured nearly 25% of the textured soy protein ingredient market in 2024, with China, India, and Japan being major contributors. Rising disposable incomes, increasing urbanization, and a shift toward protein-rich diets drive demand in this region. Soy has traditionally been part of Asian diets, and its growing use in modern food processing strengthens consumption further. Expanding food manufacturing sectors and rising interest in plant-based alternatives fuel market growth. With large-scale soybean production and rising demand for affordable protein, Asia Pacific is positioned as one of the fastest-growing regions in the forecast period.
Latin America
Latin America accounted for about 7% of the textured soy protein ingredient market in 2024, supported by strong soybean production in countries such as Brazil and Argentina. Local availability of raw materials makes soy protein a cost-effective ingredient for food and beverage applications. Increasing adoption of plant-based products and rising health awareness contribute to steady demand. The growth of urban populations and expanding retail networks support higher consumption of soy-based snacks and processed foods. However, limited consumer awareness compared to developed regions keeps growth moderate, though opportunities continue to expand.
Middle East and Africa
The Middle East and Africa region represented close to 5% share of the textured soy protein ingredient market in 2024. Demand is driven by the rising adoption of affordable protein sources and growing popularity of processed food products in urban areas. South Africa, Saudi Arabia, and the UAE are key markets, with increasing penetration of plant-based alternatives among health-conscious consumers. Limited local production of soybeans requires higher imports, slightly impacting affordability. However, rising investments in food processing and increased awareness of plant-based nutrition are expected to gradually strengthen the region’s market presence.
Market Segmentations:
By Type:
- Organic
- Conventional
- Non-GMO
By Product:
- Textured Defatted Soy Flour (TSF)
- Textured Soy Protein Concentrate (TSPC)
- Textured Soy Protein Isolate
By End Use:
- Food Processing
- Snacks and Cereals
- Bakery and Confectionery
- Dairy Alternatives
- Pet Food
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The competitive landscape of the textured soy protein ingredient market is shaped by key players such as Cargill, Incorporated, ADM, Fuji Oil Holdings Inc., BRF Global, Devansoy, Wilmar International Ltd, AG Processing Inc., International Flavors & Fragrances Inc (IFF), Crown Protein Soya Group Company, and CHS Inc. These companies focus on expanding production capacities, developing advanced processing technologies, and strengthening their global distribution networks to meet rising demand from food, beverage, and pet food industries. Strategic initiatives include product innovation, collaborations with food manufacturers, and investments in clean-label, organic, and non-GMO offerings to capture emerging consumer preferences. Sustainability remains a central priority, with companies increasingly emphasizing responsible sourcing and eco-friendly operations. Regional expansion through mergers, acquisitions, and joint ventures further supports competitiveness, enabling them to strengthen market presence and serve a diverse customer base. Overall, competition remains strong, driven by innovation, pricing strategies, and the ability to adapt to evolving consumer needs.
Key Player Analysis
- Cargill, Incorporated
- ADM
- Fuji Oil Holdings Inc.
- BRF Global
- Devansoy
- Wilmar International Ltd
- AG Processing Inc.
- International Flavors & Fragrances Inc (IFF)
- Crown Protein Soya Group Company
- CHS Inc
Recent Developments
- In 2023, ADM established a joint venture with food processing solutions provider Marel to build a Protein Innovation Center.
- In 2023, Cargill introduced TEX PW80 M, a blend of pea and wheat protein in Europe. This innovative product is designed to replicate the texture and juiciness of ground meat, offering food manufacturers a high-performance ingredient for plant-based applications.
- In 2022, IFF launched Supro Tex, a soy-based plant protein designed to mimic the texture of meat.
Report Coverage
The research report offers an in-depth analysis based on Type, Product, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily, supported by growing adoption of plant-based diets.
- Conventional soy protein will remain dominant due to cost efficiency and large-scale availability.
- Non-GMO and organic soy protein will grow faster with rising clean-label demand.
- Food processing will continue as the largest end-use segment across global markets.
- Asia Pacific will emerge as the fastest-growing region driven by urbanization and protein demand.
- Europe will strengthen adoption of organic and non-GMO soy protein ingredients.
- North America will maintain leadership with strong innovation in meat alternatives.
- Competition from alternative proteins like pea and fava beans will intensify.
- Manufacturers will focus on certifications, sustainability, and allergen management to boost trust.
- Rising investments in plant-based innovation will create long-term growth opportunities worldwide.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Plant-Based Diets
The shift towards plant-based diets for health, sustainability, and ethical reasons is driving demand for textured soy protein as a key ingredient in meat alternatives and vegan products, supporting robust market growth.
Cost-Effectiveness and Functional Versatility
Textured soy protein offers an affordable alternative to animal proteins while providing desirable texture, binding, and water-holding properties, making it attractive for manufacturers in processed foods, bakery, and dairy alternatives.
Growth of Clean Label and Non-GMO Trends
Increasing consumer preference for clean-label, non-GMO, and organic products is fueling innovation and adoption of non-GMO and organic textured soy protein, especially in North America and Europe.
Rising Demand in Food Processing and Ready Meals
The extensive use of textured soy protein in food processing, particularly in meat substitutes, ready-to-eat meals, and protein blends, is driven by health awareness and the growing flexitarian consumer base.
Innovation in Health and Wellness Products
The popularity of high-protein, health-oriented foods and the perception of soy protein as a cholesterol-lowering, heart-healthy option are encouraging its inclusion in sports nutrition, fortified snacks, and functional foods.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Textured Soy Protein Ingredient Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Textured Soy Protein Ingredient Market projected to grow between 2025 and 2032?
Which Textured Soy Protein Ingredient Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Textured Soy Protein Ingredient Market?
Growth is fueled by rising demand for plant-based diets, cost-effectiveness, and expansion in health-oriented products.
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Organic
- 1.2.2 Conventional
- 1.2.3 Non-GMO
- 1.3 By End Use
- 1.3.1 Food Processing
- 1.3.2 Snacks and Cereals
- 1.3.3 Bakery and Confectionery
- 1.3.4 Dairy Alternatives
- 1.3.5 Pet Food
- 1.4 By Product
- 1.4.1 Textured Defatted Soy Flour (TSF)
- 1.4.2 Textured Soy Protein Concentrate (TSPC)
- 1.4.3 Textured Soy Protein Isolate
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 495.59 million → 2032: USD 845.17 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Textured Soy Protein Ingredient Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Textured Soy Protein Ingredient Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Textured Soy Protein Ingredient Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Textured Soy Protein Ingredient Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Textured Soy Protein Ingredient Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Textured Soy Protein Ingredient Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Textured Soy Protein Ingredient Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Textured Soy Protein Ingredient Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 495.59 million → 2032: USD 845.17 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Textured Soy Protein Ingredient Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Organic
- 12.3.7.2 Conventional
- 12.3.7.3 Non-GMO
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Food Processing
- 12.4.7.2 Snacks and Cereals
- 12.4.7.3 Bakery and Confectionery
- 12.4.7.4 Dairy Alternatives
- 12.4.7.5 Pet Food
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Textured Defatted Soy Flour (TSF)
- 12.5.7.2 Textured Soy Protein Concentrate (TSPC)
- 12.5.7.3 Textured Soy Protein Isolate
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Textured Soy Protein Ingredient End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Textured Soy Protein Ingredient Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Textured Soy Protein Ingredient Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Textured Soy Protein Ingredient Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cargill, Incorporated
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ADM
- 18.4 Fuji Oil Holdings Inc.
- 18.5 BRF Global
- 18.6 Devansoy
- 18.7 Wilmar International Ltd
- 18.8 AG Processing Inc.
- 18.9 International Flavors & Fragrances Inc (IFF)
- 18.10 Crown Protein Soya Group Company
- 18.11 CHS Inc
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

