
Market Overview
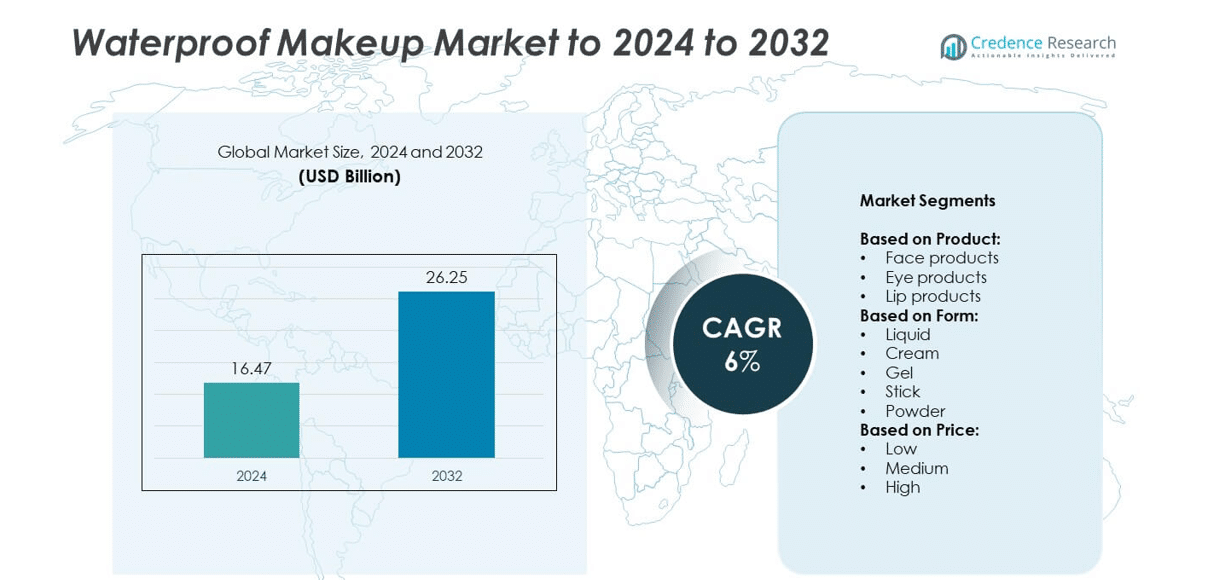
Waterproof Makeup Market size was valued at USD 16.47 Billion in 2024 and is anticipated to reach USD 26.25 Billion by 2032, at a CAGR of 6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Waterproof Makeup Market Size 2024 | USD 16.47 Billion |
| Waterproof Makeup Market, CAGR | 6% |
| Waterproof Makeup Market Size 2032 | USD 26.25 Billion |
The waterproof makeup market is led by major players including Urban Decay, Revlon, Make Up for Ever, Chanel, The Estée Lauder Companies, Huda Beauty, Procter & Gamble, NYX Professional Makeup, Christian Dior, Shiseido, L'Oréal, Tarte, Lancôme, Too Faced Cosmetics, and Anastasia Beverly Hills. These companies compete through innovative long-wear formulations, diverse shade ranges, and clean-label product offerings. Asia-Pacific dominates the market with over 35% share in 2024, driven by strong consumer demand in China, Japan, and South Korea. North America follows with around 30% share, supported by premium product launches and a robust retail network.
Market Insights
- The waterproof makeup market was valued at USD 16.47 Billion in 2024 and is projected to reach USD 26.25 Billion by 2032, growing at a CAGR of 6% between 2025 and 2032.
- Rising demand for long-lasting, smudge-proof cosmetics and increasing e-commerce penetration are key drivers boosting market expansion globally.
- Trends include the shift toward clean-label, vegan, and multifunctional products offering skincare benefits and sun protection, appealing to health-conscious consumers.
- The market is highly competitive, with global players focusing on innovation, influencer marketing, and sustainable packaging to strengthen their presence.
- Asia-Pacific leads with over 35% share, followed by North America with nearly 30%, while eye products hold the largest segment share driven by strong demand for waterproof mascaras and eyeliners.
Market Segmentation Analysis:
By Product
The product segment includes face products, eye products, and lip products. Eye products dominate the market, holding over 40% share in 2024, driven by high demand for waterproof mascaras, eyeliners, and brow products. Consumers prefer smudge-proof solutions that withstand sweat, tears, and humidity, making them ideal for daily and occasion wear. Innovation in long-lasting formulas and precision applicators has further increased adoption. Major cosmetic brands invest in vegan, ophthalmologist-tested eye products to attract health-conscious consumers and expand reach across both mass and premium categories.
- For instance, L'Oréal's Consumer Products Division, which includes brands like L'Oréal Paris and Maybelline, reported sales of €12.75 billion in 2019, contributing to L'Oréal's overall sales of €29.87 billion.
By Form
This segment covers liquid, cream, gel, stick, and powder forms. Liquid products lead the market, capturing the largest share due to their smooth application and long-wear performance. Liquid foundations, liners, and lip colors are widely adopted for their easy blending and full coverage. Growth is supported by rising consumer preference for lightweight, transfer-proof solutions and diverse shade ranges. Brands are launching multifunctional liquid products combining SPF protection, hydration, and waterproof properties, catering to busy lifestyles and climate-resistant makeup demands.
- For instance, Fenty Beauty launched with 40 foundation shades, later expanding to 50 shades
By Price
The price segment is divided into low, medium, and high categories. Medium-priced products dominate, accounting for the highest market share in 2024, supported by their balance of affordability and quality. Consumers increasingly opt for mid-range waterproof makeup, which delivers professional results without premium pricing. Growth is fueled by expanding availability of mid-tier brands in retail stores and online platforms. Social media influencers promote value-for-money products, driving higher sales among millennials and Gen Z consumers seeking performance-oriented yet cost-effective solutions.
Key Growth Drivers
Rising Demand for Long-Lasting Cosmetics
Consumers increasingly prefer makeup that lasts through sweat, tears, and humidity, which drives waterproof product demand. Busy urban lifestyles, outdoor activities, and social events make long-wear makeup a daily necessity. Brands respond with advanced smudge-proof, transfer-proof, and water-resistant formulations. This demand leads to higher sales across mass-market and premium categories. The popularity of sweat-proof mascaras and eyeliners continues to expand, especially in hot and humid regions, further strengthening this growth driver’s impact on the global market.
- For instance, e.l.f. Beauty reported 210 basis points of market share gain in Q1 FY2026 vs. same quarter last year.
Expansion of E-Commerce and Digital Influence
Online retail channels dominate sales growth, allowing consumers to compare products, access reviews, and shop conveniently. Beauty brands rely heavily on influencer marketing, live streaming, and AR-based try-on tools to boost engagement. This digital shift supports direct-to-consumer strategies and broadens reach in emerging markets. Exclusive online product launches and discounts encourage repeat purchases. Strong social media presence creates demand surges, especially among millennials and Gen Z, making e-commerce a major driver for the waterproof makeup industry’s continued expansion.
- For instance, L’Oréal Paris Voluminous Original Waterproof Mascara builds lashes up to 4× natural thickness per its product description.
Innovative Formulations and Shade Diversity
Continuous R&D investment enables brands to develop lightweight, breathable, and dermatologically tested waterproof products. Clean-label, vegan-friendly, and inclusive shade offerings attract a wider consumer base. Advances in pigments and film-forming agents improve product performance while ensuring comfort. Hybrid products combining skincare and sun protection benefits meet consumer demand for multi-functionality. These innovations differentiate brands in a competitive market and encourage premiumization, helping drive consistent growth across various price segments and geographies globally.
Key Trends & Opportunities
Shift Toward Clean and Sustainable Beauty
Demand for eco-friendly, cruelty-free, and toxin-free waterproof makeup products is rising quickly. Brands adopt recyclable packaging and natural ingredients to appeal to conscious consumers. Regulatory changes in major markets, such as Europe, are accelerating this transition. Transparency and ethical sourcing further enhance brand reputation and customer loyalty. This trend creates opportunities for collaboration with green ingredient suppliers and positions sustainability-focused players to gain a competitive advantage in the coming years.
- For instance, Maybelline’s Fit Me foundation line includes 40 shades after adding 16 new shades.
Rising Adoption of Multi-Functional Products
Consumers increasingly favor waterproof products that deliver more than color payoff, such as hydration, SPF, or anti-aging benefits. These multi-tasking solutions simplify routines, making them popular among busy professionals and travelers. Hybrid product launches from major brands gain strong traction, encouraging premium purchases. This trend also supports higher margins for manufacturers and boosts product innovation. The focus on multifunctionality is likely to expand the customer base and drive faster adoption across regions.
- For instance, The Body Shop’s refill program diverted 576 pounds of plastic (≈ 12,749 bottles) from waste in one US initiative.
Key Challenges
High Production and Compliance Costs
Developing effective waterproof formulations requires costly R&D and advanced raw materials, increasing overall production expenses. Compliance with strict regulatory standards, including FDA and EU Cosmetic Regulations, adds further cost pressure. Smaller brands face difficulties matching the innovation pace of global players with larger budgets. These factors can delay product launches and limit price competitiveness, particularly in emerging markets where affordability plays a crucial role in consumer decisions.
Concerns Over Skin Sensitivity and Removal
Consumers worry that waterproof products can clog pores, cause irritation, or be difficult to remove. These concerns reduce adoption among sensitive-skin users and health-conscious buyers. Failure to communicate safety testing and offer gentle removal solutions can restrict sales. Brands must invest in dermatologist-tested claims, non-comedogenic formulations, and effective removers to address these barriers. Educating consumers about proper use and skin compatibility will be critical to overcome this challenge and retain trust.
Regional Analysis
North America
North America holds a market share of around 30% in 2024, supported by strong demand for premium and professional-grade waterproof makeup products. High consumer spending on cosmetics, coupled with a well-established retail network, drives regional growth. Major brands launch innovative formulations, including clean-label and vegan products, to meet evolving consumer preferences. The U.S. dominates this region, with Canada contributing steadily through growing online beauty sales. Social media campaigns and celebrity endorsements further enhance product visibility and adoption. Rising participation in outdoor activities and events continues to push demand for long-lasting, sweat-proof solutions in this market.
Europe
Europe accounts for nearly 27% of the market share, led by strong consumption in countries like Germany, France, and the U.K. The region benefits from high awareness of premium beauty products and strict regulatory standards encouraging safer, dermatologist-tested formulations. Consumers increasingly prefer cruelty-free and eco-friendly waterproof makeup options, fueling innovation among established brands. Growth in e-commerce platforms and specialty beauty retailers supports accessibility and distribution. Demand is also driven by the rising influence of fashion weeks and seasonal trends, with waterproof eye and face products seeing strong adoption during festivals and social gatherings across key markets.
Asia-Pacific
Asia-Pacific leads the global market with over 35% share in 2024, driven by high beauty consciousness and growing urban populations. Countries such as China, Japan, and South Korea are major contributors, supported by strong cultural emphasis on skincare-friendly cosmetics. Regional brands focus on lightweight, humidity-resistant formulations suitable for tropical climates, driving rapid adoption. Expanding middle-class income levels and rising e-commerce penetration boost product sales. Influencer-driven marketing and K-beauty trends accelerate the adoption of waterproof mascaras, liners, and foundations. The region’s large millennial and Gen Z consumer base ensures sustained growth and increasing premium product penetration.
Latin America
Latin America holds around 5% of the market share, with Brazil and Mexico being the largest contributors. Growth is supported by rising consumer spending on beauty and personal care products and an increasing preference for durable, sweat-proof makeup solutions. Regional demand is influenced by warm climates and vibrant social cultures, where long-wear makeup is preferred for outdoor events. Expansion of international cosmetic brands in local retail markets and e-commerce platforms boosts accessibility. Social media influencers play a key role in driving consumer awareness and encouraging adoption of trending waterproof makeup products among younger demographics.
Middle East & Africa
Middle East & Africa account for nearly 3% market share, with growth driven by rising disposable incomes and increasing focus on personal grooming. Countries such as UAE and Saudi Arabia dominate the region, supported by strong demand for luxury and prestige cosmetic brands. Consumers prefer high-performance waterproof makeup to withstand warm and humid weather conditions. Growth in modern retail infrastructure and e-commerce improves product availability. Beauty-conscious younger consumers are adopting waterproof foundations, liners, and lip colors for both daily wear and special occasions, driving steady growth despite relatively lower market penetration compared to other regions.
Market Segmentations:
By Product:
- Face products
- Eye products
- Lip products
By Form:
- Liquid
- Cream
- Gel
- Stick
- Powder
By Price:
- Low
- Medium
- High
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The waterproof makeup market is highly competitive, led by key players such as Urban Decay Cosmetics, Revlon, Make Up for Ever, Chanel, The Estée Lauder Companies, Huda Beauty, Procter & Gamble, NYX Professional Makeup, Christian Dior, Shiseido, L'Oréal, Tarte, Lancôme, Too Faced Cosmetics, and Anastasia Beverly Hills. Competition is driven by innovation in long-wear formulations, shade diversity, and clean-label product development to meet consumer preferences. Companies focus on expanding e-commerce presence, leveraging influencer partnerships, and launching exclusive online collections to engage younger audiences. Product premiumization and hybrid formulations combining skincare benefits with waterproof performance are major strategies used to capture market share. Manufacturers invest in sustainable packaging and vegan certifications to appeal to eco-conscious consumers. Continuous investment in marketing campaigns, celebrity collaborations, and regional expansions supports strong brand positioning. The competitive landscape remains dynamic, with players emphasizing research and development to differentiate products in a crowded marketplace.
Key Player Analysis
- Urban Decay Cosmetics, LLC
- Revlon, Inc.
- Make Up for Ever S.A.
- Chanel S.A.
- The Estée Lauder Companies Inc.
- Huda Beauty Limited
- Procter & Gamble Co.
- NYX Professional Makeup LLC
- Christian Dior SE
- Shiseido Company, Limited
- L'Oréal S.A.
- Tarte, Inc.
- Lancôme
- Too Faced Cosmetics, LLC
- Anastasia Beverly Hills, LLC
Recent Developments
- In 2023, Estée Lauder Companies Inc. continued to leverage the strong reputation of its Double Wear Stay-in-Place Makeup line, known for its long-wearing and waterproof properties, by refining shade ranges and improving comfort levels for its prestige consumers.
- In 2023, Shiseido continued to develop its Synchro Skin line, known for its "ActiveForce™ Technology." Products like the Synchro Skin Self-Refreshing Foundation were refined to adapt to skin conditions, providing waterproof and long-wear capabilities that resist heat, humidity, and oil without feeling heavy.
- In 2023, Revlon launched ColorStay Suede Ink, a collection of matte lipsticks. This launch emphasized high-impact color and a smooth, suede-like finish, leveraging the strength of the long-standing ColorStay franchise.
Report Coverage
The research report offers an in-depth analysis based on Product, Form, Price and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily driven by rising demand for long-lasting and sweat-proof cosmetics.
- Brands will focus on clean-label, vegan, and cruelty-free formulations to attract conscious consumers.
- Online retail and influencer-driven marketing will remain critical sales channels for global expansion.
- Hybrid products with skincare benefits and SPF protection will see increased adoption.
- Shade diversity and inclusivity will stay a priority to cater to diverse consumer bases.
- Premium and mid-range products will dominate as consumers seek quality with value.
- Technological innovation in film-forming agents will enhance wearability and comfort.
- Emerging markets in Asia-Pacific and Latin America will provide strong growth opportunities.
- Strategic collaborations between brands and ingredient suppliers will accelerate sustainable innovation.
- Education on safe removal and skin compatibility will be key to driving wider acceptance.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Long-Lasting, Smudge-Proof Cosmetics
Consumers increasingly seek makeup that withstands sweat, tears, and humidity, making waterproof formulations essential for daily and occasion wear. This trend is especially strong in urban environments and regions with hot or humid climates, driving robust sales of waterproof mascaras, eyeliners, and foundations.
Expansion of E-Commerce and Digital Influence
Online retail channels and influencer-driven marketing have made it easier for consumers to discover, compare, and purchase waterproof makeup. Brands leverage social media, AR try-on tools, and exclusive online launches to engage younger demographics and expand their global reach.
Innovation in Clean-Label and Multi-Functional Products
Brands are investing in R&D to create waterproof makeup that is vegan, cruelty-free, and offers additional benefits such as SPF protection and hydration. These innovations appeal to health-conscious consumers and differentiate products in a crowded market.
Shade Diversity and Inclusivity
The push for broader shade ranges and inclusive product offerings attracts a wider consumer base, particularly in multicultural and emerging markets. This focus on diversity supports brand loyalty and drives adoption across different regions and demographics.
Premiumization and Value-Oriented Mid-Range Offerings
Consumers are willing to pay more for high-quality, long-wear waterproof makeup, but also seek value in mid-range products that deliver professional results without premium pricing. This dual demand supports growth in both premium and accessible segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Waterproof Makeup Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Waterproof Makeup Market projected to grow between 2025 and 2032?
Which Waterproof Makeup Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Waterproof Makeup Market?
Who are the leading companies in the Waterproof Makeup Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Liquid
- 1.2.2 Cream
- 1.2.3 Gel
- 1.2.4 Stick
- 1.2.5 Powder
- 1.3 By Price
- 1.3.1 Low
- 1.3.2 Medium
- 1.3.3 High
- 1.4 By Product
- 1.4.1 Face products
- 1.4.2 Eye products
- 1.4.3 Lip products
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 16.47 Billion → 2032: USD 26.25 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Waterproof Makeup Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Waterproof Makeup Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Waterproof Makeup Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Waterproof Makeup Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Waterproof Makeup Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Waterproof Makeup Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Waterproof Makeup Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Waterproof Makeup Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 16.47 Billion → 2032: USD 26.25 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Waterproof Makeup Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Liquid
- 12.3.7.2 Cream
- 12.3.7.3 Gel
- 12.3.7.4 Stick
- 12.3.7.5 Powder
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Price - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Low
- 12.4.7.2 Medium
- 12.4.7.3 High
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Face products
- 12.5.7.2 Eye products
- 12.5.7.3 Lip products
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Waterproof Makeup Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Waterproof Makeup Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Waterproof Makeup Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 L'Oréal S.A.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 The Estée Lauder Companies Inc.
- 17.4 Shiseido Company, Limited
- 17.5 Revlon, Inc.
- 17.6 Urban Decay Cosmetics, LLC
- 17.7 Huda Beauty Limited
- 17.8 Procter & Gamble Co.
- 17.9 Chanel S.A.
- 17.10 Lancôme
- 17.11 NYX Professional Makeup LLC
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

