
Peak power, not average energy, drives smart cooling buying
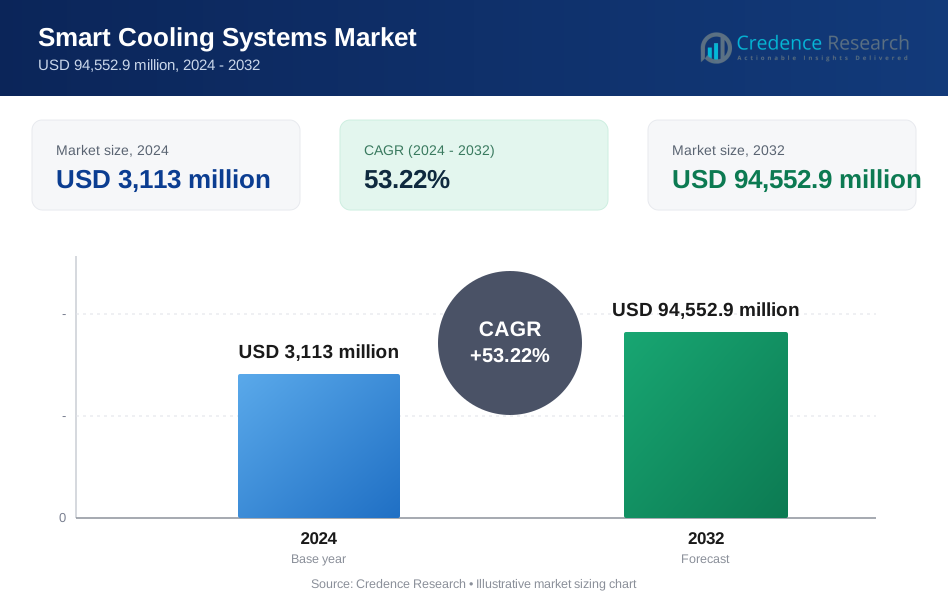
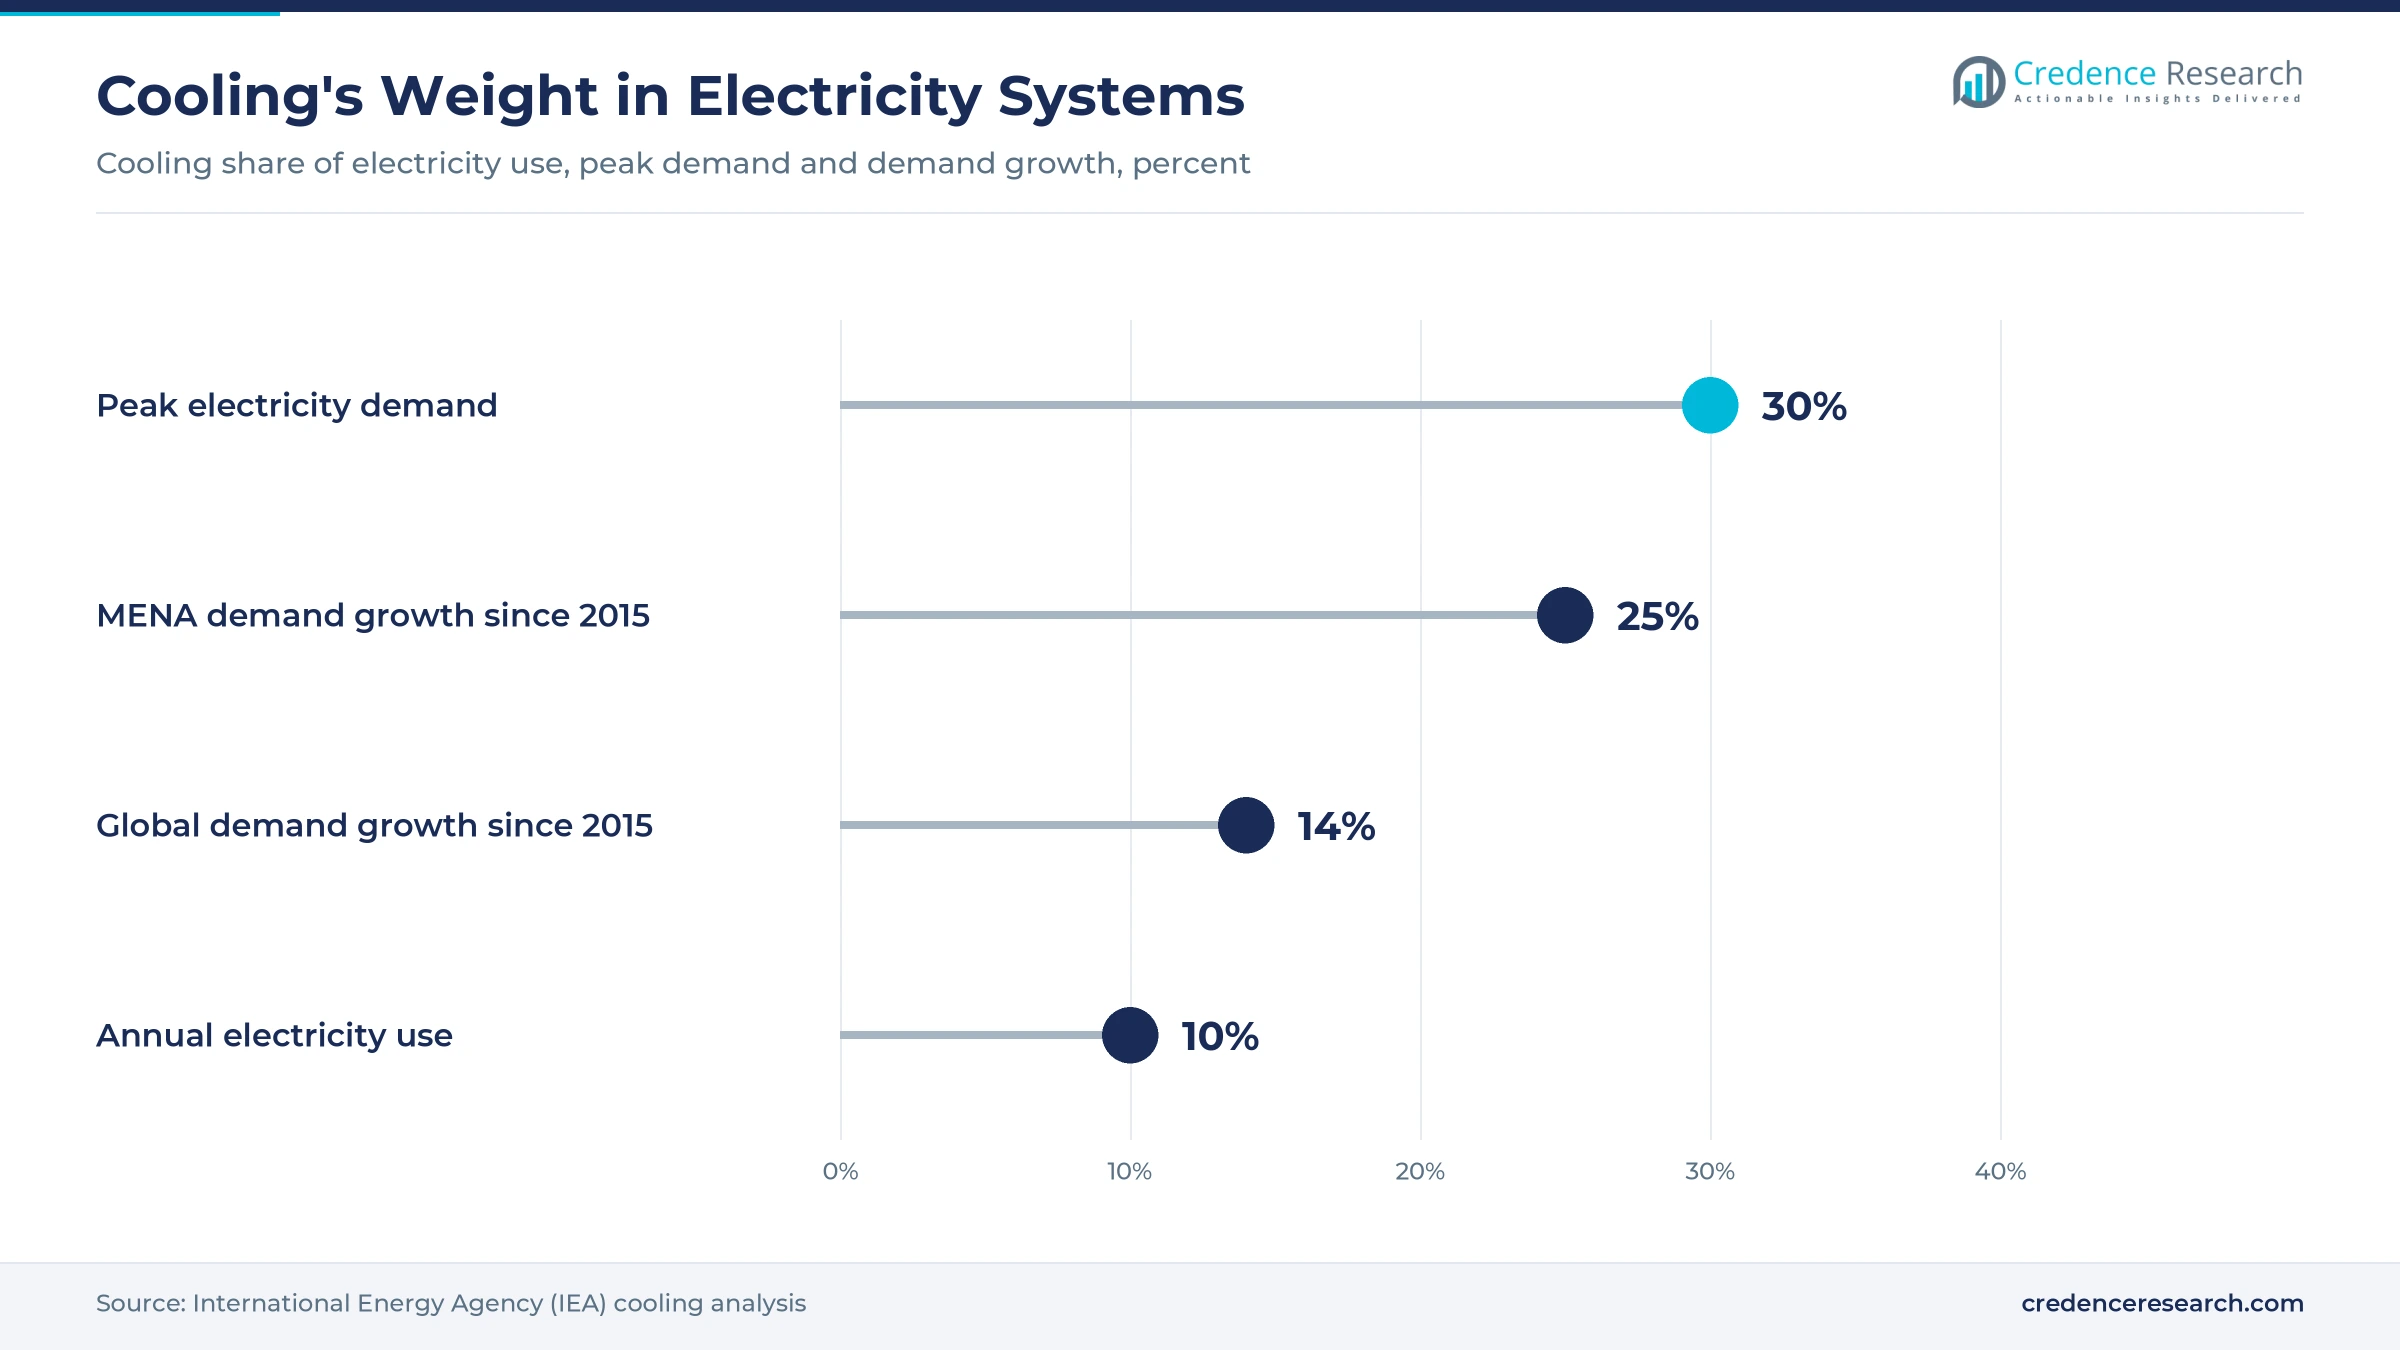
The smart cooling systems market was valued at USD 8.71 billion in 2025 and is projected to increase from USD 9.82 billion in 2026 to USD 28.82 billion by 2035, registering a CAGR of 12.71% during 2025–2035. Demand comes from three sources, starting with peak-load tariffs, which matter because cooling takes about 10% of annual electricity use but around 30% of peak demand on IEA analysis. Heat from AI servers adds a second source by pushing data centers toward liquid cooling with its own control stack, and rules under the recast EU buildings directive form the third. North America held the largest regional share, 35.0% in 2025, supported by connected thermostats and the largest cluster of AI data centers, while the Middle East & Africa is the fastest-growing region at 15.65% a year. The main commercial change is the move from fixed schedules to AI supervisory control, which large HVAC groups now buy rather than build.
What counts as a smart cooling system, and what stays out?
A device qualifies when it measures conditions, communicates over a network and changes how cooling equipment runs. The scope covers networked controllers for chiller plants, air handlers, rooftop units and coolant distribution; connected thermostats, zone controllers and smart air-conditioner controllers; software for AI supervisory control, fault detection and digital twins; and sensors installed for cooling control.
Cooling equipment itself, including chillers, split air conditioners, computer-room units, cooling towers, cold plates and immersion tanks, is excluded, as are the heating share of thermostat value and the lighting, security and access-control functions of automation platforms. Efficient compressors set the ceiling, but controls decide how close a building gets to it.
Smart Cooling Systems Market Insights
- The smart cooling systems market is projected to grow from USD 9.82 billion in 2026 to USD 28.82 billion by 2035, a 12.71% CAGR, as owners pay to shift and trim peak cooling load.
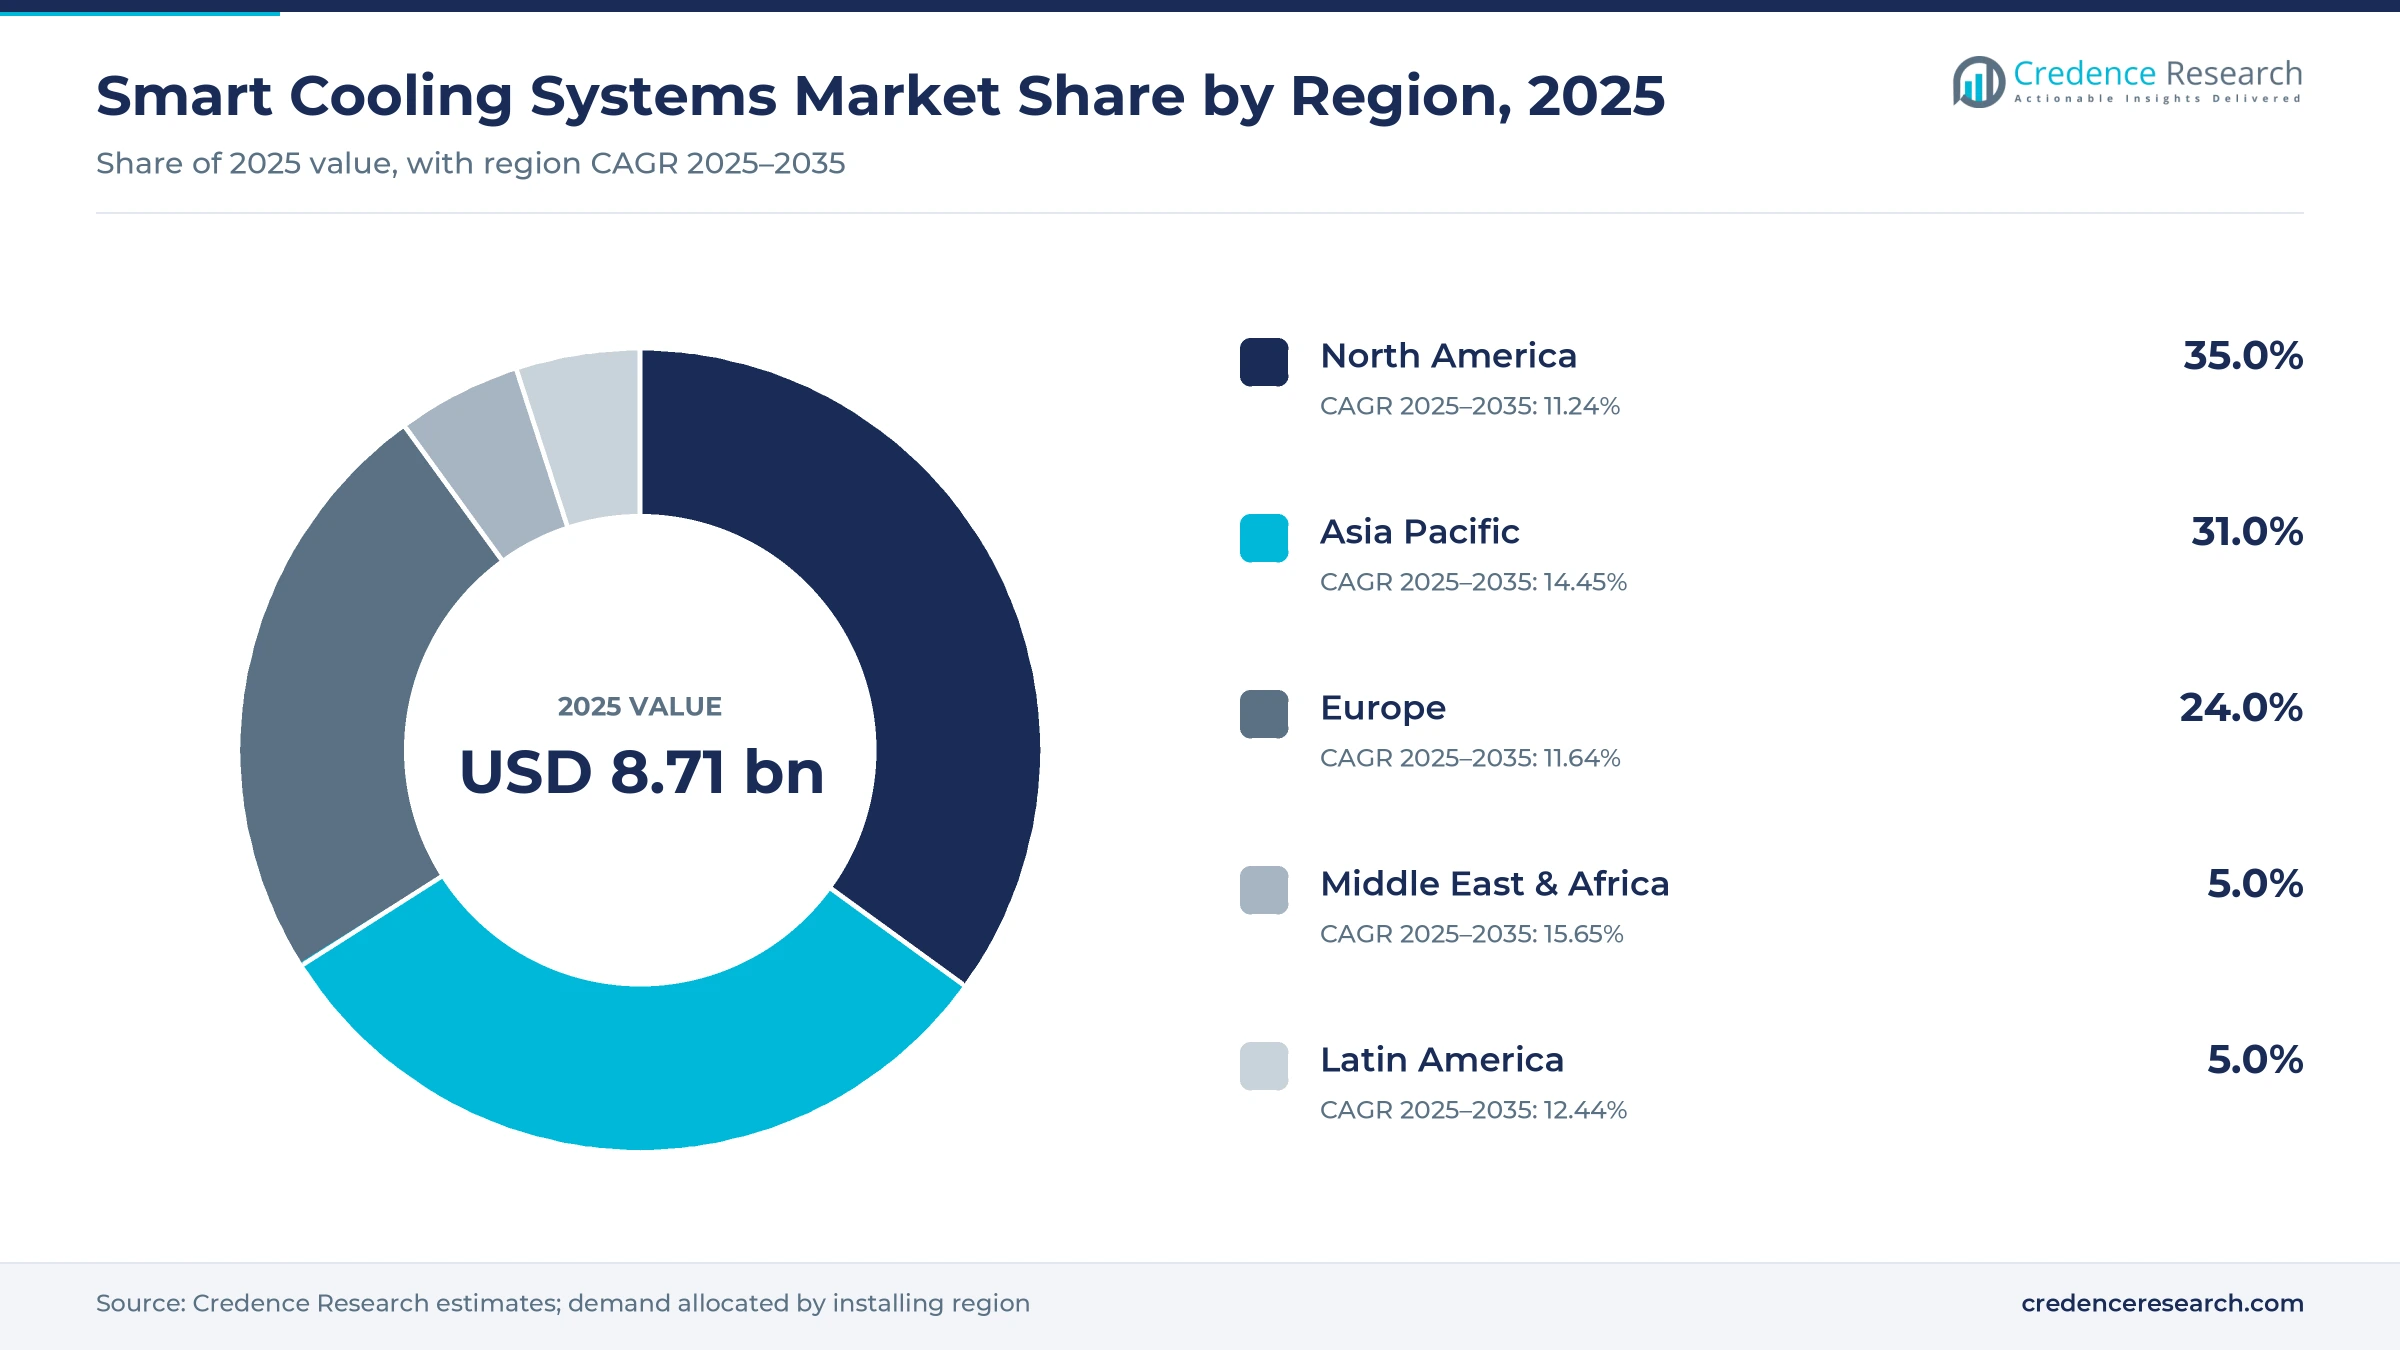
- North America held 35.0% of 2025 value, the largest regional share, on connected thermostats, utility demand-response programs and the largest cluster of AI data centers.
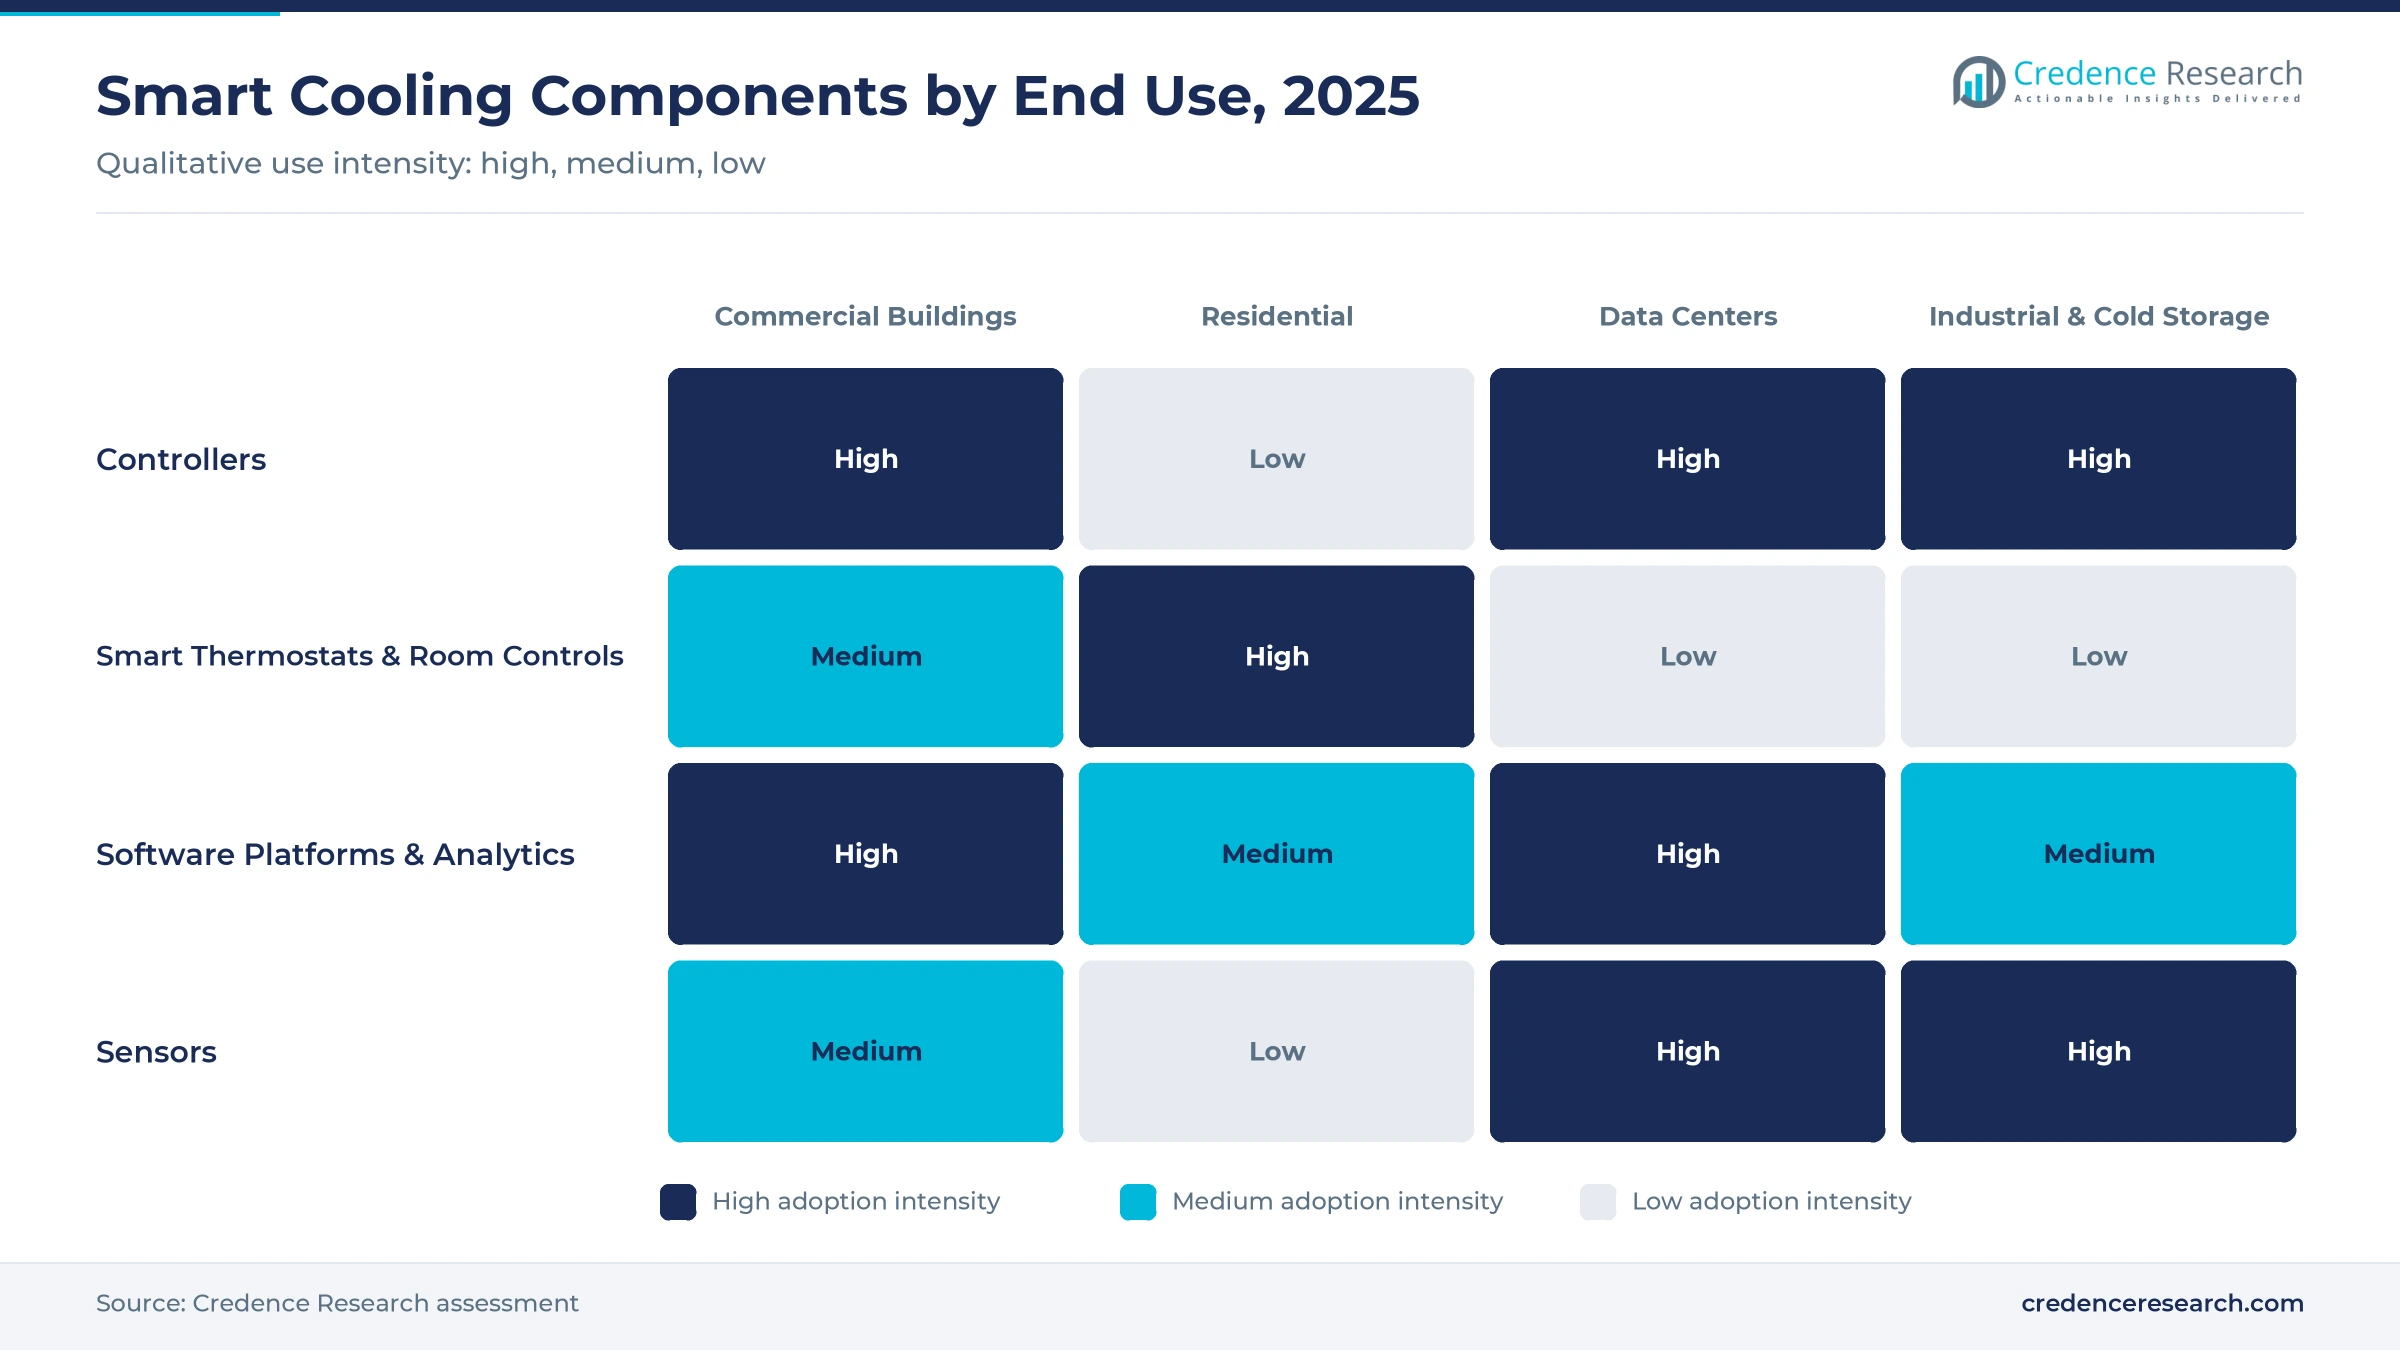
- Controllers accounted for 32.0% of 2025 value, the largest component, because every chiller plant, air handler and coolant distribution unit needs a connected controller.
- Data centers are the fastest-growing end use at 18.68% a year over 2025–2035, as AI servers move racks to liquid loops that need their own controls.
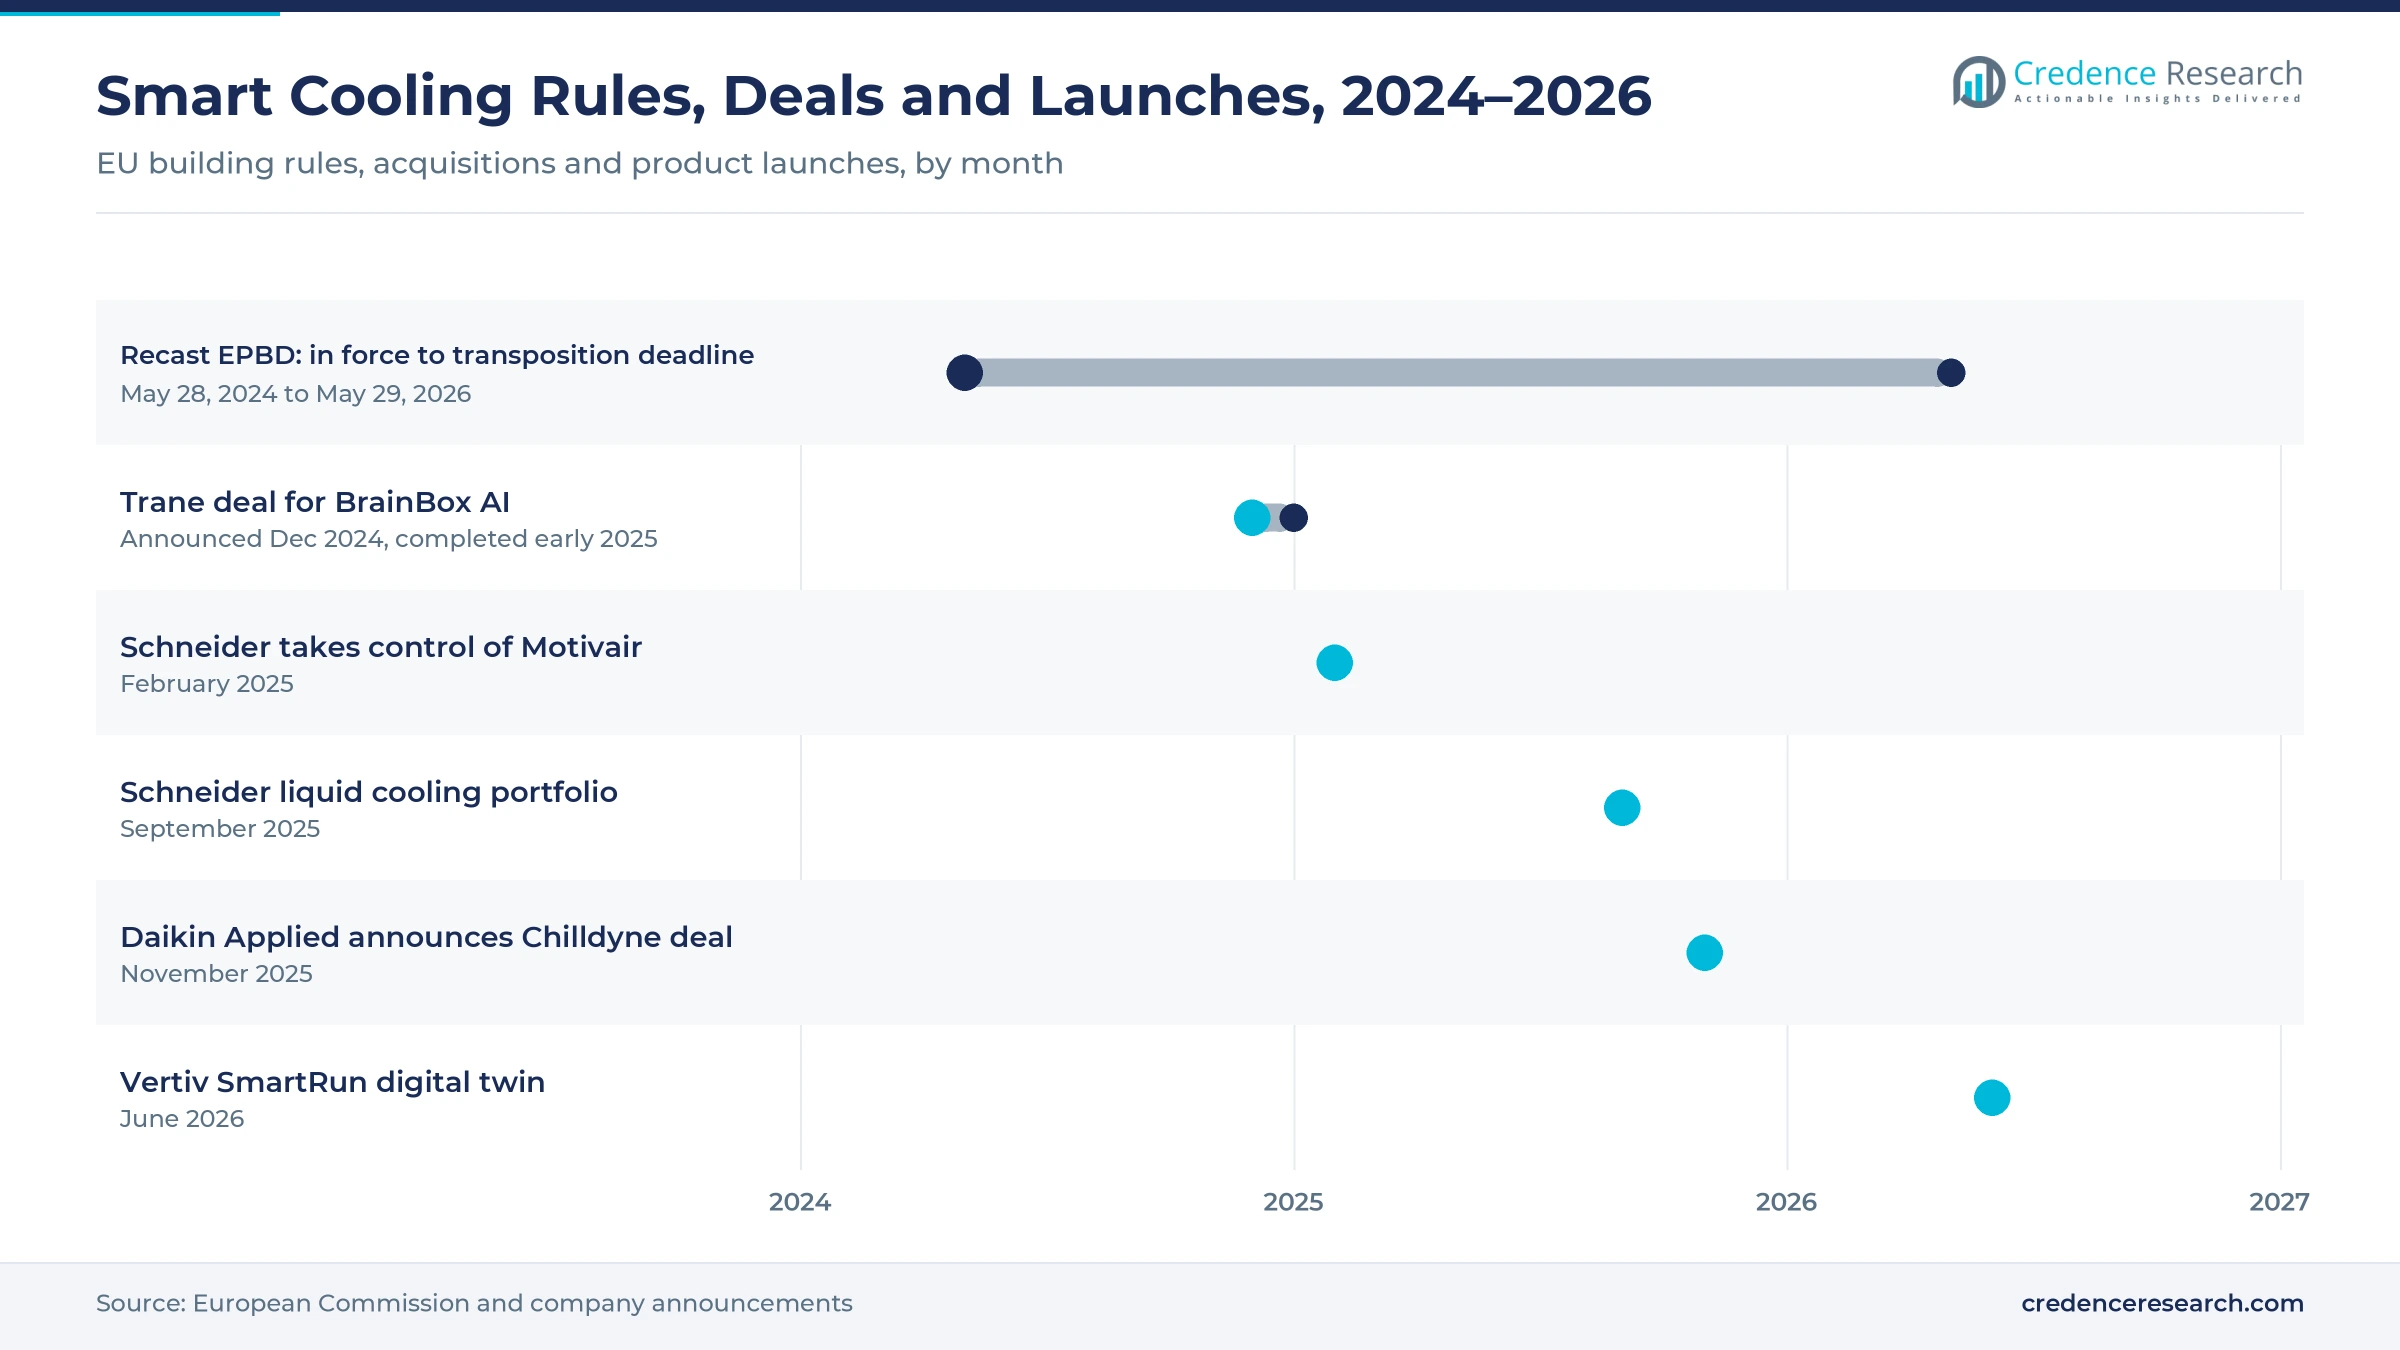
- HVAC majors are buying the control layer. Trane acquired BrainBox AI in early 2025, and Daikin Applied announced its Chilldyne acquisition in November 2025.
Controllers lead as software and data centers grow fastest
Controllers lead by component as software platforms and analytics grow fastest
Based on component, the market is categorized into controllers, smart thermostats and room controls, software platforms and analytics, and sensors. Controllers led with 32.0% of 2025 value, because every chiller plant, air handler and rooftop unit needs one and most new commercial equipment ships connected. Software platforms and analytics grow fastest at 17.60% a year, as subscriptions, AI supervisory control and digital twins raise software revenue per building.
Commercial buildings lead end use while data centers grow fastest
Based on end use, the market is categorized into commercial buildings, residential, data centers and industrial and cold storage. Commercial buildings led with 38.7% of 2025 value, supported by European building rules and corporate decarbonization targets. Data centers grow fastest at 18.68% a year, because value sits in plant controllers, coolant distribution controls, sensing and thermal software rather than in precision air conditioning units.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Component | Controllers | 32.0% | Software Platforms & Analytics | 17.60% |
| By End Use | Commercial Buildings | 38.7% | Data Centers | 18.68% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Peak tariffs, AI heat and EU rules drive cooling control
Peak-load tariffs reward buildings that can pre-cool and ramp down
A heat wave pushes millions of compressors to full speed in the same afternoon hours, when wholesale power is most expensive. The IEA estimates that cooling drove 14% of global electricity demand growth since 2015, and 25% in the Middle East and North Africa. Utilities respond with time-of-use tariffs, demand charges and demand-response payments, each rewarding buildings that pre-cool or stagger plant on a signal. The effect is strongest in North American homes and light-commercial buildings.
AI server heat moves data centers to liquid loops with their own controls
AI servers concentrate heat in smaller spaces than enterprise IT did, so racks move from air to direct-to-chip liquid loops. Each loop needs coolant distribution controls, leak and flow sensors and supervisory software. The IEA reports that data-center electricity use has grown about 12% a year since 2017 and expects it to more than double by 2030, and operators buy control software because each unit of cooling energy saved frees power for IT load.
EU building rules make automation and control a legal requirement
The recast Energy Performance of Buildings Directive entered into force on May 28, 2024, and requires building automation and control in non-residential buildings. Member states had to transpose it by May 29, 2026, which turns larger commercial buildings in Europe, a region growing 11.64% a year, into required buyers of controllers, sensors and software. In the United States, the ENERGY STAR smart thermostat label certifies devices on field data rather than lab claims, giving utilities a common savings benchmark.
AI supervisory control raises the value of the software layer
Current platforms forecast occupancy, weather and tariffs and write setpoints directly to the plant. Trane says BrainBox AI, acquired at the start of 2025, cuts energy consumption by up to 25% and greenhouse gas emissions by up to 40% in buildings it controls. Google reported in 2016 that machine learning from DeepMind cut the energy used to cool its data centers by up to 40%. As a result, software platforms and analytics grow at 17.60% a year.
HVAC majors buy AI control as liquid loops reshape cooling
HVAC majors shift to buying the decision layer above their equipment
Building owners are moving from rule-based schedules to AI agents that adjust chilled-water temperatures, fan speeds and zone setpoints every few minutes. Trane's purchase of BrainBox AI, announced in December 2024, points the same way, and Johnson Controls, which sold its residential and light commercial HVAC business to Bosch on Aug. 1, 2025, now presents itself as a building-solutions provider built around OpenBlue, a sign that large groups want to own the decision layer, not only the equipment.
Rise of liquid cooling and digital twins brings a new control stack
Schneider Electric took a controlling interest in Motivair in February 2025 and in September 2025 unveiled a liquid cooling portfolio of coolant distribution units, rear-door heat exchangers and cold plates managed with EcoStruxure software. Daikin Applied announced the acquisition of Chilldyne, a negative-pressure direct-to-chip specialist, in November 2025, and in June 2026 Vertiv introduced a SmartRun digital twin integrated with the NVIDIA Omniverse DSX Blueprint. Each of these systems ships with its own controllers and leak sensors.
Connected thermostats open an opportunity as paid grid resources
The residential thermostat is turning into a dispatchable grid resource, as utilities enroll connected thermostats into demand-response programs and pay households for pre-cooling and setback events on peak days. Because cooling dominates peak demand, aggregated thermostats act on the costliest part of utility load. Suppliers such as Google Nest and ecobee can earn program revenue on top of device sales, especially in North America, where nearly 90% of U.S. households have air conditioning.
Heat reuse, first-time buyers and performance contracts offer opportunities
Data centers and supermarkets reject heat that nearby buildings could use, and controls that manage heat recovery alongside cooling turn a cost into revenue. In South and Southeast Asia and Africa, many households are buying their first air conditioners, and IEA data show about 40% of the world's population has access to air conditioning while more than 80% experiences cooling needs, a gap low-cost Wi-Fi controllers can serve. Cooling-as-a-service contracts paid from verified savings also remove up-front cost for owners.
Retrofit cost, protocol sprawl and cyber risk slow adoption
Legacy controls make retrofits costly for small commercial owners
Most buildings that will exist in 2035 already stand today, and many run legacy pneumatic or proprietary controls, so replacing them means rewiring, re-commissioning and downtime. For small commercial owners with no energy manager, a payback of three to five years still loses out to other capital spending, which limits penetration among offices and shops even though commercial buildings hold 38.7% of 2025 value. Suppliers ease the barrier with wireless retrofit options, cloud analytics over existing controllers and performance contracts.
Fragmented protocols push integration costs above software costs
Chillers, air handlers and thermostats from different suppliers speak different dialects of BACnet, Modbus and proprietary protocols, so integration labor often costs more than the software itself. That slows deployment in mid-size buildings and favors large suppliers with service teams, and although Matter helps in homes, commercial integration stays services-heavy, so pre-built connectors and tenders that specify open protocols shorten projects.
Cyber risk lengthens sales cycles in government and critical sites
Every connected controller is a potential entry point to a building or data-center network, so owners now ask for segmented networks, signed firmware and security certifications before connecting cooling plant to the cloud, which raises project cost and lengthens sales cycles in government and critical sites. Suppliers with certified products and on-premises options can turn that requirement into an advantage over low-cost device makers.
Ending cloud support for older devices erodes household trust
When a platform owner ends cloud support for early-generation thermostats, households face replacement costs and some lose trust in connected devices. That slows adoption among cautious buyers and weakens utility programs that depend on enrolled devices, although the same events create a replacement wave that lifts unit demand for a year or two. Longer support periods, offline local control and trade-in offers reduce the risk.
North America leads while the Gulf and Asia add cooling load
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| North America | 35.0% | 11.24% |
| Asia Pacific | 31.0% | 14.45% |
| Europe | 24.0% | 11.64% |
| Middle East & Africa | 5.0% | 15.65% |
| Latin America | 5.0% | 12.44% |
North America leads on thermostat programs and AI data centers
North America held 35.0% of 2025 value and grows at 11.24% a year. Nearly 90% of U.S. households have air conditioning, according to the IEA, and utility demand-response programs keep connected thermostat demand high. The region also hosts the largest cluster of AI data centers, which lifts controller and software spending.
Asia Pacific demand rises with air-conditioner ownership and data-center construction
Asia Pacific held 31.0% of 2025 value and grows at 14.45% a year. China's household air-conditioner ownership rose 50% over the past decade on IEA figures, and Japan is close to universal ownership. Connected split units from Daikin and other makers carry much of the residential value, while data-center construction in Singapore, Malaysia, India and Japan drives commercial demand.
Europe's building automation rules anchor commercial demand
Europe held 24.0% of 2025 value and grows at 11.64% a year. Building automation requirements under the recast directive anchor commercial demand, with member states due to transpose the rules by May 29, 2026, while rising summer cooling needs in Southern Europe add residential load. Expectations on data-center heat reuse add a further role for controls, which Siemens, Schneider Electric and Danfoss are placed to serve.
The Middle East & Africa and Latin America grow fast from small bases
The Middle East & Africa held 5.0% of 2025 value and is the fastest-growing region at 15.65% a year. District cooling is widespread in the Gulf, and Saudi Arabia and the United Arab Emirates are building large AI data-center campuses. Latin America held 5.0% and grows at 12.44% a year, led by Brazil and Mexico, with data-center construction around São Paulo and Querétaro.
Liquid cooling deals, a digital twin launch and a Bosch sale
| Development | Status and market relevance |
|---|---|
| In June 2026, Vertiv introduced a SmartRun digital twin integrated with the NVIDIA Omniverse DSX Blueprint. | Launched. Brings simulation into AI-factory cooling design. |
| In June 2026, Vertiv completed its acquisition of ThermoKey, a heat-rejection and heat-exchange specialist. | Completed. Widens the plant that Vertiv's thermal controls manage. |
| In November 2025, Daikin Applied announced the acquisition of Chilldyne, a negative-pressure direct-to-chip cooling maker. | Announced. Gives Daikin a liquid cooling platform for AI data centers. |
| In September 2025, Schneider Electric unveiled a liquid cooling portfolio with Motivair, managed with EcoStruxure software. | Launched. Ties coolant distribution hardware to a software layer. |
| In August 2025, Johnson Controls completed the sale of its residential and light commercial HVAC business to Bosch. | Completed. Focuses Johnson Controls on commercial buildings and OpenBlue. |
Autonomous software, liquid-loop controls and grid signals
- AI supervisory control platforms forecast occupancy, weather and tariffs and adjust setpoints without operator input.
- Liquid-loop controls balance direct-to-chip loops against the remaining air system.
- Digital twins such as Vertiv's SmartRun move from design into operation, tuning cooling in real time.
- Grid integration lets thermostats and building controls respond to tariffs and demand-response signals.
- Interoperability improves as open protocols such as BACnet and Matter lower integration cost.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
HVAC makers, automation houses and thermal specialists
Three groups compete for the control layer of cooling, starting with HVAC equipment makers that bundle controls with their plant. Trane Technologies added AI control through BrainBox AI, Carrier markets QuantumLeap for data centers, Daikin sells connected split and VRV systems, and Johnson Controls now builds around OpenBlue. Automation houses Siemens, Honeywell and Schneider Electric control cooling alongside other building systems, while Danfoss and Emerson are strong in drives, valves and refrigeration controls. Vertiv is the most focused thermal supplier to AI data centers, with Schneider Electric its closest rival, and Google Nest and ecobee are major home thermostat brands. Concentration is highest in large commercial and data-center projects, where integration risk favors established brands.
HVAC, automation, data-center and thermostat suppliers profiled
| Company | Type | Role in the market |
|---|---|---|
| Trane Technologies | HVAC major | Commercial HVAC with BrainBox AI autonomous control |
| Carrier | HVAC major | QuantumLeap integrated data-center offering |
| Daikin | HVAC major | Connected split and VRV systems; Chilldyne liquid cooling through Daikin Applied |
| Johnson Controls | Building solutions | OpenBlue platform; sold residential HVAC business to Bosch in 2025 |
| Siemens | Building automation | Building automation platform that controls cooling plant |
| Honeywell | Building automation | Building automation platform that controls cooling plant |
| Schneider Electric | Automation and data center | EcoStruxure software and Motivair liquid cooling |
| Vertiv | Data-center thermal specialist | Thermal management and SmartRun digital twin |
| Danfoss | Components | Drives, valves and refrigeration controls |
| Emerson | Components | Drives, valves and refrigeration controls |
| Google Nest | Residential | Connected thermostats |
| ecobee | Residential | Connected thermostats |
Smart cooling is bought to manage peak power
Credence Research's view is that smart cooling is a peak-power business more than an efficiency business, because cooling drives around 30% of peak electricity demand and AI racks strain fixed grid connections. Software will capture a rising share of value as AI control and digital twins become routine, while the whole market expands at 12.71% a year. Suppliers that combine equipment, controls and analytics across brands are best placed, and the main risks are retrofit cost, cyber requirements and slower data-center construction.
End-use builds and supplier checks behind cooling figures
The report uses 2025 as the base year and forecasts to 2035. Values come from Credence Research's model, built by end use from connected-thermostat sales, the cooling share of building automation spending and a controls content ratio applied to data-center and cold-storage thermal spending; splits are Credence Research estimates. Evidence comes from IEA analysis, EU legislation, company announcements and supplier disclosures, although suppliers rarely report cooling controls separately, limiting precision.
Autonomous control and liquid loops shape cooling to 2035
Through 2035, data centers will be the fastest-growing buyers at 18.68% a year as liquid loops spread, and software will gain share from controllers, which held 32.0% of 2025 value. Asia Pacific, growing 14.45% a year, and the Middle East & Africa will add the most new cooling load, while North America remains the largest region and EU rules keep European commercial demand steady. The market is projected to rise from USD 9.82 billion in 2026 to USD 28.82 billion by 2035, with retrofit economics and cyber requirements setting the pace.
Frequently Asked Questions
What was the size of the smart cooling systems market in 2025?
What is the forecast value and CAGR of the smart cooling systems market?
Which component leads the smart cooling systems market?
Which end use grows fastest in smart cooling?
Which region holds the largest share of the smart cooling systems market?
Who are the major companies in the smart cooling systems market?
Why does peak demand matter for smart cooling systems?
What challenges could slow the smart cooling systems market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Controllers
- 1.2.2 Smart Thermostats & Room Controls
- 1.2.3 Software Platforms & Analytics
- 1.2.4 Sensors
- 1.3 By End Use
- 1.3.1 Commercial Buildings
- 1.3.2 Residential
- 1.3.3 Data Centers
- 1.3.4 Industrial & Cold Storage
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 8.71 billion → 2035: USD 28.82 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Smart Cooling Systems Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Smart Cooling Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Smart Cooling Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Smart Cooling Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Smart Cooling Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Smart Cooling Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Smart Cooling Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Smart Cooling Systems Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 8.71 billion → 2035: USD 28.82 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Smart Cooling Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Controllers
- 12.3.7.2 Smart Thermostats & Room Controls
- 12.3.7.3 Software Platforms & Analytics
- 12.3.7.4 Sensors
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Commercial Buildings
- 12.4.7.2 Residential
- 12.4.7.3 Data Centers
- 12.4.7.4 Industrial & Cold Storage
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Smart Cooling Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Smart Cooling Systems Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Smart Cooling Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Smart Cooling Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Trane Technologies
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Carrier
- 18.4 Daikin
- 18.5 Johnson Controls
- 18.6 Siemens
- 18.7 Honeywell
- 18.8 Schneider Electric
- 18.9 Vertiv
- 18.10 Danfoss
- 18.11 Emerson
- 18.12 Google Nest
- 18.13 ecobee
- 18.14 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

