
Wood Processing Machines Market Overview:
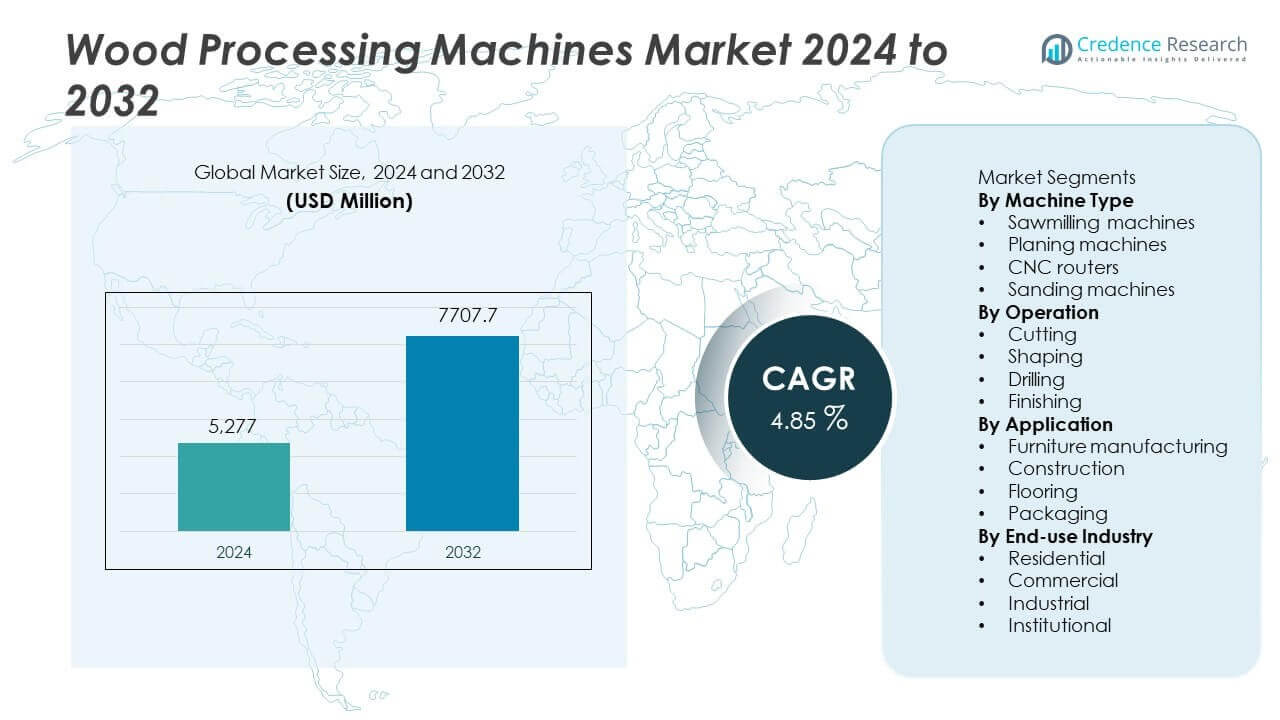
The wood processing machines market was valued at USD 5,277 million in 2024 and is expected to reach USD 7,707.7 million by 2032, growing at a CAGR of 4.85% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wood Processing Machines Market Size 2024 | USD 5,277 million |
| Wood Processing Machines Market, CAGR | 4.85% |
| Wood Processing Machines Market Size 2032 | USD 7,707.7 million |
Wood Processing Machines Market Insights
- Market growth is fueled by rising furniture production, housing expansion, and infrastructure projects, with sawmilling machines leading the machine type segment at a market share of 36.9% due to high usage in primary wood processing.
- Market trends focus on CNC routers, smart machines, and automated systems, as manufacturers seek higher precision, reduced material waste, and improved productivity.
- Competitive dynamics show moderate consolidation, with global players competing on automation, energy efficiency, and service networks, while smaller regional manufacturers focus on cost-effective solutions and niche applications.
- Asia Pacific leads regional demand with a market share of 34.5%, followed by North America at 26.3% and Europe at 23.8%, reflecting high furniture production, industrialization, and infrastructure growth.
Wood Processing Machines Market Segmentation Analysis:
By Machine Type
By machine type, sawmilling machines dominate the wood processing machines market with a market share of 36.9%. High demand comes from primary wood processing and lumber production activities. Sawmilling machines support efficient log conversion and high-volume output. Construction and furniture industries rely heavily on sawn timber. Continuous investment in housing and infrastructure drives usage. Technological upgrades improve precision and reduce material waste. CNC routers follow due to rising demand for automated and customized furniture. However, sawmilling machines remain dominant because of their essential role in upstream wood processing and large-scale industrial operations.
- For instance, HOMAG Group’s high-capacity saw lines process massive volumes of timber per shift, with automated saw carriages reaching rapid speeds to maximize throughput.
By Operation
By operation, cutting operations hold the largest share of 41.5% in the wood processing machines market. Cutting is the primary step in wood transformation and is required across all applications. High usage in sawmills, furniture plants, and construction material production supports dominance. Advanced cutting machines improve speed and accuracy. Demand rises with increased wood panel and lumber production. Shaping and drilling follow, driven by furniture design complexity. Finishing operations show steady growth but lower volumes. Cutting remains dominant due to its universal application and high equipment utilization across processing stages.
- For instance, ANDRITZ AG provides metal processing lines that achieve high-velocity feed rates for aluminum coils and finishing systems.
By Application
By application, furniture manufacturing leads the market with a share of 38.7%. Rising demand for residential and commercial furniture drives machine adoption. Urbanization and lifestyle changes increase furniture consumption. Manufacturers invest in automated machines to improve productivity and design flexibility. CNC-based processing supports mass customization. Construction and flooring follow, supported by building activity. Packaging contributes stable demand through wooden pallets and crates. Furniture manufacturing remains dominant due to high production volumes, frequent design changes, and strong demand for precision wood processing solutions.
Key Growth Drivers
Rising Demand from Furniture and Housing Industries
Growth in residential and commercial construction drives demand for wood processing machines. Furniture manufacturing expands with urbanization and income growth. Modular furniture increases precision machining needs. Manufacturers invest in efficient machines to scale production. Wood-based interiors gain popularity in housing projects. Renovation activity adds replacement demand. Production volume growth raises equipment utilization. This driver supports steady machine adoption. Furniture exports add further momentum. Housing-led demand remains a core growth pillar.
- For instance, Biesse Group’s integrated CNC furniture lines achieve positioning accuracy of 0.01 millimeters and process 500 panels per shift in industrial plants.
Expansion of Construction and Infrastructure Projects
Construction activity increases consumption of processed wood products. Structural components require accurate cutting and shaping. Flooring and panel demand supports machine usage. Infrastructure projects use wooden packaging and formwork. Contractors prefer consistent quality and faster output. Automated machines improve productivity and reduce waste. Project timelines drive continuous equipment operation. Regional infrastructure spending sustains demand. Construction diversification supports multiple machine types. This driver ensures broad-based market growth.
- For instance, SCM Group’s automated cutting centers operate at feed speeds of 100 meters per minute while maintaining straightness tolerance within 0.2 millimeters.
Increasing Adoption of Automation in Wood Processing
Manufacturers adopt automation to improve efficiency and accuracy. Labor shortages encourage machine-led production. Automated systems reduce material wastage. CNC machines support complex designs and repeatability. Digital controls improve operational consistency. Automation lowers long-term operating costs. Productivity gains support capacity expansion. Quality control improves finished output. Automation adoption strengthens competitiveness. This driver accelerates modernization across facilities.
Key Trends & Opportunities
Shift Toward CNC and Smart Wood Processing Machines
CNC routers gain popularity across furniture and flooring applications. Smart machines offer precision and flexibility. Digital integration supports design customization. Manufacturers respond to short production cycles. Software-driven controls reduce setup time. Data monitoring improves maintenance planning. Smart machines enhance throughput efficiency. Demand rises from export-oriented manufacturers. Technology adoption creates premium equipment opportunities. This trend reshapes production workflows.
- For instance, Weinig Group CNC profiling machines deliver feed speeds of 60 meters per minute with profile accuracy maintained at 0.05 millimeters in solid wood applications.
Growth in Sustainable and Efficient Wood Processing
Sustainability influences machine selection decisions. Energy-efficient machines reduce operating costs. Waste reduction aligns with environmental goals. Optimized cutting improves yield from raw wood. Manufacturers seek compliance with green standards. Sustainable practices attract institutional buyers. Efficient machines support responsible forestry usage. Environmental awareness drives equipment upgrades. This trend creates long-term investment opportunities.
- For instance, Ledinek Engineering cross-laminated timber processing lines achieve a high degree of dimensional accuracy while also ensuring efficient material recovery in engineered wood production.
Key Challenges
High Capital Investment and Maintenance Costs
Wood processing machines require high upfront investment. Small manufacturers face affordability challenges. Advanced machines increase capital burden. Maintenance costs affect operating margins. Skilled technicians are required for upkeep. Downtime risks impact production schedules. Financing access varies across regions. Cost concerns slow adoption rates. Budget constraints limit technology upgrades. Capital intensity remains a key barrier.
Volatility in Raw Wood Supply and Prices
Wood supply fluctuations affect processing volumes. Regulatory restrictions impact timber availability. Price volatility disrupts production planning. Reduced raw material access lowers machine utilization. Import dependency adds cost pressure. Environmental policies influence supply chains. Seasonal availability affects output consistency. Uncertainty limits expansion plans. Manufacturers delay capacity investments. Supply volatility remains a persistent challenge.
Regional Analysis
North America
North America holds a market share of 26.3% in the wood processing machines market. Strong housing demand drives steady machine adoption. The United States leads due to large furniture and construction industries. Renovation and remodeling projects support equipment replacement. Automation adoption improves productivity and consistency. Manufacturers invest in CNC and smart machines. Labor shortages accelerate automation needs. Sustainable wood usage influences equipment upgrades. Canada supports demand through lumber processing. Stable industrial investment sustains long-term growth across furniture, construction, and packaging applications.
Europe
Europe accounts for a market share of 23.8% in the wood processing machines market. Furniture manufacturing remains a key demand driver. Germany and Italy lead due to strong machinery and furniture sectors. Sustainable construction boosts wood usage. Strict environmental standards encourage efficient machines. Automation improves quality and waste control. Flooring and interior applications support steady demand. Export-oriented manufacturers invest in advanced equipment. Eastern Europe adds volume through expanding wood processing activities. Technological innovation supports stable regional growth.
Asia Pacific
Asia Pacific leads the wood processing machines market with a market share of 34.5%. Rapid urbanization drives furniture and housing demand. China dominates due to large-scale furniture production. India supports growth through construction expansion. Rising disposable income boosts interior furnishing demand. Automation adoption increases in large factories. Export manufacturing strengthens equipment investment. Packaging and pallet production add volume demand. Cost-effective manufacturing improves supply capacity. Strong industrial growth sustains regional market leadership.
Latin America
Latin America holds a market share of 8.7% in the wood processing machines market. Construction activity supports steady demand. Brazil leads due to furniture and panel production. Local woodworking industries invest in basic automation. Packaging and pallet manufacturing add consistent volume. Import dependency affects advanced machine adoption. Forestry resources support processing activity. Infrastructure projects drive wood usage. Small manufacturers dominate the market structure. Gradual industrial development supports moderate long-term growth.
Middle East & Africa
The Middle East & Africa region accounts for a market share of 6.7%. Construction and infrastructure projects drive wood processing needs. Furniture manufacturing remains limited but growing. Import reliance shapes equipment availability. Industrial packaging supports machine demand. Hospitality projects increase interior wood usage. Automation adoption remains gradual. Skilled labor availability affects investment decisions. Africa shows growth through expanding urban housing. Infrastructure spending supports stable market expansion over the forecast period.
Wood Processing Machines Market Segmentations:
By Machine Type
- Sawmilling machines
- Planing machines
- CNC routers
- Sanding machines
By Operation
- Cutting
- Shaping
- Drilling
- Finishing
By Application
- Furniture manufacturing
- Construction
- Flooring
- Packaging
By End-use Industry
- Residential
- Commercial
- Industrial
- Institutional
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights key players including SCM Group, Biesse Group, HOMAG Group, ANDRITZ AG, and Weinig Group. The wood processing machines market shows moderate consolidation, led by established European manufacturers with strong technology portfolios. Companies compete on automation, precision, and energy efficiency. CNC-based systems and smart controls remain key differentiators. Players invest in R&D to support furniture, construction, and panel processing applications. Global service networks and aftermarket support strengthen customer retention. Emerging market demand encourages capacity expansion and localized production. Smaller regional players focus on cost-effective solutions. Competitive intensity remains strong as customers prioritize productivity, sustainability, and flexible manufacturing capabilities.
Key Player Analysis
- SCM Group
- Biesse Group
- HOMAG Group
- ANDRITZ AG
- IMA Schelling Group
- Weinig Group
- Mühlböck Holztrocknungsanlagen
- Bürkle GmbH
- Michael Weinig AG
- Ledinek Engineering
Recent Developments
- In May 2025, SCM Group joined the new ETML standard project for cross‑manufacturer machine interoperability.
- In March 2025, Biesse showcased new wood processing technologies at INDIAWOOD 2025.
Report Coverage
The research report offers an in-depth analysis based on Machine Type, Operation, Application, End-use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise with increasing furniture production and housing construction.
- Automation adoption will grow across wood processing facilities.
- CNC routers and smart machines will see wider implementation.
- Sustainable and energy-efficient machines will gain preference.
- Expansion of flooring and panel manufacturing will drive equipment usage.
- Renovation and remodeling activities will increase replacement demand.
- Emerging markets will adopt advanced machines for industrial growth.
- Digital integration will improve operational efficiency and precision.
- Packaging and pallet production will provide stable aftermarket opportunities.
- Competition will intensify through technological innovation and regional capacity expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Wood Processing Machines market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wood Processing Machines market projected to grow between 2024 and 2032?
Which Wood Processing Machines market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wood Processing Machines market?
Who are the leading companies in the Wood Processing Machines market?
Which region commanded the largest share of the Wood Processing Machines market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,277 million → 2032: USD 7,707.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wood Processing Machines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wood Processing Machines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wood Processing Machines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wood Processing Machines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wood Processing Machines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wood Processing Machines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wood Processing Machines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wood Processing Machines Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,277 million → 2032: USD 7,707.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wood Processing Machines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wood Processing Machines Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Wood Processing Machines Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Wood Processing Machines Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

