
Market Overview:
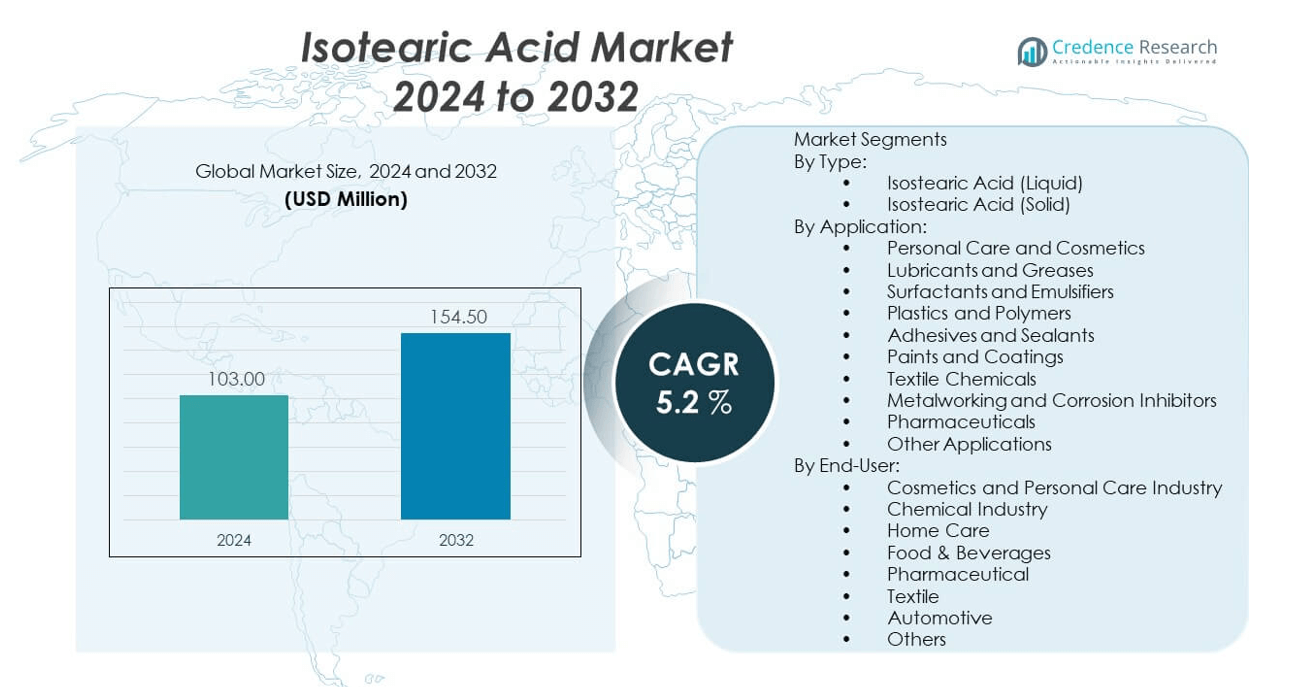
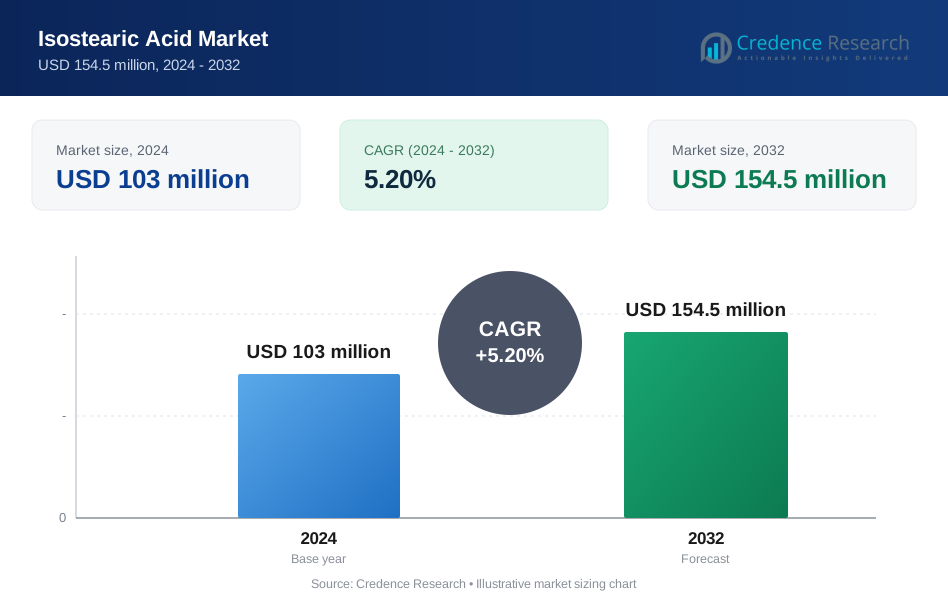
The Isotearic acid market is projected to grow from USD 103 million in 2024 to an estimated USD 154.5 million by 2032, with a compound annual growth rate (CAGR) of 5.2% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Isostearic Acid Market Size 2024 | USD 103 million |
| Isostearic Acid Market, CAGR | 5.2% |
| Isostearic Acid Market Size 2032 | USD 154.5 million |
The isotearic acid market is gaining momentum due to its rising demand in personal care, lubricants, and industrial applications. Manufacturers prefer isotearic acid for its superior oxidative stability, water repellence, and compatibility with other raw materials. Growing consumer preference for bio-based and sustainable ingredients in cosmetics and skin care products is boosting its usage. The push for environmentally friendly formulations in lubricants and coatings also supports adoption. Additionally, increasing industrial applications, including adhesives and resins, further contribute to market expansion.
Regionally, North America and Europe lead the isotearic acid market due to the early adoption of sustainable chemicals, well-established cosmetics and personal care industries, and stringent environmental regulations. The Asia-Pacific region is emerging as a high-growth market, driven by expanding industrial sectors, rising disposable incomes, and growing awareness of eco-friendly personal care products in countries such as China, India, and South Korea. Latin America and the Middle East & Africa show gradual development, supported by industrial modernization and increasing consumer demand for premium bio-based products.
Market Insights:
- The Isostearic acid market was valued at USD 103 million in 2024 and is projected to reach USD 154.5 million by 2032, growing at a CAGR of 5.2% during the forecast period.
- Rising demand for bio-based ingredients in cosmetics and personal care drives significant adoption of isostearic acid globally.
- Growth in sustainable lubricants and industrial applications supports expanding use in metalworking, adhesives, and coatings.
- High production costs and dependency on vegetable oil feedstocks limit wider adoption across price-sensitive sectors.
- North America holds the largest market share, supported by established chemical industries and strong regulatory compliance.
- Europe shows steady growth driven by clean-label cosmetic trends and increased demand for green additives in manufacturing.
- Asia-Pacific emerges as the fastest-growing region due to rising disposable incomes, industrialization, and expansion in personal care markets.
Market Drivers:
Rising Demand for Bio-Based Ingredients in Personal Care Applications:
The shift toward eco-friendly formulations is driving the demand for bio-based chemicals in cosmetics and personal care. Isotearic acid is gaining prominence for its emollient and stabilizing properties in creams, lotions, and sunscreens. Consumers are increasingly choosing products made with plant-derived and biodegradable components, aligning with broader sustainability goals. Major cosmetics manufacturers are reformulating product lines to include safer and more natural inputs. This transition supports consistent demand for isotearic acid across the skincare and haircare segments. Regulatory pressure to limit synthetic and petroleum-based additives further accelerates this shift. The Isotearic acid market benefits from this preference for renewable ingredients. Product innovation in green beauty continues to support growth in this space.
- For instance, Croda International Plc offers Super Refined™ Isostearic Acid, included in over 100 new formulations for personal care in 2024–2025, with the company reporting a 30% year-on-year increase in its use for certified natural cosmetics in Europe
Expansion of Industrial Lubricants and Functional Fluids Segment:
Industries are moving toward more sustainable lubricants that reduce environmental impact and improve performance. Isotearic acid plays a role in enhancing the oxidative stability and lubricity of industrial and automotive formulations. The chemical’s branching structure offers thermal stability and low volatility, making it suitable for demanding environments. Industrial applications such as metalworking fluids, greases, and hydraulic systems continue to adopt bio-lubricants. This change supports both environmental compliance and technical performance. The Isotearic acid market is gaining traction due to its compatibility with evolving lubricant formulations. Global efforts to reduce carbon footprints create further impetus. Demand from sectors like mining, agriculture, and automotive continues to grow.
Increased Usage in Coatings, Adhesives, and Sealants:
Coatings and sealants require consistent performance, water resistance, and surface adhesion, which isotearic acid effectively supports. Its branched-chain structure improves hydrophobicity, making it suitable for moisture-resistant coatings. Paint and adhesive manufacturers are reformulating products to meet stricter environmental and performance standards. The rise of bio-based construction chemicals presents a clear opportunity for isotearic acid. It contributes to product consistency and long-term durability. The Isotearic acid market benefits from this adoption across building materials and consumer adhesives. Regulatory policies that restrict VOC emissions push producers to select safer raw materials. Growth in infrastructure and urban development further sustains demand.
Regulatory Approvals and Certifications Boosting Market Acceptance:
Products containing isotearic acid are gaining certification from global regulatory bodies focused on safety and environmental compliance. These endorsements increase confidence among manufacturers and consumers, encouraging its broader use. The chemical’s low toxicity and biodegradability position it favorably within international regulations. Brands seek ingredients with recognized environmental profiles to enhance product marketing. The Isotearic acid market sees stable demand due to its positive regulatory outlook. Certifications such as COSMOS and ECOCERT play a vital role in expanding its acceptance. Continued investment in regulatory alignment supports the ingredient’s credibility. Governments also encourage the use of safer inputs in industrial and consumer goods.
Market Trends:
Customization of Formulations Across Niche Beauty Segments:
Personal care brands are developing customized products for niche demographics, which requires flexible and stable ingredients like isotearic acid. This compound’s ability to emulsify and improve texture supports a variety of high-performance cosmetic formulations. The rise of men’s grooming, baby care, and sensitive-skin segments demands tailored ingredient blends. Brands are focusing on texture, spreadability, and skin feel-qualities that isotearic acid enhances. Formulators rely on it for compatibility with both oil- and water-based systems. The Isotearic acid market is aligned with this trend toward personalized beauty products. Consumer preference for luxurious and non-greasy textures boosts usage. Innovation in delivery systems further expands potential applications.
- For instance, Vantage Specialty Chemicals’ LIPONATE® ISA has been listed as an emulsifier of choice in new men’s and baby care launches in their updated 2024 technical product catalog.
Surging Popularity of Vegan and Cruelty-Free Products:
Consumers are actively seeking products that do not involve animal testing or animal-derived ingredients. Isotearic acid, being plant-derived, fits these ethical criteria. The vegan cosmetics market has seen an upward trajectory globally, creating a favorable environment for bio-based emulsifiers and surfactants. Brands are using isotearic acid to formulate products that meet both performance and ethical expectations. It allows for clean labeling and transparent ingredient sourcing. The Isotearic acid market aligns with the rapid shift toward cruelty-free certifications. Retailers and e-commerce platforms are prioritizing ethically certified products. This trend is shaping both product development and marketing strategies across regions.
Growing Role in Green Chemistry-Based Manufacturing Processes:
Manufacturers across industries are adopting green chemistry principles to reduce hazardous substances and improve sustainability. Isotearic acid fits well within this framework due to its renewable sourcing and environmental compatibility. Chemical firms are modifying production lines to accommodate green raw materials that perform reliably. It contributes to safer, more efficient formulations in industrial and consumer applications. The Isotearic acid market aligns with cleaner production goals across global operations. Continuous investments in R&D support its functional optimization. The trend is especially strong in Europe and North America, where green manufacturing incentives are widely supported.
Cross-Industry Adoption in Sustainable Packaging Solutions:
Innovations in sustainable packaging are incorporating bio-based coatings and barrier agents, where isotearic acid is finding new roles. It helps improve moisture resistance and flexibility in paper-based and biodegradable materials. As brands seek to replace plastics with compostable or recyclable alternatives, performance additives become essential. Packaging suppliers are developing multilayer solutions using isotearic acid-based modifiers. The Isotearic acid market is seeing interest from packaging sectors that value renewable input materials. Retailers are driving change by prioritizing sustainable packaging. Regulatory standards are supporting the shift toward biodegradable and renewable packaging formats.
Market Challenges Analysis:
Limited Global Supply and Raw Material Dependency Constraints:
The isotearic acid market depends heavily on the availability of raw materials like oleic acid derived from vegetable oils. Fluctuations in the supply of palm or sunflower oil can impact production volumes and pricing. Limited refining infrastructure in some regions restricts large-scale output and export capability. Price volatility in agricultural commodities introduces supply chain uncertainty. It remains vulnerable to geopolitical tensions and trade regulations affecting bio-based feedstocks. Market players face challenges in ensuring consistent quality across batches. The fragmented nature of suppliers also affects global procurement strategies. These constraints increase pressure on manufacturers to secure stable and traceable supply sources.
High Production Cost and Limited Commercial Scale-Up:
The cost of producing isotearic acid remains higher compared to conventional fatty acids due to complex processing steps. Its branched structure requires additional esterification and separation stages. This increases capital expenditure for facilities and limits economies of scale. Small and medium-sized companies struggle to compete with synthetic alternatives that are cheaper and more widely available. The Isotearic acid market faces adoption resistance in price-sensitive industrial applications. Commercialization at scale requires greater automation and improved process efficiency. Many producers hesitate to invest in expansion without long-term demand guarantees. This cost barrier restricts market penetration across new segments.
Market Opportunities:
Emerging Applications in Bioplastics and Eco-Friendly Materials:
Bioplastic manufacturers are exploring isotearic acid as a plasticizer and processing aid for developing biodegradable polymers. Its compatibility with starch- and PLA-based materials supports enhanced flexibility and durability. Packaging producers can use it to improve the shelf life and water resistance of bio-based films. The Isotearic acid market is poised to benefit from ongoing R&D in the field of sustainable plastics. Regulatory pressure on petrochemical plastics creates an opening for alternative materials. As circular economy models gain momentum, demand for such renewable modifiers will likely accelerate.
Strategic Partnerships and Product Differentiation by Manufacturers:
Manufacturers are forming alliances to secure feedstock, streamline production, and co-develop innovative formulations using isotearic acid. Strategic partnerships between chemical companies and consumer brands support quicker go-to-market timelines. These collaborations help in customizing blends for niche industrial or personal care uses. It allows companies to offer cleaner ingredient lists and differentiate products in crowded markets. The Isotearic acid market benefits when producers align with sustainability goals and leverage branding opportunities. Brands are also investing in certifications and marketing to highlight green chemistry claims.
Market Segmentation Analysis:
By Type:
Liquid isostearic acid accounts for the dominant share due to its widespread use in cosmetics, lubricants, and coatings. It offers excellent flowability, ease of formulation, and thermal stability. Solid isostearic acid caters to applications requiring higher melting points and rigidity, primarily in specialized industrial products. It is used less frequently but remains important for niche processes.
- For instance, Oleon NV publicized the expansion of its isostearic acid production unit and cited the majority output is liquid type, as documented in their 2025 capacity announcement.
By Grade:
Cosmetic grade is the most utilized grade in the market due to the growing consumption in personal care products such as lotions, creams, and sunscreens. It is favored for its emollient, non-greasy, and biodegradable profile. Pharmaceutical grade is growing steadily, used in topical drugs and formulations with purity demands. Food grade is limited but serves applications like food-safe packaging and emulsifiers in regulated use cases.
- For instance, Nissan Chemical Corporation’s business partnership news in July 2025 confirmed continued growth in cosmetic-grade shipments, particularly for high-purity market requirements in Asia.
By Application:
Personal care and cosmetics lead the application segments due to increasing demand for natural, skin-friendly ingredients. Lubricants and greases represent the second-largest application, where thermal and oxidative stability is essential. Other significant uses include surfactants, plastics, adhesives, coatings, textile chemicals, and corrosion inhibitors. Pharmaceuticals and other industrial uses, such as cleaning agents and food packaging, are smaller but show growth due to rising regulatory and performance requirements.
By End-User:
The cosmetics and personal care industry holds the largest market share owing to the emphasis on natural, high-performance ingredients. The chemical industry follows closely, driven by demand for renewable and functional feedstocks. Home care, pharmaceuticals, and food & beverages also contribute, while textile and automotive sectors represent emerging end-use categories. The Isostearic acid market benefits from expanding demand across these segments due to its functional versatility and sustainability alignment.
Segmentation:
By Type:
- Isostearic Acid (Liquid)
- Isostearic Acid (Solid)
By Grade:
- Cosmetic Grade
- Food Grade
- Pharmaceutical Grade
By Application:
- Personal Care and Cosmetics
- Lubricants and Greases
- Surfactants and Emulsifiers
- Plastics and Polymers
- Adhesives and Sealants
- Paints and Coatings
- Textile Chemicals
- Metalworking and Corrosion Inhibitors
- Pharmaceuticals
- Other Applications
By End-User:
- Cosmetics and Personal Care Industry
- Chemical Industry
- Home Care
- Food & Beverages
- Pharmaceutical
- Textile
- Automotive
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America holds the largest share in the isostearic acid market, accounting for 32.1% of the global market. The region benefits from strong demand in cosmetics, personal care, and lubricant formulations, supported by a mature consumer base and innovation-driven manufacturers. The U.S. leads regional consumption due to advanced chemical processing capabilities and established regulatory frameworks favoring bio-based products. High spending on sustainable personal care items further boosts growth. Industrial applications in metalworking and adhesives also contribute steadily. It benefits from strong supply chain infrastructure and local production by key market participants.
Europe:
Europe captures 28.5% of the global isostearic acid market share, driven by stringent environmental policies and rising demand for green chemicals. Countries like Germany, France, and the UK lead consumption across cosmetics, coatings, and specialty lubricants. The region has shown strong alignment with circular economy practices, prompting adoption of renewable-based additives. Regulatory bodies encourage use of biodegradable materials, supporting consistent market expansion. Cosmetic manufacturers in the region rely on isotearic acid for compliance with clean-label standards. It sees strong demand from industries focused on low-emission and sustainable production processes.
Asia-Pacific, Latin America, and Middle East & Africa:
The Asia-Pacific region represents 25.4% of the global market and is the fastest-growing region, led by China, India, Japan, and South Korea. Rapid urbanization, increasing disposable income, and a booming cosmetics industry drive growth. It shows strong demand from both consumer and industrial segments, including home care, lubricants, and packaging. Latin America accounts for 7.2%, with growth led by Brazil and Mexico, where demand for bio-based chemicals in personal care and adhesives is increasing. The Middle East & Africa contributes 6.8%, supported by growing industrialization and expanding personal care markets in the Gulf states and South Africa. The isostearic acid market continues to expand globally, with emerging regions showing strong future potential.
Key Player Analysis:
- Croda International Plc
- Oleon NV
- Emery Oleochemicals
- Nissan Chemical Corporation
- KLK Emmerich GmbH
- Santa Cruz Biotechnology, Inc.
- Vantage Specialty Chemicals
- Jarchem Innovative Ingredients LLC
- Kraton Corporation
Competitive Analysis:
The isostearic acid market is moderately consolidated, with a few major players dominating the global landscape. Companies such as Croda International, Oleon NV, and Emery Oleochemicals lead in capacity, product diversity, and global reach. These firms maintain a competitive edge through advanced manufacturing technologies, sustainable sourcing, and established distribution networks. Product innovation focused on green chemistry and specialty applications further strengthens their position. Emerging players focus on niche offerings and regional expansion. The isostearic acid market is shaped by strategic collaborations and continuous R&D investment. It sees strong competition in personal care and industrial sectors, where quality, pricing, and regulatory compliance define market performance.
Recent Developments:
- In March 2025, Croda International Plc reinforced its position in the isostearic acid market by launching a new bio-based isostearic acid product aimed at the cosmetics and personal care industry. This product launch specifically addresses the growing consumer demand for sustainable and eco-friendly ingredients within the sector and demonstrates Croda’s commitment to innovation in green chemistry.
- In March 2025, Oleon NV, a key player in sustainable oleochemistry, announced a strategic distributor partnership with Sea-Land Chemical Company to enhance their service and product reach in the North American lubricants market. This collaboration is intended to deliver greater innovation and improved customer solutions and aligns with Oleon’s broader growth strategy in the region. Previously, in January 2023, Oleon doubled the production capacity of its isostearic and dimer acids at its Belgium facility, further boosting its competitive edge and market share.
- In May 2025, Emery Oleochemicals showcased its commitment to sustainable innovation by presenting new developments in ester base stocks and additives-featuring isostearic acid derivatives-at the STLE 2025 Annual Meeting. Emery’s portfolio, based on renewable resources, targets higher performance and environmental standards for applications in lubricants, industrial fluids, and personal care products.
- On July 18, 2025, Nissan Chemical Corporation entered into a business partnership with Axcelead Drug Discovery Partners Inc. to advance research in RNA therapeutics. While this partnership centers on pharmaceutical R&D, Nissan Chemical continues to invest in sustainable chemical innovations, including isostearic acid derivatives, by leveraging cutting-edge technology and strategic alliances.
- In February 2023, Vertellus acquired Jarchem Innovative Ingredients LLC, expanding Vertellus’s nature-based specialty ingredients portfolio and global reach. This move allows Jarchem’s innovative isostearic acid derivatives to serve a broader market through Vertellus’s global network, aligning with industry trends for natural and eco-friendly product offerings.
Market Concentration & Characteristics:
The isostearic acid market displays moderate-to-high market concentration, with top-tier players holding significant global share through integrated production and extensive product portfolios. It operates within a quality- and compliance-driven environment, where manufacturers emphasize regulatory certifications, renewable sourcing, and process innovation. It is also characterized by steady technological development, expanding end-use diversification, and growing demand from both consumer and industrial applications. Entry barriers include feedstock availability, technical complexity, and the need for sustainable differentiation.
Report Coverage:
The research report offers an in-depth analysis based on Type, Grade, Application, End-User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for isostearic acid will rise with increased adoption of bio-based personal care ingredients.
- Regulatory support for sustainable chemicals will expand its industrial application base.
- Product innovations in emollients and surfactants will drive usage across cosmetic formulations.
- Growth in green lubricants will support steady demand from the automotive and machinery sectors.
- Rising interest in biodegradable polymers will unlock new opportunities in packaging and plastics.
- Pharmaceutical and food-grade applications will grow due to stricter safety and purity standards.
- Asia-Pacific will emerge as the fastest-growing region, supported by manufacturing expansion and rising consumption.
- Strategic partnerships and backward integration will enhance competitiveness among key players.
- Technological advancements in esterification and purification processes will improve cost-efficiency.
- Market players will focus on branding and certification to differentiate in sustainability-driven sectors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Bio-Based Ingredients in Personal Care
The shift toward eco-friendly and sustainable formulations in cosmetics and personal care is driving the adoption of isostearic acid, valued for its emollient and stabilizing properties. Regulatory pressure and consumer preference for plant-derived, biodegradable components are accelerating its use in skincare and haircare products.
Expansion of Sustainable Lubricants and Industrial Applications
Industries are increasingly adopting bio-based lubricants and functional fluids to meet environmental regulations and performance standards. Isostearic acid’s oxidative stability and compatibility with evolving lubricant formulations make it a preferred choice in metalworking, greases, and hydraulic systems.
Increased Usage in Coatings, Adhesives, and Sealants
Isostearic acid’s branched structure enhances hydrophobicity and adhesion, supporting its growing use in moisture-resistant coatings, adhesives, and sealants. The push for low-VOC, bio-based construction chemicals and stricter environmental standards is boosting demand in these segments.
Regulatory Approvals and Certifications
Global regulatory certifications such as COSMOS and ECOCERT for isostearic acid-based products are increasing manufacturer and consumer confidence. These endorsements facilitate broader market acceptance, especially in regions with stringent safety and environmental compliance requirements.
Emerging Applications in Bioplastics and Eco-Friendly Materials
Ongoing R&D in bioplastics and sustainable packaging is opening new opportunities for isostearic acid as a plasticizer and processing aid. Its compatibility with biodegradable polymers and regulatory pressure on petrochemical plastics are driving its adoption in innovative, eco-friendly materials.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Isotearic acid market, and what is its projected size in 2032?
Which Isotearic acid market segment held the largest share in 2024?
Who are the leading companies in the Isostearic acid market?
Which region commanded the largest share of the Isostearic acid market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Isostearic Acid (Liquid)
- 1.2.2 Isostearic Acid (Solid)
- 1.3 By Grade
- 1.3.1 Cosmetic Grade
- 1.3.2 Food Grade
- 1.3.3 Pharmaceutical Grade
- 1.4 By End-User
- 1.4.1 Cosmetics and Personal Care Industry
- 1.4.2 Chemical Industry
- 1.4.3 Home Care
- 1.4.4 Food & Beverages
- 1.4.5 Pharmaceutical
- 1.4.6 Textile
- 1.4.7 Automotive
- 1.4.8 Others
- 1.5 By Application
- 1.5.1 Personal Care and Cosmetics
- 1.5.2 Lubricants and Greases
- 1.5.3 Adhesives and Sealants
- 1.5.4 Paints and Coatings
- 1.5.5 Plastics and Polymers
- 1.5.6 Other Applications
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 103 million → 2032: USD 154.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Isostearic Acid Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Isostearic Acid Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Isostearic Acid Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Isostearic Acid Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Isostearic Acid Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Isostearic Acid Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Isostearic Acid Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Isostearic Acid Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 103 million → 2032: USD 154.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Isostearic Acid Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Isostearic Acid (Liquid)
- 12.3.7.2 Isostearic Acid (Solid)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Grade - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cosmetic Grade
- 12.4.7.2 Food Grade
- 12.4.7.3 Pharmaceutical Grade
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Cosmetics and Personal Care Industry
- 12.5.7.2 Chemical Industry
- 12.5.7.3 Home Care
- 12.5.7.4 Food & Beverages
- 12.5.7.5 Pharmaceutical
- 12.5.7.6 Textile
- 12.5.7.7 Automotive
- 12.5.7.8 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Personal Care and Cosmetics
- 12.6.7.2 Lubricants and Greases
- 12.6.7.3 Adhesives and Sealants
- 12.6.7.4 Paints and Coatings
- 12.6.7.5 Plastics and Polymers
- 12.6.7.6 Other Applications
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Isostearic Acid End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Isostearic Acid Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Isostearic Acid Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Isostearic Acid Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Croda International Plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Oleon NV
- 18.4 Emery Oleochemicals
- 18.5 Nissan Chemical Corporation
- 18.6 KLK Emmerich GmbH
- 18.7 Santa Cruz Biotechnology, Inc.
- 18.8 Vantage Specialty Chemicals
- 18.9 Jarchem Innovative Ingredients LLC
- 18.10 Kraton Corporation
- 18.11 Vertellus
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

