
Green Chemicals Market Overview:
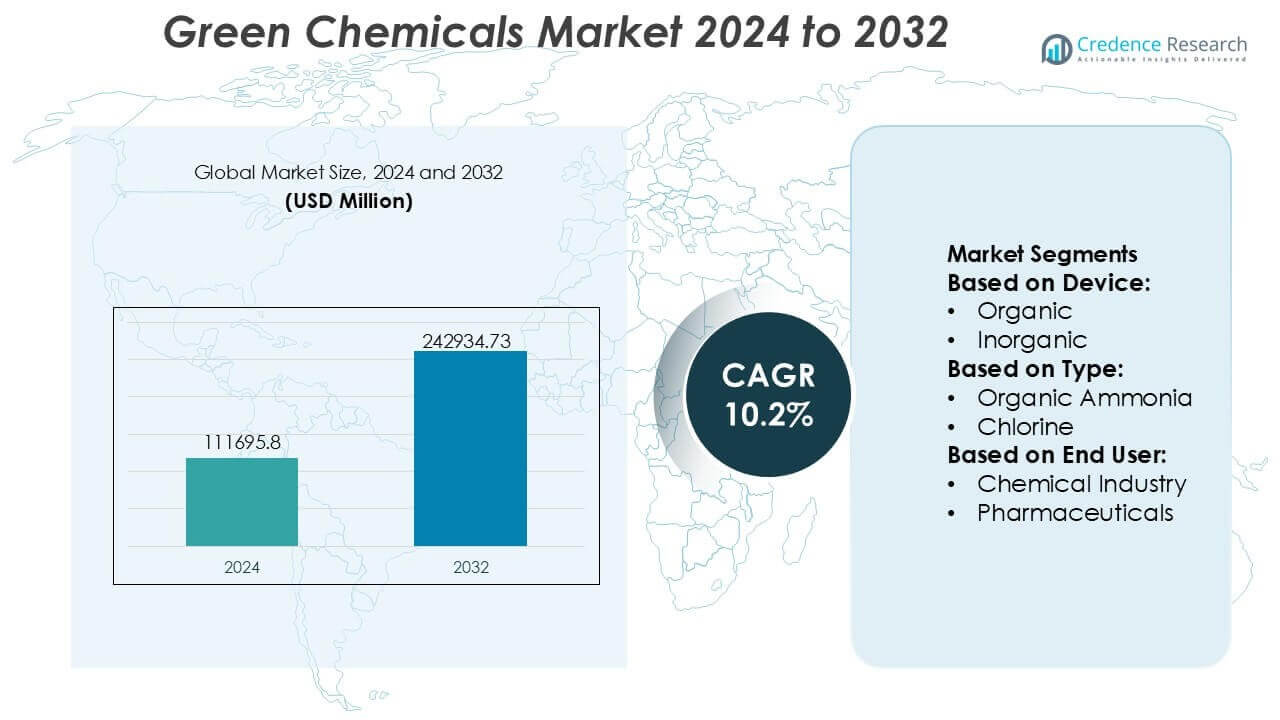
Green Chemicals Market size was valued USD 111695.8 million in 2024 and is anticipated to reach USD 242934.73 million by 2032, at a CAGR of 10.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Green Chemicals Market Size 2024 | USD 111695.8 million |
| Green Chemicals Market, CAGR | 10.2% |
| Green Chemicals Market Size 2032 | USD 242934.73 million |
Green Chemicals Market Insights
- Market growth is primarily driven by rising regulatory pressure to reduce carbon emissions, increasing adoption of bio-based feedstocks, and strong demand from packaging, chemicals, and water treatment industries seeking sustainable and compliant alternatives.
- Key market trends include rapid scaling of fermentation-based synthesis, wider use of enzymatic catalysis, and growing preference for biodegradable polymers, with bio-alcohols and bio-polymers emerging as dominant segments due to versatility and cost efficiency.
- The competitive landscape is characterized by a concentrated group of global players leveraging R&D intensity, process optimization, and strategic partnerships to strengthen supply chains and expand application-specific green chemical portfolios.
- Regionally, North America leads with an exact 38% market share, supported by strict environmental policies and advanced manufacturing, while Europe follows closely, and Asia-Pacific shows the fastest growth driven by industrial expansion and sustainability initiatives.
Green Chemicals Market Segmentation Analysis:
By Device
By device, organic green chemicals dominate the market, accounting for approximately 58% market share, driven by rising adoption of bio-based feedstocks, renewable carbon sources, and fermentation-derived processes. Organic variants benefit from lower lifecycle emissions and stronger alignment with sustainability mandates across multiple industries. Inorganic green chemicals retain relevance due to their role in essential industrial reactions, but their growth remains comparatively moderate. The dominance of organic devices is further reinforced by regulatory incentives, corporate decarbonization targets, and increasing investments in biomass processing and green synthesis routes.
- For instance, SNF operates large-scale bio-polymer production lines capable of manufacturing more than 700,000 metric tons of polyacrylamide annually, with fermentation units running continuous reactors exceeding 250 cubic meters in capacity and achieving molecular weight control above 20 million Daltons, demonstrating how industrial-scale organic green chemistry is being deployed with precise, high-performance metrics.
By Type
By type, organic ammonia emerges as the leading sub-segment with an estimated 34% market share, supported by its critical role in green fertilizers, energy storage, and hydrogen carrier applications. Demand is driven by low-carbon ammonia production using renewable hydrogen and electrolysis-based processes. Ethylene and propylene follow, benefiting from bio-ethanol dehydration and circular feedstock integration in polymers. Chlorine and sodium hydroxide maintain stable demand through greener chlor-alkali technologies, while inorganic benzene adoption grows steadily through biomass-derived aromatics.
- For instance, BASF SE has commissioned a proton exchange membrane electrolyzer with a connected load of 54 megawatts at its Ludwigshafen site, capable of producing up to 8,000 metric tons of hydrogen per year, which is directly integrated into ammonia and chemical synthesis units, demonstrating measurable progress in electrolysis-based organic ammonia production using industrial-scale, renewable hydrogen infrastructure.
By End User
By end user, the chemical industry leads with nearly 41% market share, driven by large-scale adoption of green intermediates, solvents, and feedstocks to meet emission reduction and compliance goals. This segment benefits from process electrification, renewable energy integration, and circular raw material sourcing. Pharmaceuticals and polymers follow, supported by demand for high-purity, sustainable inputs. Food & beverages and pulp & paper show steady uptake due to clean-label and eco-packaging trends, while textiles increasingly adopt green chemicals to reduce water usage and toxic effluents.
Key Growth Drivers
- Stringent Environmental Regulations and Policy Support
Government regulations targeting carbon emissions, hazardous waste, and petrochemical dependency strongly drive the adoption of green chemicals. Regulatory frameworks such as bio-based content mandates, emission caps, and restrictions on toxic intermediates push manufacturers to replace conventional chemicals with renewable and biodegradable alternatives. Incentives including tax credits, subsidies for bio-refineries, and public funding for sustainable chemistry research further accelerate commercialization. As compliance costs rise for fossil-based chemicals, green chemicals gain a competitive advantage by aligning environmental performance with regulatory adherence and long-term risk mitigation strategies.
- For instance, Cortec Corporation has developed bio-based corrosion inhibitors certified under the USDA BioPreferred Program, with several formulations containing more than 90 biogenic carbon and demonstrating corrosion protection for over 1,500 hours in ASTM B117 salt spray testing, providing quantifiable evidence of regulatory-compliant, high-performance green chemistry deployment at industrial scale.
- Rising Demand for Sustainable Products Across End-Use Industries
End-use industries such as food & beverages, pharmaceuticals, personal care, and packaging increasingly prioritize sustainable raw materials to meet corporate ESG goals and consumer expectations. Green chemicals offer low toxicity, reduced lifecycle emissions, and improved biodegradability, making them suitable replacements in formulations without compromising performance. Brand owners actively integrate bio-based solvents, polymers, and intermediates to strengthen sustainability credentials and supply-chain transparency. This demand pull from downstream industries significantly expands commercial adoption and supports long-term volume growth for green chemical producers.
- For instance, Kemira has commercialized wood-based biopolymers for water treatment under its FennoPol platform, engineered with molecular weights exceeding 10 million Daltons and applied at dosages below 5 milligrams per liter to achieve rapid turbidity and solids removal, while its renewable-feedstock coagulants have demonstrated chemical oxygen demand reductions exceeding 1,000 milligrams per liter in industrial wastewater systems, underscoring quantifiable, performance-driven adoption of sustainable chemistry across regulated end-use sectors.
- Advancements in Bio-Based and Green Production Technologies
Technological progress in biotechnology, fermentation, catalysis, and process optimization enhances the economic feasibility of green chemicals. Improved microbial strains, higher feedstock conversion efficiencies, and scalable bioreactor designs reduce production costs and improve yield consistency. Innovations in green synthesis and waste-to-chemical pathways also expand the range of commercially viable products. These advancements enable manufacturers to transition from pilot-scale to industrial-scale production, supporting broader market penetration and encouraging new entrants into the green chemicals ecosystem.
Key Trends & Opportunities
- Expansion of Bio-Based Feedstock Utilization
The market increasingly shifts toward renewable feedstocks such as agricultural residues, non-food biomass, and industrial by-products to avoid food-versus-fuel concerns. This trend creates opportunities for circular-economy models, where waste streams are converted into high-value green chemicals. Companies investing in feedstock diversification improve supply security and reduce exposure to commodity price volatility. The ability to localize feedstock sourcing also supports regional production hubs, lowering transportation emissions and strengthening sustainability positioning.
- For instance, Dow has deployed its Bio-Based Polyols platform using plant-derived feedstocks, operating dedicated units with annual nameplate capacities exceeding 200,000 metric tons, while its integrated biocircular projects have validated the conversion of mixed waste-derived feedstocks through advanced cracking systems capable of processing reactor throughputs above 30 metric tons per hour, demonstrating industrial-scale deployment of diversified, renewable feedstock chemistry with measurable operating metrics.
- Growing Adoption in Polymer and Packaging Applications
Green chemicals gain traction in bio-polymers, coatings, and packaging materials as industries seek recyclable, compostable, and low-carbon alternatives. Demand for bio-based monomers and additives increases as regulations and retailers push for sustainable packaging solutions. This trend opens opportunities for specialty green chemicals with enhanced performance characteristics, such as improved barrier properties or thermal stability, enabling differentiation beyond environmental benefits and supporting premium pricing strategies.
- For instance, Baker Hughes Company has developed bio-derived and recyclable polymer solutions within its advanced materials portfolio, including high-performance thermoplastic composites qualified for continuous operation temperatures above 200 °C and tensile strengths exceeding 150 megapascals, while its polymer processing technologies support extrusion and compounding lines operating at throughputs greater than 1,000 kilograms per hour, demonstrating industrial-scale deployment of sustainable polymer solutions with clearly defined performance metrics.
- Strategic Partnerships and Investment Activity
Collaborations between chemical companies, biotechnology firms, and research institutions accelerate innovation and commercialization. Strategic partnerships enable shared expertise in feedstock processing, scale-up, and market access, reducing development risks. Increased private equity and venture capital investments support capacity expansion and technology validation. These collaborations create opportunities for faster time-to-market and strengthen competitive positioning in an increasingly innovation-driven landscape.
Key Challenges
- High Production Costs and Scale-Up Limitations
Despite technological progress, green chemicals often face higher production costs compared to petrochemical alternatives due to feedstock variability, process complexity, and limited economies of scale. Scaling bio-based processes from laboratory to commercial production requires significant capital investment and operational expertise. Cost competitiveness remains a critical barrier, particularly in price-sensitive applications, restricting adoption to segments where sustainability premiums are accepted or regulatory pressure is high.
- Feedstock Availability and Supply-Chain Constraints
Reliable access to sustainable feedstocks poses a major challenge for green chemical producers. Seasonal availability, geographic concentration, and competition from bioenergy or agriculture can disrupt supply chains and impact cost stability. Inconsistent feedstock quality also affects process efficiency and product consistency. Addressing these constraints requires long-term sourcing agreements, diversified feedstock strategies, and investment in logistics and preprocessing infrastructure, increasing overall operational complexity.
Regional Analysis
North America
North America holds a leading position in the Green Chemicals Market, accounting for approximately 38% market share. Growth is driven by stringent environmental regulations, strong policy support for bio-based products, and high corporate commitments to sustainability. The United States dominates regional demand due to advanced R&D infrastructure, early adoption of green manufacturing technologies, and widespread use of renewable feedstocks across chemicals, packaging, and consumer goods. Canada contributes through bio-refining initiatives and forest-based chemical feedstocks. Strong collaboration between industry and government agencies continues to accelerate commercialization and large-scale adoption of green chemical solutions.
Europe
Europe represents nearly 30% of the global Green Chemicals Market, supported by aggressive climate policies and circular economy mandates. Countries such as Germany, France, and the Netherlands lead adoption through carbon-reduction targets, bioeconomy strategies, and restrictions on fossil-based chemicals. The region emphasizes biodegradable polymers, bio-based solvents, and green specialty chemicals across automotive, construction, and packaging sectors. Robust regulatory frameworks, including REACH and carbon pricing mechanisms, encourage sustainable chemical innovation. Additionally, strong consumer awareness and demand for eco-labeled products reinforce market growth and long-term investment in green chemical production.
Asia-Pacific
Asia-Pacific accounts for around 22% market share and is the fastest-growing region in the Green Chemicals Market. Rapid industrialization, expanding manufacturing bases, and increasing environmental concerns in China, India, and Southeast Asia drive demand. Governments are promoting bio-based chemicals through renewable energy targets, green manufacturing incentives, and waste-to-resource programs. China leads in production scale, while Japan and South Korea focus on high-value bio-based materials and green specialty chemicals. Rising consumer demand for sustainable packaging and eco-friendly consumer products further accelerates regional adoption.
Latin America
Latin America holds approximately 6% of the Green Chemicals Market, with growth supported by abundant biomass availability and expanding bio-refinery investments. Brazil leads the region due to its strong sugarcane-based ethanol and bio-chemical production ecosystem. Argentina and Colombia contribute through agricultural residue utilization and emerging green polymer applications. The region benefits from low-cost renewable feedstocks and increasing export-oriented production. However, limited infrastructure and regulatory variability moderate growth. Continued investments in sustainable agriculture and bio-based industrial development are expected to strengthen regional market penetration.
Middle East & Africa
The Middle East & Africa region accounts for about 4% market share in the Green Chemicals Market. Growth is driven by diversification efforts away from fossil-based economies and increasing investments in sustainable industrial development. The Middle East focuses on integrating green chemicals into petrochemical value chains, particularly in bio-based fuels and specialty chemicals. In Africa, adoption is supported by agricultural biomass availability and rising interest in sustainable fertilizers and bio-based materials. While market maturity remains limited, government-led sustainability initiatives and foreign investments are gradually improving regional growth prospects.
Green Chemicals Market Segmentations:
By Device:
- Organic
- Inorganic
By Type:
- Organic Ammonia
- Chlorine
By End User:
- Chemical Industry
- Pharmaceuticals
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The green chemicals market players such as SNF, BASF SE, Cortec Corporation, Kemira, Dow, Nouryon, Baker Hughes Company, Solenis, Ecolab, SUEZ. The green chemicals market exhibits a competitive landscape driven by sustainability performance, technological innovation, and the ability to scale bio-based and low-impact solutions across multiple end-use industries. Market participants compete by expanding portfolios that utilize renewable feedstocks, reduce carbon intensity, and comply with increasingly stringent environmental regulations.
Strong emphasis is placed on research and development to improve process efficiency, enhance product performance, and ensure compatibility with existing industrial systems. Integration of green chemistry with digital monitoring, circular economy models, and lifecycle assessment tools further strengthens competitive positioning. Companies also pursue strategic collaborations with utilities, industrial users, and downstream manufacturers to accelerate adoption and secure long-term supply agreements. Overall, competition is shaped less by price alone and more by value creation through regulatory compliance, measurable sustainability outcomes, application-specific customization, and the ability to support customers’ decarbonization and resource-efficiency objectives across global markets.
Key Player Analysis
- SNF
- BASF SE
- Cortec Corporation
- Kemira
- Dow
- Nouryon
- Baker Hughes Company
- Solenis
- Ecolab
- SUEZ
Recent Developments
- In June 2025, Syensqo launched Miracare Biopacify, a biodegradable and microplastic-free opacifier for liquid laundry detergents, aligning with upcoming European microplastics regulations. With a Renewable Carbon Index (RCI) over 90%, the product offers a sustainable alternative to styrene acrylates without compromising performance.
- In March 2025, DuPont Water Solutions launched WAVE PRO in March 2025, an advanced, web-based modeling tool for ultrafiltration (UF) in diverse applications like drinking water, industrial needs, wastewater, and desalination, building on the original WAVE tool to offer enhanced features, collaboration, and seamless updates for optimizing water treatment designs.
- In March 2025, Whitewater Management did acquire Orion Water Solutions a move that significantly boosted Whitewater's capabilities in advanced wastewater treatment, integrating Orion's specialized technologies like DAF, Chlorine Dioxide, and biological systems to serve industries such as oil & gas, mining, and municipal sectors, as confirmed by multiple sources including PR Newswire and PE Hub.
Report Coverage
The research report offers an in-depth analysis based on Device, Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of bio-based and renewable feedstocks will accelerate as industries seek to reduce dependence on fossil-derived chemicals.
- Regulatory pressure on emissions, toxicity, and waste will continue to drive substitution of conventional chemicals with greener alternatives.
- Advances in biotechnology and fermentation processes will improve yields, consistency, and scalability of green chemical production.
- Demand from water treatment, agriculture, and specialty industrial applications will remain a key growth catalyst.
- Integration of circular economy principles will increase the use of recycled and waste-derived raw materials.
- Digital tools such as process optimization and lifecycle assessment will strengthen efficiency and compliance across production chains.
- Collaboration between chemical producers and end-use industries will intensify to co-develop application-specific formulations.
- Expansion of green chemistry solutions in emerging economies will be supported by industrialization and sustainability mandates.
- Continuous improvement in cost competitiveness will narrow the gap between green and conventional chemical solutions.
- Long-term market development will be shaped by innovation that balances performance, regulatory compliance, and environmental impact reduction.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Green Chemicals Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Green Chemicals Market projected to grow between 2024 and 2032?
Which Green Chemicals Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Green Chemicals Market?
Who are the leading companies in the Green Chemicals Market?
Which region commanded the largest share of the Green Chemicals Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 111,695.8 million → 2032: USD 242,934.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Green Chemicals Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Green Chemicals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Green Chemicals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Green Chemicals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Green Chemicals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Green Chemicals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Green Chemicals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Green Chemicals Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 111,695.8 million → 2032: USD 242,934.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Green Chemicals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Green Chemicals Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Green Chemicals Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Green Chemicals Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

