
Market Overview:
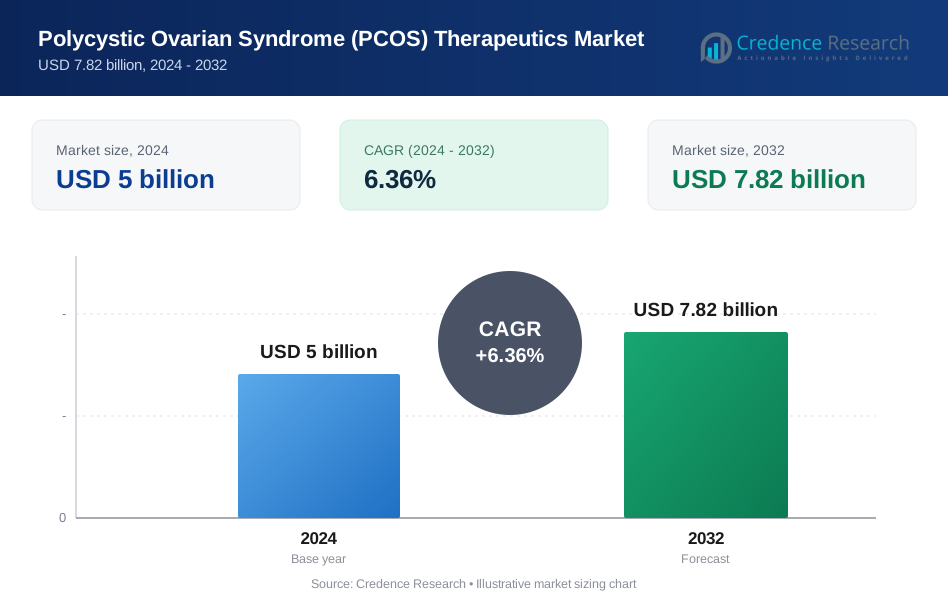
The Polycystic Ovarian Syndrome (PCOS) Therapeutics market was valued at USD 5 billion in 2024 and is expected to reach USD 7.82 billion by 2032, growing at a CAGR of 6.36% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Size 2024 | USD 5 billion |
| Polycystic Ovarian Syndrome (PCOS) Therapeutics Market, CAGR | 6.36% |
| Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Size 2032 | USD 7.82 billion |
The Polycystic Ovarian Syndrome (PCOS) therapeutics market is dominated by key players such as Abbott Laboratories, Bayer AG, Merck & Co., Inc., Sanofi S.A., Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., AstraZeneca plc, and Bristol Myers Squibb Company. These companies lead the market with a diverse range of treatments targeting hormonal imbalances, insulin resistance, and infertility associated with PCOS. North America holds the largest market share, accounting for approximately 40–45% due to its well-established healthcare infrastructure and high patient awareness. Europe follows with around 20–25% of the market share, while Asia Pacific is experiencing the fastest growth, currently holding about 15–20%. These regions are key focus areas for the top players, who are actively investing in research and expanding their product offerings to capture the increasing demand for effective PCOS treatments.

Market Insights
- The Polycystic Ovarian Syndrome (PCOS) therapeutics market is valued at USD 5 billion in 2024 and is expected to reach USD 7.82 billion by 2032, growing at a CAGR of 6.36%.
- The market is driven by the rising prevalence of PCOS, with increasing awareness of the condition leading to higher diagnosis rates and greater demand for effective treatments.
- Advancements in drug development are offering more personalized, targeted therapies that address the specific hormonal and metabolic imbalances associated with PCOS, driving the market forward.
- Key trends include a shift toward personalized medicine and the rapid growth of online pharmacies and telemedicine, providing new opportunities for delivering PCOS treatments more effectively and conveniently.
- North America dominates the market, accounting for a45% of the market share, followed by Europe at 25%, and Asia Pacific with the fastest growth rate, holding 20% share.
Market Segmentation Analysis
By Drug Class
The Polycystic Ovarian Syndrome (PCOS) therapeutics market is dominated by the Oral Contraceptives segment, which holds 40% of the market share. This sub-segment is driven by the increasing awareness of the benefits of oral contraceptives in managing symptoms such as irregular periods and excessive hair growth. Oral contraceptives are widely prescribed due to their effectiveness in regulating hormones, making them a popular choice among patients and healthcare providers. The growing adoption of combination oral contraceptives, which address both contraceptive and therapeutic needs, further boosts their dominance in the market.
- For instance, combined oral contraceptives (COCs) containing low-dose ethinyl estradiol and antiandrogenic progestins such as norgestimate or desogestrel are preferred choices, as they effectively reduce androgen levels and improve menstrual regularity.
By Route of Administration
The Oral route of administration leads the market in the PCOS therapeutics segment, capturing 55% of the market share. Oral medications are preferred by patients due to their ease of use and convenience. The widespread acceptance of oral contraceptives and insulin sensitizers as oral medications has fueled the growth of this sub-segment. Additionally, the preference for non-invasive treatments and the continuous development of oral therapies with improved bioavailability contribute to the sustained dominance of oral medications in treating PCOS.
- For instance, Clomiphene citrate, an oral ovulation stimulant, is available from companies like Cipla (brand name Fertomid) and Gynogen (brand name GENCURE 50). These brands are frequently prescribed to induce ovulation in PCOS-related infertility.
By Distribution Channel
Among the various distribution channels, Retail Pharmacies hold the largest market share, 50%. This is primarily due to the accessibility and widespread presence of retail pharmacies, allowing consumers to easily obtain their prescribed medications. The convenience and availability of a wide range of therapeutics at competitive prices in retail pharmacies drive their dominance. Additionally, retail pharmacies benefit from higher consumer footfall, increasing sales volume and contributing to the overall growth of the market. Online pharmacies are also growing rapidly, driven by convenience and increasing e-commerce adoption.
Key Growth Drivers
Rising Prevalence of PCOS
One of the primary drivers for the growth of the Polycystic Ovarian Syndrome (PCOS) therapeutics market is the increasing prevalence of PCOS worldwide. PCOS affects a significant proportion of women of reproductive age, with estimates suggesting it impacts around 10% of women globally. This rising prevalence has heightened awareness and demand for effective treatments. As the understanding of PCOS expands, more women are seeking medical advice and treatments to manage the condition’s symptoms, such as irregular periods, infertility, and excessive hair growth. The growing awareness among healthcare professionals, coupled with improved diagnostic tools, has led to an increase in the number of diagnoses and, consequently, a greater demand for therapeutics.
- For instance, a study of women across major Chinese provinces that used the Rotterdam criteria to diagnose Polycystic Ovary Syndrome (PCOS) found that the prevalence of the condition rose from 5.6% in 2010 to 7.8% in a subsequent survey in 2020.
Advancements in Drug Development
Advancements in drug development for PCOS therapeutics are fueling market growth by offering more targeted, effective, and personalized treatments. Over the past few years, new drug classes, such as insulin sensitizers, anti-androgens, and ovulation inducers, have gained approval, improving treatment outcomes for women with PCOS. The ongoing research into hormonal therapies, lifestyle modifications, and combination therapies has provided more options for treating the diverse symptoms of PCOS. Moreover, the development of drugs that specifically address underlying issues like insulin resistance and hormonal imbalances is expected to meet the evolving needs of patients.
- For instance, an anti-androgen intervention using Finasteride (5 mg daily) alone or in combination with metformin was compared against metformin alone in adult women with PCOS, over 12 months, showing substantive androgen level reductions.
Increasing Healthcare Awareness and Accessibility
The rising awareness of PCOS among women and healthcare providers is a key driver of growth in the PCOS therapeutics market. Increased awareness campaigns and initiatives by healthcare organizations, coupled with online information and support networks, have contributed significantly to the recognition of PCOS as a common yet underdiagnosed condition. Additionally, the expanding access to healthcare services, especially in emerging economies, has led to more women seeking treatment for PCOS. With improvements in healthcare infrastructure, diagnostic tools, and treatment availability, women are more likely to visit healthcare providers for PCOS diagnosis and management.
Key Trends & Opportunities
Shift Toward Personalized Medicine
The increasing trend toward personalized medicine presents a significant opportunity in the PCOS therapeutics market. Personalized approaches allow for treatment regimens that are tailored to the unique needs of each patient, considering factors such as age, medical history, and specific symptoms. For instance, therapies that target insulin resistance or androgen excess can be customized based on individual patient profiles. As genetic research and biomarker identification progress, there will be a surge in targeted therapies that can provide more effective and less invasive treatments. This trend towards personalized medicine is expected to improve treatment outcomes, minimize side effects, and foster patient satisfaction, creating growth opportunities for pharmaceutical companies to develop specialized PCOS therapies.
- For instance, research identified two glycolysis‑related gene biomarkers, TXNIP and TGFBI, which were significantly upregulated in granulosa cells from PCOS patients; TGFBI had 14 high‑confidence m6A modification sites, TXNIP had one.
Growth of Online Pharmacies and Telemedicine
The growth of online pharmacies and telemedicine is a key opportunity for the PCOS therapeutics market. The increasing adoption of telemedicine has revolutionized healthcare delivery, making it more convenient for patients to consult doctors, receive prescriptions, and access medications remotely. This trend has gained further momentum due to the COVID-19 pandemic, which accelerated the adoption of telehealth services. As a result, online pharmacies that offer PCOS medications are benefiting from a broader customer base, particularly in regions where traditional pharmacy access may be limited. This trend also allows for more discreet and convenient access to PCOS treatments, encouraging more women to seek therapy. The convenience of home delivery of prescriptions and medications is expected to drive growth in the online pharmacy segment of the market.
- For instance, Teladoc Health offers comprehensive care for PCOS including diagnosis and medication support, making it easier for women to access specialist care remotely through telemedicine consultations.
Key Challenges
Side Effects and Safety Concerns
One of the primary challenges in the PCOS therapeutics market is the side effects and safety concerns associated with various treatments. Medications such as oral contraceptives, anti-androgens, and insulin sensitizers may cause adverse effects like weight gain, nausea, and mood changes, which can deter patients from adhering to their prescribed therapies. The fear of long-term side effects, such as the risk of blood clots with oral contraceptives or liver damage with certain insulin sensitizers, may also discourage some women from seeking treatment. Healthcare providers need to address these concerns and work with patients to monitor side effects and adjust treatment plans accordingly. The challenge of ensuring patient compliance while balancing efficacy with safety continues to hinder the market’s growth potential.
High Treatment Costs
The high cost of PCOS treatments remains a significant challenge for many patients, particularly in developing regions. While pharmaceutical companies have introduced new treatments for PCOS, the prices of medications, diagnostic tests, and consultations can be prohibitively expensive for a large segment of the population. In countries with limited insurance coverage or healthcare infrastructure, out-of-pocket costs can make it difficult for women to access the necessary care. This pricing challenge restricts the potential market size and limits the ability of many women to afford ongoing treatment. Affordable solutions and government-backed healthcare initiatives will be essential to overcoming this barrier and ensuring that women worldwide have access to effective PCOS therapeutics.
Regional Analysis
North America
The North American region dominates the Polycystic Ovarian Syndrome (PCOS) therapeutics market, capturing 45% of global market share in 2024–2025. This leadership stems from well-established healthcare infrastructure, high awareness of PCOS among women of reproductive age, and substantial research investment by major pharmaceutical companies. Early diagnosis practices and accessible new therapies further reinforce demand. The considerable prevalence of PCOS in the region, combined with advanced patient monitoring and reimbursement mechanisms, ensures that North America will continue to lead market revenues in the foreseeable forecast period.
Europe
Europe holds a sizeable portion of the PCOS therapeutics market, estimated at 25% of global share. Strong public health initiatives, increasing diagnosis rates, and growing attention to women’s metabolic and reproductive health support the region’s market growth. The presence of established pharmaceutical manufacturers and favorable reimbursement policies for PCOS-related therapies also contribute. However, compared to North America, uptake is moderated by varied healthcare access across countries and differences in insurance coverage, making Europe a significant but slower-growing region in the global landscape.
Asia Pacific
In the Asia Pacific region, the PCOS therapeutics market is emerging strongly, with a current share of 20%, and the fastest anticipated growth rate among all regions. Earlier under-diagnosis is giving way to increasing awareness, improved healthcare infrastructure, and focused women’s health initiatives in countries such as India, China and Australia. These factors are driving higher adoption of PCOS treatments. Rising urbanization, lifestyle changes and increasing prevalence of metabolic disturbances in women further propel demand. The region offers significant opportunity for both global and regional players to expand their market presence.
Latin America
Latin America accounts for 10% of the global PCOS therapeutics market. Growth in this region is supported by increasing awareness of PCOS, efforts to strengthen women’s health services, and the gradual expansion of pharmaceutical distribution networks. Despite this progress, the market faces constraints in terms of varying access to care, reimbursement inconsistencies, and lower per-capita healthcare spending compared with developed regions. Nonetheless, the region presents a steady growth opportunity as awareness campaigns and access to diagnosis and treatment improve.
Middle East & Africa
The Middle East & Africa region represents the smallest share of the PCOS therapeutics market, estimated at 7% globally. Market growth is driven by a rising incidence of PCOS, a growing young female population, and governmental initiatives to enhance women’s healthcare access. However, challenges such as limited diagnostic infrastructure, variable reimbursement frameworks, and lower awareness of PCOS hinder faster adoption of therapies. As healthcare systems in the region improve and awareness increases, the market is poised for gradual expansion.
Market Segmentations
By Drug Class
- Oral Contraceptives
- Insulin Sensitizers
- Anti-Androgens
- Ovulation Inducers
By Route of Administration
- Oral
- Injectable
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the PCOS therapeutics market features a blend of major multinational pharmaceutical companies and specialized women's-health firms strategically advancing their offerings. Players such as Abbott Laboratories, Bayer AG, Merck & Co., Inc., Sanofi S.A., Pfizer Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., AstraZeneca plc, and Bristol Myers Squibb Company consistently lead in research, development, and commercialization of PCOS-relevant treatments. These companies invest heavily in R&D to address hormonal, metabolic, and fertility-related aspects of the condition and often form alliances or licensing deals to expand pipelines and geographic reach. Competitive advantage hinges on novel mechanism-based therapies, differentiation through drug classes (such as insulin sensitisers or anti-androgens), and strong global marketing networks. As a result, market players aim to capture early adopter segments and solidify their positions through lifecycle management, generic launches, and emerging-market expansion.
Key Player Analysis
- Teva Pharmaceutical Industries Ltd.
- Pfizer Inc.
- Novartis AG
- Ferring Pharmaceuticals
- AstraZeneca plc
- Merck & Co., Inc.
- Sanofi S.A.
- Bayer AG
- Bristol Myers Squibb Company
- Abbott Laboratories
Recent Developments
- In 2025, Jagat Pharma introduced “PCOS Capsules For Her”, an Ayurvedic supplement formulated to help manage PCOS symptoms.
- In August 2024, Aurelle Health (via Balaxi Pharmaceuticals) launched a women’s hormonal health brand in India, with product lines that include support for PCOS‑related hormone issues.
- In August 2023, BioSyent Inc. launched Inofolic®, a soft‑gel capsule combining myo‑inositol and folic acid, specifically for women with PCOS
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Route of Administration, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The PCOS therapeutics market is expected to continue expanding as awareness and diagnoses of the condition increase globally.
- Advances in personalized medicine will drive the development of more targeted treatments, enhancing the effectiveness of therapies for individual patients.
- New drug classes targeting specific PCOS symptoms, such as insulin resistance and androgen excess, will emerge, offering more tailored solutions.
- The increasing prevalence of PCOS, particularly in emerging economies, will fuel demand for effective therapeutic options and drive market growth.
- The rise of digital health tools, including telemedicine and online pharmacies, will improve patient access to PCOS treatments, particularly in remote areas.
- Enhanced drug delivery systems, such as novel oral and injectable forms, will improve patient adherence and outcomes in managing PCOS.
- Growing healthcare infrastructure and better access to healthcare services in developing regions will create new opportunities for market expansion.
- Pharmaceutical companies will continue to invest in R&D to discover more innovative treatments, creating a competitive environment in the market.
- Partnerships and collaborations between pharmaceutical companies and research institutions will accelerate the development and availability of new PCOS therapies.
- Regulatory advancements and favorable reimbursement policies in various regions will make PCOS treatments more affordable and accessible to a wider patient population.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence and Awareness of PCOS
The increasing global prevalence of PCOS, affecting around 10% of women of reproductive age, is driving higher diagnosis rates and demand for effective therapeutics. Greater awareness among both patients and healthcare providers is leading to more women seeking treatment for PCOS symptoms.
Advancements in Drug Development and Personalized Medicine
Ongoing research and innovation have led to the introduction of new drug classes and more targeted therapies, such as insulin sensitizers and anti-androgens, which address the specific hormonal and metabolic imbalances of PCOS. The shift toward personalized medicine is enabling more effective and tailored treatment regimens.
Expansion of Online Pharmacies and Telemedicine
The rapid growth of online pharmacies and telemedicine platforms is making it easier for patients to access PCOS treatments, especially in regions with limited healthcare infrastructure. This trend is improving convenience, privacy, and adherence to therapy, thereby expanding the market.
Improved Healthcare Infrastructure and Access in Emerging Markets
Developing regions, particularly in Asia Pacific and Latin America, are experiencing improvements in healthcare infrastructure and access, leading to increased diagnosis and treatment of PCOS. Government initiatives and expanding pharmaceutical distribution networks are further supporting market growth.
Supportive Regulatory and Reimbursement Policies
Favorable regulatory advancements and reimbursement frameworks in key markets are making PCOS therapies more accessible and affordable, encouraging more women to seek and adhere to treatment regimens.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Polycystic Ovarian Syndrome PCOS Therapeutics Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Polycystic Ovarian Syndrome PCOS Therapeutics Market projected to grow between 2025 and 2032?
Which Polycystic Ovarian Syndrome PCOS Therapeutics Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Polycystic Ovarian Syndrome PCOS Therapeutics Market?
Who are the leading companies in the Polycystic Ovarian Syndrome PCOS Therapeutics Market?
Which region commanded the largest share of the Polycystic Ovarian Syndrome PCOS Therapeutics Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Oral Contraceptives
- 1.2.2 Insulin Sensitizers
- 1.2.3 Anti-Androgens
- 1.2.4 Ovulation Inducers
- 1.3 By Route of Administration
- 1.3.1 Oral
- 1.3.2 Injectable
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5 billion → 2032: USD 7.82 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5 billion → 2032: USD 7.82 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Oral Contraceptives
- 12.3.7.2 Insulin Sensitizers
- 12.3.7.3 Anti-Androgens
- 12.3.7.4 Ovulation Inducers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Route of Administration - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Oral
- 12.4.7.2 Injectable
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Polycystic Ovarian Syndrome (PCOS) Therapeutics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Abbott Laboratories
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Bayer AG
- 17.4 Merck & Co., Inc.
- 17.5 Sanofi S.A.
- 17.6 Pfizer Inc.
- 17.7 Novartis AG
- 17.8 Teva Pharmaceutical Industries Ltd.
- 17.9 AstraZeneca plc
- 17.10 Bristol Myers Squibb Company
- 17.11 Ferring Pharmaceuticals
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

