
Medical Physics Market Overview:
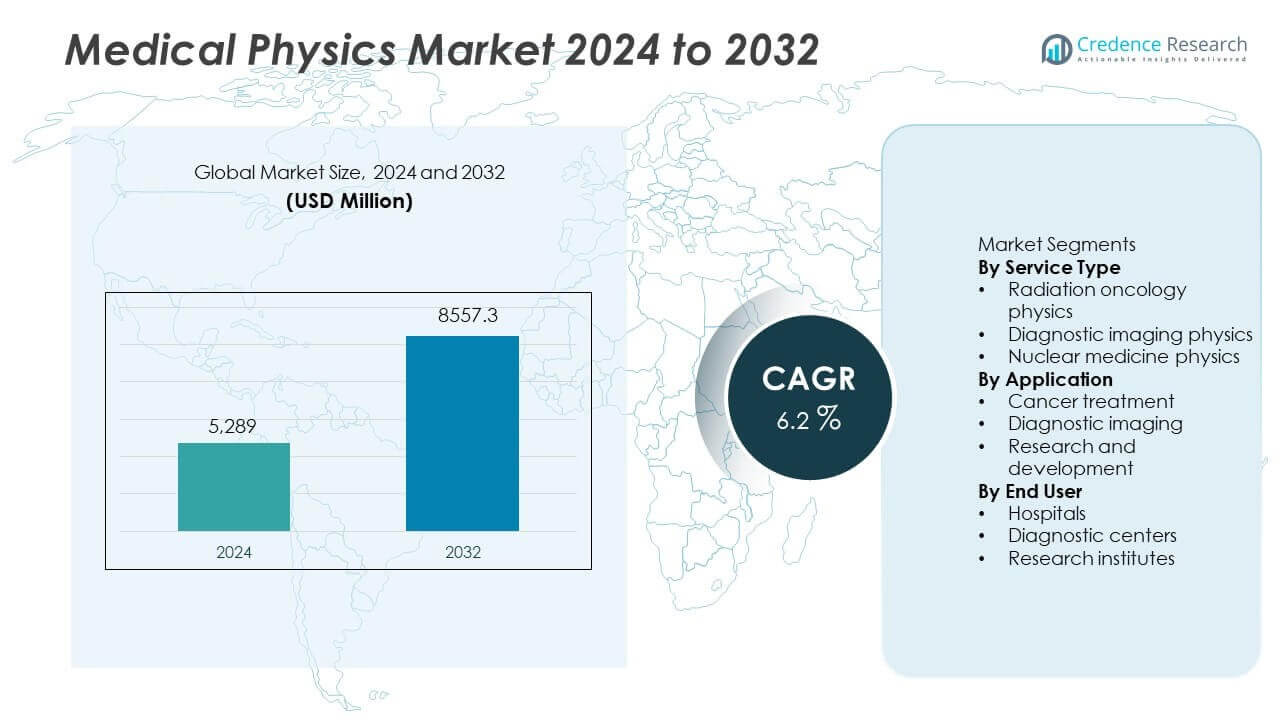
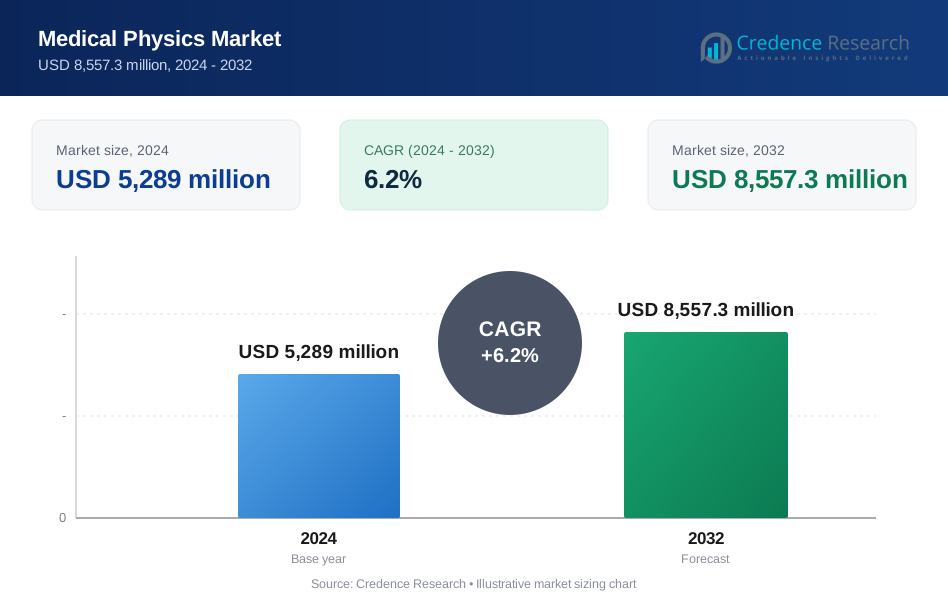
The medical physics market was valued at USD 5,289 million in 2024. The market is projected to reach USD 8,557.3 million by 2032. Growth is expected at a CAGR of 6.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Medical Physics Market Size 2024 | USD 5,289 million |
| Medical Physics Market, CAGR | 6.2% |
| Medical Physics Market Size 2032 | USD 8,557.3 million |
Medical Physics Market Insights
- Rising cancer incidence, higher radiotherapy adoption, and strict radiation safety standards drive medical physics market growth worldwide.
- Radiation oncology physics leads with a 48% segment share, supported by advanced radiotherapy techniques and quality assurance needs.
- Competition remains strong as providers invest in imaging accuracy, software integration, and compliance-focused service models.
- North America leads with a 38% regional share, followed by Europe at 29% and Asia Pacific at 23%, reflecting healthcare infrastructure strength, regulatory focus, and growing technology adoption.
Medical Physics Market Segmentation Analysis:
By Service Type
Radiation oncology physics dominates the medical physics market with a 48% segment share. Cancer treatment relies heavily on accurate dose planning and delivery. Advanced radiotherapy techniques increase demand for specialized physics support. Quality assurance and patient safety requirements strengthen this segment. Diagnostic imaging physics holds a 32% share, driven by rising imaging volumes and equipment calibration needs. Nuclear medicine physics accounts for a 20% share, supported by growth in PET and SPECT procedures. Radiation oncology physics leads due to high procedure criticality and regulatory compliance needs. Continuous technology upgrades further reinforce dominance.
- For instance, Varian Medical Systems supports linear accelerators delivering beam positioning accuracy within 1 millimeter.
By Application
Cancer treatment represents the largest application segment with a 46% market share. Rising global cancer incidence drives sustained demand for precision physics services. Radiotherapy planning, verification, and monitoring depend on medical physicists. Diagnostic imaging holds a 34% share, supported by expanding use of CT, MRI, and hybrid imaging. Research and development accounts for a 20% share, driven by innovation in imaging and therapy techniques. Cancer treatment leads due to complex workflows and strict safety standards. Increasing adoption of advanced radiotherapy technologies further supports segment growth.
- For instance, Accuray Incorporated CyberKnife systems track tumor motion at 25 frames per second.
By End User
Hospitals dominate the end-user segment with a 57% market share. Large patient volumes and integrated care models support in-house physics teams. Hospitals invest in advanced imaging and radiotherapy systems. Diagnostic centers hold a 28% share, driven by outpatient imaging growth. Research institutes account for a 15% share, focused on clinical trials and technology development. Hospital dominance reflects comprehensive oncology and imaging services. Regulatory requirements and accreditation standards further strengthen hospital-based demand for medical physics expertise.
Key Growth Drivers
Rising Global Cancer Incidence and Radiotherapy Demand
Cancer cases continue increasing worldwide. Radiotherapy remains a core treatment option. Medical physics ensures accurate dose calculation and delivery. Advanced techniques raise precision requirements. Patient safety standards drive demand for expert physics services. Hospitals expand oncology departments steadily. Regulatory bodies mandate strict quality assurance. Complex treatment planning increases physicist involvement. Adoption of image-guided therapies supports growth. This driver sustains strong demand across developed and emerging healthcare systems.
- For instance, Elekta AB adaptive radiotherapy platforms recalculate treatment plans in under 60 seconds, increasing demand for real-time physics validation.
Expansion of Diagnostic Imaging and Hybrid Modalities
Imaging volumes grow across healthcare settings. CT, MRI, PET, and SPECT usage increases. Hybrid systems require precise calibration and validation. Medical physicists ensure image quality and radiation safety. Early disease detection raises imaging reliance. Outpatient diagnostic centers expand rapidly. Equipment upgrades demand physics expertise. Compliance with exposure limits strengthens service demand. This driver supports steady growth across imaging-focused applications.
- For instance, Siemens Healthineers PET/CT systems achieve time-of-flight resolution below 400 picoseconds, requiring advanced calibration checks.
Technological Advancements in Radiation Therapy Systems
Radiotherapy technology advances rapidly. Systems become more automated and precise. Techniques require complex commissioning and testing. Medical physicists support system integration. Software-driven planning increases validation needs. Adaptive radiotherapy expands physicist roles. Continuous upgrades drive recurring service demand. Hospitals invest in next-generation platforms. This driver accelerates long-term adoption of specialized physics services.
Key Trends & Opportunities
Growth of Outsourced and Consulting Medical Physics Services
Healthcare providers adopt outsourced physics models. Smaller centers seek cost-efficient expertise. Consulting services ensure compliance and accreditation. Flexible staffing supports workload fluctuations. Remote planning tools enable wider reach. Demand rises in emerging markets. Service providers scale efficiently. This trend creates expansion opportunities for specialized medical physics firms.
- For instance, IBA Dosimetry provides remote dosimetry audits covering photon energies from 4 mega-electron volts to 25 mega-electron volts.
Integration of AI and Advanced Software Tools
AI tools support imaging analysis and treatment planning. Automation improves workflow efficiency. Medical physicists validate algorithm accuracy. Software integration expands physicist responsibilities. Decision support tools enhance precision. Digital transformation accelerates adoption. Training demand increases alongside technology. This trend opens opportunities in validation and quality management services.
- For instance, RaySearch Laboratories planning systems calculate dose distributions using voxel grids exceeding 1 million data points.
Key Challenges
Shortage of Qualified Medical Physics Professionals
Trained medical physicists remain limited globally. Education pathways require long certification periods. Workforce gaps strain healthcare delivery. High workloads increase burnout risks. Rural areas face access challenges. Training costs restrict talent expansion. This challenge limits service scalability and timely implementation.
Regulatory Complexity and Compliance Burden
Medical physics operates under strict regulations. Standards vary across regions. Documentation requirements increase workload. Compliance failures carry high risk. Frequent updates demand continuous training. Smaller facilities struggle with adherence. This challenge increases operational costs and slows service deployment.
Regional Analysis
North America
North America holds a 38% market share in the medical physics market. Advanced healthcare infrastructure supports strong adoption of physics services. High cancer incidence drives radiotherapy demand. Hospitals invest heavily in imaging and radiation technologies. Strict regulatory standards increase reliance on qualified medical physicists. Research funding supports innovation and training programs. Widespread use of advanced radiotherapy techniques boosts service needs. Academic hospitals lead clinical adoption. Strong reimbursement systems support sustained investment. The United States remains the primary contributor due to high procedure volumes and technology penetration.
Europe
Europe accounts for a 29% market share in the medical physics market. Public healthcare systems support widespread imaging and oncology services. Aging populations increase cancer treatment demand. Regulatory frameworks emphasize radiation safety and quality assurance. Hospitals adopt advanced imaging and therapy systems steadily. Research institutes drive innovation in medical physics applications. Cross-border clinical standards improve service consistency. Western Europe leads adoption due to strong healthcare spending. Continuous modernization sustains demand for medical physics expertise across the region.
Asia Pacific
Asia Pacific represents a 23% market share in the medical physics market. Expanding healthcare infrastructure drives growth. Rising cancer incidence increases radiotherapy demand. Governments invest in imaging and oncology capacity. Urban hospitals adopt advanced diagnostic technologies. Workforce training programs expand gradually. Private healthcare growth supports service demand. Medical tourism boosts procedure volumes in key countries. Technology adoption accelerates in developed Asian markets. The region shows strong long-term expansion potential due to large patient populations.
Rest of the World
The rest of the world holds a 10% market share in the medical physics market. Latin America and the Middle East lead regional demand. Healthcare modernization supports imaging and oncology services. Public hospitals expand diagnostic capacity. Regulatory frameworks continue developing. Shortage of trained professionals limits growth pace. International collaborations improve service quality. Private sector investment supports advanced equipment adoption. Gradual awareness of radiation safety increases demand. The region offers emerging opportunities as healthcare access improves.
Medical Physics Market Segmentations:
By Service Type
- Radiation oncology physics
- Diagnostic imaging physics
- Nuclear medicine physics
By Application
- Cancer treatment
- Diagnostic imaging
- Research and development
By End User
- Hospitals
- Diagnostic centers
- Research institutes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights Siemens Healthineers, GE HealthCare, Philips Healthcare, Varian Medical Systems, and Elekta AB as leading participants in the medical physics market. These players compete through advanced imaging systems, radiotherapy platforms, and integrated software solutions. Continuous innovation in dose accuracy, image quality, and patient safety strengthens differentiation. Strong R&D investment supports next-generation diagnostic and therapeutic technologies. Partnerships with hospitals and research institutions enhance clinical adoption. Training programs and technical support improve customer retention. Regulatory compliance and quality assurance remain critical competitive factors. Software-driven planning, AI integration, and workflow automation increase value offerings. Competitive intensity remains high as healthcare providers demand precision, efficiency, and compliance across imaging and radiation therapy services.
Key Player Analysis
- Siemens Healthineers
- GE HealthCare
- Philips Healthcare
- Varian Medical Systems
- Elekta AB
- Canon Medical Systems
- Accuray Incorporated
- IBA Radiopharma Solutions
- RaySearch Laboratories
- Brainlab AG
Recent Developments
- In September 2025, Philips Healthcare introduced Rembra RT and Areta RT CT platforms and the helium-free BlueSeal RT MR system at ASTRO 2025 to improve precision cancer therapy planning and imaging workflows.
- In September 2025, Varian Medical Systems (part of Siemens Healthineers) announced major advancements for its Halcyon treatment platform, focusing on enhanced imaging and cancer care workflows.
- In May 2025, Siemens Healthineers presented the Magnetom Flow RT Pro MRI system tailored for radiation therapy. The system offers helium-independent operation and AI-powered imaging, boosting precision in radiotherapy planning workflows.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Medical Physics market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Medical Physics market projected to grow between 2024 and 2032?
Which Medical Physics market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Medical Physics market?
Who are the leading companies in the Medical Physics market?
Which region commanded the largest share of the Medical Physics market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Medical Physics Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Medical Physics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,289 million → 2032: USD 8,557.3 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Medical Physics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Medical Physics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Medical Physics Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Medical Physics Market Drivers
- 3.3 Medical Physics Market Restraints & Challenges
- 3.4 Medical Physics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Medical Physics Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Medical Physics Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Medical Physics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Medical Physics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Medical Physics Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Medical Physics. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Medical Physics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Medical Physics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Medical Physics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Medical Physics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Medical Physics
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Medical Physics Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Medical Physics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Medical Physics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Medical Physics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Medical Physics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Medical Physics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Medical Physics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Medical Physics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
