
Breast Reconstruction Meshes Market Overview
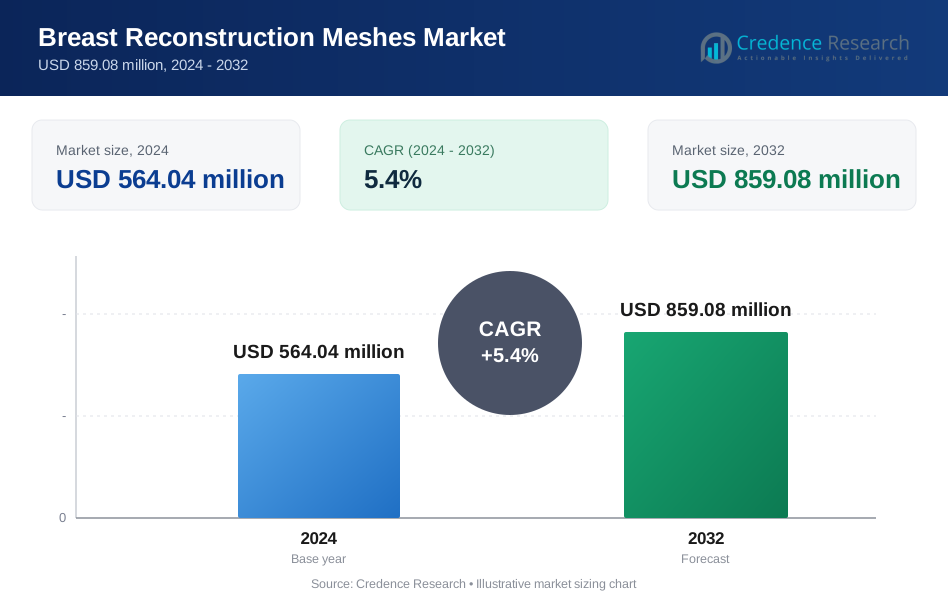
The Breast Reconstruction Meshes Market size was valued at USD 564.04 million in 2024 and is anticipated to reach USD 859.08 million by 2032, at a CAGR of 5.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Breast Reconstruction Meshes Market Size 2024 | USD 564.04 million |
| Breast Reconstruction Meshes Market, CAGR | 5.4% |
| Breast Reconstruction Meshes Market Size 2032 | USD 859.08 million |
The breast reconstruction meshes market is led by prominent players including Allergan Aesthetics, Stryker Corporation, Becton, Dickinson and Company, RTI Surgical, and PolyNovo. These companies maintain strong market positions through expansive product portfolios, technological advancements, and wide geographic reach. Biologic mesh developers such as Cook Biotech, MTF Biologics, and Tissue Regenix are gaining traction in specialized clinical settings. North America dominates the global market, holding over 40% share in 2024, driven by high mastectomy rates, advanced surgical infrastructure, and favorable reimbursement policies. Europe follows with a significant share due to public healthcare support and strong clinical adoption. The competitive landscape is shaped by continuous innovation, strategic partnerships, and regulatory approvals aimed at addressing varied reconstructive needs across regions.

Breast Reconstruction Meshes Market Insights
- The Breast Reconstruction Meshes Market was valued at USD 564.04 million in 2024 and is projected to reach USD 859.08 million by 2032, growing at a CAGR of 5.4%.
- Rising mastectomy rates and post-cancer reconstructive surgeries drive strong demand for surgical mesh products, especially in implant-based procedures.
- Pre-pectoral reconstruction and the adoption of biologic and resorbable meshes reflect a growing trend toward minimally invasive and patient-specific approaches.
- Leading players include Allergan Aesthetics, Stryker, BD, and PolyNovo, with companies focusing on hybrid mesh development and clinical partnerships to expand market share.
- North America holds the highest regional share at over 40%, followed by Europe at 28%; by product, synthetic meshes dominate the market, while implant-based reconstruction leads by application due to procedural ease and favorable outcomes.
Breast Reconstruction Meshes Market Segmentation Analysis:
By Product
The synthetic mesh segment dominates the breast reconstruction meshes market, accounting for the largest share due to its wide availability, cost-effectiveness, and favorable mechanical properties. Among synthetic materials, polypropylene and polyester (PET) are widely used for their strength, durability, and biocompatibility. These meshes are commonly applied in both implant-based and autologous reconstruction procedures. In contrast, biological meshes such as bovine and porcine-derived matrices are gaining interest for their integration with host tissues and reduced inflammatory responses, but remain costlier. Clinical preference for synthetic mesh in routine procedures sustains its leading position in the product landscape.
- For instance, BD’s Bard 3DMax polypropylene surgical mesh demonstrates a tensile strength of approximately 124.7 N/cm, significantly exceeding the physiological requirement of the human abdominal wall (approx. 32 N/cm) and ensuring long-term structural stability after implantation
By Nature
Non-absorbable mesh holds the largest market share among mesh types by nature, driven by its long-term durability and structural support in reconstruction surgeries. These meshes are particularly favored in implant-based procedures where long-lasting reinforcement is critical. Absorbable and resorbable surgical meshes are used when temporary support is sufficient, especially in revision or partial reconstructions. However, they show lower adoption due to concerns about gradual loss of tensile strength. The clear preference for permanent structural support underlines the continued dominance of non-absorbable meshes in clinical practice and procurement trends.
- For instance, Ethicon’s PROLENE™ non-absorbable polypropylene mesh retains tensile strength far exceeding 70 Newtons (typically measured up to 150+ N/cm) after extended implantation periods, supporting long-term implant positioning.
By Application
Implant-based reconstruction is the dominant application in the breast reconstruction meshes market, capturing the highest share due to its shorter surgical time, predictability, and widespread use following mastectomy. Meshes provide vital support in shaping and stabilizing implants, especially in pre-pectoral placement techniques. Autologous tissue reconstruction follows in usage but involves longer recovery and higher surgical complexity. Pre-pectoral and sub-pectoral reconstructions continue to evolve with mesh use to improve aesthetic outcomes and reduce complications. The rising mastectomy rates and advancements in implant-based techniques drive steady growth in this leading application segment.
Breast Reconstruction Meshes Market Key Growth Drivers
Increasing Mastectomy Procedures and Breast Cancer Incidence
The growing number of mastectomy procedures worldwide is a primary driver for breast reconstruction meshes. Rising breast cancer prevalence, especially in women aged 40–70, has pushed demand for reconstructive surgeries that restore form and function post-treatment. According to WHO, breast cancer remains the most diagnosed cancer globally. Reconstructive surgery is often recommended after mastectomy, and meshes provide the structural support needed for implant or flap-based procedures. Improved awareness of reconstruction options and better insurance coverage in many developed nations have further contributed to the rise in elective reconstructive surgeries. This trend continues to support steady mesh adoption across hospitals and surgical centers.
- For instance, the WHO reported more than 2.3 million new breast cancer cases globally in 2022, directly increasing post-mastectomy reconstruction needs.
Advancements in Surgical Mesh Technology
Ongoing innovation in mesh materials and configurations has improved product performance, safety, and clinical outcomes. New-generation meshes offer enhanced biocompatibility, reduced risk of infection, and better integration with host tissues. Hybrid meshes combining synthetic strength with biologic integration have emerged, addressing limitations of earlier solutions. Lightweight, flexible meshes that support pre-pectoral reconstruction are now preferred in aesthetic and oncologic applications. Companies are investing in 3D-printed and resorbable mesh products that reduce long-term complications. These improvements have expanded the surgical indications and increased surgeon confidence in using meshes for primary and revision reconstruction cases.
- For instance, PolyNovo’s NovoSorb biodegradable polymer scaffold supports tissue integration and is designed to fully resorb within 24 months while maintaining early structural support.
Expanding Reconstructive Surgery Infrastructure and Reimbursement Policies
The global healthcare infrastructure for plastic and reconstructive surgery is expanding rapidly, especially in Asia-Pacific and Latin America. More hospitals and specialty clinics now offer breast reconstruction as a standard option post-mastectomy. Government programs and private insurers in countries like the U.S., U.K., Germany, and Japan have broadened coverage for reconstructive procedures. In the U.S., the Women’s Health and Cancer Rights Act mandates insurance coverage for reconstruction after mastectomy. Such policies reduce financial burden on patients and encourage uptake. Increasing availability of trained reconstructive surgeons and growing procedural volumes support sustained demand for breast reconstruction meshes.
Key Trends & Opportunities
Rising Preference for Pre-Pectoral Reconstruction Techniques
Pre-pectoral breast reconstruction is gaining momentum as a less invasive and more comfortable alternative to traditional sub-pectoral approaches. This method involves placing the implant above the pectoral muscle, reducing postoperative pain and animation deformities. Meshes play a critical role in stabilizing implants in this technique, making them essential to its success. Surgeons increasingly prefer pre-pectoral placement due to quicker recovery times and better aesthetic outcomes. As clinical guidelines evolve and surgeon training expands, demand for meshes tailored to this method presents a growing opportunity for manufacturers to launch specialized solutions.
- For instance, AbbVie’s AlloDerm Select acellular dermal matrix is supplied in sizes up to 20 × 16 cm, enabling full implant coverage in pre-pectoral reconstruction.
Shift Toward Biologic and Resorbable Meshes
Though synthetic meshes dominate the market, there is a visible trend toward biologic and resorbable options, especially in high-risk patients. Biologic meshes derived from porcine or bovine tissue are preferred in cases with thin skin flaps or compromised vascularity. These meshes integrate well with host tissues, reducing infection and seroma rates. Resorbable meshes, which gradually degrade after supporting tissue healing, are gaining traction in patients needing temporary support. As pricing becomes more competitive and clinical data supports their use, biologic and resorbable meshes are expected to gain share, particularly in revision surgeries and radiation-exposed reconstructions.
Breast Reconstruction Meshes Market Key Challenges
High Cost of Advanced Meshes and Limited Accessibility
One of the primary challenges in this market is the high cost associated with advanced surgical meshes, particularly biologic and hybrid types. These products are significantly more expensive than traditional synthetic meshes, limiting their use in cost-sensitive healthcare settings. In many low- and middle-income countries, lack of insurance coverage and budget constraints restrict access to high-quality reconstruction materials. Even in developed markets, reimbursement caps and out-of-pocket expenses may deter patients or healthcare providers from opting for premium mesh solutions, creating disparities in care and slowing adoption in some segments.
Risk of Postoperative Complications and Regulatory Scrutiny
Surgical meshes, while beneficial, are not without risks. Complications such as infection, seroma formation, and capsular contracture can arise post-implantation. Some synthetic meshes may also trigger inflammatory responses or fail to integrate effectively in certain patients. These risks have drawn attention from regulatory bodies, especially when linked to off-label use or lack of clinical evidence. Heightened scrutiny by agencies like the FDA has led to recalls and increased documentation requirements. Manufacturers must now invest more in clinical trials and post-market surveillance to meet safety standards, delaying product approvals and increasing development costs.
Breast Reconstruction Meshes Market Regional Analysis
North America
North America holds the largest share in the breast reconstruction meshes market, accounting for over 40% of the global revenue in 2024. High breast cancer incidence, advanced surgical infrastructure, and favorable reimbursement frameworks drive this dominance. The U.S. leads the region due to strong adoption of pre-pectoral and implant-based reconstructions, supported by the Women’s Health and Cancer Rights Act. Surgeons in this region prefer synthetic meshes, but biologic mesh usage is rising in complex cases. Increasing awareness of reconstructive rights and growing demand for aesthetic outcomes further support sustained market expansion across hospitals and specialized clinics.
Europe
Europe captures around 28% of the breast reconstruction meshes market, with Germany, France, and the U.K. leading in procedural volumes. The region benefits from strong public healthcare systems and reimbursement support for post-mastectomy reconstruction. Surgeons widely use both synthetic and biologic meshes based on case complexity. Regulatory emphasis on product safety and surgeon training supports consistent adoption. Rising demand for minimally invasive, muscle-sparing techniques boosts pre-pectoral reconstruction uptake. Europe’s aging population and expanding breast cancer screening programs contribute to procedural growth, sustaining mesh demand across cancer centers, specialty hospitals, and academic institutions.
Asia-Pacific
Asia-Pacific holds approximately 18% market share and is the fastest-growing region in the breast reconstruction meshes market. Countries like Japan, China, South Korea, and Australia show increasing mastectomy and reconstruction rates. Rising breast cancer awareness, improving healthcare access, and growing surgical capacity drive mesh adoption. Japan leads in procedural quality, while China and India see rapid market growth due to expanding healthcare infrastructure. However, limited reimbursement and high mesh costs in developing nations challenge market penetration. Growing medical tourism, surgeon training programs, and patient preference for reconstruction are expected to accelerate regional demand for both synthetic and biologic meshes.
Latin America
Latin America accounts for nearly 8% of the global market, with Brazil, Mexico, and Argentina leading adoption. The region’s growth is driven by improving access to oncology care and increased awareness of reconstruction options post-mastectomy. Private hospitals and urban centers dominate mesh usage, particularly for implant-based procedures. Synthetic meshes are preferred due to affordability, while biologic options are limited to high-end clinics. Government programs supporting breast cancer treatment and the expansion of surgical training improve procedural volumes. However, inconsistent reimbursement and infrastructure gaps in rural areas restrict broader adoption of reconstruction meshes across public healthcare systems.
Middle East & Africa
The Middle East & Africa represent the smallest share of the global market, contributing under 6% in 2024. The market remains underpenetrated due to limited reconstructive surgery capacity and low awareness in several countries. However, the UAE, Saudi Arabia, and South Africa are seeing increased adoption in urban private hospitals. Breast cancer screening programs and cancer center development support gradual growth in mesh usage. Most procedures use synthetic meshes due to cost constraints. International collaborations and medical tourism in the Gulf region help drive demand, though overall adoption remains slower compared to other global regions.
Breast Reconstruction Meshes Market Segmentations:
By Product
- Synthetic Mesh
- Biological Mesh
By Nature
- Absorbable Mesh
- Nonabsorbable Mesh
- Resorbable Surgical Mesh
- Non‑Resorbable Surgical Mesh
By Application
- Implant‑Based Reconstruction
- Autologous Tissue Reconstruction
- Pre‑Pectoral Reconstruction
- Sub‑Pectoral Reconstruction
- Revision Surgeries
- Congenital Asymmetry / Deformity Surgery
By End-User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- Comprehensive Cancer Centers
- Plastic Surgery Clinics
- Academic & Research Institutes
By Geography
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The breast reconstruction meshes market features a moderately fragmented competitive landscape with a mix of multinational corporations and specialized biologics firms. Key players such as Allergan Aesthetics, Stryker Corporation, Becton, Dickinson and Company, and RTI Surgical maintain strong positions through broad product portfolios and global reach. Companies like PolyNovo, MTF Biologics, and Cook Biotech focus on biologic and resorbable mesh innovations, addressing demand for improved biocompatibility and reduced complications. Strategic initiatives such as product launches, regulatory approvals, acquisitions, and regional expansions are common. For instance, firms invest in lightweight, pre-pectoral compatible meshes and hybrid materials to enhance outcomes. Collaborations with hospitals and academic centers help drive clinical validation and surgeon adoption. European companies like SERAG-WIESSNER, Novus Scientific, and PFM medical contribute with regionally focused offerings. Competitive intensity is increasing as emerging firms target niche applications and aesthetic reconstruction. Pricing strategies and product differentiation remain crucial to gaining market share.
Key Player Analysis
- Allergan Aesthetics
- Advanced Biomedical Concept Srl
- Aziyo Biologics
- Becton, Dickinson and Company
- Biomedica
- Cook Biotech
- MedSkin Solutions Dr. Suwelack AG
- MTF Biologics
- Novus Scientific
- PFM medical
- PolyNovo
- RTI Surgical
- SERAG-WIESSNER GmbH & Co. KG
- Stryker Corporation
- Tissue Regenix
- Tutogen Medical GmbH
Recent Developments
- In January 2024, RTI Surgical, an industry-leading contract development and manufacturing organization (CDMO), serving the regenerative medicine industry, announced that it has signed a definitive agreement to acquire Cook Biotech Incorporated, a leader in advanced tissue-repair products from biomaterials, headquartered in West Lafayette, Indiana.
- In 2022, Mentor Worldwide LLC (Johnson & Johnson) received the US FDA approved a new MENTOR Memory Gel boost breast implant.
Report Coverage
The research report offers an in-depth analysis based on Product, Nature, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for breast reconstruction meshes will grow with increasing global breast cancer surgeries.
- Surgeons will adopt more pre-pectoral reconstruction techniques requiring specialized mesh support.
- Biologic and resorbable mesh products will gain traction in complex and high-risk cases.
- Hybrid mesh designs will emerge to combine strength with better tissue integration.
- Regulatory focus on product safety and long-term outcomes will shape approval timelines.
- Manufacturers will invest in clinical studies to support expanded indications and surgeon trust.
- Emerging markets will see increased adoption with rising healthcare infrastructure and awareness.
- Digital surgical planning and 3D-printed mesh technologies may enhance procedural precision.
- Reimbursement expansion for reconstruction procedures will support wider patient access.
- Competitive pressure will drive innovation, price optimization, and product differentiation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Breast Reconstruction Meshes Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Breast Reconstruction Meshes Market projected to grow between 2024 and 2032?
Which Breast Reconstruction Meshes Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Breast Reconstruction Meshes Market?
Who are the leading companies in the Breast Reconstruction Meshes Market?
Which region commanded the largest share of the Breast Reconstruction Meshes Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Breast Reconstruction Meshes Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Breast Reconstruction Meshes Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 564.04 million → 2032: USD 859.08 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Breast Reconstruction Meshes Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Breast Reconstruction Meshes Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Breast Reconstruction Meshes Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Breast Reconstruction Meshes Market Drivers
- 3.3 Breast Reconstruction Meshes Market Restraints & Challenges
- 3.4 Breast Reconstruction Meshes Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Breast Reconstruction Meshes Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Breast Reconstruction Meshes Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Breast Reconstruction Meshes category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Breast Reconstruction Meshes Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Breast Reconstruction Meshes Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Breast Reconstruction Meshes market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Breast Reconstruction Meshes Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Breast Reconstruction Meshes Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Breast Reconstruction Meshes Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Breast Reconstruction Meshes (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Breast Reconstruction Meshes Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Breast Reconstruction Meshes Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Breast Reconstruction Meshes Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Breast Reconstruction Meshes Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Breast Reconstruction Meshes Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Breast Reconstruction Meshes Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Breast Reconstruction Meshes Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Breast Reconstruction Meshes Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Breast Reconstruction Meshes Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
