
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Europe Single Use Assemblies Market Size 2023 | USD 657.69 million |
| Europe Single Use Assemblies Market, CAGR | 11.4% |
| Europe Single Use Assemblies Market Size 2032 | USD 1,740.09 million |
Market Overview:
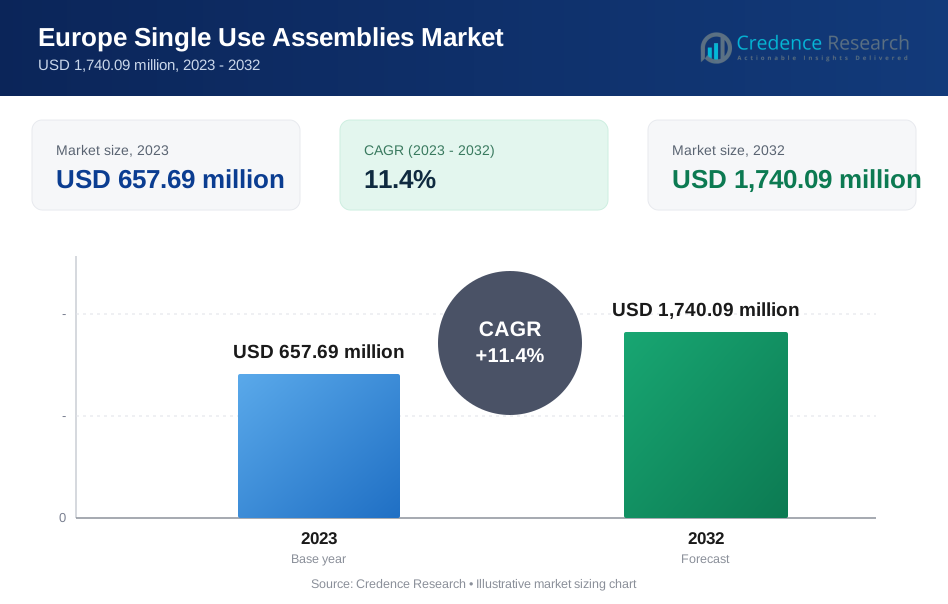
Europe Single Use Assemblies Market size was valued at USD 657.69 million in 2023 and is anticipated to reach USD 1,740.09 million by 2032, at a CAGR of 11.4% during the forecast period (2023-2032).
Several factors are propelling the growth of the single-use assemblies market in Europe. The increasing adoption of biologics and biosimilars necessitates advanced manufacturing technologies, with single-use assemblies offering flexibility, reduced risk of cross-contamination, and lower operational costs compared to traditional stainless-steel systems. Additionally, the surge in research and development activities within the pharmaceutical and biotechnology sectors is driving demand for scalable and efficient production solutions. The streamlined workflows enabled by single-use systems contribute to faster time-to-market for new therapies, further accelerating their adoption. Moreover, the rising number of clinical trials and the expansion of contract manufacturing organizations (CMOs) are increasing the need for adaptable and cost-effective bioprocessing equipment, positioning single-use assemblies as a preferred choice in the industry
Europe is a key player in the global single-use assemblies market, with countries like Germany, the United Kingdom, France, and Spain driving growth. Germany leads the region due to its robust pharmaceutical and biotechnology sectors, which rely heavily on single-use technologies for efficient and scalable biomanufacturing processes. The United Kingdom is also experiencing rapid adoption of single-use systems, supported by its advanced research and development activities in the biopharmaceutical industry. Other European nations, such as France and Spain, are increasingly integrating single-use technologies into their manufacturing processes, benefiting from their ability to reduce costs, enhance flexibility, and improve operational efficiency. The region’s favorable regulatory environment and the presence of leading biopharmaceutical companies further contribute to its growing prominence in the global market. This combination of strong industry demand and regional capabilities positions Europe as a critical hub for the expansion of single-use assembly solutions.
Market Insights:
- The Europe Single Use Assemblies Market was valued at USD 657.69 million in 2023 and is expected to reach USD 1,740.09 million by 2032, growing at a CAGR of 11.4% during the forecast period.
- The Global Single-Use Assemblies Market was valued at USD 2,480.91 million in 2023 and is expected to reach USD 6,991.12 million by 2032, growing at a CAGR of 12.2% from 2023 to 2032.
- Increasing adoption of biologics and biosimilars is driving the demand for flexible, scalable manufacturing solutions, making single-use assemblies an attractive option in Europe.
- Cost efficiency and reduced risk of cross-contamination are key factors pushing the market, as single-use systems eliminate the need for expensive cleaning processes and reduce operational downtime.
- Technological advancements in bioprocessing, including integrated sensors, automation, and real-time monitoring, are enhancing the efficiency and precision of single-use assemblies in biopharmaceutical production.
- The rise in contract manufacturing organizations (CMOs) and the surge in clinical trials across Europe are creating a greater need for scalable, rapid-deployment bioprocessing equipment, further fueling market growth.
- High initial investment costs for implementing single-use technologies remain a challenge, particularly for smaller biopharmaceutical companies transitioning from traditional systems.
- The limited reusability of single-use systems and concerns over waste generation are raising sustainability issues, prompting the development of recyclable and eco-friendly components to meet growing environmental demands.
Report Scope
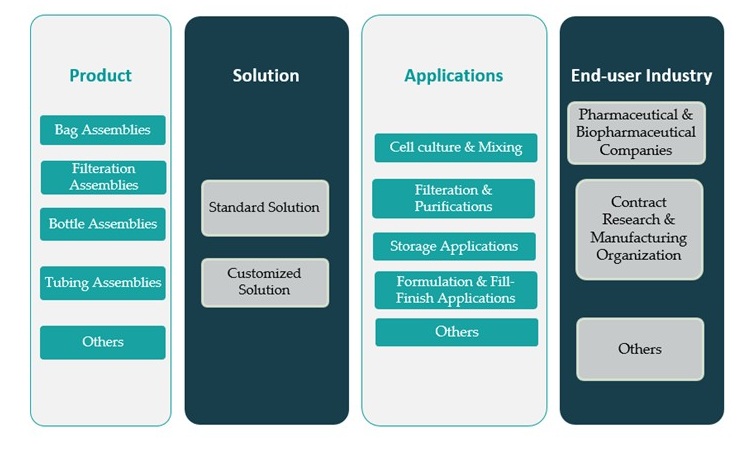
This report segments the Europe Single Use Assemblies Market as follow
Market Drivers:
Increasing Demand for Biologics and Biosimilars
The growing demand for biologics and biosimilars is one of the primary drivers fueling the expansion of the Europe single-use assemblies market. These biologically-derived drugs require highly specialized manufacturing processes that demand flexibility, scalability, and cost-efficiency. Single-use assemblies are increasingly favored in biopharmaceutical manufacturing due to their ability to streamline production while minimizing the risk of cross-contamination between batches. This flexibility is crucial in the production of biologics, where stringent control and rapid adaptation to different product types are essential. With the rising prevalence of chronic diseases and the shift toward personalized medicine, the need for efficient biologic production is set to continue driving the adoption of single-use technologies in Europe.
Cost Efficiency and Reduced Risk of Contamination
Cost efficiency is another key factor driving the market growth. Single-use assemblies offer significant cost advantages over traditional stainless-steel systems, particularly in smaller-scale and multi-product manufacturing environments. These systems eliminate the need for costly cleaning and sterilization processes, reducing both operational expenses and downtime. For instance, in March 2022, Cellexus International launched a single-use mixing system airlift bioreactor designed to help scientists grow delicate cell cultures efficiently and cost-effectively, while maintaining sterility and reducing contamination risks. Furthermore, by minimizing the need for large capital investments in dedicated facilities and equipment, single-use technologies provide a more affordable option for companies. Additionally, these systems significantly reduce the risk of cross-contamination between batches, ensuring a higher level of product integrity and safety. This combination of cost savings and enhanced operational efficiency is making single-use assemblies increasingly attractive to manufacturers across Europe.
Technological Advancements in Bioprocessing
Technological advancements in bioprocessing are accelerating the adoption of single-use assemblies in the European market. For instance, companies such as Sartorius AG have introduced advanced single-use bioreactor systems, including the BIOSTAT STR 1000 launched in March 2022, which features cutting-edge automation and control to meet the growing demand for large-scale bioprocessing. Innovations such as integrated sensors, automation, and real-time monitoring are enhancing the efficiency and precision of single-use systems. These advancements enable greater control over critical manufacturing parameters, improving the overall quality and yield of biopharmaceutical products. Additionally, the development of more sophisticated single-use components, such as filtration units and mixing systems, has expanded the applications of these technologies in various stages of the production process. The continuous evolution of these systems, along with their ability to adapt to new manufacturing demands, is positioning single-use assemblies as the preferred choice in modern biopharmaceutical production facilities.
Rise in Contract Manufacturing Organizations (CMOs) and Clinical Trials
The increasing number of contract manufacturing organizations (CMOs) and the surge in clinical trials in Europe are also contributing to the growth of the single-use assemblies market. CMOs are playing a crucial role in meeting the growing demand for biopharmaceutical production by providing flexible, outsourced manufacturing solutions to smaller and mid-sized biopharma companies. Single-use technologies are particularly well-suited to the needs of CMOs, as they offer scalable and rapid deployment capabilities without the need for large capital investments. Additionally, the rise in clinical trials for new biologics and biosimilars further drives the demand for single-use systems, as these trials often require highly adaptable and efficient manufacturing processes. As the number of clinical trials and CMOs continues to rise, the adoption of single-use assemblies in Europe is expected to grow significantly.
Market Trends:
Expansion of Personalized Medicine
A significant trend in the Europe single-use assemblies market is the growing focus on personalized medicine. With advancements in genomics and biotechnology, the demand for tailored treatments that address individual patient needs has surged. For example, Immunocore’s tebentafusp, a first-in-class TCR therapy for melanoma, exemplifies how personalized approaches are advancing oncology treatment. Single-use systems are particularly well-suited for the production of personalized biologics, as they offer the flexibility to produce small batches of unique products efficiently and cost-effectively. The ability to rapidly adapt manufacturing processes to accommodate different formulations or patient-specific requirements is driving the adoption of single-use assemblies across European pharmaceutical and biotechnology companies. This trend aligns with the broader shift towards more targeted therapeutic approaches, fueling growth in the region.
Integration of Artificial Intelligence and Automation
Another notable trend in the Europe single-use assemblies market is the integration of artificial intelligence (AI) and automation in biomanufacturing processes. For instance, companies like Sanofi have migrated from fragmented legacy systems to unified digital platforms used by more than 30 global teams and 1,500 scientists, enabling seamless data sharing and supporting the company’s ambitions of ‘AI at scale. The increasing use of AI technologies for process optimization, real-time monitoring, and predictive maintenance is enhancing the efficiency and accuracy of single-use systems. Automation helps reduce human error, speed up production cycles, and improve overall product quality. By leveraging AI and automated systems, manufacturers are able to achieve higher levels of consistency and reliability in their biopharmaceutical production. This trend is helping drive operational efficiency and cost savings, making single-use technologies more attractive to biopharma companies throughout Europe.
Sustainability and Environmental Impact
Sustainability is becoming a key trend in the European single-use assemblies market. As environmental concerns grow, there is increasing pressure on the biopharmaceutical industry to adopt more sustainable practices. Single-use systems are already considered an environmentally friendlier option compared to traditional biomanufacturing methods because they reduce the need for cleaning agents and water used in cleaning and sterilization. Moreover, there is a rising focus on developing recyclable and biodegradable single-use components, further reducing the environmental footprint of these systems. As the demand for greener manufacturing solutions increases, the single-use assemblies market in Europe is expected to see a shift toward more sustainable materials and production methods.
Adoption of Hybrid Systems
The growing trend of hybrid systems in biomanufacturing is also impacting the European single-use assemblies market. Hybrid systems combine the flexibility and efficiency of single-use technologies with the reliability of traditional stainless-steel systems. This approach is being increasingly adopted by manufacturers that require a combination of scalability, flexibility, and higher throughput for large-scale production. Hybrid systems offer the ability to scale up production while maintaining the benefits of single-use components for specific processes that demand flexibility. As companies strive to optimize their production capabilities and streamline operations, the adoption of hybrid systems is gaining momentum, further shaping the landscape of the European market for single-use assemblies.
Market Challenges Analysis:
High Initial Investment Costs
One of the key restraints in the Europe single-use assemblies market is the high initial investment costs associated with adopting these technologies. While single-use systems offer significant operational cost savings over the long term, the upfront costs for purchasing and implementing these systems can be substantial. For instance, Merck KGaA’s investment of €130 million in its MilliporeSigma site in Molsheim, France, is the largest in the site’s 50-year history and has been specifically earmarked to boost single-use technology capacity. Biopharmaceutical companies, particularly smaller and mid-sized firms, may find it challenging to justify these initial expenses, especially when transitioning from traditional stainless-steel systems. The financial burden of upgrading facilities to incorporate single-use technologies can act as a barrier to market adoption, limiting the growth potential for some companies within the region.
Limited Reusability and Waste Generation
Another challenge facing the European single-use assemblies market is the limited reusability of these systems, which can contribute to increased waste generation. While single-use technologies offer operational advantages, their disposability raises concerns regarding sustainability. As the demand for eco-friendlier solutions grows, the single-use nature of these systems is often viewed as a disadvantage due to the environmental impact. Manufacturers are under increasing pressure to address these concerns by developing recyclable or biodegradable components, but achieving widespread adoption of such solutions remains a challenge. This issue limits the appeal of single-use systems among companies prioritizing sustainability.
Regulatory and Compliance Challenges
Navigating regulatory and compliance requirements also poses a significant challenge in the European market. The biopharmaceutical industry in Europe is heavily regulated, with stringent guidelines surrounding the manufacturing of biologics and biosimilars. Single-use assemblies must meet these regulatory standards, which can sometimes be a complex and time-consuming process. In some cases, manufacturers may face delays in obtaining the necessary certifications and approvals for new single-use components or systems. These regulatory hurdles can slow the adoption of single-use technologies, particularly in emerging biopharma markets that may be less familiar with these advanced systems.
Integration with Legacy Systems
The integration of single-use technologies with existing legacy systems is another challenge. Many biopharmaceutical companies in Europe continue to operate with traditional, stainless-steel equipment, and integrating single-use systems into these facilities can be technically complex. The compatibility between older infrastructure and newer single-use solutions can require significant adjustments or modifications to existing production lines. This challenge is particularly pronounced for companies that have invested heavily in their legacy systems and may be hesitant to make substantial changes due to the associated costs and operational disruptions.
Market Opportunities:
The Europe single-use assemblies market presents significant opportunities driven by the growing demand for flexible and scalable manufacturing solutions in biopharmaceutical production. As the demand for biologics, biosimilars, and personalized medicine continues to rise, there is an increasing need for cost-effective, adaptable production systems. Single-use assemblies offer the ability to scale production quickly and efficiently, making them an ideal choice for manufacturers looking to meet the growing demand for complex biologic drugs. The expansion of contract manufacturing organizations (CMOs) in Europe further creates opportunities, as these companies require flexible, low-investment solutions to cater to various clients in a cost-effective manner. This trend is expected to drive the adoption of single-use systems, offering manufacturers a unique opportunity to meet evolving market demands without the burden of significant capital expenditures.
Furthermore, the continued focus on sustainability and environmental concerns presents an opportunity for growth in the Europe single-use assemblies market. Manufacturers are increasingly developing recyclable and eco-friendly single-use components to address the growing demand for greener production solutions. As regulatory pressures to adopt environmentally sustainable practices tighten across Europe, companies that can offer innovative, sustainable single-use technologies will gain a competitive edge. The integration of advanced technologies, such as automation and real-time monitoring, within single-use systems is another opportunity. These innovations will not only improve production efficiency but also enhance the overall quality of biopharmaceutical products, creating long-term growth prospects for stakeholders in the European single-use assemblies market.
Market Segmentation Analysis:
The Europe single-use assemblies market is categorized into various segments, offering a comprehensive view of the industry's growth potential.
By product segment, the market is divided into bag assemblies, filtration assemblies, bottle assemblies, tubing assemblies, and others. Among these, bag assemblies dominate due to their versatility in handling liquids, such as media and reagents, during the biopharmaceutical manufacturing process. Filtration assemblies also hold a significant share as they are essential for removing contaminants from biologic products, further supporting the demand for single-use solutions.
By solutions, the market is split between standard and customized solutions. Customized solutions are gaining traction as they provide tailored options for specific biomanufacturing processes, offering better flexibility and efficiency in production. This is particularly relevant in the production of biologics, where process requirements can vary significantly.
By applications segment includes cell culture and mixing, filtration and purification, storage applications, formulation and fill-finish applications, and others. Cell culture and mixing applications are a major driver due to the rising demand for biologic products, which require complex culture systems. Filtration and purification applications are equally important, as they ensure the quality of the end product by removing impurities.
By end-user segment, pharmaceutical and biopharmaceutical companies dominate the market, followed by contract research organizations and contract manufacturing organizations (CMOs), which are increasingly adopting single-use technologies to meet production demands without significant capital investment. Academic and research institutes also contribute to market growth, especially in early-stage drug development and testing. These segments highlight the diverse and expanding applications of single-use assemblies across the European market.
Segmentation:
By Product Segment:
- Bag Assemblies
- Filtration Assemblies
- Bottle Assemblies
- Tubing Assemblies
- Others
By Solution Segment:
- Standard Solutions
- Customized Solutions
By Applications Segment:
- Cell Culture & Mixing
- Filtration & Purifications
- Storage Applications
- Formulation and Fill-Finish Application
- Others
By End-User Segment:
-
- Pharmaceutical & Biopharmaceutical Companies
- Contract Research & Contract Manufacturing Organizations
- Academics & Research Institutes
Regional Analysis:
The Europe single-use assemblies market is characterized by diverse regional dynamics, with key markets including Germany, the United Kingdom, France, and Italy. These regions collectively contribute significantly to the market's growth, driven by the demand for flexible, scalable, and cost-effective manufacturing solutions in the biopharmaceutical sector.
Germany leads the European market, accounting for a substantial share due to its robust pharmaceutical and biotechnology industries. The country’s emphasis on research and development, along with a strong presence of biopharmaceutical manufacturing facilities, makes it a hub for single-use technologies. Germany's market share is estimated at around 27% in 2023. The growth of biologics and biosimilars in the country, coupled with the expansion of contract manufacturing organizations (CMOs), has significantly fueled the adoption of single-use assemblies. As the demand for personalized medicines continues to rise, Germany remains at the forefront of integrating these solutions into its manufacturing processes.
The United Kingdom follows as one of the fastest-growing regions for single-use assemblies, with an expected market share of approximately 20% in 2023. The UK benefits from its strong healthcare infrastructure, research institutions, and biopharma companies, all of which are increasingly turning to single-use technologies for the production of biologics. The growing trend toward personalized medicine and clinical trials further boosts the demand for scalable and flexible biomanufacturing solutions, positioning the UK as a key player in the market.
France and Italy also contribute to the regional growth, with both countries accounting for a combined share of approximately 30%. France's market is driven by its large pharmaceutical industry and expanding contract manufacturing services, while Italy’s adoption of single-use systems is spurred by advancements in biopharmaceutical production and a growing number of small-to-medium-sized enterprises (SMEs) that require flexible manufacturing solutions.
In addition to these major players, other regions within Europe, including Spain and the Benelux countries, are also seeing a rise in the adoption of single-use technologies. These regions benefit from the broader trends in Europe toward more efficient and adaptable biopharmaceutical manufacturing practices. The overall European market is expected to continue its upward trajectory, supported by favorable regulatory environments, technological advancements, and the growing need for sustainable production methods in the biopharmaceutical industry.
Key Player Analysis:
- Sartorius AG
- Merck KGaA
- Corning Incorporated
- Saint-Gobain S.A.
- Avantor, Inc.
- Parker-Hannifin Corporation
- Lonza
- Watson-Marlow Fluid Technology Solutions
- Keofitt A/S
- Cellexus
- Danaher Corporation
- Alpha Plan GmbH
- Entegris
- GE Healthcare
Competitive Analysis:
The Europe single-use assemblies market is characterized by the presence of several prominent players who drive innovation and cater to the growing demand for flexible, cost-effective biomanufacturing solutions. Key industry leaders include Thermo Fisher Scientific, Sartorius AG, Danaher Corporation, Merck KGaA, and Avantor Inc. These companies offer a comprehensive range of products, including bag assemblies, filtration systems, mixing solutions, and customized assemblies, to support various stages of biopharmaceutical production. Their extensive product portfolios, coupled with robust research and development capabilities, enable them to address the diverse needs of the biopharma industry. Strategic collaborations and acquisitions are prevalent among these market leaders as they seek to expand their technological capabilities and market reach. For instance, companies are increasingly focusing on the development of advanced filtration systems and bioprocess containers to enhance product quality and manufacturing efficiency. Additionally, the emphasis on sustainability has led to innovations in recyclable and eco-friendly single-use components, aligning with the industry's shift towards greener manufacturing practices. These strategic initiatives position the leading players to capitalize on the growing adoption of single-use technologies in Europe's biopharmaceutical sector
Recent Developments:
- In September 2022, Merck KGaA announced a major development directly related to the Single Use Assemblies Market by investing more than €130 million to expand its manufacturing capabilities for single-use assemblies at its Molsheim, France facility. This investment is the largest in the site’s 50-year history and is aimed at increasing production capacity for the Mobius® single-use portfolio, which is a key technology for the production of vaccines and lifesaving therapies. The expansion will create more than 800 jobs by the end of 2028 and includes new ISO7 clean rooms, an administrative building, and a logistics warehouse.
- Thermo Fisher Scientific Inc.'s February 2025 agreement to acquire Solventum’s Purification & Filtration business is relevant to the single-use assemblies market. The acquisition will expand Thermo Fisher’s capabilities in purification and filtration, which are core components of single-use assembly systems for biomanufacturing. By broadening its bioproduction portfolio, Thermo Fisher is positioned to meet the increasing demand for modular, flexible, and contamination-reducing single-use solutions in biologics manufacturing.
Market Concentration & Characteristics:
The Europe single-use assemblies market exhibits a moderately concentrated structure, with a few key players dominating the industry while also offering room for smaller companies to innovate and grow. Major companies such as Thermo Fisher Scientific, Sartorius AG, Danaher Corporation, and Merck KGaA hold a significant share of the market, leveraging their extensive product portfolios, strong research and development capabilities, and global reach. These companies are able to drive innovation in single-use technologies, offering advanced solutions such as bag assemblies, filtration systems, and customized components that meet the evolving needs of biopharmaceutical manufacturers. The market is characterized by ongoing technological advancements and high competition, which pushes companies to continuously improve their offerings. Additionally, the increasing demand for flexible, scalable, and cost-effective manufacturing solutions has led to a rising number of contract manufacturing organizations (CMOs) adopting single-use systems, further fueling market dynamics. The market’s competitive landscape is also influenced by trends such as sustainability and eco-friendly innovations.
Report Coverage:
The research report offers an in-depth analysis based on Product Segment, Solution Segment, Applications Segment and End User Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to continue its rapid growth as biopharmaceutical companies increasingly adopt single-use technologies for cost-efficient production.
- Expansion in personalized medicine will drive demand for scalable and flexible manufacturing solutions.
- The increasing focus on sustainability will promote the development of recyclable and eco-friendly single-use components.
- The rise of contract manufacturing organizations (CMOs) will fuel the adoption of single-use systems due to their lower capital investment requirements.
- Technological advancements, such as AI integration and automation, will enhance the efficiency of single-use systems.
- The growing number of clinical trials will further stimulate the demand for flexible, adaptable biomanufacturing solutions.
- European regulatory frameworks will continue to support the adoption of single-use technologies, promoting market growth.
- Advancements in filtration and mixing technologies will drive innovation in the product offerings of leading players.
- Increased R&D spending in the biopharmaceutical sector will contribute to further expansion in the market.
- The emergence of hybrid manufacturing systems combining single-use and traditional technologies will offer new growth opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Europe Single Use Assemblies Market?
What factors are driving the growth of the Europe Single Use Assemblies Market?
What are the key segments within the Europe Single Use Assemblies Market?
Who are the major players in the Europe Single Use Assemblies Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Europe Single Use Assemblies Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Europe Single Use Assemblies Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 657.69 million → 2032: USD 1,740.09 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Europe Single Use Assemblies Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Europe Single Use Assemblies Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Europe Single Use Assemblies Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Europe Single Use Assemblies Market Drivers
- 3.3 Europe Single Use Assemblies Market Restraints & Challenges
- 3.4 Europe Single Use Assemblies Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Europe Single Use Assemblies Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Europe Single Use Assemblies Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Europe Single Use Assemblies category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Europe Single Use Assemblies Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Europe Single Use Assemblies Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Europe Single Use Assemblies market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Europe Single Use Assemblies Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Europe Single Use Assemblies Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Europe Single Use Assemblies Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Europe Single Use Assemblies (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Europe Single Use Assemblies Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Europe Single Use Assemblies Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Europe Single Use Assemblies Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Europe Single Use Assemblies Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Europe Single Use Assemblies Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Europe Single Use Assemblies Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Europe Single Use Assemblies Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Europe Single Use Assemblies Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Europe Single Use Assemblies Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
