
Market Overview
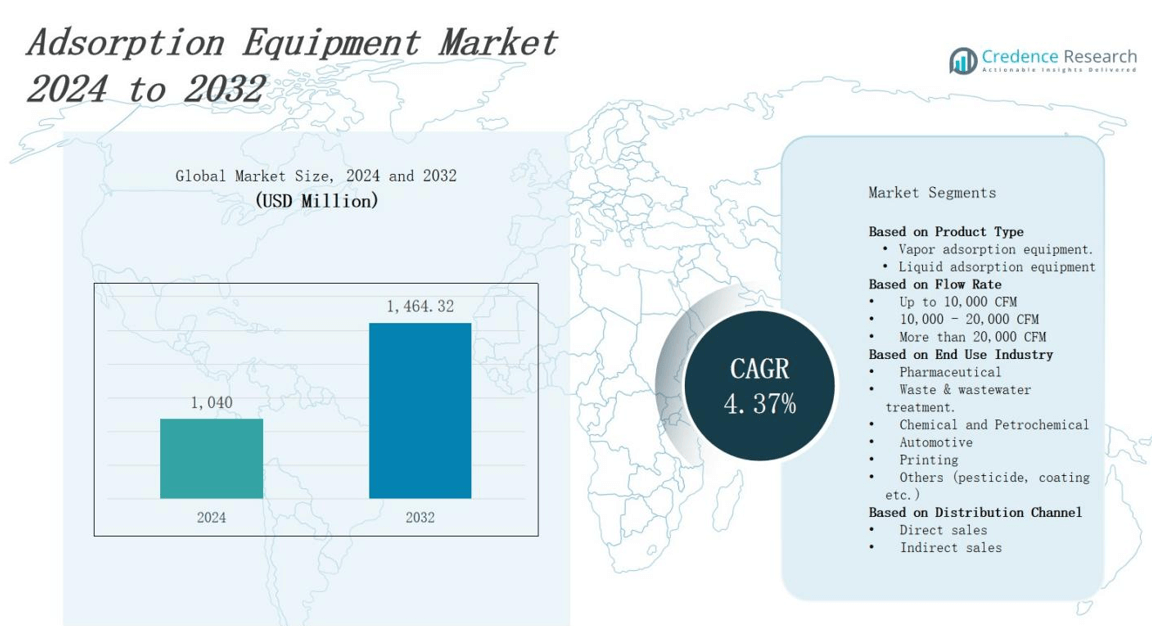
The adsorption equipment market is projected to grow from USD 1,040 million in 2024 to USD 1,464.32 million by 2032, registering a compound annual growth rate (CAGR) of 4.37%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Adsorption Equipment Market Size 2024 | USD 1,040 million |
| Adsorption Equipment Market, CAGR | 4.37% |
| Adsorption Equipment Market Size 2032 | USD 1,464.32 million |
The adsorption equipment market grows steadily driven by increasing demand for efficient gas and liquid purification across industries such as chemical processing, pharmaceuticals, and environmental management. Rising environmental regulations compel companies to adopt advanced adsorption technologies for pollutant removal and waste treatment. Innovations in adsorbent materials enhance performance and operational efficiency, further stimulating adoption. The trend toward sustainable and energy-efficient processes encourages integration of adsorption systems in manufacturing. Additionally, growing applications in water treatment and air purification support market expansion. Continuous advancements and rising industrialization, especially in emerging economies, contribute to sustained market growth and evolving customer preferences.
The adsorption equipment market spans key regions including North America, Europe, Asia-Pacific, and the Rest of the World, each contributing significantly to global demand due to industrial growth and environmental regulations. North America leads with advanced infrastructure, followed closely by Europe’s stringent sustainability policies. Asia-Pacific experiences rapid industrialization and rising pollution control needs, while the Rest of the World shows emerging potential. Leading companies such as Bry-Air, Calgon Carbon, CECO Environmental, Evoqua, and Durr drive innovation and market expansion across these regions through tailored solutions and strategic partnerships.
Market Insights
- The adsorption equipment market is projected to grow from USD 1,040 million in 2024 to USD 1,464.32 million by 2032, registering a CAGR of 4.37%.
- Increasing demand for efficient gas and liquid purification in chemical processing, pharmaceuticals, and environmental management drives steady market growth.
- Rising environmental regulations compel industries to adopt advanced adsorption technologies for pollutant removal and waste treatment.
- Innovations in adsorbent materials enhance performance and operational efficiency, stimulating wider adoption across sectors.
- Expanding applications in water treatment and air purification contribute to market expansion, supported by urbanization and industrialization.
- North America leads with a 32% market share due to stringent regulations and advanced infrastructure, followed by Asia-Pacific at 30% with rapid industrialization.
- Europe holds 28% share, driven by strict environmental policies and investments in green technologies, while the Rest of the World accounts for 10%, showing emerging potential.
Market Drivers
Rising Environmental Regulations Fuel Market Growth
Stringent environmental standards worldwide drive the demand for adsorption equipment market solutions. Industries must reduce emissions and treat waste streams to comply with regulatory mandates. It offers effective removal of pollutants such as volatile organic compounds (VOCs), heavy metals, and hazardous gases from air and water. Increasing government enforcement on air quality and wastewater treatment fuels investments in advanced adsorption systems. Companies seek reliable technologies to meet compliance while minimizing operational costs. This regulatory pressure creates sustained demand for efficient adsorption equipment across multiple sectors.
- For instance, the Tucson Airport Remediation Project (TARP) in Arizona utilizes granular activated carbon (GAC) to remove volatile organic compounds (VOCs) like trichloroethylene (TCE) from contaminated groundwater, meeting strict EPA consent decree requirements for discharge below laboratory detection limits.
Advancements in Adsorbent Materials Enhance Performance
The adsorption equipment market benefits from continuous innovation in adsorbent materials such as activated carbon, zeolites, and metal-organic frameworks (MOFs). These advancements improve adsorption capacity, selectivity, and regeneration capabilities. Enhanced materials reduce energy consumption and extend equipment lifespan. It enables industries to achieve higher purification efficiency and cost-effectiveness. Researchers and manufacturers focus on developing tailored adsorbents for specific applications, increasing system versatility. Superior materials support growth by addressing diverse industrial challenges with optimized solutions.
- For instance, SIFSIX-3-Cu, a metal-organic framework (MOF), has demonstrated exceptionally high CO₂ adsorption capacity at very low pressures, making it promising for direct air capture due to its strong interaction with CO₂ molecules.
Expanding Applications in Water and Air Treatment
Adsorption equipment finds growing application in water purification and air pollution control, boosting market demand. It effectively removes contaminants including organic compounds, heavy metals, and odor-causing substances from drinking and wastewater. The rise in urbanization and industrialization increases the need for clean water and ambient air quality. It also supports industrial processes requiring gas separation and solvent recovery. These varied applications expand the equipment’s role in environmental sustainability efforts. Demand rises with escalating focus on public health and ecological preservation.
Industrial Growth and Emerging Market Opportunities
Rapid industrialization in emerging economies presents significant growth prospects for the adsorption equipment market. Expanding chemical, pharmaceutical, and manufacturing sectors require advanced purification and separation technologies. It helps industries improve product quality, reduce waste, and comply with environmental standards. Growing infrastructure development and increasing investments in pollution control solutions accelerate adoption. Emerging markets seek cost-efficient and scalable adsorption equipment to support sustainable growth. This industrial expansion diversifies end-use applications, driving long-term market potential.
Market Trends
Integration of Advanced Automation and Monitoring Systems
The adsorption equipment market increasingly incorporates automation and real-time monitoring technologies to enhance operational efficiency and reliability. It enables precise control of adsorption cycles, reduces human error, and optimizes resource consumption. Automated systems facilitate predictive maintenance and improve data collection for performance analysis. Companies adopt smart sensors and IoT connectivity to ensure continuous process optimization. This technological integration lowers downtime and operational costs, making adsorption systems more attractive for industrial users focused on productivity and sustainability.
- For instance, Veolia uses automated activated carbon adsorption units in industrial water treatment. Online analytics help adjust regeneration cycles, cutting energy consumption by up to 15% and extending service intervals.
Shift Toward Sustainable and Energy-Efficient Solutions
Sustainability drives innovation within the adsorption equipment market, with a focus on energy-efficient and environmentally friendly technologies. It includes the development of low-energy regeneration methods and reusable adsorbents to reduce overall energy consumption. Industries prioritize equipment that minimizes carbon footprint while maintaining high purification performance. Market players invest in eco-friendly designs and processes to meet growing consumer and regulatory demands for green solutions. This trend enhances competitive advantage and promotes long-term adoption across sectors.
- For instance, Svante Inc. utilizes advanced metal-organic framework (MOF) solid sorbents in their carbon capture technology, providing energy-efficient and high-capacity CO2 adsorption from industrial flue gas while enabling rapid, low-energy regeneration through steam injection.
Customization and Application-Specific Equipment Design
The adsorption equipment market shows a growing trend toward tailor-made solutions designed for specific industrial applications. It enables precise handling of different contaminants and process conditions, improving overall system effectiveness. Manufacturers collaborate closely with clients to develop customized adsorption units that align with unique operational requirements. This approach enhances process integration and reduces waste generation. The demand for specialized equipment supports market growth by addressing the diverse purification and separation needs of various industries.
Expansion of Digital Twin and Simulation Technologies
Adoption of digital twin and simulation technologies marks a significant trend in the adsorption equipment market. It allows virtual modeling of adsorption processes to predict performance, optimize design, and reduce development time. Engineers utilize simulation tools to evaluate different operational scenarios and improve equipment reliability before physical implementation. This trend accelerates innovation cycles and enhances decision-making accuracy. Digital solutions support continuous improvement and operational excellence, boosting the market’s appeal to technologically advanced industries.
Market Challenges Analysis
High Initial Capital Investment and Maintenance Costs Impede Adoption
The adsorption equipment market faces challenges related to significant upfront costs for advanced systems and high-quality adsorbent materials. It requires substantial capital expenditure, which can deter small and medium-sized enterprises from investing. Maintenance and periodic replacement of adsorbents add to operational expenses, affecting the total cost of ownership. Industries often weigh these costs against expected benefits, delaying procurement decisions. Complex installation and integration processes further increase initial investments. These financial barriers limit market penetration in price-sensitive regions and sectors, slowing growth despite technological advantages.
Technical Limitations and Performance Variability Affect Market Expansion
Performance inconsistency of adsorption systems under varying operational conditions creates challenges for the adsorption equipment market. It depends heavily on adsorbent properties, process design, and feed composition, which may fluctuate in industrial environments. Reduced adsorption capacity over time due to fouling or degradation necessitates frequent regeneration or replacement. Certain contaminants resist effective removal, limiting application scope. Technical complexity requires skilled personnel for operation and troubleshooting, posing a barrier in regions with limited expertise. These factors restrict widespread adoption and highlight the need for ongoing innovation to enhance reliability and versatility.
Market Opportunities
Growing Demand for Sustainable Pollution Control Solutions Offers Expansion Potential
The adsorption equipment market stands to benefit from increasing global emphasis on environmental protection and sustainable industrial practices. It supports stringent emission control and wastewater treatment requirements, creating new application avenues. Rising awareness about air and water pollution drives investments in advanced purification technologies. Industries seek cost-effective methods to reduce pollutants and meet evolving regulations. This trend opens opportunities to develop innovative, eco-friendly adsorption systems tailored to specific environmental challenges. Expanding green initiatives and corporate social responsibility programs further stimulate demand across diverse sectors.
Technological Innovations and Emerging Markets Drive Market Growth Prospects
Rapid advancements in adsorbent materials and process technologies provide significant growth opportunities for the adsorption equipment market. It enables development of high-performance, energy-efficient systems suitable for complex industrial processes. Emerging economies present untapped potential due to growing industrialization and infrastructure development requiring effective pollution control. Collaborations between technology providers and end-users accelerate customized solution deployment. Expanding applications in gas separation, solvent recovery, and renewable energy sectors broaden market scope. Continuous innovation and geographic expansion position the market for sustained long-term growth.
Market Segmentation Analysis:
By Product Type
The adsorption equipment market divides into vapor adsorption equipment and liquid adsorption equipment based on product type. Vapor adsorption equipment focuses on removing gaseous contaminants, primarily used in air purification and gas separation applications. Liquid adsorption equipment targets dissolved impurities in liquids, widely applied in water and wastewater treatment. Both segments address distinct purification challenges and drive demand in their respective industries. It enables companies to select appropriate systems depending on process requirements and contamination types, supporting diverse industrial needs.
- For instance, Thermax supplied vapor absorption chillers for the Gardens by the Bay project in Singapore, providing tailored and energy-efficient cooling solutions that integrated well with sustainable building goals.
By Flow Rate
Segments based on flow rate include up to 10,000 CFM, 10,000–20,000 CFM, and more than 20,000 CFM. The up to 10,000 CFM category serves small to medium-scale operations requiring compact and efficient adsorption units. The 10,000–20,000 CFM segment targets mid-sized industrial applications with moderate purification demands. Large-scale operations with high volumetric flows utilize systems exceeding 20,000 CFM for extensive pollutant removal. It reflects market demand variation depending on industrial scale and process intensity, guiding product development and customization.
- For example, Global Industrial’s Commercial Air Scrubber offers 3300 CFM with HEPA filtration and can be combined in multiples for up to triple capacity, providing scalable air quality solutions for industrial environments.
By End Use Industry
The adsorption equipment market caters to pharmaceutical, waste and wastewater treatment, chemical and petrochemical, automotive, printing, and other industries such as pesticide and coating manufacturing. Pharmaceuticals rely on precise purification to maintain product quality and safety. Wastewater treatment facilities use adsorption to meet environmental discharge standards. Chemical and petrochemical sectors employ it for gas and liquid separation to optimize processes. Automotive and printing industries use adsorption for solvent recovery and emission control. Diverse applications across industries sustain market growth and broaden technology adoption.
Segments:
Based on Product Type
- Vapor adsorption equipment.
- Liquid adsorption equipment
Based on Flow Rate
- Up to 10,000 CFM
- 10,000 - 20,000 CFM
- More than 20,000 CFM
Based on End Use Industry
- Pharmaceutical
- Waste & wastewater treatment.
- Chemical and Petrochemical
- Automotive
- Printing
- Others (pesticide, coating etc.)
Based on Distribution Channel
- Direct sales
- Indirect sales
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of 32% in the adsorption equipment market, driven by stringent environmental regulations and advanced industrial infrastructure. It leads in adopting cutting-edge adsorption technologies for air and water purification in chemical, pharmaceutical, and manufacturing sectors. The region’s strong focus on sustainability and emission control fuels demand for efficient equipment. Well-established research and development activities accelerate innovation and product improvement. Growing government incentives encourage companies to invest in pollution control solutions. It remains a key market due to high industrial output and regulatory compliance requirements.
Europe
Europe accounts for 28% of the adsorption equipment market, supported by strict environmental policies and growing investments in green technologies. It maintains leadership in wastewater treatment and industrial emission control applications. The European Union’s commitment to carbon reduction and water quality standards propels demand for adsorption systems. It benefits from a mature industrial base and widespread adoption of eco-friendly processes. Expansion in pharmaceutical and chemical industries also drives equipment sales. Focus on circular economy principles encourages the use of energy-efficient and recyclable adsorption materials, reinforcing market growth.
Asia-Pacific
Asia-Pacific holds 30% of the adsorption equipment market, reflecting rapid industrialization and urbanization in emerging economies such as China and India. It experiences increasing demand for pollution control due to rising environmental concerns and regulatory tightening. Growing chemical, petrochemical, and pharmaceutical sectors create substantial market opportunities. Infrastructure development and government initiatives targeting clean water and air quality boost equipment adoption. Cost-effective manufacturing and expanding industrial base attract investment in adsorption technologies. It represents a fast-growing market with considerable potential for long-term expansion.
Rest of the World
The Rest of the World contributes 10% to the adsorption equipment market, driven by gradual industrial development and increasing awareness of environmental sustainability. Regions such as Latin America and the Middle East focus on improving water treatment and emission control standards. Growing industrial activities and government regulations encourage adoption of advanced purification technologies. Limited but expanding infrastructure investment creates new opportunities for adsorption equipment manufacturers. It remains a developing market with potential for growth as environmental priorities gain prominence globally.
Key Player Analysis
- Munters
- Carbtrol
- Calgon Carbon
- Process Combustion Corporation
- General Carbon
- KCH
- CECO Environmental
- Durr
- Evoqua
- GUNT
- Bry-Air
- Microtrac
Competitive Analysis
The adsorption equipment market features intense competition among established global and regional players focusing on innovation, quality, and customer service. Key companies such as Bry-Air, Calgon Carbon, CECO Environmental, Evoqua, and Durr invest heavily in research and development to enhance adsorption efficiency and energy savings. It prioritizes expanding product portfolios and customizing solutions to meet diverse industrial needs. Strategic collaborations and acquisitions enable market leaders to strengthen their geographical presence and technological capabilities. Companies also emphasize sustainability by developing eco-friendly adsorbents and energy-efficient systems. Customer-centric approaches, including after-sales support and maintenance services, contribute to competitive differentiation. Emerging players focus on niche applications and cost-effective equipment to capture regional demand. The adsorption equipment market remains dynamic, driven by continuous technological advancements and shifting regulatory requirements, compelling companies to maintain agility and innovation to secure market share.
Recent Developments
- In April 2023, Munters expanded its portfolio by acquiring Thermal Care, enhancing its presence in North America and strengthening offerings in adsorption-based industrial cooling technologies.
- In May 2023, Xylem completed its $7.5 billion acquisition of Evoqua Water Technologies, strengthening its position in the water technology sector.
- In July 2024, Munters signed an agreement to acquire Geoclima, an Italian manufacturer of air- and water-cooled chillers, expanding its data center cooling solutions portfolio.
- In October 2024, CECO Environmental acquired WK Asia-Pacific Environmental Pte Ltd., enhancing its capabilities in industrial air pollution control and air quality solutions.
Market Concentration & Characteristics
The adsorption equipment market exhibits a moderately concentrated competitive landscape, with several established players dominating key regions and applications. It features a mix of global corporations and specialized regional manufacturers that focus on innovation, quality, and customized solutions. Leading companies invest heavily in research and development to improve adsorbent materials and system efficiency, enhancing product differentiation. The market emphasizes sustainable technologies and energy-efficient processes, aligning with increasing environmental regulations. It experiences steady demand across diverse industries including pharmaceuticals, chemical processing, and wastewater treatment. Smaller players often target niche applications or cost-effective solutions for emerging markets. The adsorption equipment market’s characteristics include ongoing technological advancements, strategic partnerships, and focus on customer-specific needs, driving competitive advantage and market expansion. This dynamic environment encourages continuous innovation to address evolving industrial and regulatory challenges
Report Coverage
The research report offers an in-depth analysis based on Product Type, Flow Rate, End-Use Industry, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Environmental regulations will drive increased adoption of adsorption equipment across multiple industrial sectors globally.
- Energy-efficient adsorption systems will become essential for companies aiming to reduce operational costs and emissions.
- Advanced adsorbent materials will enhance purification efficiency and extend the lifespan of adsorption equipment.
- Growth in water treatment and air purification sectors will significantly boost demand for adsorption technologies.
- Emerging markets in Asia-Pacific and Latin America will offer lucrative opportunities for equipment manufacturers.
- Customized adsorption solutions will address specific industrial challenges, improving process performance and reliability.
- Automation and IoT integration will optimize adsorption system monitoring, reducing downtime and maintenance needs.
- Strategic partnerships between technology developers and end-users will accelerate product innovation and deployment.
- New market entrants will focus on affordable, scalable adsorption solutions targeting small and medium enterprises.
- Expanding applications in renewable energy and chemical processing will diversify the adsorption equipment market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Environmental Regulations
Stringent global environmental standards are compelling industries to adopt advanced adsorption equipment for pollutant removal and waste treatment, ensuring compliance and minimizing emissions of hazardous substances.
Advancements in Adsorbent Materials
Continuous innovation in adsorbent materials such as activated carbon, zeolites, and metal-organic frameworks is enhancing adsorption capacity, selectivity, and regeneration, making systems more efficient and cost-effective.
Expanding Applications in Water and Air Treatment
Growing needs for clean water and improved air quality, especially in urban and industrial areas, are driving the adoption of adsorption equipment for removing contaminants from both water and air streams.
Industrial Growth in Emerging Markets
Rapid industrialization in regions like Asia-Pacific and Latin America is increasing demand for scalable and efficient purification technologies, creating new opportunities for adsorption equipment manufacturers.
Integration of Automation and IoT
The adoption of automation and real-time monitoring technologies in adsorption systems is improving operational efficiency, reducing downtime, and enabling predictive maintenance, making these solutions more attractive for industrial users.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for adsorption equipment market, and what is its projected size in 2032?
Which adsorption equipment market segment held the largest share in 2024?
Who are the leading companies in the adsorption equipment market?
Which region commanded the largest share of the adsorption equipment market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Flow Rate
- 1.2.1 Up to 10,000 CFM
- 1.2.2 10,000 - 20,000 CFM
- 1.2.3 More than 20,000 CFM
- 1.3 By Product Type
- 1.3.1 Vapor adsorption equipment
- 1.3.2 Liquid adsorption equipment
- 1.4 By End Use Industry
- 1.4.1 Pharmaceutical
- 1.4.2 Waste & wastewater treatment
- 1.4.3 Chemical and Petrochemical
- 1.4.4 Automotive
- 1.4.5 Printing
- 1.4.6 Others (pesticide, coating, etc.)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,040 million → 2032: USD 1,464.32 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Adsorption Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Adsorption Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Adsorption Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Adsorption Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Adsorption Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Adsorption Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Adsorption Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Adsorption Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,040 million → 2032: USD 1,464.32 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Adsorption Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Flow Rate - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Up to 10,000 CFM
- 12.3.7.2 10,000 - 20,000 CFM
- 12.3.7.3 More than 20,000 CFM
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Vapor adsorption equipment
- 12.4.7.2 Liquid adsorption equipment
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pharmaceutical
- 12.5.7.2 Waste & wastewater treatment
- 12.5.7.3 Chemical and Petrochemical
- 12.5.7.4 Automotive
- 12.5.7.5 Printing
- 12.5.7.6 Others (pesticide, coating, etc.)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Adsorption Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Adsorption Equipment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Adsorption Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Adsorption Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bry-Air
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Calgon Carbon
- 18.4 CECO Environmental
- 18.5 Evoqua
- 18.6 Durr
- 18.7 Munters
- 18.8 Carbtrol
- 18.9 Process Combustion Corporation
- 18.10 General Carbon
- 18.11 KCH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

