
Androgen Deprivation Therapy Market Overview:
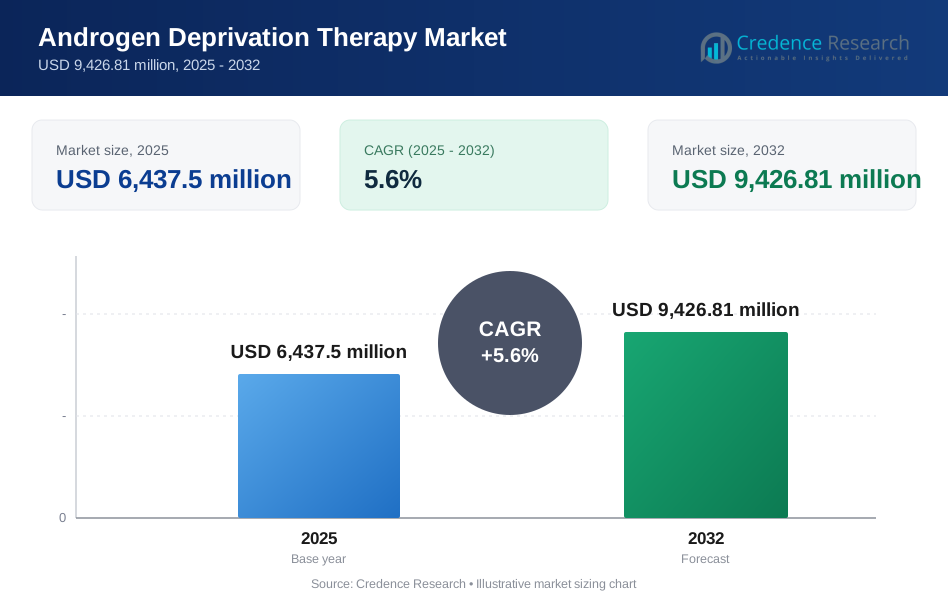
The Androgen Deprivation Therapy Market is projected to grow from USD 6,437.5 million in 2025 to an estimated USD 9,426.81 million by 2032, with a compound annual growth rate (CAGR) of 5.6% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Androgen Deprivation Therapy Market Size 2025 | USD 6,437.5 million |
| Androgen Deprivation Therapy Market, CAGR | 5.6% |
| Androgen Deprivation Therapy Market Size 2032 | USD 9,426.81 million |
Market drivers include rising prostate cancer diagnoses, early screening, and broader acceptance of next-generation hormonal agents that improve disease control. Physicians prefer advanced androgen receptor–targeted therapies due to their superior outcomes in metastatic and castration-resistant stages. Growing emphasis on long-term therapy management increases healthcare utilization across hospitals and specialty clinics. Improved clinical guidelines support wider use of combination regimens, while digital monitoring tools enhance patient adherence. The market continues to expand as more patients gain access to advanced ADT options.
Regional growth varies across major healthcare markets. North America leads due to strong diagnostic infrastructure, established oncology networks, and structured reimbursement systems that support long-term therapy use. Europe follows closely, driven by standardized clinical protocols and broad adoption of advanced hormonal therapies. Asia Pacific is emerging rapidly as awareness increases, oncology centers expand, and aging populations elevate treatment needs. Latin America and the Middle East show steady progression supported by improving cancer care capacity and rising availability of branded and generic treatment options.

Androgen Deprivation Therapy Market Insights:
- The Androgen Deprivation Therapy Market is projected to grow from USD 6,437.5 million in 2025 to USD 9,426.81 million by 2032, supported by a 5.6% CAGR during the forecast period.
- Rising prostate cancer incidence, improved screening, and strong adoption of advanced hormonal therapies drive consistent market expansion across early and advanced disease stages.
- Limited long-term efficacy in resistant cases, safety concerns linked to hormonal suppression, and access gaps in cost-sensitive regions act as key restraints on broader adoption.
- North America leads due to strong diagnostics, oncology infrastructure, and reimbursement support, while Europe maintains stable growth through standardized clinical pathways.
- Asia Pacific emerges as the fastest-growing region due to expanding healthcare capacity, rising awareness, and increasing uptake of both oral and injectable ADT options.
Androgen Deprivation Therapy Market Drivers
Rising Prostate Cancer Burden and Expanding Use of Advanced Hormonal Therapies
The Androgen Deprivation Therapy Market grows due to a sharp rise in prostate cancer cases across aging populations. Early screening programs improve detection and increase therapy demand across disease stages. Clinicians favor hormonal therapy due to strong evidence supporting better disease control. New androgen receptor inhibitors strengthen treatment outcomes in resistant cases. Oral GnRH antagonists support higher adherence and reduce clinic visits. Long-acting depot formulations improve dosing convenience for patients. Broader reimbursement support accelerates adoption across major regions. The market gains momentum through strong clinical confidence in therapy results.
- For instance, AbbVie’s Lupron Depot (leuprolide acetate) continues to serve as a clinical benchmark, with its 7.5 mg one-month formulation demonstrating the ability to maintain testosterone suppression below castrate levels (<50 ng/dL) in 94% of patients throughout the duration of treatment.
Shift Toward Combination Regimens and Improved Treatment Sequencing
Combination regimens drive strong demand due to superior survival outcomes in advanced disease. Many oncologists use ADT with chemotherapy, radiotherapy, or targeted therapies to enhance disease control. Expanded guideline recommendations improve acceptance across care settings. Treatment sequencing strategies evolve to delay resistance and extend patient quality of life. Oral agents support flexible therapy planning for clinicians. New evidence from clinical trials strengthens the role of multi-drug approaches. Hospitals adopt standardized pathways that boost therapy consistency. The Androgen Deprivation Therapy Market benefits from improved alignment between clinical data and treatment protocols.
Growing Adoption of Oral Therapies and Long-Term Treatment Requirements
Oral antagonists support rapid uptake due to ease of use and predictable testosterone suppression. Patients prefer oral agents for reduced clinic visits and better lifestyle fit. Long-term disease management increases treatment duration across large patient groups. Non-metastatic and metastatic castration-resistant cases require ongoing hormonal therapy. Expanded use in combination with next-generation agents strengthens daily demand. Drug makers invest in patient support programs that improve adherence. Digital tools help monitor treatment response and safety. The market gains stability from a large base of long-term therapy users.
- For instance, in the HERO Phase 3 study, Myovant Sciences reported that relugolix achieved a 96.7% sustained testosterone suppression rate over 48 weeks, while also providing a 90-day recovery period where testosterone levels returned to normal in 54% of patients after treatment discontinuation.
Increasing Investment in Oncology Infrastructure and Wider Physician Adoption
Oncology networks expand capacity for hormonal therapy delivery through new outpatient centers. Physicians adopt advanced hormonal agents due to improved safety and tolerability profiles. Training programs help new clinicians integrate ADT into prostate cancer pathways. Health systems update formularies to include next-generation agents. Evolving reimbursement policies reduce patient burden and increase therapy reach. Research institutions expand trial activity to validate new treatment approaches. Many providers select standardized ADT regimens for operational efficiency. The Androgen Deprivation Therapy Market grows through stronger institutional support for hormonal care.
Androgen Deprivation Therapy Market Trends
Growth of Precision Medicine and Biomarker-Driven Hormonal Therapy Selection
Precision medicine shapes therapy planning through biomarker use and genetic profiling. Physicians assess tumor characteristics to refine hormonal therapy choices. New diagnostic tools support tailored care and better treatment sequencing. Biomarker insights help identify patients likely to respond to targeted combinations. Research in genomic markers enhances understanding of resistance patterns. Laboratories integrate advanced tests into routine prostate cancer evaluation. Health systems support personalized care strategies across oncology clinics. The Androgen Deprivation Therapy Market reflects rising demand for individualized therapy plans.
Increase in Oral Formulations and Home-Based Treatment Models
Oral formulations expand access for patients seeking flexible treatment options. Many health systems encourage home-based care to reduce facility visits. Remote monitoring tools help clinicians track testosterone suppression levels. Drug makers develop oral agents with improved safety profiles. Mobile health platforms help patients manage long-term therapy schedules. Pharmacies strengthen support programs to simplify treatment continuation. Physicians value oral solutions for streamlined care pathways. The market benefits from a shift toward low-burden therapy models.
- For instance, Sumitomo Pharma and Myovant Sciences launched Orgovyx (relugolix), which achieved a 54% lower risk of major adverse cardiovascular events compared to leuprolide injections, while maintaining castrate levels of testosterone in 96.7% of patients during the HERO Phase 3 trial.
Expansion of Combination Studies Involving Radioligand and Immunotherapy Agents
Research programs accelerate trials combining hormonal therapy with radioligand or immunotherapy agents. Combination designs aim to enhance tumor targeting and improve survival. Clinical centers adopt new trial frameworks to study synergistic effects. Regulators support pathways that allow faster evaluation of innovative regimens. Radioligand therapies gain visibility due to strong precision-targeting potential. Immunotherapy interest rises for advanced prostate cancer with complex biology. Research networks collaborate globally to validate outcomes. The Androgen Deprivation Therapy Market aligns with broader oncology innovation cycles.
- For instance, Novartis’ PSMAddition Phase III trial evaluates the combination of Pluvicto (lutetium Lu 177 vipivotide tetraxetan) with standard ADT, aiming to build on the 38% reduction in risk of death demonstrated in earlier radioligand therapy trials for metastatic castration-resistant prostate cancer.
Growing Availability of Generics and Biosimilars Across Key Drug Classes
Generic and biosimilar versions of key hormonal agents expand access across cost-sensitive regions. Payers support value-based decisions that prioritize affordability. Hospitals adjust formularies to include lower-cost ADT options. Competitive pricing encourages broader adoption in developing markets. Manufacturers invest in quality and compliance to secure market presence. Pharmacies improve distribution networks to support uninterrupted supply. Clinicians maintain confidence in generics due to strong regulatory oversight. The market reflects steady growth driven by improved affordability.
Androgen Deprivation Therapy Market Challenges Analysis
Complex Resistance Patterns and Limited Long-Term Efficacy of Existing Therapies
The Androgen Deprivation Therapy Market faces growing challenges due to complex resistance mechanisms that reduce therapy effectiveness over time. Many patients progress to castration-resistant disease despite strong initial response. Clinicians struggle to predict who will experience early resistance. Limited therapeutic durability increases the need for combination approaches. Long-term hormone suppression can affect quality of life and raise safety concerns. Drug developers face pressure to create agents with stronger resistance-modifying effects. Treatment complexity increases due to evolving sequencing requirements. It must address rising clinical uncertainty through better evidence.
High Treatment Costs and Uneven Access Across Global Healthcare Systems
The market faces financial barriers that restrict therapy access across developing regions. Many health systems struggle to cover advanced hormonal agents due to limited budgets. Insurance gaps hinder adoption for patients requiring long-term therapy. Hospitals experience procurement challenges that delay steady supply. Pricing differences across regions affect standardization of care. Physicians face difficulty balancing advanced options with affordability concerns. Patients in rural areas face access gaps due to limited oncology infrastructure. The Androgen Deprivation Therapy Market must overcome economic and structural barriers to support wider treatment adoption.
Androgen Deprivation Therapy Market Opportunities
Emergence of Novel Mechanisms Targeting Resistance Pathways and Tumor Biology
The Androgen Deprivation Therapy Market holds strong potential through development of agents that target resistance-driven tumor pathways. Research teams explore next-generation receptor blockers with improved potency and specificity. Early-stage candidates aim to delay castration-resistant progression. Radioligand combinations offer new directions for tumor control. Immunotherapy integration creates further opportunity for synergistic treatment design. Pharmaceutical companies invest heavily in advanced R&D pipelines. Clinical networks accelerate trials to validate promising scientific avenues. It stands to benefit from innovation across multiple therapeutic fronts.
Rising Demand in Emerging Regions Due to Expanding Oncology Infrastructure
Emerging regions create growth opportunities through strengthening cancer care ecosystems. Governments invest in diagnostic networks that support earlier detection. Hospitals adopt advanced hormonal therapies due to improved resource availability. Training programs help clinicians integrate new treatment algorithms. Pharmaceutical firms expand market reach through pricing strategies and patient assistance programs. Regional awareness campaigns increase treatment uptake for prostate cancer. Rural outreach programs improve access to long-term therapy. The Androgen Deprivation Therapy Market gains momentum through rising healthcare investment in developing economies.
Androgen Deprivation Therapy Market Segmentation Analysis:
By Type
The Androgen Deprivation Therapy Market strengthens its position through wide adoption of LHRH agonists and antagonists that support reliable testosterone suppression across early and advanced disease stages. Anti-androgens and androgen biosynthesis inhibitors expand therapeutic control for resistant cases. Estrogen-based therapies maintain limited use due to safety concerns but remain relevant in select settings. Surgical castration delivers permanent suppression and sees use in regions with limited access to advanced drugs. Each therapy type supports different clinical needs, and it maintains steady demand through guideline-backed treatment pathways.
- For instance, Ferring Pharmaceuticals’ GnRH antagonist degarelix demonstrated rapid hormonal suppression, achieving castrate testosterone levels (≤0.5 ng/mL) in 96% of patients within three days of the first dose.
By Drug Class
The Androgen Deprivation Therapy Market shows strong traction for gonadotropin-releasing hormone analogues due to broad clinical acceptance and predictable outcomes. Anti-androgens help block receptor activity and support combination strategies for advanced disease. Androgen biosynthesis inhibitors offer deeper hormonal suppression for patients who require intensified therapy. Estrogen-based therapies occupy a small share but provide options in cost-sensitive regions. Each drug class contributes to clinical flexibility, and it supports diverse treatment protocols across oncology networks.
By Route of Administration
The Androgen Deprivation Therapy Market continues to rely on injectable formulations that provide long-acting suppression and reduce dosing frequency. Many oncology centers prefer injectables due to ease of administration and strong adherence. Oral therapies gain momentum through improved convenience and rising preference for home-based care models. Physicians use oral agents to support flexible treatment schedules and better quality of life. Each route plays a distinct role in care delivery, and it expands patient access across varied healthcare settings.
- For instance, Myovant Sciences achieved a milestone with the FDA approval of relugolix, the first oral GnRH receptor antagonist, which maintained testosterone suppression to castrate levels (<50 ng/dL) through 48 weeks in 96.7% of men
By Application
The Androgen Deprivation Therapy Market is driven mainly by prostate cancer treatment, which accounts for most therapy use due to high global prevalence. Hormonal therapy remains a core component across metastatic, recurrent, and non-metastatic disease stages. Other applications include off-label use in conditions requiring hormonal suppression. Prostate cancer maintains firm dominance, and it guides research and clinical advancement across hormonal therapy landscapes.
By End-User
The Androgen Deprivation Therapy Market sees high adoption in hospitals where oncology teams manage complex and advanced cases. Specialty clinics support steady use for long-term hormonal management and routine follow-ups. Other end-users, including outpatient centers, expand access for patients seeking convenient care models. Each setting contributes to therapy continuity, and it ensures broad market reach across diverse treatment pathways.
Androgen Deprivation Therapy Market Segmentation:
By Type
- LHRH Agonists
- LHRH Antagonists
- Anti-androgens
- Androgen Biosynthesis Inhibitors
- Estrogen-based Therapies
- Surgical Castration (Orchiectomy)
By Drug Class
- Gonadotropin-Releasing Hormone Analogues (GnRHas)
- Anti-androgens
- Androgen Biosynthesis Inhibitors
- Estrogen-based Therapies
By Route of Administration
- Injectable
- Oral
By Application
- Prostate Cancer
- Other Applications
By End-User
- Hospitals
- Specialty Clinics
- Other End-users
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Androgen Deprivation Therapy Market Regional Analysis:
North America holds the largest share of the Androgen Deprivation Therapy Market due to strong diagnostic capacity, high prostate cancer awareness, and broad reimbursement support. The region benefits from early adoption of LHRH antagonists and next-generation androgen receptor–targeted therapies. Health systems maintain structured oncology pathways that improve treatment consistency. Pharmaceutical companies introduce new hormonal agents rapidly due to favorable regulatory processes. Hospitals and specialty clinics support long-term therapy use through established care networks. The market grows steadily, and it strengthens leadership through strong clinical and commercial infrastructure.
Europe secures the second-largest share of the Androgen Deprivation Therapy Market with mature oncology systems and high compliance with clinical guidelines. Countries in Western Europe maintain strong adoption of injectable and oral hormonal therapies. Physicians follow standardized ADT protocols across both early and advanced stages. Increased investment in precision oncology supports better treatment selection. Regional health agencies encourage access to generics and biosimilars that expand affordability. The market maintains stable demand, and it benefits from coordinated cancer strategies across national health systems.
Asia Pacific captures a fast-growing share of the Androgen Deprivation Therapy Market driven by aging populations and rising prostate cancer detection rates. Countries such as Japan, China, and South Korea invest heavily in oncology infrastructure. Demand for oral agents increases due to expanding access to advanced hormonal therapies. Rural health programs support improved diagnostics, which raises treatment volumes across diverse regions. Pharmaceutical manufacturers target emerging markets with broader distribution networks. The market strengthens its presence, and it gains momentum through rapid healthcare modernization.
Key Player Analysis:
- Johnson & Johnson
- AstraZeneca
- Bayer AG
- Astellas Pharma Inc.
- AbbVie Inc.
- Pfizer Inc.
- Sanofi
- Bristol-Myers Squibb
- Ferring B.V.
- Tolmar Pharmaceuticals
Competitive Analysis:
The Androgen Deprivation Therapy Market shows strong competition driven by established pharmaceutical companies with extensive hormonal therapy portfolios. Leading firms invest in next-generation agents that target androgen production and receptor activity with greater precision. Many competitors work to secure differentiation through improved safety, longer dosing intervals, and enhanced patient adherence tools. The landscape includes brands with long market presence and new entrants focusing on oral antagonists and biosynthesis inhibitors. Pricing pressure increases as generics and biosimilars gain traction in cost-sensitive regions. Companies expand clinical research to validate combination strategies that can strengthen therapeutic positioning. The market moves toward broader innovation, and it maintains a competitive structure shaped by regulatory support, clinical evidence, and strategic partnerships.
Recent Developments:
- In January 2026, Johnson & Johnson received a positive opinion from the European Medicines Agency's CHMP for an indication extension of AKEEGA (niraparib and abiraterone acetate dual action tablet), recommended for use with prednisone or prednisolone alongside androgen deprivation therapy for patients with metastatic hormone-sensitive prostate cancer harboring BRCA1/2 mutations.
- In May 2025, Astellas Pharma Inc. and Pfizer Inc. announced longer-term follow-up results from the Phase 3 ARCHES study, highlighting the efficacy of their product XTANDI (enzalutamide), an androgen receptor pathway inhibitor, in combination with androgen deprivation therapy (ADT) for metastatic hormone-sensitive prostate cancer, showing a 30% reduction in the risk of death compared to placebo plus ADT.
- In September 2024, Orion Pharma and Bayer reported positive results from the ARANOTE trial, demonstrating the clinical benefit of darolutamide plus ADT alone (without docetaxel) for metastatic hormone-sensitive prostate cancer, with Bayer planning global regulatory submissions to expand its use.
Report Coverage:
The research report offers an in-depth analysis based on Type, Drug Class, Route of Administration, Application, and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising prostate cancer incidence will strengthen long-term demand across all major therapy classes in the Androgen Deprivation Therapy Market.
- Expansion of oral antagonists will shift treatment preferences toward convenient and home-based care models.
- Combination regimens with radioligand and immunotherapy agents will gain traction and reshape therapeutic planning.
- Increased investment in biomarker research will support more precise treatment selection and improved response outcomes.
- Broader use of long-acting depot formulations will enhance adherence and reduce clinic visits in routine care pathways.
- Growing access to generics and biosimilars will expand adoption across cost-sensitive regions.
- Healthcare modernization in Asia Pacific will support higher diagnosis rates and strengthen regional expansion.
- Digital tools for remote monitoring will improve safety tracking and patient engagement across long-term therapy plans.
- Pharmaceutical companies will accelerate development of resistance-targeting agents that address emerging clinical gaps.
- Strengthening oncology infrastructure worldwide will support wider integration of ADT into standardized treatment algorithms.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Androgen Deprivation Therapy Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Androgen Deprivation Therapy Market projected to grow between 2025 and 2032?
Which Androgen Deprivation Therapy Market segment held the largest share in 2025?
What are the primary factors fueling the growth of the Androgen Deprivation Therapy Market?
Who are the leading companies in the Androgen Deprivation Therapy Market?
Which region commanded the largest share of the Androgen Deprivation Therapy Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 6,437.5 million → 2032: USD 9,426.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Androgen Deprivation Therapy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Androgen Deprivation Therapy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Androgen Deprivation Therapy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Androgen Deprivation Therapy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Androgen Deprivation Therapy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Androgen Deprivation Therapy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Androgen Deprivation Therapy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Androgen Deprivation Therapy Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 6,437.5 million → 2032: USD 9,426.81 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Androgen Deprivation Therapy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Androgen Deprivation Therapy Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Androgen Deprivation Therapy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Androgen Deprivation Therapy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

