
More than 12 lakh chemists anchor Indian medicine retail
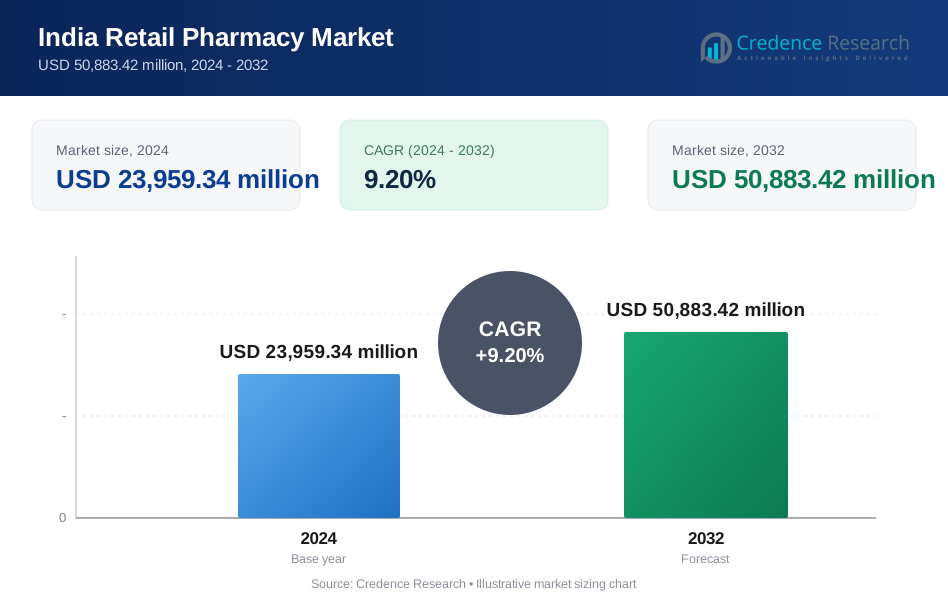
The India retail pharmacy market was valued at USD 26.16 billion in 2025 and is projected to increase from USD 28.57 billion in 2026 to USD 63.08 billion by 2035, registering a CAGR of 9.20% during 2026–2035. Demand rests on chronic therapy refills, a licensed network that the All India Organisation of Chemists & Druggists puts at more than 12 lakh chemists, and a fast build-out of chains and government generic stores. South India held the largest regional share, 34.0% in 2025, because its chain and Jan Aushadhi networks are among the densest in the country. East India is the fastest-growing region at 10.09% a year as chains and generic kendras move deeper into Bihar, Odisha and West Bengal. The most important commercial change is the Goods and Services Tax revision of Sept. 22, 2025, which moved most medicines from 12% to 5%. Online sale rules remain disputed after a nationwide chemist shutdown on May 20, 2026.
How many pharmacies does India have, and what is counted?
India has at least 12 lakh, or 1.2 million, pharmacies and medical shops by the count that the chemists association used for its May 2026 shutdown, and the association reports more than 12.40 lakh licensed stores in its own membership. This report counts retail sales of prescription drugs, OTC medicines, supplements, personal care and wellness products through these stores, chains, hospital pharmacies and online platforms.
It excludes bulk supply to government tenders and all pharmaceutical exports. Most stock reaches the counter through independent distributors and organized stockists, and many buyers pay from their own pockets, which makes price and proximity the deciding factors at the counter.
India Retail Pharmacy Market Insights
- The market grows from USD 26.16 billion in 2025 to USD 63.08 billion by 2035, a 9.20% CAGR, as refills, chains and generic stores widen access to medicines.
- South India held 34.0% of 2025 value, supported by dense chain networks in Hyderabad, Chennai and Bengaluru and by strong Jan Aushadhi coverage in Kerala and Karnataka.
- Independent Pharmacies held 59.0% of 2025 value, because licensed neighborhood chemists remain the default purchase point for most households outside large cities.
- Medicine taxes fell on Sept. 22, 2025, when most products moved from 12% to 5%, cutting shelf prices and squeezing small chemists holding older stock.
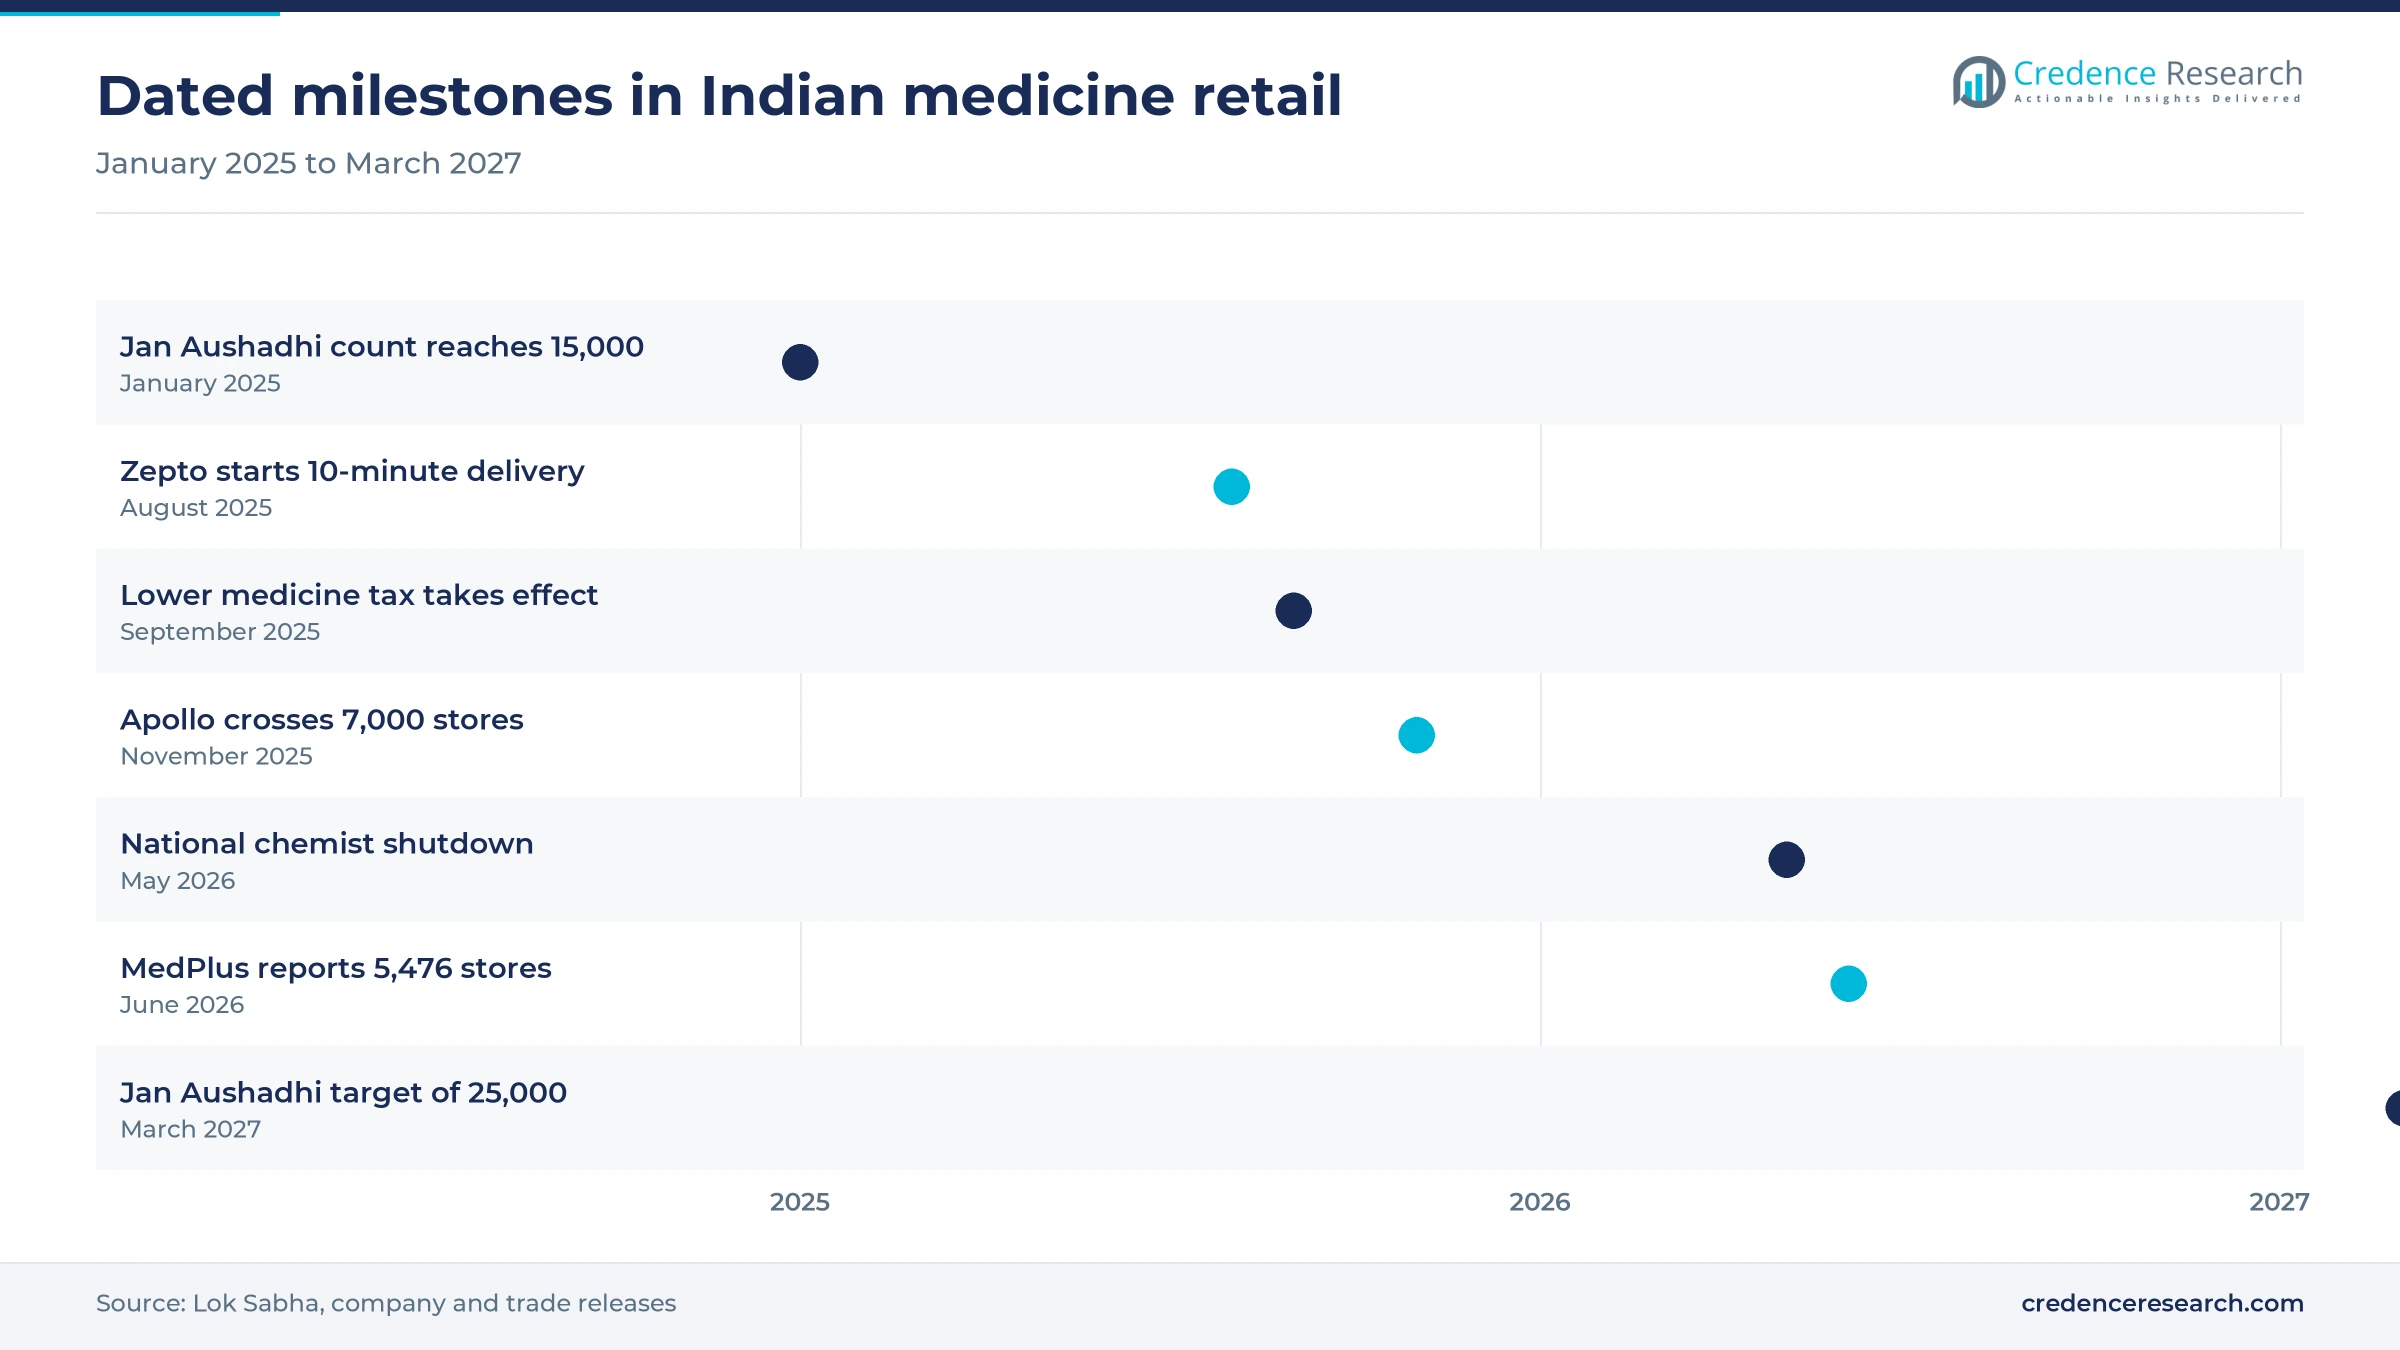
- Apollo Pharmacy passed 7,000 stores in November 2025 and MedPlus reached 5,476 by June 2026, showing how quickly organized retail is adding smaller towns.
Prescription refills and standalone stores hold most value
Chronic prescriptions lead as nutritionals gather speed
Based on product type, the market is categorized into prescription drugs, over-the-counter (OTC) medicines, health supplements, personal care products and wellness and nutraceutical products. Prescription Drugs led with 66.0% of 2025 value because chronic refills anchor the counter, with Business Standard reporting cardiac sales of Rs 2,762 crore in September 2025 alone, up 13% from a year earlier. Health Supplements grows fastest at 10.73% a year as BioSpectrum India reported in July 2026 an expected 13.0% rise in nutritionals for 2026, from 5.9% in 2025. The Free Press Journal reported in January 2026 that the OTC category was valued at about Rs 47,000 crore in 2024.
Standalone chemists lead while online platforms grow fastest
Based on distribution channel, the market is categorized into independent pharmacies, retail chain pharmacies, hospital pharmacies and online pharmacies. Independent Pharmacies led with 59.0% of 2025 value because a June 2024 supply chain study supported by the Indian Pharmaceutical Association gave standalone stores 54% of Indian pharmaceutical sales in 2023, against an 11.6% share for chains. Online Pharmacies grow fastest at 14.13% a year as Zepto, which began 10-minute delivery in August 2025, joined the quick-commerce race. Online discounts have already narrowed from 25–40% to 8–14%, according to the same study, so growth now leans on chronic drugs, which exceed 60% of online sales.
Urban households lead as chains move into smaller towns
Based on consumer type, the market is categorized into urban consumers, rural consumers and institutional buyers such as hospitals and clinics. Urban Consumers led with 68.0% of 2025 value because budgets differ sharply, with the Ministry of Statistics reporting average monthly spending per person of Rs 6,996 in urban India against Rs 4,122 in rural India for 2023-24. Rural Consumers grow fastest at 9.99% a year as chains push past big cities toward towns serving rural catchments. MedPlus placed 113 of its 146 net store additions in Tier 2 and Tier 3 towns during the June 2026 quarter, while medical costs already take 6.83% of rural spending.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Prescription Drugs | 66.0% | Health Supplements | 10.73% |
| By Distribution Channel | Independent Pharmacies | 59.0% | Online Pharmacies | 14.13% |
| By Consumer Type | Urban Consumers | 68.0% | Rural Consumers | 9.99% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Chronic refills, chains and generics are lifting sales
Chronic therapy refills anchor pharmacy counter sales
Long-term prescriptions give Indian chemists their steadiest sales because patients return every month for the same therapy. A Lancet study reported in June 2023 counted more than 101 million people with diabetes and 136 million with prediabetes, which sets a very large refill base for the counter. BioSpectrum India reported in July 2026 that cardiac sales are expected to grow 14.0% and anti-diabetic sales 13.2% in 2026, with GLP-1 drugs at about 111%. This demand feeds Prescription Drugs and the wider range of diabetes drugs stocked by neighborhood stores. As a result, chains build delivery around repeat patients, and Apollo reports more than 100,000 home medicine deliveries a day.
Organized chains are adding hundreds of stores a year
Chain expansion lifts demand because new stores bring wider assortments, loyalty pricing and longer hours to towns served mainly by small chemists. Apollo Pharmacy crossed 7,000 stores on Nov. 28, 2025 with an outlet in Ayodhya, and it plans two openings a day to exceed 10,600 stores by 2030. MedPlus reported 5,476 stores on June 30, 2026, covering more than 850 cities and towns after 146 net additions in one quarter. The 2024 supply chain study supported by the Indian Pharmaceutical Association expects chain drugstores to reach 17.4% of Indian pharmaceutical sales by 2030. In turn, chain formats are taking share from standalone counters in Tier 2 cities.
Generic store networks widen access to cheaper medicines
Low-priced generic formats expand the market by reaching patients who previously skipped or rationed therapy because of cost. The government counted 15,000 Jan Aushadhi Kendras on Jan. 31, 2025, and Indian Pharma Post reported 20,149 by June 30, 2026, against a target of 25,000 by March 2027. These kendras offer 2,110 medicines priced 50% to 80% below branded alternatives, according to the government. Private capital is following the same logic, since Zota Health Care lifted its Davaindia network from 2,331 stores at the end of December 2025 to 2,502 by Feb. 11, 2026. This competition pushes Independent Pharmacies to stock more trade generics alongside established brands.
Tax cuts and household spending lift sales value
Medicine affordability improved in late 2025 because the Goods and Services Tax revision took effect on Sept. 22, 2025. Most medicines moved from 12% to 5%, and 36 critical drugs became fully exempt, according to the Indian Pharmaceutical Alliance. Sales held firm through the change, since Business Standard reported Rs 20,886 crore for September 2025, up 7.3% from a year earlier. BioSpectrum India reported an expected 11.3% rise for 2026 after 8.1% in 2025, which would be the strongest annual growth in five years. Price still matters because National Health Accounts data put out-of-pocket payments at 39.4% of health spending in 2021-22, down from 48.8% in 2017-18.
Fast delivery and own-label generics reshape the counter
Shift toward 10-minute medicine delivery in metro cities
Quick-commerce companies are moving urgent medicine purchases from the corner store to the phone, starting with the largest cities. Zepto launched its pharmacy service on Aug. 8, 2025 in parts of Mumbai, Bengaluru, Delhi NCR and Hyderabad after a 12-month test. Blinkit had begun piloting prescription delivery in Bengaluru pin codes a month earlier, and Swiggy partnered with PharmEasy, according to Entrackr. Tata 1mg offers instant delivery in seven to eight locations through a BigBasket tie-up. Apollo answered with the Apollo 24/7 platform, which delivers across more than 19,000 pincodes. This shift favors Online Pharmacies, although Whalesbook reported in May 2026 that quick commerce has not yet lifted overall market growth.
Rise of omnichannel stores among online pharmacies
Online pharmacies are opening physical counters because stores cut last-mile cost and allow pharmacist contact. Tata 1mg ran about 220 outlets in January 2026, and its chief executive targeted close to 500 by the end of 2026 at almost a store a day. Netmeds, controlled by Reliance Retail, opened its first physical pharmacy in Chennai in early 2023, according to Team France Export. The same logic runs in reverse, since Apollo's Circle program has 10 million members and 44 million registered users. Emami's Frank Ross also plans to take its online pharmacy across Eastern and Southern India. As a result, the line between Independent Pharmacies and platform models is narrowing.
Private label generics offer chains a margin opening
Own-label medicines represent an opportunity because they earn more per pack than third-party brands while lowering patient bills. The 2024 supply chain study supported by the Indian Pharmaceutical Association put private labels at 15% to 18% of organized store revenue. MedPlus's June 2026 quarter figures imply private label products at about 14.4% of pharma sales in the June 2026 quarter, which leaves room for further gains. Frank Ross has nearly 250 products under its in-house Rosscare label, showing that regional chains can follow the same path. The opening is largest in Tier 2 and Tier 3 towns, where the same study says trade generics have already improved access. Chains that pair these lines with pharmacist counseling can defend prices against the deep discounts offered at government kendras.
A clearer OTC framework opens a self-care opportunity
Self-care offers pharmacies a large opening because India's OTC category is projected to reach Rs 98,000 crore by 2030, growing about 13% a year, according to the Free Press Journal in January 2026. Pharmacists keep an advantage at the point of advice, since 80% of the 624 survey respondents preferred them for pain relief and 67% relied on them for chronic health. Only 20% of those respondents opted for online channels in pain relief, which shows how far advice still shapes that purchase at the counter. Stores that build advice-led aisles for Health Supplements can therefore protect a category that would otherwise drift to apps.
Online rules and thin margins pressure small chemists
Unsettled e-pharmacy rules keep the channel in dispute
Online sale rules remain unresolved, which leaves retailers and platforms planning without a stable legal base. The chemists association called a nationwide shutdown on May 20, 2026, demanding withdrawal of notifications G S R 220 (E) of March 2020 and G S R 817 (E). Draft e-pharmacy rules from 2018 are still unapproved, according to Whalesbook. As a result, platforms cannot plan with certainty and small stores cannot judge future competition. A published licensing regime would reduce this risk for both sides.
Prescription checks face growing public scrutiny
Prescription integrity has become a reputational risk for delivery platforms after an India Today investigation found medicines approved in under a minute by unidentified prescribers. The chemists association wrote to the prime minister about the findings on Dec. 11, 2025, and asked for an inquiry into the doctor-on-call model. Antibiotic misuse makes the concern serious for regulators as well as patients. Platforms can respond with verified prescriber registries and pharmacist review, although these controls will raise fulfillment cost.
Tax transition and price caps squeeze small chemists
Small chemists absorbed much of the cost of the September 2025 tax change because they held stock bought at older rates. The association, representing more than 12.5 lakh chemists and distributors, said on Sept. 29, 2025 that many traders cannot claim input tax credit as unregistered or composite dealers. Margins capped by the National Pharmaceutical Pricing Authority leave little room to recover these losses. Consequently, weaker stores may close or join franchise networks unless a relief mechanism follows.
A fragmented supply chain limits range and reach
Fragmented distribution limits availability outside big cities because more than 60,000 independent distributors carry far narrower ranges than organized stockists, according to the 2024 study supported by the Indian Pharmaceutical Association. Local stockists hold 10,000 to 15,000 items against 50,000 to 60,000 at organized players, whose share was only about 10% in 2023. Investment in healthcare supply chain management could narrow this gap. Until then, patients in smaller towns face more stockouts and a higher counterfeit risk.
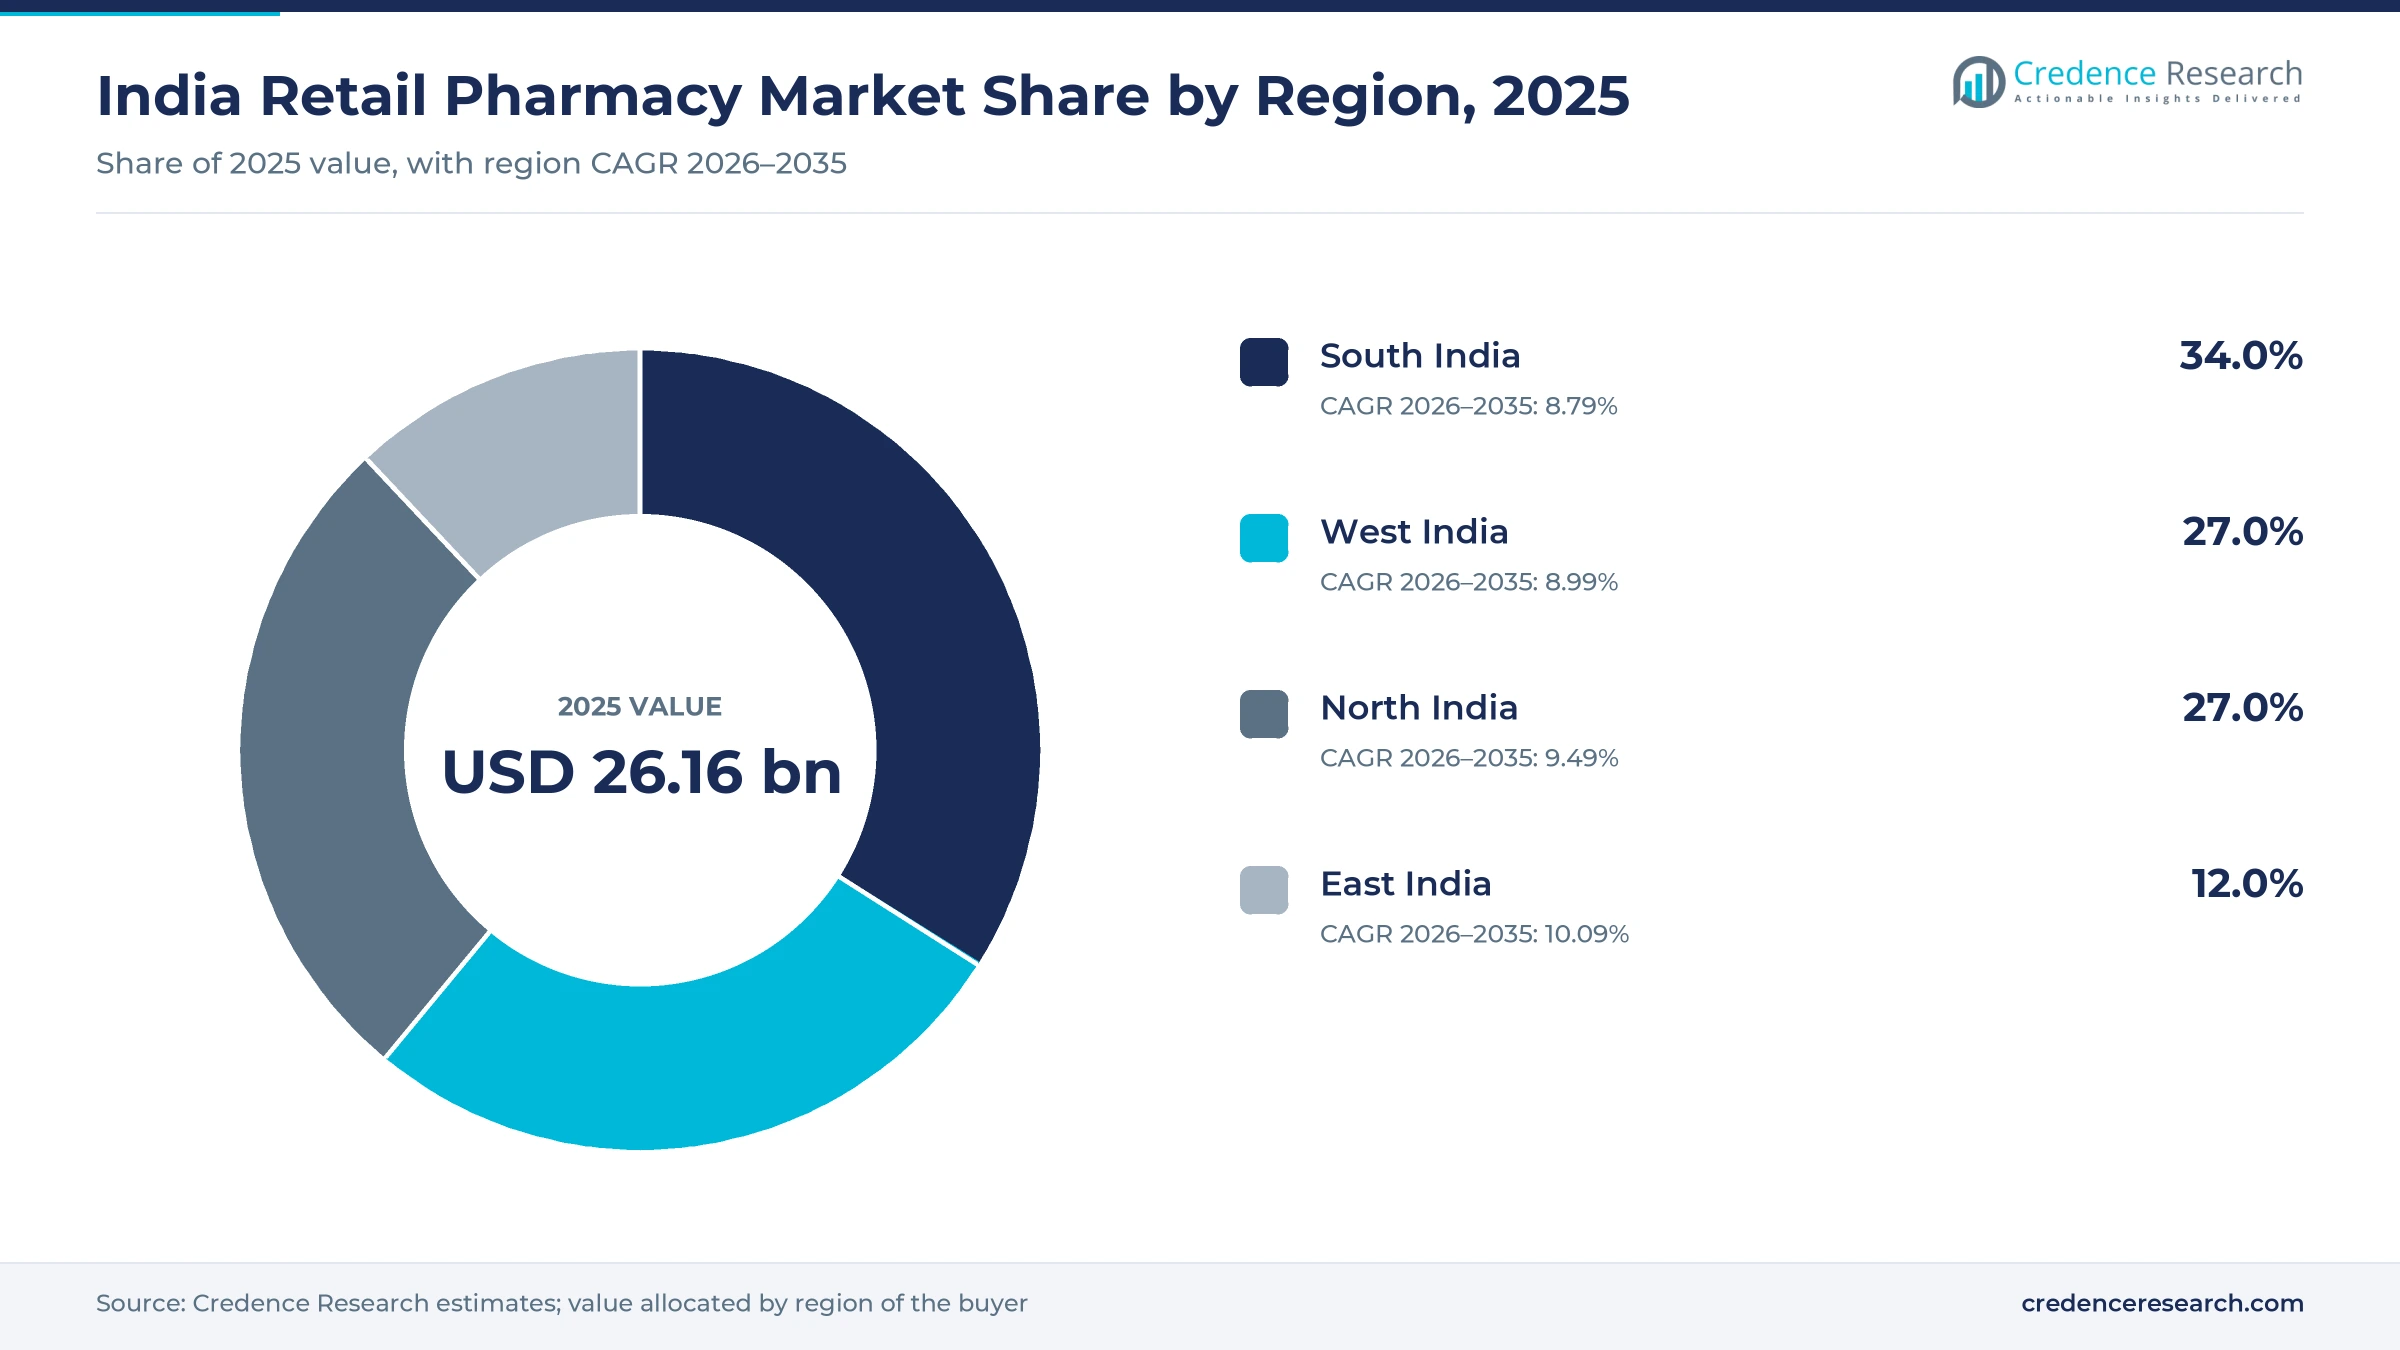
South India leads while East India grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| South India | 8.90 | 34.0% | 8.79% |
| West India | 7.06 | 27.0% | 8.99% |
| North India | 7.06 | 27.0% | 9.49% |
| East India | 3.14 | 12.0% | 10.09% |
South India leads on chain density and generic access
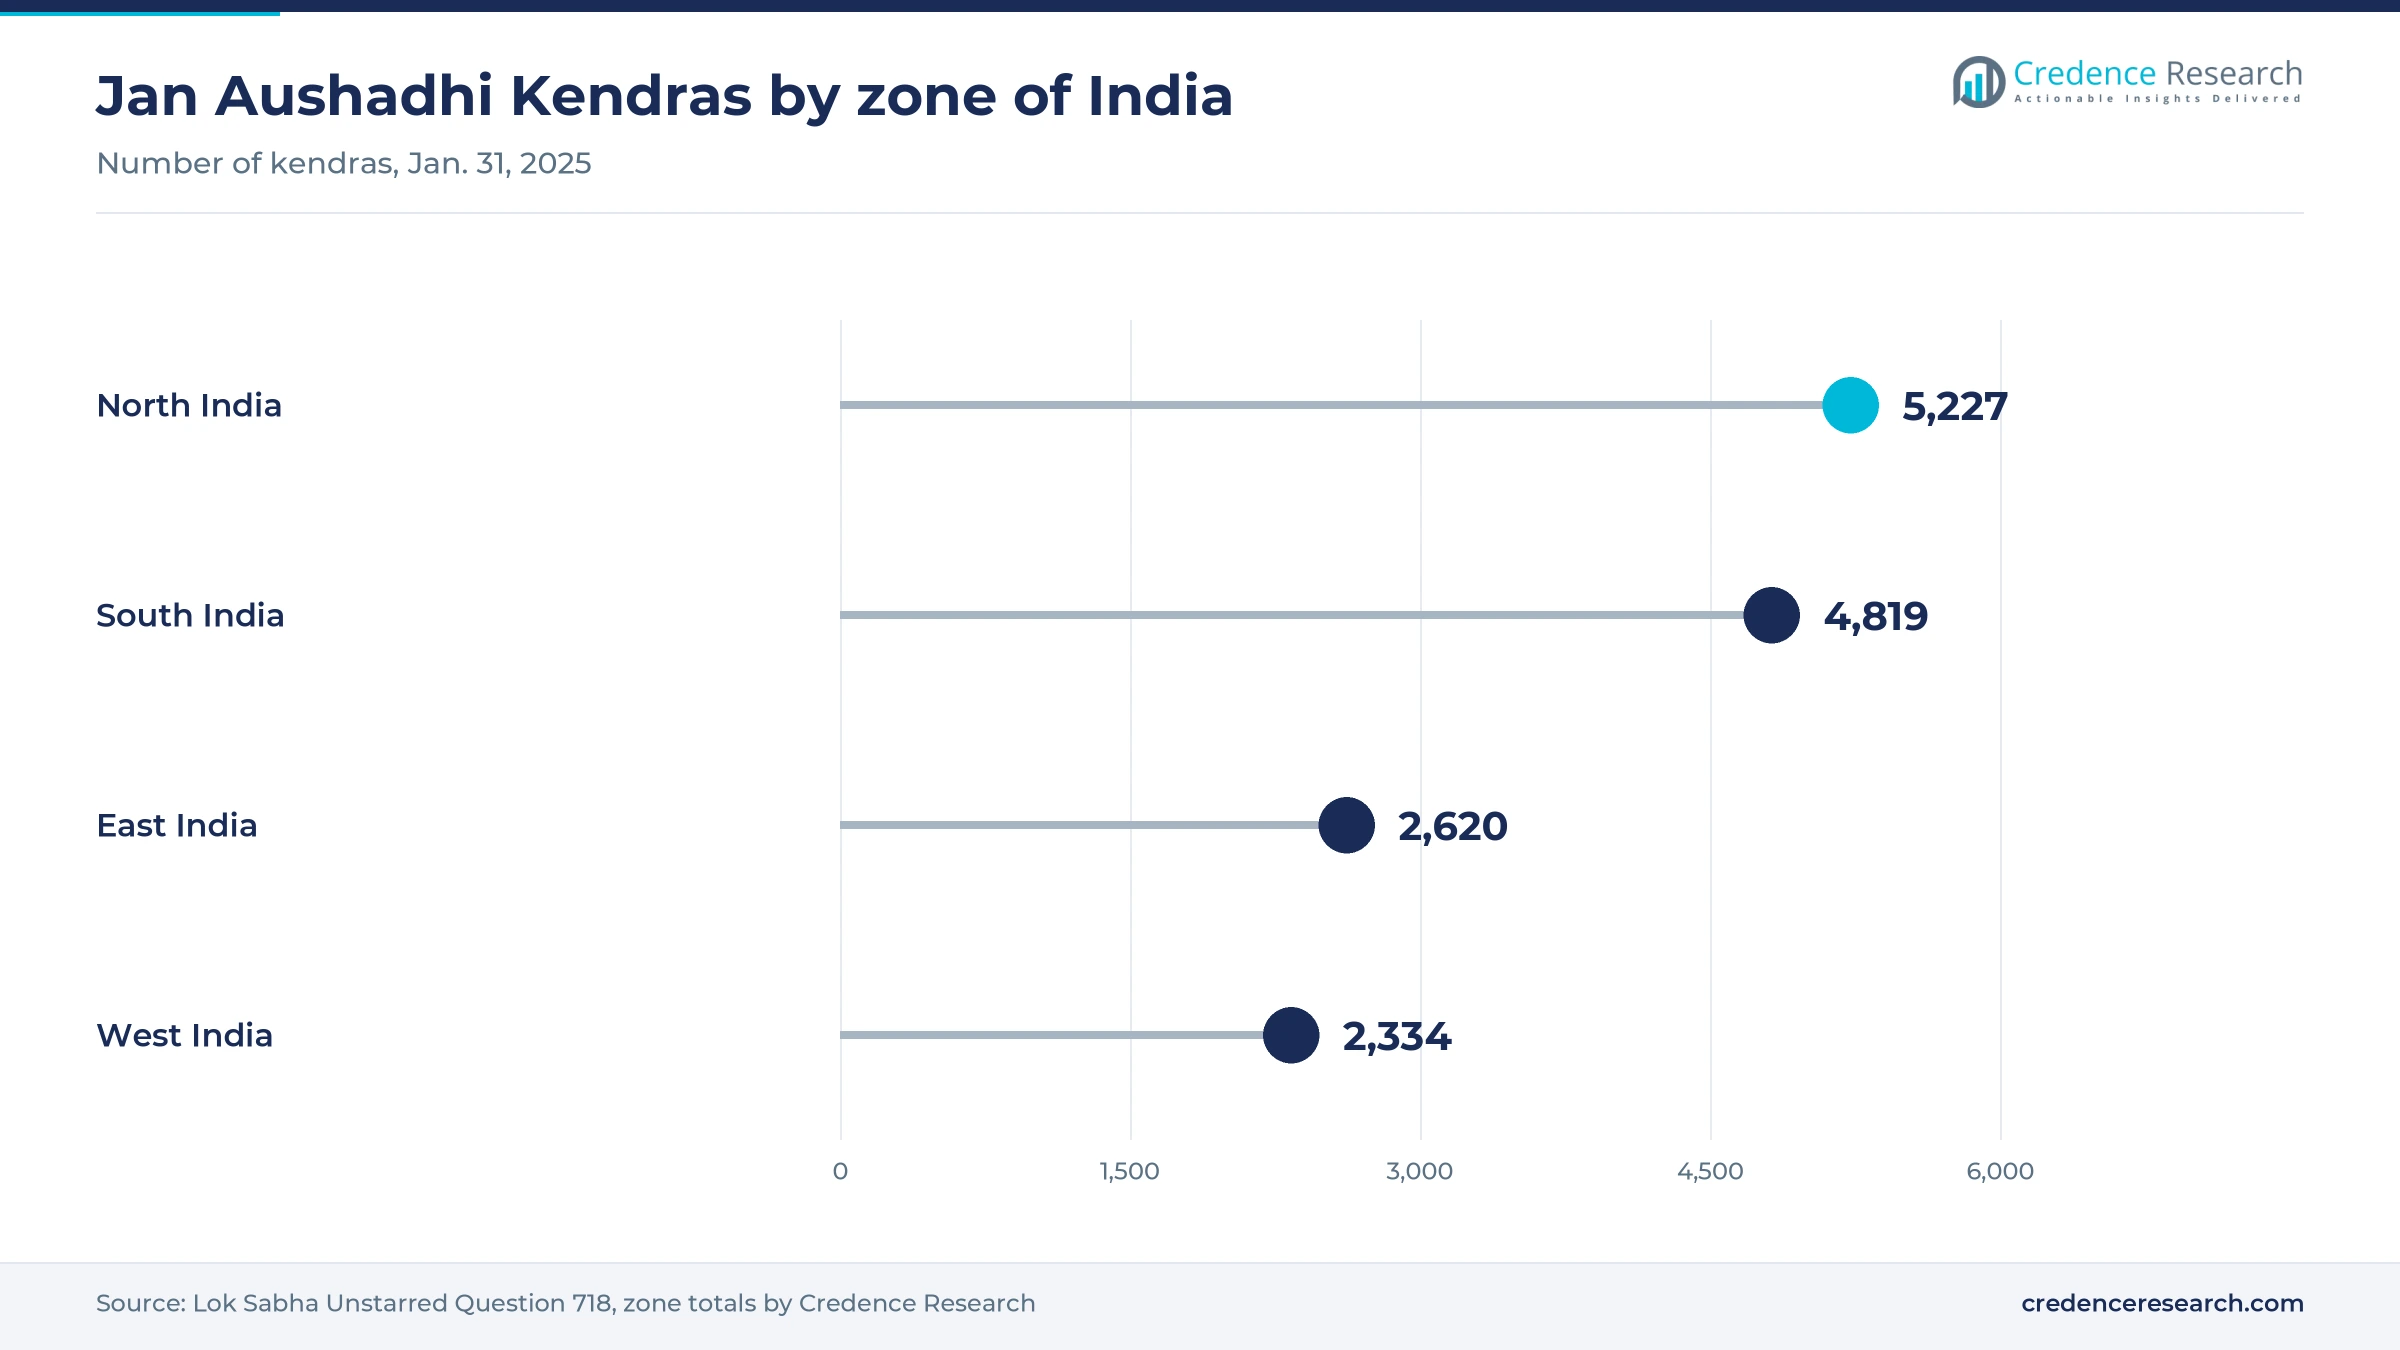
South India held 34.0% of 2025 value and grows at 8.79% a year, supported by a very deep chain presence. MedPlus alone lists 519 stores in Hyderabad, 472 in Chennai and 439 in Bengaluru. Kerala had 1,525 Jan Aushadhi Kendras and Karnataka 1,417 in the Lok Sabha count of January 2025. Chronic demand is also high, since a Lancet study reported in June 2023 put diabetes prevalence in Kerala at 25.5%.
West India relies on Maharashtra and neighboring state demand
West India held 27.0% of 2025 value and grows at 8.99% a year, helped by large urban catchments in Mumbai, Pune and Ahmedabad. Wellness Forever built its network here, reaching 300 stores across 43 cities in Maharashtra, Goa and Karnataka by April 2022. MedPlus lists 135 stores in Pune and 103 in Nagpur. Gujarat had 757 Jan Aushadhi Kendras and Maharashtra 711 in January 2025, a low count for the size of the Maharashtra population.
North India gains from Uttar Pradesh store growth
North India held 27.0% of 2025 value and grows at 9.49% a year as organized formats enter its large cities and towns. Uttar Pradesh had 2,644 Jan Aushadhi Kendras in January 2025, the most of any state, and Delhi had 492. Apollo chose Ayodhya for its milestone store in November 2025, which shows the priority given to the state. However, the Lancet study's diabetes prevalence of 4.8% in Uttar Pradesh suggests a smaller diagnosed refill base today.
East India grows fastest from a smaller base
East India held 12.0% of 2025 value and grows fastest at 10.09% a year because store density started low. Bihar had 800 Jan Aushadhi Kendras and West Bengal 627 in the Lok Sabha count of January 2025. Frank Ross, founded in Kolkata in 1906, runs about 330 outlets across 10 states, while SastaSundar is also based in the city. MedPlus lists 315 stores in Kolkata and 64 in Bhubaneswar, which points to growing chain interest.
Store milestones and a strike marked 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In August 2025, Zepto launched 10-minute medicine delivery in parts of Mumbai, Bengaluru, Delhi NCR and Hyderabad. | Live in select areas, which brought quick commerce directly into urgent medicine purchases. |
| In November 2025, Apollo Pharmacy opened its 7,000th store in Ayodhya, Uttar Pradesh and announced two openings a day. | Network target of over 10,600 stores by 2030, with growth planned at two stores daily. |
| In February 2026, Zota Health Care reported 2,502 Davaindia stores, of which 1,607 were company-owned and 895 franchised. | Operating network, which shows generic chains scaling alongside the government program. |
| In May 2026, the chemists association held a one-day national shutdown on May 20 against online medicine sales. | Completed protest, with rule withdrawal still being sought from the central government. |
| In June 2026, the Jan Aushadhi network reached 20,149 kendras, with the target of 25,000 set for March 2027. | Government program under way, with 2,110 medicines listed for sale through the kendras. |
Prescription checks and delivery tools decide trust
- Prescription verification is the most sensitive layer, because the December 2025 complaints centered on approvals made in under a minute without identifiable doctors.
- Courier allocation software supports delivery reliability, and Tata 1mg partnered with ClickPost to assign medicine shipments through AI-driven courier selection.
- Ordering platforms connect the trade, linking chemists and stockists directly to their orders across India.
- Store automation remains early in Indian chemists, although dispensing robots and packaging systems are a natural next step for high-volume chains as they add hospital counters.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
National chains take share from a fragmented base
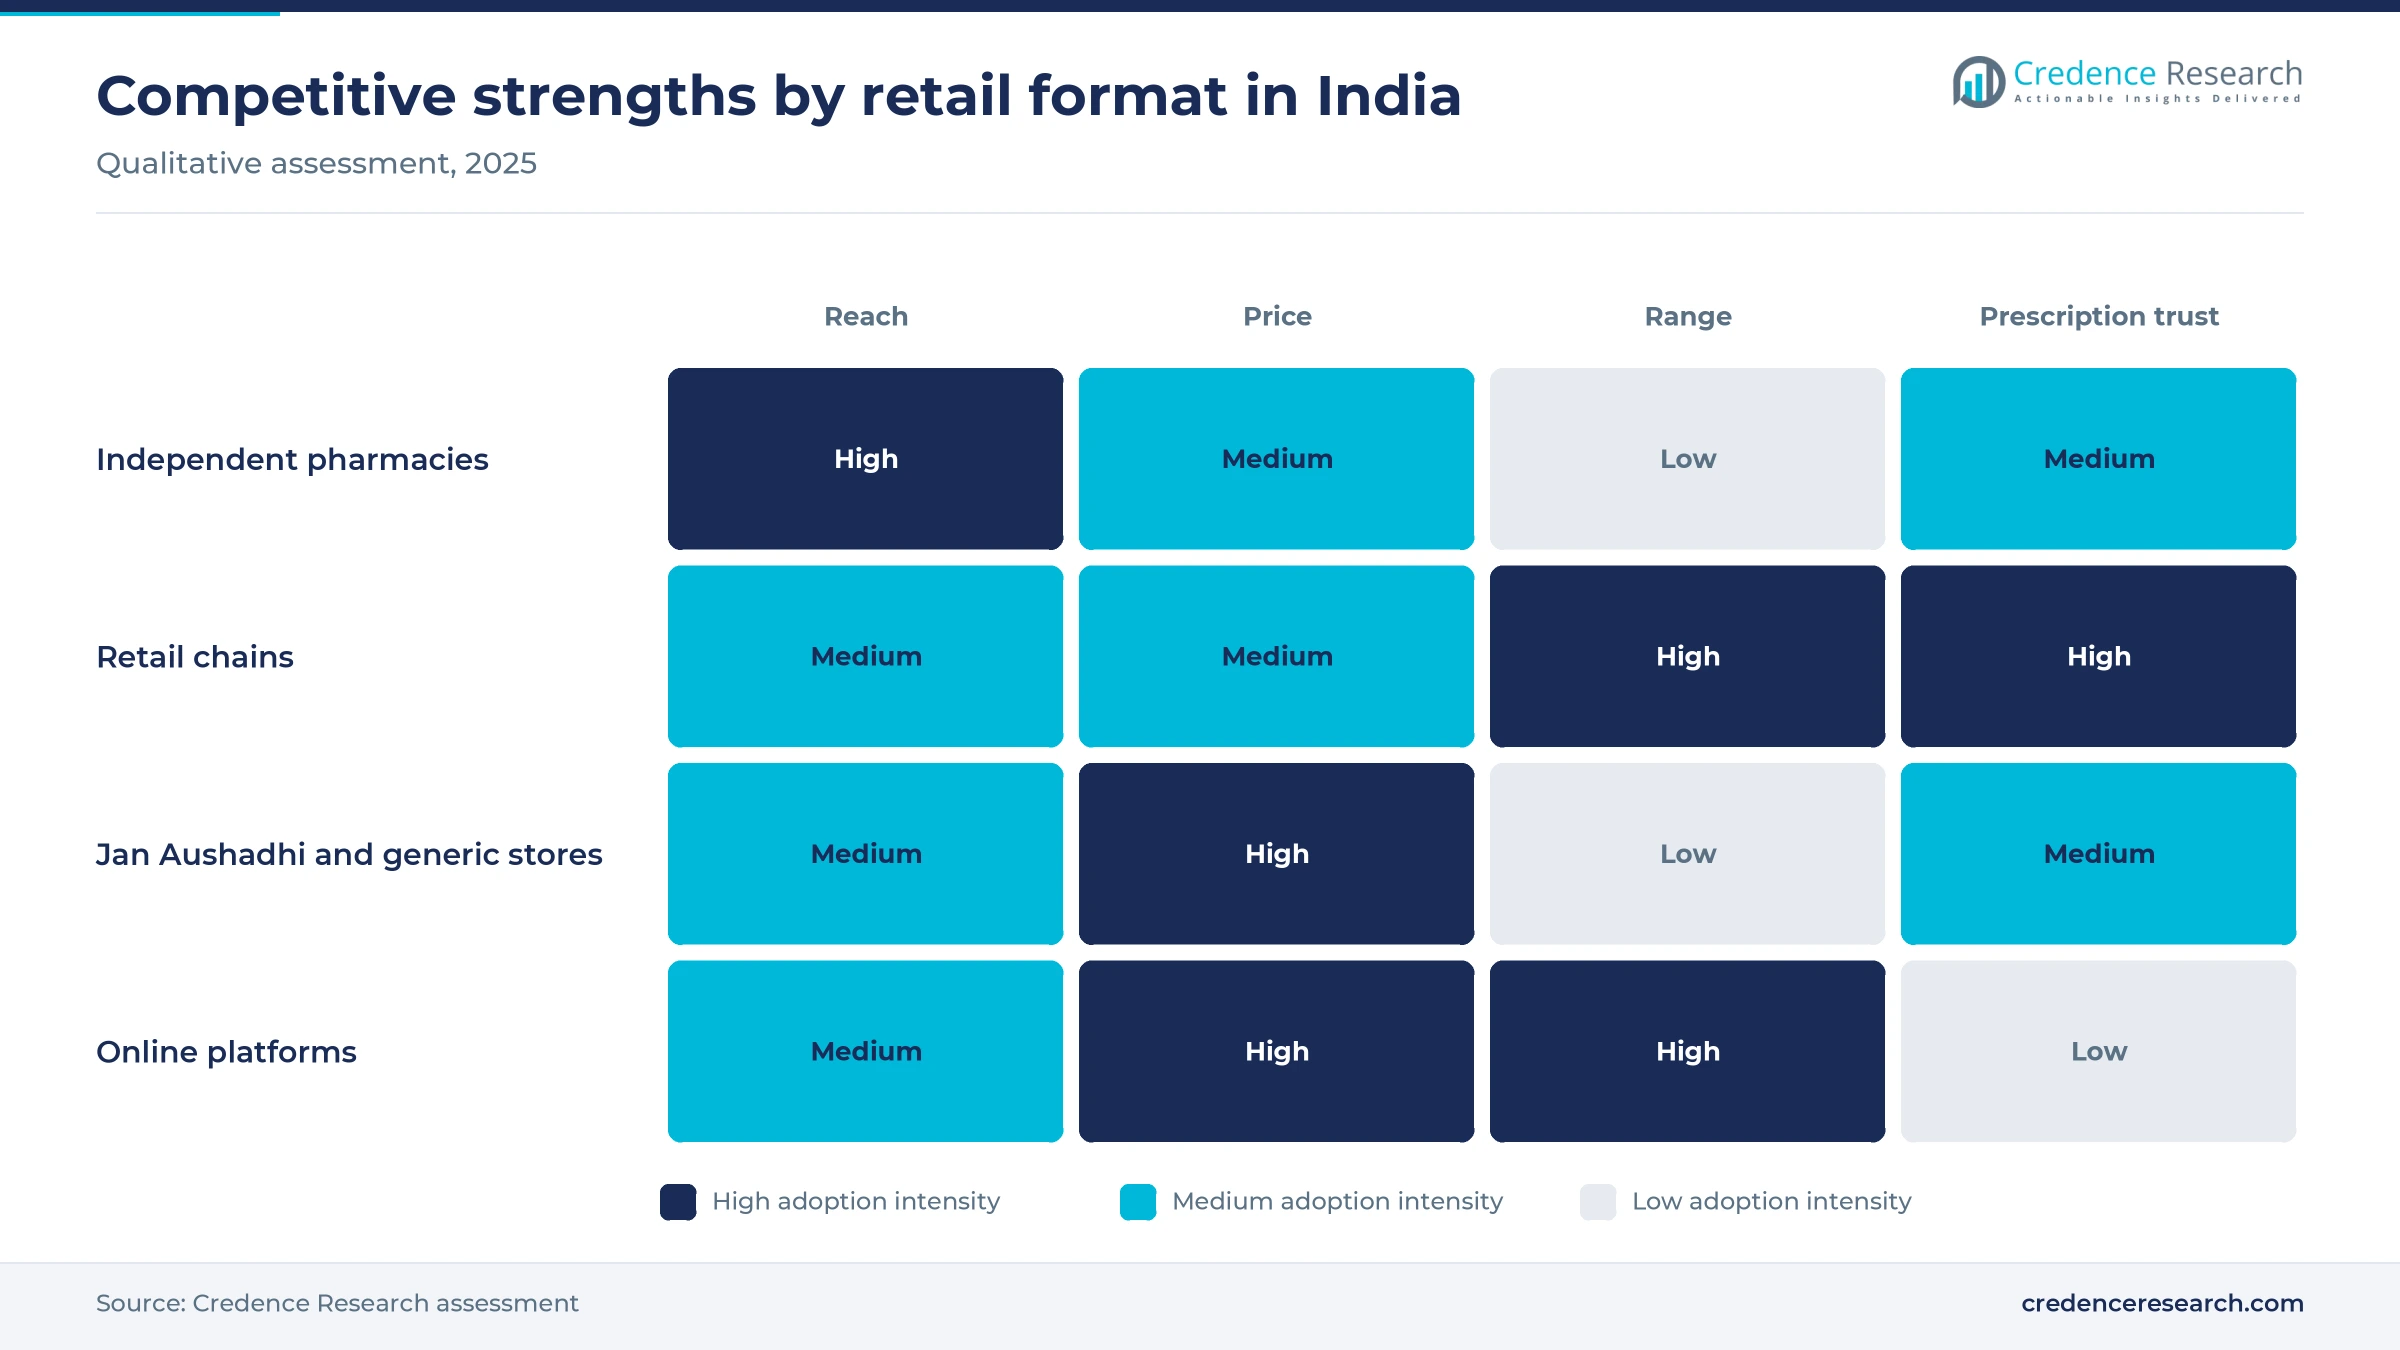
Competition splits into three groups, and each one wins customers differently. National chains compete on reach and owned brands, with Apollo Pharmacy and MedPlus leading on store count and Wellness Forever concentrating on the west. Generic specialists compete on price, led by Davaindia and the government kendras. Platforms such as Tata 1mg, PharmEasy and Netmeds compete on range and home delivery, with a 2024 study supported by the Indian Pharmaceutical Association counting over 30 national and regional online pharmacies and more than 70,000 listed items. Online pharmacies still held only 2.5% of Indian pharmaceutical sales in 2023, so physical reach remains decisive. Regional players such as Frank Ross and SastaSundar defend their eastern base through local relationships. Similar chain consolidation can be seen in the UAE, although the sheer number of small Indian licensees keeps this field far more fragmented.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Apollo Pharmacy | National chain | Crossed 7,000 stores in November 2025, with the Apollo 24/7 platform for delivery |
| MedPlus | National chain | Operates 5,476 stores, strong in South India, with own-label medicines |
| Davaindia | Generic chain | Zota Health Care network of 2,502 stores in February 2026 |
| Tata 1mg | Online and omnichannel | About 220 outlets in January 2026, with close to 500 targeted by end-2026 |
| Netmeds (Reliance Retail) | Online and omnichannel | Online pharmacy controlled by Reliance Retail, with physical stores since 2023 |
| PharmEasy | Online platform | Online pharmacy with a Swiggy delivery partnership |
| Wellness Forever | Regional chain | Stores in Maharashtra, Goa and Karnataka |
| Frank Ross Pharmacy | Regional chain | About 330 outlets, with roots in Kolkata and the Rosscare label |
| SastaSundar | Online and service centers | Kolkata-based platform supported by Healthbuddy centers |
Chains will gain, but standalone stores keep the lead
Credence Research's view is that India will remain a market of small chemists for the whole forecast period, even as chains take a much larger slice of value. The more useful question for investors is which towns convert first, and the MedPlus and Apollo opening patterns point to Tier 2 and Tier 3 locations. Retailers should treat private labels and chronic programs as the core of their margin plans. Platforms should expect tighter prescription rules, because the May 2026 shutdown has made verification a political issue rather than a compliance detail.
How the model and estimates for India were built
The report uses 2025 as the base year and 2026–2035 as the forecast period. The earlier 2024 estimate on this page was carried to 2025 with its own growth rate and then compared with published estimates and a top-down check from monthly pharmaceutical sales data. Segment and regional splits in this report are Credence Research estimates. Sources are government statistics, parliamentary answers, company filings and releases, and trade publications. No interviews or primary surveys were conducted for this particular report.
Organized and generic formats shape demand to 2035
From USD 28.57 billion in 2026, the market is projected to reach USD 63.08 billion by 2035, which keeps annual growth at 9.20%. Chronic therapies should remain the main source of value, with GLP-1 drugs and cardiac care lifting basket size. The Jan Aushadhi target and Davaindia openings will hold down prices in many towns, so sales growth will depend on volume and range rather than price alone. Final e-pharmacy rules are the largest open question, because they will decide how much share online platforms can take from neighborhood stores in the second half of the forecast period.
Frequently Asked Questions
How big is the India retail pharmacy market?
What is the growth rate of the India retail pharmacy market?
How many pharmacies are there in India?
How many stores does Apollo Pharmacy have in India?
How large is online pharmacy in India?
Which region leads the India retail pharmacy market?
Which channel sells the most medicines in India?
Who are the main retail pharmacy companies in India?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Prescription Drugs
- 1.2.2 Over-the-Counter (OTC) Medicines
- 1.2.3 Health Supplements
- 1.2.4 Personal Care Products
- 1.2.5 Wellness and Nutraceutical Products
- 1.3 By Consumer Type
- 1.3.1 Urban Consumers
- 1.3.2 Rural Consumers
- 1.3.3 Institutional Buyers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 26.16 billion → 2035: USD 63.08 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Retail Pharmacy Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Retail Pharmacy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Retail Pharmacy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Retail Pharmacy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Retail Pharmacy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Retail Pharmacy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Retail Pharmacy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Retail Pharmacy Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 26.16 billion → 2035: USD 63.08 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Retail Pharmacy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Prescription Drugs
- 12.3.7.2 Over-the-Counter (OTC) Medicines
- 12.3.7.3 Health Supplements
- 12.3.7.4 Personal Care Products
- 12.3.7.5 Wellness and Nutraceutical Products
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Consumer Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Urban Consumers
- 12.4.7.2 Rural Consumers
- 12.4.7.3 Institutional Buyers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 India Retail Pharmacy Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 India Retail Pharmacy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 India Retail Pharmacy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Apollo Pharmacy
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 MedPlus
- 17.4 Wellness Forever
- 17.5 Tata 1mg
- 17.6 Netmeds (Reliance Retail)
- 17.7 Frank Ross Pharmacy
- 17.8 SastaSundar
- 17.9 Davaindia
- 17.10 PharmEasy
- 17.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

