
Safeguard compliance pushes ACCU deals onto formal venues
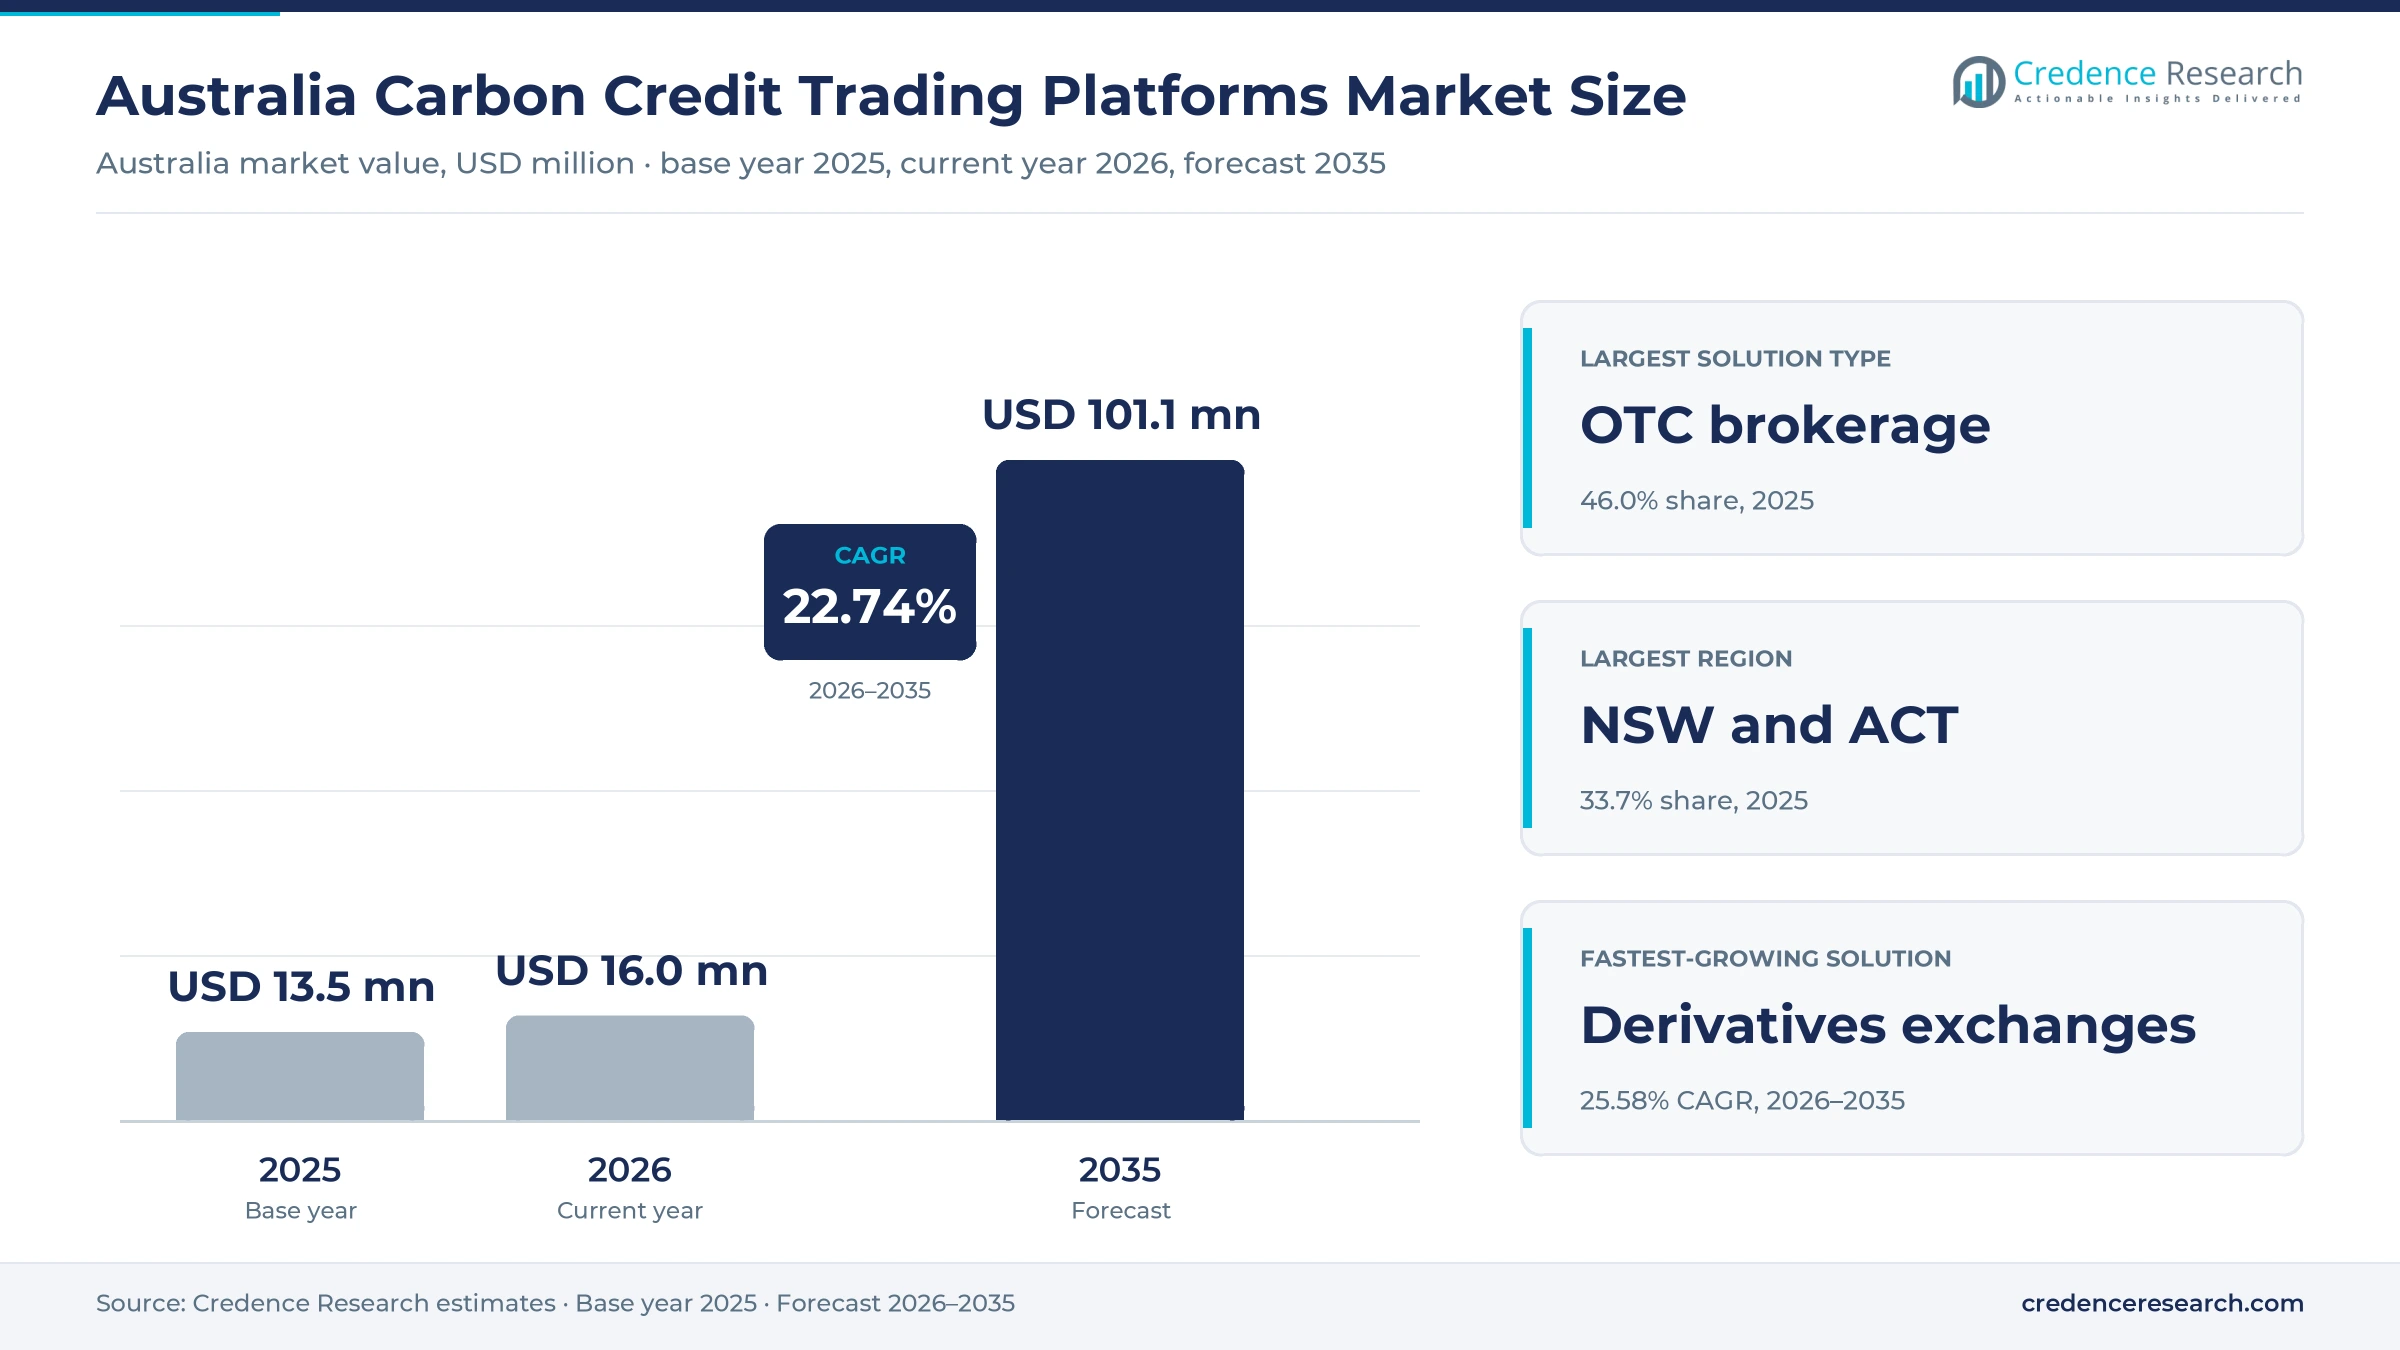
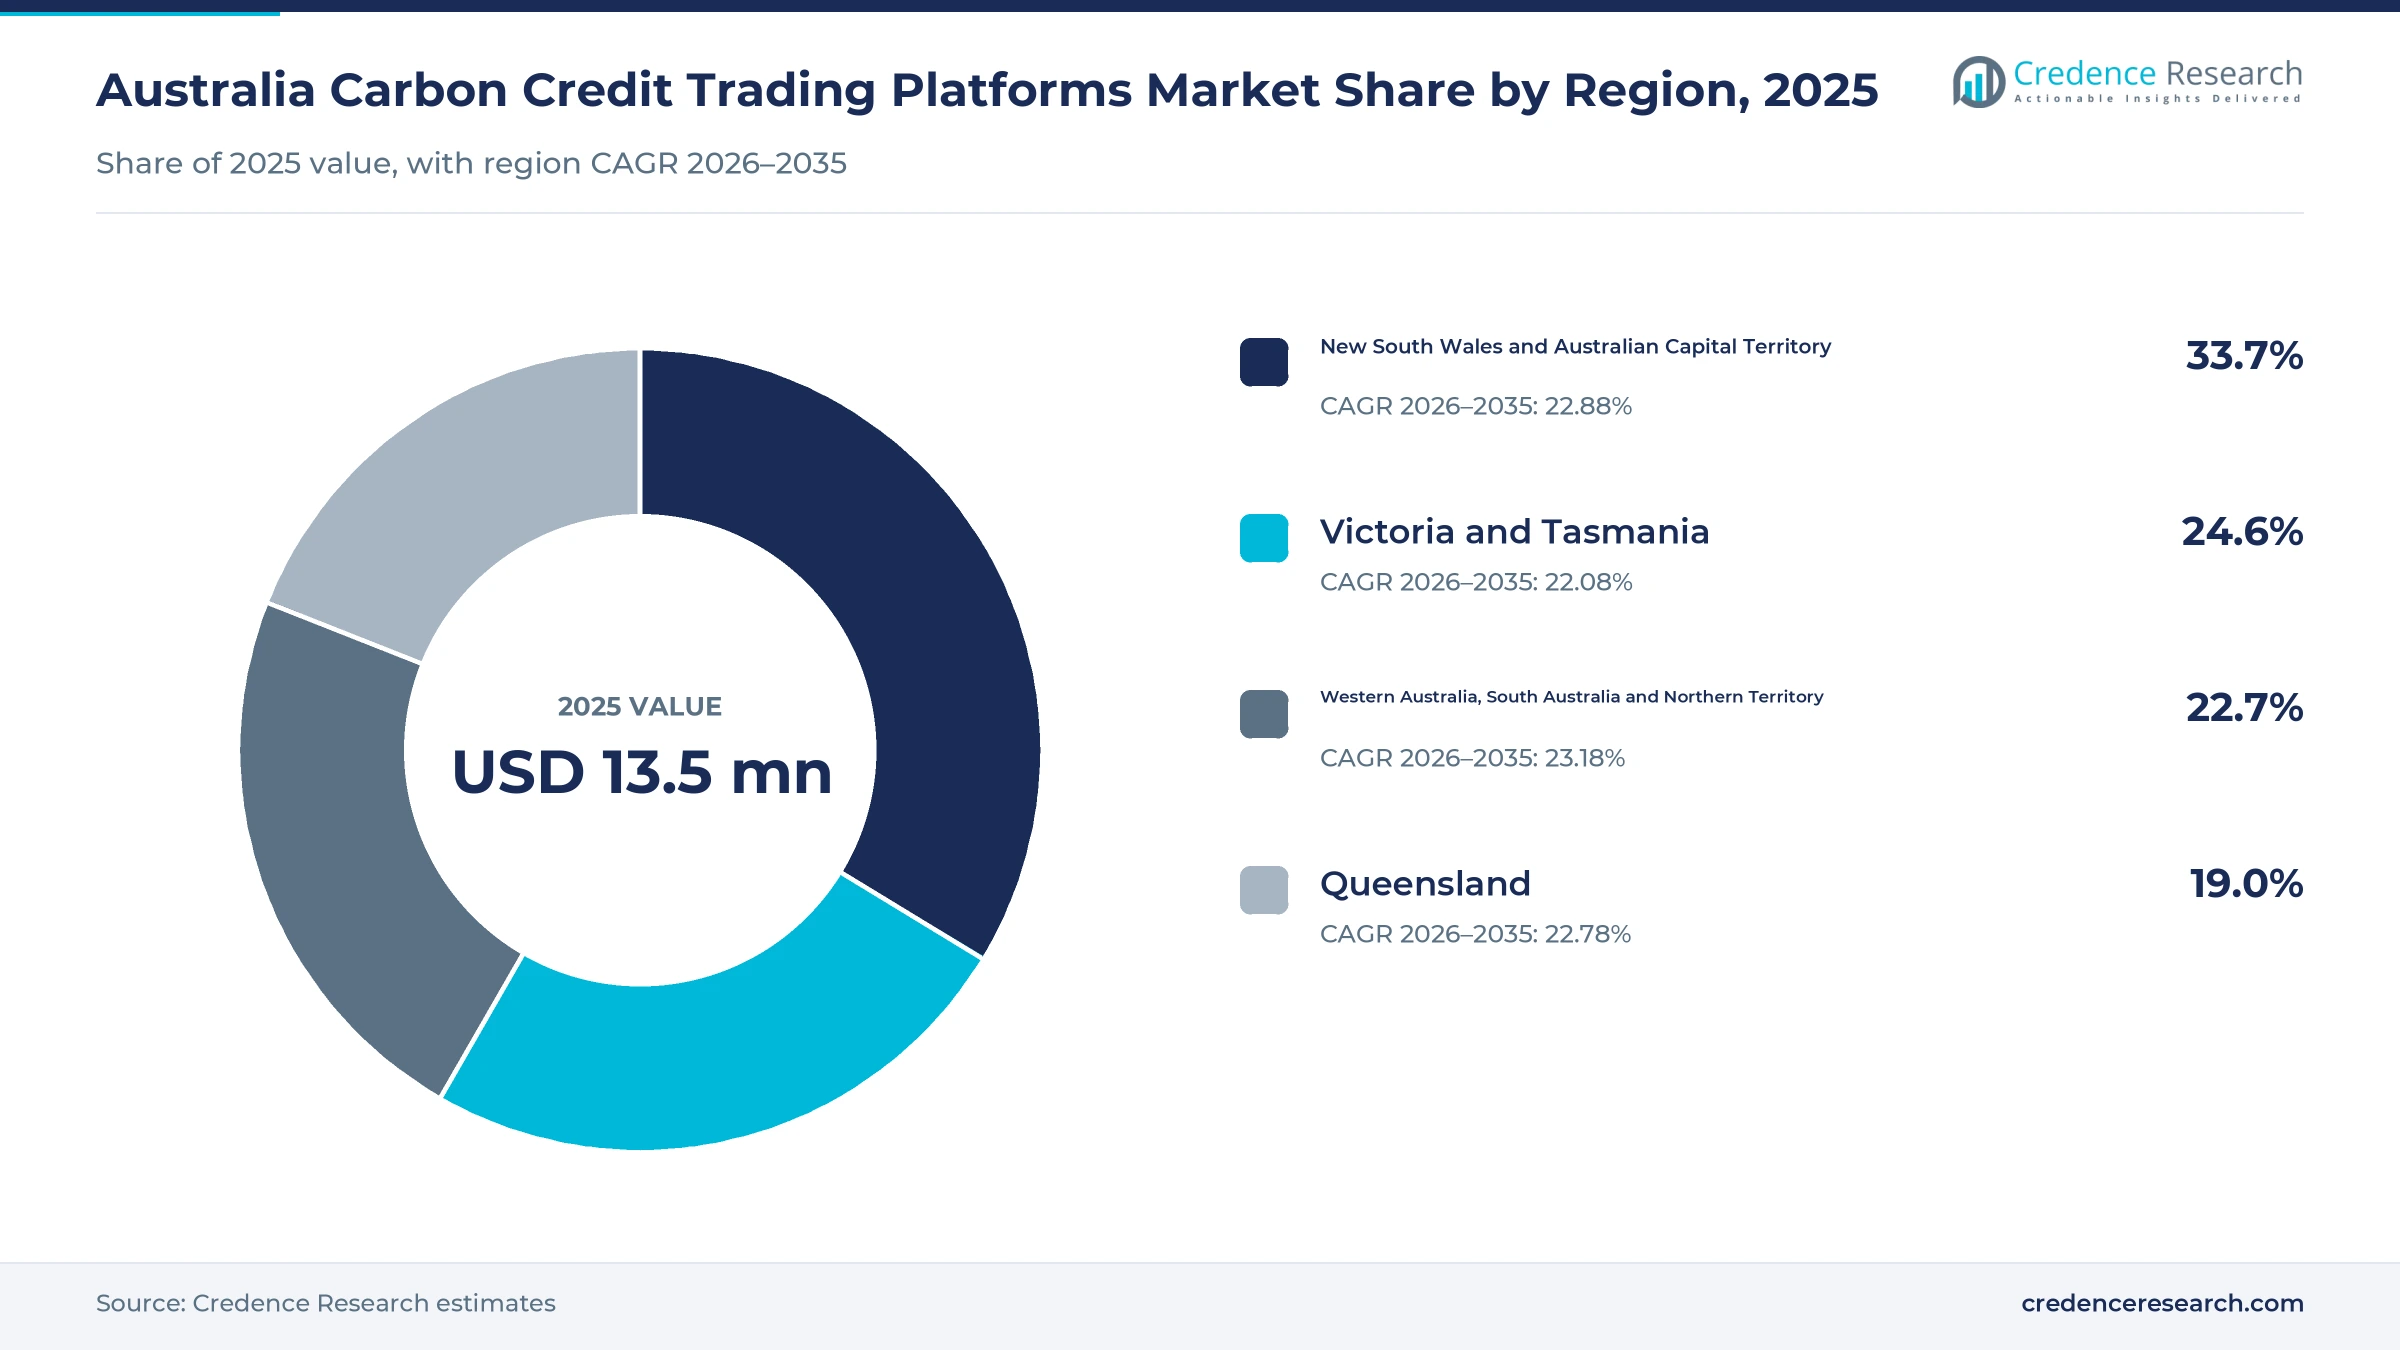
The Australia carbon credit trading platforms market was valued at USD 13.5 million in 2025 and is projected to increase from USD 16.0 million in 2026 to USD 101.1 million by 2035, registering a CAGR of 22.74% during 2026–2035. Demand comes from Safeguard facilities that must buy Australian carbon credit units and Safeguard Mechanism credit units each year, and from project developers, banks and voluntary buyers that trade through brokers, exchanges and data services. New South Wales and the Australian Capital Territory held the largest regional share, 33.7% in 2025, because Sydney hosts most brokers, exchanges and bank trading desks. Western Australia, South Australia and the Northern Territory form the fastest-growing region at 23.18% a year, as mining and gas facilities face tighter limits. However, the move of all ACCUs into a new blockchain registry in November 2025 changed how venues settle trades and connect to buyers.
Which venues, services and fees does the estimate cover?
The estimate measures fee income earned by venues and services that arrange, execute, clear or inform trades in Australian carbon credit units and Safeguard Mechanism credit units. It counts brokerage commissions, exchange and clearing fees, connectivity charges and subscriptions for market data and portfolio software paid by Safeguard operators, project developers, financial intermediaries and voluntary buyers.
The estimate excludes the value of the units themselves, project development costs, advisory fees and government purchases under fixed contracts. The value chain runs from projects and the national registry through brokers, spot screens and futures exchanges to compliance buyers, which then surrender units to meet each annual Safeguard obligation.
Australia Carbon Credit Trading Platforms Market Insights
- The Australia carbon credit trading platforms market was valued at USD 13.5 million in 2025 and is projected to reach USD 101.1 million by 2035, registering a CAGR of 22.74% during 2026–2035.
- New South Wales and the Australian Capital Territory held a 33.7% share of 2025 value, because Sydney concentrates brokers, exchange desks and bank traders.
- OTC brokerage led with a 46.0% share of 2025 value, because most ACCU deals are still negotiated by brokers who match compliance buyers with project sellers.
- The regulator migrated 177,672,533 active and cancelled ACCUs into its new Unit and Certificate Registry in November 2025, which created one ledger for ACCUs and SMCs.
- Derivatives exchanges grow fastest at 25.58% a year during 2026–2035, as ASX and CME Group futures give buyers forward prices for compliance budgets.
Brokers lead while derivatives screens grow fastest
Why does OTC brokerage still earn the largest fee pool?
Based on solution type, the market is categorized into OTC brokerage, spot exchanges, derivatives exchanges and software and data. OTC Brokerage led with a 46.0% share of 2025 value, because brokers negotiate most large compliance deals and structured forward contracts for Safeguard buyers. Derivatives Exchanges grow fastest at 25.58% a year, as listed futures let buyers lock in prices for future surrender years.
How do Safeguard operators shape platform revenue?
Based on customer type, the market is categorized into Safeguard operators, credit suppliers, financial intermediaries and voluntary buyers. Safeguard Operators led with a 44.0% share of 2025 value, because they must surrender units every year to cover emissions above their baselines. Financial Intermediaries grow fastest at 23.64% a year, as banks and trading houses add futures and market-making activity.
Which applications generate the most trading activity?
Based on application, the market is categorized into compliance procurement, risk management, voluntary retirement and portfolio intelligence. Compliance Procurement led with a 48.0% share of 2025 value, because Safeguard buyers source most units ahead of each annual surrender deadline. Risk Management grows fastest at 24.78% a year, as buyers hedge future obligations with listed futures and options.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Solution Type | OTC Brokerage | 46.0% | Derivatives Exchanges | 25.58% |
| By Customer Type | Safeguard Operators | 44.0% | Financial Intermediaries | 23.64% |
| By Application | Compliance Procurement | 48.0% | Risk Management | 24.78% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Shrinking baselines and cleared futures pull buyers onscreen
How do declining Safeguard baselines lift platform demand?
Declining compliance baselines lift platform demand, because each Safeguard facility must cover a growing gap between its emissions and a shrinking limit with ACCUs or SMCs. Baselines fall by 4.9% each financial year through June 30, 2030, under the reformed Safeguard Mechanism. The Clean Energy Regulator counted 208 covered facilities and 132.8 million metric tons of covered emissions in 2024-25, according to its April 2026 Safeguard data release. Those facilities surrendered 10.8 million ACCUs for compliance, up from 7.6 million a year earlier, while SMC surrenders rose to 2.6 million. As a result, Safeguard operators hold 44.0% of 2025 value, because they buy most units through brokers and screens before each compliance deadline.
Why does electronic execution and settlement widen access?
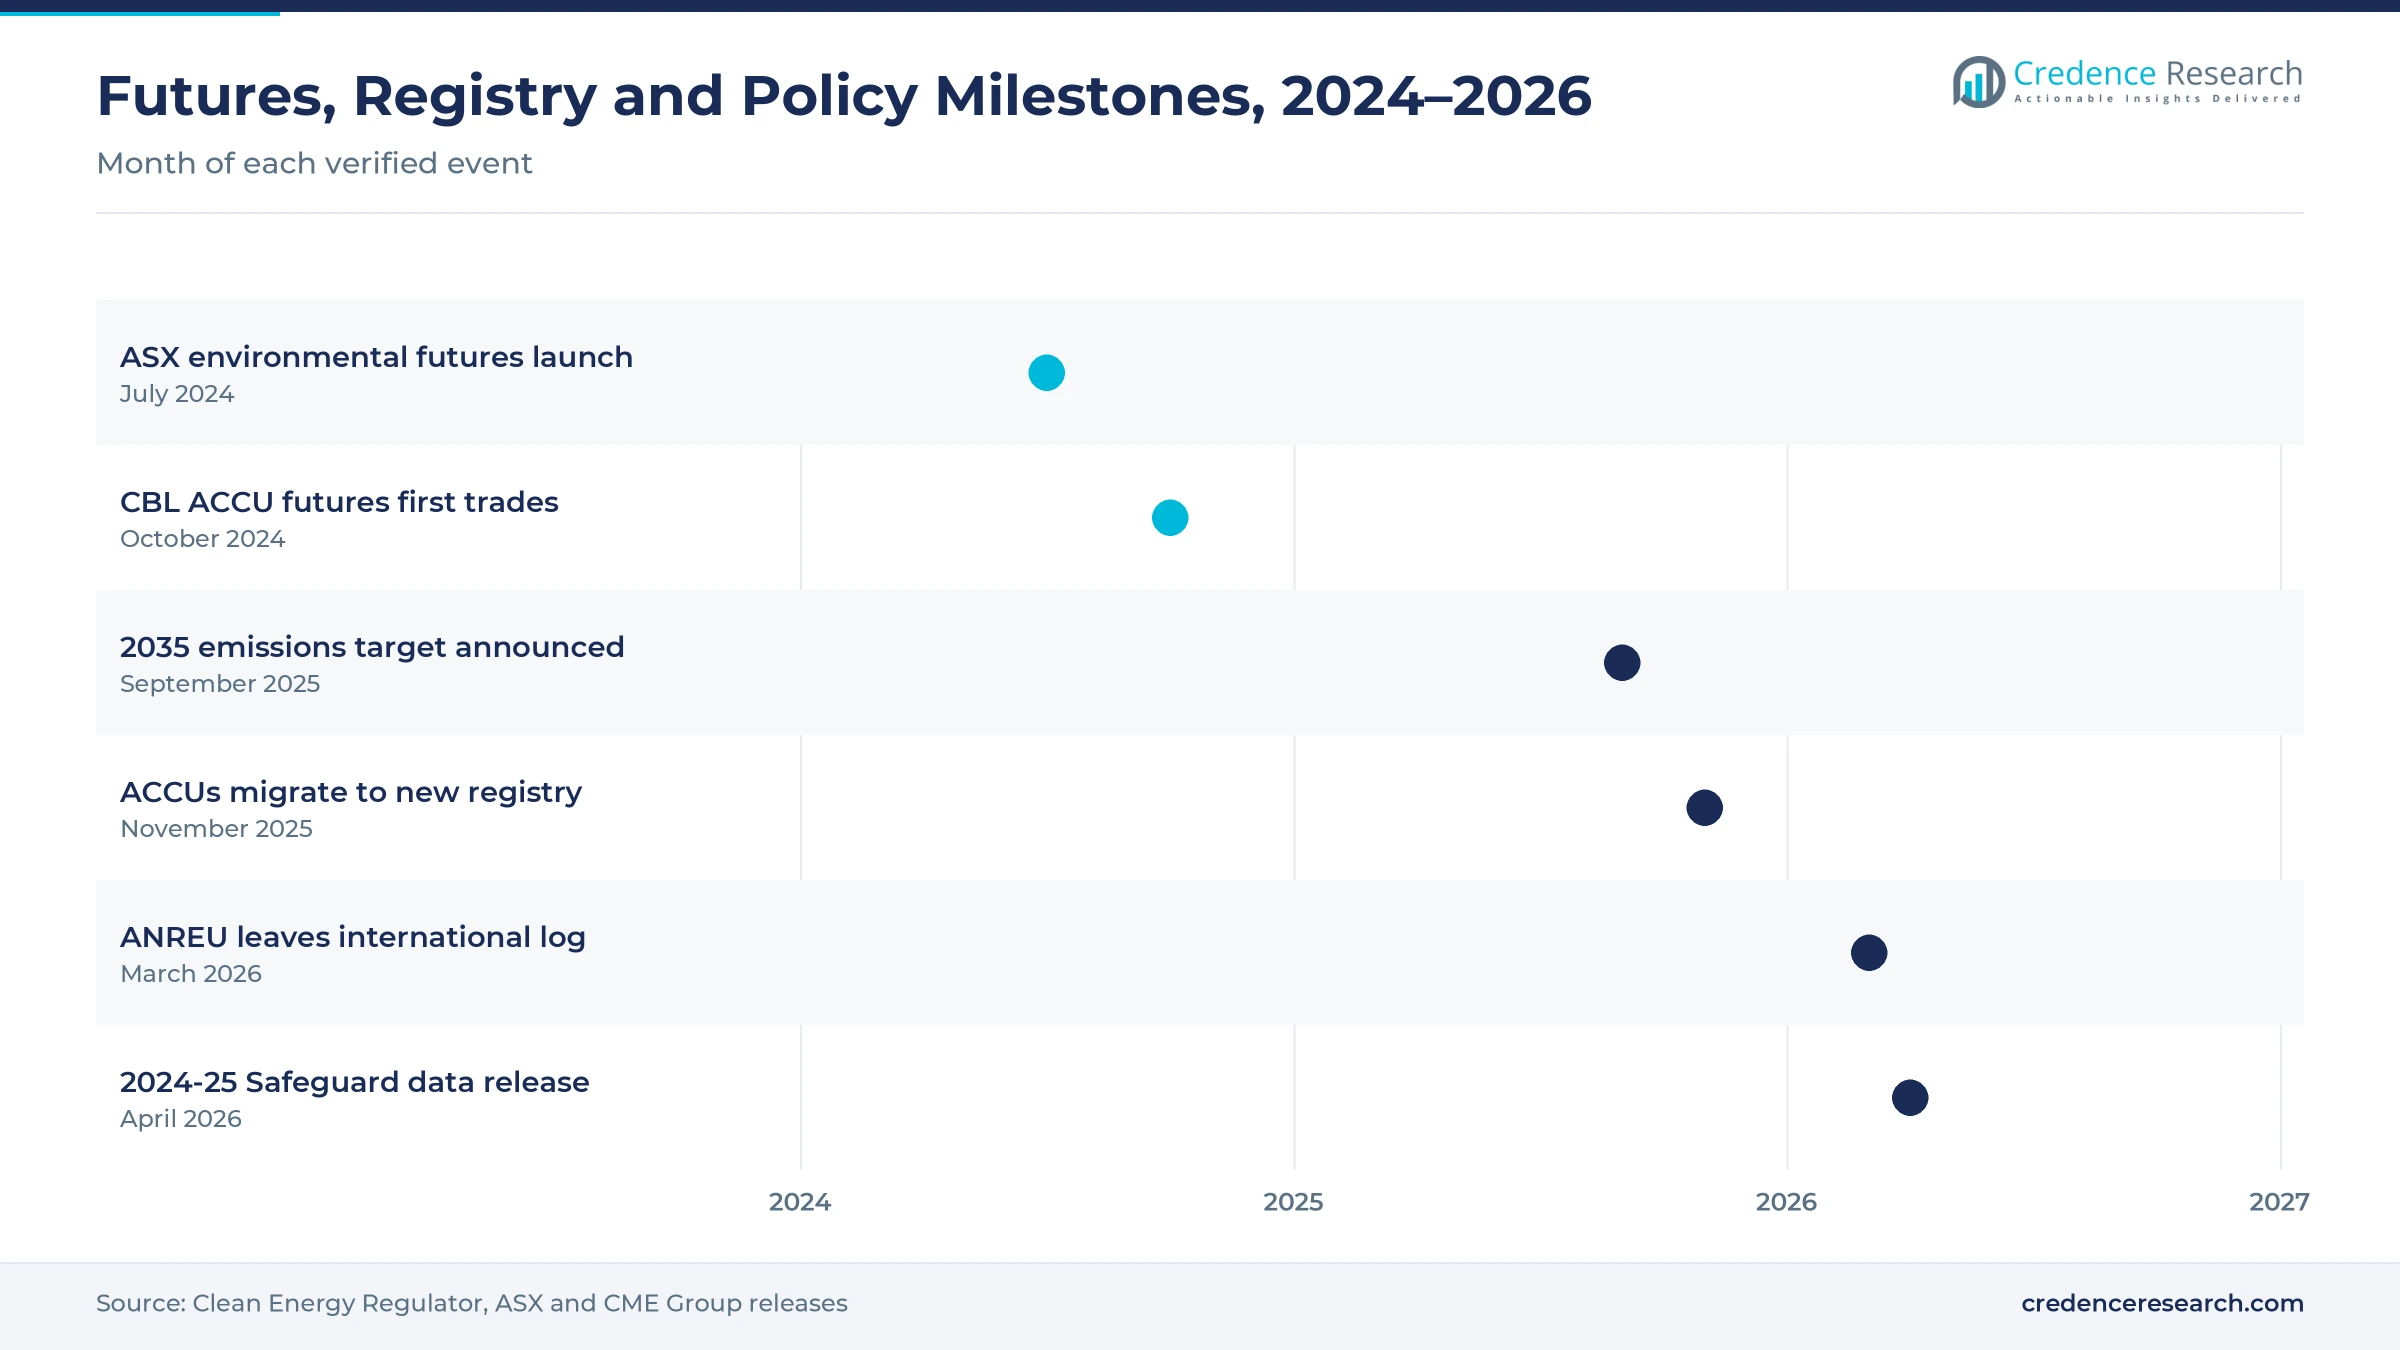
Electronic execution and settlement formalization widen access, because buyers now expect screen trading, cleared contracts and registry delivery instead of informal phone deals. The regulator migrated 177,672,533 active and cancelled ACCUs into its new Unit and Certificate Registry in November 2025, with SMCs held in the same ledger. ACCUs and SMCs are also financial products under the Corporations Act, so many brokers and venues need an Australian financial services license. ASX listed physically delivered ACCU, NZU and large-scale renewable energy certificate futures on July 29, 2024, according to its exchange launch release. In turn, spot exchanges gain share from brokerage, because registry links and licensing make screen execution easier for mid-sized buyers.
How do hedging tools and benchmarks deepen liquidity?
Hedging and benchmark development deepen liquidity, because compliance buyers want forward prices to budget for units years before surrender dates. CME Group launched CBL ACCU futures with Xpansiv, and the first five contracts traded as a block between Freepoint Commodities and Mercuria on Oct. 14, 2024, according to CME Group. ASX also aims to offer annual forward prices out to five years on its environmental futures. Derivatives volume in the brokered ACCU market reached 6.11 million units in 2024, up from 1.88 million in 2023. As a result, risk management grows at 24.78% a year, the fastest application during 2026–2035, as buyers pair spot purchases with risk management software.
Why does record ACCU issuance add tradable supply?
Record ACCU issuance adds tradable supply, because every new unit that reaches a seller account can be listed, brokered or hedged on a platform. The regulator issued a record 21.7 million ACCUs in 2025 and expects between 22 million and 26 million in 2026. Holdings outside the cost containment measure reached 60.7 million at the end of 2025, which gives sellers a large inventory to trade. Issuance in the first half of 2026 reached 10.9 million ACCUs, 15% higher than the same period a year earlier. In turn, credit suppliers use brokers and offset marketplaces to sell units from more than 600 existing projects to compliance and voluntary buyers.
Record ACCU volumes and SMC supply reshape execution
How is the rise in brokered ACCU volume changing execution?
The rise in brokered ACCU volume is changing execution, because larger and more frequent deals push brokers toward standard contracts and electronic confirmation. Secondary market volume reached just under 30 million ACCUs in 2024, about 2.5 million units a month, according to CORE Markets platform data. The spread between human-induced regeneration units and generic ACCUs reached parity in November 2024 and stayed level through December. Option strike prices for 2025 expiry contracts were set between A$28 and A$42, which shows buyers using structured products. As a result, OTC brokerage keeps 46.0% of 2025 value, because brokers still arrange most of these tailored deals.
Why is the emergence of SMCs a shift for venues?
The emergence of Safeguard Mechanism credit units is a shift for venues, because a second compliance unit now trades alongside ACCUs in the same registry. The regulator issued 6.7 million SMCs to 54 facilities for 2024-25, after 8.3 million to 64 facilities a year earlier. SMC surrenders for compliance rose to 2.6 million units in 2024-25, up from 1.4 million in 2023-24. The default prescribed SMC price for 2023-24 was A$33.19, which gave buyers a public reference point. In turn, financial intermediaries grow at 23.64% a year, the fastest customer type, as banks and trading houses quote both units.
Can a tighter 2035 target open more compliance flow?
A tighter 2035 target can open more compliance flow, because deeper emissions cuts raise the number of units Safeguard facilities must buy after 2030. The government announced a target of a 62% to 70% cut below 2005 levels by 2035 on Sept. 18, 2025. The Safeguard Mechanism is also due for review in 2026-27, with options that may include a lower facility threshold. The regulator says annual demand will grow and may surpass annual supply later this decade as baselines decline. As a result, platforms that serve compliance procurement can expect steady fee growth, because that application holds 48.0% of 2025 value.
Is there room for data and portfolio software growth?
Data and portfolio software offer room to grow, because buyers that hold several unit types need tools to track prices, holdings and surrender needs. Carbon pricing revenues exceeded US$100 billion in 2024, and around 28% of global emissions are now covered by a carbon price, according to the World Bank. The same release counted 80 carbon pricing instruments worldwide and said compliance market demand for credits almost tripled. In turn, Australian buyers link registry data with emissions accounting tools, which lifts subscriptions for portfolio intelligence services across Safeguard and voluntary accounts. As a result, software and data vendors gain recurring income that does not depend on daily spot trading volumes.
Unit surpluses and thin screens limit fee growth
How does a large unit surplus weigh on fee income?
A large unit surplus weighs on fee income, because ACCU issuance still outpaces surrenders and voluntary cancellations on an annual basis. As a result, prices can soften and brokers that charge per unit or per dollar earn less on each trade during quiet periods. Platforms respond with subscription data, futures clearing and portfolio tools, which earn steady fees even when spot prices fall. This pressure eases only as declining Safeguard baselines lift annual demand.
Why do integrity reviews slow some project sales?
Integrity reviews slow some project sales, because buyers worry about method changes and the quality of units from certain project types. In turn, sellers of contested units face wider spreads and longer deal times, which reduces brokered volume for those credits. Venues respond with project-level data, standard contract terms and clearer labeling, which help buyers screen units before purchase. This concern keeps pressure on venues to publish more project information.
How does thin screen liquidity limit exchange growth?
Thin screen liquidity limits exchange growth, because large compliance buyers still prefer negotiated deals that move size without shifting prices. As a result, listed spot and futures contracts can trade only a few blocks on many days, which deters new participants. Exchanges respond with fee waivers, market makers and block trade facilities, which help build depth over time. This challenge favors venues that can attract bank and trading house liquidity.
Why do licensing rules raise costs for small venues?
Licensing rules raise costs for small venues, because ACCUs and SMCs are financial products that can require an Australian financial services license or a market license. In turn, new entrants spend more on compliance staff, legal advice and reporting before they earn fees. Smaller platforms respond by partnering with licensed brokers or exchanges, which shortens entry time and spreads compliance costs. This rule protects buyers yet raises the bar for start-up venues.
Sydney finance and western emitters anchor platform demand
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Australian Capital Territory | 4.5 | 33.7% | 22.88% |
| Victoria and Tasmania | 3.3 | 24.6% | 22.08% |
| Western Australia, South Australia and Northern Territory | 3.1 | 22.7% | 23.18% |
| Queensland | 2.6 | 19.0% | 22.78% |
Why do New South Wales and the ACT hold the top share?
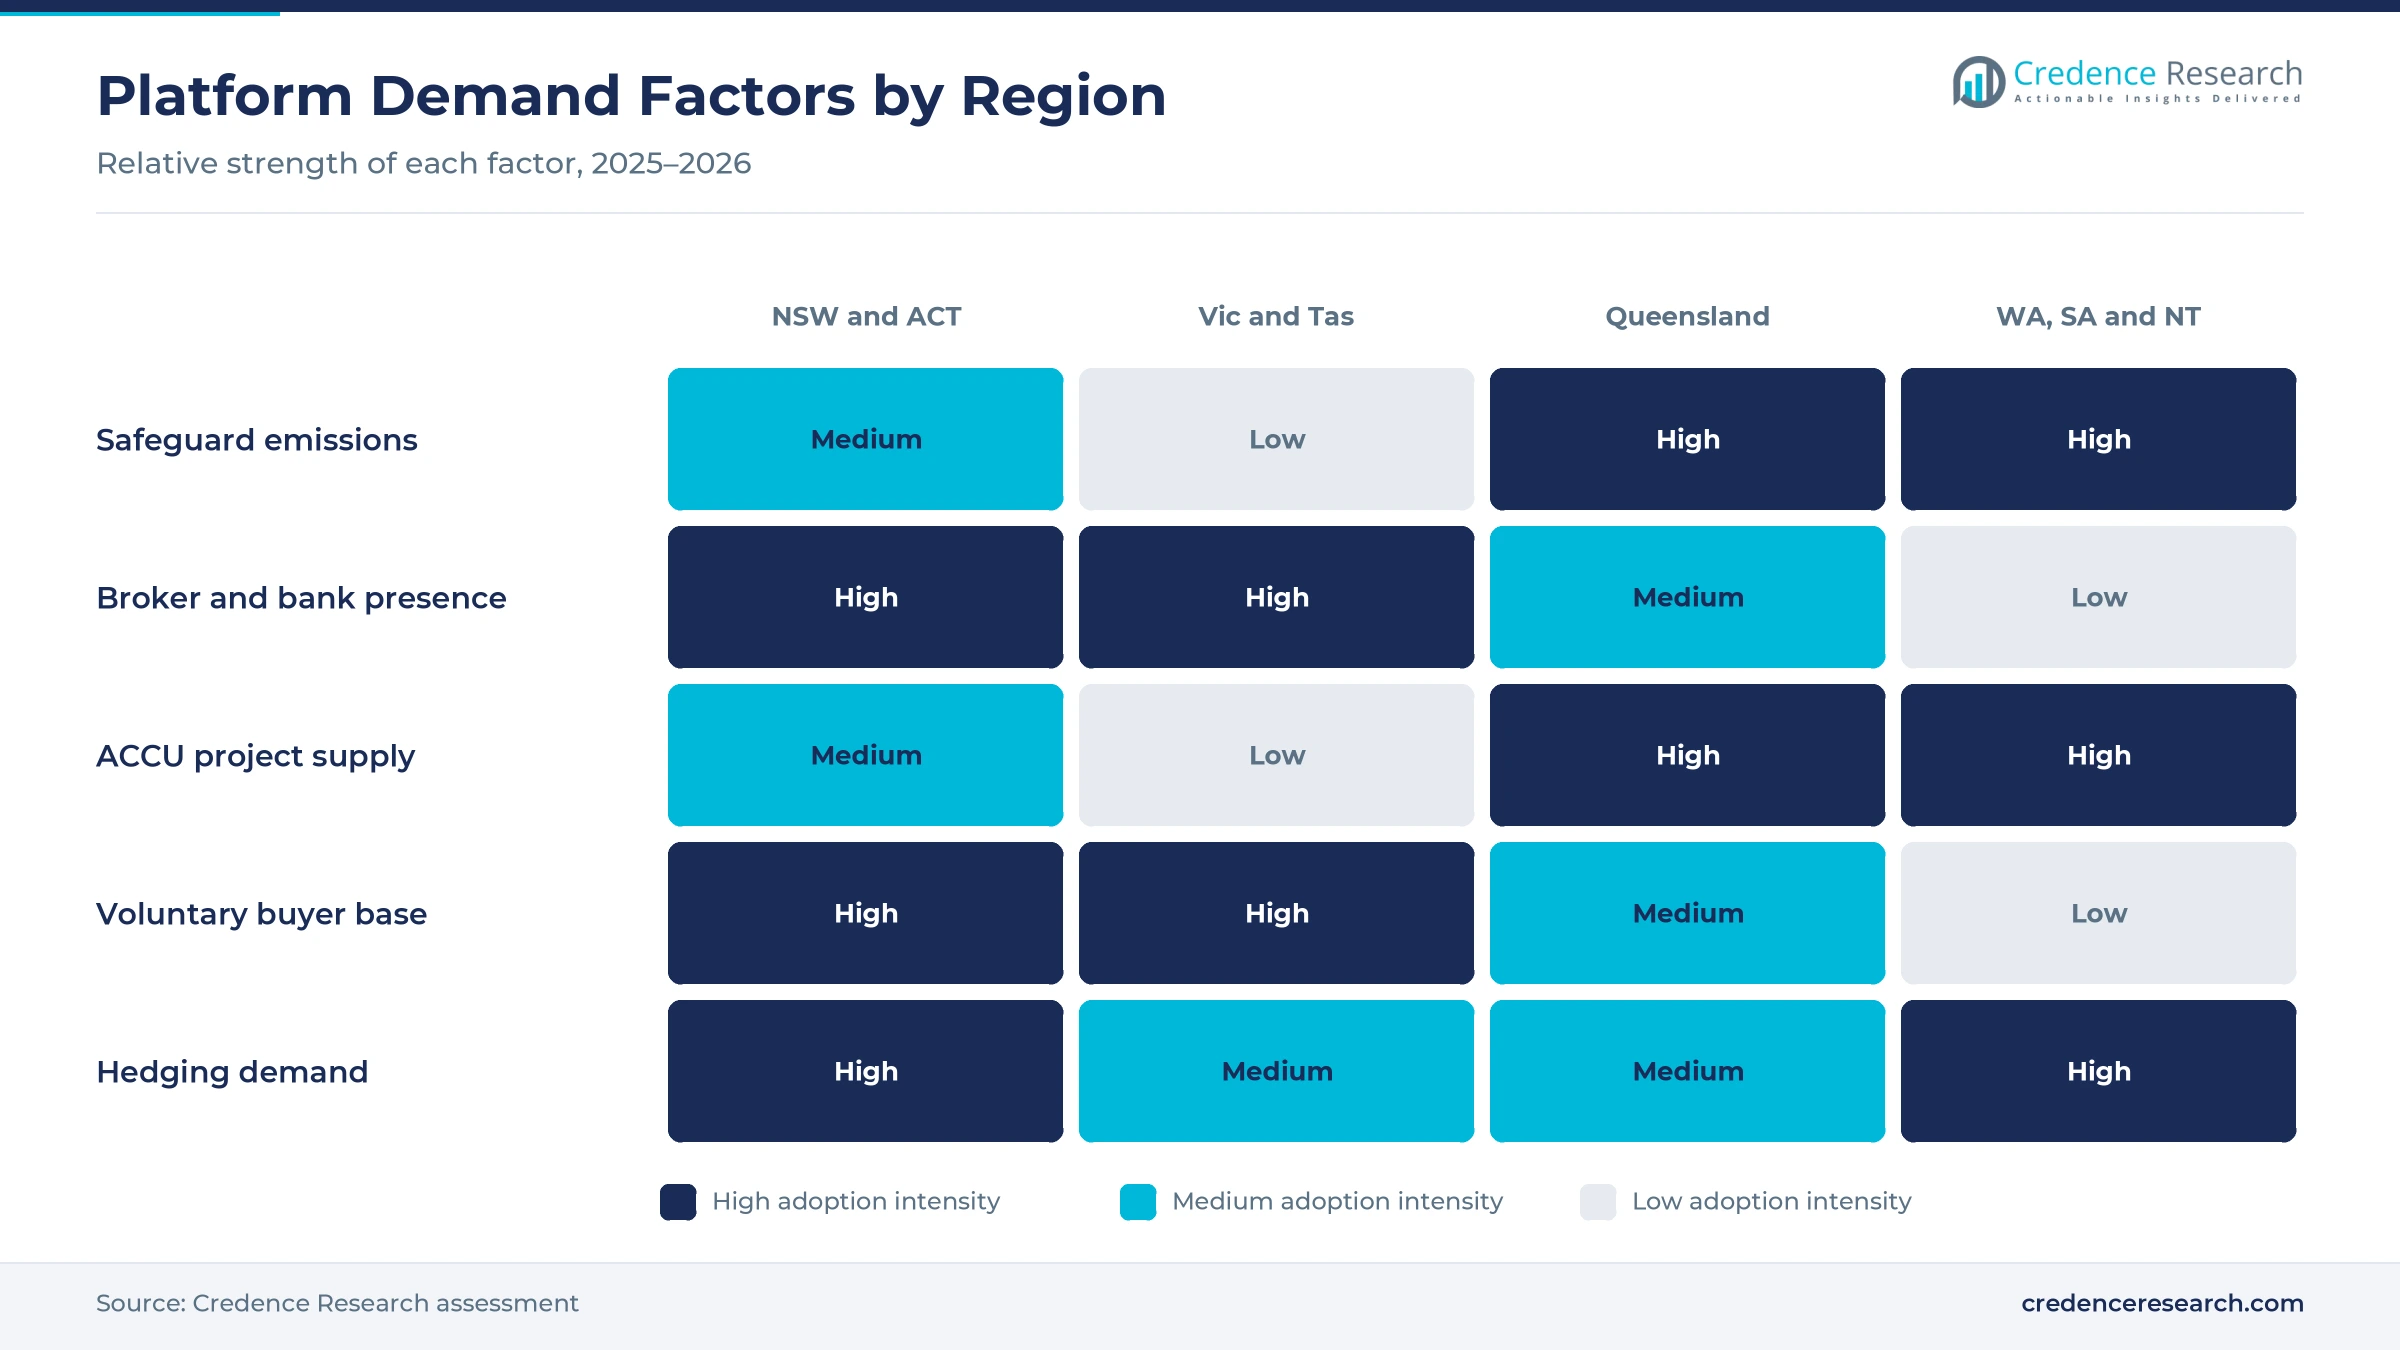
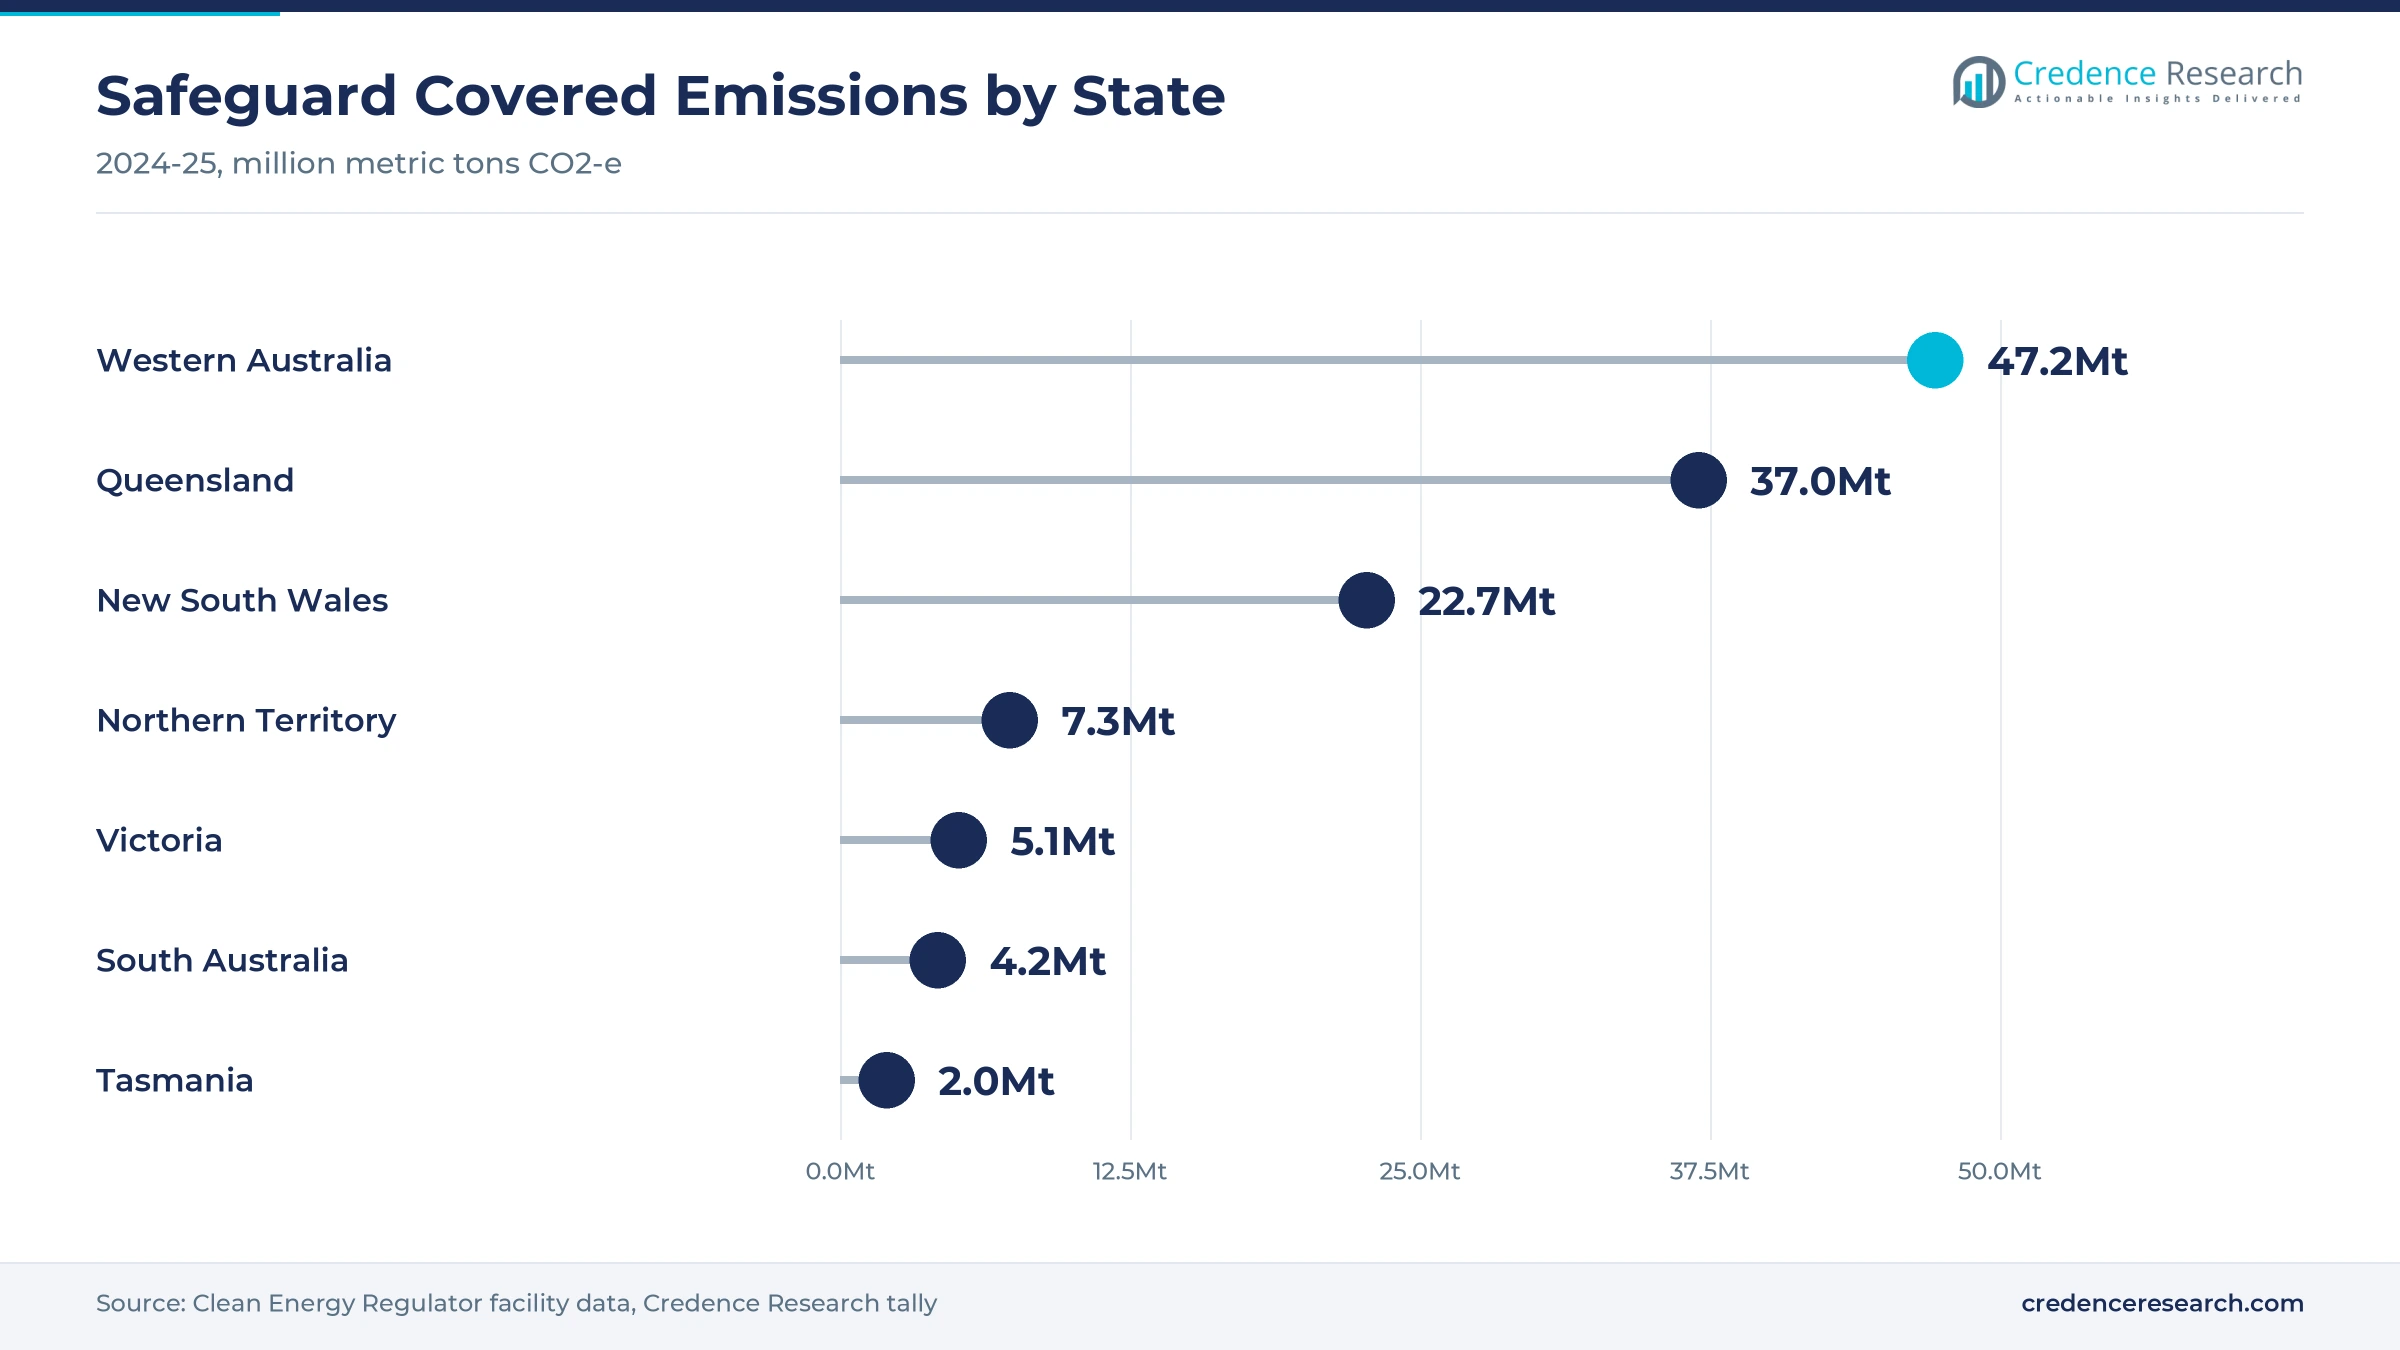
New South Wales and the Australian Capital Territory held a 33.7% share of 2025 value and grow at 22.88% a year, because Sydney concentrates brokers, exchange desks and bank traders. Facilities in New South Wales reported 22.7 million metric tons of covered emissions in 2024-25, and coal mines made up 26 of its 34 facility entries. As a result, the zone combines large compliance buyers with the deepest pool of intermediaries.
How do Victoria and Tasmania support trading activity?
Victoria and Tasmania held a 24.6% share of 2025 value and grow at 22.08% a year, because Melbourne hosts brokers, advisers and corporate voluntary buyers. Covered facilities in Victoria reported 5.1 million metric tons of emissions in 2024-25, while Tasmanian facilities reported 2.0 million metric tons. In turn, this zone relies more on voluntary retirement and portfolio data than on heavy compliance buying.
What drives compliance buying in Queensland?
Queensland held a 19.0% share of 2025 value and grows at 22.78% a year, because coal mines and industrial plants in the state face declining Safeguard baselines. Queensland facilities reported 37.0 million metric tons of covered emissions in 2024-25, the second largest total of any state. The state had 70 facility entries in the regulator's 2024-25 table, second only to Western Australia. As a result, Queensland generates steady compliance demand from mining and heavy industry.
Why are western Australia, South Australia and the NT growing fastest?
Western Australia, South Australia and the Northern Territory held a 22.7% share of 2025 value and grow fastest at 23.18% a year. Western Australian facilities reported 47.2 million metric tons of covered emissions in 2024-25, the largest total of any state. Northern Territory facilities added 7.3 million metric tons and South Australian facilities 4.2 million metric tons. In turn, gas and mining operators in this zone buy a growing number of units each year.
Futures listings, registry migration and policy milestones
| Development | Status and market relevance |
|---|---|
| In July 2024, ASX launched ACCU, LGC and NZU futures on its ASX 24 market with physical delivery. | Gave buyers the first listed local forward curve |
| In October 2024, CME Group and Xpansiv launched CBL ACCU futures, with first trades on Oct. 14, 2024. | Linked a global futures venue to the CBL spot market |
| In September 2025, the government announced a 2035 target of a 62% to 70% cut below 2005 levels. | Signals tighter Safeguard limits after 2030 |
| In November 2025, the regulator migrated 177,672,533 ACCUs into the new Unit and Certificate Registry. | Created one ledger for ACCUs and SMCs |
| In April 2026, the regulator released 2024-25 Safeguard data showing 10.8 million ACCUs surrendered. | Confirms rising compliance demand for units |
Registry ledgers and physical delivery underpin execution
- Blockchain registry ledgers hold ACCUs and SMCs in one Unit and Certificate Registry built on Trovio's CorTenX service, which gives account holders richer unit data and multi-factor transfer checks.
- Physically delivered futures settle into registry accounts at expiry, which lets buyers hedge future surrender needs and still receive real units for compliance.
- Electronic spot screens match standard ACCU contracts anonymously and provide a reference price that futures contracts and brokers can settle against.
- Post-trade delivery services manage registry transfers for futures positions held to expiry, which reduces settlement risk for buyers and sellers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Brokers, exchanges and spot screens compete for ACCU flow
Competition combines OTC brokers that arrange most large compliance deals with exchanges that offer screen trading and cleared futures. Xpansiv runs the CBL spot market, and its ACCU contract also serves as the settlement reference for CME Group futures launched in October 2024. ASX competes with physically delivered ACCU, LGC and NZU futures listed on its ASX 24 market in July 2024. CORE Markets competes in brokerage and publishes market data from its own platform, including the near 30 million ACCUs that traded in 2024. Jarden is listed by the Carbon Market Institute as a carbon broker and carbon trader. Rivals compete on liquidity, registry connectivity, licensing, price data and the ability to structure forward and option contracts for Safeguard buyers.
Which venues and brokers handle ACCU flow?
| Company | Type | Role in the market |
|---|---|---|
| Xpansiv / CBL | Spot exchange | Runs the CBL spot ACCU market used for futures settlement |
| CME Group | Derivatives exchange | Lists CBL ACCU futures launched in October 2024 |
| ASX | Derivatives exchange | Lists ACCU, LGC and NZU futures since July 2024 |
| CORE Markets | Broker and data provider | Brokers ACCU deals and publishes market volume data |
| Jarden commtrade | Broker and trader | Listed as a carbon broker and trader by the Carbon Market Institute |
Credence Research view on ACCU market infrastructure
Credence Research's view is that Australian ACCU market infrastructure will grow quickly because Safeguard baselines keep falling while supply rises, which forces more buyers and sellers onto formal venues. OTC brokerage remains the largest fee pool, yet listed futures and software services add the fastest growth. The new registry and financial product licensing raise standards for every venue. Platforms that combine deep liquidity, registry links and reliable price data should gain the most share by 2035.
How the ACCU platform fee estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines regulator data on unit issuance, surrenders and holdings, exchange and broker releases on contract launches and volumes, and international agency data on carbon pricing. Segment splits and zone growth rates are Credence Research estimates, while zone shares follow the client-provided split. Sources used are regulator releases, exchange and company releases and international agency publications, and no interviews or surveys were used.
Tighter limits after 2030 keep fee pools expanding to 2035
The Australia carbon credit trading platforms market is expected to reach USD 101.1 million by 2035, a 22.74% CAGR during 2026–2035, as Safeguard limits tighten and more buyers use cleared and electronic venues. Growth should be strongest in derivatives exchanges, risk management and the western zone, because these areas gain most from hedging needs and large emitters. Unit surpluses, thin screens and licensing costs could slow some venues, while the 2035 target should support demand after 2030.
Frequently Asked Questions
How big is the Australia carbon credit trading platforms market?
Which solution type leads ACCU platform revenue?
Which region leads the market?
How fast do Safeguard baselines decline?
How many ACCUs were issued in 2025?
When did ACCU futures start trading?
Who are the leading companies in Australian ACCU trading?
What are the main challenges for trading venues?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Solution Type
- 1.2.1 OTC Brokerage
- 1.2.2 Spot Exchanges
- 1.2.3 Derivatives Exchanges
- 1.2.4 Software and Data
- 1.3 By Customer Type
- 1.3.1 Safeguard Operators
- 1.3.2 Credit Suppliers
- 1.3.3 Financial Intermediaries
- 1.3.4 Voluntary Buyers
- 1.4 By Application
- 1.4.1 Compliance Procurement
- 1.4.2 Risk Management
- 1.4.3 Voluntary Retirement
- 1.4.4 Portfolio Intelligence
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 13.5 million → 2035: USD 101.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Carbon Credit Trading Platforms Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Carbon Credit Trading Platforms Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Australia Carbon Credit Trading Platforms Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Australia Carbon Credit Trading Platforms Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Carbon Credit Trading Platforms Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Carbon Credit Trading Platforms Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Carbon Credit Trading Platforms Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Carbon Credit Trading Platforms Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 13.5 million → 2035: USD 101.1 million)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Carbon Credit Trading Platforms Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Solution Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 OTC Brokerage
- 12.3.6.2 Spot Exchanges
- 12.3.6.3 Derivatives Exchanges
- 12.3.6.4 Software and Data
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Customer Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Safeguard Operators
- 12.4.6.2 Credit Suppliers
- 12.4.6.3 Financial Intermediaries
- 12.4.6.4 Voluntary Buyers
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Compliance Procurement
- 12.5.6.2 Risk Management
- 12.5.6.3 Voluntary Retirement
- 12.5.6.4 Portfolio Intelligence
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Carbon Credit Trading Platforms End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Carbon Credit Trading Platforms Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Carbon Credit Trading Platforms Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Carbon Credit Trading Platforms Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Xpansiv / CBL
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 CORE Markets
- 18.4 Jarden commtrade
- 18.5 Marex
- 18.6 HVB Markets
- 18.7 ASX
- 18.8 CME Group
- 18.9 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

