
Digital checkout and small business credit sustain growth
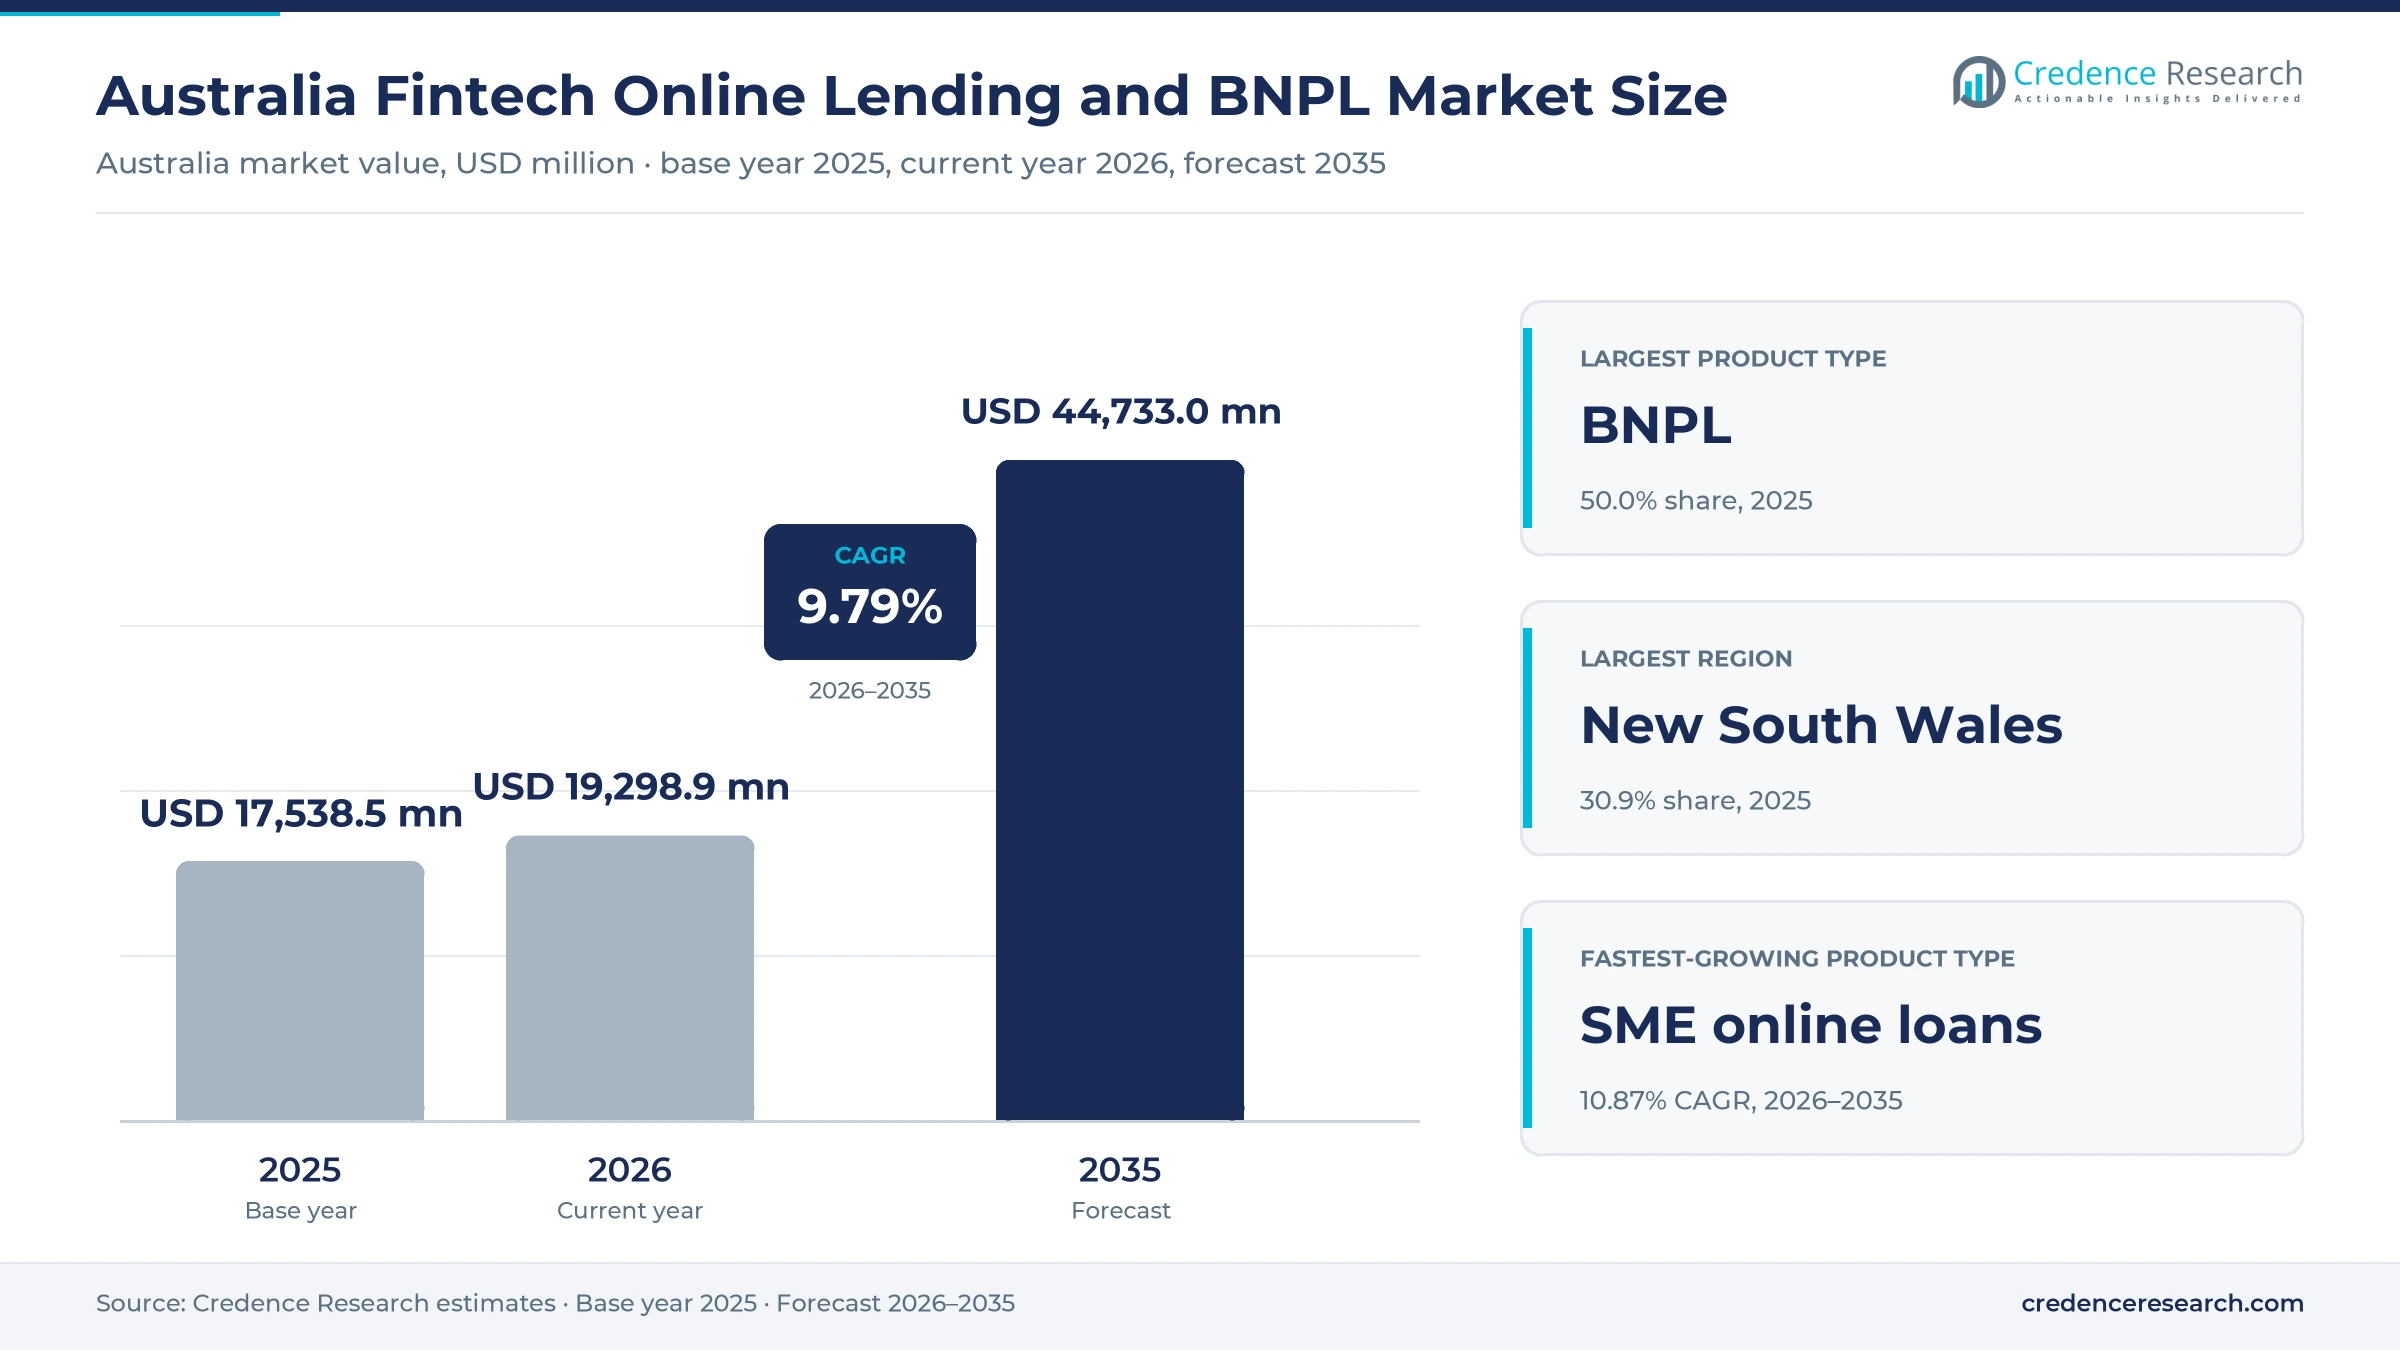
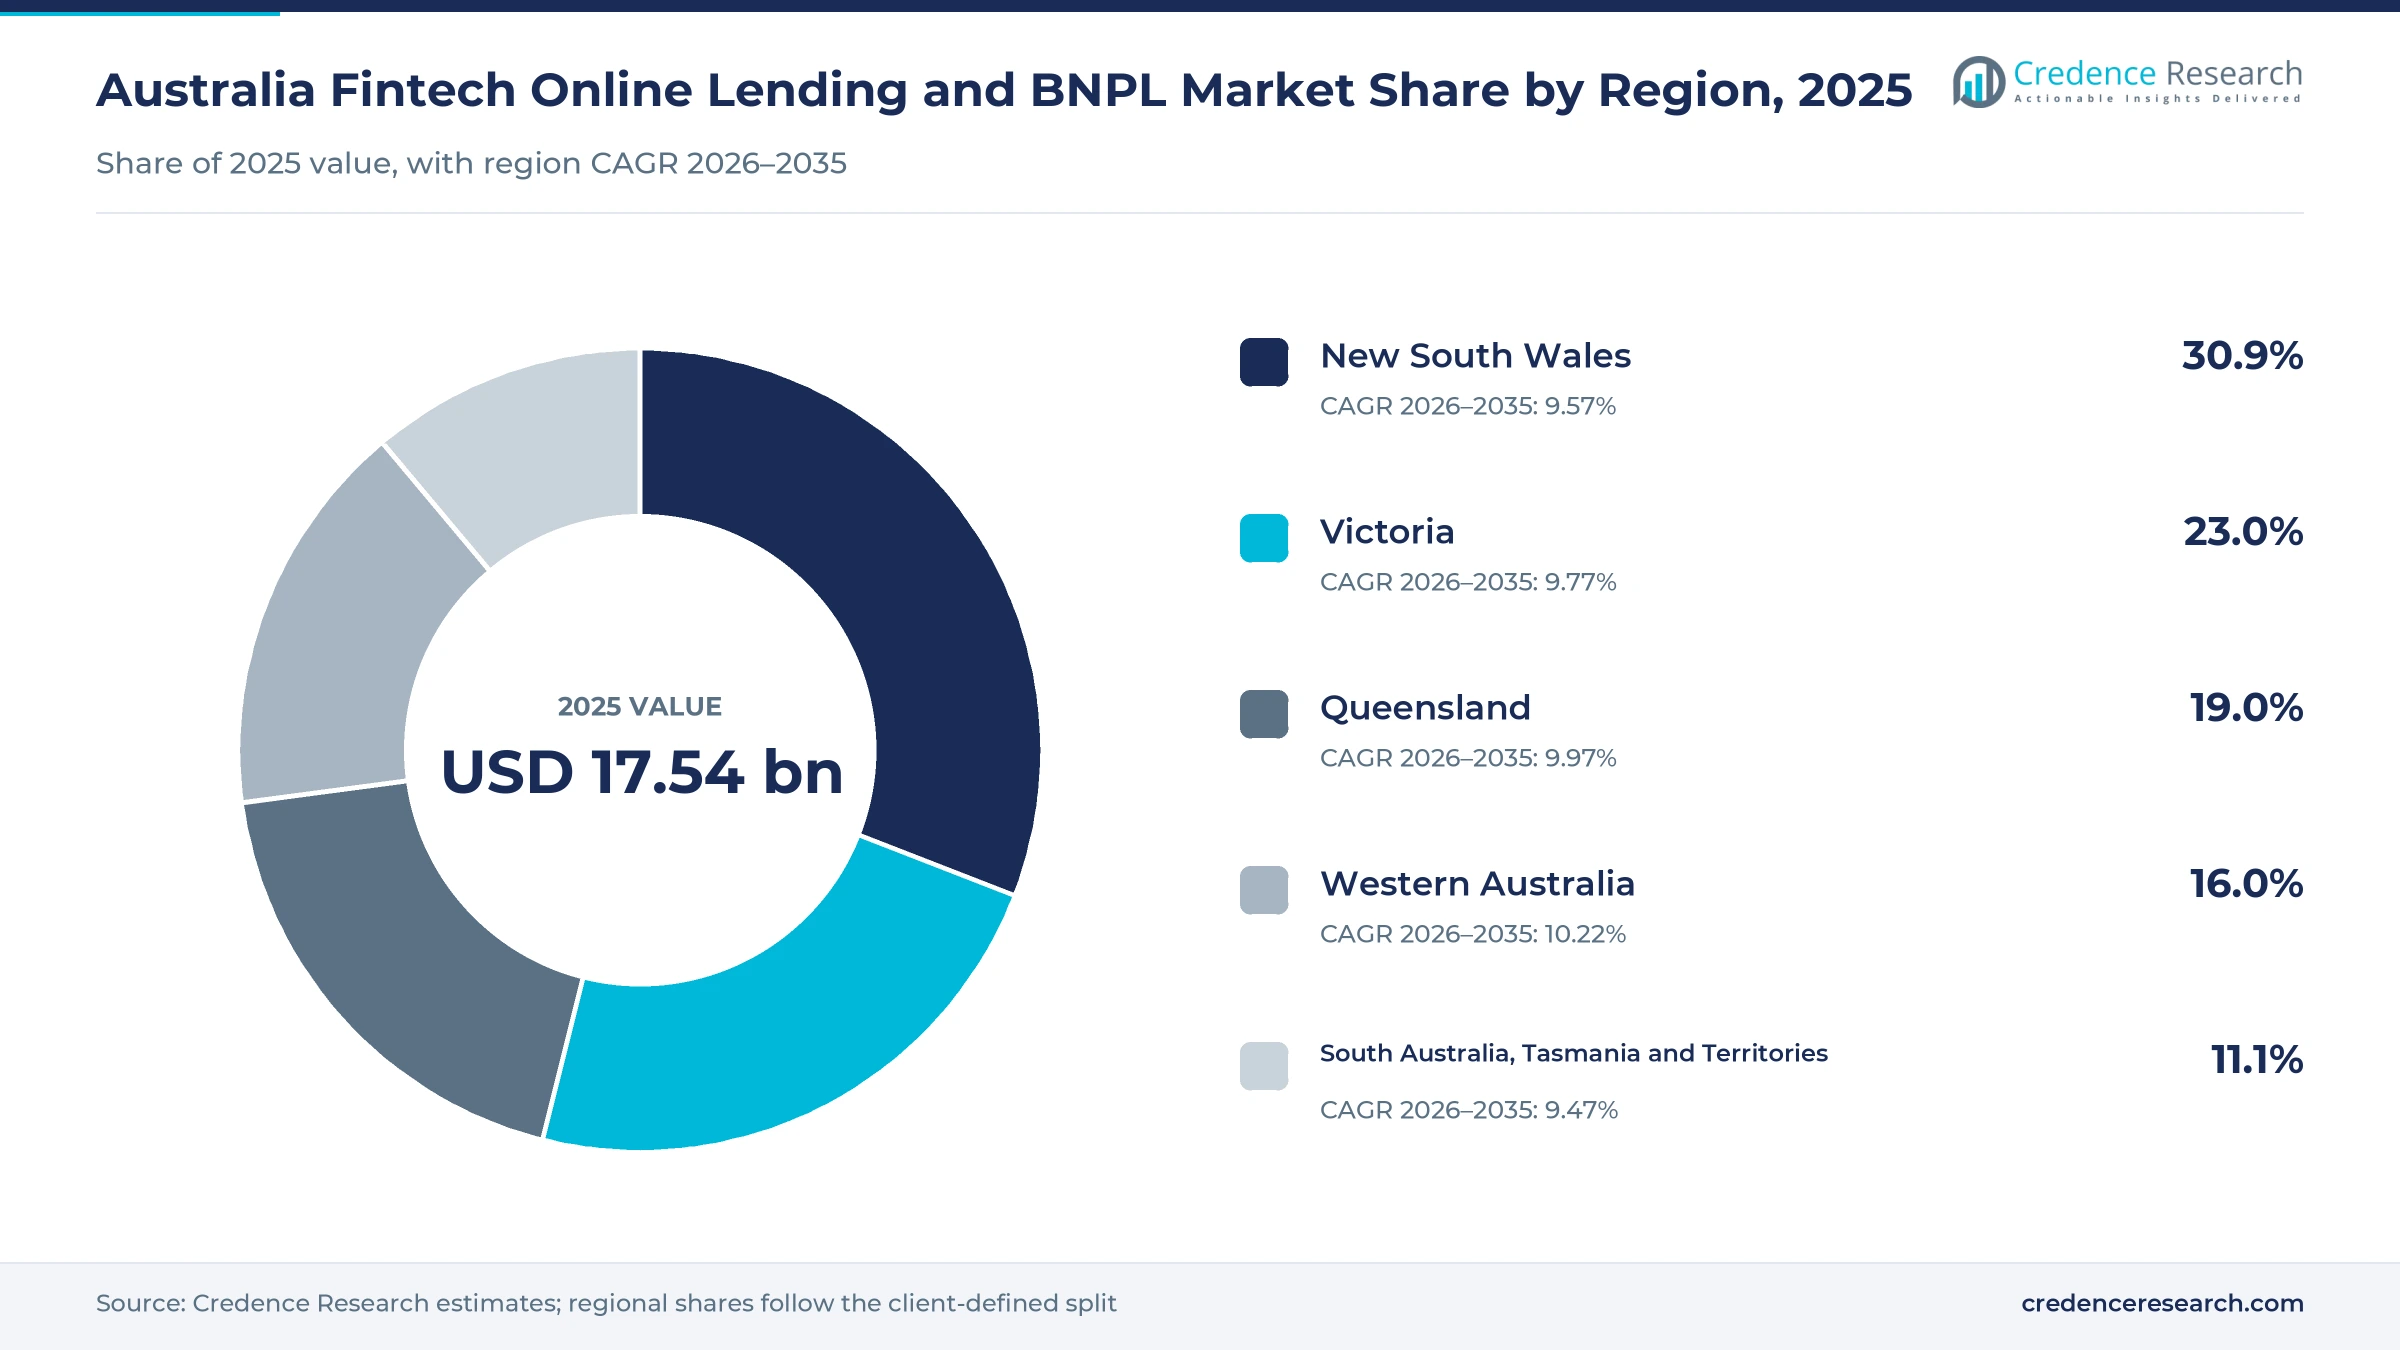
The Australia Fintech online lending and BNPL market was valued at USD 17.54 billion in 2025 and is projected to increase from USD 19.30 billion in 2026 to USD 44.73 billion by 2035, registering a CAGR of 9.79% during 2026–2035. Demand comes from shoppers who split online and in-store purchases into installments, salaried and self-employed borrowers who take personal loans through apps, and small businesses that need fast working capital. New South Wales held the largest regional share, 30.9% in 2025, because the state has the largest population, the most online retail spending and the largest net gain in businesses. Western Australia is the fastest-growing region at 10.22% a year, as business formation and population growth outpace other states. In turn, installment payment contracts became regulated credit on June 10, 2025, which requires providers to hold a credit licence and run affordability checks.
Which digital credit products and borrowers does the estimate cover?
The estimate measures the value of credit extended through installment payment plans, personal loans arranged online and small business loans originated by digital lenders in Australia. It counts credit written at merchant checkouts, in provider apps and websites, through finance brokers and through embedded platform partners.
The estimate excludes credit cards, home loans, car loans arranged at dealerships and bank overdrafts. The value chain runs from wholesale funders and securitization warehouses through licensed providers to merchants, brokers and borrowers in every state and territory.
Australia Fintech Online Lending and BNPL Market Insights
- The Australia Fintech online lending and BNPL market was valued at USD 17.54 billion in 2025 and is projected to reach USD 44.73 billion by 2035, registering a CAGR of 9.79% during 2026–2035.
- New South Wales held a 30.9% share of 2025 value, because the state leads online retail spending and business formation.
- Installment payment plans led with a 50.0% share of 2025 value, because shoppers use them at millions of online and in-store checkouts.
- Installment payment contracts became regulated credit on June 10, 2025, and providers without an accepted licence application faced unlicensed conduct risk.
- SME online loans grow fastest at 10.87% a year during 2026–2035, as banks tighten business credit and digital lenders approve faster.
Pay-in-installment plans lead while SME loans grow fastest
Why do installment payment plans hold the largest share?
Based on product type, the market is categorized into BNPL, personal online loans and SME online loans. BNPL led with a 50.0% share of 2025 value, because shoppers split fashion, electronics and household purchases into short installments at millions of checkouts. SME Online Loans grow fastest at 10.87% a year, as small businesses turn to digital lenders for unsecured working capital that banks approve more slowly.
How do consumers and businesses split borrowing?
Based on customer segment, the market is categorized into salaried consumers, self-employed consumers, microbusinesses and small and medium businesses. Salaried Consumers led with a 56.0% share of 2025 value, because regular wages support installment plans and personal loans. Small and Medium Businesses grow fastest at 10.75% a year, as firms seek larger unsecured loans and revolving facilities online.
Why does merchant checkout remain the main channel?
Based on distribution channel, the market is categorized into merchant checkout, provider direct channels, finance brokers and embedded platform partners. Merchant Checkout led with 46.0% of 2025 value, because installment plans are offered at the point of sale. Embedded Platform Partners grow fastest at 11.31% a year, as wallets, accounting software and marketplaces add credit offers inside their own apps.
How does borrower risk shape lending volumes?
Based on risk category, the market is categorized into prime credit, near-prime credit and non-prime credit. Prime Credit led with a 52.0% share of 2025 value, because licensed providers now check credit files before approving new customers. Near-Prime Credit grows fastest at 10.26% a year, as non-bank lenders serve borrowers with thin files or tax debts that banks decline.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | BNPL | 50.0% | SME Online Loans | 10.87% |
| By Customer Segment | Salaried Consumers | 56.0% | Small and Medium Businesses | 10.75% |
| By Distribution Channel | Merchant Checkout | 46.0% | Embedded Platform Partners | 11.31% |
| By Risk Category | Prime Credit | 52.0% | Near-Prime Credit | 10.26% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Online retail, licensing and working capital lift volumes
How does digital retail purchase frequency lift installment volumes?
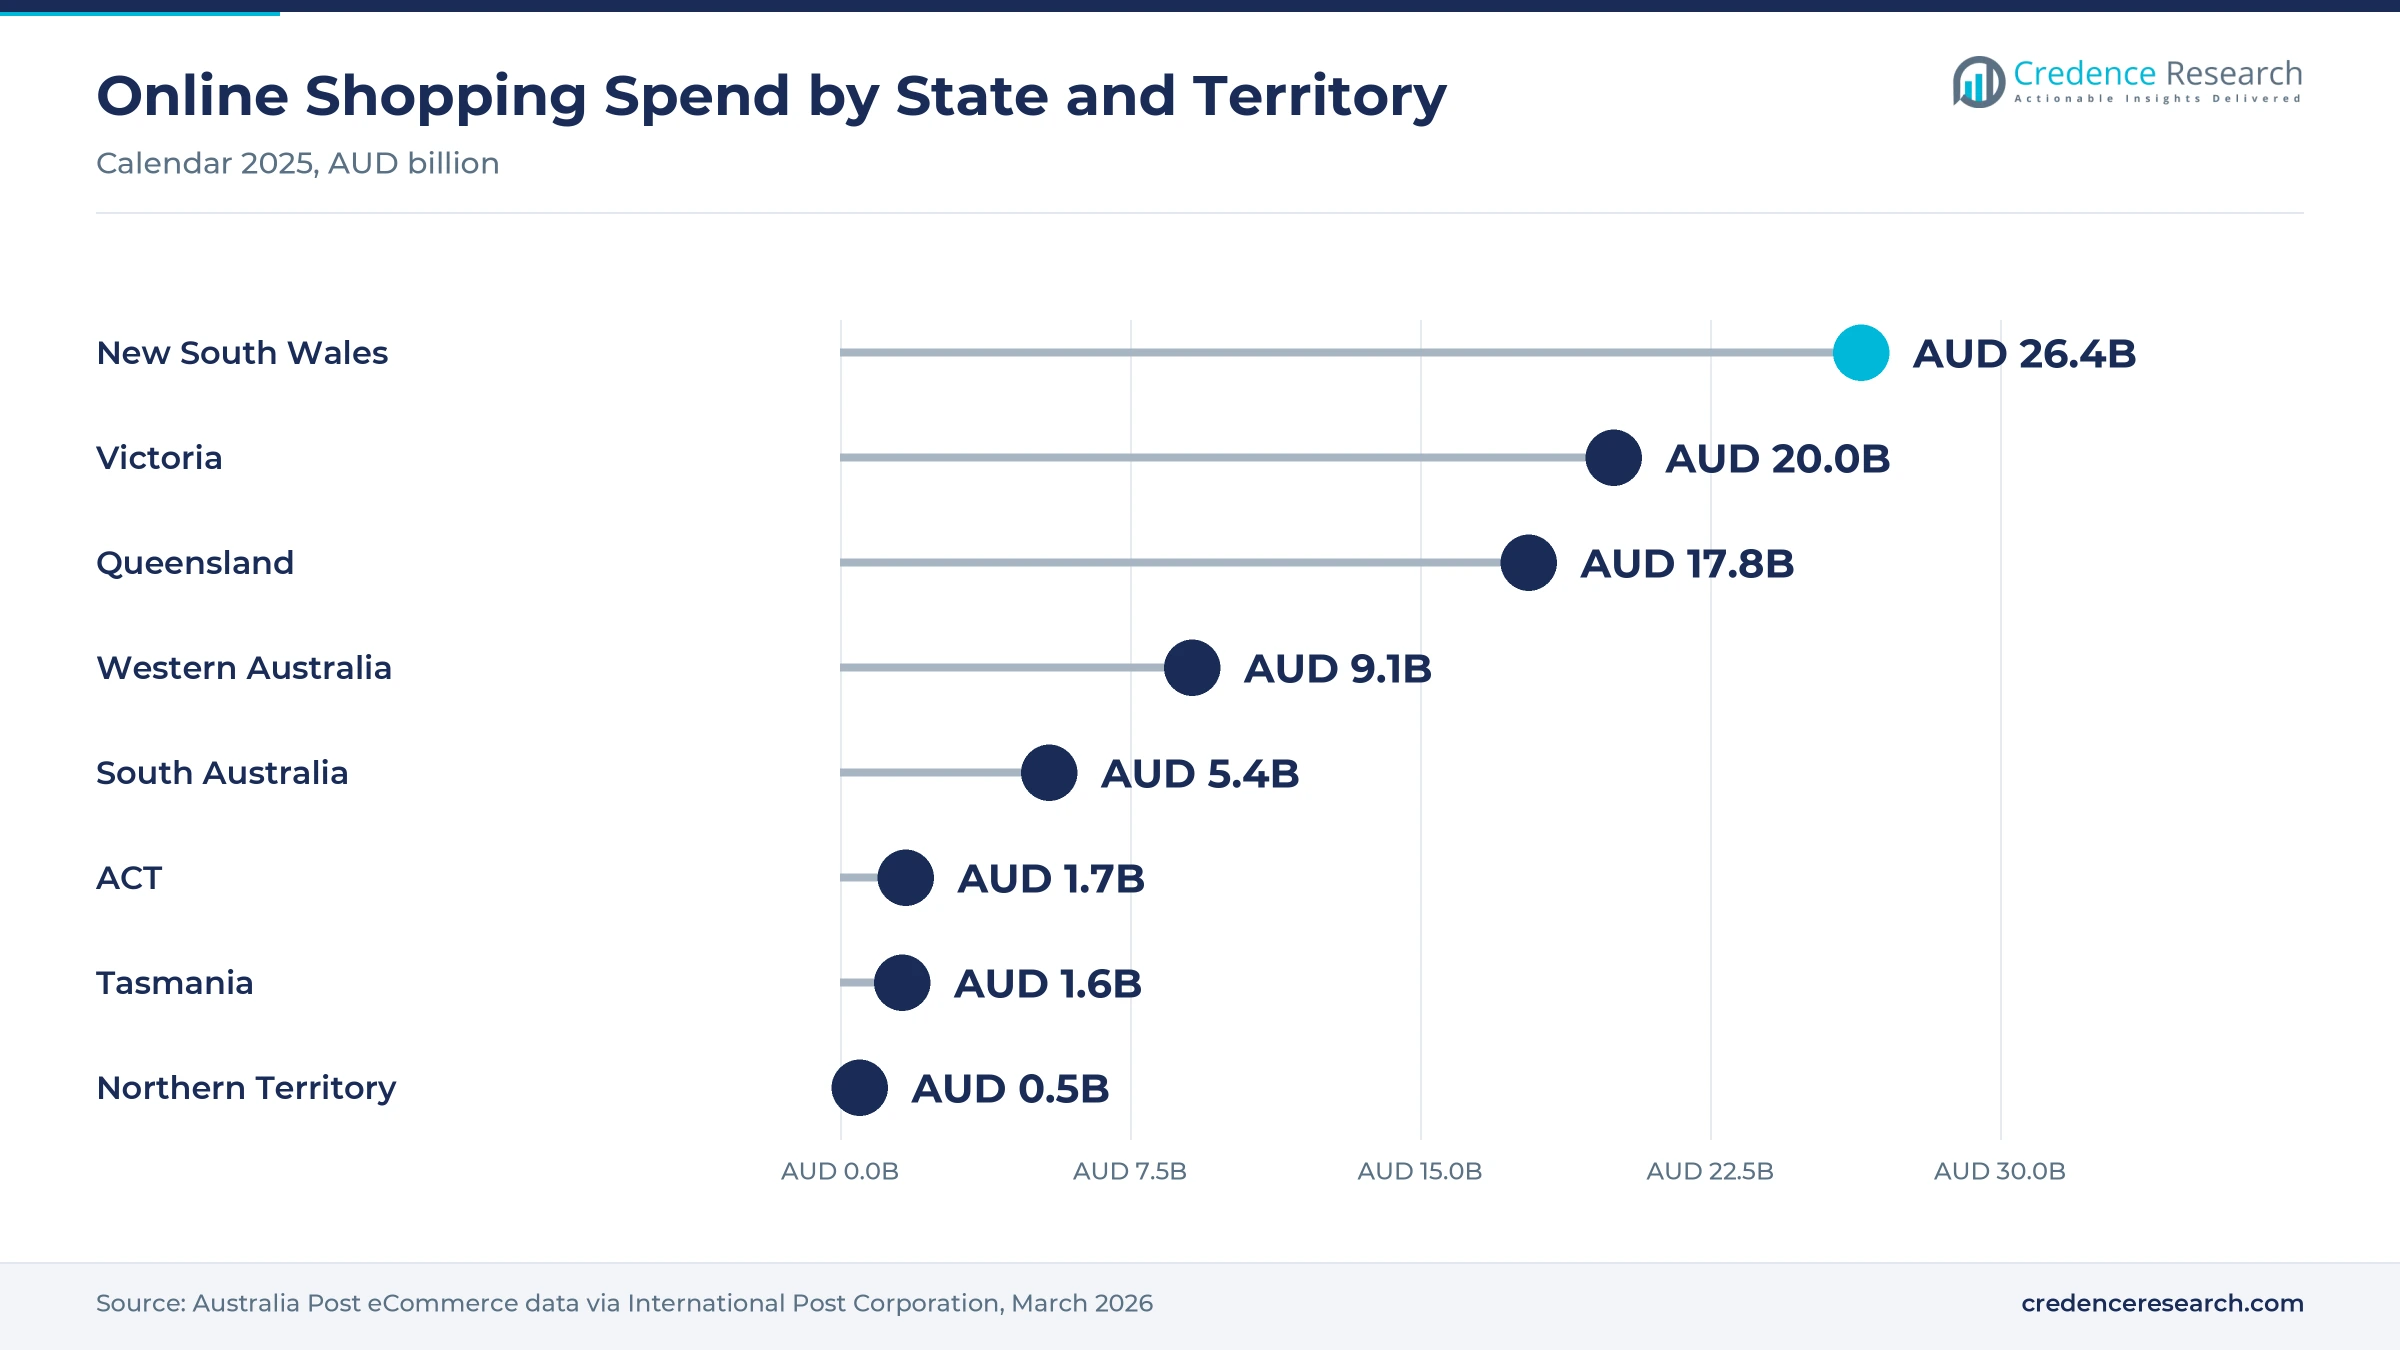
Digital retail purchase frequency lifts installment volumes, because every extra online order creates another chance to offer a payment plan at checkout. Australians spent a record AUD 82.6 billion online in 2025, up 13.9% on the year before, according to the International Post Corporation reporting national postal data. About 9.8 million Australian households shopped online at least once during the year. New South Wales shoppers spent AUD 26.4 billion, Victoria AUD 20 billion and Queensland AUD 17.8 billion. As a result, merchant checkout holds 46.0% of 2025 value, and providers of payment gateways add installment options to more retailer websites.
Why does regulated market access support provider growth?
Regulated market access supports provider growth, because licensed status gives retailers, funders and shoppers more confidence in installment credit. The national corporate regulator issued its guide on low cost credit contracts on May 8, 2025, and the new laws took effect on June 10, 2025, according to the Australian Securities and Investments Commission. The regulator received 16 submissions on the draft guide from providers, industry groups and consumer advocates. Afterpay Australia now holds Australian Credit Licence 527911, while humm moved its plan to licensed subsidiary Once Credit. In turn, prime credit keeps 52.0% of 2025 value as providers run credit checks on new applicants.
How does SME working-capital demand lift digital business loans?
SME working-capital demand lifts digital business loans, because a growing number of firms need fast, unsecured credit to manage tax bills, stock and wages. Australia had 2,814,778 actively trading businesses at June 30, 2026, up 3.1% over the year, according to the Australian Bureau of Statistics. Business entries reached 460,461 during 2025-26, and non-employing businesses rose 4.8%. Average unsecured working capital loans from non-bank lenders rose 20% to AUD 58,000 in fiscal 2026, as major banks tightened commercial credit policy. As a result, SME online loans grow at 10.87% a year, the fastest product rate, and complement alternative finance providers.
Why does deep household credit use sustain demand?
Deep household credit use sustains demand, because Australian borrowers are already familiar with revolving and installment credit for everyday spending. Domestic credit to the private sector reached about 133.8% of gross domestic product in 2025, up from 129.3% in 2024, according to the World Bank. Credit and charge cards accounted for 23% of consumer payments in 2025, down from 26% in 2022, according to the national central bank. That shift leaves room for installment plans and personal loans to replace some card borrowing. In turn, salaried consumers hold 56.0% of 2025 value, while self-employed borrowers use app-based personal loans for irregular income.
Credit checks, embedded offers and new products shape use
How is the rise of credit checks changing approvals?
The rise of credit checks is changing approvals, because licensed installment providers must now assess whether each new customer can repay. Afterpay began running credit checks on new customer applications from June 10, 2025, and may check credit again when a customer asks for a higher limit. Customers also receive monthly account statements and notices when a spend limit changes. Humm renamed its plan humm Classic on the same date and stopped new purchases on existing accounts at midnight on June 9, 2025. As a result, near-prime credit grows at 10.26% a year, while providers refine scoring for borrowers with thin files.
Why is the shift to multi-product apps notable?
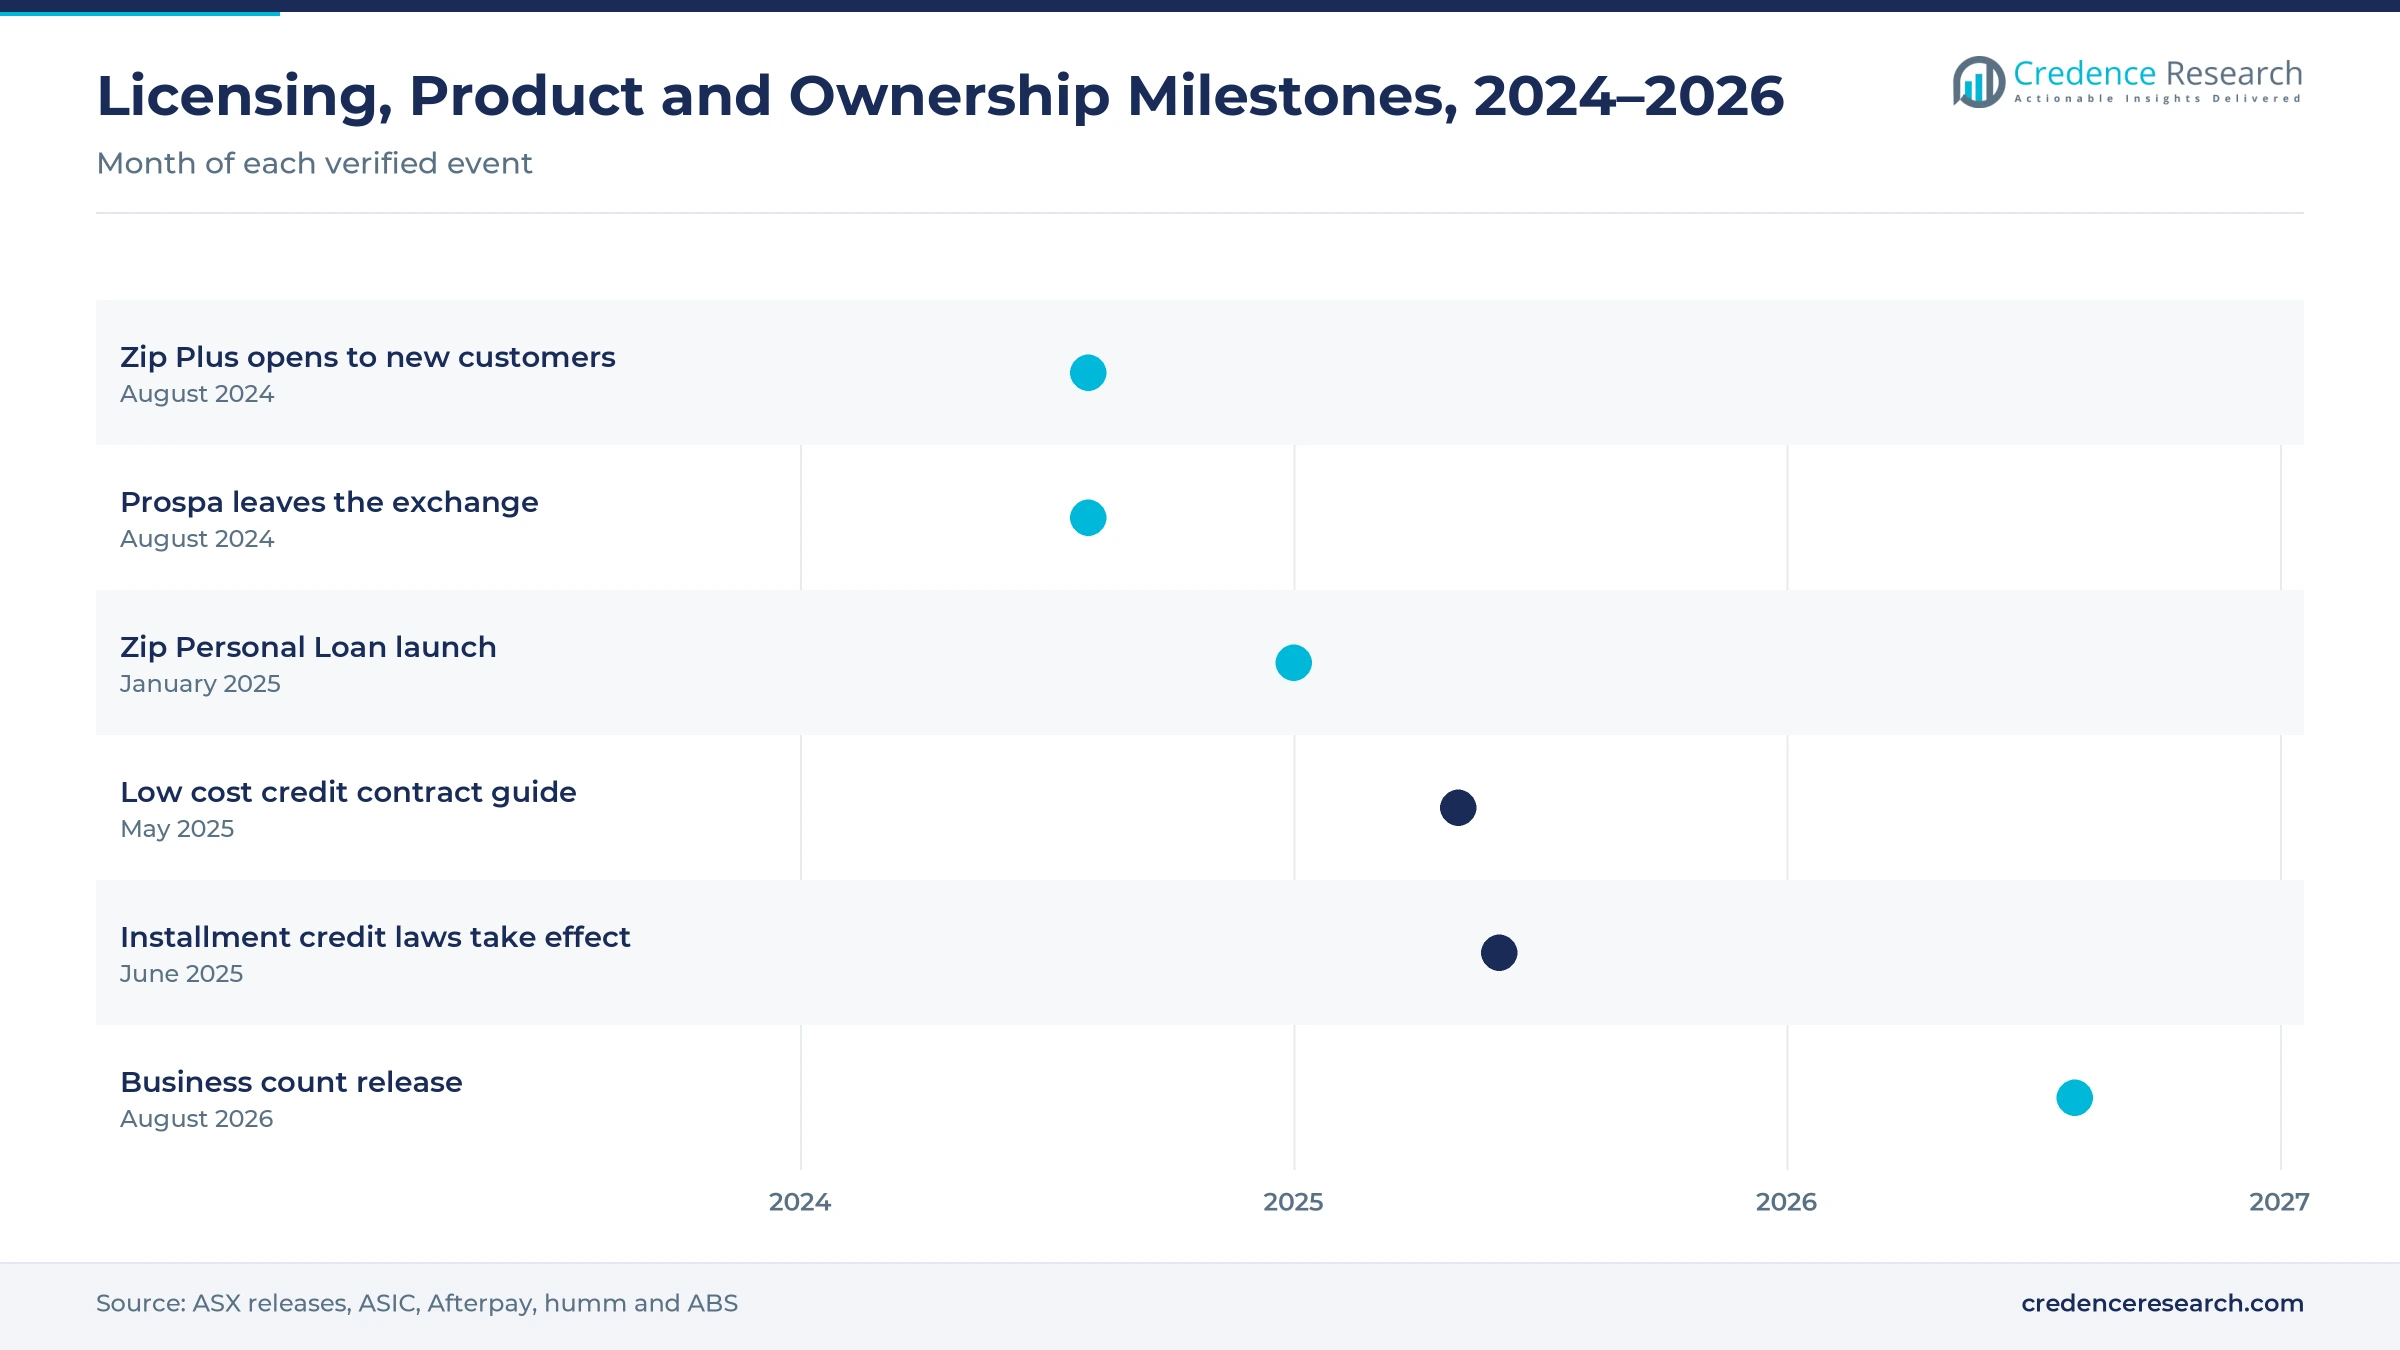
The shift to multi-product apps is notable, because providers want to keep customers after a first installment purchase by offering larger credit lines. Zip rolled out Zip Plus to new customers in August 2024 and launched Zip Personal Loan in January 2025, according to its fiscal 2025 results. Zip Plus customers transact 52% more often than Zip Pay customers, and early personal loan uses include cars, holidays and renovations. Zip counted 60,800 merchants in Australia and New Zealand at June 30, 2025, up 10.3%. In turn, personal online loans gain share, as installment brands compete with peer-to-peer credit platforms for borrowers.
Can embedded credit in wallets and platforms open new volume?
Embedded credit can open new volume, because shoppers and business owners increasingly pay through wallets, marketplaces and accounting software rather than visiting a lender. Klarna launched in Australia in January 2020 with Commonwealth Bank, which invested a total of USD 300 million in Klarna Group and co-owns the local business. Zip rolled out new payment features with Google Wallet during fiscal 2025, according to the same results filing. Online spending rose 13.9% in 2025, which widens the base for in-app credit offers. As a result, embedded platform partners grow at 11.31% a year, the fastest channel rate, alongside wider use of embedded finance tools.
Is there room to serve small firms turned away by banks?
Small firms turned away by banks offer room to grow, because non-bank lenders approve credit faster and accept borrowers with shorter trading histories. Non-employing businesses rose by 83,105 in 2025-26, a 4.8% increase, and companies grew 5.2% to 1,271,197. About 92% of Australian SMEs have used, or would consider using, a non-bank lender, according to a lender survey cited in July 2026. Prospa, a small business lender in Australia and New Zealand, left the securities exchange on Aug. 9, 2024, after a consortium bought it. In turn, small and medium businesses grow at 10.75% a year, the fastest customer rate.
Credit losses, compliance costs and funding test providers
How do credit losses limit growth in installment credit?
Credit losses limit growth in installment credit, because missed repayments erode the thin margins earned on interest-free plans. Zip reported group net bad debts of 1.52% of transaction volume in fiscal 2025. As a result, providers tighten limits for new and inactive customers. Lenders respond with credit bureau checks, lower starting limits and faster collections, which protects margins while keeping approvals open to reliable repeat users.
Why do compliance costs weigh on smaller providers?
Compliance costs weigh on smaller providers, because licensing, hardship processes, dispute schemes and responsible lending checks need staff and systems. The regulator cancelled or suspended 253 credit licences in fiscal 2025, while it granted 104 new ones. In turn, some small providers exit or sell their books. Larger groups respond by spreading compliance costs across more products and customers, which raises the scale needed to compete.
How does funding cost volatility squeeze margins?
Funding cost volatility squeezes margins, because most digital lenders borrow through warehouse facilities and securitization rather than deposits. When the cash rate moves, their funding costs change quickly. As a result, interest-free plans earn less after funding costs, and personal loan pricing must rise. Providers respond by refinancing early, adding new warehouse lines and shifting toward interest-bearing products that pass some costs to borrowers.
Why does weaker customer growth challenge established brands?
Weaker customer growth challenges established brands, because many Australian shoppers already hold one or more installment accounts. Zip reported 2.04 million active customers in Australia and New Zealand at June 30, 2025, down 6.8% on the year. In turn, providers compete harder and spend more for each new user. Brands respond by adding personal loans, wallets and merchant offers that raise spending per customer rather than relying on new sign-ups alone.
Sydney borrowers lead while western firms add fastest growth
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 5.42 | 30.9% | 9.57% |
| Victoria | 4.03 | 23.0% | 9.77% |
| Queensland | 3.33 | 19.0% | 9.97% |
| Western Australia | 2.81 | 16.0% | 10.22% |
| South Australia, Tasmania and Territories | 1.95 | 11.1% | 9.47% |
Why do new South Wales shoppers and firms borrow most?
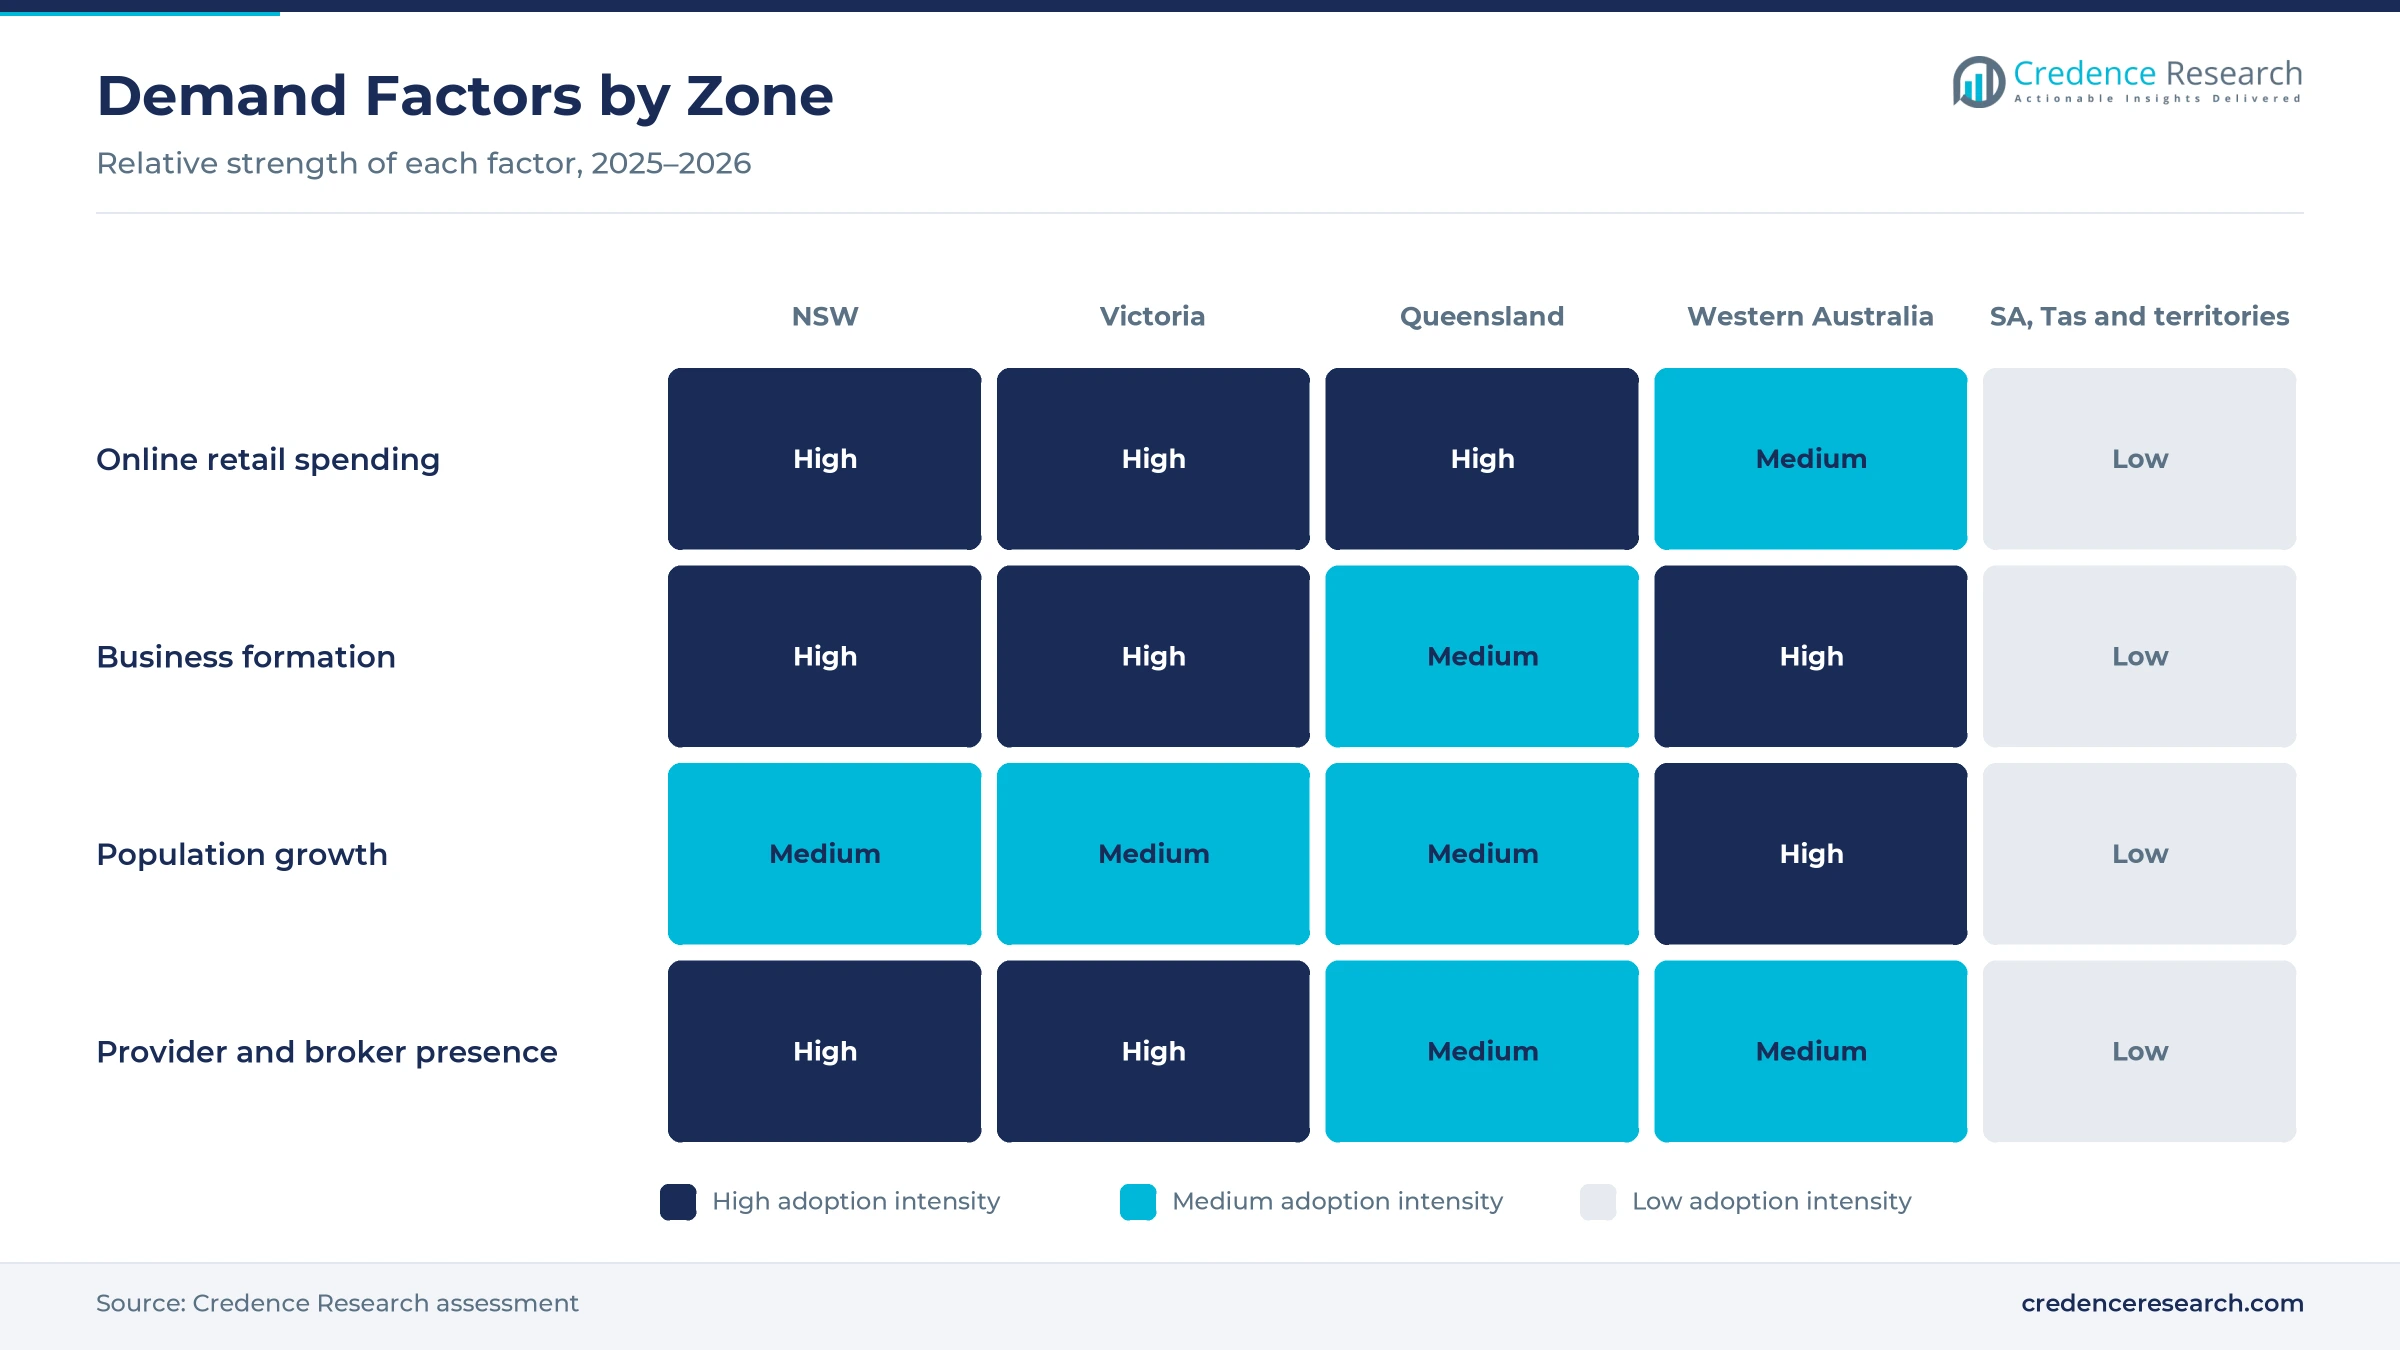
New South Wales held a 30.9% share of 2025 value and grows at 9.57% a year, because the state had about 8.67 million residents in March 2026. Shoppers in the state spent AUD 26.4 billion online in 2025, the most of any state. New South Wales also recorded the largest net increase in businesses, with 26,057 more firms in 2025-26. As a result, the state leads both installment and small business borrowing.
How does Victoria support digital credit demand?
Victoria held a 23.0% share of 2025 value and grows at 9.77% a year, because Melbourne combines a large retail base with many small businesses and startups. Victorian shoppers spent about AUD 20 billion online during calendar in 2025. Victoria counted about 7.15 million residents at March 31, 2026, after 1.6% annual growth. In turn, Victoria remains the second-largest zone for installment plans and app-based personal loans.
What drives demand in Queensland?
Queensland held a 19.0% share of 2025 value and grows at 9.97% a year, because its population and online spending are rising steadily. Queensland shoppers spent AUD 17.8 billion online in 2025, close behind Victoria. Queensland counted about 5.74 million residents at March 31, 2026, after 1.6% annual growth. As a result, installment plans and personal loans gain users in Brisbane and regional cities.
How do new firms push Western Australia ahead?
Western Australia held a 16.0% share of 2025 value and grows fastest at 10.22% a year, because it recorded the largest percentage increase in businesses, 4.6% in 2025-26. The state also had the fastest population growth at 2.1% in the year to March 2026. As a result, small business loans and installment plans expand faster than in other states.
What shapes demand in the smaller states and territories?
South Australia, Tasmania and the territories accounted for 11.1% of 2025 value and grow at 9.47% a year. Shoppers in South Australia spent AUD 5.4 billion online in 2025, while the Australian Capital Territory, Tasmania and the Northern Territory together spent about AUD 3.8 billion. As a result, merchant checkout plans dominate local volumes in these smaller markets.
Licensing, product and ownership moves, 2024–2026
| Development | Status and market relevance |
|---|---|
| In August 2024, Prospa left the securities exchange after a consortium led by Salter Brothers Tech Fund acquired the small business lender. | Moved a major SME lender into private ownership |
| In January 2025, Zip launched Zip Personal Loan to new and existing customers in Australia. | Extended an installment brand into personal loans |
| In May 2025, the national corporate regulator released its guide on low cost credit contracts for installment providers. | Set responsible lending duties ahead of the new laws |
| In June 2025, installment payment contracts became regulated credit, and Afterpay began credit checks on new customers. | Brought providers under the national credit code |
| In August 2026, national statistics showed 2,814,778 actively trading businesses at June 30, 2026, up 3.1%. | Confirms a growing base of potential SME borrowers |
Credit decisioning, open data and wallets change supply
- Automated credit decisioning combines bureau data, bank transaction data and repayment history, which lets providers approve installment plans and loans within minutes while meeting responsible lending duties.
- Open banking and accounting data give lenders verified views of income, spending and business cash flow, which supports unsecured working capital loans for firms with short trading histories.
- Wallet and platform integration places credit offers inside mobile wallets, marketplaces and accounting software, which helps providers reach shoppers and business owners at the moment they need to pay, alongside pay-in-four installment plans at checkout.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Specialist providers and bank-backed rivals compete
Competition is split between installment specialists, diversified digital lenders and bank-backed rivals. Afterpay holds Australian Credit Licence 527911 and has run credit checks on new customers since June 10, 2025. Zip counted 2.04 million active customers and 60,800 merchants in Australia and New Zealand at June 30, 2025, and it added personal loans in January 2025. Humm moved its plan to licensed subsidiary Once Credit, while Klarna operates locally with Commonwealth Bank as co-owner. Prospa serves small businesses under private ownership after leaving the exchange in August 2024. Rivals compete on approval speed, merchant reach, credit limits, fees and app features. Because regulation now covers every provider, scale in compliance and funding has become a key advantage for winning merchants and borrowers.
Which providers lead digital consumer and business credit in Australia?
| Company | Type | Role in the market |
|---|---|---|
| Afterpay | Installment payment specialist | Holds credit licence 527911 and runs credit checks since June 2025 |
| Zip Co | Diversified digital lender | 2.04 million active customers in Australia and New Zealand at June 2025 |
| Humm Group | Installment and consumer lender | Moved its plan to licensed subsidiary Once Credit in June 2025 |
| Klarna | Installment payment specialist | Local business co-owned with Commonwealth Bank since 2020 |
| Prospa | SME lending specialist | Small business lender taken private in August 2024 |
Credence Research view on digital consumer and SME credit
Credence Research's view is that Australian digital credit will keep growing because shoppers buy online more often and small businesses need fast working capital. Installment plans remain the largest value pool, while SME loans add the fastest growth. Regulation has raised the cost of entry but also given funders and retailers more confidence. Providers that combine strong credit decisioning, secure funding and wide merchant reach should gain share fastest across the Australia Fintech online lending and BNPL base over the next decade.
How the national digital credit estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines online retail spending data, business counts, population estimates, World Bank credit data, central bank payment surveys, regulator releases and company announcements. Segment splits and zone growth rates are Credence Research estimates, while zone shares follow the client-defined split. Sources used are official statistics, regulator publications, exchange filings and company releases, and no interviews or surveys were used.
SME loans and embedded partners carry growth to 2035
Credit value is expected to reach USD 44.73 billion by 2035, a 9.79% CAGR during 2026–2035, as online retail grows and small businesses borrow more through digital lenders. Growth should come from SME loans, embedded platform partners and near-prime borrowers. Stable funding costs would support interest-free plans, while higher bad debts or tighter rules would slow approvals. Providers with licensed scale, strong scoring and wide merchant reach are expected to gain the most as Australia Fintech online lending and BNPL volumes shift toward multi-product apps.
Frequently Asked Questions
How big is the Australia Fintech online lending and BNPL market?
Which product type leads Australian digital credit value?
Which region leads the Australian market?
When did installment payment plans become regulated credit?
How much did Australians spend online in 2025?
Which distribution channel is growing fastest?
Who are the leading companies in the Australian market?
What are the main challenges for providers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 BNPL
- 1.2.2 Personal Online Loans
- 1.2.3 SME Online Loans
- 1.3 By Customer Segment
- 1.3.1 Salaried Consumers
- 1.3.2 Self-Employed Consumers
- 1.3.3 Microbusinesses
- 1.3.4 Small and Medium Businesses
- 1.4 By Risk Category
- 1.4.1 Prime Credit
- 1.4.2 Near-Prime Credit
- 1.4.3 Non-Prime Credit
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 17.54 billion → 2035: USD 44.73 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Fintech Online Lending and BNPL Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Fintech Online Lending and BNPL Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Australia Fintech Online Lending and BNPL Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Australia Fintech Online Lending and BNPL Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Fintech Online Lending and BNPL Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Fintech Online Lending and BNPL Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Fintech Online Lending and BNPL Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Fintech Online Lending and BNPL Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 17.54 billion → 2035: USD 44.73 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Fintech Online Lending and BNPL Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 BNPL
- 12.3.6.2 Personal Online Loans
- 12.3.6.3 SME Online Loans
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Customer Segment - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Salaried Consumers
- 12.4.6.2 Self-Employed Consumers
- 12.4.6.3 Microbusinesses
- 12.4.6.4 Small and Medium Businesses
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Risk Category - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Prime Credit
- 12.5.6.2 Near-Prime Credit
- 12.5.6.3 Non-Prime Credit
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Fintech Online Lending and BNPL End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Fintech Online Lending and BNPL Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Fintech Online Lending and BNPL Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2025-2035
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Fintech Online Lending and BNPL Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Afterpay
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Zip Co
- 18.4 Humm Group
- 18.5 Klarna
- 18.6 Prospa
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

