
AI upgrades and cloud moves reshape core business systems
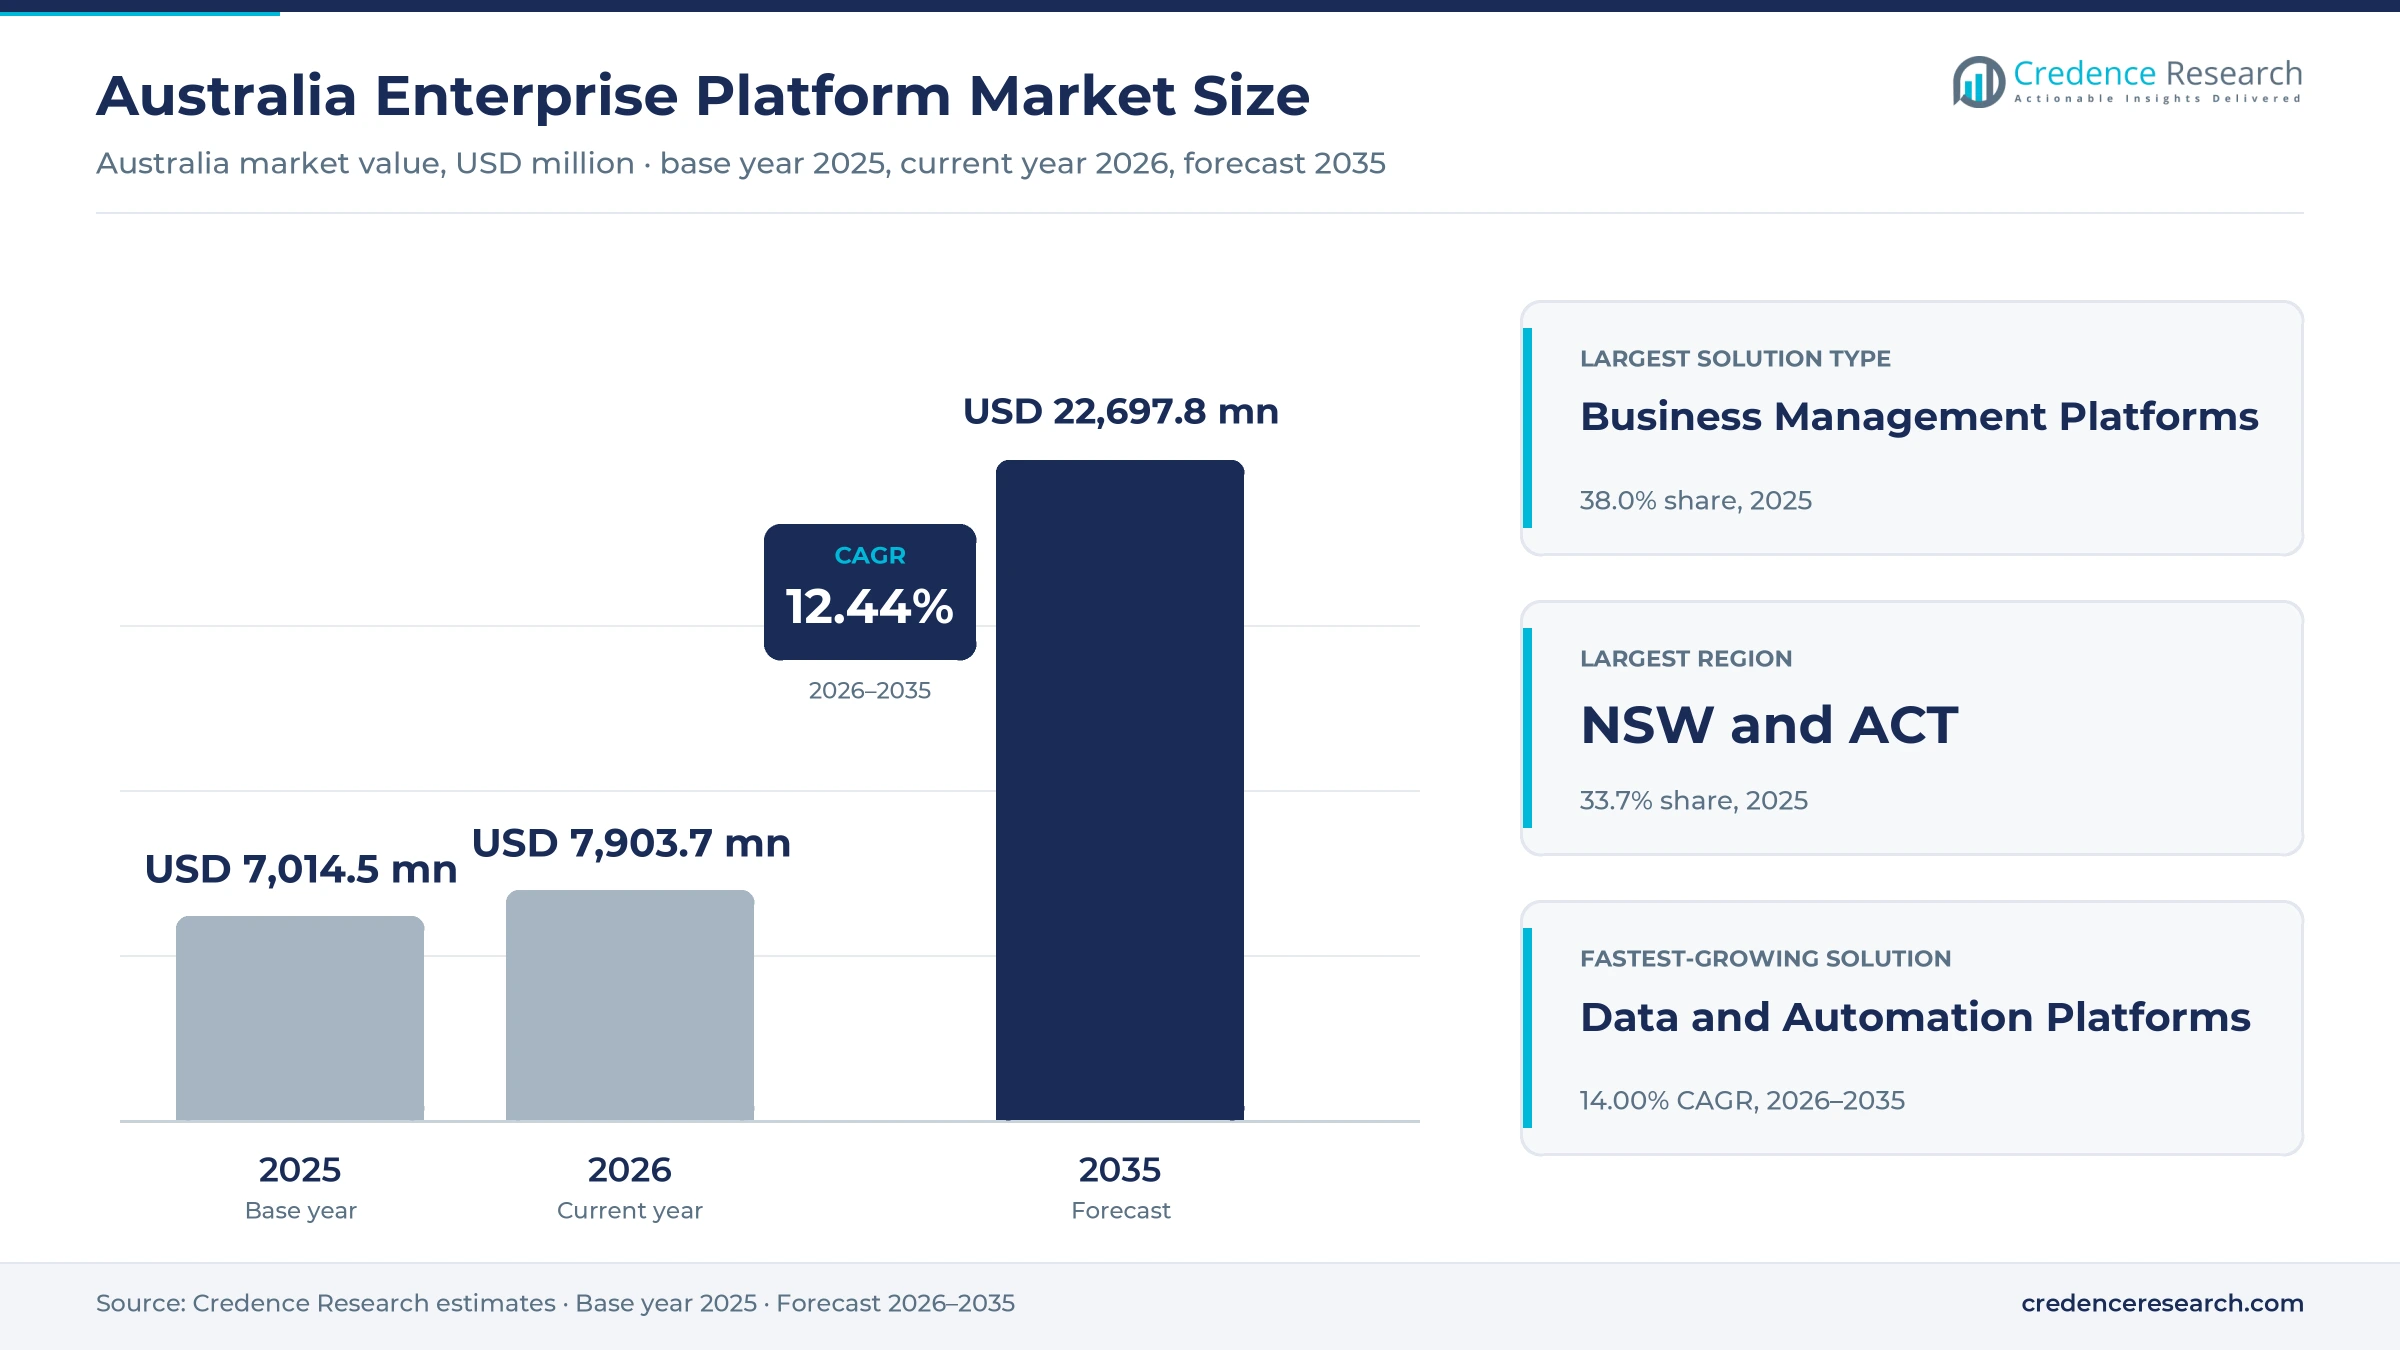
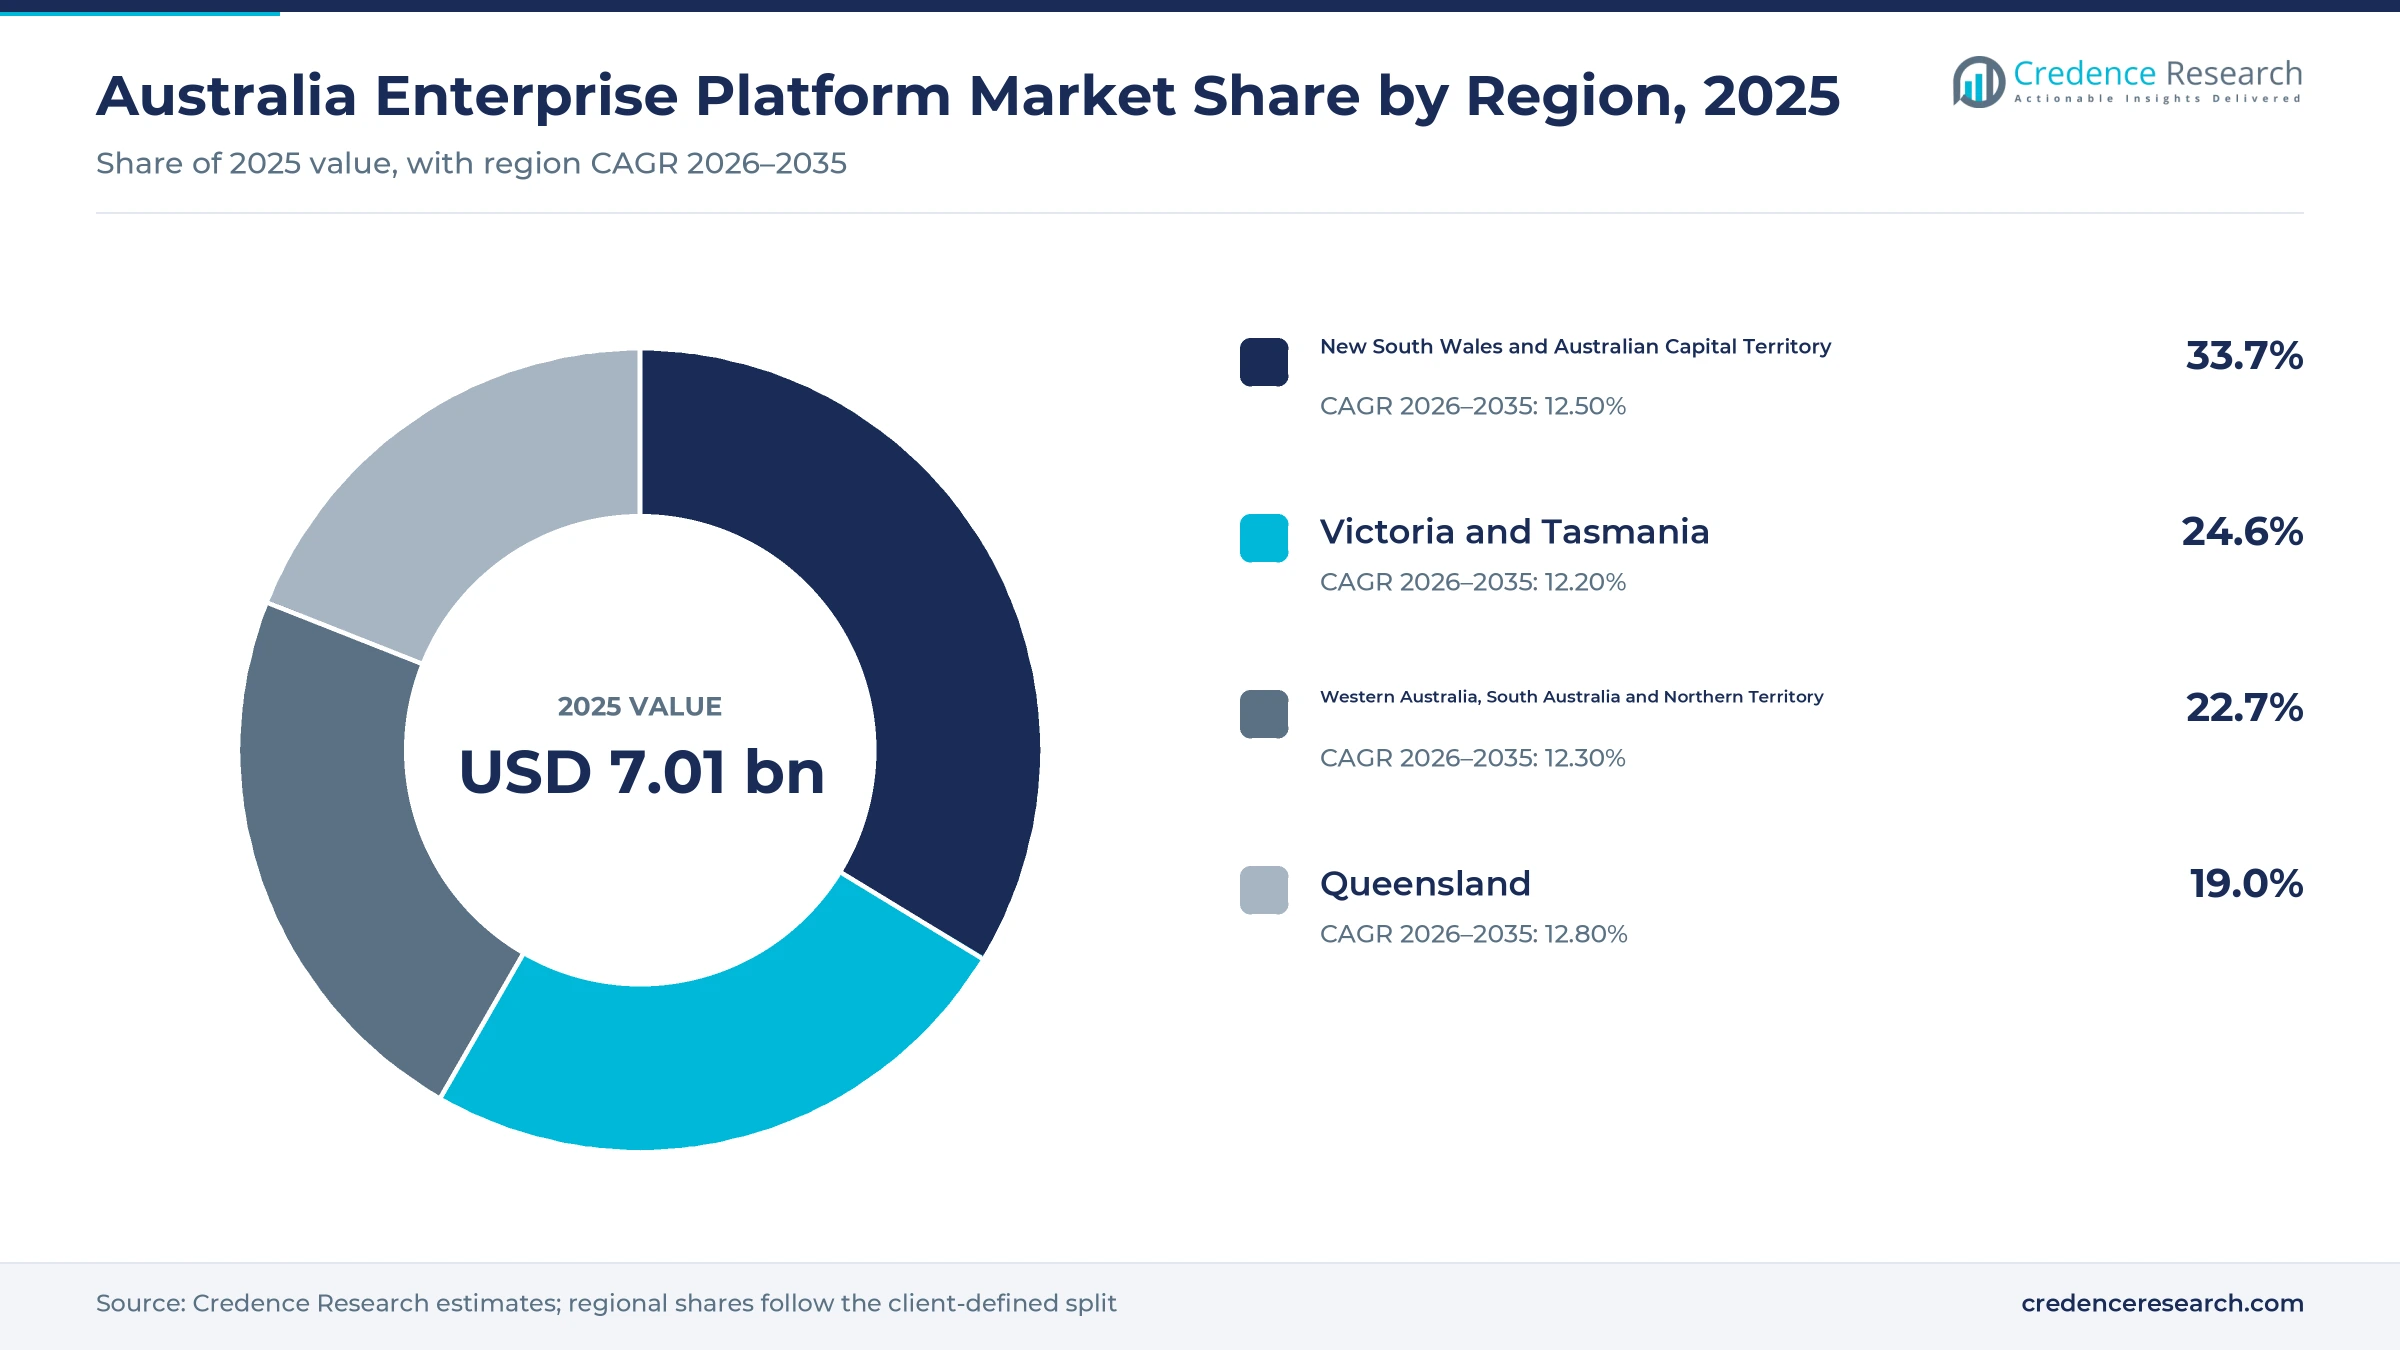
The Australia enterprise platform market was valued at USD 7.01 billion in 2025 and is projected to increase from USD 7.90 billion in 2026 to USD 22.70 billion by 2035, registering a CAGR of 12.44% during 2026–2035. Demand comes from banks, insurers, agencies, councils, universities, miners and retailers that are replacing aging finance, payroll, customer and workflow systems with cloud suites that carry embedded AI. New South Wales and Australian Capital Territory held the largest regional share, 33.7% in 2025, because Sydney head offices and Canberra federal agencies concentrate platform buying. Queensland is the fastest-growing region at 12.80% a year, supported by a four-year AUD 1 billion state digital fund announced with the 2025-26 budget. In turn, public-sector planning has become a direct spending trigger, because Commonwealth agencies must now keep digital investment plans that list current systems and their end-of-life dates.
Which finance, customer and workflow systems fall inside the scope?
The estimate measures spending by Australian employers with 20 or more staff on software platforms that run finance, procurement, payroll, customer service, sales, collaboration, data and workflow automation. It counts subscription, consumption, license and maintenance fees for business management, customer engagement, workplace and data and automation platforms, whether delivered as public cloud software, on private cloud or on premises.
The estimate excludes hardware, network services, data center construction and stand-alone consulting that is not tied to a platform fee. The value chain runs from global software vendors and a local specialist through cloud regions in Sydney, Melbourne and Canberra to integrators, and then to finance, service and operations teams that run daily work on these systems.
Australia Enterprise Platform Market Insights
- The Australia enterprise platform market was valued at USD 7.01 billion in 2025 and is projected to reach USD 22.70 billion by 2035, registering a CAGR of 12.44% during 2026–2035.
- New South Wales and Australian Capital Territory held a 33.7% share of 2025 value, as Sydney head offices and Canberra agencies concentrate buying.
- Business Management Platforms led with a 38.0% share of 2025 value, because finance, payroll and asset systems anchor most platform budgets.
- About 35% of large Australian businesses used AI in 2024-25, up from 9% in 2021-22, according to national statistics, which speeds suite upgrades.
- Data and Automation Platforms grow fastest at 14.00% a year during 2026–2035, as agents and workflow tools spread across back offices.
Business management suites lead as automation tools surge
Why do business management suites hold the largest share?
Based on solution type, the market is categorized into Business Management Platforms, Customer Engagement Platforms, Workplace Platforms and Data and Automation Platforms. Business Management Platforms led with a 38.0% share of 2025 value, because finance, payroll and asset systems run every large employer. Data and Automation Platforms grows fastest at 14.00% a year, as service teams link customer relationship management systems to workflow agents and shared data layers.
How fast is spending leaving on-premises systems?
Based on deployment model, the market is categorized into Public Cloud Software as a Service, Private Cloud Platforms and On-Premises Platforms. Public Cloud Software as a Service led with a 58.0% share of 2025 value, because vendors release new AI features first in hosted versions. Public Cloud Software as a Service grows fastest at 13.18% a year, as agencies and councils retire licensed systems with help from cloud migration and integration services.
Which industries fund most platform purchases?
Based on end-use industry, the market is categorized into Finance and Business Services, Government and Community Services, Goods Production and Trade and Consumer Services. Finance and Business Services led with a 36.0% share of 2025 value, because banks, insurers and professional firms run large regulated systems. Government and Community Services grows fastest at 12.79% a year, as federal and state digital funds pay for replacement programs.
How does employer size shape platform demand?
Based on enterprise size, the market is categorized into 20-199 Employees, 200-999 Employees, and 1,000+ Employees. 1,000+ Employees led with a 48.0% share of 2025 value, because large banks, agencies and miners license many modules across thousands of users. 20-199 Employees grows fastest at 13.09% a year, as smaller employers switch from separate accounting and payroll tools to packaged cloud suites.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Solution Type | Business Management Platforms | 38.0% | Data and Automation Platforms | 14.00% |
| By Deployment Model | Public Cloud Software as a Service | 58.0% | Public Cloud Software as a Service | 13.18% |
| By End-Use Industry | Finance and Business Services | 36.0% | Government and Community Services | 12.79% |
| By Enterprise Size | 1,000+ Employees | 48.0% | 20-199 Employees | 13.09% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
AI upgrades, cloud migration and agency plans lift demand
How do AI upgrade cycles push firms onto new suites?
Vendors now release AI assistants and agents mainly inside current cloud versions of their suites, which pushes Australian firms to upgrade finance, customer and workplace software rather than keep older releases. About 12% of Australian businesses used AI in 2024-25, and large business adoption reached about 35%, up from 9% in 2021-22, according to the Australian Bureau of Statistics. Adoption was highest in information, media and telecommunications at 38%, while financial and insurance services reached 24%. A federal trial also gave Microsoft 365 Copilot to more than 7,600 staff across over 60 agencies in 2024, and participants reported saving about an hour a day, according to the Digital Transformation Agency. As a result, Data and Automation Platforms grows fastest at 14.00% a year during 2026–2035.
Why are core systems moving to cloud subscriptions?
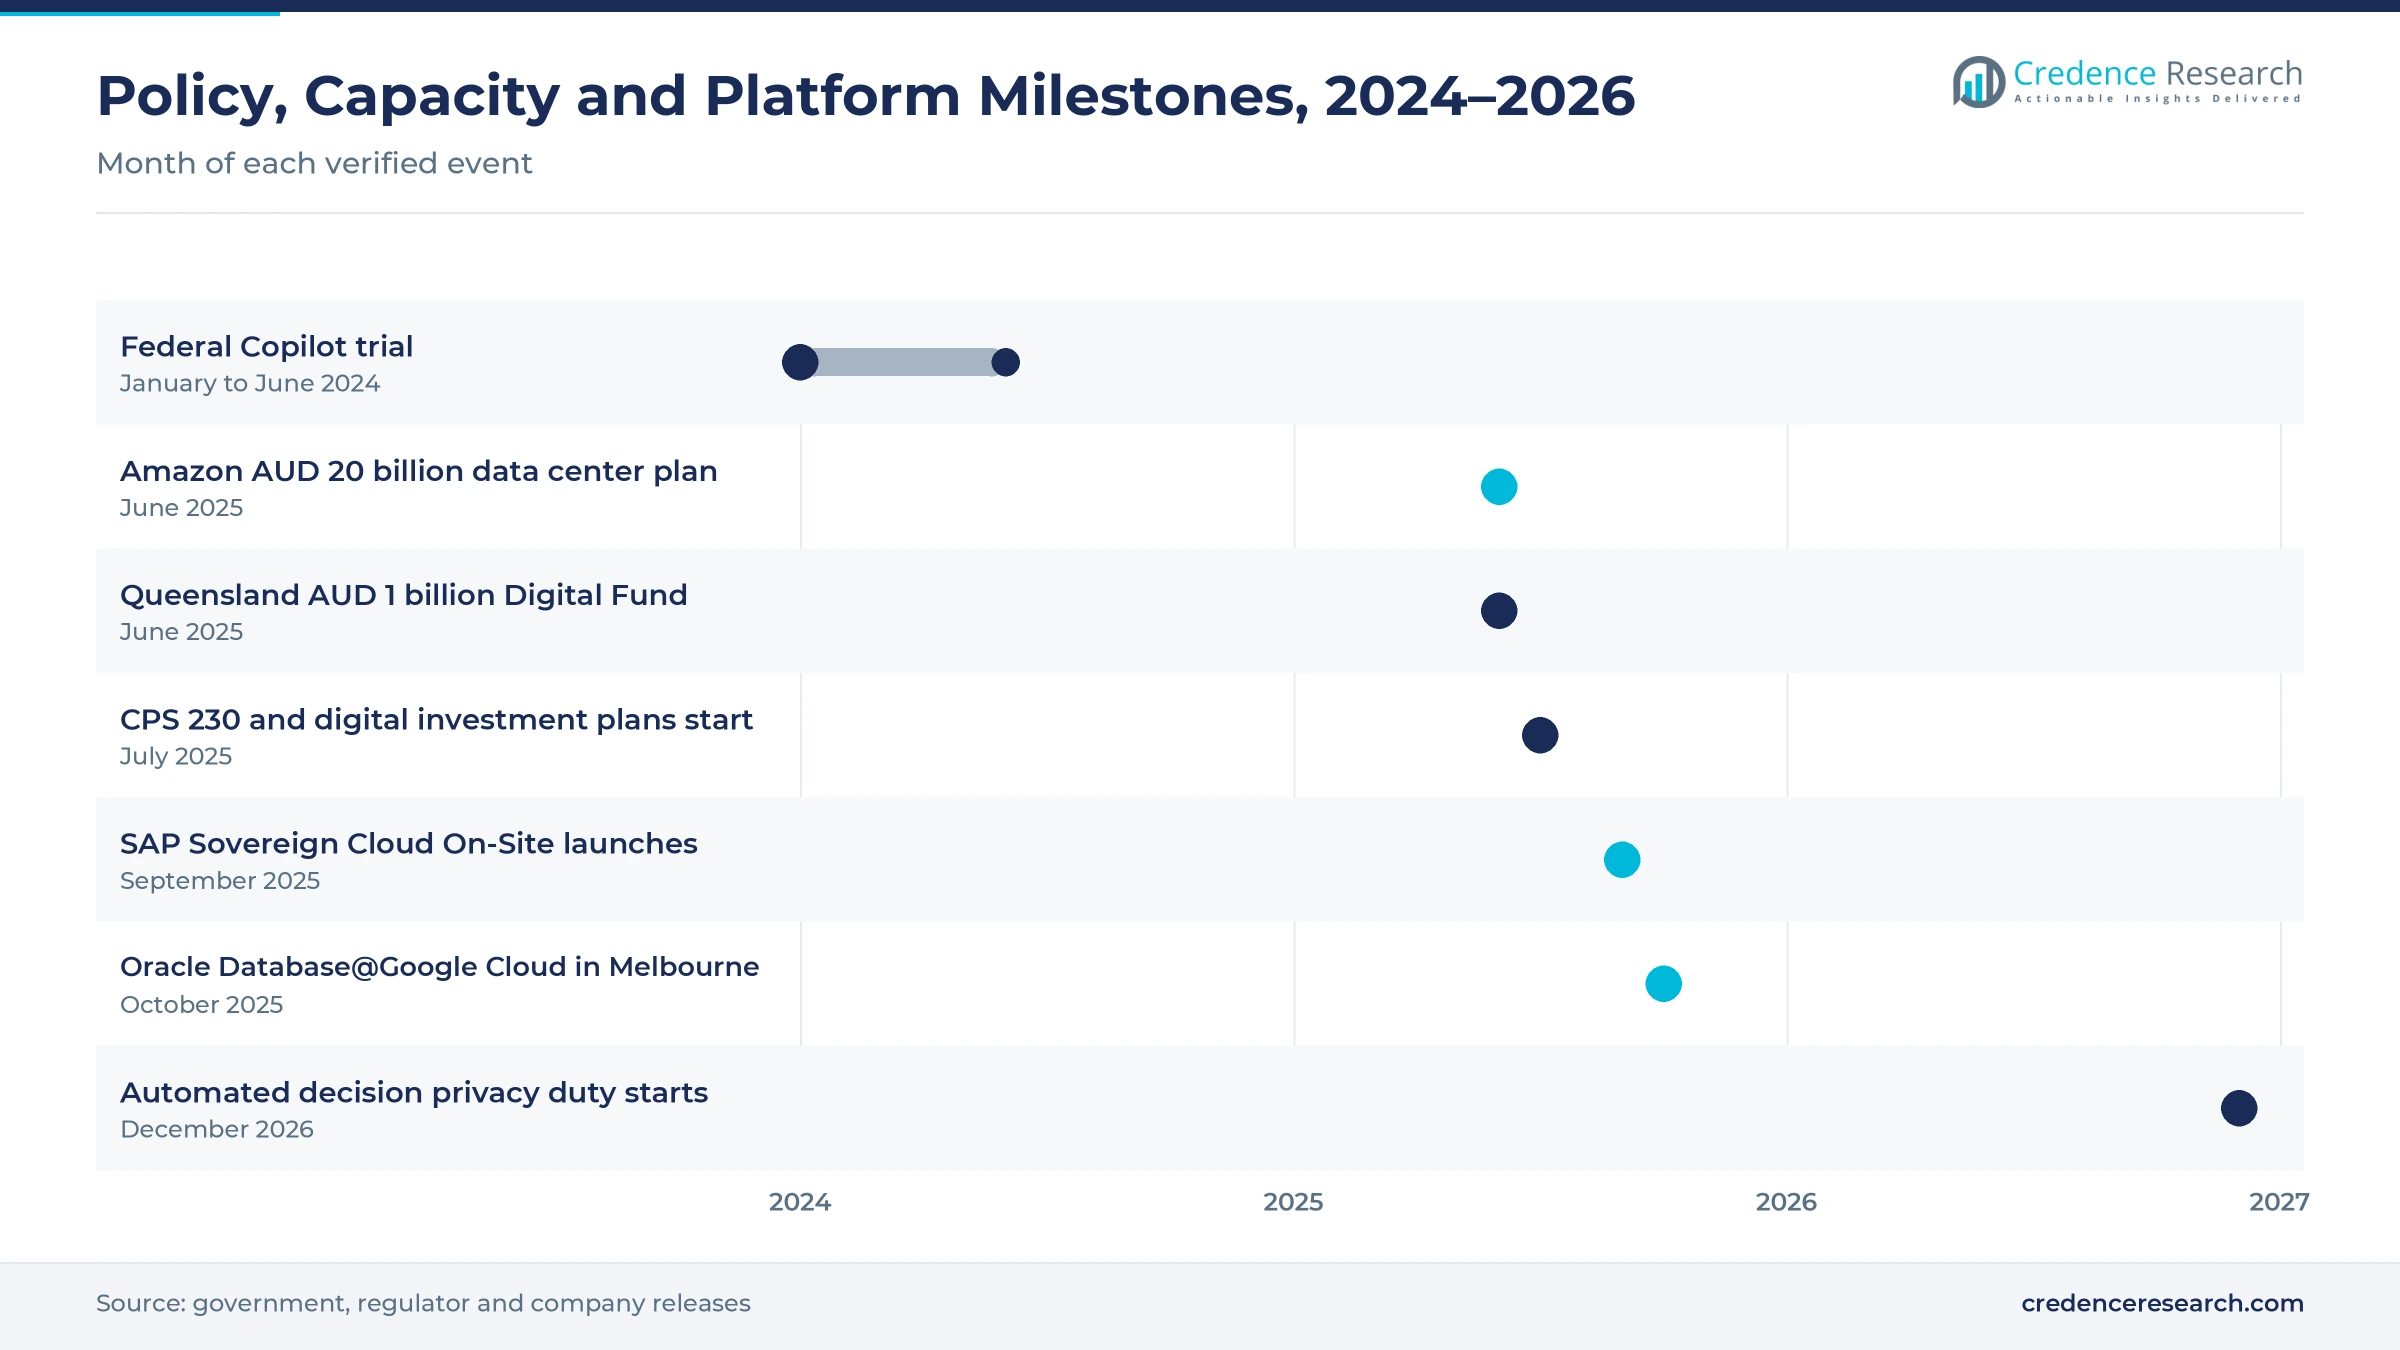
Firms and public bodies are retiring on-premises finance, payroll and asset systems, because vendors now concentrate new features, security fixes and AI services in hosted versions. TechnologyOne said in October 2023 that all of its higher education customers were using or had committed to its software-as-a-service platform, according to IT Brief Australia. Waverley Council in Sydney is moving finance, asset management, payroll and human resources onto the OneCouncil SaaS platform under a contract extended to June 30, 2030, according to council records. SAP also expanded its Australian sovereign cloud on Sept. 3, 2025, adding an on-site option and listing Business Data Cloud and AI services for 2026, according to SAP. In turn, Public Cloud Software as a Service holds 58.0% of 2025 platform value.
How does government investment planning fund replacements?
Federal and state governments now plan digital spending years ahead, which turns system replacement into funded, scheduled demand for platform suppliers. From July 1, 2025, non-corporate Commonwealth entities must prepare digital investment plans that list current systems, their end-of-life dates and planned upgrades, according to the Digital Transformation Agency. The agency expects 19 newly funded investments to enter central oversight in 2026, with project budgets of AUD 870.8 million outside the large Medicare bulk billing measure. Queensland also announced a four-year AUD 1 billion Queensland Government Digital Fund with its 2025-26 budget on June 24, 2025, according to the state government. As a result, Government and Community Services grows fastest at 12.79% a year during 2026–2035.
Why do prudential and privacy rules lift platform spending?
Regulated firms must now prove control over the systems and providers that run critical operations, which favors modern platforms with built-in audit, continuity and access controls. The prudential standard CPS 230 commenced on July 1, 2025, requiring regulated banks and insurers to strengthen operational risk management, business continuity and oversight of material service providers, according to APRA. From Dec. 10, 2026, organizations covered by the Privacy Act must describe in privacy policies the decisions that computer programs make using personal information, according to the Office of the Australian Information Commissioner. About 21% of businesses also reported a cyber security incident in 2024-25, according to national statistics. In turn, Finance and Business Services holds 36.0% of 2025 value.
AI agents, local hosting and modernization funds emerge
How is the rise of AI agents changing platform purchases?
Platform buying is shifting from separate AI pilots toward agents built into CRM, ERP and workplace suites, which lets agencies and firms automate tasks inside systems they already run. Salesforce said in June 2025 that Agentforce and the Salesforce Platform had completed an Information Security Registered Assessors Program assessment against PROTECTED-level controls, which opens them to sensitive government work. The Victorian Government renewed its State Purchase Contract with Salesforce for three more years on June 25, 2025, according to Salesforce. Medium-sized businesses also raised AI adoption to 22% in 2024-25 from 3% in 2021-22, according to national statistics. As a result, agents increasingly sit beside decision support systems within the same subscription contracts.
Why are local and sovereign hosting options on the rise?
Buyers are shifting core workloads to local cloud regions with Australian security assessments, which weakens the case for keeping finance and customer systems on premises. Amazon plans to invest AUD 20 billion from 2025 to 2029 to expand its Australian data center infrastructure, according to Amazon. Microsoft committed AUD 5 billion in October 2023 to grow its local footprint from 20 to 29 data centers across Canberra, Melbourne and Sydney. Oracle opened a Canberra cloud region for government and defense on Aug. 7, 2023, and launched Oracle Database@Google Cloud in Melbourne on Oct. 23, 2025, according to Oracle. In turn, growth in hyperscale data center capacity supports the shift toward hosted platform subscriptions.
Can mid-sized employers open a subscription growth lane?
Mid-sized and smaller employers give suppliers a clear opening, because many still run separate accounting, payroll and customer tools that packaged cloud suites can replace. Australia had 2,814,778 actively trading businesses at June 30, 2026, including 996,203 employing businesses, according to national statistics. Only 5,366 businesses employed 200 or more people, which leaves a long tail of firms with 20 to 199 staff that prefer simpler subscriptions. Internet use already reached about 96% of Australians in 2024, according to World Bank data, so connectivity is rarely the barrier. As a result, 20-199 Employees grows fastest at 13.09% a year during 2026–2035.
Can state and federal modernization funds open new deals?
Dedicated modernization funds give suppliers an opening to replace aging agency systems with shared, reusable platforms. The NSW Digital Restart Fund has invested more than AUD 2 billion since 2019 and enhanced 294 digital products and services, according to Digital NSW. Its 2024-25 review reports a return of AUD 3 for every AUD 1 invested, based on an independent economic assessment. At the federal level, newly overseen projects include AUD 255.6 million across three Veterans' Affairs investments and AUD 193.4 million across two Finance investments, according to the Digital Transformation Agency's 2026 project report. In turn, suppliers with local hosting, security assessments and shared-service references can win multiyear replacement contracts.
Skills, cyber risk and migration costs test buyers
How do skills gaps limit returns on new suites?
New platforms only pay back when staff learn to use their AI and workflow features in daily work. In the federal Copilot trial, 75% of participants with three or more forms of training felt confident, 28 points higher than those with one form. As a result, buyers that cut training budgets see slower adoption and weaker returns. Suppliers and integrators respond with structured training, adoption teams and phased rollouts.
Why does cyber risk slow platform consolidation?
Moving finance, payroll and customer records onto shared cloud suites concentrates sensitive data in fewer systems. About 28% of Australian businesses reported having no measures in place to prevent cyber security incidents in 2024-25, according to national statistics. In turn, smaller buyers face higher exposure when they connect many applications. Vendors respond with locally hosted, security-assessed services and built-in identity controls that ease approvals.
How do migration costs and overruns deter buyers?
Replacing a core finance or payroll system can take years and requires data cleanup, testing and parallel running. Queensland ministers said the new state digital fund aims for fewer ICT cost blowouts and project overruns, which shows how often large programs miss budgets. As a result, boards delay replacements when business cases look uncertain. Buyers respond with staged migrations, fixed-scope phases and central assurance reviews.
Why do usage-based charges complicate budgeting?
Consumption-based pricing for AI and data services makes annual platform costs harder to forecast than fixed subscriptions. Finance teams in agencies and listed firms must set budgets a year ahead, so variable bills create planning risk. In turn, some buyers cap AI usage or delay broader rollouts until costs settle. Suppliers respond with committed-spend agreements, usage dashboards and bundled credits that make annual costs more predictable.
New South Wales and ACT lead as Queensland grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Australian Capital Territory | 2.36 | 33.7% | 12.50% |
| Victoria and Tasmania | 1.73 | 24.6% | 12.20% |
| Western Australia, South Australia and Northern Territory | 1.59 | 22.7% | 12.30% |
| Queensland | 1.33 | 19.0% | 12.80% |
Sydney head offices and Canberra agencies anchor demand
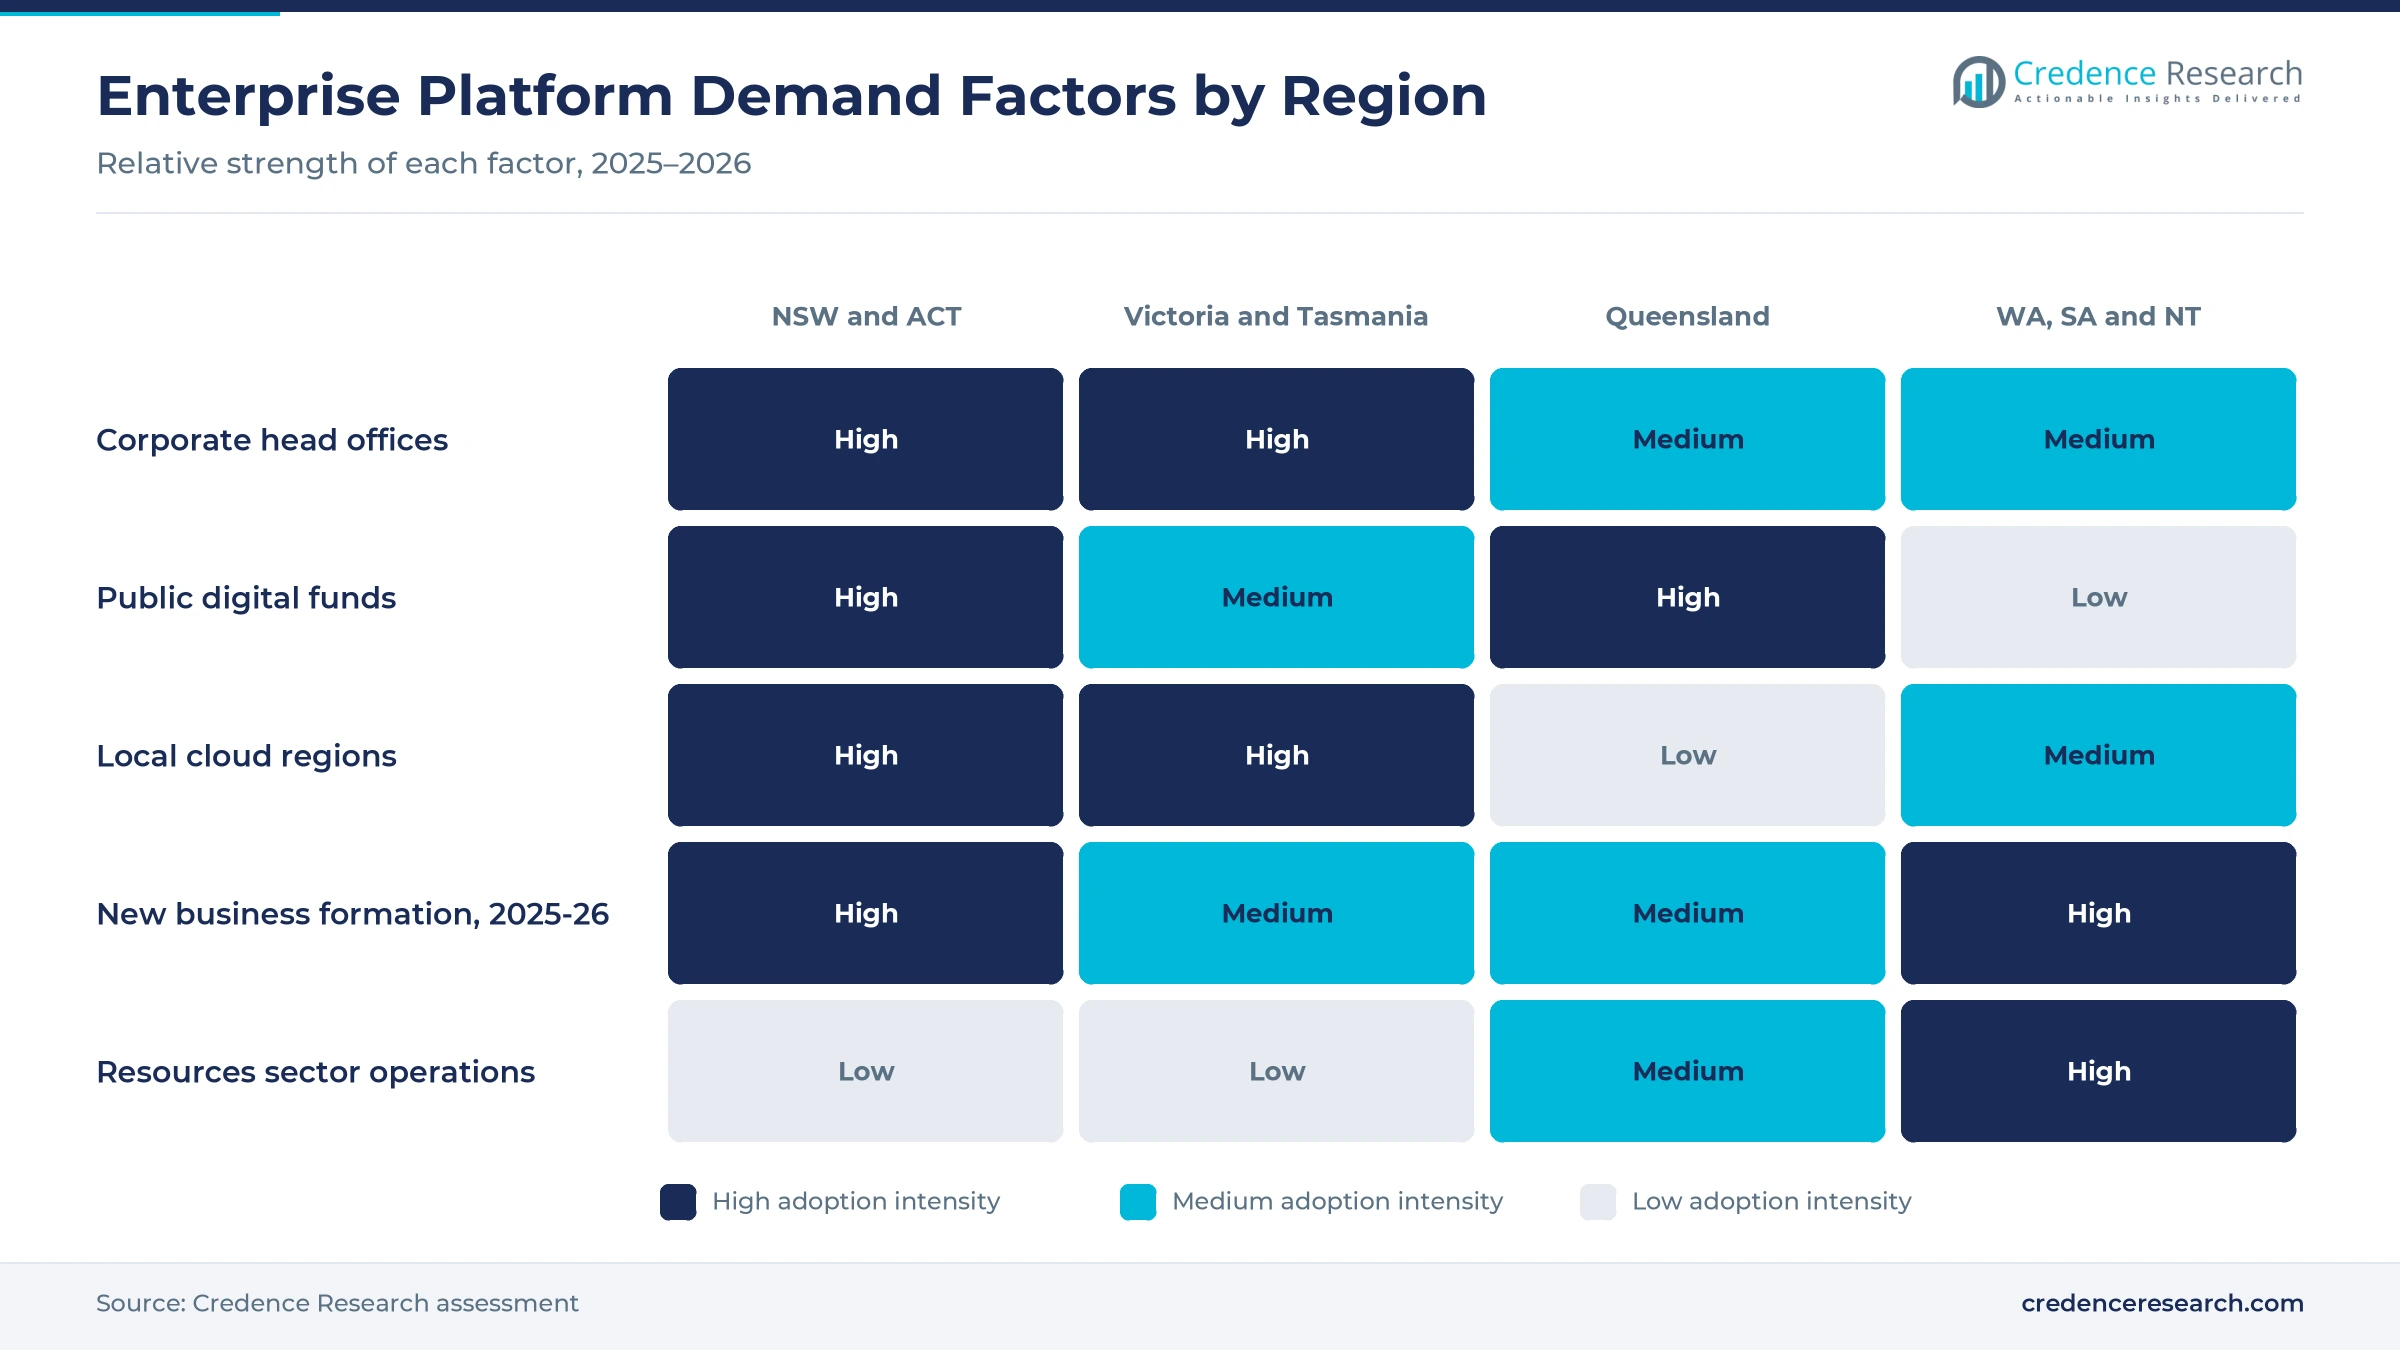
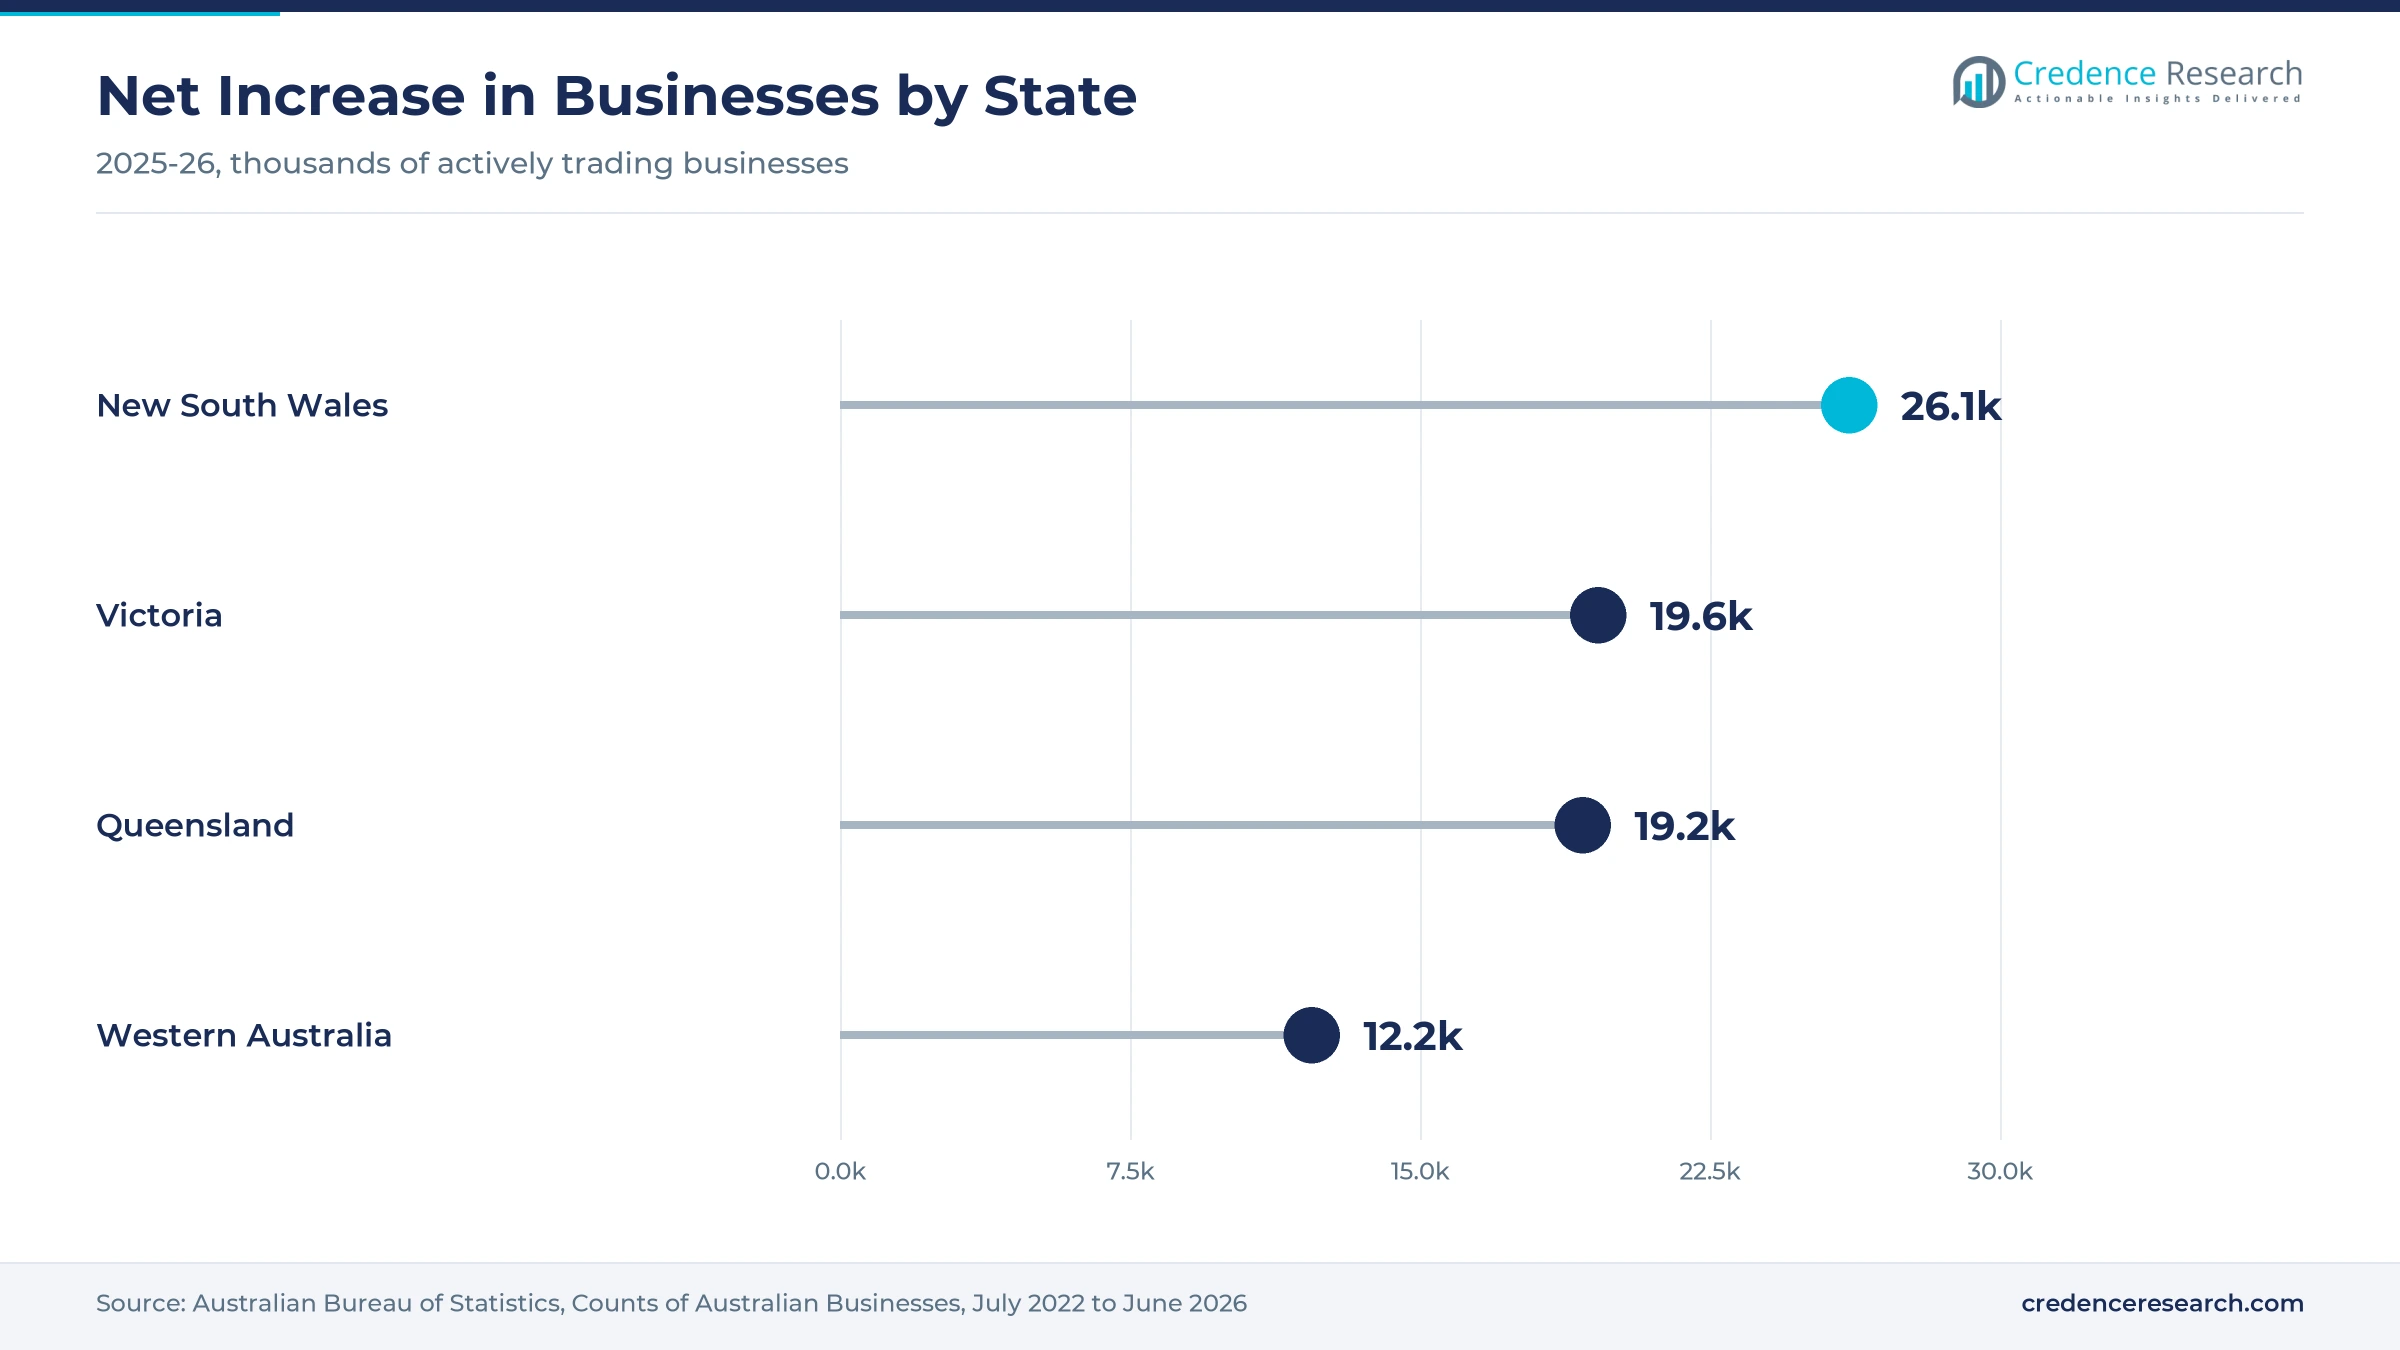
New South Wales and Australian Capital Territory held a 33.7% share of 2025 value and grow at 12.50% a year. New South Wales added 26,057 businesses in 2025-26, the largest net increase of any state, according to national statistics. Canberra also hosts federal agencies bound by digital investment planning and a dedicated government cloud region. As a result, the two jurisdictions lead in both corporate and public-sector platform spending.
How do state contracts shape demand in Victoria and Tasmania?
Victoria and Tasmania held a 24.6% share of 2025 value and grow at 12.20% a year, supported by Melbourne insurers, retailers and a large state public service. Victoria added 19,581 businesses in 2025-26, while its government renewed a whole-of-state Salesforce contract for three years in June 2025. Melbourne also hosts a public cloud region and the first local Oracle Database@Google Cloud service. In turn, hosted customer and finance platforms carry most new spending.
Why does Queensland grow fastest among the regions?
Queensland held a 19.0% share of 2025 value and grows fastest at 12.80% a year. The state announced a four-year AUD 1 billion Queensland Government Digital Fund in June 2025 to coordinate investment in critical government systems. Queensland also added 19,244 businesses in 2025-26, close to the Victorian increase. As a result, agency system replacements and new employers both add platform demand across the state.
How do resources and Perth hosting shape the western states?
Western Australia, South Australia and Northern Territory held a 22.7% share of 2025 value and grow at 12.30% a year. Western Australia added 12,248 businesses in 2025-26, the largest percentage increase at 4.6%, according to national statistics. Amazon also opened the country's first cloud Local Zones in Perth in 2023. In turn, mining, energy and agency buyers in Perth and Adelaide gain faster access to hosted platforms.
Cloud capacity, sovereign hosting and policy moves, 2025
| Development | Status and market relevance |
|---|---|
| In June 2025, Amazon announced plans to invest AUD 20 billion in Australian data center infrastructure from 2025 to 2029. | Expands local capacity for hosted platforms and AI services |
| In June 2025, the Victorian Government renewed its State Purchase Contract with Salesforce for three more years. | Keeps customer platforms available to state agencies |
| In July 2025, the Digital Transformation Agency released its first formal Digital Investment Plan policy and guidebook. | Requires agencies to list systems and end-of-life dates |
| In September 2025, SAP launched SAP Sovereign Cloud On-Site for Australian public sector buyers. | Lets agencies host managed SAP cloud in their own facilities |
| In October 2025, Oracle made Oracle Database@Google Cloud available in Melbourne. | Adds a local multicloud option for Oracle workloads |
Cloud suites, automation tools and AI agents shape choices
- Cloud ERP suites combine finance, procurement, payroll and asset management on one hosted platform, which cuts upgrade work and gives agencies and councils one data model.
- CRM and service platforms manage sales, service and case work across channels, which lets banks, insurers and agencies track each customer from a single record.
- Workflow automation tools link low-code apps with robotic process automation, which removes manual steps in invoicing, onboarding and claims.
- Embedded AI agents draft responses, summarize records and complete set tasks within suite permissions, which raises productivity while adding privacy and audit duties.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Global suites and a local specialist compete for renewals
Competition is split between global suite vendors that bundle finance, customer, workplace and data tools and a local specialist that focuses on government, councils and universities. Microsoft supplies Azure, Microsoft 365 and Copilot from local data centers and ran a whole-of-government Copilot trial with federal agencies in 2024. Salesforce sells customer and agent platforms to banks, insurers and agencies, and its platform completed a PROTECTED-level security assessment in June 2025. SAP offers finance and supply chain suites from an Australian sovereign cloud, while Oracle runs Sydney, Melbourne and Canberra cloud regions. TechnologyOne sells its SaaS enterprise suite to councils and higher education. Rivals compete on local hosting, security assessments, AI features and migration support, which favors vendors with strong public-sector references.
Which companies supply enterprise platforms in Australia?
| Company | Type | Role in the market |
|---|---|---|
| Microsoft | Cloud, workplace and AI platform | Copilot trial across federal agencies, 2024 |
| Salesforce | Customer and AI agent platform | PROTECTED-level assessment for Agentforce, 2025 |
| SAP | Enterprise suite vendor | Sovereign Cloud On-Site for public sector, 2025 |
| Oracle | Database and cloud suite vendor | Canberra government cloud region and Melbourne multicloud |
| TechnologyOne | Local SaaS enterprise suite | OneCouncil and higher education SaaS customers |
Planned replacements make platforms a steady spend line
Credence Research's view is that the Australia enterprise platform market will grow steadily because AI features, cloud migration and public investment planning now force scheduled replacements of core systems. Business Management Platforms remain the largest value pool, but Data and Automation Platforms add the fastest growth. Vendors that combine local hosting, security assessments and strong migration support should gain share with agencies and regulated firms. Skills gaps, cyber risk and migration costs will slow some programs, especially among smaller employers.
Model built from business statistics and agency records
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model draws on national business counts and technology statistics, government digital investment records, regulator standards and guidance, and company announcements on investments, launches and contracts. Segment splits and regional growth rates are Credence Research estimates, while regional shares follow the client-defined split. Sources used are official statistics, regulator releases, government documents, council records, trade press and company releases, and no interviews or surveys were used.
Agents and cloud renewals carry growth to 2035
The Australia enterprise platform market is expected to reach USD 22.70 billion by 2035, a 12.44% CAGR during 2026–2035, as AI agents and cloud renewals move into finance, customer and workplace systems. Growth should be strongest through 2029 while agency investment plans, state digital funds and new local cloud capacity take effect. After that, smaller employers and automation tools will carry more of the value. Weaker public budgets would slow agency programs, while faster AI adoption would lift subscription and usage spending.
Frequently Asked Questions
How big is the Australia enterprise platform market?
Which solution type leads Australian platform spending?
Which region leads the Australian market?
How do digital investment plans affect agency buying?
Why are firms moving core systems to the cloud?
Which employer group is growing fastest?
Who are the leading companies in Australian enterprise platforms?
What are the main challenges for buyers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Solution Type
- 1.2.1 Business Management Platforms
- 1.2.2 Customer Engagement Platforms
- 1.2.3 Workplace Platforms
- 1.2.4 Data and Automation Platforms
- 1.3 By Deployment Model
- 1.3.1 Public Cloud Software as a Service
- 1.3.2 Private Cloud Platforms
- 1.3.3 On-Premises Platforms
- 1.4 By End-Use Industry
- 1.4.1 Finance and Business Services
- 1.4.2 Government and Community Services
- 1.4.3 Goods Production
- 1.4.4 Trade and Consumer Services
- 1.5 By Enterprise Size
- 1.5.1 20-199 Employees
- 1.5.2 200-999 Employees
- 1.5.3 1,000+ Employees
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 7.01 billion → 2035: USD 22.70 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Enterprise Platform Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Enterprise Platform Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Australia Enterprise Platform Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Australia Enterprise Platform Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Enterprise Platform Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Enterprise Platform Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Enterprise Platform Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Enterprise Platform Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 7.01 billion → 2035: USD 22.70 billion)
- 11.1.2 Historical Market Size, 2018-2025
- 11.1.3 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Enterprise Platform Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Solution Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Base-Year Market Share, 2025
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Business Management Platforms
- 12.3.6.2 Customer Engagement Platforms
- 12.3.6.3 Workplace Platforms
- 12.3.6.4 Data and Automation Platforms
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Deployment Model - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Base-Year Market Share, 2025
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Public Cloud Software as a Service
- 12.4.6.2 Private Cloud Platforms
- 12.4.6.3 On-Premises Platforms
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Base-Year Market Share, 2025
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Finance and Business Services
- 12.5.6.2 Government and Community Services
- 12.5.6.3 Goods Production
- 12.5.6.4 Trade and Consumer Services
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Enterprise Size - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Base-Year Market Share, 2025
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 20-199 Employees
- 12.6.6.2 200-999 Employees
- 12.6.6.3 1,000+ Employees
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Enterprise Platform End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Enterprise Platform Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Enterprise Platform Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Enterprise Platform Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Microsoft
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Salesforce
- 18.4 SAP
- 18.5 Oracle
- 18.6 TechnologyOne
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

