
Venue renewal and public refill points shape demand
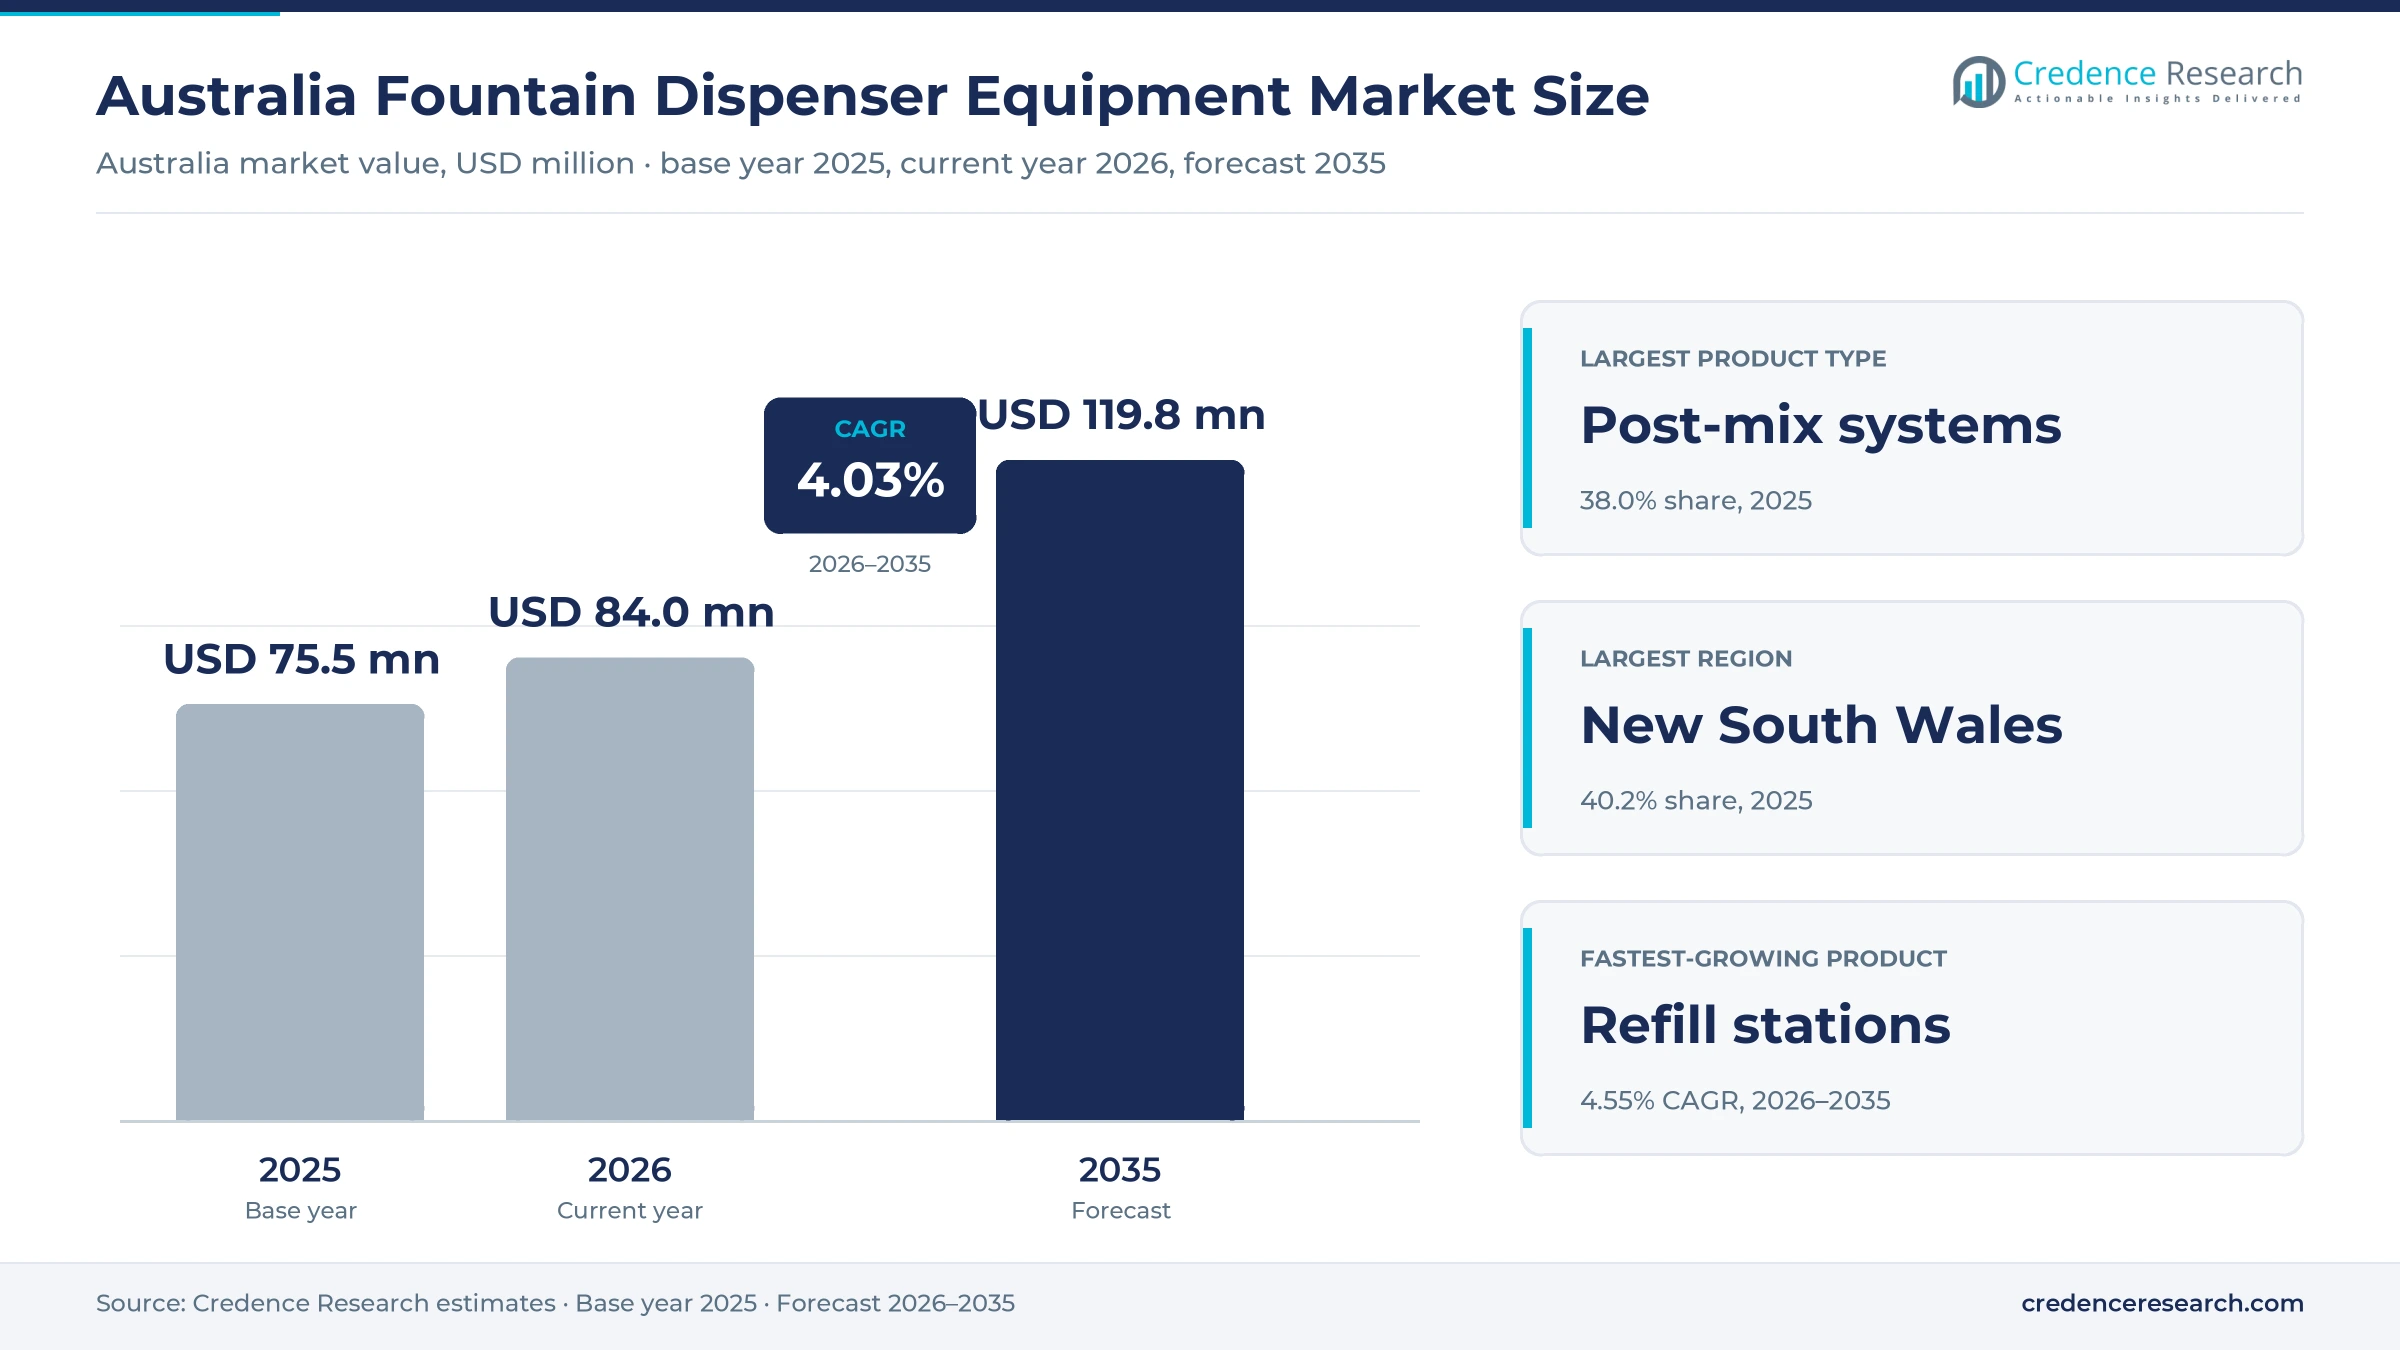
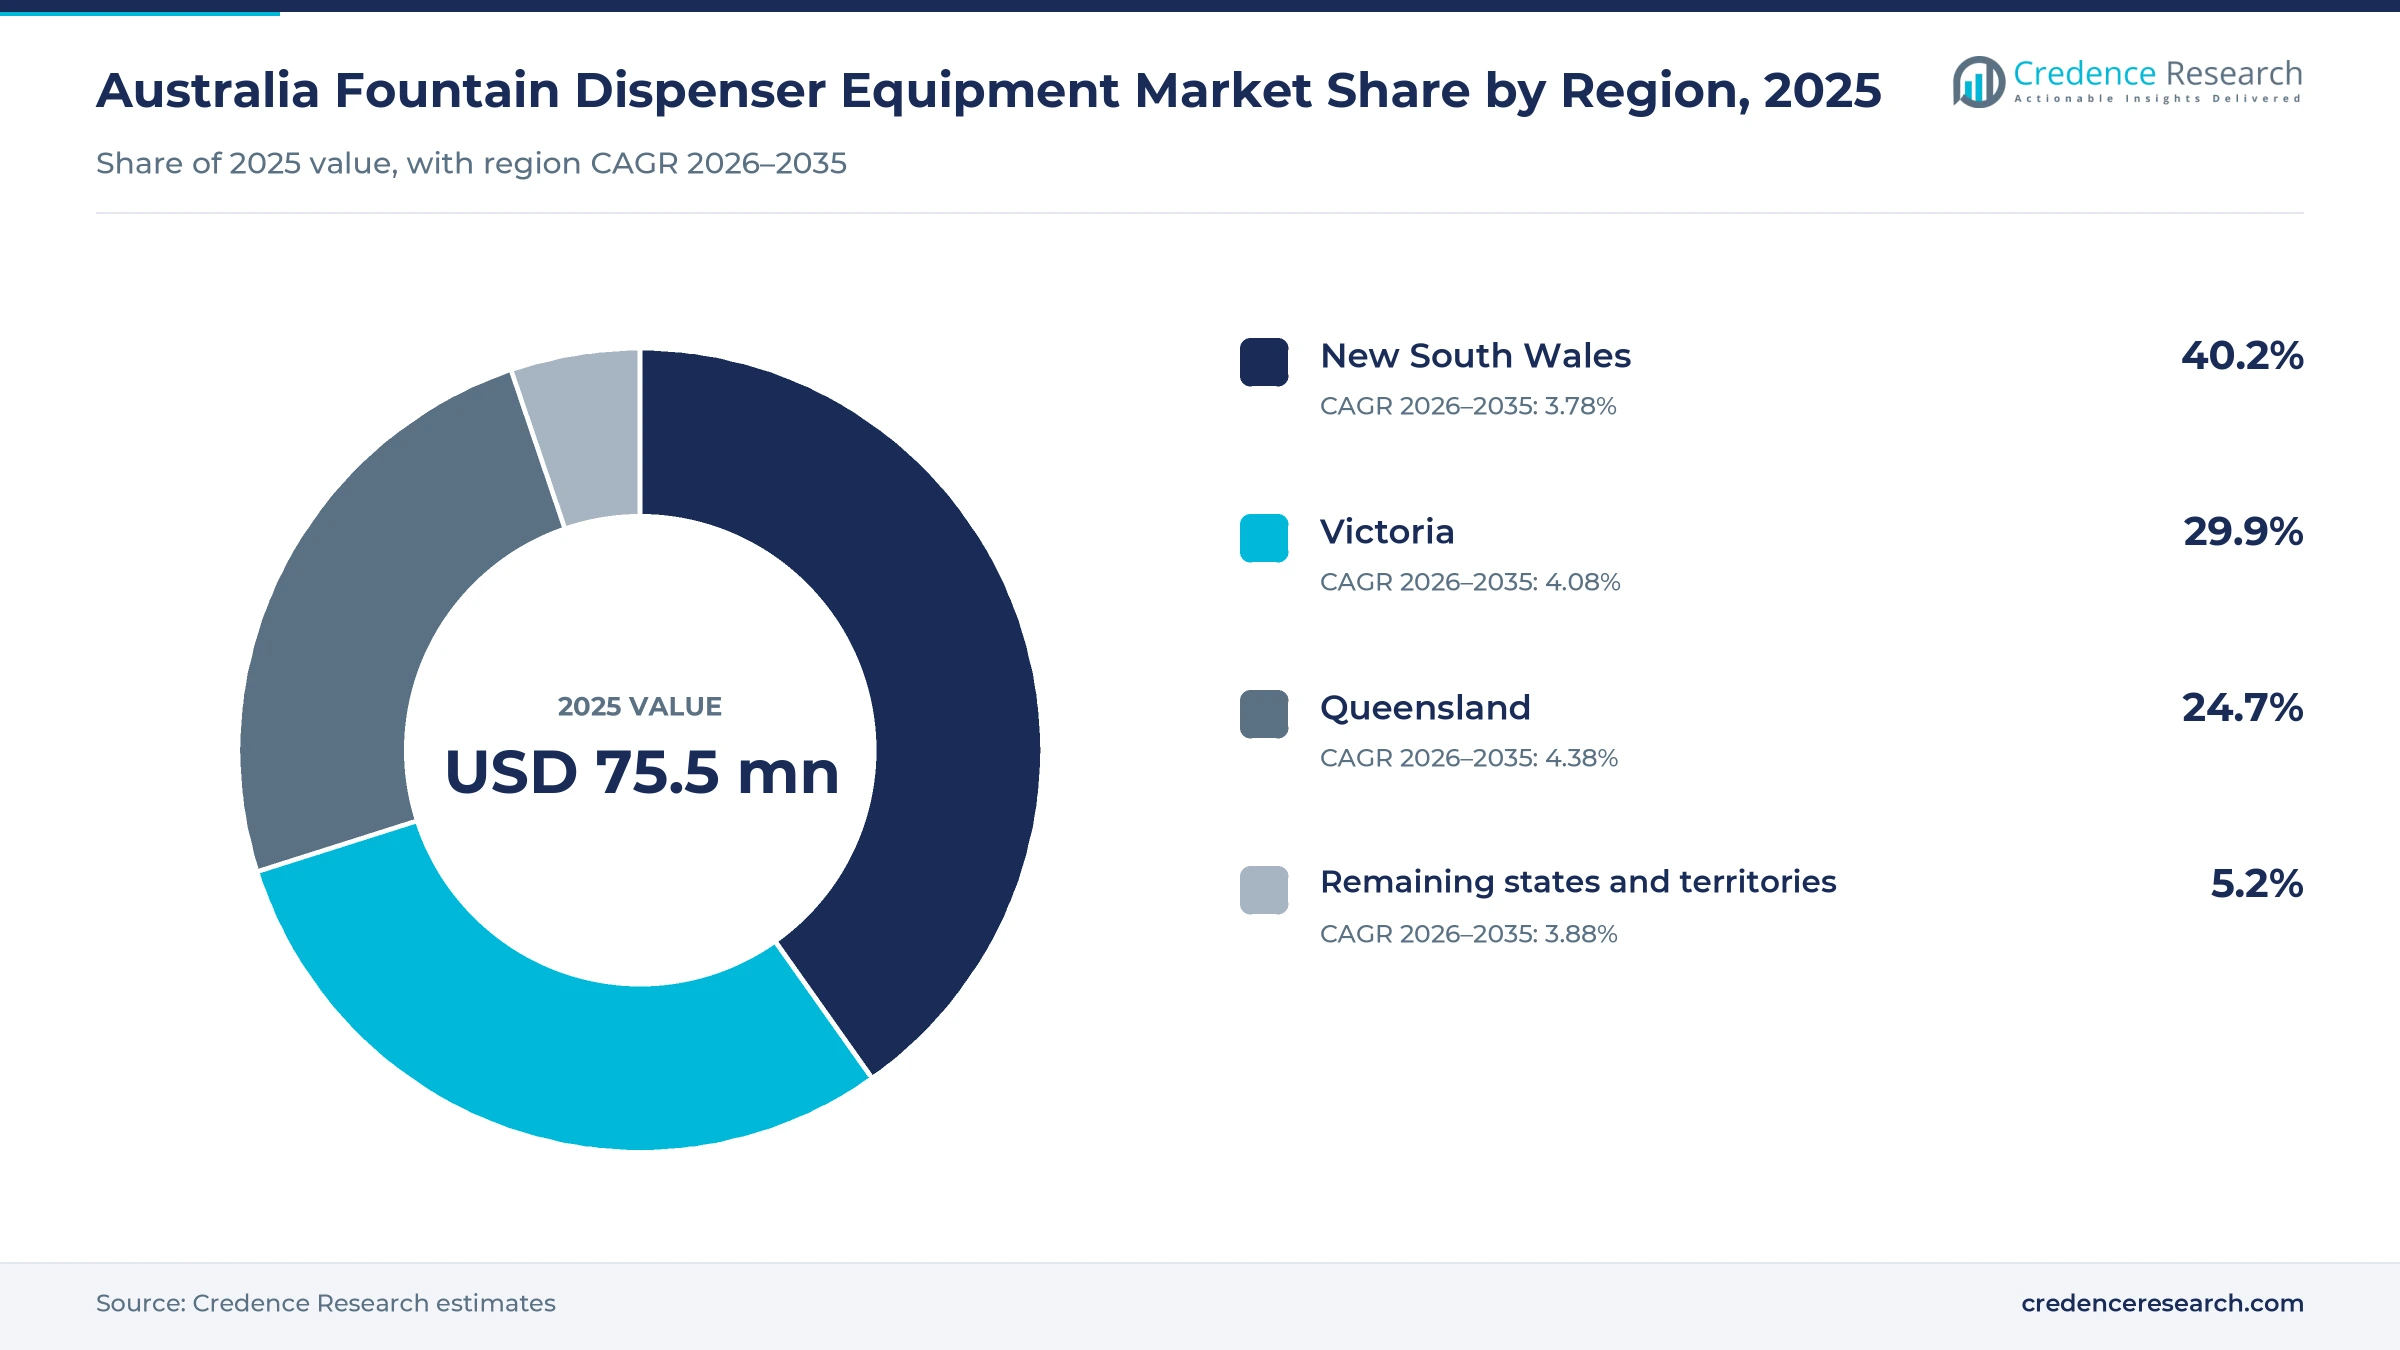
The Australia fountain dispenser equipment market was valued at USD 75.5 million in 2025 and is projected to increase from USD 84.0 million in 2026 to USD 119.8 million by 2035, registering a CAGR of 4.03% during 2026–2035. Demand comes from cafes, quick-service restaurants, cinemas and convenience stores that replace post-mix soft drink systems, and from schools, councils and transport operators that install drinking fountains and bottle refill stations. New South Wales held the largest regional share, 40.2% in 2025, because it has the largest population and the densest network of hospitality venues in the country. Queensland is the fastest-growing region at 4.38% a year, as new schools and fast population growth add installation sites. In turn, Queensland announced more than 50 state school upgrade projects in October 2025, which shows how school capital programs are adding hydration points.
Which dispensing and drinking water units does the estimate cover?
The estimate measures the value of new fountain dispensing equipment sold in Australia, including post-mix carbonated systems, drinking fountains and bottle refill stations, specialty cold beverage systems and the parts and carbonation hardware that keep them running. It counts equipment bought by hospitality, retail, education, health care, council and workplace buyers through direct, distributor, project and digital channels.
The estimate excludes beverage syrups, carbon dioxide gas, bottled water, beer dispensing systems and routine service labor that is billed separately from parts. The value chain runs from local foundries and global equipment makers through distributors and installers to venues, schools, councils and the people who drink from each unit.
Australia Fountain Dispenser Equipment Market Insights
- The Australia fountain dispenser equipment market was valued at USD 75.5 million in 2025 and is projected to reach USD 119.8 million by 2035, registering a CAGR of 4.03% during 2026–2035.
- New South Wales held a 40.2% share of 2025 value, because the state has 8.67 million residents and the largest base of hospitality venues.
- Post-mix carbonated systems led with a 38.0% share of 2025 value, because quick-service restaurants, cinemas and pubs rely on them for soft drink sales.
- Queensland began more than 50 school upgrade projects in October 2025 and reported that one third of state school assets had reached the end of their life.
- Drinking fountains and refill stations grow fastest at 4.55% a year during 2026–2035, as schools and councils replace old bubblers with bottle refill units.
Post-mix systems lead while refill stations grow fastest
Why do post-mix systems hold the largest value?
Based on product type, the market is categorized into post-mix carbonated systems, drinking fountains and refill stations, specialty cold beverage systems, and parts and carbonation hardware. Post-mix carbonated systems led with a 38.0% share of 2025 value, because quick-service chains and cinemas buy multi-valve towers with built-in cooling. Drinking fountains and refill stations grow fastest at 4.55% a year, as schools and councils replace old bubblers with combined drinking and bottle refill units.
How do replacement cycles drive most purchases?
Based on application, the market is categorized into new-site equipment deployment, scheduled equipment replacement, capacity and feature upgrades, and repair and component renewal. Scheduled equipment replacement led with a 34.0% share of 2025 value, because venues and schools retire worn units on fixed asset cycles. Capacity and feature upgrades grow fastest at 4.61% a year, as buyers add bottle fillers, chilling and touch-free sensors to existing sites.
Which buyers account for most installed units?
Based on end user, the market is categorized into food-service and hospitality operators, convenience and entertainment operators, education and healthcare facilities, and public-space and workplace operators. Food-service and hospitality operators led with a 44.0% share of 2025 value, because cafes, restaurants and pubs run the largest fleet of post-mix systems. Education and healthcare facilities grow fastest at 4.58% a year, as schools and hospitals replace old bubblers with refill units.
How do buyers source dispensing units?
Based on sales channel, the market is categorized into direct supplier contracts, specialist distributor contracts, project procurement contracts and digital equipment transactions. Direct supplier contracts led with a 36.0% share of 2025 value, because beverage brands and large chains buy fleets with service included. Digital equipment transactions grow fastest at 4.99% a year, as small cafes and schools order standard units through online hospitality and plumbing stores.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Post-mix carbonated systems | 38.0% | Drinking fountains and refill stations | 4.55% |
| By Application | Scheduled equipment replacement | 34.0% | Capacity and feature upgrades | 4.61% |
| By End User | Food-service and hospitality operators | 44.0% | Education and healthcare facilities | 4.58% |
| By Sales Channel | Direct supplier contracts | 36.0% | Digital equipment transactions | 4.99% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
School, venue and public refill renewal lifts unit sales
How does school hydration renewal lift unit demand?
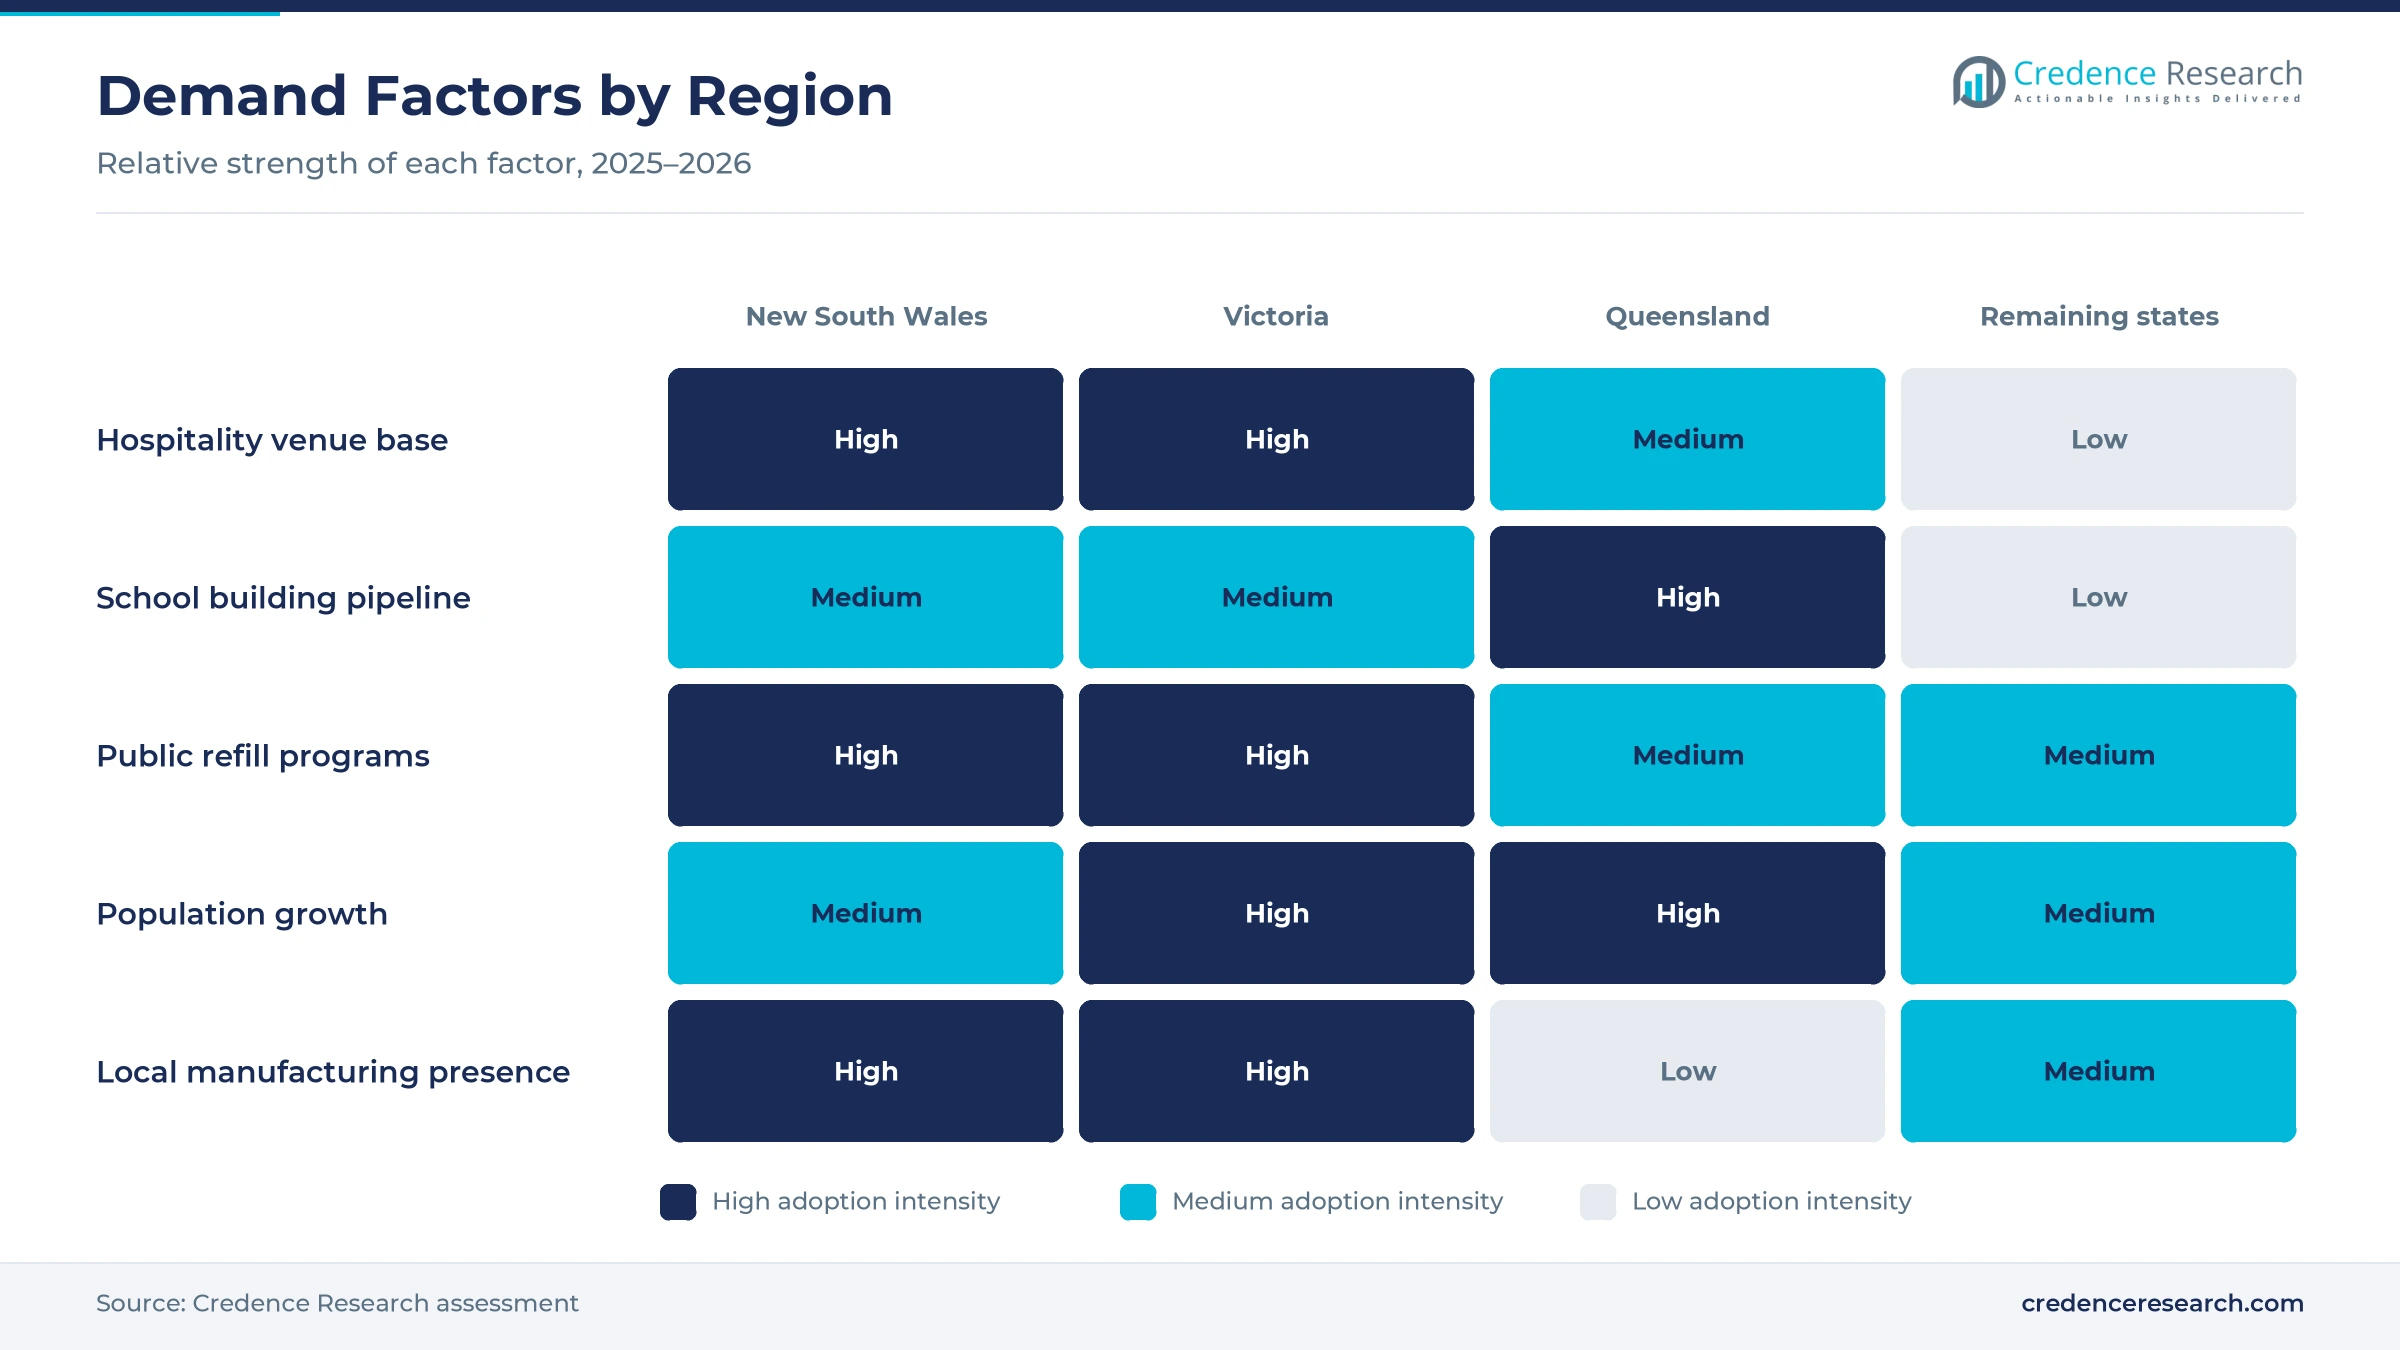
Education hydration renewal lifts demand, because many schools still run aging bubblers that need replacement with hygienic bottle refill units. Queensland reported repairs worth A$441 million for state school infrastructure and said one third of state school assets had reached the end of their life, according to an Oct. 28, 2025, Queensland government statement. The same statement said more than 50 upgrade projects were underway at 49 schools, while 15 new schools were under construction. Biloela State School introduced two Aquafil Hydrobank stations in August 2025, each with three refill points and three drinking fountains. As a result, education and healthcare facilities grow at 4.58% a year, as school capital budgets fund new hydration points.
Why does food-service equipment renewal sustain sales?
Food-service equipment renewal sustains sales, because cafes, restaurants and takeaway outlets must replace post-mix towers, coolers and valves as they wear out. Cafes, restaurants and takeaway food services turned over A$5,609.9 million in May 2025 in seasonally adjusted terms, up from A$5,402.8 million a year earlier, according to the Australian Bureau of Statistics. Total retail turnover reached A$37,293.0 million that month, up 3.3% on the year. Lancer Worldwide runs its Australian head office and factory in Adelaide, with a national service center that supports installed systems. In turn, post-mix carbonated systems hold 38.0% of 2025 value, because steady venue turnover keeps replacement orders flowing.
How do public refill programs add procurement?
Public hydration and refill procurement adds orders, because councils, water utilities and transport operators buy outdoor stations to cut plastic bottle waste. Plastic makes up about 74% of litter in New South Wales waterways, and less than 16% of plastic waste is recycled in the state, according to the New South Wales government. Sydney Water also backed eight Aquafil bubbler and refill stations with dog bowls across the Blue Mountains in 2017. Melbourne water retailers also placed six sensor-activated fountains at five train stations in March 2021. As a result, public-space and workplace operators keep adding units, as refill points spread to parks, stations and public bubblers along busy routes.
Why does population growth widen installation sites?
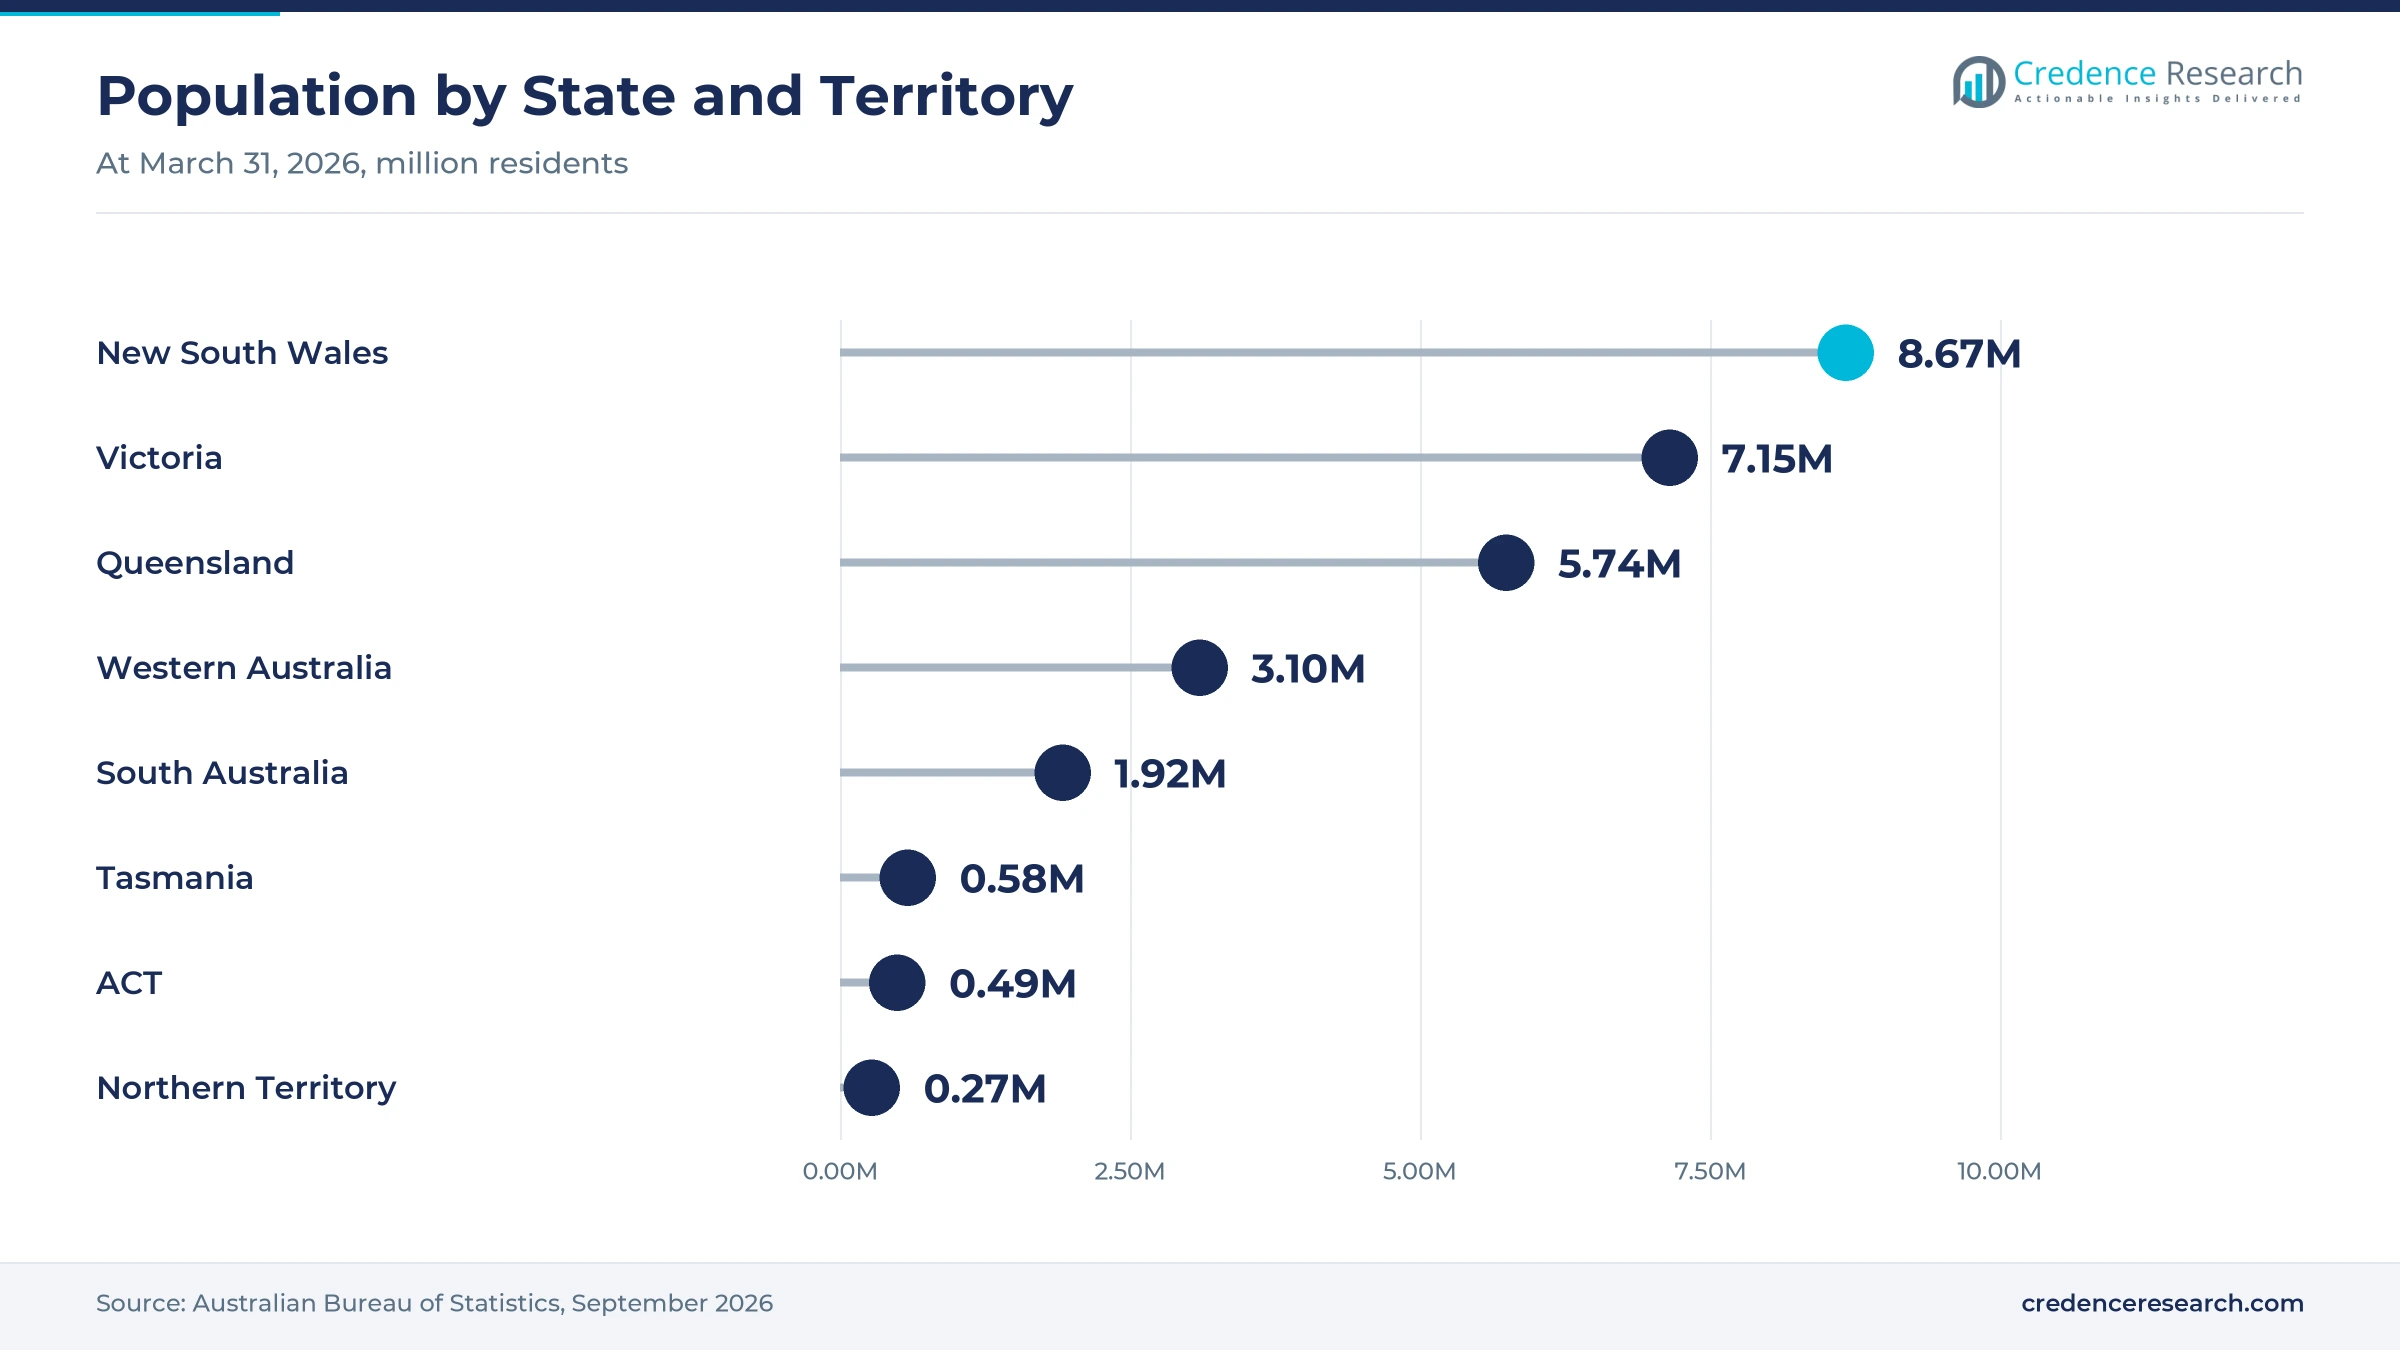
Population growth widens installation sites, because each new suburb needs schools, sports grounds, shopping centers and food outlets that install dispensing units. Australia's population reached 27.9 million at March 31, 2026, up 392,700 people or 1.4% in a year, according to the Australian Bureau of Statistics. Queensland added 90,100 residents and grew 1.6%, while Western Australia grew fastest at 2.1%. Urban residents made up 87.7% of the Australian population in 2025, according to the World Bank, which concentrates demand in dense city venues. In turn, Queensland gains the most new sites, as fast-growing suburbs add new hospitality venues and schools.
Touch-free, accessible and refill designs reshape the range
How is the shift to touch-free units changing designs?
The shift to touch-free units is changing designs, because councils and schools want hygienic fountains that users can operate without pressing buttons. Furphy Foundry makes its Aqua-Hub fountain in Shepparton with sensors that start the bubbler, bottle filler and pet drinking panel without contact. Melbourne water retailers launched 6 sensor fountains at 5 train stations in March 2021, using motion sensors that start the water flow for commuters. Zip Water won a 2026 Australian Good Design Award in October 2026 for its Accessible Remote, made in Condell Park in New South Wales. As a result, capacity and feature upgrades grow at 4.61% a year, as buyers retrofit sensors and controls onto existing sites.
Why is the rise of combined refill stations notable?
The rise of combined refill stations is notable, because buyers now want one unit that serves drinking, bottle filling and sometimes pets. The Aquafil Hydrobank stations installed at Biloela State School in August 2025 each combine three refill points with three drinking fountains. Enware released its Blueline range with six bubbler models, each offered as a bubbler alone or as a bubbler and bottle filler combination. Greater Western Water planned nearly 50 Choose Tap fountains across Melbourne's west by June 30, 2023, working with councils. In turn, drinking fountains and refill stations grow fastest at 4.55% a year, displacing bottled water coolers in many public sites.
Can reuse rules open refill demand in food service?
Reuse rules can open refill demand in food service, because operators that accept reusable cups and bottles need reliable dispensing points behind the counter and on the floor. New South Wales announced on Nov. 9, 2025, that takeaway food businesses must accept reusable cups by 2028 and large food service businesses must offer reusable options by 2030. The same reforms require tethered lids on plastic bottles by 2030. Choose Tap, a national coalition of 19 water retailers and councils, already promotes free tap water at public fountains. As a result, food-service operators that add filtered chilled taps and commercial beverage machines can meet reuse rules.
Is there room to grow in accessible school units?
Accessible school units offer room to grow, because school building programs now specify fountains that children and people with disability can use easily. Victoria announced A$13.8 million for 43 schools through its Capital Works Fund on Dec. 12, 2025, according to the Victorian government, and Fairhills High School's new outdoor area includes new drinking taps. Furphy Foundry offers its Aqua-Hub in four standard and four disability-compliant versions. Enware's Blueline levers also carry high-contrast labels with Braille for younger users. In turn, project procurement contracts grow at 4.99% a year, as state school programs bundle hydration units into wider upgrades.
Water quality, vandalism and tight budgets slow purchases
How do water quality concerns slow purchases?
Water quality concerns slow purchases, because buyers worry about lead, bacteria and taste in older pipes that feed public fountains and school bubblers. As a result, schools and councils sometimes delay new units until plumbing is tested and upgraded. Suppliers respond with filtered units, lead-safe components and flushing routines, which give facility managers confidence that the water meets health standards. This barrier is easing, and filtered models gain share in schools and hospitals as a result.
Why do vandalism and weather raise outdoor costs?
Vandalism and weather raise outdoor costs, because public fountains face heat, salt air, graffiti and deliberate damage in parks and beaches. In turn, councils budget for frequent repairs and spare parts, which reduces the number of new units they can buy each year. Makers respond with cast metal bodies, hidden fixings and stainless parts, which extend service life and cut repair visits for council crews. This cost pressure means robust designs now win more council tenders across the country.
How do tight capital budgets delay replacement?
Tight capital budgets delay replacement, because schools, councils and small cafes weigh dispensing units against roofing, air conditioning and kitchen upgrades. As a result, many buyers keep old bubblers and post-mix towers running past their planned life. Suppliers respond with rental, service bundles and staged upgrades, which spread costs over several years and let buyers replace the oldest units first. Budget limits therefore favor service-led suppliers that keep buyers loyal across replacement cycles.
Why do sugar reduction efforts cap post-mix volume?
Sugar reduction efforts cap post-mix volume, because health campaigns and school canteen rules push drinkers toward water and low-sugar options. In turn, some venues cut the number of soft drink valves and add water or low-sugar lines instead. Suppliers respond with towers that serve still and sparkling water, low-sugar drinks and flavored water from the same footprint, which protects sales as menus change. This volume risk means flexible towers now replace many single-purpose units in venues.
New South Wales leads while Queensland grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 30.4 | 40.2% | 3.78% |
| Victoria | 22.6 | 29.9% | 4.08% |
| Queensland | 18.6 | 24.7% | 4.38% |
| Remaining states and territories | 3.9 | 5.2% | 3.88% |
Why does New South Wales hold the top share?
New South Wales held a 40.2% share of 2025 value and grows at 3.78% a year, because the state had 8.67 million residents at March 31, 2026, the largest of any state. Sydney hosts the densest network of cafes, restaurants, cinemas and stadiums that run post-mix systems. Zip Water also designs and makes drinking water products at Condell Park in Sydney. As a result, New South Wales generates the largest share of replacement and new-site orders.
How does Victoria support public refill demand?
Victoria held a 29.9% share of 2025 value and grows at 4.08% a year, because the state had 7.15 million residents at March 31, 2026, and grew 1.6% in a year. Melbourne water retailers have installed Choose Tap fountains at train stations and across the western suburbs. Furphy Foundry also makes outdoor fountains in Shepparton for councils across the country. In turn, Victoria combines strong hospitality demand with active public refill programs.
Why is Queensland growing fastest?
Queensland held a 24.7% share of 2025 value and grows fastest at 4.38% a year, because the state added 90,100 residents in the year to March 2026. Queensland is building 15 new schools and announced more than 50 school upgrade projects in October 2025. Biloela State School also added two refill stations in August 2025. As a result, Queensland wins more new-site orders from schools, sports grounds and growing suburbs than other states.
How do the remaining states and territories contribute?
The remaining states and territories held a 5.2% share of 2025 value and grow at 3.88% a year, because they cover smaller populations and fewer large venues. Western Australia grew fastest of all states at 2.1% in the year to March 2026. Lancer Worldwide runs its Australian head office and factory in Adelaide. In turn, these areas rely on distributors and national service networks for most purchases.
School hydration projects and policy milestones
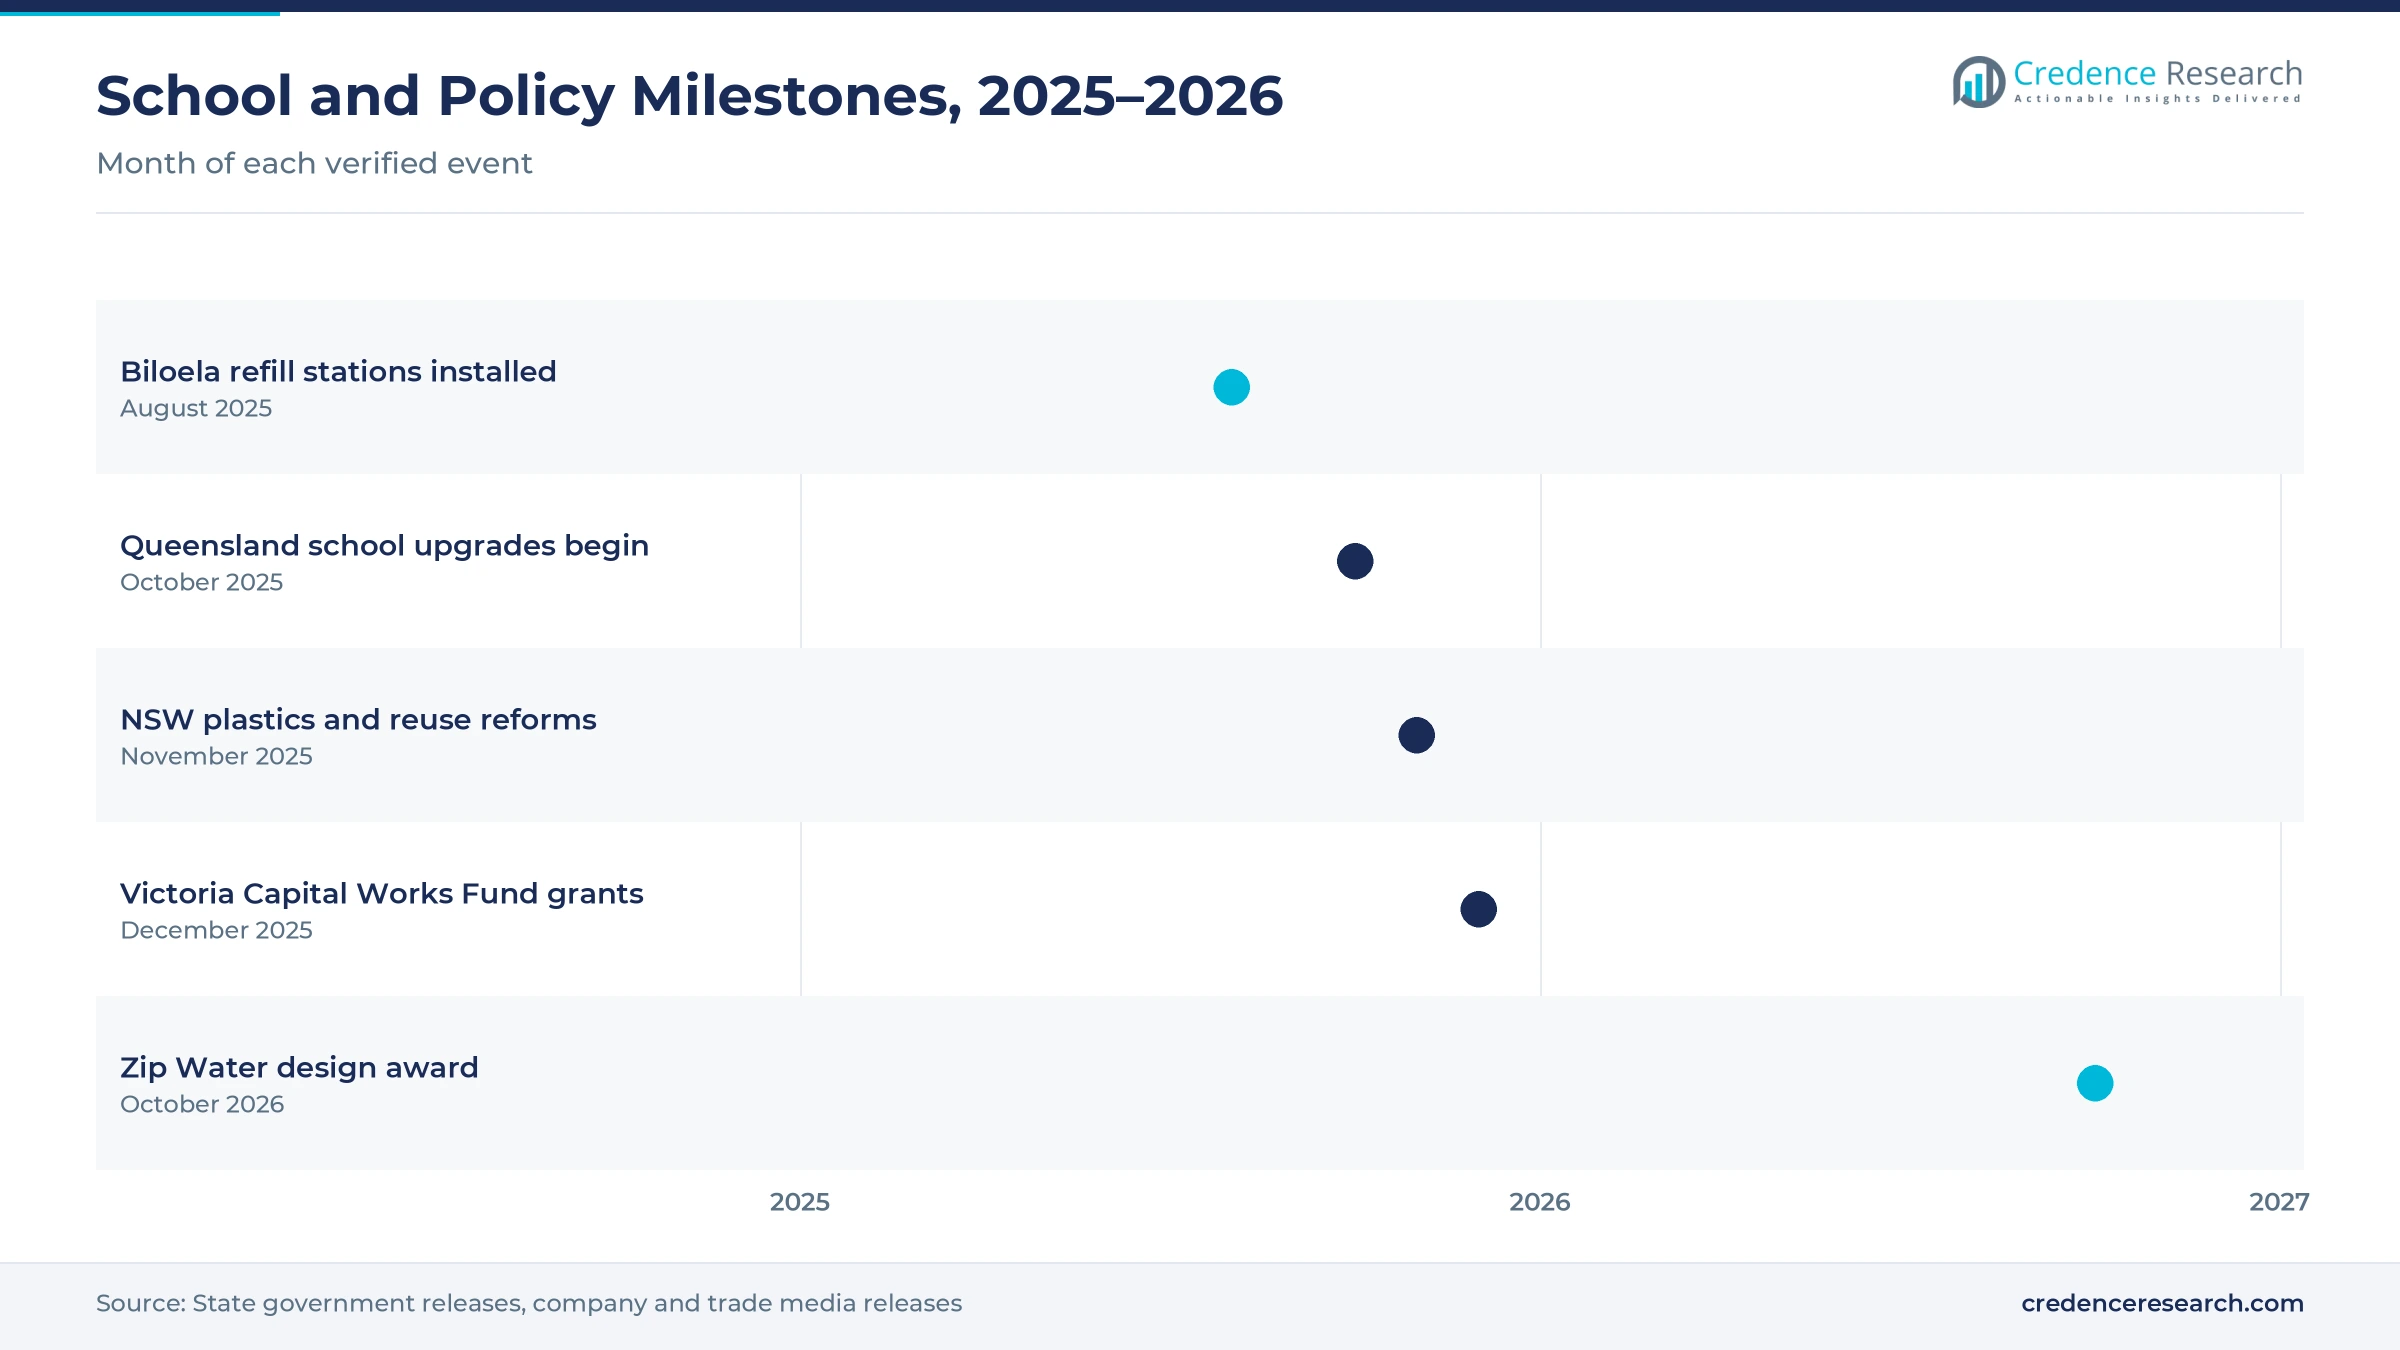
| Development | Status and market relevance |
|---|---|
| In August 2025, Civiq supplied two Aquafil Hydrobank stations to Biloela State School, each with three refill points and three drinking fountains. | Shows school demand for combined refill stations |
| In October 2025, the Queensland government reported more than 50 upgrade projects at 49 state schools and repairs worth A$441 million. | Signals renewal spending in school infrastructure |
| In November 2025, New South Wales announced that takeaway food businesses must accept reusable cups by 2028. | Supports refill and reuse in food service |
| In December 2025, Victoria shared A$13.8 million among 43 schools through its Capital Works Fund, including new drinking taps. | Funds small school upgrades with hydration points |
| In October 2026, Zip Water won a 2026 Australian Good Design Award for its Accessible Remote, made in Condell Park. | Highlights accessible drinking water design |
Controls, filtration and sensors define new units
- Electronic portion controls measure syrup and water ratios on post-mix towers, which keeps drink quality steady and cuts waste for busy venues.
- Inline filtration removes sediment, chlorine taste and some contaminants, which gives schools and offices better-tasting chilled water.
- Sensor activation starts the flow when a hand or bottle comes close, which reduces touch points in schools, stations and parks.
- Connected diagnostics report faults, filter life and usage to service teams, which shortens repair visits and plans part replacement.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Local makers and global brands compete on service reach
Competition combines global beverage equipment makers that serve chains and beverage brands with Australian manufacturers that dominate outdoor drinking fountains and school units. Lancer Worldwide competes from its Adelaide head office and factory, supported by a national service center. Zip Water competes in filtered chilled and boiling water systems with products designed and made at Condell Park in Sydney. Civiq competes in outdoor refill stations through its Aquafil range, including Hydrobank units for schools. Furphy Foundry competes with cast fountains made in Shepparton, including touch-free Aqua-Hub models. Enware competes in school bubblers and bottle fillers through its Blueline range. Waterlogic Australia competes in bottle-free coolers and bubblers, according to Australian competition regulator findings. Rivals compete on durability, hygiene, accessibility, service coverage and total cost of ownership.
Which suppliers serve Australian venues and schools?
| Company | Type | Role in the market |
|---|---|---|
| Lancer Worldwide Australia | Beverage equipment maker | Runs its Australian head office and factory in Adelaide |
| Zip Water | Drinking water systems maker | Designs and makes products at Condell Park in Sydney |
| Aquafil by Civiq | Outdoor fountain maker | Supplies Hydrobank refill stations to schools |
| Furphy Foundry | Foundry and fountain maker | Makes touch-free Aqua-Hub fountains in Shepparton |
| Enware Australia | Plumbing products maker | Offers Blueline bubblers and bottle fillers |
| Waterlogic Australia | Drinking water supplier | Supplies bottle-free coolers and bubblers |
Credence Research view on hydration and venue renewal
Credence Research's view is that Australian fountain dispensing equipment will grow steadily because schools, councils and venues must replace aging units while adding new sites in fast-growing suburbs. Post-mix systems remain the largest value pool, while refill stations and accessible school units add the fastest growth. Reuse rules in New South Wales and school capital programs in Queensland and Victoria will support purchases. Suppliers with local manufacturing, strong service networks and touch-free designs should gain the most, while tight budgets and sugar reduction efforts limit post-mix volume.
How the national dispensing estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines official population and retail statistics, state government school and plastics releases, competition regulator findings and company product information. Segment splits and zone growth rates are Credence Research estimates, while zone shares follow the client-provided split. Sources used are official statistics, government releases, trade media and company releases, and no interviews or surveys were used.
Refill stations and venue upgrades carry growth to 2035
The Australia fountain dispenser equipment market is expected to reach USD 119.8 million by 2035, a 4.03% CAGR during 2026–2035, as venues renew post-mix systems and schools and councils add refill stations. Growth should be strongest in refill stations, project procurement and Queensland, because these areas gain most from school building and population growth. Reuse rules and accessible designs will widen demand, while tight budgets, vandalism and sugar reduction efforts could slow purchases in some segments.
Frequently Asked Questions
How big is the Australia fountain dispenser equipment market?
Which product type leads Australian fountain dispensing value?
Which region leads the Australian market?
How are schools driving demand for refill stations?
Which end user is growing fastest?
How do plastics rules affect fountain demand?
Who are the leading companies in the Australian market?
What are the main challenges for fountain suppliers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Post-mix carbonated systems
- 1.2.2 Drinking fountains and refill stations
- 1.2.3 Specialty cold beverage systems
- 1.2.4 Parts and carbonation hardware
- 1.3 By Application
- 1.3.1 New-site equipment deployment
- 1.3.2 Scheduled equipment replacement
- 1.3.3 Capacity and feature upgrades
- 1.3.4 Repair and component renewal
- 1.4 By End User
- 1.4.1 Food-service and hospitality operators
- 1.4.2 Convenience and entertainment operators
- 1.4.3 Education and healthcare facilities
- 1.4.4 Public-space and workplace operators
- 1.5 By Sales Channel
- 1.5.1 Direct supplier contracts
- 1.5.2 Specialist distributor contracts
- 1.5.3 Project procurement contracts
- 1.5.4 Digital equipment transactions
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 75.5 million → 2035: USD 119.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Fountain Dispenser Equipment Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Fountain Dispenser Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Fountain Dispenser Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Fountain Dispenser Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Fountain Dispenser Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Fountain Dispenser Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Fountain Dispenser Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Fountain Dispenser Equipment Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 75.5 million → 2035: USD 119.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Fountain Dispenser Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Post-mix carbonated systems
- 12.3.7.2 Drinking fountains and refill stations
- 12.3.7.3 Specialty cold beverage systems
- 12.3.7.4 Parts and carbonation hardware
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 New-site equipment deployment
- 12.4.7.2 Scheduled equipment replacement
- 12.4.7.3 Capacity and feature upgrades
- 12.4.7.4 Repair and component renewal
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Food-service and hospitality operators
- 12.5.7.2 Convenience and entertainment operators
- 12.5.7.3 Education and healthcare facilities
- 12.5.7.4 Public-space and workplace operators
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Sales Channel - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Direct supplier contracts
- 12.6.7.2 Specialist distributor contracts
- 12.6.7.3 Project procurement contracts
- 12.6.7.4 Digital equipment transactions
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Fountain Dispenser Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Fountain Dispenser Equipment Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Fountain Dispenser Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Fountain Dispenser Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Lancer Worldwide Australia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Cornelius
- 18.4 Enware Australia
- 18.5 Aquafil by Civiq
- 18.6 Waterlogic Australia
- 18.7 Frigmac
- 18.8 Furphy Foundry
- 18.9 The Water People
- 18.10 Zip Water
- 18.11 Australian Beverage Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

