
Heavy fleets and backup power anchor early zero-emission use
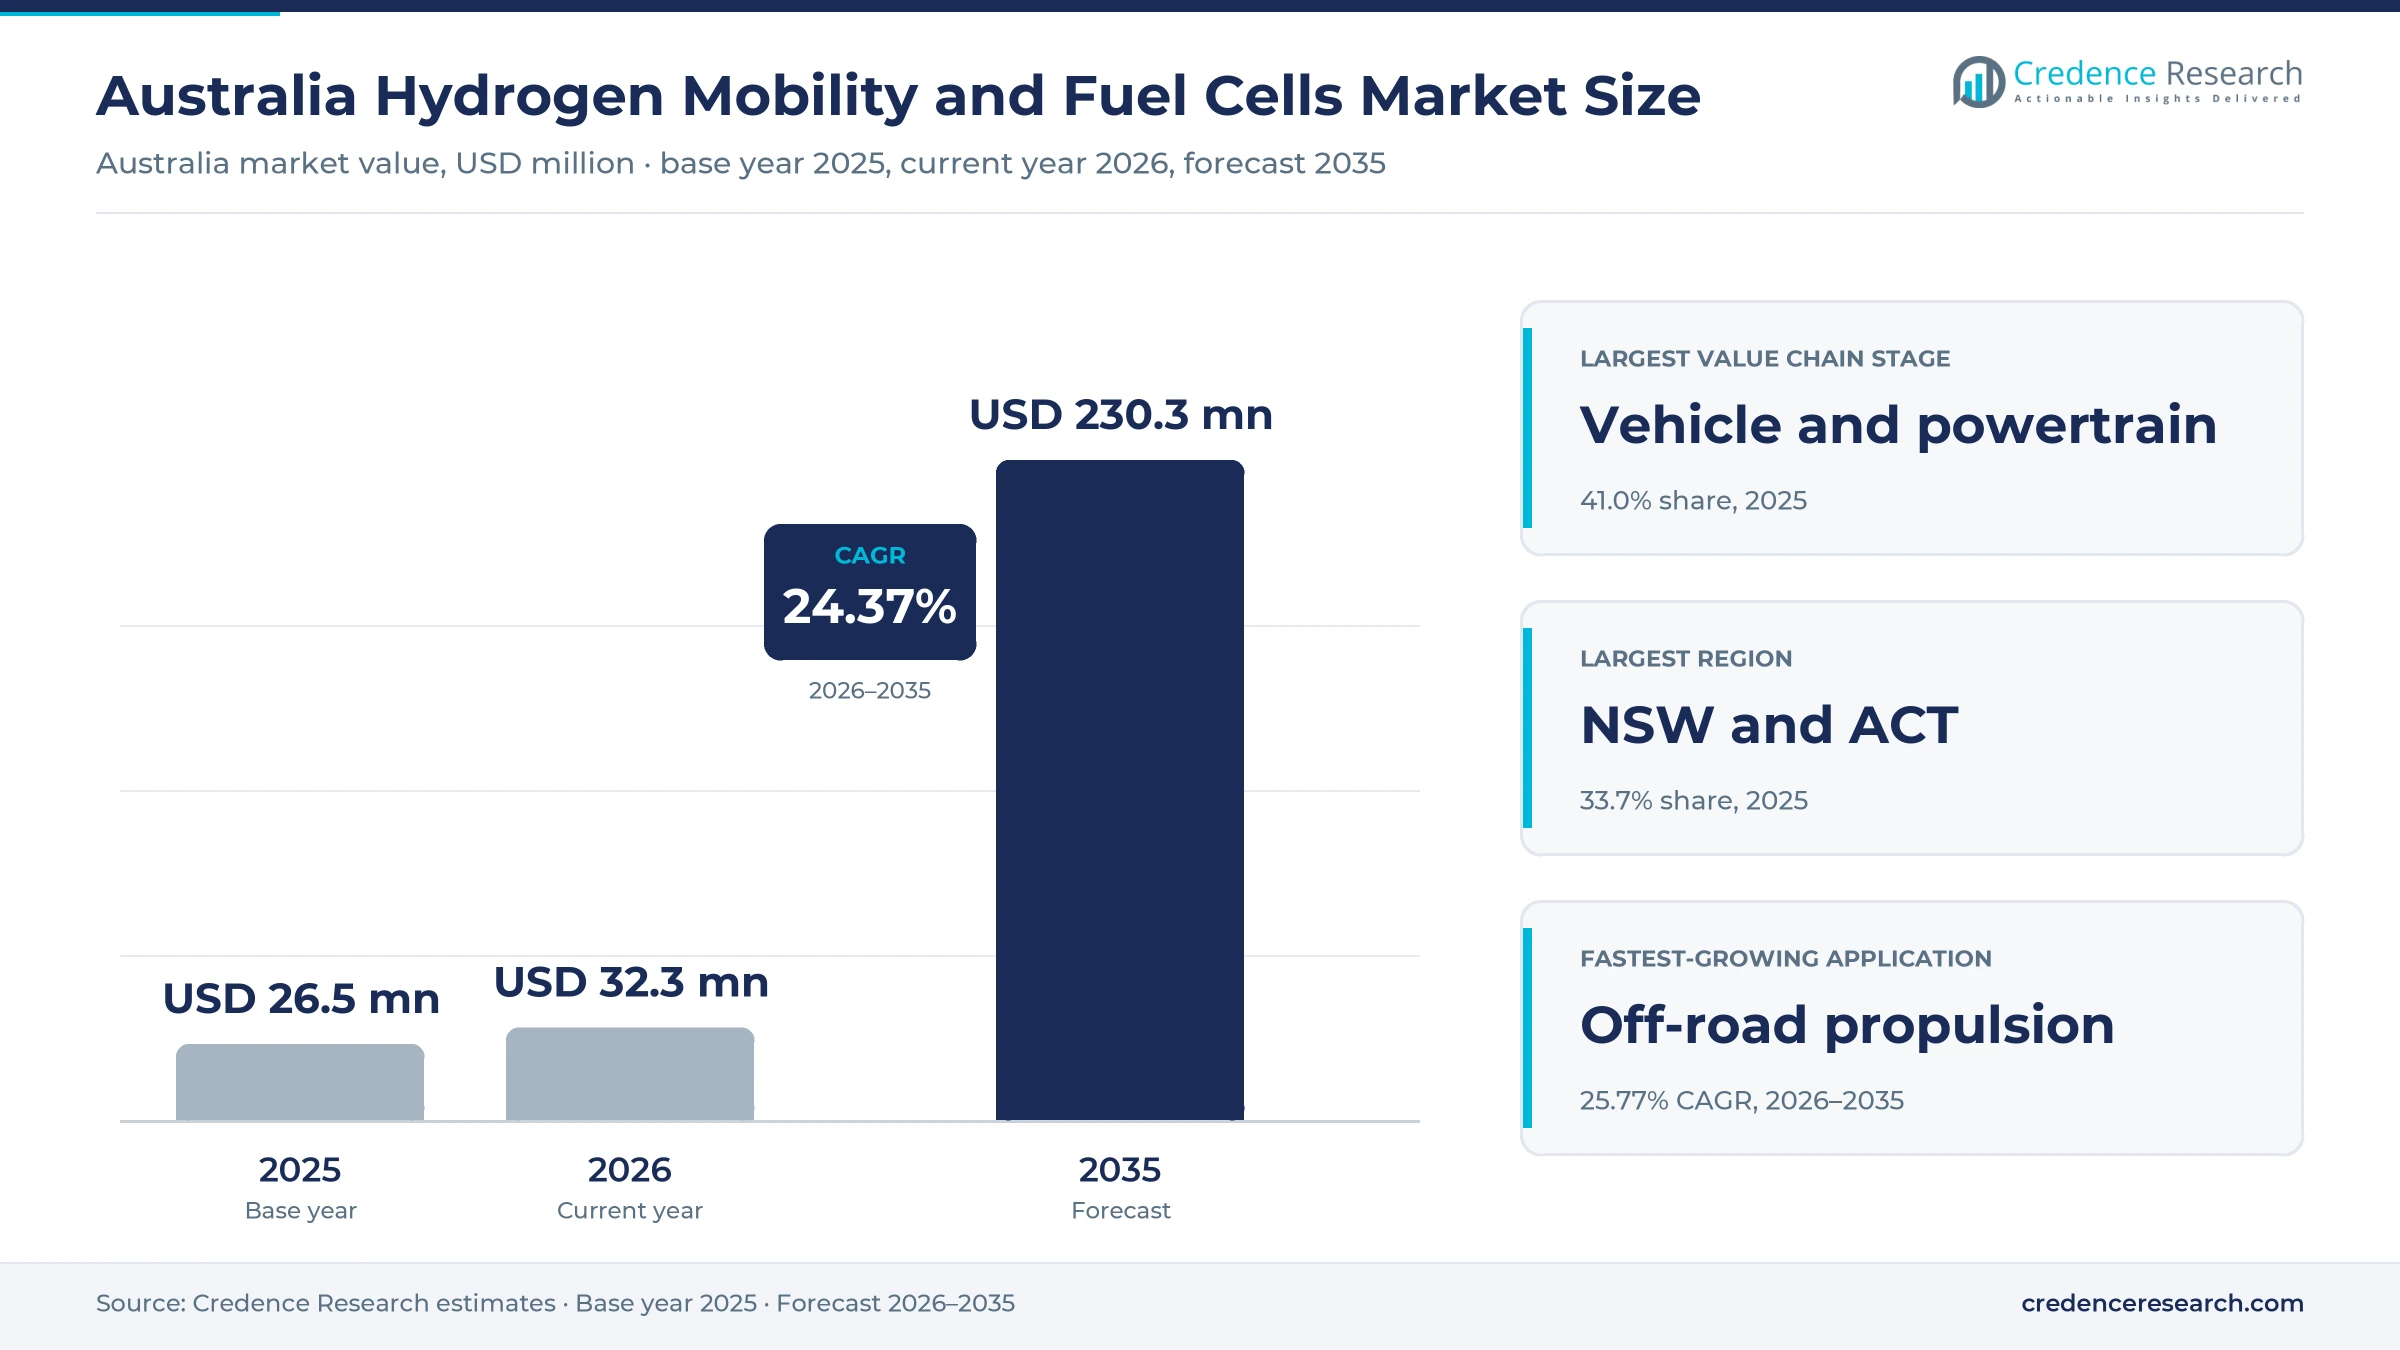
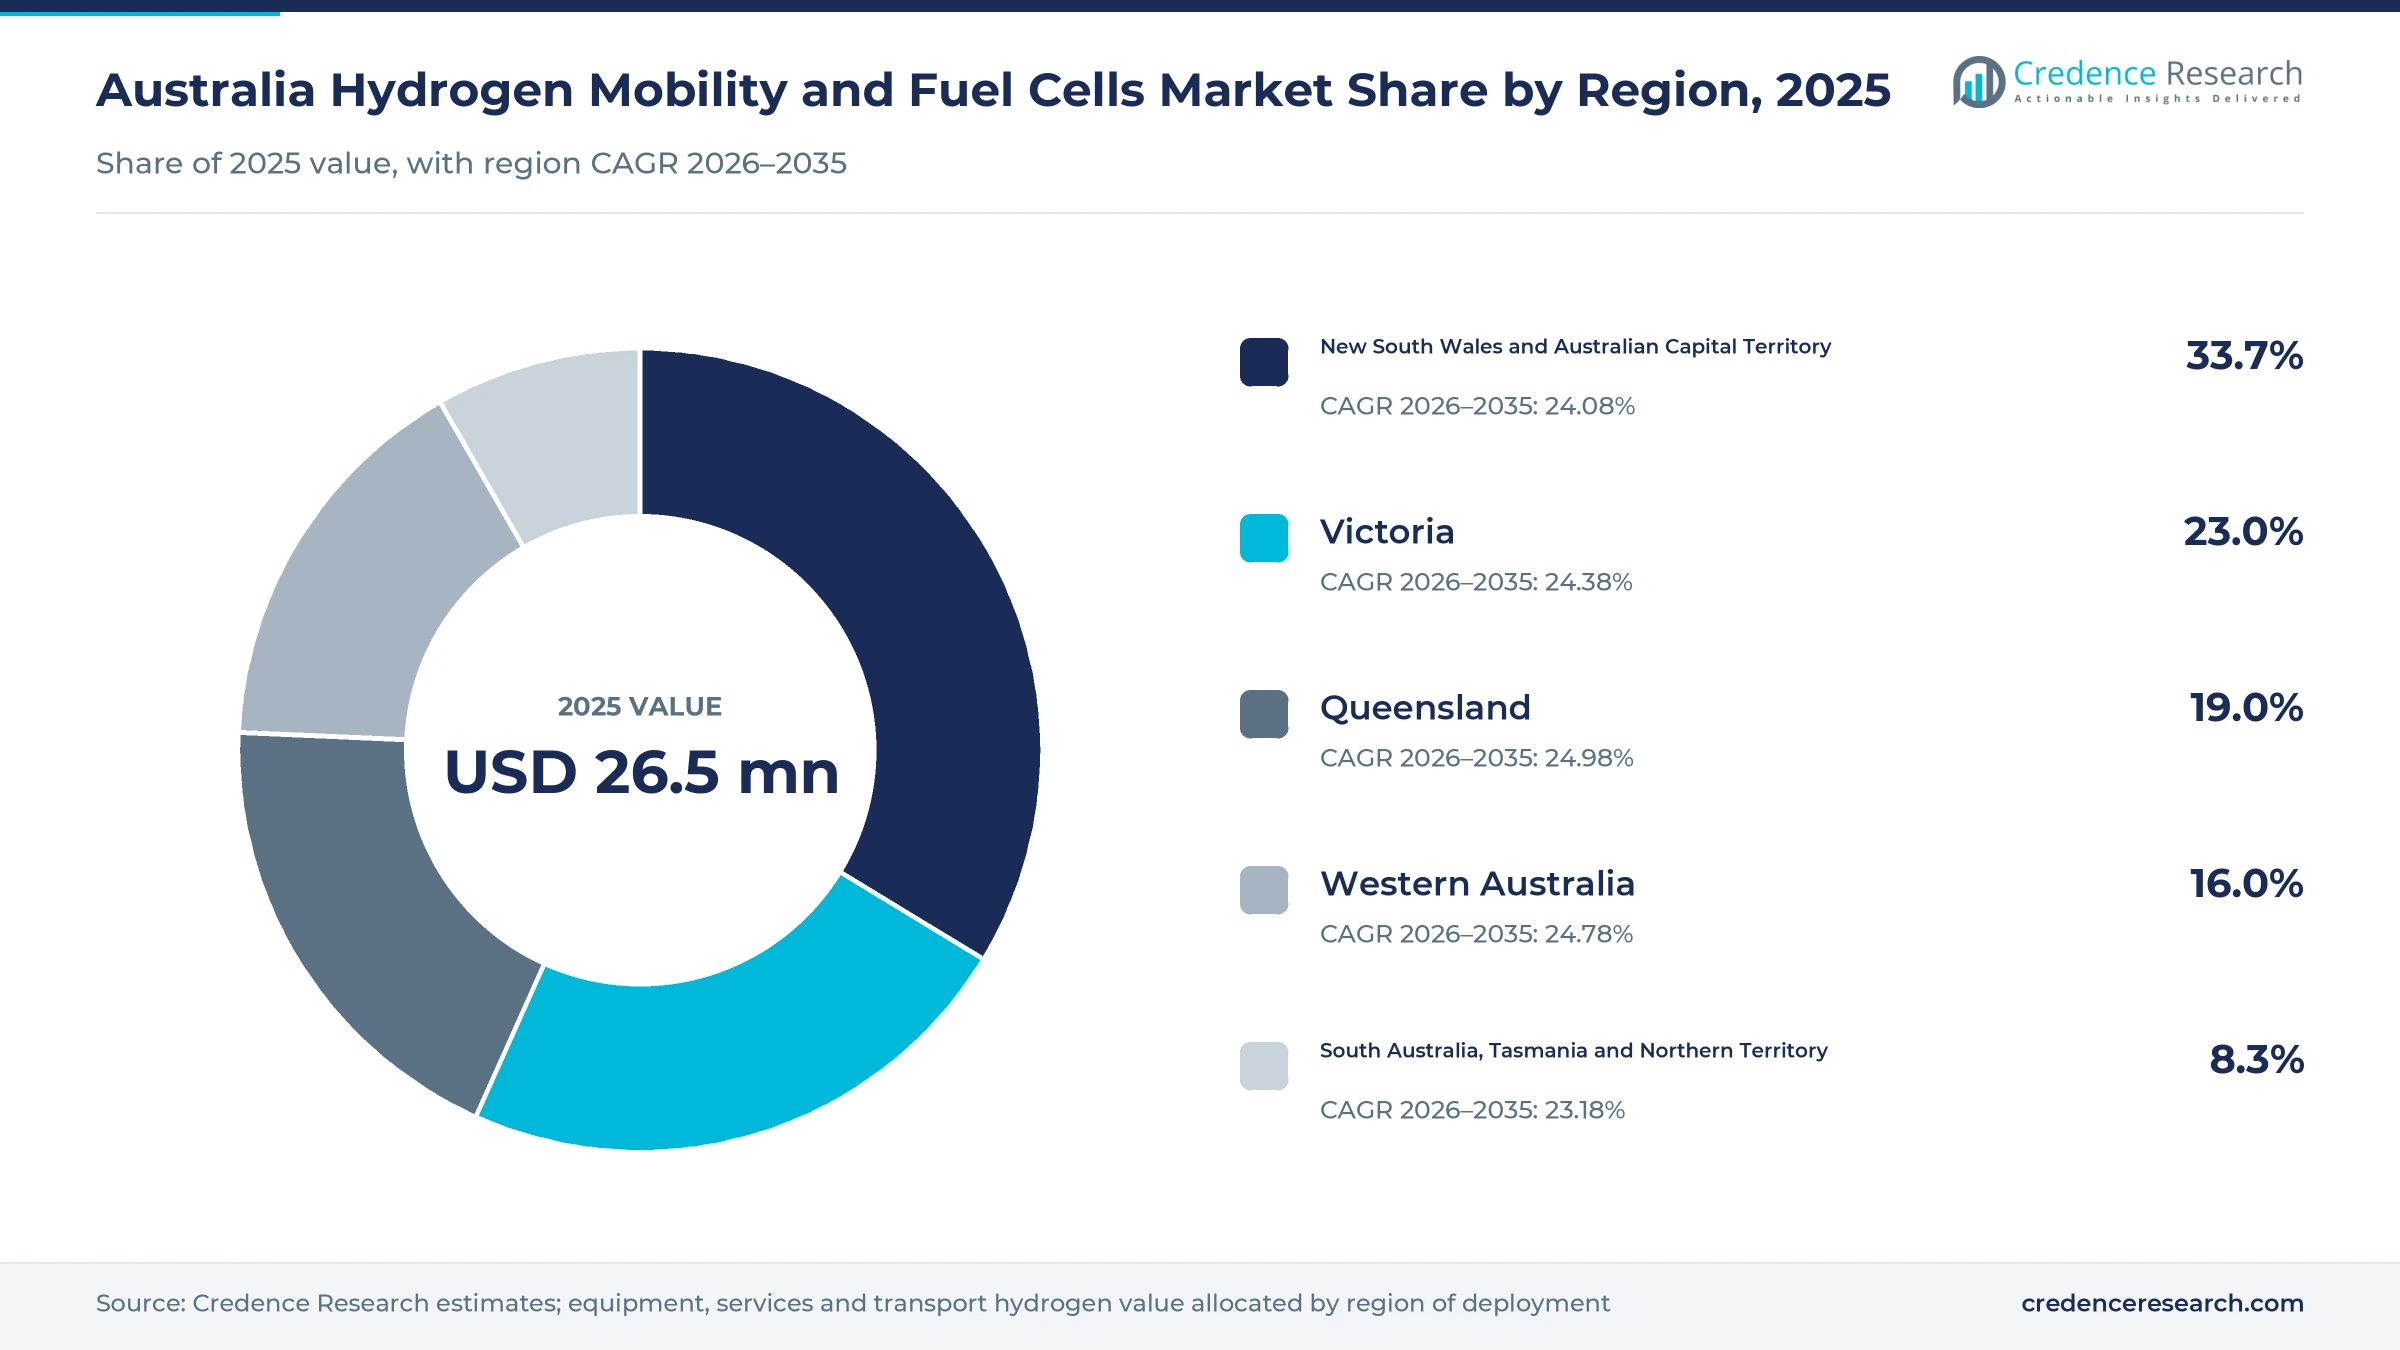
The Australia hydrogen mobility and fuel cells market was valued at USD 26.5 million in 2025 and is projected to increase from USD 32.3 million in 2026 to USD 230.3 million by 2035, registering a CAGR of 24.37% during 2026–2035. Demand comes from freight, waste and bus operators that trial zero-emission heavy vehicles on fixed routes, utilities and telecommunications companies that need clean backup power at remote sites, and mining operators that test alternatives to diesel equipment. New South Wales and the Australian Capital Territory held the largest regional share, 33.7% in 2025, because Sydney, Port Kembla and Canberra host early refueling sites and government fleets. Queensland is the fastest-growing region at 24.98% a year, as truck trials and dealer networks expand across the state. In turn, a federal production tax credit of A$2 per kilogram from 2027-28 improves the outlook for lower-cost renewable fuel at depots.
Which vehicles, systems and fuel sales does the estimate cover?
The estimate measures the value of zero-emission vehicles and powertrains, stationary and portable power systems, refueling equipment and services, transport fuel sales and engineering services linked to hydrogen used in Australia. It covers prime movers, rigid trucks, buses, waste trucks, light vehicles, mining equipment, tower backup generators and portable generators. Values include assets bought outright, leased from providers and owned through joint ventures.
The estimate excludes hydrogen made for ammonia, refining or export, large electrolyzer plants that do not supply transport or power users, and battery-electric vehicles. The value chain runs from fuel producers and equipment makers through vehicle importers, local body builders and integrators, refueling operators and service teams to fleet owners, utilities, miners and telecommunications operators across every state and territory.
Australia Hydrogen Mobility and Fuel Cells Market Insights
- The Australia hydrogen mobility and fuel cells market was valued at USD 26.5 million in 2025 and is projected to reach USD 230.3 million by 2035, registering a CAGR of 24.37% during 2026–2035.
- New South Wales and the Australian Capital Territory held a 33.7% share of 2025 value, because they host early stations and fleets.
- Vehicle and powertrain supply led with a 41.0% share of 2025 value, because trucks, buses and powertrains carry the highest unit prices.
- Viva Energy opened a public heavy-vehicle refueling station in Geelong on June 13, 2025, with an electrolyzer able to produce 1,000 kg a day.
- The federal production tax incentive pays A$2 per kilogram of renewable fuel from 2027-28 to 2039-40, for up to 10 years per project.
Vehicle supply leads while transport fuel sales grow fastest
Why does vehicle and powertrain supply lead value?
Based on value chain stage, the market is categorized into vehicle and powertrain supply, stationary system supply, refuelling equipment and services, transport hydrogen sales and engineering and commercial development. Vehicle and Powertrain Supply led with a 41.0% share of 2025 value, because prime movers, buses and powertrains carry high unit prices. Transport Hydrogen Sales grows fastest at 25.66% a year, as larger fleets buy fuel every day.
How does road fleet propulsion dominate applications?
Based on application, the market is categorized into road fleet propulsion, off-road vehicle propulsion, stationary backup power and portable prime power. Road Fleet Propulsion led with a 58.0% share of 2025 value, because trucks, buses and waste vehicles form most deployments. Off-Road Vehicle Propulsion grows fastest at 25.77% a year, as miners test zero-emission haulage and support equipment at remote sites.
Why do freight operators lead end-user demand?
Based on end user, the market is categorized into freight fleet operators, passenger transport operators, mining and construction operators, telecommunications operators and government and research fleets. Freight Fleet Operators led with a 30.0% share of 2025 value, because logistics companies run heavy vehicles on fixed depot routes. Mining and Construction Operators grow fastest at 25.60% a year, as remote mine sites seek diesel alternatives.
How does renewable fuel lead the energy source mix?
Based on energy source, the market is categorized into renewable electrolytic hydrogen, fossil-derived hydrogen with carbon capture, unabated fossil-derived hydrogen and mixed-origin merchant hydrogen. Renewable Electrolytic Hydrogen led with a 46.0% share of 2025 value, because depot projects pair vehicles with on-site electrolysis. Renewable Electrolytic Hydrogen grows fastest at 26.05% a year, as production tax credits lower supply costs.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Value Chain Stage | Vehicle and Powertrain Supply | 41.0% | Transport Hydrogen Sales | 25.66% |
| By Application | Road Fleet Propulsion | 58.0% | Off-Road Vehicle Propulsion | 25.77% |
| By End User | Freight Fleet Operators | 30.0% | Mining and Construction Operators | 25.60% |
| By Energy Source | Renewable Electrolytic Hydrogen | 46.0% | Renewable Electrolytic Hydrogen | 26.05% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Fleet orders, backup power and local builds lift demand
How does captive fleet procurement lift vehicle demand?
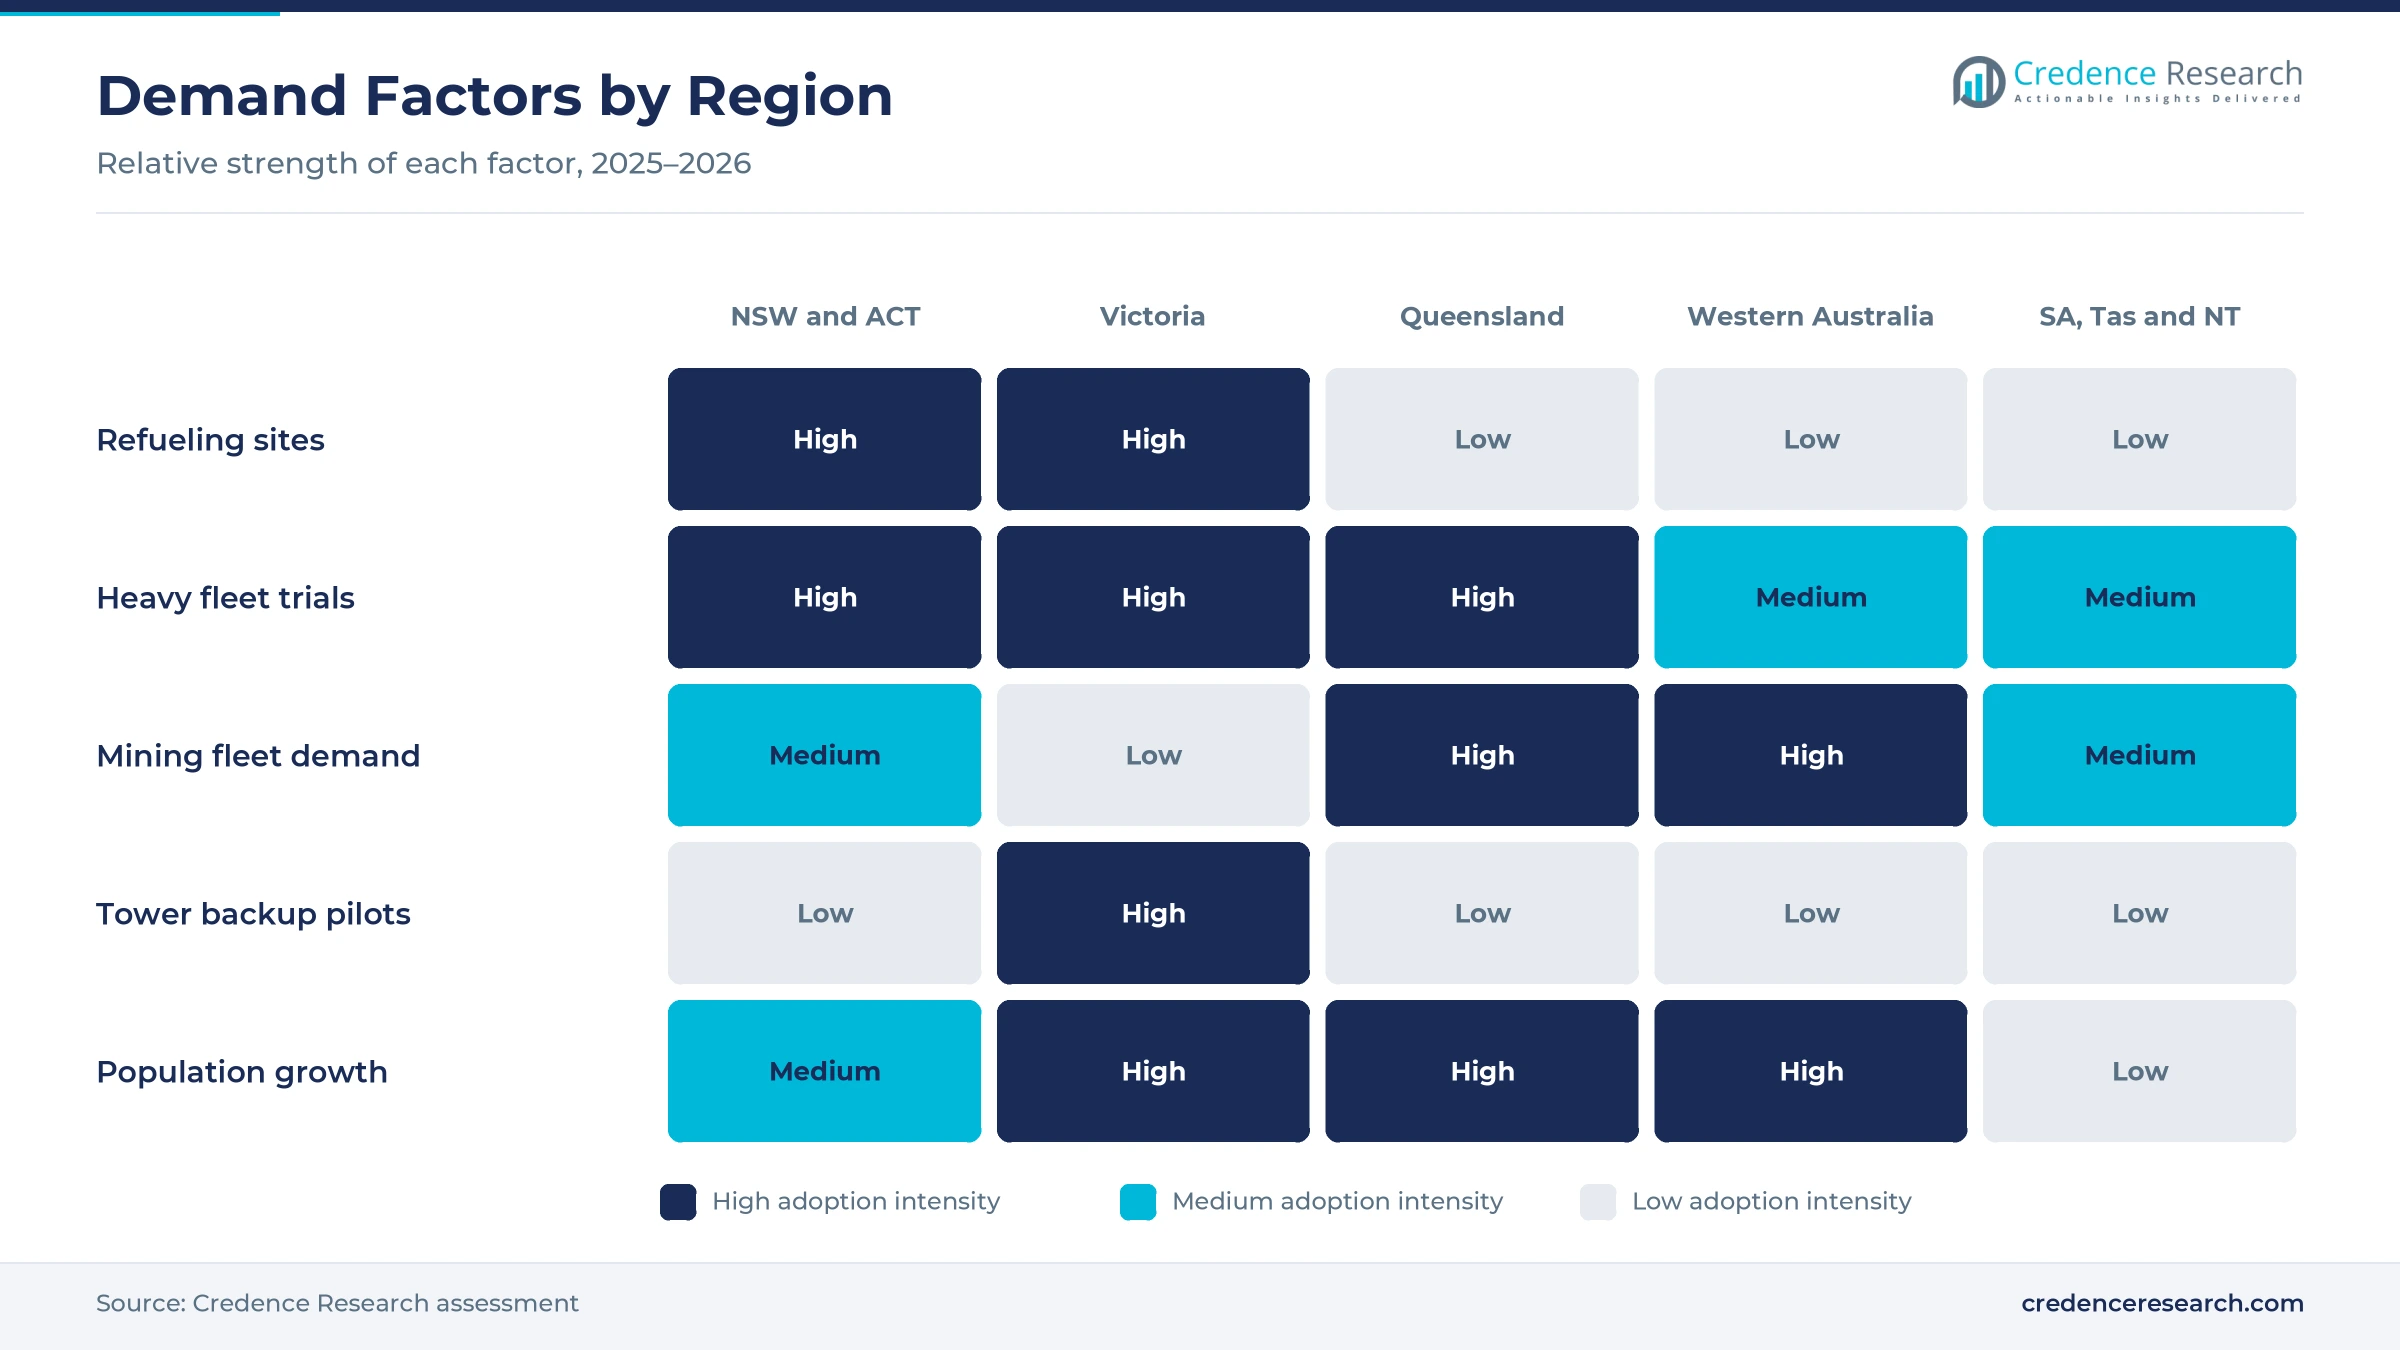
Captive fleet procurement lifts vehicle demand, because operators that return to one depot every night can share a single refueling site. Toll Group, ComfortDelGro, Cleanaway and Barwon Water bought vehicles for the Geelong hub with a A$34 million grant from the renewable energy agency, according to Viva Energy. Pure Hydrogen received a purchase order from Toll in January 2025 for two 70-ton prime movers, with delivery scheduled for late 2025. Coregas also added a heavy truck in November 2025 to carry industrial and medical cylinders. As a result, freight fleet operators hold a 30.0% share of 2025 value, as depot-based zero-emission trucks move from trials into service.
Why does stationary power commercialization widen use?
Stationary power commercialization widens use, because generators can replace diesel backup at sites that lose grid supply during storms. Energys and Telstra deployed five backup generators at mobile towers in Victoria, according to H2 View. The sites at Neerim North, Chum Creek, Christmas Hills, Coldstream and Kinglake were chosen for their vulnerability to storm damage. The pilot was co-funded by the Victorian Government, and Energys manufactures the generators with a largely local supply chain. The same state fund also contributed A$1 million to the Geelong refueling hub in 2025, which shows broad state support for clean backup and transport power. In turn, telecommunications operators add steady demand for tower power systems, and Victoria grows at 24.38% a year as storm-exposed sites replace diesel backup units.
How does local integration capability support fleet orders?
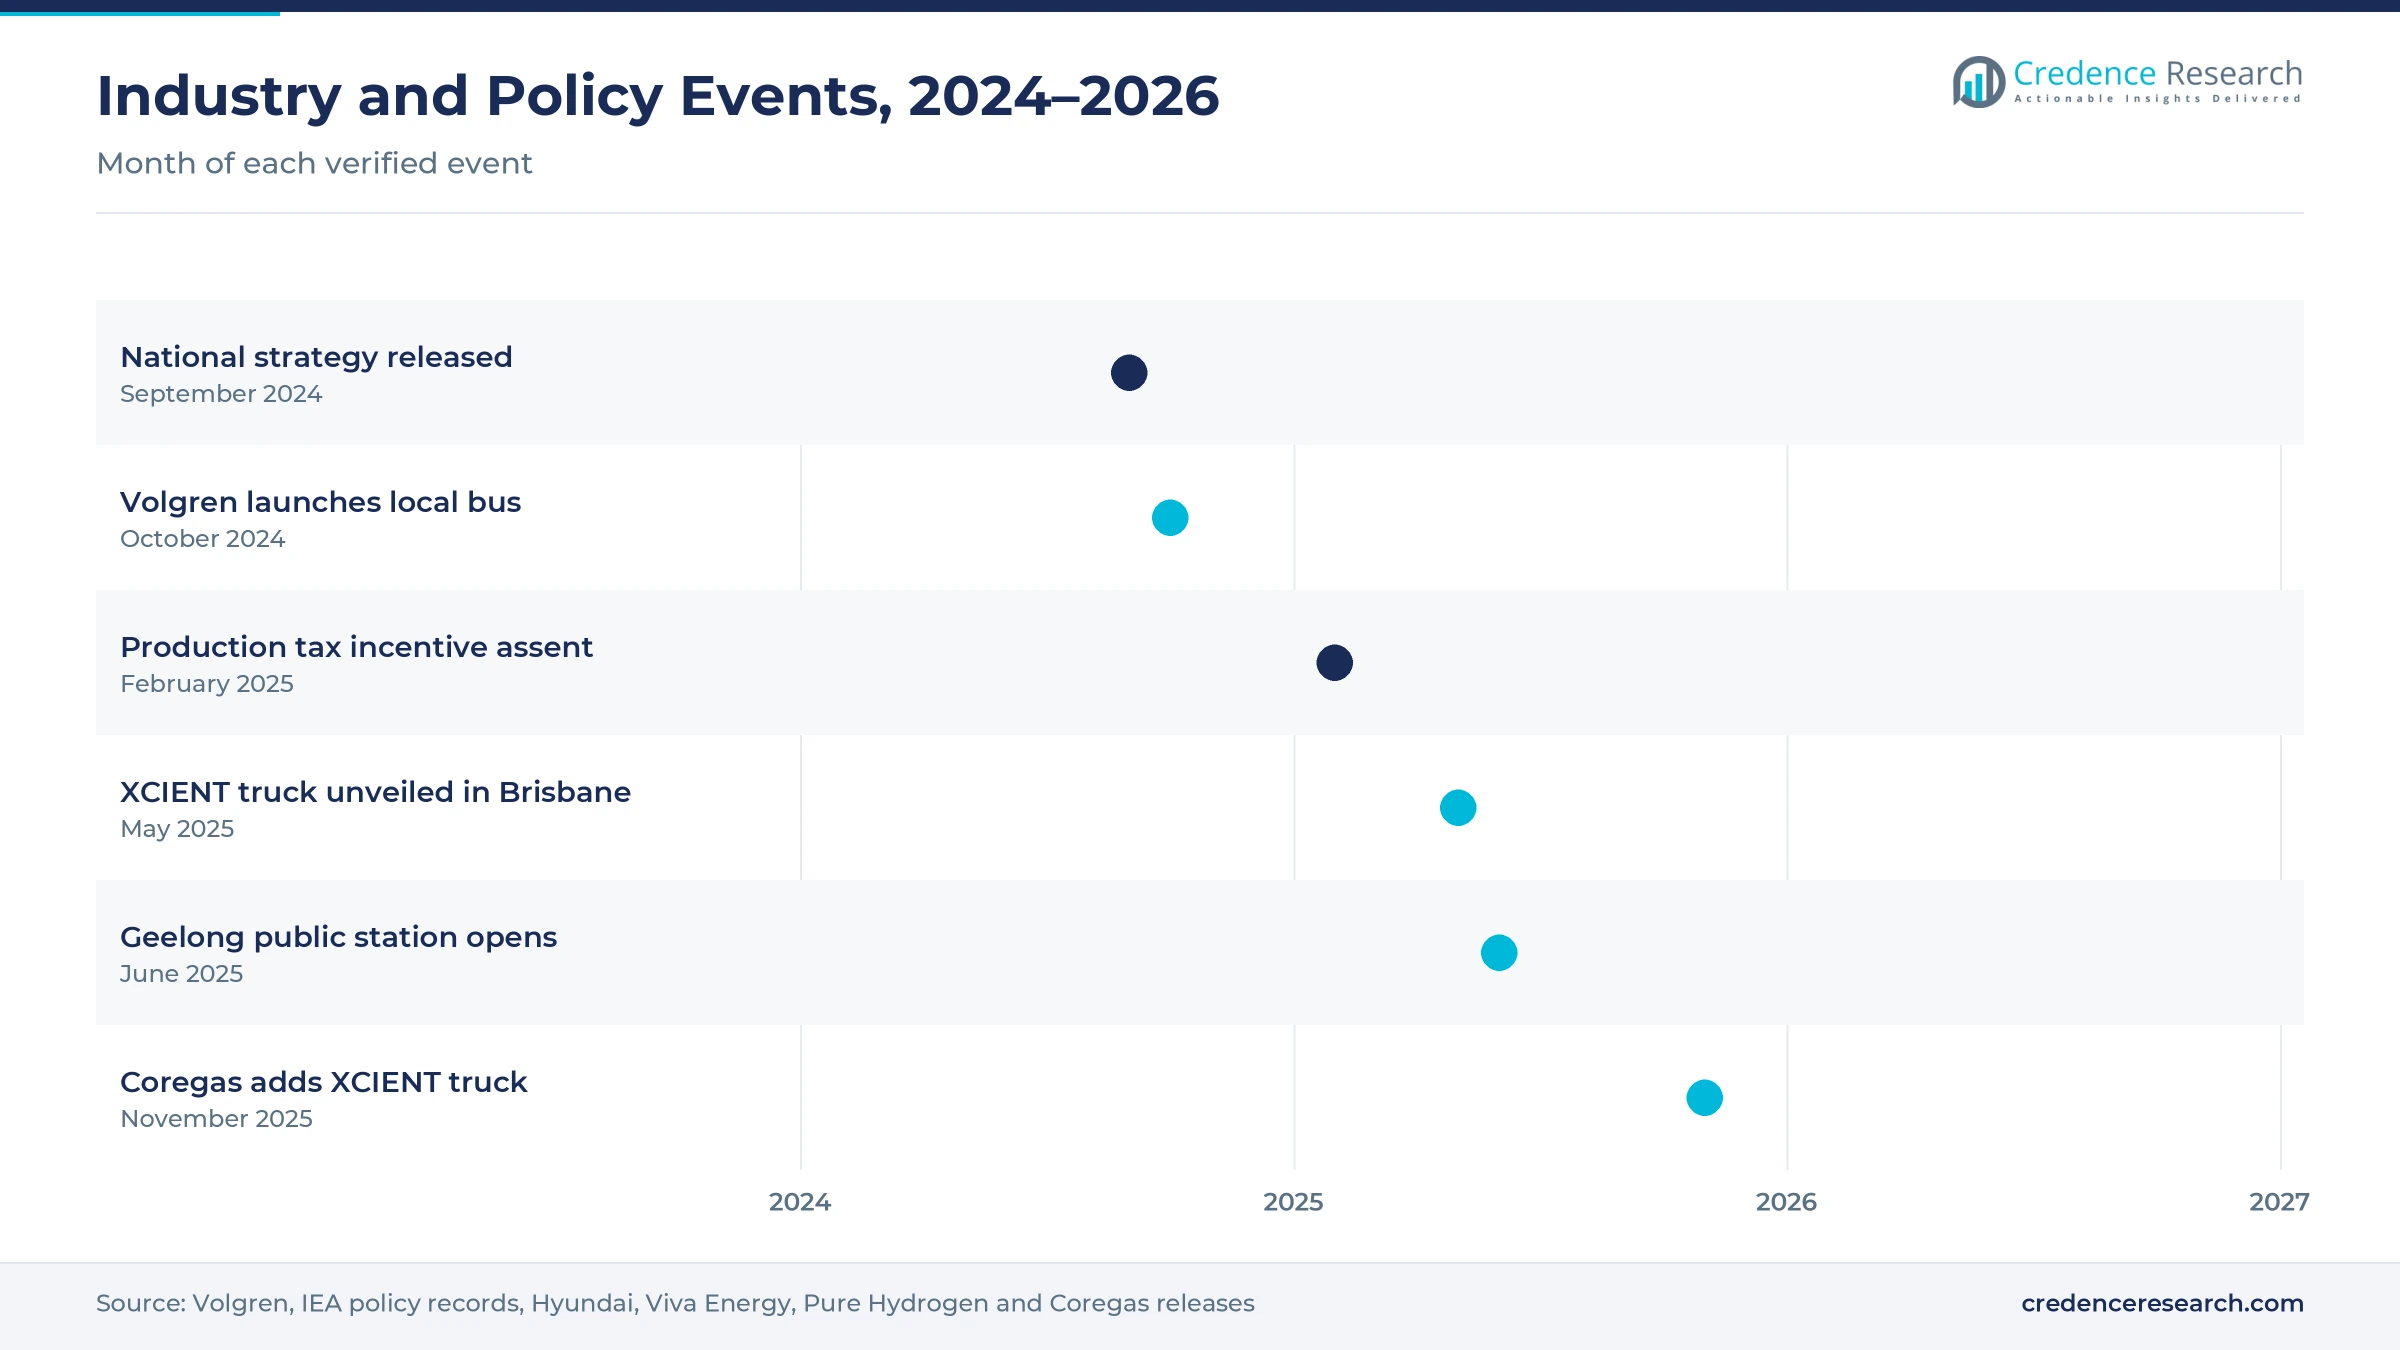
Local integration capability supports fleet orders, because Australian builders can adapt imported stacks to local vehicle rules and duty cycles. Volgren launched its first locally built bus in October 2024 using Wrightbus technology, with a second bus already in production. Pure Hydrogen handed Barwon Water the first fully registered, type-approved prime mover in Australia during fiscal 2025. Heidelberg Materials ordered a 30-ton concrete agitator in March 2025 fitted with a 200 kW Ballard stack and a 58 kWh battery. As a result, vehicle and powertrain supply keeps a 41.0% share of 2025 value, as local builders deliver zero-emission buses and trucks.
Why does federal production support improve fuel economics?
Federal production support improves fuel economics, because cheaper renewable supply narrows the cost gap with diesel. The production tax incentive pays A$2 per kilogram from 2027-28 to 2039-40, and the law received assent on Feb. 14, 2025, according to the International Energy Agency. The national strategy of September 2024 set clean production targets of 0.5 million metric tons a year by 2030 and 15 million metric tons by 2050. Operational clean production capacity reached 697 metric tons a year in December 2024, up more than 52% on 2023, according to Geoscience Australia. In turn, renewable electrolytic supply grows at 26.05% a year.
Shared depots, imported trucks and mine sites widen use
How is the shift to shared refueling hubs changing supply?
The shift to shared refueling hubs is changing supply, because one station can serve several fleets and lower the cost of each kilogram. The Geelong hub opened on June 13, 2025, with a 2.5 MW electrolyzer that can produce 1,000 kg a day. Its fast-fill system can dispense 300 kg in under two hours and refuel at least 10 trucks in a row. Coregas opened its Port Kembla station in 2023 as the first site in Australia built for heavy transport. As a result, refuelling equipment and services gain value, as each new hub needs an electrolyzer, compressors and dispensers.
Why is the rise of imported heavy trucks reshaping trials?
The rise of imported heavy trucks is reshaping trials, because proven models shorten the time fleets need to test zero-emission freight. Hyundai showed its XCIENT truck at the Brisbane Truck Show in May 2025 ahead of fleet trials, according to Hyundai Motor Company Australia. The truck uses 180 kW of stack output, carries 31 kg of fuel in 350-bar storage tanks and refuels in about 8 to 20 minutes. The model has operated in 13 countries and covered more than 100,000 km in New Zealand trials since 2021. In turn, road fleet propulsion holds a 58.0% share of 2025 value, as fleets compare imported trucks on local routes.
Can mine sites open a larger off-road opportunity?
Mine sites open a larger off-road opportunity, because remote operations burn large volumes of diesel and often have space for on-site solar and electrolysis. The Christmas Creek mobility project in Western Australia produces 193 metric tons a year, the largest operating clean production project in the country. Pure Hydrogen signed a dealer agreement in September 2025 covering Western Australia and Queensland, two states with large mining fleets. Western Australia also recorded the fastest state population growth at 2.1% in the year to March 2026, which adds workers and regional freight demand. As a result, off-road vehicle propulsion grows at 25.77% a year, the fastest application rate.
Is there room for light commercial vehicles to scale?
Light commercial vehicles have room to scale, because utility and fleet buyers want long range and quick refueling for regional work. In August 2026, Toyota confirmed its commitment to a hydrogen HiLux by 2028, alongside diesel and battery-electric versions. Its Altona site in Melbourne can produce up to 80 kg of fuel a day with an on-site electrolyzer. Toyota also plans relocatable refuelers with partners such as Viva Energy and Hyundai, which would bring fuel to fleet locations. Viva Energy's Geelong hub already shows the model, refueling at least 10 trucks in a row. In turn, Victoria, home to the Altona site, holds a 23.0% share of 2025 value, and its fleets could move into work vehicles once supply points spread.
Sparse stations, high costs and project delays slow uptake
How does sparse refueling access limit fleet adoption?
Sparse refueling access limits fleet adoption, because operators cannot run vehicles far beyond the few stations that exist. Toyota described public infrastructure as pretty much non-existent in August 2026, with Hyundai's head office station the only site in Sydney. As a result, most fleets stay on short depot routes. Providers respond with relocatable refuelers and shared hubs that serve several operators at once, which spreads station costs across more vehicles.
Why do high vehicle costs depend on grant funding?
High vehicle costs depend on grant funding, because zero-emission heavy vehicles still cost far more than diesel models. Scott Lovatt Transport signed for two prime movers in August 2025, but the sale depends on securing government grants. In turn, order books move with funding rounds rather than steady demand. Suppliers respond with leasing, service bundles and joint ownership that spread capital costs over the full working life of each vehicle.
How does a shrinking project pipeline slow supply growth?
A shrinking project pipeline slows supply growth, because fewer production projects mean fewer low-cost fuel sources for fleets. The number of tracked projects fell from 104 in 2023 to 90 in 2024. As a result, some operators wait for clearer fuel prices before ordering vehicles. Developers respond by tying smaller electrolyzers to specific fleets and backup power users that guarantee demand, which lowers the risk of building supply ahead of vehicles.
Why does battery-electric competition narrow some uses?
Battery-electric competition narrows some uses, because battery trucks and buses now cover many urban routes at lower energy cost. Volgren's zero-emission portfolio of more than 150 buses includes both battery and fuel cell models. In turn, operators choose fuel cells mainly for long routes, heavy loads and remote sites. Suppliers respond by targeting duty cycles where range, payload and refueling time matter most, such as regional freight and mining haulage.
New South Wales leads while Queensland grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Australian Capital Territory | 8.9 | 33.7% | 24.08% |
| Victoria | 6.1 | 23.0% | 24.38% |
| Queensland | 5.0 | 19.0% | 24.98% |
| Western Australia | 4.2 | 16.0% | 24.78% |
| South Australia, Tasmania and Northern Territory | 2.2 | 8.3% | 23.18% |
Why do New South Wales and the ACT hold the largest share?
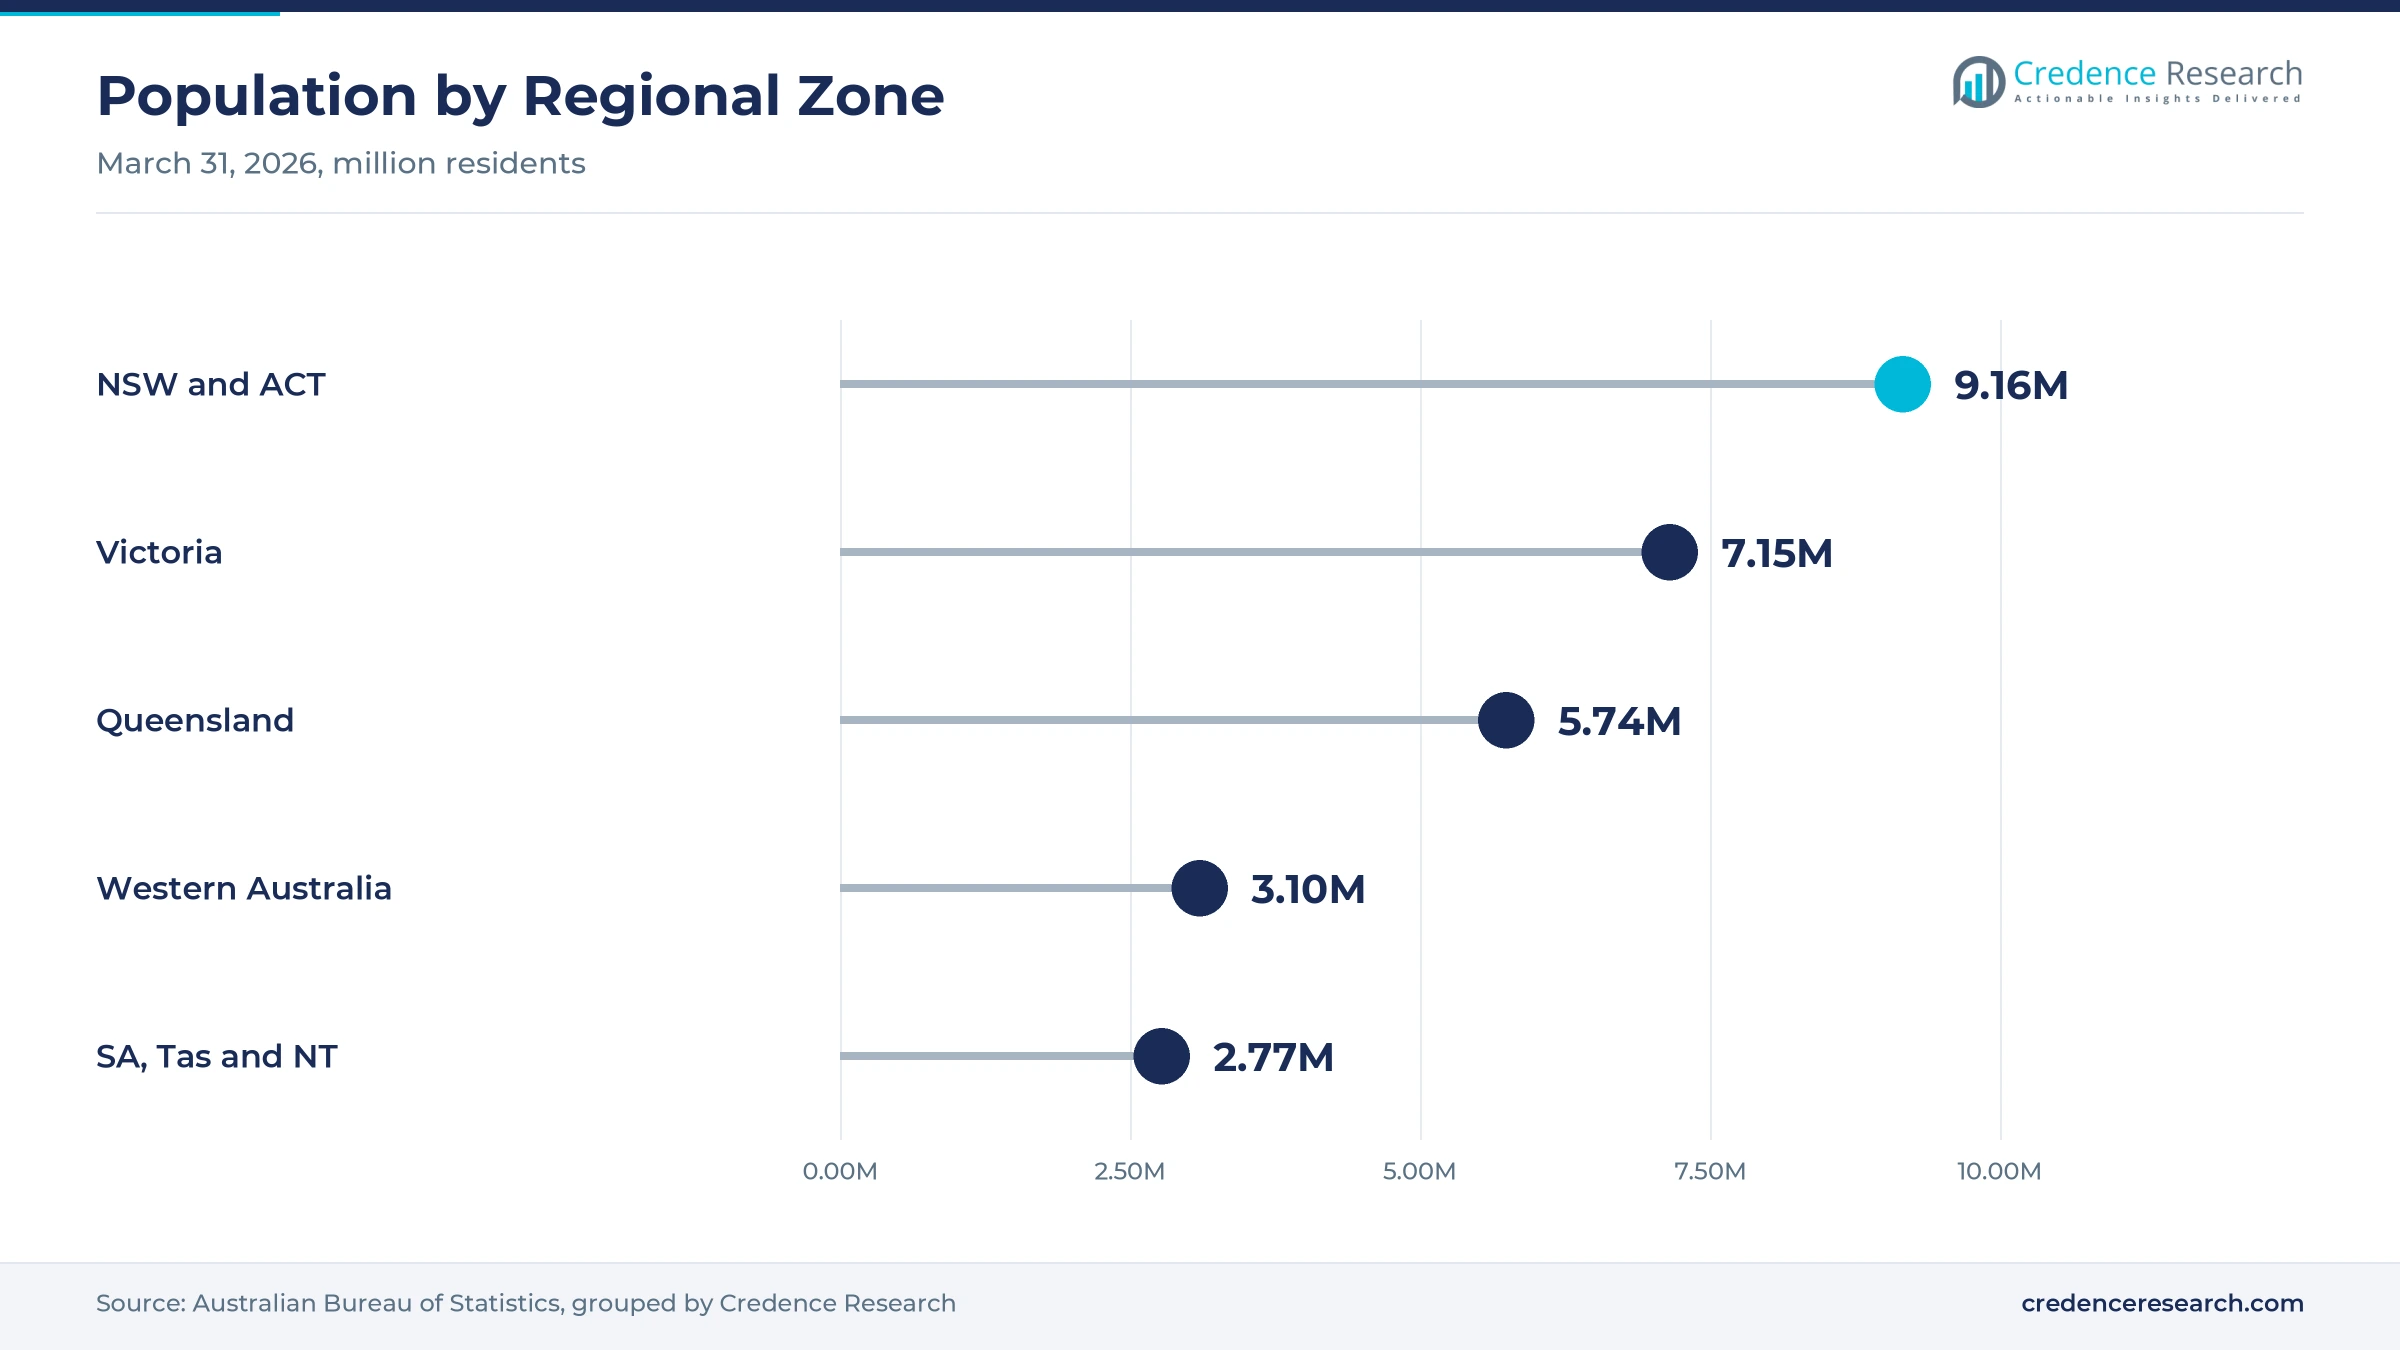
New South Wales and the Australian Capital Territory held a 33.7% share of 2025 value and grow at 24.08% a year, because they host early stations and fleets. Coregas runs a heavy-vehicle station at Port Kembla, while Hyundai operates a station at its Sydney head office. The two jurisdictions had about 9.16 million residents at March 31, 2026, the largest combined population. Scott Lovatt Transport also ordered prime movers in the state in 2025.
How does Victoria anchor depot-based deployments?
Victoria held a 23.0% share of 2025 value and grows at 24.38% a year, because the Geelong hub, the Toyota Altona site and tower backup projects concentrate early deployments. The Geelong station opened in June 2025 to serve Toll, ComfortDelGro, Cleanaway and Barwon Water vehicles. Energys and Telstra also run five backup generators at regional Victorian towers. The state added about 109,500 residents in the year to March 2026.
Why is Queensland the fastest-growing region?
Queensland held a 19.0% share of 2025 value and grows fastest at 24.98% a year, because truck trials, dealer networks and mining fleets expand across the state. Hyundai launched its XCIENT truck in Brisbane in May 2025 ahead of fleet trials. Pure Hydrogen also signed a dealer agreement covering Queensland in September 2025. The state added about 90,100 residents in the year to March 2026, a growth rate of 1.6%.
How does Western Australia build off-road demand?
Western Australia held a 16.0% share of 2025 value and grows at 24.78% a year, because mining operators test zero-emission haulage at remote sites. The Christmas Creek mobility project produces 193 metric tons a year, the largest operating clean production project in Australia. The state also had the fastest population growth at 2.1% in the year to March 2026.
What drives demand in the southern and northern jurisdictions?
South Australia, Tasmania and the Northern Territory held an 8.3% share of 2025 value and grow at 23.18% a year, because waste and municipal fleets lead early use. Pure Hydrogen delivered a rear-loading waste truck in February 2025 for work with the City of West Torrens in Adelaide. These smaller markets depend on single-asset deployments until more stations open.
Station openings, truck debuts and tax credits in 2024-2026
| Development | Status and market relevance |
|---|---|
| In October 2024, Volgren launched its first locally built bus using Wrightbus technology. | Started local assembly of zero-emission buses for Australian operators |
| In February 2025, the production tax incentive law received assent. | Set A$2 per kilogram support for renewable fuel from 2027-28 |
| In May 2025, Hyundai Motor Company Australia unveiled the XCIENT truck at the Brisbane Truck Show. | Began evaluation and fleet trials of the heavy truck in Australia |
| In June 2025, Viva Energy opened a public heavy-vehicle refueling station in Geelong. | Added a 2.5 MW electrolyzer producing up to 1,000 kg a day |
| In November 2025, Coregas added an XCIENT truck to its cylinder delivery fleet. | Moved a heavy truck into daily commercial service in New South Wales |
Electrolysis, 350-bar storage and modular stacks evolve
- On-site electrolysis makes fuel from water and renewable power at the depot, which removes trucked supply and lowers delivered costs over time.
- High-pressure storage holds 31 kg or more on heavy trucks at 350 bar, which gives ranges of up to 400 km on regional routes.
- Hybrid stack and battery systems pair a 200 kW stack with a battery pack, which handles peak loads on agitators and prime movers.
- Relocatable refuelers move fuel to fleet locations on demand, which lets operators start trials before permanent stations open.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Vehicle makers and local integrators compete for fleets
Competition is led by global vehicle makers that import proven models, alongside local integrators that adapt imported stacks to Australian rules and duty cycles. Hyundai Motor Company Australia brought its XCIENT truck to Brisbane in May 2025, and Coregas put one into daily service in November 2025. Toyota Australia runs an electrolyzer at Altona and plans a hydrogen HiLux by 2028. Pure Hydrogen builds prime movers, agitators and waste trucks, several with Ballard stacks, for Toll, Barwon Water, Heidelberg Materials and Solo. Volgren builds buses with Wrightbus technology, while Energys supplies tower backup generators to Telstra. Rivals compete on vehicle range, refueling access, service support, local approvals and the ability to bundle fuel, maintenance and financing for fleet buyers.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Toyota Australia | Vehicle maker | Runs an Altona electrolyzer and plans a hydrogen HiLux |
| Hyundai Motor Company Australia | Vehicle maker | Brought the XCIENT truck to Australia in 2025 |
| Volgren | Bus builder | Launched its first locally built bus in October 2024 |
| Wrightbus | Technology partner | Supplies bus technology to Volgren in Australia |
| Pure Hydrogen Corporation | Vehicle integrator | Delivers prime movers, agitators and waste trucks |
| Ballard Power Systems | Stack supplier | Supplies 200 kW stacks for Pure Hydrogen agitators |
| Energys Australia | Stationary systems maker | Supplies backup generators for Telstra towers |
Credence Research view on Australian zero-emission fleets
Credence Research's view is that Australian zero-emission fleet value will grow quickly from a small base because depot-based fleets, tower backup and mining trials keep adding assets. Vehicle supply remains the largest part of the market, while fuel sales gain share as fleets scale up. Production tax credits from 2027-28 should lower fuel costs, although sparse stations and grant-dependent orders slow uptake. Suppliers that bundle vehicles, fuel and service around shared hubs should gain share fastest.
How the Australian deployment value estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines government energy resource data, international policy records, population statistics, company releases on vehicle orders and station openings, and trade press on fleet trials. Segment splits and regional growth rates are Credence Research estimates, while regional shares follow the client-defined split. Sources used are public reports, official statistics, company releases and trade press, and no interviews or surveys were used.
Fleet scale-up and tax credits carry growth to 2035
Deployment value is expected to reach USD 230.3 million by 2035, a 24.37% CAGR during 2026–2035, as fleets, miners and tower operators add zero-emission assets. Growth should stay strong through 2028 while depot hubs open and production tax credits begin. After that, fuel sales, off-road equipment and light commercial vehicles will carry more growth as supply points spread. Slower station building would delay orders, while cheaper renewable fuel would speed them. Suppliers with shared hubs and service networks are expected to gain the most.
Frequently Asked Questions
How big is the Australia hydrogen mobility and fuel cells market?
Which value chain stage leads Australian deployment value?
Which region leads the Australia hydrogen mobility and fuel cells market?
When did the Geelong refueling station open?
What federal support exists for renewable fuel production?
Which application is growing fastest?
Who are the leading companies in Australian zero-emission fleets?
What are the main challenges for fleet adoption?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Value Chain Stage
- 1.2.1 Vehicle and Powertrain Supply
- 1.2.2 Stationary System Supply
- 1.2.3 Refuelling Equipment and Services
- 1.2.4 Transport Hydrogen Sales
- 1.2.5 Engineering and Commercial Development
- 1.3 By Application
- 1.3.1 Road Fleet Propulsion
- 1.3.2 Off-Road Vehicle Propulsion
- 1.3.3 Stationary Backup Power
- 1.3.4 Portable Prime Power
- 1.4 By End User
- 1.4.1 Freight Fleet Operators
- 1.4.2 Passenger Transport Operators
- 1.4.3 Mining and Construction Operators
- 1.4.4 Telecommunications Operators
- 1.4.5 Government and Research Fleets
- 1.5 By Energy Source
- 1.5.1 Renewable Electrolytic Hydrogen
- 1.5.2 Fossil-Derived Hydrogen With Carbon Capture
- 1.5.3 Unabated Fossil-Derived Hydrogen
- 1.5.4 Mixed-Origin Merchant Hydrogen
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 26.5 million → 2035: USD 230.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Hydrogen Mobility and Fuel Cells Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Hydrogen Mobility and Fuel Cells Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Hydrogen Mobility and Fuel Cells Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Hydrogen Mobility and Fuel Cells Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Hydrogen Mobility and Fuel Cells Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Hydrogen Mobility and Fuel Cells Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Hydrogen Mobility and Fuel Cells Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Hydrogen Mobility and Fuel Cells Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 26.5 million → 2035: USD 230.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Hydrogen Mobility and Fuel Cells Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Value Chain Stage - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Vehicle and Powertrain Supply
- 12.3.7.2 Stationary System Supply
- 12.3.7.3 Refuelling Equipment and Services
- 12.3.7.4 Transport Hydrogen Sales
- 12.3.7.5 Engineering and Commercial Development
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Road Fleet Propulsion
- 12.4.7.2 Off-Road Vehicle Propulsion
- 12.4.7.3 Stationary Backup Power
- 12.4.7.4 Portable Prime Power
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Freight Fleet Operators
- 12.5.7.2 Passenger Transport Operators
- 12.5.7.3 Mining and Construction Operators
- 12.5.7.4 Telecommunications Operators
- 12.5.7.5 Government and Research Fleets
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Energy Source - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Renewable Electrolytic Hydrogen
- 12.6.7.2 Fossil-Derived Hydrogen With Carbon Capture
- 12.6.7.3 Unabated Fossil-Derived Hydrogen
- 12.6.7.4 Mixed-Origin Merchant Hydrogen
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Hydrogen Mobility and Fuel Cells End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Hydrogen Mobility and Fuel Cells Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Hydrogen Mobility and Fuel Cells Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Hydrogen Mobility and Fuel Cells Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Toyota Australia
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Hyundai Motor Company Australia
- 18.4 Panasonic
- 18.5 Volgren
- 18.6 Ballard Power Systems
- 18.7 Wrightbus
- 18.8 Pure Hydrogen Corporation
- 18.9 Energys Australia
- 18.10 H2X Global
- 18.11 Siltrax
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

