
Severe underarm sweating anchors funded specialist care
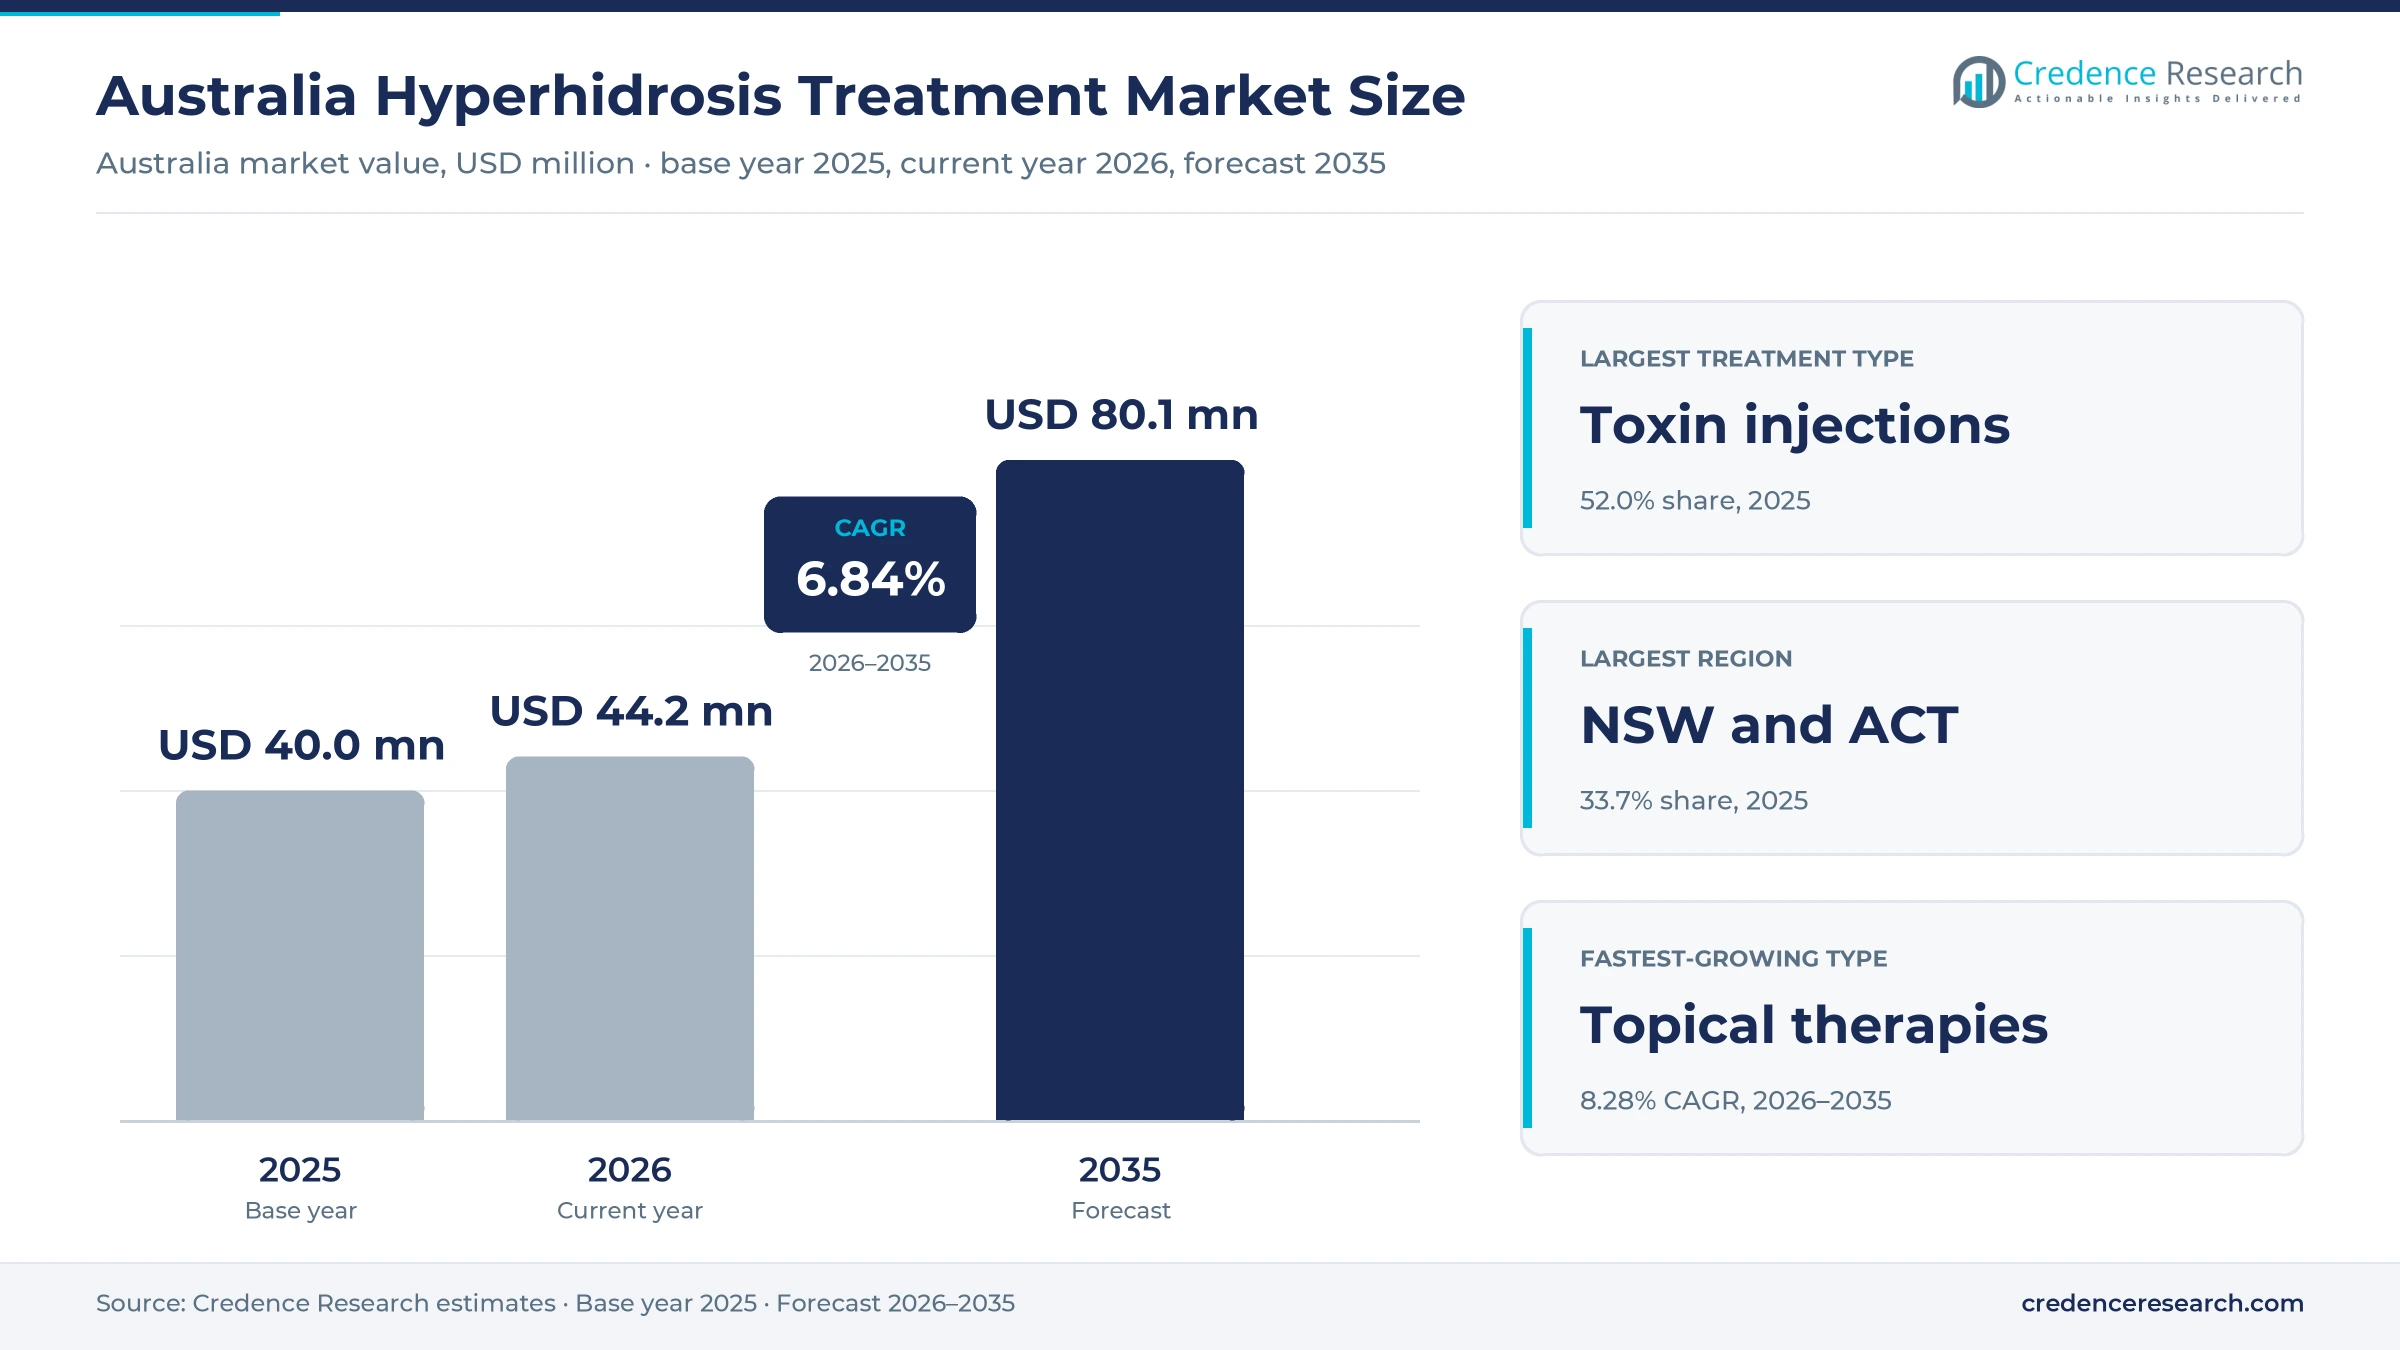
The Australia hyperhidrosis treatment market was valued at USD 40.0 million in 2025 and is projected to increase from USD 44.2 million in 2026 to USD 80.1 million by 2035, registering a CAGR of 6.84% during 2026–2035. Demand comes from dermatologists, neurologists, general practitioners and cosmetic clinics that treat severe underarm, palm, foot and facial sweating with botulinum toxin, prescription creams, tablets and energy-based devices. New South Wales and Australian Capital Territory held the largest regional share, 33.7% in 2025, because Sydney and Canberra hold the largest population and the densest specialist networks. Queensland is the fastest-growing region at 7.05% a year, as population growth and a warm climate raise treatment volumes. Most medicines and devices are imported and supplied by global sponsors through local subsidiaries. A glycopyrronium cream for severe underarm sweating joined the Pharmaceutical Benefits Scheme on May 1, 2026, which gives patients a subsidized option before injections.
Which sweating therapies and services does the estimate cover?
The estimate measures the value of botulinum toxin injections, topical therapies, oral medications and device and surgical interventions used to treat primary and secondary hyperhidrosis in Australia. It covers medicine costs, procedure fees and device-based sessions paid through the Pharmaceutical Benefits Scheme, Medicare or private funds. Values are measured at the point of sale to the patient or the funder.
The estimate excludes ordinary deodorants, cosmetic toxin use for wrinkles and general consultation fees that are not tied to sweating care. The value chain runs from global drug and device makers and their Australian sponsors through wholesalers and community pharmacies to dermatology, neurology and cosmetic clinics and the patients who apply creams at home.
Australia Hyperhidrosis Treatment Market Insights
- The Australia hyperhidrosis treatment market was valued at USD 40.0 million in 2025 and is projected to reach USD 80.1 million by 2035, registering a CAGR of 6.84% during 2026–2035.
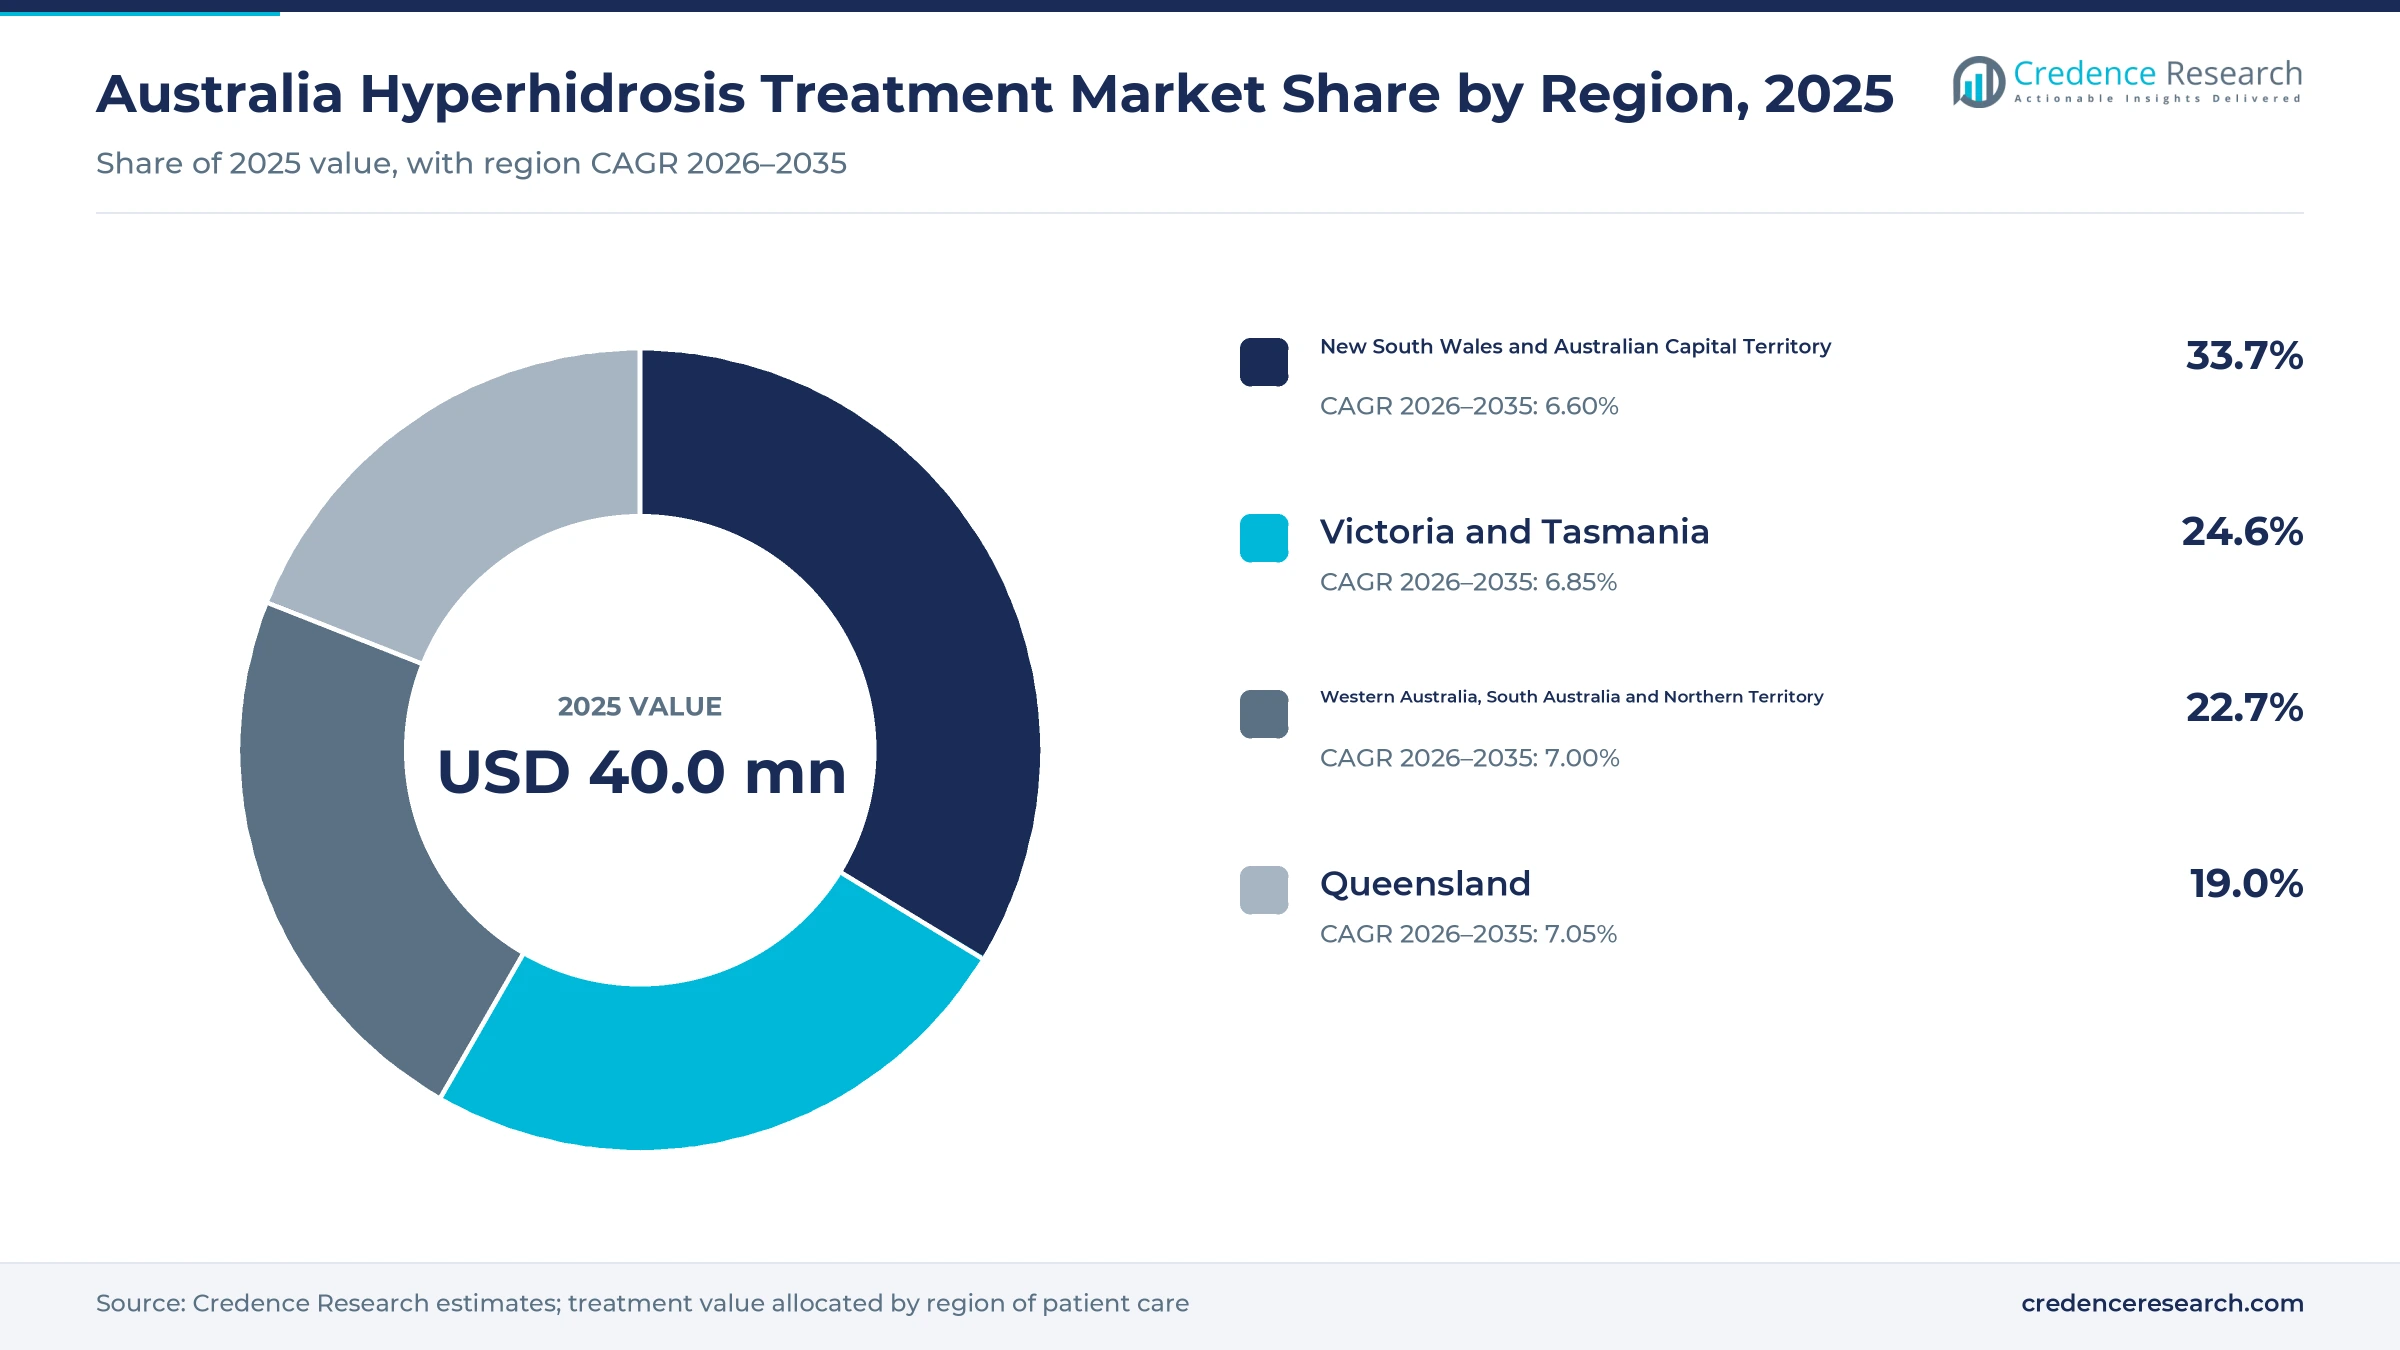
- New South Wales and Australian Capital Territory held a 33.7% share of 2025 value, because Sydney has the largest specialist network.
- Botulinum toxin injections led treatment demand with a 52.0% share of 2025 value, because they remain the main funded option for severe cases.
- The Pharmaceutical Benefits Scheme recorded 18,778 services for Botox in severe underarm sweating during 2024, which shows a large base of repeat patients.
- A glycopyrronium cream sponsored by Actor Pharmaceuticals was first listed on the Pharmaceutical Benefits Scheme on May 1, 2026, after a November 2025 recommendation.
Toxin injections lead while prescription creams grow fastest
Why do toxin injections lead the treatment mix?
Based on treatment type, the market is categorized into botulinum toxin injections, topical therapies, oral medications and device and surgical interventions. Botulinum toxin injections led with a 52.0% share of 2025 value, because repeat injections at least four months apart are funded for severe underarm sweating. Topical therapies grow fastest at 8.28% a year, as a subsidized glycopyrronium cream now sits before injections in care.
How does underarm sweating shape treatment spending?
Based on application, the market is categorized into axillary hyperhidrosis, palmar hyperhidrosis, plantar hyperhidrosis and craniofacial and generalised hyperhidrosis. Axillary hyperhidrosis led with a 62.0% share of 2025 value, because public funding for toxin and the new cream covers only underarm sweating. Axillary hyperhidrosis also grows fastest at 7.00% a year, as more severe cases reach funded care.
Why does private payment still dominate funding?
Based on funding source, the market is categorized into PBS-supported medicines, Medicare-supported services and private-funded care. Private-funded care led with a 75.0% share of 2025 value, because palm, foot and facial sweating, devices and many clinic visits fall outside public funding. PBS-supported medicines grow fastest at 8.62% a year, as the listed cream adds subsidized scripts from 2026.
How do pharmacies gain share from clinics?
Based on distribution channel, the market is categorized into community pharmacy, professional providers and direct device supply. Professional providers led with a 55.0% share of 2025 value, because injections and energy-based procedures happen in specialist and cosmetic clinics. Community pharmacy grows fastest at 7.69% a year, as patients fill cream scripts and buy aluminum antiperspirants at retail pharmacy counters.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Treatment Type | Botulinum toxin injections | 52.0% | Topical therapies | 8.28% |
| By Application | Axillary hyperhidrosis | 62.0% | Axillary hyperhidrosis | 7.00% |
| By Funding Source | Private-funded care | 75.0% | PBS-supported medicines | 8.62% |
| By Distribution Channel | Professional providers | 55.0% | Community pharmacy | 7.69% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Population growth, a PBS cream and repeat care lift use
How does population growth widen the treatment funnel?
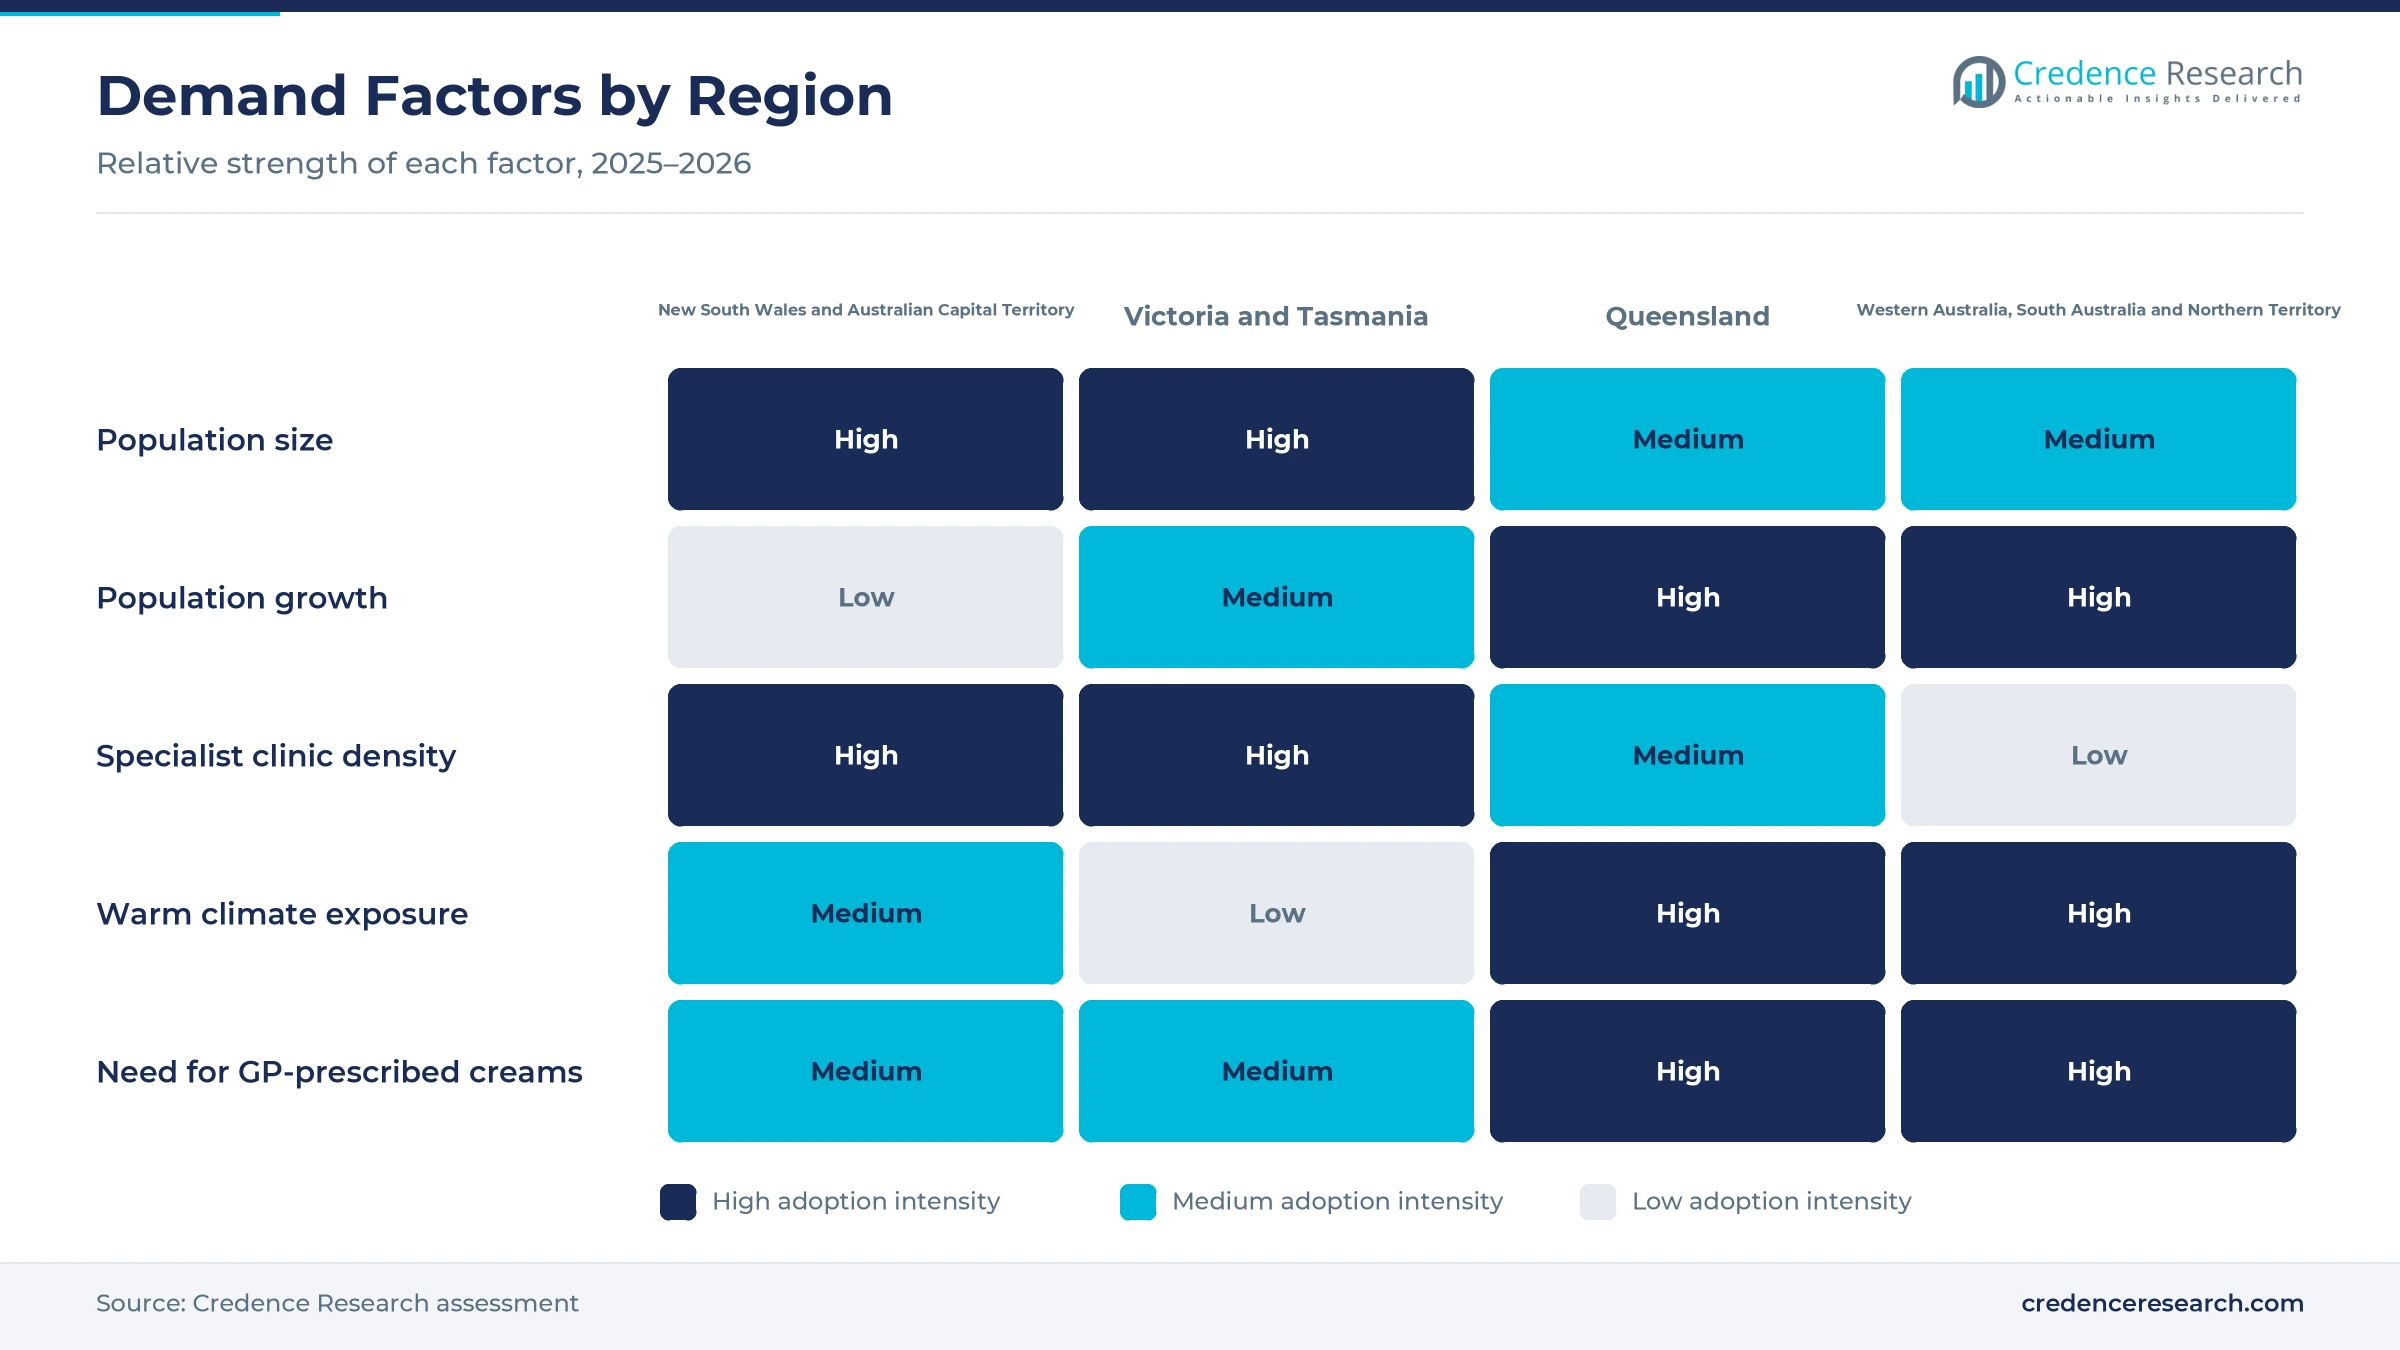
Each year adds more teenagers and adults who may develop severe sweating, which steadily widens the pool of people who could seek care. Australia had about 27.9 million residents at March 31, 2026, up 1.4% in a year, according to the Australian Bureau of Statistics. Net overseas migration added 292,100 people in that year, while natural increase added 100,600, which keeps the young adult base growing. Primary underarm sweating affects about 4.8% of adults, or roughly 1.27 million Australians, according to prevalence data cited by the Pharmaceutical Benefits Advisory Committee. Around 33.8% of those cases are severe, which defines the pool eligible for funded care. As a result, axillary hyperhidrosis holds a 62.0% share of 2025 value.
Why does a funded prescription cream broaden access?
Patients can now start a subsidized cream before they need a specialist injection, which lowers the first barrier to medical care. The Pharmaceutical Benefits Advisory Committee recommended glycopyrronium bromide cream for severe primary axillary hyperhidrosis in November 2025, according to its public summary document. The committee placed the cream after aluminum antiperspirants fail and likely before toxin injections. Actor Pharmaceuticals then launched the cream on the scheme, where it was first listed on May 1, 2026, with a dispensed price of $156.24 per pack and two repeats. The sponsor's submission forecast 50,000 to 60,000 scripts in each of the first two years, although the committee judged script numbers for newly treated patients uncertain and potentially overestimated. In turn, topical therapies grow at 8.28% a year, the fastest treatment rate.
How do existing injection pathways support repeat care?
Toxin injections wear off after several months, so patients already in specialist care return several times a year for further sessions. The scheme recorded 18,778 services for Botox in severe underarm sweating during 2024, under an authority listing limited to dermatologists, neurologists and pediatricians. Medicare item 18362 pays a schedule fee of $295.30 for each injection session, according to the Medicare Benefits Schedule. The item allows up to three treatments in 12 months, with at least four months between sessions, for patients aged 12 and over. As a result, botulinum toxin injections keep a 52.0% share of 2025 value, and professional providers lead distribution with 55.0% of value.
Why do private procedures extend care beyond funded criteria?
Public support covers only severe underarm cases that failed aluminum antiperspirants, so many patients pay for clinic care themselves. Brisbane dermatology practice Cutis explains that some sweating options are not covered by Medicare and are quoted privately at consultation. Melbourne practice Laser Dermatology offers miraDry, an underarm device it describes as approved by the Therapeutic Goods Administration and not covered by Medicare. Out-of-pocket payments made up 15.85% of Australian health spending in 2023, according to World Bank data, which shows that households already fund a large part of care. In turn, private-funded care holds a 75.0% share of 2025 value.
Registered creams and new patient groups reshape demand
How is the shift to registered creams changing practice?
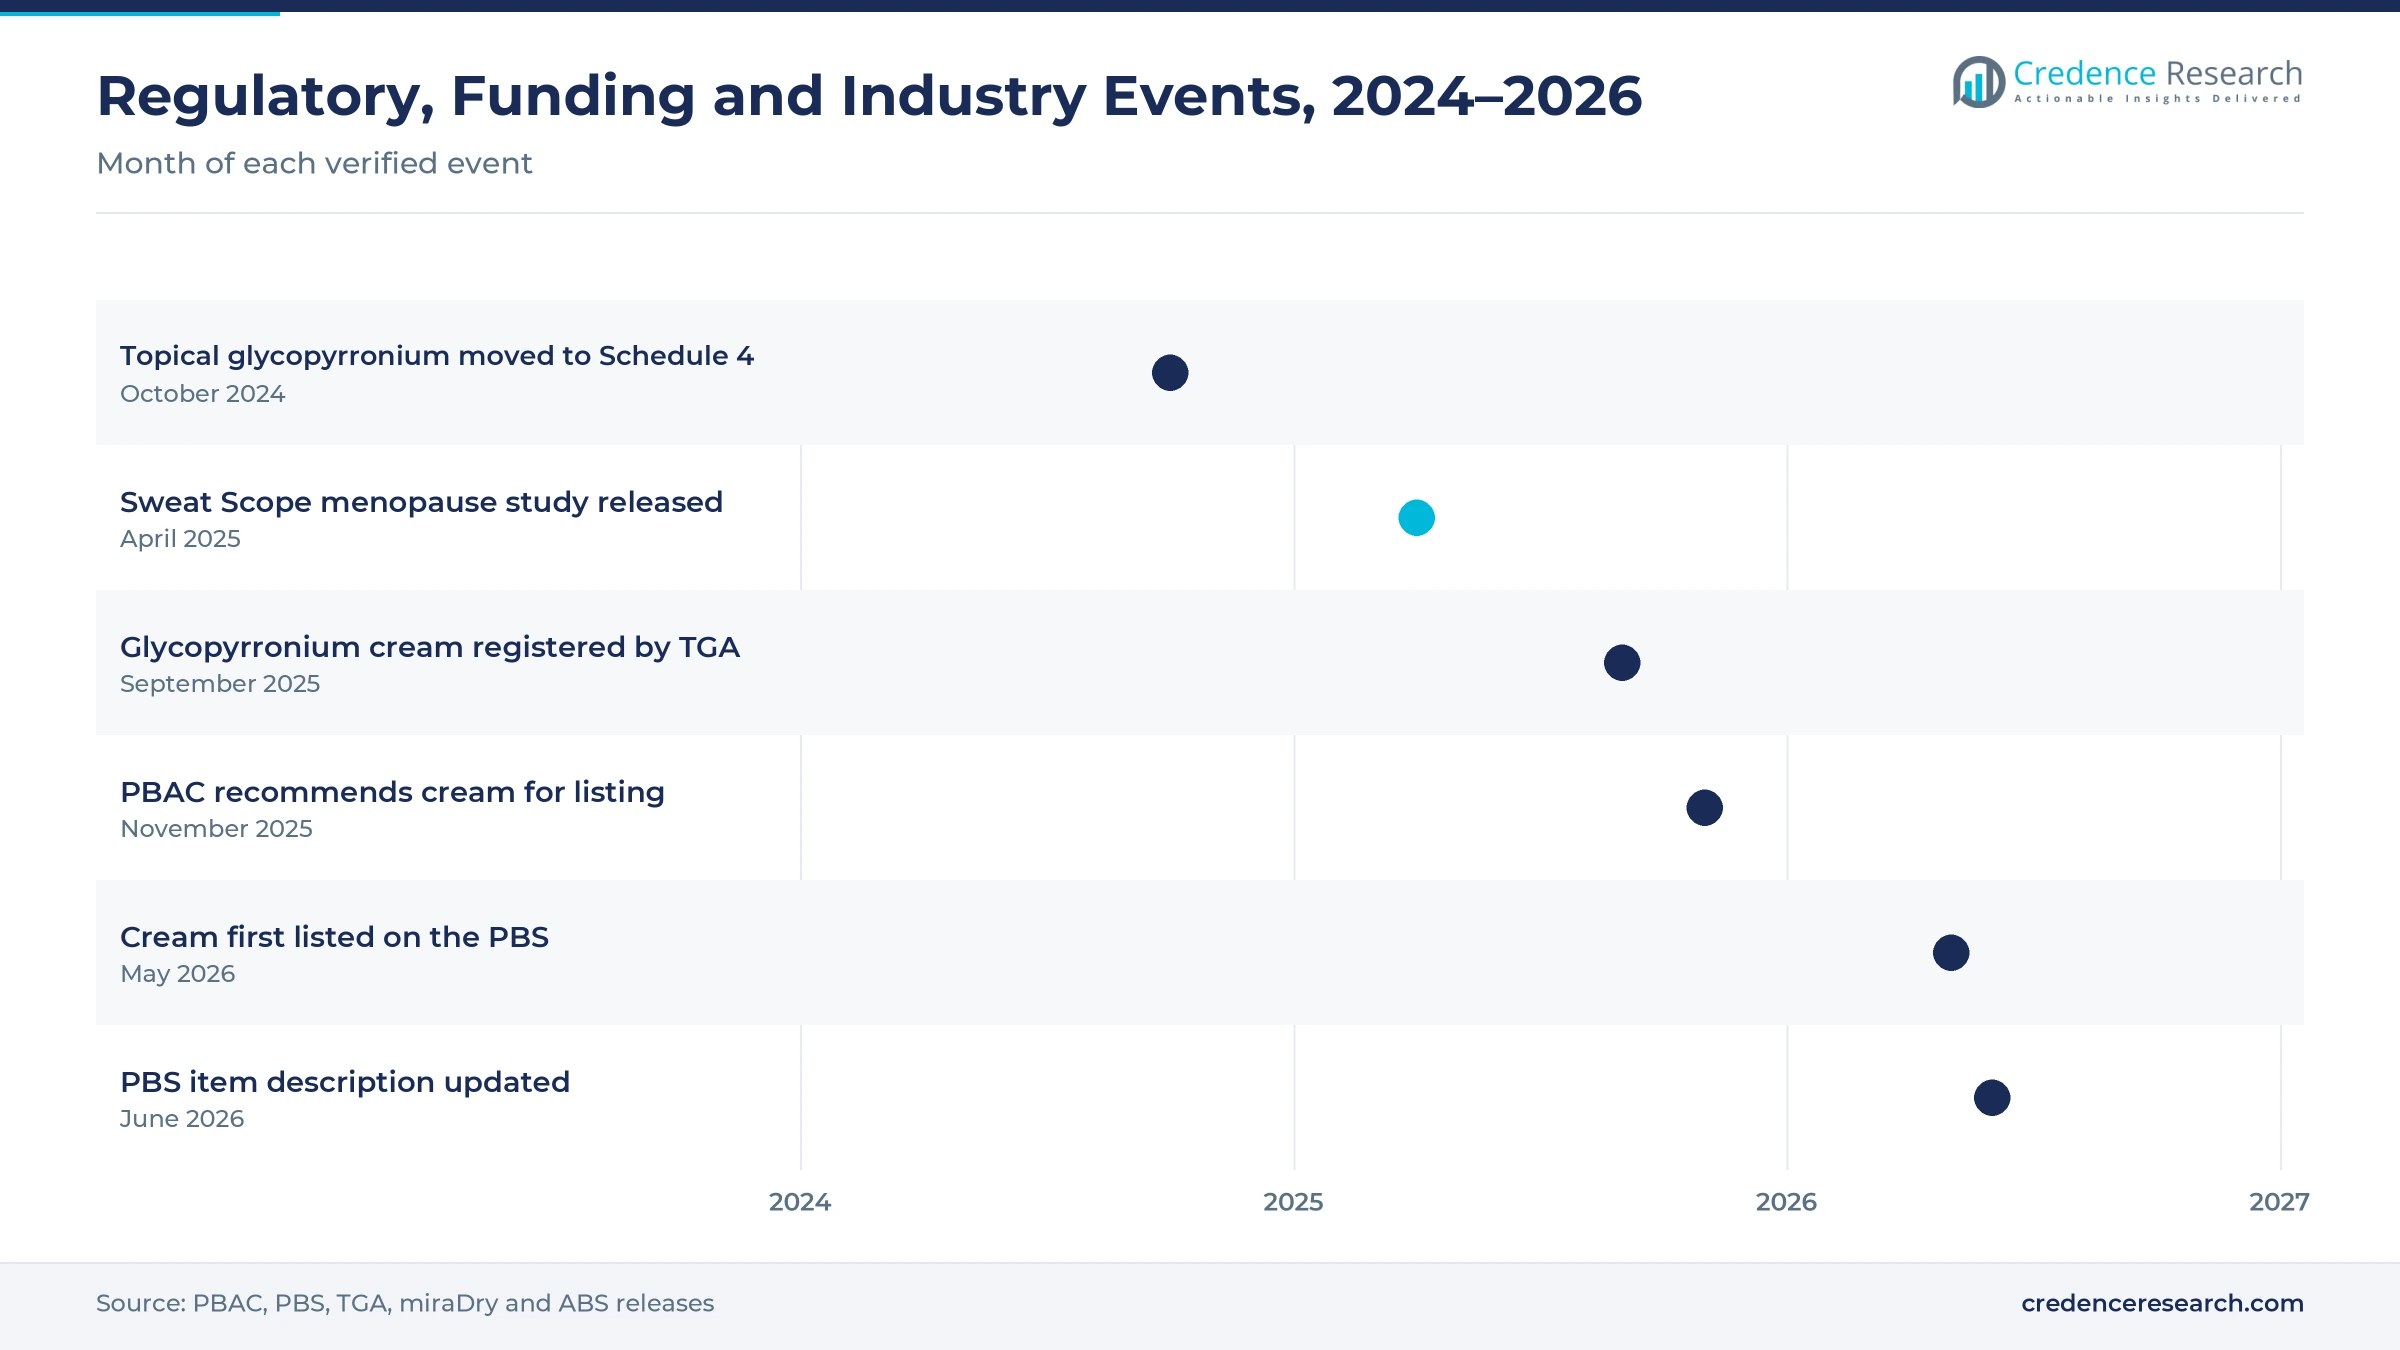
Doctors now have an approved glycopyrronium product with fixed quality and dosing, which is replacing pharmacy-compounded preparations. Topical glycopyrronium moved to Schedule 4, which makes it prescription-only, from Oct. 1, 2024, according to the committee summary. The Therapeutic Goods Administration registered the cream for severe underarm sweating in adults on Sept. 9, 2025, and Actor Pharmaceuticals introduced it to subsidized care in May 2026. The Australasian College of Dermatologists supported listing, noting that a ready-made cream removes the need for compounded products. In a four-week trial, 57.5% of patients on the cream reached at least a 50% cut in sweat output, compared with 34.5% on placebo. As a result, PBS-supported medicines grow at 8.62% a year, the fastest funding rate.
Why are menopausal women and teenagers emerging as patient groups?
Women in midlife and teenagers are emerging as distinct patient groups, because both often live with heavy sweating without care. A Sweat Scope study announced by miraDry, Inc. with the International Hyperhidrosis Society on April 2, 2025, reported that up to 70% of women notice more underarm sweat and odor near menopause. The committee also noted that its age assumption should reflect 85% of patients aged 12 and over, rather than adults alone. Sponsor evidence described bullying and school difficulties among young patients with severe sweating. In turn, clinics that treat women in midlife and adolescents can add new patients to underarm care, the largest application area.
Can general practice prescribing open regional demand?
The new cream can be prescribed by any medical practitioner, while toxin injections need a specialist, which opens demand outside capital cities. The scheme opened the listing in May 2026 to medical practitioners, although nurse practitioners cannot prescribe it. The committee noted access challenges for patients in regional and rural areas, as well as prohibitive out-of-pocket costs for injections. Western Australia grew 2.1% in the year to March 2026, the fastest of any state, while Queensland grew 1.6%, according to the statistics bureau. These states also have large regional populations that live far from dermatologists. As a result, Queensland is the fastest-growing region, and community pharmacy grows at 7.69% a year as scripts reach local stores.
Is there room for growth in non-underarm sweating care?
Palm, foot and facial cases sit outside current public funding, which leaves a large private opening for clinics. All 18,778 subsidized Botox services in 2024 were for underarm sweating, because the listing covers no other body site. The Botox listing and the new cream both carry restrictions for severe primary axillary hyperhidrosis only, so palmar and plantar patients pay privately. Medicare item 18362 likewise pays its $295.30 fee only for underarm injections. Cutis lists separate pages for facial sweating, tablets and antiperspirants, which shows how clinics build programs for each body site. Sydney North Neurology & Neurophysiology in Naremburn also lists focal and generalised hyperhidrosis among the conditions it treats. In turn, clinics that combine botulinum toxin, tablets and device treatments for palms, feet and face can win private patients outside funded criteria.
Strict criteria, costs and rural access limit uptake
How do strict funding criteria limit treated patients?
Subsidized injections need specialist confirmation of severe disease and failure of aluminum antiperspirants, which excludes many people from funded care. Patients with milder or non-underarm sweating must pay the full cost themselves. As a result, many people keep using shop antiperspirants and never reach medical care. Sponsors and clinics respond with patient education, severity scales and referral pathways that help general practitioners identify eligible cases.
Why do out-of-pocket costs deter repeat injections?
Specialist consultation, toxin and injection fees often exceed Medicare benefits, which leaves a gap payment at each session. Patients who need two or three sessions a year face a large gap payment each time. In turn, some patients stop treatment once the first effect fades. Clinics respond with bulk-billing for eligible cases, clear quotes and treatment plans that combine creams with less frequent injections.
How does specialist distance slow rural uptake?
Funded toxin injections for severe sweating must be given by a dermatologist, neurologist or pediatrician, and few practice outside large cities. Many regional patients live hours from the nearest specialist clinic. As a result, waiting times and travel costs delay care for people outside capital cities. Health services and sponsors respond with telehealth reviews, outreach clinics and wider use of creams that general practitioners can prescribe.
Why do side effects and price pressure test new creams?
Anticholinergic medicines carry safety signals that doctors must monitor, and funders push hard on the price of new products. The FDA adverse event system recorded 735 events for glycopyrronium tosylate from 2018 to 2024, 77 of them severe, the committee summary noted. The committee also judged the first requested price unacceptably high and asked for a lower price with a risk-sharing arrangement. In turn, the sponsor must balance price, supply and safety follow-up. Doctors respond by starting with short trials and reviewing patients after several weeks.
Sydney and Canberra lead while Queensland grows fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales and Australian Capital Territory | 13.5 | 33.7% | 6.60% |
| Victoria and Tasmania | 9.8 | 24.6% | 6.85% |
| Western Australia, South Australia and Northern Territory | 9.1 | 22.7% | 7.00% |
| Queensland | 7.6 | 19.0% | 7.05% |
Why does New South Wales lead with the capital territory?
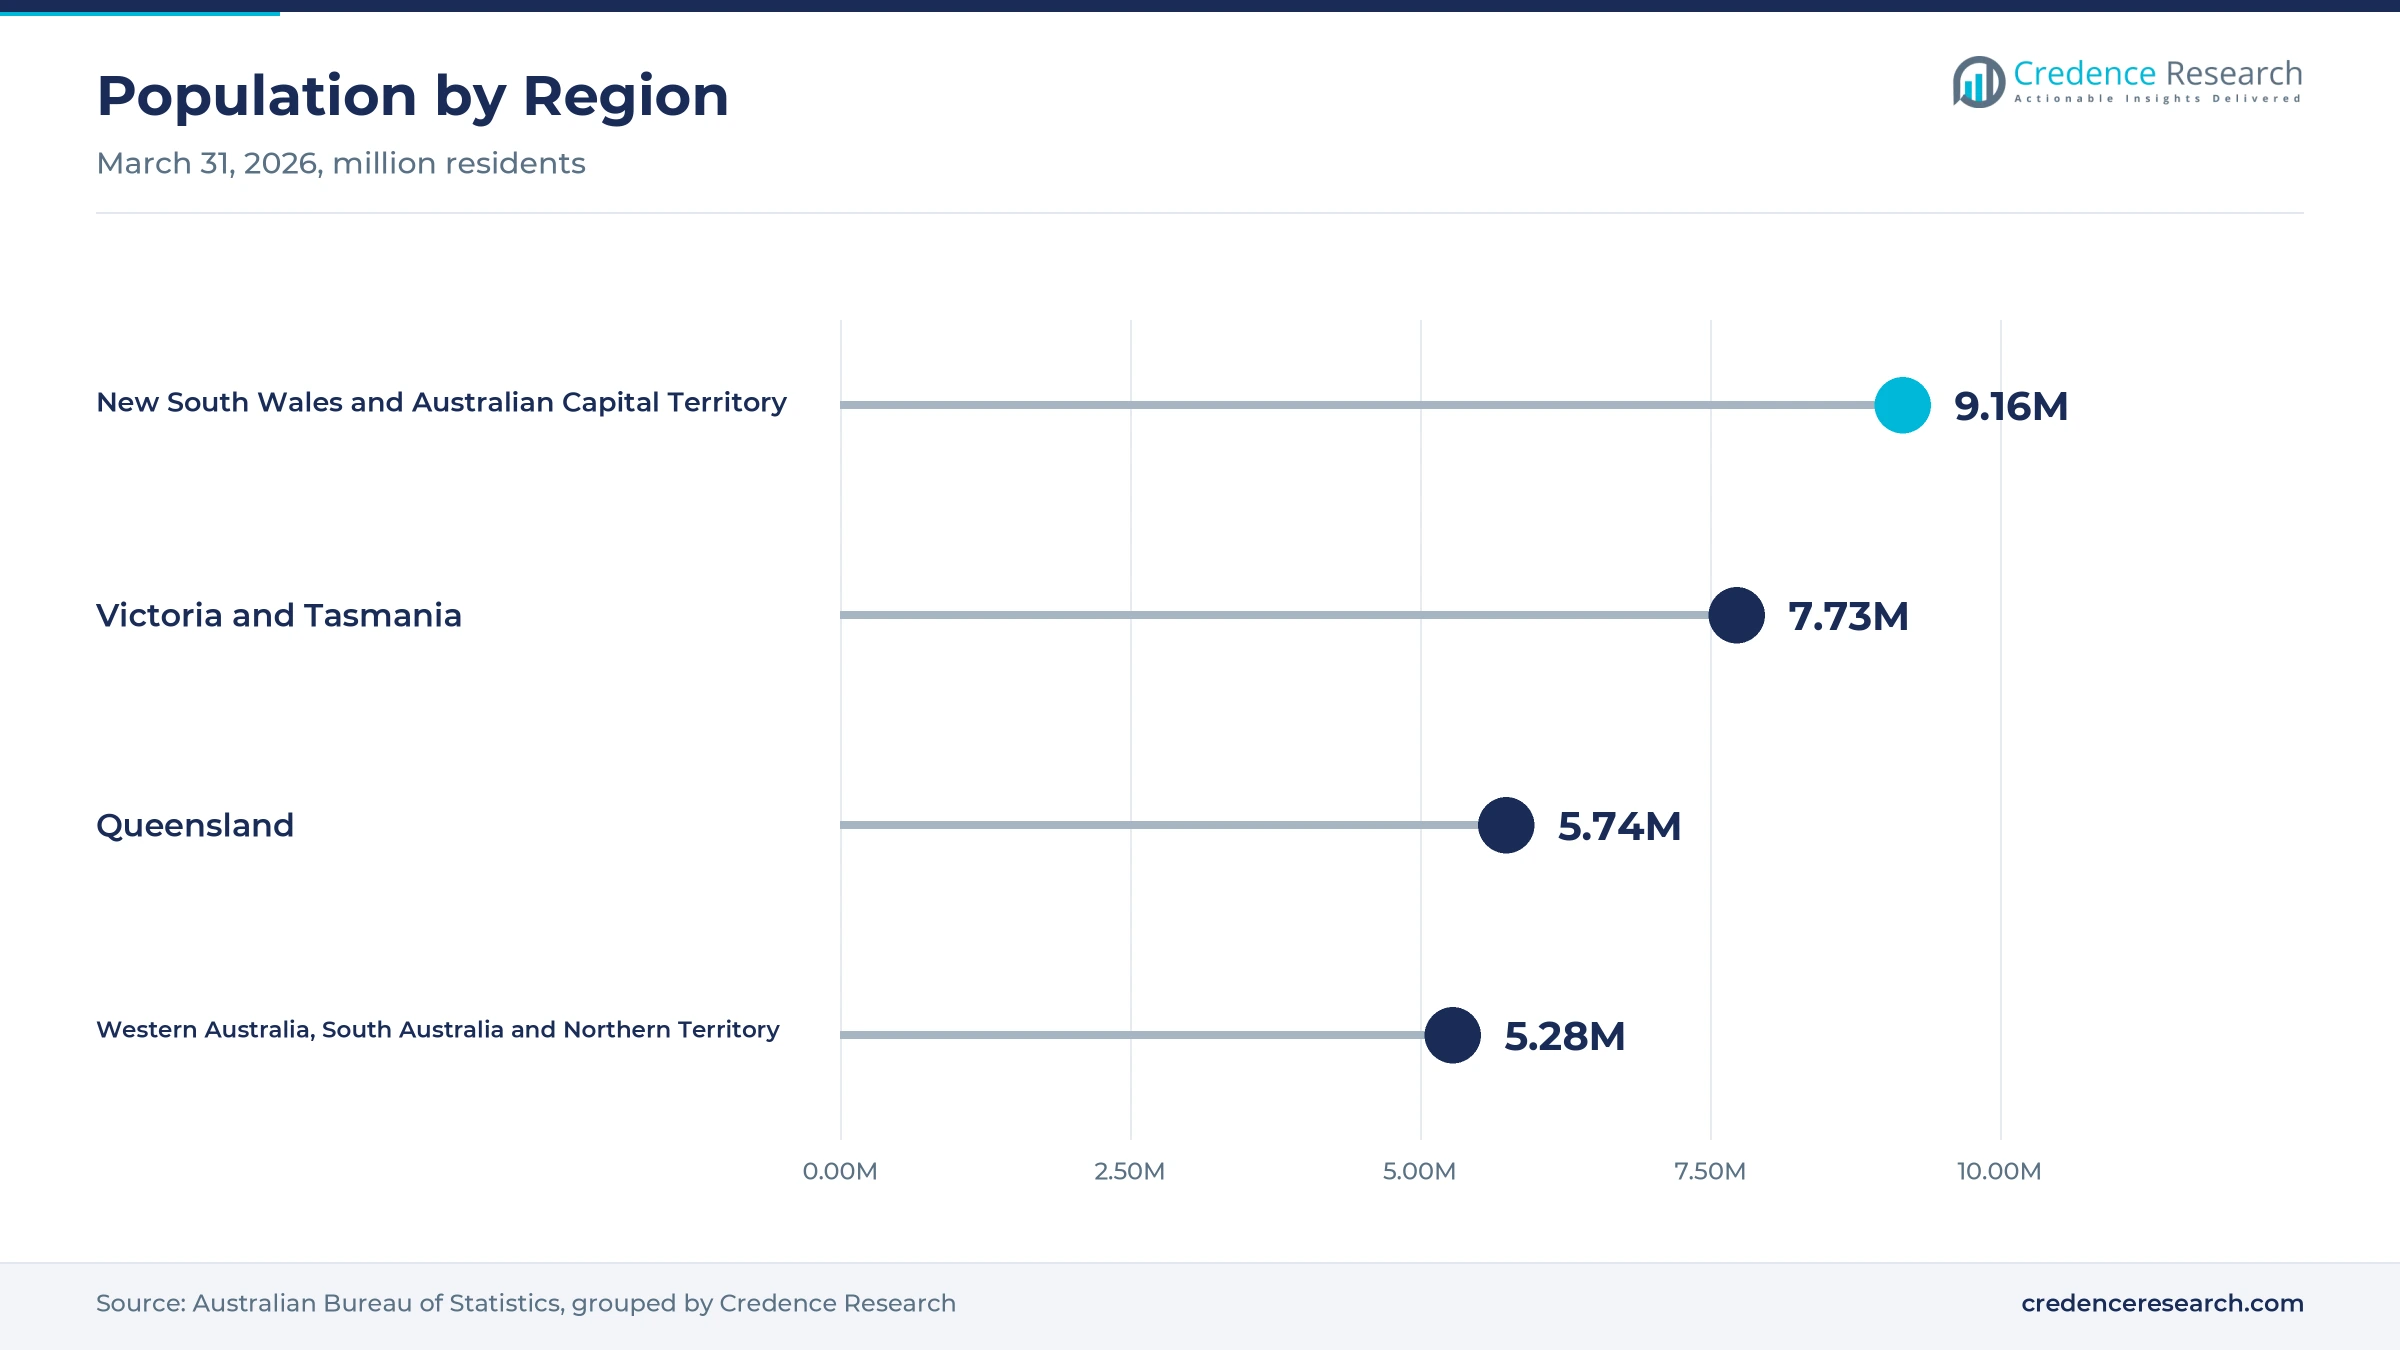
Sydney and Canberra anchor the largest specialist base in the country. New South Wales and Australian Capital Territory held a 33.7% share of 2025 value and grow at 6.60% a year. The two areas had about 9.16 million residents at March 31, 2026, the largest combined population of any region. However, New South Wales grew only 1.1% in that year, which keeps regional growth below the national rate. Sydney also hosts many dermatology and neurology practices, including neurology clinics on the lower North Shore that treat focal and generalised sweating.
How do Victoria and Tasmania support specialist demand?
Victoria and Tasmania held a 24.6% share of 2025 value and grow at 6.85% a year, because the two states had about 7.73 million residents at March 31, 2026. Victoria added about 109,500 residents in that year, the largest increase of any state, while Tasmania grew only 0.6%. Melbourne also hosts large dermatology centers, including the not-for-profit Skin Health Institute in Carlton and practices that offer miraDry and other dermatology devices.
Why is Queensland the fastest-growing region?
Queensland held a 19.0% share of 2025 value and grows fastest at 7.05% a year, because its population reached about 5.74 million at March 31, 2026, after 1.6% growth. A warm and humid climate in much of the state also makes heavy sweating more noticeable and more disruptive. As a result, Brisbane dermatology practices run dedicated programs for underarm injections, tablets, antiperspirants and facial sweating.
What shapes demand across the western and southern states?
Western Australia, South Australia and Northern Territory held a 22.7% share of 2025 value and grow at 7.00% a year. The region had about 5.28 million residents at March 31, 2026, across two states and one territory. Western Australia grew fastest at 2.1%, while long distances to specialists favor creams that general practitioners can prescribe.
Scheduling, approval and PBS listing marked 2024 to 2026
| Development | Status and market relevance |
|---|---|
| In October 2024, topical glycopyrronium moved to Schedule 4 as a prescription-only medicine. | Set the regulatory base for registered creams |
| In April 2025, miraDry, Inc. released its Sweat Scope study on underarm sweat during menopause. | Raised awareness of sweating among women in midlife |
| In September 2025, the Therapeutic Goods Administration registered glycopyrronium bromide cream for adults. | Approved the first ready-made cream for severe underarm sweating |
| In November 2025, the Pharmaceutical Benefits Advisory Committee recommended the cream for listing. | Placed the cream after antiperspirants and before injections |
| In May 2026, Actor Pharmaceuticals' Axhidrox cream was first listed on the Pharmaceutical Benefits Scheme. | Added a subsidized topical option for eligible patients |
Toxins, anticholinergic creams and microwave energy compete
- Botulinum toxin injections block the nerve signals that drive sweat glands, which cuts underarm sweating for several months per session.
- Glycopyrronium creams block acetylcholine at the sweat gland from the skin surface, which lets patients treat themselves at home each day.
- Microwave energy devices heat and destroy underarm sweat and odor glands, which gives a lasting reduction after one or two sessions.
- Oral anticholinergic tablets reduce sweating across the whole body, which suits generalised cases but brings body-wide side effects.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Drug sponsors and specialist clinics share patient flow
Competition combines global drug and device sponsors with specialist clinics that control patient flow. AbbVie supplies Botox, the only toxin listed on the Pharmaceutical Benefits Scheme for severe underarm sweating, while Actor Pharmaceuticals sponsors the Axhidrox glycopyrronium cream listed in May 2026. miraDry, Inc. supplies a microwave device that private clinics such as Laser Dermatology in Melbourne offer outside Medicare. Specialist practices compete on access and range, and Cutis in Brisbane offers injections, tablets, antiperspirant advice and facial sweating care. Sydney North Neurology & Neurophysiology treats focal and generalised hyperhidrosis from its Naremburn clinic. Companies compete on funded access, treatment comfort, duration of effect and out-of-pocket cost rather than on unit price alone. Clinics linked to non-invasive aesthetic care also attract private patients who want lasting underarm results.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| AbbVie | Drug sponsor | Supplies Botox under PBS item 11016T for severe underarm sweating |
| Actor Pharmaceuticals | Drug sponsor | Sponsors the Axhidrox glycopyrronium cream listed in May 2026 |
| miraDry, Inc. | Device maker | Supplies microwave devices used by private clinics |
| Cutis Dermatology | Specialist clinic | Brisbane practice offering injections, tablets and facial sweating care |
| Laser Dermatology | Specialist clinic | Melbourne practice offering miraDry underarm treatment |
| Sydney North Neurology & Neurophysiology | Specialist clinic | Treats focal and generalised hyperhidrosis in Naremburn |
Credence Research view on Australian sweating care
Credence Research's view is that Australian demand for hyperhidrosis treatment will grow steadily because funded options now span creams and injections. Botulinum toxin remains the base of specialist care, while the listed glycopyrronium cream grows fastest as general practitioners prescribe it earlier. Private payment still funds most palm, foot and device care, which supports clinics with broad programs. However, strict criteria, gap payments and specialist distance will hold back uptake outside capital cities. Sponsors and clinics that pair funded access with simple home treatment and clear pricing should gain share fastest.
How the Australian sweating care estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines population statistics, prevalence data, Pharmaceutical Benefits Scheme service counts and prices, Medicare fees, regulator decisions and clinic information on private treatments. Segment splits and regional growth rates are Credence Research estimates, while regional shares follow the client-defined split. Sources used are official statistics, government and regulator websites and company and clinic websites, and no interviews or surveys were used.
Earlier topical use and repeat injections carry 2035 demand
Hyperhidrosis treatment value in Australia is expected to reach USD 80.1 million by 2035, a 6.84% CAGR during 2026–2035, as earlier cream use and repeat injections keep demand rising. Growth should be strongest through 2028 while the listed cream reaches more general practices and patients. After that, steady population growth and private device care will carry more of the increase. Wider funding for palm and foot sweating would raise this outlook, while tighter price controls would lower it. Sponsors with funded products and clinics with broad treatment programs are expected to gain the most.
Frequently Asked Questions
How big is the Australia hyperhidrosis treatment market?
Which treatment type leads Australian demand?
Which region leads the Australian market?
What changed for sweating creams in 2026?
Who can give subsidized toxin injections for sweating?
Why does private payment dominate funding?
Who are the leading companies in Australian sweating care?
What are the main challenges for the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Treatment Type
- 1.2.1 Botulinum toxin injections
- 1.2.2 Topical therapies
- 1.2.3 Device and surgical interventions
- 1.2.4 Oral medications
- 1.3 By Application
- 1.3.1 Axillary hyperhidrosis
- 1.3.2 Palmar hyperhidrosis
- 1.3.3 Plantar hyperhidrosis
- 1.3.4 Craniofacial and generalised hyperhidrosis
- 1.4 By Funding Source
- 1.4.1 PBS-supported medicines
- 1.4.2 Medicare-supported services
- 1.4.3 Private-funded care
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 40.0 million → 2035: USD 80.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Hyperhidrosis Treatment Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Hyperhidrosis Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Hyperhidrosis Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Hyperhidrosis Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Hyperhidrosis Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Hyperhidrosis Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Hyperhidrosis Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Hyperhidrosis Treatment Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 40.0 million → 2035: USD 80.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Hyperhidrosis Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Treatment Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Botulinum toxin injections
- 12.3.7.2 Topical therapies
- 12.3.7.3 Device and surgical interventions
- 12.3.7.4 Oral medications
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Axillary hyperhidrosis
- 12.4.7.2 Palmar hyperhidrosis
- 12.4.7.3 Plantar hyperhidrosis
- 12.4.7.4 Craniofacial and generalised hyperhidrosis
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Funding Source - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 PBS-supported medicines
- 12.5.7.2 Medicare-supported services
- 12.5.7.3 Private-funded care
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Hyperhidrosis Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Hyperhidrosis Treatment Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Hyperhidrosis Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Hyperhidrosis Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AbbVie
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Allergan Australia
- 18.4 Actor Pharmaceuticals
- 18.5 miraDry, Inc.
- 18.6 Cutis Dermatology
- 18.7 Melbourne Skin & Dermatology
- 18.8 Skin Health Institute
- 18.9 Dermatology Institute of Victoria
- 18.10 Sydney North Neurology & Neurophysiology
- 18.11 Laser Dermatology
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

