
Severe seasons and single-dose antivirals lift flu care
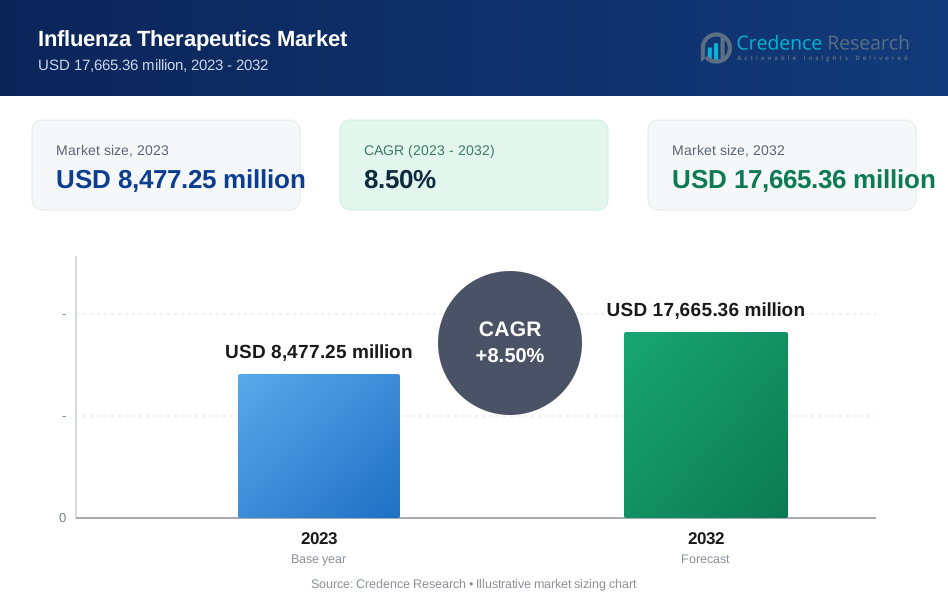
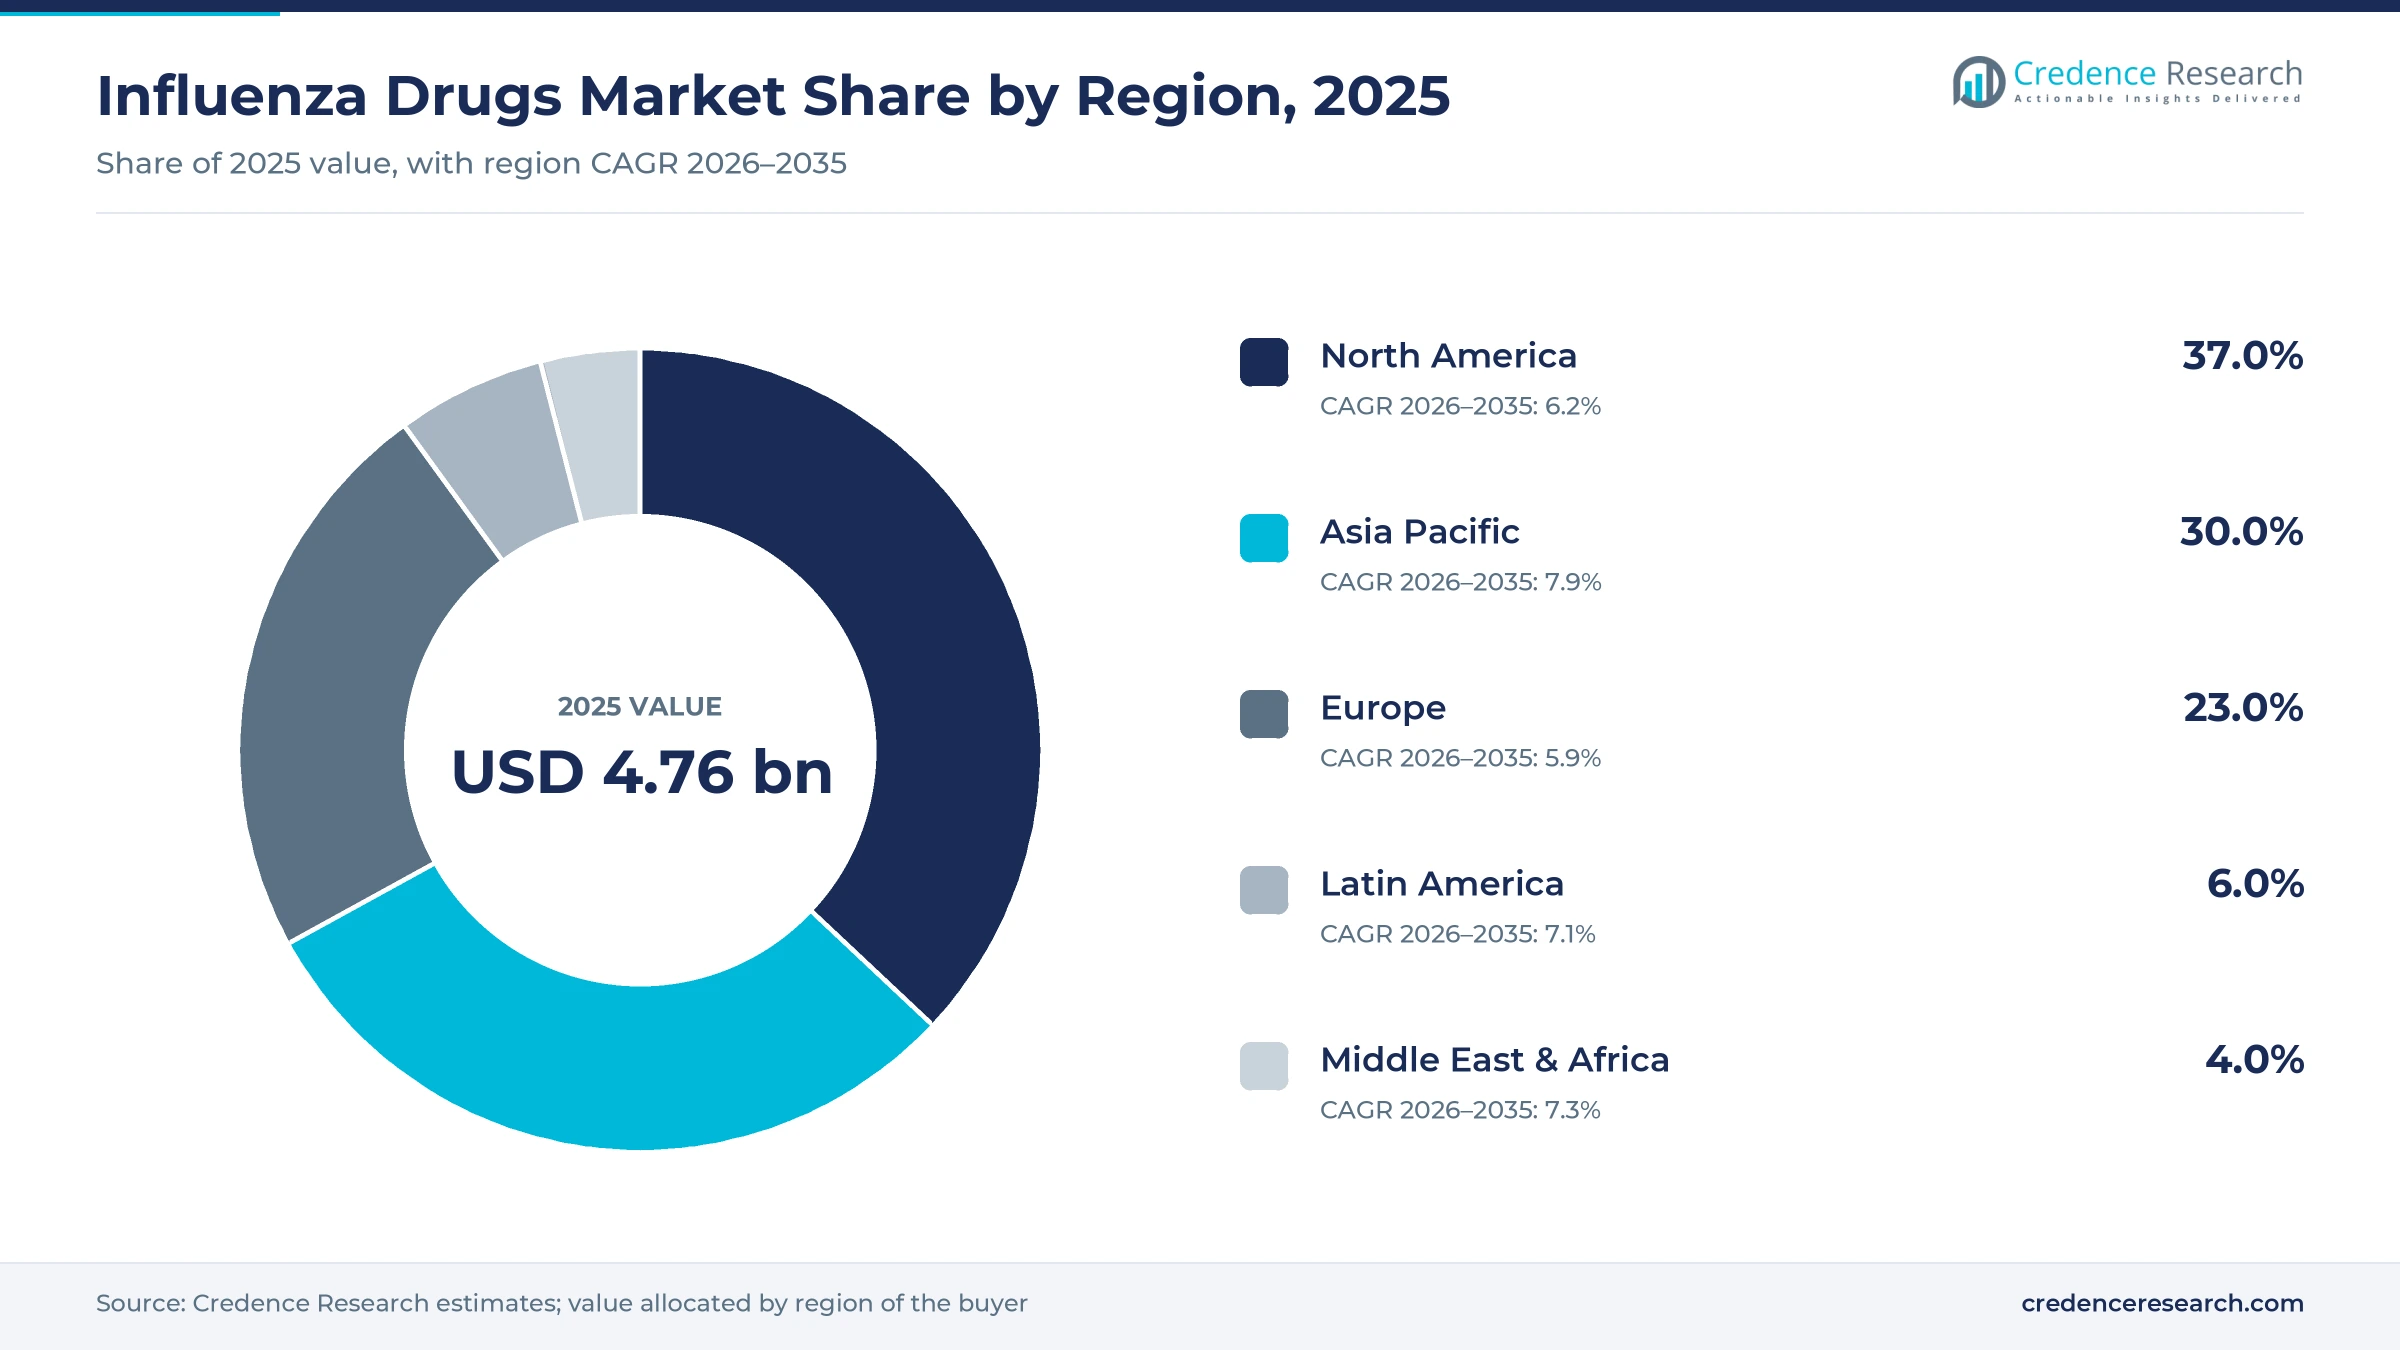
The global influenza drugs market was valued at USD 4.76 billion in 2025 and is projected to increase from USD 5.08 billion in 2026 to USD 9.14 billion by 2035, registering a CAGR of 6.74% during 2026–2035. Demand comes from seasonal epidemics that send patients to doctors, urgent care centers and pharmacies each winter, with older adults, young children, pregnant people and patients with chronic illness most likely to need treatment. North America held the largest regional share, 37.0% in 2025, because U.S. doctors prescribe antivirals widely and insurance covers most of the cost. Asia Pacific is the fastest-growing region at 7.9% a year, as Japan keeps high antiviral use and China and India widen access. The main change is the rise of single-dose polymerase inhibitors, with phase III data published in 2025 showing that baloxavir cut household transmission of the virus.
Which flu medicines count toward market value?
The market counts manufacturer revenue from medicines used to treat, prevent and relieve seasonal and pandemic influenza. It covers neuraminidase inhibitors such as oseltamivir, zanamivir and peramivir, the polymerase inhibitor baloxavir, and symptomatic antipyretics and antihistamines sold for flu relief. It also counts the share of seasonal vaccine sales tracked in this market definition.
Prescription antivirals account for most of the value, while fever and allergy relief products add large unit volumes at drugstores. The scope excludes rapid flu tests, hospital services and supportive care such as oxygen, and the value chain runs from originator and generic makers through wholesalers to hospital, retail and online pharmacies.
Influenza Drugs Market Insights
- The influenza drugs market grows from USD 4.76 billion in 2025 to USD 9.14 billion by 2035, a 6.74% CAGR over 2026–2035, as severe seasons and newer antivirals lift treatment rates.
- North America held 37.0% of global influenza drug value in 2025, backed by wide antiviral prescribing, insurance coverage and high-severity seasons.
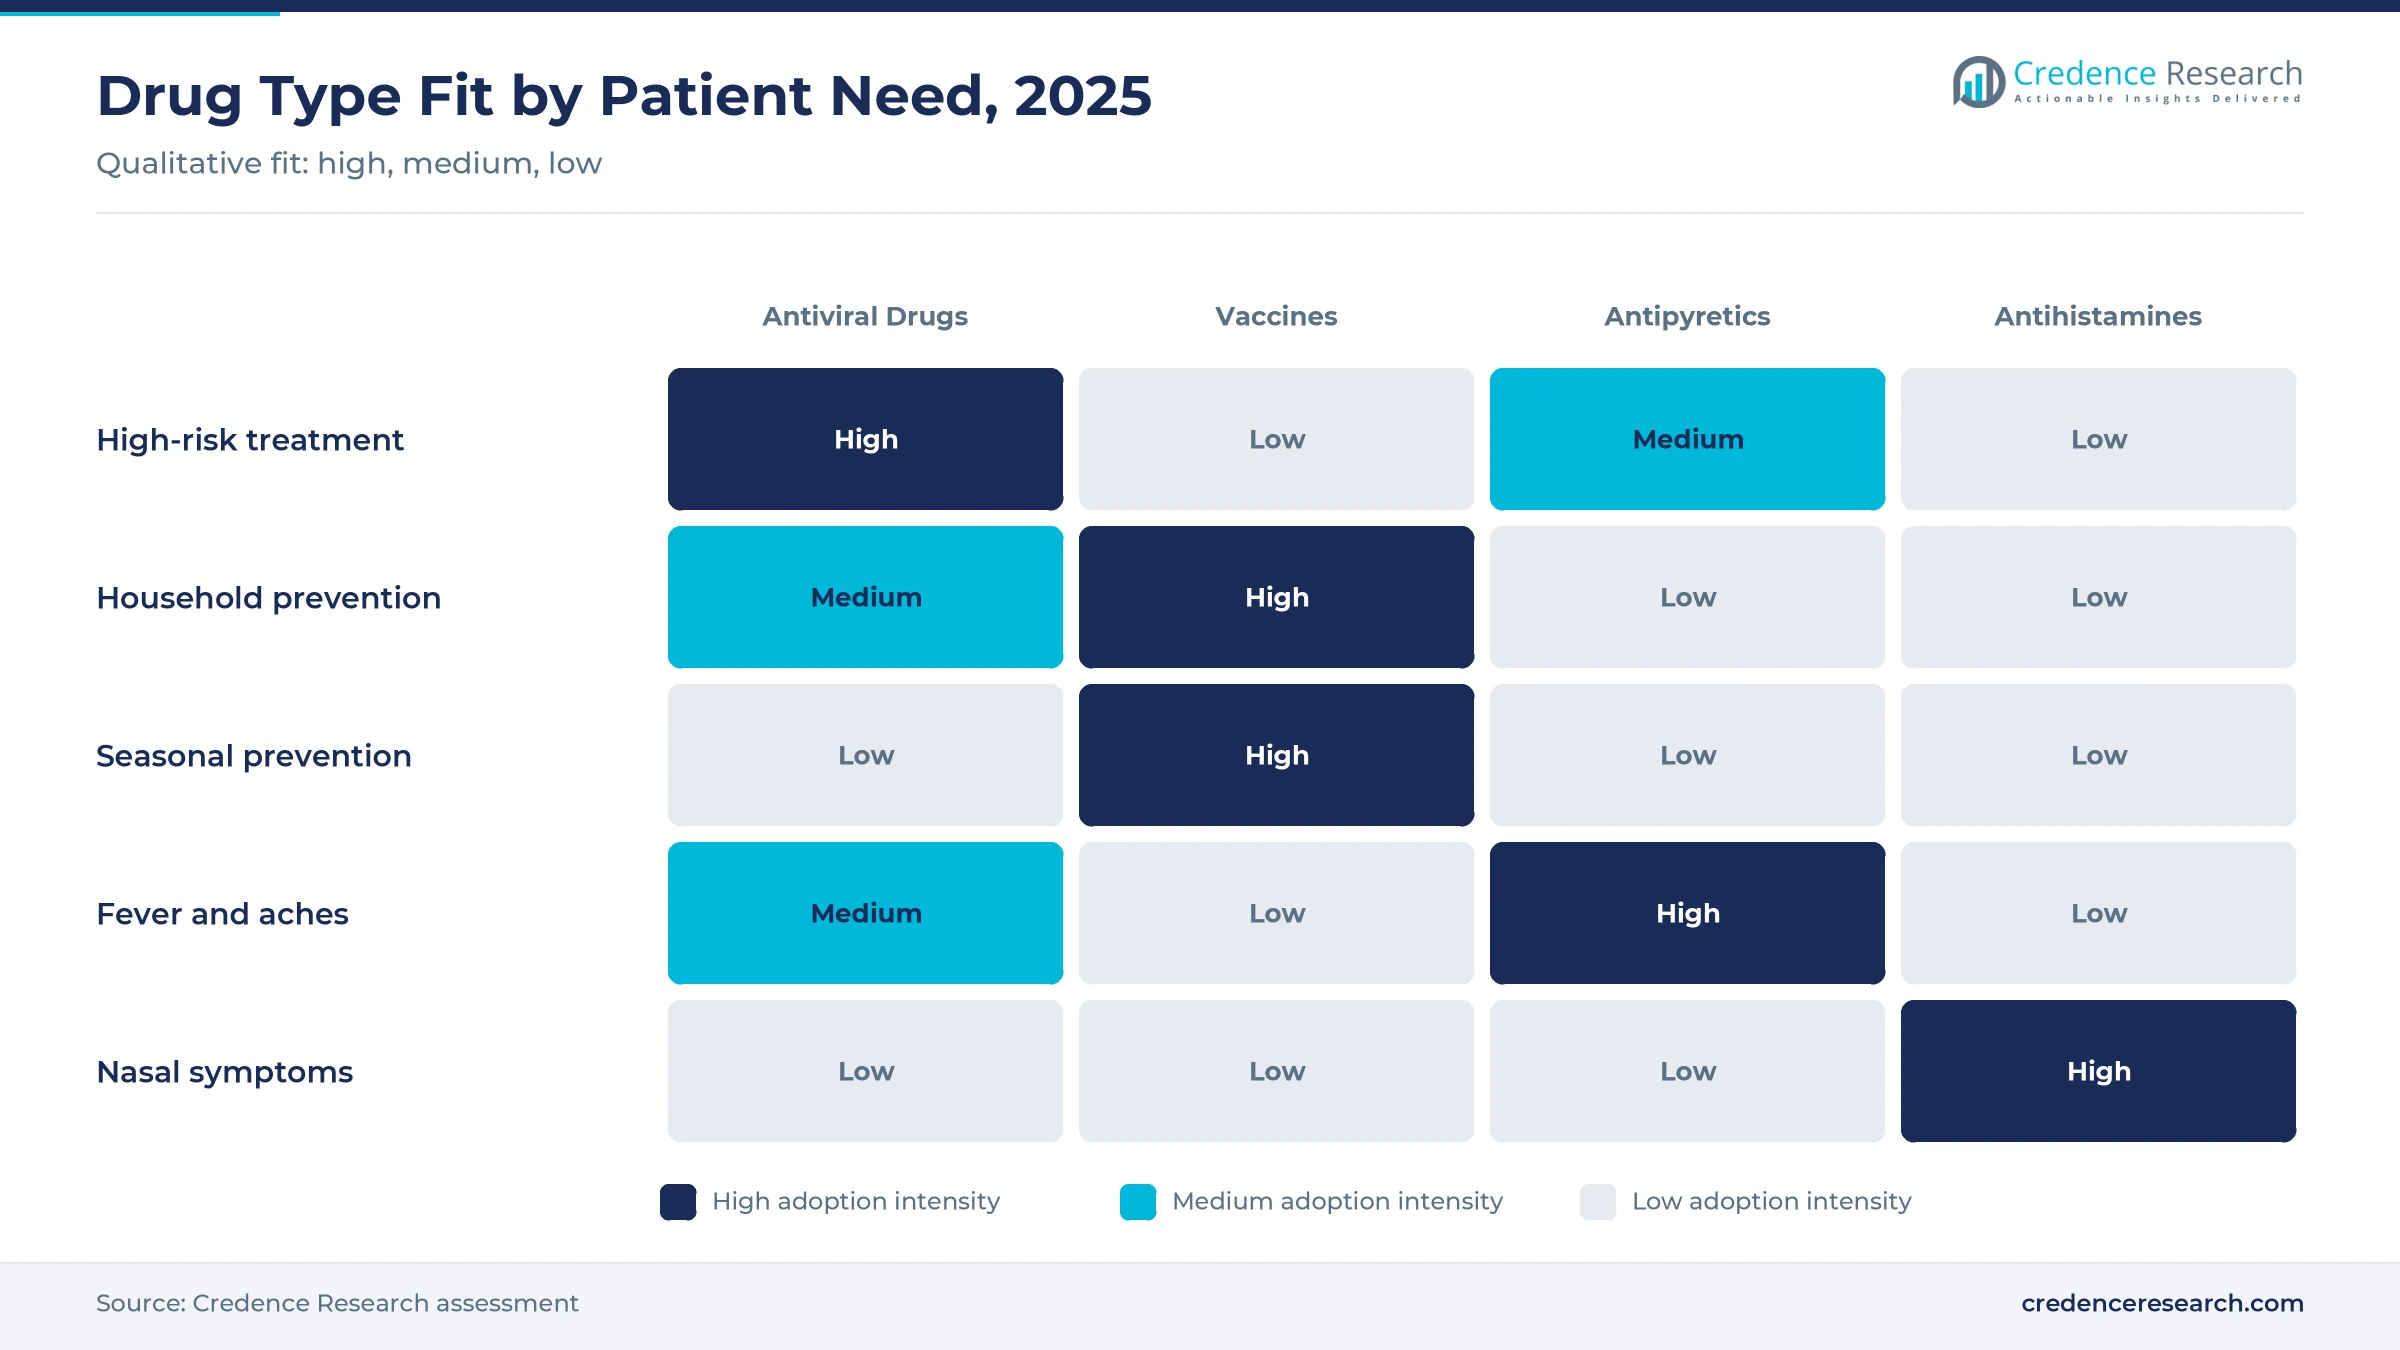
- Antiviral drugs led drug types with 46.0% of 2025 value, because doctors treat high-risk patients with oseltamivir or baloxavir within the first days of illness.
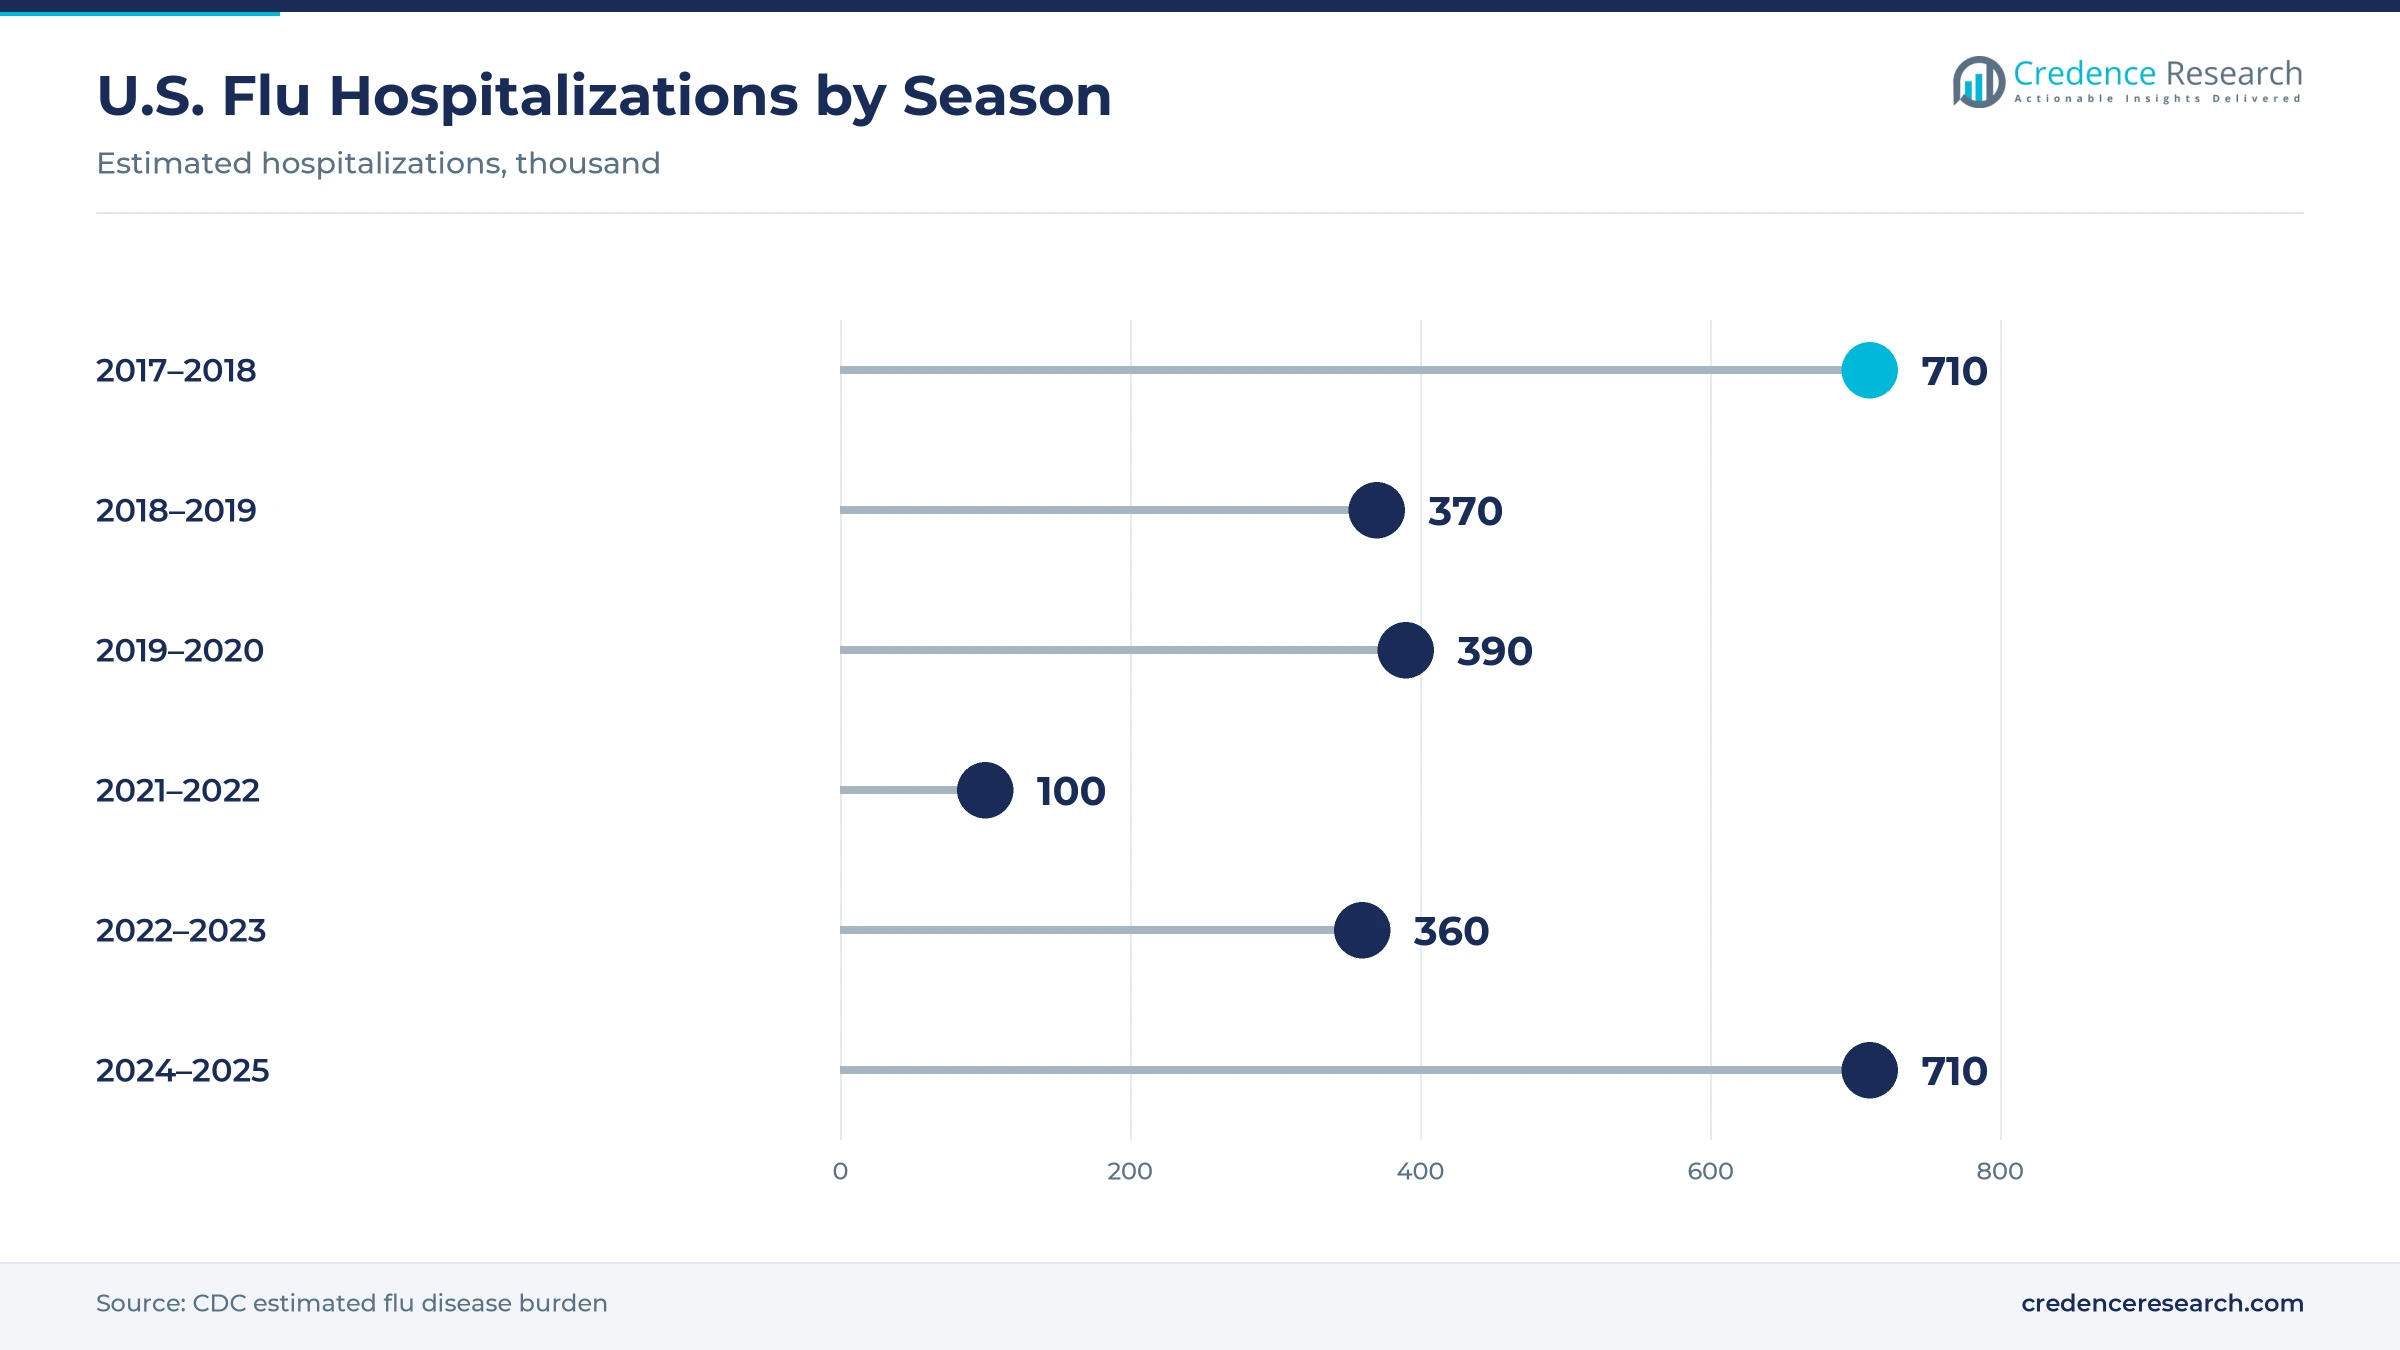
- CDC rated the 2024–2025 U.S. flu season high severity across all ages, with an estimated 710,000 hospitalizations and 45,000 deaths.
- Merck completed its acquisition of Cidara Therapeutics in January 2026, adding a phase 3 long-acting antiviral designed for season-long flu prevention.
Antivirals, influenza a and retail pharmacies lead
Why do antivirals hold the largest share?
Based on drug type, the market is categorized into antiviral drugs, antihistamines, antipyretics and vaccines. Antiviral Drugs led with a 46.0% share of 2025 value and also grow fastest at 7.3% a year. This lead reflects prescription prices for oseltamivir and baloxavir, which are far higher per course than fever and allergy relief products. In turn, guidance that urges early treatment for high-risk patients keeps antiviral demand strong in severe seasons.
Why does influenza a account for most treated cases?
Based on influenza type, the market is categorized into influenza A and influenza B. Influenza A led with a 72.0% share of 2025 value and also grows fastest at 6.9% a year. This lead reflects the H1N1 and H3N2 subtypes, which drive most seasonal epidemics and hospital admissions in older adults. Influenza B causes smaller waves, mainly in children and one B lineage has not been confirmed in circulation since March 2020.
Where do patients obtain flu medicines?
Based on distribution channel, the market is categorized into hospital pharmacy, retail pharmacy, online pharmacy and others. Retail Pharmacy led with a 44.0% share of 2025 value, because most patients fill antiviral prescriptions and buy fever relief at drugstores. Online Pharmacy grows fastest at 8.9% a year, as telehealth visits and home delivery services handle more winter orders.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Drug Type | Antiviral Drugs | 46.0% | Antiviral Drugs | 7.3% |
| By Influenza Type | Influenza A | 72.0% | Influenza A | 6.9% |
| By Distribution Channel | Retail Pharmacy | 44.0% | Online Pharmacy | 8.9% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Seasonal burden, high-risk groups and faster treatment
How does the global burden of seasonal flu sustain demand?
Seasonal influenza returns every year in both hemispheres, which creates a recurring need for treatment, prevention and symptom relief. The WHO estimates around a billion cases of seasonal influenza each year, including 3 to 5 million cases of severe illness and 290,000 to 650,000 respiratory deaths. In temperate climates epidemics peak mainly in winter, while tropical regions see outbreaks throughout the year, so demand never fully leaves the global market. Because immunity from vaccination fades over time, the WHO recommends yearly vaccination for pregnant women, children aged six months to five years, people over 65, people with chronic conditions and health workers. As a result, antiviral, vaccine and symptom relief demand repeats each season across all five regions.
Why do severe seasons lift antiviral prescribing?
High-severity seasons send more patients to doctors and hospitals, which raises antiviral prescriptions sharply. The CDC estimates that the 2024–2025 U.S. season caused 51 million illnesses and 710,000 hospitalizations, and it rated the season high severity across all age groups for the first time since 2017–2018. The CDC also counted 290 pediatric deaths, the most since the 2009 pandemic. Between 2010 and 2023, yearly U.S. flu hospitalizations ranged from 100,000 to 710,000, so the latest season matched the top of that range. In turn, clinicians treated more patients early with oseltamivir and baloxavir, which kept North America the largest regional market in 2025.
How do high-risk groups shape treatment demand?
Older adults, young children, pregnant people and patients with chronic heart, lung or kidney disease face the highest risk of flu complications. WHO advice states that people at high risk or with severe symptoms should receive antiviral treatment as soon as possible. World Bank data show that people aged 65 and above made up 10.2% of the world population in 2024, up from 8.3% in 2015, and 29.8% of Japan's population. Sanofi reported in October 2025 that adults aged 65 and older account for up to 70% of flu hospitalizations. Because the number of patients who qualify for early treatment rises each year, this trend supports steady demand for antiviral treatment through 2035, even in milder seasons.
Why does demand for symptom relief keep pharmacy sales steady?
Most people with uncomplicated flu manage fever, aches, cough and congestion at home with over-the-counter products. The WHO notes that most people recover from fever and other symptoms within a week without medical attention, and it advises people with mild symptoms to rest and treat fever. Acetaminophen and ibuprofen reduce fever and pain, while antihistamines ease runny nose and sneezing in combination cold and flu products. Because only 3 to 5 million of the roughly one billion yearly cases become severe, most patients buy their relief at drugstores, which helps Retail Pharmacy hold 44.0% of 2025 value. However, low prices for generic fever relief keep value growth below the market average.
Transmission data, home vaccination and new prevention
Why is transmission data shifting interest toward single-dose antivirals?
Doctors and health agencies are paying closer attention to antivirals that may also protect household members. On April 25, 2025, Roche announced that the phase III CENTERSTONE trial, published in the New England Journal of Medicine, showed single-dose Xofluza cut the odds of household transmission by 32% compared with placebo. The trial enrolled more than 4,000 participants at 272 sites, and patients took the drug within 48 hours of symptom onset. Roche notes that about one-third of all influenza transmission occurs within households, and it said the results were submitted to the FDA and the EMA. This shift supports wider use of polymerase inhibitors alongside older neuraminidase inhibitors through 2035.
How is home vaccination changing prevention?
Prevention is moving out of clinics, as regulators clear new ways to give flu vaccines at home. On Sept. 20, 2024, the FDA approved FluMist for self- or caregiver-administration in people aged 2 through 49 years, with adults able to give the nasal spray to themselves. The FDA called it the first flu vaccine that does not need a health care provider, more than 20 years after it first cleared FluMist in 2003. The manufacturer announced plans to supply it through an online pharmacy with a prescription. This rise in home options also lifts online orders, and Online Pharmacy grows fastest at 8.9% a year during 2026–2035.
Where is the opening in long-acting flu prevention?
Long-acting antivirals that protect high-risk patients for a whole season are a clear opening, because vaccines work less well in older adults and people with weak immune systems. The WHO notes that vaccine protection may be weaker in older people, a group that accounts for up to 70% of flu hospitalizations. Merck completed its acquisition of Cidara Therapeutics on Jan. 7, 2026, adding CD388, a phase 3 antiviral designed for season-long prevention that does not rely on an immune response. Similar approaches using monoclonal antibodies could open a new prevention class after 2030. If such products reach approval, antiviral drugs, which already held 46.0% of 2025 value, would extend their lead.
Can higher-dose vaccines open value in older adults?
Higher-dose vaccines for older adults are another opening, because this group accounts for most flu hospitalizations. On Oct. 20, 2025, Sanofi announced that the FLUNITY-HD study, published in The Lancet, found its high-dose vaccine gave an additional 31.9% reduction in flu hospitalizations versus standard-dose vaccines in adults aged 65 and older. The study also showed 8.8% additional protection against pneumonia or influenza hospitalizations. Sanofi estimated that one all-cause hospitalization is averted for every 515 older adults who receive the high-dose product instead of a standard dose. This evidence supports premium pricing and wider public program use of enhanced vaccines through 2035.
Resistance, late treatment and short selling seasons
How does antiviral resistance threaten treatment value?
Influenza viruses can develop resistance to neuraminidase and polymerase inhibitors, which reduces how well these medicines work. Resistance has appeared in some treated patients, especially children and people with weak immune systems who shed virus for longer. As a result, health agencies monitor circulating strains closely each season. Companies must therefore invest in new mechanisms and combination approaches to protect the long-term value of their antivirals.
Why does late treatment limit antiviral use?
Antivirals work best when started within about two days of symptom onset, yet many patients wait too long to see a doctor. Many people with flu also never receive a confirmed diagnosis, which leaves them on symptom relief alone. These gaps reduce the number of treated cases below the number of infections. In turn, telehealth, pharmacy testing and faster prescribing are important for raising treatment rates.
How does seasonality strain supply and revenue planning?
Flu demand peaks in winter and varies sharply from year to year, which makes production planning hard for manufacturers. A mild season can leave pharmacies with unsold stock, while a severe season can cause local shortages of antivirals and pediatric suspensions. As a result, revenue swings widely between one year and the next. Governments reduce this risk with national stockpile purchases, although these orders are irregular and depend on pandemic planning budgets.
Why do generic prices hold down value growth?
Oseltamivir lost patent protection years ago and now sells as low-cost generics from makers in India and other producing countries. Generic competition lowers revenue per course even when severe seasons push volumes higher. Antipyretics and antihistamines are almost entirely generic or store brand products with thin margins. This price pressure explains why symptom relief segments grow below the market average through 2035.
U.S. treatment volumes lead as Asian access grows
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 1.76 | 37.0% | 6.2% |
| Asia Pacific | 1.43 | 30.0% | 7.9% |
| Europe | 1.10 | 23.0% | 5.9% |
| Latin America | 0.29 | 6.0% | 7.1% |
| Middle East & Africa | 0.19 | 4.0% | 7.3% |
North America leads on antiviral prescribing
North America held a 37.0% share of 2025 value and grows at 6.2% a year through 2035. The U.S. leads spending, because doctors prescribe oseltamivir and baloxavir widely and insurance covers most of the cost. The high-severity 2024–2025 season raised treatment volumes, and home vaccination options added online pharmacy sales. Retail chains also offer flu shots and same-day antiviral fills, which shortens the path to treatment. However, generic oseltamivir holds down price growth for older treatment courses.
Europe relies on public programs and generics
Europe held a 23.0% share of 2025 value and grows at 5.9% a year, the slowest pace among the five regions. Germany, France, the U.K., Italy and Spain account for most demand, with national programs that focus on vaccination and reserve antivirals for high-risk patients. As a result, European antiviral use per person stays below U.S. levels. Public tenders for seasonal vaccines and pandemic stockpiles also shape supplier revenue across the region from year to year.
Asia Pacific grows on Japanese use and wider access
Asia Pacific held a 30.0% share of 2025 value and is the fastest-growing region at 7.9% a year. Japan has long had high antiviral use, while China and India are widening access through public insurance and generic supply. Indian manufacturers such as NATCO Pharma and Lupin also supply generic oseltamivir to domestic and export markets. In turn, treated volume grows faster than in mature markets, although average prices per course stay lower. Rising awareness after severe seasons also supports demand for antivirals among older adults in South Korea and Australia.
Latin America depends on pharmacy access
Latin America held a 6.0% share of 2025 value and grows at 7.1% a year through 2035. Brazil and Mexico account for most demand, with pharmacies selling large volumes of fever relief and cold and flu products directly to patients.
Middle East and Africa start from a low base
The Middle East & Africa held a 4.0% share of 2025 value and grows at 7.3% a year. Gulf states lead antiviral spending through public hospitals, while much of Africa relies on symptom relief and limited antiviral access.
Approvals, trial results and deals from 2024 to 2026
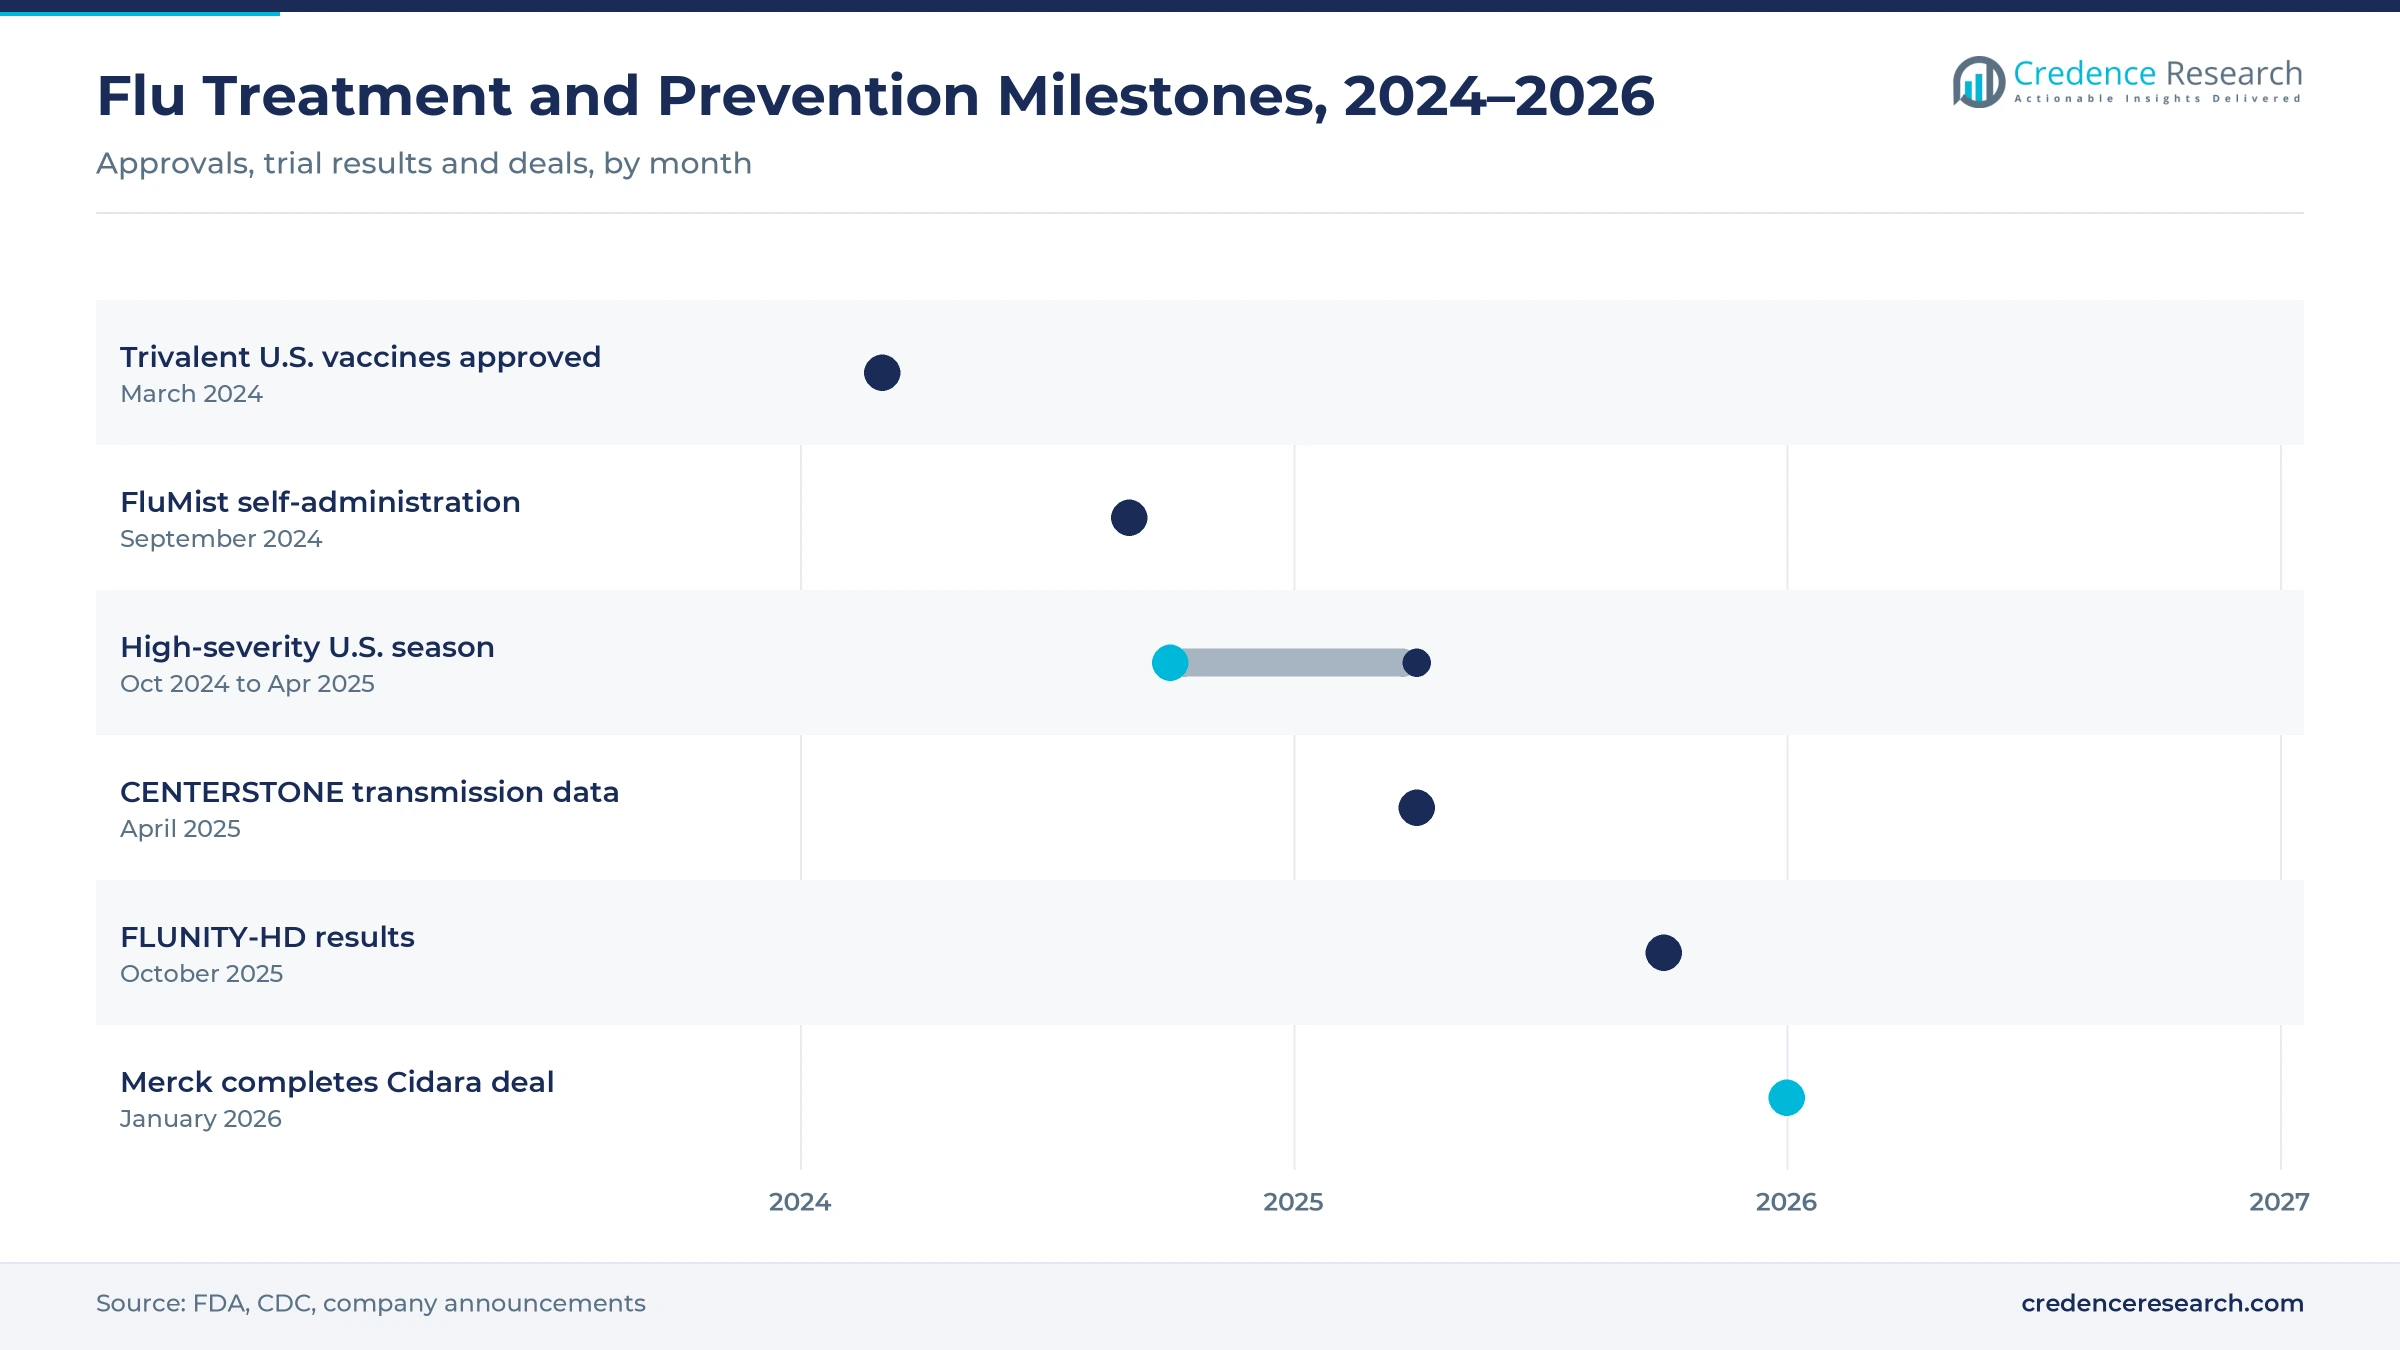
| Development | Status and market relevance |
|---|---|
| In September 2024, the FDA approved FluMist for self- or caregiver-administration in people aged 2 through 49 years. | Approved. First flu vaccine people can give themselves at home. |
| In April 2025, Roche announced that the CENTERSTONE trial showed single-dose Xofluza cut household transmission odds by 32%. | Submitted. Data filed with the FDA and EMA. |
| In October 2025, Sanofi announced FLUNITY-HD results showing a 31.9% further cut in flu hospitalizations with its high-dose vaccine. | Published. Supports high-dose use in adults aged 65 and older. |
| In January 2026, Merck completed its acquisition of Cidara Therapeutics and its long-acting antiviral CD388. | Completed. Phase 3 season-long prevention candidate. |
Polymerase inhibitors and long-acting prevention
- Polymerase acidic endonuclease inhibitors such as baloxavir block viral replication with a single oral dose and may reduce household spread.
- Neuraminidase inhibitors such as oseltamivir, zanamivir and peramivir stop the release of new virus particles and remain the most used class.
- Long-acting antivirals such as CD388 aim to protect high-risk people for a full season without relying on an immune response.
- Self-administered nasal vaccines let adults give a live attenuated vaccine to themselves at home after an online prescription.
- High-dose and adjuvanted vaccines give older adults a stronger immune response and fewer hospital admissions than standard doses.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Originators, vaccine makers and generic suppliers compete
Competition in influenza drugs splits into originators of antivirals, vaccine makers and generic suppliers. Roche and its U.S. unit Genentech lead in branded antivirals with Tamiflu and Xofluza, and they compete on clinical data such as transmission results. GSK, Sanofi, CSL Seqirus and AstraZeneca supply seasonal vaccines to public programs and pharmacies, and they win contracts through supply reliability and enhanced formulations. Serum Institute of India supplies lower-cost vaccines to many emerging markets. NATCO Pharma, Lupin and Viatris compete in generic oseltamivir with low prices and large volumes. Shionogi, which discovered baloxavir, sells Xofluza in Japan and partners with Roche on sales in other markets. Because generic oseltamivir sets price floors, value shifts toward newer antivirals and enhanced vaccines.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| F. Hoffmann-La Roche Ltd. (Genentech) | Originator | Tamiflu and Xofluza antivirals, sold in the U.S. through Genentech |
| Shionogi & Co., Ltd. | Originator | Discoverer of Xofluza, which Shionogi sells in Japan |
| GSK plc | Vaccines | Seasonal flu vaccines |
| Sanofi | Vaccines | High-dose and standard flu vaccines |
| CSL Seqirus (CSL) | Vaccines | Cell-based and adjuvanted seasonal flu vaccines |
| AstraZeneca | Vaccines | FluMist nasal spray vaccine, including the FluMist Home service |
| Serum Institute of India | Vaccines | Lower-cost vaccines for emerging markets |
| NATCO Pharma Limited | Generics | Generic oseltamivir supply |
| Lupin Limited | Generics | Generic oseltamivir capsules and suspension |
| Viatris Inc. | Generics | Generic oseltamivir capsules in markets such as New Zealand |
Antiviral use and prevention carry value to 2035
Credence Research's view is that prescription antivirals will carry most of the value growth in influenza drugs through 2035. Severe seasons such as 2024–2025 show how quickly treatment volumes rise when hospitals fill with flu patients. Single-dose polymerase inhibitors gain share as transmission data support their use, while generic oseltamivir keeps volumes high at low prices. Long-acting prevention for high-risk groups could open a new class after 2030. Companies with newer antivirals and enhanced vaccines are best placed for value, while generic makers win on volume.
Treated cases and pack prices anchor the model
The report uses 2025 as the base year and forecasts market value to 2035, with growth rates stated for 2026–2035. Market values come from the Credence Research market model, which combines treated flu cases by region, typical therapy use and average pack prices by channel. Splits by drug type, influenza type, distribution channel and region are Credence Research estimates. Sources used include WHO and CDC disease data, FDA announcements and company press releases. No primary interviews or surveys were used to build the estimates in this report.
Prevention and early treatment shape flu care by 2035
By 2035, the market reaches USD 9.14 billion, with antivirals still providing the largest share of value. Single-dose polymerase inhibitors gain ground as transmission data reach treatment guidance, while generic oseltamivir keeps courses affordable. Online pharmacies grow fastest as telehealth and home vaccination become routine each winter. Asia Pacific adds volume as China and India widen access, and North America remains the largest region. Long-acting prevention for high-risk groups could become a meaningful new segment after 2030.
Frequently Asked Questions
How big is the influenza drugs market?
Which drug type leads the market?
Which distribution channel grows fastest?
Which region holds the largest share?
How severe was the 2024–2025 flu season?
What did the CENTERSTONE trial show?
Who are the leading companies?
What are the main challenges?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Type
- 1.2.1 Antiviral Drugs
- 1.2.2 Vaccines
- 1.2.3 Antipyretics
- 1.2.4 Antihistamines
- 1.3 By Influenza Type
- 1.3.1 Influenza A
- 1.3.2 Influenza B
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 4.76 billion → 2035: USD 9.14 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Influenza Drugs Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Influenza Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Influenza Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Influenza Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Influenza Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Influenza Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Influenza Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Influenza Drugs Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 4.76 billion → 2035: USD 9.14 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Influenza Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Antiviral Drugs
- 12.3.7.2 Vaccines
- 12.3.7.3 Antipyretics
- 12.3.7.4 Antihistamines
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Influenza Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Influenza A
- 12.4.7.2 Influenza B
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Influenza Drugs Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Influenza Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Influenza Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 F. Hoffmann-La Roche Ltd. (Genentech)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Shionogi & Co., Ltd.
- 17.4 GSK plc
- 17.5 Sanofi
- 17.6 CSL Seqirus (CSL)
- 17.7 AstraZeneca
- 17.8 Serum Institute of India
- 17.9 NATCO Pharma Limited
- 17.10 Lupin Limited
- 17.11 Viatris Inc.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

