
Market Overview:
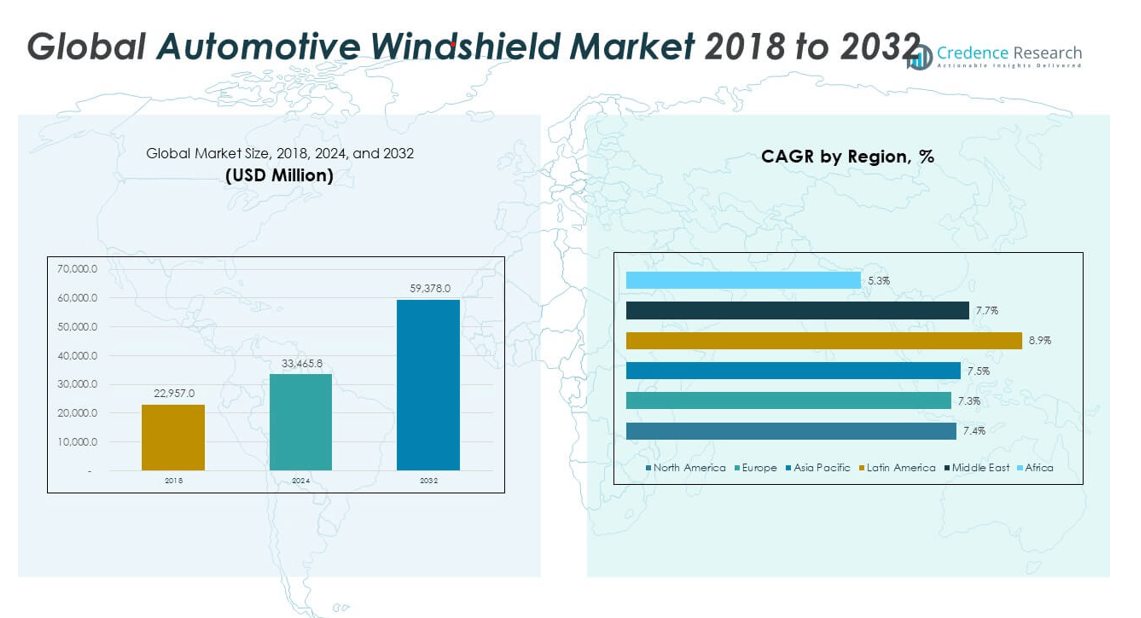
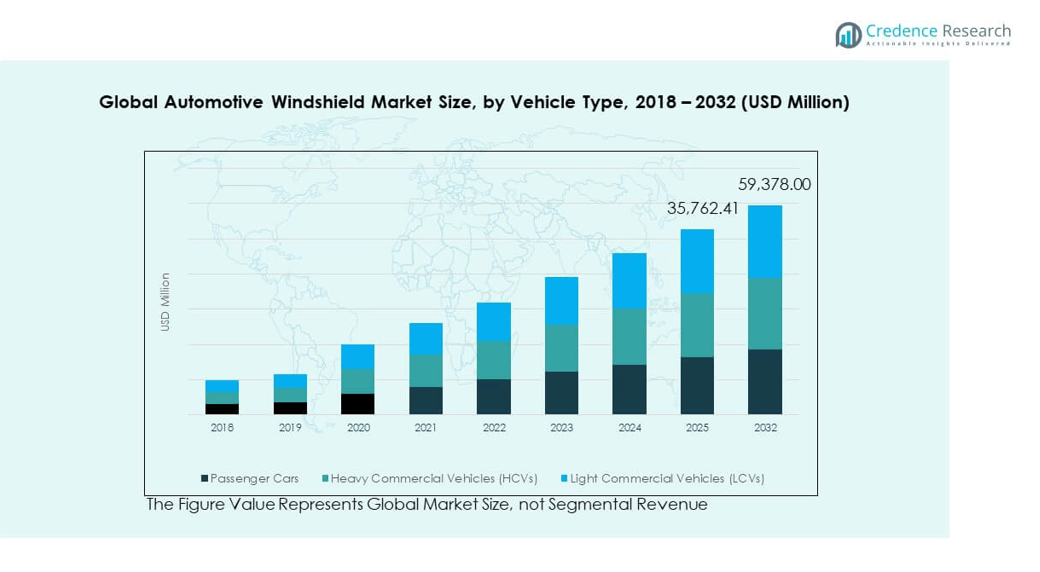
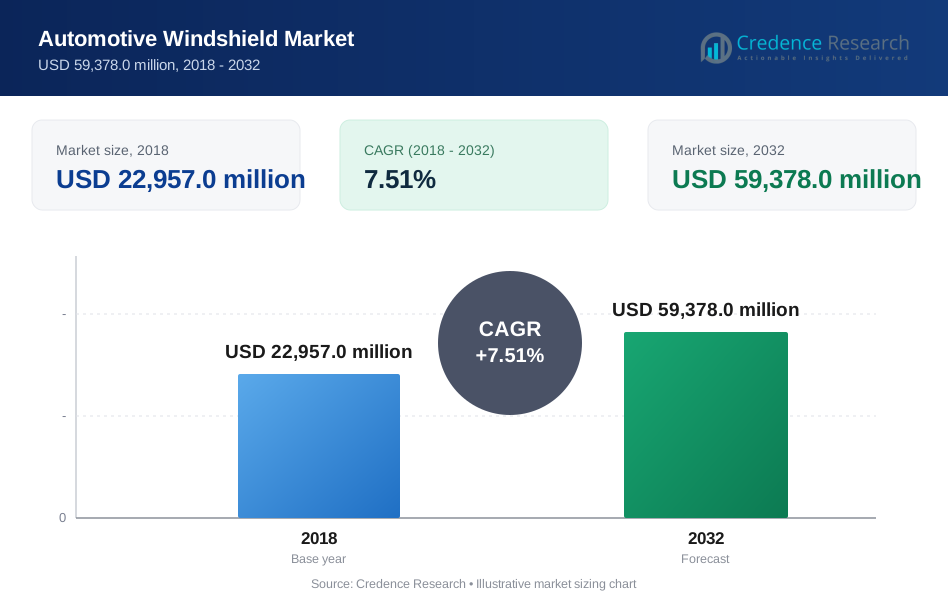
The Global Automotive Windshield Market size was valued at USD 22,957.0 million in 2018 to USD 33,465.8 million in 2024 and is anticipated to reach USD 59,378.0 million by 2032, at a CAGR of 7.51% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Windshield Market Size 2024 | USD 33,465.8 million |
| Automotive Windshield Market, CAGR | 7.51% |
| Automotive Windshield Market Size 2032 | USD 59,378.0 million |
The market is driven by rising vehicle production, growing demand for safety features, and adoption of advanced glazing technologies. Increasing use of laminated and tempered glass to enhance occupant protection and visibility supports market expansion. The integration of smart windshields with sensors, head-up displays, and rain detection systems is also fueling demand among OEMs. Environmental regulations promoting lightweight and energy-efficient vehicles further strengthen the adoption of innovative windshield materials.
Asia-Pacific dominates the market due to its strong automotive manufacturing base and expanding consumer demand. North America and Europe follow, supported by high technology adoption and strong safety regulations. Emerging economies in Latin America and the Middle East are experiencing growing demand for passenger and commercial vehicles, driving aftermarket and OEM sales. The presence of major automotive suppliers and rising investments in smart mobility accelerate regional market growth.
Market Insights:
- The Global Automotive Windshield Market was valued at USD 22,957.0 million in 2018, reached USD 33,465.8 million in 2024, and is expected to attain USD 59,378.0 million by 2032, growing at a CAGR of 7.51%.
- Asia Pacific leads with 34% of the global share due to its strong automotive manufacturing base, technological progress, and rapid adoption of electric and connected vehicles.
- Europe follows with 28%, supported by its advanced automotive ecosystem and high integration of smart and safety glass technologies, while North America holds 23%, driven by luxury vehicle demand and strong OEM presence.
- Latin America is the fastest-growing region, holding 8% share, with expansion driven by urbanization, replacement demand, and growing production capacity in Brazil and Mexico.
- Passenger cars account for about 60% of total demand, reflecting high production and safety adoption, while light commercial vehicles represent around 25%, supported by logistics and e-commerce growth.
Market Drivers:
Rising Vehicle Production and Demand for Enhanced Safety Standards
The Global Automotive Windshield Market is driven by growing vehicle production across passenger and commercial segments. Automakers are increasingly integrating advanced safety features, which has elevated demand for laminated and tempered glass windshields. Rising consumer awareness of occupant safety and visibility improvements also boosts adoption. Government regulations mandating safety glass usage strengthen the market outlook. Automakers focus on producing lightweight, impact-resistant, and energy-efficient windshields to meet evolving standards. The development of noise-reducing and glare-resistant designs further enhances driving comfort. Growing disposable income in developing economies contributes to higher vehicle sales, sustaining windshield demand.
- For instance, AGC Automotive's “Lamisafe” laminated windshields have achieved impact resistance that meets ECE R43 and FMVSS 208 certifications, with intrusion resistance measured at over 10 minutes during simulated break-in attempts and acoustic dampening reduction of external noise by up to 35 decibels in actual highway conditions.
Adoption of Smart and Connected Windshield Technologies
Integration of smart technologies in vehicles is significantly influencing windshield design and functionality. Manufacturers are developing windshields equipped with sensors, cameras, and head-up displays to enhance situational awareness. Smart windshields support driver-assistance features like lane-departure warning and collision detection, improving safety performance. Increasing use of augmented reality displays and connectivity features elevates driving experience. Demand for such advanced systems is rising among luxury and premium vehicles, pushing innovation across the supply chain. OEMs are collaborating with tech providers to produce cost-effective smart glass solutions. It encourages large-scale adoption across mid-range and electric vehicle models.
- For instance, NSG Group was selected by Mercedes-Benz in 2024 to supply augmented reality head-up display windshields for the S-Class; these deliver high display image quality using advanced press bending technology and include solar reflecting coatings for de-icing, all verified and launched as standard in new S-Class models.
Growing Electric Vehicle Adoption and Sustainability Focus
Rising electric vehicle (EV) production is creating new opportunities for windshield manufacturers. EVs require aerodynamically optimized and thermally efficient glass to improve energy efficiency. The trend toward lightweight materials supports the use of advanced laminated and coated glass. Sustainable production processes and recyclable glass options align with global environmental goals. Increasing consumer preference for EVs drives investment in specialized glass manufacturing for energy retention and solar control. Governments promoting green mobility accelerate adoption across key markets. Continuous R&D in solar-reflective coatings and acoustic insulation adds value to EV-specific windshield systems.
Increasing Aftermarket Demand and Replacement Rates
The expanding vehicle fleet and growing focus on vehicle maintenance support the replacement windshield market. Rising cases of damage due to road debris, accidents, and temperature fluctuations boost replacement needs. Insurance coverage and service contracts are making repairs and replacements more accessible. The aftermarket segment benefits from digital service networks offering quick installation and calibration. Consumers prefer OEM-quality replacements to maintain performance and compliance with safety standards. Technological improvements, including automated windshield calibration systems, enhance service efficiency. Expanding e-commerce platforms and service centers also drive availability and accessibility across regions.
Market Trends:
Advancement in Head-Up Display (HUD) and Augmented Reality Windshields
The integration of head-up display (HUD) and augmented reality features is transforming the Global Automotive Windshield Market. These technologies project navigation, speed, and hazard alerts directly on the glass, improving driver awareness. Luxury and high-end vehicles have led this adoption, while mid-range segments are following through modular solutions. The use of AR windshields is growing due to demand for connected and intuitive driving experiences. Automakers collaborate with electronics and software firms to enhance display accuracy and clarity. Optical coatings and anti-reflective materials are improving projection visibility under varied light conditions. It is reshaping how drivers interact with vehicle information.
- For instance, BMW launched its Panoramic Vision system for 2025 Neue Klasse models, projecting critical information onto the full-width windshield with high-definition display capabilities, recognized for consistent driver visibility and seamless integration into the vehicle’s line of sight, verified during the system’s CES 2025 world premiere.
Increased Use of Acoustic and Thermal Control Laminated Glass
Laminated glass with acoustic and thermal properties is gaining traction among OEMs and consumers. It minimizes road noise and enhances cabin comfort, especially in premium vehicles. Rising awareness of passenger comfort and energy conservation fuels demand for advanced glazing solutions. Thermal-control coatings reduce heat transmission, improving air conditioning efficiency. The technology also supports vehicle electrification goals by optimizing energy usage. Manufacturers are investing in multi-layer interlayer glass to balance durability and insulation. This trend is shaping material innovation and design strategies for next-generation windshields.
Shift Toward Lightweight and Sustainable Glass Manufacturing
Automakers are emphasizing vehicle weight reduction to improve fuel efficiency and reduce emissions. The windshield segment contributes to this through thinner, stronger glass compositions. Manufacturers are adopting chemical strengthening and advanced lamination techniques to ensure safety. Use of recycled glass materials is also expanding to meet sustainability targets. Regulatory focus on green production practices encourages innovation in energy-efficient processes. Companies are transitioning toward eco-friendly coatings and adhesives that lower environmental impact. The shift aligns with the global trend of sustainable automotive manufacturing.
Expansion of Windshield Integration in Autonomous and ADAS Vehicles
The rise of autonomous and semi-autonomous vehicles is increasing windshield functional complexity. Windshields now serve as structural, sensor, and data interface components in advanced driver-assistance systems (ADAS). Cameras, LiDAR, and sensors are being embedded into windshield structures for better field-of-view performance. Automakers rely on precision glass alignment and optical clarity to enhance sensor accuracy. Growth in ADAS-equipped vehicles boosts the integration of multifunctional glass panels. It drives demand for coatings that prevent signal interference and maintain visibility. This technological shift enhances the role of windshields as core safety and intelligence components.
Market Challenges Analysis:
High Production Costs and Complexity of Advanced Windshield Technologies
The Global Automotive Windshield Market faces cost challenges linked to advanced materials and processing methods. Production of smart, laminated, and coated glass requires expensive raw materials and precise manufacturing equipment. Integration of sensors and display systems increases design complexity and raises production expenses. OEMs struggle to balance innovation with affordability for mass-market vehicles. Supply chain fluctuations in specialty glass and chemical coatings further impact pricing stability. High maintenance and calibration costs also limit replacement affordability. It creates financial constraints for both manufacturers and consumers in emerging markets.
Stringent Safety Regulations and Supply Chain Constraints
Global safety standards demand compliance with rigorous impact resistance, clarity, and durability tests. Achieving these standards requires consistent material quality and testing accuracy, which raises operational costs. Supply chain disruptions caused by raw material shortages and logistics delays affect timely production. Dependence on specific glass suppliers limits flexibility and increases vulnerability during market fluctuations. Shortages of specialty glass components can delay OEM deliveries. Manufacturers must also manage regulatory differences across regions, complicating standardization. These challenges collectively hinder smooth market expansion and innovation speed.
Market Opportunities:
Emergence of Smart Mobility and Connected Vehicle Ecosystems
The Global Automotive Windshield Market benefits from the rise of connected mobility and smart infrastructure. Integration of 5G, V2X communication, and advanced display systems supports development of intelligent windshields. Automakers and tech firms are exploring glass-based interface solutions for real-time data visualization. Growing investment in connected vehicles opens space for sensor-embedded and display-integrated windshields. Partnerships among automakers, glass makers, and electronics companies encourage scalable innovation. It positions the windshield as a key human-machine interaction surface in next-generation vehicles.
Rising Adoption of Electric and Autonomous Vehicles
Expanding EV and autonomous vehicle production creates new applications for advanced windshields. These vehicles demand aerodynamically efficient, energy-optimizing, and sensor-compatible glass designs. Manufacturers can leverage opportunities by developing thermal-insulated and solar-protective glazing. Governments promoting cleaner mobility and EV incentives accelerate adoption across major economies. Innovation in lightweight, transparent conductive coatings further enhances EV range and visibility. These trends open a broad scope for technological advancement and premium product development.
Market Segmentation Analysis:
By Vehicle Type
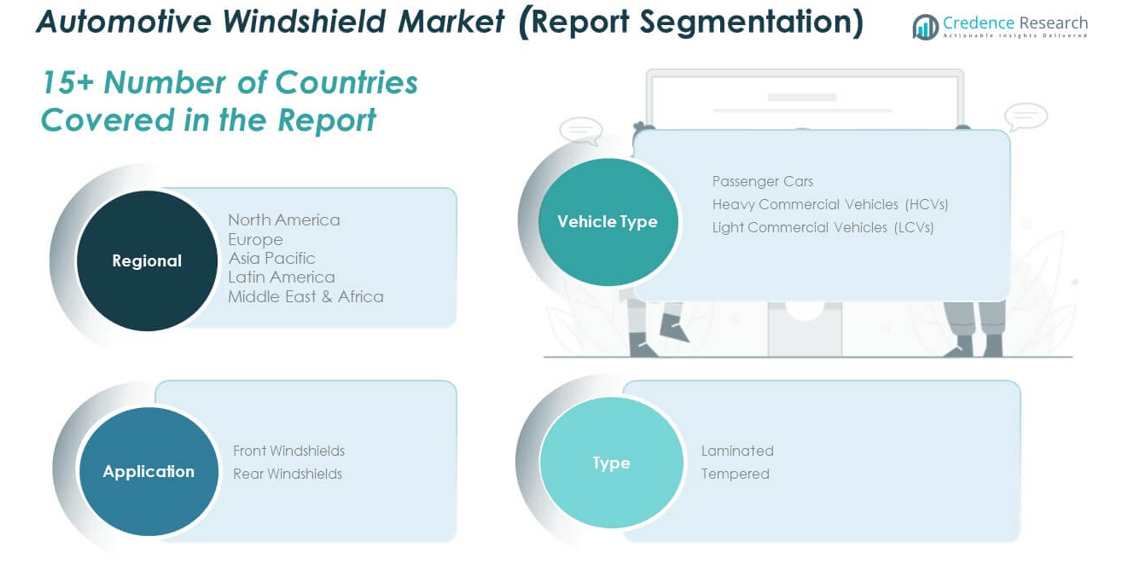
The Global Automotive Windshield Market is segmented into passenger cars, heavy commercial vehicles (HCVs), and light commercial vehicles (LCVs). Passenger cars hold the dominant share due to high production volumes and growing demand for comfort and safety features. Rising urbanization and disposable income levels drive strong sales across this category. Light commercial vehicles are witnessing steady growth supported by expanding logistics and e-commerce activities. Heavy commercial vehicles contribute through demand for durable and impact-resistant windshields designed for extended operational use. Each vehicle segment focuses on improved visibility, safety, and performance standards.
- For instance, Fuyao Glass, in partnership with Isuzu, produced windshields for heavy commercial vehicles that withstand debris impacts at velocities exceeding 120 km/h and complete durability tests over 1,000-hour continuous vibration cycles, according to 2025 third-party test results.
By Application
The market is divided into front and rear windshields, with front windshields accounting for the largest share. Their integration with sensors, cameras, and display systems enhances driver safety and vehicle intelligence. Rear windshields are evolving with defogging, heating, and improved visibility features. The rise in connected and electric vehicles strengthens demand across both applications. Manufacturers prioritize aerodynamic design and optical clarity to improve driver experience and vehicle efficiency.
- For instance, Tesla vehicles are equipped with a standard heated rear windshield, side mirrors, and charge port that activate automatically with the defrost function. According to Tesla's owner manuals, the rear defroster runs for 15 minutes before automatically shutting off. While the exact defrost time varies with weather conditions, independent winter tests on a snow-covered Model 3 and Model Y showed that the system needed 20–30 minutes to make the cars fully drivable without manual clearing.
By Type
Based on type, the market includes laminated and tempered glass. Laminated glass dominates due to its superior safety and shatter-resistance properties. It prevents fragmentation during impact, improving occupant protection. Tempered glass remains preferred for cost-effective applications and rear installations. Continuous innovation in coatings, UV protection, and lightweight glass formulations supports growth across both segments. It highlights the industry’s focus on safety, durability, and performance enhancement.
Segmentation:
By Vehicle Type
- Passenger Cars
- Heavy Commercial Vehicles (HCVs)
- Light Commercial Vehicles (LCVs)
By Application
- Front Windshields
- Rear Windshields
By Type
- Laminated
- Tempered
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
The North America Global Automotive Windshield Market size was valued at USD 5,307.65 million in 2018 to USD 7,704.31 million in 2024 and is anticipated to reach USD 13,591.62 million by 2032, at a CAGR of 7.4% during the forecast period. North America holds around 23% share of the global market, driven by strong automotive production and high consumer preference for advanced safety technologies. The United States leads due to the presence of key OEMs and adoption of smart glass technologies. It benefits from rising integration of head-up displays and ADAS-enabled windshields in premium vehicles. Canada contributes through demand for replacement windshields and sustainable vehicle models. Mexico supports regional expansion with growing manufacturing capabilities and exports. Regulatory emphasis on road safety and energy efficiency encourages innovation across the supply chain.
Europe
The Europe Global Automotive Windshield Market size was valued at USD 6,607.01 million in 2018 to USD 9,533.93 million in 2024 and is anticipated to reach USD 16,685.22 million by 2032, at a CAGR of 7.3% during the forecast period. Europe accounts for nearly 28% of the total market share, supported by a strong automotive base and technological innovation. Germany, France, and the UK dominate due to luxury vehicle manufacturing and early adoption of smart glass. It benefits from regulations favoring laminated safety glass and low-emission materials. The region’s focus on electric mobility drives demand for lightweight and energy-efficient windshields. Eastern Europe shows steady growth from rising vehicle production and infrastructure investment. High replacement demand in Western Europe reinforces aftermarket growth.
Asia Pacific
The Asia Pacific Global Automotive Windshield Market size was valued at USD 7,858.17 million in 2018 to USD 11,471.13 million in 2024 and is anticipated to reach USD 20,390.41 million by 2032, at a CAGR of 7.5% during the forecast period. Asia Pacific commands the largest market share of about 34%, driven by rapid industrialization and expanding automotive production. China leads the region with strong domestic manufacturing and rising electric vehicle penetration. Japan and South Korea contribute through advanced materials and R&D innovations. India’s growing automotive sector and rising disposable income enhance demand for affordable safety glass. Southeast Asia is emerging as a hub for automotive component manufacturing. It benefits from favorable government policies and international collaborations.
Latin America
The Latin America Global Automotive Windshield Market size was valued at USD 1,455.47 million in 2018 to USD 2,312.49 million in 2024 and is anticipated to reach USD 4,554.29 million by 2032, at a CAGR of 8.9% during the forecast period. Latin America holds an estimated 8% share of the global market, supported by vehicle modernization and aftermarket expansion. Brazil leads production due to its strong automotive infrastructure. Argentina and Mexico contribute through growing assembly plants and imports of advanced glass systems. It benefits from the increasing preference for laminated and solar-control glass in passenger vehicles. The aftermarket sector is expanding through urban growth and replacement demand. Regional economic recovery and improved financing options are strengthening new vehicle sales.
Middle East
The Middle East Global Automotive Windshield Market size was valued at USD 1,095.05 million in 2018 to USD 1,614.96 million in 2024 and is anticipated to reach USD 2,909.52 million by 2032, at a CAGR of 7.7% during the forecast period. The region contributes about 5% of the global market share, led by GCC countries with increasing luxury vehicle imports. It experiences growth through rising urbanization and higher disposable income levels. Demand for UV-protected and heat-resistant windshields is strong due to extreme climatic conditions. The market benefits from the expansion of regional manufacturing capabilities and distribution networks. Strategic partnerships with European and Asian suppliers enhance product availability. Saudi Arabia and the UAE lead demand through premium and commercial vehicle segments.
Africa
The Africa Global Automotive Windshield Market size was valued at USD 633.61 million in 2018 to USD 829.00 million in 2024 and is anticipated to reach USD 1,246.94 million by 2032, at a CAGR of 5.3% during the forecast period. Africa represents nearly 2% share of the global market, supported by increasing vehicle imports and rising urban mobility. South Africa leads with its established automotive industry and growing local production. Egypt and Nigeria are emerging markets with expanding aftermarket demand. It benefits from rising awareness of vehicle safety and durability. Limited manufacturing infrastructure remains a challenge but creates opportunities for investment. Growing partnerships with international OEMs are expected to strengthen supply chains and regional presence.
Key Player Analysis:
- Corning
- AGC Inc.
- Fuyao Group
- PPG
- Dura Automotive
- Vitro
- Guardian Glass
- Saint-Gobain
- Nippon Glass
- Asahi Glass
Competitive Analysis:
The Global Automotive Windshield Market is characterized by intense competition among global and regional manufacturers. Leading players focus on innovation, lightweight materials, and smart windshield integration to strengthen market position. Strategic mergers, collaborations, and investments in R&D are expanding product portfolios and geographic reach. It is witnessing high investment in advanced laminated, tempered, and solar-control glass technologies to meet rising safety and efficiency standards. Companies are aligning with OEMs to develop customized solutions for electric and autonomous vehicles. The market remains technology-driven, with firms competing on durability, design precision, and optical clarity.
Recent Developments:
- In October 2025, Corning expanded its technology collaboration with GlobalFoundries to develop advanced glass-waveguide-based solutions for photonic integrated circuits, furthering its impact on smart and connected automotive applications. Additionally, Corning launched a new generation of Gorilla Glass Ceramic for vehicle applications earlier in 2025, which is positioned to offer enhanced durability and transparency for automotive windshields.
- In September 2025, Fuyao Glass Industry Group unveiled an innovative front windshield integrating LiDAR and camera sensors. This new product, which debuted in the AITO M7 SUV, is designed to enhance intelligent driving features by improving near-infrared light transmittance and reducing signal attenuation.
Report Coverage:
The research report offers an in-depth analysis based on vehicle type, application, and type segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising integration of smart and connected windshield technologies across vehicle models.
- Increasing adoption of laminated and solar-control glass for enhanced safety and efficiency.
- Expansion of electric and autonomous vehicles boosting demand for specialized windshields.
- Strong growth in Asia-Pacific supported by large-scale vehicle manufacturing.
- Aftermarket services gaining traction with digital repair and calibration systems.
- Advancements in lightweight and sustainable glass manufacturing processes.
- Strategic partnerships between OEMs and glass producers to enhance innovation.
- Growing consumer demand for noise reduction and temperature control features.
- Regulatory support promoting eco-friendly windshield production standards.
- Continuous R&D investment driving new materials and digital display integration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Vehicle Production and Safety Standards
Increasing global vehicle production, especially in emerging markets, and stricter safety regulations are driving demand for advanced windshields that offer better occupant protection and visibility. Automakers are adopting laminated and tempered glass to comply with safety mandates and consumer expectations.
Adoption of Smart and Connected Windshield Technologies
The integration of sensors, cameras, and head-up displays into windshields is enhancing vehicle intelligence and safety. OEMs are increasingly equipping vehicles with smart windshields to support ADAS features, boosting demand for technologically advanced glass solutions.
Growth in Electric and Autonomous Vehicles
The shift toward electric and autonomous vehicles is creating new requirements for lightweight, thermally efficient, and sensor-compatible windshields. This trend is accelerating innovation in glass materials and coatings to improve energy efficiency and support advanced vehicle functions.
Aftermarket Expansion and Replacement Demand
A growing global vehicle fleet and increased focus on vehicle maintenance are fueling the replacement windshield market. Higher rates of windshield damage from road debris and accidents, along with improved insurance coverage and digital service networks, are making replacements more accessible and frequent.
Focus on Lightweight and Sustainable Manufacturing
Automakers' emphasis on reducing vehicle weight for fuel efficiency and emissions reduction is driving the adoption of thinner, stronger, and more sustainable windshield materials. Regulatory and consumer pressure for eco-friendly production is encouraging innovation in recycled glass and energy-efficient manufacturing processes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Automotive Windshield Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Automotive Windshield Market projected to grow between 2025 and 2032?
Which Global Automotive Windshield Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Automotive Windshield Market?
Who are the leading companies in the Global Automotive Windshield Market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Laminated
- 1.2.2 Tempered
- 1.3 By Application
- 1.3.1 Front Windshields
- 1.3.2 Rear Windshields
- 1.4 By Vehicle Type
- 1.4.1 Passenger Cars
- 1.4.2 Heavy Commercial Vehicles (HCVs)
- 1.4.3 Light Commercial Vehicles (LCVs)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 22,957.0 million → 2032: USD 59,378.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Windshield Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Windshield Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Windshield Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Windshield Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Windshield Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Windshield Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Windshield Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Windshield Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 22,957.0 million → 2032: USD 59,378.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Windshield Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Laminated
- 12.3.7.2 Tempered
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Front Windshields
- 12.4.7.2 Rear Windshields
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Cars
- 12.5.7.2 Heavy Commercial Vehicles (HCVs)
- 12.5.7.3 Light Commercial Vehicles (LCVs)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Windshield End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automotive Windshield Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automotive Windshield Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automotive Windshield Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Corning
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 AGC Inc.
- 18.4 Fuyao Group
- 18.5 PPG
- 18.6 Dura Automotive
- 18.7 Vitro
- 18.8 Guardian Glass
- 18.9 Saint-Gobain
- 18.10 Nippon Glass
- 18.11 Asahi Glass
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

