
Second-axle hardware shifts from shafts to motors
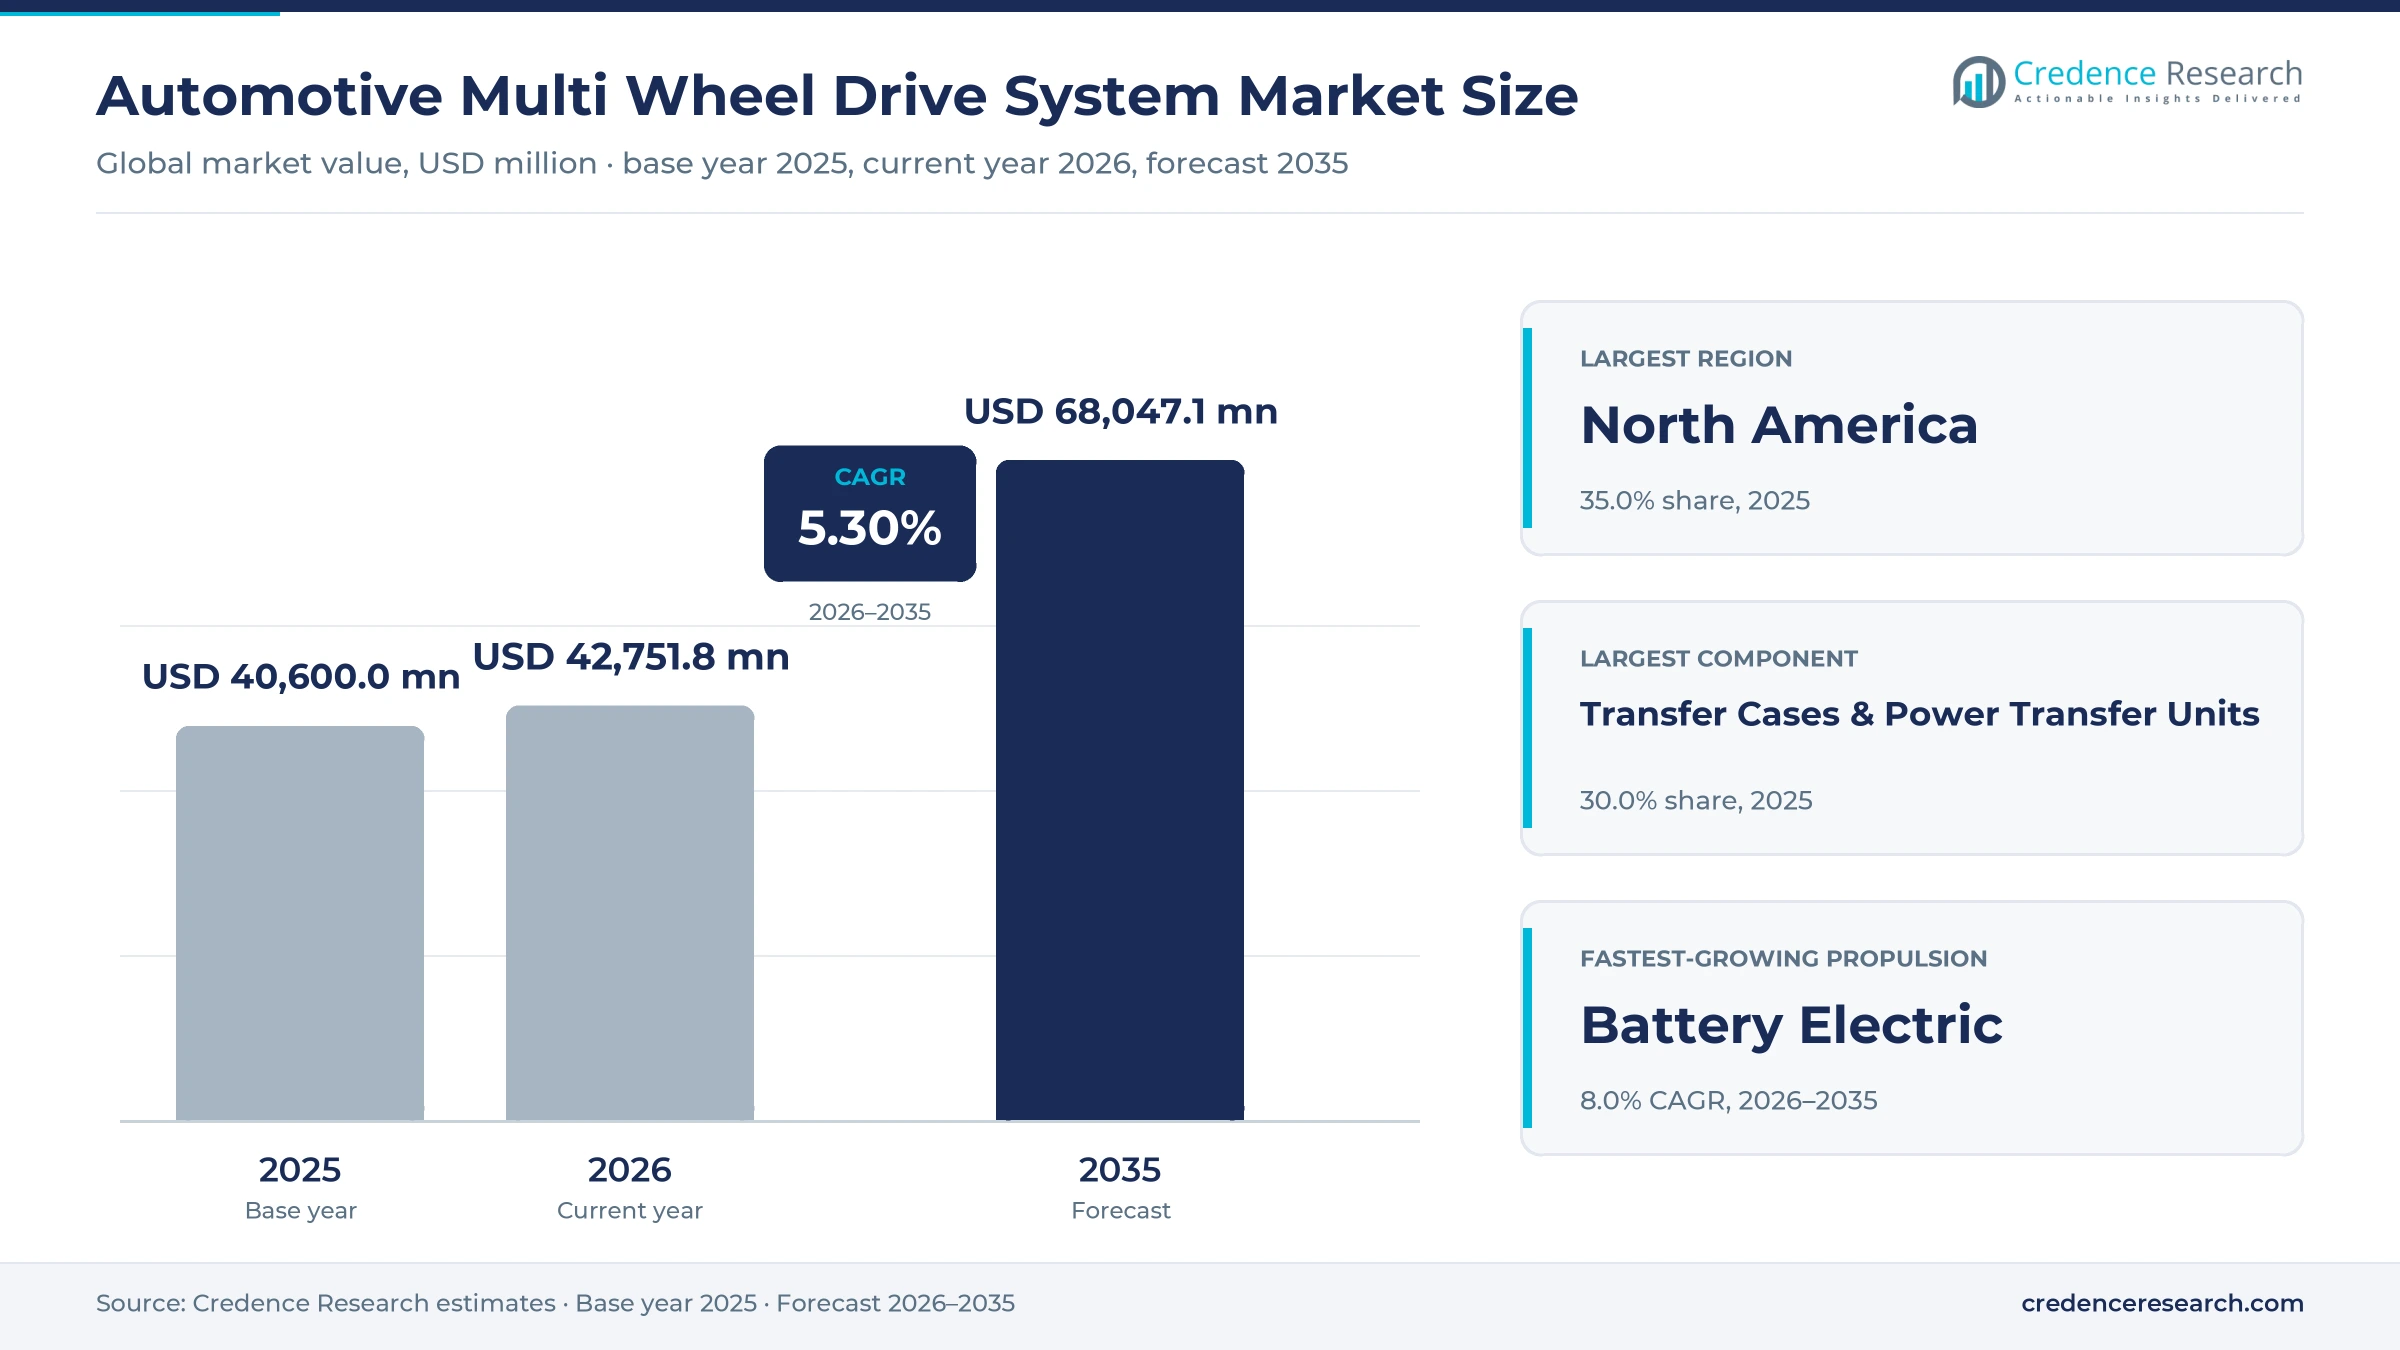
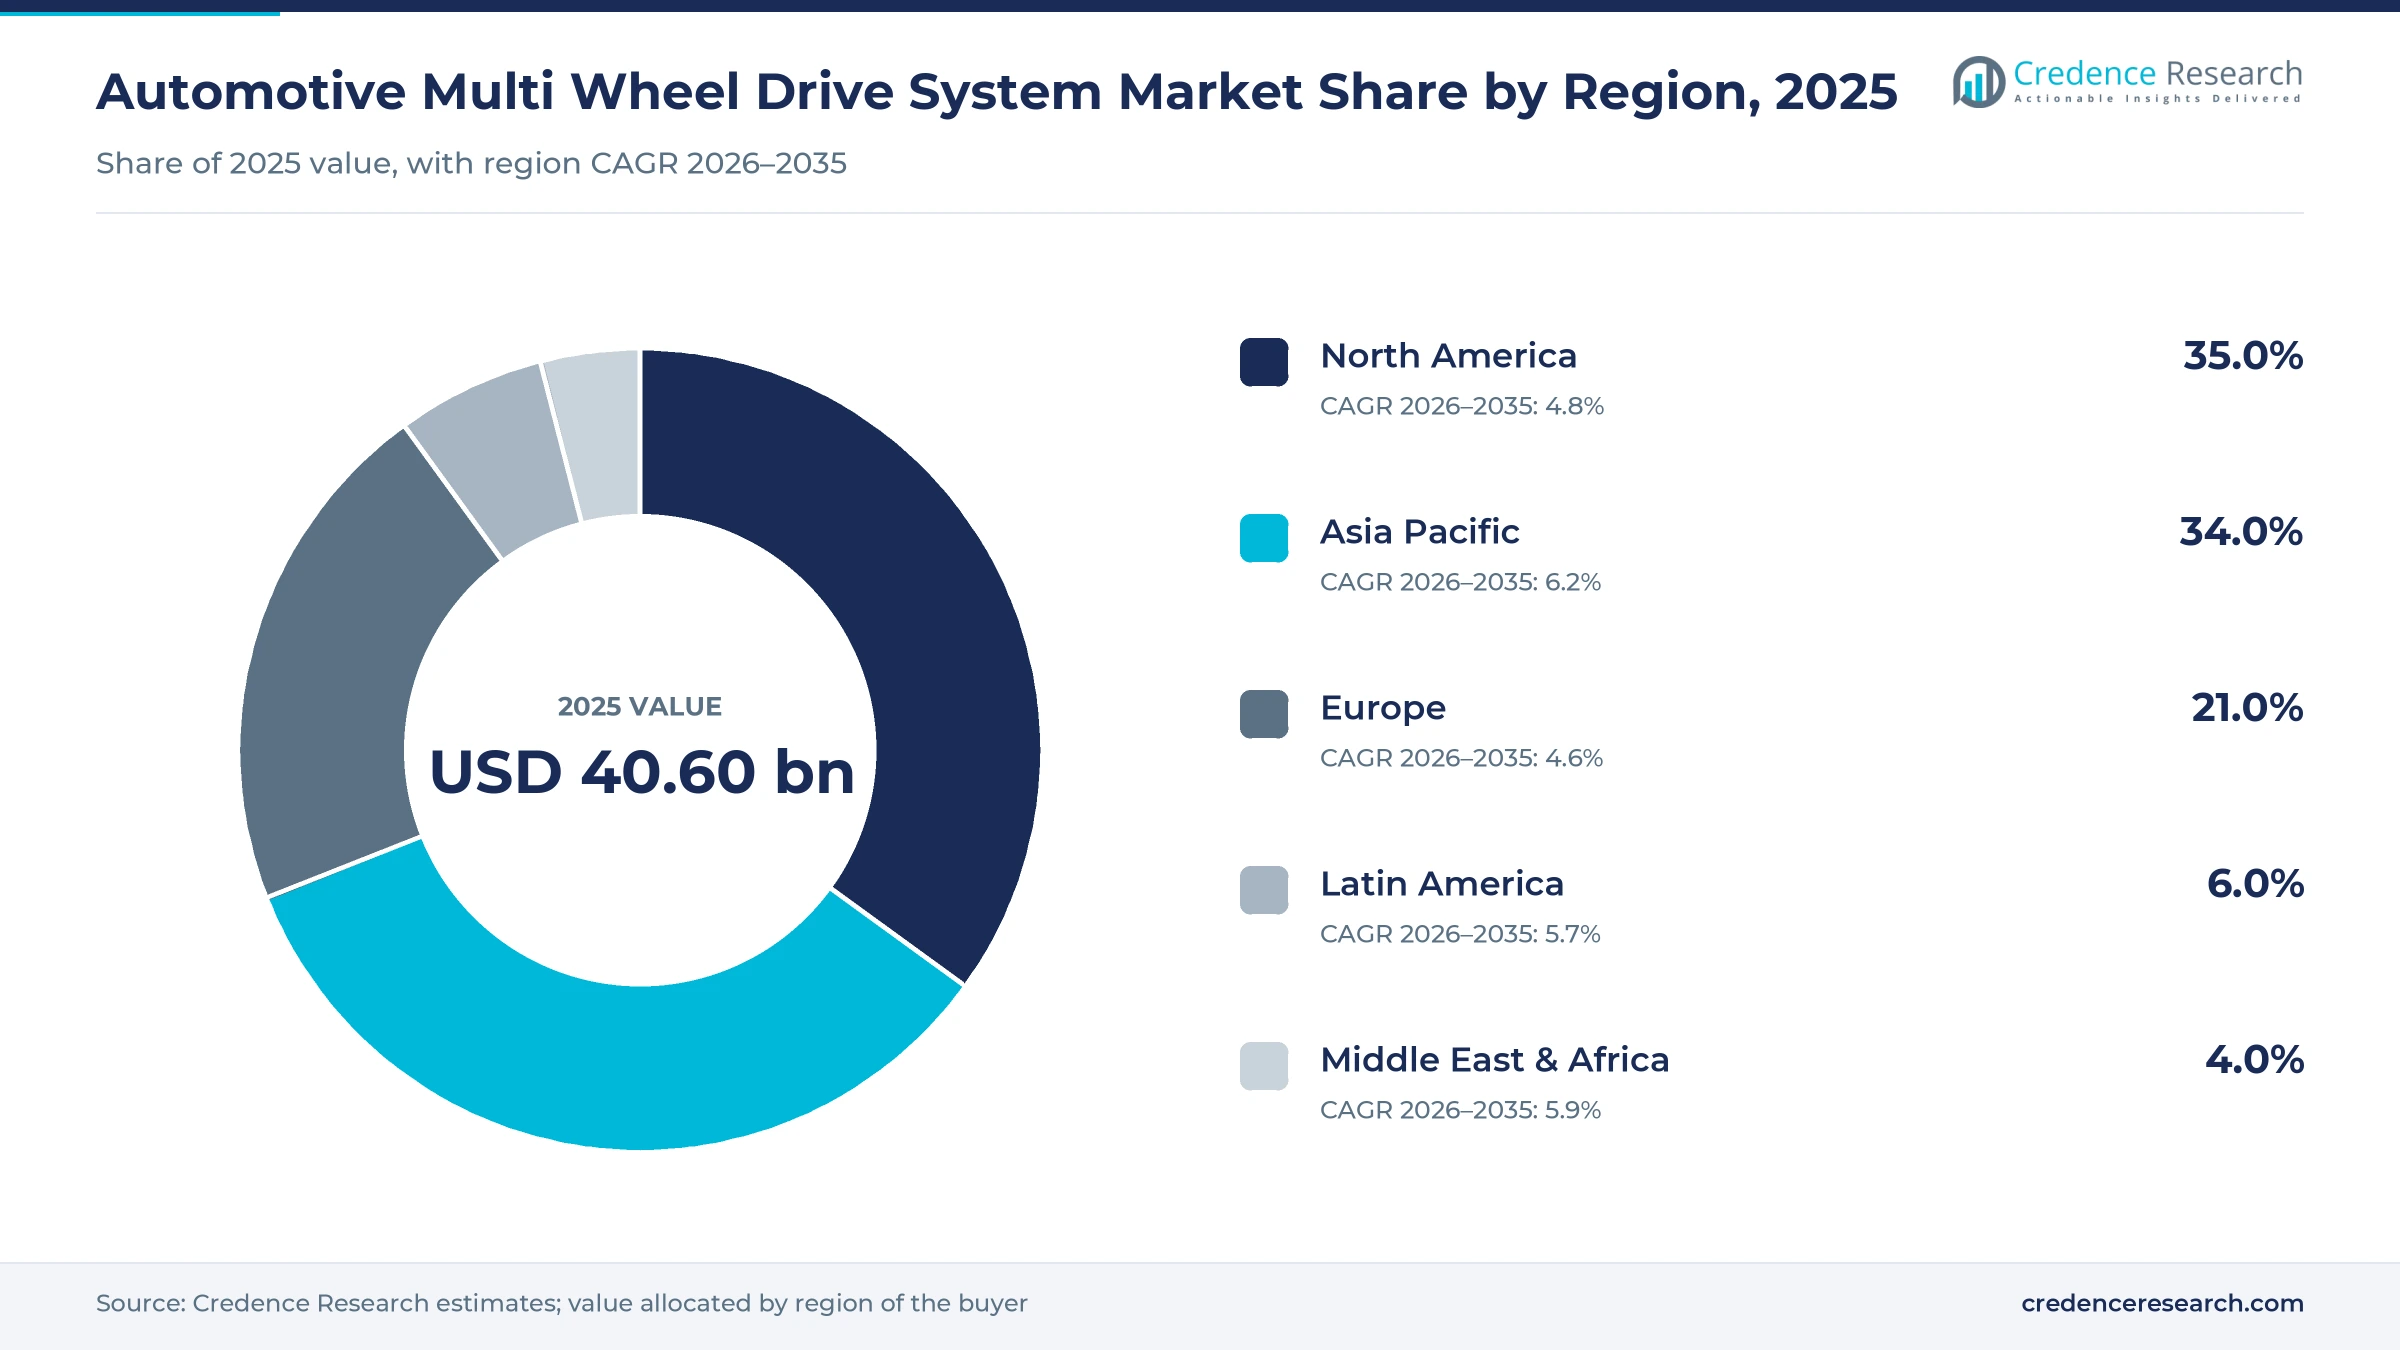
The global automotive multi wheel drive system market was valued at USD 40.60 billion in 2025 and is projected to increase from USD 42.75 billion in 2026 to USD 68.05 billion by 2035, registering a CAGR of 5.30% during 2026–2035. Demand comes from pickups, SUVs and crossovers that carry all-wheel or four-wheel drive as standard or as an option, and from battery electric and hybrid models that add a second motor on the other axle. North America held the largest regional share, 35.0% in 2025, because truck-based vehicles dominate U.S. production and most of them drive both axles. Asia Pacific is the fastest-growing region at 6.2% a year, as Chinese automakers fit electric four-wheel drive to new energy vehicles and Indian buyers shift toward utility vehicles. Suppliers are moving value from mechanical transfer cases and propeller shafts to secondary-axle electric drive modules. The added cost of a second axle still limits fitment on entry-level cars.
Why is the second motor replacing the propeller shaft?
The estimate counts the hardware that sends torque to a second axle, including transfer cases, power transfer units, electronically controlled couplings, differentials, propeller shafts, secondary-axle electric drive modules and the control units that manage them. Automakers buy these systems per platform from a small group of driveline suppliers, usually several years before a vehicle enters production.
Complete vehicles, primary drive units on two-wheel-drive models and off-highway machinery fall outside the scope. Because a single award covers a platform for its full life, the outcome of sourcing decisions on new pickups, SUVs and electric architectures decides supplier volume for most of the decade.
Automotive Multi Wheel Drive System Market Insights
- The market is valued at USD 40.60 billion in 2025 and is projected to reach USD 68.05 billion by 2035, growing at a 5.30% CAGR as electric second axles add value per vehicle.
- North America led with 35.0% of 2025 value, because 59% of U.S. light vehicles produced in 2022 had all-wheel or four-wheel drive.
- Transfer Cases & Power Transfer Units held 30.0% of 2025 value, since pickups and body-on-frame SUVs still route torque through a mechanical transfer case.
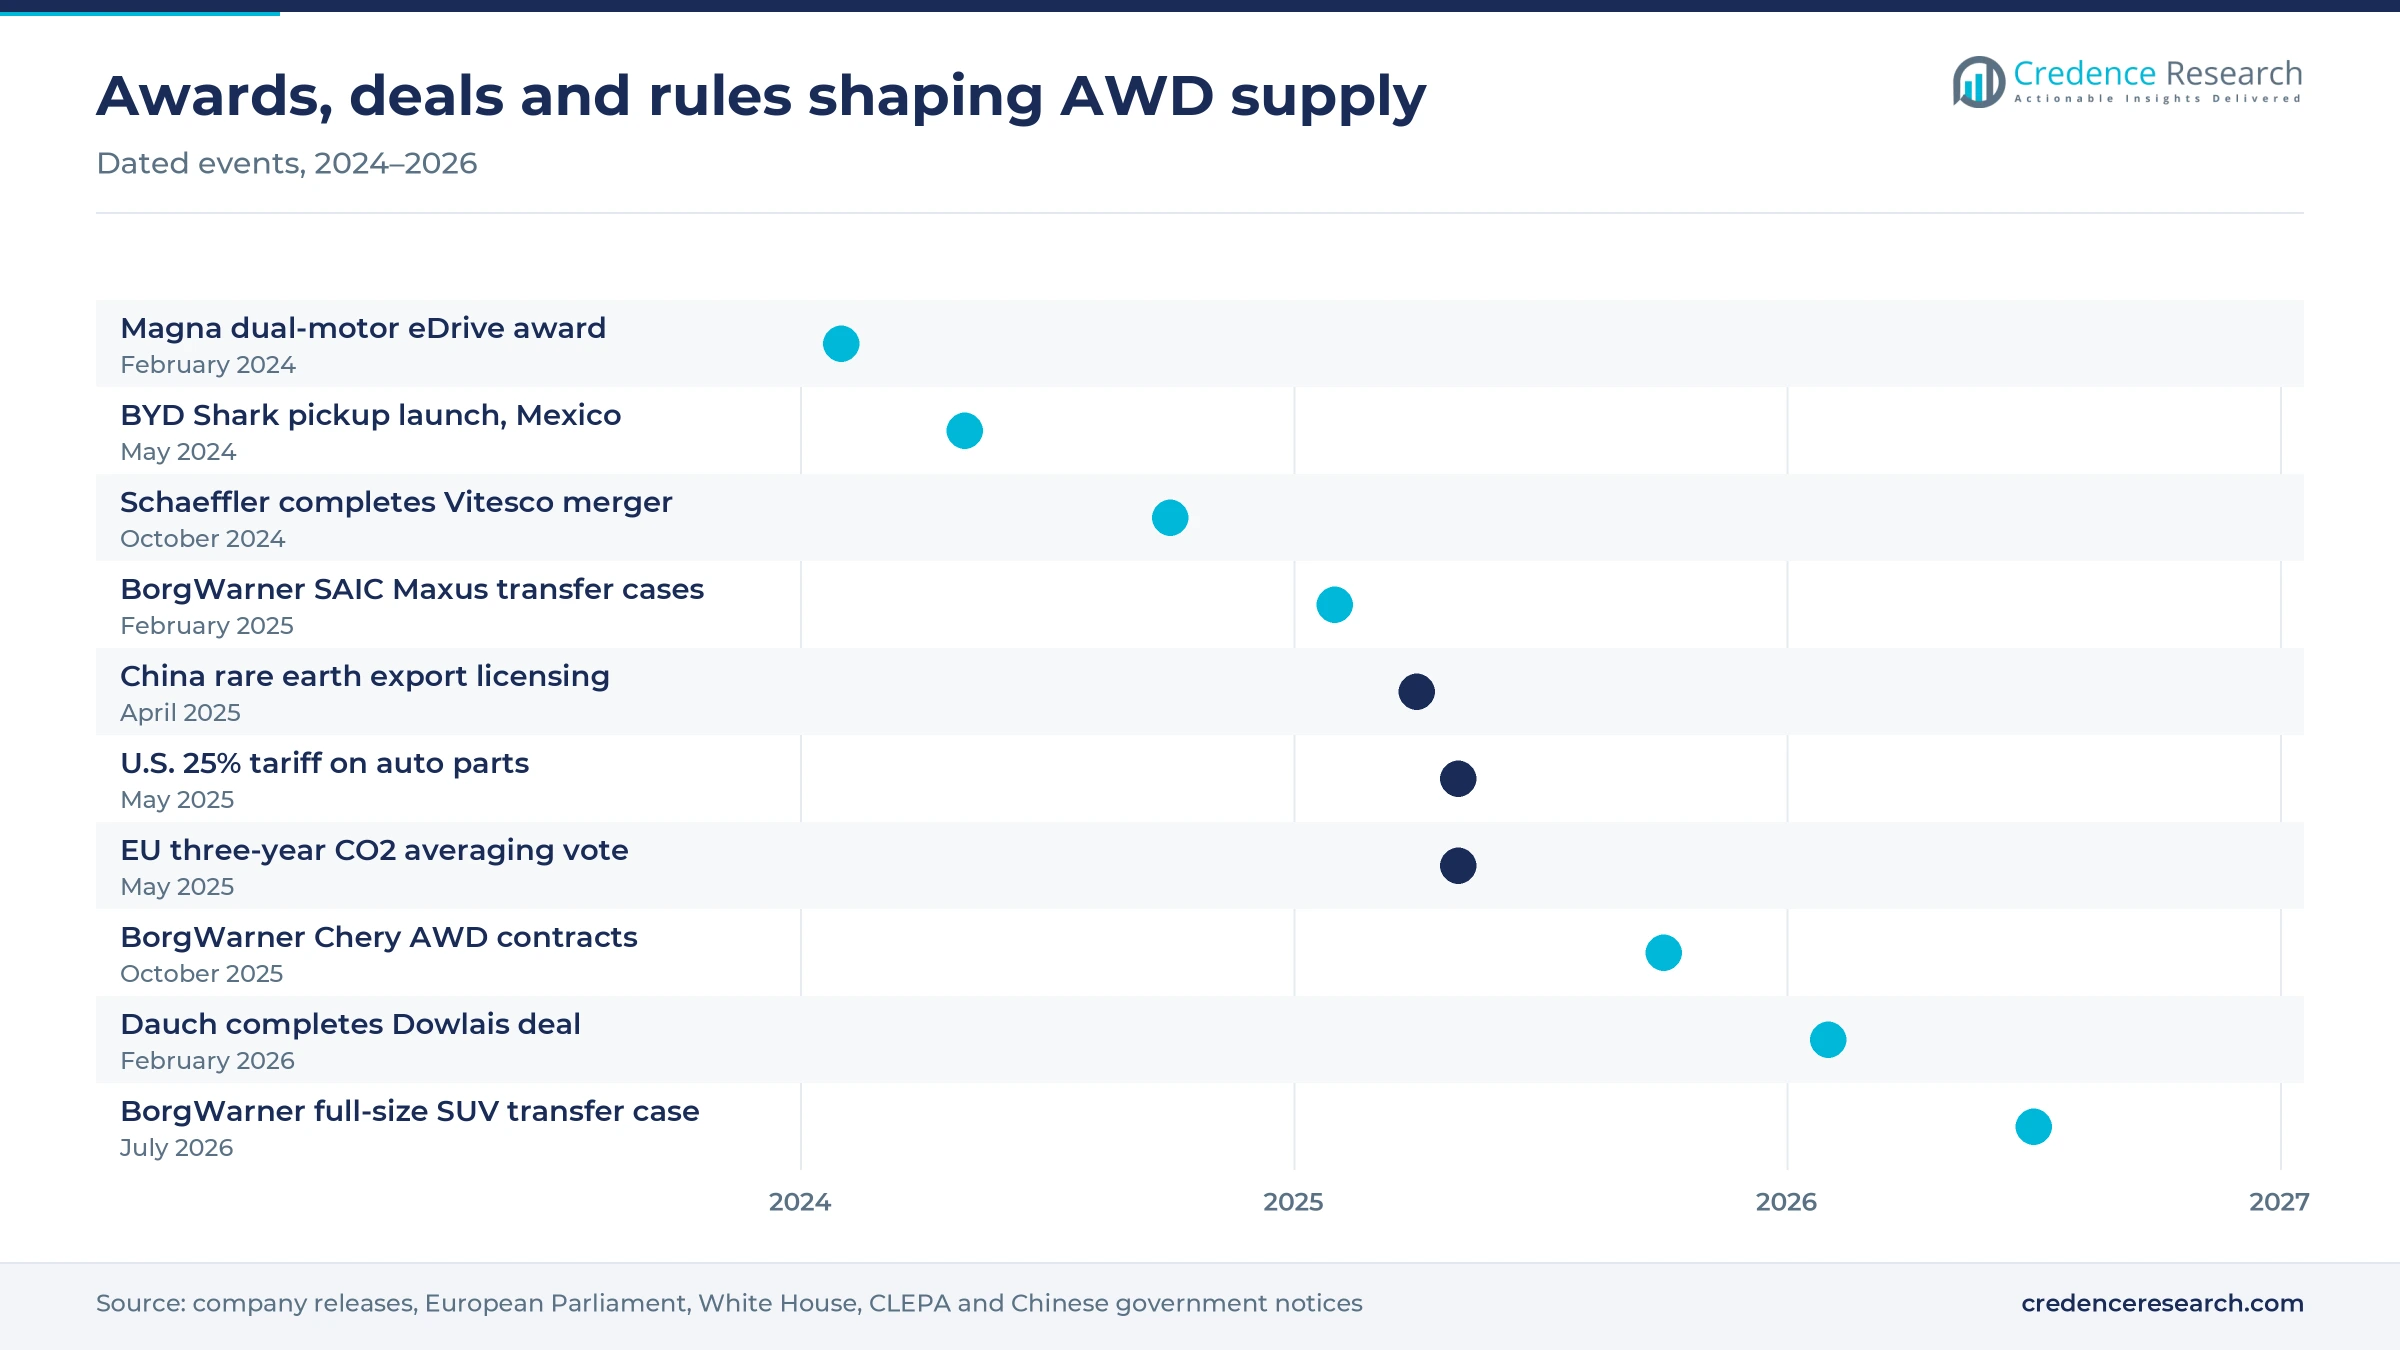
- In February 2026, Dauch Corporation, the former American Axle & Manufacturing, completed its acquisition of Dowlais Group and with it GKN Automotive.
- In July 2026, BorgWarner won a transfer case award for a new full-size SUV from a Chinese automaker, with production planned for the fourth quarter of 2026.
Transfer cases lead while electric drive modules gain
Pickup transfer cases anchor value as e-drive modules gain
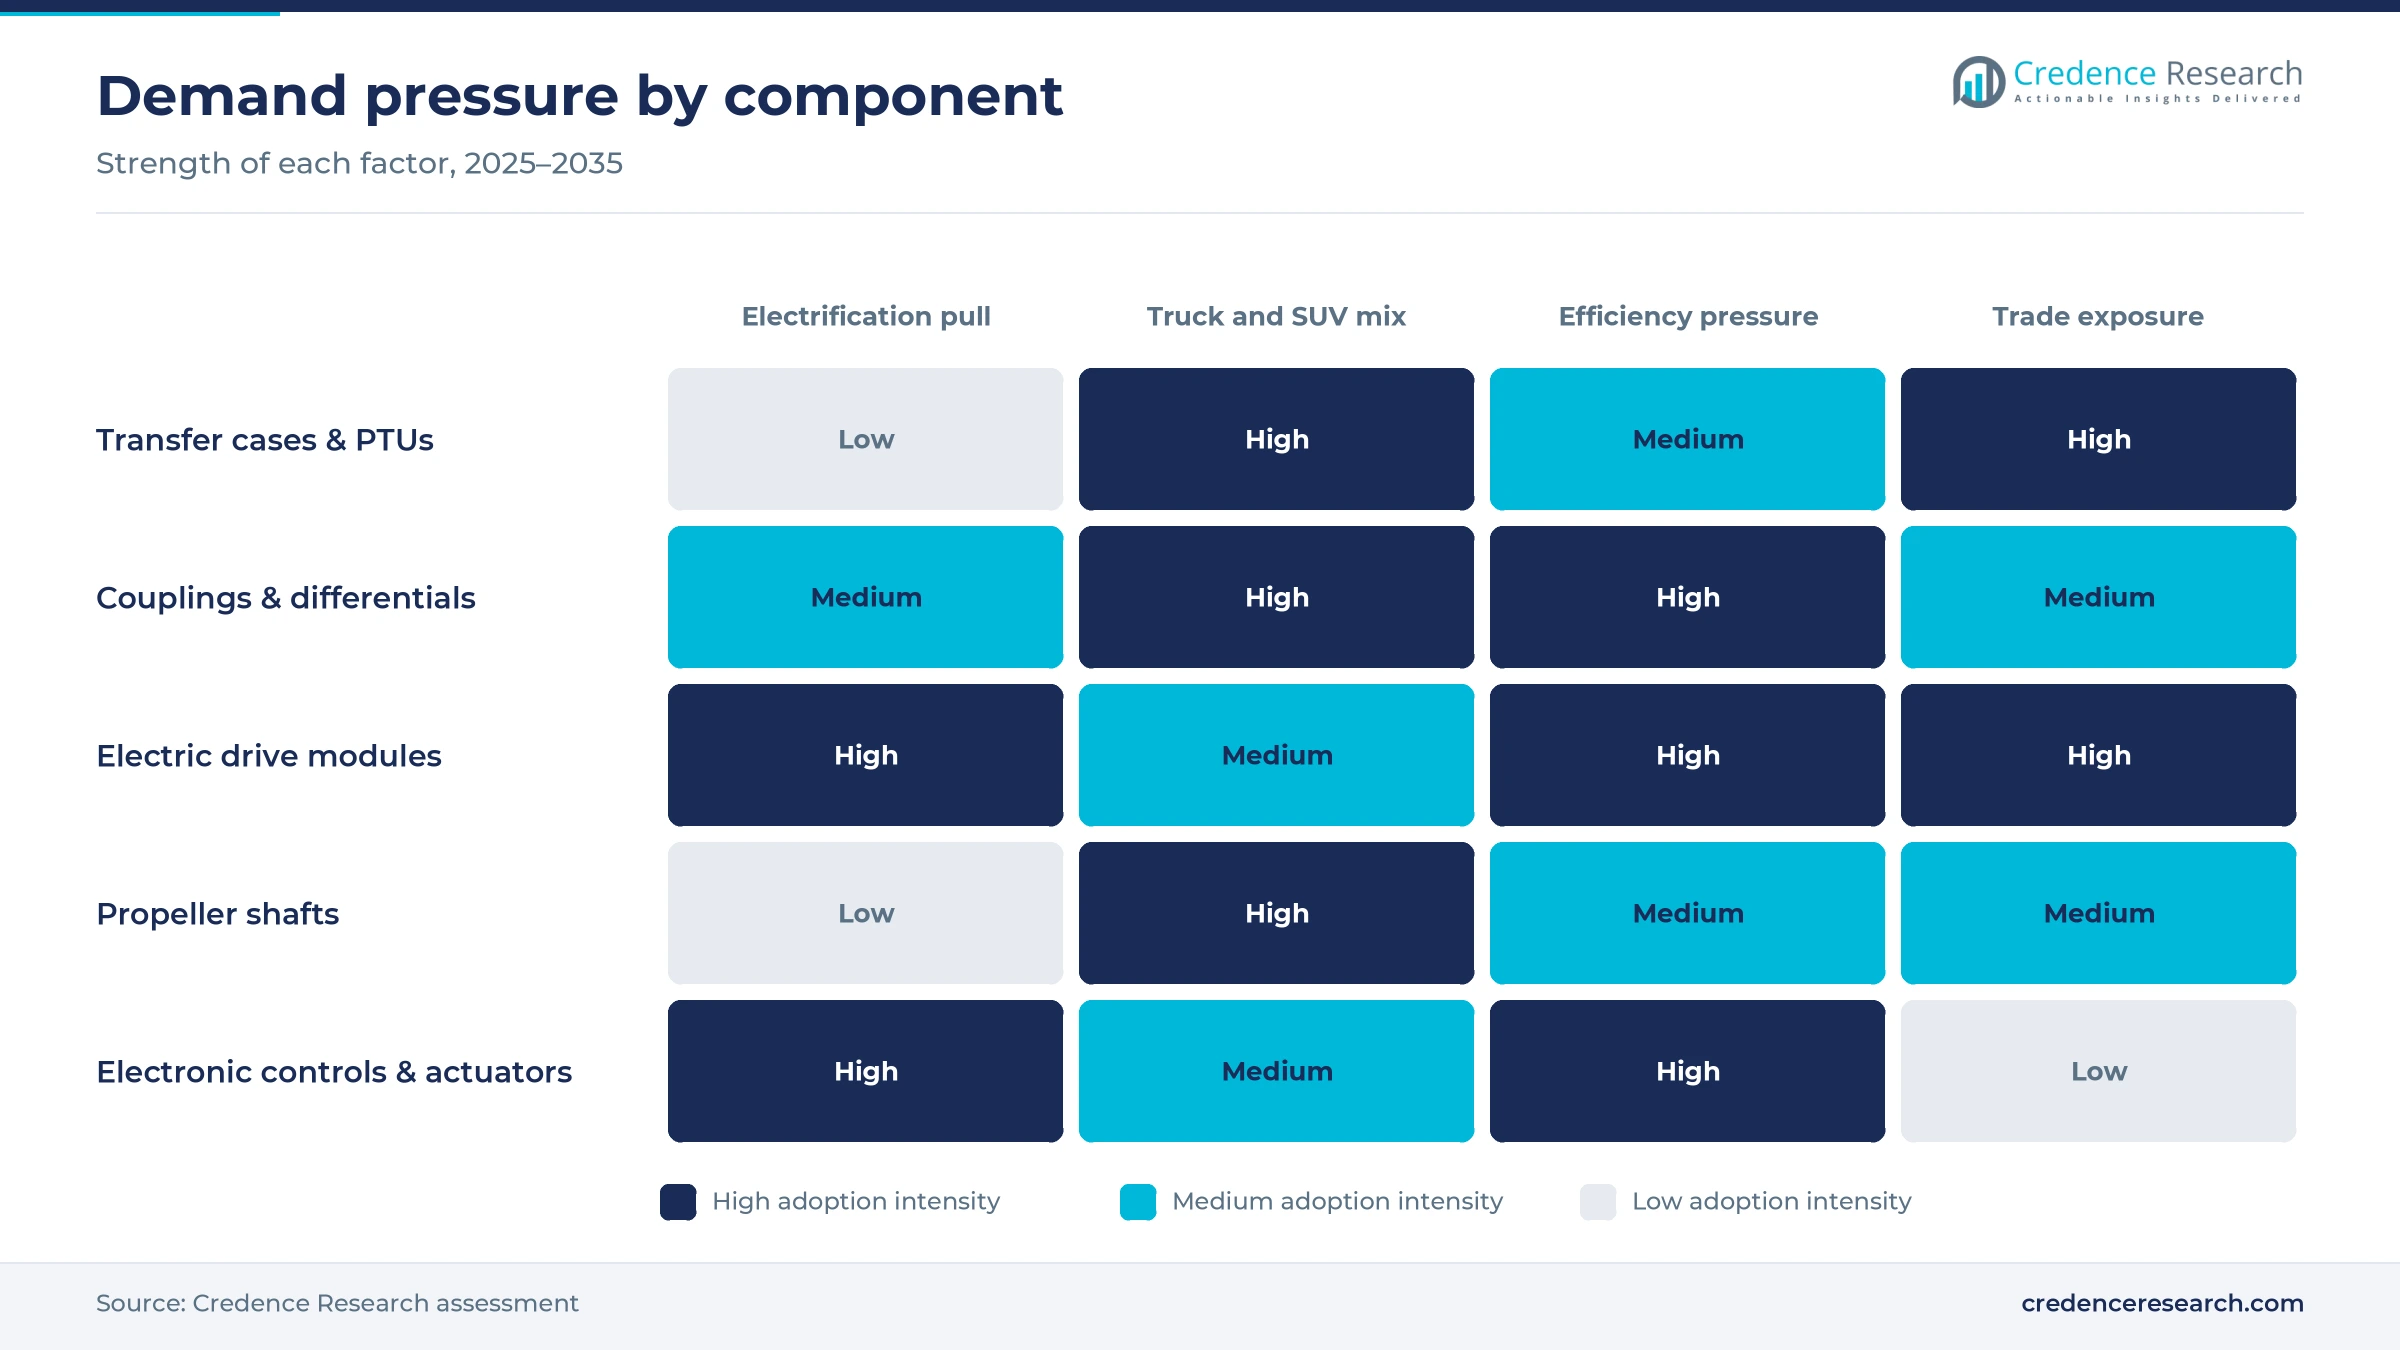
Based on component, the market is categorized into transfer cases & power transfer units, couplings & differentials, electric drive modules, propeller shafts and electronic controls & actuators. Transfer Cases & Power Transfer Units led with 30.0% of 2025 value because full-size pickups and SUVs still need a transfer case, and BorgWarner said it won a torque-on-demand transfer case award for a new full-size SUV from a Chinese automaker in July 2026, with production planned for the fourth quarter. Electric Drive Modules grow fastest at 7.2% a year as automakers replace the shaft with a motor, and Magna announced a 726 kW, 8,000 Nm dual-motor rear eDrive award from a North American automaker in February 2024.
Combustion trucks hold the base while dual-motor EVs add content
Based on propulsion type, the market is categorized into internal combustion engine, hybrid & plug-in hybrid and battery electric vehicles. Internal Combustion Engine models led with 58.0% of 2025 value because truck SUVs alone made up 50% of all new U.S. vehicle production in model year 2024, according to the EPA Automotive Trends Report. Battery Electric models grow fastest at 8.0% a year as a dual-motor layout adds a complete drive module rather than a shaft, and the EV sales growth noted in the drivers section enlarges that base each year.
Factory fitment dominates because torque control is calibrated in development
Based on sales channel, the market is categorized into OEM and aftermarket. OEM supply led with 89.0% of 2025 value and also grows fastest at 5.4% a year, because torque management is calibrated with the vehicle stability system during development. JTEKT, for example, described a new intelligent torque-controlled coupling engineered for rear-wheel-drive-based four-wheel-drive crossover SUVs in its 2023 engineering journal. Aftermarket value comes mainly from replacing worn transfer cases, couplings and seals on aging trucks and SUVs, which keeps it steady but slower, with a transfer case output shaft seal repair alone costing about USD 350, according to ConsumerAffairs in June 2026.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Component | Transfer Cases & Power Transfer Units | 30.0% | Electric Drive Modules | 7.2% |
| By Propulsion Type | Internal Combustion Engine | 58.0% | Battery Electric | 8.0% |
| By Sales Channel | OEM | 89.0% | OEM | 5.4% |
Buyers pay USD 1,400–3,900 extra to drive both axles
Automakers price all-wheel drive as a fixed option premium per trim, while the supplier bills the automaker per unit under a multiyear platform contract with annual price-down clauses. The premium a buyer sees depends on the architecture, since a mechanical system adds a power transfer unit, a shaft and a rear drive unit, while an electric vehicle adds a full motor and inverter. Toyota charges USD 1,400 for all-wheel drive on the 2026 RAV4 hybrid, against about USD 3,500 for the second motor on a 2026 Hyundai Ioniq 5. Suppliers earn the better margins on electronically controlled couplings and on aftermarket replacement units.
| Offer or repair | Typical price or fee | Basis |
|---|---|---|
| All-wheel drive option, 2026 Toyota RAV4 hybrid | USD 1,400 over front-wheel drive | Toyota pricing reported by Carscoops, November 2025 |
| Dual-motor all-wheel drive, 2026 Hyundai Ioniq 5 | USD 3,500 (SE, SEL) to USD 3,900 (Limited) over rear-wheel drive | Hyundai pricing reported by Automotive Fleet, October 2025 |
| Transfer case replacement, U.S. light vehicles | USD 2,000–9,000, average about USD 3,360 | ConsumerAffairs citing RepairPal estimates, June 2026 |
| Transfer case output shaft seal repair | About USD 350 | ConsumerAffairs, June 2026 |
| Conventional AWD hardware set sold to automakers | About USD 900–1,600 per vehicle | Credence Research estimate from retail option premiums less dealer and automaker margin |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Truck-heavy fleets, EVs and Asian SUVs lift AWD fitment
Truck-heavy U.S. production keeps both axles driven
The truck-heavy mix of U.S. production sustains the largest pool of multi-wheel-drive demand, because pickups and truck-based SUVs are usually sold with power to both axles. The U.S. Department of Energy reported that 59% of light-duty vehicles produced in 2022 had all-wheel or four-wheel drive, the most common drive type since 2017, citing EPA data. In model year 2024, 66% of new vehicles were classed as trucks under NHTSA rules, the EPA reported in February 2026, so trucks and truck-based SUVs set the volume base for driveline plants. Suppliers with North American transfer case and rear drive unit plants hold the most secure volume as long as this mix persists.
Electric platforms turn AWD into a second-motor decision
Electrification changes how automakers deliver all-wheel drive, because a battery electric model can add a motor on the second axle instead of a shaft and transfer unit. The IEA reported that global electric car sales exceeded 17 million in 2024, more than 20% of car sales, and expected more than 20 million in 2025. Electric cars accounted for almost half of all car sales in China in 2024, the IEA added. It projects electric cars at around 60% of Chinese car sales in 2025, the market where dual-motor layouts spread fastest. Suppliers that can deliver motor, inverter and gearbox as one module gain content per vehicle that mechanical specialists cannot match.
Utility vehicles take over Asian showrooms
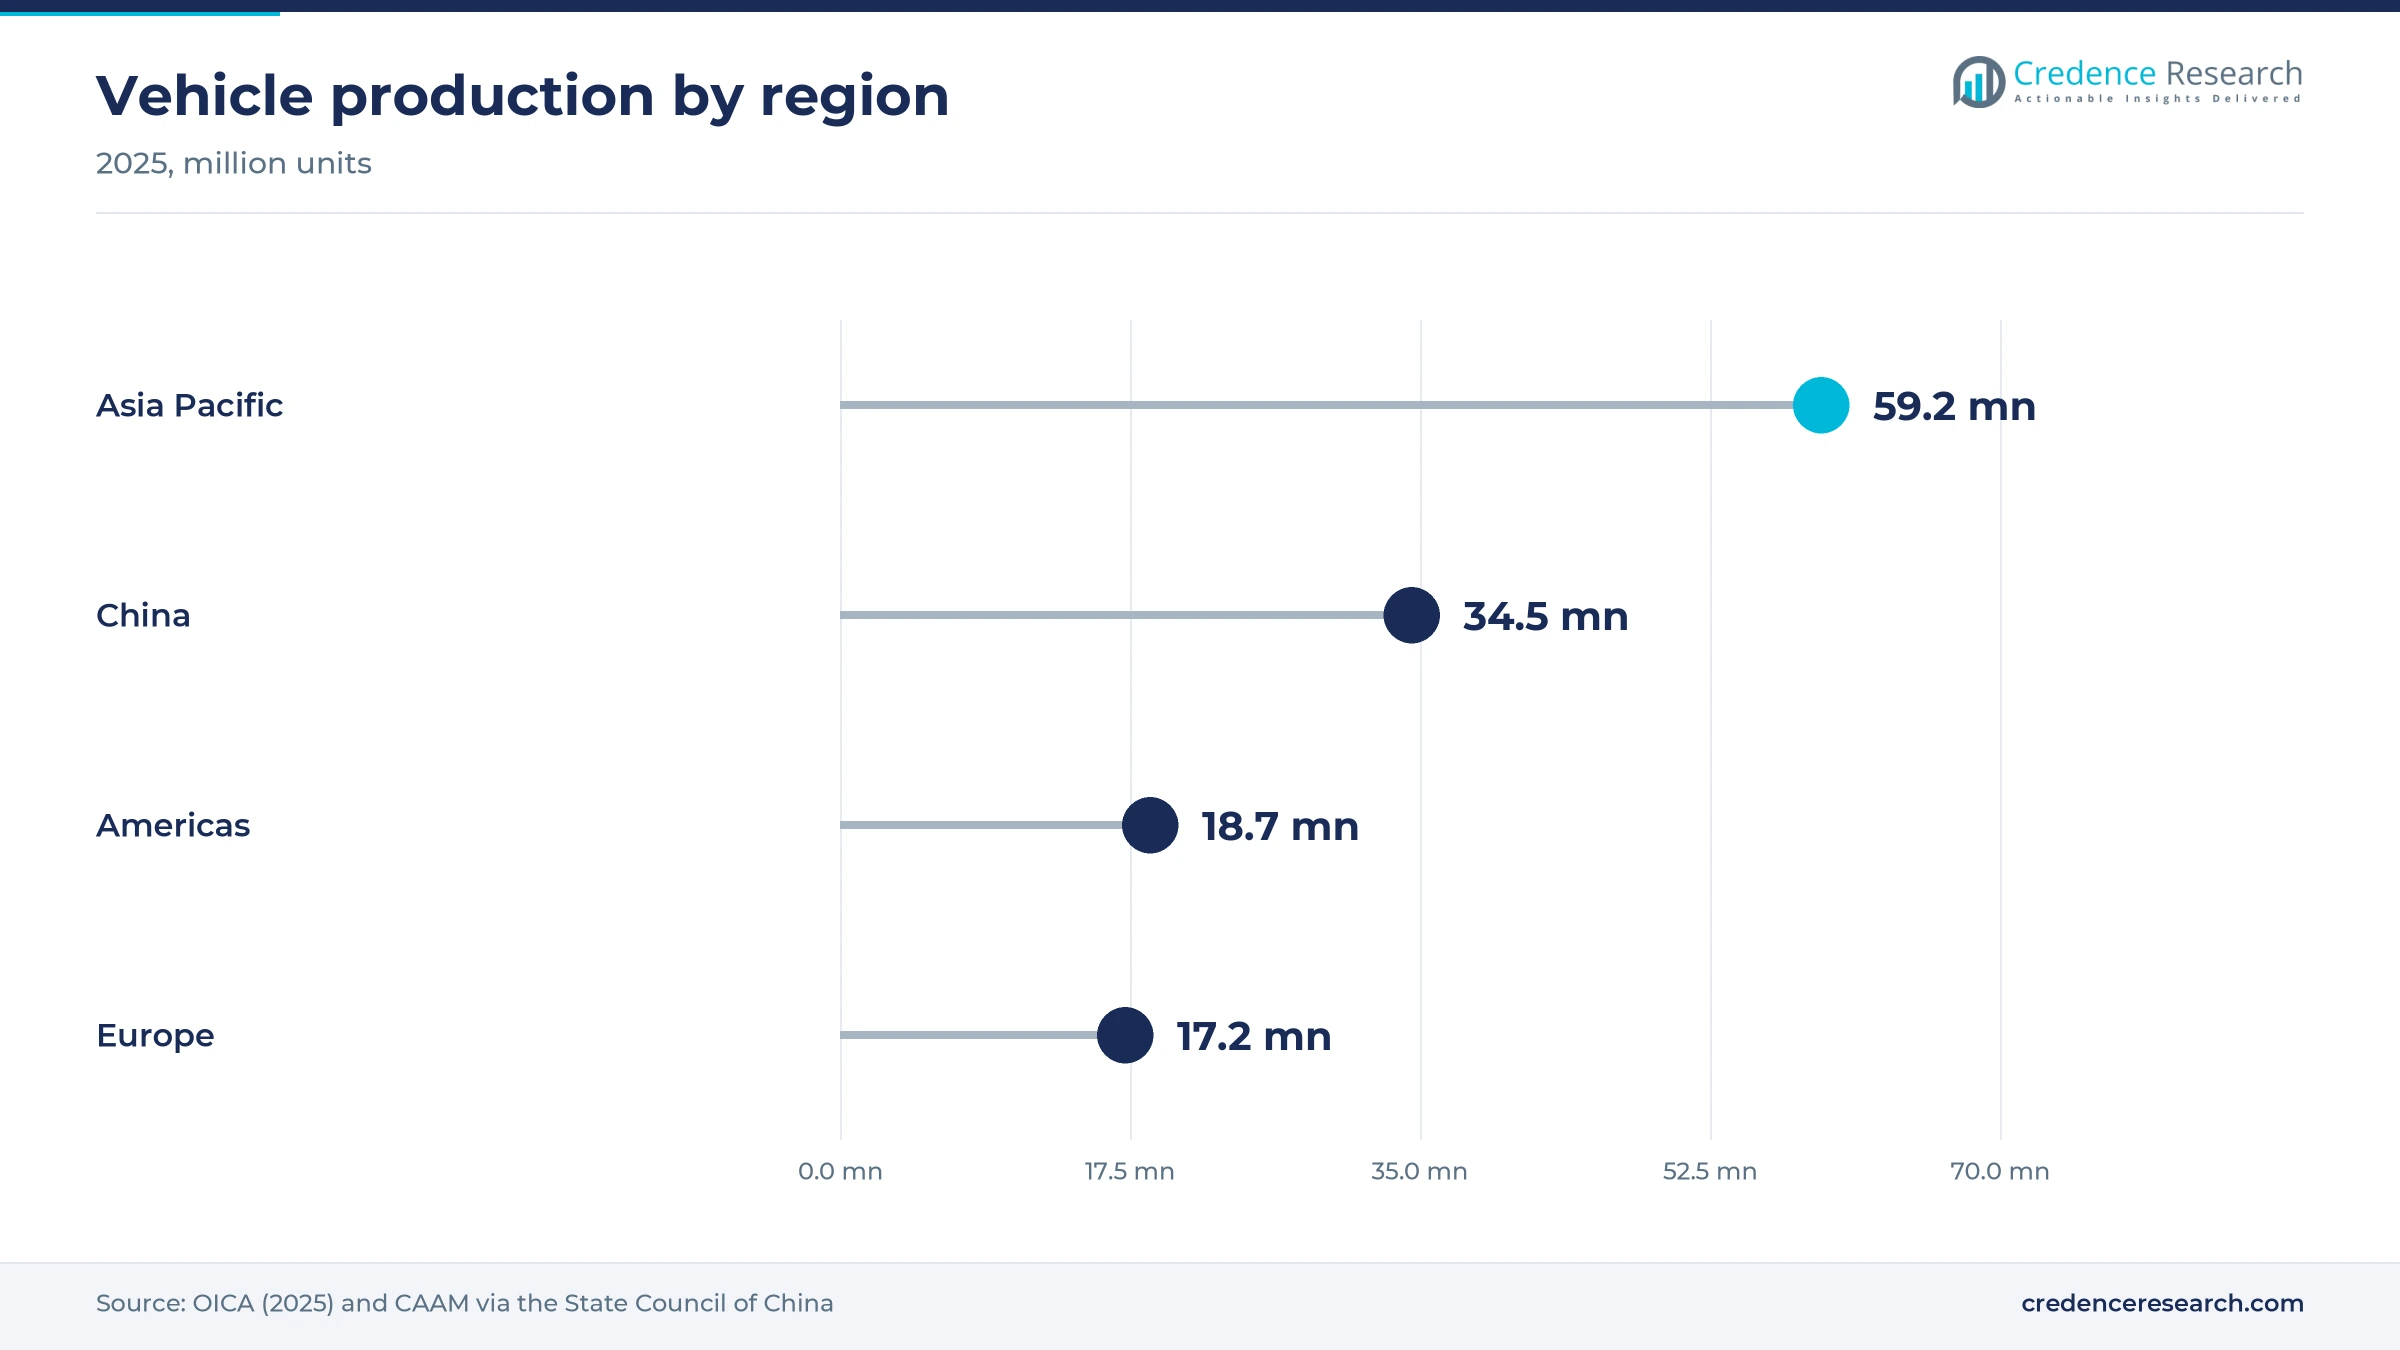
The shift of Asian buyers toward utility vehicles widens the base of models engineered for all-wheel drive. Utility vehicles reached 66% of Indian passenger vehicle wholesales in calendar 2025, or 2.95 million units, up from 33% in 2019, Autocar Professional reported from industry data. Asia Pacific produced about 59.2 million vehicles in 2025, more than 61% of global output, according to OICA. Only part of this fleet drives both axles today, so regional demand rises faster than vehicle output as fitment climbs from a low base. Suppliers that can localize couplings and transfer cases at Asian cost levels stand to win most of these programs.
Chinese exporters source four-wheel-drive hardware
Chinese automakers expanding abroad with pickups and SUVs are buying proven four-wheel-drive hardware, because export buyers judge these vehicles on towing and off-road ability. BorgWarner announced an agreement in February 2025 to supply two transfer cases made in China for SAIC Maxus export models, with mass production expected in 2026. In October 2025, it extended its Chery business to an Mlock torque-on-demand transfer case for pickups and a Gen VI coupling with an electronic limited-slip differential for SUVs, with mass production scheduled for 2027. These awards show that established suppliers can still win Chinese programs where in-house electric drives do not cover rugged use.
Disconnects, hybrid AWD and electric pickups gain ground
Axle disconnects cut the efficiency penalty of AWD
Automakers are shifting toward systems that decouple the secondary axle when traction is not needed, to address the drag that full-time all-wheel drive adds to fuel use and electric range. Dana says its SmartConnect disconnecting axle on the Ford Edge platform delivers up to a 45% reduction in energy loss compared with a typical axle. Hyundai Transys developed an electric vehicle AWD disconnector for the E-GMP platform and the Ioniq 5 line, citing a 6% to 8% efficiency gain, in June 2021. Magna launched production of an eDecoupling unit in Lannach, Austria, in August 2023 for a German premium automaker, citing up to 9% more range. Suppliers with in-house clutch and actuator designs gain content that a simple shaft supplier cannot offer.
Hybrid all-wheel drive gains share in China
Hybrid powertrains are shifting the delivery of all-wheel drive toward an electric rear axle paired with an engine, which creates openings for compact motors and couplings in SUVs and pickups. The IEA reported that plug-in hybrids rose to nearly 30% of Chinese electric car sales in 2024, while extended-range models passed 10%. Toyota made the 2026 RAV4 a hybrid-only line, with all-wheel drive available on every trim in the United States, Carscoops reported in November 2025. Hybrid buyers keep the fuel tank yet gain electric traction on slippery roads and in towing. Suppliers with both mechanical and electric axle products are best placed, because the same platform often carries combustion, hybrid and electric versions.
Electric pickups open full-time electric 4WD
Electric pickups and work vehicles create a new opening for full-time electric four-wheel drive, because towing and off-road users need torque at both axles at all times. The Isuzu D-MAX EV, which went into production in April 2025, uses front and rear eAxles in a full-time 4WD system developed by BluE Nexus, Aisin and Denso, with shipments starting in major European countries. Kelley Blue Book put the average price paid for a full-size pickup at USD 66,386 in December 2025, which leaves room for costly dual-motor hardware. Suppliers able to rate e-axles for payload and towing can win these programs early.
Aging AWD fleets need replacement units
The large installed base of all-wheel-drive and four-wheel-drive vehicles opens a service opportunity for remanufactured and replacement units, because couplings, seals and transfer cases wear with mileage and towing. ConsumerAffairs, citing RepairPal estimates in June 2026, put an average U.S. transfer case replacement at about USD 3,360. Parts made up 70% to 90% of that cost, which shifts most of the value to the component supplier rather than the workshop. Brands with remanufacturing programs and wide part catalogs gain recurring revenue as the 2017 to 2025 U.S. production years age. Independent workshops also favor remanufactured units when the vehicle value no longer justifies a new dealer part.
Magnets, tariffs and price premiums squeeze suppliers
Rare earth licensing threatens e-axle supply
China's licensing of rare earth exports from April 2025 exposed makers of permanent-magnet motors for secondary axles. In June 2025, the European supplier association CLEPA said several production lines had shut down and only about a quarter of hundreds of licence requests had been granted. China suspended its wider October 2025 controls through Nov. 10, 2026, and public confirmation of the regime after that date was not found. E-axle suppliers without magnet stocks or alternative motor designs remain the most exposed.
U.S. tariffs raise the cost of imported driveline parts
U.S. tariffs raise the landed cost of imported transfer cases, power transfer units and drive modules. A March 2025 proclamation set a 25% duty on key automobile parts, including powertrain parts, to start no later than May 3, 2025, while USMCA-compliant parts stayed duty-free pending a process to tax their non-U.S. content. Suppliers that ship Asian-made units into U.S. assembly plants carry the largest exposure. Automakers can respond by resourcing to North American plants, which favors suppliers with local capacity.
Dual-motor premiums deter price-sensitive buyers
The cost of a second motor limits electric all-wheel-drive fitment among price-sensitive buyers. Hyundai priced its 2026 Ioniq 5 at about USD 3,500 more for all-wheel drive on SE and SEL trims and USD 3,900 more on the Limited after its October 2025 price cuts. That premium is more than double the USD 1,400 option noted for the RAV4 hybrid. Entry buyers in China, India and Latin America are the most likely to choose the single-motor version, which caps module volume.
Western production slips while Asia expands
Production is moving away from the regions where most mechanical AWD plants sit, which exposes suppliers with Western capacity. OICA reported that Americas output fell 2.1% to 18.74 million vehicles in 2025, while Asia Pacific output rose 7.6%. Plants in the United States and Mexico that build transfer cases and rear drive units face lower utilization if the decline continues. Suppliers without a strong Chinese or Indian footprint face pressure on fixed-cost recovery and must win new platforms or consolidate.
North America leads on value, Asia Pacific on growth
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 14.21 | 35.0% | 4.8% |
| Asia Pacific | 13.80 | 34.0% | 6.2% |
| Europe | 8.53 | 21.0% | 4.5% |
| Latin America | 2.44 | 6.0% | 5.7% |
| Middle East & Africa | 1.62 | 4.0% | 5.8% |
North America leads on trucks and AWD fitment
North America held 35.0% of 2025 value and grows at 4.8% a year, because truck-based vehicles dominate production and most leave the plant with power to both axles. The fitment rate noted in the drivers section is the highest of any major market. Magna plans to build its high-output rear eDrive at Ramos, Mexico, which keeps electric axle value in the region. The tariff rules noted above push automakers to source transfer cases and rear drive units from U.S., Mexican and Canadian plants.
Asia Pacific grows on Chinese NEVs and Indian SUVs
Asia Pacific held 34.0% of 2025 value and is the fastest-growing region at 6.2% a year. China produced 34.53 million vehicles in 2025 and sold 16.49 million new energy vehicles, up 28.2%, according to CAAM data reported by the State Council. The BorgWarner awards in Chinese transfer case programs show demand for mechanical units in pickups and large SUVs. Japanese and Korean suppliers such as Aisin, JTEKT and Hyundai Transys anchor regional production.
Europe balances CO2 rules with premium AWD
Europe held 21.0% of 2025 value and grows at 4.5% a year, the slowest pace, because output slipped 0.8% to 17.2 million vehicles in 2025, according to OICA, and carbon rules penalize heavy drivetrains. The European Parliament voted 458 to 101 on May 8, 2025 to let carmakers average CO2 compliance over 2025 to 2027, which eases pressure on hybrid and combustion AWD models. German premium brands keep regional value per vehicle high despite flat unit output.
Latin America depends on pickups and Chinese imports
Latin America held 6.0% of 2025 value and grows at 5.7% a year, with demand concentrated in pickups and SUVs in Brazil, Mexico and Argentina. Regional pickup demand gained an electrified option in May 2024, when BYD launched the Shark plug-in hybrid with intelligent electric all-wheel drive and more than 430 horsepower in Mexico City. Public data on AWD fitment in the region are thin, so this split is a Credence Research estimate with a wider error band.
Middle East & Africa favors rugged four-wheel drive
Middle East & Africa held 4.0% of 2025 value and grows at 5.8% a year, as buyers in the Gulf and southern Africa favor body-on-frame SUVs and pickups for desert and rural use. The SAIC Maxus export transfer cases noted above target such overseas markets, although the destinations were not named. No official statistic on AWD fitment in the region was found, so the share rests on Credence Research estimates from the vehicle mix.
Mergers, divestments and China awards reshape supply
| Development | Status and market relevance |
|---|---|
| In October 2024, Schaeffler completed its merger with Vitesco Technologies and formed an E-Mobility division led by a former Vitesco manager. | Completed merger; it combines bearings and chassis know-how with electric drive capacity for e-axle programs. |
| In January 2026, Dana Incorporated completed the USD 2.7 billion sale of its Off-Highway business to Allison Transmission. | Completed divestment; Dana now concentrates on light and commercial vehicle drivelines, including AWD axles. |
| In February 2026, Dauch Corporation, formerly American Axle & Manufacturing, completed its acquisition of Dowlais Group, the parent of GKN Automotive. | Completed acquisition; it joins two of the largest independent driveline makers across 24 countries and more than 175 locations. |
| In October 2025, BluE Nexus, Aisin and Denso said a new eAxle with a silicon carbide inverter would be fitted to the new Toyota bZ4X. | Adoption announced, with a 167 kW front unit and an 88 kW rear unit; it shows Japanese suppliers sizing paired axles per platform. |
Couplings, disconnects and e-axles set efficiency
- Transfer cases and power transfer units split engine torque between axles, with part-time units for pickups and torque-on-demand designs that engage the front axle automatically.
- Electronically controlled couplings use a clutch pack and actuator to vary torque to the rear axle on demand, which also enables torque vectoring when paired with twin clutches.
- Axle disconnect systems stop the shafts or the secondary motor from spinning when traction is not needed, which recovers fuel economy or electric range.
- Secondary electric drive modules combine motor, inverter and gearbox on the second axle, and suppliers of e-axles now offer them as one bolt-in unit.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Five driveline groups compete for platform awards
Competition centers on platform awards, because a supplier selected for a pickup, SUV or electric architecture usually keeps the business for the life of the program. BorgWarner is building its transfer case and coupling business with Chinese automakers. Dauch, now combining American Axle with GKN Automotive, offers axles, shafts, couplings and eDrives from one group. Magna pairs mechanical AWD with high-voltage eDrives and decoupling units, while Dana focuses on disconnecting axles for SUVs. Aisin, JTEKT and Hyundai Transys hold strong positions with Japanese and Korean automakers, which limits access for outsiders. In-house motor production at some electric automakers caps the open market for drive modules, so independent suppliers compete on cost, efficiency and integration of the automotive multi wheel drive system with stability control.
How concentrated is the supply of second-axle hardware?
Mechanical AWD supply is concentrated among a handful of independent driveline groups, led by BorgWarner, Dauch with GKN Automotive, Magna and Dana, alongside captive or affiliated suppliers such as Hyundai Transys, Aisin and JTEKT. Entry barriers are high because couplings and transfer cases need validated durability, stability-control calibration and multiyear platform awards. Electric drive modules are more contested, since some automakers design their own motors and inverters. Margins sit in controlled couplings, disconnect actuators and aftermarket units, while propeller shafts are the most commoditized line.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| BorgWarner Inc. | Driveline supplier | Transfer cases, couplings and electronic limited-slip differentials |
| Dauch Corporation | Driveline supplier | GKN Automotive axles, propeller shafts, couplings, Twinster units and eDrives |
| Schaeffler AG | Powertrain and e-axle supplier | Electric axles and E-Mobility drives from the Vitesco merger |
| Magna International Inc. | Driveline and eDrive supplier | Mechanical AWD, eDS dual-motor drives and eDecoupling units |
| Dana Incorporated | Driveline supplier | Spicer disconnecting AWD axles and e-axles for light vehicles |
| JTEKT Corporation | Driveline supplier | ITCC torque-controlled couplings for 4WD crossovers and SUVs |
| Aisin Corporation | Powertrain supplier | Front and rear eAxles for electric 4WD pickups and SUVs |
| Hyundai Transys Inc. | Affiliated powertrain supplier | AWD systems and EV AWD disconnectors for Hyundai Motor Group |
Value migrates to the secondary electric axle
Credence Research's view is that value in the automotive multi wheel drive system is migrating from shafts and gears to the secondary electric axle, even though Transfer Cases & Power Transfer Units still hold 30.0% of 2025 value. Suppliers that master both mechanical torque transfer and electric modules will keep platform access as automakers mix combustion, hybrid and battery electric versions on one architecture. Tariff and magnet risks favor suppliers with regional plants and alternative motor designs. The weakest position belongs to pure shaft makers, whose content shrinks with every dual-motor model.
Old estimate replaced after a content-per-vehicle test
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. The earlier Credence Research estimate was tested against a content-per-vehicle model built from OICA production data, U.S. drive-type statistics and published option premiums, and the 2025 value was replaced with a new Credence Research estimate because the earlier figure implied implausibly low hardware content. All regional and segment splits shown in this report are Credence Research estimates. Sources used include OICA, the IEA, the EPA and the U.S. Department of Energy, CAAM data, European Parliament and White House documents, company releases and trade press. No interviews or surveys were conducted for this edition of the study.
Electric second axles carry growth to 2035
Through 2035, spending on the automotive multi wheel drive system should grow at 5.30% a year as electric second axles replace propeller shafts and as Asian buyers move into utility vehicles. North America will keep the largest value pool on pickups and SUVs, while China and India add the most new units. Hybrid all-wheel drive will bridge the transition in markets where charging lags. Magnet supply and trade rules remain the main swing factors, and suppliers with regional plants and both mechanical and electric products should hold their platforms.
EV adoption and tariffs set the range of outcomes
The outcome to 2035 depends mostly on how fast dual-motor electric and hybrid models spread outside premium segments and how trade rules reshape driveline sourcing. Steady electric adoption in China and gradual U.S. resourcing would hold the base case. A slower electric transition with lasting magnet shortages would keep value in lower-content mechanical hardware, while cheaper motors would push electric all-wheel drive into mid-priced crossovers.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 3.7% | USD 59.29 billion | Magnet shortages persist, EV growth stalls and tariffs delay new driveline programs |
| Base | 5.30% | USD 68.05 billion | Electric second axles spread steadily while North American truck demand holds |
| Upside | 6.5% | USD 75.35 billion | Cheaper motors move dual-motor AWD into mass-market crossovers in China and India |
Frequently Asked Questions
How big is the automotive multi wheel drive system market?
What is an automotive multi wheel drive system?
Which region leads the automotive multi wheel drive market?
Which region grows fastest?
What role do OEM electric drive units play in all-wheel drive?
How much does all-wheel drive add to a vehicle price?
Who are the leading multi-wheel-drive suppliers?
What are the main risks for suppliers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Transfer Cases & Power Transfer Units
- 1.2.2 Couplings & Differentials
- 1.2.3 Electric Drive Modules
- 1.2.4 Propeller Shafts
- 1.2.5 Electronic Controls & Actuators
- 1.3 By Propulsion Type
- 1.3.1 Internal Combustion Engine
- 1.3.2 Hybrid & Plug-in Hybrid
- 1.3.3 Battery Electric
- 1.4 By Sales Channel
- 1.4.1 OEM
- 1.4.2 Aftermarket
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 40.60 billion → 2035: USD 68.05 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Multi Wheel Drive System Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Multi Wheel Drive System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Multi Wheel Drive System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Multi Wheel Drive System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Multi Wheel Drive System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Multi Wheel Drive System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Multi Wheel Drive System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Multi Wheel Drive System Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 40.60 billion → 2035: USD 68.05 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Multi Wheel Drive System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Transfer Cases & Power Transfer Units
- 12.3.7.2 Couplings & Differentials
- 12.3.7.3 Electric Drive Modules
- 12.3.7.4 Propeller Shafts
- 12.3.7.5 Electronic Controls & Actuators
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Propulsion Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Internal Combustion Engine
- 12.4.7.2 Hybrid & Plug-in Hybrid
- 12.4.7.3 Battery Electric
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 OEM
- 12.5.7.2 Aftermarket
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Multi Wheel Drive System Geographic Market Outlook, 2025-2035
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2035
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Automotive Multi Wheel Drive System Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Automotive Multi Wheel Drive System Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 BorgWarner Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Dauch Corporation
- 17.4 Magna International Inc.
- 17.5 Dana Incorporated
- 17.6 Schaeffler AG
- 17.7 JTEKT Corporation
- 17.8 Aisin Corporation
- 17.9 Hyundai Transys Inc.
- 17.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

