
Defense fleets and armored security vans set demand
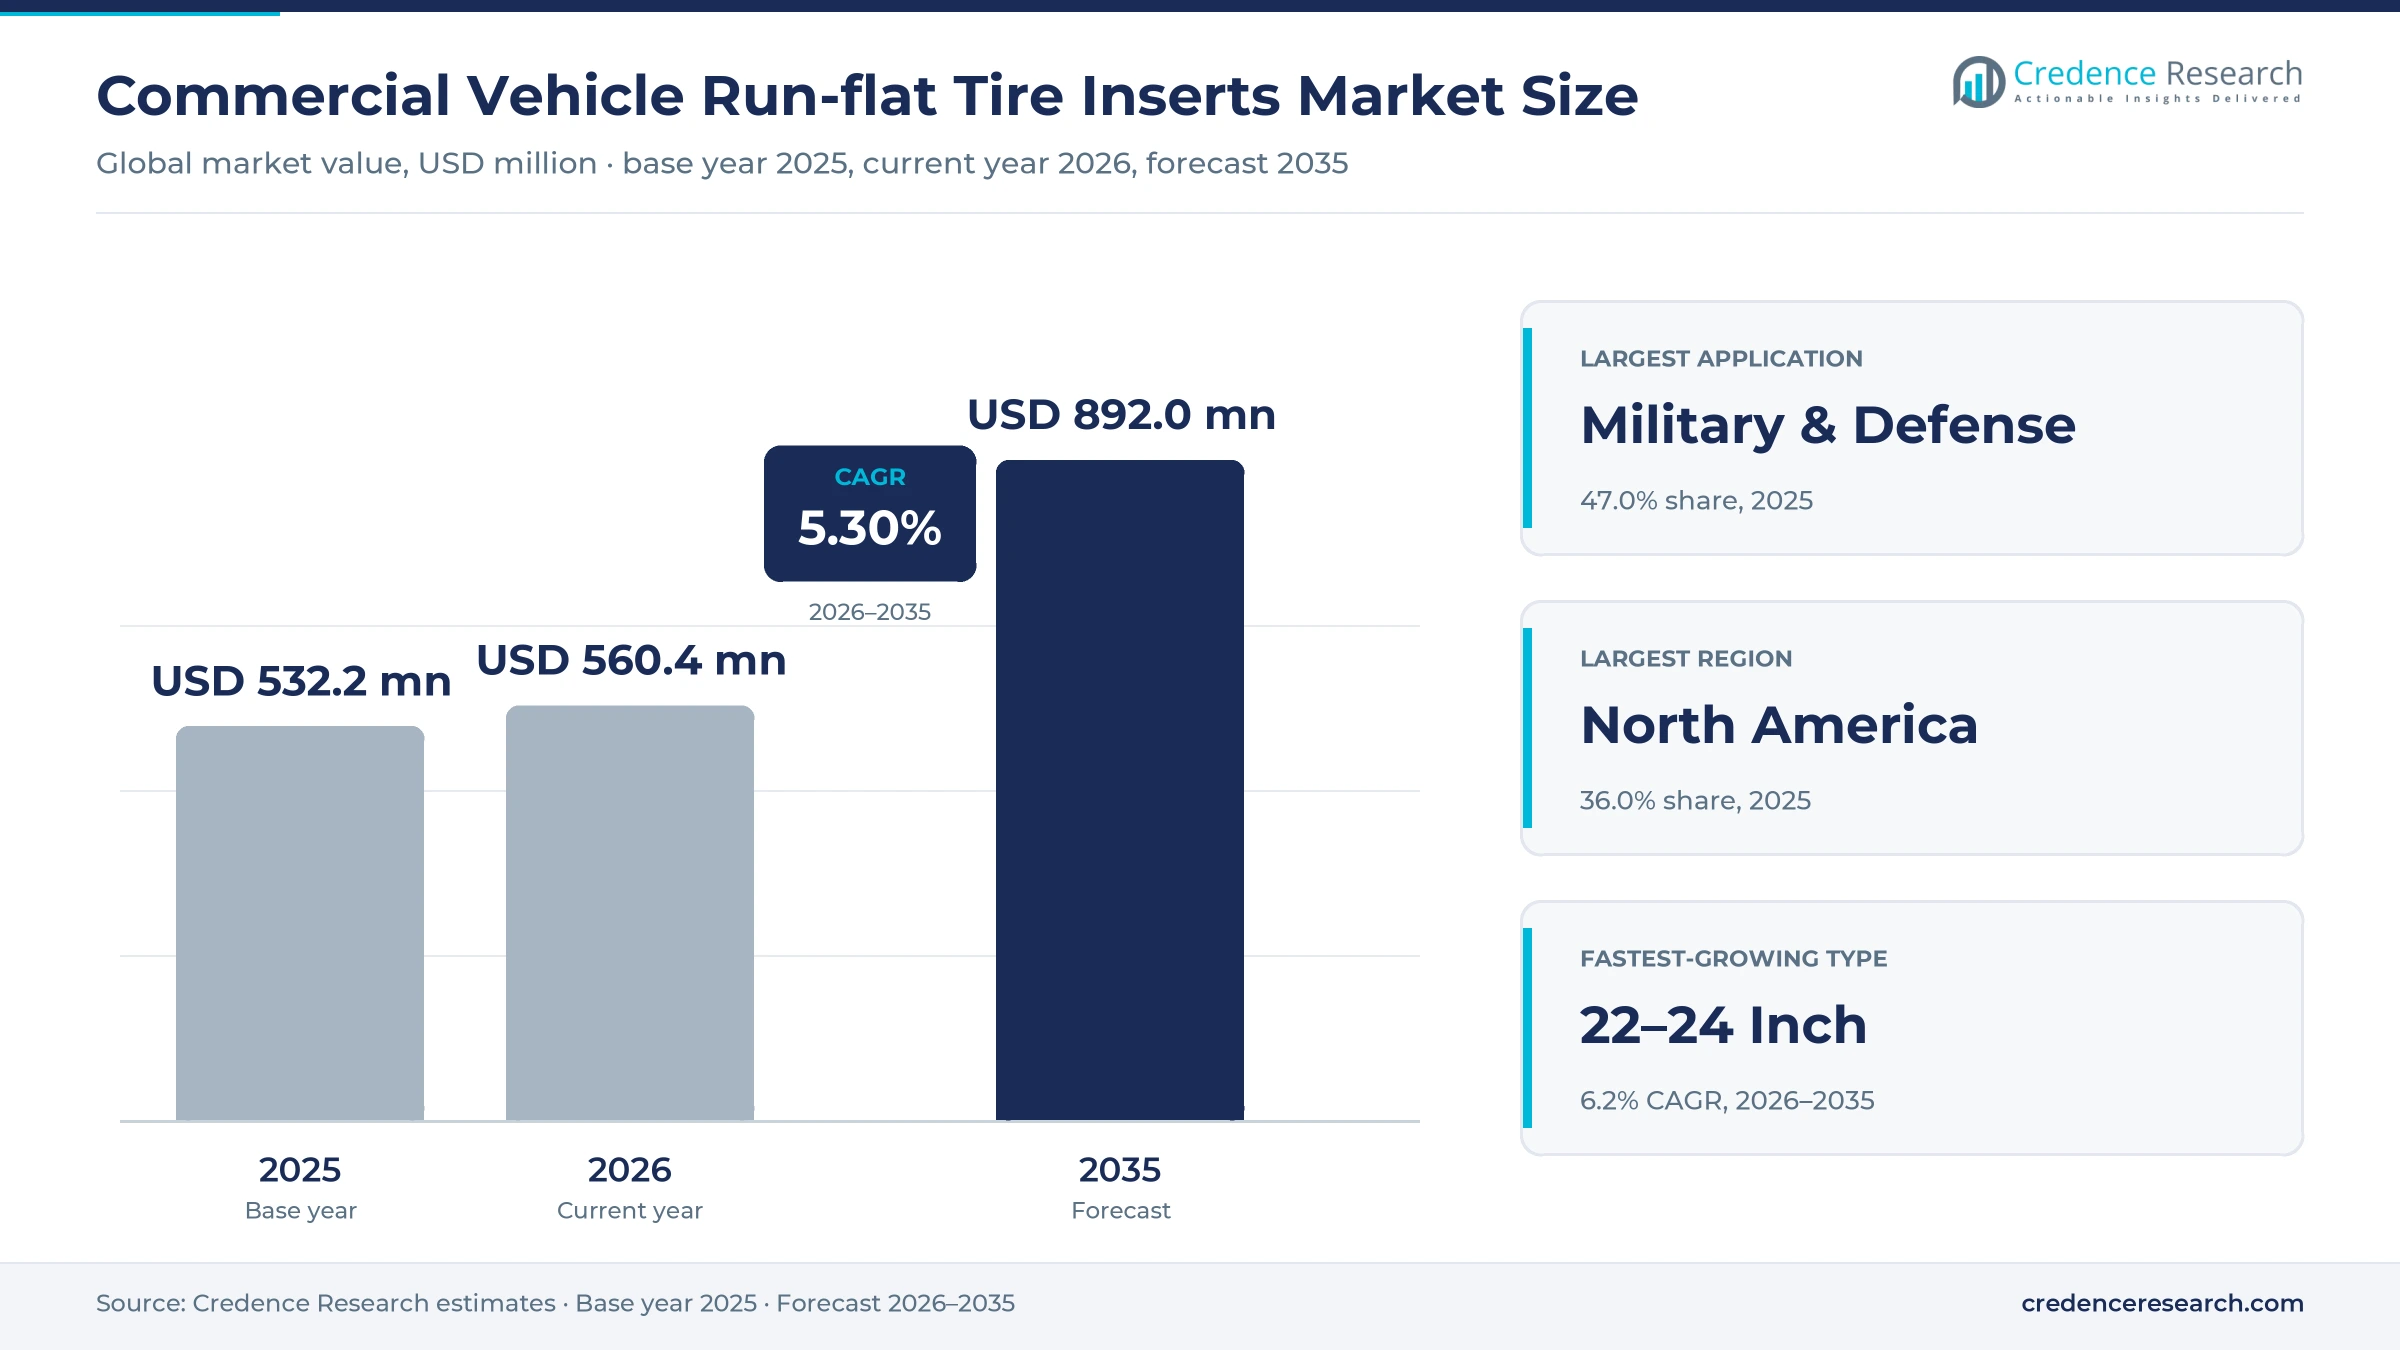
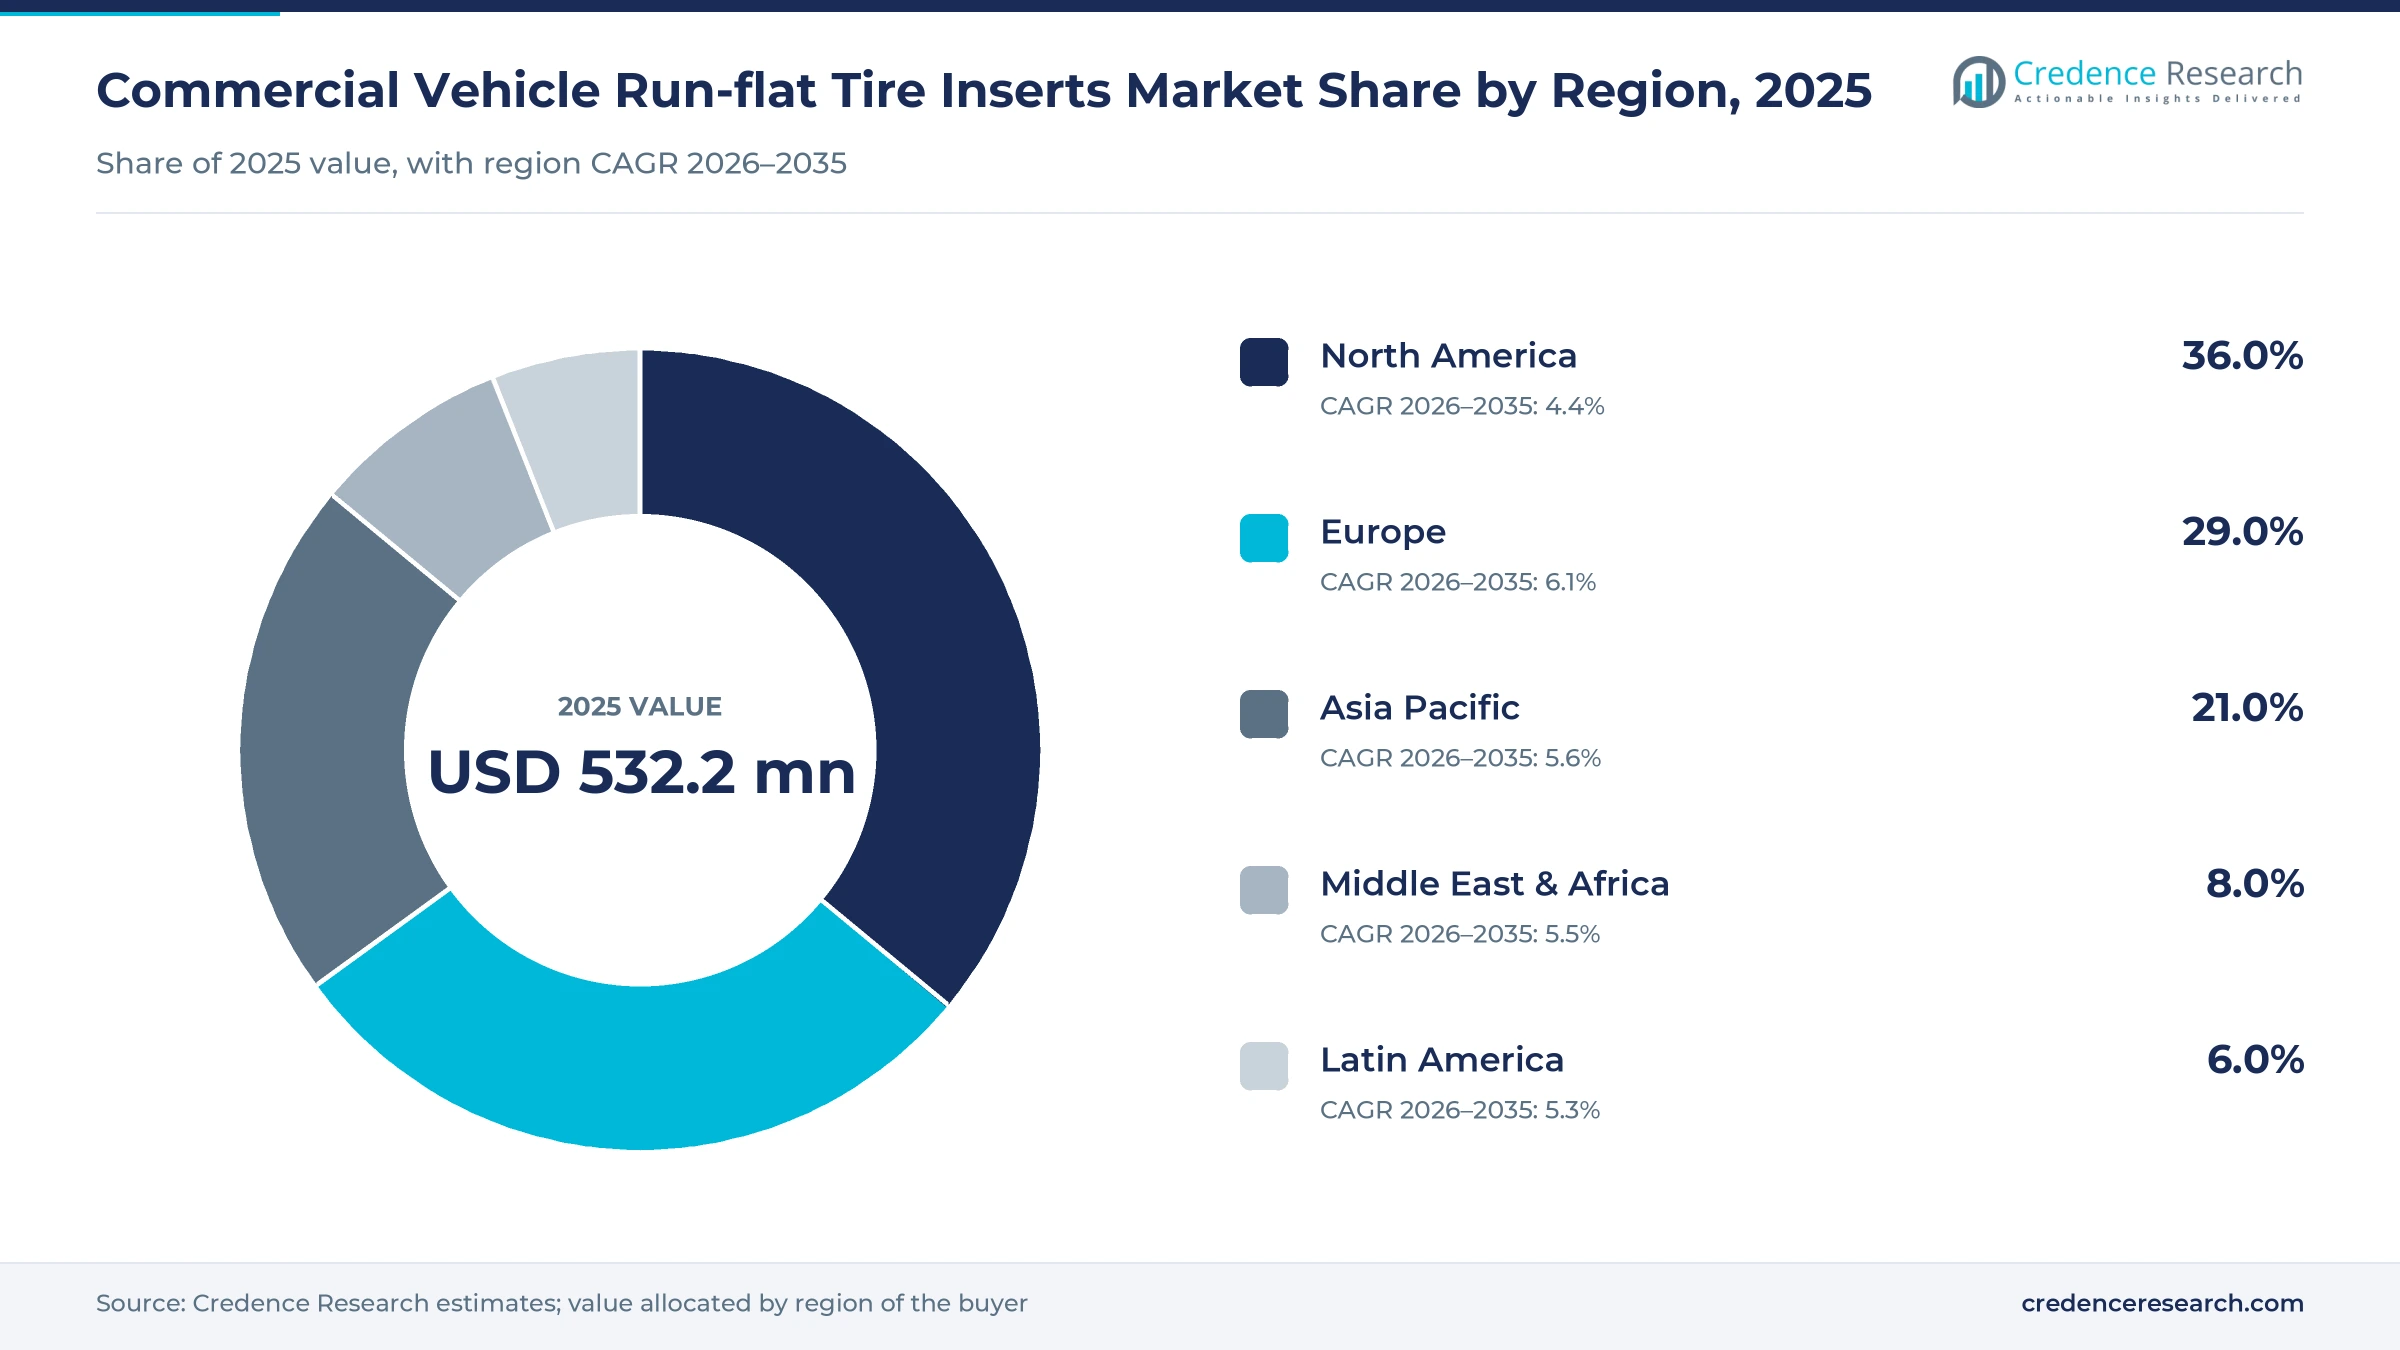
The global commercial vehicle run-flat tire inserts market was valued at USD 532.2 million in 2025 and is projected to increase from USD 560.4 million in 2026 to USD 892.0 million by 2035, registering a CAGR of 5.30% during 2026–2035. Demand comes from armies replacing tactical wheel sets, from armoring workshops that build cash-in-transit vans and executive vehicles, and from police and emergency fleets that cannot risk a roadside stop after a puncture or spike attack. North America held the largest regional share, 36.0% in 2025, because U.S. logistics agencies buy replacement insert kits on recurring contracts. Europe is the fastest-growing region at 6.1% a year, as NATO members turn larger budgets into multiyear orders for 4x4, 6x6 and 8x8 wheeled platforms. Lighter rubber and composite designs that fit single-piece wheels are widening use beyond military two-piece rims. The main restraint is that qualified inserts are priced per wheel position and must pass defense or certification testing before fleets accept them.
Which vehicles carry inserts and who decides the purchase?
The market counts rings and bands of rubber, cast nylon, composite or metal that sit on the wheel inside the tire and carry the load after pressure loss, sold both fitted on new vehicles and as replacement kits. Buyers are defense logistics agencies, vehicle builders, armoring workshops and fleet operators, and the rating they buy is distance, from short escape bands for cash vans to long-range kits for military convoys.
Self-supporting run-flat tires with reinforced sidewalls, airless tires and pressure monitoring hardware are excluded from the value. The chain runs from compound and core makers through insert specialists and distributors to the armorer or depot that mounts the kit, which is why the fitting partner often chooses the brand.
Commercial Vehicle Run-flat Tire Inserts Market Insights
- The market grows from USD 532.2 million in 2025 to USD 892.0 million by 2035 at 5.30%, led by armored wheeled vehicle orders and recurring spares buying rather than civilian trucks.
- North America held 36.0% of 2025 value, supported by recurring DLA insert tenders and steady HMMWV and tactical truck contracts through 2026.
- Military & Defense led applications with 47.0% of 2025 value, as armies specify inserts on wheeled combat, patrol and logistics vehicles.
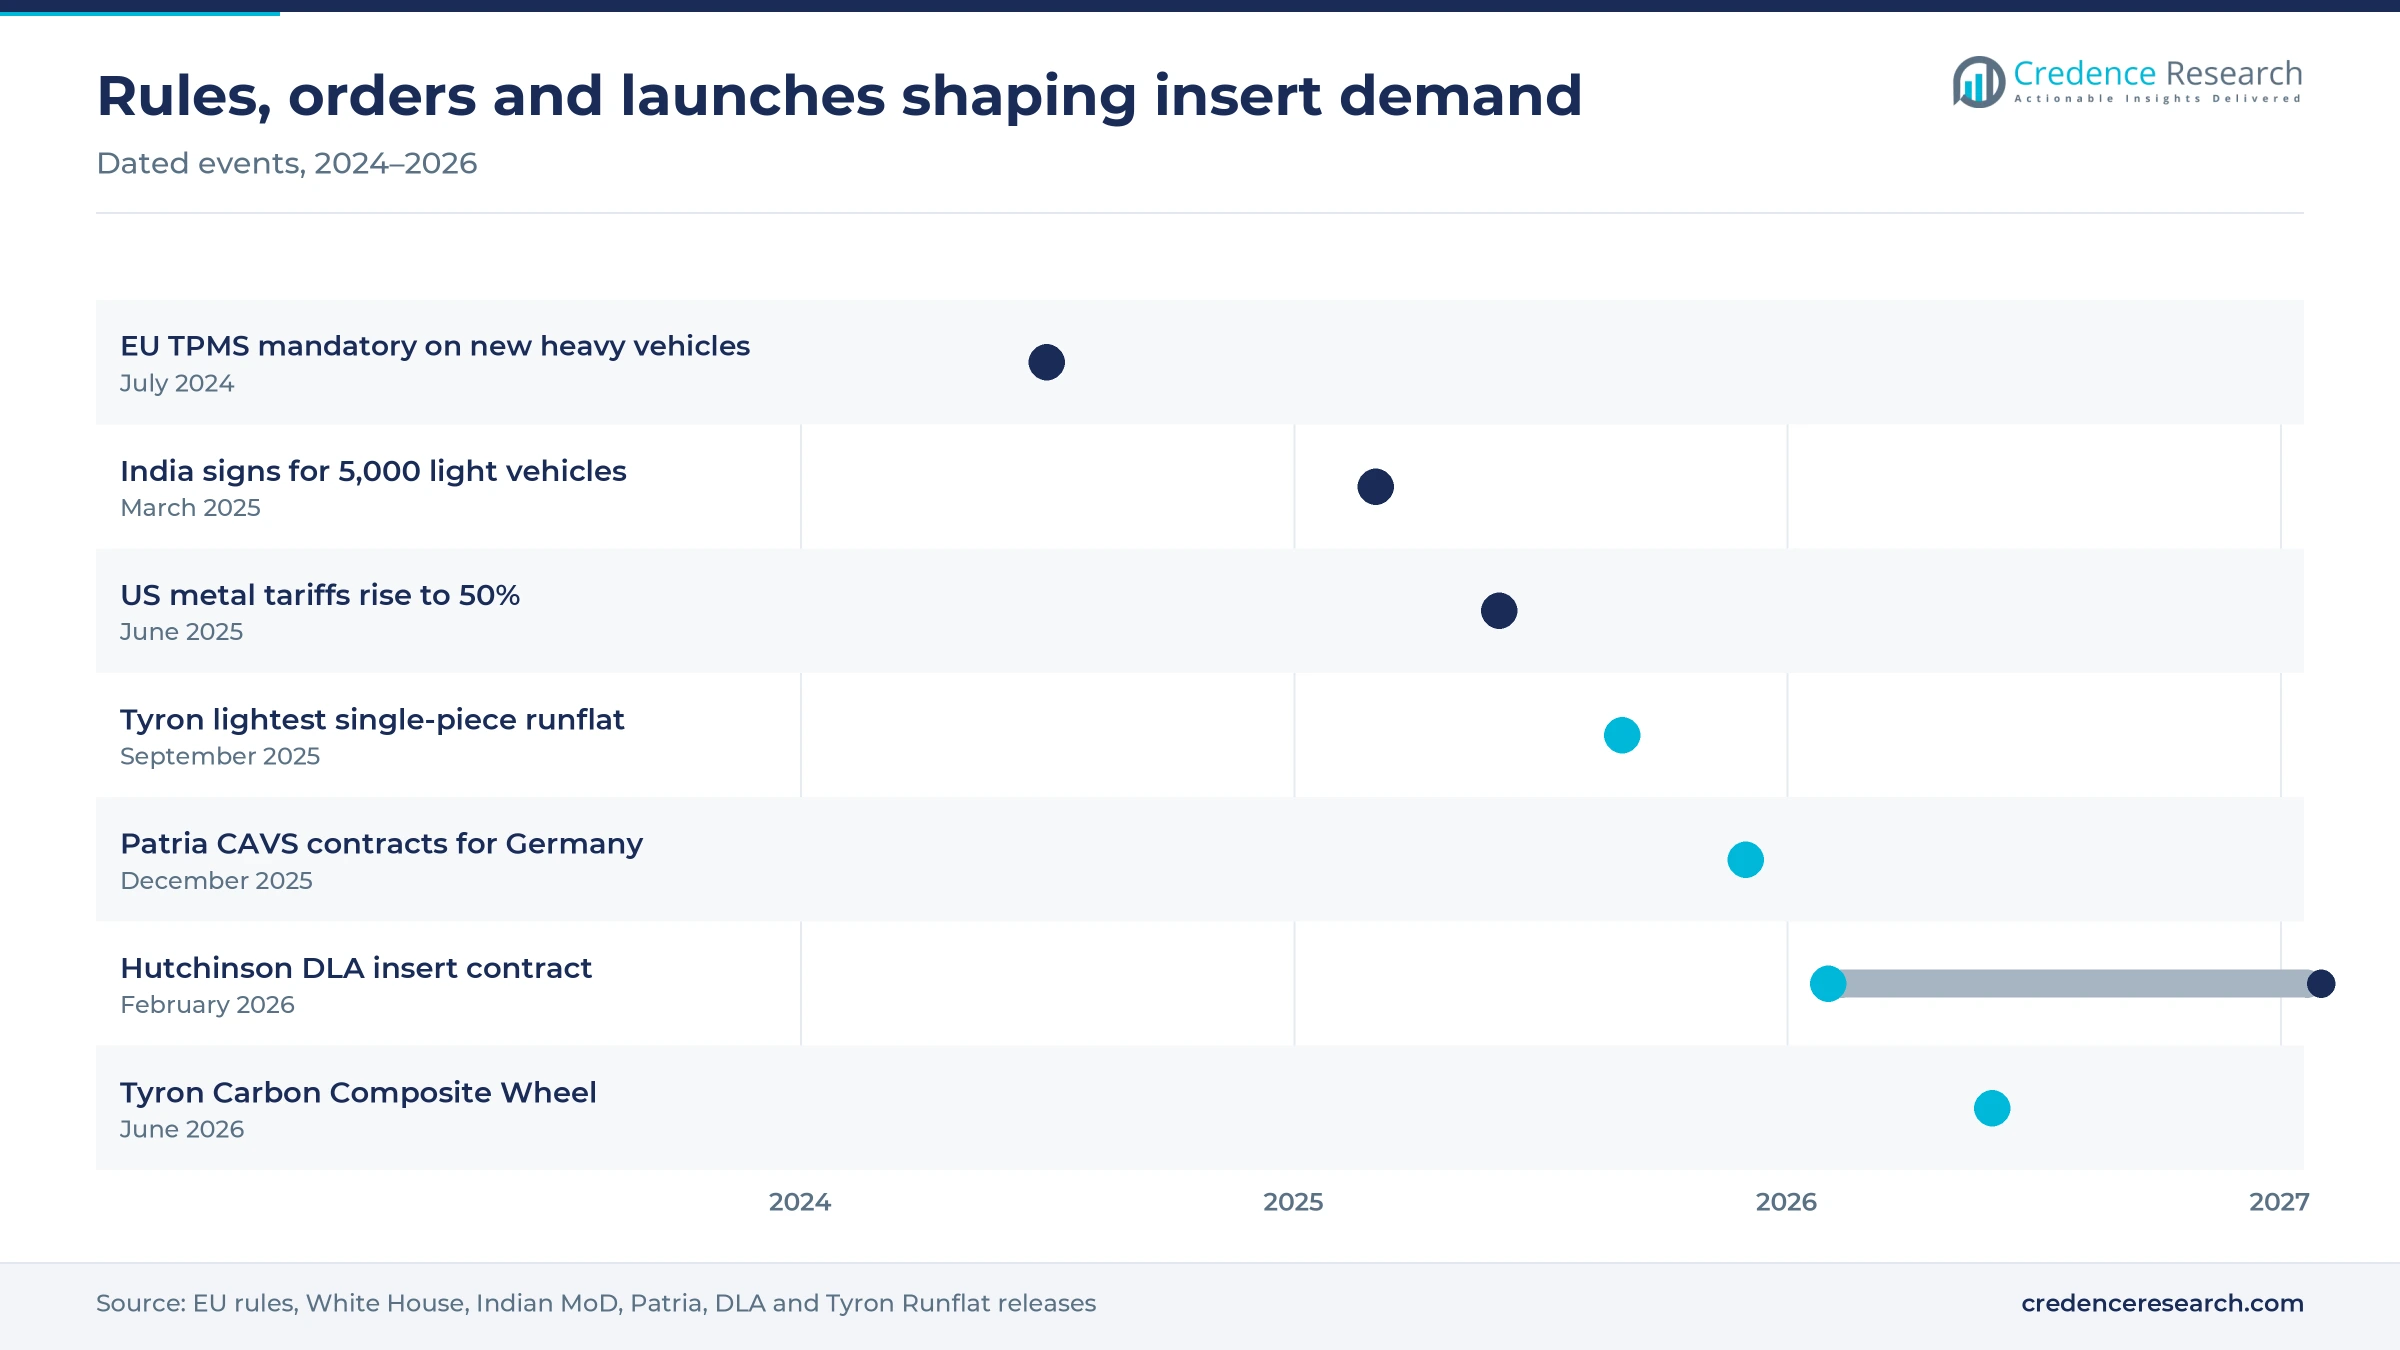
- Tyron Runflat launched its lightest single-piece runflat at DSEI U.K. in September 2025, signaling a shift toward lighter inserts for standard wheels.
- Patria signed contracts on Dec. 18, 2025, for up to 876 6x6 vehicles for Germany, adding a large original-equipment pipeline from 2026.
Military buyers and mid-size rims hold most value
Light tactical rims lead and heavy truck sizes grow fastest
Based on type, the market is categorized into 17–18 inch, 19–20 inch, 22–24 inch and other rim sizes. 19–20 Inch inserts led with 38.0% of 2025 value because this band covers the light tactical and protected 4x4 fleets that consume the most kits, and AM General's JLTV A2 contract alone allows up to 20,682 such vehicles. 22–24 Inch rims grow fastest at 6.2% a year as heavy trucks, coaches and 6x6 carriers add protection, and TSS International lists Rodgard runflats for rims up to 22.5 inches. Rim-size splits are Credence Research estimates, because no public body reports insert sales by wheel diameter.
Defense buyers dominate while police and emergency fleets accelerate
Based on application, the market is categorized into military and defense, transportation and logistics, construction, agricultural, manufacturing and other uses such as healthcare and municipal fleets. Military & Defense led with 47.0% of 2025 value because armies specify inserts on most wheeled combat and patrol vehicles, and recurring DLA tenders for qualified run-flat kits, priced as shown in the pricing section, keep military buying steady between vehicle programs. Others (Healthcare and Municipal) grows fastest at 6.3% a year as police and emergency services armor patrol fleets, and Abrablin counted 42,800 vehicles armored in Brazil in 2025, up 24.6% from 2024, a base from which police and municipal patrol conversions draw their inserts.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | 19–20 Inch | 38.0% | 22–24 Inch | 6.2% |
| By Application | Military & Defense | 47.0% | Others (Healthcare and Municipal) | 6.3% |
Military kits sell at several times security-grade prices
Pricing works per wheel position, and the gap between qualified military kits and security-grade rings is wide. On the DLA item in the table, the most recent award went to Triman Industries at USD 1,530.37 per unit for 108 units in September 2026, against historical awards of USD 1,413.03 to 1,530.37. Qualification, run-distance rating and wheel type move prices most, so long-distance composite inserts generally sit above short-distance bands. Buyers that accept security-grade ratings can cut kit costs sharply, while defense suppliers keep margin through part-number qualification.
| Offer or segment | Typical price or fee | Basis |
|---|---|---|
| U.S. DLA run-flat kit insert, military | USD 2,283.07 standard unit price | DLA Land and Maritime via HigherGov, October 2026 |
| Same DLA item, latest award | USD 1,530.37 per unit for 108 units | HigherGov award record, September 2026 |
| South Africa security rings, set of four | From ZAR 43,786 excluding VAT | SVI Engineering via TopAuto |
| India cast nylon or composite insert | INR 15,000–18,500 per piece | IndiaMART seller listings, November 2026 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Rearmament and sustainment buying lift insert demand
European rearmament turns budgets into wheeled vehicle orders
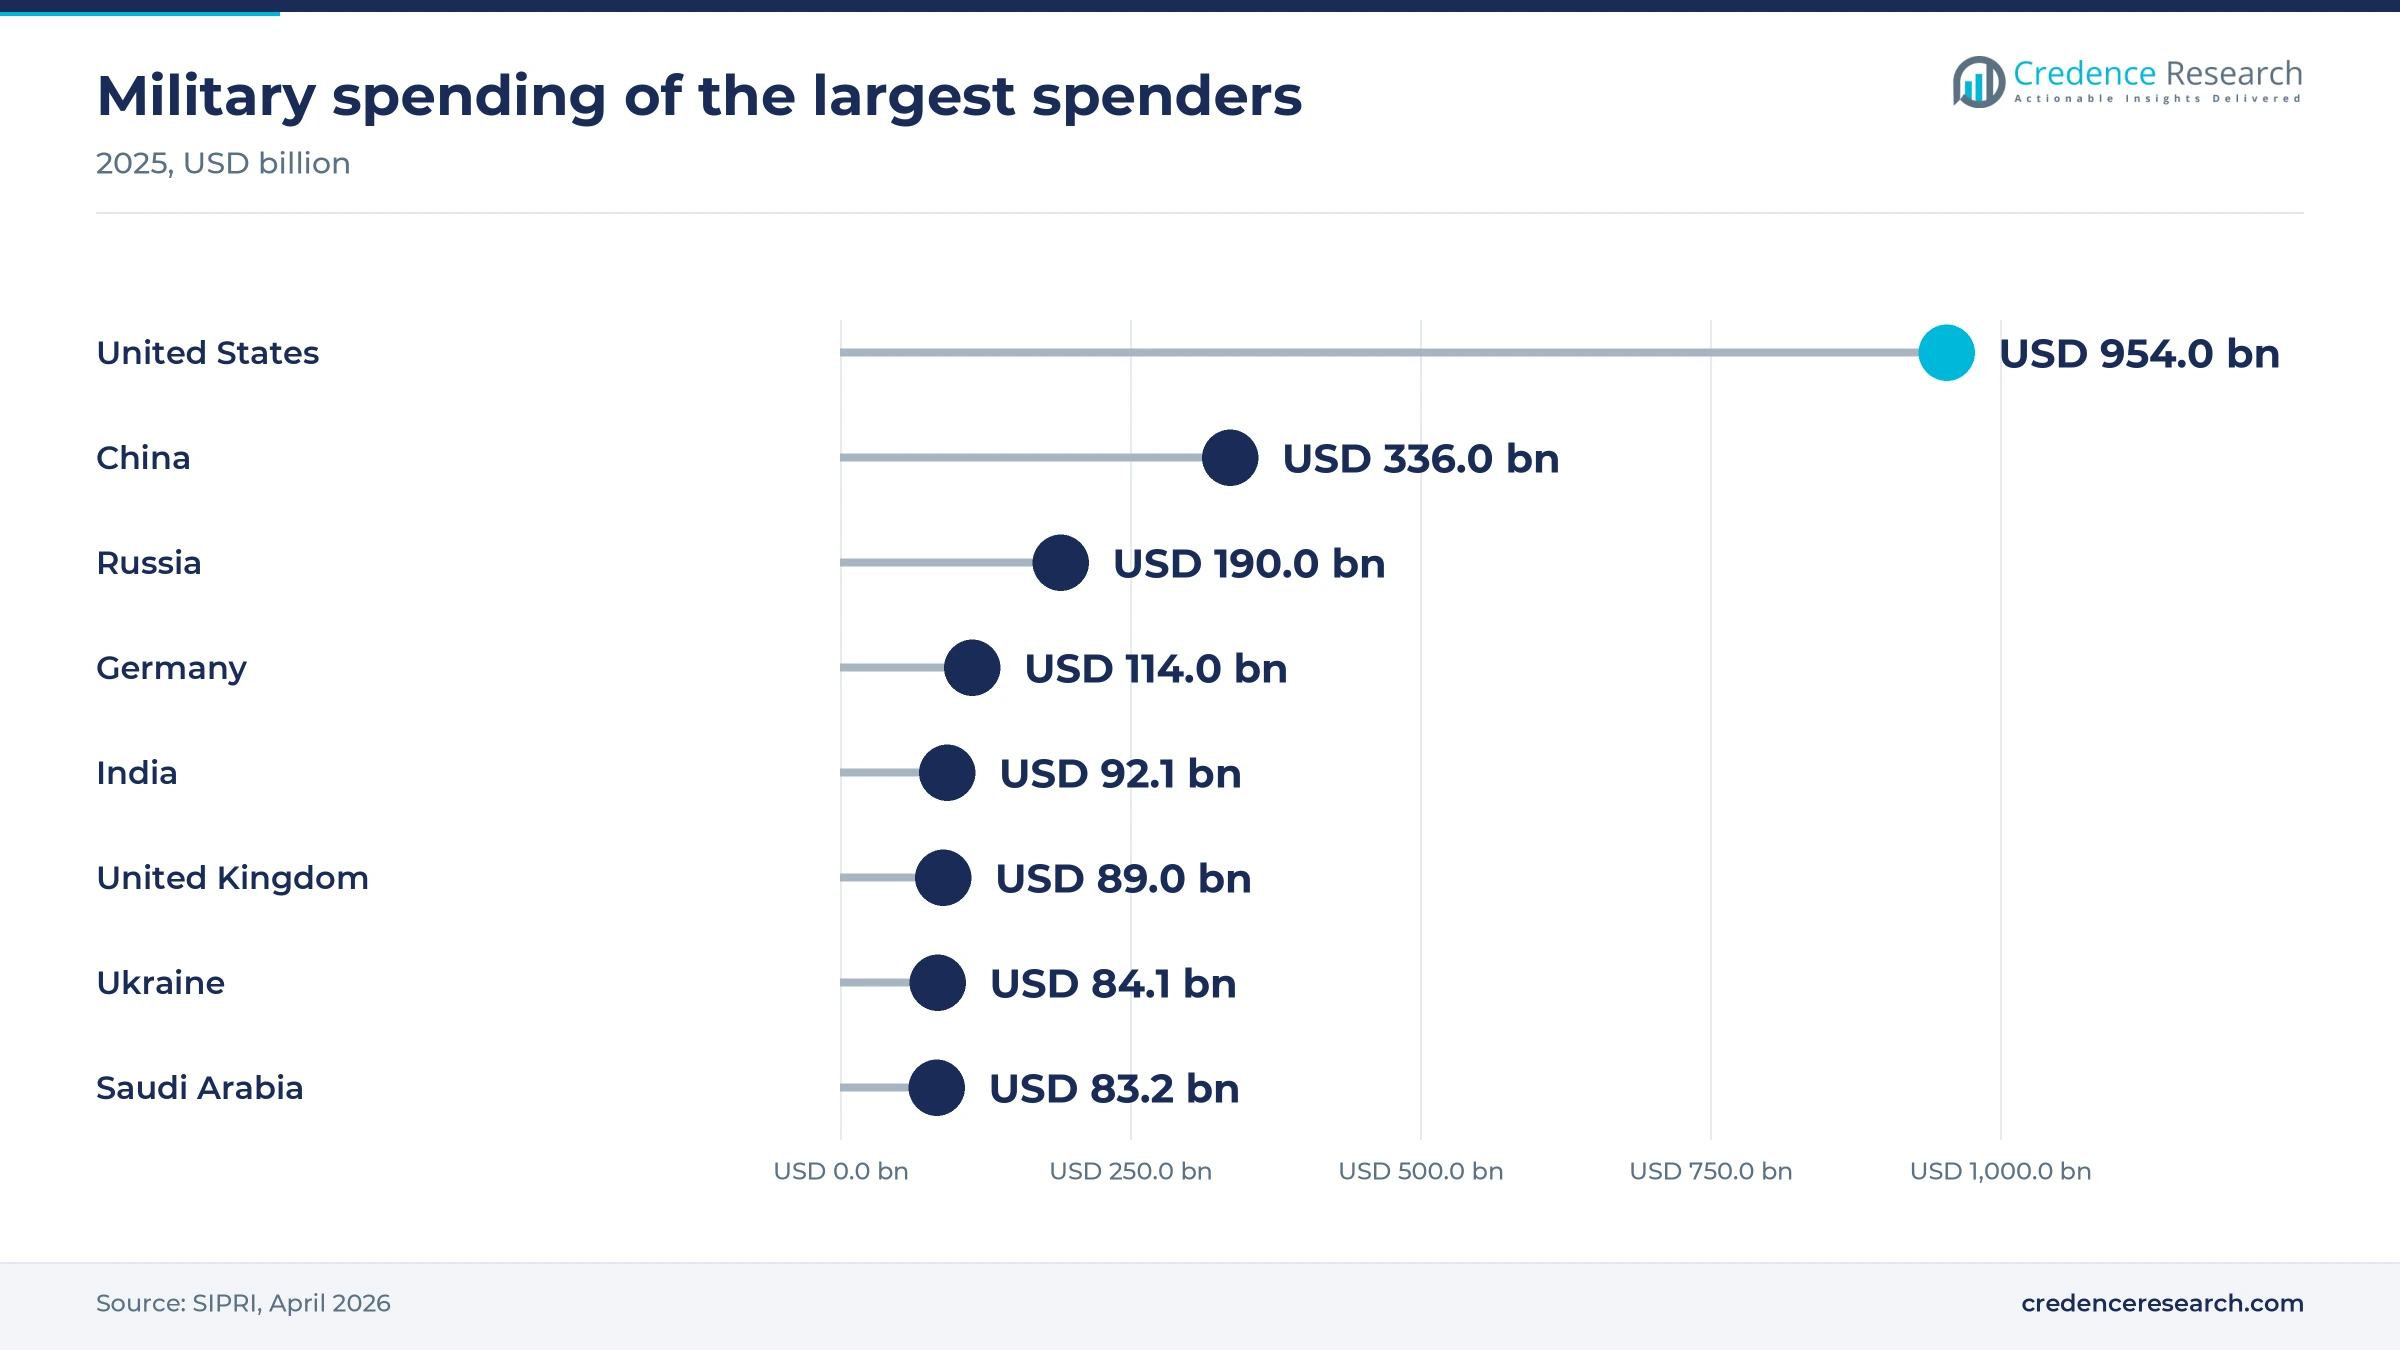
European rearmament is now the strongest source of new original-equipment demand, because every armored wheeled vehicle delivered needs a full set of inserts plus spares. SIPRI reported that European military spending rose 14% to USD 864 billion in 2025, with Germany up 24% to USD 114 billion, according to its April 2026 release. That money is reaching order books, since Patria signed contracts on Dec. 18, 2025, for up to 876 6x6 vehicles for Germany, with deliveries starting in 2026. Local assembly by FFG, JWT and KNDS from 2027 favors insert suppliers that qualify early with German integrators. Europe's faster regional growth reflects this order pipeline rather than a broad civilian upswing, so suppliers without defense approvals gain little from it.
U.S. sustainment buying keeps replacement kits moving
Recurring U.S. sustainment purchases give insert makers a replacement base that does not depend on new vehicle starts. DLA Land and Maritime lists a standard unit price of USD 2,283.07 for one run-flat kit insert line, and its October 2026 request covered 149 units, according to HigherGov contract records. Hutchinson Industries also holds a DLA indefinite-delivery contract from February 2026 with a USD 350,000 ceiling for insert kits. Vehicle buying continues alongside, as AM General won a new HMMWV contract in August 2026 with orders allowed up to USD 754.6 million by 2028, according to Militarnyi. These purchases favor suppliers with qualified part numbers and U.S. production, while newcomers must first win a place on the approved source list.
Civil armoring in Latin America widens the buyer base
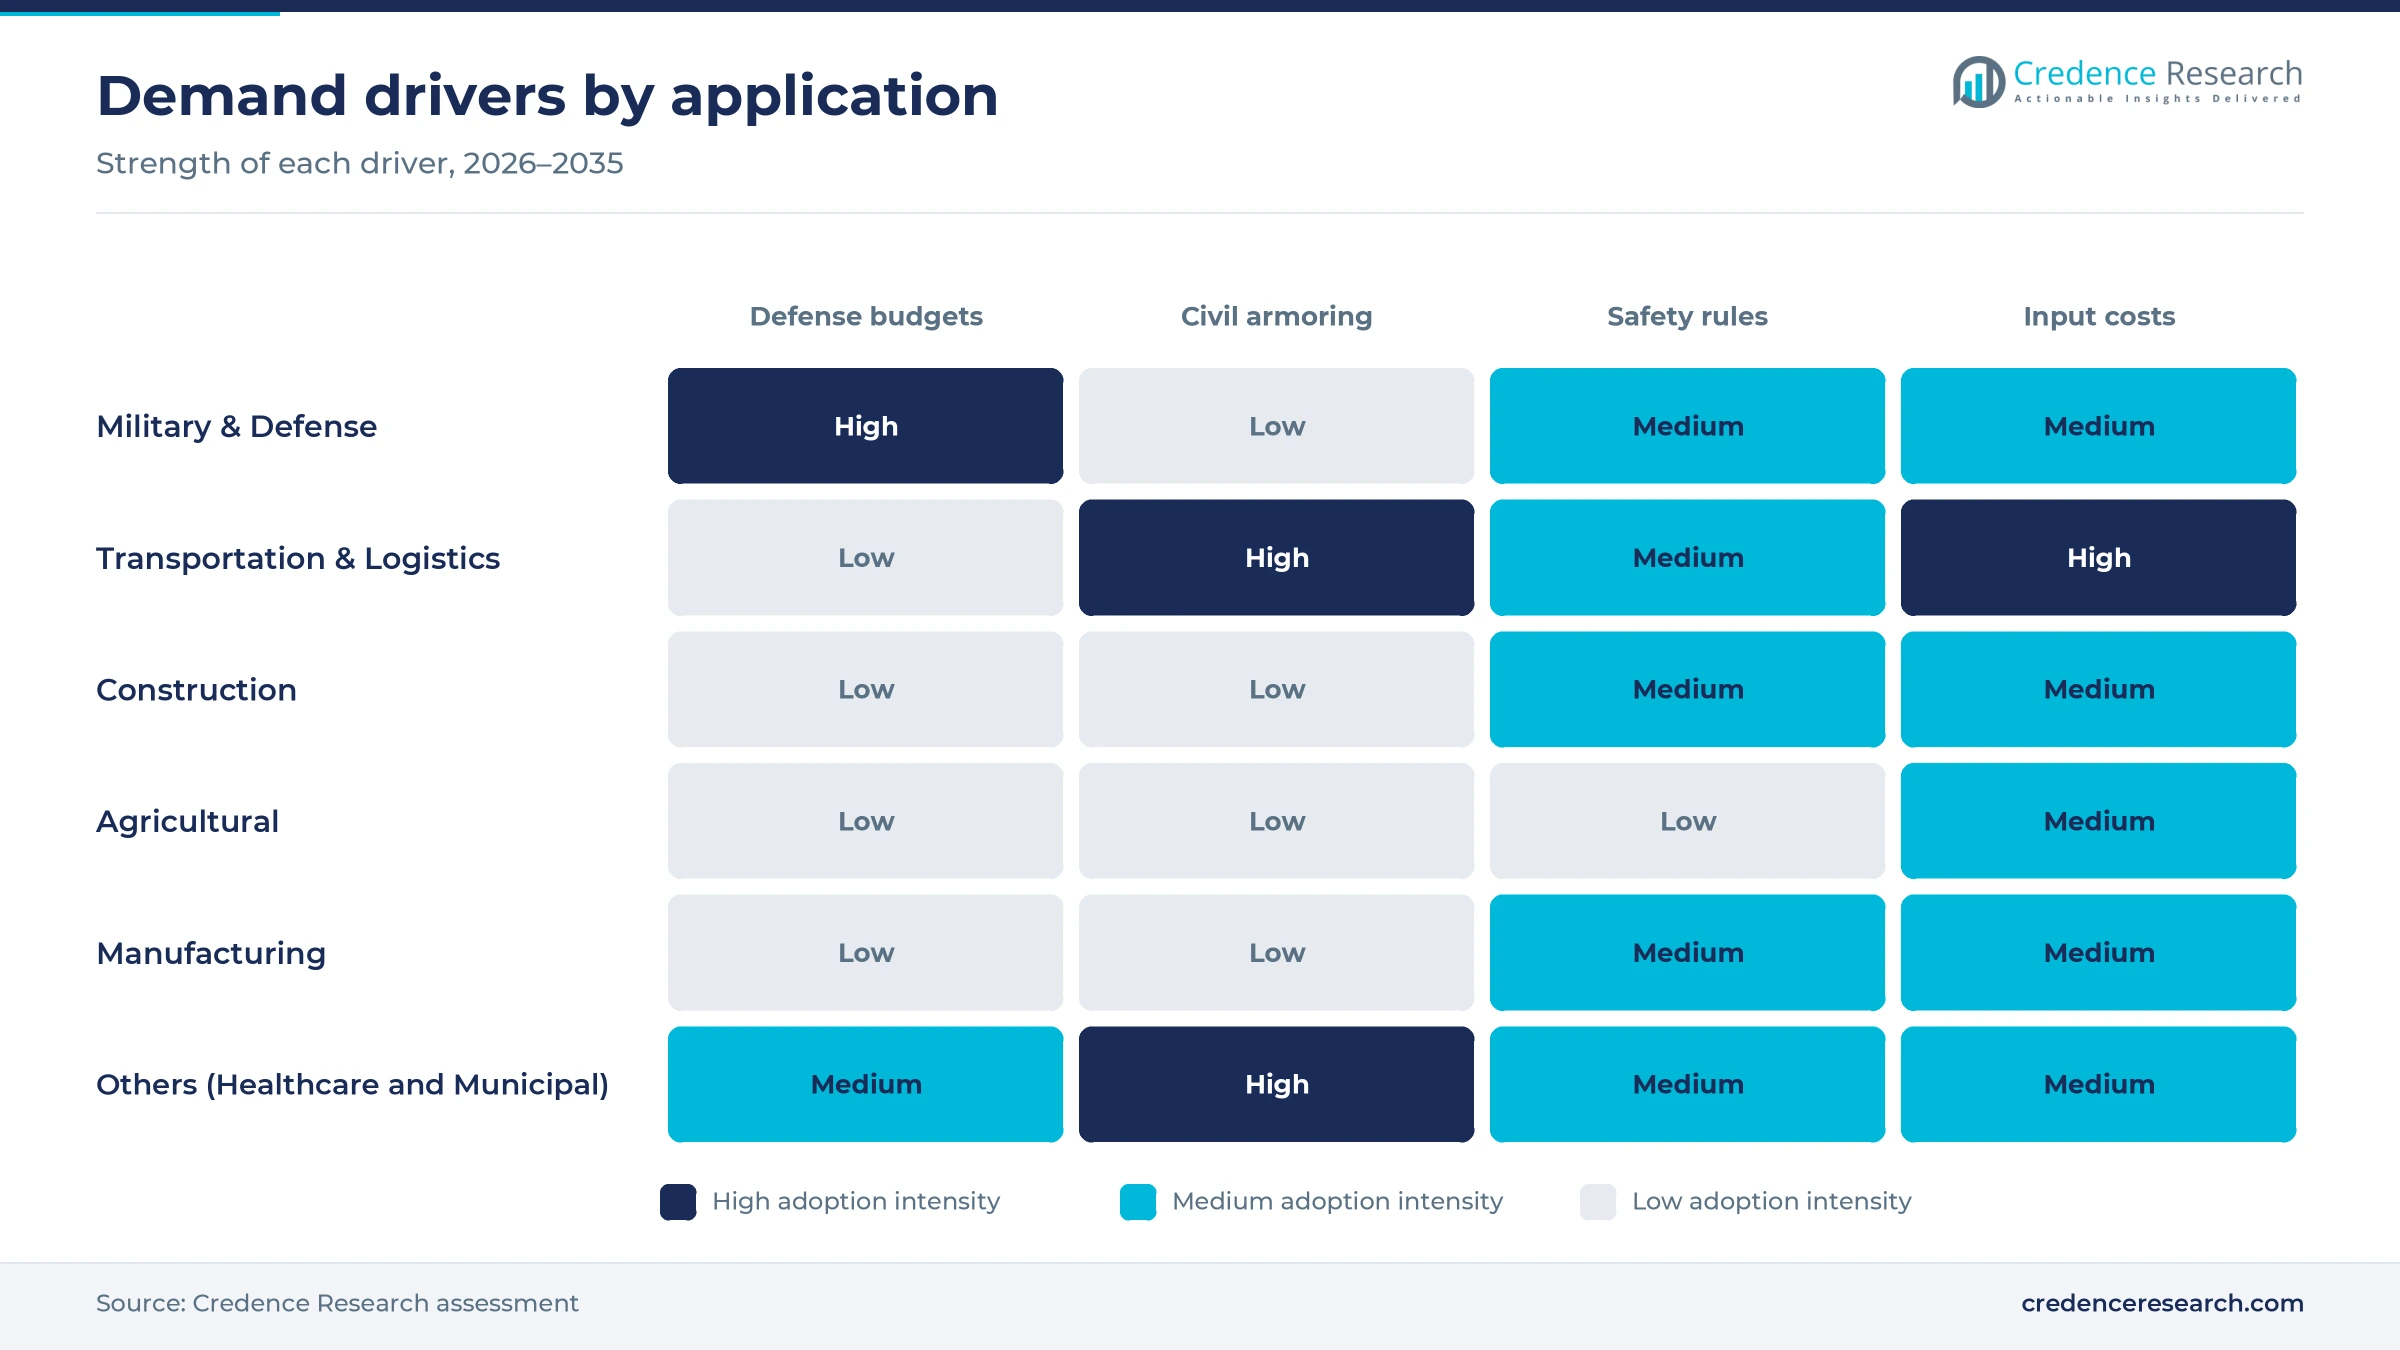
Civil armoring is widening the buyer base beyond defense ministries, because cash vans, security patrol trucks and executive vehicles all need inserts to escape a spike strip or a shot tire. Abrablin counted 42,800 vehicles armored in Brazil in 2025, up 24.6% from 34,402 in 2024, as reported by Radio Itatiaia in May 2026. The Intercontinental Association of Armorers expected Mexican armoring activity to rise 30% in 2025 from a base of about 4,000 vehicles a year, according to Mexico Business News. Most of this volume is private cars, so only the commercial and security share counts here. Armoring workshops rather than fleets usually pick the insert brand, which makes converter relationships the deciding factor for share in this channel.
Asian procurement adds volume for light patrol vehicles
Asia Pacific procurement adds volume at the lighter end of the market, where patrol and utility vehicles are bought in large batches. India's Ministry of Defence signed contracts on March 27, 2025, for about 5,000 light vehicles from Force Motors and Mahindra & Mahindra, according to the Press Information Bureau, adding to the region's military land fleets. SIPRI estimated India's 2025 military spending at USD 92.1 billion, up 8.9% in real terms. The Indian contracts do not disclose insert fitment, which is the main uncertainty in this estimate. Asia Pacific grows at 5.6% a year, with price-led domestic makers competing against imported European designs for patrol fleets.
Lighter, single-piece designs reshape specifications
Lighter inserts are shifting buyer specifications
Vehicle builders are shifting toward lighter inserts to recover payload lost to armor, creating openings for rubber bands and composite designs across 4x4 and 6x6 platforms. Tyron Runflat launched what it calls the lightest single-piece runflat at DSEI U.K. in September 2025 and said its lower unsprung weight helps the tire keep better road contact after damage. At Eurosatory in June 2026, the company added a Carbon Composite Wheel that it says saves up to 500 kg of gross weight against steel wheels. Hutchinson already sells composite TMR and CMRF inserts for two-piece tactical wheels. Weight is therefore becoming a selection criterion beside run distance for armored platforms.
Single-piece wheel fitment is emerging as the next standard
Fleet engineers are shifting toward inserts that fit standard single-piece drop-center wheels, which avoids the cost of converting vehicles to multi-piece rims. Run Flat Systems markets its CBR insert, which combines a beadlock with runflat support and takes under ten minutes to fit, and IDIADA in Tarragona certified its runflat capability. Hutchinson's RRF Rodgard and HMR lines also target one-piece wheels, while RunFlat International rates its Dynamic RunFlat for 15, 30, 50 or 100 km. This change opens police, ambulance and logistics fleets, where vehicles arrive from the factory on single-piece wheels. It also widens the field to smaller regional makers, which adds price pressure in civilian tenders.
Higher-speed ratings open VIP and special forces work
Higher-speed ratings create an opening in VIP protection and special forces fleets, where vehicles must escape at road speed rather than limp to safety. Tyron Runflat said in October 2025 that it is raising the test speed for its rubber runflats and bands to 250 km/h, against an often-quoted industry limit of 150 km/h, and linked the work to a new European Special Forces partnership. The company also expanded a 3,000 square meter testing factory in Pattaya, Thailand, during 2025. Rodgard cash-in-transit systems come in 15, 25, 50, 80 and 150 km versions, which shows how distance tiers already segment the offer. Suppliers that certify higher speeds can sell premium kits to armoring houses serving executives and diplomats.
Pressure monitoring rules create an integration opening
European pressure monitoring rules create an integration opening for insert makers that pair runflat support with sensors on heavy vehicles. Under the EU General Safety Regulation, TPMS became mandatory from July 6, 2024, on all newly registered buses, trucks and heavy trailers in categories M2, M3, N2, N3, O3 and O4, after UN Regulation 141 had required the sensors on newly approved types from July 6, 2022. Inserts must leave room for the sensor and for central inflation systems on tactical trucks, and RunFlat International already sells wheel assemblies with TPMS and CTIS integration. The Rodgard rim range noted in the segment analysis already reaches coach and truck sizes. Coach operators that carry passengers through high-risk corridors are the most likely early buyers of such combined packages.
Metal tariffs and program delays squeeze suppliers
U.S. metal tariffs raise insert costs
Higher U.S. metal tariffs raise the cost of steel cores, aluminum rims and hardware used in many insert designs. A White House proclamation raised Section 232 tariffs on steel and aluminum from 25% to 50% from June 4, 2025, while U.K. metal stayed at 25%. U.S. distributors importing finished kits or metal parts face the largest margin squeeze on fixed-price DLA contracts. Suppliers with U.S. machining, or U.K. plants shipping at the lower rate, are better placed to hold their prices.
Rubber costs keep band makers exposed
Rubber-band and rubber-faced insert makers remain exposed to natural rubber prices that they cannot pass through on long contracts. The World Bank reported that rubber prices rose 2% in the third quarter of 2025 on trade and weather concerns, and it forecast further rises of 2% in 2026 and 3% in 2027. Smaller converters with fixed quotes to armoring workshops carry most of this risk. Composite designs and indexed pricing clauses reduce the exposure, although both raise development costs.
Vehicle program delays make orders lumpy
Program delays turn original-equipment demand into lumpy, hard-to-plan orders for insert suppliers tied to one vehicle. Lawmakers said the JLTV A2 program was more than 20 months behind schedule with a backlog of about 2,000 vehicles, and the Marine Corps suspended new batches in its 2026 budget, according to Militarnyi. A supplier sized for full-rate production then carries idle tooling and inventory. Diversified suppliers with replacement-kit contracts across many fleets absorb such gaps more easily than single-platform specialists.
Airless tires threaten light commercial use
Puncture-proof tires threaten insert demand in light commercial vans, where operators want no flats rather than a short escape distance. Michelin and La Poste put Uptis tires on French delivery vans from June 27, 2023, with nearly 40 vans planned by 2024, although the tire still needed full road homologation. Logistics fleets are the most exposed segment if such airless designs reach volume. Heavier armored platforms face less near-term risk, since the published deployments cover light vans only.
North America leads while Europe adds orders fastest
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| North America | 191.6 | 36.0% | 4.4% |
| Europe | 154.3 | 29.0% | 6.1% |
| Asia Pacific | 111.8 | 21.0% | 5.6% |
| Middle East & Africa | 42.6 | 8.0% | 5.5% |
| Latin America | 31.9 | 6.0% | 5.3% |
North America leads on spares and tactical truck contracts
North America held 36.0% of 2025 value and grows at 4.4% a year, the largest share because U.S. agencies buy inserts both on new vehicles and as spares. SIPRI estimated U.S. military spending at USD 954 billion in 2025, down 7.5% in real terms, yet vehicle and spares contracts kept flowing through 2026. Oshkosh Defense received USD 214.7 million in FMTV A2 truck orders in February 2025. The slower rate reflects a mature fleet, where replacement cycles rather than new vehicles drive most purchases.
Europe grows fastest on German orders and a U.K. supply cluster
Europe accounts for 29.0% of 2025 value and is the fastest-growing region at 6.1% a year, supported by the German vehicle orders discussed above and by a dense U.K. supply cluster. Tyron Runflat in Loughborough said in December 2025 that it had invested in doubling its facility and planned a new design team for 2026. RunFlat International, a Westley Plastics subsidiary in Cradley Heath, and Run Flat Systems near Doncaster add to the cluster. This concentration gives European vehicle builders short qualification loops and local spares.
Asia Pacific combines military volume with price-led security demand
Asia Pacific holds 21.0% of 2025 value and grows at 5.6% a year, with demand split between military light vehicles and price-sensitive security conversions. Indian sellers on IndiaMART list cast nylon and composite inserts at INR 15,000 to 18,500 per piece, well below Western military kit prices. Tyron's Pattaya test facility shows European suppliers building capacity in the region. Public data on Chinese insert makers are thin, which limits confidence in the regional estimate.
Latin America depends on civil armoring rather than defense
Latin America holds 6.0% of 2025 value and grows at 5.3% a year, the only region where civil armoring rather than defense sets the pace. The record Brazilian armoring volume and the expected Mexican rise, both noted above, come mostly from private cars, so only cash-in-transit, security and executive fleets count toward this market. Public data do not show how many inserts local armorers make versus import, a gap that limits this estimate.
Middle East & Africa splits between Gulf defense and security fleets
The Middle East & Africa holds 8.0% of 2025 value and grows at 5.5% a year, with Gulf buyers of armored combat platforms and African security fleets as the two demand pools. SIPRI put Saudi Arabia's 2025 spending at USD 83.2 billion, up 1.4%. In South Africa, SVI Engineering ran a test vehicle 23 km at about 50 km/h over a spike strip on its Flats Over rings, which fit 16- to 23-inch wheels. Spike attacks on cash vans make such rings a practical purchase for security operators.
Insert launches and defense orders in 2025 and 2026
| Development | Status and market relevance |
|---|---|
| In September 2025, Tyron Runflat launched its lightest single-piece runflat and a discreet defense wheel at DSEI U.K. in London. | Launch; the company reported a first order at the show, an early sign of demand for lighter inserts. |
| In December 2025, Patria signed serial contracts with Germany for up to 876 6x6 armored vehicles valued at over 2 billion euros. | Order; deliveries begin in 2026 and create original-equipment insert demand. |
| In February 2026, DLA Land and Maritime awarded Hutchinson Industries an indefinite-delivery contract for run-flat kit inserts. | Order; the USD 350,000 ceiling runs to February 2027. |
| In June 2026, Tyron Runflat introduced a Carbon Composite Wheel at Eurosatory in Paris, citing up to 500 kg of weight savings. | Launch; enquiries from vehicle makers reported, no firm orders disclosed. |
| In August 2026, the U.S. Army awarded AM General a new HMMWV contract with an initial value of USD 82.2 million. | Order; orders may reach USD 754.6 million by August 2028. |
Rubber, composite and beadlock designs compete
- Rubber bands clamp a segmented rubber ring with a steel core around the rim and suit light and medium vehicles where fitting time matters.
- Composite inserts replace metal with reinforced polymers or carbon fiber to cut weight while carrying heavy armored loads.
- Combined beadlock runflats lock the tire bead to the rim and support the load, which keeps steering control after a blowout.
- Multi-piece wheel systems pair a static insert with a split rim and remain the standard for heavy tactical trucks and 8x8 carriers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Qualified specialists compete on weight and approvals
Competition turns on qualification, weight and run distance rather than on price alone. Hutchinson covers the widest range, from RRF Rodgard and HMR inserts for one-piece wheels to VFI, TMR and CMRF designs for two-piece tactical wheels, and it holds direct DLA contracts. Tyron Runflat competes on lightweight rubber bands and new composite wheels, and its test speed work targets special forces and VIP buyers. RunFlat International and Run Flat Systems compete for 4x4 and armored conversions with dynamic and combined beadlock inserts for standard wheels. SVI Engineering serves South African security fleets with its own rings, while Runflat Tire Systems in Hyderabad sells low-cost inserts to Indian converters. Entry is hard at the military end, because new suppliers need test approvals and source-list status before they can bid. The civilian end is more open, and price competition there is rising.
A handful of qualified specialists control supply
Supply is concentrated among a handful of specialists that hold military qualifications, with a long tail of regional converters below them. Published product documents in this group cite U.S. Army, NATO and FINABEL specifications, TUV approval or PAS 301 certification, and these approvals are the main entry barrier. Distributors such as TSS International, which sells Rodgard systems, and Triman Industries on DLA tenders sit between makers and buyers. Margins are highest on qualified military part numbers and lowest on commodity nylon rings sold to armoring shops, where price decides most orders.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Hutchinson | Full-line supplier | Military and security runflat inserts for one-piece and two-piece wheels, including Rodgard |
| Tyron Runflat Ltd | Specialist | Rubber runflat bands, single-piece runflats and composite wheels for armored vehicles |
| RunFlat International Ltd (Westley Plastics) | Specialist | Dynamic and static runflat inserts and complete military wheel assemblies |
| Run Flat Systems Ltd | Specialist | Combined beadlock runflat inserts for single-piece drop-center wheels |
| SVI Engineering | Armorer and insert maker | Flats Over runflat rings for armored and security vehicles in South Africa |
| Runflat Tire Systems | Local manufacturer | Composite and custom runflat inserts for Indian armored and utility vehicles |
Replacement kits matter more than new vehicles
Credence Research's view is that replacement and spares buying, not new vehicle builds, gives the commercial vehicle run-flat tire inserts market its stability. New European programs add volume from 2026, yet the steadier money sits in recurring kit tenders and depot refits. Suppliers should treat weight reduction and single-piece fitment as the two features most likely to win new fleets. Buyers should expect price gaps between qualified military kits and security-grade rings to persist, because approvals remain costly to earn. The largest uncertainty is how much of the civil armoring boom counts as commercial use rather than private cars.
Estimates rest on procurement and armoring data
The report uses 2025 as the base year and forecasts to 2035, with market values from the Credence Research model, which carries forward the earlier estimate of this market and checks it against a bottom-up count of vehicles fitted and kit prices. Regional, type and application splits are Credence Research estimates built from these inputs. Inputs come from SIPRI military spending data, U.S. procurement records, company product pages and releases, armoring association figures reported in the press, World Bank commodity data and published regulations. No interviews or surveys were conducted for this edition of the report.
European orders shape growth through 2035
Through 2035, growth in commercial vehicle run-flat tire inserts depends on European vehicle programs moving from order to delivery and on steady U.S. spares buying. Germany's locally built 6x6 vehicles from 2027 should add steady insert demand in the second half of the decade. Lighter composite and single-piece designs are likely to spread into police, ambulance and coach fleets, while airless tires may take some light van demand. Suppliers that combine military approvals with low-cost civilian lines will be best placed, and price pressure will rise at the civilian end as regional makers multiply.
Defense order timing sets the range of outcomes
The range of outcomes for commercial vehicle run-flat tire inserts depends mainly on how quickly European budgets become delivered vehicles and whether U.S. spares buying holds after the 2025 real-terms spending cut. Civil armoring adds a second, smaller swing factor in Latin America and Africa. Weight-saving and single-piece designs could lift the upside by opening police and emergency fleets, while airless tire adoption in vans would mainly affect the downside.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 3.8% | USD 783.9 million | European vehicle deliveries slip and U.S. spares budgets tighten after the 2025 cut |
| Base | 5.30% | USD 892.0 million | Announced vehicle programs deliver on schedule and civil armoring grows at recent rates |
| Upside | 6.6% | USD 996.1 million | NATO orders accelerate and single-piece inserts reach police and emergency fleets |
Frequently Asked Questions
How big is the commercial vehicle run-flat tire inserts market?
Which region leads the market?
Which application uses the most run-flat inserts?
How much does a run-flat insert cost?
What is the difference between a run-flat insert and a run-flat tire?
Who are the main suppliers of run-flat inserts?
What is driving demand for run-flat inserts?
What are the main challenges for insert suppliers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 17–18 Inch
- 1.2.2 19–20 Inch
- 1.2.3 22–24 Inch
- 1.2.4 Others
- 1.3 By Application
- 1.3.1 Military & Defense
- 1.3.2 Transportation & Logistics
- 1.3.3 Construction
- 1.3.4 Agricultural
- 1.3.5 Manufacturing
- 1.3.6 Others (Healthcare and Municipal)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 532.2 million → 2035: USD 892.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Commercial Vehicle Run-flat Tire Inserts Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Commercial Vehicle Run-flat Tire Inserts Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Commercial Vehicle Run-flat Tire Inserts Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Commercial Vehicle Run-flat Tire Inserts Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Commercial Vehicle Run-flat Tire Inserts Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Commercial Vehicle Run-flat Tire Inserts Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Commercial Vehicle Run-flat Tire Inserts Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Commercial Vehicle Run-flat Tire Inserts Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 532.2 million → 2035: USD 892.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Commercial Vehicle Run-flat Tire Inserts Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 17–18 Inch
- 12.3.7.2 19–20 Inch
- 12.3.7.3 22–24 Inch
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Military & Defense
- 12.4.7.2 Transportation & Logistics
- 12.4.7.3 Construction
- 12.4.7.4 Agricultural
- 12.4.7.5 Manufacturing
- 12.4.7.6 Others (Healthcare and Municipal)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Commercial Vehicle Run-flat Tire Inserts End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Commercial Vehicle Run-flat Tire Inserts Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Commercial Vehicle Run-flat Tire Inserts Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Commercial Vehicle Run-flat Tire Inserts Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Hutchinson
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Tyron Runflat Ltd
- 18.4 RunFlat International Ltd (Westley Plastics)
- 18.5 Run Flat Systems Ltd
- 18.6 SVI Engineering
- 18.7 Runflat Tire Systems
- 18.8 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

