
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cable Modems Market Size 2024 | USD 5,122.51 million |
| Cable Modems Market, CAGR | 5.52% |
| Cable Modems Market Size 2032 | USD 7,843.43 million |
Market overview
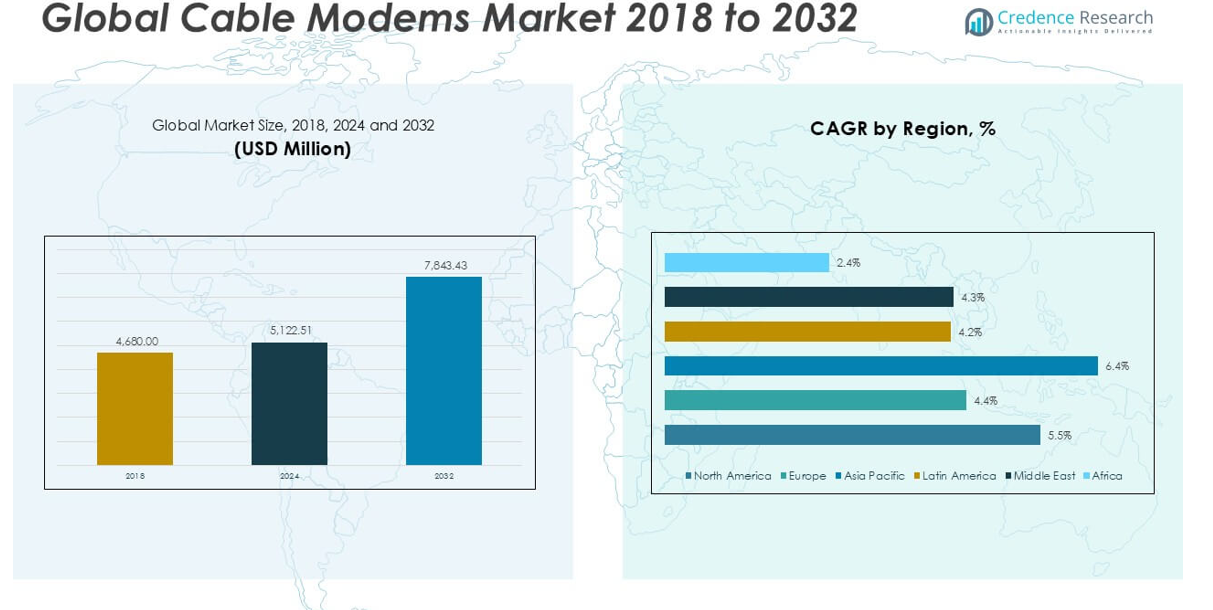
The Cable Modems market size was valued at USD 4,680.00 million in 2018, reached USD 5,122.51 million in 2024, and is anticipated to reach USD 7,843.43 million by 2032, at a CAGR of 5.52% during the forecast period.
The cable modems market is led by prominent players such as Arcadyan Technology Corporation, ARRIS International Limited, Cisco Systems, NETGEAR, TP-Link Technologies, Technicolor, and Broadcom, who collectively drive innovation and market growth through advanced product offerings and strategic partnerships. These companies focus on delivering high-speed, DOCSIS-compatible modems with enhanced security and connectivity features to meet evolving consumer demands. Asia Pacific holds the largest regional share, accounting for 41.2% of the global market in 2024, driven by rapid digitalization, expanding broadband infrastructure, and a growing consumer base. North America follows, supported by high internet penetration and advanced telecommunications networks.
Market Insights
- The Cable Modems market was valued at USD 4,680.00 million in 2018, reached USD 5,122.51 million in 2024, and is projected to reach USD 7,843.43 million by 2032 at a CAGR of 5.52% during the forecast period.
- Increasing demand for high-speed internet, driven by remote work, e-learning, and smart home adoption, is fueling market growth across both developed and emerging regions.
- Key trends include the rising adoption of DOCSIS 3.1 and 4.0 standards and growing penetration of mid-range cable modems, which hold the largest segment share due to their affordability and reliable performance.
- Major players like Arcadyan Technology Corporation, ARRIS International Limited, Cisco Systems, NETGEAR, and Technicolor lead the market through product innovation, though pricing pressure and competition from fiber and 5G technologies remain key restraints.
- Asia Pacific dominates the regional landscape with 41.2% market share in 2024, followed by North America at 30.1%, with wired modems holding a significant product segment share globally.
Market Segmentation Analysis:
By Type:
In the Cable Modems market, the wired segment holds the dominant market share, accounting for a significant portion of total revenue. Wired cable modems are widely preferred due to their stable connectivity, lower latency, and reliable high-speed internet delivery, especially for residential and enterprise users. The increasing demand for uninterrupted video streaming, online gaming, and large data transfers continues to drive the growth of this segment. Although wireless modems are gaining traction for their convenience and mobility, they currently lag behind wired options in terms of performance and widespread consumer preference.
- For instance, the NETGEAR CM1200 DOCSIS 3.1 cable modem delivers up to 2 Gbps download speeds via wired connections, supporting four Gigabit Ethernet ports, which ensures stability for multi-device streaming and gaming setups.
By Modem Speed:
The 601 - 1 Gbps modem speed segment dominates the Cable Modems market, securing the largest market share. Consumers increasingly prefer higher-speed modems to support bandwidth-intensive activities such as HD video streaming, virtual meetings, and smart home integrations. The growing adoption of gigabit internet plans by telecommunication providers further accelerates demand for modems in this speed range. Additionally, small businesses and remote workers require faster, more reliable internet connections, which significantly contributes to this segment’s dominance. The demand for future-proof technology that supports expanding digital requirements strengthens this segment’s position in the market.
- For instance, ARRIS SURFboard SB8200 supports up to 2 Gbps download speeds and handles over 1 Gbps throughput, with dual Gigabit Ethernet ports enabling users to fully utilize multi-gigabit internet plans.
By Price Point:
The mid-range price point segment leads the Cable Modems market, holding the largest revenue share. These modems offer a balanced combination of cost-effectiveness and advanced features, making them the preferred choice among both residential users and small businesses. Consumers are increasingly looking for reliable, high-performance modems without premium pricing, and the mid-range category effectively meets this demand. Additionally, competition among manufacturers has resulted in frequent product upgrades and price optimization in this segment, further driving its growth. The mid-range segment is likely to maintain its leadership due to its affordability and performance balance.
Market Overview
Rising Demand for High-Speed Internet Connectivity
The growing consumer and enterprise demand for high-speed internet is a primary driver of the cable modems market. With the increasing use of bandwidth-intensive applications such as 4K video streaming, online gaming, remote work, and virtual conferencing, there is a continuous need for faster and more reliable internet connections. Telecommunication providers are expanding gigabit internet services, which further drives the adoption of advanced cable modems capable of supporting high-speed data transmission. This trend is significantly fueling the market's growth across both developed and emerging economies.
- For instance, TP-Link’s TC-7610 cable modem supports DOCSIS 3.0 with up to 343 Mbps download speeds and is compatible with major service providers like Comcast XFINITY, driving broad adoption in high-speed internet packages.
Expansion of Smart Homes and IoT Devices
The rapid proliferation of smart homes and Internet of Things (IoT) devices is accelerating the need for high-performance, stable internet connections, boosting cable modem demand. Consumers are increasingly integrating smart TVs, security systems, voice assistants, and connected appliances into their homes, all of which require consistent, high-speed internet access. Cable modems, particularly in the mid-range and premium categories, offer the necessary bandwidth and reliability to support these connected ecosystems. This rising dependency on smart home technologies is creating sustained growth opportunities in the cable modems market.
- For instance, the Cisco DPC3941T cable modem supports over 32 downstream and 8 upstream channels, enabling it to manage dense smart home environments with multiple active IoT devices without sacrificing performance.
Growing Remote Work and E-Learning Adoption
The shift towards remote work and e-learning, accelerated by the global pandemic, continues to act as a major growth driver for the cable modems market. Households now require higher internet speeds to manage multiple connected devices simultaneously for video conferencing, online collaboration, and virtual classrooms. This new working and learning environment has pushed many consumers to upgrade their internet plans and invest in higher-performance cable modems. The long-term adoption of hybrid work models and digital education platforms is expected to sustain this increased demand.
Key Trends & Opportunities
Integration of DOCSIS 3.1 and 4.0 Standards
The adoption of advanced DOCSIS (Data Over Cable Service Interface Specification) standards, particularly DOCSIS 3.1 and the emerging DOCSIS 4.0, is a significant market trend. These technologies enable faster data speeds and improved network efficiency, which meet growing consumer expectations for high-performance internet. Manufacturers are actively developing and promoting modems that support these standards to capitalize on their performance advantages. The continued rollout of DOCSIS 4.0 presents an opportunity for companies to introduce next-generation products that cater to future high-bandwidth applications.
- For instance, the ARRIS SURFboard G36 supports DOCSIS 3.1 and delivers download speeds up to 2.5 Gbps, positioning it for the next phase of gigabit internet deployment.
Growing Penetration in Developing Markets
Expanding internet infrastructure and rising digital adoption in developing regions present a key opportunity for the cable modems market. As broadband services become more accessible and affordable, there is a growing customer base in Asia-Pacific, Latin America, and parts of Africa. The demand for cost-effective, entry-level cable modems is particularly high in these regions, driven by the increasing number of first-time internet users. Market players focusing on price-sensitive, scalable solutions can effectively tap into these emerging markets for long-term growth.
- For instance, TP-Link’s TC-W7960 cable modem-router combo, offering speeds up to 343 Mbps, has gained popularity in price-sensitive markets like India and Brazil due to its affordability and integrated Wi-Fi capabilities
Key Challenges
Intense Competition from Fiber and Wireless Technologies
One of the major challenges for the cable modems market is the rising competition from fiber-optic and advanced wireless technologies. Fiber-to-the-home (FTTH) solutions offer faster, more stable internet speeds, while 5G is rapidly advancing as a competitive alternative for residential and enterprise connectivity. These technologies threaten to reduce the market share of traditional cable broadband services, potentially slowing the demand for cable modems, especially in highly developed urban areas.
Security and Network Vulnerabilities
Security concerns related to cable modems, including susceptibility to hacking and data breaches, pose a significant challenge. As more devices become connected, safeguarding home and enterprise networks becomes critical. Outdated firmware and the lack of timely security updates make some cable modems vulnerable, leading consumers to seek more secure alternatives. This issue forces manufacturers to invest in improved security features, driving up production costs and complicating product development cycles.
Technological Obsolescence and Compatibility Issues
The rapid pace of technological advancements can render existing cable modem models obsolete, creating a product lifecycle management challenge for manufacturers. Consumers demand future-proof devices that can seamlessly integrate with evolving broadband technologies and smart home ecosystems. Compatibility issues with newer service provider networks or emerging DOCSIS standards may limit the appeal of older modem models, compelling companies to innovate continuously and manage inventory risks associated with outdated technology.
Regional Analysis
North America North America holds a dominant position in the cable modems market, accounting for the largest market share of approximately 30.1% in 2024. The market size increased from USD 1,430.21 million in 2018 to USD 1,542.87 million in 2024, and it is projected to reach USD 2,358.53 million by 2032, growing at a CAGR of 5.5%. The region benefits from widespread broadband penetration, advanced telecommunication infrastructure, and high consumer demand for high-speed internet. The strong presence of major service providers and rapid adoption of smart home devices further strengthen North America’s leadership in the global market.
Europe
Europe holds a significant market share of approximately 17.4% in 2024 within the global cable modems market. The market size grew from USD 863.46 million in 2018 to USD 892.71 million in 2024 and is expected to reach USD 1,256.93 million by 2032, registering a CAGR of 4.4%. The increasing demand for high-speed connectivity across residential and commercial sectors, coupled with government investments in broadband expansion, drives growth in this region. European consumers' rising preference for DOCSIS 3.1 cable modems and the growing adoption of telecommuting further support the market’s steady progression.
Asia Pacific
Asia Pacific leads as the fastest-growing region in the cable modems market, holding a market share of approximately 41.2% in 2024. The regional market expanded from USD 1,877.62 million in 2018 to USD 2,110.71 million in 2024 and is projected to reach USD 3,448.64 million by 2032, driven by a robust CAGR of 6.4%. Rapid urbanization, expanding broadband infrastructure, and the increasing use of internet-based applications fuel demand across key countries such as China, India, and Japan. The region's growing consumer base and favorable government initiatives for digital connectivity significantly contribute to market growth.
Latin America
Latin America represents a smaller but steadily growing segment in the cable modems market, with a market share of approximately 4.7% in 2024. The market size increased from USD 220.90 million in 2018 to USD 238.66 million in 2024 and is expected to reach USD 329.97 million by 2032, registering a CAGR of 4.2%. The region’s market growth is driven by improving broadband infrastructure, rising digital adoption, and increasing internet penetration in both urban and semi-urban areas. Affordability of cable internet services and growing consumer awareness about high-speed connectivity further support the region’s development.
Middle East
The Middle East cable modems market holds a market share of approximately 3.7% in 2024. The regional market grew from USD 186.26 million in 2018 to USD 191.55 million in 2024 and is forecasted to reach USD 265.94 million by 2032, expanding at a CAGR of 4.3%. The increasing demand for high-speed broadband in commercial hubs, smart city initiatives, and expanding digital infrastructure are key growth factors. However, compared to other regions, market penetration remains moderate, offering opportunities for further growth as governments invest in enhancing telecommunication networks.
Africa
Africa accounts for the smallest share in the cable modems market, holding approximately 2.9% in 2024. The market size rose from USD 101.56 million in 2018 to USD 146.01 million in 2024 and is expected to reach USD 183.41 million by 2032, growing at a CAGR of 2.4%. Growth in the region is mainly supported by increasing efforts to improve broadband accessibility and affordability. However, challenges such as limited infrastructure, low consumer purchasing power, and competition from mobile internet solutions restrain rapid expansion. Despite this, Africa presents long-term potential as digitalization gradually progresses.
Market Segmentations:
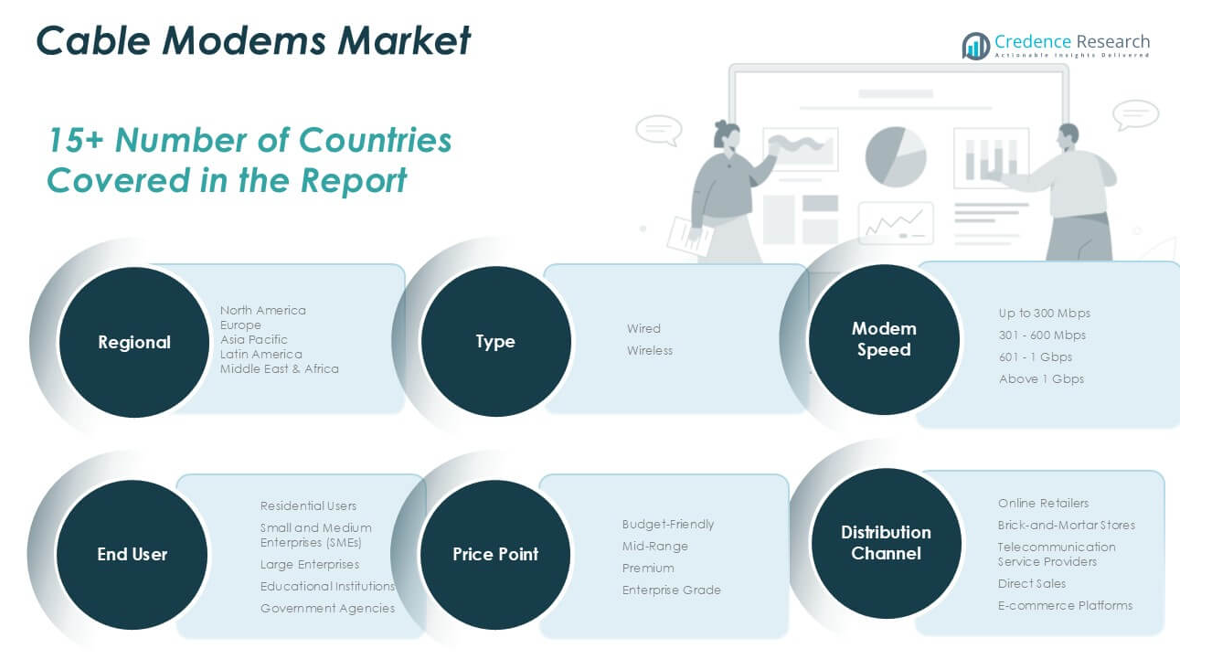
By Type
- Wired
- Wireless
By Modem Speed
- Up to 300 Mbps
- 301 - 600 Mbps
- 601 - 1 Gbps
- Above 1 Gbps
By Price Point
- Budget-Friendly
- Mid-Range
- Premium
- Enterprise Grade
By End User
- Residential Users
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- Educational Institutions
- Government Agencies
By Distribution Channel
- Online Retailers
- Brick-and-Mortar Stores
- Telecommunication Service Providers
- Direct Sales
- E-commerce Platforms
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The cable modems market is highly competitive, characterized by the presence of several established global and regional players striving to expand their market share through product innovation, strategic partnerships, and geographic expansion. Key companies such as Arcadyan Technology Corporation, ARRIS International Limited, Cisco Systems, NETGEAR, TP-Link Technologies, and Technicolor dominate the market with extensive product portfolios and strong distribution networks. These players are focusing on developing advanced modems compatible with the latest DOCSIS standards to meet the rising demand for high-speed connectivity. Additionally, companies are enhancing their offerings with features like dual-band support, improved security, and energy efficiency to differentiate their products. Strategic collaborations with telecommunication service providers and investments in emerging markets are common growth strategies. The market also witnesses competition from new entrants introducing cost-effective solutions, intensifying pricing pressure. Continuous technological advancements and the need for future-proof, high-performance devices drive the competitive dynamics within the global cable modems market.
Key Player Analysis
- Arcadyan Technology Corporation
- ARRIS International Limited
- Askey Computer Corporation
- CastleNet Technology
- Cisco Systems
- D-Link Corporation
- Lindsay Broadband
- MTRLC LLC
- NETGEAR
- Technicolor
- TP-Link Technologies
- Zoom Telephonics
- Casa Systems
- Broadcom
- C9 Networks
- Vecima Networks
- Teleste Corporation
- UBee
Recent Developments
- In March 2024, Netgear introduced a new Nighthawk DOSCIS 3.1 high-speed internet cable modem CM3000 for providing high speed internet connectivity. This modem device can support up to 2.5 GBPS and has a high upload speed of 1 GBPS.
- In October 2023, Arris, a subsidiary of CommScope, launched a new ARRIS SURFboard Wi-Fi 7 cable modem for internet connection. It has a high speed internet connectivity of 10 GBPS and can be used for residential and industrial enterprises.
- In January 2023, CommScope announced its entry into the Wi-Fi 7 retail market with the introduction of the SURFboard G54 DOCSIS 3.1 quad-band Wi-Fi 7 cable modem. The leading SURFboard G54 offers significant performance improvements, including the latest Wi-Fi 7 technology, and is compatible with multi-gigabit Internet plans. The SURFboard G54 is engineered to incorporate other advanced features such as DOCSIS 3.1, quad-band Wi-Fi 7, a 10 Gbps Ethernet port, and four 1 Gbps LAN ports.
Market Concentration & Characteristics
The Cable Modems Market shows a moderately concentrated structure, with several key players holding significant shares while smaller companies contribute to niche segments. It features a blend of global leaders and regional manufacturers competing on product quality, speed, security, and pricing. Major players such as Arcadyan Technology Corporation, ARRIS International Limited, Cisco Systems, NETGEAR, TP-Link Technologies, and Technicolor maintain a strong foothold through advanced technology and wide distribution channels. It is highly technology-driven, with rapid product life cycles requiring continuous upgrades to meet evolving DOCSIS standards and consumer demands for faster internet. Price sensitivity impacts competition, particularly in developing regions where mid-range and budget-friendly modems dominate. Product differentiation focuses on speed, compatibility, and security features to attract diverse customer groups. It faces external pressure from the growing adoption of fiber-optic and wireless broadband alternatives, which challenge long-term demand stability. The market requires sustained innovation to retain consumer interest and defend against technology displacement.
Report Coverage
The research report offers an in-depth analysis based on Type, Modem Speed, Price Point, End User, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for high-speed cable modems will continue to rise, driven by remote work and digital learning.
- Mid-range cable modems will remain the most preferred segment due to their balance of cost and performance.
- Adoption of DOCSIS 4.0 technology will shape future product development and market competitiveness.
- Asia Pacific will retain its position as the leading regional market with strong growth potential.
- North America will continue to show stable demand supported by advanced broadband infrastructure.
- Competition from fiber-optic and 5G technologies will create pricing and market share challenges.
- Manufacturers will focus on improving security features to address rising concerns over network vulnerabilities.
- Product innovation will emphasize faster speeds, energy efficiency, and multi-device compatibility.
- Emerging markets in Latin America and Africa will offer new opportunities for low-cost cable modem providers.
- Strategic partnerships with telecommunication service providers will remain essential for expanding market reach.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of High-Speed Internet Applications
The increasing use of bandwidth-intensive applications such as 4K video streaming, online gaming, and virtual conferencing is driving the need for faster and more reliable cable modems, pushing both consumers and enterprises to upgrade their devices.
Expansion of Smart Homes and IoT Devices
The rapid adoption of smart home technologies and IoT devices requires stable, high-speed internet connections, boosting demand for advanced cable modems that can support multiple connected devices simultaneously.
Remote Work and E-Learning Trends
The shift toward remote work and digital education, accelerated by the pandemic, has led households and businesses to invest in higher-performance cable modems to ensure seamless connectivity for multiple users and devices.
Adoption of Advanced DOCSIS Standards
The rollout of DOCSIS 3.1 and 4.0 standards enables higher data speeds and improved network efficiency, prompting consumers and service providers to adopt new cable modems compatible with these technologies.
Broadband Infrastructure Expansion in Emerging Markets
Ongoing investments in broadband infrastructure, especially in Asia Pacific and developing regions, are increasing internet accessibility and driving demand for cost-effective cable modems among new and existing internet users.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cable Modems Market?
What are the key segments within the Cable Modems Market?
What are some challenges faced by the Cable Modems Market?
Who are the major players in the Cable Modems Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Wired
- 1.2.2 Wireless
- 1.3 By End User
- 1.3.1 Residential Users
- 1.3.2 Small and Medium Enterprises (SMEs)
- 1.3.3 Large Enterprises
- 1.3.4 Educational Institutions
- 1.3.5 Government Agencies
- 1.4 By Modem Speed
- 1.4.1 Up to 300 Mbps
- 1.4.2 301 - 600 Mbps
- 1.4.3 601 - 1 Gbps
- 1.4.4 Above 1 Gbps
- 1.5 By Price Point
- 1.5.1 Budget-Friendly
- 1.5.2 Mid-Range
- 1.5.3 Premium
- 1.5.4 Enterprise Grade
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,122.51 million → 2032: USD 7,843.43 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cable Modems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cable Modems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cable Modems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cable Modems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cable Modems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cable Modems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cable Modems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cable Modems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,122.51 million → 2032: USD 7,843.43 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cable Modems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Wired
- 12.3.7.2 Wireless
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Residential Users
- 12.4.7.2 Small and Medium Enterprises (SMEs)
- 12.4.7.3 Large Enterprises
- 12.4.7.4 Educational Institutions
- 12.4.7.5 Government Agencies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Modem Speed - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Up to 300 Mbps
- 12.5.7.2 301 - 600 Mbps
- 12.5.7.3 601 - 1 Gbps
- 12.5.7.4 Above 1 Gbps
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Price Point - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Budget-Friendly
- 12.6.7.2 Mid-Range
- 12.6.7.3 Premium
- 12.6.7.4 Enterprise Grade
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cable Modems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cable Modems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cable Modems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cable Modems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arcadyan Technology Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 ARRIS International Limited
- 18.4 Cisco Systems
- 18.5 NETGEAR
- 18.6 TP-Link Technologies
- 18.7 Technicolor
- 18.8 Broadcom
- 18.9 D-Link Corporation
- 18.10 Casa Systems
- 18.11 Zoom Telephonics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

