
Brain-inspired systems move from lab racks to edge devices
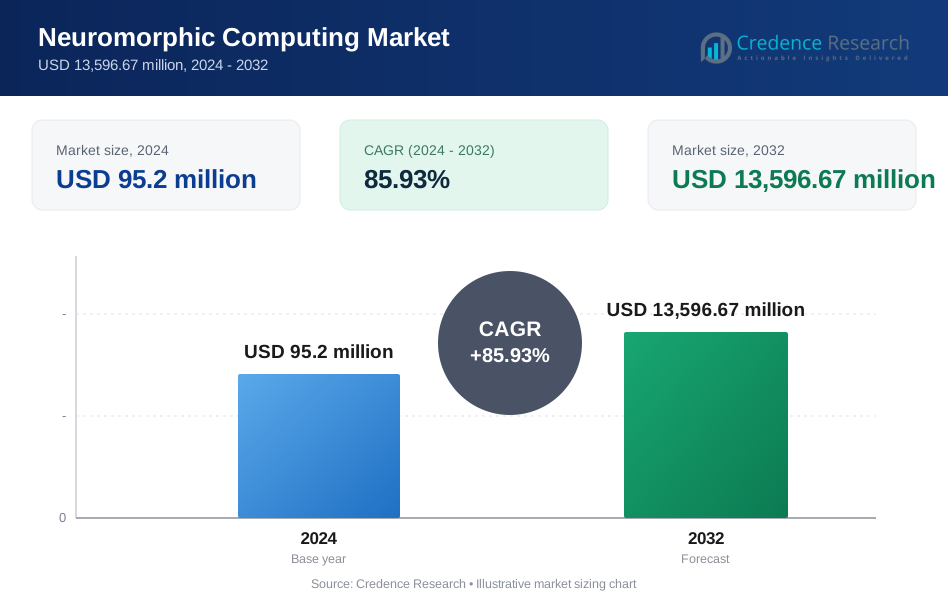
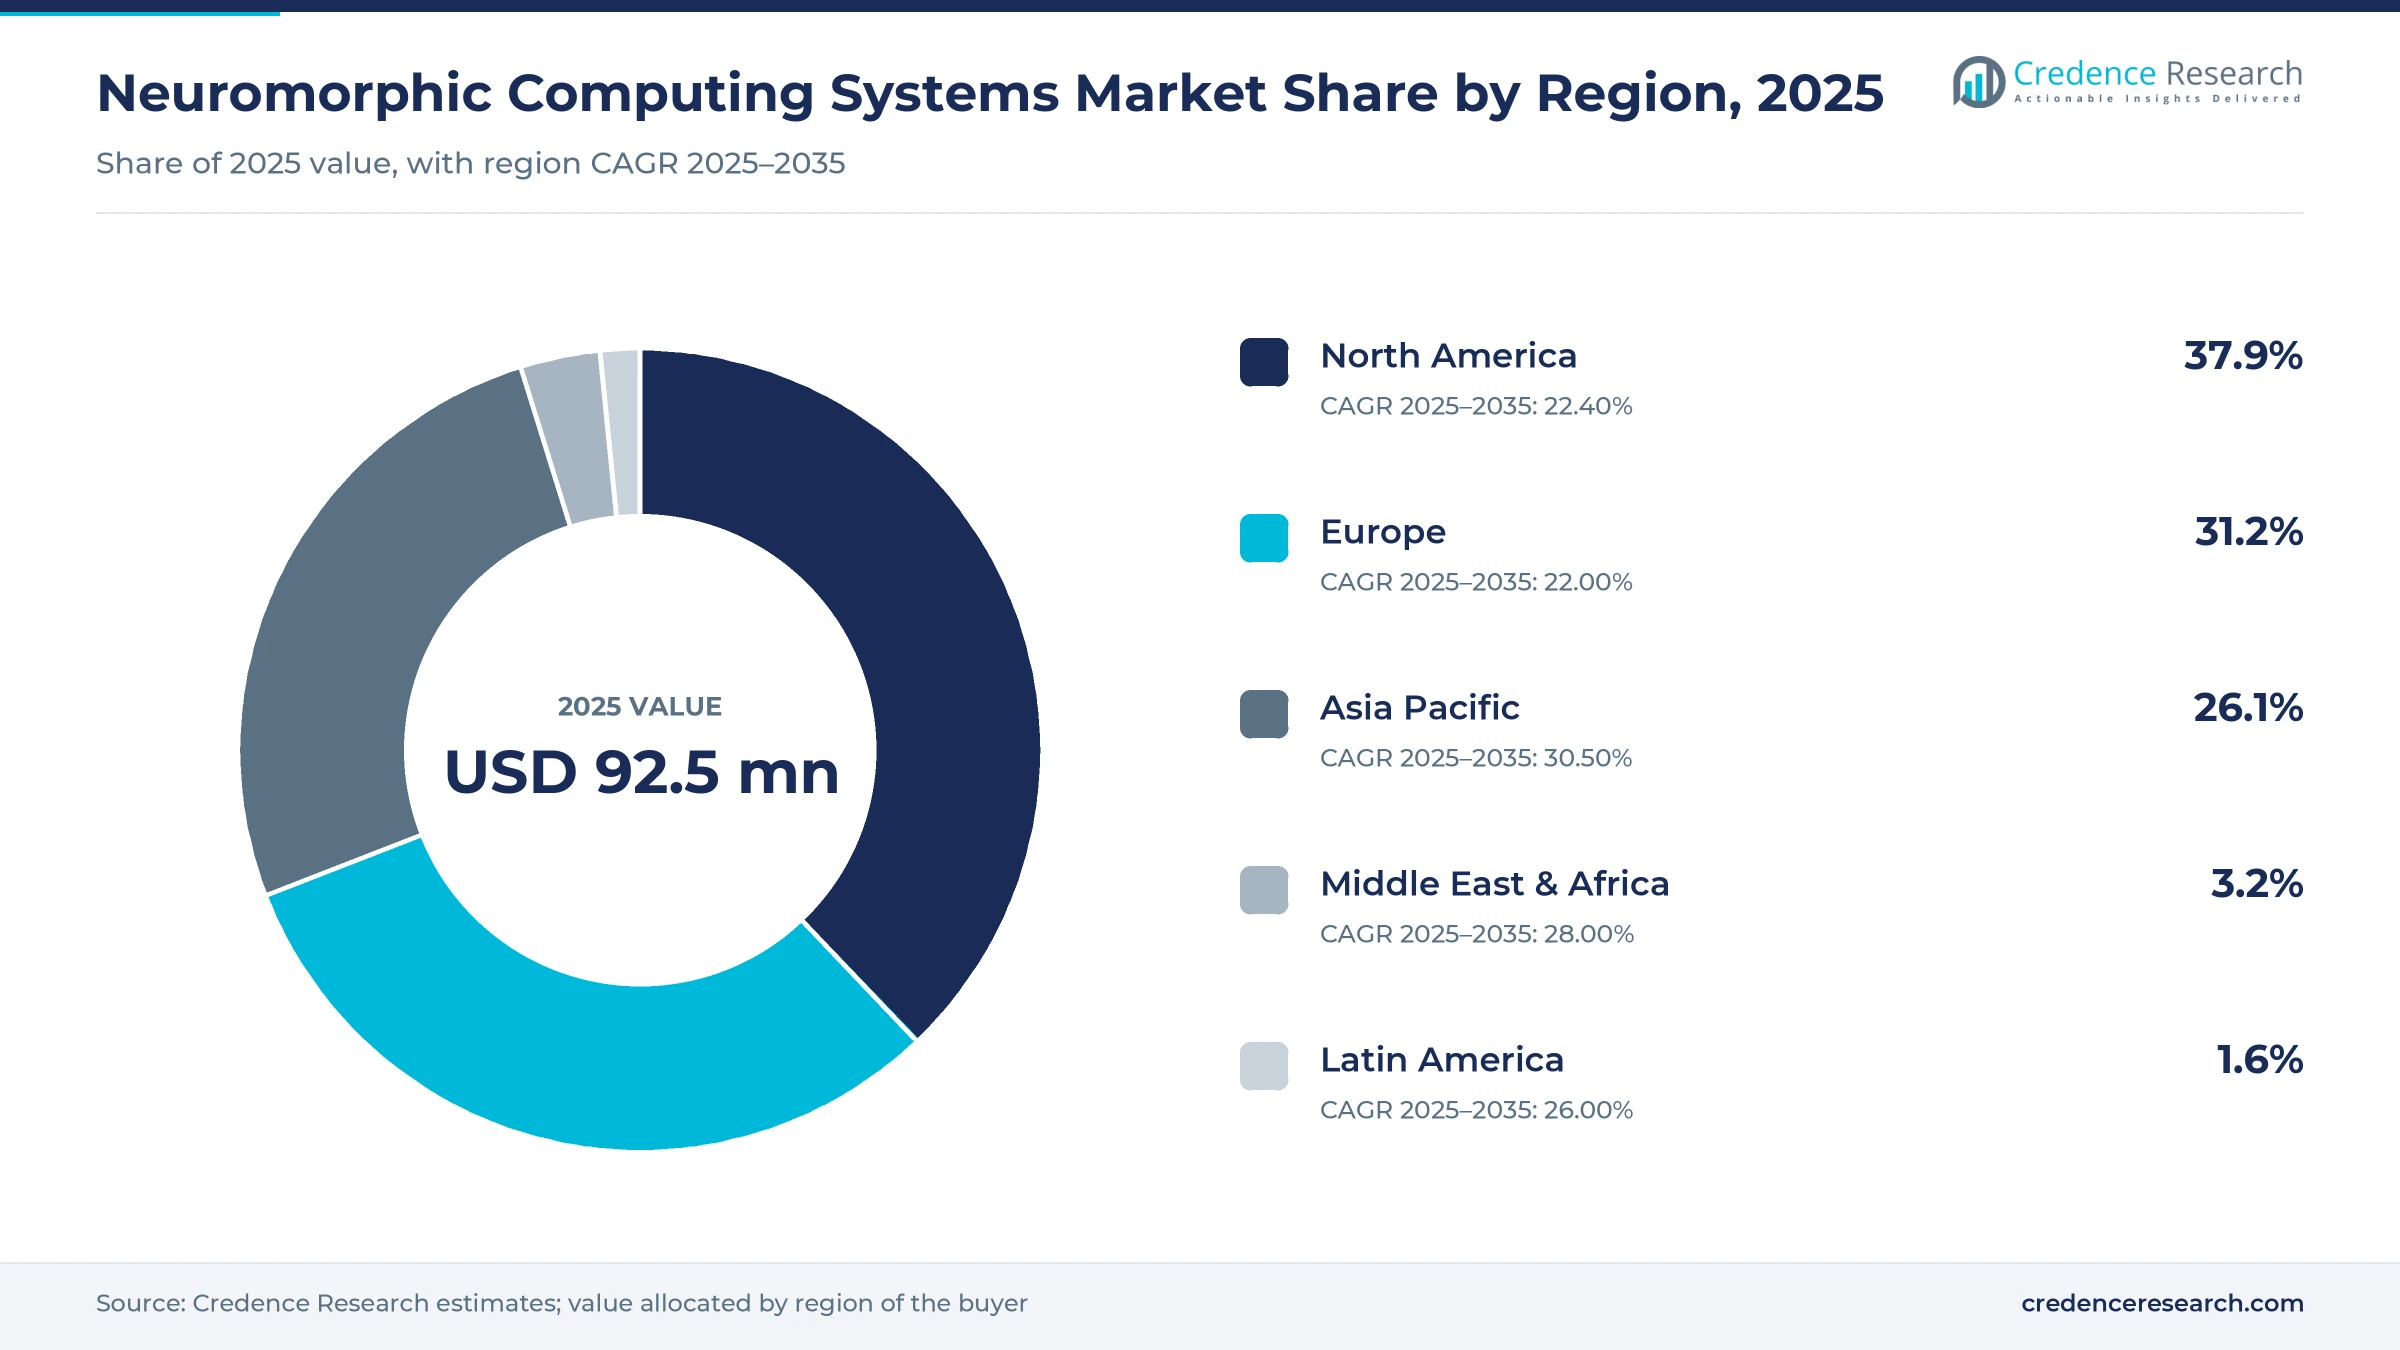
The neuromorphic computing systems market was valued at USD 92.5 million in 2025 and is projected to increase from USD 111.5 million in 2026 to USD 871.2 million by 2035, registering a CAGR of 25.14% during 2025–2035. Three forces lift demand, namely the power cost of artificial intelligence, steady public funding for national laboratories and universities, and the need for always-on sensing in wearables, radar sensors and industrial cameras that must run on milliwatt power budgets. North America held the largest regional share, 37.9% in 2025, because U.S. national laboratories host both Intel's Hala Point and the SpiNNaker2-based Braunfels system. Asia Pacific, by contrast, is the fastest-growing region at 30.50% a year. The main commercial change is the arrival of hybrid parts such as Innatera's Pulsar microcontroller, launched in May 2025, which place a spiking engine beside a standard RISC-V core, so device makers can add neuromorphic processing without redesigning the product.
Who buys neuromorphic systems and what is counted?
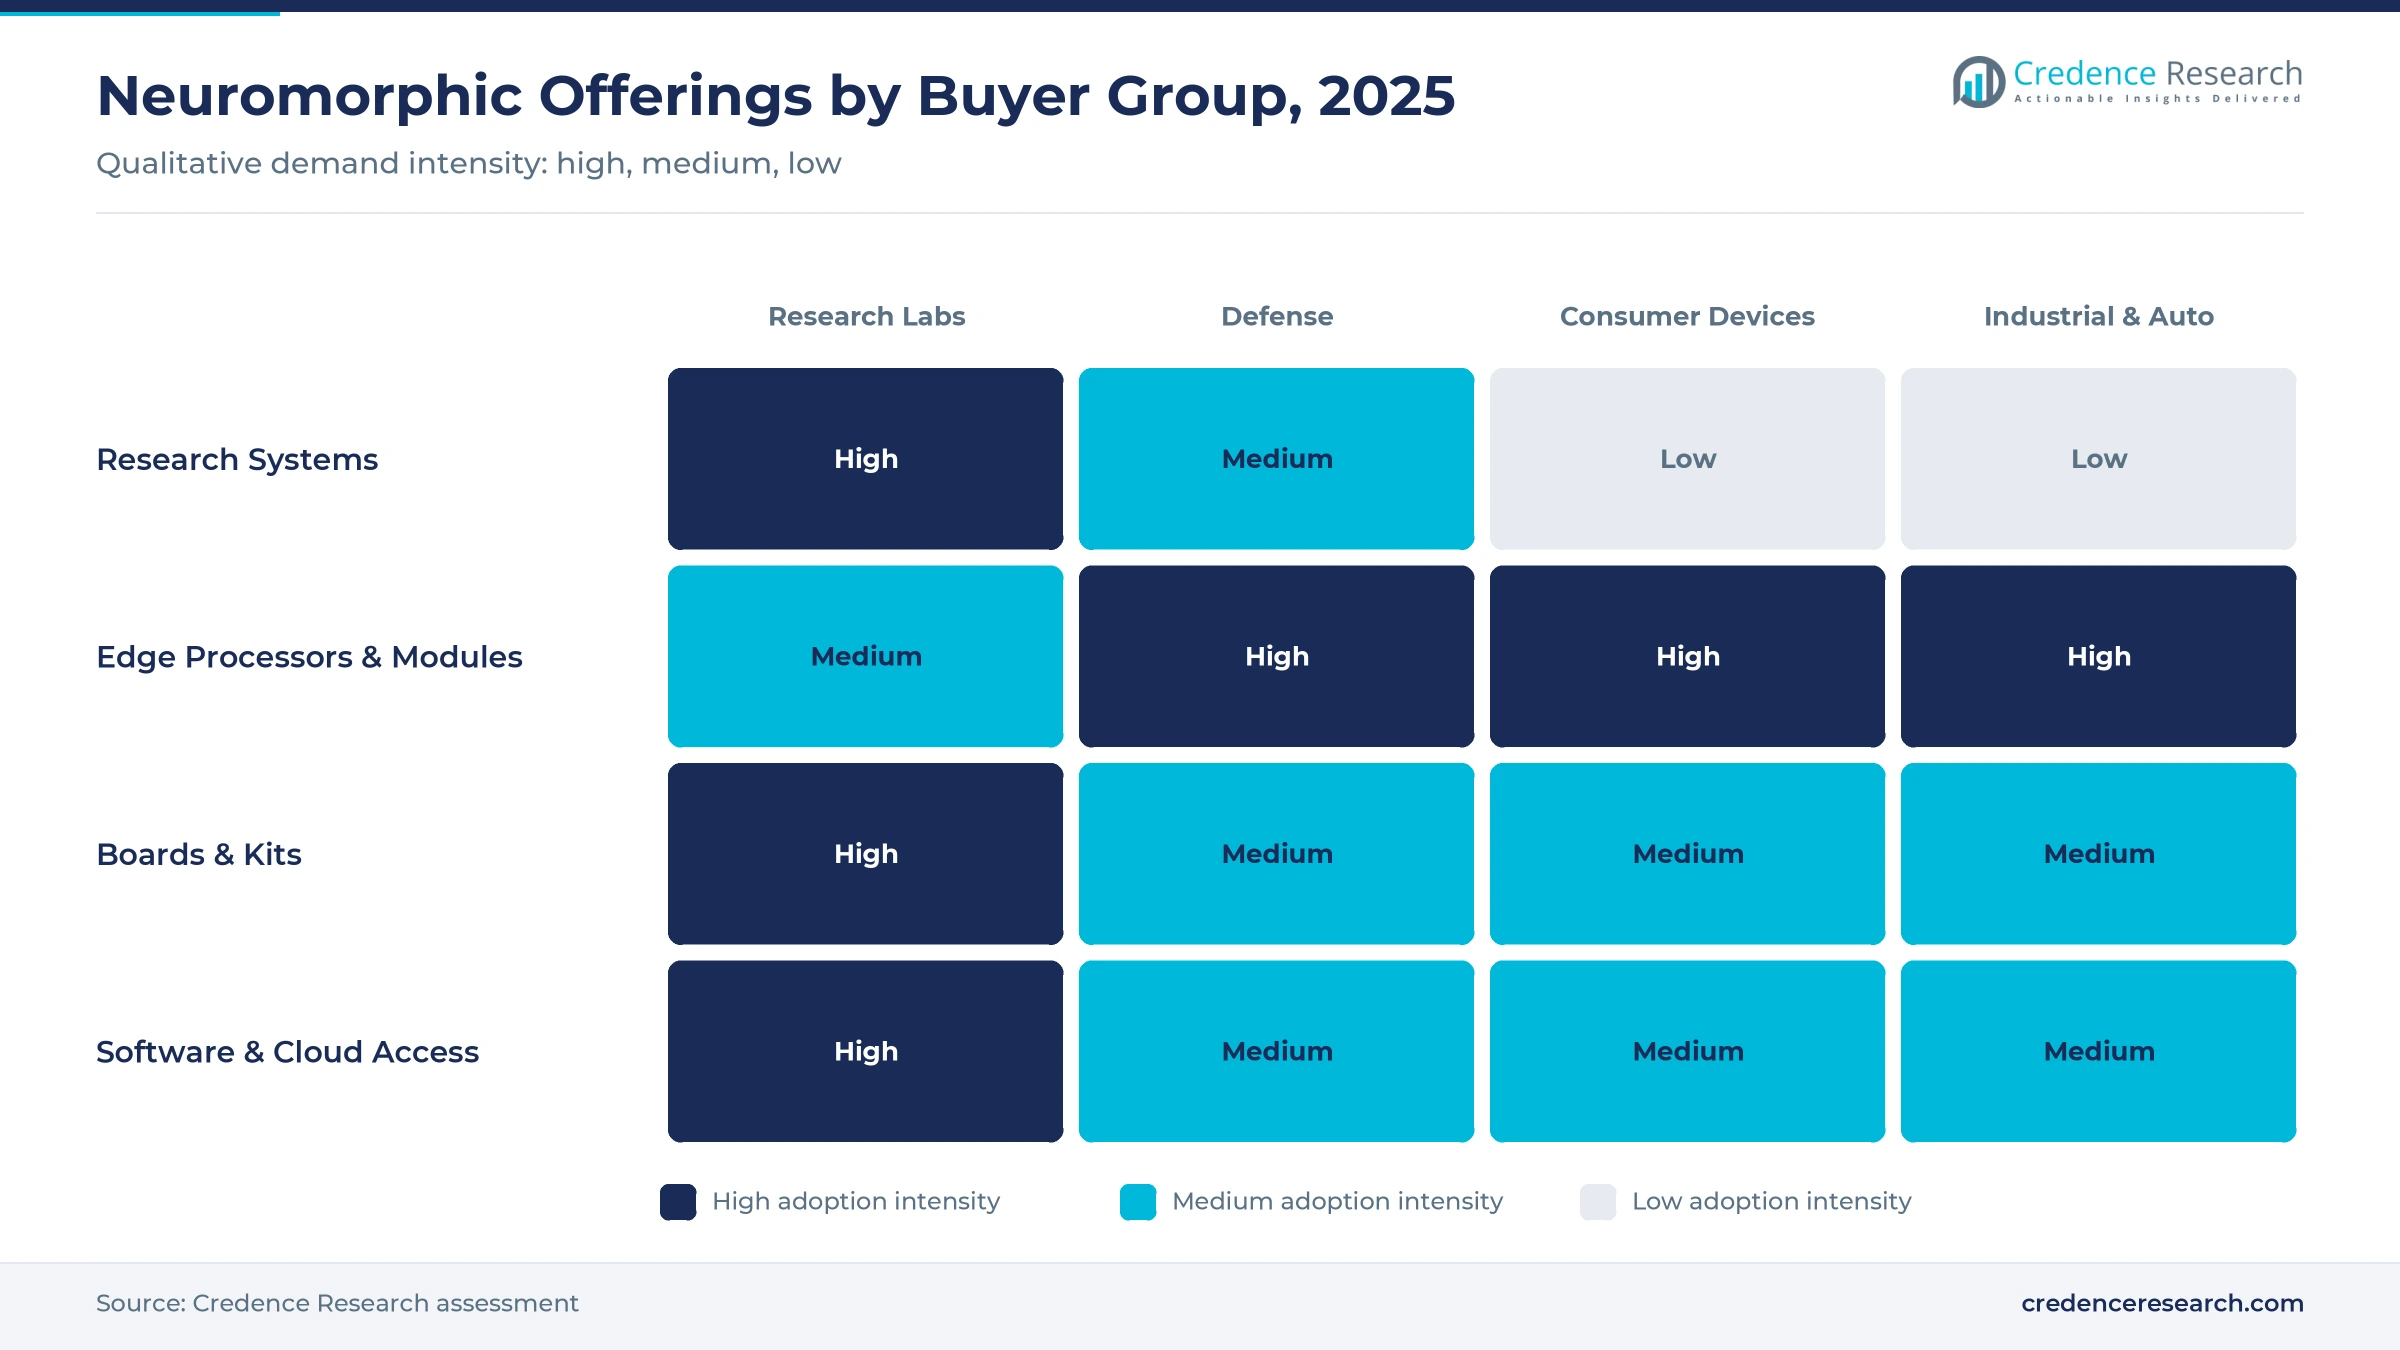
A large neuromorphic system is still a research instrument ordered one at a time by a laboratory with a specific question. Hala Point, for example, packs 1,152 Loihi 2 processors and 140,544 neuromorphic cores into a six-rack-unit chassis drawing at most 2,600 watts, according to Intel. Edge buyers behave differently, since device makers buy processors in modules, boards and reference designs, then pay for software and integration help to train their first spiking models.
The market counts research machines, edge processors sold in modules or reference platforms, development boards and kits, and software, cloud access and services. Bare neuromorphic chips, custom silicon work and event-based vision sensors sold on their own are excluded, as are conventional GPUs, NPUs and inference accelerators even when they run spiking network software, which keeps the estimate far below headline AI hardware figures.
Neuromorphic Computing Systems Market Insights
- The neuromorphic computing systems market is projected to grow from USD 111.5 million in 2026 to USD 871.2 million by 2035, a 25.14% CAGR, as edge devices add spiking processors.
- North America held 37.9% of 2025 value, the largest regional share, because Sandia National Laboratories hosts both the Hala Point and Braunfels systems.
- Large-scale research systems accounted for 46.0% of 2025 value, the largest offering, since each order bundles multi-rack hardware, cooling, interconnect and support.
- Hybrid microcontrollers that pair a spiking engine with a RISC-V core, such as Innatera's Pulsar from May 2025, are moving neuromorphic processing into consumer and industrial devices.
- SpiNNcloud placed SpiNNaker2 systems at Sandia, TU Dresden and UT San Antonio and won a Leipzig University order in 2025–2026, making it the most active system supplier.
Research machines lead while edge processors set the pace
Research systems lead the offering mix while edge processors and modules grow fastest
Based on offering, the market is categorized into large-scale research systems, edge processors and modules, development boards and kits, and software, cloud access and services. Large-scale research systems led with 46.0% of 2025 value, because each SpiNNaker2, Loihi 2 or NorthPole installation carries multi-rack hardware and support contracts. Edge processors and modules grow fastest at 36.00% a year, counted when they ship in a module, board or reference platform for edge computing deployments.
Government labs lead by end-use while consumer electronics grows fastest
Based on end-use, the market is categorized into research and government labs, military and defense, consumer electronics, industrial and IoT, automotive and healthcare. Research and government labs led with 40.6% of 2025 value, as national programs in the U.S., Germany and China fund most system purchases. Consumer electronics grows fastest at 34.50% a year as spiking processors enter wearables, hearables and smart home sensors that must listen all day on small batteries.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2025–2035 |
|---|---|---|---|---|
| By Offering | Large-Scale Research Systems | 46.0% | Edge Processors & Modules | 36.00% |
| By End-use | Research & Government Labs | 40.6% | Consumer Electronics | 34.50% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Power limits, lab funding and always-on sensing drive demand
The power cost of AI makes energy per inference a buying criterion
Data center power is now a planning limit for large AI buyers, and neuromorphic hardware sells on energy per inference. Intel says its Hala Point system reaches 20 petaops and more than 15 TOPS/W on conventional deep neural networks. IBM's NorthPole team reports a rack serving 28 concurrent users of an 8-billion-parameter language model at 2.8 ms per token. Results like these keep the high-performance computing community buying neuromorphic test systems through 2035, even before production workloads move over.
Public research funding turns into system orders and access fees
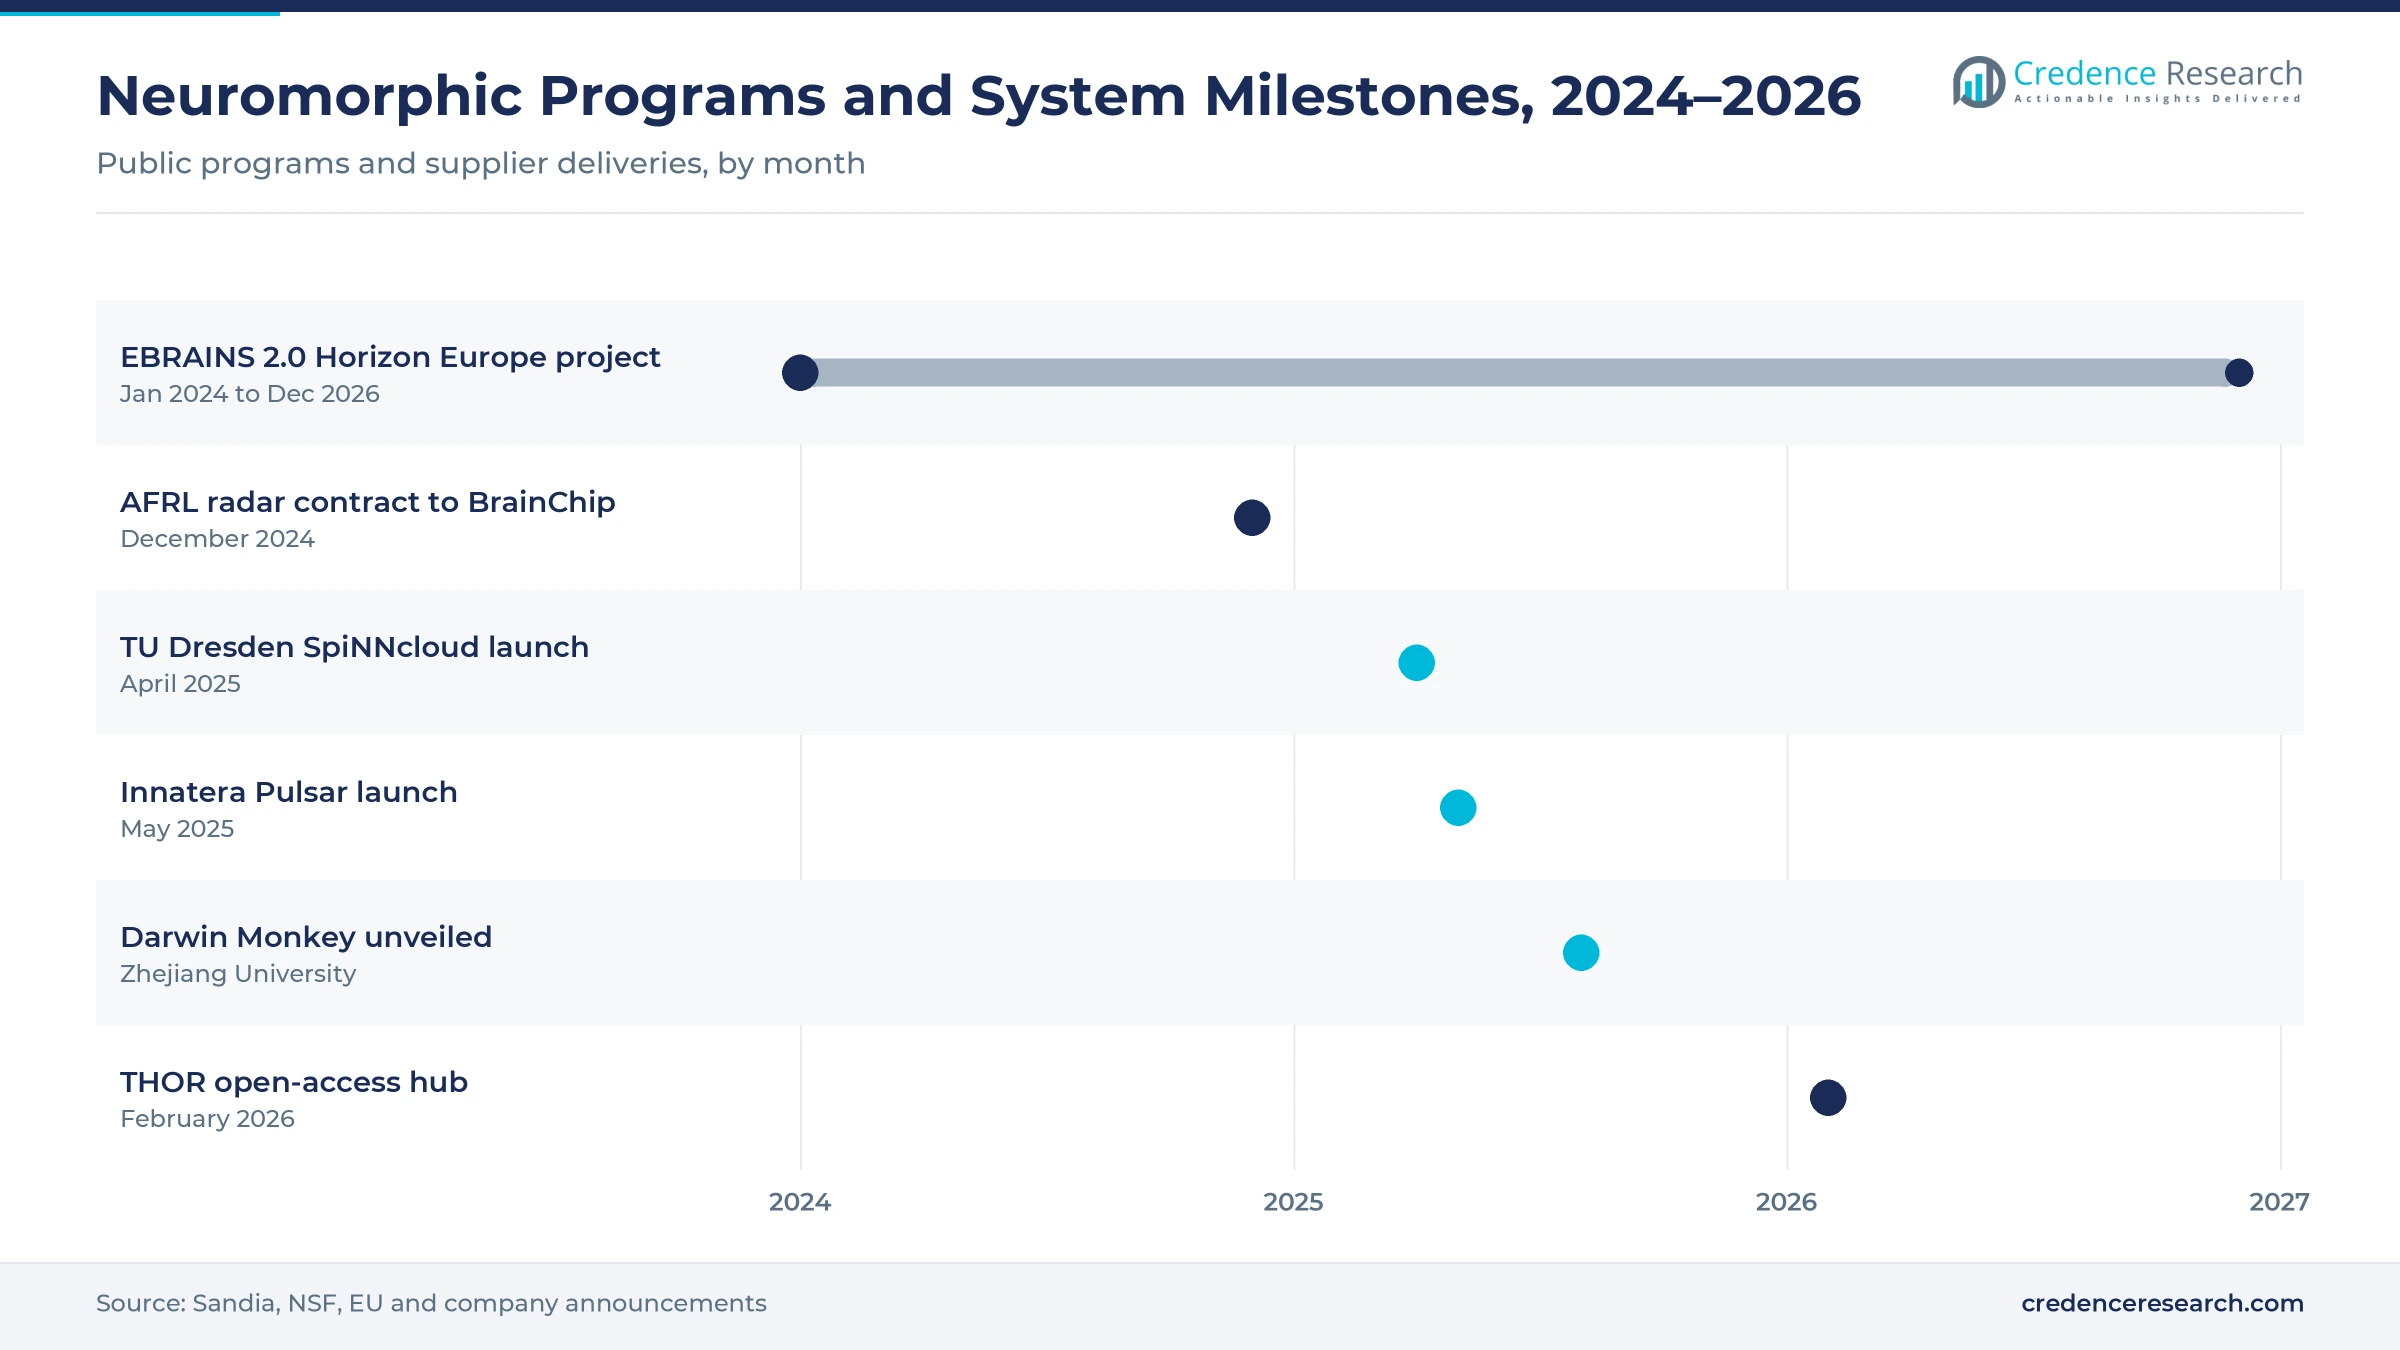
Research and government labs account for 40.6% of 2025 value. Sandia National Laboratories installed its Braunfels SpiNNaker2 system to study nuclear deterrence missions, with each chip carrying 153 Arm-based cores. TU Dresden's machine was funded by the European Regional Development Fund and Saxony, and the EBRAINS 2.0 Horizon Europe project runs from January 2024 to December 2026. Each of these funded programs turns into system orders, access fees and support contracts over the next 3 to five years.
Defense platforms need signal processing within tight power budgets
Drones, aircraft and satellites process radar and radio signals continuously but are short of power, weight and space. The U.S. Air Force Research Laboratory awarded BrainChip a Small Business Innovation Research contract in December 2024 to map radar processing onto Akida hardware. North America gains most from this defense signal processing demand, and BrainChip now offers radar and communication reference platforms built on its AKD1500 processor for integrators over the medium term.
Always-on sensing puts spiking processors where AI chips cannot go
A wearable, a smart doorbell or a radar presence sensor has to listen or watch all day on a small battery. Innatera says Pulsar runs radar presence detection at 600 µW and audio scene classification at 400 µW, budgets that a conventional AI chip rarely meets. Its Talamo SDK is built on PyTorch, so device engineers need no prior neuroscience background. Consumer electronics is therefore the fastest-growing end use, with these parts reaching volume products by 2030.
Racks, language models and hybrid chips redefine the offer
Neuromorphic machines shift from lab benches to server racks
The first wave of systems were boards on lab benches; the current wave fills racks. SpiNNcloud's server-scale SpiNNaker2 systems went live at Sandia and TU Dresden in 2025, and Zhejiang University unveiled its Darwin Monkey system on Darwin 3 chips in August 2025. Hala Point alone holds 1.15 billion neurons and 128 billion synapses. Large-scale research systems, already the largest offering, benefit from this shift, though each order still depends on a single lab budget.
Language model inference emerges as a target workload
Until 2023, most neuromorphic work focused on sensing, control and brain simulation. IBM's scalable NorthPole system, described in November 2025, runs IBM Granite models for enterprise agent workflows, and Zhejiang University says Darwin Monkey runs a DeepSeek-based model. The shift ties rack-scale systems to the largest pool of AI spending, which favors suppliers with mature compilers. The barrier is proof, since buyers want benchmarks on 8-billion-parameter models and larger before moving production work.
Radar, communications and event-based industrial vision open an opportunity
Signal processing at the edge suits event-driven hardware, and defense primes and telecom suppliers are natural integrators of BrainChip's radar and communication reference platforms. In March 2026, IDS Imaging Development Systems and Prophesee signed a letter of intent to build industrial vision systems that combine conventional imaging with event-based sensing. Suppliers that ship tested reference designs can win design-ins within 12 to 24 months, ahead of rivals selling bare silicon.
Open-access hubs create an opportunity to turn researchers into future buyers
Shared facilities let researchers try neuromorphic hardware without buying it. UT San Antonio launched THOR, a National Science Foundation-backed open-access hub on SpiNNaker2 hardware, in February 2026, and EBRAINS keeps European platforms open to users. Intel's research community, for its part, has more than 200 members. Every user trained on a shared machine is a future buyer of a dedicated system or a development kit, which supports kit, software and service revenue over the next decade.
Toolchains, small wafer lots and faster GPUs slow orders
Fragmented toolchains keep switching costs high
Spiking networks behave differently from the deep learning models most engineers know. Training methods are less mature, benchmarks are scattered and each hardware family has its own toolchain, so a model built for Loihi 2 needs rework before it runs on SpiNNaker2 or Akida. Device makers keep pilot projects small as a result, which delays volume orders. Mitigation comes from PyTorch-based kits such as Talamo and from shared benchmarks run on 2 or more architectures.
Start-ups struggle to reach volume production
Small suppliers buy wafers in small lots, so they pay more per die and wait longer for foundry slots. BrainChip's first production batch of AKD1500 processors came in with lower-than-expected yields, according to its 2026 half-year report to the ASX, and the cause was still under review. Device makers face late samples and higher module prices as a result. Second-source foundry deals, multi-project wafers and licensing designs to larger chip groups reduce the risk for customers planning volume launches.
AI demand pushes small neuromorphic orders to the back of the foundry queue
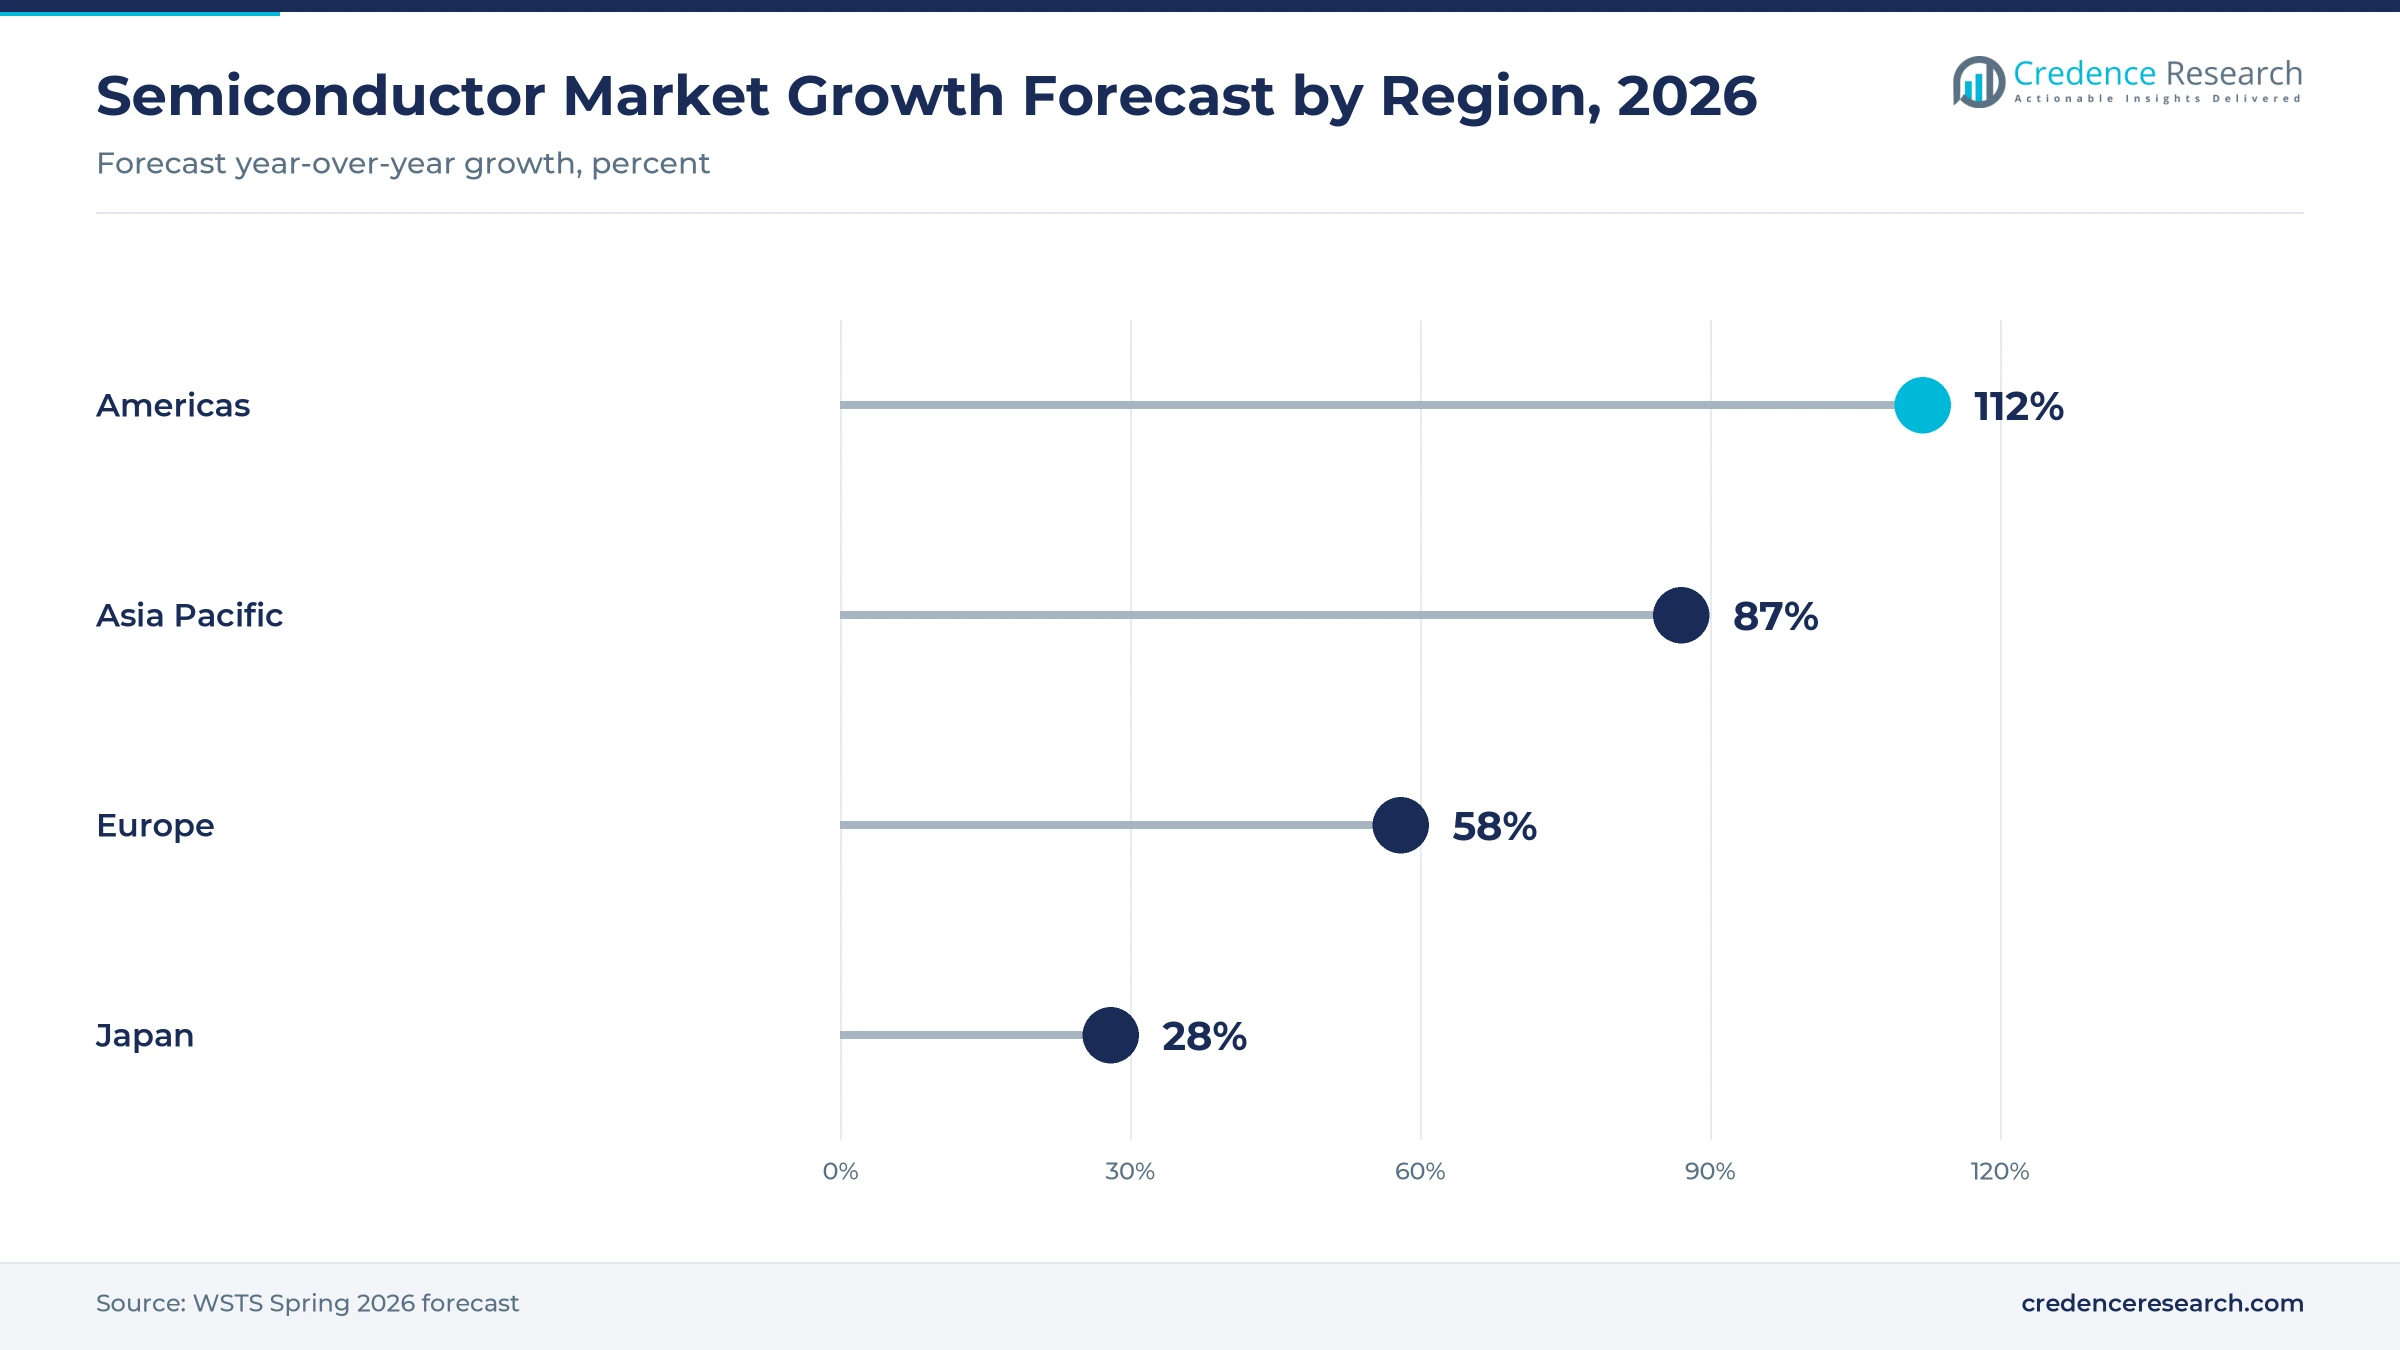
The WSTS Spring 2026 forecast has the global semiconductor market growing 90% in 2026 to USD 1.51 trillion, with memory up about 250% and logic up 37%, as AI infrastructure absorbs wafer, packaging and memory supply. Neuromorphic start-ups with small orders wait longer for capacity, which slows edge module launches and raises costs. Suppliers respond with mature process nodes, long-term capacity agreements and partnerships with established chip groups such as Socionext.
Faster GPUs and NPUs narrow the efficiency gap
Each new generation of conventional accelerators adds sparsity support and lower-precision arithmetic, which narrows the energy advantage that neuromorphic suppliers sell on. Buyers with flexible power budgets may stay with mainstream hardware, which caps demand outside niche uses. Neuromorphic systems win clearly where data arrive as sparse events or where the budget sits below what a conventional NPU can meet, such as 400 µW audio sensing, so suppliers focus on those workloads first.
U.S. national labs lead while Asia Pacific grows fastest
| Region | Share, 2025 | CAGR, 2025–2035 |
|---|---|---|
| North America | 37.9% | 22.40% |
| Europe | 31.2% | 22.00% |
| Asia Pacific | 26.1% | 30.50% |
| Middle East & Africa | 3.2% | 28.00% |
| Latin America | 1.6% | 26.00% |
North America has national labs and defense research anchoring the largest market
North America held 37.9% of 2025 value and grows at 22.40% a year. Sandia hosts both Intel's Hala Point and the Braunfels SpiNNaker2 system, and UT San Antonio opened the NSF-funded THOR hub in February 2026, widening access for researchers who cannot buy their own machine. Air Force Research Laboratory contracts add defense demand for radar processing. WSTS expects the Americas semiconductor market to grow 112% in 2026, which tightens supply but signals strong AI spending that neuromorphic suppliers can tap.
Europe sustains a dense supplier cluster on the human brain project legacy
Europe held 31.2% of 2025 value and grows at 22.00% a year. The region builds on SpiNNaker2 and BrainScaleS platforms, the EBRAINS infrastructure and start-ups in Dresden, Delft and Zurich. TU Dresden launched its SpiNNcloud machine in April 2025, and Leipzig University ordered a system in July 2025 to run protein folding simulations for drug discovery. Public funding runs through project cycles, so orders cluster around program renewals, with EBRAINS 2.0 due to end in December 2026.
Asia Pacific grows fastest on Chinese brain programs and device makers
Asia Pacific held 26.1% of 2025 value and is the fastest-growing region at 30.50% a year. China funds brain-inspired computing as a national priority, and Zhejiang University's Darwin Monkey, unveiled in August 2025, is among the largest disclosed systems in the region. SynSense, a Zurich spin-off headquartered in Chengdu, supplies Speck vision and Xylo signal processors to device makers, and Japan's Socionext works with Innatera on radar sensing. WSTS forecasts 87% semiconductor growth in the region in 2026.
Middle East & Africa and Latin America rely on single orders and remote access
The Middle East & Africa held 3.2% of 2025 value and grows at 28.00% a year, with Gulf national AI programs and defense buyers placing orders one system at a time. Latin America held 1.6% and grows at 26.00% a year. Demand there comes from university research groups, often through remote access to European and U.S. platforms rather than local machines.
Five spiking hardware deliveries and launches, 2025–2026
| Development | Status and market relevance |
|---|---|
| In March 2026, IDS Imaging Development Systems and Prophesee signed a letter of intent to develop industrial vision systems with event-based sensing. | Letter of intent. Brings event-based processing toward mainstream camera lines. |
| In February 2026, UT San Antonio launched THOR, an NSF-funded open-access neuromorphic hub built on SpiNNaker2 hardware. | Operating. Widens access for U.S. researchers without their own system. |
| In August 2025, Zhejiang University unveiled Darwin Monkey, a brain-like computer built on Darwin 3 chips. | Unveiled. Shows China building large systems on domestic chips. |
| In June 2025, SpiNNcloud announced that Sandia National Laboratories had deployed a SpiNNaker2 system, later named Braunfels. | Deployed. Adds a second large architecture at a U.S. national lab. |
| In May 2025, Innatera launched Pulsar, a neuromorphic microcontroller for sensor-edge devices. | Launched. Puts spiking processing into a general-purpose microcontroller. |
Efficiency, Python toolchains and hybrid chips come next
- Efficiency targets for rack systems such as Hala Point exceed 15 TOPS/W, so energy per token becomes the main sales metric for language model inference.
- Hybrid chips such as microcontrollers that combine a spiking engine with RISC-V cores and convolution accelerators let device makers adopt neuromorphic processing step by step.
- Toolchains built on PyTorch-based SDKs and Python frameworks let ordinary machine learning engineers train spiking models, cutting pilot time from months to weeks.
- Event-based sensing pairs event-based cameras and radar with spiking processors and cuts data volumes at the sensor, which suits industrial vision and drones.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Chip majors, spin-offs and Chinese labs share a small field
Supply splits into three groups, the first being large chip and computing companies, led by Intel and IBM, which build research systems such as Loihi 2-based Hala Point and NorthPole, keep them close to partner labs and do not report neuromorphic sales separately. University spin-offs form the second group and sell complete systems or edge platforms, as SpiNNcloud commercializes SpiNNaker2, BrainChip sells Akida processors, modules and licenses, Innatera ships Pulsar and SynSense supplies Speck and Xylo kits. Chinese state laboratories, including Zhejiang University, make up the third group and build their own Darwin-family machines. Credence Research estimates that the 5 largest suppliers of systems and services hold a little over half of 2025 value, with concentration highest in research systems and lowest in edge modules. Winners combine Python toolchains, reliable volume supply and reference designs that shorten a customer's time to product.
Companies profiled and their roles
| Company | Type | Role in the market |
|---|---|---|
| Intel | Chip major | Loihi 2 processors and the Hala Point research system at Sandia |
| IBM | Computing major | NorthPole chip and a rack-scale NorthPole system for language model inference |
| SpiNNcloud | University spin-off | SpiNNaker2 server-scale systems for Sandia, TU Dresden, Leipzig University and THOR |
| BrainChip | Edge processor supplier | Akida processors, AKD1500 modules, boards and radar reference platforms |
| Innatera | Edge processor supplier | Pulsar neuromorphic microcontroller and Talamo SDK |
| SynSense | Edge processor supplier | Speck vision and Xylo signal processors with development kits |
| Prophesee | Event-based vision supplier | Event-based sensing for industrial vision with IDS |
| IDS Imaging Development Systems | Industrial camera maker | Letter of intent with Prophesee on event-based vision systems |
| Socionext | Chip design partner | Radar sensing work with Innatera; system-level role not confirmed |
Neuromorphic computing is shipping, useful and still small
Credence Research's view is that neuromorphic computing is real, shipping and small, and that the decade's value will come from edge parts rather than ever larger research machines. Research systems keep the largest share, but edge processors and consumer devices add most new revenue. Suppliers with familiar toolchains, secure wafer supply and tested reference designs are best positioned. The main risk is that faster GPUs and NPUs close the efficiency gap. Buyers and investors should watch AKD1500 yields, Pulsar design-ins and national lab renewals.
How Credence Research sized neuromorphic system demand
The report uses 2025 as the base year and forecasts to 2035, with CAGR calculated over 2025–2035. Market values come from Credence Research's market model, built offering by offering from disclosed system deliveries, edge module and kit shipments and service contracts; segment and regional splits are Credence Research estimates. Supporting evidence comes from supplier filings, company and laboratory announcements, research papers and WSTS industry data. Private suppliers disclose little, which limits precision for edge modules.
Research instruments give way to embedded edge parts by 2035
Through 2035, demand will tilt from one-off research machines toward edge processors embedded in wearables, radar sensors, cameras and cars. Hybrid microcontrollers and Python toolchains will make neuromorphic processing an option for ordinary device teams, while rack-scale systems seek a role in language model inference. Asia Pacific will gain share on Chinese programs and device makers, and North America will remain the largest buyer. The pace will depend on start-up supply, foundry access and how quickly conventional GPUs and NPUs improve their energy efficiency.
Frequently Asked Questions
What was the size of the neuromorphic computing systems market in 2025?
What is the forecast value and CAGR of the neuromorphic computing systems market?
What is driving demand for neuromorphic computing systems?
Which region holds the largest share of the neuromorphic computing systems market?
Which offering leads the neuromorphic computing systems market?
Who are the major companies in neuromorphic computing systems?
What technologies are shaping neuromorphic computing systems?
What challenges could slow the neuromorphic computing systems market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Offering
- 1.2.1 Large-Scale Research Systems
- 1.2.2 Software, Cloud Access & Services
- 1.2.3 Edge Processors & Modules
- 1.2.4 Development Boards & Kits
- 1.3 By End-use
- 1.3.1 Research & Government Labs
- 1.3.2 Consumer Electronics
- 1.3.3 Military & Defense
- 1.3.4 Industrial & IoT
- 1.3.5 Automotive
- 1.3.6 Healthcare
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 92.5 million → 2035: USD 871.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Neuromorphic Computing Systems Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Neuromorphic Computing Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Neuromorphic Computing Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Neuromorphic Computing Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Neuromorphic Computing Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Neuromorphic Computing Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Neuromorphic Computing Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Neuromorphic Computing Systems Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 92.5 million → 2035: USD 871.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Neuromorphic Computing Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Offering - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Large-Scale Research Systems
- 12.3.7.2 Software, Cloud Access & Services
- 12.3.7.3 Edge Processors & Modules
- 12.3.7.4 Development Boards & Kits
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End-use - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Research & Government Labs
- 12.4.7.2 Consumer Electronics
- 12.4.7.3 Military & Defense
- 12.4.7.4 Industrial & IoT
- 12.4.7.5 Automotive
- 12.4.7.6 Healthcare
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Neuromorphic Computing Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Neuromorphic Computing Systems Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Neuromorphic Computing Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Neuromorphic Computing Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Intel
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 IBM
- 18.4 SpiNNcloud
- 18.5 BrainChip
- 18.6 Innatera
- 18.7 SynSense
- 18.8 Prophesee
- 18.9 IDS Imaging Development Systems
- 18.10 Socionext
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

