
Market Overview
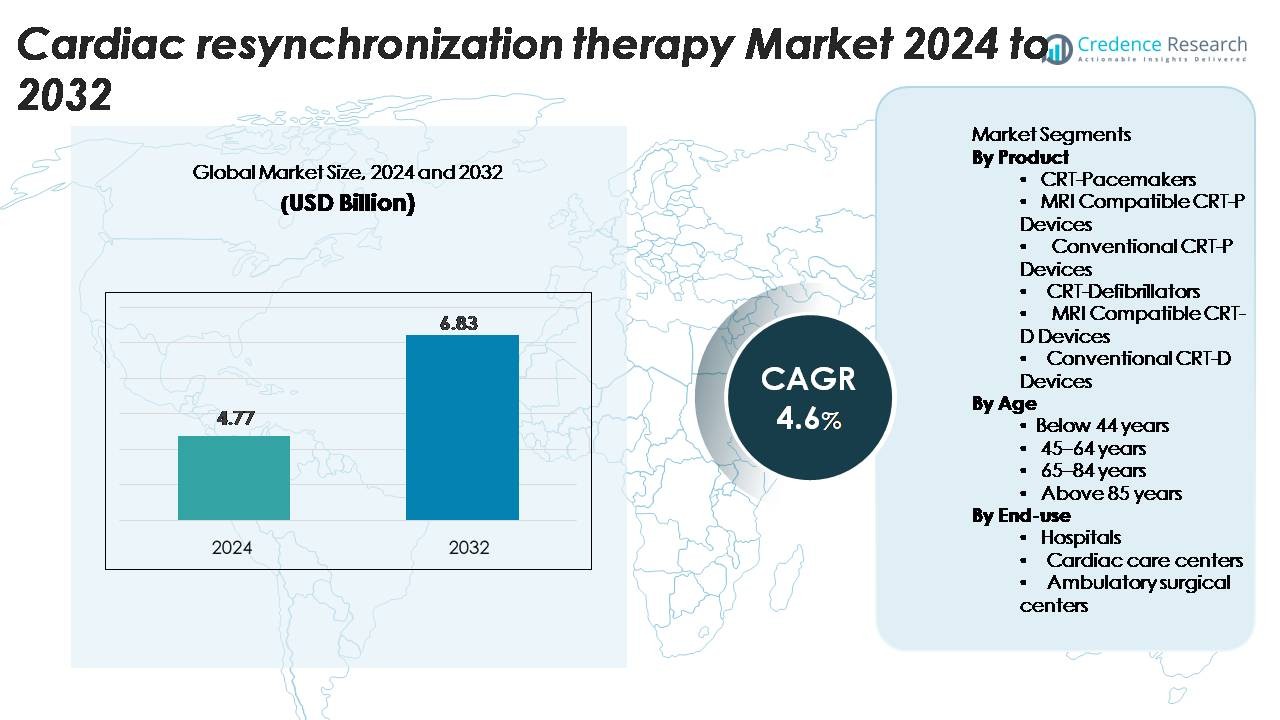
The Cardiac Resynchronization Therapy market size was valued at USD 4.77 billion in 2024 and is projected to reach USD 6.83 billion by 2032, growing at a CAGR of 4.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cardiac Resynchronization Therapy Market Size 2024 | USD 4.77 Billion |
| Cardiac Resynchronization Therapy Market, CAGR | 4.6% |
| Cardiac Resynchronization Therapy Market Size 2032 | USD 6.83 Billion |
The Cardiac Resynchronization Therapy market is shaped by strong participation from global device manufacturers that focus on advanced CRT-D and MRI-compatible pacing systems. Companies with broad electrophysiology portfolios lead adoption across major hospitals and cardiac centers by offering reliable devices and strong post-implant support. North America remains the leading region with 41% market share, supported by high diagnosis rates, strong reimbursement, and early uptake of next-generation systems. Europe follows with significant demand driven by structured care pathways and aging populations. Asia-Pacific grows rapidly as cardiac centers expand and more patients gain access to advanced pacing therapies.
Market Insights
- The market size reached USD 4.77 billion in 2024 and will hit USD 6.83 billion by 2032 at a 4.6% CAGR.
- Rising heart failure cases drive higher demand for CRT-D devices, which hold the 61% share as providers prefer dual therapy for high-risk patients.
- MRI-compatible systems gain traction as hospitals adopt safer imaging-friendly devices and remote monitoring becomes a key trend in long-term care.
- Competition remains strong among global electrophysiology device makers that expand innovation pipelines, but high device cost and lead-related complications restrain wider adoption.
- North America leads with 41%, followed by Europe at 32%, while Asia-Pacific at 19% grows fastest; by age, the 65–84 group dominates with 54% share, and hospitals lead end-use with 68% share.
Market Segmentation Analysis:
By Product:
CRT-Defibrillators lead this segment with an estimated 61% share in 2024 due to strong adoption among high-risk cardiac patients. These devices support both pacing and defibrillation, which enhances survival in advanced heart failure. MRI-compatible CRT-D devices continue to gain traction because patients often require MRI scans during long-term care. CRT-Pacemakers hold steady demand due to their suitability for moderate heart failure cases. MRI-compatible CRT-P devices also expand as providers shift toward safer imaging options. Growth across all product groups is driven by rising heart failure prevalence and improved device reliability.
- For instance, a large CRT-D study reported that among 320 patients treated, the primary endpoint (death, heart transplantation, or LV-assist device) was reached by 37% in the CRT-D group at a median follow-up of 4.3 years.
By Age:
The 65–84 years group dominates the market with nearly 54% share, reflecting the high incidence of heart failure in older adults. Advancing age increases the need for synchronized cardiac pacing, which boosts demand across this demographic. Patients aged 45–64 years account for a growing share as early diagnosis rates improve due to broader use of cardiac screening. Individuals above 85 years show stable device adoption, supported by better post-implant survival. The below-44 group remains the smallest segment, driven mainly by genetic or congenital cardiac conditions.
- For instance, data from one study showed that individuals aged 80–84 years had a heart failure prevalence of 5.2% in that age band.
By End-use:
Hospitals lead the segment with an estimated 68% share, driven by the availability of advanced electrophysiology labs and skilled cardiac surgeons. These facilities manage complex CRT-D and CRT-P implantation procedures, which require continuous monitoring and post-operative care. Cardiac care centers show strong growth as they provide dedicated rhythm management services and faster intervention for heart failure cases. Ambulatory surgical centers hold a smaller share but expand steadily as minimally invasive implantation techniques reduce recovery time and support outpatient procedures.
Key Growth Drivers
Rising Burden of Heart Failure
Growing heart failure cases drive strong demand for cardiac resynchronization therapy. The rising burden among older adults increases the need for advanced pacing solutions. More patients now receive earlier diagnosis, which boosts therapy adoption across hospitals and cardiac centers. Better awareness programs help people understand treatment benefits and lower their fear of implants. Wider access to screening tools supports timely referral for CRT. This steady flow of new patients creates a large base for repeat follow-ups and long-term device use.
·For instance, prevalence data show that the self-reported, diagnosed overall rate of specific severe cardiovascular diseases (heart attack, chronic heart disease, and stroke) among adults aged 45 years and older in India was 5.2% according to one analysis of the Longitudinal Ageing Study in India (2017–2019).
Shift Toward Advanced CRT-D and MRI-Compatible Systems
The shift toward safer and more advanced devices raises adoption across clinical settings. MRI-compatible systems attract strong demand due to the higher number of patients needing imaging during long-term care. CRT-D devices offer more protection by combining pacing and defibrillation, which improves survival in high-risk groups. This dual function strengthens market preference for premium models. Faster regulatory approvals for new designs also support growth. Doctors trust these devices because they reduce imaging limits while improving safety.
- For instance, Medtronic’s Cobalt XT™ MRI CRT-D system lists a device volume of 35 cc and a mass of 82 g, making it suitable for full-body MRI scans at both 1.5 T and 3 T field strengths.
Improved Clinical Outcomes and Expanding Reimbursement Support
Better clinical outcomes encourage wider use of CRT in heart failure treatment. Studies show improved heart function, reduced hospital stays, and higher quality of life after implantation. These gains raise confidence among both doctors and patients. Strong reimbursement policies make therapy more affordable in major markets. Insurance coverage for device placement and follow-up care reduces the financial burden for families. Supportive guidelines from medical bodies also drive higher adoption. These combined factors help the therapy reach more patients each year.
Key Trends & Opportunities
Rising Use of Remote Monitoring and Connected CRT Devices
Connected CRT systems create new growth opportunities as care shifts toward remote monitoring. These tools help doctors track heart rhythm and device function with higher accuracy. Real-time data improves early detection of clinical issues and reduces emergency visits. Many hospitals adopt these systems to support home-based care. This trend improves patient comfort and encourages long-term device use. Higher investment in digital healthcare tools will strengthen this shift.
- For instance, BIOTRONIK’s Home Monitoring® platform demonstrated the ability to detect clinically relevant events a median of 47 days earlier than traditional in-office follow-ups, according to the TRUST clinical study.
Growing Preference for Minimally Invasive Procedures
Minimally invasive CRT implantation attracts interest due to shorter recovery time and lower risk. Hospitals prefer these methods because they help reduce bed occupancy and speed up patient discharge. Patients also choose these procedures because they experience less pain and faster return to normal activity. Better technology and skilled teams support safer and more precise lead placement. This trend will continue to open new opportunities for device makers.
- For instance, Medtronic’s SelectSecure™ 3830 lead-used in conduction system pacing during CRT implantation-has a 4.1-French diameter, enabling implantation through smaller sheaths and contributing to reduced tissue trauma during lead placement.
Expansion of CRT Programs in Developing Regions
Developing markets show rising opportunity as hospitals upgrade cardiac care units. More centers now offer electrophysiology services that support CRT implantation. Governments and private groups invest in training programs to address device shortages. Growing insurance penetration helps patients afford treatment. These combined changes help expand therapy access across wider populations.
Key Challenges
High Device Cost and Limited Access in Low-Resource Settings
High device prices remain a major barrier in many regions. The total cost includes the device, surgery, follow-up visits, and periodic replacement. Many hospitals in low-income areas lack trained specialists or electrophysiology labs. This reduces access for large patient groups. Even with partial reimbursement, families struggle to manage long-term expenses. These gaps slow adoption in developing markets with high disease burden.
Complications Linked to Lead Placement and Device Management
Lead-related issues create challenges for both surgeons and patients. Problems such as lead displacement, infection, or poor electrical contact require repeat procedures. These events increase healthcare costs and patient stress. Device management becomes harder in older adults with multiple health conditions. Some people also fear surgery and delay treatment. These clinical and psychological barriers limit the full reach of CRT therapy.
Regional Analysis
North America
North America holds the largest share at 41% in 2024 due to strong access to advanced cardiac care. Hospitals use CRT-D and MRI-safe devices at high rates. The region benefits from early diagnosis programs and high awareness among older adults. Wide insurance coverage supports steady demand. Many patients receive remote monitoring, which improves long-term care. Large device makers also operate major research units in the United States. This support drives faster adoption of new CRT models. Canada shows stable growth due to rising heart failure cases and improved access to specialty centers.
Europe
Europe captures 32% of the market share, supported by structured cardiac care networks. The region benefits from strong clinical guidelines and early patient referral systems. Germany, France, and the UK lead due to high installation of CRT-D units. Aging populations increase demand for pacing therapy. Reimbursement policies improve patient access and reduce treatment delays. Many hospitals use MRI-compatible systems, which raise safety levels and device preference. Research groups also support clinical trials that validate long-term outcomes. Eastern Europe shows steady growth as cardiac centers upgrade facilities.
Asia-Pacific
Asia-Pacific accounts for 19% of the market, driven by rising heart failure cases and fast healthcare expansion. China and Japan lead due to large patient bases and strong hospital capacity. India shows rapid growth as more cardiac centers adopt electrophysiology services. Awareness programs help patients understand pacing benefits. A growing middle-aged population increases long-term demand. Device makers expand training programs to support skilled teams. New private hospitals also add CRT implantation units. These changes drive stronger adoption across the region.
Latin America
Latin America holds 5% of the market and shows steady expansion as hospitals improve cardiac care. Brazil and Mexico lead due to large populations and rising diagnosis rates. Public and private hospitals add CRT-D and CRT-P services in major cities. Cost remains a barrier in rural areas, but insurance coverage improves access. Training programs support better device management. Growing investment in heart failure treatment raises adoption. The region benefits from partnerships with global device makers. These efforts help more patients receive advanced pacing therapy.
Middle East & Africa
The Middle East & Africa region holds 3% of the market, driven by gradual improvement in specialized cardiac centers. Gulf countries lead due to high investment in advanced hospitals. Awareness programs support higher diagnosis of heart failure. Access improves in urban areas, but rural regions face device shortages. South Africa shows steady growth with expanding electrophysiology services. Partnerships with global firms help train specialists. Rising chronic disease rates support long-term demand. Expansion of private hospitals strengthens adoption of CRT-D and MRI-safe devices.
Market Segmentations:
By Product
- CRT-Pacemakers
- MRI Compatible CRT-P Devices
- Conventional CRT-P Devices
- CRT-Defibrillators
- MRI Compatible CRT-D Devices
- Conventional CRT-D Devices
By Age
- Below 44 years
- 45–64 years
- 65–84 years
- Above 85 years
By End-use
- Hospitals
- Cardiac care centers
- Ambulatory surgical centers
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Cardiac Resynchronization Therapy market features strong participation from global medical device companies that focus on advanced pacing and defibrillation technologies. Leading players compete through innovation in MRI-compatible CRT-D and CRT-P systems, improved battery life, and enhanced lead performance. Many companies strengthen their market position through continuous product upgrades, clinical evidence, and strong physician training programs. Strategic partnerships with hospitals support wider device adoption and long-term follow-up programs. Firms also invest in remote monitoring platforms that improve patient management and reduce hospital visits. Competition intensifies as manufacturers introduce smaller, more efficient devices aimed at improving implant precision and patient comfort. Expanding geographic reach, particularly in Asia-Pacific and Latin America, remains a key priority for most companies.
Key Player Analysis
- Boston Scientific Corporation
- Medico S.p.A
- Abbott Laboratories
- Microport Scientific Corporation
- LivaNova PLC
- Medtronic PLC
- Biotronik
Recent Developments
- In November 2024, Boston Scientific also entered into a definitive agreement to acquire Cortex, Inc. (an Ajax Health company) to strengthen its electrophysiology portfolio.
- In February 2024, MicroPort also announced the launch of its GALI™ SonR® CRT-D device with NAVIGO 4LV pacing leads in Japan.
Report Coverage
The research report offers an in-depth analysis based on Product, Age, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for CRT-D devices will rise as more high-risk patients get early diagnosis.
- MRI-compatible CRT systems will gain wider use due to increased imaging needs.
- Remote monitoring will expand as hospitals adopt connected care platforms.
- Minimally invasive implantation methods will improve patient recovery times.
- Device makers will focus on longer battery life and improved lead durability.
- Adoption will grow in Asia-Pacific as cardiac centers expand electrophysiology capacity.
- Training programs will increase to support skilled CRT implantation teams.
- Reimbursement support will strengthen access in both developed and developing regions.
- Integration of AI-driven rhythm monitoring will improve long-term outcomes.
- Smaller and more ergonomic devices will enhance patient comfort and acceptance.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Cardiac Resynchronization Therapy, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cardiac Resynchronization Therapy market projected to grow between 2025 and 2032?
Which Cardiac Resynchronization Therapy segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cardiac Resynchronization Therapy market?
Who are the leading companies in the Cardiac Resynchronization Therapy market?
Which region commanded the largest share of the Cardiac Resynchronization Therapy market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4.77 billion → 2032: USD 6.83 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cardiac Resynchronization Therapy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cardiac Resynchronization Therapy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cardiac Resynchronization Therapy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cardiac Resynchronization Therapy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cardiac Resynchronization Therapy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cardiac Resynchronization Therapy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cardiac Resynchronization Therapy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cardiac Resynchronization Therapy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4.77 billion → 2032: USD 6.83 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cardiac Resynchronization Therapy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cardiac Resynchronization Therapy Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cardiac Resynchronization Therapy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cardiac Resynchronization Therapy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

