
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cardiopulmonary Resuscitation (CPR) Machine Market Size 2024 | USD 1,600 million |
| Cardiopulmonary Resuscitation (CPR) Machine Market, CAGR | 9% |
| Cardiopulmonary Resuscitation (CPR) Machine Market Size 2032 | USD 3,188 million |
Market Overview:
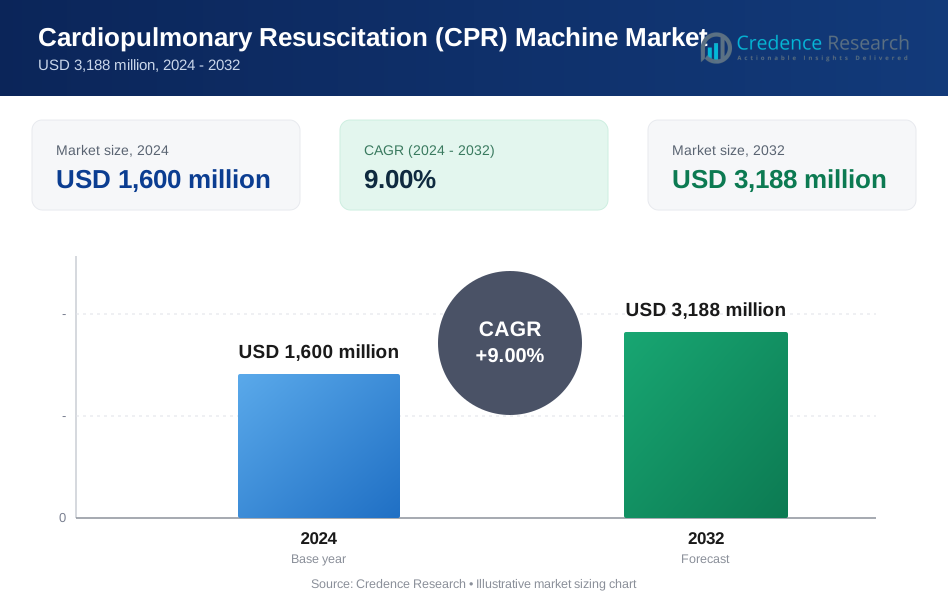
The Cardiopulmonary Resuscitation (CPR) Machine Market is projected to grow from USD 1,600 million in 2024 to USD 3,188 million by 2032, reflecting a compound annual growth rate (CAGR) of 9% over the forecast period.
The Cardiopulmonary Resuscitation (CPR) Machine Market is driven by the rising incidence of cardiac arrest and the growing demand for advanced emergency medical services. Increasing awareness about the importance of timely resuscitation, coupled with supportive government initiatives and training programs, continues to fuel market growth. Technological advancements, such as real-time feedback systems, portability, and automation in CPR devices, are enhancing the efficiency and reliability of resuscitation efforts, thereby boosting adoption across hospitals, ambulances, and public settings. The shift toward automated solutions is also supported by a shortage of trained medical personnel, particularly in pre-hospital scenarios. Additionally, favorable reimbursement policies and increased investments in healthcare infrastructure across emerging economies are contributing to market expansion. Key market players are focusing on strategic partnerships, product innovations, and geographic expansion to strengthen their market position. Overall, the market is witnessing a strong trend toward smart, user-friendly, and highly efficient CPR machines designed to improve survival rates and resuscitation outcomes.
The Cardiopulmonary Resuscitation (CPR) Machine Market demonstrates strong geographical presence across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America leads the market due to advanced healthcare infrastructure and high cardiac arrest incidence, followed by Europe with significant adoption across public and private healthcare sectors. Asia-Pacific is rapidly emerging as a growth hub, driven by expanding medical infrastructure and rising awareness of emergency care. Latin America and the Middle East & Africa are gradually advancing with growing investments and public-private healthcare collaborations. Key players such as SCHILLER, Vyaire Medical Inc., Corpus, Nihon Kohden Corporation, ZOLL Medical Corporation, General Electric Company, CPR Medical Devices Inc., Koninklijke Philips N.V., Michigan Instruments, and Medtronic maintain a competitive edge through innovation, strategic alliances, and regional expansion to address the evolving global demand for effective CPR technologies.
Market Insights:
- The CPR machine market is projected to grow from USD 1,600 million in 2024 to USD 3,188 million by 2032, registering a 9% CAGR during the forecast period.
- Rising global cases of cardiac arrest and cardiovascular diseases are driving demand for effective and reliable resuscitation technologies.
- Technological advancements, such as real-time feedback, automation, and device portability, are significantly improving resuscitation quality and outcomes.
- Expansion of emergency medical services (EMS) and widespread CPR training initiatives are increasing device accessibility across various settings.
- Government incentives, reimbursement policies, and healthcare investments—especially in emerging economies—are boosting market growth.
- High device costs, limited access in rural areas, and lack of standardization across CPR technologies remain key market challenges.
- North America leads the market with 38% share, followed by Europe (27%), Asia-Pacific (20%), and Latin America & MEA (15%), reflecting strong global presence and varying growth dynamics across regions.
Market Drivers:
Rising Incidence of Cardiac Arrest and Cardiovascular Diseases:
One of the primary drivers of the Cardiopulmonary Resuscitation (CPR) Machine Market is the increasing prevalence of cardiac arrest and other cardiovascular diseases worldwide. Sudden cardiac arrest remains a leading cause of mortality, emphasizing the urgent need for rapid and effective resuscitation solutions. For instance, automated CPR devices like the LUCAS system by Stryker have demonstrated life-saving capabilities during emergencies, such as when STARS air medical crews successfully used it to provide consistent chest compressions during critical flights, allowing healthcare professionals to focus on other vital tasks. The growing global burden of sedentary lifestyles, obesity, hypertension, and stress-related conditions further contributes to the rising incidence of heart-related emergencies. As the number of cardiac events continues to grow, the demand for reliable and efficient CPR machines is expected to increase proportionally, particularly in both hospital and pre-hospital settings.
Technological Advancements in Automated CPR Devices:
Technological innovation plays a pivotal role in driving market growth, with modern CPR machines now incorporating features such as real-time feedback, enhanced monitoring, and automated compression systems. These advancements are significantly improving the accuracy and consistency of chest compressions, which are crucial for improving patient survival outcomes. Furthermore, the integration of connectivity features and data tracking capabilities is enabling healthcare providers to monitor and evaluate resuscitation performance more effectively. These enhancements not only improve clinical outcomes but also support training, compliance, and continuous quality improvement.
Expanding Emergency Medical Services and Training Programs:
The expansion of emergency medical services (EMS) and increased focus on first-responder training are key contributors to market growth. Governments and healthcare organizations are investing in CPR training and public awareness programs, resulting in a broader base of skilled personnel capable of using CPR machines effectively. For instance, William Newton Hospital in Kansas offers free community-wide CPR certification events during American Heart Month, providing training in adult/infant CPR, AED usage, and NARCAN® administration to hundreds of participants annually. Moreover, initiatives to equip ambulances, public places, and even educational institutions with automated CPR devices are reinforcing demand. This growing emphasis on preparedness and rapid response is making CPR machines more accessible and essential across various sectors.
Favorable Government Policies and Healthcare Investments:
Supportive government policies, increased healthcare funding, and strategic public-private partnerships are further fueling the growth of the CPR machine market. Incentives and reimbursement schemes for emergency medical equipment, especially in developed economies, are encouraging hospitals and emergency services to invest in advanced resuscitation devices. Additionally, emerging economies are enhancing their healthcare infrastructure, which includes the procurement of automated CPR machines to support improved emergency care delivery. These favorable conditions are expected to sustain long-term market expansion.
Market Trends:
Integration of Smart Technologies and Real-Time Feedback:
A prominent trend in the Cardiopulmonary Resuscitation (CPR) Machine Market is the integration of smart technologies, including real-time feedback mechanisms and advanced monitoring systems. These features allow healthcare professionals to assess the quality and effectiveness of chest compressions during resuscitation efforts. By delivering real-time data on compression depth, rate, and recoil, modern CPR devices help improve adherence to clinical guidelines, ultimately enhancing patient outcomes. This trend reflects a broader movement toward data-driven healthcare and continuous performance improvement in emergency medical response.
Increased Adoption of Portable and User-Friendly Devices:
There is a growing preference for lightweight, portable, and easy-to-use CPR machines, especially among emergency medical responders and non-clinical users. Manufacturers are focusing on developing compact devices that can be rapidly deployed in ambulances, public spaces, and field environments. For instance, Stryker’s LUCAS 3 chest compression system, which ensures uninterrupted compressions during patient transport.These user-friendly machines are designed for quick application with minimal training, enabling faster response times and broader adoption across various settings. This trend supports the global emphasis on timely intervention in cardiac emergencies and aligns with efforts to expand access to life-saving technologies.
Expansion of Pre-Hospital and Out-of-Hospital Applications:
Another emerging trend is the growing use of CPR machines in pre-hospital and out-of-hospital environments. With the increasing incidence of cardiac arrest occurring outside clinical settings, first responders and community health workers are increasingly equipped with automated CPR devices. For instance, Michigan Instruments CPR devices are lightweight, easy to use, and allow the transition from manual to automatic CPR with minimal interruption to compressions. This shift is encouraging the decentralization of advanced life-saving interventions and promoting better survival rates for out-of-hospital cardiac arrests. It also emphasizes the importance of public awareness, emergency preparedness, and widespread device availability.
Focus on Training and Simulation-Based Education:
Training and simulation-based education are becoming integral to the implementation of CPR machines. Healthcare institutions and emergency services are investing in comprehensive training programs that incorporate high-fidelity simulators and CPR devices with real-time feedback. This trend ensures that medical personnel and lay responders can operate CPR machines effectively under pressure, fostering confidence, reducing errors, and ultimately improving the quality of care delivered during critical situations.
Market Challenges Analysis:
High Cost of Advanced CPR Machines and Limited Accessibility:
One of the major challenges facing the Cardiopulmonary Resuscitation (CPR) Machine Market is the high cost associated with technologically advanced devices. While automated CPR machines offer significant benefits in terms of performance and outcomes, their elevated price point can hinder widespread adoption, particularly in low- and middle-income regions. Budget constraints in public healthcare systems and smaller medical facilities often result in limited procurement capacity, restricting access to these critical life-saving tools. For instance, the Lucas 2 automated CPR device, widely used in emergency medical services, costs approximately $14,495, making it inaccessible for many healthcare facilities in low- and middle-income countries. Additionally, the cost of maintenance, calibration, and periodic training required to operate these devices adds to the overall financial burden. This creates a disparity in availability between urban and rural settings, where emergency response teams may lack the necessary equipment to perform effective resuscitation, thereby impacting patient survival rates.
Operational Challenges and Lack of Standardization:
Another significant hurdle in the CPR machine market is the variability in device design, operation protocols, and compatibility with existing emergency response systems. Despite technological advancements, a lack of standardization across manufacturers can lead to inconsistencies in use, training, and integration with other medical technologies. Emergency personnel may encounter difficulties in operating different models under high-pressure situations, especially when switching between devices in various healthcare settings. Furthermore, concerns related to device reliability, such as mechanical failure or inaccurate feedback during critical moments, can undermine user confidence. In many regions, there is also a shortage of adequately trained personnel who can effectively deploy and troubleshoot CPR machines, particularly in out-of-hospital scenarios. These operational challenges highlight the need for industry-wide standards, better training initiatives, and design innovations that prioritize user-friendliness and interoperability. Overcoming these issues will be essential to improving the effectiveness and scalability of CPR machines across diverse healthcare environments.
Market Opportunities:
The Cardiopulmonary Resuscitation (CPR) Machine Market presents significant growth opportunities driven by the increasing demand for advanced emergency medical technologies across both developed and emerging markets. As healthcare systems worldwide continue to prioritize timely and effective cardiac care, there is a growing emphasis on expanding access to automated CPR machines in ambulances, hospitals, and public settings. Emerging economies, in particular, are investing in the modernization of healthcare infrastructure, creating a favorable environment for market expansion. Strategic collaborations between public health agencies, private organizations, and manufacturers are opening avenues for the wider distribution and affordability of these devices. Additionally, the global rise in community-based emergency response programs is fostering demand for portable and user-friendly CPR machines that can be operated by trained non-clinical personnel, thereby broadening the potential customer base.
Another promising opportunity lies in the integration of artificial intelligence, cloud-based monitoring, and wireless communication into CPR machines, enhancing their functionality and value proposition. These smart features enable remote performance tracking, data analysis, and automated reporting, which are increasingly valued in quality assurance and patient care continuity. Manufacturers can capitalize on the growing trend of digital health to differentiate their offerings and support clinical decision-making. Moreover, expanding CPR and first-aid training programs at the community level can stimulate market growth by equipping more individuals with the knowledge and confidence to use CPR machines effectively. With regulatory bodies supporting faster approvals and increased investments in research and development, the CPR machine market is well-positioned to capitalize on the intersection of innovation, awareness, and expanding healthcare access.
Market Segmentation Analysis:
By Product Type:
The CPR machine market is segmented by product type into piston CPR devices, load-distributing band (LDB) systems, active compression decompression (ACD) devices with impedance threshold devices, extracorporeal techniques and invasive perfusion devices, and others. Among these, LDB and ACD devices are gaining popularity due to their ability to deliver consistent, high-quality chest compressions during emergencies.
By Compressor Type:
Based on compressor type, the market is divided into manual CPR and automatic mechanical CPR devices. Automatic mechanical CPR systems are witnessing increased adoption, particularly in high-pressure emergency scenarios, as they offer standardized compression cycles, reduce fatigue among responders, and enhance the quality of cardiopulmonary resuscitation delivered across various healthcare and field settings.
By Applications:
Application-wise, CPR machines are utilized in ambulances, emergency departments, coronary and intensive care units, cardiac catheterization labs, organ transplant facilities, air medevac units, and EMT rescue units. Their critical role in delivering timely resuscitation is expanding their deployment across diverse clinical and emergency response environments.
Segments:
Based on Product Type
- Piston CPR Devices
- Load-Distributing Band (LDB)
- Active Compression Decompression (ACD) Devices and Impedance Threshold Devices
- Extracorporeal Techniques and Invasive Perfusion Devices
- Others
Based on Compressor Type
- Manual CPR
- Automatic Mechanical CPR
Based on Applications
- Ambulances
- Emergency Departments
- Coronary and Intensive Care Units
- Cardiac Catheterization Labs
- Organ Transplant Facilities
- Air Medevac Units
- EMT Rescue Units
Based on End-User
- Hospital and Clinic
- Cardiac Catheterization Laboratories
- Organ Transplant Unit
Based on the Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
North America holds the largest share of the Cardiopulmonary Resuscitation (CPR) Machine Market, accounting for 38% of the global market in 2024. This dominance is primarily driven by the region's well-established healthcare infrastructure, high adoption rate of advanced medical technologies, and increasing incidence of cardiac arrests. The United States, in particular, plays a pivotal role due to its strong presence of key market players, favorable reimbursement policies, and substantial investments in emergency medical services. Public awareness campaigns and extensive CPR training programs further enhance the demand for both manual and automated CPR machines across various emergency care settings.
Europe:
Europe represents the second-largest regional market, contributing 27% to the global CPR machine market share in 2024. The region benefits from advanced healthcare systems, rising cardiovascular disease rates, and growing support for pre-hospital care initiatives. Countries such as Germany, the United Kingdom, and France are witnessing increased procurement of automated CPR devices in ambulances, hospitals, and air medevac units. Furthermore, the European Union’s emphasis on improving emergency response protocols and funding for innovative medical technologies continues to support steady market growth.
Asia-Pacific:
The Asia-Pacific region holds a 20% share of the global CPR machine market in 2024 and is projected to experience the fastest growth over the coming years. Rapidly developing healthcare infrastructure, increasing healthcare expenditure, and a growing burden of heart disease are contributing to heightened demand for CPR machines. Key markets such as China, Japan, India, and South Korea are witnessing rising adoption of automated CPR systems, especially in urban emergency departments and trauma centers. Government initiatives aimed at improving emergency response systems and increasing awareness of cardiac care are further driving market expansion.
Latin America and Middle East & Africa (MEA):
Latin America and the Middle East & Africa regions collectively account for the remaining 15% of the global CPR machine market share in 2024, with Latin America contributing slightly more than MEA. Growth in these regions is supported by gradual improvements in healthcare infrastructure, rising investment in emergency services, and increasing awareness of the importance of early cardiac intervention. While challenges such as limited access to advanced technology and financial constraints persist, growing public and private sector partnerships are paving the way for enhanced market penetration and long-term development in these emerging markets.
Key Player Analysis:
- SCHILLER
- Vyaire Medical Inc.
- Corpus
- Nihon Kohden Corporation
- ZOLL Medical Corporation
- General Electric Company
- CPR Medical Devices Inc.
- Koninklijke Philips N.V.
- Michigan Instruments
- Medtronic
Competitive Analysis:
The Cardiopulmonary Resuscitation (CPR) Machine Market is characterized by intense competition, with leading players including SCHILLER, Vyaire Medical Inc., Corpus, Nihon Kohden Corporation, ZOLL Medical Corporation, General Electric Company, CPR Medical Devices Inc., Koninklijke Philips N.V., Michigan Instruments, and Medtronic. These companies compete on the basis of innovation, product performance, global distribution networks, and strategic collaborations. Continuous investment in research and development allows these players to enhance device functionality with features such as real-time feedback, automation, and data integration. Market leaders are also expanding their geographic reach through mergers, acquisitions, and partnerships with healthcare providers and emergency services. Regulatory approvals and product certifications remain critical to sustaining competitive advantage, especially in highly regulated markets like North America and Europe. Additionally, companies are focusing on user-centric design and training support to improve device usability in high-pressure emergency scenarios. As technological sophistication and demand for portable, efficient CPR machines increase, competition is expected to intensify, driving further innovation and market differentiation.
Recent Developments:
- In January 2023, Mindray launched its next-generation BeneHeart defibrillator series—BeneHeart D60 and D30—with the goal of raising resuscitation standards. These devices integrate advanced monitoring tools, reliable performance, and a comprehensive quality improvement system to support both in-hospital and pre-hospital emergency care scenarios.
- In April 2023, Nordic Capital acquired a majority stake in Corpuls, a leading innovator in emergency medical solutions and cardiac resuscitation. Specializing particularly in external defibrillators, Corpuls has emerged as one of Germany’s fastest-growing mid-market firms, driven by its strong R&D capabilities and cutting-edge product lineup.
- In April 2023, Defibtech introduced the ARM XR, a significant advancement in its lineup of automated CPR devices. Engineered for use by emergency medical professionals, the ARM XR aims to expand the adoption of automated CPR technology and improve survival rates in out-of-hospital cardiac arrest situations.
- In February 2023, ZOLL Medical Corporation introduced a new automated CPR device equipped with enhanced real-time feedback features, aimed at increasing the efficiency and effectiveness of chest compressions during resuscitation procedures.
Market Concentration & Characteristics:
The Cardiopulmonary Resuscitation (CPR) Machine Market exhibits a moderately high level of market concentration, with a select group of established players dominating global sales through technological innovation, strong brand recognition, and extensive distribution networks. These leading companies maintain a competitive edge by offering integrated solutions that combine automation, real-time feedback, and data connectivity to support advanced resuscitation outcomes. The market is characterized by continuous research and development, regulatory compliance, and a strong emphasis on clinical efficacy and user safety. While innovation remains a key differentiator, partnerships with emergency services, hospitals, and government health bodies further reinforce market presence. Additionally, the market demonstrates a trend toward product customization and user-friendly design, catering to both professional responders and broader public deployment. Although developed regions lead in adoption, emerging markets are gradually gaining traction due to improved healthcare infrastructure and strategic investments. Overall, the CPR machine market reflects a dynamic, innovation-driven environment with growing global reach.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Compressor Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for automated CPR machines will continue to rise with the growing need for efficient emergency response solutions.
- Advancements in AI and IoT integration will enhance real-time monitoring and feedback capabilities in CPR devices.
- Increased public awareness and government-backed CPR training programs will drive broader adoption in public and pre-hospital settings.
- Strategic collaborations between healthcare providers and medical device companies will accelerate product development and accessibility.
- Manufacturers will focus on improving device portability and ease of use for faster deployment in critical situations.
- Growth in healthcare infrastructure across emerging economies will expand market penetration for CPR technologies.
- Investments in smart medical technologies will support the development of connected CPR systems for data-driven care.
- Market players will prioritize user training and post-sales support to improve confidence and efficiency in device usage.
- Standardization efforts across the industry will address operational challenges and improve cross-platform compatibility.
- The focus on improving survival rates will lead to innovation in hybrid CPR systems and advanced resuscitation techniques.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cardiopulmonary Resuscitation (CPR) Machine Market?
What factors are driving the growth of the Cardiopulmonary Resuscitation (CPR) Machine Market?
What are some challenges faced by the Cardiopulmonary Resuscitation (CPR) Machine Market?
Who are the major players in the Cardiopulmonary Resuscitation (CPR) Machine Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cardiopulmonary Resuscitation (CPR) Machine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cardiopulmonary Resuscitation (CPR) Machine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,600 million → 2032: USD 3,188 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cardiopulmonary Resuscitation (CPR) Machine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cardiopulmonary Resuscitation (CPR) Machine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cardiopulmonary Resuscitation (CPR) Machine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cardiopulmonary Resuscitation (CPR) Machine Market Drivers
- 3.3 Cardiopulmonary Resuscitation (CPR) Machine Market Restraints & Challenges
- 3.4 Cardiopulmonary Resuscitation (CPR) Machine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cardiopulmonary Resuscitation (CPR) Machine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cardiopulmonary Resuscitation (CPR) Machine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cardiopulmonary Resuscitation (CPR) Machine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cardiopulmonary Resuscitation (CPR) Machine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cardiopulmonary Resuscitation (CPR) Machine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cardiopulmonary Resuscitation (CPR) Machine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cardiopulmonary Resuscitation (CPR) Machine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cardiopulmonary Resuscitation (CPR) Machine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cardiopulmonary Resuscitation (CPR) Machine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cardiopulmonary Resuscitation (CPR) Machine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cardiopulmonary Resuscitation (CPR) Machine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cardiopulmonary Resuscitation (CPR) Machine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cardiopulmonary Resuscitation (CPR) Machine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cardiopulmonary Resuscitation (CPR) Machine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cardiopulmonary Resuscitation (CPR) Machine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cardiopulmonary Resuscitation (CPR) Machine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cardiopulmonary Resuscitation (CPR) Machine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cardiopulmonary Resuscitation (CPR) Machine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cardiopulmonary Resuscitation (CPR) Machine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
