
Weddings and record gold prices shape jewelry spending
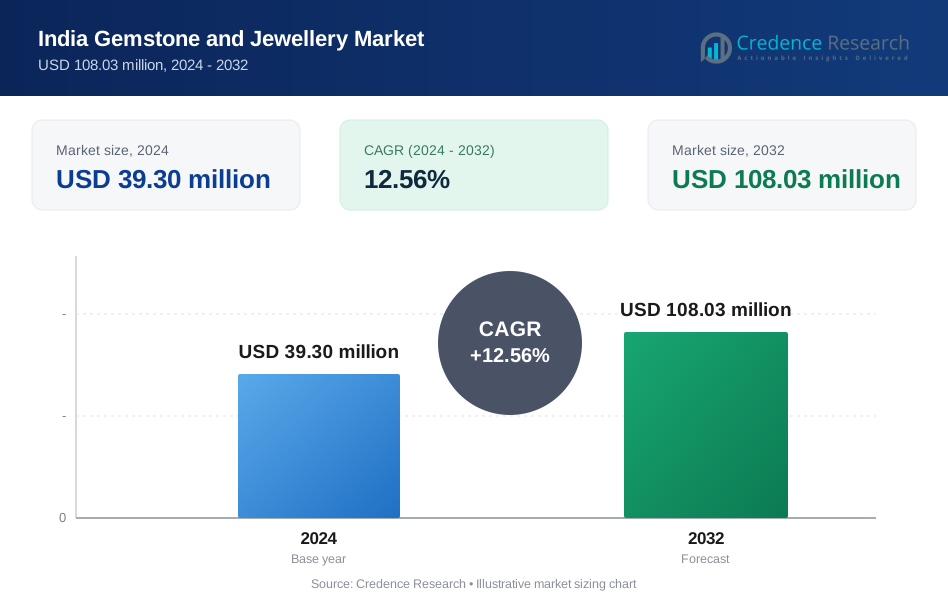
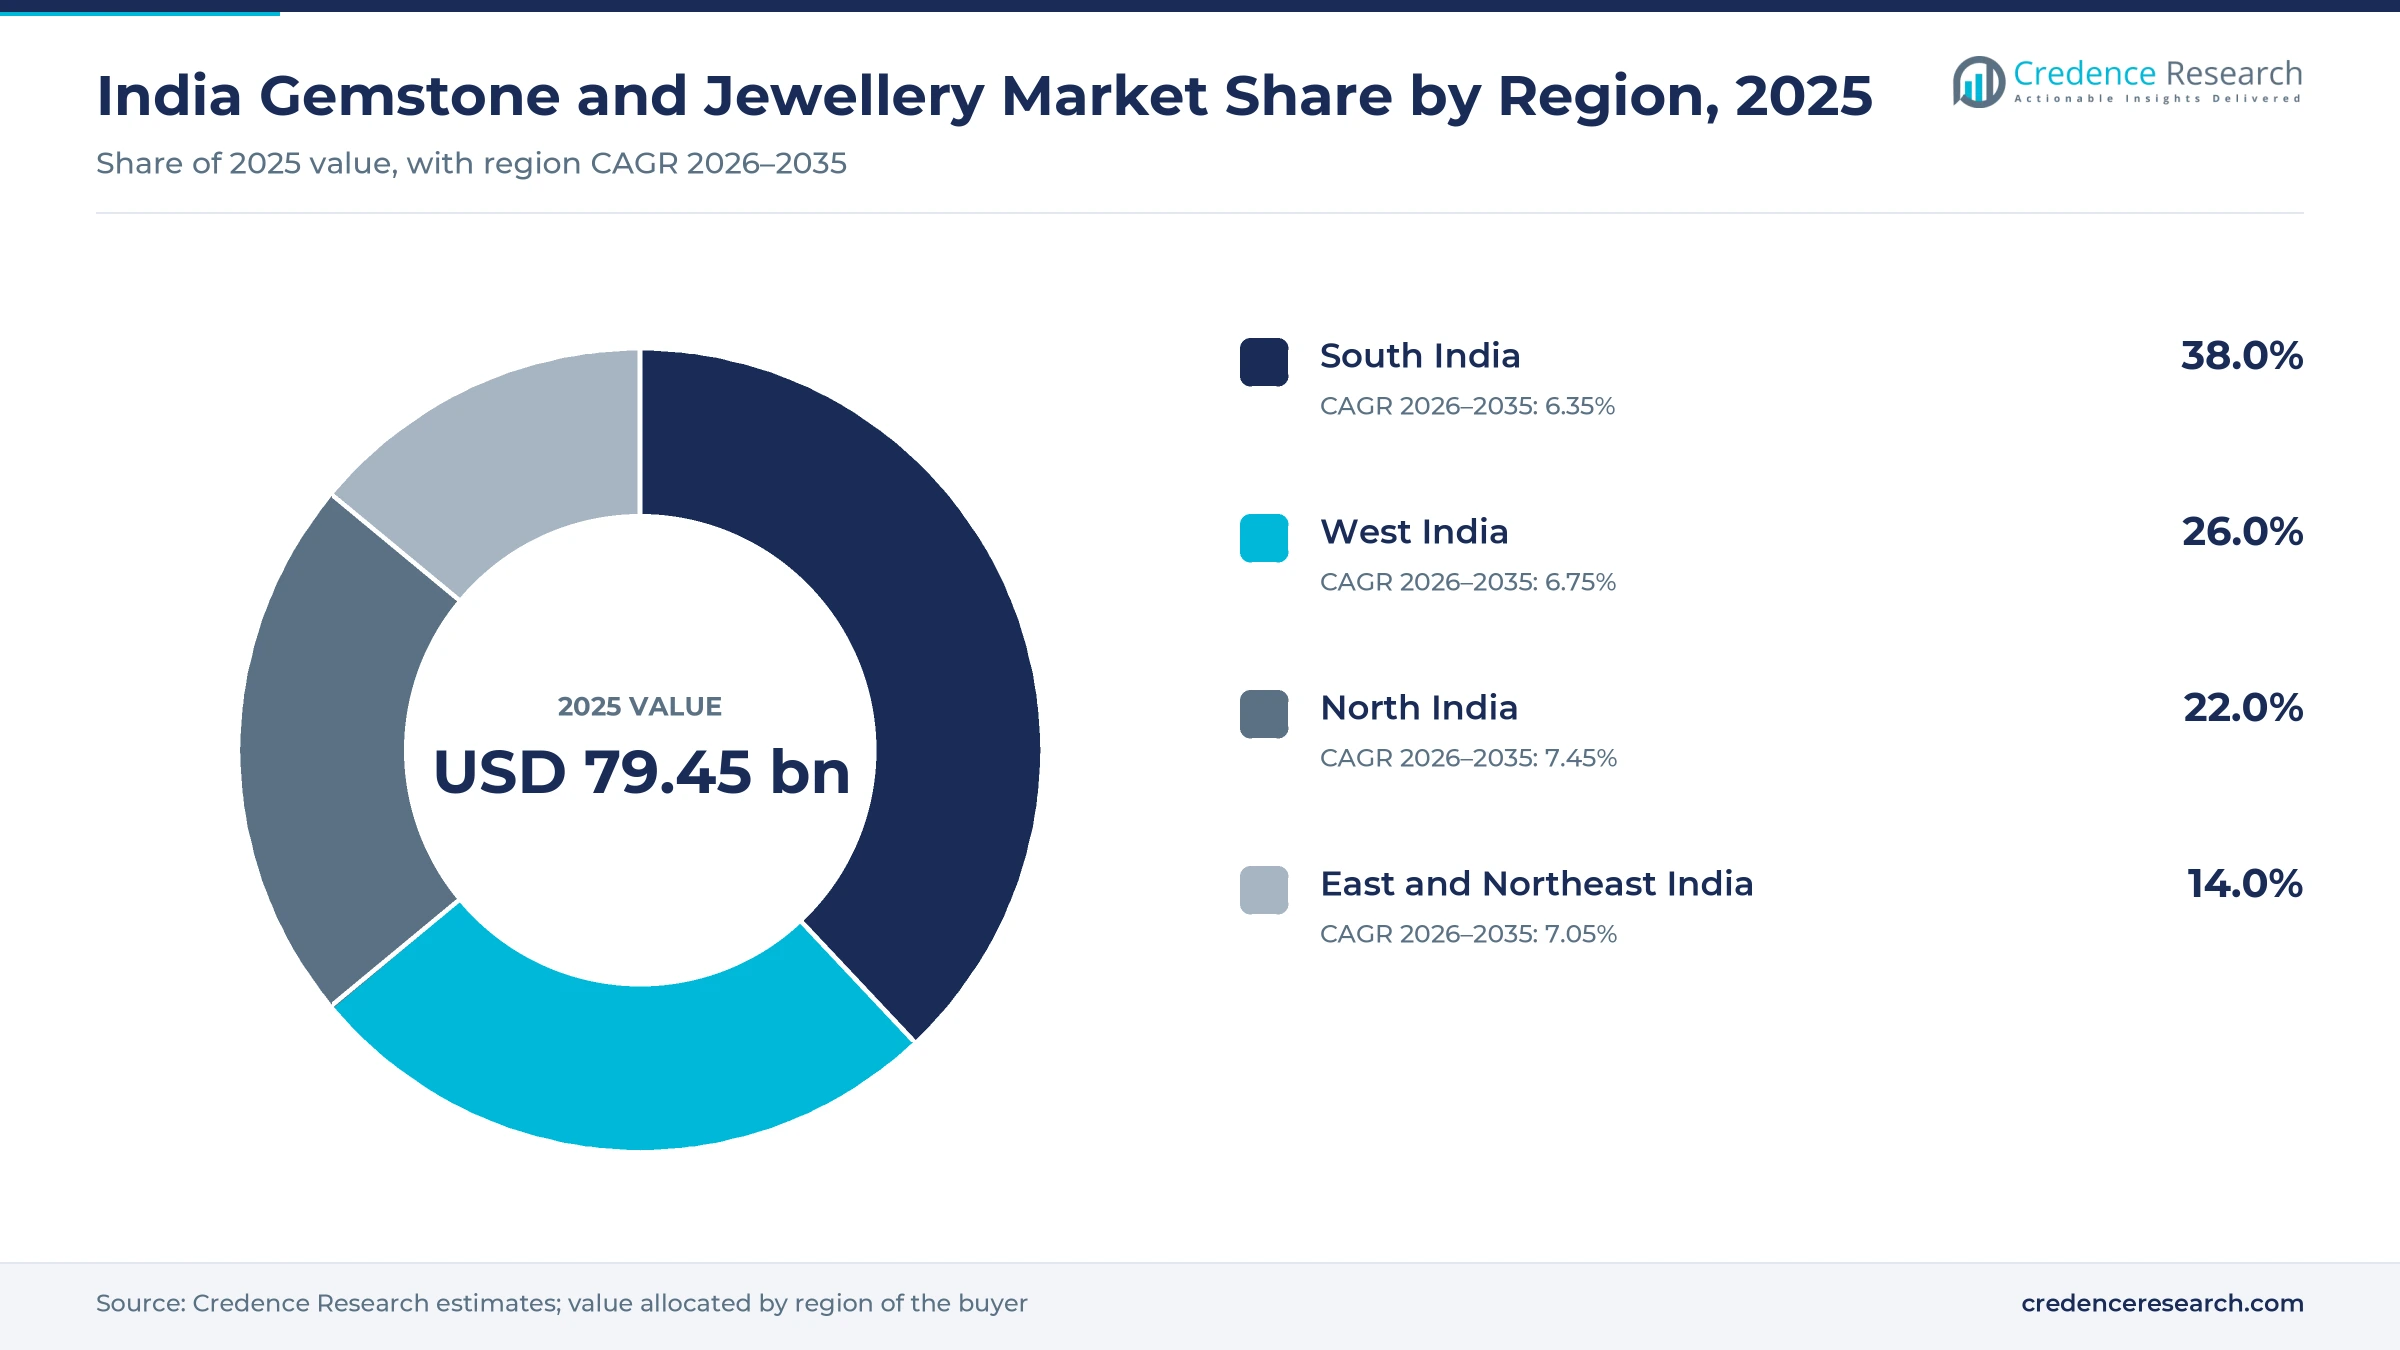
The India gemstone and jewellery market was valued at USD 79.45 billion in 2025 and is projected to increase from USD 84.85 billion in 2026 to USD 153.39 billion by 2035, registering a CAGR of 6.80% during 2026–2035. Demand rests on wedding and festival buying of gold, diamond and colored stone jewelry, on a large rural customer base and on a steady move from family jewelers to hallmarked branded chains. South India held the largest regional share, 38.0% in 2025, because plain 22-carat gold jewelry is bought in heavier weights across Kerala, Tamil Nadu, Karnataka and Andhra Pradesh. North India is the fastest-growing region at 7.45% a year, as national chains open franchise stores in smaller cities and younger urban buyers accept 14-carat designs. The main commercial change is price, because record gold prices in 2025 cut jewelry tonnage while lifting spending to a new high. Mandatory hallmarking with a unique HUID number also continues to widen across districts, which favors organized sellers.
What does the Indian gems and jewelry industry include?
The report counts the retail value of finished gold, diamond, platinum, silver and colored stone jewelry, together with loose certified gemstones, bought by consumers in India. The World Gold Council estimated that Indian buyers spent a record USD 49 billion on gold jewelry in 2025, even though volume fell 24% to 430.5 metric tons. Buyers purchase through national and regional chains, family-run stores, franchise outlets and brand websites and apps.
Exports, bullion bars, coins, gold exchange-traded funds and base metal costume pieces are excluded from the market value. According to the India Brand Equity Foundation, the sector has more than 300,000 players, employs about 5 million people and contributes about 7% of national GDP. The value chain runs from diamond cutting in Surat and Mumbai and colored stone cutting in Jaipur, through hallmarking centers and grading laboratories, to retail counters. On the export side, NITI Aayog reported in April 2026 that the country held 2.9% of global gems and jewellery exports in 2024, or 7.8% excluding raw gold.
India Gemstone and Jewellery Market Insights
- The market is projected to grow from USD 79.45 billion in 2025 to USD 153.39 billion by 2035 at a 6.80% CAGR, as higher gold prices and branded retail lift average ticket sizes.
- South India held 38.0% of 2025 value, because Kerala, Tamil Nadu and Karnataka buy plain 22-carat gold jewelry in heavier weights for weddings.
- Weddings held 45.0% of 2025 value, as the Confederation of All India Traders expected about 4.6 million weddings between Nov. 1 and Dec. 14, 2025.
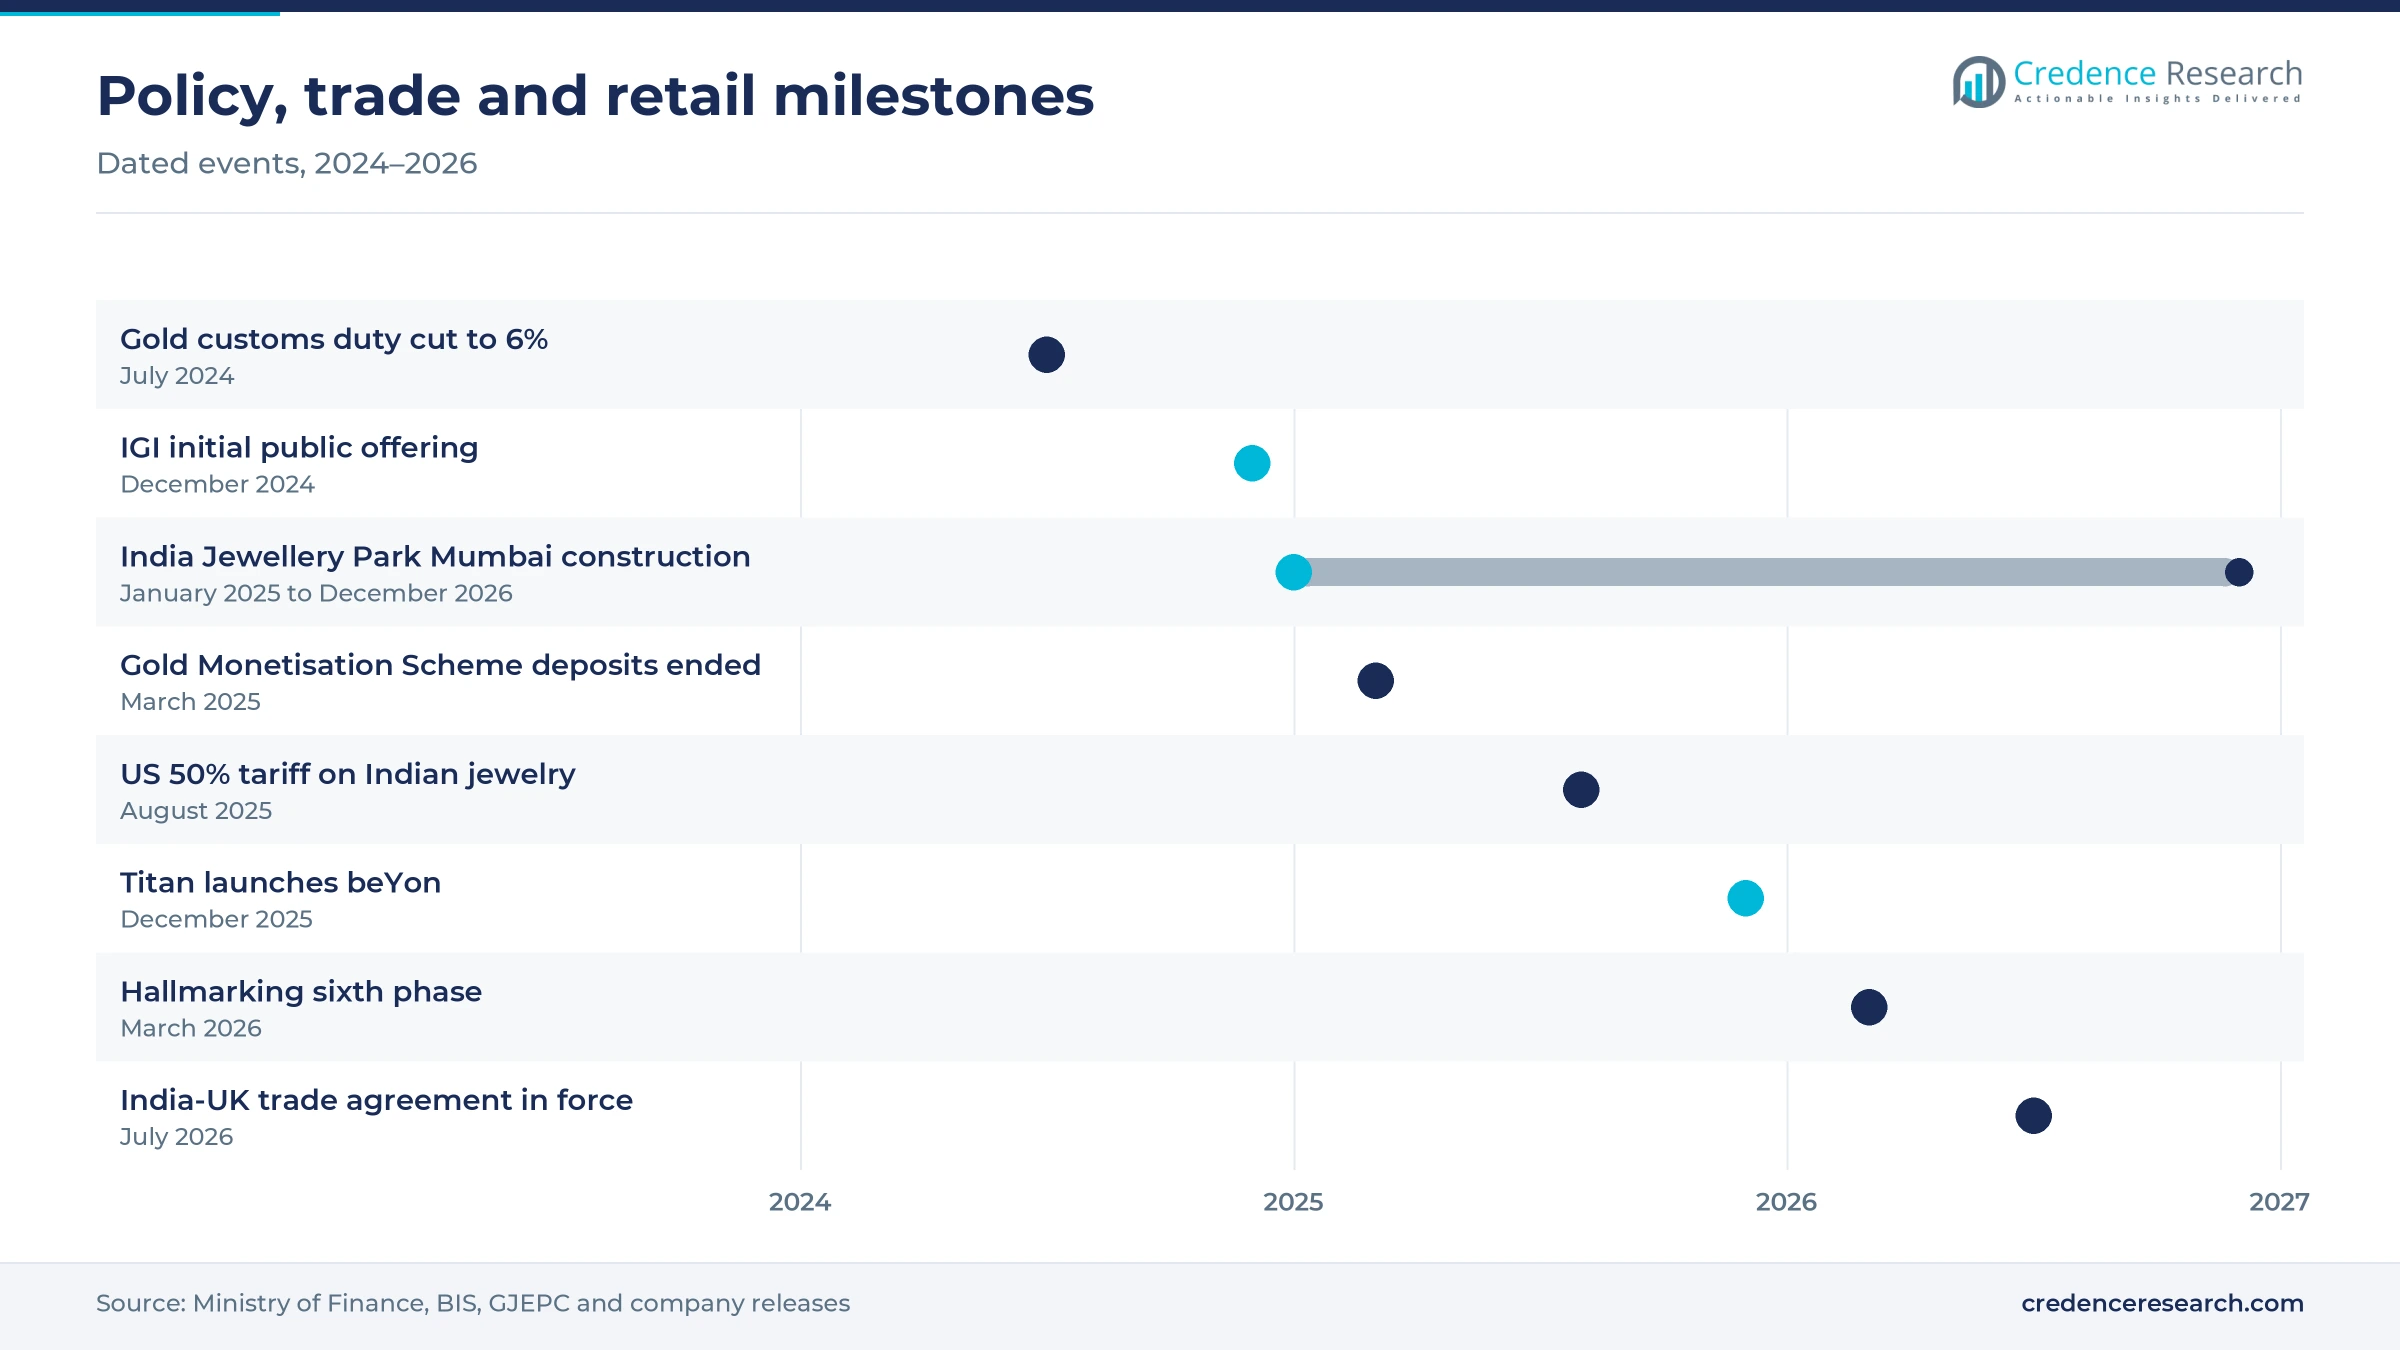
- The Bureau of Indian Standards extended mandatory hallmarking to 380 districts from March 2, 2026, after more than 600 million gold items received HUID marks.
- Titan ran 1,194 jewelry stores in India at the end of March 2026, while Kalyan Jewellers planned 170 new stores in fiscal 2026 through franchise partners.
Necklaces and wedding purchases hold the largest shares
Why do necklaces lead and chains and pendants grow fastest?
Based on product, the market is categorized into rings, necklaces, earrings, bracelets, chains and pendants, brooches and others. Necklaces led with 30.0% of 2025 value because heavy bridal and temple sets carry the most gold, and the World Gold Council places about 40% of national gold jewelry demand in the south, where plain 22-carat pieces dominate. Chains and Pendants grow fastest at 7.76% a year, as the World Gold Council found in January 2023 that 5 to 8 gram chains and mangalsutras, which were hard to find five years earlier, are now widely stocked for daily wear.
Why do weddings lead and fashion buying grow fastest?
Based on application, the market is categorized into collections, weddings, festive blessings, fashion and others. Weddings led with 45.0% of 2025 value because families buy gold as both adornment and savings at marriage, and the Confederation of All India Traders projected Rs 6.5 lakh crore of trade from about 4.6 million weddings between Nov. 1 and Dec. 14, 2025. Fashion grows fastest at 8.32% a year, as Titan opened its first beYon lab-grown diamond store in Mumbai on Dec. 29, 2025, and Reliance Jewels now sells IGI certified diamond and silver pieces online.
Why do physical stores lead while online sales grow fastest?
Based on distribution channel, the market is categorized into offline and online. Offline led with 92.0% of 2025 value because buyers want to check weight, purity and hallmarks in person, and Malabar Gold & Diamonds opened its 400th showroom in Noida in June 2025. Online grows fastest at 9.98% a year, as digital-first brands are scaling up quickly. BlueStone, which began as an online seller, opened its initial public offering on Aug. 11, 2025, and Kalyan Jewellers planned 80 new stores in fiscal 2026 for Candere, its digital-first brand.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product | Necklaces | 30.0% | Chains and Pendants | 7.76% |
| By Application | Weddings | 45.0% | Fashion | 8.32% |
| By Distribution Channel | Offline | 92.0% | Online | 9.98% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Weddings, branded chains and hallmarking lift sales
Wedding and festival buying anchors jewelry spending
Weddings and festivals remain the main reason Indian households buy jewelry, because gold given at marriage doubles as family savings. The Confederation of All India Traders expected the wedding season from Nov. 1 to Dec. 14, 2025, to generate Rs 6.5 lakh crore of trade, with jewelry taking 15% of that spending. Festival buying adds a second peak, as the same trade body estimated gold and bullion sales of about Rs 60,000 crore on Dhanteras in October 2025, up 25% from a year earlier. Senco Gold & Diamonds also reported that its retail sales rose 56% in October 2025 over October 2024. As a result, wedding purchases held 45.0% of 2025 value, and festive blessings form the second-largest application.
Branded chains expand into smaller cities
The move from family jewelers to national chains lifts market value, because branded stores sell hallmarked pieces with exchange and buyback policies that build trust. Titan ran 1,194 jewelry stores in India at the end of March 2026, including 370 CaratLane stores, according to its fourth-quarter update to the National Stock Exchange. Kalyan Jewellers planned 170 new stores in fiscal 2026, 90 under the Kalyan name and 80 under Candere, mostly through franchise partners outside the south. Malabar Gold & Diamonds opened its 400th showroom in June 2025 and planned 60 more stores by March 2026. In turn, these chains are filling franchise gaps in northern towns, which supports the fastest regional demand growth.
Mandatory hallmarking raises buyer confidence
Compulsory hallmarking is pushing purchases toward organized sellers, because each piece now carries a six-digit HUID code that buyers can check on the BIS CARE app. The Bureau of Indian Standards said more than 600 million gold items were hallmarked between July 1, 2021, and March 5, 2026, and it added seven districts in a sixth phase from March 2, 2026, taking coverage to 380 districts. The bureau then rolled out HUID-based silver hallmarking from Sept. 1, 2025, and more than 1.7 million silver articles were marked in the first three months, according to the Gems and Jewellery Export Promotion Council. These steps shrink the room for underkarated gold and support pricing at certified counters.
Lower import duty and steady GST support spending
Tax and duty changes since 2024 have kept jewelry affordable even as metal prices climbed. The Union Budget of July 23, 2024, cut basic customs duty on gold bars and findings from 15% to 6% to raise domestic value addition in precious metal jewelry, according to The Tribune. The GST Council kept gold and silver at 3% GST at its 56th meeting on Sept. 3, 2025, while making charges stayed at 5%. As a result, Indian buyers spent a record USD 49 billion on gold jewelry in 2025, according to the World Gold Council, even as gold prices in India rose about 74% over the year. This shift moved spending into value rather than weight, which favors retailers with large inventories.
Lighter designs and lab-grown diamonds reshape demand
Shift toward lighter and lower-carat designs
Record prices are shifting buyers toward lighter pieces, because households keep a fixed budget per occasion rather than a fixed weight. The World Gold Council reported that Indian gold jewelry volume fell 24% to 430.5 metric tons in 2025, and that buyers chose lighter pieces, traded in old jewelry and, in some north Indian cities, accepted 14-carat designs. In the third quarter alone, jewelry demand fell 31% to 117.7 metric tons while its value held at about Rs 1.14 lakh crore, according to Council data published by GJEPC. As early as January 2023, the World Gold Council reported that 5 to 8 gram chains and mangalsutras, impossible to buy five years before, were widely stocked. In turn, Chains and Pendants grow fastest at 7.76% a year.
Rise of lab-grown diamond jewelry
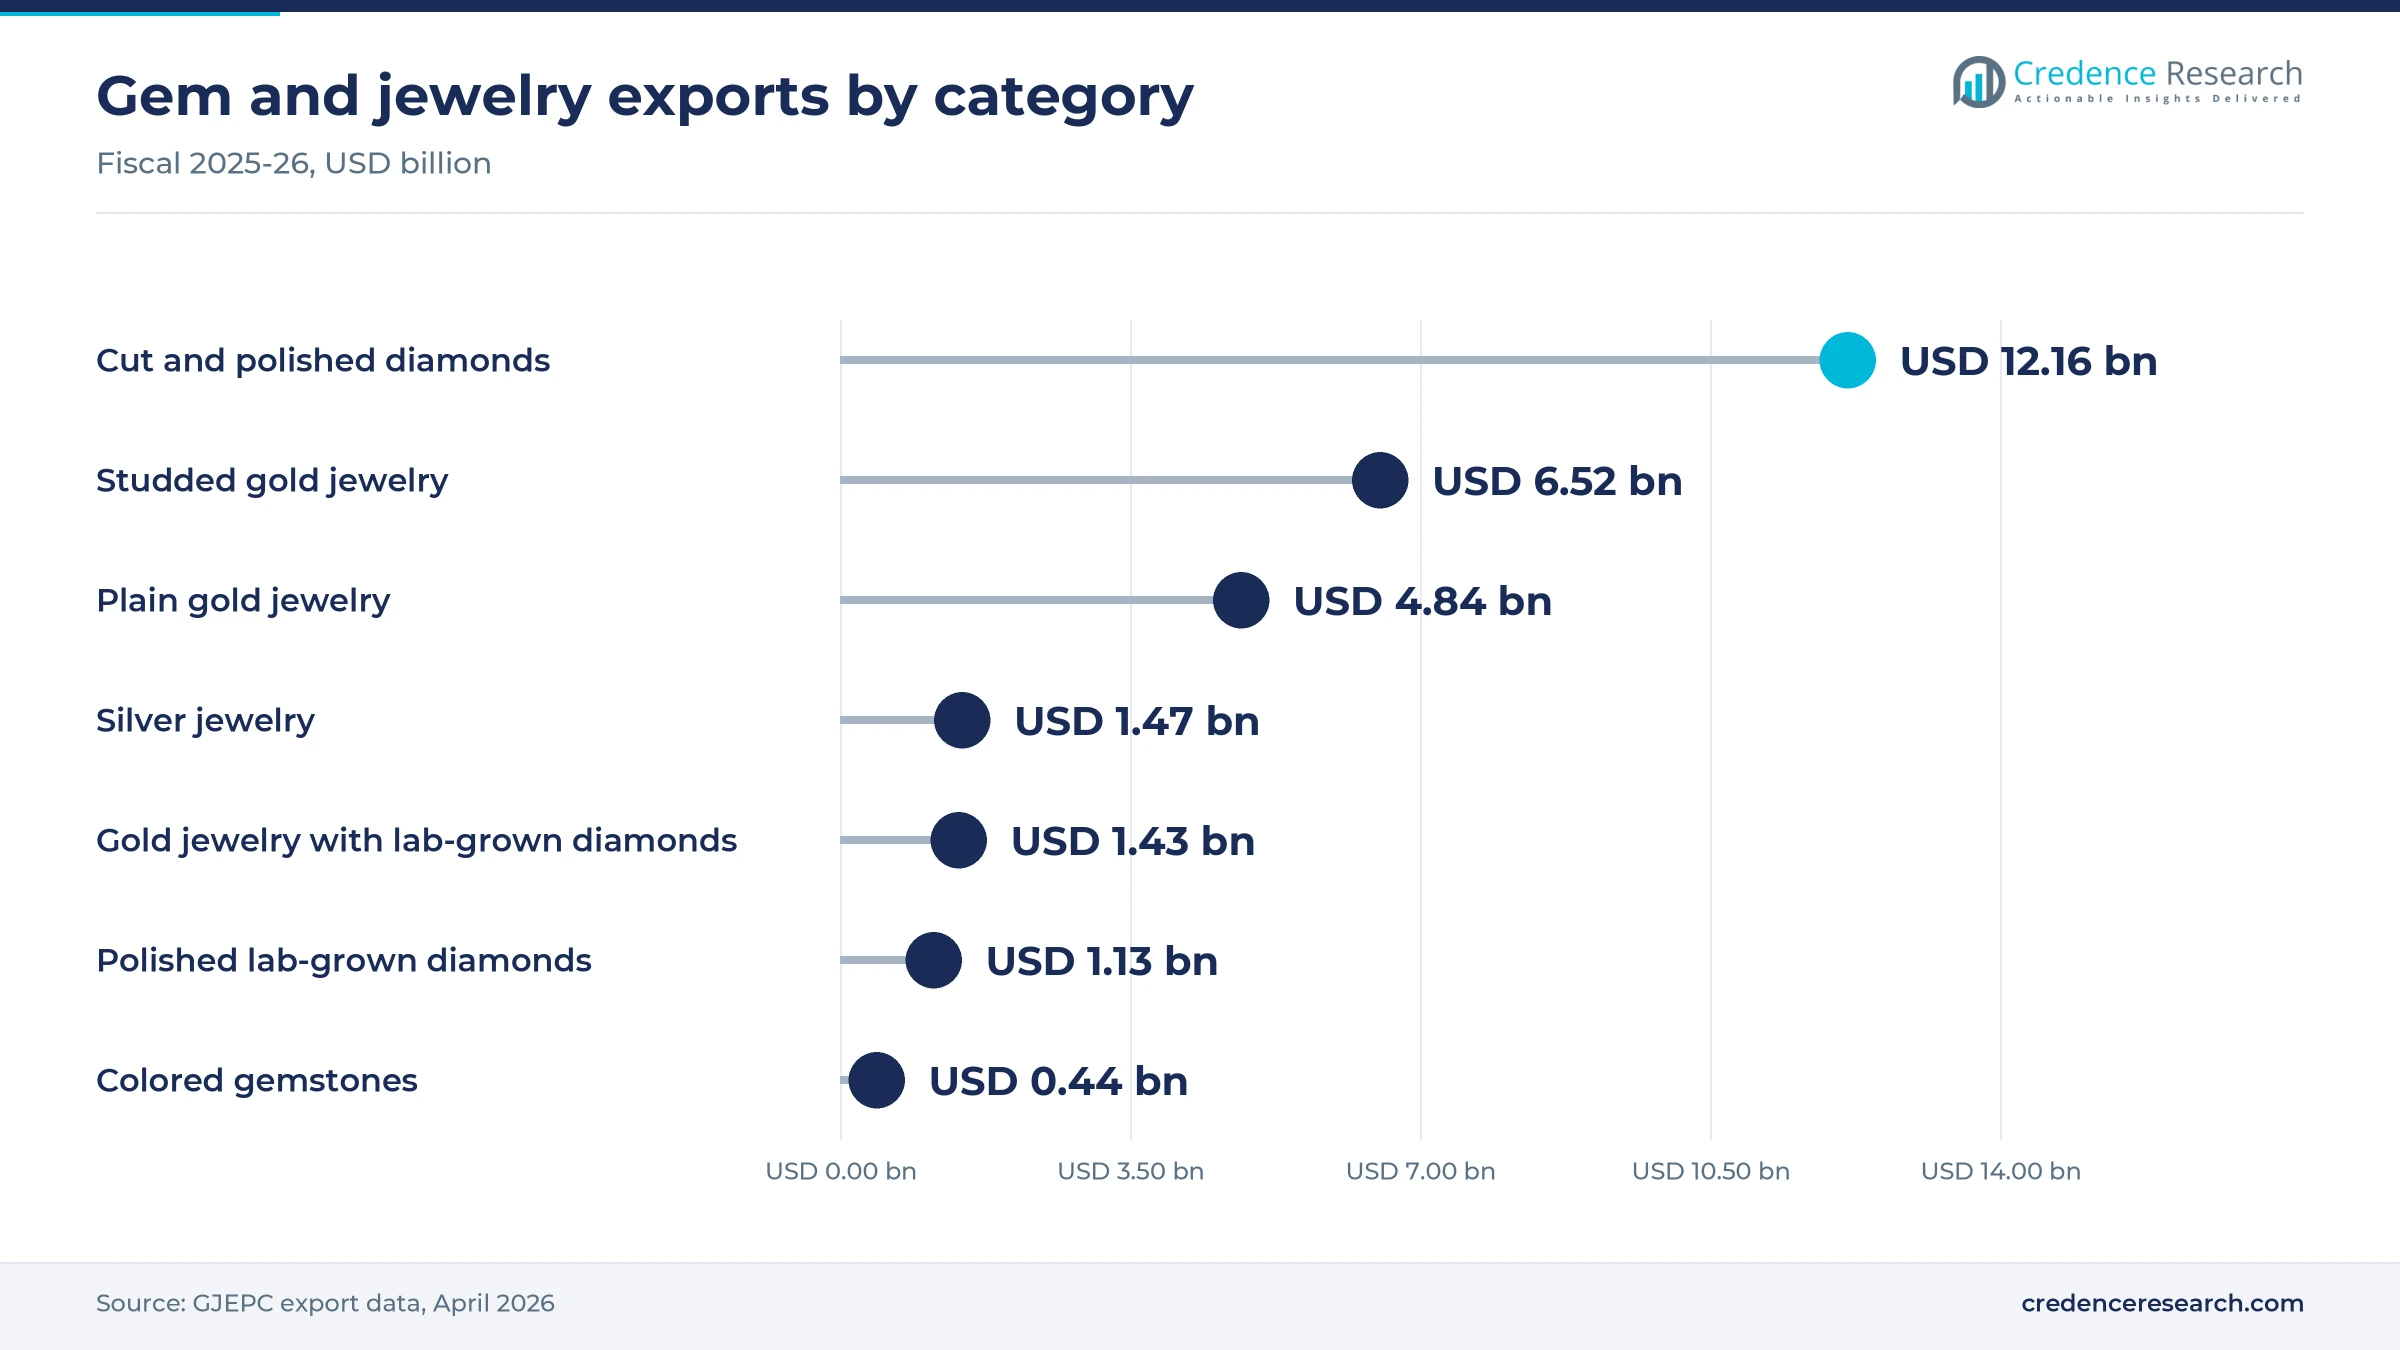
Lab-grown diamonds are emerging as a lower-cost route into diamond jewelry for first-time buyers and daily wear. Titan launched its beYon lab-grown brand with an exclusive store in Mumbai on Dec. 29, 2025, and planned more stores in Mumbai and Delhi, according to GJEPC. Supply is local, because India exported USD 1.13 billion of polished lab-grown diamonds and USD 1.43 billion of gold jewelry studded with lab-grown stones in fiscal 2025-26, according to GJEPC data reported by JewelBuzz. The second figure rose 31.30% in a year, which shows how quickly manufacturers have retooled. As a result, diamond-studded pieces now reach buyers at lower price points than natural stones allowed.
Opportunity in certified colored gemstones
Certified colored stones offer an opening for retailers that want higher margins than plain gold. India exported only USD 437.31 million of colored gemstones in fiscal 2025-26, against USD 11.36 billion of gold jewelry and USD 12.16 billion of cut and polished diamonds, according to GJEPC data reported by JewelBuzz. Grading capacity is already in place, because the International Gemological Institute, which runs 31 laboratories in 10 countries, raised Rs 4,225 crore in an IPO in December 2024. Brands that sell rubies, emeralds and sapphires with grading reports and buyback terms can build a premium niche, much as the colored stone trade has done in other consumer markets.
Opportunity in silver and hallmarked silver pieces
Silver jewelry is an opening for brands targeting buyers priced out of gold. Silver prices rose nearly 55% to about Rs 1.8 lakh per kilogram around Dhanteras 2025, according to the Confederation of All India Traders, yet Senco Gold & Diamonds reported about 8% growth in silver volume in October 2025. HUID-based silver hallmarking began on Sept. 1, 2025, which gives silver pieces the same purity check as gold. Export makers are also scaling up, as silver jewelry exports rose 52.21% to USD 1.47 billion in fiscal 2025-26, according to GJEPC data. Sterling silver direct-to-consumer brands can use this certified base to sell daily-wear designs in smaller cities.
Gold prices, U.S. tariffs and purity gaps strain sellers
Record gold prices squeeze volumes
High metal prices cut the weight of jewelry that households can afford. The World Bank's April 2026 Commodity Markets Outlook projected gold at USD 4,700 per troy ounce in 2026, while the average price in India reached Rs 97,075 per 10 grams in the third quarter of 2025, according to the World Gold Council. Smaller retailers that buy gold on credit face higher working capital needs as a result. Chains respond with lighter designs, gold metal loans and old-gold exchange programs that recycle customer stock.
U.S. tariffs hit export manufacturers
Export makers lost their largest buyer after the United States imposed a 50% tariff on Indian gems and jewelry from Aug. 27, 2025. Total exports fell 3.32% to USD 27.72 billion in fiscal 2025-26, and shipments to the U.S. dropped 44.92% to USD 5.09 billion, according to GJEPC data reported by JewelBuzz. The council had warned that nearly 170,000 workers in Surat, Mumbai and Jaipur were at risk. Some units now push stock to domestic retailers, which adds price pressure in the home market.
Unorganized trade and purity gaps persist
Large parts of the trade still sell outside formal billing, which limits buyer protection and tax collection. Mandatory hallmarking applies only in notified districts even after its sixth phase in March 2026, so stores elsewhere can still sell unmarked gold. Rural buyers, who account for 55% to 58% of Indian gold demand according to the World Gold Council, are the most exposed. As a result, chains spend on purity-testing machines and awareness drives, and the Bureau of Indian Standards keeps adding districts in phases.
Fewer channels to recycle household gold
The Ministry of Finance discontinued the medium and long term deposit components of the Gold Monetisation Scheme on March 26, 2025, which removed a route for idle household gold to reach jewelers through banks. Retailers now depend more on their own old-gold exchange schemes and on imported metal for raw material. This raises exposure to import prices and the rupee for jewelers that lack large exchange programs. Gold metal loans remain available, but they carry hedging and interest costs.
South India leads as north India grows fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
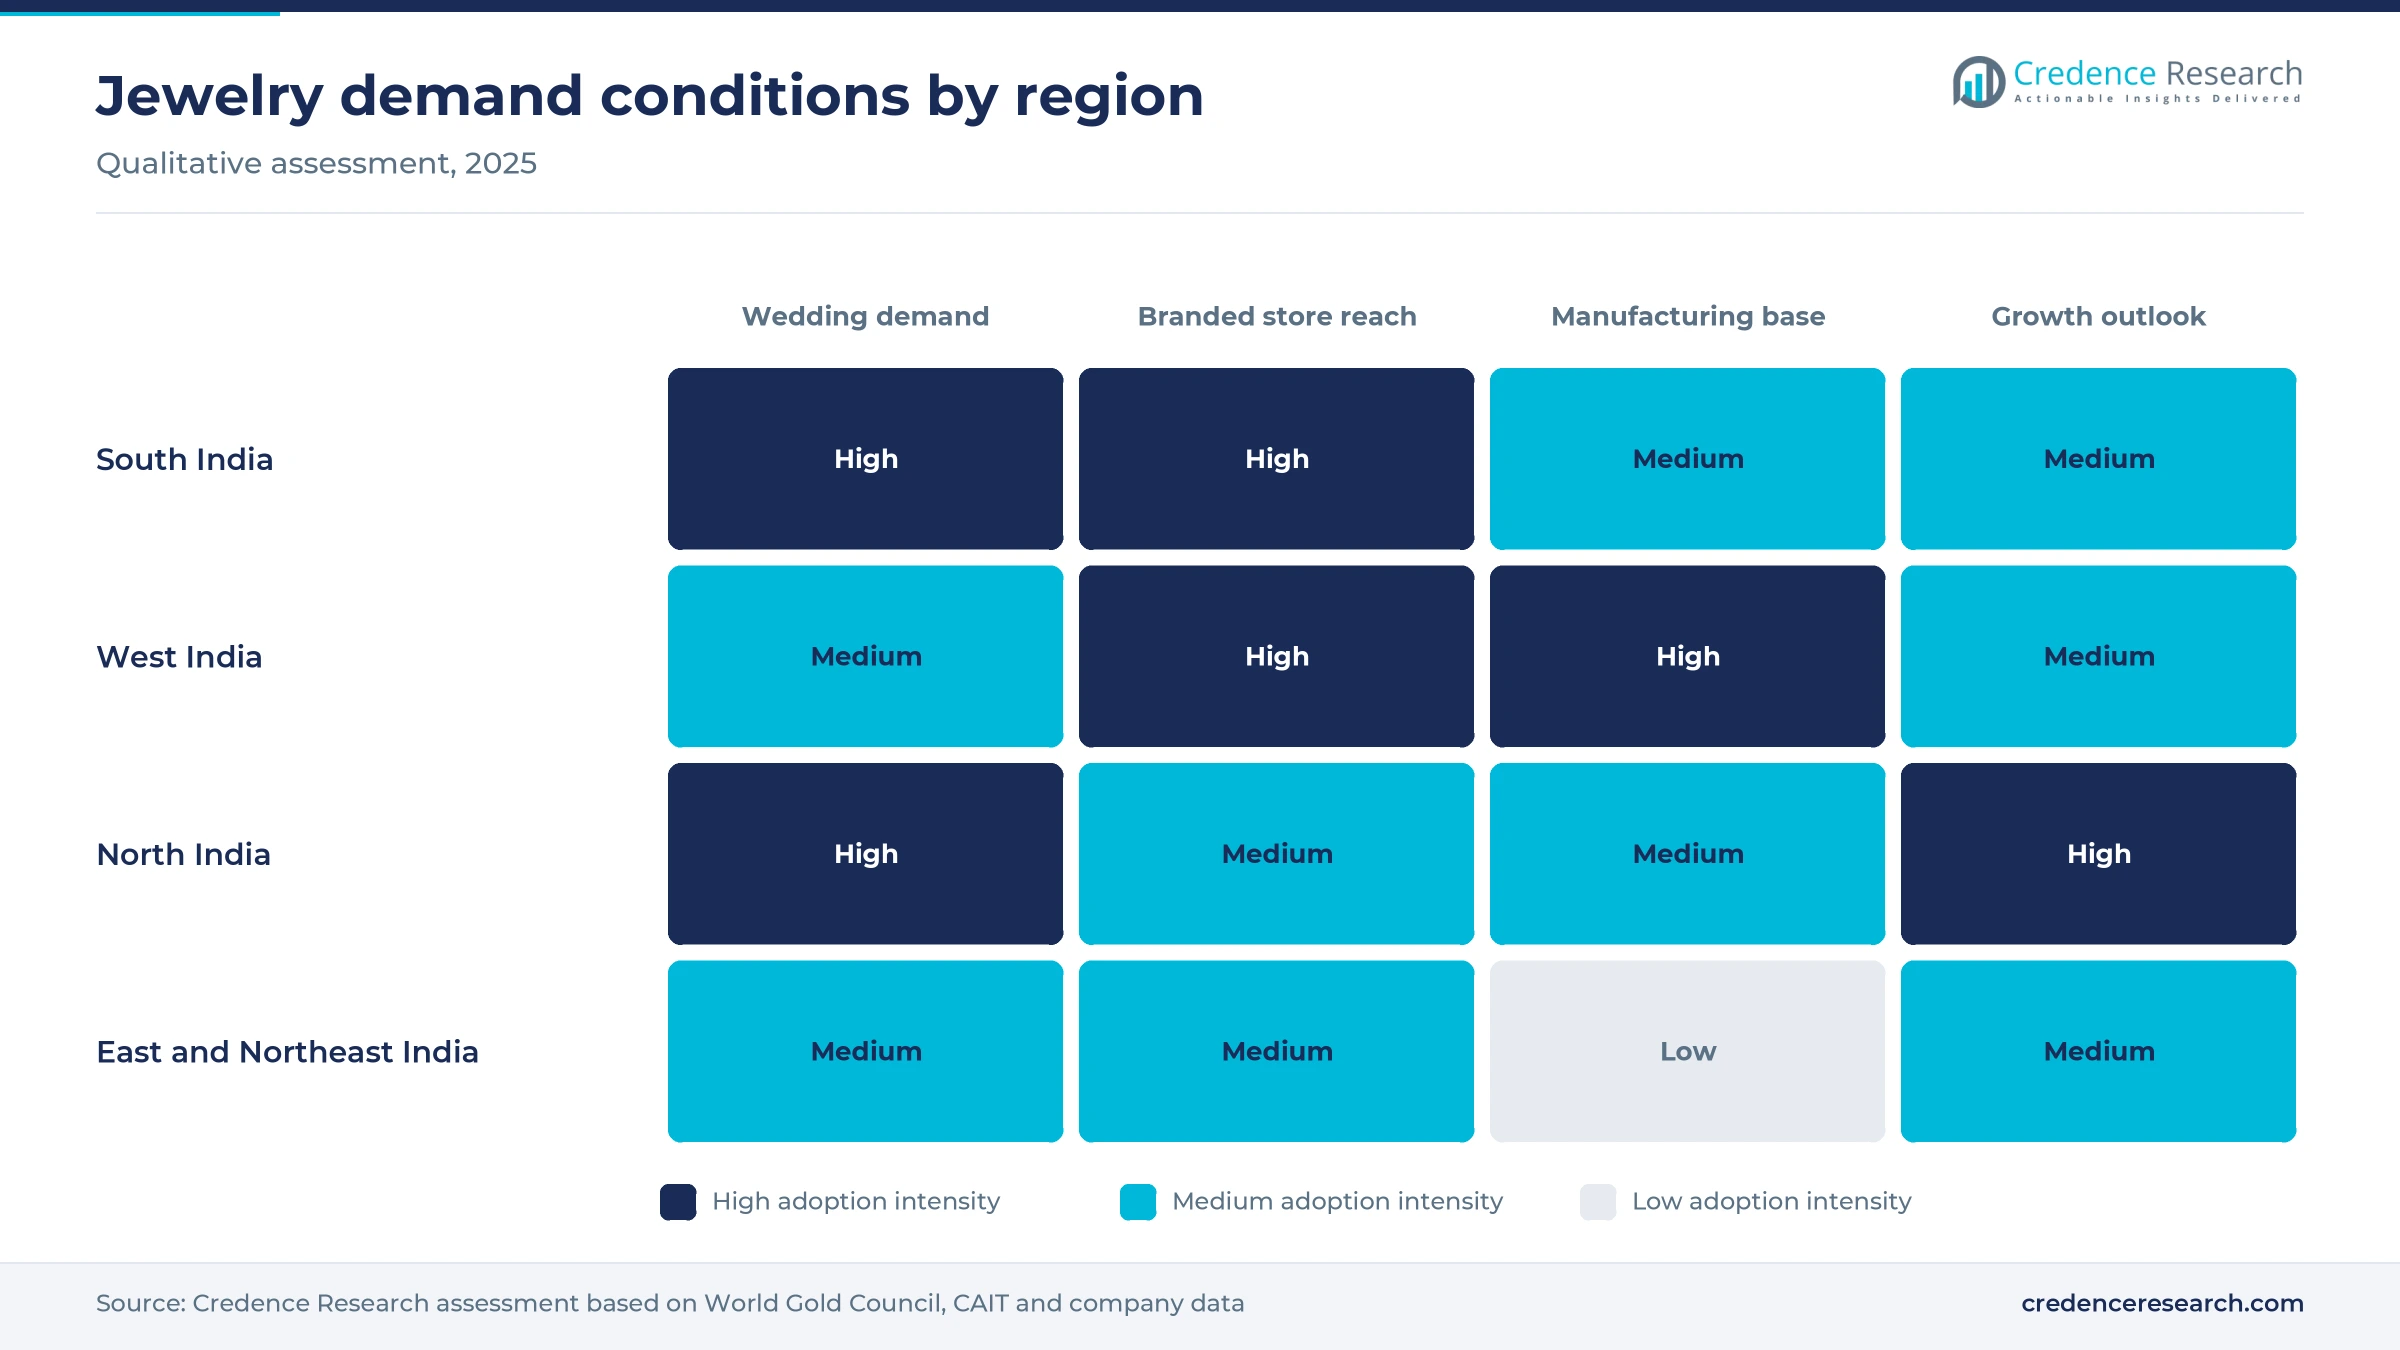
| South India | 30.19 | 38.0% | 6.35% |
| West India | 20.66 | 26.0% | 6.75% |
| North India | 17.48 | 22.0% | 7.45% |
| East and Northeast India | 11.12 | 14.0% | 7.05% |
South India leads on plain gold bridal buying
South India held 38.0% of 2025 value and grows at 6.35% a year, because plain 22-carat gold jewelry dominates bridal and festive buying in Kerala, Tamil Nadu, Karnataka, Andhra Pradesh and Telangana. Store density is already high, since Kalyan Jewellers alone ran 287 stores in India at June 30, 2025, many of them in the south. Growth is steadier than elsewhere for that reason, and Kalyan Jewellers now directs new franchise stores to markets outside the south, according to the company.
West India gains from Mumbai and Surat supply
West India held 26.0% of 2025 value and grows at 6.75% a year, supported by the manufacturing base in Mumbai and the diamond cutting hub in Surat. Construction of India Jewellery Park Mumbai in Navi Mumbai began in January 2025, with Rs 50,000 crore of planned investment and more than 100,000 expected jobs, according to Indian Jeweller. The Western region shipped USD 18.58 billion of exports in fiscal 2025-26, according to GJEPC data. This supplier density shortens design-to-shelf times for retailers in Maharashtra and Gujarat.
North India grows fastest as chains add franchises
North India held 22.0% of 2025 value and is the fastest-growing region at 7.45% a year, as national chains add franchise stores in Uttar Pradesh, Punjab, Rajasthan and Delhi. The Confederation of All India Traders expected Delhi alone to host about 480,000 weddings with Rs 1.8 lakh crore of trade in the 2025 season. Delhi bullion markets also recorded sales above Rs 10,000 crore on Dhanteras 2025, according to the All India Jewellers and Goldsmith Federation. Jaipur adds a colored gemstone cutting cluster to the region.
East and Northeast India rely on regional chains
East and Northeast India held 14.0% of 2025 value and grows at 7.05% a year, led by West Bengal, Odisha, Bihar, Assam and the northeastern states. Senco Gold & Diamonds, which ran 185 showrooms in India in November 2025, reported 60% growth in gold jewelry value in its October 2025 festive sales. The company also expected 18% to 20% growth for the rest of fiscal 2026 and planned 7 to 9 more showrooms. BlueStone opened its 150th store in Dimapur, Nagaland, in February 2023, which was its 14th city in the east.
Duty cuts, tariffs and new brands since 2024
| Development | Status and market relevance |
|---|---|
| In March 2025, the Ministry of Finance discontinued the medium and long term deposit components of the Gold Monetisation Scheme. | Short-term bank deposits continue at the discretion of individual banks |
| In August 2025, the United States applied a 50% tariff on gems and jewelry imported from India, effective Aug. 27. | Exporters are shifting sales toward the UAE, Hong Kong and domestic buyers |
| In December 2025, Titan launched beYon, its lab-grown diamond jewelry brand, with an exclusive store in Mumbai. | More beYon stores are planned in Mumbai and Delhi |
| In March 2026, the Bureau of Indian Standards added seven districts to mandatory gold hallmarking in a sixth phase. | Hallmarking coverage keeps widening in phases |
| In July 2026, the India-U.K. Comprehensive Economic and Trade Agreement took effect with duty-free access for Indian jewelry. | GJEPC expects U.K. exports to rise from USD 754 million to about USD 2.5 billion |
HUID codes, lab-grown stones and purity testing
- HUID hallmarking assigns each gold or silver piece a laser-engraved code that buyers can verify on the BIS CARE app before purchase.
- CVD diamond growing lets factories in Surat produce lab-grown stones that are cut and set into lower-priced jewelry for domestic and export buyers.
- Computer-aided design and casting allows chains to turn out lightweight designs at scale with consistent purity and finish.
- Gold purity analyzers use X-ray fluorescence at store counters to test old gold before exchange, which supports trade-in programs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
National chains compete with regional family jewelers
Competition in the India gemstone and jewellery market splits between national chains, regional family jewelers and digital-first brands. Titan, through Tanishq, Mia, Zoya, beYon and CaratLane, runs the widest branded network, while Kalyan Jewellers and Malabar Gold & Diamonds compete on large showrooms and wedding collections. Senco Gold & Diamonds is the main chain in the east, and Reliance Jewels, PC Jeweller and Joyalukkas add further organized capacity with hallmarked gold and certified diamond lines. BlueStone and Candere use online catalogs to steer buyers into stores. Players compete on making charges, exchange offers for old gold, lightweight designs and certified diamonds. Independent jewelers still control a large share of sales in smaller towns, so franchise partnerships are the main way chains enter new districts. Hallmarking has narrowed the purity gap between organized and independent sellers, which shifts the contest toward design, service and financing.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Titan Company (Tanishq, CaratLane, beYon) | National chain | Largest branded store network with 1,194 jewelry stores |
| Kalyan Jewellers | National chain | Franchise-led expansion outside the south, owns Candere |
| Malabar Gold & Diamonds | National chain | Large-format showrooms, 400th store opened in June 2025 |
| Senco Gold & Diamonds | Regional chain | Leading eastern chain with 185 showrooms in India |
| BlueStone Jewellery and Lifestyle | Omnichannel brand | Online-led diamond jewelry with company and franchise stores |
| Reliance Jewels | National chain | Hallmarked gold, IGI certified diamonds and silver online and in stores |
| Joyalukkas India | National chain | Gold and diamond showrooms with online sales |
| PC Jeweller | National chain | Gold, diamond and silver collections sold in stores and online |
Value, not tonnage, will drive growth to 2035
Credence Research's view is that value, not tonnage, will drive the market through 2035. Record gold prices cut 2025 jewelry volume by about a quarter, yet spending reached a new high, which shows that buyers in the India gemstone and jewellery market adjust weight and carat before they skip an occasion. The winners will be chains that combine hallmarked gold, certified diamonds and lab-grown options with exchange programs in smaller towns. Export makers hurt by U.S. tariffs may add domestic supply and press margins in the near term. Over the forecast period, branded reach, lighter designs and wider certification should keep growth steady.
How Credence Research sized the market
The report uses 2025 as the base year and forecasts the market to 2035, with growth rates for 2026–2035. Market values come from the Credence Research model, which starts from World Gold Council estimates of gold jewelry spending and adds making charges, taxes and diamond, silver, platinum and colored stone jewelry. Regional and segment splits are Credence Research estimates based on zone-level demand data, store networks and wedding activity. Sources include World Gold Council reports, Bureau of Indian Standards releases, GJEPC export data, Ministry of Finance notices, World Bank price forecasts, company stock exchange filings and trade press. No interviews or surveys were used to prepare this edition of the report.
Daily wear and certified stones gain share to 2035
The India gemstone and jewellery market is projected to reach USD 153.39 billion by 2035, growing at a 6.80% CAGR over 2026–2035. Weddings will keep the largest share of spending, while daily-wear chains, pendants and lab-grown diamond pieces gain ground with younger buyers. North India should gain share as chains open franchise stores, while South India keeps the lead on value. Wider hallmarking of gold and silver, the India-U.K. trade agreement and the planned India Jewellery Park Mumbai will strengthen the supply base. Gold price swings remain the main risk to volume, so retailers with strong exchange and buyback programs are best placed.
Frequently Asked Questions
How big is the India gemstone and jewellery market?
What is the size of the gemstone segment in India?
How large is the gems and jewelry industry in India?
What is India's share of world gems and jewellery exports?
Which region leads the market?
Which application holds the largest share?
How are gemstones and jewelry certified in India?
Who are the leading companies in the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Necklaces
- 1.2.2 Chains and Pendants
- 1.2.3 Earrings
- 1.2.4 Rings
- 1.2.5 Bracelets
- 1.2.6 Brooches
- 1.2.7 Others
- 1.3 By Application
- 1.3.1 Weddings
- 1.3.2 Festive Blessings
- 1.3.3 Fashion
- 1.3.4 Collections
- 1.3.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 79.45 billion → 2035: USD 153.39 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Gemstone and Jewellery Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Gemstone and Jewellery Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Gemstone and Jewellery Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Gemstone and Jewellery Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Gemstone and Jewellery Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Gemstone and Jewellery Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 India Gemstone and Jewellery Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Gemstone and Jewellery Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 79.45 billion → 2035: USD 153.39 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Gemstone and Jewellery Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Necklaces
- 12.3.7.2 Chains and Pendants
- 12.3.7.3 Earrings
- 12.3.7.4 Rings
- 12.3.7.5 Bracelets
- 12.3.7.6 Brooches
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Weddings
- 12.4.7.2 Festive Blessings
- 12.4.7.3 Fashion
- 12.4.7.4 Collections
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 India Gemstone and Jewellery End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Gemstone and Jewellery Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Gemstone and Jewellery Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Gemstone and Jewellery Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Titan Company Limited (Tanishq, CaratLane)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Malabar Gold & Diamonds
- 18.4 Kalyan Jewellers
- 18.5 Senco Gold & Diamonds
- 18.6 Reliance Jewels
- 18.7 PC Jeweller Ltd.
- 18.8 Joyalukkas India Ltd.
- 18.9 BlueStone Jewellery and Lifestyle
- 18.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

