
Room revenue from 73,000 hotel rooms and serviced stays
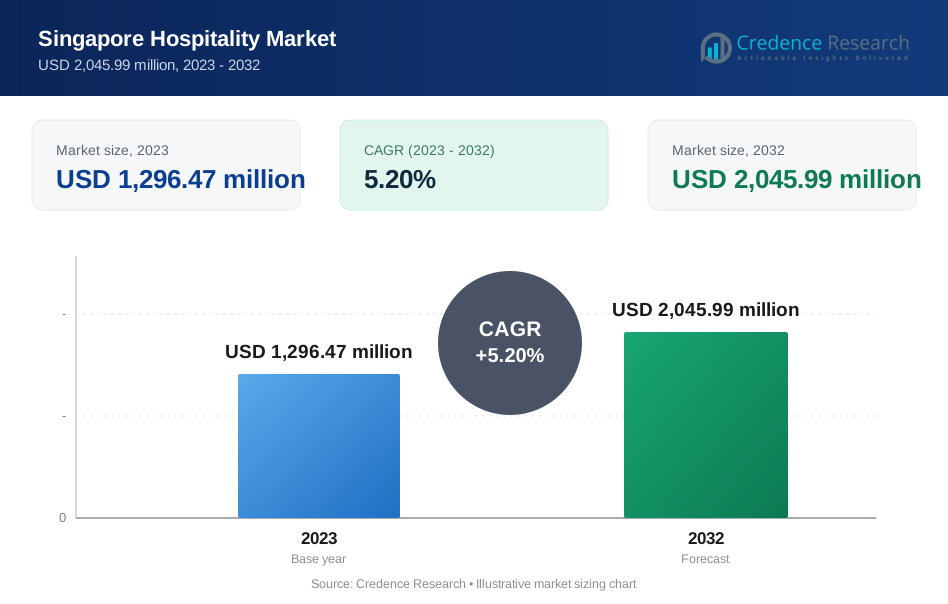
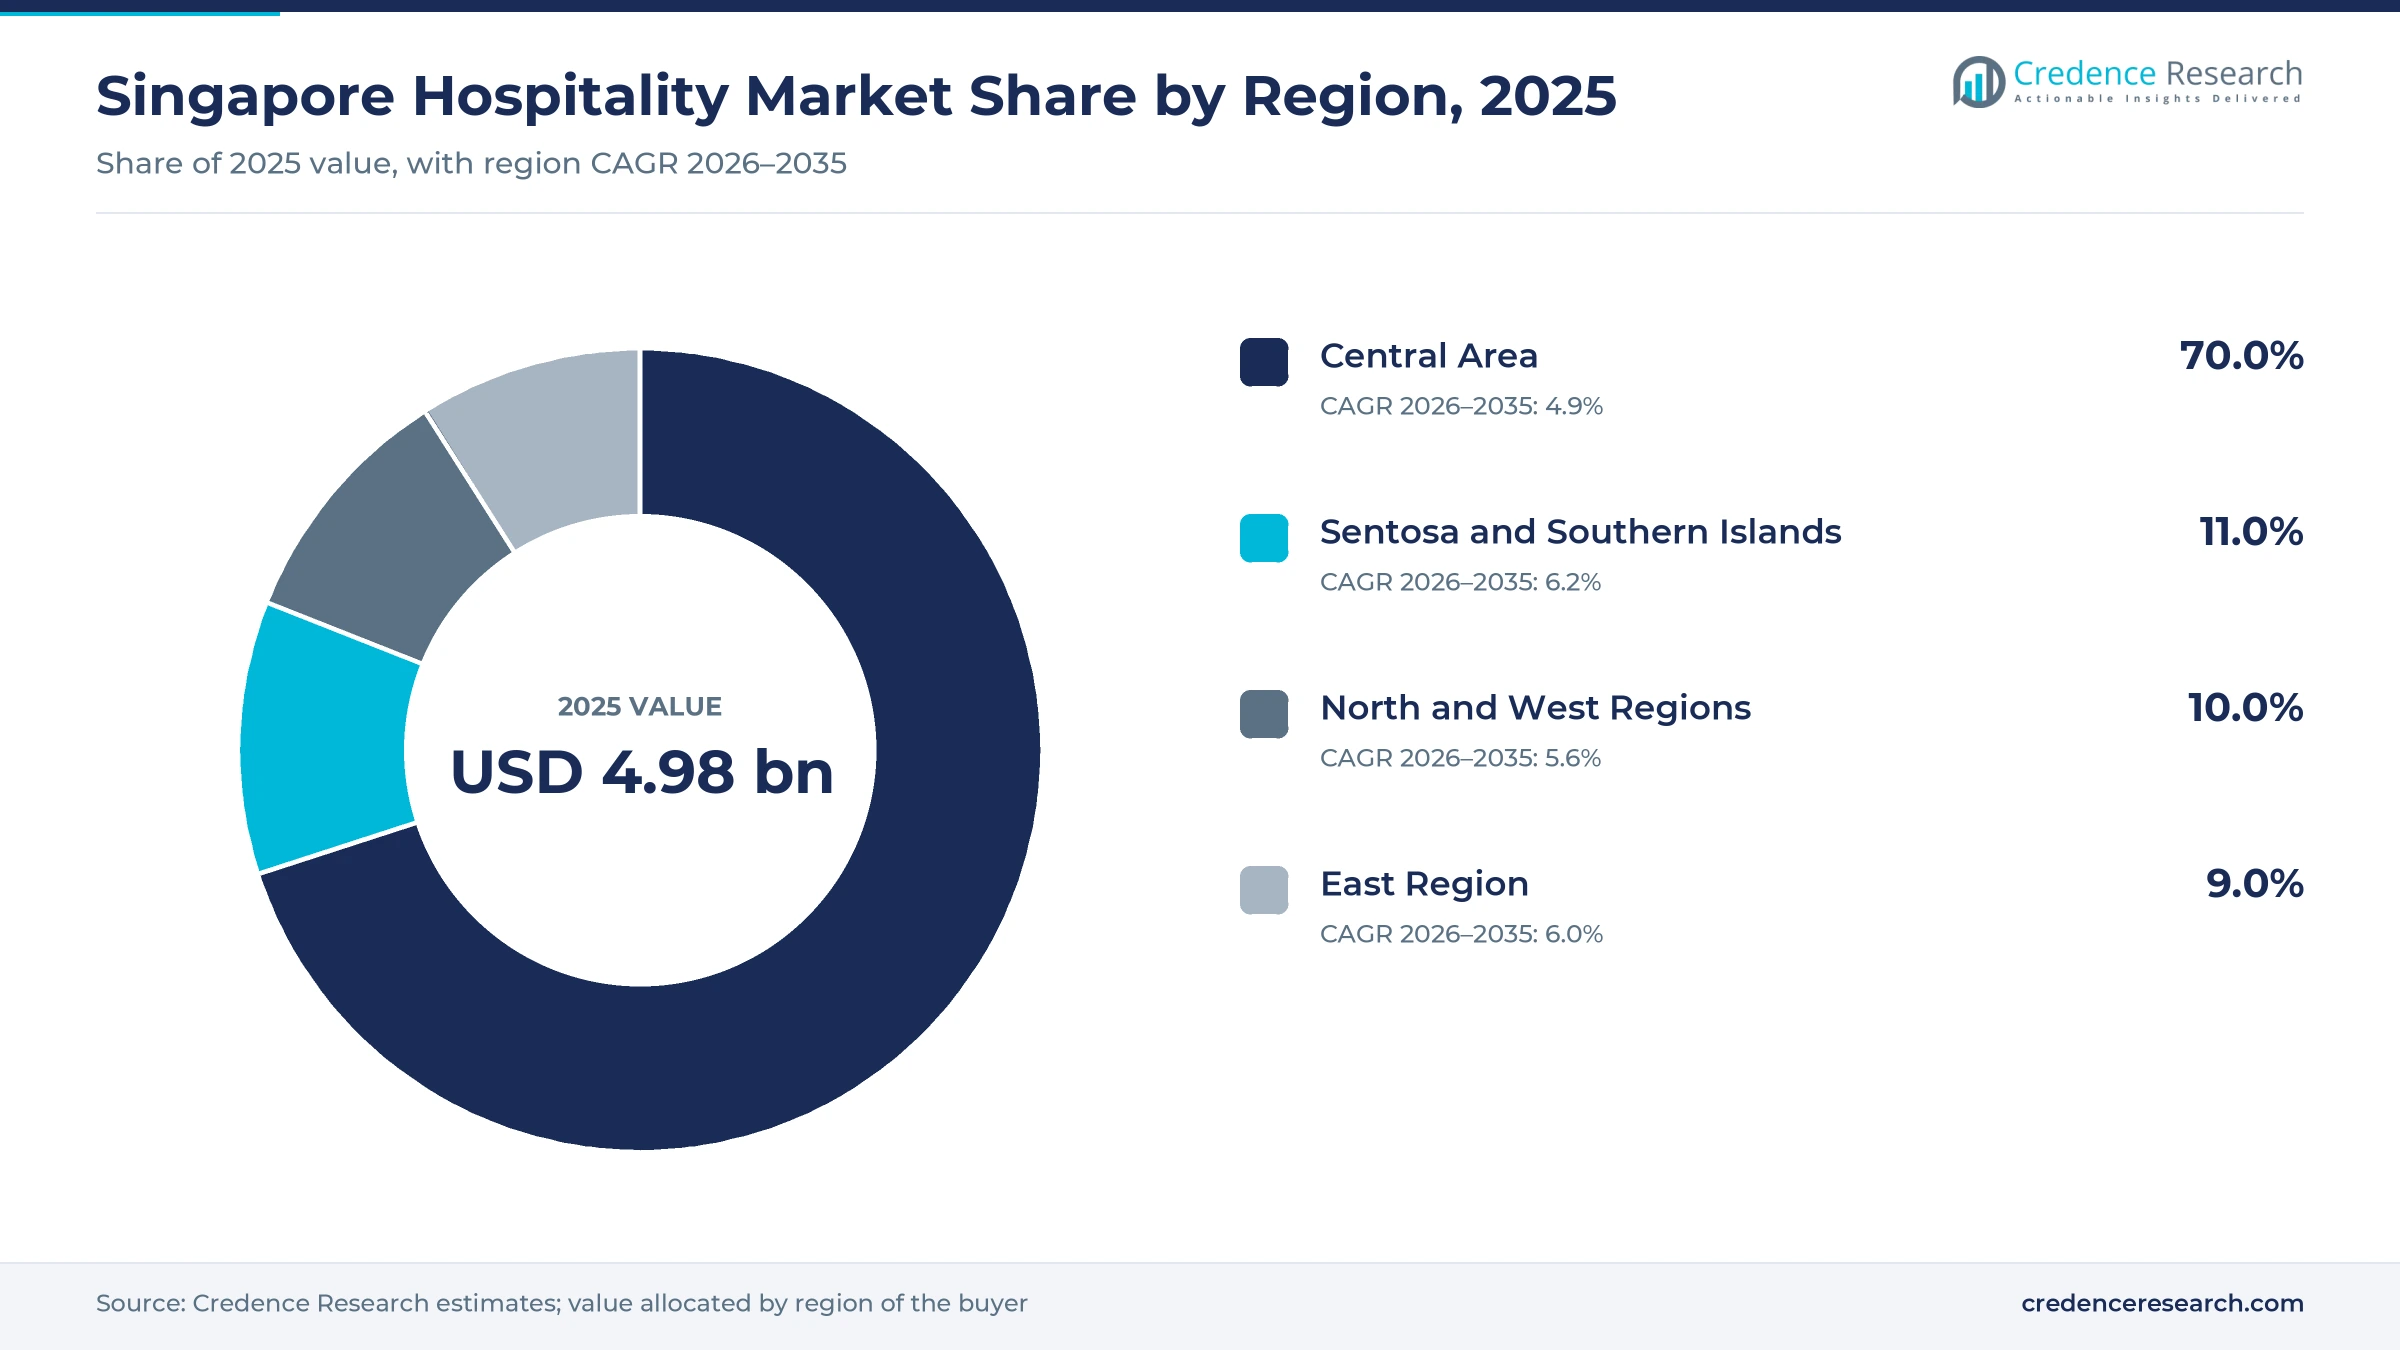
The Singapore hospitality market was valued at USD 4.98 billion in 2025 and is projected to increase from USD 5.24 billion in 2026 to USD 8.27 billion by 2035, registering a CAGR of 5.20% during 2026–2035. Demand comes from 16.9 million international visitors in 2025, business events, major concerts and sports weekends, and longer corporate assignments that fill serviced apartments. Central Area held the largest regional share, 70.0% in 2025, because Marina Bay, Orchard Road and the downtown core hold most of the room stock and convention space. Sentosa and Southern Islands is the fastest-growing region at 6.2% a year, as new resort suites and villas open on the island. The main commercial change is a wave of brand conversions and refurbishments, as older hotels join international soft brands and use state co-funding to upgrade rooms. Room rates were broadly flat in 2025, so growth now depends on occupancy, events and new supply rather than price increases.
How large is the hotel industry in Singapore?
The report counts room and accommodation revenue earned by licensed hotels and serviced apartments in Singapore, from budget and economy hotels to luxury resorts in the integrated resorts. The Singapore Tourism Board says the hotel industry has more than 450 properties, more than 73,000 rooms and about 30,000 workers, and that hotels earn about 20% of tourism receipts.
Food and beverage sales to non-staying guests, casino revenue, private short-term rentals and purpose-built worker dormitories are excluded from the market value. The value chain runs from owners, real estate trusts and developers through brand franchisors and hotel management companies to online travel agencies, corporate travel buyers and event organizers that bring guests to the hotels.
Singapore Hospitality Market Insights
- The market reached USD 4.98 billion in 2025 and should reach USD 8.27 billion by 2035, growing at a 5.20% CAGR during 2026–2035 as events and long stays rise.
- The Central Area held 70.0% of 2025 value because Marina Bay Sands, Orchard Road hotels and downtown business hotels hold most rooms.
- Chain hotels led with 68.0% of 2025 value, and luxury hotels held 36.0% as the integrated resorts carry the highest room rates.
- Hotel occupancy averaged 81.9% in 2025 while the average room rate eased 1% to S$273.56, according to the Singapore Tourism Board.
- Marina Bay Sands broke ground on a US$8 billion expansion in July 2025 that adds a 570-suite hotel tower and a 15,000-seat arena by 2031.
Chain and luxury hotels earn most of the room revenue
Why do chain hotels earn most room revenue?
Based on type, the market is categorized into chain hotels and independent hotels. Chain Hotels led with 68.0% of 2025 value because global brands run the largest properties, such as the 1,080-room Hilton Singapore Orchard that opened in February 2022 as the largest Hilton in Asia Pacific. Conversions keep adding branded rooms, and InterContinental Singapore moved to the Luxury Collection in January 2026, EdgeProp reported. Independent Hotels grow fastest at 5.6% a year, as owner-operated concepts open new keys, including the 84-room Mett Hotel Singapore in October 2025 and the planned 165-room Casa Mett in 2027.
Why do luxury hotels hold the largest share?
Based on segment, the market is categorized into service apartments, budget and economy hotels, mid- and upper-mid-scale hotels and luxury hotels. Luxury Hotels led with 36.0% of 2025 value because the integrated resorts and the top hotels carry the highest rates, and Marina Bay Sands alone runs 1,850 rooms including 775 suites. Luxury RevPAR fell only 0.8% to October 2025 against 5.7% for economy hotels, EdgeProp reported. Service Apartments grow fastest at 5.9% a year, as the Urban Redevelopment Authority created a long-stay class with a three-month minimum on Dec. 4, 2023, and Ascott opened the 299-room Oakwood Premier Raffles Place on April 1, 2026.
Why do leisure travelers fill most rooms?
Based on traveler type, the market is categorized into leisure travelers and business and MICE travelers. Leisure Travelers led with 64.0% of 2025 value because concerts, sports weekends and attractions fill rooms through the year, and the Singapore Grand Prix drew 300,641 people in 2025, according to the Singapore Tourism Board. Business and MICE Travelers grow fastest at 5.7% a year, as MICE tourism receipts rose 35% to S$2.3 billion in 2025 and Singapore hosted 156 association meetings ranked by ICCA, up 8%, the Singapore Tourism Board said in May 2026.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Chain Hotels | 68.0% | Independent Hotels | 5.6% |
| By Segment | Luxury Hotels | 36.0% | Service Apartments | 5.9% |
| By Traveler Type | Leisure Travelers | 64.0% | Business and MICE Travelers | 5.7% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Record receipts, events and resort projects lift demand
Record tourism receipts and a dense events calendar
Visitor spending reached a record in 2025, and the events calendar keeps rooms full on the busiest weekends. Tourism receipts rose 10% to S$32.8 billion in 2025, from S$29.8 billion in 2024, and international arrivals rose 2.3% to 16.9 million, according to the Singapore Tourism Board. Receipts for January to September 2025 had already reached S$23.9 billion, up 6.5%, with concerts by Lady Gaga and BLACKPINK on the calendar. During the Grand Prix weekend, hotel occupancy peaked at 95.9% and the average daily rate at S$757.62 on Oct. 3, 2025, according to CoStar. As a result, hotels near the circuit and Marina Bay earn their highest rates of the year.
Business events and conventions fill weekday rooms
Business events give hotels steady weekday demand, and Singapore keeps winning large meetings from across Asia. MICE tourism receipts rose 35% to S$2.3 billion in 2025, and Singapore remained the top meeting city in Asia Pacific in the ICCA ranking for the 23rd year, according to the Singapore Tourism Board. The Herbalife APAC Extravaganza was expected to bring 25,000 attendees in June 2026, and the board targets S$4.5 billion in MICE receipts by 2040. Hilton Singapore Orchard also offers 16 meeting spaces totaling 2,400 square meters. In turn, business and MICE travelers grow at 5.7% a year, faster than leisure guests.
Integrated resort and attraction projects add new rooms
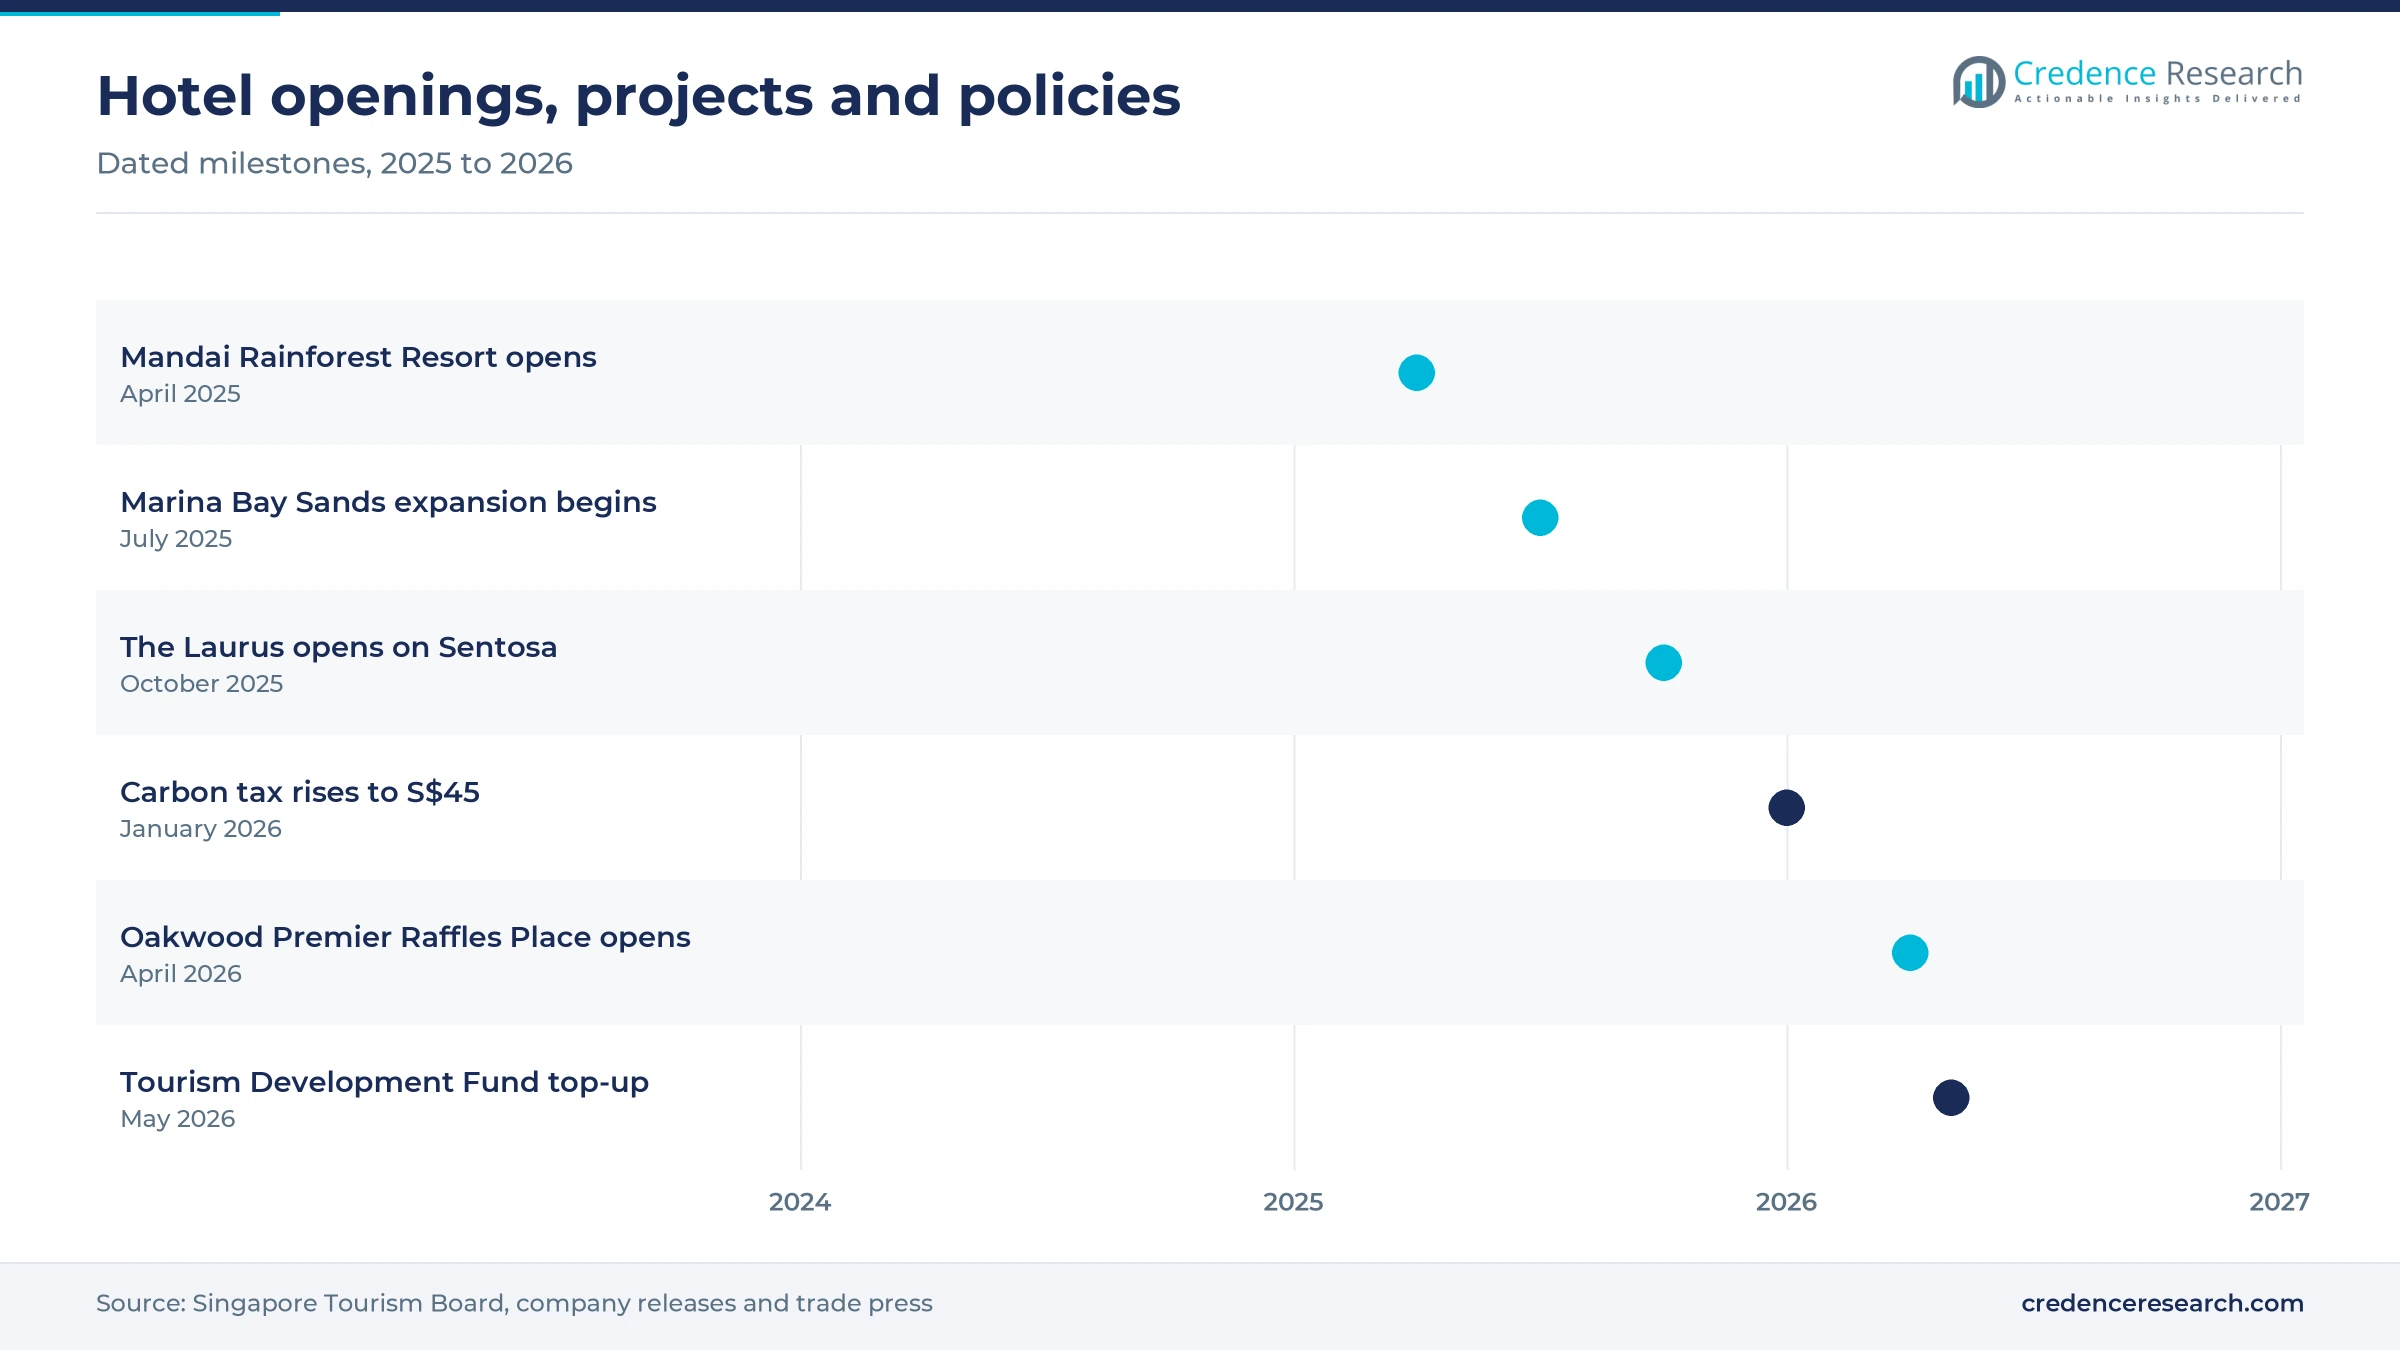
Large resort and attraction projects add both rooms and reasons to visit, which supports rates in the luxury class. Marina Bay Sands broke ground on July 15, 2025, on a US$8 billion expansion with a 570-suite tower and a 15,000-seat arena due in early 2031, Inside Asian Gaming reported. Resorts World Sentosa opened The Laurus with 183 suites in October 2025, and Raffles Sentosa opened 62 villas in March 2025, EdgeProp reported. The government also added S$740 million to the Tourism Development Fund in May 2026, to be spent over five years. Because of this, luxury hotels hold 36.0% of 2025 room revenue, the largest share by segment.
Air connectivity and a steady economy support travel
Strong air links and a steady economy keep both corporate and leisure travel flowing into Singapore hotels. Changi Airport handled nearly 70 million passenger movements in 2025, an all-time high, TTG Asia reported in May 2026. Real GDP grew 5.0% in 2025 and the IMF projects 3.5% growth for 2026, which supports regional headquarters travel and corporate stays. Visitor arrivals reached 4.4 million in the first quarter of 2026, according to JLL. The board projects 17 million to 18 million arrivals for 2026. As a result, demand stays spread across the business districts, Orchard Road and the airport hotels.
Green certification, brand conversions and long stays
Shift toward certified low-energy hotels
Sustainability certification has moved from a niche to the norm for Singapore hotels, and new projects aim even higher. About 61% of hotel room stock, or some 42,700 rooms across 100 hotels, held recognized sustainability certification by September 2025, ahead of a 60% target for end-2025, TTG Asia reported. Mandai Rainforest Resort by Banyan Tree opened on April 2, 2025, with Green Mark Platinum status as the first Super Low Energy resort in Singapore. Hotel Indigo Changi Airport is due in 2028 as the first zero-energy hotel, the Ministry of Trade and Industry said. As a result, buyers of corporate stays now ask for certified rooms in tenders.
Rise of brand conversions and soft brands
Owners increasingly convert older hotels to international brands instead of building new towers, because land and construction are expensive. Hotel Miramar was bought by Aravest and Wee Hur Holdings for S$160 million in November 2025 and will reopen as the 344-key DoubleTree by Hilton Robertson Quay in 2026, EdgeProp reported. Hotel Waterloo is joining the Handwritten Collection with 502 keys, and the 132-room Varel Singapore was due to open in the Tribute Portfolio in early 2026. Three hotel deals worth S$188 million closed in the first quarter of 2026, according to JLL. In turn, chain hotels keep 68.0% of room revenue as branded rooms replace independent ones.
Opportunity in long-stay serviced apartments
Long-stay apartments offer a clear opening, because project staff, relocating families and regional managers need homes for several months. The Urban Redevelopment Authority introduced the long-stay serviced apartment class on Dec. 4, 2023, with a three-month minimum stay and an average unit size of at least 35 square meters. Ascott opened the 299-room Oakwood Premier Raffles Place on April 1, 2026, and broke ground on Ascott Shenton Way for a fourth-quarter 2029 opening. Coliwoo is also planning a 350-key resort chalet project at Pasir Ris, EdgeProp reported. As a result, service apartments grow at 5.9% a year, faster than other classes.
Opportunity in co-funded hotel refurbishment
Refurbishment is a large opening for contractors, designers and technology vendors, because many hotels need upgrades to stay competitive. The Hotel Rejuvenation Fund, launched in 2025, had supported 13 hotels by May 2026 and was extended by one year, TTG Asia reported. The Singapore Tourism Board co-funds up to 50% of product and productivity costs for small firms, and up to 70% of sustainability costs, for projects of at least S$3 million approved by March 31, 2027. Older properties can also add energy and water upgrades that cut running costs. In turn, upgraded mid-scale and upper-mid-scale hotels can lift rates against new rivals, and refurbished rooms often need contract cleaning support during works.
Flat room rates, staffing and energy costs squeeze margins
Flat room rates in a mature market
Room rates have stopped rising, so revenue growth depends on filling more rooms. The average room rate fell 1% to S$273.56 in 2025, and RevPAR slipped 0.4% to S$224.04 even as occupancy averaged 81.9%, according to the Singapore Tourism Board. Economy hotels were hit hardest, with RevPAR down 5.7% to October 2025, EdgeProp reported. As a result, budget and economy hotels grow at the slowest pace, and owners rely on events and corporate contracts to hold rates.
Tight labor supply for housekeeping and service roles
Staffing remains a constraint, because hotels need many service workers for every room. The industry employs about 30,000 people for more than 73,000 rooms, according to the Singapore Tourism Board. The Ministry of Manpower allowed hotels to hire housekeepers and porters from six more countries from Sept. 1, 2023, but capped them at 8% of staff with a S$2,000 monthly wage, AGBrief reported. Hotels therefore invest in automation and shared services to run with fewer staff.
Rising carbon and energy costs
Energy costs weigh on margins, because hotels run air conditioning, laundries and kitchens around the clock. The carbon tax rose from S$25 to S$45 per metric ton of emissions in 2026 and is planned to reach S$50 to S$80 by 2030, The Straits Times reported in January 2026. The IMF also warned in July 2026 that the war in the Middle East is passing an energy shock to Singapore. Owners respond with chiller upgrades, solar panels and energy dashboards.
Uneven source markets and muted demand signals
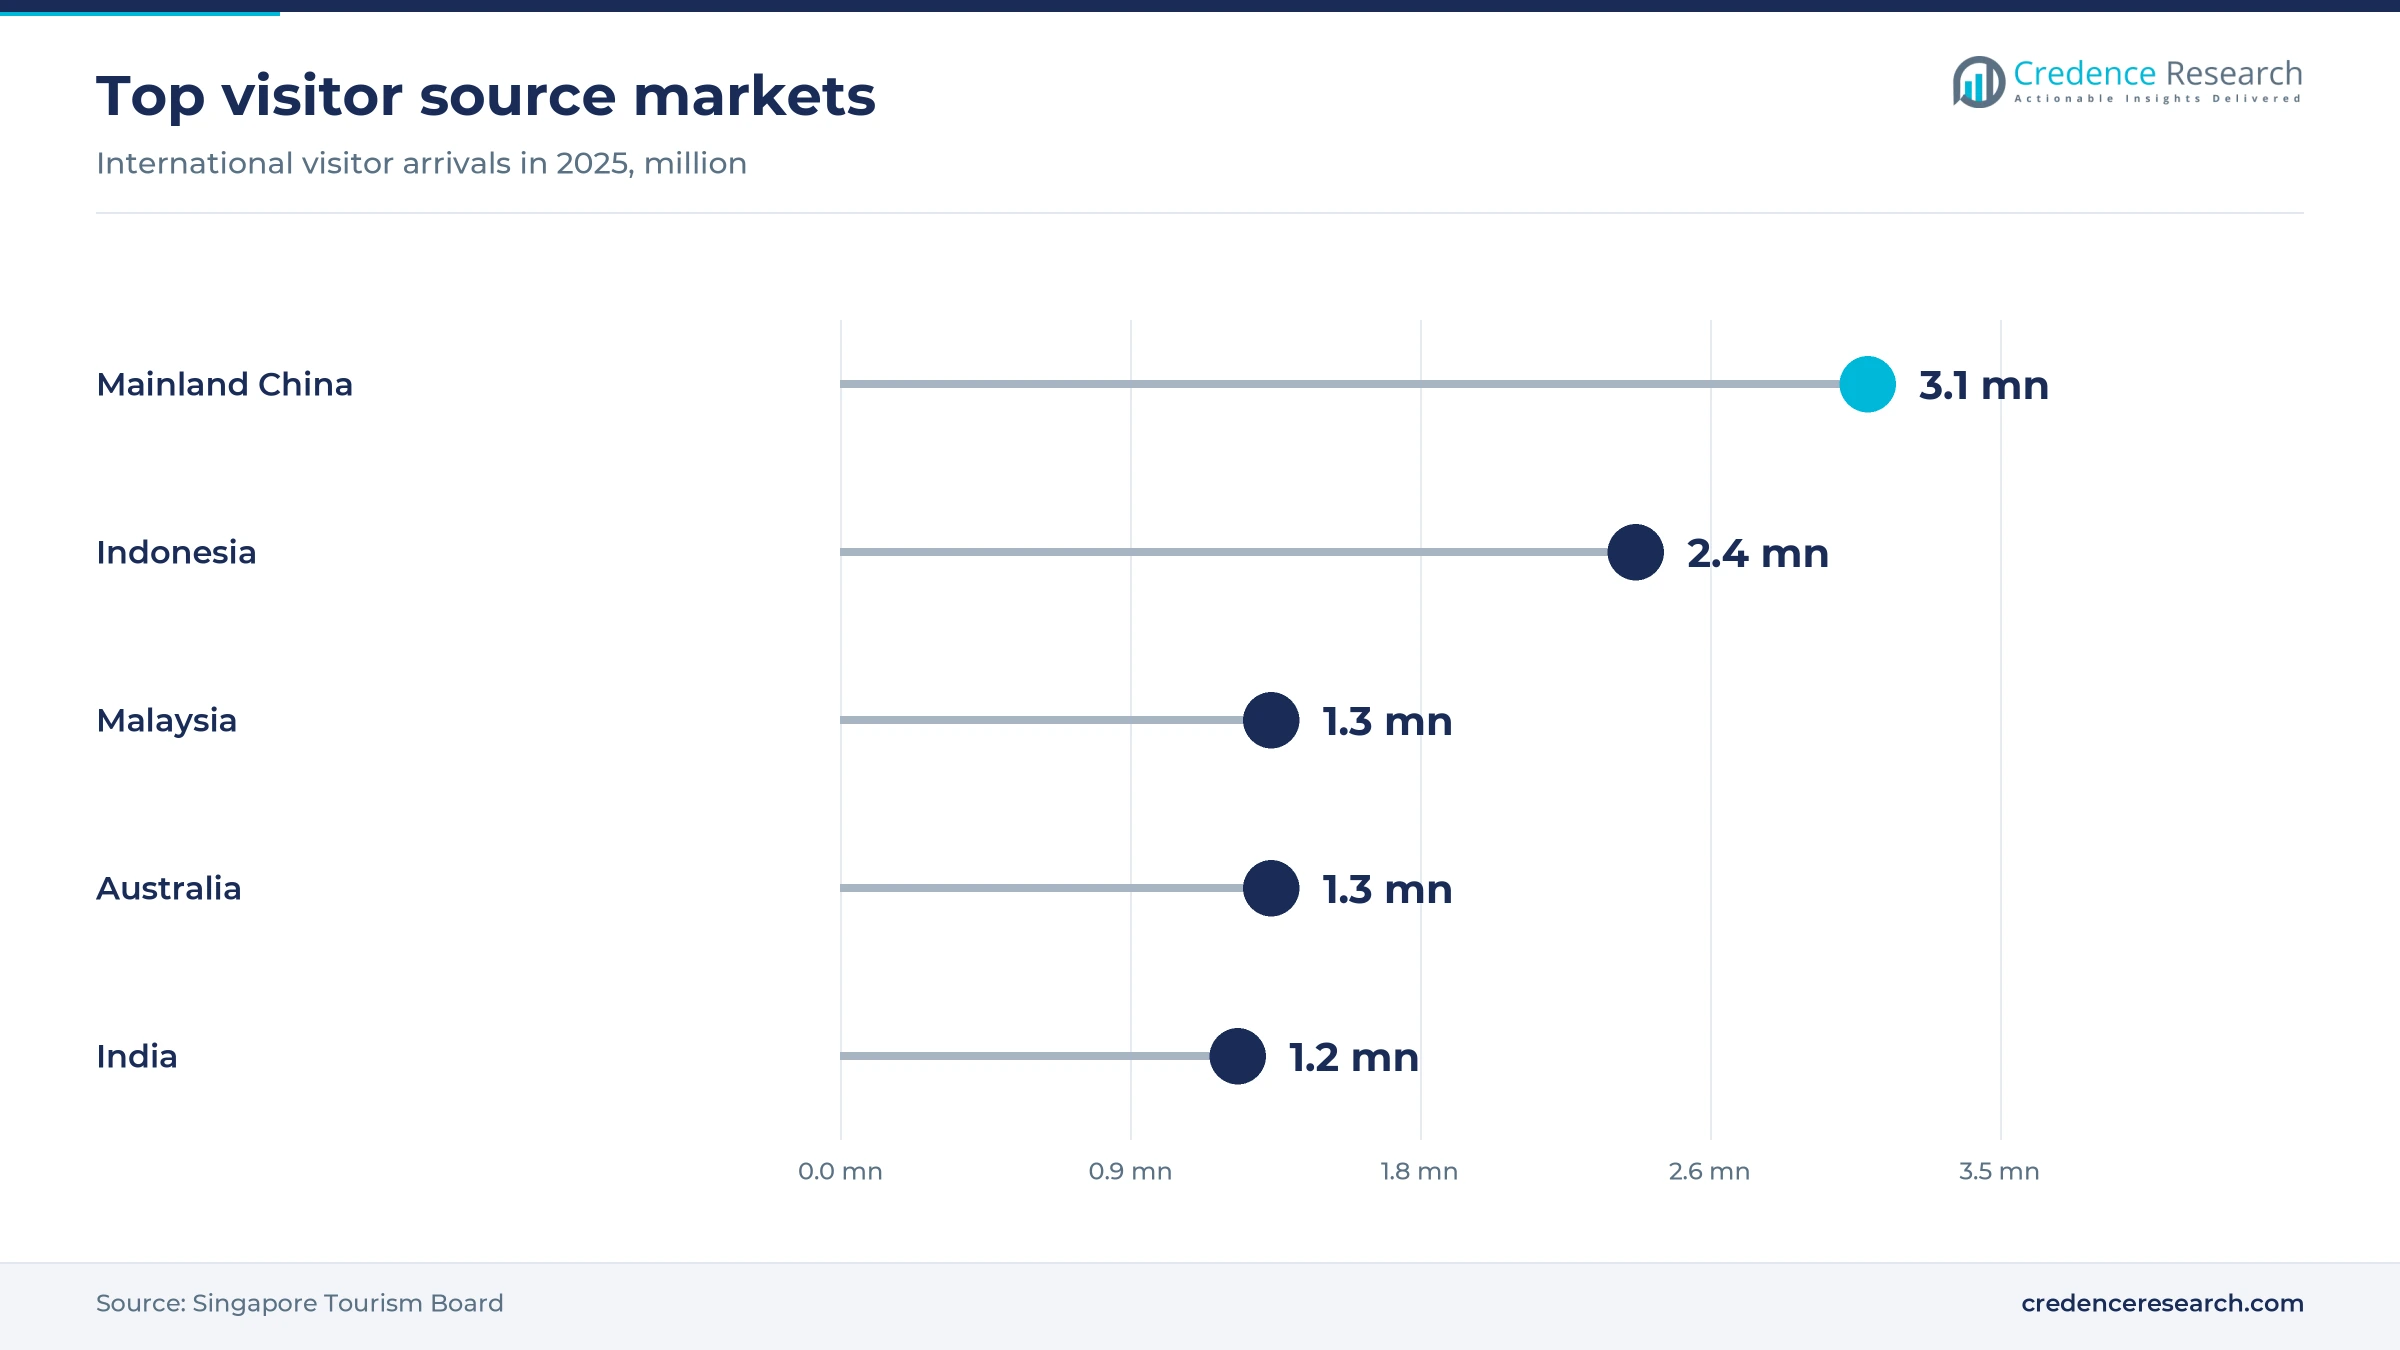
Demand depends on a few large source markets, so weakness in one quickly shows up in occupancy. Mainland China sent 3.1 million visitors in 2025, while arrivals from Vietnam fell to 344,000 from 393,000 and the Philippines to 726,000 from 779,000, the Singapore Tourism Board said. The board also expected muted demand in the months after May 2026, TTG Asia reported. Hotels respond with campaigns in Japan, India and Australia, where arrivals grew in 2025.
Central Area leads while Sentosa adds rooms fastest
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Central Area | 3.49 | 70.0% | 4.9% |
| Sentosa and Southern Islands | 0.55 | 11.0% | 6.2% |
| North and West Regions | 0.50 | 10.0% | 5.6% |
| East Region | 0.45 | 9.0% | 6.0% |
Central Area holds most rooms and convention space
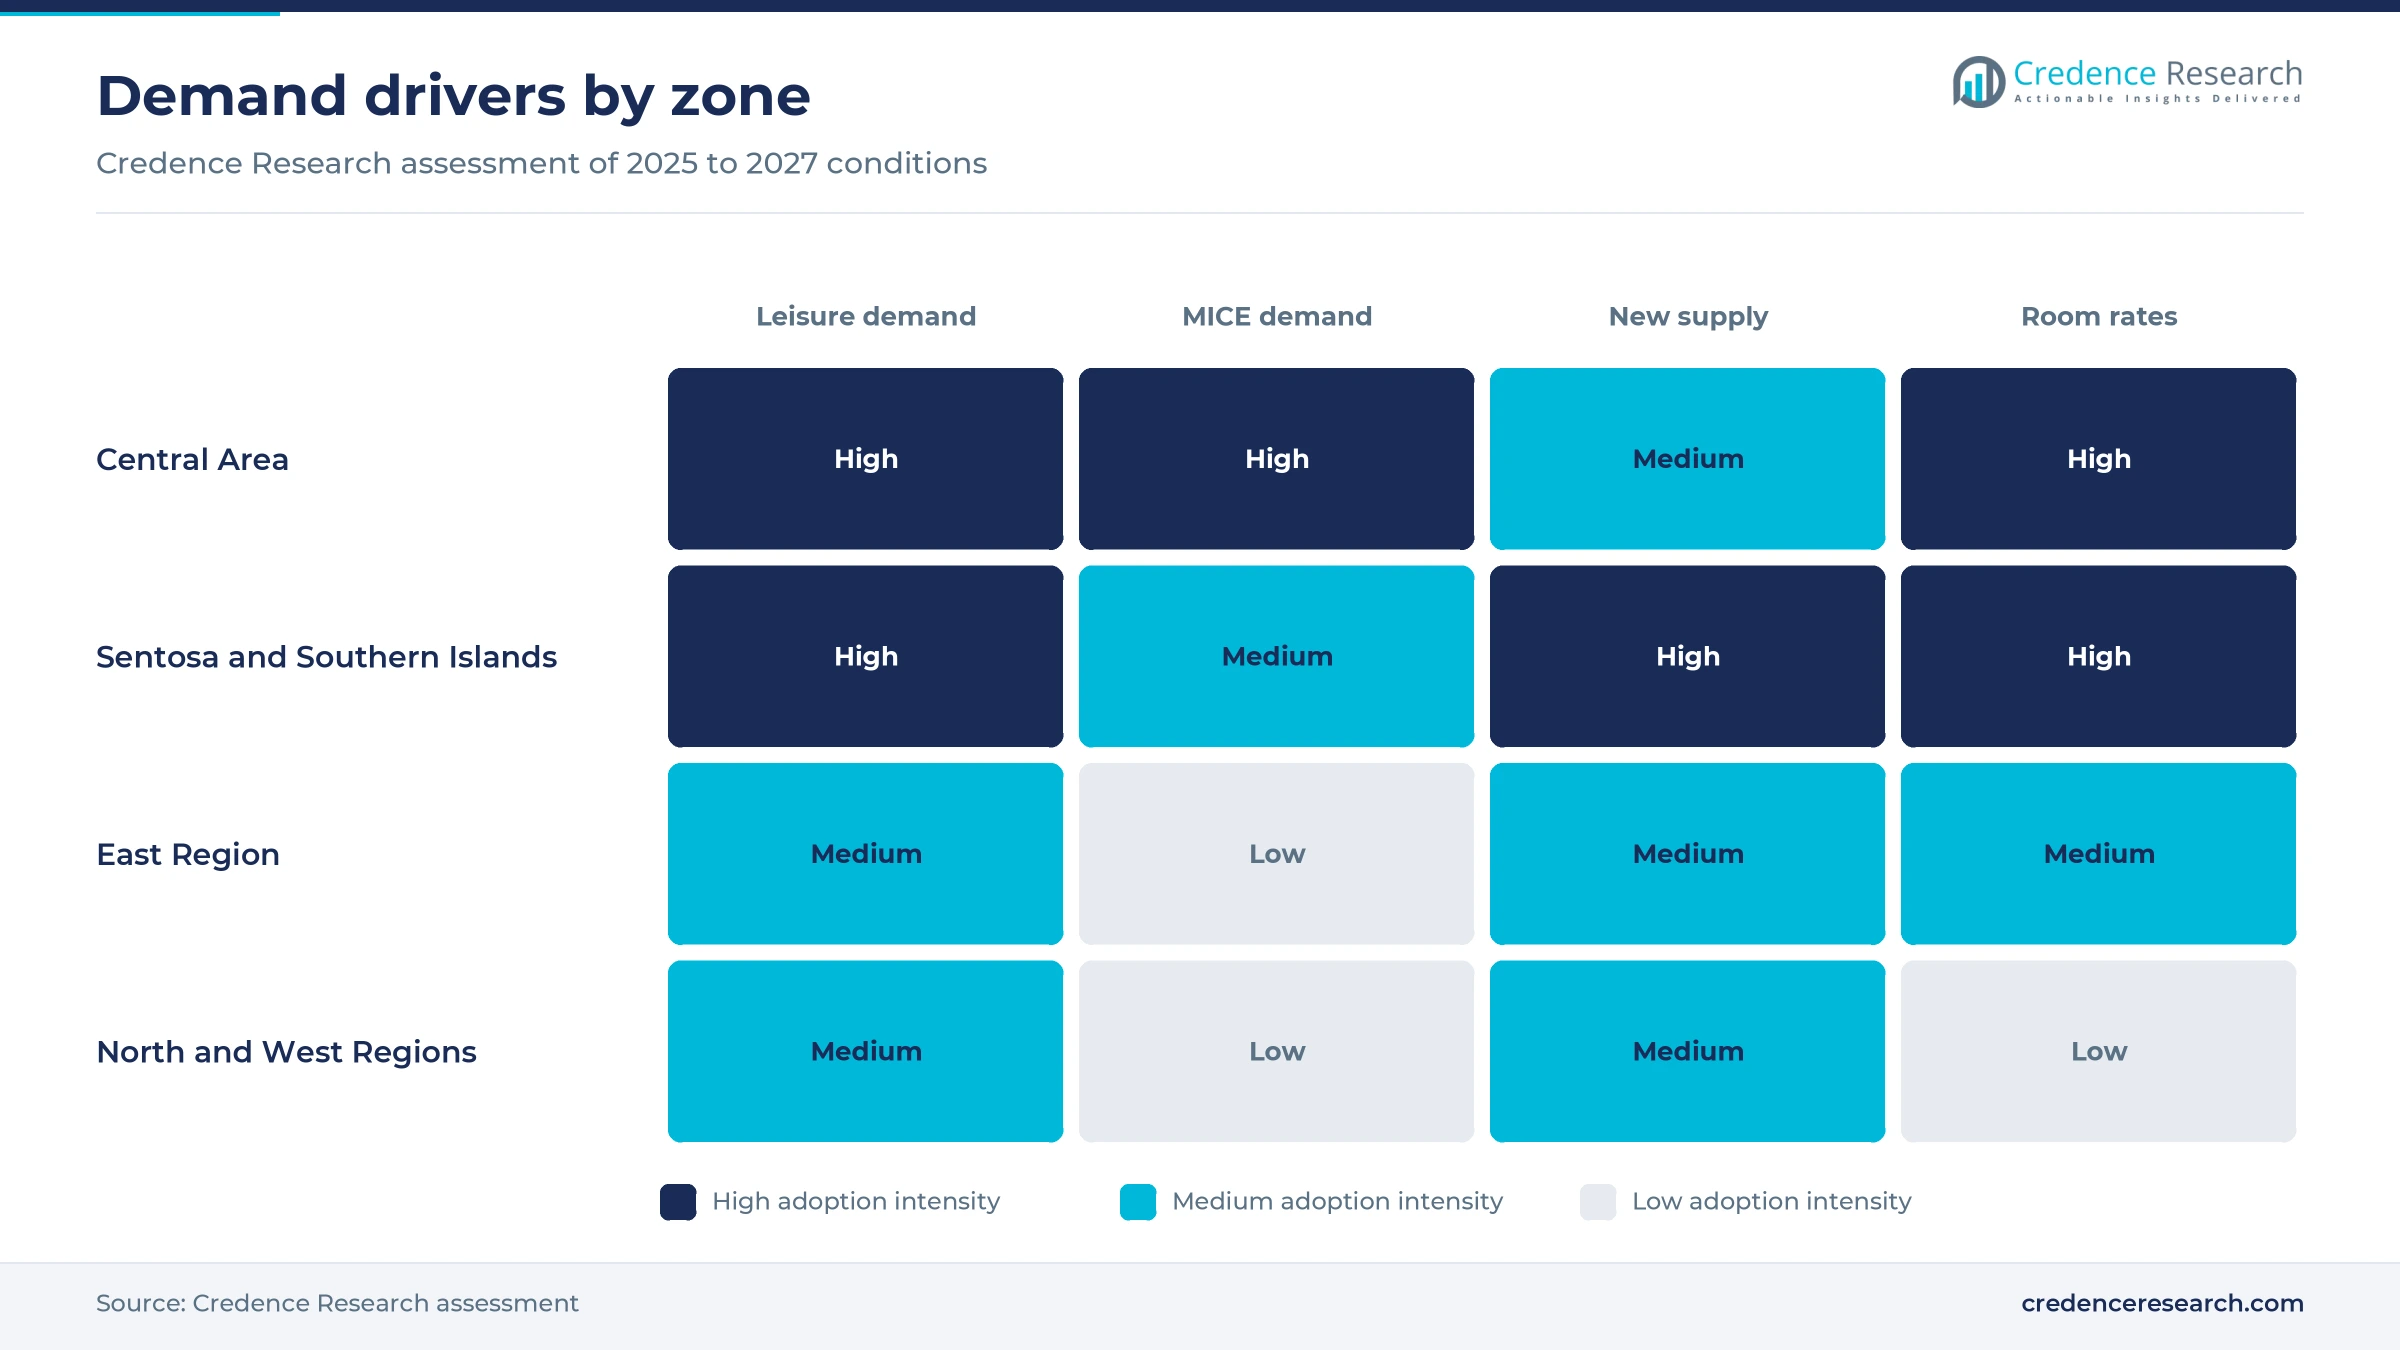
The Central Area held 70.0% of 2025 value and grows at 4.9% a year, the slowest of the four zones. It includes Marina Bay Sands, the 1,080-room Hilton Singapore Orchard and most business hotels in the downtown core. New central supply in 2026 includes the 808-key Movenpick Singapore on Hoe Chiang Road, according to JLL. Grand Prix weekends lift rates here most, and the board charges a 30% F1 cess on trackside hotels for 2026.
Sentosa and Southern Islands add resort suites fastest
Sentosa and Southern Islands held 11.0% of 2025 value and grow fastest at 6.2% a year. Resorts World Sentosa opened The Laurus with 183 suites in October 2025, and Raffles Sentosa opened 62 villas in March 2025. Island resorts serve families, incentive groups and visitors to the attractions, and they also benefit from casino tourism at Resorts World Sentosa. The Mandai and Sentosa openings of 2025 together added more than 580 new keys outside the Central Area, which shows how leisure supply is moving toward resort settings.
East Region grows with Changi airport traffic
The East Region held 9.0% of 2025 value and grows at 6.0% a year. Changi Airport handled nearly 70 million passenger movements in 2025, which supports transit and airline crew stays near the terminals. Hotel Indigo Changi Airport is due in 2028 as the first zero-energy hotel in Singapore, and Coliwoo plans a 350-key chalet project at Pasir Ris. Many east-side properties also suit extended-stay hotel guests on project work.
North and West Regions gain nature resort demand
The North and West Regions held 10.0% of 2025 value and grow at 5.6% a year. Mandai Rainforest Resort by Banyan Tree opened on April 2, 2025, with 338 keys, including 24 tree houses, next to the zoo, Night Safari and Bird Paradise. It also has a 300-seat ballroom for weddings and company events. The zone is otherwise served by smaller business hotels near industrial estates and the Woodlands checkpoint.
Resort openings, funds and new hotels since 2025
| Development | Status and market relevance |
|---|---|
| In April 2025, Banyan Group opened Mandai Rainforest Resort by Banyan Tree with 338 keys in the Mandai Wildlife Reserve. | Open; first Super Low Energy resort in Singapore |
| In July 2025, Marina Bay Sands broke ground on a US$8 billion expansion with a 570-suite hotel tower and a 15,000-seat arena. | Under construction; opening planned for early 2031 |
| In October 2025, Resorts World Sentosa opened The Laurus with 183 suites. | Open; adds luxury capacity on Sentosa |
| In November 2025, Aravest and Wee Hur Holdings bought Hotel Miramar for S$160 million to reopen it as DoubleTree by Hilton. | Conversion; 344 keys due in 2026 |
| In May 2026, the government added S$740 million to the Tourism Development Fund over five years. | Approved; supports Tourism 2040 plans |
Smart rooms, digital check-in and low-energy design
- Smart rooms and robotics are two of the five technologies in the refreshed Hotel Industry Digital Plan, alongside digital concierge and asset management tools.
- Digital check-in and check-out cut front desk queues, and about 50 hotels used E-Visitor Authentication to verify guests by 2022.
- In-room energy displays show guests their power use at Mandai Rainforest Resort, which also uses rainwater for toilet flushing.
- Zero-energy design will be tested at Hotel Indigo Changi Airport, planned for 2028 as the first hotel of its kind in Singapore.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Global chains and resort operators compete for guests
Competition centers on global chains, two integrated resorts and a few regional groups that compete for corporate accounts, events and leisure guests. Marina Bay Sands and Resorts World Sentosa compete on scale, attractions and suites, and both are adding capacity. Marriott International, Hilton Worldwide, Accor and IHG compete through loyalty programs and conversions, as shown by the Luxury Collection, Tribute Portfolio, DoubleTree and Handwritten Collection deals of 2025 and 2026. Pan Pacific Hotels Group and Far East Hospitality compete as home-grown groups, with properties such as the 347-room Pan Pacific Orchard and the Oasia and Village hotel brands. The Ascott Limited leads serviced apartments for corporate stays and long project assignments. Many hotels also compete through restaurants and banquets, which link them to the wider food service trade, while independent boutique hotel operators compete on design and neighborhood character.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Marina Bay Sands | Integrated resort | Runs 1,850 rooms including 775 suites; building a 570-suite tower due in early 2031 |
| Resorts World Sentosa | Integrated resort | Opened The Laurus with 183 suites in October 2025 |
| Marriott International | Global hotel chain | Signed the former InterContinental Singapore as Frasers House, a Luxury Collection Hotel, from Jan. 1, 2026 |
| Hilton Worldwide | Global hotel chain | Runs the 1,080-room Hilton Singapore Orchard; DoubleTree Robertson Quay due in 2026 |
| Accor SA | Global hotel chain | Opened Raffles Sentosa and Mama Shelter in 2025; Movenpick and Handwritten Collection hotels in the pipeline |
| InterContinental Hotels Group plc | Global hotel chain | Hotel Indigo Changi Airport due in 2028 as the first zero-energy hotel |
| Hyatt Hotels Corporation | Global hotel chain | Grand Hyatt Singapore removed more than 10,000 single-use plastic items a year, the Ministry of Trade and Industry said in September 2025 |
| Pan Pacific Hotels Group | Regional hotel group | Runs the 347-room Pan Pacific Orchard; partner in the Manpower Transformation Lighthouse project |
| Far East Hospitality | Local hotel group | Home-grown operator of Oasia, Village and Far East Collection hotels in Singapore |
| The Ascott Limited | Serviced apartment operator | Opened the 299-room Oakwood Premier Raffles Place on April 1, 2026 |
| Banyan Group | Resort operator | Opened the 338-key Mandai Rainforest Resort, its 100th resort, on April 2, 2025 |
Events and business travel will set the pace of growth
Credence Research's view is that Singapore hospitality will grow mainly through occupancy, events and new resort supply rather than through higher room rates. Business events, the Marina Bay Sands expansion and Sentosa resort suites are the clearest sources of new demand, while long-stay apartments open a steady corporate niche. Conversions to global soft brands will keep shifting rooms from independent to chain operation. The main risks are flat rates, staff shortages, higher energy costs and weak demand from a few short-haul source markets.
How Credence Research sized the market
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. Market values come from the Credence Research model, built from Singapore Tourism Board data on hotel room stock, occupancy, average room rates and tourism receipts, with an allowance for serviced apartments; the 2025 base replaces the earlier edition's estimate, which used a narrower scope. Zone, type, segment and traveler splits are Credence Research estimates based on hotel locations, announced openings and visitor data. Sources include government releases, company announcements, IMF reports and trade press.
MICE growth and long-stay apartments lead to 2035
Singapore hospitality should grow steadily to 2035, as the market adds rooms at a measured pace and fills them with events, business travelers and resort guests. The Marina Bay Sands tower in 2031, Hotel Indigo Changi Airport in 2028 and new Sentosa suites will add premium capacity. Service apartments should gain share as long-stay rules and corporate relocations support demand. Room rates are likely to follow inflation, so operators that manage labor and energy costs will gain the most.
Frequently Asked Questions
How big is the Singapore hospitality market?
How large is the hospitality industry in Singapore?
How did hotels in Singapore perform in 2025?
Do hotels in Singapore meet international hospitality standards?
Which hospitality companies operate in Singapore?
Are there hotels in Singapore for both business meetings and family stays?
Which region leads the Singapore hospitality market?
What are the main challenges for Singapore hotels?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Chain Hotels
- 1.2.2 Independent Hotels
- 1.3 By Segment
- 1.3.1 Luxury Hotels
- 1.3.2 Mid- and Upper-Mid-Scale Hotels
- 1.3.3 Budget and Economy Hotels
- 1.3.4 Service Apartments
- 1.4 By Traveler Type
- 1.4.1 Leisure Travelers
- 1.4.2 Business and MICE Travelers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 4.98 billion → 2035: USD 8.27 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Singapore Hospitality Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Singapore Hospitality Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Singapore Hospitality Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Singapore Hospitality Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Singapore Hospitality Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Singapore Hospitality Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Singapore Hospitality Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Singapore Hospitality Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 4.98 billion → 2035: USD 8.27 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Singapore Hospitality Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Chain Hotels
- 12.3.7.2 Independent Hotels
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Segment - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Luxury Hotels
- 12.4.7.2 Mid- and Upper-Mid-Scale Hotels
- 12.4.7.3 Budget and Economy Hotels
- 12.4.7.4 Service Apartments
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Traveler Type - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Leisure Travelers
- 12.5.7.2 Business and MICE Travelers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Singapore Hospitality Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Singapore Hospitality Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Singapore Hospitality Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Marina Bay Sands
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Resorts World Sentosa
- 17.4 Marriott International
- 17.5 Hilton Worldwide
- 17.6 Accor SA
- 17.7 InterContinental Hotels Group plc
- 17.8 Hyatt Hotels Corporation
- 17.9 Pan Pacific Hotels Group
- 17.10 Far East Hospitality
- 17.11 The Ascott Limited
- 17.12 Banyan Group
- 17.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

