
Body size data and shrinking store fleets reshape demand
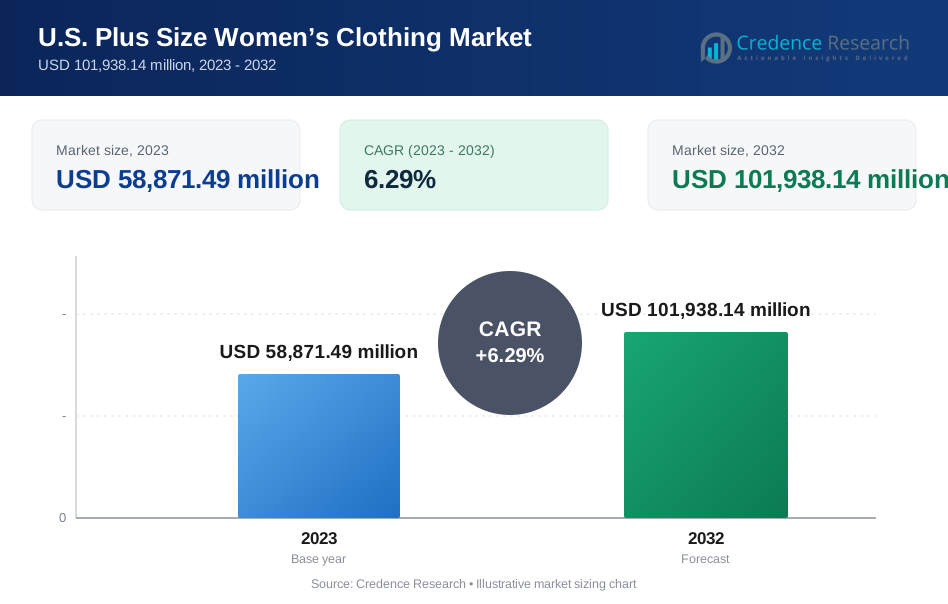
The U.S. plus size women’s clothing market was valued at USD 45.50 billion in 2025 and is projected to increase from USD 47.73 billion in 2026 to USD 73.41 billion by 2035, registering a CAGR of 4.90% during 2026–2035. Demand rests on measured body sizes, since 41.3% of adult women had obesity in the August 2021 to August 2023 national health survey, and on retailers that now stock sizes 10 to 40. South held the largest regional share, 39.0% in 2025, because it has the largest population and its 25 to 44 age group grew 9.0% from 2020 to 2025. South is also the fastest-growing region at 5.25% a year. Store networks are shrinking, however, as Torrid ended fiscal 2025 with 483 stores, down from 634 a year earlier. Online selling is absorbing that demand, and Lane Bryant opened its website to dropship brand partners in January 2026. Weight-loss drugs add a new variable, because 21% of U.S. households included a GLP-1 user by May 2026.
What does the U.S. plus size women’s clothing market count, and how do women buy it?
The value counts new casual wear, formal wear and sports wear sold in women’s sizes 14 and above, including extended ranges that now reach size 40 at some brands. Shoppers buy through specialist chains such as Lane Bryant and Torrid, department stores, mass merchants, brand websites and marketplaces, and most purchases are basics bought at full or promoted prices.
Footwear, bras and other intimates, accessories, secondhand garments and rentals are excluded from the value, although they compete for the same budget. The value chain runs from brand owners and private-label teams through contract factories in Asia and Central America to importers and retailers, which set most shelf prices and decide how many size points each style carries.
U.S. Plus Size Women’s Clothing Market Insights
- The market moves from USD 45.50 billion in 2025 to USD 73.41 billion by 2035 at a 4.90% CAGR, a premium over total women’s apparel spending growth.
- The South led with 39.0% of 2025 value, as its 25 to 44 population grew 9.0% from 2020 to 2025, according to the Census Bureau.
- Casual Wear led product types with 58.0% of 2025 value, because jeans, tops and knit basics make up most purchases.
- Torrid closed 151 stores in fiscal 2025, while Lane Bryant opened its website to dropship partners in January 2026.
- Section 301 duties of 10% to 12.5% on major Asian apparel suppliers took effect on July 24, 2026, raising landed costs.
Casual basics lead while sportswear and online gain
Which product types lead plus size women’s clothing sales?
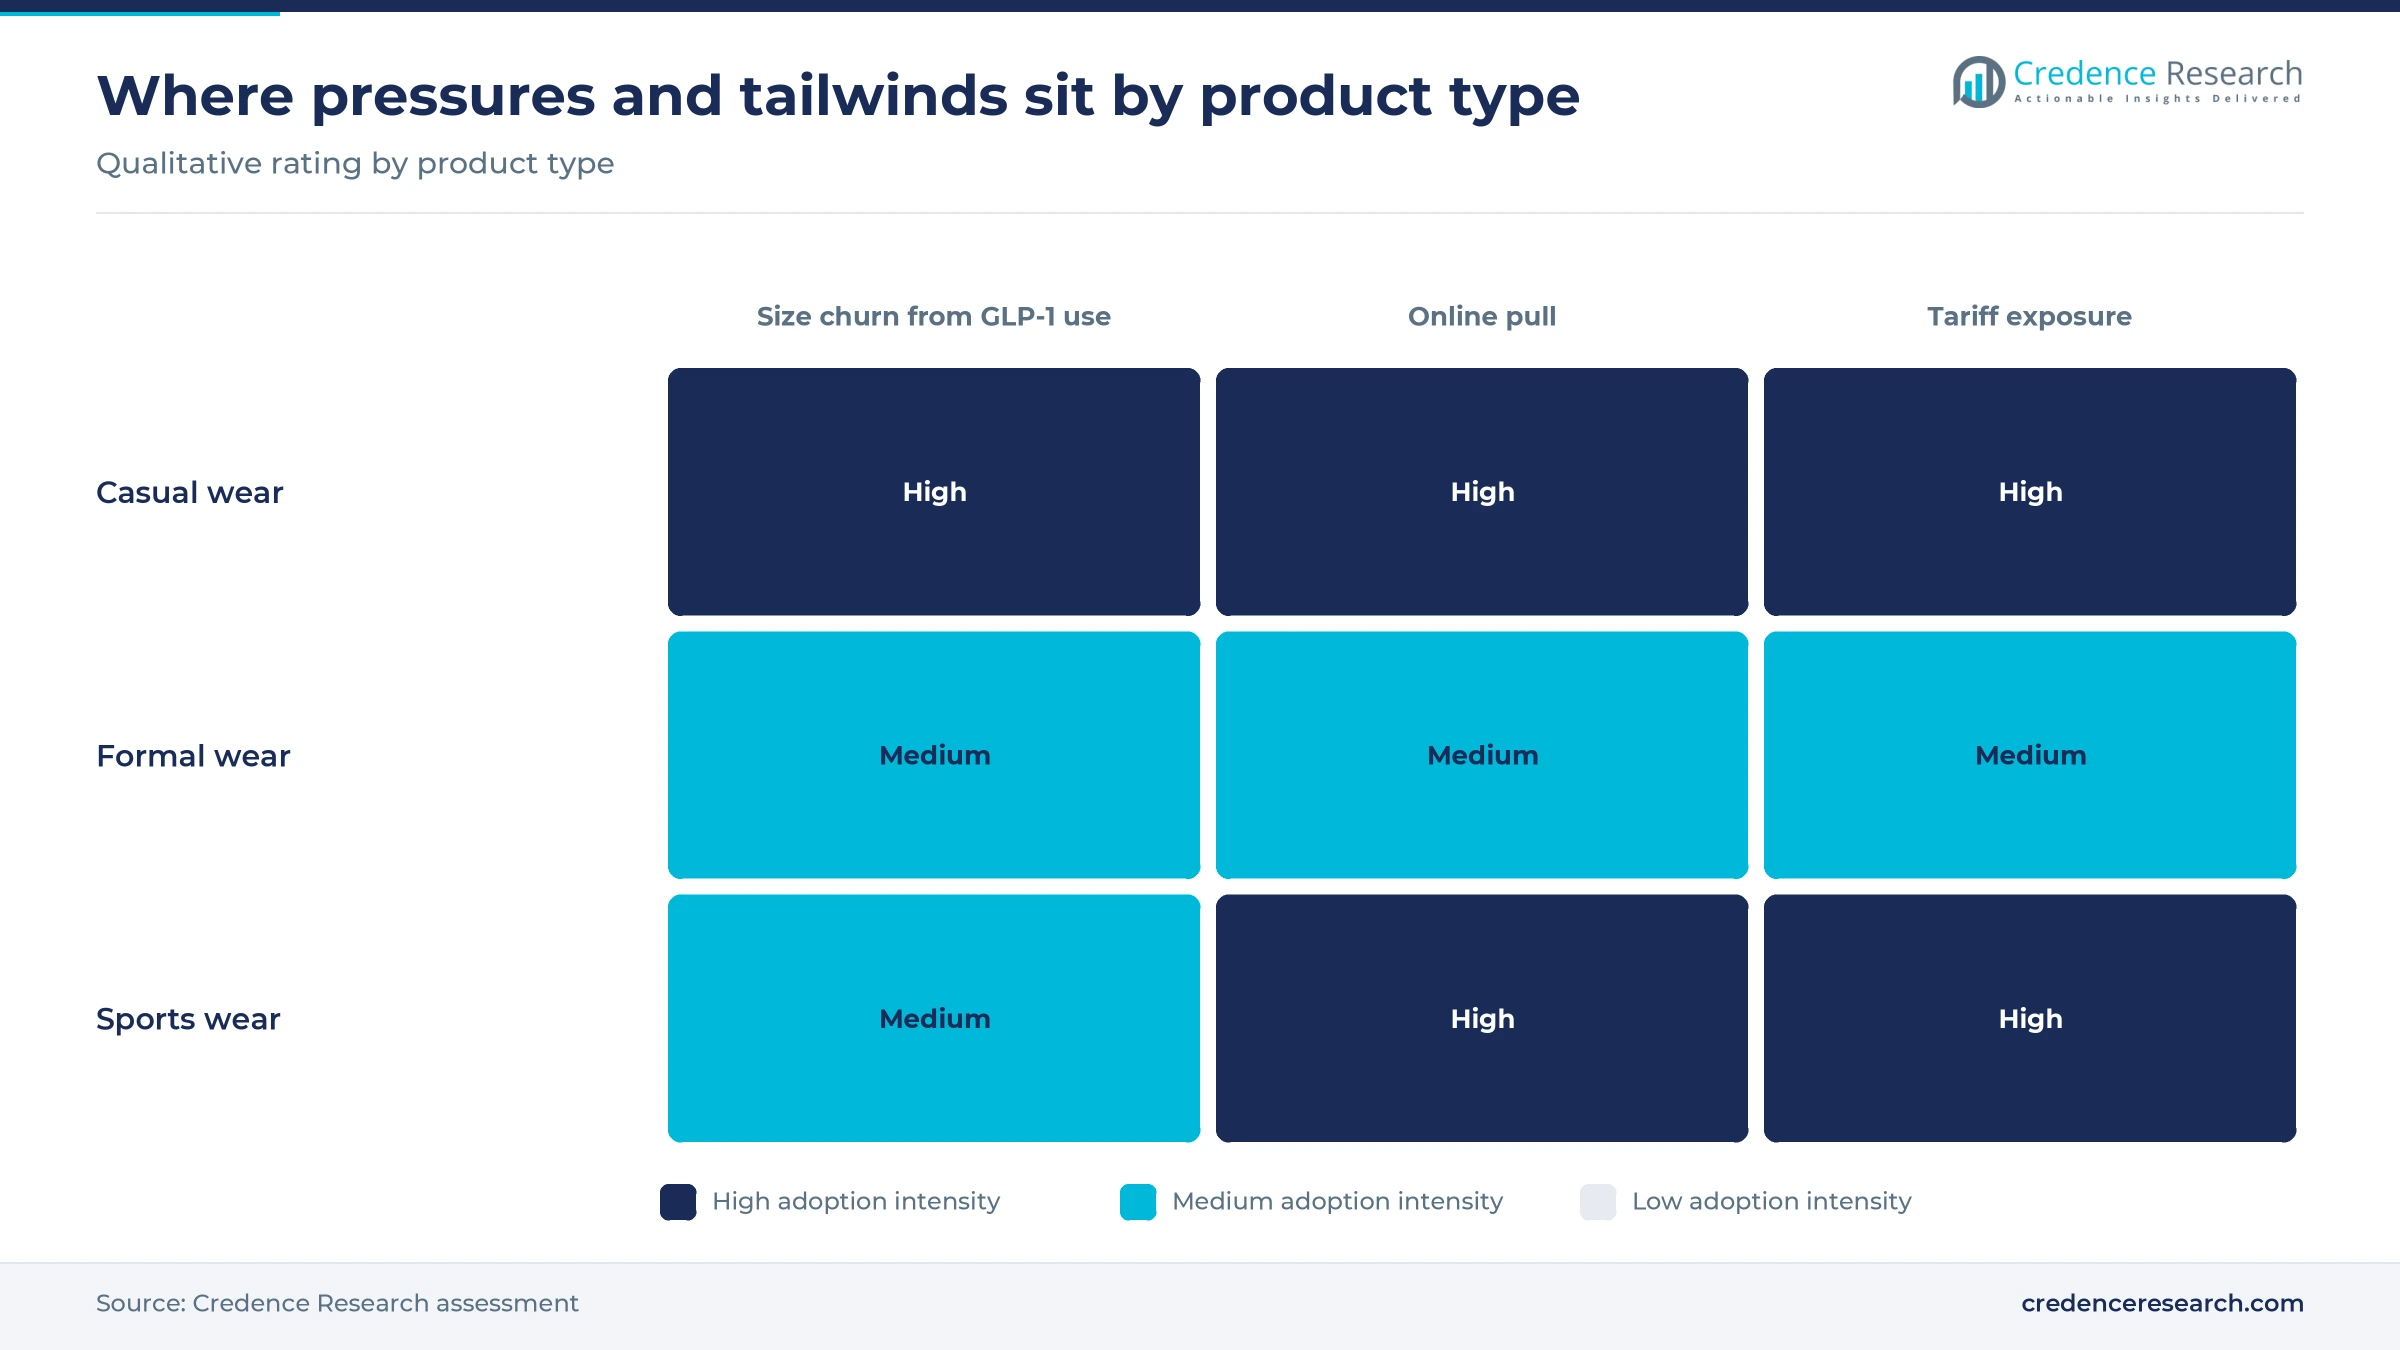
Based on product type, the market is categorized into casual wear, formal wear and sports wear. Casual Wear led with 58.0% of 2025 value because jeans, tops and knit basics form most of the volume, and Walmart lists Terra & Sky plus sweaters in sizes 0X to 5X for USD 8.29. Denim demand also jumped, since PwC and Numerator data reported by Glossy showed GLP-1 users raising women’s jeans spending 66.1%. Sports Wear grows fastest at 5.79% a year, as Torrid said in March 2026 that activewear gained momentum in its fourth quarter. Nike also sells extended activewear in sizes 0X to 4X.
Which age groups buy the most extended-size apparel?
Based on age group, the market is categorized into below 15 years, 15-24 years, 25-45 years, 46-60 years and above 60 years. 25-45 Years led with 38.0% of 2025 value because this band holds most working mothers and professionals, and the Census Bureau reported that the 25 to 44 population grew in every region from 2020 to 2025, by 9.0% in the South. Above 60 Years grows fastest at 5.79% a year, as residents aged 65 and over rose 16.2% to 64.6 million over those years. The CDC also found obesity peaks at 46.4% among adults aged 40 to 59, which keeps the 46-60 band large.
Are online retailers overtaking specialty stores for larger sizes?
Based on distribution channel, the market is categorized into online retailers, super markets & hyper markets and speciality stores. Speciality Stores led with 38.0% of 2025 value because dedicated chains still offer fitting rooms, and Lane Bryant operated 400 stores in January 2026 while Torrid ran 457 stores on Aug. 1, 2026. However, Torrid closed 151 stores in fiscal 2025, so that store base is shrinking. Online Retailers grow fastest at 5.98% a year, as U.S. e-commerce reached 17.1% of retail sales in the second quarter of 2026, according to the Census Bureau.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Casual Wear | 58.0% | Sports Wear | 5.79% |
| By Age Group | 25-45 Years | 38.0% | Above 60 Years | 5.79% |
| By Distribution Channel | Speciality Stores | 38.0% | Online Retailers | 5.98% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Body measurements, aging and online ranges lift demand
Measured body sizes keep larger fits in steady demand
National body measurements show that demand for larger sizes is structural rather than a passing fashion cycle. The CDC’s National Center for Health Statistics reported in September 2024 that 41.3% of adult women had obesity in its August 2021 to August 2023 survey. Severe obesity reached 12.1% among women, nearly double the 6.7% rate among men. The same survey put the average adult woman at 63.5 inches tall, 171.8 pounds and a 38.5-inch waist, according to CDC FastStats. In addition, Eloquii’s chief executive told Digital Commerce 360 in 2018 that about 67% of American women wear size 14 or above. As a result, Credence Research expects Casual Wear to keep 58.0% of value as basics are bought in volume.
Older and midlife shoppers widen the buyer base
Age shifts are widening the buyer base, because the groups with the highest obesity rates are also the groups that are growing. The Census Bureau reported on June 25, 2026, that residents aged 65 and over rose 16.2% from 2020 to 2025, reaching 64.6 million, while the under-18 population fell 2.4%. Women made up 50.9% of the population and outnumbered men by 6.3 million in 2025. In addition, the CDC found obesity prevalence of 46.4% among adults aged 40 to 59, the highest of any age group it measured. Consequently, Credence Research expects the above 60 years band to gain share, while comfort fits and easy-care fabrics gain range depth across older buyers.
Online checkout extends ranges beyond store shelves
Online selling lets brands carry far more size points than a mall store can hold, which suits a customer base spread across many sizes. U.S. e-commerce reached USD 340.2 billion in the second quarter of 2026, or 17.1% of total retail sales, up 12.2% from a year earlier, according to the Census Bureau. In January 2026, Lane Bryant joined Rithum’s network so U.S. brand partners can sell directly on its website, which already offers apparel in sizes 10 to 40 and bras in 97 sizes. Universal Standard said nearly 60% of first-week direct sales of its September 2026 capsule came within 48 hours, according to Glossy. As a result, Online Retailers grow fastest at 5.98% a year.
Department stores and mass merchants add extended sizes
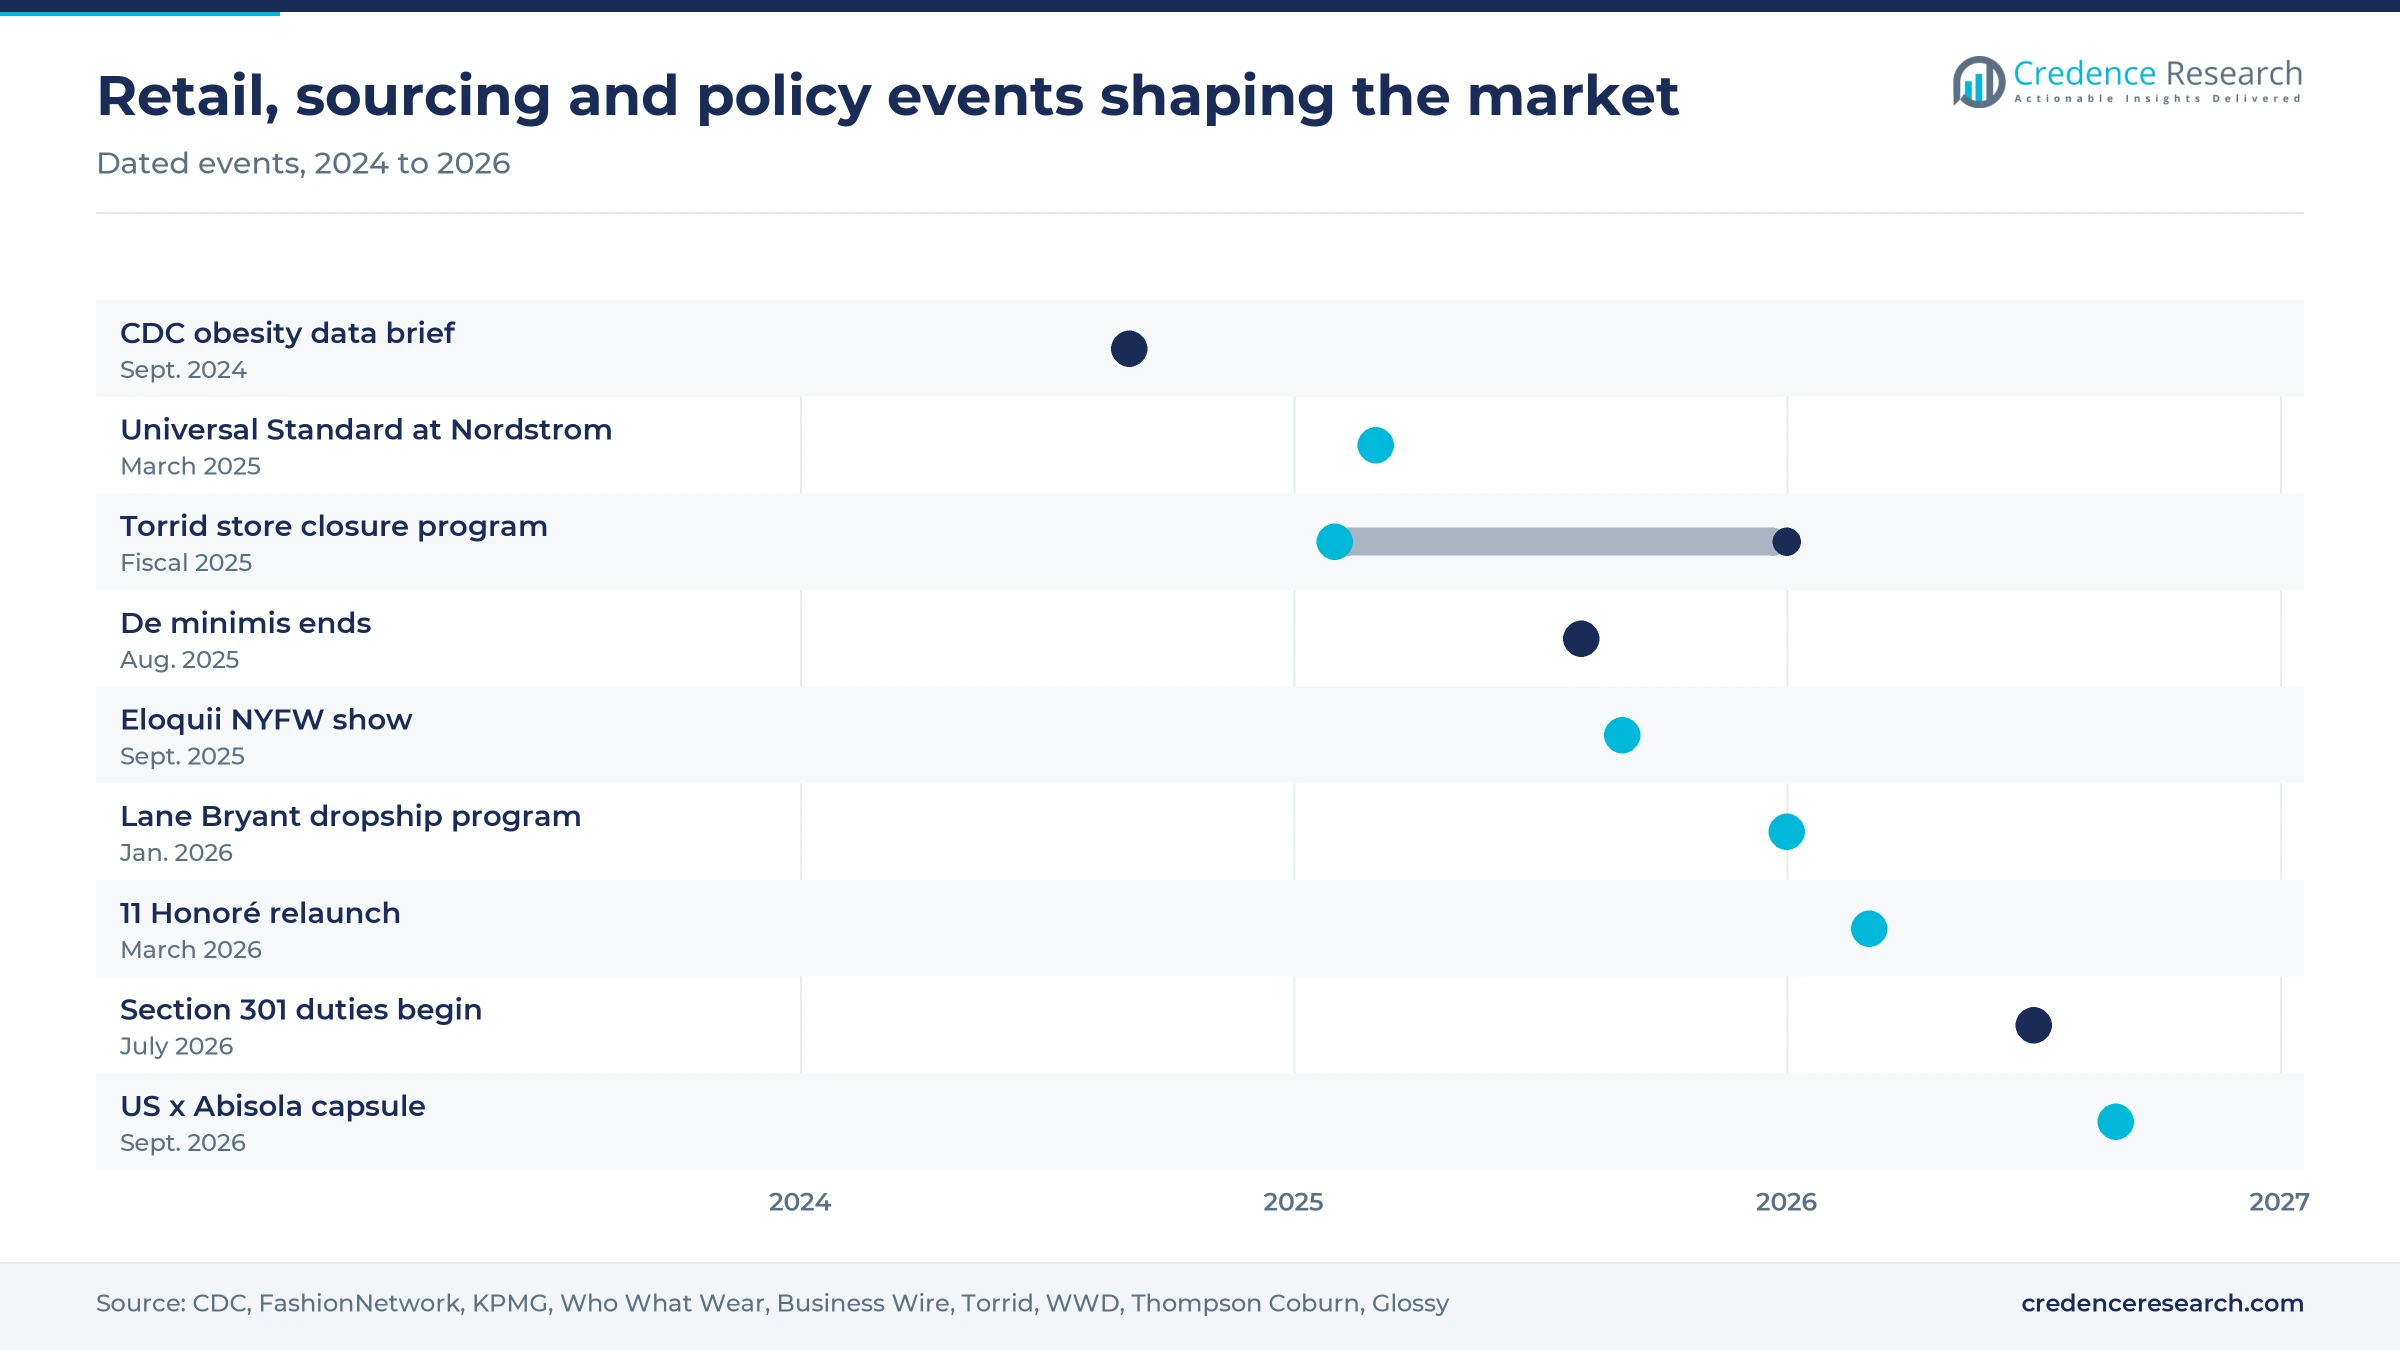
Wholesale and mass channels are adding extended sizes, which brings the category to shoppers who rarely visit a specialist chain. On March 24, 2025, Universal Standard launched in 20 Nordstrom stores in sizes 12 to 32, according to FashionNetwork, and it named Anthropologie and Macy’s among upcoming wholesale partners. In March 2026, Full Beauty Brands relaunched 11 Honoré with a 15-piece eveningwear capsule priced at USD 229 to USD 799 on Eloquii.com and Nordstrom.com, WWD reported. At the value end, Walmart’s Terra & Sky label lists sweaters in sizes 0X to 5X for USD 8.29. Therefore, Credence Research expects shelf space for extended sizes to broaden across price tiers through 2035, even as specialist store fleets shrink.
GLP-1 use and a runway retreat shift the category
GLP-1 use shifts size curves and repeat buying
Weight-loss drugs are shifting how often and in which sizes larger women buy clothes, rather than simply removing demand. According to Glossy, PwC and Numerator data showed that 21% of U.S. households included a current GLP-1 user in May 2026, up from 9% in January 2025. Among users, 73% reported a meaningful change in clothing size, and apparel spending rose 9.9% after six to eight months on the drugs. Spending on women’s jeans rose 66.1% and dresses 22.1%, while off-price spending climbed 18%. As a result, retailers must plan for faster size churn, because buyers move down the size curve in stages and replace basics at each step.
Shift in runway casting widens the gap with shoppers
Runway representation of larger bodies is falling, which widens the gap between fashion imagery and what most American women wear. Vogue Business data reported by FashionUnited in October 2025 showed plus-size models in only 0.9% of 9,038 Spring/Summer 2026 looks across New York, London, Milan and Paris. Glossy later counted about 1% curve or plus-size appearances across about 11,550 Spring 2027 looks. Who What Wear reported in November 2025 that major brands had scaled back extended sizing, yet Eloquii still staged its own runway show during New York Fashion Week in September 2025. Consequently, specialist brands that keep investing in visibility can win shoppers whom mainstream labels are leaving behind.
Opportunity in premium fits designed from size 18
Premium ranges built around larger fit models offer an opening, because buyers reward reliable fit with repeat purchases. Universal Standard starts design at size 18, and its U.S. x Abisola capsule of September 2026, priced at USD 150 to USD 225 in sizes 00 to 40, sold nearly 90% of units in size 14 or above, according to Glossy. Sizes 18 to 24 alone took 54% of units, and the brand’s repeat-customer rate rose from 70% in 2022 to 80% in 2024. In addition, the 11 Honoré relaunch in March 2026 priced eveningwear at up to USD 799, WWD reported. Brands that grade from a larger base size can therefore support higher prices in formal and occasion wear.
Opportunity in value ranges sold beside straight sizes
Value ranges displayed beside straight sizes offer an opening for mass chains that can carry depth across many size points. Old Navy merged its women’s and plus collections at the same price in all 1,200 stores in August 2021, offering sizes 0 to 28 in store and 00 to 30 online, according to KTVU. Target’s All in Motion activewear runs to size 4X with most items under USD 40, The Curvy Fashionista reported. In turn, PwC and Numerator data cited by Glossy showed off-price spending by GLP-1 users rising 18%. As a result, mass and off-price chains can capture shoppers who leave specialist stores, since price still decides most purchases of American apparel.
Store closures, duties and returns squeeze margins
Store closures cut local fitting-room access
Specialist store fleets are shrinking, which removes fitting rooms from many local malls. Torrid closed 151 stores in fiscal 2025 and ended the year with 483 locations, down from 634, according to its results of March 19, 2026. Its comparable sales fell 7% for the year and 6.3% in the second quarter of 2026. Shoppers in smaller markets lose local access as a result, so brands must hold them through digital channels and loyalty programs.
Asian sourcing duties lift landed costs
Import duties raise landed costs for ranges that rely on Asian factories. Section 301 duties of 12.5% on China and Vietnam and 10% on Bangladesh, India and Cambodia took effect on July 24, 2026, according to Thompson Coburn. Duty-free entry for parcels of USD 800 or less had already ended on Aug. 29, 2025, according to KPMG. Importers that cannot shift to CAFTA-DR suppliers face thinner margins or higher shelf prices.
Why do returns weigh on online clothing sales?
Fit uncertainty drives returns, and returns are costly for retailers selling many size points online. The National Retail Federation estimated on Oct. 15, 2025, that consumers would return USD 849.9 billion of merchandise in 2025, or 15.8% of sales. The online return rate was higher, at an estimated 19.3% of online sales. Brands with inconsistent grading carry the most risk, so fit tools and exchange programs such as Universal Standard’s one-year Fit Liberty policy matter.
GLP-1 use makes size planning less predictable
Weight-loss drug use makes inventory planning harder, because historical size curves may no longer match demand. In May 2026, 73% of GLP-1 users reported a meaningful change in clothing size, according to PwC data cited by Glossy, and PwC’s Ali Furman said historical size curves may become less reliable. Growth in compounded GLP-1 telehealth services widens access to these drugs. Retailers that buy deep in the largest sizes risk markdowns as a result.
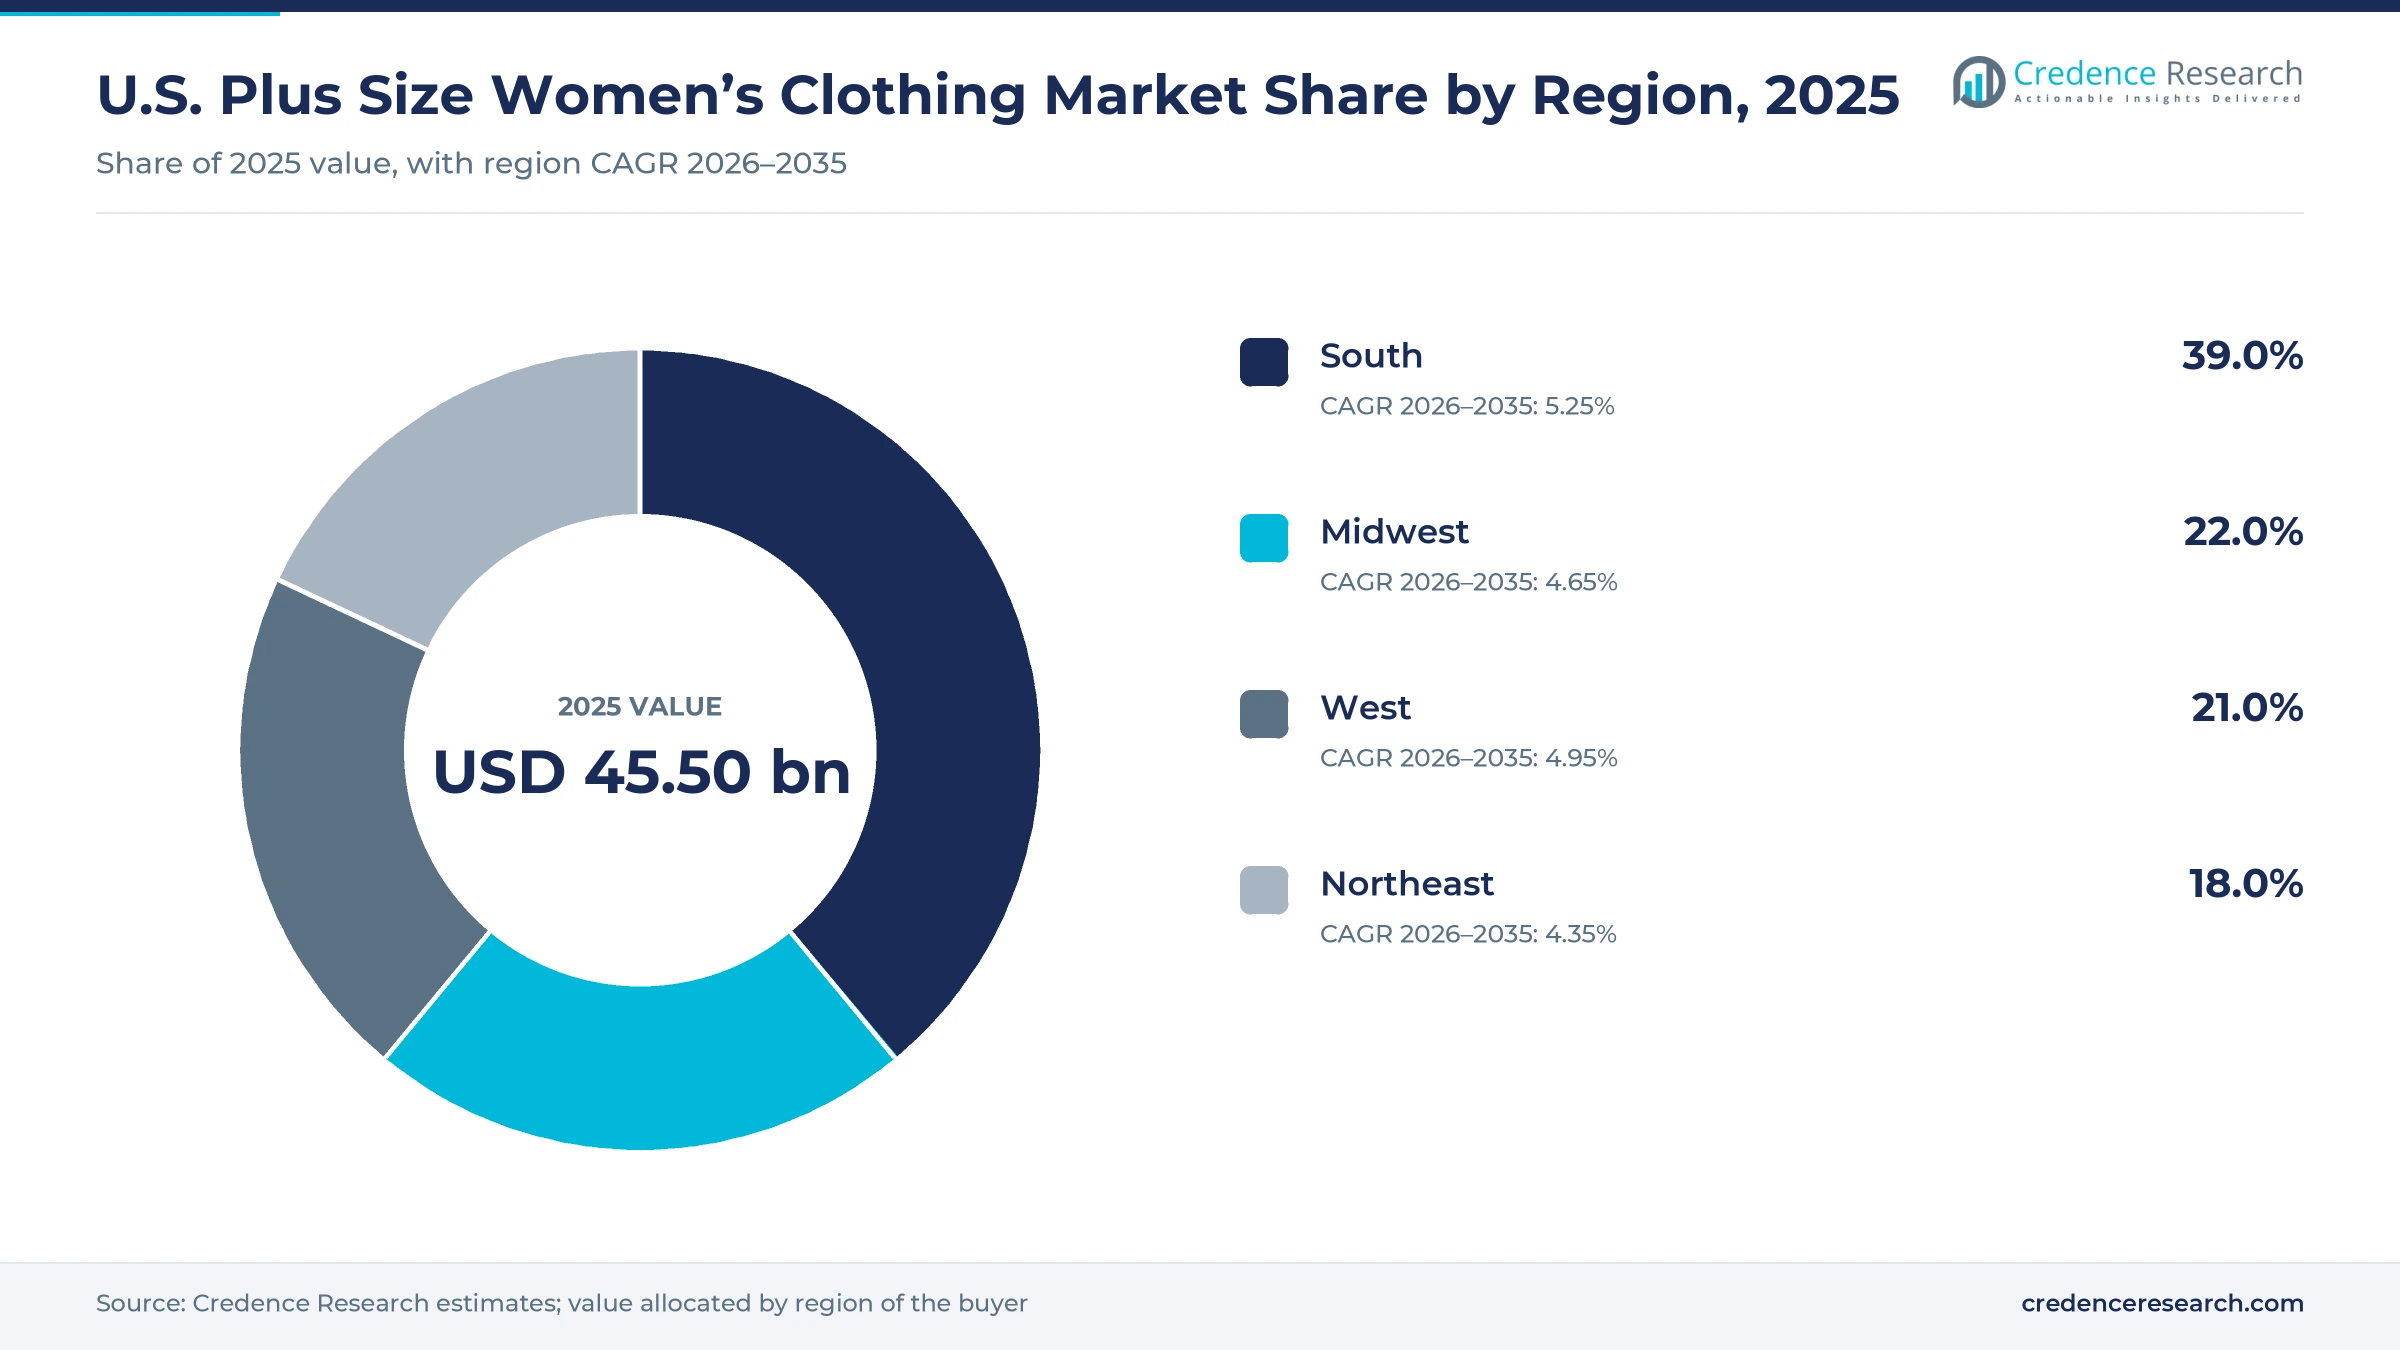
The South leads while the Midwest shows highest obesity
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| South | 17.75 | 39.0% | 5.25% |
| Midwest | 10.01 | 22.0% | 4.65% |
| West | 9.55 | 21.0% | 4.95% |
| Northeast | 8.19 | 18.0% | 4.35% |
South leads on population growth and a large buyer base
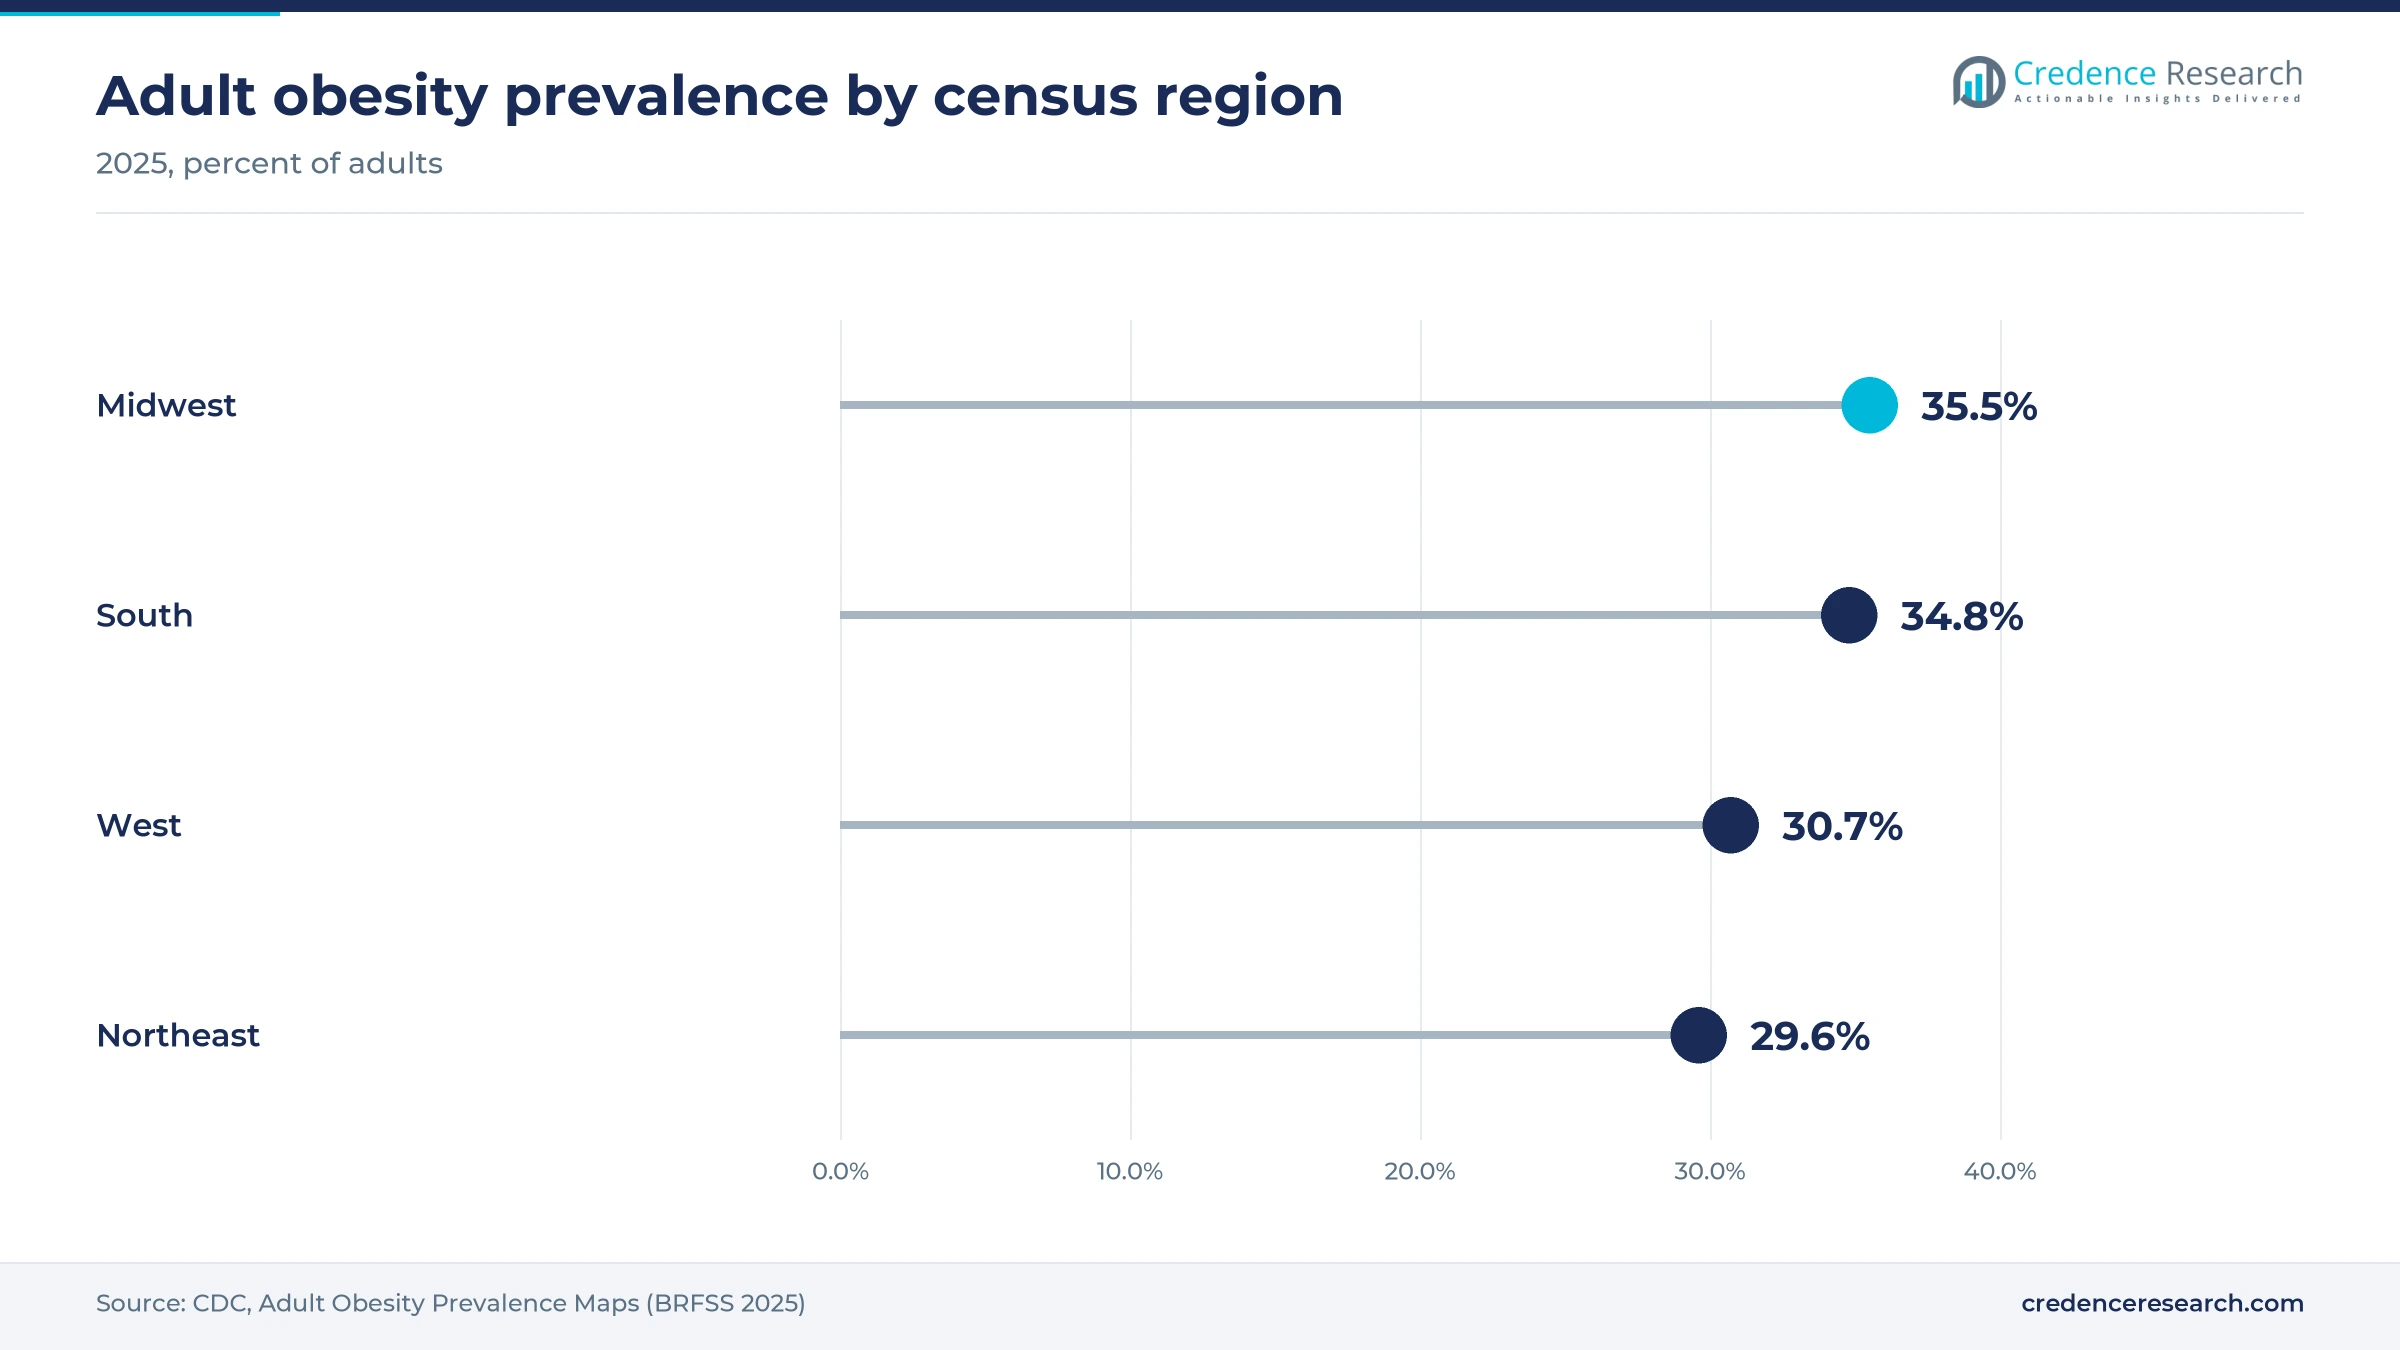
The South held 39.0% of 2025 value and grows at 5.25% a year, the fastest of the four regions. The CDC put adult obesity prevalence there at 34.8% in 2025, close to the Midwest’s top rate. The region’s population also grew 0.9% in the year to July 1, 2025, against 0.5% nationally, according to an NAHB analysis of Census data. Its 25 to 44 population also grew faster than that of any other region from 2020 to 2025, which adds shoppers in the leading age band.
Midwest pairs the highest obesity rate with slow growth
The Midwest held 22.0% of 2025 value and grows at 4.65% a year, a little below the national pace. Adult obesity prevalence was highest there, at 35.5% in 2025 according to CDC maps, which supports a large customer base for plus size women’s clothing. However, its population grew only 0.4% in the year to July 2025, and its under-18 group fell 3.9% from 2020 to 2025. Credence Research therefore assumes value chains and online orders carry most growth in the region.
West relies on premium department stores and online buyers
The West held 21.0% of 2025 value and grows at 4.95% a year, supported by online adoption and premium labels. Its adult obesity prevalence was 30.7% in 2025, according to the CDC, below the South and Midwest. The region’s population aged 65 and over rose 16.5% from 2020 to 2025, according to the Census Bureau. Universal Standard’s Nordstrom rollout also included the Alderwood store near Seattle, which shows premium department stores testing extended sizes there.
Northeast keeps fashion visibility but grows slowest
The Northeast held 18.0% of 2025 value and grows at 4.35% a year, the slowest of the four regions. The CDC put adult obesity prevalence there at 29.6% in 2025, the lowest regional rate. Its population grew 0.2% in the year to July 2025, and its 45 to 64 group fell 7.1% from 2020 to 2025, according to the Census Bureau. However, New York Fashion Week keeps the region central to brand visibility, as Eloquii’s September 2025 show indicated.
Wholesale launches and store exits mark 2025–2026
| Development | Status and market relevance |
|---|---|
| In March 2025, Universal Standard launched in 20 Nordstrom stores in sizes 12 to 32. | The rollout put a size-inclusive premium label on department store floors. |
| In September 2025, Eloquii staged its own runway show during New York Fashion Week. | The show came as runway casting of plus-size models fell to 0.9% of looks. |
| In January 2026, Lane Bryant joined Rithum’s network to launch a dropship program for U.S. brand partners. | Partner brands can now list and ship products directly on lanebryant.com. |
| In March 2026, Torrid reported that it closed 151 stores in fiscal 2025, ending with 483 stores. | The closures shift more Torrid customers toward nearby stores and digital channels. |
| In September 2026, Universal Standard launched its U.S. x Abisola capsule in sizes 00 to 40. | Nearly 90% of units sold were size 14 or above, according to the brand. |
Fit data, dropship feeds and size grading matter more
- Grading from a larger fit model lets Universal Standard design from a size 18 base, which the brand labels a medium.
- Dropship integrations let Lane Bryant list partner products on its website through Rithum’s network without building one-off connections.
- National body measurement data from the CDC’s August 2021 to August 2023 survey give brands an updated reference for average waist and weight.
- Size exchange programs such as Universal Standard’s Fit Liberty let shoppers swap eligible garments for another size within one year.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Specialist chains face mass merchants and new labels
Competition in plus size women’s clothing splits into specialist chains, digital-first labels, department stores and mass merchants. Lane Bryant operates 400 stores, sells apparel in sizes 10 to 40 and carries Cacique lingerie and bras in 97 sizes, and it added a dropship program in January 2026. Torrid serves sizes 10 to 30 and is building five sub-brands led by Festi, although it closed 151 stores in fiscal 2025. Eloquii, owned by Full Beauty Brands since 2023, now also houses the relaunched 11 Honoré eveningwear line. Universal Standard competes on fit from a size 18 base and wholesale reach through Nordstrom. Credence Research views Old Navy, Walmart and Target as the main value competitors, because they sell larger sizes beside straight sizes at mass prices. Nike extends athletic ranges to size 4X, which pressures specialists in sportswear. As store fleets shrink, competition is moving toward assortment depth, fit consistency and loyalty programs.
Companies profiled and their roles in this market
| Company | Type | Role in the market |
|---|---|---|
| Lane Bryant | Specialist retailer | 400 stores, apparel in sizes 10 to 40, dropship program since January 2026 |
| Torrid | Specialist retailer | Sizes 10 to 30, 457 stores in August 2026 after a closure program |
| Eloquii | Digital-first brand | Full Beauty Brands label that also sells the relaunched 11 Honoré line |
| Universal Standard | Premium brand | Designs from a size 18 base and sells through 20 Nordstrom stores |
| Old Navy | Mass specialty chain | Merged women’s and plus ranges at one price across 1,200 stores |
| Walmart | Mass merchant | Terra & Sky label in sizes 0X to 5X at value prices |
| Target | Mass merchant | All in Motion activewear in women’s sizes up to 4X |
| Nike | Athletic brand | Women’s plus range expanded to sizes 0X to 4X |
Why Credence Research expects steady, not rapid, growth
Credence Research’s view is that plus size women’s clothing will grow steadily but not rapidly, because rising demand meets a shrinking store base. Measured body sizes keep the customer pool large, with more than four in ten adult women classed as obese in the latest CDC survey. However, Torrid’s 7% fall in comparable sales during fiscal 2025 shows that specialist chains are losing visits to mass merchants and online sellers. GLP-1 use also adds size churn rather than a clean decline in demand. The forecast therefore keeps a 4.90% CAGR, above total women’s apparel growth but below earlier estimates.
How the 2025 value was rebuilt and checked
The report uses 2025 as the base year and 2026 to 2035 as the forecast period. The earlier Credence Research estimate was brought to 2025 with its own growth rate and then corrected to a Credence Research estimate built from Bureau of Economic Analysis spending on women’s and girls’ clothing, an adult share and a plus-size share of that spending, with a lower growth rate. Regional splits are Credence Research estimates from Census Bureau population and CDC obesity data. Segment splits are estimates anchored to company and trade data. Sources include government statistics, company releases and trade press, and no interviews or surveys were conducted.
Wider ranges and fewer stores through 2035
Through 2035, Credence Research expects plus size women’s clothing value to grow as an older, larger-sized population keeps demand broad. Online retailers should gain share while specialist chains finish closing weaker stores, and mass merchants should keep widening ranges beside straight sizes. Weight-loss drugs remain the largest swing factor, since faster size changes could raise purchase frequency but also leave stores with the wrong size mix. Tariff policy matters too, because duties on Asian suppliers raise costs. Brands that grade from larger fit models, track size curves monthly and offer exchanges should be best placed.
Frequently Asked Questions
How big is the U.S. plus size women’s clothing market?
What is the average size of an American woman?
Which product type leads plus size women’s clothing?
Are plus size clothes in style right now?
Which plus size fashion brands operate in the U.S.?
What is the average return rate for clothing retailers?
How do GLP-1 drugs affect demand for larger sizes?
Which U.S. region buys the most plus size clothing?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Casual Wear
- 1.2.2 Formal Wear
- 1.2.3 Sports Wear
- 1.3 By Age Group
- 1.3.1 Below 15 Years
- 1.3.2 15-24 Years
- 1.3.3 25-45 Years
- 1.3.4 46-60 Years
- 1.3.5 Above 60 Years
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 45.50 billion → 2035: USD 73.41 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 U.S. Plus Size Women’s Clothing Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 U.S. Plus Size Women’s Clothing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 U.S. Plus Size Women’s Clothing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 U.S. Plus Size Women’s Clothing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 U.S. Plus Size Women’s Clothing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 U.S. Plus Size Women’s Clothing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 U.S. Plus Size Women’s Clothing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 U.S. Plus Size Women’s Clothing Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 45.50 billion → 2035: USD 73.41 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 U.S. Plus Size Women’s Clothing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Casual Wear
- 12.3.7.2 Formal Wear
- 12.3.7.3 Sports Wear
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Age Group - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Below 15 Years
- 12.4.7.2 15-24 Years
- 12.4.7.3 25-45 Years
- 12.4.7.4 46-60 Years
- 12.4.7.5 Above 60 Years
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 U.S. Plus Size Women’s Clothing Geographic Market Outlook, 2025-2035
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 U.S. Plus Size Women’s Clothing Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2035
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 U.S. Plus Size Women’s Clothing Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2035
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Lane Bryant
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Torrid
- 17.4 Eloquii
- 17.5 Universal Standard
- 17.6 Old Navy
- 17.7 Walmart
- 17.8 Target
- 17.9 Nike
- 17.10 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

