
Market Overview
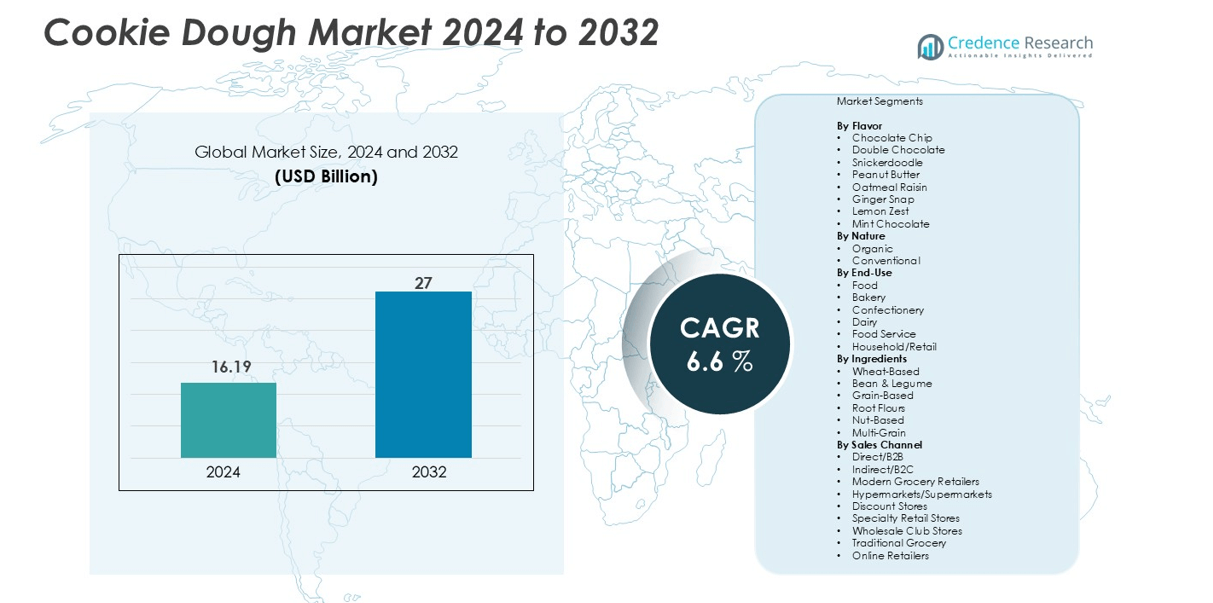
The cookie dough market size was valued at USD 16.19 billion in 2024 and is anticipated to reach USD 27 billion by 2032, at a CAGR of 6.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cookie Dough Market Size 2024 | USD 16.19 billion |
| Cookie Dough Market, CAGR | 6.6% |
| Cookie Dough Market Size 2032 | USD 27 billion |
The cookie dough market is dominated by leading players such as General Mills Inc., Nestlé S.A., Cérélia Group, Dawn Foods UK Ltd., Dough-to-Go Inc., Rhino Foods Inc., Neighbors LLC, Gregory’s Foods Inc., Mo’s Ltd., Foxtail Foods, Michael’s Bakery Products LLC, George Weston Limited, Wewalka, and Sara Lee Bakery Group. General Mills and Nestlé hold a commanding position, collectively accounting for approximately 55–60% of the global market, driven by extensive product portfolios, brand recognition, and wide distribution networks. Regionally, North America leads the market with a 32% share, supported by strong U.S. consumption of ready-to-bake and edible cookie dough products. Europe follows with about 18% market share, fueled by premiumization and bakery culture, while Asia-Pacific and emerging regions contribute roughly 35–40% combined, reflecting growing urbanization, disposable incomes, and modern retail expansion. The competitive landscape is shaped by product innovation, flavor diversification, and strategic regional penetration.
Market Insights
- The global cookie dough market was valued at USD 16.19 billion in 2024 and is projected to reach USD 27 billion by 2032, growing at a CAGR of 6.6% during the forecast period.
- Strong demand for convenient and ready-to-eat desserts, along with rising indulgence trends among millennials and working consumers, drives market growth across North America and Europe.
- Key trends include flavor diversification with chocolate chip, double chocolate, and peanut butter leading the segment, as well as the rising popularity of organic, plant-based, and clean-label cookie dough.
- The market is highly competitive, dominated by players like General Mills Inc., Nestlé S.A., Cérélia Group, Dawn Foods UK Ltd., and Dough-to-Go Inc., with North America holding 32% market share, Europe 18%, and Asia-Pacific and emerging regions 35–40% combined.
- Challenges include regulatory compliance, food safety concerns for raw consumption, and short shelf life, which restrict distribution and increase operational costs, particularly for organic and preservative-free products.
Market Segmentation Analysis:
By Flavor
Among flavors, the chocolate chip segment dominates the global cookie dough market, accounting for the largest market share. Its widespread consumer appeal, nostalgic value, and versatility in bakery and dessert applications drive its strong demand. Double chocolate and peanut butter follow closely, supported by growing indulgence trends and the popularity of protein-rich snack formulations. Emerging flavors such as lemon zest and mint chocolate are gaining traction due to premiumization and seasonal product launches, while innovations incorporating M&M’s and macadamia pieces attract younger demographics seeking texture-rich experiences.
- For instance, Nestlé provides Toll House Chocolate Chip Cookie Dough in varying formats for both retail and foodservice, such as a 30 oz retail tube for home baking and cases containing 240 pre-portioned cookies for commercial use.
By Nature
Within the nature segment, conventional cookie dough holds the dominant market share, driven by its affordability and wide availability across retail and foodservice channels. However, the organic sub-segment is expanding rapidly, fueled by increasing consumer preference for clean-label, preservative-free, and ethically sourced ingredients. Manufacturers are responding by reformulating products using organic wheat flour, natural sweeteners, and non-GMO ingredients. This shift is further supported by the rise of vegan and allergen-free options, appealing to health-focused and environmentally conscious consumers, thereby gradually reshaping purchasing patterns in both developed and emerging markets.
- For instance, Nestlé Toll House produces large quantities of refrigerated cookie dough for retail distribution across North America, supported by automated production lines to ensure consistency and scalability.
Key Growth Driver
Rising Demand for Ready-to-Eat and Convenience Foods
The growing preference for convenient and indulgent food options has become a major driver of the cookie dough market. Consumers increasingly seek ready-to-eat products that offer both taste and time efficiency, particularly among working professionals and millennials. The introduction of heat-treated, edible cookie dough that can be safely consumed raw has revolutionized product availability across retail and foodservice outlets. Brands like Nestlé and Ben & Jerry’s have expanded their portfolios with refrigerated and single-serve formats, appealing to on-the-go lifestyles. This convenience-driven consumption pattern continues to propel market growth, particularly in developed economies with fast-paced consumer habits.
- For instance, Nestlé launched its Toll House Edible Cookie Dough in 15-ounce tubs in July 2019. Initially available at retailers like Publix, the product became available in select Walmart stores and other regional grocery chains later that month.
Product Innovation and Flavor Diversification
Continuous innovation in flavors and formulations significantly drives cookie dough market expansion. Manufacturers are experimenting with premium ingredients, novel inclusions such as protein and fiber fortification, and indulgent flavor profiles like double chocolate, peanut butter, and mint. Product differentiation through limited-edition and seasonal releases further enhances brand engagement. Companies such as General Mills and Doughp have launched creative flavor extensions targeting younger consumers and dessert enthusiasts. Additionally, advancements in cold-chain logistics and packaging technologies enable longer shelf life and freshness, allowing brands to diversify offerings without compromising quality.
- For instance, In May 2025, General Mills introduced Pillsbury BIG COOKIES cookie dough. The new product became available at Walmart that month before rolling out to other retailers later in the summer. The manufacturer's suggested retail price (MSRP) was $5.99 for a six-count pack.
Expansion of Online and Retail Distribution Channels
E-commerce growth and digital marketing have redefined cookie dough accessibility and consumer outreach. Online platforms enable brands to directly connect with niche consumer groups, offering subscription-based models and personalized assortments. Meanwhile, expanding shelf presence in supermarkets, convenience stores, and specialty bakeries strengthens brand visibility. Partnerships between manufacturers and large retail chains, such as Walmart and Target, have enhanced market penetration. The surge in online grocery adoption, especially post-pandemic, has further boosted sales of refrigerated and edible cookie dough, underscoring the strategic importance of omnichannel distribution.
Key Trend & Opportunity
Rising Popularity of Plant-Based and Clean-Label Formulations
The market is witnessing a strong shift toward plant-based and clean-label cookie dough, driven by health-conscious consumers and vegan dietary preferences. Brands are introducing dairy-free, egg-free, and gluten-free variants using alternative proteins and natural sweeteners. The growing awareness of ethical sourcing and sustainable ingredients presents new opportunities for innovation. Companies focusing on transparency in labeling and minimal processing are gaining a competitive advantage. This trend aligns with the broader shift toward wellness-oriented indulgence, where consumers seek products that balance taste, nutrition, and sustainability without compromising texture or flavor.
- For instance, Deux Foods offers functional, plant-based cookie dough enhanced with ingredients such as immunity-boosting elderberry extract and zinc, and protein from sources like peas.
Integration of Functional Ingredients and Nutritional Benefits
Manufacturers are leveraging functional ingredients such as oats, nuts, and legumes to enhance the nutritional profile of cookie dough. The inclusion of protein, probiotics, and superfoods supports health-driven snacking trends. This opens opportunities for hybrid product positioning, merging indulgence with functionality. Brands introducing high-protein or low-sugar cookie dough variants cater to fitness-focused and diabetic-friendly markets. The blending of indulgent flavor experiences with better-for-you attributes allows companies to reach new consumer segments, particularly in premium retail and online wellness platforms.
- For instance, Whoa Dough cookie dough snack bars are made with a chickpea and oat flour blend. Depending on the flavor, each bar contains 3–4 grams of fiber and 3–5 grams of protein.
Key Challenges
Regulatory Compliance and Food Safety Concerns
Stringent food safety regulations pose a significant challenge for cookie dough manufacturers, especially in ensuring products are safe for raw consumption. Heat treatment of flour and pasteurization of eggs are essential to eliminate pathogens like E. coli and Salmonella. However, these processes increase production complexity and costs. Maintaining compliance across multiple regions with varying labeling and food safety standards also adds operational burden. Any lapse can lead to product recalls and brand damage, making quality assurance and traceability critical components of the supply chain.
Short Shelf Life and Distribution Limitations
Cookie dough, particularly in its fresh or refrigerated form, faces challenges related to shelf stability and transportation. Maintaining optimal temperature and preventing ingredient separation or spoilage require robust cold-chain logistics. Small-scale manufacturers often struggle to manage these costs, limiting product reach beyond local markets. Additionally, consumer demand for natural and preservative-free ingredients further reduces shelf life, necessitating frequent inventory turnover. Addressing these logistical constraints through advanced packaging and formulation innovation remains vital for sustained market competitiveness.
Regional Analysis
North America (United States & Canada)
North America leads the global cookie dough market, securing around 32 % of global revenue, driven chiefly. The U.S. dominates, supported by strong consumption of ready-to-eat and refrigerated dough segments, high retail penetration, and consumer preference for convenience. Canada, while smaller, exhibits stable growth fueled by health and specialty product demand (e.g. organic and gluten-free). Investments in cold-chain logistics, national distribution networks, and flavor innovation further reinforce North America’s commanding share and steady growth trajectory.
Europe, Middle East & Africa (EMEA)
In the EMEA region, Europe takes the lead in cookie dough consumption, supported by established bakery traditions and growing adoption of convenient dessert formats. The region’s market share is estimated in the mid-teens percent range of the global total (i.e. roughly 15–20 %). Manufacturers in Western Europe emphasize premiumization, clean labels, and gourmet variants, while Eastern Europe shows rising interest in Western-style indulgent snacks. Meanwhile, Middle Eastern and African markets are nascent yet promising, aided by rising urbanization, retail modernisation, and increasing exposure to Western dessert trends.
Asia-Pacific & Rest of World
Asia-Pacific and Rest of World (Latin America, MEA beyond core, etc.) currently hold a combined share of about 35–40 % of the global cookie dough market. In Asia-Pacific, fast urbanization, rising disposable incomes, and expanding modern retail chains in China, India, Japan, and Australia are driving demand for refrigerated and ready-to-bake dough. Markets in Latin America, the Middle East, and Africa are emerging, propelled by growing middle classes, tourism, and increasing exposure to Western dessert formats. Although base volumes remain lower, these regions present high growth potential, especially in e-commerce and niche premium offerings.
Market Segmentations:
By Flavor
- Chocolate Chip
- Double Chocolate
- Snickerdoodle
- Peanut Butter
- Oatmeal Raisin
- Ginger Snap
- Lemon Zest
- Mint Chocolate
By Nature
- Organic
- Conventional
By End-Use
- Food
- Bakery
- Confectionery
- Dairy
- Food Service
- Household/Retail
By Ingredients
- Wheat-Based
- Bean & Legume
- Grain-Based
- Root Flours
- Nut-Based
- Multi-Grain
By Sales Channel
- Direct/B2B
- Indirect/B2C
- Modern Grocery Retailers
- Hypermarkets/Supermarkets
- Discount Stores
- Specialty Retail Stores
- Wholesale Club Stores
- Traditional Grocery
- Online Retailers
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The global cookie dough market is highly competitive, with a mix of multinational corporations and regional players driving innovation and growth. General Mills Inc. and Nestlé S.A. are key leaders, commanding a significant market share of approximately 55–60%, supported by extensive brand portfolios and strong distribution networks. Cérélia Group has expanded its presence in Europe and North America through strategic acquisitions and product diversification. Other notable players include Dawn Foods UK Ltd., Dough-to-Go Inc., Rhino Foods Inc., Mo's Ltd., Neighbors LLC, and Sara Lee Bakery Group, which compete by offering niche flavors, premium ingredients, and customized formulations. Companies are increasingly focusing on clean-label, organic, and ready-to-eat variants to meet evolving consumer preferences. The market’s competitive dynamics are further shaped by regional consumption patterns, retail expansion, and e-commerce penetration, requiring continuous innovation and strategic positioning to maintain and grow market share.
Key Player Analysis
- Cérélia Group
- Foxtail Foods
- Neighbors LLC
- Wewalka
- General Mills Inc.
- Michael's Bakery Products LLC
- Mo's Ltd.
- Dough-to-Go Inc.
- Sara Lee Bakery Group
- Gregory's Foods Inc.
- Nestlé S.A.
- Rhino Foods Inc.
- Dawn Foods UK Ltd.
Recent Developments
- In 2024, Tiff’s Treats expanded their product line with a new range of edible cookie dough flavors, including classic Chocolate Chip, Brownie Batter, and Cake Batter. The dough is heat-treated to ensure safety for raw consumption and comes in convenient, resealable tubs.
- In 2024, Nestlé Toll House introduced a new line of edible cookie dough featuring their signature chocolate morsels. Available in flavors like Chocolate Chip and Peanut Butter Cup, this dough is designed for safe raw consumption and also works well for baking.
Report Coverage
The research report offers an in-depth analysis based on Flavor Outlook, Nature Outlook, Ingredients Outlook, Sales Channel Outlook, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The cookie dough market is expected to witness steady growth driven by rising consumer preference for convenient and ready-to-bake products.
- Innovation in flavors and premium ingredients will continue to attract new consumer segments.
- Plant-based and organic cookie dough variants will see increased adoption due to health-conscious trends.
- Expansion of online retail and e-commerce channels will enhance market reach and accessibility.
- Functional and fortified cookie dough products with added protein or fiber will gain popularity.
- Emerging markets in Asia-Pacific and Latin America will offer high growth opportunities.
- Companies will focus on sustainable sourcing and clean-label ingredients to meet evolving consumer expectations.
- Strategic collaborations and acquisitions will help players strengthen regional presence.
- Short shelf-life challenges will drive innovation in packaging and preservation technologies.
- Overall, the market will continue to evolve with premiumization, convenience, and health-oriented offerings shaping future growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Cookie Dough market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Cookie Dough market projected to grow between 2025 and 2032?
Which Cookie Dough market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Cookie Dough market?
Who are the leading companies in the Cookie Dough market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 16.19 billion → 2032: USD 27 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cookie Dough Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cookie Dough Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cookie Dough Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cookie Dough Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cookie Dough Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cookie Dough Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cookie Dough Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cookie Dough Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 16.19 billion → 2032: USD 27 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cookie Dough Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cookie Dough Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cookie Dough Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cookie Dough Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

