
Market Overview
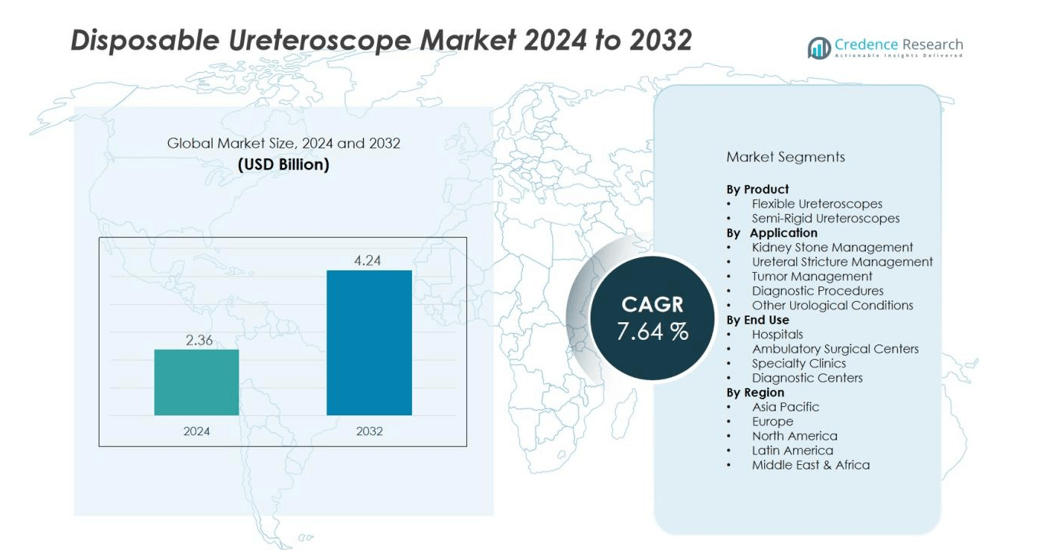
The Disposable Ureteroscope Market size was valued at USD 2.36 billion in 2024 and is anticipated to reach USD 4.24 billion by 2032, at a CAGR of 7.64 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Disposable Ureteroscope Market Size 2024 | USD 2.36 billion |
| Disposable Ureteroscope Market, CAGR | 7.64% |
| Disposable Ureteroscope Market Size 2032 | USD 4.24 billion |
Market growth is strongly driven by the rising adoption of minimally invasive surgeries, growing awareness about infection control, and technological improvements in fiber-optic and digital visualization systems. The shift toward disposable medical devices also aligns with hospital efforts to enhance patient safety and operational efficiency. Additionally, healthcare providers are increasingly integrating single-use ureteroscopes for outpatient procedures, boosting procedural volume and market demand.
Regionally, North America leads the market due to well-established healthcare infrastructure, higher prevalence of urological disorders, and early adoption of advanced endoscopic technologies. Europe follows closely, supported by regulatory initiatives promoting infection control. The Asia-Pacific region is anticipated to experience the fastest growth, driven by expanding healthcare access, rising medical tourism, and growing investment in modern urology centers.
Market Insights:
- The Disposable Ureteroscope Market was valued at USD 1.42 billion in 2018, reached USD 2.36 billion in 2024, and is expected to attain USD 4.24 billion by 2032, growing at a CAGR of 7.64% from 2024 to 2032.
- North America holds 39% share, driven by advanced healthcare systems, strong reimbursement structures, and widespread use of minimally invasive procedures.
- Europe accounts for 27% share, supported by stringent infection control regulations, active R&D investments, and the adoption of single-use medical devices.
- Asia Pacific represents 23% share and is the fastest-growing region, fueled by healthcare infrastructure expansion, rising medical tourism, and government support for advanced urology technologies.
- Flexible ureteroscopes dominate with 64% share due to better navigation and visualization, while hospitals lead the end-use segment with 58% share, supported by higher procedural volume and advanced surgical setups.
Market Drivers:
Rising Prevalence of Urological Disorders Driving Demand
The growing occurrence of urological diseases such as kidney stones, urinary tract infections, and prostate conditions is a major factor propelling the Disposable Ureteroscope Market. Sedentary lifestyles, poor hydration habits, and dietary changes have led to a surge in kidney stone cases worldwide. It has increased the need for efficient diagnostic and therapeutic tools in urology. Hospitals and clinics are adopting single-use ureteroscopes to minimize infection risk during procedures and ensure consistent device performance across multiple patients.
- For instance, Olympus received FDA clearance for its RenaFlex single-use flexible ureteroscope system in April 2024, featuring a 9.5 Fr outer diameter with a 3.6 Fr working channel and 270-degree up/down angulation capability.
Shift Toward Minimally Invasive Procedures Encouraging Adoption
The expanding preference for minimally invasive surgical techniques is fueling demand for disposable ureteroscopes. Patients and healthcare providers favor shorter recovery times and reduced hospital stays. It provides precise visualization and maneuverability within the urinary tract, improving surgical accuracy and outcomes. Healthcare systems are prioritizing single-use devices to avoid the cost and time associated with sterilization of reusable scopes.
- For instance, Boston Scientific’s LithoVue™ single-use digital flexible ureteroscope has demonstrated up to 100% device sterility per procedure, directly addressing hospital infection control protocols.
Technological Advancements Enhancing Performance and Reliability
Continuous innovations in fiber-optic imaging, digital camera integration, and ergonomic design are strengthening the appeal of disposable ureteroscopes. It delivers high-definition visualization and better access to complex anatomy during endoscopic procedures. Enhanced image quality and device flexibility support complex stone management and tumor detection. These improvements have positioned single-use ureteroscopes as reliable alternatives to traditional reusable models in both inpatient and outpatient settings.
Focus on Infection Control and Operational Efficiency Boosting Usage
Growing awareness of hospital-acquired infections has led healthcare institutions to seek safer medical instruments. Disposable ureteroscopes eliminate the need for disinfection and reprocessing, reducing contamination risks. It streamlines workflow, lowers maintenance costs, and ensures consistent device readiness. This operational advantage has made single-use ureteroscopes an increasingly preferred choice for urology departments worldwide.
Market Trends:
Integration of Digital Visualization and Wireless Imaging Technologies
Technological innovation is redefining the capabilities of disposable ureteroscopes, enhancing clinical precision and user convenience. The integration of advanced digital visualization systems offers high-resolution imaging that supports accurate diagnosis and efficient stone retrieval. It improves visibility in complex procedures and reduces the need for repeated interventions. Wireless imaging technology is also gaining traction, allowing real-time data transmission and remote monitoring during surgeries. Compact, portable designs are making single-use ureteroscopes more practical in outpatient and ambulatory care settings. These advancements strengthen surgeon confidence, promote better patient outcomes, and expand the application scope of disposable devices.
- For instance, Boston Scientific’s LithoVue™ disposable ureteroscope features a digital CMOS sensor that provides 1920 x 1080-pixel HD images, allowing for detailed visualization during ureteroscopy procedures.
Growing Hospital Preference for Single-Use Devices and Supply Chain Optimization
Healthcare facilities worldwide are shifting toward single-use endoscopic instruments to enhance infection control and operational efficiency. The Disposable Ureteroscope Market reflects this trend, supported by stricter hospital hygiene standards and the cost of maintaining reusable scopes. It eliminates sterilization delays and enables faster patient turnover in high-volume centers. Manufacturers are optimizing supply chains to deliver ready-to-use sterile devices with reduced lead times. Sustainability initiatives are prompting companies to introduce recyclable components and eco-friendly packaging. Hospitals increasingly value predictable performance and reduced maintenance costs, strengthening the transition toward disposable systems in both developed and emerging healthcare markets.
- For instance, Boston Scientific's LithoVue ureteroscope demonstrated a 5.4% complication rate in 115 procedures, compared to 18.0% with reusable fiber-optic ureteroscopes. Manufacturers are optimizing supply chains to deliver ready-to-use sterile devices with reduced lead times.
Market Challenges Analysis:
High Cost per Procedure and Limited Reimbursement Policies
The adoption of single-use ureteroscopes faces resistance due to their higher per-procedure cost compared to reusable models. Hospitals in cost-sensitive regions often hesitate to invest in disposable devices without adequate reimbursement coverage. The Disposable Ureteroscope Market encounters pricing pressure, particularly in public healthcare systems with strict procurement budgets. It requires manufacturers to balance quality and affordability while demonstrating long-term economic benefits. Limited awareness of cost-saving potential through reduced reprocessing and infection control also slows adoption. Reimbursement gaps remain a major barrier, especially in emerging markets with evolving healthcare funding structures.
Environmental Concerns and Waste Management Issues
The growing use of disposable medical instruments raises environmental sustainability challenges. Healthcare facilities are under scrutiny for increasing medical waste from single-use devices. It intensifies pressure on manufacturers to develop recyclable or biodegradable materials without compromising product integrity. Regulatory bodies are introducing stricter waste management policies, prompting hospitals to seek eco-conscious solutions. Lack of efficient disposal systems in developing regions further complicates adoption. Addressing these sustainability issues is crucial for broader acceptance and long-term viability of disposable ureteroscopes.
Market Opportunities:
Expansion in Emerging Healthcare Markets and Ambulatory Centers
Rapid healthcare infrastructure growth in emerging economies offers strong potential for disposable ureteroscope adoption. The Disposable Ureteroscope Market benefits from rising awareness of infection control and government support for advanced medical technologies. It finds opportunity in smaller hospitals and ambulatory surgical centers that prefer ready-to-use, maintenance-free equipment. Increasing healthcare expenditure and the spread of private urology clinics expand the customer base. Demand is growing in Southeast Asia, Latin America, and the Middle East due to a surge in urological procedures. Local manufacturing and distribution partnerships can further strengthen market penetration in these regions.
Sustainability-Driven Product Innovation and Material Advancements
The shift toward eco-friendly medical devices creates new development pathways for manufacturers. It encourages the design of recyclable or biodegradable disposable ureteroscopes that meet global environmental standards. Companies investing in sustainable materials and low-waste packaging gain a competitive advantage. Integration of reusable components in hybrid models may also attract cost-conscious healthcare providers. Innovation in lightweight polymers and miniaturized imaging components enhances performance while reducing material waste. These sustainability-focused advancements are expected to open long-term growth opportunities in regulated and green healthcare markets.
Market Segmentation Analysis:
By Product
Based on product type, the Disposable Ureteroscope Market is divided into flexible and semi-rigid ureteroscopes. Flexible ureteroscopes dominate due to their enhanced maneuverability and superior visualization during complex urological procedures. It offers easier access to renal cavities and reduces patient discomfort, which strengthens its preference among urologists. Semi-rigid models maintain relevance for lower urinary tract procedures, supported by their durability and cost-effectiveness. Growing adoption of high-definition digital flexible scopes continues to drive innovation and market share expansion.
- For InstanceThe Olympus URF-V3 digital flexible ureteroscope features an 8.4 Fr distal tip and shaft diameter and a 275-degree angulation range for improved access within the urinary tract and to reach renal calyces. This model utilizes a chip-on-the-tip digital sensor providing an approximately 80-degree field of view
By Application
In terms of application, kidney stone management represents the largest share due to the rising global prevalence of nephrolithiasis. It supports high procedural volume in both inpatient and outpatient settings. Ureteral stricture and tumor management applications are expanding with improved endoscopic precision and safety standards. Disposable ureteroscopes are widely used for diagnostic and therapeutic interventions, ensuring reduced contamination risk. The segment benefits from the increased preference for minimally invasive procedures in urology.
- For Instance, In the prospective randomized ASPIRE clinical trial, Calyxo's CVAC System (used in the SURE procedure) demonstrated a mean stone volume reduction of 97% at 30 days, which was superior to standard ureteroscopy and maintained high efficacy regardless of the patient's baseline stone burden.
By End Use
Hospitals hold the dominant position among end users due to higher patient inflow and advanced surgical infrastructure. It allows integration of disposable devices for efficient workflow and infection control. Ambulatory surgical centers are gaining momentum owing to growing demand for short-duration, cost-efficient urological procedures. Specialty clinics also contribute to market growth through targeted adoption in outpatient care. Expanding use of single-use scopes in these facilities supports broader market penetration worldwide.
Segmentations:
By Product
- Flexible Ureteroscopes
- Semi-Rigid Ureteroscopes
By Application
- Kidney Stone Management
- Ureteral Stricture Management
- Tumor Management
- Diagnostic Procedures
- Other Urological Conditions
By End Use
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- Diagnostic Centers
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leading with Strong Adoption and Advanced Infrastructure
North America holds 39% share of the global Disposable Ureteroscope Market, supported by early technology adoption and high procedural volume. The United States dominates the regional landscape with a well-established healthcare infrastructure and growing demand for minimally invasive urology solutions. It benefits from strong reimbursement frameworks and high awareness of infection control standards. Technological advancements in digital imaging and flexible scopes further drive product utilization. Canada also contributes to steady market expansion through government-backed healthcare modernization. Growing investments in hospital upgrades and outpatient surgical centers continue to reinforce regional dominance.
Europe Expanding Through Infection Control and Technological Integration
Europe accounts for 27% share of the global market, driven by increasing focus on patient safety and hygiene compliance. Countries such as Germany, the United Kingdom, and France are leading adopters of disposable ureteroscopes across both public and private hospitals. It gains traction from EU-supported initiatives encouraging single-use medical device utilization to prevent cross-contamination. Continuous R&D investment by European manufacturers strengthens the competitive environment. Demand for flexible and digital scopes is expanding across smaller clinics and ambulatory centers. Growth in day-care surgical procedures further supports market penetration throughout the region.
Asia Pacific Emerging as the Fastest-Growing Regional Market
Asia Pacific represents 23% share of the global market and is expected to record the highest growth rate through 2032. Rapid urbanization, increasing healthcare expenditure, and rising kidney stone prevalence drive demand for advanced urology devices. It benefits from expanding hospital networks and rising medical tourism in countries such as India, China, and Thailand. Government initiatives promoting modern surgical technologies support adoption in public healthcare facilities. Local production capabilities and cost-effective imports enhance product accessibility. The region’s growing focus on minimally invasive procedures continues to strengthen its global market position.
Key Player Analysis:
- Boston Scientific Corporation
- Richard Wolf GmbH
- Olympus Corporation
- FUJIFILM Holdings Corporation
- Karl Storz GmbH
- Smith & Nephew Inc.
- PENTAX Medical
- Elmed Electronics & Medical Systems S.A.
- Dornier MedTech
- OPCOM
- MD
Competitive Analysis:
The Disposable Ureteroscope Market features strong competition among global medical device manufacturers focused on innovation, cost-efficiency, and procedural safety. Key players include Boston Scientific Corporation, Richard Wolf GmbH, Olympus Corporation, FUJIFILM Holdings Corporation, and Karl Storz GmbH. It emphasizes continuous product development to enhance imaging quality, maneuverability, and sterilization-free operation. Leading companies are investing in digital integration, single-use fiber technology, and ergonomic designs to strengthen clinical adoption. Strategic partnerships and distribution expansions support penetration in emerging healthcare markets. The competition is marked by efforts to balance affordability and high performance while maintaining regulatory compliance across regions.
Recent Developments:
- In October 2025 Boston Scientific Corporation announced an agreement to acquire Nalu Medical, Inc. to enhance its neuromodulation device portfolio for chronic pain therapy.
- In September 2025, Olympus Corporation revealed a new distribution partnership with MacroLux Medical to deliver single-use urology products to global markets.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application, End Use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Growing preference for minimally invasive and infection-free urological procedures will continue to drive market expansion.
- Integration of high-definition digital imaging and wireless visualization systems will improve procedural accuracy and efficiency.
- Manufacturers will focus on developing recyclable and biodegradable materials to address environmental concerns.
- Rising healthcare investments in emerging economies will enhance product accessibility and adoption.
- Hospitals and ambulatory surgical centers will increase the use of single-use scopes to reduce sterilization costs.
- Partnerships between medical device firms and healthcare providers will support large-scale procurement and technology integration.
- Continuous innovation in flexible ureteroscope design will improve ergonomics and ease of navigation during surgeries.
- Regulatory approvals for sustainable manufacturing practices will strengthen the position of leading market players.
- Training programs and workshops for surgeons will accelerate the transition toward disposable endoscopic devices.
- It will evolve into a cost-efficient and sustainable solution, becoming a standard tool in modern urology practice.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Disposable Ureteroscope Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Disposable Ureteroscope Market projected to grow between 2024 and 2032?
Which Disposable Ureteroscope Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Disposable Ureteroscope Market?
Who are the leading companies in the Disposable Ureteroscope Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.36 billion → 2032: USD 4.24 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Disposable Ureteroscope Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Disposable Ureteroscope Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Disposable Ureteroscope Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Disposable Ureteroscope Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Disposable Ureteroscope Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Disposable Ureteroscope Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Disposable Ureteroscope Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Disposable Ureteroscope Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.36 billion → 2032: USD 4.24 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Disposable Ureteroscope Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Disposable Ureteroscope Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Disposable Ureteroscope Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Disposable Ureteroscope Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

