
Market Overview:
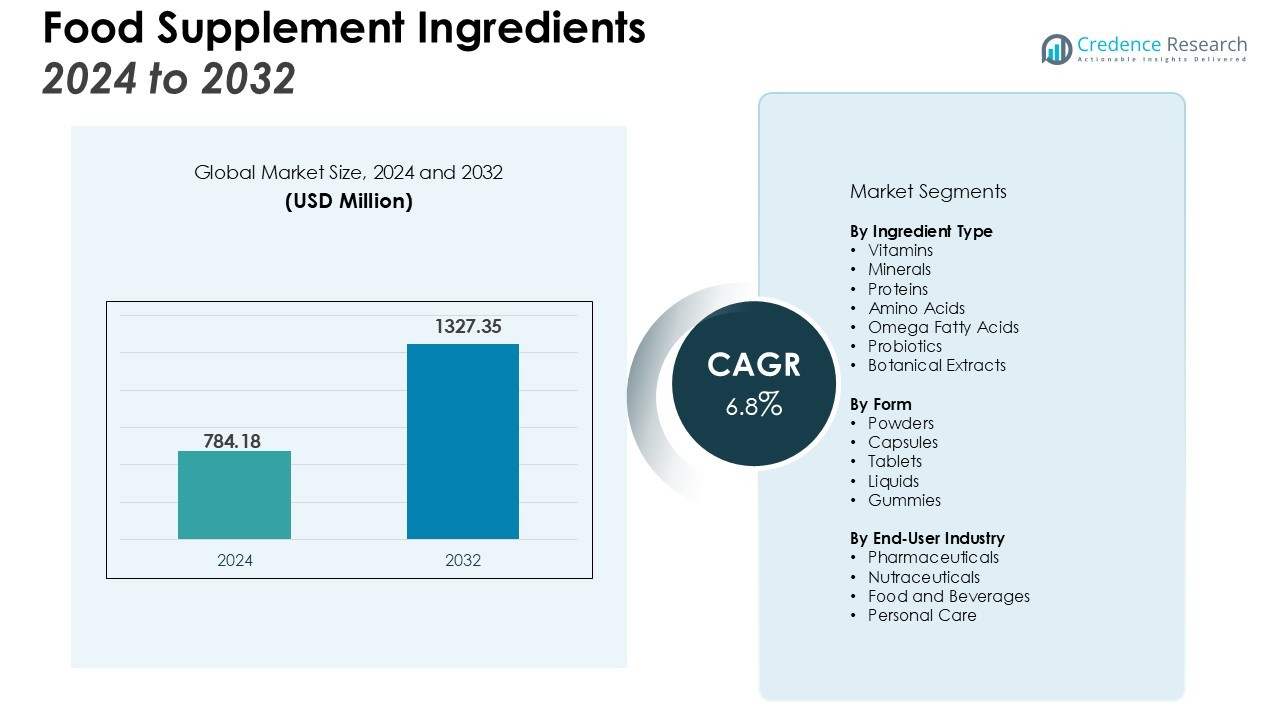
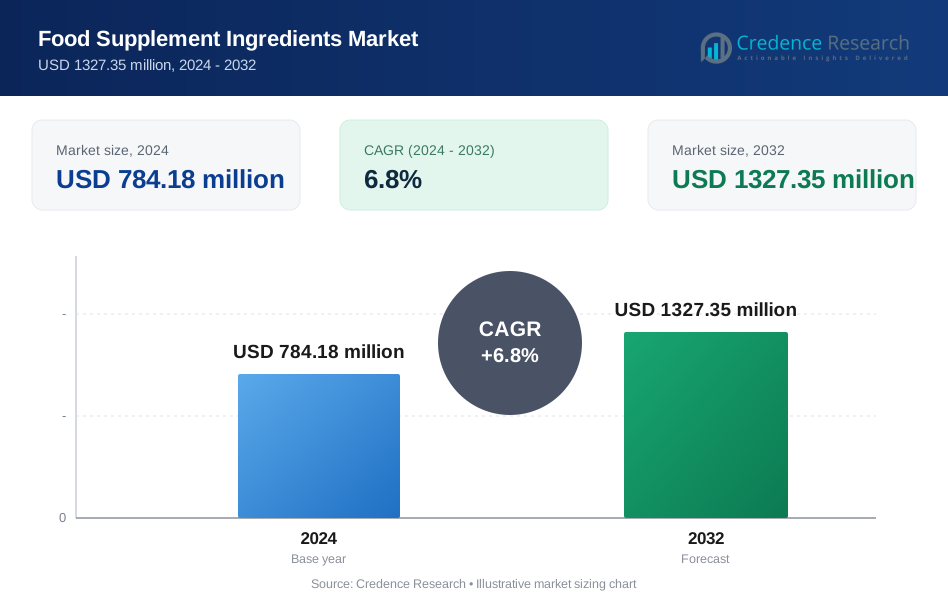
The Food Supplement Ingredients Market size was valued at USD 784.18 million in 2024 and is anticipated to reach USD 1327.35 million by 2032, at a CAGR of 6.8% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Food Supplement Ingredients Market Size 2024 | USD 784.18 Million |
| Food Supplement Ingredients Market, CAGR | 6.8% |
| Food Supplement Ingredients Market Size 2032 | USD 1327.35 Million |
Growth is driven by rising health consciousness and preventive healthcare awareness. Increasing prevalence of lifestyle-related conditions such as obesity, diabetes, and cardiovascular diseases encourages consumers to seek supplements enriched with vitamins, minerals, proteins, and omega fatty acids. Regulatory support for clean-label and natural ingredients also accelerates innovation in product formulations. Additionally, e-commerce expansion broadens product accessibility, enabling manufacturers to capture diverse consumer bases.
Regionally, North America leads the market due to high supplement consumption, well-established healthcare awareness, and robust product innovation. Europe follows, supported by strict regulatory frameworks and growing demand for natural ingredients. Asia-Pacific is expected to register the fastest growth, fueled by rapid urbanization, a rising middle-class population, and increasing investments in nutraceutical manufacturing. This regional momentum highlights strong opportunities for ingredient suppliers and supplement brands worldwide.
Market Insights:
- The Food Supplement Ingredients Market size was USD 784.18 million in 2024 and will reach USD 1327.35 million by 2032, registering a CAGR of 6.8%.
- Rising health consciousness and preventive healthcare awareness fuel demand for supplements enriched with vitamins, minerals, proteins, and omega fatty acids.
- Increasing preference for natural, plant-based, and clean-label products drives reformulation efforts and supports strong consumer trust.
- E-commerce platforms expand global accessibility, with direct-to-consumer models enhancing engagement and personalized product adoption.
- Strict regulations and compliance requirements challenge smaller players, creating higher operational costs and longer approval cycles.
- North America leads with 38% share due to high supplement adoption, innovation, and FDA-backed regulatory trust.
- Asia-Pacific, holding 24% share, is the fastest-growing region, supported by urbanization, middle-class expansion, and strong nutraceutical investments.
Market Drivers:
Rising Focus on Preventive Healthcare and Wellness
The Food Supplement Ingredients Market benefits from growing awareness of preventive healthcare. Consumers are actively choosing supplements to support immunity, mental well-being, and long-term vitality. The rise in chronic diseases has strengthened the role of dietary supplements in daily routines. Companies highlight scientifically backed formulations to meet this rising demand. The trend reinforces the importance of nutrition-driven health management.
- For instance, Natural Alternatives International, Inc. announced that its TriBsyn™ beta-alanine complex increased plasma beta-alanine levels 4.5-fold compared to conventional beta-alanine supplements in a clinical trial.
Increased Demand for Natural and Clean-Label Products
The Food Supplement Ingredients Market is expanding with a shift toward natural and clean-label solutions. Consumers prefer plant-based, organic, and chemical-free ingredients that align with healthier lifestyles. It drives manufacturers to reformulate supplements with minimal additives and transparent labeling. Regulatory approvals for natural extracts further strengthen trust among buyers. The market is witnessing strong innovation in botanical and functional ingredients.
E-Commerce Growth and Wider Consumer Access
The Food Supplement Ingredients Market gains momentum through online retail channels and digital platforms. E-commerce improves access to diverse products, enabling global reach for suppliers. It also provides consumers with tailored choices supported by data-driven recommendations. Direct-to-consumer models strengthen engagement and build trust through transparency. Expanding digital distribution supports faster adoption of supplement-based health routines.
- For instance, Amway, a key player in the direct-to-consumer model, empowers a network of over 1 million Independent Business Owners globally, enhancing consumer access to its nutritional products through a robust e-commerce platform.
Technological Advancements in Ingredient Development
The Food Supplement Ingredients Market advances with innovations in bioavailability and formulation technology. It allows manufacturers to deliver enhanced nutrient absorption and targeted health benefits. Controlled-release systems and microencapsulation techniques increase the effectiveness of supplements. The industry invests in R&D to differentiate product offerings with clinical validation. Technology-driven innovation shapes competitive advantage and strengthens market growth potential.
Market Trends:
Growing Popularity of Personalized Nutrition and Functional Formulations
The Food Supplement Ingredients Market is witnessing strong growth through the adoption of personalized nutrition. Consumers seek products tailored to specific health needs, such as weight control, digestive health, or cognitive performance. It reflects the shift toward individualized wellness solutions supported by genetic testing and lifestyle assessments. Brands invest in functional ingredients like probiotics, adaptogens, and plant proteins to create targeted formulations. Evolving consumer preferences drive companies to integrate advanced research with innovative product design. The trend supports the premiumization of supplements, encouraging higher spending on specialized health solutions.
- For instance, the personalized wellness company InsideTracker utilizes a sophisticated algorithm that analyzes up to 48 blood biomarkers.
Expansion of Plant-Based and Sustainable Ingredient Portfolios
The Food Supplement Ingredients Market is shaped by rising demand for plant-based and sustainable ingredient choices. Consumers increasingly prefer supplements made from natural extracts, algae, and alternative proteins. It aligns with global priorities for environmental responsibility and ethical sourcing. Companies respond with investments in eco-friendly processes, recyclable packaging, and supply chain transparency. The emphasis on sustainability extends to the development of bio-based vitamins and mineral blends. Industry players strengthen market positioning by offering products that combine health benefits with environmental responsibility. The trend accelerates global adoption of supplement ingredients aligned with clean living and responsible consumption.
- For instance, IFF showcased its commitment to plant-based innovation at Vitafoods™ Europe 2025 by presenting a portfolio of at least 7 distinct dietary supplement ingredients, including advanced solutions like SeaGel®, a plant-derived alternative for vegan softgels.
Market Challenges Analysis:
Stringent Regulatory Frameworks and Compliance Issues
The Food Supplement Ingredients Market faces challenges due to strict regulations and evolving compliance standards. Authorities enforce rigorous quality checks, labeling requirements, and safety assessments that delay product launches. It creates barriers for smaller players with limited resources to manage approvals. Frequent changes in global regulations increase operational complexity and raise compliance costs. The market must balance innovation with adherence to legal frameworks. Delays in approvals restrict the speed of introducing novel ingredients and formulations.
Rising Raw Material Costs and Supply Chain Disruptions
The Food Supplement Ingredients Market is challenged by fluctuating raw material prices and supply chain instability. Volatility in agricultural production, energy costs, and global trade tensions increases pressure on ingredient sourcing. It impacts pricing strategies and profit margins for manufacturers. Unstable supply chains also cause shortages that limit product availability across regions. Companies are required to secure long-term partnerships and diversify suppliers to reduce risk. These cost pressures affect both large-scale producers and emerging market participants.
Market Opportunities:
Expansion in Emerging Economies with Rising Health Awareness
The Food Supplement Ingredients Market presents strong opportunities in emerging economies driven by increasing consumer health awareness. Rising disposable incomes and urbanization encourage greater adoption of dietary supplements. It supports demand for vitamins, minerals, and functional ingredients tailored to regional health needs. Governments in Asia-Pacific, Latin America, and Africa promote preventive healthcare, boosting supplement acceptance. Local players and global brands expand presence through affordable product lines. Strategic collaborations with healthcare providers enhance consumer trust and adoption in these markets.
Innovation Through Advanced Formulations and Bioavailability Solutions
The Food Supplement Ingredients Market creates opportunities through innovations that improve nutrient delivery and absorption. It enables manufacturers to differentiate products with enhanced effectiveness. Developments in microencapsulation, controlled-release systems, and biotechnology offer new possibilities for functional ingredients. Companies invest in research to combine scientific validation with consumer-friendly formats such as gummies, powders, and fortified beverages. Rising demand for personalized nutrition further accelerates innovation. This trend positions technologically advanced suppliers to capture greater market share and strengthen competitiveness.
Market Segmentation Analysis:
By Ingredient Type
The Food Supplement Ingredients Market is segmented into vitamins, minerals, proteins, amino acids, omega fatty acids, probiotics, and botanical extracts. Vitamins and minerals hold a significant share due to their essential role in preventive healthcare and disease management. Proteins and amino acids witness strong demand from sports nutrition and weight management segments. Omega fatty acids and probiotics gain traction with growing interest in cardiovascular and digestive health. Botanical extracts expand with rising adoption of plant-based supplements supported by clean-label demand.
- For instance, in a 2015 in-vitro study, Melaleuca's proprietary amino acid-oligosaccharide complex used for its mineral supplements demonstrated a 4.4-fold increase in the bioavailability of zinc compared to inorganic mineral forms.
By Form
The market is categorized into powders, capsules, tablets, liquids, and gummies. Powders and capsules dominate due to convenience and higher stability in nutrient delivery. Tablets continue to serve traditional demand across pharmacies and retail outlets. Liquids cater to children and elderly consumers who require easy-to-consume formats. Gummies show rapid growth, driven by consumer preference for flavored, functional, and innovative delivery options. It reflects the diversification of supplement formats tailored to modern lifestyles.
By End-User Industry
The market serves pharmaceuticals, nutraceuticals, food and beverages, and personal care. Nutraceuticals represent the leading segment, fueled by consumer demand for preventive health solutions. Pharmaceuticals adopt supplement ingredients to support therapeutic formulations and strengthen recovery. The food and beverage sector integrates fortified ingredients into functional foods and drinks. Personal care applications expand through supplements focused on skin health, beauty, and anti-aging benefits. Each end-user sector enhances market scope through targeted applications.
- For instance, in 2023, Ausnutria launched its Probiotics Industrialization Production Demonstration Line, a smart factory capable of producing 33 probiotic powder variations in 8 types annually for the nutraceutical and food sectors.
Segmentations:
By Ingredient Type
- Vitamins
- Minerals
- Proteins
- Amino Acids
- Omega Fatty Acids
- Probiotics
- Botanical Extracts
By Form
- Powders
- Capsules
- Tablets
- Liquids
- Gummies
By End-User Industry
- Pharmaceuticals
- Nutraceuticals
- Food and Beverages
- Personal Care
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Leading with High Supplement Adoption and Innovation
North America accounted for 38% share of the Food Supplement Ingredients Market in 2024. The region holds dominance supported by high consumer awareness and strong adoption of preventive healthcare. It benefits from advanced research capabilities and frequent product launches by established nutraceutical companies. The market is strengthened by robust distribution networks across retail, pharmacies, and digital platforms. Regulatory support from the FDA ensures product quality and safety, which builds consumer confidence. Rising demand for clean-label and plant-based supplements further drives innovation in ingredient sourcing.
Europe Strengthened by Regulatory Standards and Natural Ingredient Demand
Europe captured 29% share of the Food Supplement Ingredients Market in 2024. It is shaped by strict regulatory frameworks that ensure quality and transparency across dietary supplements. The region benefits from a mature consumer base seeking natural, organic, and sustainable ingredients. Countries such as Germany, the UK, and France are key contributors, driven by high demand for functional nutrition. European companies invest in research and collaborate with health organizations to validate product claims. Distribution through pharmacies and specialty health stores supports consistent growth across the region.
Asia-Pacific Emerging as the Fastest-Growing Regional Market
Asia-Pacific represented 24% share of the Food Supplement Ingredients Market in 2024. It is expanding rapidly with rising health awareness and growing middle-class populations across key economies. Growth is fueled by increasing investments in nutraceutical manufacturing and supportive government policies promoting preventive healthcare. China, India, and Japan represent major markets with high supplement consumption across vitamins, minerals, and herbal products. Local and international players expand through affordable product lines and e-commerce platforms. Rising urbanization and lifestyle changes further boost supplement adoption among younger demographics.
Key Player Analysis:
- Nutralliance (U.S.)
- DSM Nutritional Products AG (Switzerland)
- BASF SE (Germany)
- Kerry Group (Ireland)
- Archer Daniels Midland Company (ADM) (U.S.)
- Lonza Group (Switzerland)
- Cargill, Incorporated (U.S.)
- International Flavors & Fragrances Inc. (U.S.)
- Glanbia Nutritionals (Ireland)
- ABF Ingredients (U.K.)
Competitive Analysis:
The Food Supplement Ingredients Market is highly competitive with global and regional players focusing on innovation, partnerships, and regulatory compliance to strengthen their positions. Leading companies such as BASF SE, DSM Nutritional Products, Kerry Group, Archer Daniels Midland Company, and DuPont de Nemours invest heavily in research to develop advanced formulations that improve bioavailability and product differentiation. It emphasizes clean-label, plant-based, and sustainable ingredients to meet evolving consumer preferences. Regional firms expand through cost-effective offerings and localized supply chains, enhancing accessibility in emerging economies. Strategic mergers, acquisitions, and collaborations support portfolio expansion and geographic reach. Intense competition drives continuous innovation, with companies aligning closely to health trends, regulatory frameworks, and consumer demand for transparent labeling. This competitive landscape highlights a balance between global corporations with strong R&D capabilities and regional players that offer tailored solutions to niche markets.
Recent Developments:
- In September 2025 dsm-firmenich launched the next generation of Dairy Safe™ all-in-one cultures for various cheese varieties.
- In October 2025 BASF launched "xarvio® HEALTHY FIELDS for RiTA" in Japan, a yield guarantee service for rice farmers.
Report Coverage:
The research report offers an in-depth analysis based on Ingredient Type, Form, End-User Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Food Supplement Ingredients Market will experience strong growth driven by rising health awareness.
- Demand for personalized nutrition will expand, supported by genetic testing and lifestyle-based solutions.
- Plant-based and sustainable ingredients will gain wider adoption as consumers prioritize eco-friendly choices.
- E-commerce will remain a key distribution channel, with direct-to-consumer models enhancing accessibility.
- Technological advances in bioavailability and controlled-release systems will shape next-generation formulations.
- Partnerships between ingredient manufacturers and healthcare providers will strengthen consumer trust and product adoption.
- Pharmaceutical and nutraceutical companies will integrate functional ingredients into therapeutic and preventive health solutions.
- Emerging economies in Asia-Pacific and Latin America will offer significant opportunities through rising disposable incomes.
- Regulatory frameworks will continue to evolve, encouraging quality compliance while challenging smaller market entrants.
- Continuous R&D investment will drive differentiation, positioning innovation as the core of competitive advantage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Food Supplement Ingredients Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Food Supplement Ingredients Market projected to grow between 2024 and 2032?
Which Food Supplement Ingredients Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Food Supplement Ingredients Market?
Who are the leading companies in the Food Supplement Ingredients Market?
Which region commanded the largest share of the Food Supplement Ingredients Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Food Supplement Ingredients Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Food Supplement Ingredients Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 784.18 million → 2032: USD 1327.35 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Food Supplement Ingredients Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Food Supplement Ingredients Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Food Supplement Ingredients Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Food Supplement Ingredients Market Drivers
- 3.3 Food Supplement Ingredients Market Restraints & Challenges
- 3.4 Food Supplement Ingredients Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Food Supplement Ingredients Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Food Supplement Ingredients Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Food Supplement Ingredients category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Food Supplement Ingredients Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Food Supplement Ingredients Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Food Supplement Ingredients. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Food Supplement Ingredients Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Food Supplement Ingredients Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Food Supplement Ingredients Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Food Supplement Ingredients (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Food Supplement Ingredients
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Food Supplement Ingredients Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Food Supplement Ingredients Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Food Supplement Ingredients Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Food Supplement Ingredients Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Food Supplement Ingredients Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Food Supplement Ingredients Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Food Supplement Ingredients Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Food Supplement Ingredients Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
