
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Lens Cleaning Tissues Market Size 2024 | USD 13974 million |
| Lens Cleaning Tissues Market, CAGR | 3.5% |
| Lens Cleaning Tissues Market Size 2032 | USD 18401 million |
Market Overview:
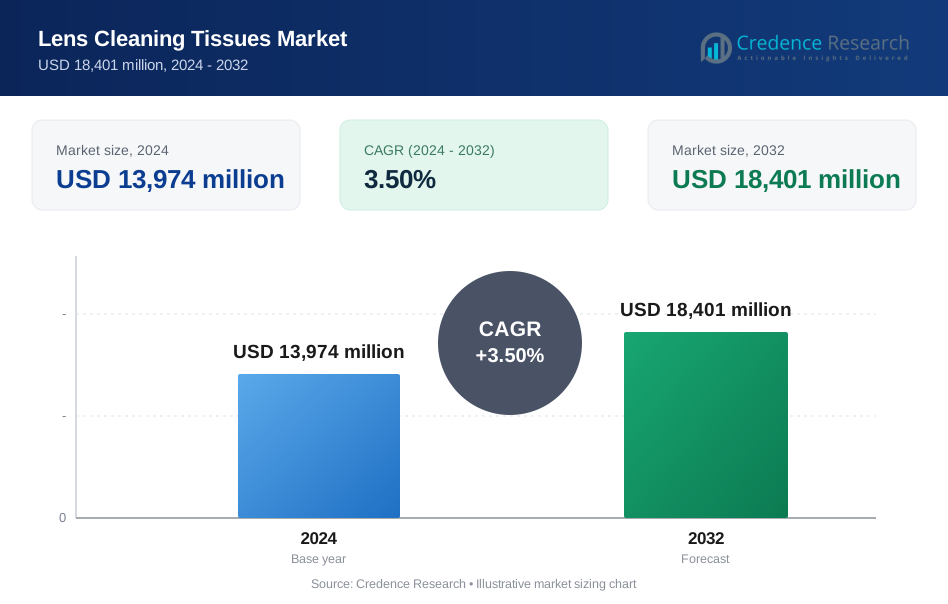
Lens Cleaning Tissues Market size was valued at USD 13974 million in 2024 and is anticipated to reach USD 18401 million by 2032, at a CAGR of 3.5% during the forecast period (2024-2032).
Several key factors are propelling the growth of the lens cleaning tissues market. First, the widespread use of digital devices such as cameras, eyeglasses, microscopes, and smartphones has increased the need for effective and safe lens maintenance solutions. Lens cleaning tissues, offering anti-static and streak-free properties, are becoming a preferred choice among users for regular cleaning and maintenance. Second, the growing emphasis on professional-grade optical equipment cleanliness, particularly in healthcare, research labs, and industrial applications, is boosting institutional demand. In addition, heightened hygiene consciousness post-pandemic has accelerated the use of disposable lens wipes in both personal and professional settings. Product innovations, such as biodegradable and alcohol-free formulations, are further enhancing market appeal among environmentally conscious consumers. Furthermore, the increasing availability of lens cleaning tissues through e-commerce platforms is making them more accessible to a wider customer base. Brand differentiation based on packaging, tissue quality, and added features such as anti-fog or anti-bacterial coatings is also intensifying competition among manufacturers.
Regionally, North America dominates the global lens cleaning tissues market, accounting for the largest revenue share due to strong demand from the consumer electronics and healthcare sectors. The region benefits from well-established distribution channels and the presence of major optical retailers and pharmacies. Europe follows closely, supported by high optical product penetration and strong consumer awareness regarding lens care. Stringent EU regulations related to product safety and environmental sustainability are also driving the adoption of eco-friendly tissue options. The Asia-Pacific region is poised for the fastest growth, driven by rapid urbanization, expanding middle-class populations, and increasing adoption of smartphones and eyewear. Rising investments in healthcare infrastructure and growing sales of optical accessories in countries such as China and India are further contributing to regional market expansion.
Market Insights:
- The Lens Cleaning Tissues Market was valued at USD 13,974 million in 2024 and is expected to reach USD 18,401 million by 2032, growing at a CAGR of 3.5% during the forecast period.
- Growing usage of smartphones, cameras, eyeglasses, and microscopes is driving steady demand for lens cleaning tissues that ensure clear, scratch-free surfaces for optimal device performance.
- The market benefits from institutional demand across healthcare, research, and industrial settings, where maintaining the cleanliness of optical instruments is critical to operational accuracy.
- Environmentally conscious consumers are increasingly opting for biodegradable and alcohol-free tissues, prompting brands to innovate with sustainable materials and packaging.
- North America leads the global market with 32% share due to advanced healthcare and retail infrastructure, while Asia-Pacific, with 26% share, records the fastest growth amid rising device adoption and urbanization.
- The rise of e-commerce platforms and direct-to-consumer sales models is enhancing market accessibility, enabling users to compare features, access reviews, and make informed purchases.
- Market players face challenges from pricing pressure, private label competition, and evolving compliance standards, pushing manufacturers to invest in product quality and differentiation strategies.
Market Drivers:
Increasing Demand for Precision in Optical and Electronic Device Maintenance
The Lens Cleaning Tissues Market experiences strong growth due to rising demand for precision in cleaning optical and electronic devices. Consumers and professionals require spotless, scratch-free lenses for cameras, eyeglasses, microscopes, and smartphones to ensure optimal performance and longevity. This need extends across industries such as healthcare, photography, and scientific research, where clear vision and accuracy are critical. It drives manufacturers to develop specialized tissues that deliver effective cleaning without leaving residue or causing abrasion. The heightened awareness of proper lens care fuels market expansion, encouraging innovation in both product formulation and packaging. Companies respond by offering convenient, portable solutions tailored to diverse user requirements.
Advancements in Material Science and Product Innovation
Continuous advancements in material science significantly influence the Lens Cleaning Tissues Market. Manufacturers invest in research to create tissues that combine softness, strength, and absorbency, ensuring safe use on delicate surfaces. The development of lint-free, anti-static, and anti-fog properties enhances product appeal and performance. It encourages brand differentiation and customer loyalty, as users seek reliable solutions for maintaining optical clarity. Product innovation also extends to packaging, with individually wrapped tissues and compact dispensers gaining popularity. These improvements reflect a commitment to meeting evolving consumer expectations and maintaining a competitive edge.
- For instance, Bausch + Lomb Sight Savers Lens Cleaning Tissues are anti-fog, anti-static, silicone-free, and come individually wrapped with 100 pre-moistened tissues per box, each measuring 5" x 8", and the box can be used as a gravity-feed dispenser for added convenience.
Emphasis on Sustainability and Eco-Friendly Manufacturing Practices
Sustainability emerges as a key driver in the Lens Cleaning Tissues Market, with consumers increasingly favoring eco-friendly options. Companies respond by adopting biodegradable materials and reducing plastic use in packaging. Regulatory pressures and growing environmental awareness prompt manufacturers to prioritize green initiatives throughout the production process. It enables brands to appeal to environmentally conscious buyers and comply with global sustainability standards. The shift toward sustainable products not only addresses ecological concerns but also opens new market opportunities among consumers seeking responsible choices.
- For instance, Wipe N Clear Biodegradable Lens Wipes by Flents are individually wrapped, made from 100% recycled, wood pulp-based material, use vegetable-based inks, and are fully biodegradable, providing a cleaner and softer wipe for users.
Expansion of Online Retail and Direct-to-Consumer Sales Channels
The rapid expansion of online retail channels transforms the distribution landscape for the Lens Cleaning Tissues Market. E-commerce platforms allow consumers to conveniently access a wide range of products, compare features, and read reviews before making informed purchases. Direct-to-consumer sales models enable manufacturers to build stronger relationships with customers and gather valuable feedback for product improvement. It supports increased market penetration and brand visibility, especially in regions with growing digital adoption. The convenience and accessibility of online shopping continue to drive sales growth, reshaping traditional retail dynamics and supporting the market’s upward trajectory.
Market Trends:
Shift Toward Sustainable Materials and Eco-Conscious Consumer Preferences
The Lens Cleaning Tissues Market displays a clear trend toward sustainable materials and environmentally responsible manufacturing. Consumers increasingly seek products made from biodegradable fibers and recyclable packaging, reflecting heightened environmental awareness. It prompts manufacturers to reformulate products, reduce plastic content, and adopt greener production processes. Brands that emphasize eco-friendly attributes gain a competitive advantage and attract a broader customer base. Regulatory pressures further accelerate the adoption of sustainable practices across the industry. The market now features a wider range of plant-based and compostable tissues, aligning with global sustainability goals and shifting consumer values.
- For instance, Bausch + Lomb’s recycling programs, ONE by ONE and Biotrue Eye Care Recycling, have collectively recycled 41,358,603 units of lens care materials as of November 2021, demonstrating a large-scale commitment to circular economy principles.
Integration of Advanced Features and Premiumization of Product Offerings
Product innovation stands out as a defining trend in the Lens Cleaning Tissues Market, with manufacturers introducing advanced features to meet evolving user expectations. It includes the development of anti-fog, anti-static, and streak-free formulations that enhance cleaning performance. Premium packaging and individually wrapped tissues cater to consumer demand for convenience and hygiene. The market also sees a rise in multi-functional products designed for use on various optical devices, from cameras to smartphones and medical equipment. This trend drives differentiation and supports higher price points, reflecting a move toward premiumization within the industry. Brands leverage technological advancements to deliver superior cleaning solutions and reinforce customer loyalty.
Market Challenges Analysis:
Intense Price Competition and Market Saturation Impact Profit Margins
The Lens Cleaning Tissues Market faces significant challenges from intense price competition and market saturation. Numerous brands offer similar products, leading to limited differentiation and downward pressure on prices. It becomes difficult for manufacturers to maintain healthy profit margins while competing on cost. Private label and generic options further intensify competition, making it challenging for established brands to retain market share. Companies must invest in innovation and branding to stand out, which increases operational costs. This environment demands strategic pricing and continuous product development to sustain long-term growth.
- For instance, Bausch + Lomb’s Sight Savers® line offers a package of 100 pre-moistened, anti-fog, anti-static tissues, providing a tangible value proposition for customers seeking premium features in a saturated market.
Quality Assurance and Regulatory Compliance Present Ongoing Hurdles
Maintaining consistent product quality and adhering to evolving regulatory standards remain ongoing challenges for the Lens Cleaning Tissues Market. Stringent regulations on material safety, environmental impact, and packaging require significant investment in compliance and testing. It places added pressure on manufacturers to update processes and documentation regularly. Quality lapses can lead to customer dissatisfaction and reputational damage, especially in professional and healthcare settings. Smaller players may struggle to meet these requirements, limiting their ability to compete. The need for reliable supply chains and robust quality control systems is critical in addressing these industry hurdles.
Market Opportunities:
Expansion into Emerging Markets and Untapped Consumer Segments
The Lens Cleaning Tissues Market holds significant growth potential through expansion into emerging markets and untapped consumer segments. Rising disposable incomes and increasing adoption of optical devices in regions such as Asia-Pacific and Latin America create new demand for high-quality cleaning solutions. It enables manufacturers to introduce tailored products that address local needs and preferences. Educational campaigns about lens care can further stimulate market penetration in these regions. Companies that establish strong distribution networks and local partnerships can secure a competitive edge. The market’s global reach continues to widen as awareness and accessibility improve.
Product Diversification and Integration of Advanced Technologies
Opportunities for growth also arise from product diversification and the integration of advanced technologies. The Lens Cleaning Tissues Market can benefit from developing specialized tissues for various applications, including medical, industrial, and consumer electronics sectors. It encourages innovation in features such as anti-fog, anti-bacterial, and multi-surface compatibility. Collaborations with technology firms can lead to smart packaging or enhanced cleaning formulations. Brands that invest in research and development can capture new customer segments and command premium pricing. The evolving needs of consumers drive ongoing demand for differentiated and value-added products.
Market Segmentation Analysis:
By Product Type
The Lens Cleaning Tissues Market divides into wet and dry tissue segments. Wet tissues hold the largest share due to their effectiveness in removing smudges and oils quickly and safely from sensitive surfaces. It appeals to users who prioritize convenience and a streak-free finish, especially for high-value optical devices. Dry tissues remain popular among those who prefer a gentle, residue-free option or wish to combine them with separate cleaning solutions. Manufacturers continue to improve both types, focusing on softness, absorbency, and lint-free performance to address varied consumer preferences.
- For instance, Berkshire’s LT000125 large rectangular swab is specifically designed for cleaning small and confined areas in laboratory and optical environments, featuring a closed-cell polyurethane foam head for superior cleanliness and particle entrapment.
By Application
Market segmentation by application includes consumer electronics, medical devices, and professional optics. Consumer electronics dominate demand, reflecting the widespread use of smartphones, cameras, and laptops that require regular lens care. It benefits from the large and growing user base that values clear, undamaged screens and lenses. Medical devices form a robust segment, as strict hygiene and clarity requirements drive the need for sterile, high-quality cleaning tissues. Professional optics, such as photography and scientific equipment, require specialized solutions that deliver precision and reliability.
- For instance, the UCMSmartLine system can be configured with up to nine modules for sequential cleaning and rinsing, supporting the cleaning of thin-film coated parts and medical instruments in high-volume settings.
By Distribution Channel
Distribution channels comprise online retail, specialty stores, and supermarkets. Online retail leads the segment, driven by ease of access, product variety, and the ability to reach a broad customer base. It allows brands to interact directly with consumers and adapt quickly to feedback. Specialty stores attract professional users and enthusiasts seeking expert advice and advanced products. Supermarkets ensure widespread availability, catering to everyday consumers and supporting consistent sales volume across regions.
Segmentations:
By Product Type
- Wet Tissues
- Dry Tissues
- Pre-Moistened Wipes
- Microfiber Tissues
- Biodegradable Tissues
By Application
- Eyewear Lenses
- Camera Lenses
- Microscope Lenses
- Optical Instruments
- Mobile Device Screens
By Distribution Channel
- Supermarkets & Hypermarkets
- Optical Retail Stores
- Pharmacies & Drug Stores
- Online Retail
- Specialty Stores
By End-User
- Individual Consumers
- Hospitals & Clinics
- Laboratories
- Industrial Facilities
- Educational Institutions
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America and Europe Maintain Leadership with Innovation and High Consumer Awareness
North America accounts for 32% of the global Lens Cleaning Tissues Market, while Europe holds 28% of total sales. These regions continue to lead the market, driven by high consumer awareness and a strong culture of optical device usage. The presence of established brands and advanced retail infrastructure supports steady demand for premium cleaning solutions. It benefits from a consumer base that values product quality, safety, and sustainability. Regulatory standards in these regions encourage manufacturers to invest in eco-friendly materials and rigorous quality control. The market sees frequent product innovations, including anti-fog and anti-static features, catering to professional and personal users alike. Strong distribution networks and effective marketing strategies further reinforce regional dominance.
Asia-Pacific Emerges as a High-Growth Region with Expanding Consumer Base
Asia-Pacific holds a 26% share of the global Lens Cleaning Tissues Market, making it the fastest-growing region in this sector. Rising disposable incomes and rapid urbanization fuel demand for reliable cleaning products as adoption of smartphones, cameras, and other optical devices increases. It attracts both global and local manufacturers aiming to capture market share through affordable and innovative offerings. Government initiatives to promote digital literacy and healthcare infrastructure also contribute to market expansion. The region’s large population and evolving consumer preferences create opportunities for tailored product launches. Companies that invest in localized marketing and distribution gain a significant advantage in this dynamic environment.
Latin America and Middle East & Africa Present Emerging Opportunities
Latin America represents 8% of the global Lens Cleaning Tissues Market, while the Middle East & Africa account for 6%. These regions offer emerging opportunities, though growth remains moderate compared to other markets. Rising awareness of personal and professional optical care supports gradual market development. It faces challenges such as limited distribution channels and price sensitivity among consumers. Manufacturers that focus on affordability and educational outreach can accelerate adoption rates. Strategic partnerships with local distributors and retailers help improve product accessibility. The potential for growth increases as economic conditions stabilize and demand for optical devices rises across these regions.
Key Player Analysis:
- 3M Company
- Johnson & Johnson Vision Care, Inc.
- Canon Inc.
- Kimberly-Clark Corporation
- Fisher Scientific International, Inc.
- Carl Zeiss AG
- Thorlabs, Inc.
- PDI Healthcare
- Bausch & Lomb Incorporated
- Essilor International S.A.
- Parker Laboratories, Inc.
- VWR International, LLC
Competitive Analysis:
The Lens Cleaning Tissues Market features a mix of global and regional players competing on product quality, innovation, and pricing. Leading companies focus on developing lint-free, anti-static, and eco-friendly formulations to meet rising consumer expectations. It sees strong competition from private label brands and generic offerings, especially in cost-sensitive regions. Established brands leverage wide distribution networks and partnerships with optical retailers and healthcare providers to strengthen market presence. E-commerce platforms support increased visibility and direct-to-consumer engagement, allowing brands to differentiate through packaging and added features. Continuous investment in R&D enables manufacturers to introduce biodegradable and alcohol-free products that appeal to environmentally conscious buyers. Marketing strategies emphasize convenience, safety, and sustainability to build customer loyalty. The market remains fragmented, with small and medium enterprises competing alongside multinational firms. Competitive intensity is high, prompting players to focus on brand positioning, regulatory compliance, and product performance to maintain relevance and capture market share.
Recent Developments:
- In January 2025, Bausch + Lomb launched the enVista Aspire™ Intermediate Optimized Monofocal and Toric Intraocular Lenses in the European Union, following CE Mark approval. These IOLs offer enhanced depth of focus and stability for cataract patients.
- In June 2025, Kimberly-Clark announced a strategic partnership with Suzano to create a leading international tissue and professional products company.
- In January 2025, Bausch + Lomb launched the enVista Aspire™ Intermediate Optimized Monofocal and Toric Intraocular Lenses in the European Union, following CE Mark approval.
- In June 2025, Kimberly-Clark announced a strategic partnership with Suzano to create a leading international tissue and professional products company.
Market Concentration & Characteristics:
The Lens Cleaning Tissues Market exhibits moderate concentration with a blend of well-established global players and a wide base of regional manufacturers. It remains highly competitive due to low entry barriers and minimal capital requirements. Product standardization is limited, allowing brands to compete through quality, formulation, and packaging innovation. The market is characterized by frequent product launches, rising demand for biodegradable options, and strong price sensitivity in developing regions. It shows seasonal demand spikes driven by promotional campaigns and back-to-school or holiday shopping periods. Consumer preference for single-use, portable solutions influences product formats and distribution strategies. E-commerce and retail store presence play a critical role in brand visibility and customer reach. It continues to evolve with changing hygiene practices and environmental regulations, which shape product development and sourcing practices across all regions.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, Distribution Channel, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rapid adoption of biodegradable materials will align lens cleaning tissues with global sustainability standards while meeting consumer expectations.
- Integration of anti-fog and anti-bacterial properties will enhance functionality and expand use cases beyond traditional cleaning.
- Packaging innovations, such as individually wrapped wipes and resealable dispensers, will support portability and hygiene preferences.
- Expansion of online marketplaces will improve product visibility and support direct-to-consumer sales strategies.
- Collaborations with eyewear and camera manufacturers will create co-branded cleaning solutions and strengthen market penetration.
- Manufacturers will invest in eco-friendly production processes to comply with evolving environmental regulations.
- Enhanced quality control protocols will ensure consistency, reduce product returns, and enhance consumer trust.
- Rising demand from professional sectors-including healthcare, laboratories, and precision manufacturing-will drive bulk sales.
- Emerging markets in Asia-Pacific, Latin America, and the Middle East will attract new product launches targeting growing middle-class consumers.
- Real-time consumer feedback via digital channels will guide rapid iteration of product features and designs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Lens Cleaning Tissues Market
What are the key segments within the Lens Cleaning Tissues Market?
What are some challenges faced by the Lens Cleaning Tissues Market?
Who are the major players in the Lens Cleaning Tissues Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 13,974 million → 2032: USD 18,401 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lens Cleaning Tissues Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lens Cleaning Tissues Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lens Cleaning Tissues Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lens Cleaning Tissues Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lens Cleaning Tissues Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lens Cleaning Tissues Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lens Cleaning Tissues Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lens Cleaning Tissues Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 13,974 million → 2032: USD 18,401 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lens Cleaning Tissues Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lens Cleaning Tissues Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Lens Cleaning Tissues Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Lens Cleaning Tissues Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
