
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Toric Intraocular Lenses Market Size 2024 | USD 4,525.45 million |
| Toric Intraocular Lenses Market, CAGR | 5.5% |
| Toric Intraocular Lenses Market Size 2032 | USD 6,945.1 million |
Market Overview:
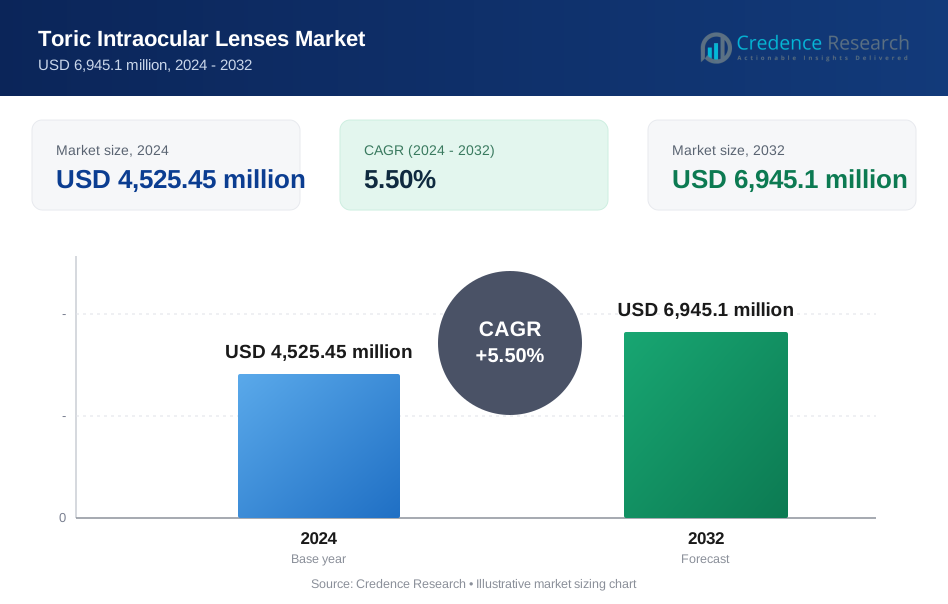
The global sales of Toric Intraocular Lenses (IOLs) are projected to grow from USD 4,525.45 million in 2024 to USD 6,945.1 million by 2032, registering a compound annual growth rate (CAGR) of 5.5% during the forecast period.
The Toric Intraocular Lens (IOLs) sales market is experiencing robust growth due to rising incidences of cataracts and astigmatism, particularly among the aging global population. Advancements in lens technology, such as enhanced precision in astigmatism correction and improved postoperative visual outcomes, are driving adoption. Patients increasingly prefer premium intraocular lenses for their ability to reduce dependence on glasses, supporting market expansion. The growing number of cataract surgeries performed worldwide, coupled with increased awareness of advanced vision correction options, further accelerates demand. Healthcare infrastructure improvements in emerging economies and favorable reimbursement policies in developed nations also contribute to market growth. Additionally, trends such as the adoption of minimally invasive surgical techniques and the integration of digital diagnostics and image-guided systems are enhancing surgical accuracy and patient outcomes. Key manufacturers are investing in product innovation and strategic partnerships with ophthalmic clinics to expand their reach, while increasing consumer demand for customized visual solutions continues to shape product development.
The Toric Intraocular Lens (IOLs) Sales market exhibits strong geographical presence across North America, Europe, and Asia Pacific. North America leads the market due to advanced surgical infrastructure and widespread adoption of premium IOLs, while Europe benefits from universal healthcare access and a growing geriatric population. Asia Pacific shows the fastest growth, driven by large patient pools, rising healthcare investments, and expanding surgical access. Key players operating in the global market include Alcon Inc., Johnson & Johnson Vision Care, Inc., Bausch + Lomb, Carl Zeiss Meditec AG, HOYA Corporation, STAAR Surgical Company, Rayner Intraocular Lenses Limited, PhysIOL SA, HumanOptics AG, Oculentis GmbH, SIFI S.p.A., and NIDEK Co., Ltd. These companies focus on innovation, training, and regional expansion to strengthen their market presence and meet the rising demand for advanced toric vision correction solutions across all major regions.
Market Insights:
- The global Toric IOLs market is projected to grow from USD 4,525.45 million in 2024 to USD 6,945.1 million by 2032, registering a CAGR of 5.5% during the forecast period.
- Rising cases of cataracts and astigmatism, particularly among aging populations, continue to drive strong demand for dual-correction Toric IOLs globally.
- Technological advancements in lens stability, alignment precision, and surgical techniques are improving outcomes and increasing surgeon confidence in premium lens use.
- Consumer preference for spectacle-free lifestyles is fueling demand for multifocal and EDOF Toric IOLs, particularly among active seniors and professionals.
- Emerging markets are witnessing rising adoption due to expanding healthcare infrastructure, public-private vision care programs, and medical tourism.
- Market growth faces constraints from high costs and limited insurance coverage, especially in developing regions where affordability impacts product accessibility.
- North America leads with 38% market share, followed by Europe at 27% and Asia Pacific at 22%, with the latter experiencing the fastest growth driven by large patient populations and rising healthcare investments.
Market Drivers:
Rising Prevalence of Cataracts and Astigmatism Boosts Market Demand:
The increasing incidence of cataracts and age-related eye disorders continues to drive the Toric Intraocular Lens (IOLs) Sales market. A large segment of the elderly population suffers from astigmatism alongside cataracts, prompting demand for corrective solutions. Toric IOLs offer dual correction, which makes them a preferred choice among ophthalmologists and patients. Growing life expectancy further increases the number of age-related surgeries, contributing to consistent market expansion. It aligns with the rising volume of cataract procedures performed globally. Healthcare providers are recommending premium lens options more frequently to improve patient satisfaction. This demographic shift strengthens the long-term outlook for the market.
- For instance, Johnson & Johnson Vision reported that their TECNIS Toric II IOL helped reduce postoperative spectacle dependence in 94% of patients with pre-existing astigmatism, according to a 2022 clinical study.
Technological Advancements in Lens Design Improve Clinical Outcomes:
Continuous innovations in lens design and surgical techniques have significantly enhanced the precision and outcomes of Toric IOL implantation. Modern lenses offer better rotational stability and accurate alignment, which are critical for effective astigmatism correction. These advancements contribute to fewer postoperative complications and improved patient satisfaction. Toric Intraocular Lens (IOLs) Sales benefit from the growing trust in technologically superior products. Manufacturers invest heavily in R&D to bring innovative designs that meet surgeon preferences and patient expectations. Surgeons favor lenses that offer ease of implantation and consistent visual acuity, further encouraging adoption. It fosters brand loyalty and repeat demand from healthcare providers.
- For instance, Bausch + Lomb’s enVista Toric IOL utilizes a glistening-free hydrophobic acrylic material, and real-world data from 2023 reported a 96% patient satisfaction rate due to improved visual acuity and minimal postoperative complications.
Increasing Consumer Preference for Spectacle-Free Vision Drives Adoption:
Patients today are more aware of their options and often seek solutions that minimize dependence on glasses after surgery. Toric IOLs address both cataract and refractive issues, offering greater visual freedom. The preference for spectacle-free lifestyles is particularly strong among active seniors and working professionals. It leads to growing acceptance of premium intraocular lenses, despite higher costs. Toric Intraocular Lens (IOLs) Sales reflect this shift in consumer expectations toward better quality of life. Clinics and surgical centers highlight these advantages during consultations, influencing patient choices. This consumer-driven trend supports steady market growth.
Improved Healthcare Infrastructure and Surgical Access in Emerging Markets:
Emerging economies are witnessing rapid improvements in ophthalmic care facilities, supported by public health programs and private investments. It enables more people to access advanced surgical options, including Toric IOLs. As affordability increases and awareness spreads, demand rises beyond urban centers. Toric Intraocular Lens (IOLs) Sales in these regions show upward trends driven by infrastructure development and training of specialized surgeons. Governments in Asia, Latin America, and the Middle East support vision care initiatives, enhancing market reach. Medical tourism also plays a role, attracting patients seeking cost-effective premium eye surgeries. These structural changes unlock new growth avenues for manufacturers.
Market Trends:
Growing Demand for Premium and Personalized Vision Correction Solutions:
Patients are increasingly seeking advanced intraocular lens solutions that provide enhanced visual outcomes and lifestyle convenience. This trend is driving interest in premium options like Toric IOLs, which address both cataracts and astigmatism. Individuals prefer customized solutions that offer clear distance and intermediate vision without requiring glasses. Toric Intraocular Lens (IOLs) Sales benefit from this shift toward higher-value lens segments. Surgeons are more inclined to recommend these lenses due to predictable outcomes and improved patient satisfaction. The market reflects a growing consumer willingness to invest in vision correction that aligns with active, spectacle-free lifestyles. It supports a broader trend toward individualized eye care.
- For instance, ZEISS continues to invest in research and development of advanced toric IOLs, introducing innovations in lens design and materials that provide predictable outcomes and support individualized eye care for patients seeking premium solutions.
Integration of Digital Surgical Planning Tools and Image-Guided Systems:
Surgeons now rely on advanced diagnostics and digital planning systems to enhance the precision of IOL alignment. These tools improve rotational accuracy and minimize residual astigmatism, which directly impacts patient outcomes. Clinics increasingly adopt image-guided technologies that support consistent, repeatable results. Toric Intraocular Lens (IOLs) Sales are supported by the availability of such surgical innovations. It increases surgeon confidence in offering premium lenses and enhances clinical workflow efficiency. These systems also assist in patient education, helping individuals understand the benefits of Toric IOLs. Integration of technology across surgical steps is becoming a key differentiator in clinical practice.
- For instance, Carl Zeiss Meditec’s Veracity Surgical platform integrates data from devices such as the IOLMaster biometer and corneal topographers, automatically importing measurements and calculations to streamline surgical planning and reduce manual data entry by 88%, as demonstrated in a study of 40 patients.
Rising Influence of Medical Tourism and Private Eye Clinics:
Medical tourism is expanding access to advanced eye care procedures, especially in regions with high-quality yet cost-effective services. Patients from developed markets travel to emerging economies for Toric IOL implantation, seeking affordability without compromising quality. Private clinics are capitalizing on this trend by offering packaged procedures and shorter waiting periods. Toric Intraocular Lens (IOLs) Sales grow in such regions due to competitive pricing and rising international patient volumes. It drives global competition among providers and manufacturers alike. This trend also encourages investment in localized manufacturing and distribution networks. Medical travel accelerates market globalization and patient choice.
Increased Marketing Focus on Visual Outcomes and Lifestyle Benefits:
Manufacturers and clinics now emphasize functional outcomes and lifestyle enhancements when promoting Toric IOLs. Marketing campaigns highlight the ability to restore sharp vision and reduce spectacle dependence. Patients respond positively to value-based messaging focused on quality of life rather than just clinical performance. Toric Intraocular Lens (IOLs) Sales are influenced by this patient-centric approach. It creates awareness across broader demographics, including younger cataract patients. Eye care providers tailor consultations to align with patient expectations, enhancing engagement and conversion. Marketing strategies are evolving to reflect real-world benefits over technical specifications.
Market Challenges Analysis:
High Cost and Limited Insurance Coverage Restrict Patient Access:
The premium pricing of Toric IOLs remains a significant barrier for many patients, especially in regions with limited reimbursement options. While the clinical benefits are well-established, out-of-pocket expenses discourage widespread adoption. Insurance plans in several countries exclude coverage for advanced IOLs, classifying them as elective upgrades. Toric Intraocular Lens (IOLs) Sales face resistance in cost-sensitive markets where affordability outweighs perceived benefits. It limits access to technologically superior products and widens the gap between public and private healthcare segments. This pricing disparity hampers market penetration in lower-income groups despite growing awareness. Addressing affordability challenges requires strategic pricing models and broader policy support.
- For instance, Cigna, a major U.S. insurer, classifies astigmatism-correcting IOLs as convenience items and excludes them from coverage in many of its health benefit plans, leaving patients responsible for the full expense.
Surgical Precision Requirements and Training Gaps Affect Outcomes:
Successful implantation of Toric IOLs depends on precise alignment and surgical expertise, which not all ophthalmic surgeons possess. Even minor rotational misalignment can compromise the lens's corrective effectiveness, leading to patient dissatisfaction. It creates hesitation among less-experienced surgeons to recommend or perform Toric IOL procedures. Toric Intraocular Lens (IOLs) Sales are influenced by the uneven distribution of skilled professionals, particularly in rural or underdeveloped healthcare systems. Limited access to training programs and advanced surgical tools further slows adoption. Manufacturers and institutions must invest in surgeon education and digital support systems to overcome this technical challenge. Bridging this skills gap is essential for sustained market growth.
Market Opportunities:
Expansion of Vision Care Services in Emerging Economies Presents Growth Potential:
Healthcare systems in emerging markets are evolving rapidly, creating new demand for advanced ophthalmic procedures. Rising incomes, improved awareness of eye health, and increasing cataract surgery volumes position these regions as high-potential growth areas. Governments are supporting vision care through national programs and public-private partnerships. Toric Intraocular Lens (IOLs) Sales are expected to grow in these regions where access to surgical care is expanding. It creates opportunities for manufacturers to introduce region-specific pricing and distribution strategies. Partnering with local clinics and investing in training programs can build long-term market presence. Early market entry in these regions can deliver strong competitive advantages.
Rising Demand for Minimally Invasive and Customized Vision Correction Solutions:
Global demand for personalized healthcare is creating space for tailored IOL solutions that offer improved comfort and post-surgical outcomes. Patients prefer procedures that reduce recovery time and eliminate the need for glasses. This preference aligns with innovations in lens design and surgical techniques that enhance convenience and precision. Toric Intraocular Lens (IOLs) Sales stand to benefit from this shift toward minimally invasive, lifestyle-enhancing solutions. It opens the door for premium product lines and bundled service offerings in private care settings. Companies that focus on patient-centric product design and service delivery will gain market share.
Market Segmentation Analysis:
By Product Type
Toric Monofocal IOLs hold a significant share due to their cost-effectiveness and consistent visual performance for distance correction. However, Toric Multifocal IOLs are gaining traction among patients seeking spectacle-free vision for both near and far distances. Toric Extended Depth of Focus (EDOF) IOLs are also emerging as a strong alternative, offering smoother visual transitions and reduced glare. The premium positioning of these lenses appeals to younger cataract patients and professionals. Toric Intraocular Lens (IOLs) Sales in the multifocal and EDOF categories are increasing, driven by lifestyle-focused demand and favorable clinical outcomes. It reflects the broader market trend toward customized vision correction.
By Material
Hydrophobic acrylic remains the dominant material due to its optical clarity, biocompatibility, and reduced risk of posterior capsule opacification. Hydrophilic acrylic lenses offer flexibility and easier handling, making them a popular alternative in certain surgical settings. Polymethylmethacrylate (PMMA) has limited usage due to its rigidity and older design characteristics. Toric Intraocular Lens (IOLs) Sales favor hydrophobic acrylic due to its performance consistency and surgeon preference. It continues to be the material of choice for most premium IOL manufacturers. Demand for next-generation materials with enhanced light-filtering or blue-light blocking features is also rising.
By End-User
Hospitals account for the largest share due to high patient turnover, advanced surgical infrastructure, and availability of trained ophthalmic surgeons. Ophthalmic clinics are expanding their footprint, offering specialized and personalized care that appeals to private-pay patients. Ambulatory Surgery Centers (ASCs) are growing in popularity for their cost-effectiveness and shorter patient recovery times. Toric Intraocular Lens (IOLs) Sales are increasing across all end-user segments, supported by rising cataract surgeries and growing awareness. It creates diverse opportunities for vendors to target both high-volume institutions and niche private providers. Demand across these settings reflects strong procedural growth and patient preference for premium care.
Segments:
Based on Product Type
- Toric Monofocal IOLs
- Toric Multifocal IOLs
- Toric Extended Depth of Focus IOLs
Based on Material
- Hydrophobic Acrylic
- Hydrophilic Acrylic
- Polymethylmethacrylate (PMMA)
- Others
Based on End-User
- Hospitals
- Ophthalmic Clinics
- Ambulatory Surgery Centers
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America leads the Toric Intraocular Lens (IOLs) Sales market with a 38% share, supported by advanced surgical infrastructure and a strong presence of global ophthalmic device manufacturers. The United States drives regional growth through high awareness of premium vision correction and favorable insurance coverage for cataract procedures. Patients increasingly prefer Toric IOLs to achieve spectacle-free outcomes, which supports the segment’s continued expansion. Surgeons in North America utilize digital imaging tools and precision-guided systems, improving clinical accuracy and patient satisfaction. It enables faster adoption of next-generation lenses. Canada contributes to the region’s performance with healthcare investments and steady procedural growth. The region remains a top market for innovation, clinical research, and product launches.
Europe
Europe accounts for 27% of global Toric Intraocular Lens (IOLs) Sales, with strong demand from countries such as Germany, France, and the United Kingdom. Universal healthcare systems, combined with an aging population, drive consistent cataract surgery volumes. Patients are open to premium lens options, even in markets with limited reimbursement for advanced IOLs. The region balances high-volume public hospitals with expanding private ophthalmic clinics offering specialized care. It supports market penetration across income segments and patient demographics. Medical tourism in Eastern Europe further contributes to demand. Manufacturers prioritize Europe for pilot programs, surgeon training, and regulatory approvals.
Asia Pacific
Asia Pacific holds a 22% share of the Toric Intraocular Lens (IOLs) Sales market and shows the fastest growth rate among all regions. High cataract prevalence, rising healthcare expenditure, and expanding access to eye surgeries contribute to market momentum. Countries such as China, India, Japan, and South Korea lead in procedural volume due to large populations and improving infrastructure. It creates strong opportunities for global and local manufacturers to introduce cost-effective, high-performance IOLs. Government programs, mobile surgery units, and rural outreach initiatives are expanding care access. Local players are entering the market with competitive pricing strategies, increasing product availability. The region’s growing middle class further supports demand for premium eye care solutions.
Key Player Analysis:
- SIFI S.p.A.
- PhysIOL SA
- HOYA Corporation
- STAAR Surgical Company
- Alcon Inc.
- Oculentis GmbH
- Rayner Intraocular Lenses Limited
- Johnson & Johnson Vision Care, Inc.
- Bausch + Lomb
- HumanOptics AG
- NIDEK Co., Ltd.
- Carl Zeiss Meditec AG
Competitive Analysis:
The Toric Intraocular Lens (IOLs) Sales market features strong competition among global and regional players focused on technological innovation, clinical performance, and surgeon engagement. Key companies such as Alcon Inc., Johnson & Johnson Vision Care, Inc., Bausch + Lomb, and Carl Zeiss Meditec AG lead with advanced product portfolios and strong distribution networks. It encourages ongoing investment in R&D, training programs, and digital surgery tools to maintain market share. Firms like STAAR Surgical Company, HOYA Corporation, and Rayner Intraocular Lenses Limited compete by offering cost-effective and customizable solutions. Emerging players including PhysIOL SA, HumanOptics AG, and SIFI S.p.A. are expanding through niche applications and regional partnerships. Strategic moves include product launches, geographic expansion, and collaborations with eye care institutions. Toric Intraocular Lens (IOLs) Sales are influenced by clinical reputation, innovation pipelines, and pricing flexibility. Competitive dynamics remain strong, with manufacturers racing to enhance surgical outcomes and improve patient satisfaction.
Recent Devlopments:
- In April 2025, Alcon Inc. announced the introduction of the Clareon® PanOptix® Pro intraocular lens (IOL) for cataract patients in the U.S., expanding its leadership in IOL innovation and planning additional market rollouts later in 2025.
- In September 2024, Rayner unveiled the world’s first spiral IOL, the RayOne Galaxy, and its toric variant at the ESCRS congress in Barcelona. Between October and December 2024, these lenses were available in a limited release to selected surgeons for further clinical evaluation.
- On January 15, 2025, Rayner announced the full commercial release of the RayOne Galaxy and RayOne Galaxy Toric IOLs, making them widely available globally (subject to local regulatory approval).
Market Concentration & Characteristics:
The Toric Intraocular Lens (IOLs) Sales market is moderately concentrated, with a few global players dominating through advanced product portfolios, strong distribution networks, and established surgeon relationships. It exhibits high entry barriers due to regulatory requirements, clinical validation needs, and the demand for surgical precision. Market characteristics include a strong focus on innovation, surgeon training, and patient-specific customization. Leading companies invest in research and collaborate with ophthalmic institutions to maintain technological leadership. The market favors firms with proven product performance, support infrastructure, and strategic partnerships. Growth is driven by increasing global cataract volumes and rising demand for premium vision correction solutions. It also reflects a growing shift toward digital surgery platforms, improving accuracy and patient satisfaction. Companies that integrate advanced diagnostics and offer post-surgical support are likely to gain competitive advantage. The market continues to evolve with advancements in biomaterials, rotational stability, and image-guided implantation technologies, which define the next phase of product differentiation.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Material, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for toric intraocular lenses will continue to rise due to the global increase in cataract and astigmatism cases.
- Patients will increasingly prefer premium IOLs that reduce dependence on corrective eyewear.
- Surgeons will adopt more digital planning tools to improve lens alignment and surgical precision.
- Manufacturers will focus on developing lenses with better rotational stability and visual outcomes.
- Emerging markets will contribute significantly to sales growth as healthcare access improves.
- Companies will invest more in surgeon training and education to expand procedural adoption.
- Reimbursement policies may evolve to include coverage for advanced toric lenses in more regions.
- Product innovation will shift toward offering personalized and lifestyle-enhancing vision solutions.
- Strategic collaborations with eye hospitals and clinics will help manufacturers strengthen market presence.
- Adoption of minimally invasive procedures will support faster recovery and patient satisfaction.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Toric Intraocular Lens (IOLs) Sales market?
What factors are driving the growth of the Toric Intraocular Lens (IOLs) Sales market?
What are some challenges faced by the Toric Intraocular Lens (IOLs) Sales market?
Who are the major players in the Toric Intraocular Lens (IOLs) Sales market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,525.45 million → 2032: USD 6,945.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Toric Intraocular Lenses Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Toric Intraocular Lenses Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Toric Intraocular Lenses Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Toric Intraocular Lenses Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Toric Intraocular Lenses Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Toric Intraocular Lenses Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Toric Intraocular Lenses Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Toric Intraocular Lenses Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,525.45 million → 2032: USD 6,945.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Toric Intraocular Lenses Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Toric Intraocular Lenses Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Toric Intraocular Lenses Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Toric Intraocular Lenses Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
