
Market Overview:
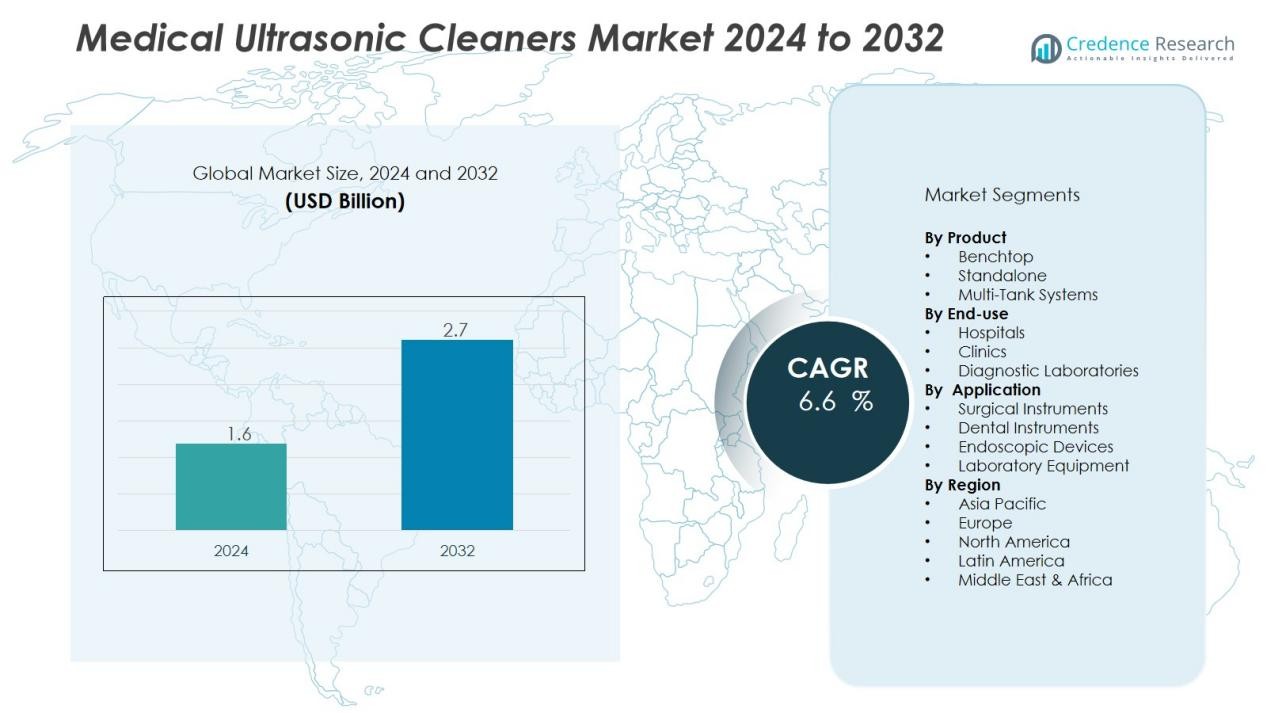
The medical ultrasonic cleaners market size was valued at USD 1.6 billion in 2024 and is anticipated to reach USD 2.7 billion by 2032, at a CAGR of 6.6 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Medical Ultrasonic Cleaners Market Size 2024 | USD 1.6 Billion |
| Medical Ultrasonic Cleaners Market, CAGR | 7.8% |
| Medical Ultrasonic Cleaners Market Size 2032 | USD 2.7 Billion |
Key market drivers include the growing prevalence of hospital-acquired infections (HAIs) and the rising emphasis on effective sterilization of surgical tools and instruments. Ultrasonic cleaners provide deep cleaning capabilities, reduce manual effort, and help healthcare facilities meet stringent regulatory standards. Expanding healthcare infrastructure, coupled with advancements in cleaning technologies such as digital controls and multi-frequency systems, further strengthens market adoption.
Regionally, North America dominates the medical ultrasonic cleaners market due to advanced healthcare systems, high procedural volumes, and strict compliance requirements. Europe follows with strong adoption driven by regulatory frameworks and expanding hospital networks. The Asia-Pacific region is projected to grow fastest, fueled by increasing healthcare investments, medical tourism, and rising awareness of infection control practices. Meanwhile, Latin America and the Middle East & Africa show gradual adoption, supported by infrastructure upgrades and growing focus on healthcare quality.
Market Insights:
- The medical ultrasonic cleaners market was valued at USD 1.6 billion in 2024 and is projected to reach USD 2.7 billion by 2032 at a CAGR of 6.6%.
- Rising prevalence of hospital-acquired infections drives strong demand for ultrasonic cleaners in healthcare facilities.
- Complex surgical instruments create higher need for advanced cleaning solutions, making ultrasonic systems essential.
- Stringent global sterilization and hygiene regulations increase adoption of ultrasonic cleaners to ensure compliance.
- Technological innovations such as digital controls and multi-frequency systems improve cleaning precision and efficiency.
- High initial costs and limited awareness in developing regions remain key barriers to wider adoption.
- North America leads with 38% share, followed by Europe at 29%, supported by strong healthcare systems.
- Asia-Pacific holds 23% share and is expected to grow fastest, driven by infrastructure investments and medical tourism.
Market Drivers:
Rising Need for Effective Infection Control in Healthcare Settings:
The medical ultrasonic cleaners market is strongly driven by the growing demand for effective infection control solutions. Hospitals and clinics face increasing pressure to reduce hospital-acquired infections, which can severely impact patient outcomes. Ultrasonic cleaners provide deep and consistent cleaning for complex surgical tools and medical devices, minimizing contamination risks. It supports healthcare facilities in meeting safety standards and enhancing patient care.
- For instance, Morantz ultrasonic cleaning equipment demonstrated bacterial reduction rates as high as 99.98 percent in hospitals, effectively removing bacterial contamination from instruments starting with over 259,900 colonies, thereby significantly reducing infection risks
Growing Surgical Procedures and Instrument Complexity:
The expansion of surgical procedures worldwide boosts the demand for advanced cleaning technologies. Modern surgical instruments often feature intricate designs, making manual cleaning insufficient. The medical ultrasonic cleaners market benefits from the ability of ultrasonic systems to reach hidden surfaces and ensure thorough cleaning. It improves efficiency while reducing reliance on labor-intensive processes, supporting higher throughput in busy hospitals and surgical centers.
- For instance, Crest Ultrasonics® systems enabled sterilization departments at major hospitals to increase cleaning throughput with faster cleaning cycles tailored to complex surgical instruments, achieving cleaning times as low as 15 minutes per cycle.
Stringent Regulatory Standards for Sterilization and Hygiene:
Global healthcare regulations impose strict requirements for sterilization and hygiene practices in medical facilities. Regulatory bodies mandate the use of reliable cleaning systems to maintain compliance and avoid penalties. The medical ultrasonic cleaners market gains traction by offering solutions that align with these standards. It ensures consistent performance and helps facilities maintain accreditation while protecting patient safety.
Technological Advancements Enhancing Cleaning Efficiency:
Continuous innovation in ultrasonic cleaning systems enhances precision, efficiency, and ease of use. Features such as digital controls, automated cycles, and multi-frequency technology expand their effectiveness across diverse applications. The medical ultrasonic cleaners market benefits from these advancements by attracting both large hospitals and smaller clinics. It enables healthcare providers to adopt cost-effective, scalable solutions that improve overall operational efficiency.
Market Trends:
Integration of Digital and Automated Features in Cleaning Systems:
The medical ultrasonic cleaners market is experiencing a notable trend toward the integration of digital and automated technologies. Manufacturers are introducing cleaners with programmable settings, touchscreen controls, and automated cycles to improve precision and reduce manual intervention. These features allow healthcare professionals to customize cleaning intensity and duration based on instrument type, ensuring higher consistency and safety. Automation also minimizes human error, streamlines workflow, and improves traceability for compliance purposes. It reflects a shift from traditional manual cleaning methods to smart systems that enhance efficiency and reliability. Growing adoption of such advanced features underscores the industry’s focus on quality assurance in medical environments.
- For instance, the Getinge Ultra Clean Systems 1101 tabletop ultrasonic cleaner features a large, user-friendly touchscreen with programmable timers and automatic enzyme dispensing for wash, rinse, and air purge cycles, capable of processing up to 8 da Vinci robotic instruments per cycle with a 25-lb instrument weight capacity.
Rising Adoption Across Emerging Healthcare Markets and Specialty Applications:
The medical ultrasonic cleaners market is witnessing strong uptake in emerging economies where healthcare infrastructure is expanding rapidly. Governments and private investors are focusing on upgrading sterilization facilities in hospitals and laboratories, fueling demand for ultrasonic cleaners. Their adoption is also increasing in specialty applications such as dental practices, ophthalmology, and laboratories requiring delicate yet thorough cleaning. It supports a broader penetration of ultrasonic cleaning beyond traditional surgical departments. Market participants are responding by offering compact, cost-effective, and portable devices tailored for smaller clinics and specialty centers. This trend highlights a growing diversification of demand across both advanced and developing healthcare systems.
- For Instance, A Crest Ultrasonics P500HT with 120W of acoustic power and a frequency of 45 kHz can complete an ultrasonic cleaning cycle for dental instruments in approximately 5 to 10 minutes, as part of a multi-step decontamination process that includes presoaking, rinsing, and final sterilization
Market Challenges Analysis:
High Initial Costs and Limited Awareness in Developing Regions:
The medical ultrasonic cleaners market faces challenges due to the relatively high upfront cost of equipment. Smaller clinics and hospitals in developing regions often hesitate to invest in advanced cleaning technologies, relying instead on manual or less effective methods. Limited awareness about the long-term benefits of ultrasonic cleaning further restricts adoption. It creates barriers to penetration in price-sensitive markets where budget allocation for sterilization technologies remains low. Manufacturers must focus on cost-effective solutions and awareness programs to address these gaps.
Maintenance Requirements and Risk of Misuse Impacting Adoption:
Another challenge for the medical ultrasonic cleaners market lies in maintenance and proper usage of the devices. These systems require regular calibration, correct cleaning solutions, and skilled handling to maintain efficiency. Misuse or neglect can lead to suboptimal performance and potential damage to delicate medical instruments. It raises concerns among healthcare providers about operational reliability. Training requirements and the need for ongoing technical support add to the complexity of adoption. Addressing these issues is essential for expanding market acceptance and ensuring consistent performance.
Market Opportunities:
Expansion into Emerging Healthcare Markets with Growing Infrastructure Investments:
The medical ultrasonic cleaners market holds significant opportunities in emerging economies where healthcare infrastructure is expanding rapidly. Governments and private players are investing heavily in modern hospitals, laboratories, and specialty clinics. Rising awareness about infection control and global hygiene standards creates strong demand for advanced cleaning solutions. It positions ultrasonic cleaners as an essential tool for meeting patient safety requirements. Vendors introducing affordable, portable models can capture market share among small and mid-sized facilities. Expanding distribution networks in Asia-Pacific, Latin America, and Africa will further accelerate adoption.
Rising Demand for Advanced Cleaning in Specialized Medical Fields:
Specialized fields such as dentistry, ophthalmology, and diagnostic laboratories present untapped growth potential. These areas require precision cleaning of delicate instruments that manual methods cannot achieve. The medical ultrasonic cleaners market benefits from this need, as ultrasonic systems ensure thorough and safe cleaning of fine tools. It allows providers to reduce equipment damage and extend instrument life. Growing use in pharmaceutical labs for cleaning delicate glassware also widens application scope. Companies focusing on compact, high-performance devices tailored for specialty practices can create new revenue streams.
Market Segmentation Analysis:
By Product:
The medical ultrasonic cleaners market by product is divided into benchtop, standalone, and multi-tank systems. Benchtop models dominate due to their affordability and ease of use in small clinics and dental offices. Standalone systems hold strong adoption in hospitals, offering higher capacity and advanced automation features. Multi-tank units are gaining traction in specialized labs and surgical centers where different cleaning cycles are required. It reflects growing demand for product diversity tailored to healthcare facility size and workload.
- For instance, the Branson M2800H benchtop ultrasonic cleaner offers a 0.75-gallon tank and operates at 40 kHz for consistent cavitation throughout the cleaning cycle. 0.75 gallon
By Application:
The medical ultrasonic cleaners market by application includes surgical instruments, dental instruments, endoscopic devices, and laboratory equipment. Surgical instruments form the largest segment, driven by rising procedure volumes and stringent sterilization standards. Dental practices show increasing adoption of ultrasonic cleaners to ensure safe and efficient instrument care. Endoscopic devices benefit from ultrasonic systems that clean intricate and delicate surfaces effectively. Laboratory applications expand steadily, with demand for precision cleaning of glassware and diagnostic tools. It highlights broad applicability across diverse medical fields.
- For Instance, For dental instruments, Coltene-Whaledent offers ultrasonic cleaning systems designed specifically for dental applications, using advanced cavitation technology at frequencies between 25 to 45 kHz to ensure removal of debris and contaminants from delicate dental instruments.
By End Use:
The medical ultrasonic cleaners market by end use is categorized into hospitals, clinics, and diagnostic laboratories. Hospitals represent the largest share, supported by high surgical volumes and regulatory compliance needs. Clinics, including dental and specialty practices, adopt compact systems for cost-effective sterilization. Diagnostic laboratories utilize ultrasonic cleaners for efficient cleaning of sensitive testing equipment and instruments. It shows strong alignment of ultrasonic cleaning solutions with varied healthcare facility requirements.
Segmentations:
By Product:
- Benchtop
- Standalone
- Multi-Tank Systems
By Application:
- Surgical Instruments
- Dental Instruments
- Endoscopic Devices
- Laboratory Equipment
By End Use:
- Hospitals
- Clinics
- Diagnostic Laboratories
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America:
North America holds 38% market share in the medical ultrasonic cleaners market in 2024. The region benefits from advanced healthcare infrastructure, high adoption of innovative cleaning technologies, and strict infection control standards. Strong regulatory frameworks ensure compliance with sterilization protocols, driving steady demand for ultrasonic cleaners. It gains further momentum from large hospital networks, outpatient centers, and specialized clinics requiring advanced cleaning solutions. The presence of leading manufacturers and a high volume of surgical procedures strengthen the market position. Continuous investments in digital and automated cleaning technologies also enhance adoption across healthcare facilities.
Europe:
Europe accounts for 29% market share in the medical ultrasonic cleaners market in 2024. Strict regulatory mandates on sterilization and hygiene practices drive consistent demand across the region. Growing hospital networks and increasing procedural volumes further accelerate adoption of ultrasonic cleaning systems. It benefits from strong healthcare funding and government-led initiatives to improve patient safety. The market also sees growth in specialty clinics such as dental and ophthalmology centers adopting compact devices. Continuous research and development by European manufacturers improve efficiency and sustainability in cleaning solutions. Rising demand for eco-friendly systems enhances market penetration in this region.
Asia-Pacific:
Asia-Pacific represents 23% market share in the medical ultrasonic cleaners market in 2024. The region is projected to record the fastest growth through 2032 due to rapid healthcare infrastructure expansion. Rising investments in hospital construction, laboratory upgrades, and infection control measures drive adoption of ultrasonic cleaners. It benefits from growing awareness of hygiene standards and increasing medical tourism in countries like India, Thailand, and Malaysia. Affordable product offerings tailored for small and mid-sized facilities also support wider penetration. The presence of local manufacturers introducing cost-effective systems further strengthens the regional landscape. Government healthcare reforms and rising surgical procedure rates continue to boost market growth.
Key Player Analysis:
- Carestream Health
- Intelagard
- Medisafe
- Elma Schmidbauer
- L and R Manufacturing
- Giant Systems
- CAVITRON
- Miele
- Vanguard Medical
- Thermo Fisher Scientific
- KUDOS
- Spartan Chemical
Competitive Analysis:
The medical ultrasonic cleaners market is characterized by strong competition among global and regional players. Key companies include Carestream Health, Intelagard, Medisafe, Elma Schmidbauer, L and R Manufacturing, Giant Systems, CAVITRON, and Miele. These companies focus on expanding product portfolios, enhancing cleaning efficiency, and integrating digital features to strengthen market presence. It emphasizes precision cleaning technologies that meet strict healthcare sterilization standards, appealing to hospitals, clinics, and laboratories. Leading players invest in research and development to introduce multi-frequency systems, automated controls, and eco-friendly designs. Strategic partnerships with healthcare providers and distributors enhance accessibility in both developed and emerging markets. Competitive differentiation is achieved through product reliability, affordability, and after-sales support, positioning established brands to secure long-term growth.
Recent Developments:
- In May 2025, Launched Carestream 360°, an advanced analytics dashboard for radiology departments to track performance metrics and optimize operations.
- In May 2025, Launched the GOMEKLI™ Digital Companion in collaboration with SpringWorks Therapeutics, supporting patients with neurofibromatosis type 1 (NF1) and symptomatic plexiform neurofibromas.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application, End Use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The medical ultrasonic cleaners market will witness strong demand with rising focus on hospital-acquired infection prevention.
- Adoption of compact and portable ultrasonic cleaners will expand in small clinics and specialty centers.
- Manufacturers will integrate smart features such as IoT connectivity and digital monitoring to improve efficiency.
- The market will benefit from government-led healthcare reforms promoting modern sterilization practices.
- It will see growing applications in dental, ophthalmology, and diagnostic laboratories requiring precision cleaning.
- Sustainability will shape product development with eco-friendly cleaning solutions and reduced water consumption.
- Collaborations between healthcare providers and equipment manufacturers will drive innovation and product customization.
- The market will expand in emerging economies supported by infrastructure growth and rising healthcare investments.
- Training programs and awareness initiatives will strengthen adoption by improving user confidence and compliance.
- Continuous innovation in multi-frequency and automated systems will enhance reliability and widen clinical applications.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Hospital-Acquired Infections (HAIs)
Increasing rates of HAIs are pushing healthcare facilities to adopt more effective sterilization technologies, with ultrasonic cleaners offering deep cleaning and reducing contamination risks for surgical and medical instruments.
Stringent Global Sterilization and Hygiene Regulations
Regulatory bodies worldwide are mandating higher standards for instrument cleaning and sterilization, driving healthcare providers to invest in ultrasonic cleaners to ensure compliance and avoid penalties.
Advancements in Ultrasonic Cleaning Technology
Innovations such as digital controls, automated cycles, and multi-frequency systems are making ultrasonic cleaners more efficient, precise, and user-friendly, encouraging broader adoption across hospitals and clinics.
Expansion of Healthcare Infrastructure in Emerging Markets
Rapid investments in new hospitals, laboratories, and specialty clinics in Asia-Pacific, Latin America, and Africa are increasing demand for advanced cleaning solutions like ultrasonic cleaners to meet modern infection control standards.
Growing Complexity of Surgical and Diagnostic Instruments
The increasing use of intricate and delicate medical devices, which are difficult to clean manually, is boosting the need for ultrasonic cleaners that can effectively reach and clean complex surfaces.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Medical Ultrasonic Cleaners Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Medical Ultrasonic Cleaners Market projected to grow between 2024 and 2032?
Which Medical Ultrasonic Cleaners Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Medical Ultrasonic Cleaners Market?
Who are the leading companies in the Medical Ultrasonic Cleaners Market?
Which region commanded the largest share of the Medical Ultrasonic Cleaners Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Hospitals
- 1.2.2 Clinics
- 1.2.3 Diagnostic Laboratories
- 1.3 By Product
- 1.3.1 Benchtop
- 1.3.2 Standalone
- 1.3.3 Multi-Tank Systems
- 1.4 By Application
- 1.4.1 Surgical Instruments
- 1.4.2 Dental Instruments
- 1.4.3 Endoscopic Devices
- 1.4.4 Laboratory Equipment
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.6 billion → 2032: USD 2.7 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Medical Ultrasonic Cleaners Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Medical Ultrasonic Cleaners Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Medical Ultrasonic Cleaners Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Medical Ultrasonic Cleaners Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Medical Ultrasonic Cleaners Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Medical Ultrasonic Cleaners Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Medical Ultrasonic Cleaners Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Medical Ultrasonic Cleaners Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.6 billion → 2032: USD 2.7 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Medical Ultrasonic Cleaners Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Clinics
- 12.3.7.3 Diagnostic Laboratories
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Benchtop
- 12.4.7.2 Standalone
- 12.4.7.3 Multi-Tank Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Surgical Instruments
- 12.5.7.2 Dental Instruments
- 12.5.7.3 Endoscopic Devices
- 12.5.7.4 Laboratory Equipment
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Medical Ultrasonic Cleaners End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Medical Ultrasonic Cleaners Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Medical Ultrasonic Cleaners Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Medical Ultrasonic Cleaners Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Carestream Health
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Intelagard
- 18.4 Medisafe
- 18.5 Elma Schmidbauer
- 18.6 L and R Manufacturing
- 18.7 Giant Systems
- 18.8 CAVITRON
- 18.9 Miele
- 18.10 Vanguard Medical
- 18.11 Thermo Fisher Scientific
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

