
Statewide records and Medicare telehealth reshape care
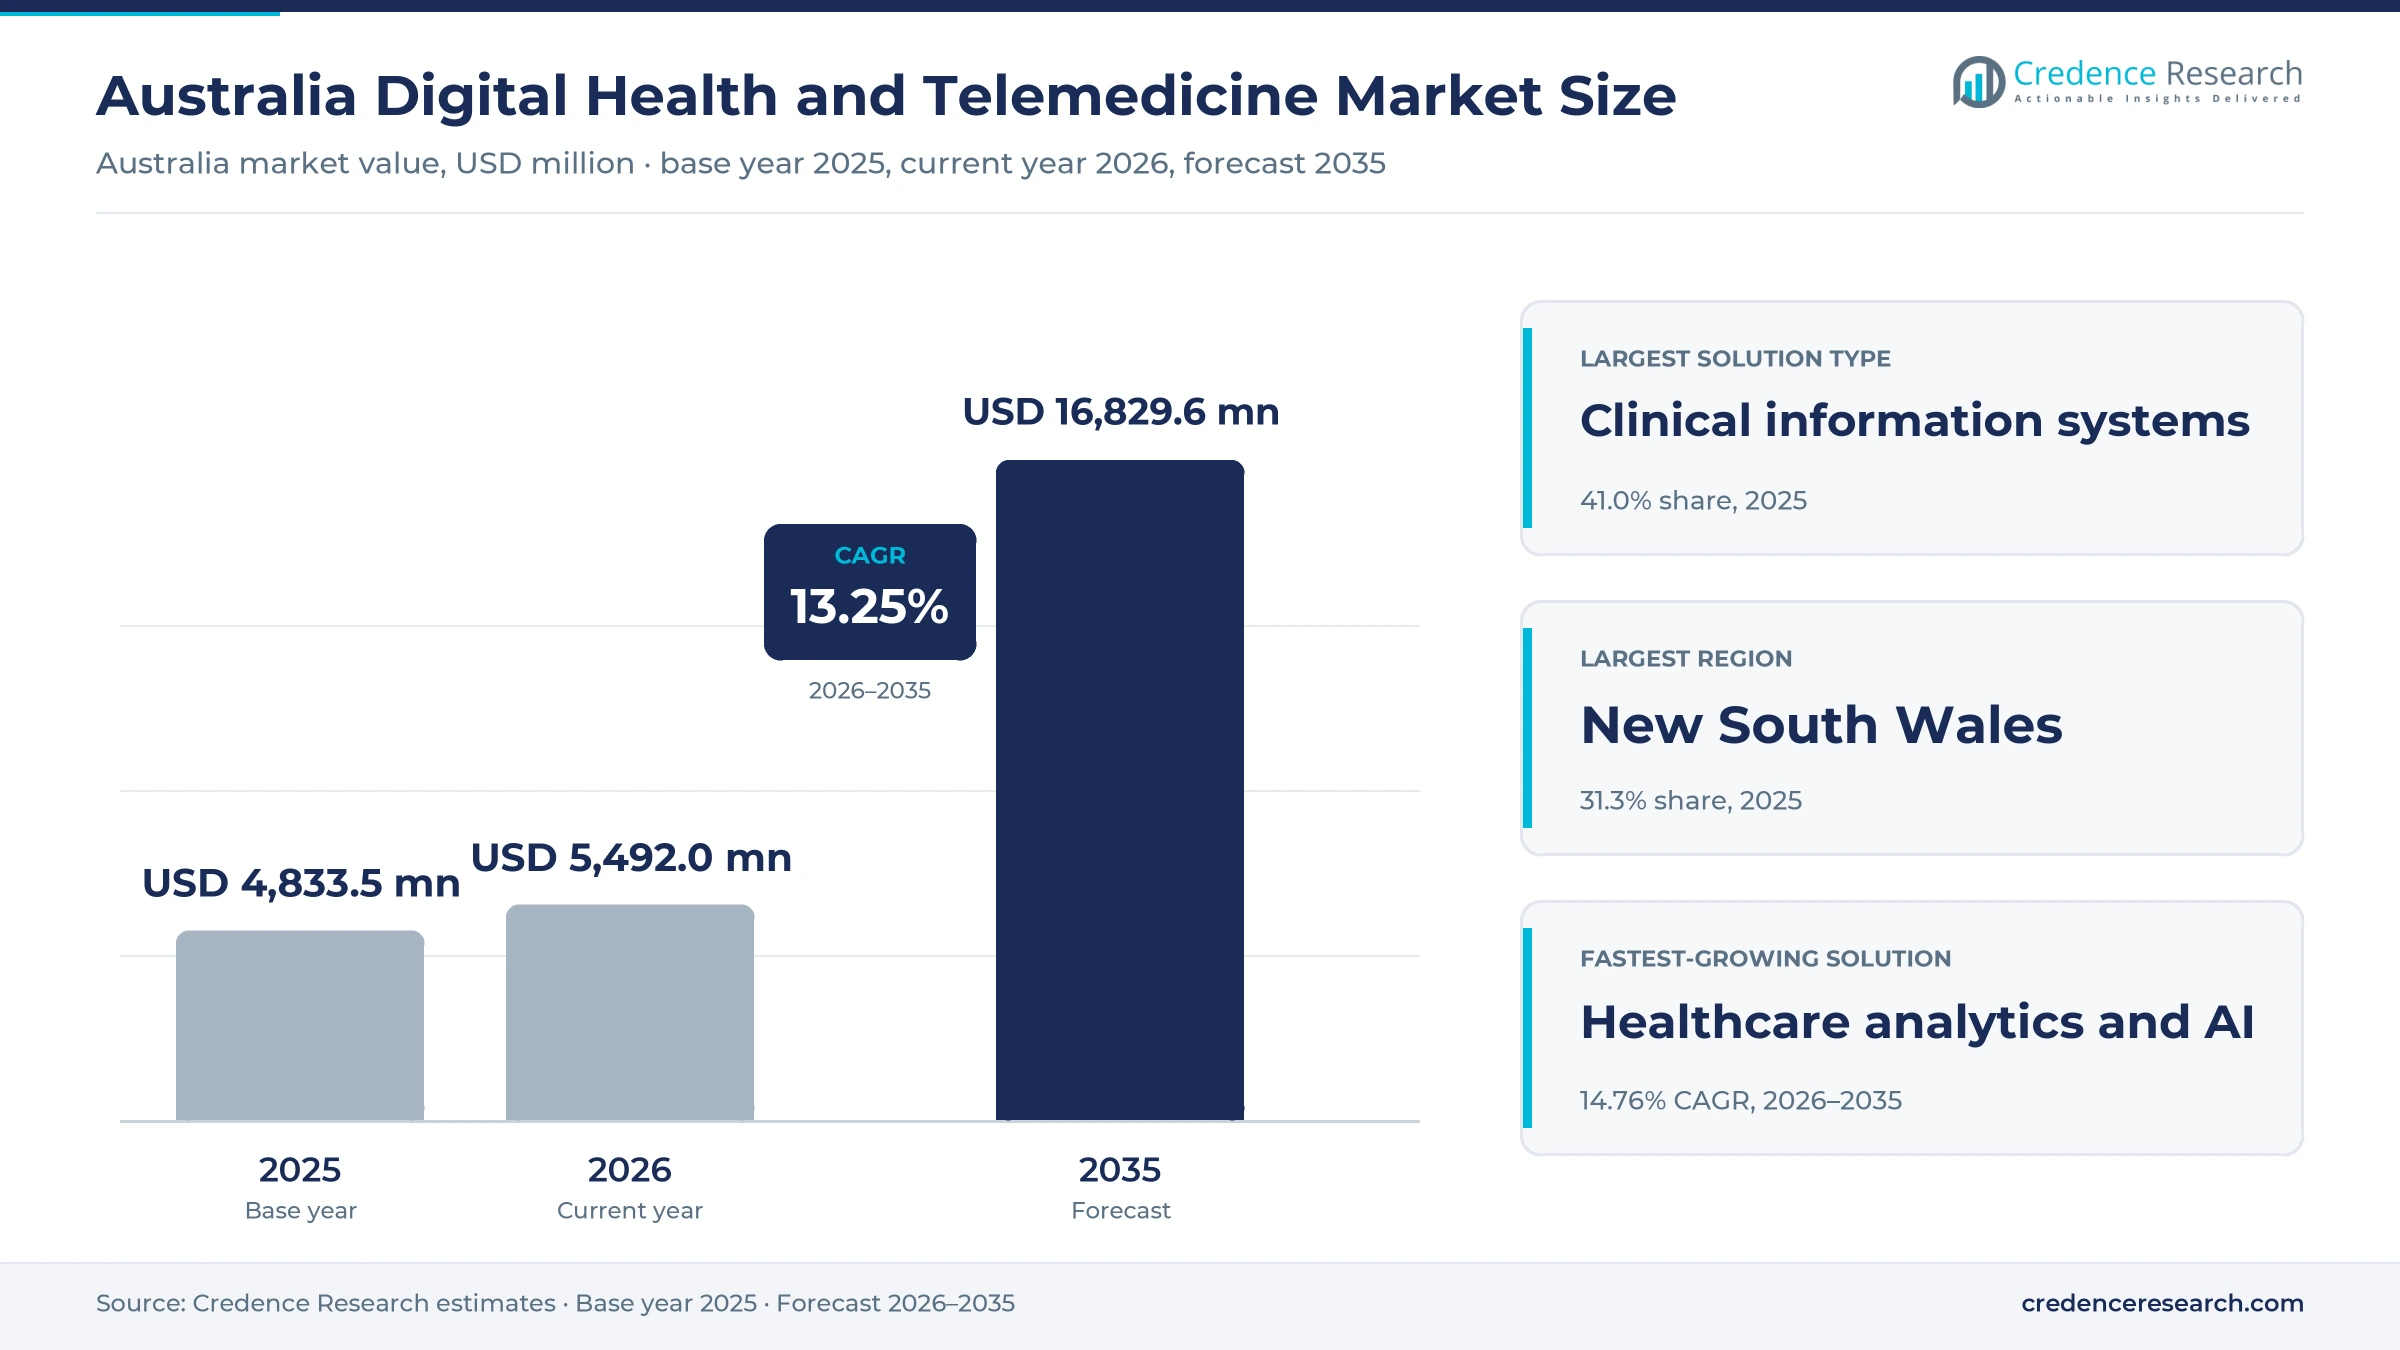
The Australia digital health & telemedicine market was valued at USD 4.83 billion in 2025 and is projected to increase from USD 5.49 billion in 2026 to USD 16.83 billion by 2035, registering a CAGR of 13.25% during 2026–2035. Demand comes from state health departments replacing paper and legacy hospital systems, from general practices that bill Medicare telehealth items every day, and from virtual emergency and home care services that keep patients out of crowded wards. New South Wales held the largest regional share, 31.3% in 2025, because it has the largest population and is moving every public hospital onto one statewide patient record. New South Wales is also the fastest-growing region at 13.59% a year, as that rollout moves through its districts. In turn, chronic care funding is changing, with new GP chronic condition management plans starting on July 1, 2025, and tying many patients to a registered practice.
Which software, platforms and services does the estimate cover?
The estimate measures what Australian clinicians, managers and patients spend on tools that record, share and deliver care digitally. It counts license, subscription, hosting, implementation and support fees for telehealth platforms, electronic medical records, patient administration systems, remote monitoring, patient apps and analytics and AI tools.
The estimate excludes Medicare benefits paid to clinicians for telehealth consultations, medical devices sold as hardware, and general office software. The value chain runs from global record vendors and local platform companies through system integrators to state health departments, private hospital groups, general practices, pharmacies, aged care operators and the patients who use the tools at home.
Australia Digital Health & Telemedicine Market Insights
- The Australia digital health & telemedicine market was valued at USD 4.83 billion in 2025 and is projected to reach USD 16.83 billion by 2035, registering a CAGR of 13.25% during 2026–2035.
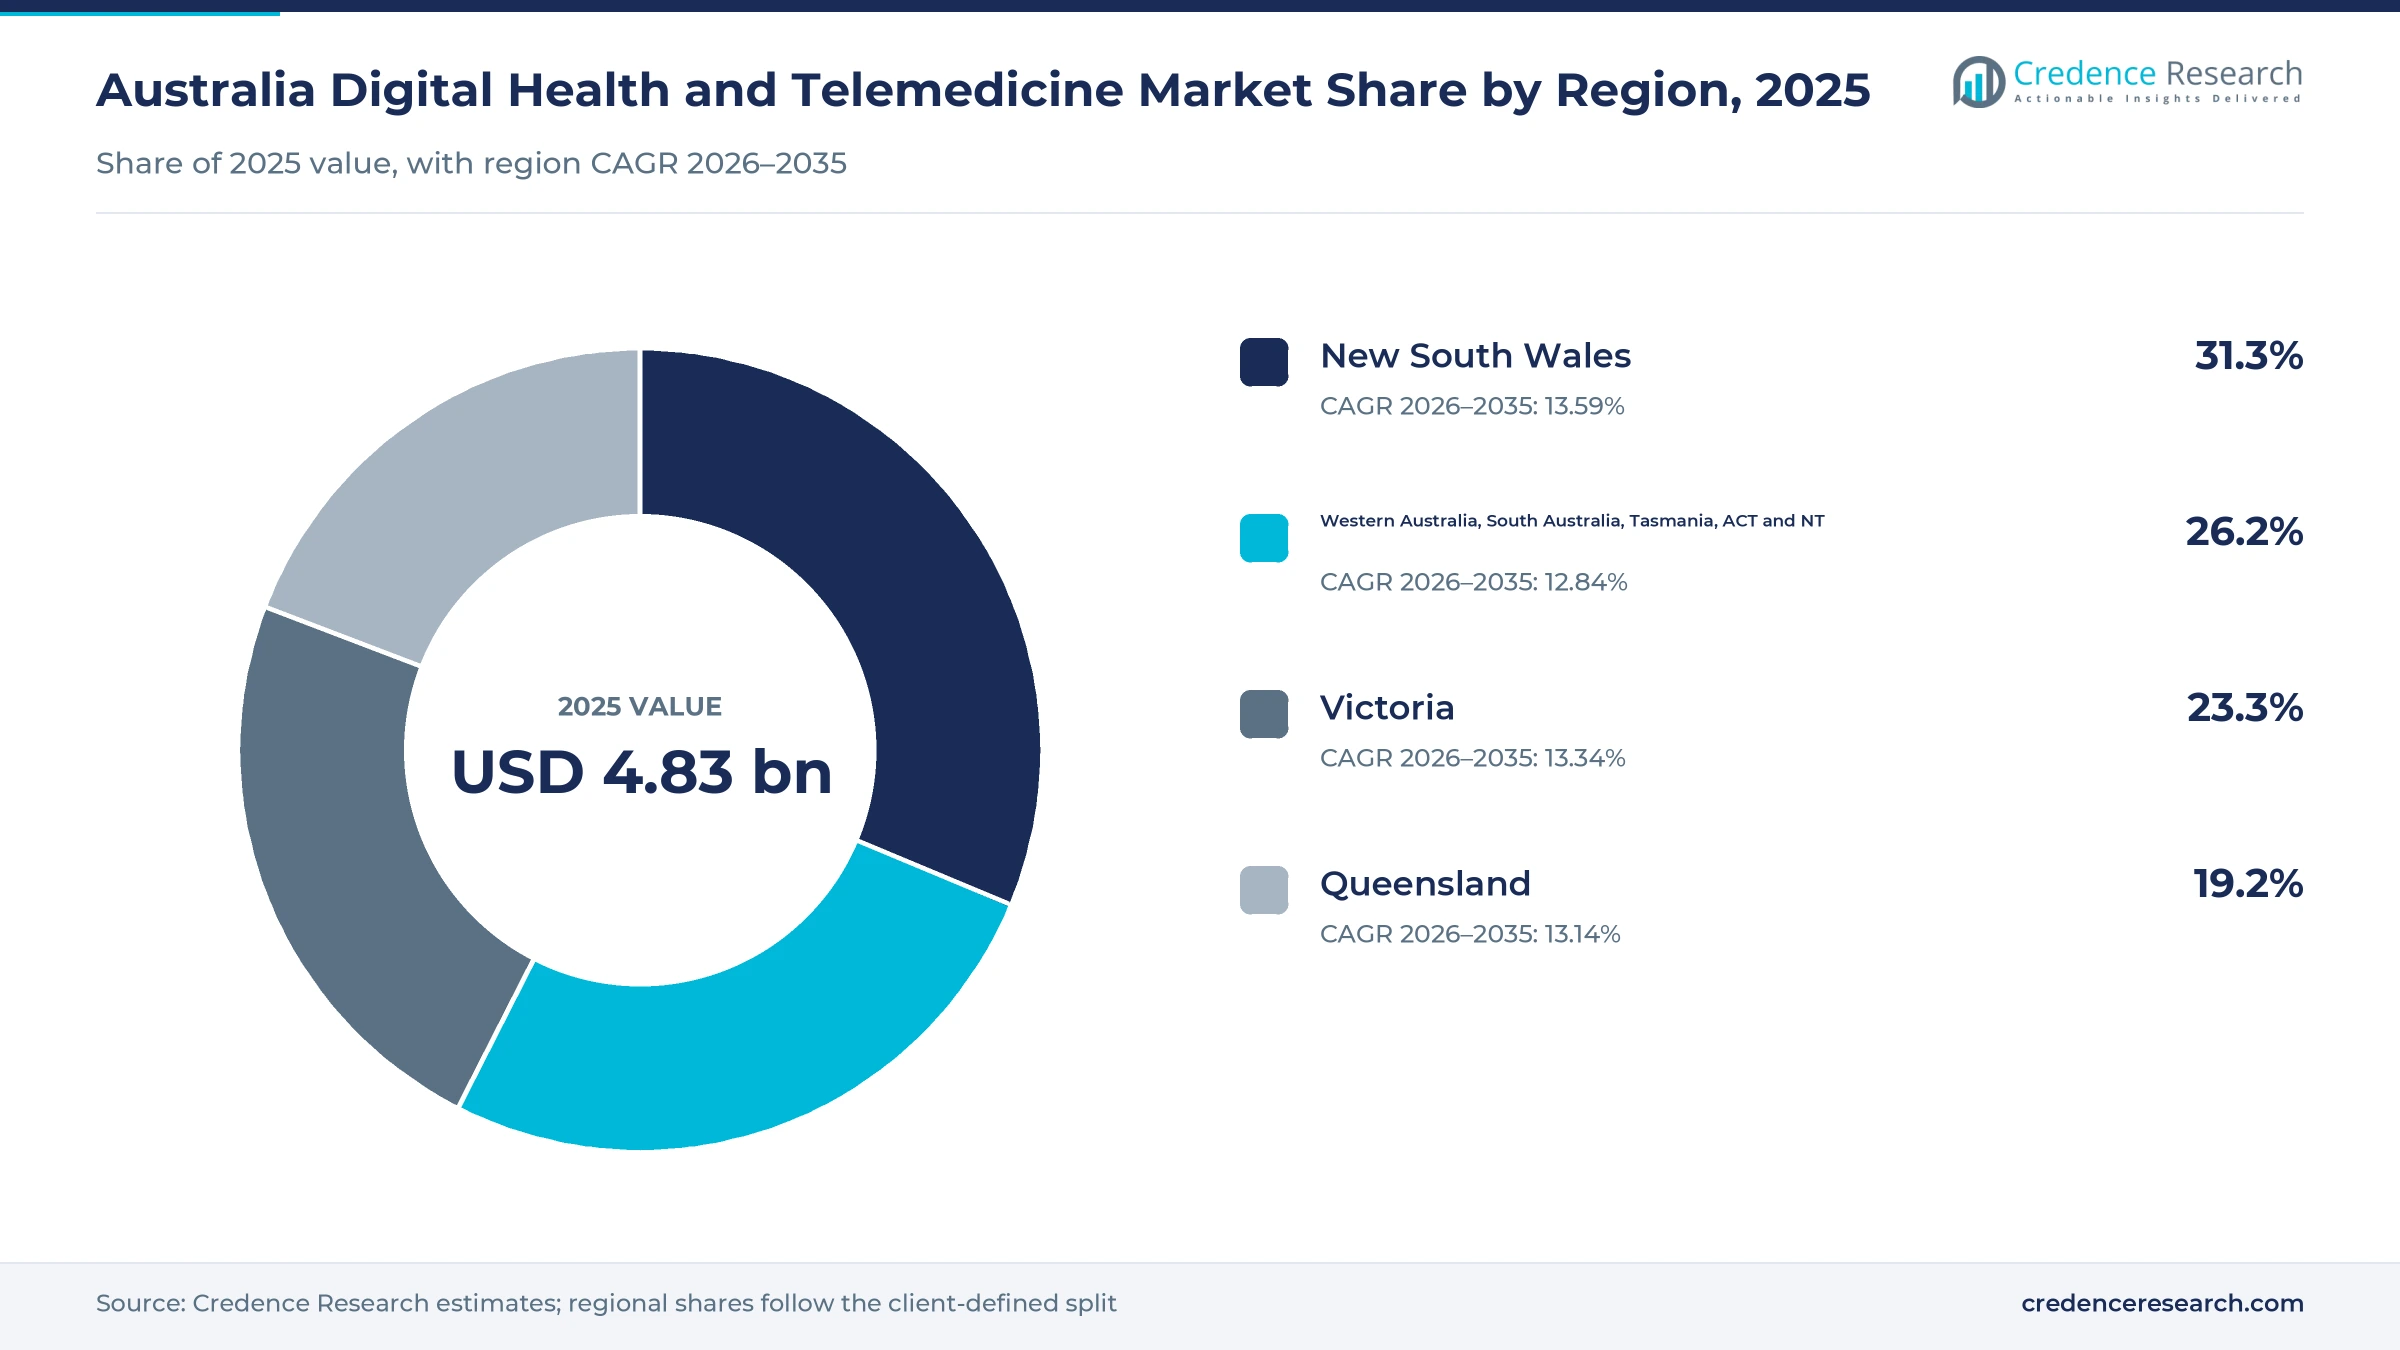
- New South Wales held a 31.3% share of 2025 value, because the state has the largest population and is rolling out a single statewide patient record.
- Clinical information systems led with a 41.0% share of 2025 value, because state record programs absorb the largest software and implementation budgets.
- South Australia became the first jurisdiction to run the Sunrise record across all public hospitals and health services in April 2025, at almost 100 sites.
- Healthcare analytics and AI grows fastest at 14.76% a year during 2026–2035, as hospitals and practices add AI scribes and predictive tools.
Clinical systems lead as analytics and AI grow fastest
Why do clinical information systems hold the largest share?
Based on solution type, the market is categorized into Telehealth Platforms, Clinical Information Systems, Connected Care Applications and Healthcare Analytics and AI. Clinical Information Systems led with a 41.0% share of 2025 value, because statewide record programs carry long contracts for licenses, build and support. Healthcare Analytics and AI grows fastest at 14.76% a year, as clinicians adopt AI scribes and hospitals add predictive tools on top of new records.
How do hospitals and home care settings split spending?
Based on care setting, the market is categorized into Hospitals, Primary and Specialist Clinics, Home and Community Care, and Residential Aged Care. Hospitals led with a 48.0% share of 2025 value, because public hospital record and patient administration systems are the largest single purchases. Home and Community Care grows fastest at 14.52% a year, as virtual emergency services and remote monitoring kits from medical device suppliers move care into homes.
Which end users drive purchases and daily use?
Based on end user, the market is categorized into Clinical Practitioners, Patients and Carers, Healthcare Administrators and Pharmacy Professionals. Clinical Practitioners led with a 45.0% share of 2025 value, because doctors and nurses use records, ordering and telehealth tools at every shift. Patients and Carers grow fastest at 14.23% a year, as patients book mental health telemedicine sessions, use virtual emergency services and track conditions at home.
How do public tenders and private sales reach buyers?
Based on channel, the market is categorized into Public Procurement, Private Enterprise Sales and Patient Self-Service. Public Procurement led with a 56.0% share of 2025 value, because state health departments buy most hospital systems through multi-year tenders. Patient Self-Service grows fastest at 14.42% a year, as patients use apps, online booking and paid virtual consultations without a referral from a hospital or clinic.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Solution Type | Clinical Information Systems | 41.0% | Healthcare Analytics and AI | 14.76% |
| By Care Setting | Hospitals | 48.0% | Home and Community Care | 14.52% |
| By End User | Clinical Practitioners | 45.0% | Patients and Carers | 14.23% |
| By Channel | Public Procurement | 56.0% | Patient Self-Service | 14.42% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Medicare items, chronic care and record rollouts lift spend
How does permanent Medicare telehealth funding lift demand?
Practices have billed video and phone consultations as standard Medicare items since Jan. 1, 2022, which gives them a reason to keep investing in booking, video and messaging tools. The federal government set aside AUD 106 million over four years to support that permanent arrangement, according to the Royal Australian College of General Practitioners. Telehealth made up 20% of GP services in 2022-23, according to a Medicare review of telehealth items, with the GP share stabilizing at about that level. The same review found that non-GP specialists used video for 48% of their telehealth consultations, while allied health telemedicine ran on video in 75% of cases. As a result, primary and specialist clinics are a steady buyer of platforms, while patients and carers grow at 14.23% a year.
Why does longitudinal chronic care need connected tools?
Patients with long-term conditions need repeated reviews, shared care plans and results that follow them across clinicians, which raises demand for connected records and remote monitoring. Some 49.9% of Australians, or 12.6 million people, had at least one chronic condition in 2022, according to the Australian Bureau of Statistics. Mental and behavioral conditions were the most common at 26.1%, a group that already relies heavily on video and phone counseling. New GP chronic condition management plans began on July 1, 2025, and become required for allied health referrals from July 1, 2027, according to the Department of Health. In turn, home and community care grows fastest at 14.52% a year as practices monitor these patients between visits.
How do enterprise record rollouts reshape public hospitals?
State health departments are replacing older hospital systems with single statewide records, which creates the largest contracts in the market. New South Wales signed with Epic Systems in October 2023 to build a single digital patient record for all public hospitals, with statewide rollout planned for 2026 to 2029-30. South Australia ran the Sunrise record across almost 100 sites by April 2025, covering more than 5 million people and over 4,900 beds, according to Altera Digital Health. Western Australia committed AUD 247 million to its record program and moved to procurement of a full system after phase one finished in August 2025. As a result, clinical information systems hold 41.0% of 2025 value.
Why do state virtual care services widen the buyer base?
State governments now fund virtual emergency and outpatient services that need video, triage and record links, which brings hospitals into telehealth buying alongside general practice. The Victorian Virtual Emergency Department passed 500,000 consultations by March 2025, and 83% of patients who would otherwise have gone to hospital avoided the trip, according to the Victorian government. Victoria then committed AUD 437 million in its 2025-26 budget to make the virtual emergency service permanent and lift capacity from about 600 callers a day to more than 1,750 by 2028-29. The service began as a pilot in October 2020 and went statewide in April 2022. In turn, Victoria holds 23.3% of 2025 value and grows at 13.34% a year.
Record exchanges, cloud systems and AI scribes emerge
How are statewide record exchanges changing access to results?
Health services are shifting from point-to-point messages toward shared exchanges that show a patient history from any public hospital, which raises demand for integration software. Victoria began rolling out its CareSync Exchange in August 2025, built on the dbMotion platform from Altera Digital Health, according to Healthcare IT News. The exchange gives clinicians a near real-time view of more than 2.3 million patient records, with Austin Health and Eastern Health live first and statewide coverage expected by 2028. National law will also require pathology and diagnostic imaging providers to upload reports to My Health Record once the Department of Health rules commence. As a result, groups that sell electronic medical record platforms compete more on integration than on features.
Why is the shift to cloud-hosted record systems rising?
Private hospital groups and smaller states increasingly prefer subscription records hosted by the vendor, because they avoid large upfront data center and upgrade costs. St Vincent's Health Australia chose MEDITECH Expanse for 10 private hospitals in Queensland, New South Wales and Victoria in February 2024, delivered through the vendor's cloud subscription model. Alfred Health expanded its Oracle Health record with oncology modules in August 2024, which link treatment orders to pharmacy systems and the national Safescript database. Mackay Hospital and Health Service also became the seventh fully digital health service in Queensland in 2025, within a hub-and-spoke project that covered 31 sites statewide. In turn, hospitals keep 48.0% of 2025 value as private groups follow public hospitals onto modern records.
Can AI scribes and analytics open a new value pool?
Clinicians spend a large part of each visit on notes and letters, which creates a clear opening for AI tools that draft records and flag risk from data already in the system. Australian practices and hospitals are trialing AI scribes that draft consultation notes, which adds a new software layer on top of existing records. The Therapeutic Goods Administration stepped up its review of digital scribes that add diagnosis or treatment suggestions, which pushes vendors toward clearer product claims. The World Health Assembly extended the global digital health strategy of the World Health Organization to 2027 in May 2025, when 129 countries had national strategies. As a result, Healthcare Analytics and AI grows fastest at 14.76% a year, often alongside AI-assisted virtual consultations.
Is there room to link telehealth with pharmacy dispensing?
Patients who see a doctor by video still need their medicines, which gives prescription exchanges and pharmacy software a growing role in the virtual care chain. Telstra Health describes its eRx Script Exchange as the largest prescription exchange service in Australia for GPs, pharmacists and patients. More than 40 private telehealth platforms used the exchange in July 2025, according to Medical Republic, while a 15-cent fee on each private script took effect on July 1, 2025. Fred IT told the same publisher that the private script market grew 60% in 18 months. In turn, pharmacy professionals grow faster than healthcare administrators as more prescriptions move through connected systems.
Delivery risk, AI rules and cyber threats test buyers
How do large record programs create delivery risk?
Statewide record programs run for many years and often cost more than first planned, which can delay later stages and new purchases. The Queensland Audit Office reported in December 2018 that the state record program was estimated to cost AUD 1.2 billion to 2025, against an initial approval of up to AUD 412 million in 2011. As a result, treasuries now ask for staged business cases. Vendors respond with phased go-lives, as New South Wales did by starting with one district before statewide rollout.
Why do AI and software rules slow some launches?
Software that suggests a diagnosis or treatment can count as a medical device, which means it needs approval before sale in Australia. The Therapeutic Goods Administration found in July 2025 that some software proposing diagnoses or treatments was potentially supplied in breach of the law. In turn, AI scribe vendors must limit claims or seek approval, which lengthens sales cycles. Larger vendors respond with regulatory teams, while smaller start-ups narrow features to note taking.
How do cyber threats raise the cost of connected care?
Each new link between hospitals, practices and pharmacies creates another path that attackers can use to reach patient data. Shared exchanges such as CareSync hold millions of records, which makes them attractive targets. As a result, buyers add security reviews, testing and monitoring to every contract, which raises costs and slows go-lives. Health services respond by funding cyber defense for hospital networks alongside new systems.
Why does phone-based telehealth cap platform revenue?
Most GP telehealth in Australia still happens by phone, which needs little paid software beyond the practice system. GPs used video for less than 5% of telehealth consultations in 2022-23, the lowest of any clinician group, according to the Medicare review. As a result, platform vendors earn less from general practice than from specialists, hospitals and allied health providers that consult mainly by video. Vendors respond by bundling video, booking and messaging into practice software, so that video becomes an easy default.
New South Wales leads as its record rollout accelerates
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 1.51 | 31.3% | 13.59% |
| Western Australia, South Australia, Tasmania, ACT and NT | 1.27 | 26.2% | 12.84% |
| Victoria | 1.13 | 23.3% | 13.34% |
| Queensland | 0.93 | 19.2% | 13.14% |
How does one statewide record shape spending in NSW?
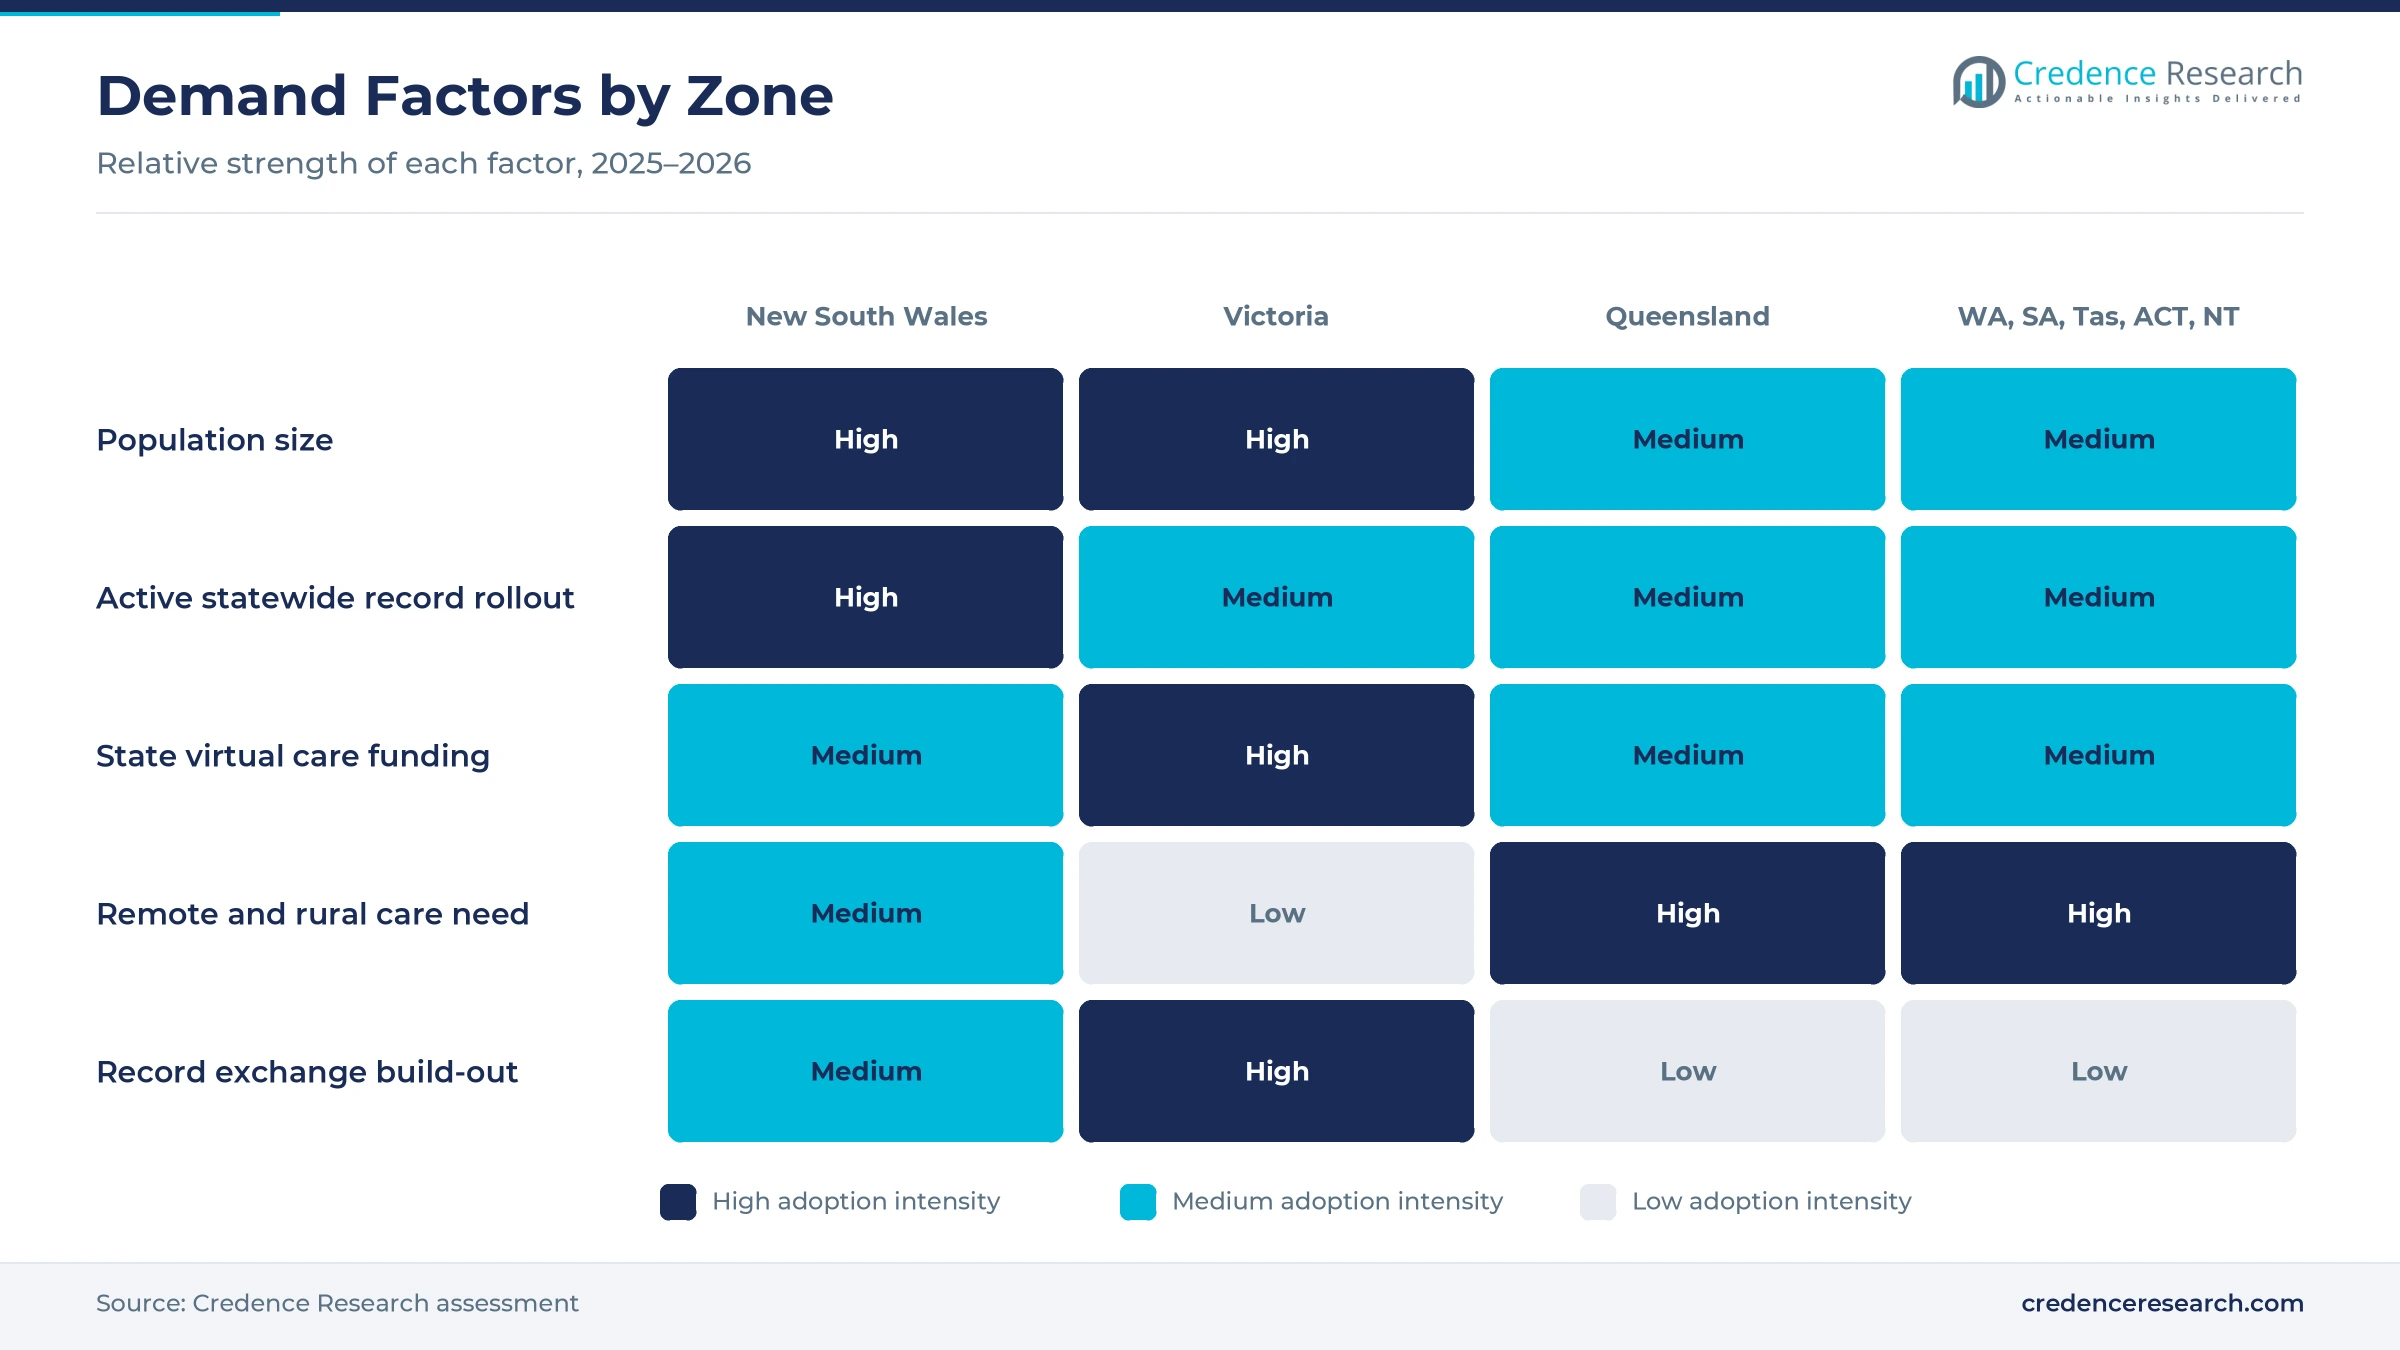
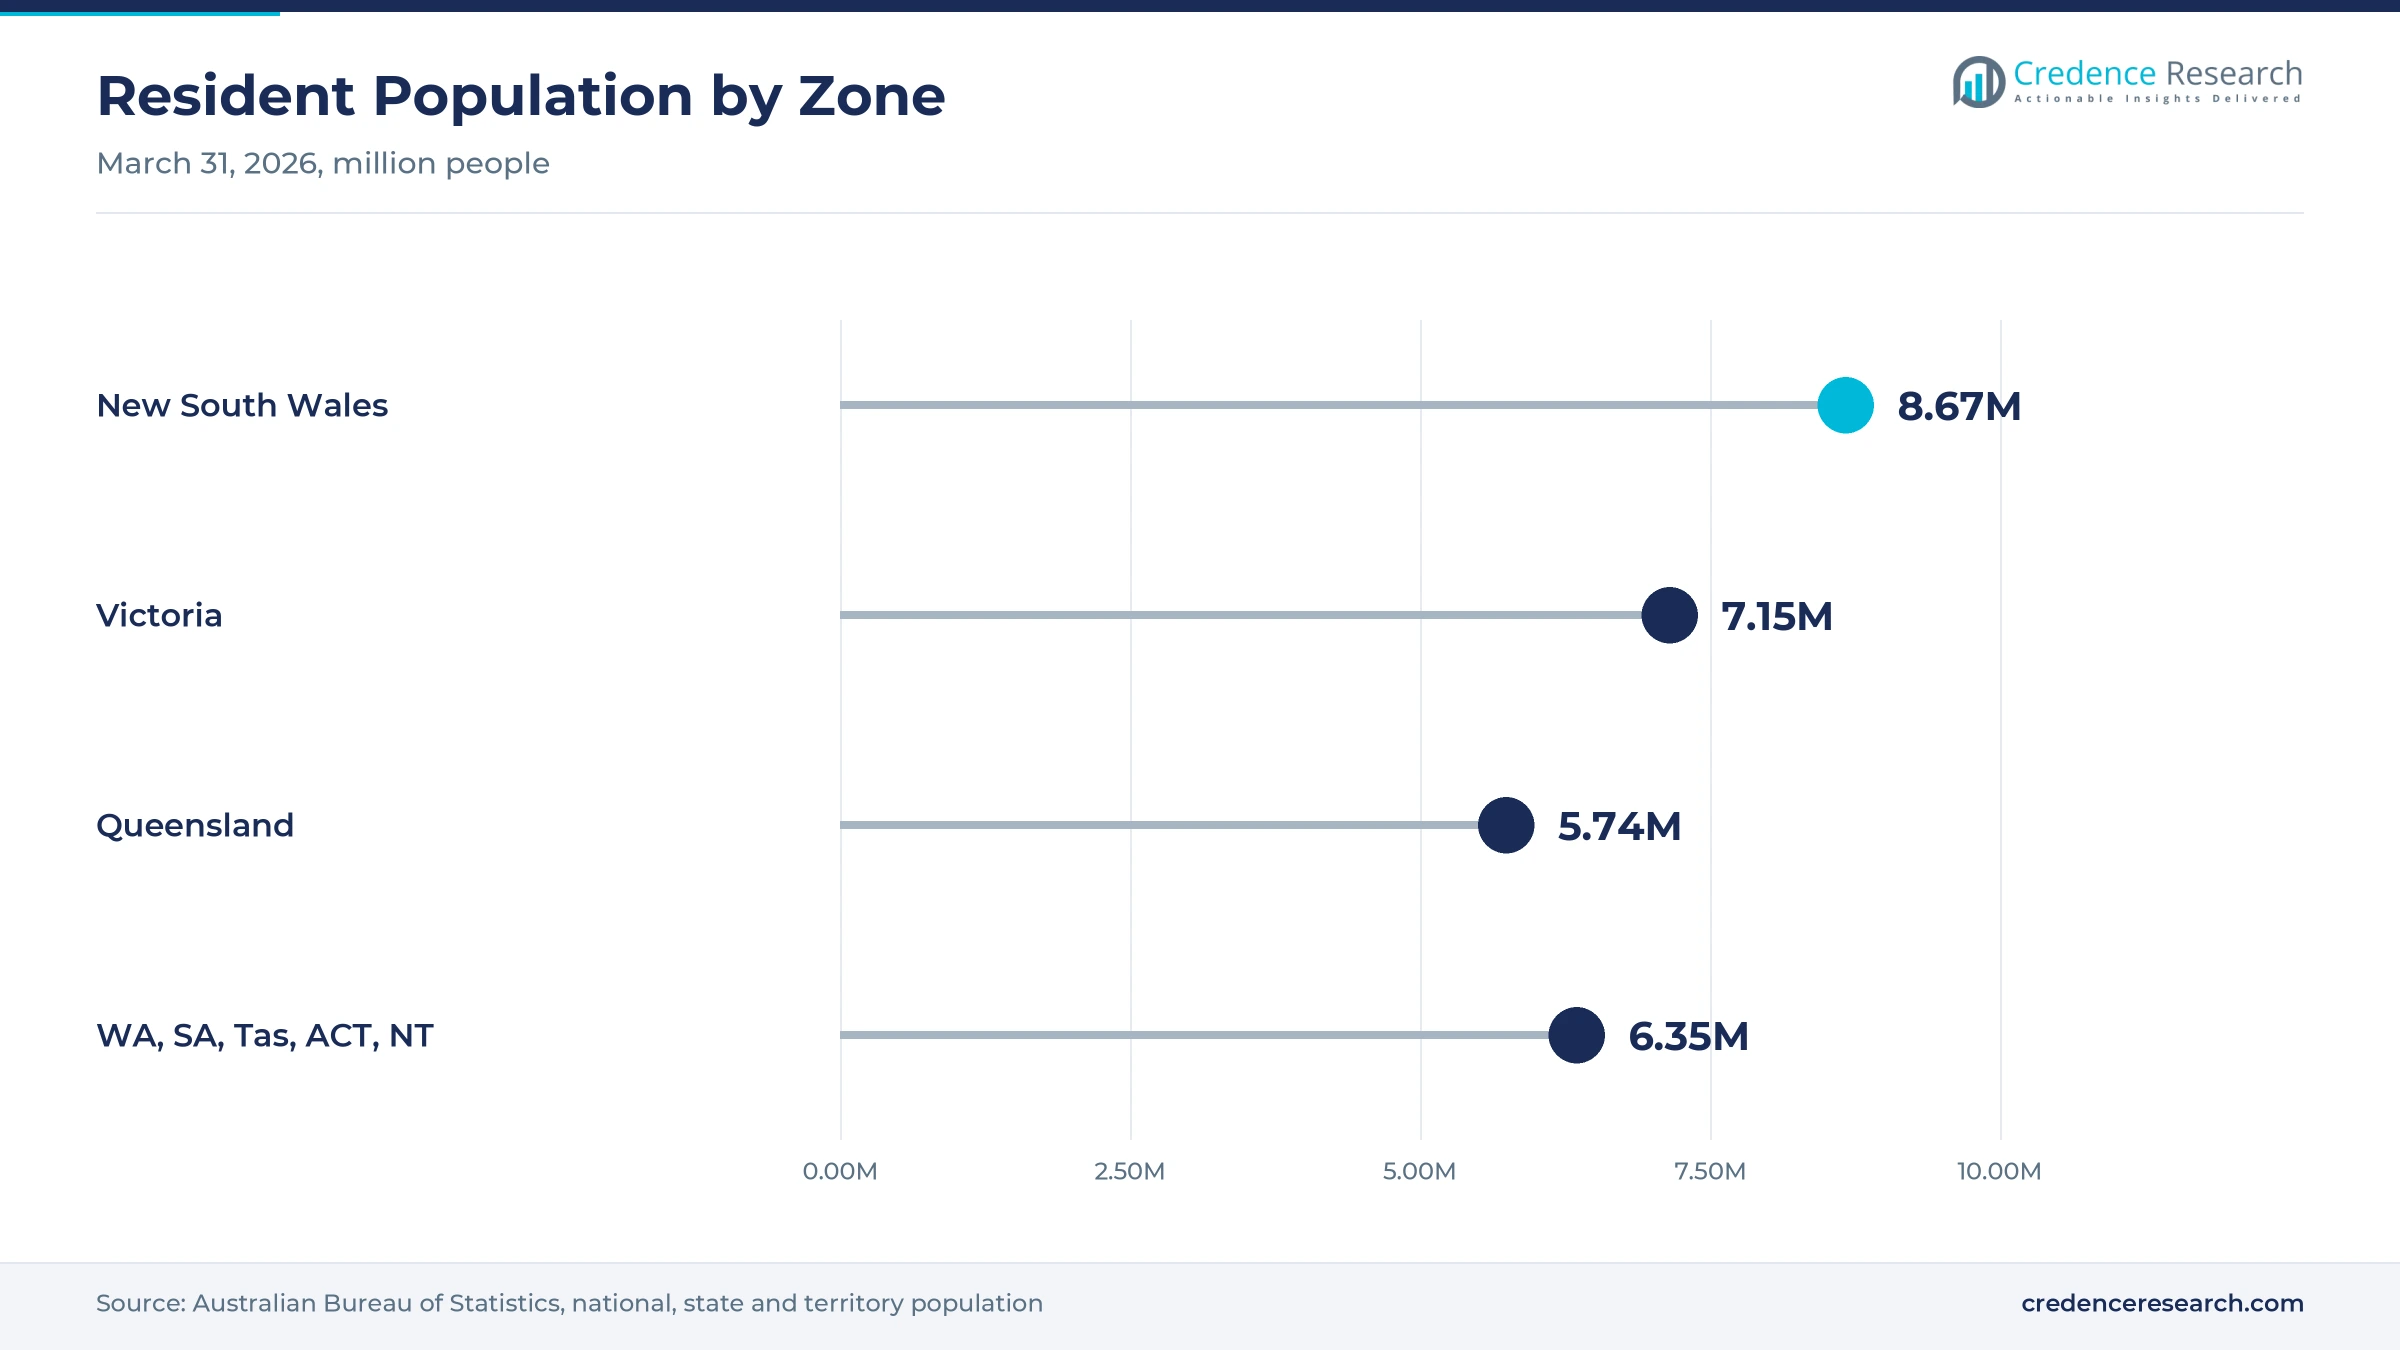
New South Wales held a 31.3% share of 2025 value and grows fastest at 13.59% a year, because the state is moving every public hospital onto one Epic record. Hunter New England Local Health District was set to go first in 2025-26, with other districts and NSW Health Pathology following from 2026. The state also had 8.67 million residents on March 31, 2026, the largest population nationally. As a result, implementation and support spending stays high through the forecast.
How does Victoria build on virtual emergency care?
Victoria held a 23.3% share of 2025 value and grows at 13.34% a year, because the state funds both virtual emergency care and a statewide record exchange. The Victorian Virtual Emergency Department is now permanent, and CareSync Exchange is expected to cover all public health services by 2028. Victoria had 7.15 million residents on March 31, 2026, after growth of 1.6% over the year. In turn, Victoria remains the second-largest zone for connected care spending.
What shapes connected care demand in Queensland?
Queensland held a 19.2% share of 2025 value and grows at 13.14% a year, because much of its hospital record work is already complete and new spending shifts to rural sites and upgrades. Mackay became the seventh fully digital health service in 2025, and Cairns and Hinterland was due to follow later that year. Queensland had 5.74 million residents on March 31, 2026, spread across many remote towns. As a result, demand moves toward virtual care for outlying communities and analytics on existing records.
How do the western, southern and territory zones differ?
Western Australia, South Australia, Tasmania, ACT and NT held a 26.2% share of 2025 value and grow at 12.84% a year, because South Australia has finished its rollout while Western Australia is still buying a full record. These states and territories had 6.35 million residents combined on March 31, 2026. In turn, Western Australia drives most new demand, while vast distances keep virtual consultations important for rural patients across the zone.
Record go-lives, virtual care budgets and reforms, 2024–2026
| Development | Status and market relevance |
|---|---|
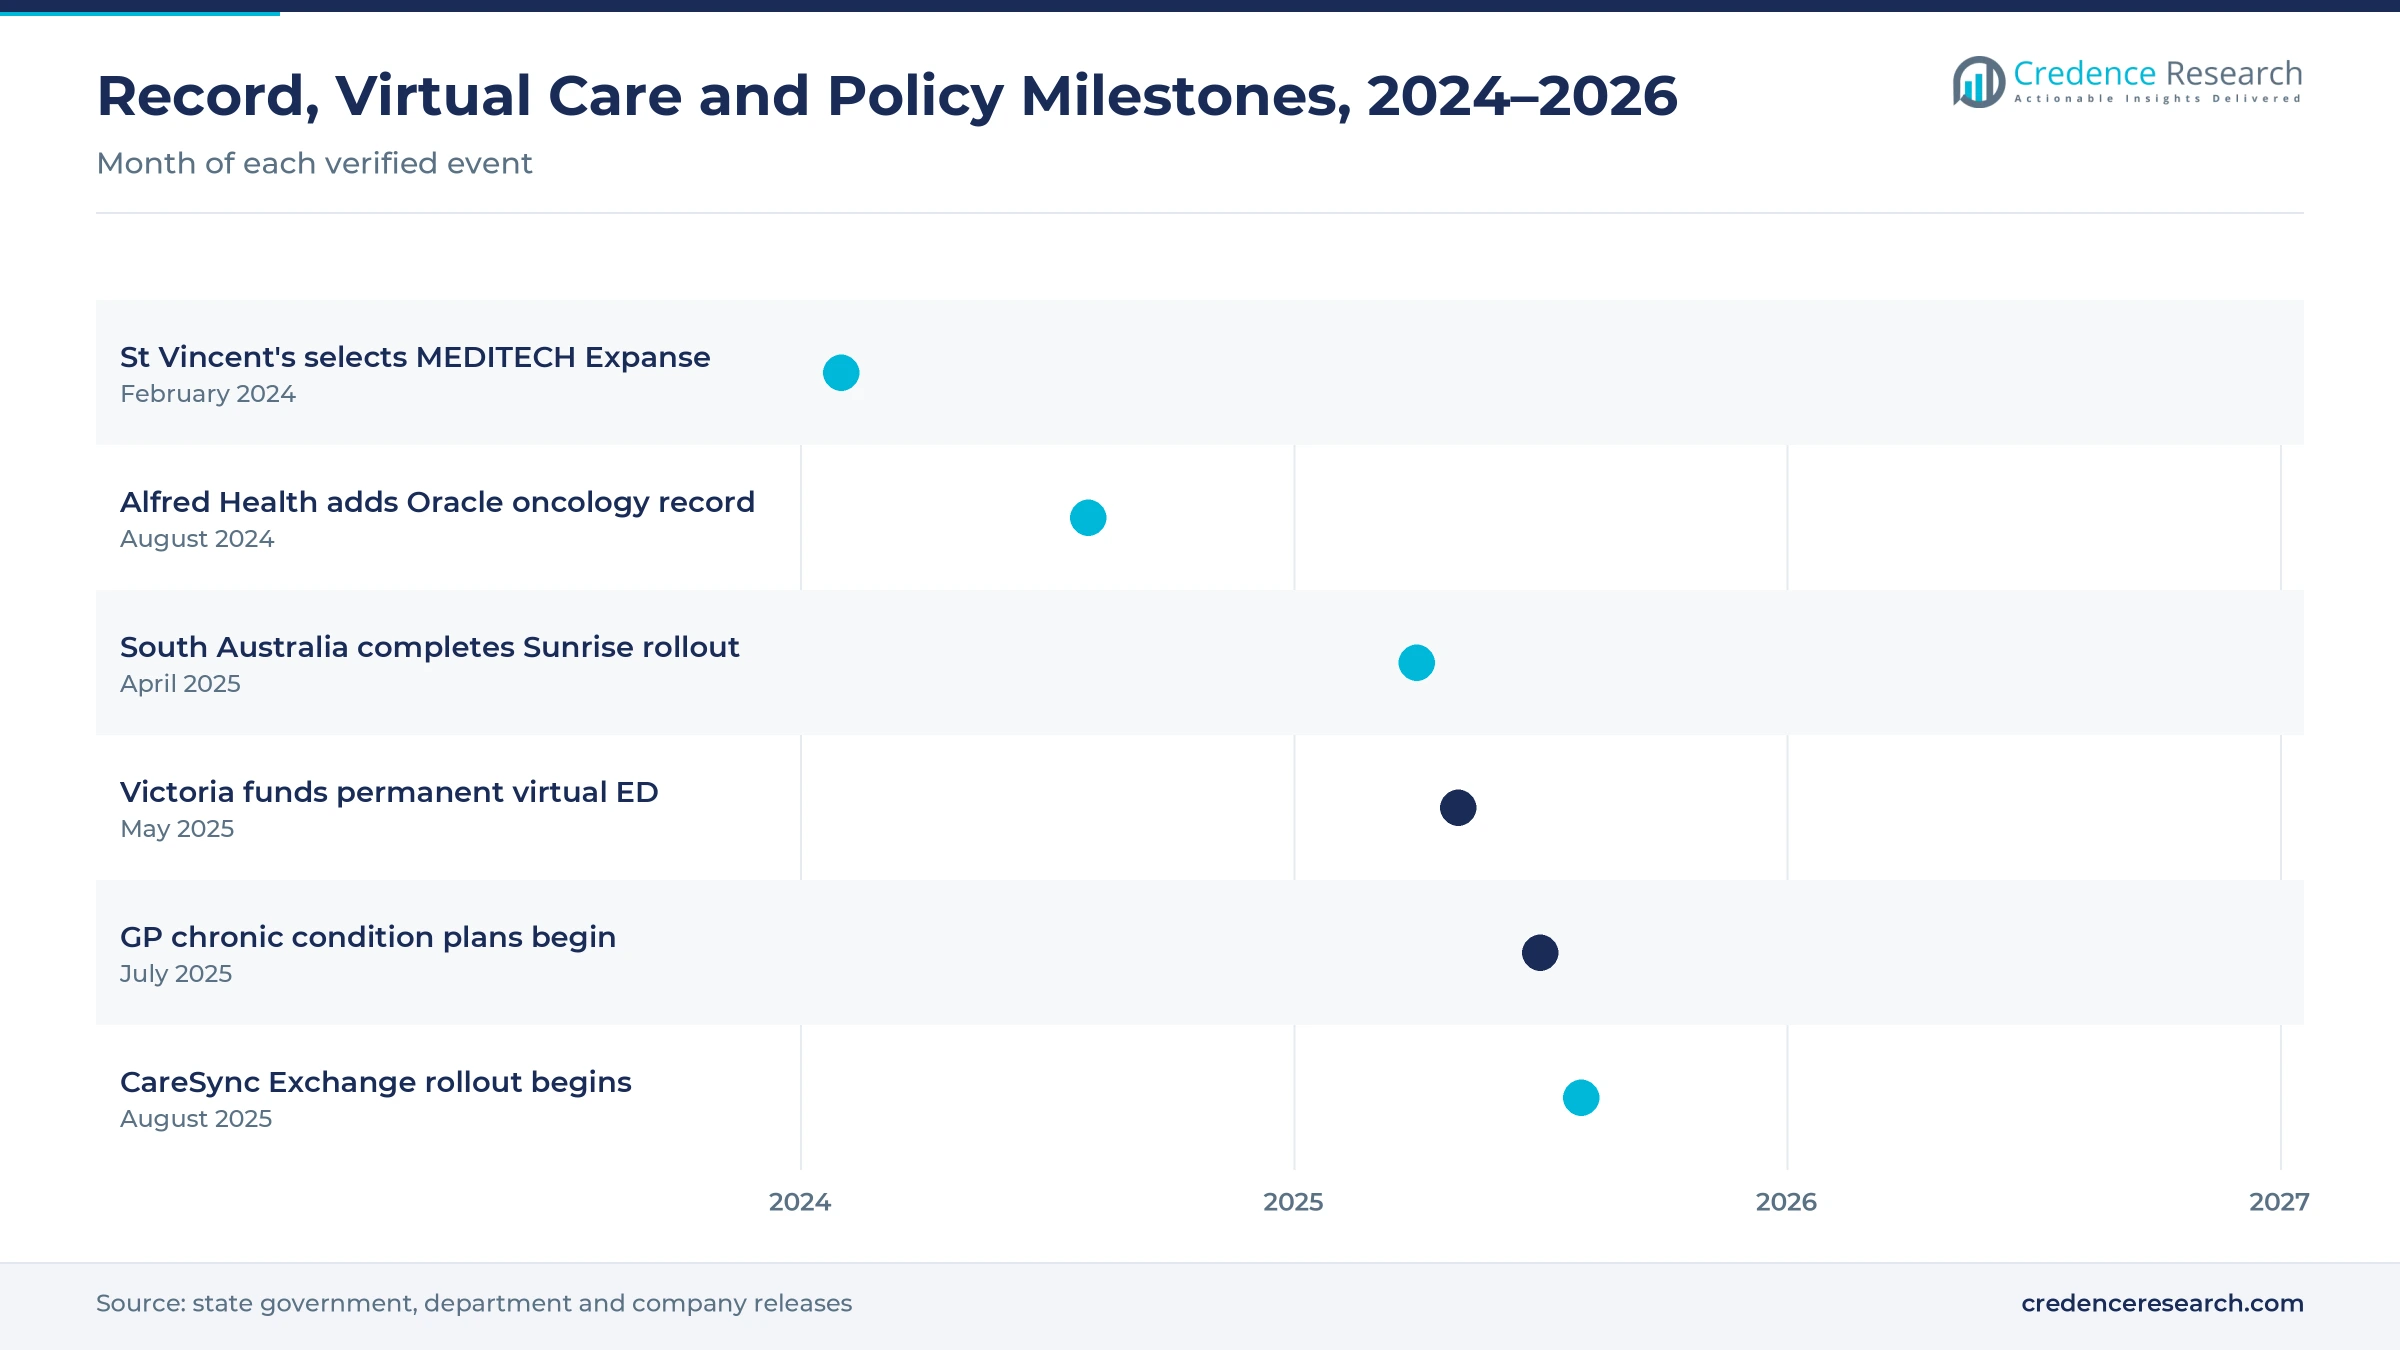
| In February 2024, St Vincent's Health Australia selected MEDITECH Expanse for 10 private hospitals in three states. | Moves a large private group to a cloud subscription record |
| In August 2024, Alfred Health expanded its Oracle Health record with oncology modules linked to pharmacy systems. | Adds cancer care ordering to an existing hospital record |
| In April 2025, South Australia completed the statewide Sunrise record across almost 100 public health sites. | First jurisdiction with one record across all public hospitals |
| In May 2025, Victoria committed AUD 437 million to make its virtual emergency department permanent. | Lifts planned capacity to more than 1,750 people a day by 2028-29 |
| In August 2025, Victoria began rolling out CareSync Exchange, starting with Austin Health and Eastern Health. | Statewide record sharing expected by 2028 |
Cloud records, exchanges and AI change clinical work
- Statewide electronic records replace local hospital systems with one patient record, which lets clinicians see results, orders and medicines across every public site and cuts repeat tests when patients move between hospitals.
- Record exchanges link hospitals that run different systems, which gives clinicians near real-time histories, pathology reports and discharge summaries without waiting for faxed or posted letters.
- AI scribes and analytics draft clinical notes and flag patient risk from existing data, which saves clinician time at each visit but brings closer scrutiny from the medicines regulator when tools suggest a diagnosis.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Record vendors and a telco-owned group compete for states
Competition is split between global record vendors that win statewide hospital contracts and local companies that serve practices, pharmacies and virtual care services. Epic Systems holds the New South Wales statewide record contract, while Altera Digital Health runs the Sunrise record across South Australia and supplies the dbMotion platform behind the CareSync Exchange in Victoria. Oracle Health supplies records to Alfred Health and has expanded them into cancer care. MEDITECH is moving St Vincent's private hospitals onto its cloud-hosted Expanse record. Telstra Health runs the eRx Script Exchange and pharmacy software used by GPs and community pharmacies. Rivals compete on statewide references, integration with national services such as My Health Record, local support and hosting terms. Because state contracts last many years, vendors that win one large program gain an edge in the next tender.
Which companies supply connected care systems in Australia?
| Company | Type | Role in the market |
|---|---|---|
| Telstra Health | Local platform group | Runs the eRx Script Exchange and pharmacy software |
| Oracle Health | Global record vendor | Supplies Alfred Health records, expanded into oncology in 2024 |
| Epic Systems | Global record vendor | Building the New South Wales single digital patient record |
| Altera Digital Health | Global record vendor | Sunrise record in South Australia and dbMotion for CareSync |
| MEDITECH | Global record vendor | Expanse cloud record for 10 St Vincent's private hospitals |
Credence Research view on connected care in Australia
Credence Research's view is that Australian digital health & telemedicine will grow strongly because every state is either rolling out, finishing or planning a single hospital record, and Medicare keeps allied and mental health telemedicine as a normal way to see a clinician. Clinical information systems remain the largest value pool, while analytics and AI add the fastest growth. Vendors that hold statewide references and integrate cleanly with national services should gain share, while cost overruns, medical device rules for AI and cyber threats will slow some purchases.
How the national connected care estimate was built
The report uses 2025 as the base year on a calendar basis, and market values come from the Credence Research model. That model combines state budget papers and program announcements, Medicare telehealth reviews, national health surveys, population data, audit office reports and company releases on contracts and go-lives. Segment splits and zone growth rates are Credence Research estimates, while zone shares follow the client-defined split. Sources used are official statistics, government releases, audit reports, trade press and company releases, and no interviews or surveys were used.
State record programs and virtual care carry growth
Value across Australian digital health & telemedicine is expected to reach USD 16.83 billion by 2035, a 13.25% CAGR during 2026–2035, as states finish their record programs and virtual care becomes a standard part of hospital services. Growth should be strongest through 2030 while New South Wales and Western Australia roll out new records. After that, AI tools, remote monitoring, mental health telemedicine and patient apps will carry more of the value. Stricter rules for AI would slow some launches, while wider record sharing would lift demand for integration and analytics.
Frequently Asked Questions
How big is the Australia digital health & telemedicine market?
Which solution type leads the Australian market?
Which region leads the Australian market?
How common is telehealth in Australian general practice?
Which states have finished statewide hospital records?
Which care setting is growing fastest?
Who are the leading companies in the Australian market?
What are the main challenges for connected care buyers?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Solution Type
- 1.2.1 Clinical Information Systems
- 1.2.2 Telehealth Platforms
- 1.2.3 Connected Care Applications
- 1.2.4 Healthcare Analytics and AI
- 1.3 By Care Setting
- 1.3.1 Hospitals
- 1.3.2 Primary and Specialist Clinics
- 1.3.3 Home and Community Care
- 1.3.4 Residential Aged Care
- 1.4 By End User
- 1.4.1 Clinical Practitioners
- 1.4.2 Healthcare Administrators
- 1.4.3 Patients and Carers
- 1.4.4 Pharmacy Professionals
- 1.5 By Channel
- 1.5.1 Public Procurement
- 1.5.2 Private Enterprise Sales
- 1.5.3 Patient Self-Service
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 4.83 billion → 2035: USD 16.83 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia Digital Health & Telemedicine Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia Digital Health & Telemedicine Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia Digital Health & Telemedicine Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia Digital Health & Telemedicine Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia Digital Health & Telemedicine Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia Digital Health & Telemedicine Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia Digital Health & Telemedicine Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia Digital Health & Telemedicine Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 4.83 billion → 2035: USD 16.83 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia Digital Health & Telemedicine Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Solution Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Clinical Information Systems
- 12.3.7.2 Telehealth Platforms
- 12.3.7.3 Connected Care Applications
- 12.3.7.4 Healthcare Analytics and AI
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Care Setting - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Primary and Specialist Clinics
- 12.4.7.3 Home and Community Care
- 12.4.7.4 Residential Aged Care
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Clinical Practitioners
- 12.5.7.2 Healthcare Administrators
- 12.5.7.3 Patients and Carers
- 12.5.7.4 Pharmacy Professionals
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Channel - Market Size and Forecast, 2025-2035
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size, 2018-2025
- 12.6.3 Revenue Forecast, 2025-2035
- 12.6.4 Volume Forecast, 2025-2035
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Public Procurement
- 12.6.7.2 Private Enterprise Sales
- 12.6.7.3 Patient Self-Service
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Australia Digital Health & Telemedicine End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia Digital Health & Telemedicine Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia Digital Health & Telemedicine Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia Digital Health & Telemedicine Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Telstra Health
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Oracle Health
- 18.4 Epic Systems
- 18.5 Altera Digital Health
- 18.6 MEDITECH
- 18.7 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

